South Dakota Department of Revenue Tax Guides & Bulletins
South Dakota Motor Vehicle Sales and Purchases Sales Tax Guide
Motor Vehicle Sales and Purchases https://dor.sd.gov/ 1-800-829-9188 The purpose of this tax fact is to explain how South Dakota state and local taxes apply to motor vehicle dealers. It is not intended to answer all questions that may arise. The information contained in this fact sheet is current as of the date of publication.
# Motor Vehicle Sales and Purchases
- being issued.
Only certain vehicles qualify for a title only. For a list of approved vehicles, see the Motor Vehicle Procedure •
Manual. Contact your County Treasurer with questions or to apply for a title only.
Vehicles approved for a title only are subject to use tax.
•
The purchaser is responsible for contacting the Department of Revenue to pay the state use tax, plus applicable municipal use tax.
Use tax is not due if the vehicle is purchased from a person and not from a business.
All sales of vehicles by auction are subject to either sales or use tax or motor vehicle excise tax unless exempt under SDCL 32-5B-2.
The vehicle is exempt from motor vehicle excise tax under SDCL 32-5B-2.
Motor vehicles exempt from the motor vehicle excise tax under SDCL 32-5B-2 are also exempt from sales tax.
•
This includes the following (see SDCL 32-5B-2 for a complete list):
•
Any motor vehicle sold or transferred that is eleven or more model years old and which is sold or transferred for $2,500 or less before trade-in;
Any motor vehicle transferred as part of the sale of the assets of a LLC, corporation, or a limited or general partnership if the motor vehicle was previously titled, licensed, and registered in South Dakota;
Any motor vehicle repossessed by a secured party or lien holder in satisfaction of the debt;
Any damaged motor vehicle transferred to an insurance company in the settlement of an insurance claim;
Any motor vehicle rented for twenty-eight days or less that is subject to the tax imposed by SDCL 32-5B-20.
# Motor Vehicle Sales or Purchases
The following table shows the tax that applies to the purchase or sale of certain motor vehicles. Also shown is titling, license, and registration requirements for those vehicles. This is not an all-inclusive list of motor vehicles. For title, license, and registration information on a specific vehicle, please contact your County Treasurer.
# Motor Vehicle Sales or Purchases Tax, Titling, Licensing, and Registration
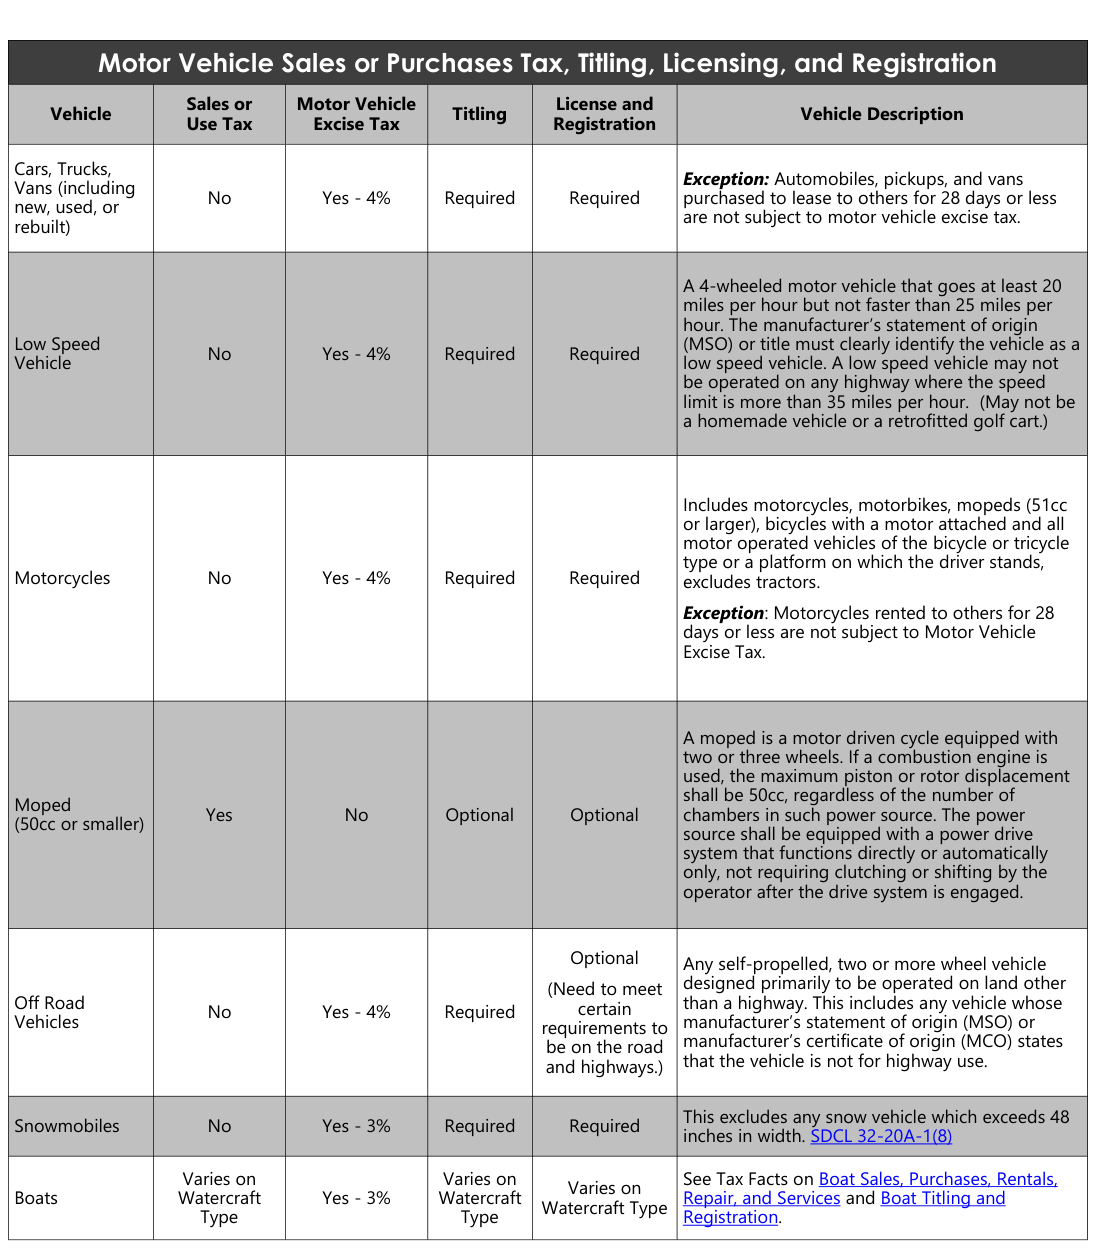
Text version of this table
| Motor Vehicle Sales or Purchases Tax, Titling, Licensing, and Registration | |||||
| Vehicle | Sales or Use Tax | Motor Vehicle Excise Tax | Titling | License and Registration | Vehicle Description |
| Cars, Trucks, Vans (including new, used, or rebuilt) | No | Yes - 4% | Required | Required | Exception: Automobiles, pickups, and vans purchased to lease to others for 28 days or less are not subject to motor vehicle excise tax. |
| Low Speed Vehicle | No | Yes - 4% | Required | Required | A 4-wheeled motor vehicle that goes at least 20 miles per hour but not faster than 25 miles per hour. The manufacturer’s statement of origin (MSO) or title must clearly identify the vehicle as a low speed vehicle. A low speed vehicle may not be operated on any highway where the speed limit is more than 35 miles per hour. (May not be a homemade vehicle or a retrofitted golf cart.) |
| Motorcycles | No | Yes - 4% | Required | Required | Includes motorcycles, motorbikes, mopeds (51cc or larger), bicycles with a motor attached and all motor operated vehicles of the bicycle or tricycle type or a platform on which the driver stands, excludes tractors. Exception: Motorcycles rented to others for 28 days or less are not subject to Motor Vehicle Excise Tax. |
| Moped (50cc or smaller) | Yes | No | Optional | Optional | A moped is a motor driven cycle equipped with two or three wheels. If a combustion engine is used, the maximum piston or rotor displacement shall be 50cc, regardless of the number of chambers in such power source. The power source shall be equipped with a power drive system that functions directly or automatically only, not requiring clutching or shifting by the operator after the drive system is engaged. |
| Off Road Vehicles | No | Yes - 4% | Required | Optional (Need to meet certain requirements to be on the road and highways.) | Any self-propelled, two or more wheel vehicle designed primarily to be operated on land other than a highway. This includes any vehicle whose manufacturer’s statement of origin (MSO) or manufacturer’s certificate of origin (MCO) states that the vehicle is not for highway use. |
| Snowmobiles | No | Yes - 3% | Required | Required | This excludes any snow vehicle which exceeds 48 inches in width. SDCL 32-20A-1(8) |
| Boats | Varies on Watercraft Type | Yes - 3% | Varies on Watercraft Type | Varies on Watercraft Type | See Tax Facts on Boat Sales, Purchases, Rentals, Repair, and Services and Boat Titling and Registration. |
Contact your County Treasurer to pay tax, apply for title, and register your vehicle within
45 days of purchase.
If you purchased a vehicle outside of South Dakota, proof of tax paid is required upon title application and you may have an additional tax obligation. Contact your County Treasurer to see if any additional tax is due.
# Dealer Fees and Purchase Options with the Sale of a Vehicle
All optional services and products a customer may purchase are taxable unless specially exempted.
A dealer may purchase and install optional products that become part of the motor vehicle for resale. See the table to the right for examples.
Examples of optional services and products that are exempt from sales, use, and motor vehicle excise tax:
Interest Charges
•
Credit Life & Disability Insurance (subject to insurance
- premium tax)
GAP Insurance (subject to insurance premium tax) • Mechanical Breakdown Insurance (subject to insurance
- premium tax)
Commissions for Loans
Commission or fees you receive for arranging a loan between the buyer of your product and a lending institution are not subject to sales tax. This includes fees received for arranging loans for a customer's purchase of a motor vehicle.
Delivery and Handling Fees
The retailers' charge for delivery is subject to the same state and municipal sales tax rate as the product or service sold. If the product or service sold is not taxable, the delivery charge is not taxable. The same is true if a dealer hires a transportation company and bills the customer for the transportation service, the transportation charge is subject to the same tax as the product sold, as long as it is done at the time of purchase.
Examples of Optional Products and
Customizing that can be Purchased for Resale:
Bed Liners
•
Bug Shields
•
Crystal Fusion
•
Customized Paint Decals
•
Electric MV Connector
•
Floor Mats
•
LoJack
•
Mirror
•
Polyshield
•
Running Boards
•
Seat Covers
•
Starter Interrupter Devices Theft Etch • Windshield Enhancements • Delivery charges include any charge for transportation, shipping, postage, handling, crating, and packing.
When a shipment contains taxable and nontaxable products, sales tax is due on the portion of the delivery charge for the taxable products. This is determined by using a percentage of the sales price compared to the total sales or a percentage of the weight of the taxable products compared to the total weight of all products in the shipment.
Examples:
- A parts store ships a part to a customer in rural Minnehaha County for $200 plus $20 delivery.
- The parts store owes state sales tax on $220. No municipal sales tax is due because the customer takes possession of the part outside the city limits.
- Jones Auto sells and delivers the following items to Fred's Farm Store in Pierre: Two tires for resale for $1000 and one tire display rack for use by Fred for $1000. Jones bills Fred $2000 plus $200 delivery. Fred gave Jones an exemption certificate for the two tires.
- Jones charges state sales tax plus Pierre municipal sales tax on $1,100 ($1000 for the display rack plus $100 shipping). Taxable shipping was determined by dividing the taxable products by the total sale ($1000/$2000 = 50%). 50% of the shipping is taxable ($200 x 50% = $100).
# Dealer Fees and Purchase Options with the Sale of a Vehicle (cont.)
Warranties, Insurance, and Service Contracts
Manufacturer's Warranty
Parts and labor furnished to fulfill a warranty obligation of the manufacturer are not subject to sales tax. Your receipts from the manufacturer for warranty work are not taxable. You do not owe use tax on parts taken from inventory to complete work under a manufacturer's warranty, this does not include warranty software.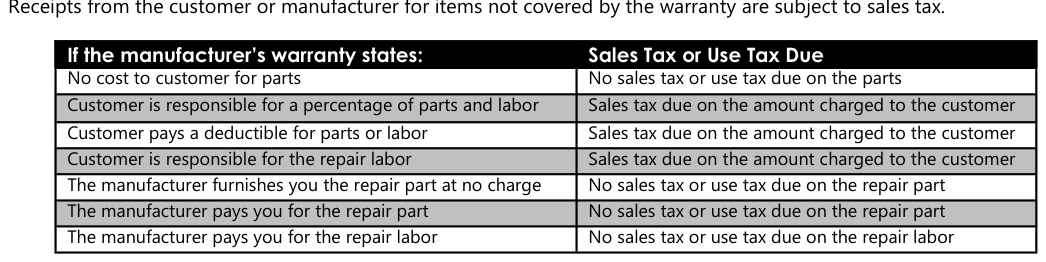
Text version of this table
If the manufacturer's warranty states: Sales Tax or Use Tax Due No cost to customer for parts No sales tax or use tax due on the parts Customer is responsible for a percentage of parts and labor Sales tax due on the amount charged to the customer Customer pays a deductible for parts or labor Sales tax due on the amount charged to the customer Customer is responsible for the repair labor Sales tax due on the amount charged to the customer The manufacturer furnishes you the repair part at no charge No sales tax or use tax due on the repair part The manufacturer pays you for the repair part No sales tax or use tax due on the repair part The manufacturer pays you for the repair labor No sales tax or use tax due on the repair labor
Extended service contracts that cover unexpected repair costs are subject to the motor vehicle excise tax when sold at the time of the vehicle purchase.
Extended service contracts sold later are subject to sales tax. Sales tax applies where the extended service contract is delivered to the customer. If customer takes possession at the dealer, the tax rate is based on the dealer's location. If the extended warranty is mailed to the customer, the tax rate is based on the customer's mailing address.
Mechanical Breakdown Insurance
Insurance policies are not considered warranty or service contracts. Insurance premiums are not subject to sales tax; however, the premiums are subject to insurance premiums tax. All charges made to the insurance company for parts and labor are subject to sales tax.
If you do not know if a service contract is insurance or not, you may contact the South Dakota Department of Labor, Insurance Division and ask if the company that sells the contract is a licensed insurance company, or call the Department of Revenue at 1.800.829.9188.
Implied Warranty
If you do not charge for repairs made to a customer's motor vehicle after the sale and those repairs are not covered by a written warranty, you owe use tax on the cost of all parts installed in the customer's vehicle. You do not owe use tax on your employee's labor.
Fees with Purchase of a Vehicle-Applicable Taxes 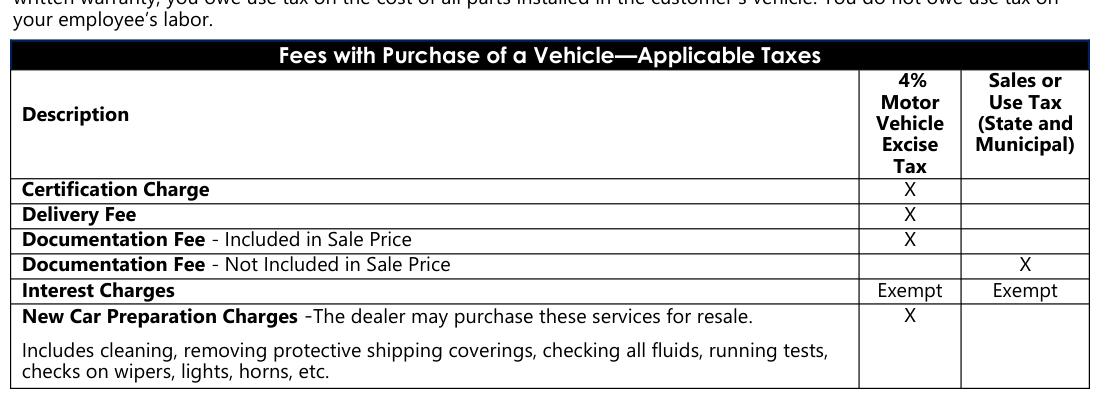
Text version of this table
Fees with Purchase of a Vehicle—Applicable Taxes Description 4% Motor Vehicle Excise Tax Sales or Use Tax (State and Municipal) Certification Charge X Delivery Fee X Documentation Fee - Included in Sale Price X Documentation Fee - Not Included in Sale Price X Interest Charges Exempt Exempt New Car Preparation Charges -The dealer may purchase these services for resale. Includes cleaning, removing protective shipping coverings, checking all fluids, running tests, checks on wipers, lights, horns, etc. X
# Unconventional Motor Vehicles
The following items are subject to sales tax or use tax. You may pull these items on a road; however, they are not subject to motor vehicle excise tax and may not be titled. This is not an all-inclusive list.
Log Splitters, Tree Chippers, Stump Grinders Axles
- • Tar Pits Jeep Boosters
- •
Small Pull-Type Cement Mixers
Car Dollies
- • Welders Street Sweepers
- •
Example:
Smith buys a 50cc moped from a dealer in Sioux Falls and has it delivered to Mitchell. Smith provides the dealer with the delivery information.
- The dealer should collect and remit state sales tax and Mitchell municipal sales tax because the dealer delivered the moped to Mitchell.
# Driving Services
A dealer may add mounted equipment to a vehicle prior to a sale or include the equipment with the sale but add the equipment later. Sometimes a customer may buy the mounted equipment from a separate dealer. The tax that applies depends on when the customer buys the equipment.
- Mounted equipment sold with the vehicle or included in the sale price of the vehicle is subject to the motor vehicle excise tax and is not subject to sales tax. The dealer may install the equipment before or after the sale. This applies to new or used motor vehicles and new or used mounted equipment.
- Mounted equipment sold separately from the vehicle and added after the sale of the motor vehicle, is subject to sales tax or use tax. Sales tax or use tax also applies to installation charges.
Examples of mounted equipment are truck boxes, hoists, digger equipment, and cherry pickers.
Mounted medical equipment is not subject to motor vehicle excise tax when the applicant shows proof of prescription.
Examples:
- Smith buys a truck chassis for $12,000. Smith then buys a cement mixer and has it mounted on the truck.
- The $12,000 is subject to motor vehicle excise tax.
- The mixer and installation charges are subject to sales tax.
- James buys a truck chassis for $12,000 and a cement mixer for $8,000 from a dealer. Both are listed on the motor vehicle purchase agreement. The Dealer installs the cement mixer on the truck. James pays $20,000.
- The truck and cement mixer are subject to the motor vehicle excise tax.
Sales tax applies where the customer receives the product or service.
Receive means where the customer takes possession of the product.
Products purchased, repaired, or serviced that are picked up at the seller's shop are taxed at the shop's location.
Products the seller delivers, with their vehicle or by a delivery company, are taxed at the delivery address.
When a shipping company is hired, sales tax is owed based on the delivery address. The shipping company should give the seller documentation showing the delivery address.
Products or services delivered to locations outside South Dakota are not subject to South Dakota sales tax. The seller must keep documentation of the address used to determine tax.
Fees charged for driving a motor vehicle from one location to another are subject to sales tax or use tax. Sales tax applies based on the location to which the vehicle is driven.
For example, if a person drives a car from Highmore to Pierre for hire, the state and municipal (Pierre) sales tax or use tax is due.
# Contact Us
If you have any questions, please contact the South Dakota Department of Revenue.
Call toll-free: 1-800-829-9188
Business Tax Division Email: bustax@state.sd.us
Motor Vehicle Division Email: motorv@state.sd.us Website: https://dor.sd.gov/ Mailing address and office location: South Dakota Department of Revenue 445 East Capitol Ave Pierre, SD 57501
Source: view the official PDF
Nearby sections (24 sections)
- contractors-excise-tax-guide · South Dakota Contractors' Excise Tax…
- drop-shipments · South Dakota Sales/Use Tax — Drop Shipments Guide
- exempt-entities · South Dakota Sales/Use Tax — Exempt Entities Guide
- exemption-certificate · South Dakota Sales/Use Tax Exemption…
- financial-institutions · South Dakota Bank Franchise (Financial…
- hotels-motels-campgrounds · South Dakota Sales/Use + Tourism Tax Guide…
- internet-services · South Dakota Sales/Use Tax Guide — Internet /…
- landscaping · South Dakota Sales/Use Tax Guide — Landscaping
- license-requirements · South Dakota License Requirements — Sales/Use…
- manufacturing · South Dakota Sales/Use Tax Guide — Manufacturing
- marketplace-provider-bulletin · South Dakota Marketplace Provider Sales…
- metal-mining · South Dakota Sales/Use Tax Guide — Metal Mining
- motor-vehicle-sales-purchases · South Dakota Motor Vehicle Sales and…
- prepared-food · South Dakota Sales/Use Tax — Prepared Food Guide
- property-tax-101 · South Dakota Property Tax 101 — Overview
- real-estate · South Dakota Sales/Use Tax Guide — Real Estate
- remote-seller-bulletin · South Dakota Remote Seller (Wayfair) Sales Tax…
- restaurants-and-bars · South Dakota Sales/Use Tax Guide — Restaurants…
- sales-use-tax-guide · South Dakota Sales and Use Tax Guide — master…
- self-contractors · South Dakota Sales/Use + Contractors' Excise Tax…
- taxpayer-bill-of-rights · South Dakota Taxpayer Bill of Rights
- tourism-tax · South Dakota Tourism Tax Guide
- use-tax-business · South Dakota Use Tax Guide — Business
- use-tax-individual · South Dakota Use Tax Guide — Individual