South Dakota Department of Revenue Tax Guides & Bulletins
South Dakota Sales/Use + Tourism Tax Guide — Hotels, Motels, and Campgrounds
https://dor.sd.gov/ 1-800-829-9188
# Campgrounds
The purpose of this tax fact is to provide general guidelines to lodging establishments and campgrounds on how tax applies to items and services they sell. It is not intended to answer January 2026 all questions that may arise. The information contained in this fact sheet is current as of the date of publication.
# Definitions
# Campgrounds
•
Grounds
Camping Cabins
•
Organizational
•
Camping Resorts
•
Recreational Vehicle
•
Parks
Trailer Parks
•
Camps Park Units
Youth Camps
•
A transient guest is any person who resides in a lodging establishment or campground less than 28 consecutive days.
A person includes any individual, firm, partnership, association, limited liability company, corporation, the State of SD and its political subdivision, or any group or combination acting as a unit.
Casual or occasional is the rental of a sleeping accommodation or camping site for ten or less days in a calendar year.
The casual or occasional rental of a sleeping accommodation or camping site is not subject to sales tax. Any establishment or campground that has a sales tax license is not offering the rental of lodging or campsites on a casual or occasional basis.
# Application of Tax
The rentals of rooms or parking sites by lodging establishments or campgrounds to a transient guest are subject to the state sales tax, applicable municipal sales tax, municipal gross receipts tax, and tourism tax. Rentals of rooms or campgrounds to the same guest for 28 or more consecutive days are not subject to sales, use, or tourism tax.
# Municipal Tax
In South Dakota, more than 200 municipalities have a sales or use tax that is in addition to the state sales tax. If a business is located in one of these municipalities, the municipal tax will apply to lodging, services, and products sold.
The municipality may also have an additional gross receipts tax on lodging, eating establishments, alcoholic beverages and ticket sales or admissions to places of amusement, athletic or cultural events. This is in addition to the state sales tax, the municipal sales tax and tourism tax. A list of municipal tax rates is available on the department's web site at https://dor.sd.gov or by calling 1-800-829-9188.
# Tourism Tax
applies to hotels and lodging places, campgrounds, motor vehicle rentals, recreational equipment rentals, recreational services, spectator events, visitor attractions and visitor-intensive businesses. The tourism tax rate is in addition to the state sales tax and any applicable municipal taxes.
Tourism tax does not apply to eating establishments, except for those that are on the grounds of a visitor attraction or special event.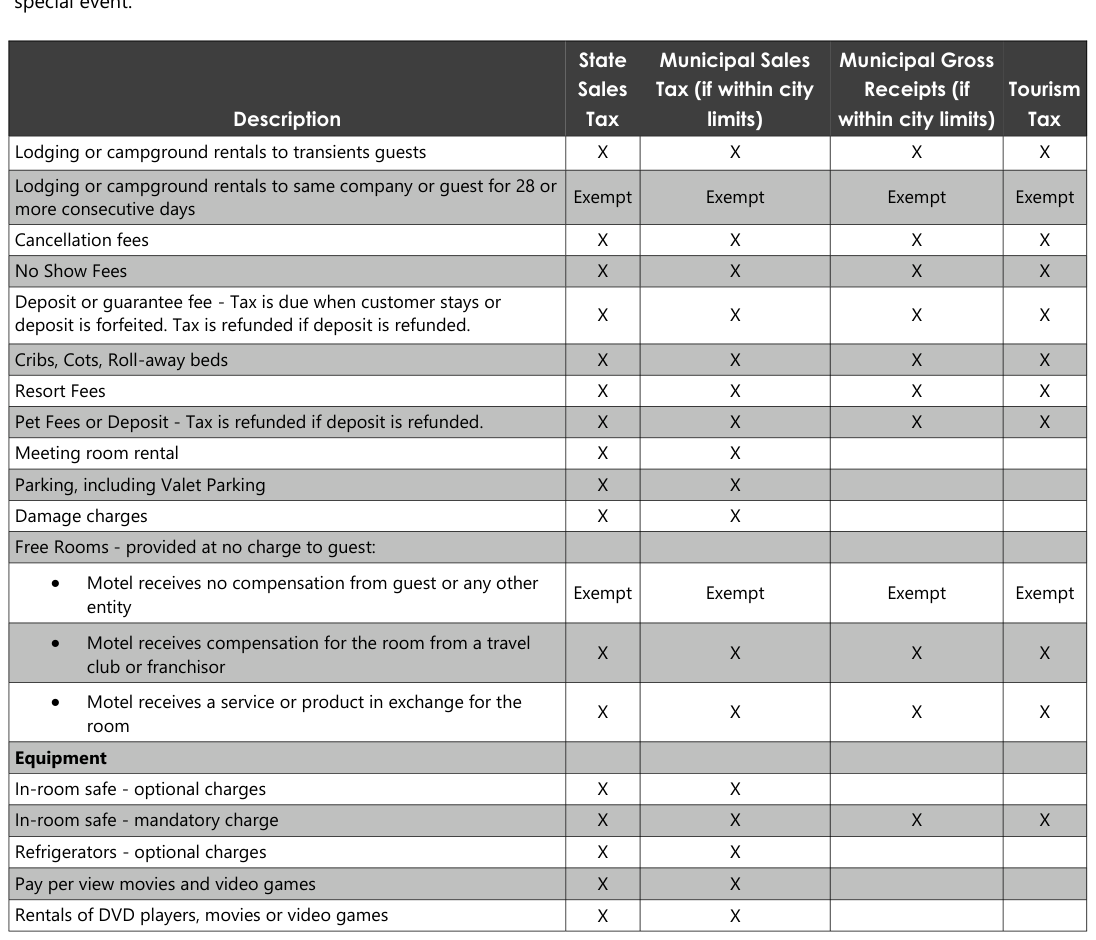
Text version of this table
Description State Sales Tax Municipal Sales Tax (if within city limits) Municipal Gross Receipts (if within city limits) Tourism Tax Lodging or campground rentals to transients guests X X X X Lodging or campground rentals to same company or guest for 28 or more consecutive days Exempt Exempt Exempt Exempt Cancellation fees X X X X No Show Fees X X X X Deposit or guarantee fee - Tax is due when customer stays or deposit is forfeited. Tax is refunded if deposit is refunded. X X X X Cribs, Cots, Roll-away beds X X X X Resort Fees X X X X Pet Fees or Deposit - Tax is refunded if deposit is refunded. X X X X Meeting room rental X X Parking, including Valet Parking X X Damage charges X X Free Rooms - provided at no charge to guest: • Motel receives no compensation from guest or any other entity Exempt Exempt Exempt Exempt • Motel receives compensation for the room from a travel club or franchisor X X X X • Motel receives a service or product in exchange for the room X X X X Equipment In-room safe - optional charges X X In-room safe - mandatory charge X X X X Refrigerators - optional charges X X Pay per view movies and video games X X Rentals of DVD players, movies or video games X X
X X
X X
X X
# Food and Drinks
# Exempt Exempt
- Laundry service performed by hotel for guests • X X Laundry service provided by independently owned laundry
# Exempt Exempt
- Services fees charged in addition to the fee charged by the independently owned laundry Transportation - Shuttle, taxi, or limousine service:
- Originates or terminates outside SD Tours - Tour operator owes the tax on receipts from sale of tour:
- Tours within SD, no destinations outside SD, but not all within the same city
- Tours to or from destinations outside SD • X Exempt X
# Bed & Breakfast
Bed and Breakfasts are subject to state sales tax, applicable municipal sales tax, municipal gross receipts tax, and the tourism tax. The Bed and Breakfast must pay state and municipal sales or use tax on all purchases including food.
# Equipment Rentals
Charges by a hotel for equipment rental and services, including VCR's, computers, microphones, projectors, televisions, Internet access and service charges for convention groups are subject to sales tax, plus the applicable municipal sales tax.
Items purchased that the hotel provides to conventions are subject to sales or use tax at the time of purchase.
Items purchased for a specific customer may be purchased for resale.
Other taxable receipts include charges for electricity.
# Food/Drinks
Examples of items purchased that the hotel provides to conventions:
Tables Tablecloths
- •
Chairs Presentation
- • equipment
Examples of products and services that can be purchased for resale:
Entertainment Catering
- •
Decorations Leased tablecloths
- •
The sale of food and drinks are subject to the state tax, applicable municipal sales tax, and municipal gross receipts tax.
Food and drinks provided to customers at no charge are subject to the state sales or use tax, plus the applicable municipal sales or use tax at the time of purchase. Motels that have restaurants attached owe sales or use tax on food taken out of inventory or purchased to give away at the motel.
# Gift Shops
Sales made by gift shops are subject to the state sales tax, plus applicable municipal sales tax. The gift shop may also be subject to tourism tax if the shop is distinct from the business in which it is located.
A gift shop is distinct from the business in which it is located if:
The gift shop is physically separate from the other business. Being physically separate may include a separate
- cash register or walls separating the gift shop from the remainder of the business. In some hotels the gift shop is down the hall from the front desk and appears to the customer to be as separate as the hotel's restaurant; or The gift shop is operated by a person other than the owner of the business in which it is located.
•
If the gift shop is distinct from the business and 50% or more of the gift shop's total receipts are during June through September, then the gift shop receipts from June through September are also subject to tourism tax. Items sold at the registration desk are not subject to tourism tax.
# Movies and Videos
Rentals of movies, VCRs, and DVDs are subject to the state sales tax, plus applicable municipal sales tax. Charges for movies offered via TV are subject to sales tax. The company that provides the equipment is responsible for use tax on all equipment that is furnished for use in the motel rooms. If the company sells or leases equipment to the motel and the motel collects for the movies, sales tax is due on the sale or lease of the equipment. The motel owes state plus applicable municipal sales tax on the receipts from the movie.
# Vending and Amusement Machines
The gross receipts from vending machines are subject to the state sales tax, plus applicable municipal sales tax. Gross receipts from vending machines that serve prepared food, such as hot soup, coffee, or hot chocolate, are also subject to the municipal gross receipts tax.
If a vending machine sells prepared food and other items, the municipal gross receipts tax will apply to all receipts unless documentation is kept to show the products sold. Gross receipts from vending machines located outside municipal limits are subject to the state sales tax only.
Owners of vending and amusement machines that place machines in another person's business are considered retailers.
They must have a sales tax license, and report and pay tax on the gross receipts from these machines.
Businesses do not owe sales or use tax on commissions they receive from receipts of amusement or vending machines owned and operated by others.
The purchase of vending machines is subject to a state sales tax, plus the municipal sales tax. Mechanical or electronic amusement devices or machines are subject to the state sales tax, no municipal tax. Machines purchased and used in other states, then brought into South Dakota are subject to South Dakota use tax. Credit will be allowed for sales or use tax paid to the state in which the machine was previously used.
# Franchise Operations
Royalties or service fees paid by a franchisee strictly for the privilege of engaging in business using the franchisor's name are not subject to sales or use tax. However, when a franchisor bundles its fee and the payment is for taxable and nontaxable items, the entire fee is subject to the state sales tax, plus applicable municipal sales tax.
Examples of taxable items that may be included with the royalty
Training
- •
Marketing
- • contributions
•
Accounting
•
Reservation fees Consulting
•
Gift certificates Software
•
Quality assurance Advertising and
- inspections Promotions
When taxable sales are included within the royalty fee, and not separately stated, the entire royalty payment is subject to state sales tax, plus applicable municipal sales tax.
Travel agency fees collected by a franchisor that are passed directly to the franchisee with no markup are not subject to tax.
# Reservation Services
Fees received by a reservation service, that are based on the sale of a room or camping site, are not subject to sales tax.
When a business is paid a fee to take reservations, but the fee is not based on the sale of a room or camping site, the fee is subject to tax.
Lodging establishments, that use reservations services, owe tax on the total charge for the room without deduction for amounts paid to or retained by the reservation service.
# Reservation Services (cont.)
Examples:
- Rooms at a motel in Pierre, SD are booked through a reservation service. The service collects the room charge of $100 plus tax of $8.70 (4.2% state + 2% city + 1% MRGT + 1.5% tourism = 8.7%). The reservation service sends $98.70 to the motel and retains $10 for their service.
The motel owes tax on the total charge of $100.
•
The reservation service does not owe sales tax on the $10 they retain.
•
- Another motel also uses a reservation service; however, the customer pays the motel at the time of stay. The motel collects $100 plus tax of $8.70 (4.2% state + 2% city + 1% MRGT + 1.5% tourism = 8.7%). The motel sends a commission to the reservation service of $10.
The motel owes tax on the room charge of $100.
•
The reservation service does not owe sales tax on the $10 commission paid by the motel.
•
- A motel pays Sam's Service $1,000 per month to take reservations for the motel. Sam's receives payment whether or not rooms are reserved. When Sam's makes a reservation, they collect the room charge of $100 plus tax of $8.70 (4.2% state + 2% city + 1% MRGT + 1.5% tourism = 8.7%) and forward the entire $108.70 to the motel.
The motel owes tax on the room charge of $100.
•
Sam's owes sales tax on the $1000 per month for providing the reservation service.
•
# Reservation Systems
Fees to use a reservation system, such as the reservation systems provided by a franchisor for their franchisees, are subject to the state and municipal sales or use tax.
Charges by global distribution systems are subject to the state and municipal sales or use tax. These service provide up to date information on availability and rates to travel agencies and reservation services.
# Membership Organizations
Receipts from membership fees are exempt when paid to any lodging house and hotel membership organization operated for the benefit of its members. This exemption does not apply to any membership fee that represents payment for tangible personal property and services provided by the membership organization.
# Purchases for Resale
Examples of taxable services and property:
Advertising or promotional services
•
Inspections
•
Reservations services
•
Lodging establishments and campgrounds purchasing services or supplies for resale must give an exemption certificate to their suppliers. State law requires exemption certificates to be complete and accurate. The buyer is responsible for properly completing an exemption certificate.
Complimentary items cannot be purchased for resale. The lodging establishment furnishes these items such as soaps, shampoos, and lotions for the guest's use.
Lodging establishments may sell items they provide for use in the room such as robes, trays, comforters, pillows, and featherbeds. The sale of these items is subject to the state and municipal sales tax. Items sold to customers can be purchased for resale.
# Sales for Resale
A lodging establishment or campground may sell services or products for resale if the buyer provides an exemption certificate. It is the buyer's responsibility to know when a service or product qualifies as a sale for resale. The seller is responsible for maintaining a complete exemption certificate.
# Use Tax
Supplies, materials, equipment or services used by the facility are subject to sales tax when purchased. If the supplier does not charge sales tax, use tax is due at the same tax rate as sales tax. The state use tax rate, plus applicable municipal use tax, is payable to the Department of Revenue in the filing period in which the lodging establishment or campground receives the supplies or services.
Tangible personal property delivered into South Dakota is subject to the South Dakota sales or use tax, even if the supplier charges another state's sales tax.
When a purchase is made out of state and possession is taken out of state the supplier may charge you that state's sales tax. If the other state's sales tax is the same or more than South Dakota's tax, no South Dakota tax is due.
If it is less than South Dakota's, the difference must be paid to South Dakota. The state plus applicable municipal taxes must be added together to determine if additional tax is owed.
Examples of commonly used items found in lodging establishments that are subject to use tax:
- Beds
- Bedding
- Towels
- TVs
- Drapes
- Laundry bags
- Ice bucket
- Cups
- Furniture
- Soaps
- Stationery
- Paper bags
- Ice machine
- Shampoos
- Pens
- Pool supplies
- Office supplies
- Coffee pots
- Shower caps
- Toilet paper
- Pillow mints
- Cleaning supplies & equipment
- Laundry supplies & equipment
- Electronic lock systems
Examples of services subject to sales or use tax are:
- Accounting
- Architectural
- Computer
- Engineering
- Consulting
Use tax is also due on supplies taken out of retail inventory for the business' use. Use tax is due on these items in the filing period they are taken out of inventory.
# Exempt Entities
The sale of products and services to the following entities is exempt from South Dakota sales and use tax.
- Indian Tribes
- United States government agencies
- State of South Dakota
- Public or municipal corporations of the State of South Dakota
- Municipal or volunteer fire or ambulance departments
- Public schools, including K-12, universities, and technical institutes that are supported by the State of South Dakota or public or municipal corporations of South Dakota.
- Non-profit hospitals
- Religious or private schools
- Relief agencies
Governments from other states or the District of Columbia, including public schools and state universities, are exempt from sales tax if the law in that state provides a similar exemption for South Dakota governments.
Governments providing similar exemptions are Colorado, Indiana, Iowa (lodging is not exempt), Minnesota
(prepared food, drinks and lodging are not exempt), North Dakota, Ohio, and West Virginia. The governments from states without a sales tax are exempt from SD sales tax. These state are Alaska, Delaware, Montana, New
Hampshire, and Oregon.
Purchases made by individuals working for an exempt entity that pay with their own funds or credit card are not exempt from sales tax, even if they will be reimbursed by their employer.
# Documentation Required
Government entities must provide an exemption certificate to the vendor or the vendor must keep documentation to show the purchase was paid from government funds. Documentation may include a purchase order or a check stub.
- Government entities do not need to provide an exemption number on the exemption certificate.
- Non-profit hospitals must provide an exemption certificate to the seller.
- Relief Agencies and Religious or Private Schools must provide an exemption certificate with their South Dakota exempt permit number. The permit number should contain the letters "RA," "RS," or "RE." The purchase must be made directly from the exempt entity's funds.
When a purchase is made with a government credit card, Proof of Government Exemption for Hotels must be kept as documentation.
# Federal Government Credit Cards
The federal government uses GSA SmartPay® 3 cards. Purchases made with Fleet Cards, Purchase Cards, and Department of Interior Cards are exempt from sales tax. Purchases made with Travel Cards may be taxable.
Travel Cards are blue, with a jet background and the Great Seal of the United States in the upper right hand corner.
There is a grey border on the left side of the card that states "For Official Government Use Only". These cards can be used for meals, lodging, rental cars, and similar travel-related venues. Purchases made with Travel Cards that have a sixth digit of 1, 2, 3, or 4 are subject to sales tax. Purchases made with Travel Cards that have a sixth digit of 0, 6, 7, 8, or 9 are exempt from sales tax. Proof of Government Exemption for Hotels must be kept as documentation if the purchase is exempt.
Contact Us
If you have any questions, please contact the South Dakota Department of Revenue.
Call toll-free: 1-800-829-9188
Business Tax Division Email: bustax@state.sd.us Website: https://dor.sd.gov/ Mailing address and office location: South Dakota Department of Revenue
445 East Capitol Ave
Pierre, SD 57501
# State of South Dakota Purchasing Cards
The state issues a purchasing card to certain state employees to make state purchases. Such cards are not for the personal use by the employee. Purchases with this card are tax exempt. Retailers need to keep a copy of the credit card transaction slip or some other proof of the exemption for documentation. This card is labeled Citibank Purchasing and contains the SD State Seal in the upper left-hand corner. The card contains the agency's initials such as DOT. There is also a credit card issued by Citibank to state employees. This is labeled Citibank The Business Card.
This card is to an individual, even though it says State of South Dakota at the bottom; purchases with this card are taxable.
# Diplomatic Tax Exemption Program
The U.S. Department of State issues tax exemption cards to certain foreign diplomats and consular personnel stationed in this country. These cards may have restrictions on their use. Restrictions are printed at the bottom of the card, inside the colored band. For example, some include hotel rooms while others do not. Please keep a photocopy of the card as documentation of the exempt sale. For further questions regarding the diplomatic tax exemption program, contact the Office of Foreign Missions, Washington, DC.
# Required Records
Lodging accommodations and campgrounds must have a South Dakota sales tax license for each place of business within the state. Records, such as purchase and sales invoices, bills of lading, registration forms, books of all receipts and sales, cash register receipts, and other pertinent papers and documents, must be kept for at least three years and be available for inspection during business hours.
Source: view the official PDF
Nearby sections (19 sections)
- audits · South Dakota DOR — Audit Process Guide
- contractors-excise-tax-guide · South Dakota Contractors' Excise Tax…
- drop-shipments · South Dakota Sales/Use Tax — Drop Shipments Guide
- exempt-entities · South Dakota Sales/Use Tax — Exempt Entities Guide
- exemption-certificate · South Dakota Sales/Use Tax Exemption…
- financial-institutions · South Dakota Bank Franchise (Financial…
- hotels-motels-campgrounds · South Dakota Sales/Use + Tourism Tax Guide…
- internet-services · South Dakota Sales/Use Tax Guide — Internet /…
- landscaping · South Dakota Sales/Use Tax Guide — Landscaping
- license-requirements · South Dakota License Requirements — Sales/Use…
- manufacturing · South Dakota Sales/Use Tax Guide — Manufacturing
- marketplace-provider-bulletin · South Dakota Marketplace Provider Sales…
- metal-mining · South Dakota Sales/Use Tax Guide — Metal Mining
- motor-vehicle-sales-purchases · South Dakota Motor Vehicle Sales and…
- prepared-food · South Dakota Sales/Use Tax — Prepared Food Guide
- property-tax-101 · South Dakota Property Tax 101 — Overview
- real-estate · South Dakota Sales/Use Tax Guide — Real Estate
- remote-seller-bulletin · South Dakota Remote Seller (Wayfair) Sales Tax…
- restaurants-and-bars · South Dakota Sales/Use Tax Guide — Restaurants…