South Dakota Department of Revenue Tax Guides & Bulletins
South Dakota Use Tax Guide — Business
1 | July 2023 | South Dakota Department of Revenue | Use Tax - Business
Use Tax - Business
The purpose of this tax fact is to provide general guidelines to businesses on how to remit use tax on products and services in South Dakota. It is not intended to answer all questions that may arise.
The information contained in this fact sheet is current as of the date of publication.
July 2023 https://dor.sd.gov/ 1-800-829-9188
What is Use Tax?
When is Use Tax Owed?
The South Dakota use tax is the counterpart of the South Dakota sales tax. The two taxes apply to the sales of the same products and services, have the same tax rates, and have similar laws. The difference is in how the taxes are applied. Use tax applies when state and applicable municipal sales tax has not been paid on products and services (including products and services transferred electronically) that are used, stored, or consumed in South Dakota.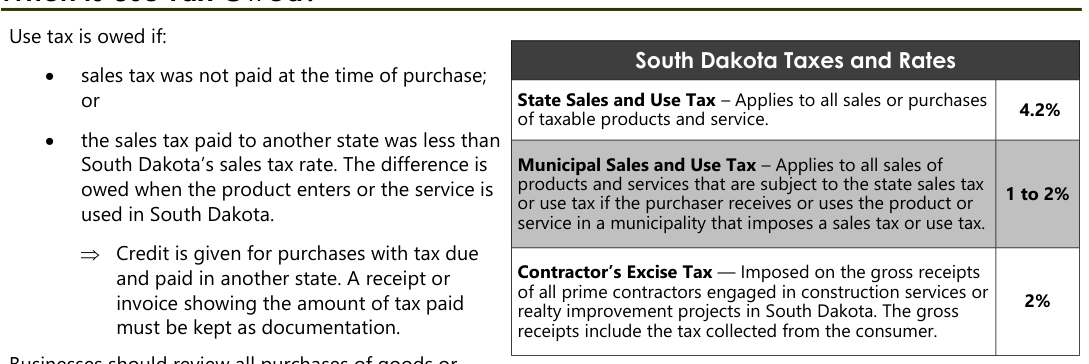
Text version of this table
South Dakota Taxes and Rates State Sales and Use Tax – Applies to all sales or purchases of taxable products and service. 4.2% Municipal Sales and Use Tax – Applies to all sales of products and services that are subject to the state sales tax or use tax if the purchaser receives or uses the product or service in a municipality that imposes a sales tax or use tax. 1 to 2% Contractor’s Excise Tax — Imposed on the gross receipts of all prime contractors engaged in construction services or realty improvement projects in South Dakota. The gross receipts include the tax collected from the consumer. 2%
- Click here to submit a use tax payment online if the business does not have/or get a tax return.
Use tax is due on the full purchase price, including delivery charges, or other fees, where the product is received or removed from inventory. Applicable municipal sales and use tax rates are based on the location the product or service is received. Use tax is due in the filing period in which the business buys the product or removes the item from inventory.
There is a use tax liability plus penalty and interest if use tax is not reported in a timely manner.
- Click here to find the sales and use tax rate for a given address.
Use tax is not due on payments to contractors for construction services.
Realty improvements are subject to contractor's excise tax and the contractor is responsible for the excise tax due. Use tax may be due on materials you provide to the contractor to install.
Examples of Use Taxable Products
& Services:
- Books
- Computers
- Leases of Equipment
- Meals Furnished for Employees
- Office Supplies
- Software
- Lawncare
- Snow Removal
# South Dakota Taxes and Rates
State Sales and Use Tax - Applies to all sales or purchases of taxable products and service.
4.2%
Municipal Sales and Use Tax - Applies to all sales of products and services that are subject to the state sales tax or use tax if the purchaser receives or uses the product or service in a municipality that imposes a sales tax or use tax.
1 to 2%
Contractor's Excise Tax - Imposed on the gross receipts of all prime contractors engaged in construction services or realty improvement projects in South Dakota. The gross receipts include the tax collected from the consumer.
2%
When is Use Tax Owed? (cont.)
Purchases from Out of State Businesses
Businesses using services in South Dakota owe use tax on those services, even if the service provider completes their work outside of the state. State and municipal use tax is based on the location the product or service is received.
Examples:
- A South Dakota business hires an unlicensed Iowa accountant to do their monthly payroll. Everything is done through the mail or by phone.
Use tax is owed on the payroll services.
•
An unlicensed attorney from Nebraska provides legal advice to a South Dakota client on a parcel of land purchased
- in South Dakota. The attorney does not have a sales tax license.
The South Dakota client will owe state use tax plus applicable municipal use tax based on where the client
- uses the service.
Multiple Locations
Businesses operating multiple locations both in and outside South Dakota owe use tax on the portion of services allocated to their South Dakota locations if sales tax was not legally due in the state where first receipt was taken.
Examples:
A company with locations in both Iowa and South Dakota hires an Iowa accountant to do their monthly payroll for their employees in both states. All reports and billings are sent to the company's headquarters in Iowa.
Use tax is owed on the percentage of the service allocated to the South Dakota employees. If 50% of the
- employees are located in South Dakota, then 50% of the service would be subject to South Dakota use tax.
Examples of Use Tax Liabilities
Demonstration and Sample Items
Items withdrawn from inventory to be used for demonstration temporarily and then returned to inventory to be sold later are not subject to use tax.
Items withdrawn from inventory to be used for demonstration ARE subject to use tax if they are not returned to inventory. If a
Examples:
- A grocery store gives food samples to customers.
- The grocery store owes use tax on the cost of the food given away.
- A computer store displays computers for sale demonstration item is later sold, the sale is also subject to sales tax plus applicable municipal tax. in their store.
- These computers are a display item and
Samples owned by a business to display products and samples given to customers at no charge ARE subject to use tax.
Donations
A business donating items, such as prizes for a contest or fundraiser, are not subject to use tax. If the computers are returned to inventory to be sold, the sale of the display computers are subject to sales tax. owes use tax on the cost of the donated item if sales tax was not already paid on the item.
- A business does NOT owe use tax on items donated to entities that are exempt from sales and use tax.
To learn more about exempt entities, see the Exempt
Entities Tax Fact.
Inventory Items for Other Use
Products withdrawn from inventory for purposes other than demonstration, such as personal or commercial use, ARE subject to state and applicable municipal use tax when withdrawn. The sale of the used product is subject to state and applicable municipal sales tax on the sale price without any deduction for use tax paid.
2 | July 2023 | South Dakota Department of Revenue | Use Tax - Business
Example:
A furniture store purchases computer desks exempt from tax to resell to customers. The store uses one of the desks in their office for three months.
- The store owes use tax on the cost of the desk.
When the desk is sold, sales tax is due on the selling price.
Examples of Use Tax Liabilities (cont.)
Equipment Brought into South Dakota from Another State
New or used equipment brought into South Dakota is subject to sales or use tax on the purchase price. The business owes state and applicable municipal use tax if the vendor did not collect the sales tax.
Equipment less than seven years old: State and applicable municipal use tax is due on the fair market value of equipment brought into South Dakota that is less than seven years old AND was purchased for use in another state.
Reciprocity (credit) is given for purchases with tax due and paid in another state. A receipt or invoice showing
- the amount of tax paid must be kept as documentation that tax was already paid.
Equipment more than seven years old: State and applicable municipal use tax is NOT due on equipment brought into South Dakota that is older than seven years old AND was purchased for use in another state.
The equipment's age is determined by the manufacture date, if documented, or the date of the purchase by the
- individual bringing the equipment into South Dakota.
Example:
A Minnesota manufacturer moved to South Dakota June 1, 2019. Equipment brought into South Dakota on June 1, 2019 includes equipment that was purchased new in 2016, and no MN tax was paid, and equipment manufactured in 2010, that was purchased used in 2012.
- The equipment purchased new in 2016, was less than seven years old when it was brought into South Dakota. South Dakota state sales tax and applicable municipal use tax is due on the fair market value of the equipment as of 2019.
- The equipment purchased used in 2012, was purchased for use in another state and over seven years old when brought into South Dakota. This equipment is not subject to South Dakota state sales tax and applicable municipal use tax.
Contact Us
If you have any questions, please contact the South Dakota Department of Revenue.
Call toll-free: 1-800-829-9188
Business Tax Division Email: bustax@state.sd.us Website: http://dor.sd.gov/ Mailing address and office location: South Dakota Department of Revenue 445 East Capitol Ave Pierre, SD 57501 3 | July 2023 | South Dakota Department of Revenue | Use Tax - Business
Source: view the official PDF
Nearby sections (14 sections)
- marketplace-provider-bulletin · South Dakota Marketplace Provider Sales…
- metal-mining · South Dakota Sales/Use Tax Guide — Metal Mining
- motor-vehicle-sales-purchases · South Dakota Motor Vehicle Sales and…
- prepared-food · South Dakota Sales/Use Tax — Prepared Food Guide
- property-tax-101 · South Dakota Property Tax 101 — Overview
- real-estate · South Dakota Sales/Use Tax Guide — Real Estate
- remote-seller-bulletin · South Dakota Remote Seller (Wayfair) Sales Tax…
- restaurants-and-bars · South Dakota Sales/Use Tax Guide — Restaurants…
- sales-use-tax-guide · South Dakota Sales and Use Tax Guide — master…
- self-contractors · South Dakota Sales/Use + Contractors' Excise Tax…
- taxpayer-bill-of-rights · South Dakota Taxpayer Bill of Rights
- tourism-tax · South Dakota Tourism Tax Guide
- use-tax-business · South Dakota Use Tax Guide — Business
- use-tax-individual · South Dakota Use Tax Guide — Individual