South Dakota Department of Revenue Tax Guides & Bulletins
South Dakota Sales/Use Tax Guide — Metal Mining
Metal Mining https://dor.sd.gov/ 1-800-829-9188 The purpose of this tax fact is to explain how South Dakota's sales and use and contractor's excise tax applies to the metal mining industry. It is not intended to answer all questions that may arise. The information contained in this fact sheet is current as of the date of publication.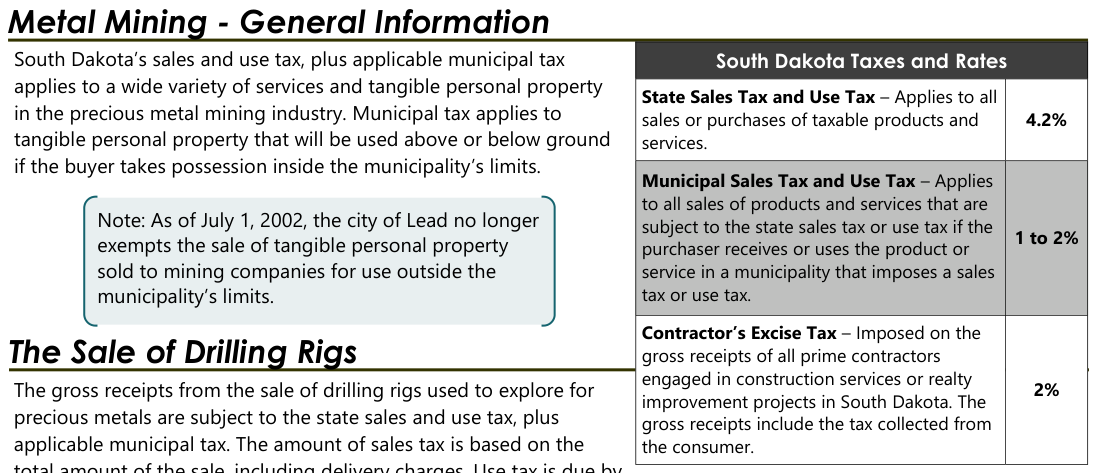
Text version of this table
South Dakota’s sales and use tax, plus applicable municipal tax applies to a wide variety of services and tangible personal property in the precious metal mining industry. Municipal tax applies to tangible personal property that will be used above or below ground if the buyer takes possession inside the municipality’s limits. Note: As of July 1, 2002, the city of Lead no longer exempts the sale of tangible personal property sold to mining companies for use outside the municipality’s limits. The Sale of Drilling Rigs South Dakota Taxes and Rates State Sales Tax and Use Tax – Applies to all sales or purchases of taxable products and services. 4.2% Municipal Sales Tax and Use Tax – Applies to all sales of products and services that are subject to the state sales tax or use tax if the purchaser receives or uses the product or service in a municipality that imposes a sales tax or use tax. 1 to 2% Contractor’s Excise Tax – Imposed on the gross receipts of all prime contractors The gross receipts from the sale of drilling rigs used to explore for precious metals are subject to the state sales and use tax, plus applicable municipal tax. The amount of sales tax is based on the engaged in construction services or realty improvement projects in South Dakota. The gross receipts include the tax collected from the consumer. 2%
July 2023
# South Dakota Taxes and Rates
State Sales Tax and Use Tax - Applies to all sales or purchases of taxable products and 4.2% services.
Municipal Sales Tax and Use Tax - Applies to all sales of products and services that are subject to the state sales tax or use tax if the 1 to 2% purchaser receives or uses the product or service in a municipality that imposes a sales tax or use tax.
Contractor's Excise Tax - Imposed on the gross receipts of all prime contractors engaged in construction services or realty 2% improvement projects in South Dakota. The gross receipts include the tax collected from the consumer. the purchaser of the drilling rigs if the vendor did not remit sales tax to the State of South Dakota.
Drilling rigs purchased for out-of-state use that are later used or stored in South Dakota and are less than seven years old are subject to use tax based on the cost or fair market value of the rig when brought into South Dakota, if sales tax has not been paid.
Examples of tangible personal property subject to the South Dakota sales and use tax, plus applicable municipal tax:
Acid wash tanks Drying ovens
- • Process vessels
•
Electrowinning cells
Conveying systems not
- • installed or secured to
Fork lift
- real property
Front end loader
•
Cranes
•
Pumps
•
Reclamation equipment
•
Solution heaters
•
Laboratory equipment
•
Crusher (primary and
•
Stacking equipment
- not affixed to a building secondary) Strip vessels • Laboratory furniture not • Drag lines and shovels • Tertiary crusher
- affixed to a building
Drilling rigs used to
•
Trucks not used on the
•
Machinery and tools
- locate precious metals
1 | July 2023 │ South Dakota Department of Revenue │ Metal Mining highway
The Sale of Drilling Services
The gross receipts from the sale of drilling services used to explore for precious metals are subject to the state sales and use tax, plus applicable municipal tax. If the sale of drilling services is made by a vendor without a South Dakota sales tax license, and no South Dakota sales tax is paid, state use tax, plus applicable municipal tax is due by the purchaser of the service. The drilling service company is also responsible for use tax on all equipment and supplies they use in performing their service.
Examples of services that are subject to the South Dakota state sales tax, plus applicable municipal tax:
Overall Mine Services Mine Exploration Environmental impact Boring test holes
- • studies Exploratory drilling • Designing buildings or
- Geophysical
- other realty exploration improvements if Geophysical studies
- performed without
Lab testing and
- any realty analysis improvement work Test drilling • Mine feasibility studies • Mine Operations Mine Development Contract crushing Adits
- •
Contract hauling Developmental drilling
- •
Contract mining Drifts
- •
Contract security Haul roads
- • services Overburden removal • Contract draining or
- Pre-strip metal mining
- pumping of mines
Sinking mine shafts
•
Realty Improvements and the Contractor's Excise Tax Contractors engaged in realty improvement contracts in South Dakota are subject to the contractor's excise tax. The contractor's excise tax is due on the total gross receipts from realty improvements in South Dakota. Sales or use tax must be paid on all materials used or consumed in completing the construction project.
The following examples are subject to excise tax: furniture pumps, or Ball mills
- cranes affixed to a
Concrete work
- building
Conveying systems if
•
Land clearing
- installed and secured to construction Fences Regeneration kilns • Leach pads Repairing buildings • Solution ponds Rod mills • Stormwater ponds Masonry and stonework
- real property
Mill building and
•
Design and erection of
- foundations buildings
Mine loading and
•
Electrical work
- discharging
Excavation Work
•
Roofing, siding and
•
Tailing sheet metal work impoundments Service roads • Office Buildings and • Thickener tanks foundations • Plumbing, heating and Vaults
- •
Mining appurtenances
•
Furnaces
•
Access roads
Fences
•
Buildings
Laboratory equipment,
•
Motor Vehicle Registration Fee air conditioning Water mains and wells • Power lines
- Water well drilling
•
Reclamation project
•
The following are subject to the motor vehicle registration fee and not to the sales, use or contractor's excise tax:
Motor vehicles, including trucks, that are required to be licensed for use on the highways.
•
Contact Us
If you have any questions, please contact the South Dakota Department of Revenue.
Call toll-free: 1-800-829-9188
Business Tax Division Email: bustax@state.sd.us Website: https://dor.sd.gov/
Mailing address and office location:
445 East Capitol Ave
Pierre, SD 57501
2 | July 2023 │ South Dakota Department of Revenue │ Metal Mining
Source: view the official PDF
Nearby sections (25 sections)
- audits · South Dakota DOR — Audit Process Guide
- contractors-excise-tax-guide · South Dakota Contractors' Excise Tax…
- drop-shipments · South Dakota Sales/Use Tax — Drop Shipments Guide
- exempt-entities · South Dakota Sales/Use Tax — Exempt Entities Guide
- exemption-certificate · South Dakota Sales/Use Tax Exemption…
- financial-institutions · South Dakota Bank Franchise (Financial…
- hotels-motels-campgrounds · South Dakota Sales/Use + Tourism Tax Guide…
- internet-services · South Dakota Sales/Use Tax Guide — Internet /…
- landscaping · South Dakota Sales/Use Tax Guide — Landscaping
- license-requirements · South Dakota License Requirements — Sales/Use…
- manufacturing · South Dakota Sales/Use Tax Guide — Manufacturing
- marketplace-provider-bulletin · South Dakota Marketplace Provider Sales…
- metal-mining · South Dakota Sales/Use Tax Guide — Metal Mining
- motor-vehicle-sales-purchases · South Dakota Motor Vehicle Sales and…
- prepared-food · South Dakota Sales/Use Tax — Prepared Food Guide
- property-tax-101 · South Dakota Property Tax 101 — Overview
- real-estate · South Dakota Sales/Use Tax Guide — Real Estate
- remote-seller-bulletin · South Dakota Remote Seller (Wayfair) Sales Tax…
- restaurants-and-bars · South Dakota Sales/Use Tax Guide — Restaurants…
- sales-use-tax-guide · South Dakota Sales and Use Tax Guide — master…
- self-contractors · South Dakota Sales/Use + Contractors' Excise Tax…
- taxpayer-bill-of-rights · South Dakota Taxpayer Bill of Rights
- tourism-tax · South Dakota Tourism Tax Guide
- use-tax-business · South Dakota Use Tax Guide — Business
- use-tax-individual · South Dakota Use Tax Guide — Individual