Michigan Department of Treasury Form Instructions
Form 5081 — Michigan Sales, Use & Withholding Taxes Annual Return (instructions)
This form cannot be used as an amended return; see the 2025
Sales, Use and Withholding
2025 Sales, Use and Withholding Taxes Annual Return
Taxes Amended Annual Return
Issued under authority of Public Acts 167 of 1933, 94 of 1937, and 281 of 1967, all as amended.
(Form 5082).
Do not use this form to replace a monthly/quarterly return.
File this return by February 28, 2026.
Taxpayer's Business Name
Street Address City
Business Account Number (FEIN or TR Number) State ZIP Code
A. Sales
PART 1: SALES AND USE TAX
- Total gross Michigan sales for tax year being reported … 1.
B. Use: Sales & Rentals
XXXXXXX
- Rentals of tangible property and accommodations … 2.
# XXXXXXX
- Telecommunications services …
- Add lines 1, 2 and 3 …
3.
4.
A. Sales Tax
- ALLOWABLE DEDUCTIONS a. Resale, sublease or subrent … b. Industrial processing exemption … c. Agricultural production exemption … d. Interstate commerce … e. Separately itemized nontaxable service charges … f. Bad debts … g. Food for human/home consumption … h. Government exemption … i. Michigan motor fuel tax … j. Delivery and installation exemption … k. Other exemptions and/or deductions (see instructions) … l. Tax included in gross sales … 5a.
5b.
5c.
5d.
5e.
5f.
5g.
5h.
5i.
5j.
5k.
5l.
B. Use Tax
# XXXXXXX
m. Total allowable deductions. Add lines 5a - 5l … 5m.
- Taxable balance. Subtract line 5m from line 4 …
- Gross tax due. Multiply line 6 by 6% (0.06) …
- Tax collected in excess of line 7 …
- Tax due before discount allowed. Add lines 7 and 8 …
- Total discount allowed (see instructions) …
- 0000 2025 68 01 27 6
6.
7.
8.
9.
10.
Continue on page 2.
2025 Form 5081, Page 2 of 2
Taxpayer's Business Name Business Account Number 11.
12.
A. Sales Tax B. Use Tax
- Total tax due. Subtract line 10 from line 9 …
- Tax payments and credits in current year (after discounts) … PART 2: USE TAX ON ITEMS PURCHASED FOR BUSINESS OR PERSONAL USE
- Purchases for which no tax was paid or inventory purchased or withdrawn for business or personal use … 13.
- Total use tax on purchases due. Multiply Line 13 by 6% (0.06) … 14.
- Use tax paid on purchases and withdrawals in current year … 15.
PART 3: WITHHOLDING TAX
- Gross Michigan payroll, pension and other taxable compensation … 16.
- Total number of W-2 and 1099 forms … 17.
- Total Michigan income tax withheld per W-2 and 1099 forms … 18.
- Total Michigan income tax withholding paid during current tax year … 19.
PART 4: SUMMARY
- Total sales, use and withholding tax due. Add lines 11A, 11B, 14 and 18 … 20.
- Total sales, use and withholding tax paid. Add lines 12A, 12B, 15 and 19 … 21.
- If line 21 is greater than line 20, enter the dierence here. If not, skip to line 25 … 22.
- Amount of line 22 to be credited forward to a future period … 23.
- REFUND. Subtract line 23 from line 22 … 24.
- If line 21 is less than 20, enter balance due … 25.
- Penalty for late ling or late payment (see instructions) … 26.
- Interest for late payment (see instructions) … 27.
- TOTAL PAYMENT DUE. Add lines 25, 26 and 27 … 28.
Text version of this table
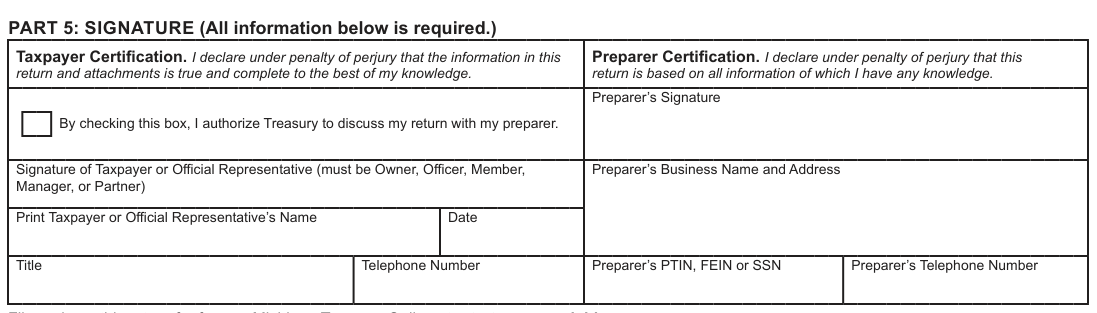
Taxpayer Certification. I declare under penalty of perjury that the information in this return and attachments is true and complete to the best of my knowledge. Preparer Certification. I declare under penalty of perjury that this return is based on all information of which I have any knowledge. By checking this box, I authorize Treasury to discuss my return with my preparer. Preparer's Signature Signature of Taxpayer or Official Representative (must be Owner, Officer, Member, Manager, or Partner) Preparer’s Business Name and Address Print Taxpayer or Official Representative’s Name Date Title Telephone Number Preparer’s PTIN, FEIN or SSN Preparer’s Telephone Number
Preparer's Business Name and Address
Print Taxpayer or Official Representative's Name Date Title Telephone Number Preparer's PTIN, FEIN or SSN Preparer's Telephone Number File and pay this return for free on Michigan Treasury Online at mto.treasury.michigan.gov.
Alternatively, make check payable to "State of Michigan." Write the account number, "SUW Annual" and tax year on the check.
Send the return and payment due to: Michigan Department of Treasury, P.O. Box 30401, Lansing, MI 48909-7901
- 0000 2025 68 02 27 4
Instructions for 2025 Sales, Use and
Withholding Taxes Annual Return (Form 5081)
Form 5081 is available for submission electronically using Michigan Treasury Online (MTO) at mto.treasury.michigan.gov or by using approved tax preparation software. Most taxpayers will have the option to file the Annual EZ form, reducing the amount of fields needed to complete. Visit MTO to see if you qualify.
NOTE: The address field on this form is required to be completed but will not be used to replace an existing valid address for the purpose of correspondence or refunds. Update address and other registration information using MTO or mail a completed Notice of Change or Discontinuance (Form 163).
IMPORTANT: This is a return for sales tax, use tax and/ or withholding tax. If the taxpayer inserts a zero on or leaves blank any line reporting sales tax, use tax or withholding tax, the taxpayer is certifying that no tax is owed for that tax type. Only enter figures for taxes the business is registered and/or liable for. If it is determined that tax is owed the taxpayer will be liable for the deficiency as well as penalty and interest.
PART 1: SALES AND USE TAX
Lines 1 through 4: Nexus and Reporting Requirements:
For information about determining whether a person has nexus with Michigan, see Revenue Administrative Bulletins (RAB) 2021-21 and 2021-22. Also visit www.michigan.gov/remotesellers for guidance for remote sellers and marketplace sellers, including FAQs.
Tax Included in Gross Sales Method ("TIGS method"):
Michigan sales tax (and use tax reported in this section, if applicable) is imposed on the seller. However, a seller is authorized to collect the tax at the point of sale from the customers. Sellers that separately state the tax (for example, on a receipt) and track their sales and tax separately in their books and records should report sales in this section without tax included and should leave line 5l blank. Other taxpayers prefer to charge their customers one amount that includes tax (they do not separately state the tax) yet still account for the tax in their books and records. These taxpayers are allowed, but are not required, to use the TIGS method. The TIGS method means that the taxpayer reports its gross sales on lines 1 through 4 with the tax included and uses line 5l to calculate and deduct the tax that was included. See line 5l for further instruction. A seller that did not collect the tax at the point of sale from its customers is not permitted to use the TIGS method.
# Line 1A: SALES TAX - Total Gross Sales for the Tax
Year: This line should be used by sellers with nexus to report sales of tangible personal property where ownership transfers in Michigan. This includes sellers with nexus through physical presence or economic presence (remote sales).
Enter total sales, including cash and installment transactions, of tangible personal property.
Include:
Any costs incurred before ownership of the property is transferred to the buyer, including installation, shipping, handling, and delivery charges.
Trade-in allowances if you are a vehicle dealer.
Do not report:
Nontaxable services that do not involve the sale or lease of tangible personal property.
Sales made through a marketplace facilitator, if you are a marketplace seller.
Line 1B: USE TAX - Total Sales for the Tax Year: This line should be used by:
Sellers with nexus to report sales of tangible personal property sourced to Michigan, for which ownership transfers outside Michigan, or Remote sellers without nexus who voluntarily collect
Michigan tax.
Enter total sales, including cash, credit, and installment transactions, of tangible personal property. However, marketplace sellers should not report sales made through a marketplace facilitator.
# Line 2B: USE TAX - Rentals of Tangible Personal
Property and Accommodations.
Marketplace sellers: Do not report sales made through a marketplace facilitator.
Lessors of tangible personal property: Lessors that have made a valid election under MCL 205.95(4) and MAC R 205.132(1) should report receipts from rentals of that tangible personal property under the election.
Persons providing accommodations: This includes but is not limited to total hotel, motel, and vacation home rentals, and assessments imposed under the Convention and Tourism Act, the Convention Facility Development Act, the Regional Tourism Marketing Act, and the Community Convention or Tourism Marketing Act.
Line 3B: USE TAX - Telecommunications Services. Enter gross income from telecommunications services.
Line 5a-5l: Allowable Exemptions and/or Deductions. Use lines 5a - 5l to deduct from gross sales the nontaxable sales included in line 4. Deductions taken for tax exempt sales must be substantiated in business records. A completed copy of Michigan Sales and Use Tax Certificate of Exemption (Form 3372) or the same information in another format must be obtained from the purchaser. For more information on exemption documentation, see Revenue Administrative Bulletin (RAB) 2022-19.
Line 5a: Resale, Sublease or Subrent. Enter resale, sublease or subrent exemption claims.
Line 5b: Industrial Processing Exemption. The sale or lease of tangible personal property ultimately used in industrial processing by an industrial processor is exempt.
Industrial processing is the activity of converting or conditioning tangible personal property by changing its form, composition, quality, combination, or character. In general, all of the following must be met:
Property must be used in producing a product for ultimate sale at retail, Property must be sold or leased to an industrial processor, including a person that performs industrial processing on behalf of another industrial processor or performs industrial processing on property that will be incorporated into a product for ultimate sale at retail, and Activity starts when property begins moving from raw materials storage to begin industrial processing and ends when finished goods first come to rest in finished goods inventory.
If property is used for both an exempt and a taxable purpose, the property is only exempt to the extent that it is used for an exempt purpose. In such cases, the exemption is limited to the percentage of exempt use to total use determined by a reasonable formula or method approved (but not required to be pre-approved) by Treasury. For exceptions and exclusions, see MCL 205.54t and 205.94o.
Line 5c: Agricultural Production Exemption. Property must be directly or indirectly used in agricultural production.
Generally, the following non-exhaustive list may be exempt:
(i) Tangible personal property sold or leased to a person engaged in a business enterprise that uses or consumes the property for either:
Tilling, planting, draining, caring for, maintaining, or harvesting things of the soil, or Breeding, raising, or caring for livestock, poultry, or horticultural products.
(ii) To the extent that the property is affixed to and made a structural part of real estate for others and used for an exempt purpose in (i), tangible personal property sold to a contractor that is one of the following:
Agricultural land tile
Subsurface irrigation pipe
Portable grain bins
Grain drying equipment and its fuel or energy source However, the following sales from (i) or (ii) are not exempt:
Food, fuel, clothing, or similar property for personal living or human consumption, or Property permanently affixed to and becoming a structural part of real estate unless it is agricultural land tile, subsurface irrigation pipe, a portable grain bin, or grain drying equipment. Certain property that can be disassembled and reassembled may be exempt.
Some specific types of exempt property and exempt uses of property are clarified in the statute. If property is used for both an exempt and a taxable purpose, the property is only exempt to the extent that it is used for an exempt purpose.
In such cases, the exemption is limited to the percentage of exempt use to total use determined by a reasonable formula or method approved (but not required to be pre-approved) by Treasury. For more information, see MCL 205.54a and 205.94.
Line 5d: Interstate Commerce. Enter sales made in interstate commerce. To claim such a deduction, the property must be delivered by the business to the out-of-state purchaser. Property transported out-of-state by the purchaser does not qualify as interstate commerce. Documentation of out-of-state shipments must be retained in business records to support this deduction.
# Line 5e: Separately Itemized Nontaxable Service
Charges. Enter separately itemized labor or service charges involved in maintenance and repair work on property owned by others if these charges were included in gross sales on line 1. Do not subtract any other service necessary to complete the sale of taxable property or any delivery or installation charges that were incurred before the completion of transfer of ownership of the property.
Line 5f: Bad Debts. Bad debts may be eligible for a deduction if the following criteria are met:
The debts are charged off as uncollectible on business books and records at the time the debts become worthless The debts are deducted on the return for the period during which the bad debts are written off as uncollectible The debts are or would be eligible to be deducted for federal income tax purposes.
A bad debt deduction may be claimed by a third-party lender if the retailer who reported the tax and the lender financing the sale timely execute and maintain a separate written election designating which party may claim the deduction.
Certain additional conditions must be met. See MCL 205.54i, 205.99a, and RAB 2019-3.
Line 5g: Food for Human/Home Consumption. Enter the total of retail sales of grocery-type food, excluding tobacco, marihuana products, and alcoholic beverages. Prepared food is subject to tax. See MCL 205.54g and MCL 205.94d for more information.
Line 5h: Government Exemption. Direct sales to the United States government or the state of Michigan or its political subdivisions are exempt.
Line 5i: Michigan Motor Fuel Tax. Motor fuel retailers may deduct the Michigan motor fuel taxes that were included in gross sales on line 1 and paid to the State or the distributor.
Line 5j: Delivery and Installation Exemption. Enter itemized delivery and installation charges included in gross sales. Public Acts 20 and 21 of 2023 state that delivery and installation charges are exempt from sales and use taxes when charges are separately stated on the invoice, bill of sale, or similar document and the seller maintains its books and records to show separately from the transaction. Delivery and installation charges that fail to satisfy these conditions or that involve, or are related to, the sale of electricity, natural gas, or artificial gas by a utility remain subject to sales tax and use tax unless otherwise exempt. See Notice Regarding Changes in the Taxability of Delivery and Installation Charges for Sales and Use Taxes.
Line 5k: Other Exemptions and/or Deductions. Identify exemptions or deductions not covered in items 5a through 5j on this line. Examples of exemptions or deductions are:
Trade in deduction. When the trade-in value of a motor vehicle is less than the Michigan trade-in allowance, use the trade-in value for the allowable deduction. When the trade-in value of a motor vehicle is equal to or greater than the Michigan trade-in allowance, use the Michigan trade-in allowance amount for the allowable deduction.
Trade-ins of RVs and watercraft are not subject to limitation. Visit the Sales and Use Taxes FAQ page at michigan.gov/taxes for trade-in limits. Taxes paid to Secretary of State are not reported here. Instead, they are reported on the Vehicle Dealer Supplemental Schedule (Form 5086, e-file only).
Credit for the core charge attributable to a recycling fee, deposit, or disposal fee for a motor vehicle or recreational vehicle part or battery if the recycling fee, deposit, or disposal fee is separately stated on the invoice, bill of sale, or similar document given to the purchaser.
Direct sales, not for resale, to certain nonprofit agencies, churches, schools, hospitals, and homes for the care of children and the aged, to the extent the property is used to carry out the nonprofit purpose of the organization.
For sales to certain nonprofit agencies, the exemption is limited based on the sales price of property used to raise funds or obtain resources. All sales must be paid for directly from the funds of the exempt organization to qualify.
Assessments imposed under the Convention and Tourism Act, the Convention Facility Development Act, the Regional Tourism Marketing Act, or the Community Convention or Tourism Marketing Act. Hotels and motels may deduct the assessments included in gross sales and rentals if use tax on the assessments was not charged to the customers.
Credits allowed to customers for sales tax originally paid on merchandise voluntarily returned, provided the return is made within the time period for returns stated in the taxpayer's refund policy or 180 days after the initial sale, whichever is earlier. Repossessions are not allowable deductions.
Sales to contractors of materials which will become part of a finished structure for a qualified exempt nonprofit hospital, qualified exempt nonprofit housing entity or church sanctuary, or materials to be affixed to and made a structural part of real estate located in another state.
The purchaser will provide a Michigan Sales and Use Tax Contractor Eligibility Statement (Form 3520). See RAB 2016-18.
Vehicle sales to non-reciprocal states for which no tax was paid to Secretary of State.
Qualified nonprofit organizations with aggregate sales in the calendar year of less than $25,000 may exempt the first $10,000 of sales for fundraising purposes.
Separately, veterans organizations exempt under IRC 501(c)(19) may exempt sales for the purpose of raising funds for the benefit of an active duty service member or veteran, up to $25,000 per event.
Direct Pay Exemption. Enter sales made to purchasers that claimed direct pay exemption from sales and use taxes. Purchasers claiming direct pay exemption from sales and use taxes on qualified transactions may provide sellers the Michigan Sales and Use Tax Certificate of Exemption (Form 3372), the same information in another format, the Uniform Sales and Use Tax Certificate approved by the Multistate Tax Commission, or the Streamlined Sales and Use Tax agreement Certificate of Exemption. MCL 205.98.
Line 5l: Tax Included in Gross Sales. Complete this line only if you reported sales on lines 1 through 4 with the tax included and you collected tax that was not separately stated from your customers (you used the Tax in Gross Sales Method-see above line 1). If these conditions apply, all tax will be deducted on this line so that line 7, "Gross tax due", calculates correctly. Subtract lines 5a through 5k from line 4, then divide the difference by 17.6667. Enter the result on line 5l.
Example: Joe sells t-shirts for $9.43 each and collects sales tax from customers. Therefore, he generally collects $10 ($9.43 + 0.57 tax) from each customer. Joe chose to not separately state the tax to his customers. Ten t-shirts were sold during the year. One of those t-shirts was sold to someone who would resell the t-shirt and who provided an exemption claim; therefore, that sale was not subject to sales tax and Joe collected just $9.43.
Option 1: Joe reports his total sales on line 1 and 4 without the tax included; therefore, he leaves line 5l blank. Joe's return is completed (in part) as follows:
*Line 1 = 10 shirts @ $9.43
Amount:
Line:
1 94.30*
4 94.30
5a 9.43
5l
5m 9.43
6 84.87
7 5.09
8 0.04
9 5.13
Option 2: Joe reports his total sales on line 1 and 4 with the tax included; therefore, he is using the TIGS method and needs to remove the tax from his tax base using line 5l.
Joe's return is completed (in part) as follows:
Line 1 = (9 shirts @ $10.00) + (1 shirt @ $9.43) Line: Amount:
1 99.43
4 99.43
5a 9.43
5l 5.09
5m 14.52
6 84.91
7 5.09
8 0.04
9 5.13
# Line 8: If more tax was collected than the amount on line
7, enter the difference. This line is used to report differences due to the rounding of numerous transactions. In addition, tax over-collected by a seller is required by law to paid to Treasury, unless refunded to the customer(s), and must be reported here.
Line 10: Total Discount Allowed for Timely Payments.
Annual filers: Enter $72 if the tax due on line 9 is $108 or more. If tax due is less than $108, calculate the discount by multiplying line 9 by 2/3 (0.6667).
Accelerated/Monthly/Quarterly filers: Enter total discounts allowed for the year.
# Line 12: Enter total payments plus credits from 2025 Fuel
Supplier and Wholesaler Prepaid Sales Tax Schedule (Form 5083), 2025 Fuel Retailer Supplemental Schedule (Form 5085), and 2025 Vehicle Dealer Supplemental Schedule (Form 5086), if applicable, made for the current tax year.
Note: all prepaid sales tax schedules are e-file only.
PART 2: USE TAX ON ITEMS PURCHASED FOR
BUSINESS OR PERSONAL USE
Line 13: Unless a specific exemption applies enter purchases for which no sales or use tax was paid, including property withdrawn for business or personal use. See Michigan Use Tax Act, 1937 PA 94, for information on various exemptions. For questions contact Michigan Department of Treasury at 517-636-4230. For Manufacturer/Contractors, alternative measures of the use tax base should be reported (see MCL 205.93a(1)(f) and (g) and RAB 2016-24 for more information). For all other taxpayers, report the "purchase price" as defined in MCL 205.92(f).
PART 3: WITHHOLDING TAX
Line 17: Enter the number of your W-2 and 1099 statements.
Do not attach copies of W-2s, 1099s, or any other information returns to this return. Instead, see Michigan Income Tax Withholding Guide (Form 446), to report that information.
Line 18: Enter the total Michigan income tax withheld for the return year.
Line 19: Enter the total Michigan income tax withholding previously paid for the return year. (Do not include penalty and interest.)
PART 4: SUMMARY
Line 24: Enter the amount of overpayment from line 22 to be refunded. Refunds will not be made in amounts of less than $1.
Line 25: If line 21 (tax paid) is less than line 20 (tax due), enter the additional tax due. Pay any amount greater than or equal to $1.
Line 28: Total Payment Due. Add lines 25, 26 and 27.
Submit payments electronically on MTO or make check payable to "State of Michigan." Write the account number, "SUW Annual" and the tax year on the check. Do not pay if the amount due is less than $1.
How to Compute Penalty and Interest
If the return is filed after February 28 and no tax is due, compute penalty at $10 per day up to a maximum of $400.
If the return is filed with additional tax due, include penalty and interest with the payment. Penalty is 5% of the tax due and increases by an additional 5% per month or fraction thereof, after the second month, to a maximum of 25%.
Interest is charged daily using the average prime rate, plus 1 percent.
Refer to www.michigan.gov/taxes for current interest rate information or help in calculating late payment fees.
PART 5: SIGNATURE
REMINDER: Taxpayers must sign and date returns.
Preparers must provide a Preparer Taxpayer Identification Number (PTIN), Social Security Number (SSN) or Preparer Firm ID (FEIN), as well as business name, business address and phone number.
Annual Return Reporting
Taxpayers are encouraged to file electronically using MTO or approved tax preparation software. Visit mto.treasury.michigan.gov for more information. Taxpayers with 250 or more employees must file their withholding return electronically. Do not include wage statements with your mailed annual return.
1099 and Income Record Form Reporting
Overview. "Income record forms" are defined as Michigan copies of Forms W-2, W-2C, W-2 G, 1099-R, 1099-MISC, and 1099-NEC. "Wage statements" are a sub-set of these forms, that is, Michigan copies of Forms W-2, W-2C. The IRS refers to the federal version of income record forms as "information returns."
W-2s. Employers required by federal law to file Form W-2, Wage and Tax Statement, must provide a copy to the
State of Michigan if the Form W-2 is issued to a Michigan resident employee, to report work performed in Michigan, or to report Michigan income tax withheld. For more about federal requirements, see IRS Publication 15, (Circular E), Employer's Tax Guide or visit www.irs.gov.
Correcting W-2 Errors. If the error was due to underreporting withholding on the original W-2, issue a corrected W-2 and send a copy to Treasury. As provided in Mich Admin Code, R 206.22(3)(b), the employer can only receive a refund if the original W-2 is recovered from the employee. When an employee retains the original, erroneous W-2, the employee, not the employer, must request the refund. The corrected form should be clearly marked "Corrected by the Employer".
If the error was due to overreporting withholding on the original W-2, do not issue a corrected W-2. This type of correction must be handled in one of the following ways (see Rule 206.22):
- The employer may repay the amount withheld in error to the employee anytime within the same calendar year.
The employer shall obtain a receipt from the employee and keep in business records. The employer may adjust their records and deduct the amount refunded from the tax owing on his next return or ask for a cash refund.
- If the employer does not repay the employee as noted above, the employee may claim a credit for the amount withheld on their individual income tax return (Form MI-1040).
If an issued W-2 is lost or destroyed, provide the employee with a substitute copy clearly marked "Reissued by Employer".
If the withholding error occurs before a W-2 is issued, adjust a later paycheck and make the same adjustment in the next payment due to Treasury.
W-2Gs. Michigan casinos, racetracks, and off-track betting facilities may be required to report winnings of, and withholding for, nonresidents of Michigan. See the associated information in the "Other Withholding" section for more information.
1099s. Persons required by the internal revenue code to issue certain 1099 forms (specifically, 1099-R, 1099-MISC, and 1099-NEC) must file a copy with the State of Michigan of each form issued to a Michigan resident, regardless where the issuer is domiciled or where the resident's work or services were performed. 1099 state copies must also be sent to Michigan if the form reports Michigan withholding. For more information about who is required to issue 1099s, see www.irs.gov.
Due Dates. State copies of most income statements are due to the Michigan Department of Treasury on or before January 31. The exceptions to this general rule are paper filed Form 1099-MISCs, which are due February 28, and electronically filed Form 1099-MISCs, which are due March
- Late filing is subject to penalty. Treasury does not have the authority to grant an extension of these due dates.
Tax Assistance
For assistance, call 517-636-6925. Assistance is available using TTY through the Michigan Relay Center by calling 711.
Source: view the official PDF
Nearby sections (12 sections)
- form-4890-cit-booklet · Form 4890 — Michigan CIT Forms and Instructions…
- form-4891-cit · Form 4891 — Michigan Corporate Income Tax Annual Return…
- form-5772-fte-instructions · Form 5772 Instructions — Michigan…
- form-5774-instructions · Form 5774 Instructions — Schedule for…
- form-807-composite · Form 807 — Michigan Composite Individual Income…
- mi-1040-book · MI-1040 Book — Michigan Individual Income Tax Return &…
- mi-1040cr · MI-1040CR — Michigan Homestead Property Tax Credit Claim…
- mi-1041-book · MI-1041 Book — Michigan Fiduciary Income Tax Return &…
- schedule-fte · Form 6072 — Michigan Schedule FTE (Flow-Through Entity)…
- schedule-tiered-entities · Form 6074 — Michigan Schedule of Tiered…
- suw-5080 · Form 5080 — Michigan Sales, Use & Withholding Taxes…
- suw-5081-annual · Form 5081 — Michigan Sales, Use & Withholding Taxes…