Wisconsin Department of Revenue Form Instructions
Form 1NPR — Nonresident & Part-Year Resident Income Tax
1NPR
Wisconsin Income Tax for
Nonresidents and Part-Year Residents Form 1NPR Instructions Use My Tax Account (MTA) to manage and protect your Wisconsin tax account. MTA allows you to:
- Sign up for Wisconsin Identity Protection PIN (see page 47)
- View and schedule estimated payments and cancel previously scheduled payments
- Opt in to receive electronic notices - no need to wait for the mail
- Check refund status and more
New in 2025
New Retirement Income Subtraction - Individuals who are at least 67 years old at the end of 2025 may subtract up to $24,000 of retirement income. See the Schedule M instructions.
College Savings Account - The subtraction for contributions to a Wisconsin state-sponsored college savings account is increased to $5,130 per beneficiary ($2,560 per beneficiary if you are married and file a separate return). See the Schedule CS instructions.
Adoption Expenses Subtraction - The maximum subtraction for expenses paid for a qualifying adoption is now $15,000 per child. See the Schedule M instructions.
# MY TAX ACCOUNT
Reminder
IRS adjustments - If the IRS adjusted any of your federal income tax returns, you must notify us within 180 days of any adjustment affecting your Wisconsin income tax returns. See page 11.
Tax Tips:
E-file for a faster refund (see page 6) If you moved out of Wisconsin in 2025, complete the Legal Residence (Domicile) Questionnaire on If you have to make estimated tax payments in 2026 and do not receive Form 1-ES in the mail, contact any of our offices or use our estimated income tax interactive voucher on our website to get a copy of the form
Tax returns are due:
Wednesday
April 15, 2026
Have questions?
See page 13 for office locations and other helpful numbers.
FEDERAL PRIVACY ACT In compliance with federal law, you are hereby notified that the request for your Social Security number on the Wisconsin income tax return is made under the authority of sec. 71.03(6)(a) of the Wisconsin Statutes. The disclosure of this number on your return is mandatory. It will be used for identification purposes throughout the processing, filing, and auditing of your return, and issuing refund checks.
I-152
Table of Contents
Page
File online. Pay online. Direct deposit. www.revenue.wi.gov General Instructions … 3
- Resident Status … 3
- Who Must File … 4
- What Income Does Wisconsin Tax? … 4
- Which Form To File … 5
- When To File … 5
- How To Get An Extension Of Time To File … 5
- Filing Your Return … 6
- Questions About Refunds … 8
- Amending Your Return … 8
Special Instructions … 11
Tax Help / Resources … 13
Line Instructions … 14
2025 Standard Deduction Table … 48 2025 Tax Table … 51 2025 Tax Computation Worksheet … 57 Wisconsin School District Number … 58 Index … 59 Legal Residence (Domicile Questionnaire) … 60
Resident Status
■ Am I a resident, a nonresident, or a part-year resident of Wisconsin?
The following will help you decide.
Full-year resident You are a full-year resident if you are domiciled in Wisconsin for all of 2025.
Nonresident You are a nonresident if you aren't domiciled in Wisconsin for any part of 2025.
Part-year resident You are a part-year resident if you are domiciled in Wisconsin for part of 2025.
Exception If you are a service member or their spouse and you elect to treat Wisconsin as your state of residency under 50 U.S.C. 4001, you are considered a full-year resident of Wisconsin regardless of where you are domiciled and should follow the instructions for full-year residents of this state. Conversely, electing a different state as your state of residence will make you a nonresident of Wisconsin. If a joint return is being filed and both the service member and their spouse are a normal full-year resident of Wisconsin or elect Wisconsin as their state of residency under 50 U.S.C. 4001, then Wisconsin Form 1 should be used.
■ What is domicile?
Your domicile is the permanent legal home you intend to use for an indefinite or unlimited period, and to which, when absent, you intend to return. It is not always where you presently live. You can be physically present or residing in one state but maintain a domicile in another. "Domicile" is often referred to as "legal residence." You can have only one domicile at a time.
Your domicile, once established, is never lost unless all three of the following occur or exist:
- You specifically intend to abandon your old domicile and take actions consistent with such intent
- You intend to acquire a new domicile and take actions consistent with such intent, such as those listed in question 7 of the questionnaire at the end of these instructions
- You are physically present in the new domicile Your domicile does not change if either of the following occur:
- You leave your state of domicile for a brief rest or vacation
- You leave your state of domicile to complete a particular transaction, perform a particular contract, or fulfill a particular engagement, but you intend to return to your state of domicile whether or not you complete the transaction, contract, or engagement (for example, migrant workers or students) ■ Armed forces personnel If you were a Wisconsin resident on the date you entered military service, you are considered a Wisconsin resident during your entire military career unless you take positive action to change your domicile to another state as described in the above section entitled "What is domicile?" or you qualify and make an election to be a resident of another state under 50 U.S.C. 4001. For more information, get Publication 128, Wisconsin Tax Information for Military Personnel and Veterans.
■ Aliens
If you are considered a nonresident alien for federal tax purposes for the entire taxable year, you are considered a nonresident of Wisconsin. If you are considered a resident alien for federal tax purposes for all or part of the tax year, you may be either a full-year resident, part-year resident, or nonresident of Wisconsin as follows:
- If you are a lawful permanent resident of the United States and you intend to remain permanently in Wisconsin, you are considered a Wisconsin resident. You are a lawful permanent resident of the United States at any time if you have been given the privilege, according to the immigration laws, of residing permanently in the United States as an immigrant. You generally have this status if the federal government has issued you an alien registration card, also known as Form I-551, green card, or permanent residence card.
- If you are a non immigrant (have not been granted immigrant status by the federal government), you are considered a nonresident of Wisconsin. Exception If you are a refugee or have been granted asylum and you intend to remain permanently in Wisconsin, you are considered a Wisconsin resident.
For those able to be considered a Wisconsin resident, you are generally treated as a resident as of the later of the date you are physically domiciled in Wisconsin or you obtain the necessary federal legal status (lawful permanent resident, refugee, or granted asylum).
Example For Wisconsin tax purposes, you must be a lawful permanent resident of the United States in order to be considered a resident of Wisconsin. On August 1, 2025, you were issued a green card by the federal government.
As such, you are considered a Wisconsin resident as of August 1, 2025 (assuming your intent was to establish a domicile in Wisconsin). For the 2025 tax year, you are considered a part-year resident of Wisconsin (a nonresident of Wisconsin from January 1, 2025, through July 31, 2025, and a resident from August 1, 2025, through December 31, 2025). As a part-year resident for 2025, you must file a 2025 Form 1NPR.
Note: Certain tax credits (for example, homestead credit and earned income credit) may not be claimed by part-year residents or nonresidents.
Example A foreign student in this country with an "F" visa under the Immigration and Nationality Act may be classified for federal tax purposes as a nonresident alien or as a resident alien depending on their intended length of stay in this country. Regardless of the student's alien status, the student maintains their domicile in their homeland. The student is a nonresident of Wisconsin. A student with an "F" visa cannot become domiciled in Wisconsin.
# Who Must File
If you are a nonresident or part-year resident of Wisconsin and your gross income from Wisconsin sources (or the combined Wisconsin source gross income of you and your spouse) is $2,000 or more for 2025, you must file a Wisconsin return. A return does not have to be filed by a nonresident of Wisconsin if all income is exempt from tax as disaster relief work performed during a state of emergency declared by the Governor.
Gross income means all income (before deducting expenses) reportable to Wisconsin. The income may be received in the form of money, property, or services. It doesn't include items that are exempt from Wisconsin income tax. For example, it does not include U.S. government interest. For further information, see Publication 122, Tax Information for Part-year Residents and Nonresidents of Wisconsin.
■ Other filing requirements
You may have to file a return even if your gross income is less than $2,000. You must file a Wisconsin income tax return if:
- You can be claimed as a dependent on another person's income tax return (for example, on your parent's return) and you have gross income of more than $1,350 which included at least $451 of unearned income. Unearned income includes interest, dividends, capital gain distributions, etc., that are reportable to Wisconsin.
- You owe a Wisconsin penalty on an IRA, retirement plan, Coverdell education savings account, health savings account, ABLE account, or Archer medical savings account.
Note: Even if you don't have to file, if you had Wisconsin income tax withheld from your wages or you paid estimated tax for 2025, you should file a Wisconsin return since this is the only way to get a refund. (Complete lines 1 through 31 of Form 1NPR, fill in a 0 on line 38, and complete lines 58, 59, 67, 69, 70, and 71. If the amount on line 1 differs from your Wisconsin wages on your wage statement (Form W-2), include an explanation of the difference and indicate where this income was earned.) If you are a resident of Illinois, Indiana, Kentucky, or Michigan, see the exceptions under the line 1 instructions on page 17.
# What Income Does Wisconsin Tax?
Full-year residents Wisconsin taxes your income from all sources.
Nonresidents Wisconsin taxes only your income from Wisconsin sources.
Part-year residents During the time you are a Wisconsin resident, Wisconsin taxes your income from all sources.
During the time you aren't a Wisconsin resident, Wisconsin taxes only your income from Wisconsin sources.
■ What is income from Wisconsin sources?
Income from Wisconsin sources includes:
- Wages, salaries, commissions, and other income for services performed in Wisconsin (see the exceptions under the line 1 instructions on page 17).
- Rents and royalties from real or tangible property located in Wisconsin, such as land, buildings, and machinery.
Gains or losses from sales or other dispositions of real or tangible property located in Wisconsin, such as land, buildings, and machinery.
- Profits or losses from businesses, professions, and farm operations conducted in Wisconsin, including sole proprietorships, trusts, partnerships, limited liability companies (LLCs), and tax-option (S) corporations. For taxoption (S) corporations, this includes capital gains, interest, and dividends passed through from a tax-option (S) corporation that is engaged in business in Wisconsin.
- Income from the Wisconsin state lottery, a multijurisdictional lottery if the winning lottery ticket or lottery share was purchased from a Wisconsin retailer, or Wisconsin pari-mutuel wager winnings and purses. This includes all income realized from the sale of or purchase and subsequent sale or redemption of lottery prizes if the winning tickets were originally purchased in Wisconsin.
- Winnings from a casino or bingo hall located in Wisconsin and operated by a Native American tribe or band.
- Income derived from a covenant not to compete to the extent the covenant was based on a Wisconsin-based activity.
Service member's spouse Under 50 U.S.C. 4001, a service member's spouse may elect to use one of three options as their state of residence for purposes of taxation, regardless of the date on which the marriage of the spouse and the service member occurred. Get Publication 128, Wisconsin Tax Information for Military Personnel and Veterans, for more information. However, nontaxable amounts excluded from the Wisconsin column for the service member's spouse must still be included in the federal column. Amounts entered in the federal column are the amounts from your federal return, as adjusted for differences between federal and Wisconsin law. See "Column A and Column B Instructions" on page 16.
# Which Form To File
If you are a nonresident or part-year resident of Wisconsin in 2025, you must file Wisconsin Form 1NPR.
If you are a full-year resident of Wisconsin in 2025, you must file Wisconsin Form 1. You can get Form 1 from any Department of Revenue office or from the department's website at revenue.wi.gov. Exception If you are a full-year Wisconsin resident but your spouse isn't, and you are filing a joint return, you must file Form 1NPR.
# When To File
You should file as soon as you can, but not later than April 15, 2026. If you file late without an extension, you are subject to interest at 1.5% per month, late filing fees, and penalties.
Farmers and fishers Persons who earn at least two-thirds of their gross income from farming or fishing who don't make payments of estimated income tax (Wisconsin Form 1-ES) must file their 2025 Wisconsin income tax returns and pay any tax due by March 2, 2026, to avoid interest for underpayment of estimated tax.
# How To Get An Extension Of Time To File
Your return is due April 15, 2026.
If you cannot file on time, you can get an extension. You can use any federal extension provision for Wisconsin, even if you are filing your federal return by April 15.
You do not need to submit a request for an extension to us prior to the time you file your Wisconsin return. When you file your Form 1NPR include either of the following:
- A copy of your federal extension application (for example, Form 4868)
- A statement indicating which federal extension provision you want to apply for Wisconsin (for example, the federal automatic 6-month extension provision) Note: You will owe interest on any tax that you have not paid by April 15, 2026. This applies even though you may have an extension of time to file. If you do not file your return by April 15, 2026, or during an extension period, you may have to pay additional interest and penalties. If you expect to owe tax with your return, you can avoid the 1% per month interest charge during the extension period by paying the tax by April 15, 2026. Submit the payment with a 2025 Wisconsin Form 1-ES. You can get this form from any Department of Revenue office or use our estimated income tax interactive voucher on our website. Use Form 1-ES to make an extension payment even if you will be filing your return electronically - do not use Form PV. Exception: You will not be charged interest during an extension period if (1) you qualify for a federal extension because of service in a combat zone or contingency operation, or
(2) you qualify for a federal extension due to a federally declared disaster. See "Special Conditions" below.
If you were a farmer or fisher and you did not make estimated tax payments, you must file your return and pay any tax due by March 2, 2026, to avoid paying interest for underpayment of estimated tax. Farmers and fishers are individuals who earn at least two-thirds of their gross income (gross income of both spouses if married filing a joint return) from farming or fishing. An extension of the March 2 date is not available.
Special Conditions A "Special Conditions" section is located under the name and address section on page 1 of Form 1NPR. If you qualify for an extension because of service in a combat zone or contingency operation, fill in "02" in the box. If you qualify for a 2-month extension because you live outside or are on duty in military or naval service outside the United States and Puerto Rico on the due date of the return, fill in "18" in the box. If you qualify for an extension because of a federally declared disaster, fill in "03" in the box and indicate the specific disaster on the line provided.
# Filing Your Return
■ E-filing (electronic filing) Electronic filing is the fastest way to get your federal and state income tax refunds. Certain software will allow you to file Form 1NPR electronically.
Check with your tax preparer/software to determine if you can electronically file Form 1NPR. For more information on e-filing, go to the department's website at revenue.wi.gov/Pages/OnlineServices/home.aspx.
■ Paper filing
Electronic filing (e-filing) is the fastest way to receive your refund. However, if you paper file, there are several things you can do to ensure you receive your refund faster.
Important information:
- Send original copies
- Use black ink
- Clearly write your name and address using capital letters (do not use mailing labels)
- Do not use commas and dollar signs as they can be misread when scanned
- Round amounts to whole dollars
- Do not add cents in front of the preprinted zeros on entry lines
- To indicate a negative number, use a negative sign (for example, -8300 not (8300))
- Print your numbers clearly: Do not use:
- If you make a mistake, erase or start over (do not cross out entries)
- Put entries on the lines, and do not write in the margins, above or below the lines
- Lines where no entry is required should be left blank (do not enter zeros)
- Do not draw vertical lines in entry fields (they can be read as an "I" or a "1" when scanned)
- Do not staple your return as stapling will delay the processing of your return and any refund ■ Assembling your return Begin by putting the five pages of Form 1NPR in numerical order. Then, attach, using a paper clip, the following in the order listed.
Do not attach a Form W-RA if you are filing your return on paper. Form W-RA is used only when submitting information for an electronically filed return. Note: If filing Form 804, Claim for Decedent's Wisconsin Income Tax Refund, with the return, place Form 804 on top of Form 1NPR.
- Payment - If you owe an amount with your return, paper clip your payment to the front of Form 1NPR, unless you are paying by credit card or online.
- Forms W-2 or 1099 - Paper clip the appropriate copy of each of your withholding statements (Forms W-2, W-2G, WT-11, 1042-S, 1099-G, 1099-R, 1099-MISC, and 1099-NEC, and Schedules 2K-1, 3K-1, and 5K-1) to the front of Form 1NPR.
- Wisconsin schedules - Copies of appropriate Wisconsin schedules and supporting documents, such as Schedule H (homestead credit), Schedule FC or FC-A (farmland preservation credit), Schedule CR, or Schedule RT. If you are reporting income and expenses of a disregarded entity, attach Schedule DE, Disregarded Entity Schedule.
- Amended return - Include Schedule AR, Explanation of Amended Return, with your amended return and all supporting forms and schedules for items changed. (Don't send a copy of your original return.)
- Federal return - A complete copy of your federal return (Form 1040, 1040-SR, or 1040NR) and its supporting schedules and forms (such as federal Form 8886, Reportable Transaction Disclosure Statement.)
- Extension form or statement - A copy of your federal extension application form or required statement if you are filing under an extension of time to file.
- Divorce decree -
- Persons divorced after June 20, 1996, who compute a refund - If your divorce decree apportions any tax liability owed to the department to your former spouse, include a copy of the decree with your Form 1NPR. Fill in "04" in the Special Conditions box on page 1 of Form 1NPR. This will prevent your refund from being applied against such tax liability.
- Persons divorced who file a joint return - If your divorce decree apportions any refund to you or your former spouse, or between you and your former spouse, the department will issue the refund to the person(s) to whom the refund is awarded under the terms of the divorce. Include a copy of the portion of your divorce decree that relates to the tax refund with your Form 1NPR. Fill in "04" in the Special Conditions box on page 1 of Form 1NPR.
- Injured spouse - If you are filing federal Form 8379, Injured Spouse Allocation, include a copy with your Form 1NPR.
Fill in "05" in the Special Conditions box on page 1 of Form 1NPR.
CAUTION Be sure to file all five pages of Form 1NPR. Send the original of your return. Do not send a photocopy.
■ Where to File
Mail your return (an original return or amended return) to the Wisconsin Department of Revenue at:
(if payment enclosed) (if refund or no payment enclosed) (if homestead credit claimed) PO Box 268 PO Box 59 PO Box 34
# Madison WI Madison WI
53790-0001 53785-0001 53786-0001 Envelopes without enough postage will be returned to you by the post office. Your envelope may need additional postage if it contains more than five pages or is oversized (for example, it is over ¼" thick). Also, include your complete return address.
Private Delivery Services You can use certain private delivery services approved by the IRS to meet the timely filing rule. The approved private delivery services are listed in the instructions for your federal tax form. Items must be delivered to Wisconsin Department of Revenue, 2135 Rimrock Rd., Madison WI 53713. Private delivery services cannot deliver items to PO boxes. The private delivery service can tell you how to get written proof of the mailing date.
# Questions About Refunds
Call: (608) 266-8100 in Madison, Visit our website at: revenue.wi.gov
(414) 227-4907 in Milwaukee, or 1-866-WIS-RFND (1-866-947-7363) toll-free within the U.S. or Canada If you need to contact us about your refund, please wait at least 12 weeks after filing your Form 1NPR. Refund information may not be available until that time. The department may not issue a refund before March 1 unless both the individual and the individual's employer have filed all required returns and forms with the department for the taxable year for which the refund was claimed.
You may call one of the numbers above or write to: Mail Stop 5-77
# Department of Revenue
PO Box 8949
Madison WI 53708-8949
If you call, you will need your social security number and the dollar amount of your refund.
An automated response is available when you call one of the numbers. If you need to speak with a person, assistance is available Monday through Friday from 7:45 a.m. to 4:30 p.m. by calling (608) 266-2486 in Madison (long-distance charges, if applicable, will apply).
You may also get information on your refund using our secure website at revenue.wi.gov.
# Amending Your Return
File an amended return only after you file your original return. Generally, a claim for refund must be filed within 4 years after the unextended due date of your original return (for example, April 15, 2030, for 2025 calendar-year returns).
However, a claim for refund to recover all or part of any tax paid as a result of an office or field audit may be filed within 4 years after the date assessed. This applies only if you paid the tax and did not file a petition for redetermination (written appeal).
If you filed an amended return with the Internal Revenue Service (IRS) or another state, you generally must also file an amended Wisconsin return within 180 days. You must file an amended Wisconsin return if the changes affect your Wisconsin income, any credit, or tax payable. You should also file an amended Wisconsin return to claim a refund or pay any additional tax due even though you are not amending your federal or other state return.
If your original return was filed on Form 1NPR, you would file an amended return using Form 1NPR and checking the amended return space at the top of page 1. Exception: If you incurred a net operating loss (NOL) on your 2025 Form 1NPR and elect to carry the NOL back to 2023 and/or 2024, you must file Form X-NOL for the appropriate year, in addition to a Form 1NPR for each year, to amend your return and claim a refund.
Check the space on Form 1NPR to indicate your filing status on the amended return. If you are changing from separate returns to a joint return, both of you must sign the amended return. If there is any tax due, it must be paid in full. You cannot change from joint to separate returns after the due date for filing your original return has passed.
If you are changing your filing status, the amount reported on line 31 of Form 1NPR as federal adjusted gross income must be based on the same filing status used for Wisconsin. For example, you and your spouse both originally filed Form 1NPR as married filing a separate return. You are amending to change your filing status to married filing a joint return. The amount reported on line 31 must be taken from a federal return based on a married filing joint status. If you did not file a joint federal return, you should prepare a pro forma federal return using a married filing joint return status. The federal adjusted gross income and other amounts from this pro forma return are then used to complete the amended return. Follow the Form 1NPR instructions to complete your amended return.
If you are changing an amount on any line of Form 1NPR, fill in the corrected amount on that line. If you are not changing an amount on a line, fill in the amount from your 2025 return as originally filed or as you later amended it.
If your latest filed return was changed or audited by the department, use the corrected figures from the adjustment notice.
Sign and date your amended return in the space provided on page 4. Your spouse must also sign if it is a joint return.
Include Schedule AR with your amended Form 1NPR to explain the changes you made and the reasons for those changes. If you owe an additional amount, include your check or money order for the additional tax and interest, made payable to the Wisconsin Department of Revenue.
Mail your amended return to the address shown on Form 1NPR.
Interest is charged on additional tax owed at the rate of 1% per month from the due date of your 2025 return (April 15, 2026). Figure the interest charge on the additional tax you owe. Enter this amount on line 76.
# Credit Repayments
If you are required to repay a Wisconsin credit, you must amend your Wisconsin return for the year in which the disposal of the property occurred to report the amount of the repayment. Report the repayment on line 56. See below for credits for which you may have to repay.
- State historic rehabilitation credit You may have to repay all or part of the state historic rehabilitation credit if you disposed of the property within 5 years after the date on which the preservation or rehabilitation work was complete or the Wisconsin Historical Society determines that you have not complied with all of the requirements. If sale, conveyance or noncompliance of the property on which the historic rehabilitation credit is computed occurs during the 1st, 2nd, 3rd, 4th, or 5th year after the date on which the preservation or rehabilitation is completed, then 100%, 80%, 60%, 40% or 20%, respectively, of the amount of the credits received for rehabilitating or preserving the property will be calculated and added back into the individual's tax liability, according to sec. 71.07(9r)(k), Wis.
Stats. The repayment is made for the taxable year in which the recapture event occurs.
The IRS created federal Form 4255, Recapture of Investment Credit, and the federal Form 4255 instructions in order to compute the amount of the historic rehabilitation tax credit required to be repaid. While Wisconsin has a separate historic tax credit for personal residences, federal Form 4255 can be used to determine the repayment by substituting the Wisconsin credit for the federal credit.
Example: Taxpayer completed $20,000 of historic rehabilitation expenditures which were approved on November 1, 2023. Taxpayer computes a Wisconsin historic rehabilitation credit of $5,000 ($20,000 qualified rehabilitation expenses x 25% credit rate). Taxpayer uses $1,000 of credit to offset tax in 2023 and $2,000 of credit to offset tax in
- On December 1, 2025, the property is sold. The repayment is figured as follows:
- Compute the number of full years between the date the property was approved and when it was sold and use the result to find the recapture percentage in the chart below. The number of full years between November 1, 2023, and December 1, 2025, is two, so the recapture percentage is 60%
# Number of Full Years from Date Approved to Recapture Date
Recapture
Percentage
100%
80%
60%
40%
20%
0%
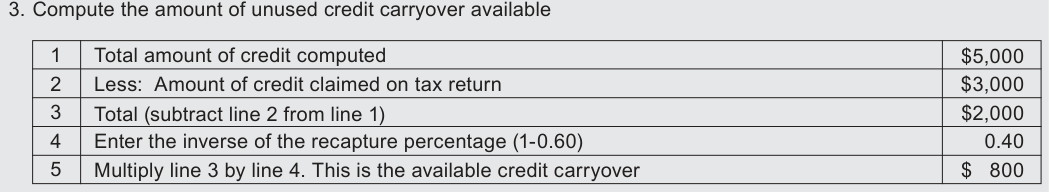
Text version of this table
| 1 | Total amount of credit computed | $5,000 |
| 2 | Less: Amount of credit claimed on tax return | $3,000 |
| 3 | Total (subtract line 2 from line 1) | $2,000 |
| 4 | Enter the inverse of the recapture percentage (1-0.60) | 0.40 |
| 5 | Multiply line 3 by line 4. This is the available credit carryover | $ 800 |
Special Instructions
# Penalties for Not Filing Returns or Filing Incorrect Returns
If you do not file an income tax return which you are required to file, or if you file an incorrect return due to negligence or fraud, penalties and interest may be assessed against you. The interest rate on delinquent taxes is 18% per year.
Civil penalties can be as much as 100% of the amount of tax not reported on the return. Criminal penalties for failing to file or filing a false return include a fine up to $10,000 and imprisonment.
# Fraudulent or Reckless Credit Claims
Fraudulent or reckless claims for any refundable credit, including, but not limited to, the earned income credit, homestead credit, or the veterans and surviving spouses property tax credit, are subject to filing limitations. If you file a "fraudulent claim," you will not be allowed to take any refundable credit for 10 years. "Fraudulent claim" means a claim that is false or excessive and filed with fraudulent intent. If you file a "reckless claim," you will not be allowed to take any refundable credit for 2 years. "Reckless claim" means a claim that was improper, due to reckless or intentional disregard of income tax law or department rules and regulations. You may also have to pay penalties.
# Internal Revenue Service and Other State Adjustments
Did the IRS adjust any of your federal income tax returns? If yes, you may have to notify the Department of Revenue of such adjustments. You must notify the department if the adjustments affect your Wisconsin income, any credit, or tax payable.
The department must be notified within 180 days after the adjustments are final. You must submit a copy of the final federal audit report by either of the following methods:
(1) Including it with an amended return that reflects the federal adjustments
(2) Mailing the copy to: Wisconsin Department of Revenue
# Audit Bureau
PO Box 8906
Madison WI 53708-8906
If you filed an amended return with the IRS or another state, you generally must also file an amended Wisconsin return within 180 days. An amended Wisconsin return must be filed if the changes affect your Wisconsin income, any credit, or tax payable.
Age
If your birthday falls on January 1, 2026, you are considered to be a year older as of December 31, 2025. Example:
If you were born on January 1, 1961, you are considered to be age 65 as of December 31, 2025.
# Estimated Tax Payments Required for Next Year
If your 2026 Wisconsin income tax return will show a tax balance due to the department of $500 or more, you must do either of the following:
- Make estimated tax payments for 2026 in installments beginning April 15, 2026, using 2026 Wisconsin Form 1-ES or the estimated income tax interactive voucher on our website
- Increase the amount of income tax withheld from your 2026 pay For example, you may have a tax balance due with your return if you have income from which Wisconsin tax is not withheld. If you do not make required installment payments, you may be charged interest.
For more information, contact the department's Customer Service Bureau at (608) 266-2486 or visit any Department of Revenue office. For additional information on making payments, see our Make a Payment webpage.
If you must file Form 1-ES for 2026 and do not receive a form in the mail, go to our website at revenue.wi.gov to obtain a personalized copy of Form 1-ES. You may also visit or contact the department using one of the methods listed above.
# Special Instructions
Death of a Taxpayer
A return for a taxpayer who died in 2025 should be filed on the same form which would have been used if they had lived. Include only the taxpayer's income up to the date of their death.
If there is no estate to probate, a surviving heir may file Form 1NPR for the person who died. If there is an estate, the personal representative for the estate must file the return. The person filing the Form 1NPR should sign it and indicate their relationship to the person who died (for example, "surviving heir" or "personal representative"). Be sure to fill in the surviving heir's or personal representative's mailing address in the address area of Form 1NPR.
If the taxpayer did not have to file a return but paid estimated tax or had tax withheld, a return must be filed to get a refund.
If your spouse died during 2025 and you did not remarry in 2025, you can file a joint return. You can also file a joint return if your spouse died in 2026 before filing a 2025 return. A joint return should show your spouse's 2025 income before death and your income for all of 2025. Write "Filing as surviving spouse" in the area where you sign the return.
If someone else is the personal representative, they must also sign.
If the return for the decedent is filed as single, head of household, or married filing separate, fill in "06" in the Special Conditions box and indicate the date of death on the line provided. If a joint return is being filed, fill in "06" in the box if it is the primary taxpayer (person listed first on the tax form) who is deceased and the date of death. If it is the spouse who is deceased, fill in "07" in the box and the date of death. If both spouses are deceased, fill in "08" in the box and both dates of death.
If your spouse died before 2025 and you have not remarried, you must file as single or, if qualified, as head of household.
Claiming a Refund:
If you are filing a return on behalf of a decedent, submit Form 804, Claim for Decedent's Wisconsin Income Tax Refund, with the return and check the box below the special conditions box on page 1 of Form 1NPR. If you did not submit Form 804 with the return, you were issued a refund, and you are not able to cash the refund check, complete Form 804 and mail the completed form and refund check to the address shown on Form 804. Note: If there is an estate, the personal representative for the estate must file the return and claim for refund. See Form 804 for more information and required documentation.
For more information about the final income tax return to be filed for a deceased person, visit any department office or call our Customer Service Bureau at (608) 266-2486.
# Requesting Copies of Your Returns
The Department of Revenue will provide copies of your Wisconsin returns for prior years. Persons requesting copies should complete the online application at tap.revenue.wi.gov/mta, then click on Request Tax Record Copy under Additional Services. Include all required information and fee with your application.
Applicable Laws and Rules
This document provides statements or interpretations of the following laws and regulations enacted as of October 16, 2025: ch. 71, Wis. Stats., and secs. 42, 50, 67, 71, 72, 220, 223, 265, 529A, 530, 4975, 6081, 6402, 7508, 7508A, and 7701, IRC.
Tax Help / Resources
# Internet Address
Our website, revenue.wi.gov, has many resources to help you with your tax needs.
- Complete electronic forms and submit them for free
- Download forms, schedules, instructions, and publications
- View answers to common questions
- Email us comments or request help TTY Equipment - Telephone help is available using TTY equipment. Call the Wisconsin Telecommunications Relay System at 711.
Publications Available
The following is a list of some of our publications. These publications give detailed information on specific areas of Wisconsin tax law. You can get these publications from our website.
Number and Title
102 Wisconsin Tax Treatment of Tax-Option (S) Corporations and Their Shareholders
103 Reporting Capital Gains and Losses for Wisconsin
106 Wisconsin Tax Information for Retirees 109 Tax Information for Married Persons Filing Separate Returns and Persons Divorced in 2025
111 How to Get a Private Letter Ruling 113 Federal and Wisconsin Income Tax Reporting Under the Marital Property Act
117 Guide to Wisconsin Wage Statements and Information Returns
120 Net Operating Losses for Individuals, Estates, and Trusts
121 Reciprocity
122 Tax Information for Part-Year Residents and Nonresidents
125 Credit for Tax Paid to Another State
126 How Your Retirement Benefits Are Taxed
128 Wisconsin Tax Information for Military Personnel and Veterans
401 Extensions of Time to File
405 Wisconsin Taxation Related to Native Americans
411 Disaster Relief
503 Wisconsin Farmland Preservation Credit
600 Wisconsin Taxation of Gambling Income
# Tax Help and Additional Forms
You can get tax help and some forms at any of the following Department of Revenue offices:
(Note: Mail completed returns to the address shown on the return.) Customer assistance: phone: (608) 266-2486 email: DORIncome@wisconsin.gov Forms requests: phone: (608) 266-1961 website: revenue.wi.gov Madison -
# Mail Stop 5-77
2135 Rimrock Rd.
PO Box 8949
Madison WI 53708-8949
Milwaukee -
State Office Bldg., 819 N. 6th St., Rm. 408 Milwaukee WI 53203-1606 Appleton -265 W. Northland Ave.
Appleton WI 54911-2016
Eau Claire -
State Office Bldg., 718 W. Clairemont Ave.
Eau Claire WI 54701-4558
Green Bay -
200 N. Jefferson St., Rm. 140 Green Bay WI 54301-5189 Wausau -Check website
Before starting your Form 1NPR, fill in your federal return and its supporting schedules. If you aren't required to file a federal return, list the types and amounts of your income and deductions on a separate sheet of paper and include it with your Form 1NPR.
Follow these line instructions to fill in your Form 1NPR. Prepare one copy to file with the department and another for your records.
■ Amended return If you already filed your original return and this is an amended return, place a check mark where indicated at the top of Form 1NPR. For more information, see Amending Your Return on page 8 of these instructions. Be sure to include a copy of Schedule AR with your amended return.
■ Period covered File the 2025 return for calendar year 2025 and fiscal years that begin in 2025. For a fiscal year (a 52-53 week period) or a short-period return, fill in the taxable year beginning and ending dates in the taxable year space at the top of the form. If your return is for a fiscal year or a short-period, also fill in "11" in the Special Conditions box located under the name and address area on page 1 of Form 1NPR.
■ Name and address Print or type your legal name and address. Include your apartment number, if any. Fill in your PO Box number only if your post office does not deliver mail to your home. If you are married filing a joint return, fill in your spouse's name (even if your spouse didn't have any income). If you filed a joint return for 2024 and you are filing a joint return for 2025 with the same spouse, be sure to enter your names and social security numbers in the same order as on your 2024 return.
If you have a foreign address, enter the city name on the appropriate line. Don't enter any other information on that line, but also complete the spaces below that line. Don't abbreviate the country name. Follow the country's practice for entering the postal code and the name of the province, state, or county.
■ Social security number Fill in your social security number. Also fill in your spouse's social security number if you are married filing a joint return or if you are married filing a separate return.
If you are an alien who has been issued an individual taxpayer identification number (ITIN), fill in your ITIN wherever your social security number is requested.
■ Special conditions Below is a list of the special condition codes that you may need to enter in the special conditions box on Form 1NPR. Be sure to read the instruction on the page listed for each code before using it. Using the wrong code or not using a code when appropriate could result in an incorrect tax computation or a delay in processing your return.
02 Extension - Combat zone (page 6)
# 03 Extension - Federally-declared disaster (page 6)
04 Divorce decree (page 7)
05 Injured spouse (page 7)
06 Single decedent or primary taxpayer if joint return (page 12) 07 Spouse deceased if joint return (page 12) 08 Both taxpayers deceased (page 12) 09 Nonresident service member (page 17) 11 Fiscal filer (page 14) 15 Military spouse (page 17) 16 Schedule RT included (Schedule M instructions, line 66) 17 Disaster relief (pages 17 and 19) 18 Extension - Live outside or military or naval service outside U.S. or Puerto Rico (page 6) 99 Multiple special conditions If more than one special condition applies, fill in "99" in the Special Conditions box and list the separate code numbers on the line next to the box, in addition to any other information required on the line.
■ Tax district Nonresidents - don't fill in these lines. Part-year and full-year residents - check the proper box and fill in the name of the Wisconsin city, village, or town in which you lived on December 31, 2025, or before leaving Wisconsin.
Also fill in the name of the county in which you lived.
■ School district number Nonresidents - don't fill in this line. Part-year and full-year residents - See the list of school district numbers on page 58. Fill in the number of the school district in which you lived on December 31, 2025, or before leaving Wisconsin.
■ Filing status Check one of the boxes to indicate your filing status for 2025. More than one filing status may apply to you. If it does, choose the one that will give you the lowest tax.
If you obtained a decree of divorce or separate maintenance during 2025 or are married and will file a separate return, you should get Publication 109, Tax Information for Married Persons Filing Separate Returns and Persons Divorced in 2025.
This publication has information on what income you must report.
Single You may check the "single" box if any of the following was true on December 31, 2025:
- You were never married
- You were legally separated under a final decree of divorce or separate maintenance. Note: A decree of separate maintenance in Wisconsin is a judgment of legal separation granted by a judge under sec. 767.35, Wis. Stats.
- You were widowed before January 1, 2025, and did not remarry in 2025 Nonresident aliens filing federal Form 1040NR You can't consider yourself single if you were married but lived apart from your spouse.
Married filing joint return Most married couples will pay less tax if they file a joint return. You may check the "married filing a joint return" box if any of the following is true.
- You were married as of December 31, 2025
- Your spouse died in 2025 and you did not remarry in 2025
- You were married at the end of 2025, and your spouse died in 2026 before filing a 2025 return A married couple may file a joint return even if only one had income or if they did not live together all year. Both spouses must sign the return, and both are responsible for any tax due on the return. This means that if one spouse does not pay the tax due, the other may have to.
You can't file a joint return if either you or your spouse were a nonresident alien at any time during 2025. You also can't file a joint return if you and your spouse have different tax years.
Exception If at the end of 2025 one spouse was a dual-status or nonresident alien and the other spouse was a U.S. citizen or a resident alien, you may be able to file a joint return. In order to file a joint return, you must elect to treat the nonresident alien spouse as a U.S. resident. If you do file a joint return, you and your spouse must report your combined worldwide income as your federal income. Note: Even though electing to be treated as a U.S. resident, the nonresident alien spouse is considered a nonresident of Wisconsin.
If you file a joint return, you may not, after the due date for filing that return, amend it to file as married filing separate return.
Married filing separate return A joint return usually produces the lowest tax, but you and your spouse may be among the few married couples for whom separate returns are better. This will require filing two returns, one for each spouse.
If you file a separate return, print or type your spouse's social security number in the space at the top of the form and full name on the line provided. If you file a separate return, you and your spouse can amend it to file as married filing a joint return within four years after the unextended due date of the return.
Head of household If you qualify to file your federal return as head of household, you may also file as head of household for Wisconsin. Unmarried individuals who paid over half the cost of keeping up a home for a qualifying person (such as a child or parent) may be able to use this filing status.
Certain married persons who lived apart from their spouse for the last 6 months of 2025 who paid over half the cost of keeping up a home that was the main home of their child, stepchild, or foster child for more than half of 2025 may be able to use this status. If you do not have to file a federal return, visit any department office or contact the department's Customer Service Bureau at (608) 266-2486 to see if you qualify. If you file your federal return as a qualifying surviving spouse, you may file your Wisconsin return as head of household.
If you qualify to file as head of household and are NOT married, check "Head of household, NOT married".
If you are married and qualify to file as head of household, be sure to check "Head of household, married". Also, fill in your spouse's social security number in the space next to the name area and fill in your spouse's name in the spaces above the head of household line.
■ Resident status Check the resident status to indicate your resident status in 2025. If you are married filing a joint return, also check one of the spaces to indicate your spouse's resident status in 2025. See the definitions on page 3.
If you are a nonresident of Wisconsin, also indicate in the space provided the 2-letter postal abbreviation for your state of legal residence. If you are a resident of a foreign country, fill in "99".
Legal residence (domicile) questionnaire If you changed your domicile from Wisconsin during 2024 or 2025 and you did not previously complete a questionnaire for that change, fill in the questionnaire at the end of these instructions.
Column A and Column B Instructions
Form 1NPR has two columns for figures.
# Column A
is labeled "Federal column." In this column, lines 1-31, fill in the amounts reported on your federal return.
If you are filing federal Form 1040NR, fill in the amounts from each line on page 1 of Form 1040NR on the corresponding line on Form 1NPR. If there is no corresponding line on Form 1NPR for an income or adjustment item, include the income item on line 15, and the adjustment item on line 28 of Form 1NPR. The amount reported on line 1k of Form 1040NR (income exempt by a treaty) should not be carried over to Form 1NPR.
Exceptions
- If you are using a different filing status for Wisconsin and federal purposes, the amounts you enter in column A cannot be taken from the federal return you file with the IRS. If you file a joint return for Wisconsin but separate returns for the IRS, report in column A the amounts you would report on a federal return using a married filing joint status. (For example, you reported $15,000 of wages on your separate federal return and your spouse reported $20,000 of wages on their separate federal return. If you file a joint Wisconsin return, report $35,000 of wages in column A.) If you file separate returns for Wisconsin but you're filing a joint return for the IRS, report in column A the amounts you would report on a federal return using a married filing separate status.
- The federal income that you must use to complete column A of Form 1NPR may not always be the same as the amount reported on your federal Form 1040 or 1040-SR. Differences between federal and Wisconsin law may occur because Wisconsin uses the federal law as amended to December 31, 2022, with certain exceptions.
A list of certain provisions of federal law that may not be used for Wisconsin purposes for 2025 can be found in the instructions for Wisconsin Schedule I. The following is a list of the items that may affect the largest number of taxpayers.
- Bonus depreciation • Student loan forgiveness
- Business interest expense deduction limitation • Entertainment, amusement, and recreation expenses If any provision of federal law that does not apply for Wisconsin affects your federal adjusted gross income, complete Wisconsin Schedule I and include it with your Form 1NPR. The amount you fill in on lines 1 through 31 and 60 of Form 1NPR (and amounts filled in on Schedule 1 on page 4 of Form 1NPR) should be the revised amount from Schedule I.
To the extent Schedule I adjustments in a prior year affect income or expense items in 2025, you must also make adjustments on Schedule I for 2025. If an adjustment was made to depreciation, amortization, or sec. 179 expense on your 2014 or later Schedule I, you may also have to make an adjustment on Schedule I for 2025. For example, you had to make an adjustment on Schedule I because Wisconsin did not allow bonus depreciation. You must continue to make an adjustment on Schedule I each year until the depreciable asset is fully depreciated or you sell or otherwise dispose of the asset. This does not apply to property that was being depreciated or amortized and was placed in service in a taxable year beginning before January 1, 2014.
You may also have to fill in Schedule I if you sold property during 2025, and the gain or loss from the sale is different for federal and Wisconsin purposes due to Schedule I adjustments made in a prior year. This does not apply to property
Column A and Column B Instructions - continued that was being depreciated or amortized and was placed in service in a taxable year beginning before January 1, 2014.
Gain or loss on such property is the same for federal and Wisconsin tax purposes. See the instructions for Schedule I for more information.
# Column B
on Form 1NPR is labeled "Wisconsin column." In this column, fill in the amounts that apply to Wisconsin.
Your federal income may include items that aren't taxable or deductible for Wisconsin, or it may not include items that are taxable or deductible for Wisconsin. Most differences between federal and Wisconsin income (called "modifications") are added to or subtracted from income on Schedule M. See the Schedule M and instructions for more information on these additions and subtractions.
Rounding off to whole dollars Form 1NPR has preprinted zeros in the place used to enter cents. All amounts filled in on the form should be rounded to the nearest dollar. Drop amounts under 50¢ and increase amounts that are 50¢ or more to the next dollar. For example, $129.39 becomes $129 and $236.50 becomes $237. When you round off, do so for all amounts. But if you need to add two or more amounts to figure the amount to fill in on a line, include cents when adding and only round off the total.
If completing the form by hand, do not use commas when filling in amounts.
Line 1 Wages, Salaries, Tips, Etc.
# Column A
Federal column Fill in the amount from line 1z of federal Form 1040 or 1040-SR.
Exception If you were a member of the U.S. uniformed services, do not include military compensation received during a period of time in which you were a nonresident of Wisconsin on line 1, federal column. If you meet this exception, fill in "09" in the Special Conditions box on page 1 of Form 1NPR. Write the amount of military compensation on the line next to the box. This does not apply to Wisconsin residents who are stationed outside Wisconsin or service members who have elected to treat Wisconsin as their state of residence under 50 U.S.C. 4001. (See page 3 for information on Armed Forces Personnel.)
# Column B
Wisconsin column Nonresidents - fill in the amount received for working in Wisconsin (see Exceptions below). If that amount differs from your Wisconsin wages on your wage statement (Form W-2), include an explanation of the difference and indicate where this income was earned. If you are retired on disability, do not fill in any disability income. Part-year and full-year residents - figure the amount received for working in and outside Wisconsin while a Wisconsin resident. Add to that figure the amount received for working in Wisconsin while a nonresident. If the total differs from your Wisconsin wages on your wage statement (Form W-2), include an explanation of the difference and indicate where this income was earned. If you are retired on disability, include the amount of disability income received while you were a Wisconsin resident.
Exceptions
■ Income of military spouse Income from services performed in Wisconsin by a nonresident spouse of a service member is not taxable to Wisconsin if the spouse is in Wisconsin solely to be with the service member serving in Wisconsin under military orders (Note: Even though the nonresident spouse's wages may not be taxable to Wisconsin, they would be taxable to the nonresident spouse's state of legal residence.) If you meet this exception, fill in "15" in the Special Conditions box on page 1 of Form 1NPR.
Nonresident military spouses may claim an exemption from Wisconsin withholding. See Form W-221, Nonresident Military Spouse Withholding Exemption.
■ Residents of Illinois, Indiana, Kentucky, or Michigan Don't include on line 1, column B, wages earned while a resident of one of these states. Under agreements with these 4 states, Wisconsin doesn't tax the wages of their residents.
If your only Wisconsin income is wages earned in Wisconsin while you were a resident of one of the above states, and you are filing to get a refund of Wisconsin tax withheld in error, fill in 0 on lines 1 and 30, column B, and line 38. Fill in the Wisconsin tax withheld from your wages on lines 58, 69, 70, and 71. Include your Wisconsin Form(s) W-2. Sign your return (both spouses if filing a joint return).
■ Disaster relief work If you are a nonresident of Wisconsin and your only Wisconsin income is from disaster relief work performed in connection with a state of emergency declared by the governor, don't include on line 1, column B, wages earned from the disaster relief work. If you are filing to get a refund of Wisconsin tax withheld in error, fill in 0 on lines 1 and 30, column B, and line 38. Fill in the Wisconsin tax withheld from your wages on lines 58, 69, 70, and 71. Sign your return (both spouses if filing a joint return). Include your Wisconsin Form(s) W-2. If you meet this exception, fill in "17" in the Special Conditions box on page 1 of Form 1NPR.
■ Nonqualified deferred compensation See the instructions for line 10, column B, for information on the taxation of income received while a nonresident of Wisconsin from a nonqualified deferred compensation plan.
Modifications If you were a member of the U.S. Armed Forces and on active duty or received disability income, you may qualify for a subtraction from Wisconsin income on Schedule M. See the Schedule M and instructions for more information.
Columns A & B
■ Treaty exemption If you filed your federal return on Form 1040NR and have wages that are exempt from federal tax by a treaty, do not include the exempt wages in either column A or column B.
Line 2 Taxable Interest
Column A
Federal column Fill in the amount from line 2b of federal Form 1040 or 1040-SR.
# Column B
Wisconsin column Nonresidents - don't fill in any amount of your interest. Exception Include your share of interest income attributable to Wisconsin and passed through from a tax-option (S) corporation, as reported to you on Wisconsin Schedule 5K-1. Note: Interest received from a land contract sale is not taxable to a nonresident of Wisconsin. Partyear and full-year residents - figure the interest received while a Wisconsin resident. For the period of time you were a nonresident, include your share of interest income attributable to Wisconsin and passed through from a tax-option (S) corporation, as reported to you on Wisconsin Schedule 5K-1.
Caution:
- If including interest reported on Schedule 2K-1, 3K-1, or 5K-1, only report the Wisconsin source amount of the amount reported in the federal column.
- If you are a shareholder of a tax-option (S) corporation or partner of a partnership that elected to be taxed at the entity level, include any interest shown on Schedule 3K-1 or 5K-1 in the Wisconsin column. Any income, gain, loss, or deduction reported on these schedules is removed on Schedule M, line 30, 32, 80, or 82.
Modifications If you received any state or municipal bond interest or U.S. government interest, you may be required to add or subtract from your Wisconsin income the amount of interest received on Schedule M. See the Schedule M instructions for more information.
Line 3 Ordinary Dividends
Column A
Federal column Fill in the amount from line 3b of federal Form 1040 or 1040-SR.
# Column B
Wisconsin column Nonresidents - don't fill in any amount of your dividends. Exception Include your share of dividend income attributable to Wisconsin and passed through from a tax-option (S) corporation as reported to you on Wisconsin Schedule 5K-1. Part-year and full-year residents - fill in the total dividends you received while a Wisconsin resident. For the period of time you were a nonresident, include your share of dividend income attributable to Wisconsin and passed through from a tax-option (S) corporation.
Caution:
- If including dividends reported on Schedule 2K-1, 3K-1, or 5K-1, only report the Wisconsin source amount of the amount reported in the federal column.
# Line 1 - Wages, Salaries, Tips, Etc. - continued
- If you are a shareholder of a tax-option (S) corporation or partner of a partnership that elected to be taxed at the entity level, include any dividends shown on Schedule 3K-1 or 5K-1 in the Wisconsin column. Any income, gain, loss, or deduction reported on these schedules is removed on Schedule M, line 30, 32, 80, or 82.
Modifications If you received any ordinary dividends from a mutual fund which invests in U.S. government securities, you may qualify for a subtraction from Wisconsin income on Schedule M. See the Schedule M instructions for more information.
Line 4 Taxable Refunds, Credits, or Offsets of State and Local Income Taxes
Column A
Federal column Fill in the amount from line 1 of federal Schedule 1 (Form 1040).
Column B
Wisconsin column Don't fill in any amount on line 4, column B. Wisconsin doesn't tax refunds, credits, or offsets of state and local income taxes.
Line 5 Alimony Received
Column A
Federal column Fill in the amount from line 2a of federal Schedule 1 (Form 1040).
Column B
Wisconsin column Nonresidents - don't fill in any amount. Part-year and full-year residents - fill in any alimony you received while a Wisconsin resident.
# Columns A & B
For divorce or separation agreements executed after December 31, 2018, or for divorce or separation agreements executed on or before December 31, 2018, and modified after that date, alimony and separate maintenance payments are no longer included in federal adjusted gross income. Do not include any amount on line 5, column A or B. However, for divorce or separation agreements which are executed prior to January 1, 2019, and not modified after that date, include any alimony or maintenance payments received in 2025 on line 5, columns A and/or B.
Line 6 Business Income or (Loss)
# Column A
Federal column Fill in the amount from line 3 of federal Schedule 1 (Form 1040).
If there is a difference between the federal and Wisconsin definition of the IRC, the difference may have to be adjusted on Schedule I. The federal column, column A, of Form 1NPR includes the amount of business income or loss allowed for Wisconsin after taking into consideration Schedule I adjustments. Some differences which may apply are:
- Bonus depreciation
- Entertainment, amusement, and recreation expenses
# Column B
Wisconsin column Nonresidents - nonresident individuals conducting business within and outside Wisconsin are taxed only on income derived in Wisconsin. The apportionment method must be used to determine income subject to tax unless the department gives permission to use separate accounting. Under this method, a business shows all income and deductions attributable to the business and assigns a part to Wisconsin based on an apportionment percentage. For detailed instructions, see Publication 122, Tax Information for Part-Year Residents and Nonresidents of Wisconsin. Partyear and full-year residents - figure the income or loss from business in and outside Wisconsin while a Wisconsin resident.
Combine with that figure the income or loss apportioned to Wisconsin while a nonresident.
Exception Income from an out-of-state business from disaster relief work performed in Wisconsin in connection with a state of emergency declared by the Governor is not taxable to Wisconsin. An out-of-state business means a sole proprietorship that, except for disaster relief work during a disaster period, was not doing business in Wisconsin during the 3 taxable years immediately preceding the disaster period or the current taxable year in which the declared state of emergency occurs. If you meet this exception, fill in "17" in the Special Conditions box on page 1 of Form 1NPR.
# Line 3 - Ordinary Dividends - continued
Modifications If the federal basis of your property isn't the same as the Wisconsin basis (not due to a difference in the adopted IRC or different federal election for Wisconsin purposes), you may qualify for a subtraction from Wisconsin income.
See the Schedule M instructions for more information.
Line 7 Capital Gain or (Loss)
Column A
Federal column Fill in the amount from line 7 of federal Form 1040 or 1040-SR.
# Column B
Wisconsin column Nonresidents - complete Schedule WD if you have capital gain or loss from Wisconsin sources (see definition of Wisconsin sources below.) If you don't, fill in 0 on line 7, column B. Part-year and full-year residents - all capital gain or loss received while you are a Wisconsin resident and capital gain or loss received from Wisconsin sources while you are a nonresident is includable in your Wisconsin income. If you have any capital gain or loss taxable to Wisconsin, complete Schedule WD to determine your taxable gain or allowable loss. If you don't, fill in 0 on line 7, column B.
All taxpayers with Wisconsin capital gain or loss - Wisconsin allows a 30% (60% in the case of farm assets) exclusion for net long-term capital gain, and limits your deduction for net capital loss to $3,000. Fill in the amount from line 27 or 28 of Schedule WD on line 7, column B, of Form 1NPR.
Exception: If you are a shareholder of a tax-option (S) corporation or partner of a partnership that elected to be taxed at the entity level, do not report the amount of capital gain or loss from Schedule 5K-1 or 3K-1 on Schedule WD and do not include these amounts in the Wisconsin column. See the Schedule WD Instructions for more information.
Wisconsin sources Capital gain or loss from Wisconsin sources includes gain or loss from the sale of land, buildings, and machinery located in Wisconsin and your share of capital gain and loss from an estate or trust, partnership, limited liability company (LLC), or tax-option (S) corporation which has been reported to you on Wisconsin Schedule 2K-1, 3K-1, or 5K-1. It also includes gain from the sale of stock acquired under an incentive stock option or employee stock purchase plan to the extent attributable to personal services performed in Wisconsin. It doesn't include losses from nonbusiness bad debts and worthless securities, and gains or losses from sales of stocks (except gain on stock acquired under an incentive stock option or employee stock purchase plan as explained above) while a nonresident.
Columns A & B
Sale of your Wisconsin home If you sold your Wisconsin home and qualify to exclude all or a portion of the gain on the sale for federal tax purposes, you may exclude the same amount for Wisconsin.
Line 8 Other Gains or (Losses)
Column A
Federal column Fill in the amount from line 4 of federal Schedule 1 (Form 1040).
# Column B
Wisconsin column Nonresidents - fill in the gain or loss from Wisconsin sources. Part-year and full-year residents - figure the gain or loss from all sources while a Wisconsin resident. Combine with that figure gain or loss from Wisconsin sources while a nonresident.
If you are a shareholder of a tax-option (S) corporation or partner of a partnership that elected to be taxed at the entity level, include the amount of other gain or loss from Schedule 5K-1 or 3K-1 in the Wisconsin column. Any income, gain, loss, or deduction reported on these schedules is removed on Schedule M, line 30, 32, 80, or 82.
Modifications If the federal basis of your property isn't the same as the Wisconsin basis (not due to a difference in the adopted IRC or different federal election for Wisconsin purposes), you may qualify for a subtraction from Wisconsin income. See the Schedule M instructions for more information.
Line 9 IRA Distributions
Column A
Federal column Fill in the amount of IRA distributions reported on line 4b of federal Form 1040 or 1040-SR.
Column B
Wisconsin column Nonresidents - don't fill in any amount on line 9, column B. Part-year and full-year residents - fill in the taxable amount of IRA distributions you received while a Wisconsin resident.
Line 6 - Business Income or (Loss) - continued
Line 10 Pensions and Annuities
Column A
Federal column Fill in the amount of pensions and annuities reported on line 5b of federal Form 1040 or 1040-SR.
# Column B
Wisconsin column Nonresidents - don't fill in any amount on line 10, column B. Part-year and full-year residents - fill in the federally taxable amount of pension and annuity income you received while a Wisconsin resident, including any benefits that may qualify for a subtraction on Wisconsin Schedule M. Wisconsin taxes pension, annuity, profit-sharing, and stock bonus plan distributions received while a Wisconsin resident even though the distributions may relate to work you did in another state.
Exception
Nonqualified retirement and deferred compensation plans Amounts received while a nonresident of Wisconsin from a nonqualified retirement plan or a nonqualified deferred compensation plan must be included in the Wisconsin column to the extent attributable to services performed as an employee in Wisconsin unless one of the following applies:
(1) The distribution is paid out in annuity form over the life expectancy of the individual or a period of not less than 10 years
(2) The distribution is paid in either an annuity or lump-sum from arrangements known commonly as "mirror" plans Modifications If you received lump-sum distributions; military and uniformed services retirement benefits; certain local, state, and federal retirement system benefits; railroad benefits; or disability income, you may be required to make an addition to Wisconsin income or qualify for a subtraction from Wisconsin income. See Schedule M instructions for more information.
Line 11 Rental Real Estate, Royalties, Partnerships, S Corporations, Trusts, Etc.
# Column A
Federal column Fill in the amount from line 5 of federal Schedule 1 (Form 1040).
CAUTION Wisconsin follows the federal treatment of passive activity losses (PALs). However, if there is a difference in the federal and Wisconsin definition of the IRC, any PAL may have to be adjusted on Schedule I to account for the difference. The federal column of Form 1NPR includes the amount of PAL allowed for Wisconsin after taking into consideration Schedule I adjustments.
Modifications
If there is a difference between federal and Wisconsin law, Schedule I should be completed to adjust for these differences. Any federal schedules or forms affected by the Schedule I adjustment (such as federal Schedule E and Form
- should be recomputed and attached to the Wisconsin return. Mark these recomputed forms or schedules "Revised for Wisconsin." The amounts recomputed under Wisconsin law are the amounts to enter in the federal column, column A, of line 11.
Tax-option (S) corporation, partnership, estate, or trust modifications If an adjustment listed on Schedule 2K-1, 3K-1, or 5K-1 is due to a difference between federal and Wisconsin law, such as bonus depreciation, this amount should be adjusted on Wisconsin Schedule I. This revised amount should be reported in the federal column of Form 1NPR.
Required Attachments Submit a copy of your Schedule 2K-1, 3K-1, or 5K-1, and all supplemental schedules by attaching them as PDF documents to your electronically filed return. If you cannot attach and submit the PDF documents with your e-filed return, you can upload the PDF documents through the department's website using Form W-RA at tap.revenue.wi.gov/WRA/.
If you cannot create PDF documents, you can mail the attachments with Form W-RA to the address listed on the form.
# Column B
Wisconsin column Nonresidents - fill in the amount of rent, royalty, partnership, tax-option (S) corporation, estate, and trust income from Wisconsin sources. If you received Schedules 2K-1, 3K-1 and/or 5K-1 with column (e) completed, use the amounts from column (e). Part-year and full-year residents - figure the amount of rent, royalty, partnership, tax-option
(S) corporation, estate, and trust income from sources in and outside Wisconsin received while a Wisconsin resident.
Combine with that figure the amount of rent, royalty, partnership, tax-option (S) corporation, estate, and trust income from Wisconsin sources received while a nonresident.
Rent, royalty, partnership, tax-option (S) corporation, estate, and trust income from Wisconsin sources includes:
- Rents and royalties from real or tangible property located in Wisconsin, such as land, buildings, and machinery.
- Profits and losses from businesses, professions, and farm operations conducted in Wisconsin, including partnerships and tax-option (S) corporations.
Line 11 - Rental Real Estate, Royalties, Partnerships, S Corporations, Trusts, Etc. - continued
- State and municipal interest
- Nonqualified distributions from Edvest and Tomorrow's Scholar college savings account
- Nonqualified distributions from ABLE accounts
- Income (lump-sum) distributions reported on federal
# Form 4972
- Excess distribution from a passive foreign investment company
- Expenses paid to or incurred with related entities
- Expenses for moving business outside of Wisconsin or the United States
- Differences in federal and Wisconsin basis of assets
Modifications
- Additional modifications may be required for tax-option (S) corporations, partnerships, estates, and trusts, including modifications for owner level adjustments, such as basis and passive loss limitations, or if any entity makes an election to be taxed at the entity level. See the Schedule M instructions for more information.
- If the federal basis of your property isn't the same as the Wisconsin basis, (not due to a difference in the adopted IRC or different federal election for Wisconsin purposes), you may qualify for a subtraction from Wisconsin income. See the Schedule M instructions for more information.
Line 12 Farm Income or (Loss)
Column A
Federal column Fill in the amount from line 6 of federal Schedule 1 (Form 1040).
# Column B
Wisconsin column Nonresidents - fill in the amount of income or loss from Wisconsin farms. Part-year and full-year residents - figure the income or loss from farms in and outside Wisconsin while a Wisconsin resident. Combine with that figure the income or loss from Wisconsin farms while a nonresident.
Modifications If the federal basis of your property isn't the same as the Wisconsin basis (not due to a difference in the adopted IRC or different federal election for Wisconsin purposes), you may qualify for a subtraction from Wisconsin income.
See the Schedule M instructions for more information.
Line 13 Unemployment Compensation
Column A
Federal column Fill in the amount of unemployment compensation from line 7 of federal Schedule 1 (Form 1040).
# Column B
Wisconsin column Nonresidents - don't fill in any amount on line 13, column B. Part-year and full-year residents - Input the unemployment compensation benefits received while a Wisconsin resident on line 13, column B. Do not include any railroad unemployment insurance benefits.
Modifications You may qualify for a subtraction from Wisconsin income. See the Schedule M instructions for line 37.
Line 14 Social Security Benefits
Column A
Federal column Fill in the amount from line 6b of federal Form 1040.
Column B
Wisconsin column Don't fill in any amount on line 14. Wisconsin does not tax social security benefits.
Line 15 Other Income
Column A
Federal column Fill in the amount from line 9 of federal Schedule 1 (Form 1040).
Column B
Wisconsin column Complete Schedule M if you have an amount on line 15, column A, or you are affected by any of the modifications listed below. See the Schedule M instructions for more information on these modifications.
# Line 15 - Other Income - continued
# Schedule M Addition Modifications (continued)
- Differences in federal and Wisconsin reporting of marital property (community) income
- Addition required for certain credits
- Farmland preservation credit
- Enterprise zone jobs credit
- Community rehabilitation program credit
- Research credits
- Manufacturing/Agriculture credit
- Business development credit
- Addition required for certain credits (continued)
- Electronics and information technology manufacturing zone credit
- Employee college savings account contribution credit
- Tax-option (S) corporation adjustments
- Tax-option (S) corporation entity level tax election adjustments
- Partnership, limited liability company, trust, or estate adjustments
- Partnership entity level tax election adjustments
Line 17 Educator Expenses
Column A
Federal column Fill in the amount from line 11 of federal Schedule 1 (Form 1040).
Column B
Wisconsin column Fill in the amount from the federal column.
Line 18 Certain Business Expenses of Reservists, Performing Artists, and Fee-Basis Government
Officials
Column A
Federal column Fill in the amount from line 12 of federal Schedule 1 (Form 1040).
Column B
Wisconsin column Fill in the amount from the federal column.
Line 19 Health Savings Account Deduction
Column A
Federal column Fill in the amount from line 13 of federal Schedule 1 (Form 1040).
Column B
Wisconsin column Fill in the amount from the federal column.
Line 20 Moving Expenses for Members of the Armed Forces The moving expense deduction is only allowed for members of the armed forces on active duty who move pursuant to a military order and incident to a permanent change of station.
Column A
Federal column Fill in the amount from line 14 of federal Schedule 1 (Form 1040).
# Column B
Wisconsin column Nonresidents - don't fill in any amount on line 20, column B. Part-year and full-year residents - fill in your expenses from line 14 of federal Schedule 1 (Form 1040) which were for moving into Wisconsin or within Wisconsin.
Don't include expenses for moving out of Wisconsin if your new domicile is outside Wisconsin. You may include expenses for moving out of Wisconsin only if you retained your Wisconsin domicile.
Line 21 Deductible Part of Self-Employment Tax
Column A
Federal column Fill in the amount from line 15 of federal Schedule 1 (Form 1040).
# Column B
Wisconsin column Fill in the allowable deduction for self-employment tax. Use the following formula to figure the deduction:
Net earnings from a trade or Deductible part of Wisconsin business taxable to Wisconsin x self-employment tax = self-employment tax Total net earnings from from line 15, deduction to line 21, a trade or business federal Schedule 1 Col. B, Form 1NPR (Form 1040) Note: If you are married filing a joint return and both you and your spouse had self-employment income, you must figure each spouse's allowable deduction separately. Fill in the total of both spouses' allowable deduction on line 21, column B, of Form 1NPR.
Line 22 Self-Employed SEP, SIMPLE, and Qualified Plans
Column A
Federal column Fill in the amount from line 16 of federal Schedule 1 (Form 1040).
# Column B
Wisconsin column Fill in the amount of the self-employed SEP, SIMPLE, and qualified plan (Keogh) deduction allowable for Wisconsin.
- Use the appropriate formula below to figure the amount of your Keogh and self-employed SEP and SIMPLE deduction allowable for Wisconsin.
- If you are married filing a joint return and both you and your spouse had a Keogh or self-employed SEP or SIMPLE deduction, you must figure each spouse's allowable deduction separately. Fill in the total of each spouse's deduction on line 22, column B, of Form 1NPR.
- If you have both a Keogh and self-employed SEP or SIMPLE deduction, figure the allowable deduction for each separately.
Fill in the total of the allowable deductions on line 22, column B, of Form 1NPR.
Formula to figure allowable Keogh deduction:
Your net earnings from a trade or Keogh deduction Keogh deduction business* taxable to Wisconsin x included in line 16, = allowable for Your total net earnings federal Schedule 1 Wisconsin to line 22, from a trade or business* (Form 1040) Col. B, Form 1NPR
- Use net earnings only from the business that has the Keogh plan.
Formula to figure allowable self-employed SEP or SIMPLE deduction:
Your wages and Self-employed SEP Self-employed net earnings from a trade or or SIMPLE deduction SEP or SIMPLE business* taxable to Wisconsin x included in line 16, = deduction allowable for Your total wages and net earnings federal Schedule 1 Wisconsin to line 22, from a trade or business* (Form 1040) Col. B, Form 1NPR
- Do not reduce your wages by losses from self-employment, and use net earnings only from the business that has the SEP or SIMPLE plan.
Line 23 Self-Employed Health Insurance Deduction
# Column A
Federal column Fill in the amount from line 17 of federal Schedule 1 (Form 1040).
# Column B
Wisconsin column Fill in the amount of the self-employed health insurance deduction allowable for Wisconsin. Use the formula below to figure the amount allowable for Wisconsin.
Your net earnings from a trade or Insurance deduction Insurance deduction business* taxable to Wisconsin x included in line 17 = allowable for Your total net earnings federal Schedule 1 Wisconsin to line 23, from a trade or business* (Form 1040) Col. B, Form 1NPR *Use net earnings only from the business that has the health insurance plan.
Note: If you are married filing a joint return and both you and your spouse had self-employment health insurance, you must figure each spouse's allowable deduction separately. Fill in the total of both spouses' allowable deduction on line 23, column B, of Form 1NPR.
See the Schedule M instructions for information on claiming a subtraction from Wisconsin income for medical care or long-term care insurance.
Line 24 Penalty on Early Withdrawal of Savings
Column A
Federal column Fill in the amount from line 18 of federal Schedule 1 (Form 1040).
Column B
Wisconsin column Nonresidents - don't fill in any amount on line 24. Part-year and full-year residents - fill in the penalty for early withdrawal of savings you paid while a Wisconsin resident.
Line 25 Alimony Paid
Column A
Federal column Fill in the amount from line 19a of federal Schedule 1 (Form 1040).
Column B
Wisconsin column Fill in the amount of alimony paid from the federal column.
# Columns A & B
For divorce or separation agreements executed after December 31, 2018, or for divorce or separation agreements executed on or before December 31, 2018, and modified after that date, alimony and separate maintenance payments are no longer deductible from federal adjusted gross income. Do not include any amount on line 25, column A or B. However, for divorce or separation agreements which are executed before January 1, 2019, and not modified after that date, deduct any alimony or maintenance payments paid in 2025 on line 25, columns A and B.
Line 26 IRA Deduction
Column A
Federal column Fill in the amount from line 20 of federal Schedule 1 (Form 1040).
# Column B
Wisconsin column Fill in the amount of IRA deduction allowable for Wisconsin.
- Use the following formula to figure your allowable IRA deduction. Note: An IRA deduction is allowable for Wisconsin only if the owner of the IRA has wages or net earnings from a trade or business taxable to Wisconsin.
- If you are married filing a joint return and both you and your spouse qualify for an IRA deduction, you must separately figure each spouse's allowable IRA deduction. Fill in the total of both your and your spouse's allowable IRA deductions in Col. B.
Your wages and Your IRA deduction IRA net earnings from a trade or from line 20, deduction allowable business* taxable to Wisconsin x federal = for Wisconsin Your total wages and net earnings Schedule 1 to line 26, Col. B, from a trade or business* (Form 1040) Form 1NPR
- Do not reduce your wages by losses from self-employment. Do not include your spouse's wages or earnings from a trade or business.
Line 27 Student Loan Interest Deduction Note: You cannot take this deduction if you, or your spouse if filing jointly, are claimed as a dependent on someone's (such as your parent's) federal tax return.
Column A
Federal column Fill in the amount from line 21 of federal Schedule 1 (Form 1040).
Column B
Wisconsin column Fill in the amount of student loan interest deduction from the federal column.
Line 28 Other Adjustments
# Column A
Federal column Fill in the total of the other adjustments (items listed below) from lines 23 and 25 of federal Schedule 1 (Form 1040).
- Archer MSA deduction
- Jury duty pay given to employer
- Reforestation amortization
- Repayment of supplemental unemployment benefits (SUB)
- Contributions to section 501(c)(18)(D) pension plans
- Attorney fees and court costs involving certain unlawful discrimination claims
- Expenses related to income from the rental of personal property
- Attorney fees and court costs in connection with an IRS award
- The value of Olympic and Paralympic medals and United States Olympics Committee prize money.
- Contributions by certain chaplains to section 403(b) plans
- Housing deduction
- Excess deductions of section 67(e) expenses from federal Schedule K-1 (Form 1041)
- Other adjustments
Column B
Wisconsin column Complete Schedule M if you have an amount on line 28, column A, or you are affected by any of the modifications listed below. See the Schedule M instructions for more information on these modifications.
# Line 26 - IRA Deduction- continued
- United States government interest
- Unemployment compensation
- Medical care insurance
- Long-term care insurance
- Tuition and fee expenses
- Private school tuition
- Contributions to an Edvest or Tomorrow's Scholar college savings account
- Distribution of earnings from Wisconsin state-sponsored college tuition programs
- Military and uniformed services retirement benefits
- Local and state retirement benefits
- Federal retirements benefits
- Railroad retirement benefits, railroad unemployment insurance, and sickness benefits
- Retirement income subtraction (credits restricted)
- $5,000 retirement income subtraction (income restricted)
- U.S. Armed Forces active duty pay
- Combat zone related death
- Adoption expenses
- Contributions to ABLE accounts
- Disability income exclusion
# Line 28 - Other Adjustments - continued
Schedule M Subtraction Modifications (continued)
- Wisconsin net operating loss deduction
- Farm loss carryover
- Certain income received by a Native American
- Sales of business assets or assets used in farming to a related person
- Recoveries of federal itemized deductions
- Repayment of income previously taxed
- Human organ donation
- Expenses paid to related entities
- Income from a related entity
- Sales of certain insurance policies
- Physician or psychiatrist grant
- Olympic, Paralympic, and Special Olympic medals and United States Olympic Committee and Special Olympic Board of Directors prize money
- AmeriCorps education awards
- Differences in federal and Wisconsin basis of assets
- Differences in federal and Wisconsin reporting of marital property (community) income
- Charitable contributions from tax-option (S) corporations
- Tax-option (S) corporation adjustments
- Tax-option (S) corporation entity level tax election adjustments
- Partnership, limited liability company, trust, or estate adjustments
- Partnership entity level tax election adjustments Line 30 Wisconsin Income Within the Wisconsin column, subtract line 29 from line 16. Fill in the result on line 30. If line 29 is more than line 16, fill in 0. Line 31 Federal Income
Within the federal column, subtract line 29 from line 16. Fill in the result on line 31. If line 29 is more than line 16, fill in 0.
Line 32 Ratio of Your Wisconsin Income to Federal Income Divide the amount on line 30, Wisconsin column, by the amount on line 31, federal column. Fill in the result on line 32. Carry your decimal to four places, rounding off to the fourth position. Don't fill in more than 1.0000 or less than zero. If the amount on line 30 or line 31 is zero, fill in 1.0000 on line 32.
Example If $14,000 is reported on line 30, Wisconsin column, and is divided by $26,000 on line 31, federal column, the result is .5384615, or rounded is .5385.
# Line 33
Fill in the larger of Wisconsin income from line 30, column B, or federal income from line 31, column A. If Wisconsin income from line 30, column B, is zero or less, fill in 0 (zero).
Note: Even though you may start the tax computation based on federal income, the tax will be later prorated based on the ratio of your Wisconsin income to federal income. The result is that you pay only the portion of the tax attributable to Wisconsin income.
# Line 34a
If you (or your spouse, if married filing a joint return) can be claimed as a dependent by another person, check line 34a.
Complete line 34b and see the "Exceptions" for line 34c.
Line 34b Aliens
If for federal tax purposes you are a dual-status or nonresident alien for 2025, check line 34b and fill in 0 on line 34c. You can't claim a standard deduction.
Exception If, at the end of 2025, one spouse was a nonresident alien or a dual-status alien and the other spouse was a U.S. citizen or a resident alien and you qualify to file a joint return (as explained in the Exception on page 15), do not check line 34b. Complete line 34c.
Line 36 Exemptions
Complete lines 36a and 36b. Fill in the number of exemptions on the lines provided. Multiply that number by the amount indicated ($700 or $250), and fill in the result on line a or b, as appropriate. Fill in the total of the amounts on lines 36a and 36b on line 36c.
# Line 36a
The exemptions allowed for you (and your spouse, if married) on line 36a are equal to:
0 - If you are single and can be claimed as a dependent on someone else's return, or if you are married filing jointly and both you and your spouse can be claimed as a dependent on someone else's return.
1 - If you are single and cannot be claimed as a dependent on someone else's return, or if you are married filing jointly and either you or your spouse (not both) can be claimed as a dependent on someone else's return.
2 - If you are married filing jointly and neither you nor your spouse can be claimed as a dependent on someone else's return.
Additional exemptions are allowed equal to the number of dependents you may claim, which is the number of dependents listed on the front of federal Form 1040 or 1040-SR. Enter an additional exemption for each dependent filled in on federal Form 1040 or 1040-SR.
# Line 36b
If you or your spouse were 65 or older on December 31, 2025, check the appropriate lines. Your number of exemptions is equal to the number of lines checked.
You may claim the $250 exemption on line 36b for you and/or your spouse only if you and/or your spouse are allowed the $700 exemption on line 36a.
# Line 34c Standard Deduction
Go to the 2025 Standard Deduction Table on page 48 to find your standard deduction. Fill in your standard deduction on line 34c. See Exceptions below.
Exceptions
■ Taxpayers who file short period returns or federal Form 4563 to claim an exclusion of income from sources within U.S. possessions - You can't claim a standard deduction. Fill in 0 on line 34c.
■ Dependents If you (or your spouse if married filing a joint return) can be claimed as a dependent for income tax purposes by another person, your standard deduction is limited. Use the worksheet below to figure your standard deduction.
If line 5 of the Standard Deduction Worksheet for Dependents multiplied by the ratio on line 32 of Form 1NPR is larger than your Wisconsin income on line 30, column B, of Form 1NPR, fill in 0 on lines 35, 38, 39, and 52 of Form 1NPR. You do not have to complete lines 36, 37, and 40-51.
- Fill in your standard deduction from table, page 48 … 1. .00
- Fill in the amount of your earned income* … 2. .00
- Addition amount … 3. 450.00
- Add lines 2 and 3. If less than $1,350, fill in $1,350 … 4. .00
- Compare lines 1 and 4. Fill in the smaller of the two amounts here and on line 34c of Form 1NPR … 5. .00
Standard Deduction Worksheet for Dependents
# Line 38 Tax
Use the amount on line 37 to find your tax in the Tax Table that starts on page 51. Find your income-level bracket and read across to the column showing your filing status to find your tax. Be sure you use the correct column in the Tax Table for your filing status. If the amount on line 37 is $100,000 or more, use the Tax Computation Worksheet on page 57 to compute your tax. Fill in your tax on line 38.
# Line 40 Wisconsin Itemized Deduction Credit
If the total of certain federal itemized deductions exceeds your Wisconsin standard deduction, you may claim the Wisconsin itemized deduction credit.
Complete Schedule 1 on page 4 of Form 1NPR to see if you can claim the credit. Schedule 1 lists the specific deductions to use from federal Schedule A (Form 1040) (see Exceptions below).
If you did not itemize deductions for federal tax purposes, use the amounts which would be deductible if you had itemized deductions. To determine the amounts to use, complete a federal Schedule A (Form 1040). Write "Wisconsin" at the top of this Schedule A and include it with Form 1NPR.
Caution: If your federal adjusted gross income has been increased or decreased in Part I of Schedule I, itemized deductions which are computed using federal adjusted gross income may require adjustment. The deductible amounts of any such items used to compute the Wisconsin itemized deduction credit must be determined by using the federal adjusted gross income computed on line 31 of Form 1NPR. Complete Part II of Schedule I to figure the amount to enter on Schedule 1 on page 4 of Form 1NPR.
Example: You made charitable contributions in 2025 in the amount of $20,000. Your charitable contributions reported on line 11 of Schedule A are $12,000 and are subject to an income limitation of 60%. Your federal adjusted gross income for federal purposes is $20,000. An adjustment to your federal adjusted gross income is required due to a difference in depreciation allowed for federal and Wisconsin purposes. The amount of federal adjusted gross income for Wisconsin purposes, as reported on line 31 of Form 1NPR, is $30,000. The amount of charitable contributions allowed as an itemized deduction for Wisconsin purposes is $18,000 ($30,000 x 60% = $18,000). Enter $18,000 on line 3 of Schedule 1. Note: The difference in this example also impacts the amount of charitable contributions carried forward to a future year and may require further adjustments on Schedule I and Schedule 1 in those years.
Exceptions Even though Schedule 1 has entry lines for medical expenses, interest paid, and gifts to charity, not all of the amounts of these items that are deducted on federal Schedule A (Form 1040) can be used for the Wisconsin itemized deduction credit. The following describes the portion of these items that may not be used to compute the Wisconsin itemized deduction credit.
- Amounts allocated to you on Schedule 5K-1 or 3K-1 by a tax-option (S) corporation or partnership if the entity elected to be taxed at the entity level.
- Medical expenses - the amount of medical care insurance and long-term care insurance claimed as a subtraction for Wisconsin. If this applies to you, complete the worksheet on the next page to figure the amount allowable, if any, for purposes of the itemized deduction credit.
Note: Any reference in the worksheet to an amount from or on federal Schedule A is after accounting for any changes reported on Schedule I for differences in the adopted IRC.
- Interest - paid to purchase a second home located outside Wisconsin
- paid to purchase a residence which is a boat
- paid to purchase or hold U.S. government securities
- Contributions and interest allocated to you by a tax-option (S) corporation if you treated the deduction as a subtraction.
# Line 40 - Wisconsin Itemized Deduction Credit - continued
Worksheet for Medical Care and Long-Term Care Insurance Expenses Claimed for Itemized Deduction Credit
- Total medical expenses from federal Schedule A (Form 1040), line 1 … 1.
- Deductible medical expenses from federal Schedule A (Form 1040), line 4 … 2.
- Total medical care insurance (MCI) deducted on federal Schedule A (Form 1040) (included in line 1 above). If none, skip to line 6 … 3.
- Ratio of MCI to total medical expenses. . Divide line 3 by line 1 (carry to 4 decimal places) … 4.
- Multiply line 2 by line 4 … 5.
- Long-term care insurance (LTCI) deducted on federal Schedule A (Form 1040) (included on line 1 above). If none, skip to line 9 … 6.
- Ratio of LTCI to total medical expenses. Divide line 6 by line 1 . (carry to 4 decimal places) … 7.
- Multiply line 2 by line 7 … 8.
- Add lines 5 and 8 … 9.
- Subtract line 9 from line 2. If zero or less, fill in 0 (zero) … 10.
- MCI subtracted on Schedule M, line 40. If none, skip to line 13 … 11.
- Subtract line 11 from line 5. If zero or less, fill in 0 (zero) … 12.
- LTCI subtracted on Schedule M, line 41. If none, skip to line 15 … 13.
- Subtract line 13 from line 8. If zero or less, fill in 0 (zero) … 14.
- Wisconsin medical expenses. Add lines 10, 12 and 14. Fill in here and on line 1 of Schedule 1 . 15. Line 41 Additional Child and Dependent Care Tax Credit Nonresidents and part-year residents - don't fill in any amount. Only full-year Wisconsin residents are eligible for the additional child and dependent care tax credit.
If you are filing a joint return and one spouse is a full-year Wisconsin resident, you may claim the additional child and dependent care tax credit.
Full-year residents - enter the amount from line 14 of Schedule WI-2441 on line 41.
What to include with your return You must include a copy of your completed Schedule WI-2441 with Form 1NPR. If you have an amount on line 13 of Schedule WI-2441, you must also submit a copy of the completed Worksheet A (found in the Schedule WI-2441 instructions). Failure to provide this information may delay your refund.
You are not required to send in any documentation of your qualifying expenses with your return; however, including copies of any payment statements received from a care provider or other documentation with your Wisconsin return may speed up the processing of your return if it is selected for review.
Line 42 Blind Worker Transportation Services Credit If you (or your spouse if filing a joint return) are blind, employed, and paid for qualifying transportation services to get to work, you may claim a credit for 50% of the expenses paid. The credit may not exceed $1,500 ($3,000 of expenses) per qualifying person.
Blind: You are considered blind if you meet the definition in section 63(f)(4), IRC, to claim the increased federal standard deduction for being blind. See the federal Form 1040 instructions for more information.
Qualifying transportation services: Any transportation services provided between a person's home (place of residence) and place of employment by means of mass transit, paratransit, taxicab, or transportation network company, as defined in s. 440.40(6), Wis. Stats.
Caution: Amounts paid for qualifying transportation services that are reimbursed to you or that are paid using funds from an ABLE account (sec. 529A, IRC) with the contribution having been subtracted from income under s. 71.05(6)(b)52., Wis.
Stats., do not qualify and are ineligible for computing the credit.
# Line 42 - Blind Worker Transportation Services Credit - continued
Step 1 Fill in the amount you paid for qualifying transportation services during 2025 on the line provided next to "Qualifying expenses". Do not enter more than $3,000 of expenses paid per qualifying person.
Step 2 Multiply the amount of your qualifying expenses (Step 1) by 50%. Fill in the result on line 42. This is your blind worker transportation services credit.
# Line 43 School Property Tax Credit
Nonresidents - don't fill in any amount on these lines. Nonresidents aren't eligible for the school property tax credit.
Note: If you are filing a joint return and one spouse is a full-year or part-year Wisconsin resident but the other is a nonresident, you can claim the school property tax credit. Figure your credit by using the rent and property taxes of both spouses.
Part-year and full-year residents - read the following instructions if you paid rent during 2025 for living quarters used as your principal home or property taxes during 2025 on your home.
Note: You may not claim the school property tax credit if you are claiming the veterans and surviving spouses property tax credit.
Special cases
If you paid both property taxes and rent You may claim both the renter's credit and the homeowner's credit. The total combined credit claimed on lines 43a and 43b can't be more than $300 ($150 if married filing a separate return or if married filing as head of household).
Married persons filing a joint return Figure your credit by using the rent and property taxes paid by both spouses.
Married persons filing separate returns or married persons filing as head of household Each spouse can claim a credit. Each of you can use only your own property taxes and rent to figure the credit. The maximum credit allowable to each spouse is $150.
Persons who jointly own a home or share rented living quarters When two or more persons (other than a married couple) jointly own a home or share rented living quarters, each may claim a credit. However, the property taxes and rent paid must be divided among the owners or occupants. See the instructions for lines 43a and 43b.
Line 43a How to Figure the Renter's School Property Tax Credit Step 1 Rent paid in 2025 Fill in on the appropriate line(s) the total rent that you paid in 2025 for living quarters (1) where the heat was included in the rent, and (2) where the heat was not included in the rent. These living quarters must have been used as your principal home but don't have to be located in Wisconsin. Don't include any rent that you may claim as a business expense. Don't include rent paid for housing that is exempt from property taxes, for example, rent for a university dorm, nonprofit senior housing, or public housing. (Property owned by a public housing authority is considered tax-exempt unless that authority makes payments in place of property taxes to the city or town in which it is located. If you live in public housing, you may wish to ask your manager about this.) If your rent included food, housekeeping, medical, or other services, reduce your rent paid in 2025 by the value of these items. If you shared living quarters with one or more persons (other than your spouse or dependents), fill in only the portion of the total rent that you paid in 2025. For example, if you and two other persons rented an apartment and paid a total rent of $6,000 in 2025, and you each paid $2,000 of the rent, each could claim a credit based on $2,000 of rent.
Step 2 Use the Renter's School Property Tax Credit Table on the next page to figure your credit. If heat was included in your rent, use column 1 of the table. If heat was not included, use column 2. Fill in your credit on line 43a.
Exception If you paid both rent where heat was included and rent where heat was not included, complete the worksheet below.
- Do not fill in more than $300 ($150 if married filing a separate return or married filing as head of household).
- Credit for rent with heat included (from Column 1 of Table on the next page) … 1.
- Credit for rent with heat not included (from Column 2 of Table on the next page) … 2.
- Add lines 1 and 2. Fill in on line 43a of Form 1NPR* … 3.
Renter's Worksheet
(Complete only if Exception described above applies)
Line 43a - How to Figure the Renter's School Property Tax Credit - continued
Renter's School Property Tax Credit Table*
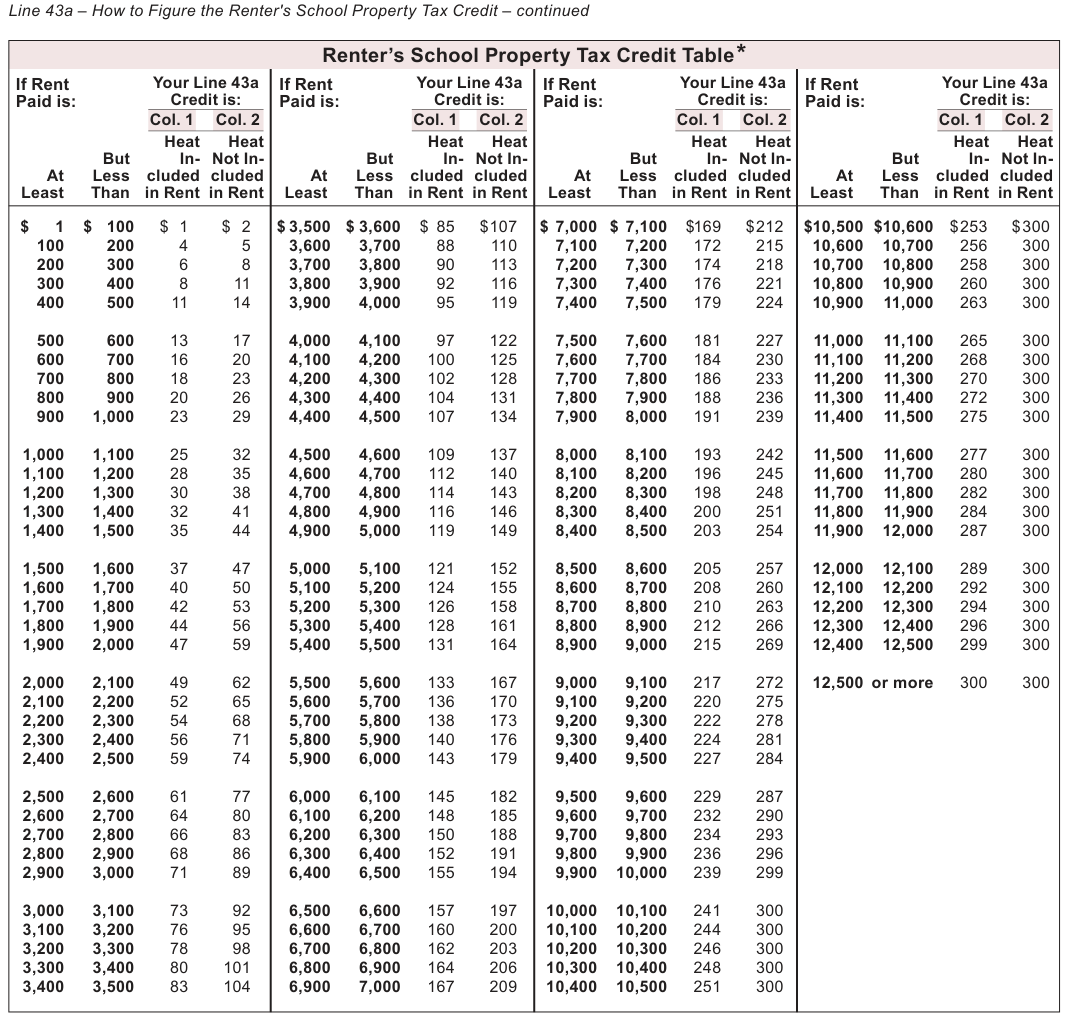
Text version of this table
| Renter’s School Property Tax Credit Table* | |||
| If Rent Your Line 43a Paid is: Credit is: Col. 1 Col. 2 Heat Heat But In- Not In- At Less cluded cluded Least Than in Rent in Rent | If Rent Your Line 43a Paid is: Credit is: Col. 1 Col. 2 Heat Heat But In- Not In- At Less cluded cluded Least Than in Rent in Rent | If Rent Your Line 43a Paid is: Credit is: Col. 1 Col. 2 Heat Heat But In- Not In- At Less cluded cluded Least Than in Rent in Rent | If Rent Your Line 43a Paid is: Credit is: Col. 1 Col. 2 Heat Heat But In- Not In- At Less cluded cluded Least Than in Rent in Rent |
| $ 1 $ 100 $ 1 $ 2 100 200 4 5 200 300 6 8 300 400 8 11 400 500 11 14 500 600 13 17 600 700 16 20 700 800 18 23 800 900 20 26 900 1,000 23 29 1,000 1,100 25 32 1,100 1,200 28 35 1,200 1,300 30 38 1,300 1,400 32 41 1,400 1,500 35 44 1,500 1,600 37 47 1,600 1,700 40 50 1,700 1,800 42 53 1,800 1,900 44 56 1,900 2,000 47 59 2,000 2,100 49 62 2,100 2,200 52 65 2,200 2,300 54 68 2,300 2,400 56 71 2,400 2,500 59 74 2,500 2,600 61 77 2,600 2,700 64 80 2,700 2,800 66 83 2,800 2,900 68 86 2,900 3,000 71 89 3,000 3,100 73 92 3,100 3,200 76 95 3,200 3,300 78 98 3,300 3,400 80 101 3,400 3,500 83 104 | $ 3,500 $ 3,600 $ 85 $ 107 3,600 3,700 88 110 3,700 3,800 90 113 3,800 3,900 92 116 3,900 4,000 95 119 4,000 4,100 97 122 4,100 4,200 100 125 4,200 4,300 102 128 4,300 4,400 104 131 4,400 4,500 107 134 4,500 4,600 109 137 4,600 4,700 112 140 4,700 4,800 114 143 4,800 4,900 116 146 4,900 5,000 119 149 5,000 5,100 121 152 5,100 5,200 124 155 5,200 5,300 126 158 5,300 5,400 128 161 5,400 5,500 131 164 5,500 5,600 133 167 5,600 5,700 136 170 5,700 5,800 138 173 5,800 5,900 140 176 5,900 6,000 143 179 6,000 6,100 145 182 6,100 6,200 148 185 6,200 6,300 150 188 6,300 6,400 152 191 6,400 6,500 155 194 6,500 6,600 157 197 6,600 6,700 160 200 6,700 6,800 162 203 6,800 6,900 164 206 6,900 7,000 167 209 | $ 7,000 $ 7,100 $1 69 $ 212 7,100 7,200 172 215 7,200 7,300 174 218 7,300 7,400 176 221 7,400 7,500 179 224 7,500 7,600 181 227 7,600 7,700 184 230 7,700 7,800 186 233 7,800 7,900 188 236 7,900 8,000 191 239 8,000 8,100 193 242 8,100 8,200 196 245 8,200 8,300 198 248 8,300 8,400 200 251 8,400 8,500 203 254 8,500 8,600 205 257 8,600 8,700 208 260 8,700 8,800 210 263 8,800 8,900 212 266 8,900 9,000 215 269 9,000 9,100 217 272 9,100 9,200 220 275 9,200 9,300 222 278 9,300 9,400 224 281 9,400 9,500 227 284 9,500 9,600 229 287 9,600 9,700 232 290 9,700 9,800 234 293 9,800 9,900 236 296 9,900 10,000 239 299 10,000 10,100 241 300 10,100 10,200 244 300 10,200 10,300 246 300 10,300 10,400 248 300 10,400 10,500 251 300 | $ 1 0,500 $1 0,600 $ 253 $300 10,600 10,700 256 300 10,700 10,800 258 300 10,800 10,900 260 300 10,900 11,000 263 300 11,000 11,100 265 300 11,100 11,200 268 300 11,200 11,300 270 300 11,300 11,400 272 300 11,400 11,500 275 300 11,500 11,600 277 300 11,600 11,700 280 300 11,700 11,800 282 300 11,800 11,900 284 300 11,900 12,000 287 300 12,000 12,100 289 300 12,100 12,200 292 300 12,200 12,300 294 300 12,300 12,400 296 300 12,400 12,500 299 300 12,500 or more 300 300 |
# Heat Heat
# Heat Heat
But In- Not In- But In- Not In-At Less cluded cluded At Less cluded cluded Least Than in Rent in Rent Least Than in Rent in Rent $ 7,000 $ 7,100 $ $ 10,500 $ 10,600 $ 169 212 $ 253 $ 300 7,100 7,200 10,600 10,700 172 215 256 300 7,200 7,300 10,700 10,800 174 218 258 300 7,300 7,400 10,800 10,900 176 221 260 300 7,400 7,500 10,900 11,000 179 224 263 300 7,500 7,600 11,000 11,100 181 227 265 300 7,600 7,700 11,100 11,200 184 230 268 300 7,700 7,800 11,200 11,300 186 233 270 300 7,800 7,900 11,300 11,400 188 236 272 300 7,900 8,000 11,400 11,500 191 239 275 300 8,000 8,100 11,500 11,600 193 242 277 300 8,100 8,200 11,600 11,700 196 245 280 300 8,200 8,300 11,700 11,800 198 248 282 300 8,300 8,400 11,800 11,900 200 251 284 300 8,400 8,500 11,900 12,000 203 254 287 300 8,500 8,600 12,000 12,100 205 257 289 300 8,600 8,700 12,100 12,200 208 260 292 300 8,700 8,800 12,200 12,300 210 263 294 300 8,800 8,900 12,300 12,400 212 266 296 300 8,900 9,000 12,400 12,500 215 269 299 300 9,000 9,100 12,500 or more 217 272 300 300 9,100 9,200 220 275 9,200 9,300 222 278 9,300 9,400 224 281 9,400 9,500 227 284 9,500 9,600 229 287 9,600 9,700 232 290 9,700 9,800 234 293 9,800 9,900 236 296 9,900 10,000 239 299 10,000 10,100 241 300 10,100 10,200 244 300 10,200 10,300 246 300 10,300 10,400 248 300 10,400 10,500 251 300 *Caution The credit allowed certain persons may be less than the amount indicated. See "Special cases" on page 31.
Line 43b How to Figure the Homeowner's School Property Tax Credit Step 1 Property taxes paid on home in 2025 Fill in the amount of property taxes you paid in 2025 on your home. Your home doesn't have to be located in Wisconsin. Do not include:
- Charges for special assessments, delinquent interest, or services that may be included on your tax bill (such as trash removal, recycling fee, or a water bill)
- Property taxes that you can claim as a business expense (for example, farm taxes or rental property taxes)
- Property taxes paid on property that is not your primary residence (such as a cottage or vacant land)
- Property taxes that you paid in any year other than 2025
Line 43b - How to Figure the Homeowner's School Property Tax Credit - continued Property taxes are further limited as follows: a. If you bought or sold your home during 2025, the property taxes of the seller and buyer are the taxes set forth for each in the closing agreement made at the sale or purchase. If the closing agreement does not divide the taxes between the seller and buyer, divide them on the basis of the number of months each owned the home. b. If you owned a mobile home during 2025, property taxes include the municipal permit fees paid to your municipality and/or the property taxes paid on your mobile home. (Payments for space rental for parking a mobile home or manufactured home should be filled in as rent on line 43a.) c. If you, or you and your spouse, owned a home jointly with one or more other persons, you may only use that portion of the property taxes which reflects your percentage of ownership. For example, if you and another person (not your spouse) jointly owned a home on which taxes of $1,500 were paid, each of you can claim a credit based on $750 of taxes.
Step 2 Use the Homeowner's School Property Tax Credit Table below to figure your credit. Fill in the amount of your credit on line 43b.
Caution If you are also claiming the renter's credit on line 43a, the total of your renter's and homeowner's credits can't be more than $300 ($150 if married filing a separate return or married filing as head of household).
Homeowner's School Property Tax Credit Table*
# If Property Taxes
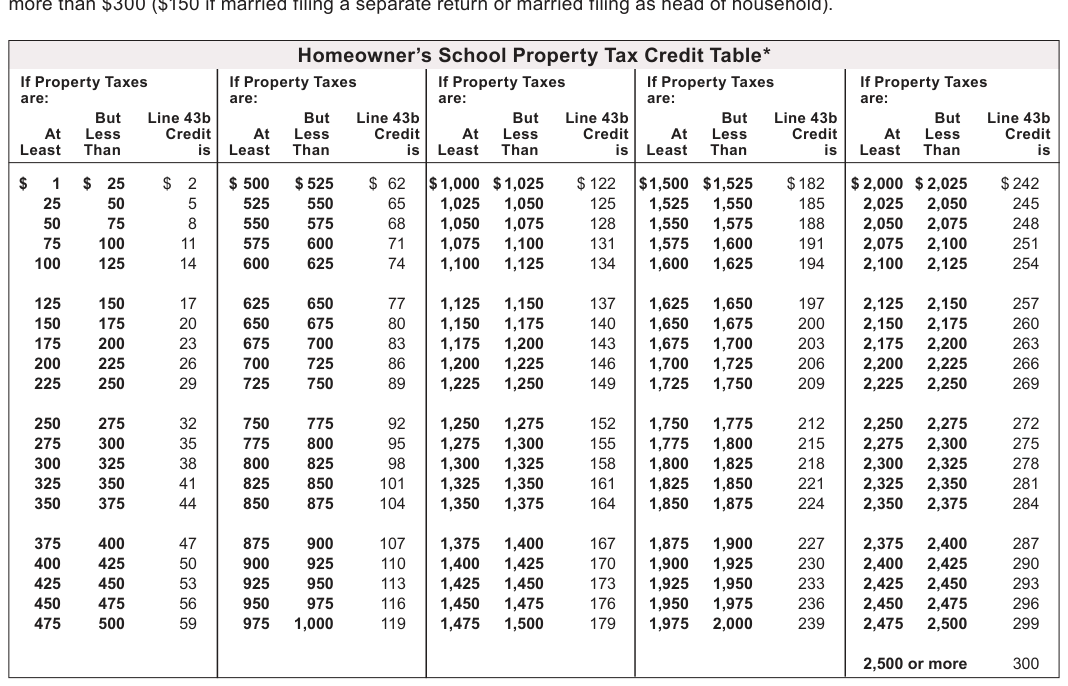
Text version of this table
| Homeowner’s School Property Tax Credit Table* | ||||
| If Property Taxes are: But Line 43b At Less Credit Least Than is | If Property Taxes are: But Line 43b At Less Credit Least Than is | If Property Taxes are: But Line 43b At Less Credit Least Than is | If Property Taxes are: But Line 43b At Less Credit Least Than is | If Property Taxes are: But Line 43b At Less Credit Least Than is |
| $ 1 $ 25 $ 2 25 50 5 50 75 8 75 100 11 100 125 14 125 150 17 150 175 20 175 200 23 200 225 26 225 250 29 250 275 32 275 300 35 300 325 38 325 350 41 350 375 44 375 400 47 400 425 50 425 450 53 450 475 56 475 500 59 | $ 500 $ 525 $ 62 525 550 65 550 575 68 575 600 71 600 625 74 625 650 77 650 675 80 675 700 83 700 725 86 725 750 89 750 775 92 775 800 95 800 825 98 825 850 101 850 875 104 875 900 107 900 925 110 925 950 113 950 975 116 975 1,000 119 | $ 1,000 $ 1,025 $ 122 1,025 1,050 125 1,050 1,075 128 1,075 1,100 131 1,100 1,125 134 1,125 1,150 137 1,150 1,175 140 1,175 1,200 143 1,200 1,225 146 1,225 1,250 149 1,250 1,275 152 1,275 1,300 155 1,300 1,325 158 1,325 1,350 161 1,350 1,375 164 1,375 1,400 167 1,400 1,425 170 1,425 1,450 173 1,450 1,475 176 1,475 1,500 179 | $ 1,500 $ 1,525 $ 182 1,525 1,550 185 1,550 1,575 188 1,575 1,600 191 1,600 1,625 194 1,625 1,650 197 1,650 1,675 200 1,675 1,700 203 1,700 1,725 206 1,725 1,750 209 1,750 1,775 212 1,775 1,800 215 1,800 1,825 218 1,825 1,850 221 1,850 1,875 224 1,875 1,900 227 1,900 1,925 230 1,925 1,950 233 1,950 1,975 236 1,975 2,000 239 | $ 2,000 $ 2,025 $242 2,025 2,050 245 2,050 2,075 248 2,075 2,100 251 2,100 2,125 254 2,125 2,150 257 2,150 2,175 260 2,175 2,200 263 2,200 2,225 266 2,225 2,250 269 2,250 2,275 272 2,275 2,300 275 2,300 2,325 278 2,325 2,350 281 2,350 2,375 284 2,375 2,400 287 2,400 2,425 290 2,425 2,450 293 2,450 2,475 296 2,475 2,500 299 2,500 or more 300 |
# Least Than is Least
# Line 43c Prorated School Property Tax Credit
Your school property tax credit is limited based on the ratio of your Wisconsin income to federal adjusted gross income.
Prorate your allowable credit using the formula below and enter on line 43c.
Sum* of lines 43a and 43b x Ratio on line 32 = Prorated credit on line 43c *Can't be more than $300 ($150 if married filing a separate return or married filing as head of household).
# Line 47 Working Families Tax Credit
Nonresidents and part-year residents - don't fill in any amount. Only full-year residents are eligible for the working families tax credit.
Note: If you are married filing a joint return and one spouse is a full-year Wisconsin resident, the resident spouse may be able to claim the working families tax credit.
Full-year residents - If you are married filing a joint return, read the instructions which follow.
Note: You may not claim the working families tax credit if you may be claimed as a dependent on another person's (for example, your parent's) income tax return.
- If the amount on line 30 of Form 1NPR is $18,000 or less, complete lines 1, 2, and 3 of the worksheet below. The amount on line 3 is your credit. Fill in the amount of your credit on line 47 of Form 1NPR.
- If the amount on line 30 of Form 1NPR is more than $18,000 but less than $19,000, use the worksheet below to compute your credit.
- If the amount on line 30 of Form 1NPR is $19,000 or more, leave line 47 blank. You do not qualify for the credit.
# Working Families Tax Credit Worksheet
Do not complete this worksheet if:
- You were a nonresident or part-year resident of Wisconsin for 2025
- Line 30 of Form 1NPR is $19,000 or more
- You may be claimed as a dependent on another person's return.
- Amount from line 46 of Form 1NPR … 1.
- Total of lines 1 through 4, column B, of Schedule CR … 2.
- Subtract line 2 from line 1 … 3.
- Fill in $19,000 … 4.
- Fill in amount from line 30 of Form 1NPR … 5.
- Subtract line 5 from line 4 … 6.
- Divide line 6 by one thousand (1,000). Fill in decimal amount … 7. .
- Multiply line 3 by line 7. This is your working families tax credit. Fill in this amount on line 47 of Form 1NPR … 8.
# Line 48 Married Couple Credit
You may claim the married couple credit if all of the following apply:
- You are married filing a joint return
- Both you and your spouse have qualified earned income taxable by Wisconsin
- You do not file federal Form 2555 or Form 2555-EZ to claim an exclusion of foreign earned income, or Form 4563 to claim an exclusion of income from sources in United States possessions To figure the credit, fill in Schedule 2 on page 4 of Form 1NPR. Figure qualified earned income separately for yourself and your spouse on lines 1 through 5 in columns (A) and (B) of Schedule 2.
"Earned income" includes taxable wages, salaries, tips, other employee compensation, scholarships and fellowships (only amounts reported on a Form W-2), disability income treated as wages, and net earnings from self-employment reported to Wisconsin. Earned income doesn't include deferred compensation (even though it may be reported on a Form W-2), interest, dividends, unemployment compensation, rental income, social security, pensions, annuities, or income that is not taxable to Wisconsin. Don't consider the Wisconsin marital property law, marital property agreements, or unilateral statements in figuring each spouse's earned income.
Example You are a member of the U.S. Armed Forces on active duty. You claimed a subtraction on line 52 of Schedule M for the amount of military pay you received for active duty. Because this military pay is not taxable to Wisconsin, it cannot be used when computing the married couple credit.
# Line 49 Nonrefundable Credits
If you are claiming any of the following credits, you must complete Schedule CR. Include Schedule CR, along with the appropriate schedule for the credit(s) you are claiming and any required Department of Commerce (DOC), Wisconsin Economic Development Corporation (WEDC), or Wisconsin Housing and Economic Development Authority (WHEDA) approval, certification, or allocation with Form 1NPR. Include Schedule CF for each credit for which you claim a carryforward of unused credit. Fill in the amount from line 34 of Schedule CR on line 49. See page 13 for information on obtaining Schedule CR.
- Postsecondary Education Credit Carryforward (Schedule CF)
- Biodiesel Fuel Production Credit Carryforward (Schedule CF)
- Health Insurance Risk-Sharing Plan Assessments Credit Carryforward (Schedule CF)
- Schedule ES - Employee College Savings Account Contribution Credit The employee college savings account contribution credit is available to employers who contribute an amount into an employee's college savings account. Complete Schedule ES.
- Schedule CM - Community Rehabilitation Program Credit The community rehabilitation program credit is available to persons who enter into a contract with a community rehabilitation program to have the program perform work for the entity. Complete Schedule CM.
- Research Facilities Credit Carryforward (Schedule CF)
- Schedule LI - Low-Income Housing Credit The low-income housing credit is available to qualified development owners who are allocated a credit amount by WHEDA. Complete Schedule LI.
- Schedule HR - Supplement to Federal Historic Rehabilitation Tax Credit The supplement to the federal historic rehabilitation tax credit is available for rehabilitating certified historic structures used for business purposes. Complete Schedule HR.
- Schedule MA-A and MA-M - Manufacturing and Agriculture Credit The manufacturing and agricultural credit is based on the production gross receipts of a business less certain expenses. Complete Schedule MA-A or MA-M. If you are a shareholder of a tax-option (S) corporation or partner of a partnership that elected to be taxed at the entity level, and the manufacturing and agricultural credit is passed through to you on Schedule 5K-1 or 3K-1, you may not claim the credit to offset tax imposed on income which is taxable to the entity. See the instructions for the Schedule MA-A or MA-M for additional limitations on the allowable credit (e.g. business income limitation).
- Schedule HR - State Historic Rehabilitation Credit An individual who has received certification or approval of a project for rehabilitating a personal residence from the State Historical Society of Wisconsin may be eligible for the credit. Complete Schedule HR.
- Schedule R - Research Credits The research credits are available for increasing research activities in Wisconsin. This includes credits related to internal combustion engines and certain energy efficient products. Complete Schedule R.
- Schedule MS - Manufacturer's Sales Tax Credit If you had an unused manufacturer's sales tax credit of $25,000 or less from 1998 through 2005 that you were unable to use for 2006-2024, complete Schedule MS to determine the amount of carryover credit you may claim.
- Manufacturing Investment Credit Carryforward (Schedule CF)
- Dairy and Livestock Farm Investment Credit Carryforward (Schedule CF)
- Ethanol and Biodiesel Fuel Pump Credit Carryforward (Schedule CF)
- Technology Zone Credit Carryforward (Schedule CF)
- Development Zones Credits Carryforward (Schedule CF)
- Capital Investment Credit Carryforward (Schedule CF)
- Economic Development Tax Credit Carryforward (Schedule CF)
- Schedule VC (Part II) - Early Stage Seed Investment Credit The early stage seed investment credit is based on an investment paid to a fund manager certified by the WEDC that the fund manager invests in a certified business. Complete Schedule VC.
- Schedule VC (Part I) - Angel Investment Credit The angel investment credit is available to accredited investors who make a bona fide angel investment in a qualified new business venture that is certified by the WEDC. Complete Schedule VC.
- Electronic Medical Records Credit Carryforward (Schedule CF)
- Internet Equipment Credit Carryforward (Schedule CF) Line 50 Credit for Net Income Tax Paid to Another State If, while a Wisconsin resident, you paid a net income tax both to Wisconsin and another state on the same income, you may be able to claim a credit for such tax. Read the Schedule OS instructions to determine if you may claim the credit. If you qualify for the credit, complete Schedule OS. Fill in the amount of your credit from Schedule OS on line 50. Be sure to enter in the space on line 50 the 2-letter postal abbreviation for the other state to which you paid tax. If you paid tax to more than one other state, fill in the number "99" in the space. See the Schedule OS instructions for other situations where additional code numbers may be required. Include Schedule OS and copies of the other state's return.
Caution Credit cannot be claimed for taxes paid to Illinois, Indiana, Kentucky, or Michigan on wages, salaries, commissions, tips, bonuses, etc. you received from employment in one of those states. Instead, file a return with that state to get a refund of any tax withheld from your wages. Be sure to explain on that state's return that you were a Wisconsin resident when earning the wages in that state. See Publication 121, Reciprocity, for more information.
Line 53 Sales and Use Tax Due on Internet, Mail Order, or Other Out-of-State Purchases If you made any taxable purchases from out-of-state firms during 2025 on which sales and use tax was not charged, you must report Wisconsin sales and use tax on these purchases on line 53 if they were stored, used, or consumed in Wisconsin. You must also report sales and use tax on taxable purchases from a retailer located in another country regardless of whether you were charged any tax for that country or any duty by the U.S. Customs Service if the items were stored, used, or consumed in Wisconsin. Taxable purchases include furniture, carpet, clothing, computers, books, CDs, DVDs, cassettes, video tapes, certain digital goods (e.g., greeting cards, video games, music, and books, transferred electronically), artwork, jewelry, most coins purchased for more than face value, etc.
Example You purchased $300 of clothing through a catalog or over the internet. No sales and use tax was charged. The clothing was delivered in a county with a 5% tax rate. You are liable for $15 Wisconsin tax ($300 x 5% = $15) on this purchase.
If you do not have sales or use tax to report on line 53, place a checkmark in the space provided to certify that you do not owe any sales or use tax. Only returns certified as "no use tax due" will be recognized as filing a sales/use tax return.
Complete the worksheet that follows to determine the amount of Wisconsin sales and use tax you are liable for on any untaxed purchases. Fill in the amount from line 4 of the worksheet on line 53 of Form 1NPR.
# Line 49 - Nonrefundable Credits - continued
Worksheet for Computing Wisconsin Sales and Use Tax
- Total purchases subject to Wisconsin sales and use tax (i.e., purchases on which no sales and use tax was charged by the seller) … $
- a) Wisconsin (state) sales and use tax rate … 5.0 b) County sales and use tax (see rate chart) … c) City sales and use tax (city of Milwaukee only, 2.0%) …
- Sales and use tax rate (sum of lines 2. a, b, and c) … x %
- Amount of sales and use tax due for 2025 (line 1 multiplied by tax rate on line 3). Round this amount to the nearest dollar and fill in on line 53 of Form 1NPR … $
# Line 53 - Sales and Use Tax Due on Internet, Mail Order, or Other Out-of-State Purchases - continued
# Line 54 Donations
Complete Part I of Schedule 3 (page 5 of Form 1NPR) if you wish to make a financial donation to one or more of the designated programs. Enter the amount from line 2 of Schedule 3, Part I on line 54 of Form 1NPR. Your donation will either reduce your refund or be added to tax due.
# Part I of Schedule 3 (Financial Donations)
Enter the amount you wish to donate to one or more of the programs listed on lines 1a through 1h. Add the amounts on lines 1a through 1h and fill in the total on line 2.
Line 1a Endangered Resources Donation With your gift, the Endangered Resources Program works to protect and manage native plant and animal species, natural communities, and other natural features. Gifts up to a predetermined amount will be matched by state general purpose revenue. Fill in the amount you want to donate on line 1a.
Line 1b Cancer Research Donation Your cancer research donation will be divided equally between the Medical College of Wisconsin, Inc., and the University of Wisconsin Carbone Cancer Center for cancer research projects. Fill in the amount you want to donate on line 1b.
Line 1c Veterans Trust Fund Donation Your donation to the Veterans Trust Fund will be used by the Wisconsin Department of Veterans Affairs for the benefit of veterans or their dependents. Fill in the amount you want to donate on line 1c.
Line 1d Multiple Sclerosis Donation Donations will be forwarded to the National Multiple Sclerosis Society to be distributed to entities located in Wisconsin that operate health-related programs for people in Wisconsin with multiple sclerosis. Fill in the amount you want to donate on line 1d.
Line 1e Military Family Relief Fund The Wisconsin Department of Military Affairs will use donations to the military family relief fund to provide financial aid to eligible members of the immediate family of members of the U.S. Armed Forces or the National Guard who are residents of Wisconsin serving on active duty. Fill in the amount you want to donate on line 1e.
Line 1f Second Harvest / Feeding America Your donation to the food banks supports efforts to feed the hungry and will be divided as follows: 65% to Feeding America Eastern Wisconsin (located in Milwaukee); 20% to Second Harvest Foodbank of Southern Wisconsin (located in Madison); and 15% to Feed My People (located in Eau Claire). The food banks provide food to food pantries, meal programs, shelters, and soup kitchens throughout the state. Fill in the amount you want to donate on line 1f.
Line 1g Red Cross Wisconsin Disaster Relief You may donate an amount to the American Red Cross for its Wisconsin Disaster Relief Fund. Fill in the amount you want to donate on line 1g.
Line 1h Special Olympics Wisconsin You may donate an amount to Special Olympics Wisconsin, Inc. Fill in the amount you want to donate on line 1h.
Amended return only - Fill in the amount of your donations from your original return. If you did not make a donation on your original return, but now wish to, or if you want to increase your donation, fill in the new amount on the appropriate line(s).
If you want to decrease the amount of your donation, you may only fill in a smaller amount if you file an amended return by October 15, 2027, or if your original return was filed after April 15, 2026, within 18 months of the date your return was filed.
# Part II of Schedule 3 (Anatomical Gift Registration)
If you are not currently on the Wisconsin Donor Registry for organ and tissue donations upon your death and wish to have your name added, complete Part II of Schedule 3. All information fields must be completed to become registered. Do NOT In Milwaukee County the county tax rate was 0.9% for 2025 If storage, use, or consumption in 2025 was in Waukesha County or Winnebago County, there was no county tax. In all other Wisconsin counties, the county tax rate was 0.5% for all of 2025 (see note).
Note: The 0.5% county tax rate only applies in Racine County to applicable purchases on or after April 1, 2025. Prior to that date there was no county tax.
# Sales and Use Tax Rate Chart
Line 54 - Donations - continued complete Part II if you are a nonresident of Wisconsin or have moved out of the state. Instead, go to donatelife.net to register in your current state of residence.
Visit donatelifewisconsin.org to learn about organ and tissue donation in Wisconsin, become a donor, update your registration information, or remove your name from the registry. Also visit the National Donor Registry Program at donatelife.net to learn about organ and tissue donation in the United States.
Line 55 Penalties on IRAs, Other Retirement Plans, MSAs, etc.
Nonresidents - don't fill in this line. Part-year and full-year residents - fill in this line if (1) you owe any of the federal penalty taxes listed below and (2) the action which caused you to owe the federal penalty tax occurred while you were a Wisconsin resident.
- Tax on IRAs, other qualified retirement plans, etc., from line 8 of federal Schedule 2 (Form 1040). Exception: Do not include any amount based on line 8 of federal Form 5329. Wisconsin does not assess a penalty on distributions from education savings accounts and ABLE accounts.
- Total tax due from lines 4, 17, 25, 33, 41, 49, 51, and 55 of federal Form 5329. Include only if the tax due on this form was paid separately and is not included on line 8 of your federal Schedule 2 (Form 1040).
- Tax on excess contributions from line 2 of federal Form 5330.
- Tax on prohibited transactions from lines 3a and 3b of federal Form 5330.
- Section 72(m)(5) excess benefits tax included on line 17j of federal Schedule 2 (Form 1040).
- Tax on Archer MSA distributions from line 9b of federal Form 8853.
- Tax on health savings account distributions from line 17b of federal Form 8889.
If you are subject to the Wisconsin penalty, fill in the total of your federal penalty taxes in the space provided on line 55.
Multiply the amount filled in by .33 (33%) and fill in the result on line 55. If you were required to file federal Form 5329 or 5330, include a copy of your Form 5329 or 5330 with your Form 1NPR.
Note: You are not subject to the penalty on payments from certain retirement plans if the payments are exempt from Wisconsin tax. See the Schedule M instructions for information on the retirement payments from local and state retirement systems and federal retirement systems that are exempt from Wisconsin tax.
# Line 56 Other Penalties
If you are subject to a penalty for selling business or farming assets purchased from a related person or inconsistent estate basis reporting, or repayment of the state historic rehabilitation credit, angel investment credit, early stage seed investment credit, supplement to federal historic rehabilitation credit, or low-income housing credit, fill in the amount of the penalty or repayment on line 56. See page 9 for more information on repayment of the credits. See below for further information on the penalties.
- Penalty for selling business assets (or assets used in farming) purchased from a related person Capital gain on the sale or disposition of business assets or on assets used in farming may be excluded from Wisconsin taxation if the assets were held more than one year and the assets are disposed of to certain related persons. The related person who purchases or otherwise receives the assets on which the gain is excluded is subject to a penalty if they sell or otherwise dispose of the assets within two years. The penalty does not apply in the case of an involuntary conversion (for example, assets are destroyed by fire or livestock dies). Visit any department office or contact our Customer Service Bureau at
(608) 266-2486 for information on how to compute the penalty.
- Penalty for underpayment of taxes due to inconsistent estate basis reporting An inconsistent estate basis reporting occurs if the property basis claimed on a Wisconsin tax return exceeds the property basis determined for federal estate tax purposes. The penalty is equal to 20% of the portion of any underpayment of taxes due to the inconsistent estate basis reporting.
# Line 58 Wisconsin Income Tax Withheld
Add the Wisconsin income tax withheld shown on your withholding statements (Forms W-2 [or W-2c if corrected], W-2G, 1042-S, 1099-G, 1099-R, 1099-MISC, and 1099-NEC or from a pass-through entity as shown on Wisconsin Schedule 2K-1, 3K-1, or 5K-1). Fill in the total on line 58. Paper clip readable copies of your withholding statements (include any Schedule 2K-1, 3K-1, or 5K-1) to page 1 of Form 1NPR.
# Line 58 - Wisconsin Income Tax Withheld - continued
Wisconsin tax withheld is shown in Box 17 of Form W-2 or Box 14 of Form 1099-R, but only if Wisconsin is the state identified in Box 15 of Form W-2 or Box 15 of Form 1099-R.
CAUTION Nonresident entertainers who are claiming credit for cash deposit or withholding from an employer, as shown on Wisconsin Form WT-11, should claim such amounts as withholding on line 58. Do not claim such amounts as estimated tax paid on line 59. Submit a copy of Form WT-11 with your Wisconsin income tax return.
DO NOT:
- Claim credit for tax withheld for other states (you must file in the other state to receive credit for the withholding)
- Claim amounts marked social security or Medicare tax withheld
- Claim credit for federal tax withheld
- Include withholding statements from other tax years
- Write on, change, or attempt to correct the amounts on your withholding statements
- Claim Wisconsin withholding from a tax-option (S) corporation or partnership, if it elected to be taxed at the entity level and claimed a refund of the pass-through withholding or a written request was submitted to apply the withholding against the tax liability at the entity level It is your responsibility to ensure that your employer or other payer has provided withholding statements that:
- Are clear and easy to read
- Show withholding was paid to Wisconsin If you do not have a withholding statement or need a corrected withholding statement, contact your employer or other payer. Line 59 2025 Wisconsin Estimated Tax Paid and Amount Applied From 2024 Return Fill in any payments you made on your 2025 estimated Wisconsin income tax (2025 Form 1-ES). This includes any extension payments made on 2025 Form 1-ES. Include any overpayment from your 2024 return that you were allowed as credit to your 2025 Wisconsin estimated tax.
Check your estimated tax payments Before filling in line 59, check the amount of your estimated tax payments on the department's website at tap.revenue.wi.gov/eslookup. Processing of your return will be delayed if there is a difference between the amount of estimated tax payments you claim and the amount the department has on record.
If you are married filing a joint return, fill in the total of:
- Any separate estimated tax payments made by each spouse
- Any joint estimated tax payments
- Any overpayments from your 2024 return(s) that you and your spouse were allowed as credit to 2025 Wisconsin estimated tax If you are filing a separate tax return, you may not claim any part of your spouse's separate estimated tax payments or credits. You and your spouse may split your joint estimated tax payments and credits between you as you choose. If you cannot agree on how joint estimated tax payments are to be split between you, the department will split them between you according to your respective income tax liabilities.
Follow these instructions even if your spouse died during 2025.
Name change If you changed your name because of marriage or divorce, and you made estimated tax payments using your former name, paper clip a statement to the front of Form 1NPR. On the statement, explain all the payments you and your spouse made for 2025 and the name(s) and social security number(s) under which you made them.
If you had withholding allocated to you from a pass-through entity, do NOT fill in such amount on line 59. Withholding from a pass-through entity should be included on line 58.
CAUTION Nonresident entertainers should claim credit for cash deposits or withholding by an employer, as shown on Wisconsin Form WT-11, as withholding on line 58. Do not claim such amounts on line 59.
# Line 60 Earned Income Credit
Nonresidents and part-year residents - don't fill in any amount. Only full-year Wisconsin residents are eligible for the Wisconsin earned income credit.
If you are filing a joint return and one spouse is a full-year Wisconsin resident, you may claim the Wisconsin earned income credit if you qualify for the federal earned income credit and you had a qualifying child.
"Federal earned income credit" means the credit computed using the IRC as adopted by Wisconsin. If you had to make adjustments to your income in Part I of Schedule I, complete Part III of Schedule I to show your recomputed federal earned income credit for Wisconsin purposes.
If you recklessly or fraudulently claim a false credit, you may be ineligible to claim any refundable credit for up to 10 years and could also owe a penalty.
Full-year residents - To claim the Wisconsin earned income credit, complete the following steps and fill in the required information in the spaces provided on line 60.
Step 1 Fill in the number of children who meet the requirements of a "qualifying child" for purposes of the federal earned income credit (see the instructions for the earned income credit in your federal return for definition of a "qualifying child").
Step 2 If you entered adjustments to federal adjusted gross income in Part I of Schedule I, fill in the earned income credit from Column II of line 1a for Part III of Schedule I. Otherwise, fill in the federal earned income credit from line 27 of federal Form 1040 or 1040-SR.
Step 3 Fill in the percentage rate which applies to you.
Number of qualifying children Fill in this (see Step 1) percentage rate 1 4% 2 11% 3 or more 34% Step 4 Multiply the amount of your federal credit (Step 2) by the percentage determined in Step 3. Fill in the result on line 60. This is your Wisconsin earned income credit.
What to include with your return You must include a copy of your completed federal Schedule EIC with Form 1NPR. If you used a paid preparer to complete your federal return, also include federal Form 8867. Failure to provide this information may delay your refund.
Note: If the IRS is computing your federal earned income credit and you want the department to compute your Wisconsin earned income credit for you, fill in the number of your qualifying children in the space provided on line 60. Write "EIC" in the space to the right of line 60. Complete your return through line 65 of Form 1NPR. Include a copy of your federal return (Form 1040 or 1040-SR) with your Form 1NPR.
# Line 61 Farmland Preservation Credit
Nonresidents and part-year residents - don't fill in any amount. Only full-year Wisconsin residents are eligible for farmland preservation credit.
Note: If you are filing a joint return and one spouse is a full-year Wisconsin resident, the resident spouse may be able to claim farmland preservation credit. Fill in the amount from line 17 of your Schedule FC on line 61a. Fill in the amount from line 13 of Schedule FC-A on line 61b. If you are claiming farmland preservation credit, include your completed Schedule FC or FC-A with your Form 1NPR.
If you recklessly or fraudulently claim a false credit, you may be ineligible to claim any refundable credit for up to 10 years and could also owe a penalty.
# Line 62 Repayment Credit
If you repaid during 2025 an amount that you included in income in an earlier year because at that time you thought you had an unrestricted right to it, you may be able to claim a credit based on the amount repaid. To qualify for the credit, the amount repaid must be over $3,000 and cannot have been subtracted in computing Wisconsin adjusted gross income or used in computing the Wisconsin itemized deduction credit.
Use the following steps to compute your credit:
(1) Refigure your tax from the earlier year without including in income the amount you repaid in 2025.
(2) Subtract the tax in (1) from the tax shown on your return for the earlier year. The difference is the amount of your credit.
Fill in the amount of your credit on line 62 of Form 1NPR. Include a statement showing how you computed your credit.
# Line 63 Homestead Credit
Nonresidents and part-year residents - don't fill in any amount. Only full-year Wisconsin residents are eligible for homestead credit.
Note: If you are filing a joint return and one spouse is a full-year Wisconsin resident, the resident spouse may be able to claim homestead credit. Fill in the amount from line 19 of Schedule H on line 63. Include your completed Schedule H with Form 1NPR.
If you recklessly or fraudulently claim a false credit, you may be ineligible to claim any refundable credit for up to 10 years and could also owe a penalty.
# Line 64 Eligible Veterans and Surviving Spouses Property Tax Credit
Nonresidents - don't fill in any amount. Only full-year and part-year residents of Wisconsin are eligible for the credit. Partyear and full-year residents - read the instructions below.
Who may claim the credit An eligible unremarried surviving spouse or an eligible veteran may claim the veterans and surviving spouses property tax credit. (Note: If you claim the veterans and surviving spouses property tax credit, you or your spouse may not claim the school property tax credit, homestead credit, or farmland preservation credit.) If you recklessly or fraudulently claim a false credit, you may be ineligible to claim any refundable credit for up to 10 years and could also owe a penalty.
An "eligible unremarried surviving spouse" means an unremarried surviving spouse, as certified by the Wisconsin Department of Veterans Affairs (WDVA), of an individual who meets all of the following conditions:
- Served on active duty in the U.S. Armed Forces or in forces incorporated as part of the U.S. Armed Forces or in the National Guard or a reserve component of the U.S. Armed Forces
- Was a resident of Wisconsin at the time of entry into active service or who had been a resident of Wisconsin for any consecutive 5-year period after entry into that active duty service
- Met one of the following conditions:
- Died while on active duty and while a resident of Wisconsin
- Was a resident of Wisconsin at the time of their death and had either a service-connected disability rating of 100% under 38 USC 1114 or 1134 or a 100% disability rating based on individual unemployability
- In the case of an individual who served in the National Guard or a reserve component, while a resident of Wisconsin died in the line of duty while on active or inactive duty for training purposes
- Was a resident of Wisconsin at the time of their death and following the individual's death, their spouse began to receive, and continues to receive, dependency and indemnity compensation, as defined in 38 USC 101(14) "Eligible veteran" means an individual who is certified by the WDVA as meeting all of the following conditions:
- Served on active duty under honorable conditions in the U.S. Armed Forces or in forces incorporated in the U.S. Armed Forces
- Was a resident of Wisconsin at the time of entry into active service or who had been a resident of Wisconsin for any consecutive 5-year period after entry into that active duty service
- Is currently a resident of Wisconsin for purposes of receiving veterans benefits under ch. 45, Wis. Stats.
- Has a service-connected disability rating of 100% under 38 USC 1114 or 1134 or a 100% disability rating based on individual unemployability Computing the credit The credit is equal to the property taxes paid by the claimant during the year on the claimant's principal dwelling in Wisconsin, exclusive of special assessments, delinquent interest, and charges for service. Do not include any property taxes that are properly includable as a trade or business expense. "Principal dwelling" means any dwelling and the land surrounding it that is reasonably necessary for use of the dwelling as a primary dwelling, but not more
# Line 60 - Repayment Credit - continued
Line 64 - Eligible Veterans and Surviving Spouses Property Tax Credit - continued than one acre. It may include a part of a multi-dwelling or multipurpose building and a part of the land upon which it is built that is used as the primary dwelling.
Example: Taxpayer received a property tax bill on the house they owned in the amount of $3,000 for the 2025 tax year on December 22, 2025. Taxpayer did not pay any of the 2024 property tax bill in 2025. Taxpayer paid the 2025 property tax bill in 2 installments:
- $1,500 on December 28, 2025
- $1,500 on April 11, 2026
The amount allowed for purposes of computing the veterans and surviving spouses property tax credit for 2025 is $1,500, which is the amount they paid on December 28, 2025. The remaining amount paid on April 11, 2026, of $1,500 may be claimed on the 2026 Wisconsin income tax return if the taxpayer is still eligible for the credit.
Complete Worksheet 1 if your principal dwelling is located on more than one acre of land.
If your property contains land assessed as a type other than residential, complete Worksheet 2. You may have to contact your municipality to find the value of land which contains multiple classifications (agricultural, undeveloped, other, etc.).
- Assessed value of land (from tax bill) … 1.
- Number of acres of land … 2.
- Divide line 1 by line 2 … 3.
- Assessed value of principal dwelling … 4.
- Add line 3 and line 4 … 5.
- Total assessed value of all land and improvements (from tax bill) … 6.
- Divide line 5 by line 6 … 7. .
- Net property taxes paid … 8.
- Multiply line 8 by line 7. This is the amount of property tax allowed for the credit … 9.
Worksheet 1 - Property Tax Bill Shows More than 1 Acre of Land
- Value of land from property tax bill, residential … 1.
- Value of land from property tax bill, other … 2.
- Value of land from property tax bill, undeveloped … 3.
- Value of land from property tax bill, agricultural … 4.
- Value of land from property tax bill, agricultural forest … 5.
- Value of land from property tax bill, forest … 6.
- Total value of land (add lines 1 through 6) … 7.
Worksheet 2 - Property Tax Bill Contains Nonresidential Land
# Part I Part II
- Value of residential land (from Part I, line 1) … 1.
- Number of acres of residential land (not less than 1.0) … 2.
- Divide line 1 by line 2 … 3.
- Value of improvements … 4.
- Add lines 3 and 4 … 5.
- Total value of all land (Part I, line 7) and improvements … 6.
- Divide line 5 by line 6 … 7. .
- Net property taxes paid … 8.
- Multiply line 8 by line 7. This is the amount of property tax allowed for the credit … 9.
# Line 64 - Eligible Veterans and Surviving Spouses Property Tax Credit - continued
If your property contains structures in addition to the primary dwelling, provide a copy of the assessor's report with the return.
If the principal dwelling on which the taxes were paid is owned by two or more persons or entities as joint tenants or tenants in common, use only that part of property taxes paid that reflects the ownership percentage of the claimant. (See
Exceptions below.)
Exceptions
- Married filing a joint return If property is owned by an eligible veteran and spouse as joint tenants, tenants in common, or as marital property, the credit is based on 100% of their combined share of property taxes paid on the principal dwelling (subject to the 1-acre limitation).
- Married filing a separate return If property is owned by an eligible veteran and spouse as joint tenants, tenants in common, or as marital property, each spouse may claim the credit based on their respective ownership interest in the eligible veteran's principal dwelling (subject to the 1-acre limitation).
If the principal dwelling is sold during the taxable year, the property taxes for the seller and buyer shall be the amount of the tax prorated to each in the closing agreement pertaining to the sale. If not provided for in the closing agreement, the tax shall be prorated between the seller and buyer in proportion to months of ownership.
If you owned and lived in a mobile home as your principal dwelling, "property taxes" include monthly mobile home municipal permit fees you paid to the municipality. If you paid the fee directly to the landowner, or community licensee, include proof of payment by the landowner or community licensee to the municipality.
If you did not own your principal dwelling but were required to pay the property taxes as rent, you may claim the credit based on the property taxes paid during the year if all of the following are met:
- The rental unit must be the principal dwelling of the eligible veteran or surviving spouse
- The principal dwelling must be located in Wisconsin
- The eligible veteran or surviving spouse is required to pay the property taxes under the rental agreement or other written agreement entered into with the landlord
- The eligible veteran or surviving spouse must pay the property taxes directly to the municipality A copy of the agreement with the landlord and proof of payment to the municipality must be included with the Wisconsin income tax return.
The credit must be claimed within 4 years of the unextended due date of the return.
Certification of eligibility for the credit If you did not claim the credit in a prior year, before claiming the credit for 2025, you must request certification from the WDVA indicating that you qualify for the credit. Use Form WDVA 2097 (which you can find in WDVA Brochure B0106) to submit your request, along with a copy of the veteran's DD Form 214 and Veterans Administration disability award letter and, if applicable, the veteran's death certificate, a marriage certificate, and a completed copy of Form WDVA 0001 (if the veteran never previously submitted one). The WDVA 0001 and the brochure are available from your county veterans service officer or on the internet at dva.wi.gov/services/housing-and-financial-services/propertytax-credit/. You may submit these forms and supporting documents to your county veterans service officer or mail them to:
Wisconsin Department of Veterans Affairs, Attn: VBRC-PTC Application, 201 W. Washington Ave., PO Box 7843, Madison WI 53707-7843. The WDVA will send you a certification of your eligibility.
Note: You do not have to obtain certification from the WDVA for 2025 if you previously received certification for a prior year.
If you still qualify for the credit, you may claim the credit but do not have to include a certification with your return.
What to include Include a copy of your property tax bill, proof of payment made in 2025, and the certification (if required) received from the WDVA with your return.
# Line 65 Refundable Credits from Schedule CR
If you are claiming any of the following refundable credits, you must complete Schedule CR. Include Schedule CR, along with the appropriate schedule for the credit(s) you are claiming and any required approval or certification from the Wisconsin Economic Development Corporation (WEDC). Fill in the amount from line 40 of Schedule CR on line 65.
See page 13 for information on obtaining Schedule CR.
- Schedule EC - Enterprise Zone Jobs Credit The enterprise zone jobs credit is available to persons doing business in an enterprise zone. The WEDC must certify the business as eligible for the credit and determine the amount of credit.
Complete Schedule EC.
- Schedule BD - Business Development Credit The credit is based on wages paid to eligible employees; training costs; and investments in personal and real property, workforce housing, and employee child care programs. The credit is available to taxpayers who are certified by the WEDC. Complete Schedule BD.
- Schedule EIT - Electronics and Information Technology Manufacturing Zone Credit The credit is based on payroll and capital expenditures in the zone. The credit is available to taxpayers who are certified by the WEDC. Complete Schedule EIT.
- Schedule R - Research Credits The research credits are available for increasing research activities in Wisconsin.
This includes credits related to internal combustion engines and certain energy efficient products. Complete Schedule R.
No interest is paid on refunds issued for the enterprise zone jobs credit, business development credit, or electronics and information technology manufacturing zone credit.
# Line 66 Amount Previously Paid
Amended return only - Complete this line only if this is an amended 2025 Form 1NPR. Fill in the amount of tax you paid with your original Form 1NPR plus any additional amounts paid after it was filed.
If you did not pay the full amount shown on your original Form 1NPR, fill in only the portion that you actually paid. Also, include any additional tax that may have resulted if your original return was changed or audited. This includes additional tax paid with a previously filed 2025 amended return and additional tax paid as a result of a department adjustment to your return. Do not include payments of interest or penalties.
# Line 68 Amount Previously Refunded
Amended return only - Complete this line only if this is an amended 2025 Form 1NPR. Fill in the refund from your original 2025 return (not including the amount applied to your 2026 estimated tax). This is generally the amount from line 71 of Form 1NPR.
If your refund was reduced because you owed underpayment interest or any penalties, fill in the amount of your refund before the reduction for underpayment interest or penalty. If your 2025 return was adjusted by the department, fill in the refund shown on the adjustment notice you received. If the adjustment notice shows a tax due rather than a refund, complete line 66 instead of line 68.
# Line 70 Amount You Overpaid
If line 69 is more than line 57, subtract line 57 from line 69 and fill in the difference on line 70. This is the amount you overpaid.
Amended return only - If the amount on line 70 (amount you overpaid) is less than the amount applied to your estimated tax on line 72, do not complete line 70. Instead, subtract line 70 from line 72 and fill in the result on line 73. This is the amount you owe.
Note: If you were required to make estimated tax payments and you did not make such payments timely, you may owe what is called "underpayment interest." You may owe underpayment interest even if you are due a refund. Read the line 74 instructions to see if you owe underpayment interest. If you owe underpayment interest and you show an overpayment on line 70, reduce the amount on line 70 by the amount of underpayment interest on line 74.
# Line 71 Refund
Fill in on line 71 the amount from line 70 that you want refunded to you. The department may not issue a refund before March 1 unless both the individual and the individual's employer have filed all required returns and forms with the department for the taxable year for which the refund was claimed.
Note: If you are divorced, see item 7 on page 7. You may be required to include a copy of your judgment of divorce with your return.
Line 65 - Refundable Credits from Schedule CR - continued
# Line 71 - Refund - continued
Note: If appropriate, we will figure interest and include it in your refund check. Interest is at a rate of 3% per year from the due date of your 2025 return. However, interest is not allowed on (1) a refund issued within 90 days of the due date of the return or within 90 days of the date an original return was filed, whichever is later, (2) a refund due from the homestead credit, enterprise zone jobs credit, business development credit, and electronics and information technology manufacturing zone credit, or (3) any portion of the refund that is applied to 2026 estimated tax.
Line 72 Amount Applied to 2026 Estimated Tax Fill in on line 72 the amount, if any, of the overpayment on line 70 you want applied to your 2025 estimated tax.
If you are married filing a joint return, we will apply the amount on line 72 to your joint estimated tax. If you are married filing a separate return, we will apply the amount on line 72 to your separate estimated tax.
Amended return only - If this is an amended return, the amount to fill in on line 72 will generally be the amount to be applied to your 2026 estimated tax from line 72 of your original Form 1NPR. However, if you file your amended return by January 15, 2027, you may increase or reduce this amount.
Line 73 Amount You Underpaid If the amount on line 57 is more than the amount on line 69, subtract line 69 from line 57 and fill in the difference on line 73.
This is the amount you underpaid.
Interest on any tax due is 12% per year from the due date of your 2025 return. If you owe any interest, figure the interest on the amount of tax you underpaid. Enter the amount of interest on line 76. Do not include amount of interest in the total on either line 73 or 75.
Amended return only - If the amount on line 57 is more than the amount on line 69, subtract line 69 from line 57 and add the amount on line 72 (amount applied to estimated tax) to the result. This is the amount you underpaid. Fill in the amount you underpaid on line 73.
If the amount you underpaid with your return is $500 or more or you made late estimated tax payments, you may also owe what is called "underpayment interest." This is an interest charge that applies when you have not prepaid enough of your tax through withholding and/or estimated tax payments. Read the line 74 instructions to see if you owe underpayment interest.
Line 74 Underpayment Interest You may owe underpayment interest if the amount of Wisconsin income tax withheld from your wages was less than your tax liability, or if you had income that was not subject to withholding and you did not make timely estimated tax payments.
In general, in each quarter of the year you should be paying enough tax through withholding payments and estimated tax payments to cover the taxes you expect to owe for the tax year. For more information on making estimated tax payments, see Estimated Tax Payments Required for Next Year on page 11.
Underpayment interest applies if either of the following occurs:
- Line 73 is at least $500 and it is more than 10% of the tax shown on your return.
- You did not pay enough estimated tax by any of the due dates. This is true even if you are due a refund.
The "tax shown on your return" is the amount on line 52 minus the amounts on lines 60 through 65.
Exceptions You will not owe underpayment interest if your 2024 tax return was for a tax year of 12 full months (or would have been had you been required to file) AND either of the following applies:
- You were a Wisconsin resident for all of 2024, and you had no tax liability for 2024.
- The amounts on lines 58 and 59 on your 2025 return are at least as much as the tax shown on your 2024 return. This exception does not apply if you did not file a 2024 Wisconsin return. Your estimated tax payments for 2025 must have been made on time and for the required amount.
The "tax shown on your 2024 return" is the amount on line 52 minus the amounts on lines 60 through 65.
# Line 74 - Underpayment Interest - continued
Fill in the exception code in the brackets to the left of line 74 if you are enclosing an application for a waiver, qualify for an exception, or are using the annualized income installment method (Part IV of Schedule U) to compute underpayment interest. See Schedule U, Underpayment of Estimated Tax by Individuals and Fiduciaries, and its instructions for further information on the exception codes.
Example Farmers and fishers are not subject to underpayment interest if two-thirds of their total gross income (gross income of both spouses if married filing a joint return) is from farming or fishing and they file their return and pay any tax due by March 2, 2026. Qualified farmers and fishers must fill in exception code "04" in the brackets to the left of line 74. Failure to fill in the exception code may result in an assessment for underpayment interest.
Figuring underpayment interest
If the Exceptions on the previous page do not apply, see Schedule U to find out if you owe underpayment interest. If you do, you can use the schedule to figure the amount. In certain situations, you may be able to lower your underpayment interest. For details, see the instructions for Schedule U. Fill in the underpayment interest from Schedule U on line 74. If you are due a refund, subtract the underpayment interest from the overpayment you show on line 70. Include Schedule U with your Form 1NPR.
Amended return only - If you were subject to underpayment interest on your original return and you are now changing the amount of such interest, include a corrected Schedule U with Form 1NPR. Fill in the appropriate exception code in the brackets on line 74 only if you are enclosing an application for a waiver, qualify for an exception, or are using the annualized income installment method (Part IV of Schedule U) to compute underpayment interest. See Schedule U instructions for the exception codes. Figure the difference between the amount of underpayment interest as reported on your original return (or as assessed by the department) and the amount of underpayment interest shown on your corrected Schedule
U. Fill in the difference on line 74. If the amount of underpayment interest is reduced, put a minus sign (−) in front of the amount on line 74.
If line 70 of Form 1NPR shows an overpayment and you are reducing the amount of underpayment interest, add the amount on line 74 to the amount on line 70 of Form 1NPR. Adjust lines 71 and 72 accordingly.
If line 73 of Form 1NPR shows an underpayment and you are reducing the amount of underpayment interest, add the amount on line 74 to the amount on line 73 of Form 1NPR. If the sum of lines 73 and 74 is greater than zero, enter the net amount on line 75. If the sum of lines 73 and 74 is less than zero, enter the net amount on line 70 as a positive number and complete lines 71 and 72 accordingly. Note: You may still owe interest (line 76) on the amount of tax you underpaid even if the sum of lines 73 and 74 is zero or an overpayment.
Line 75 Amount You Owe
Add lines 73 and 74 and enter the amount on line 75. The amount on lines 75 and 76 is the total amount you owe.
You can pay online or by check, money order, or credit card. Do not include any 2026 estimated tax payments in your check, money order, or amount you charge. Instead, make the estimated tax payments separately.
To pay online Go to the department's website at: tap.revenue.wi.gov/pay/_/.
To pay by check or money order Make your check or money order payable to the Wisconsin Department of Revenue.
Paper clip it to the front of your Form 1NPR. If the name of the taxpayer does not match the printed name on the check, print the taxpayer's name on the memo line of the check.
If you e-filed your return and are paying by check or money order, attach your payment to Form PV. Mail Form PV and your payment to the address shown on Form PV. You can get this form by using our electronic payment interactive voucher on our website.
Other payment methods You may also pay by credit card (MasterCard®, American Express®, Visa®, or Discover®), Apple Pay, or PayPal. To pay using one of these methods, go to the department's website at tap.revenue.wi.gov/pay. You will be redirected to the department's third-party processor at the appropriate step. A $1 transaction fee plus a processing fee of 2.25% will be charged by the service provider based on the amount you are paying. You will be told what the fee is during the transaction and you will have the option to either continue or cancel the transaction. For the most up to date information, see the department's webpage for Credit Card and Other Payment Options.
# Line 75 -Amount You Owe - continued
Installment payments If you cannot pay the full amount shown as due on your tax return when you file, you may ask to make installment payments to the Department of Revenue. It is generally to your advantage to pay your liability in full rather than in installments. Installment agreements with the department are subject to a $20 installment agreement fee. In addition, bills not paid in full by the due date become liable for additional interest of 18% per year and a delinquent tax collection fee of the greater of $35 or 6.5% of the unpaid amount.
For more information concerning payments, go to revenue.wi.gov/Pages/OnlineServices/Pay.aspx. To obtain the Payment Plan Request (Form A-771) go to revenue.wi.gov/DORForms/a-771.pdf. To file an installment agreement request electronically, go to revenue.wi.gov/Pages/HTML/payplan.aspx.
Note: Failure to pay your Wisconsin individual income tax may result in certification of your unpaid liability to the Treasury Offset Program. Federal law authorizes the U.S. Department of Treasury to reduce, or offset, any federal income tax refunds payable to you by the IRS to satisfy unpaid state income tax debts. Any unpaid liability will remain eligible for this offset until it is paid.
# Line 76 Interest
Interest on the amount you underpaid is 12% per year from the due date of your 2025 return. Figure the interest on the underpayment from line 73. Enter the amount of interest on line 76. Do not include this interest in the total on line 73 or 75.
■ Third party designee If you want to allow a tax preparer or tax preparation firm, family member, friend, or any other person you choose to discuss your 2025 tax return with the Department of Revenue, check "Yes" in the "Third Party Designee" area of your return. Also, enter the designee's name, phone number, and any five digits the designee chooses as a personal identification number (PIN).
If you check "Yes," you, and your spouse if filing a joint return, are authorizing the department to discuss with the designee any questions that may arise during the processing of your return. You are also authorizing the designee to:
- Give the department any information that is missing from your return
- Call the department for information about the processing of your return or the status of your refund or payment(s)
- Respond to certain department notices about math errors, offsets, and return preparation You are not authorizing the designee to receive any refund check, bind you to anything (including any additional tax liability), or otherwise represent you before the department. If you want to expand the designee's authorization, you must submit Form A-222, Power of Attorney.
The authorization will automatically end no later than the due date (without regard to extensions) for filing your 2026 tax return. This is April 15, 2027, for most people.
■ Sign and date your return Sign and date your return in the space provided on page 4. Form 1NPR is not considered a valid return unless you sign it. Your spouse must also sign if it is a joint return. Keep a copy of your return for your records.
■ Wisconsin Identity Protection PIN If you received a Wisconsin Identity Protection PIN from the Department of Revenue, enter it in the Wisconsin Identity Protection PIN spaces provided to the right of your signature. You must correctly enter all seven characters of your Wisconsin Identity Protection PIN. If you didn't receive a Wisconsin Identity Protection PIN, leave these spaces blank. Caution: This Wisconsin Identity Protection PIN is different from any Identity Protection PIN you may have received from the IRS.
If you and your spouse are filing a claim together and both the claimant and the claimant's spouse receive a Wisconsin Identity Protection PIN, enter both Wisconsin Identity Protection PINs in the spaces provided. For more information, see our Wisconsin Identity Protection PIN common questions at revenue.wi.gov/Pages/FAQS/IP-PIN.aspx.
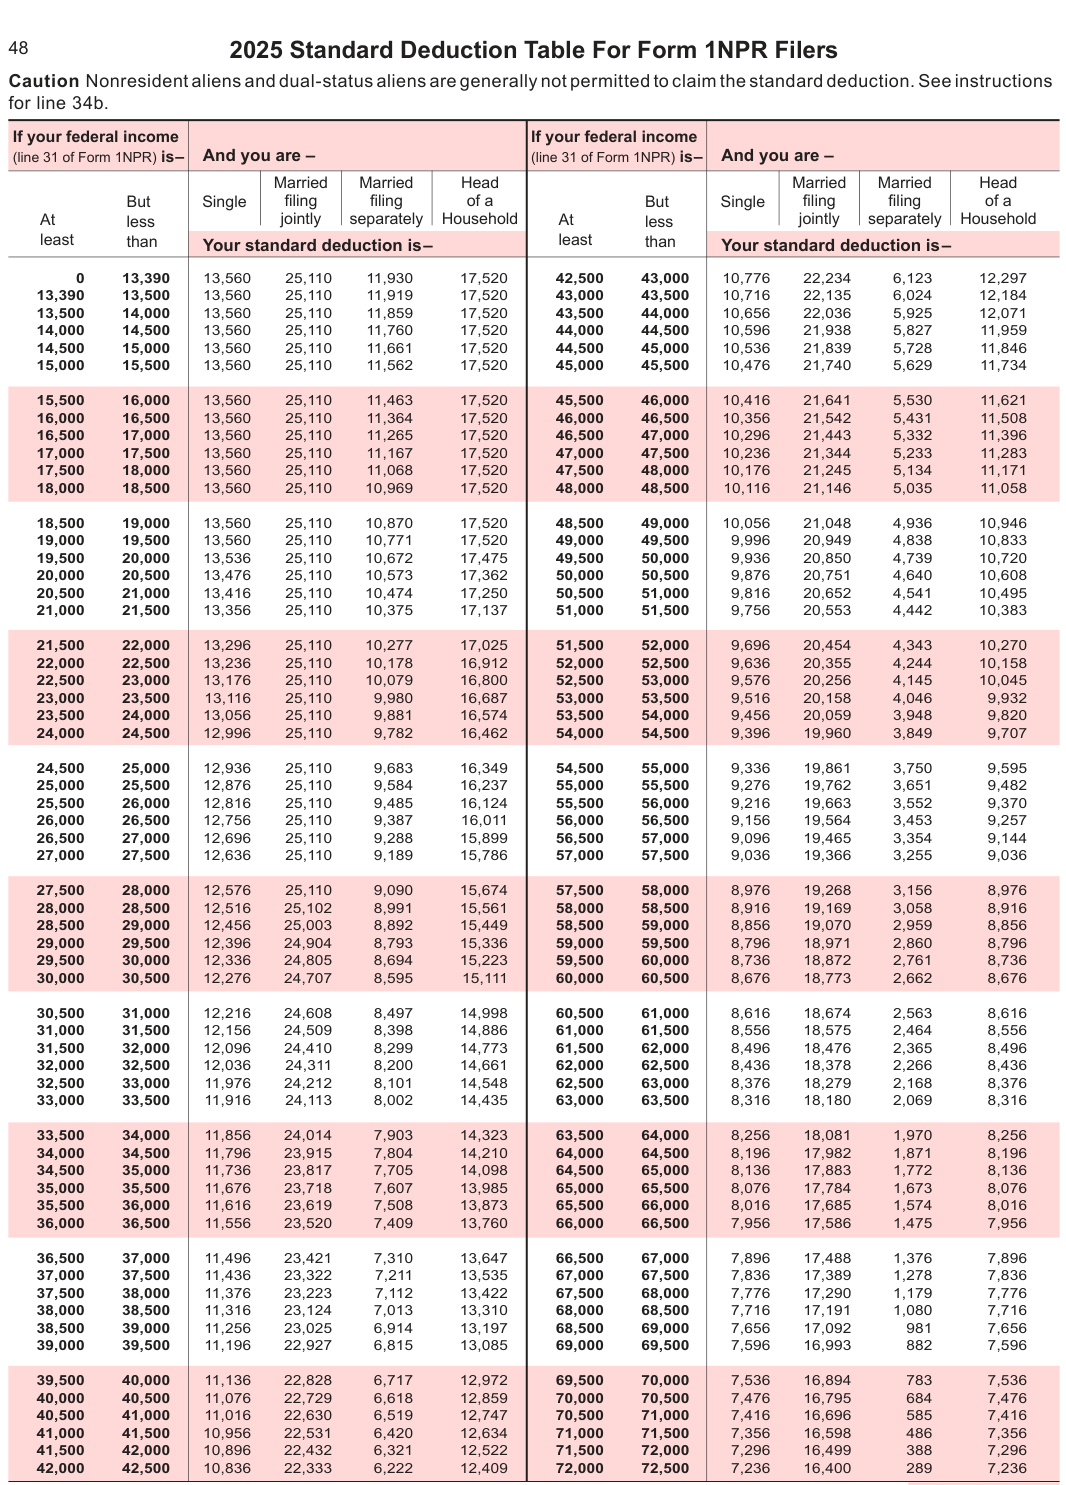
Text version of this table
| 48 | 2025 | Stand | ard Dedu | ction Ta | ble For | Form 1 | NPR Fil | ers | ||||
| Ca | ution Non | resident a | liens and d | ual-statu | s aliens are | generally n | ot permitte | d to claim | the standa | rd deduc | tion. See ins | tructi |
| for | line 34b. | |||||||||||
| If y | our federal | income | If y | our federal | income | |||||||
| (line | 31 of Form 1 | NPR) is– | And you are - | re – | (line | 31 of Form 1 | NPR) is– | And you a | re – | |||
| M | arried | Married | Head | M | arried | Married | Head | |||||
| But | Single | filing | filing | of a | But | Single | filing | filing | of a | |||
| At | less | j | ointly s | eparately Ho | usehold | At | less | j | ointly s | eparately Ho | usehol | |
| least | than | Your stan | dard dedu | ction is– | least | than | Your stan | dard dedu | ction is– | |||
| 0 | 13,390 | 13,560 | 25,110 | 11,930 | 17,520 | 42,500 | 43,000 | 10,776 | 22,234 | 6,123 | 12,297 | |
| 13,390 | 13,500 | 13,560 | 25,110 | 11,919 | 17,520 | 43,000 | 43,500 | 10,716 | 22,135 | 6,024 | 12,184 | |
| 13,500 | 14,000 | 13,560 | 25,110 | 11,859 | 17,520 | 43,500 | 44,000 | 10,656 | 22,036 | 5,925 | 12,071 | |
| 14,000 | 14,500 | 13,560 | 25,110 | 11,760 | 17,520 | 44,000 | 44,500 | 10,596 | 21,938 | 5,827 | 11,959 | |
| 14,500 | 15,000 | 13,560 | 25,110 | 11,661 | 17,520 | 44,500 | 45,000 | 10,536 | 21,839 | 5,728 | 11,846 | |
| 15,000 | 15,500 | 13,560 | 25,110 | 11,562 | 17,520 | 45,000 | 45,500 | 10,476 | 21,740 | 5,629 | 11,734 | |
| 15,500 | 16,000 | 13,560 | 25,110 | 11,463 | 17,520 | 45,500 | 46,000 | 10,416 | 21,641 | 5,530 | 11,621 | |
| 16,000 | 16,500 | 13,560 | 25,110 | 11,364 | 17,520 | 46,000 | 46,500 | 10,356 | 21,542 | 5,431 | 11,508 | |
| 16,500 | 17,000 | 13,560 | 25,110 | 11,265 | 17,520 | 46,500 | 47,000 | 10,296 | 21,443 | 5,332 | 11,396 | |
| 17,000 | 17,500 | 13,560 | 25,110 | 11,167 | 17,520 | 47,000 | 47,500 | 10,236 | 21,344 | 5,233 | 11,283 | |
| 17,500 | 18,000 | 13,560 | 25,110 | 11,068 | 17,520 | 47,500 | 48,000 | 10,176 | 21,245 | 5,134 | 11,171 | |
| 18,000 | 18,500 | 13,560 | 25,110 | 10,969 | 17,520 | 48,000 | 48,500 | 10,116 | 21,146 | 5,035 | 11,058 | |
| 18,500 | 19,000 | 13,560 | 25,110 | 10,870 | 17,520 | 48,500 | 49,000 | 10,056 | 21,048 | 4,936 | 10,946 | |
| 19,000 | 19,500 | 13,560 | 25,110 | 10,771 | 17,520 | 49,000 | 49,500 | 9,996 | 20,949 | 4,838 | 10,833 | |
| 19,500 | 20,000 | 13,536 | 25,110 | 10,672 | 17,475 | 49,500 | 50,000 | 9,936 | 20,850 | 4,739 | 10,720 | |
| 20,000 | 20,500 | 13,476 | 25,110 | 10,573 | 17,362 | 50,000 | 50,500 | 9,876 | 20,751 | 4,640 | 10,608 | |
| 20,500 | 21,000 | 13,416 | 25,110 | 10,474 | 17,250 | 50,500 | 51,000 | 9,816 | 20,652 | 4,541 | 10,495 | |
| 21,000 | 21,500 | 13,356 | 25,110 | 10,375 | 17,137 | 51,000 | 51,500 | 9,756 | 20,553 | 4,442 | 10,383 | |
| 21,500 | 22,000 | 13,296 | 25,110 | 10,277 | 17,025 | 51,500 | 52,000 | 9,696 | 20,454 | 4,343 | 10,270 | |
| 22,000 | 22,500 | 13,236 | 25,110 | 10,178 | 16,912 | 52,000 | 52,500 | 9,636 | 20,355 | 4,244 | 10,158 | |
| 22,500 | 23,000 | 13,176 | 25,110 | 10,079 | 16,800 | 52,500 | 53,000 | 9,576 | 20,256 | 4,145 | 10,045 | |
| 23,000 | 23,500 | 13,116 | 25,110 | 9,980 | 16,687 | 53,000 | 53,500 | 9,516 | 20,158 | 4,046 | 9,932 | |
| 23,500 | 24,000 | 13,056 | 25,110 | 9,881 | 16,574 | 53,500 | 54,000 | 9,456 | 20,059 | 3,948 | 9,820 | |
| 24,000 | 24,500 | 12,996 | 25,110 | 9,782 | 16,462 | 54,000 | 54,500 | 9,396 | 19,960 | 3,849 | 9,707 | |
| 24,500 | 25,000 | 12,936 | 25,110 | 9,683 | 16,349 | 54,500 | 55,000 | 9,336 | 19,861 | 3,750 | 9,595 | |
| 25,000 | 25,500 | 12,876 | 25,110 | 9,584 | 16,237 | 55,000 | 55,500 | 9,276 | 19,762 | 3,651 | 9,482 | |
| 25,500 | 26,000 | 12,816 | 25,110 | 9,485 | 16,124 | 55,500 | 56,000 | 9,216 | 19,663 | 3,552 | 9,370 | |
| 26,000 | 26,500 | 12,756 | 25,110 | 9,387 | 16,011 | 56,000 | 56,500 | 9,156 | 19,564 | 3,453 | 9,257 | |
| 26,500 | 27,000 | 12,696 | 25,110 | 9,288 | 15,899 | 56,500 | 57,000 | 9,096 | 19,465 | 3,354 | 9,144 | |
| 27,000 | 27,500 | 12,636 | 25,110 | 9,189 | 15,786 | 57,000 | 57,500 | 9,036 | 19,366 | 3,255 | 9,036 | |
| 27,500 | 28,000 | 12,576 | 25,110 | 9,090 | 15,674 | 57,500 | 58,000 | 8,976 | 19,268 | 3,156 | 8,976 | |
| 28,000 | 28,500 | 12,516 | 25,102 | 8,991 | 15,561 | 58,000 | 58,500 | 8,916 | 19,169 | 3,058 | 8,916 | |
| 28,500 | 29,000 | 12,456 | 25,003 | 8,892 | 15,449 | 58,500 | 59,000 | 8,856 | 19,070 | 2,959 | 8,856 | |
| 29,000 | 29,500 | 12,396 | 24,904 | 8,793 | 15,336 | 59,000 | 59,500 | 8,796 | 18,971 | 2,860 | 8,796 | |
| 29,500 | 30,000 | 12,336 | 24,805 | 8,694 | 15,223 | 59,500 | 60,000 | 8,736 | 18,872 | 2,761 | 8,736 | |
| 30,000 | 30,500 | 12,276 | 24,707 | 8,595 | 15,111 | 60,000 | 60,500 | 8,676 | 18,773 | 2,662 | 8,676 | |
| 30,500 | 31,000 | 12,216 | 24,608 | 8,497 | 14,998 | 60,500 | 61,000 | 8,616 | 18,674 | 2,563 | 8,616 | |
| 31,000 | 31,500 | 12,156 | 24,509 | 8,398 | 14,886 | 61,000 | 61,500 | 8,556 | 18,575 | 2,464 | 8,556 | |
| 31,500 | 32,000 | 12,096 | 24,410 | 8,299 | 14,773 | 61,500 | 62,000 | 8,496 | 18,476 | 2,365 | 8,496 | |
| 32,000 | 32,500 | 12,036 | 24,311 | 8,200 | 14,661 | 62,000 | 62,500 | 8,436 | 18,378 | 2,266 | 8,436 | |
| 32,500 | 33,000 | 11,976 | 24,212 | 8,101 | 14,548 | 62,500 | 63,000 | 8,376 | 18,279 | 2,168 | 8,376 | |
| 33,000 | 33,500 | 11,916 | 24,113 | 8,002 | 14,435 | 63,000 | 63,500 | 8,316 | 18,180 | 2,069 | 8,316 | |
| 33,500 | 34,000 | 11,856 | 24,014 | 7,903 | 14,323 | 63,500 | 64,000 | 8,256 | 18,081 | 1,970 | 8,256 | |
| 34,000 | 34,500 | 11,796 | 23,915 | 7,804 | 14,210 | 64,000 | 64,500 | 8,196 | 17,982 | 1,871 | 8,196 | |
| 34,500 | 35,000 | 11,736 | 23,817 | 7,705 | 14,098 | 64,500 | 65,000 | 8,136 | 17,883 | 1,772 | 8,136 | |
| 35,000 | 35,500 | 11,676 | 23,718 | 7,607 | 13,985 | 65,000 | 65,500 | 8,076 | 17,784 | 1,673 | 8,076 | |
| 35,500 | 36,000 | 11,616 | 23,619 | 7,508 | 13,873 | 65,500 | 66,000 | 8,016 | 17,685 | 1,574 | 8,016 | |
| 36,000 | 36,500 | 11,556 | 23,520 | 7,409 | 13,760 | 66,000 | 66,500 | 7,956 | 17,586 | 1,475 | 7,956 | |
| 36,500 | 37,000 | 11,496 | 23,421 | 7,310 | 13,647 | 66,500 | 67,000 | 7,896 | 17,488 | 1,376 | 7,896 | |
| 37,000 | 37,500 | 11,436 | 23,322 | 7,211 | 13,535 | 67,000 | 67,500 | 7,836 | 17,389 | 1,278 | 7,836 | |
| 37,500 | 38,000 | 11,376 | 23,223 | 7,112 | 13,422 | 67,500 | 68,000 | 7,776 | 17,290 | 1,179 | 7,776 | |
| 38,000 | 38,500 | 11,316 | 23,124 | 7,013 | 13,310 | 68,000 | 68,500 | 7,716 | 17,191 | 1,080 | 7,716 | |
| 38,500 | 39,000 | 11,256 | 23,025 | 6,914 | 13,197 | 68,500 | 69,000 | 7,656 | 17,092 | 981 | 7,656 | |
| 39,000 | 39,500 | 11,196 | 22,927 | 6,815 | 13,085 | 69,000 | 69,500 | 7,596 | 16,993 | 882 | 7,596 | |
| 39,500 | 40,000 | 11,136 | 22,828 | 6,717 | 12,972 | 69,500 | 70,000 | 7,536 | 16,894 | 783 | 7,536 | |
| 40,000 | 40,500 | 11,076 | 22,729 | 6,618 | 12,859 | 70,000 | 70,500 | 7,476 | 16,795 | 684 | 7,476 | |
| 40,500 | 41,000 | 11,016 | 22,630 | 6,519 | 12,747 | 70,500 | 71,000 | 7,416 | 16,696 | 585 | 7,416 | |
| 41,000 | 41,500 | 10,956 | 22,531 | 6,420 | 12,634 | 71,000 | 71,500 | 7,356 | 16,598 | 486 | 7,356 | |
| 41,500 | 42,000 | 10,896 | 22,432 | 6,321 | 12,522 | 71,500 | 72,000 | 7,296 | 16,499 | 388 | 7,296 | |
| 42,000 | 42,500 | 10,836 | 22,333 | 6,222 | 12,409 | 72,000 | 72,500 | 7,236 | 16,400 | 289 | 7,236 |
# But Single jointly separately Household
# But Single jointly separately Household
# Married Head
Married filing of a filing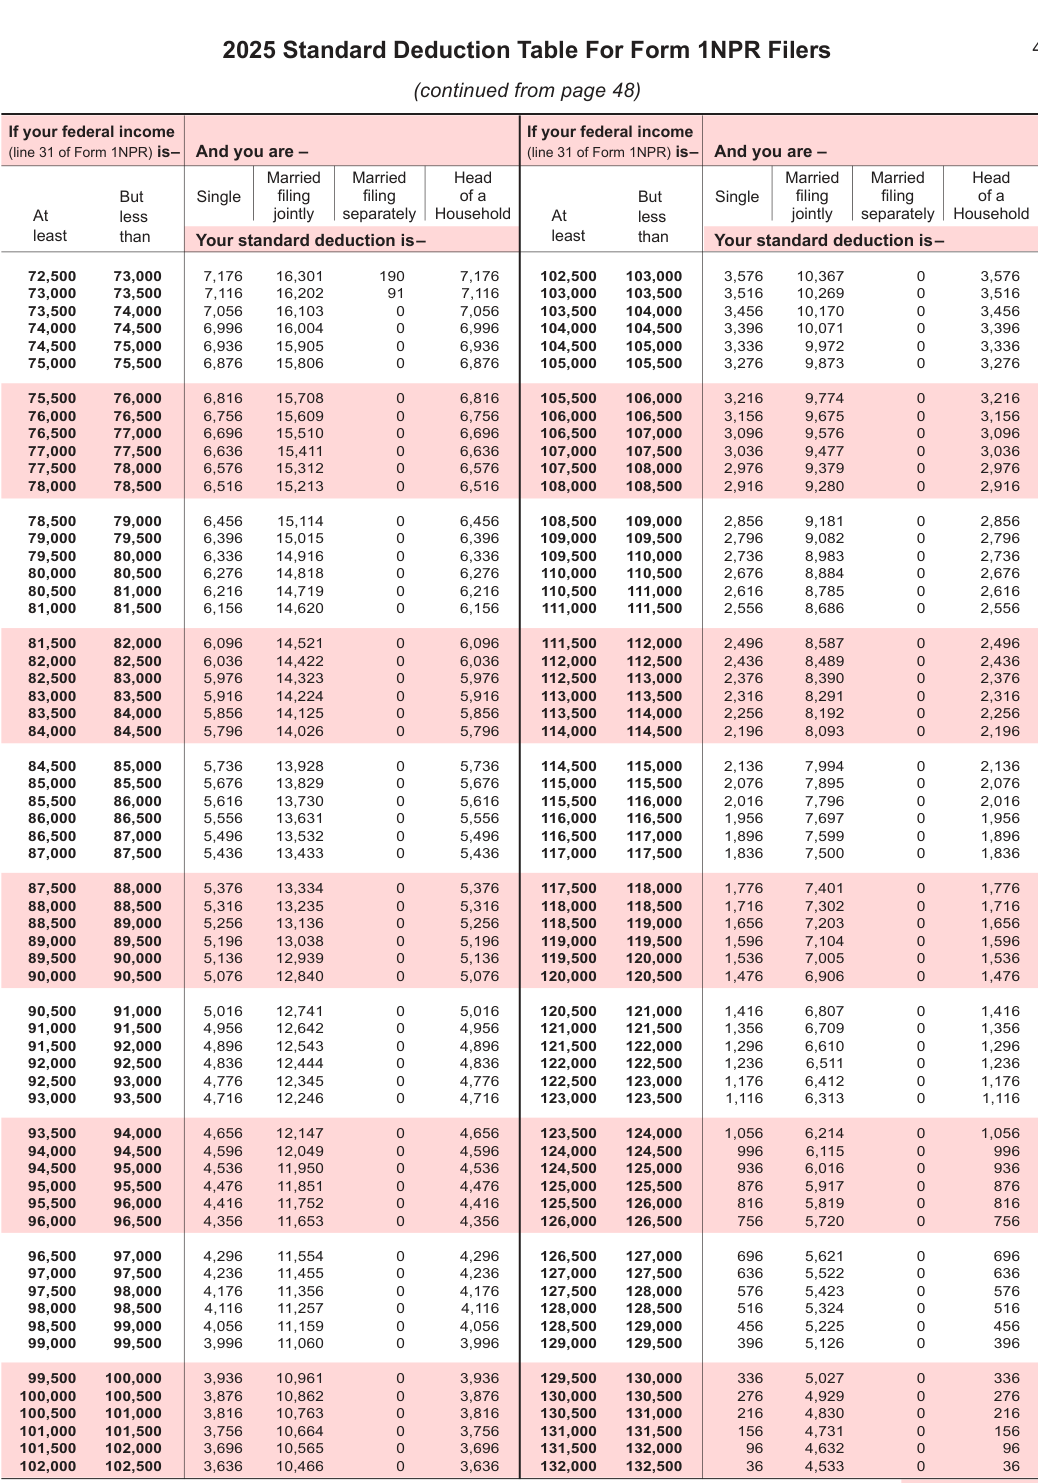
Text version of this table
2025 Stand ard Dedu ction Ta ble For Form 1 N PR F il ers (cont inued fro m page 4 8) your feder al income If your federa l income ne 31 of Form 1 NPR) is– And you a re – (li ne 31 of Form 1NPR) is– A nd you a re – M arried Married Head M arried Married H ead But Single filing filing of a But S ingle filing filing of a At less j ointly s eparately Hou sehold At less j ointly s eparately Hou sehol least than Your stan dard dedu ction is– least than Y our sta n dard dedu ction is– 72,500 7 3,000 7,176 16,301 190 7,176 102,500 103,000 3,576 10,367 0 3,576 73,000 7 3,500 7,116 16,202 91 7,116 103,000 103,500 3,516 10,269 0 3,516 73,500 7 4,000 7,056 16,103 0 7,056 103,500 104,000 3,456 10,170 0 3,456 74,000 7 4,500 6,996 16,004 0 6,996 104,000 104,500 3,396 10,071 0 3,396 74,500 7 5,000 6,936 15,905 0 6,936 104,500 105,000 3,336 9,972 0 3,336 75,000 7 5,500 6,876 15,806 0 6,876 105,000 105,500 3,276 9,873 0 3,276 75,500 7 6,000 6,816 15,708 0 6,816 105,500 106,000 3,216 9,774 0 3,216 76,000 7 6,500 6,756 15,609 0 6,756 106,000 106,500 3,156 9,675 0 3,156 76,500 7 7,000 6,696 15,510 0 6,696 106,500 107,000 3,096 9,576 0 3,096 77,000 7 7,500 6,636 15,411 0 6,636 107,000 107,500 3,036 9,477 0 3,036 77,500 7 8,000 6,576 15,312 0 6,576 107,500 108,000 2,976 9,379 0 2,976 78,000 7 8,500 6,516 15,213 0 6,516 108,000 108,500 2,916 9,280 0 2,916 78,500 7 9,000 6,456 15,114 0 6,456 108,500 109,000 2,856 9,181 0 2,856 79,000 7 9,500 6,396 15,015 0 6,396 109,000 109,500 2,796 9,082 0 2,796 79,500 8 0,000 6,336 14,916 0 6,336 109,500 110,000 2,736 8,983 0 2,736 80,000 8 0,500 6,276 14,818 0 6,276 110,000 110,500 2,676 8,884 0 2,676 80,500 8 1,000 6,216 14,719 0 6,216 110,500 111,000 2,616 8,785 0 2,616 81,000 8 1,500 6,156 14,620 0 6,156 111,000 111,500 2,556 8,686 0 2,556 81,500 8 2,000 6,096 14,521 0 6,096 111,500 112,000 2,496 8,587 0 2,496 82,000 8 2,500 6,036 14,422 0 6,036 112,000 112,500 2,436 8,489 0 2,436 82,500 8 3,000 5,976 14,323 0 5,976 112,500 113,000 2,376 8,390 0 2,376 83,000 8 3,500 5,916 14,224 0 5,916 113,000 113,500 2,316 8,291 0 2,316 83,500 8 4,000 5,856 14,125 0 5,856 113,500 114,000 2,256 8,192 0 2,256 84,000 8 4,500 5,796 14,026 0 5,796 114,000 114,500 2,196 8,093 0 2,196 84,500 8 5,000 5,736 13,928 0 5,736 114,500 115,000 2,136 7,994 0 2,136 85,000 8 5,500 5,676 13,829 0 5,676 115,000 115,500 2,076 7,895 0 2,076 85,500 8 6,000 5,616 13,730 0 5,616 115,500 116,000 2,016 7,796 0 2,016 86,000 8 6,500 5,556 13,631 0 5,556 116,000 116,500 1,956 7,697 0 1,956 86,500 8 7,000 5,496 13,532 0 5,496 116,500 117,000 1,896 7,599 0 1,896 87,000 8 7,500 5,436 13,433 0 5,436 117,000 117,500 1,836 7,500 0 1,836 87,500 8 8,000 5,376 13,334 0 5,376 117,500 118,000 1,776 7,401 0 1,776 88,000 8 8,500 5,316 13,235 0 5,316 118,000 118,500 1,716 7,302 0 1,716 88,500 8 9,000 5,256 13,136 0 5,256 118,500 119,000 1,656 7,203 0 1,656 89,000 8 9,500 5,196 13,038 0 5,196 119,000 119,500 1,596 7,104 0 1,596 89,500 9 0,000 5,136 12,939 0 5,136 119,500 120,000 1,536 7,005 0 1,536 90,000 9 0,500 5,076 12,840 0 5,076 120,000 120,500 1,476 6,906 0 1,476 90,500 9 1,000 5,016 12,741 0 5,016 120,500 121,000 1,416 6,807 0 1,416 91,000 9 1,500 4,956 12,642 0 4,956 121,000 121,500 1,356 6,709 0 1,356 91,500 9 2,000 4,896 12,543 0 4,896 121,500 122,000 1,296 6,610 0 1,296 92,000 9 2,500 4,836 12,444 0 4,836 122,000 122,500 1,236 6,511 0 1,236 92,500 9 3,000 4,776 12,345 0 4,776 122,500 123,000 1,176 6,412 0 1,176 93,000 9 3,500 4,716 12,246 0 4,716 123,000 123,500 1,116 6,313 0 1,116 93,500 9 4,000 4,656 12,147 0 4,656 123,500 124,000 1,056 6,214 0 1,056 94,000 9 4,500 4,596 12,049 0 4,596 124,000 124,500 996 6,115 0 996 94,500 9 5,000 4,536 11,950 0 4,536 124,500 125,000 936 6,016 0 936 95,000 9 5,500 4,476 11,851 0 4,476 125,000 125,500 876 5,917 0 876 95,500 9 6,000 4,416 11,752 0 4,416 125,500 126,000 816 5,819 0 816 96,000 9 6,500 4,356 11,653 0 4,356 126,000 126,500 756 5,720 0 756 96,500 9 7,000 4,296 11,554 0 4,296 126,500 127,000 696 5,621 0 696 97,000 9 7,500 4,236 11,455 0 4,236 127,000 127,500 636 5,522 0 636 97,500 9 8,000 4,176 11,356 0 4,176 127,500 128,000 576 5,423 0 576 98,000 9 8,500 4,116 11,257 0 4,116 128,000 128,500 516 5,324 0 516 98,500 9 9,000 4,056 11,159 0 4,056 128,500 129,000 456 5,225 0 456 99,000 9 9,500 3,996 11,060 0 3,996 129,000 129,500 396 5,126 0 396 99,500 10 0,000 3,936 10,961 0 3,936 129,500 130,000 336 5,027 0 336 100,000 10 0,500 3,876 10,862 0 3,876 130,000 130,500 276 4,929 0 276 100,500 10 1,000 3,816 10,763 0 3,816 130,500 131,000 216 4,830 0 216 101,000 10 1,500 3,756 10,664 0 3,756 131,000 131,500 156 4,731 0 156 101,500 10 2,000 3,696 10,565 0 3,696 131,500 132,000 96 4,632 0 96 102,000 10 2,500 3,636 10,466 0 3,636 132,000 132,500 36 4,533 0 36
And you are -
(line 31 of Form 1NPR) is-
# Married Head
50 2025 Standard Deduction Table For Form 1NPR Filers
If your federal income
And you are -
(line 31 of Form 1NPR) is-
(continued from page 49)
If your federal income
And you are -
(line 31 of Form 1NPR) is-
Married
Married filing
# But Single
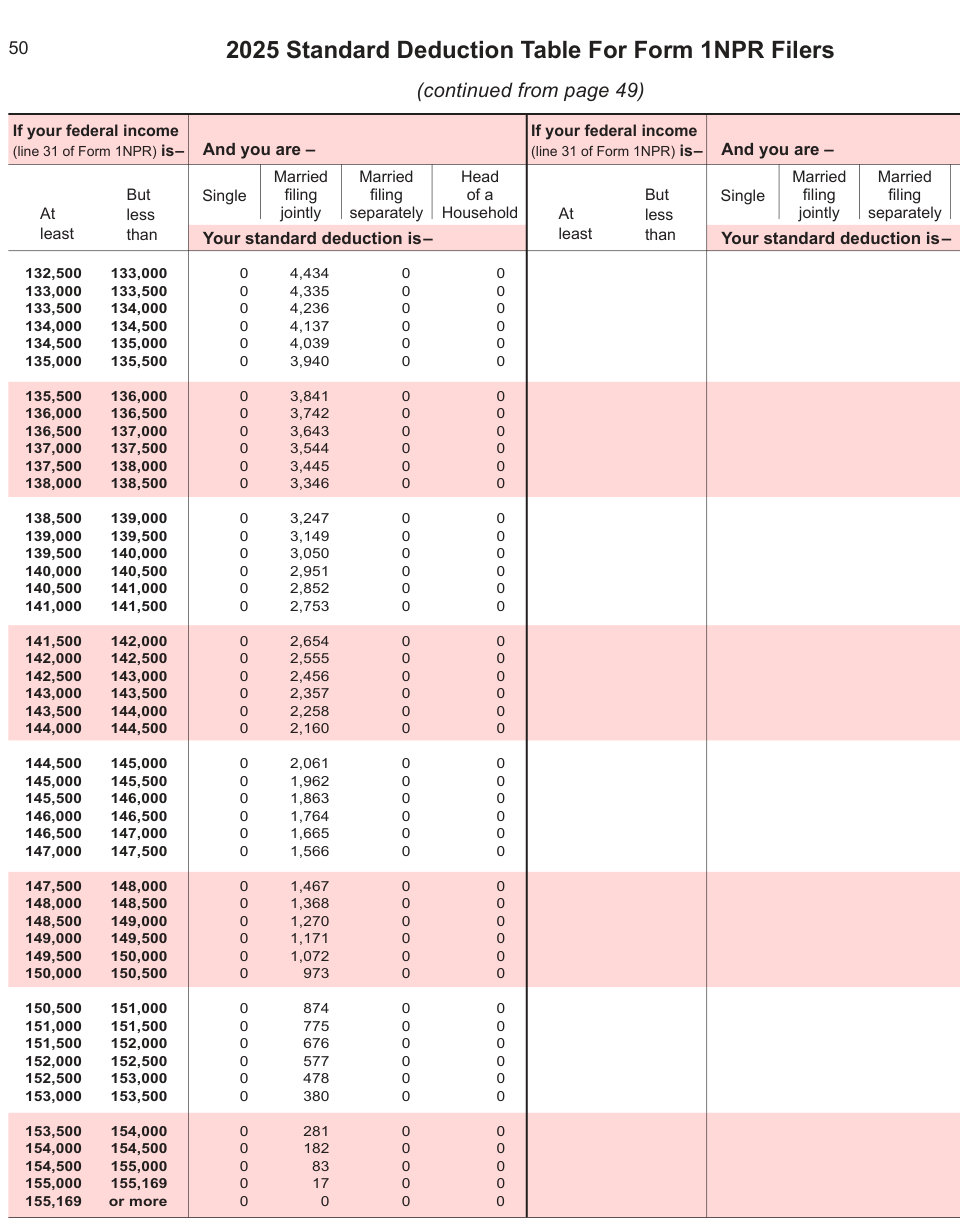
Text version of this table
2 025 Stand ard Deductio n Table For F orm 1NPR Filers (continue d from page 49) your federa l income If your federal i ncome ne 31 of Form 1NPR) is– And you are – (line 31 of Form 1 NPR) is– And you are – Married Marrie d Head Married Married But Singl e filing filing of a But Single filing filing At less jointly separat ely Househ old At less jointly separately least than Your sta ndard ded uction is– least than Your standard ded uction is 132,500 133,000 0 4,434 0 0 133,000 133,500 0 4,335 0 0 133,500 134,000 0 4,236 0 0 134,000 134,500 0 4,137 0 0 134,500 135,000 0 4,039 0 0 135,000 135,500 0 3,940 0 0 135,500 136,000 0 3,841 0 0 136,000 136,500 0 3,742 0 0 136,500 137,000 0 3,643 0 0 137,000 137,500 0 3,544 0 0 137,500 138,000 0 3,445 0 0 138,000 138,500 0 3,346 0 0 138,500 139,000 0 3,247 0 0 139,000 139,500 0 3,149 0 0 139,500 140,000 0 3,050 0 0 140,000 140,500 0 2,951 0 0 140,500 141,000 0 2,852 0 0 141,000 141,500 0 2,753 0 0 141,500 142,000 0 2,654 0 0 142,000 142,500 0 2,555 0 0 142,500 143,000 0 2,456 0 0 143,000 143,500 0 2,357 0 0 143,500 144,000 0 2,258 0 0 144,000 144,500 0 2,160 0 0 144,500 145,000 0 2,061 0 0 145,000 145,500 0 1,962 0 0 145,500 146,000 0 1,863 0 0 146,000 146,500 0 1,764 0 0 146,500 147,000 0 1,665 0 0 147,000 147,500 0 1,566 0 0 147,500 148,000 0 1,467 0 0 148,000 148,500 0 1,368 0 0 148,500 149,000 0 1,270 0 0 149,000 149,500 0 1,171 0 0 149,500 150,000 0 1,072 0 0 150,000 150,500 0 973 0 0 150,500 151,000 0 874 0 0 151,000 151,500 0 775 0 0 151,500 152,000 0 676 0 0 152,000 152,500 0 577 0 0 152,500 153,000 0 478 0 0 153,000 153,500 0 380 0 0 153,500 154,000 0 281 0 0 154,000 154,500 0 182 0 0 154,500 155,000 0 83 0 0 155,000 155,169 0 17 0 0 155,169 or more 0 0 0 0
Your standard deduction is-
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
0 0
# 2025 TAX TABLE FOR FORM 1NPR FILERS
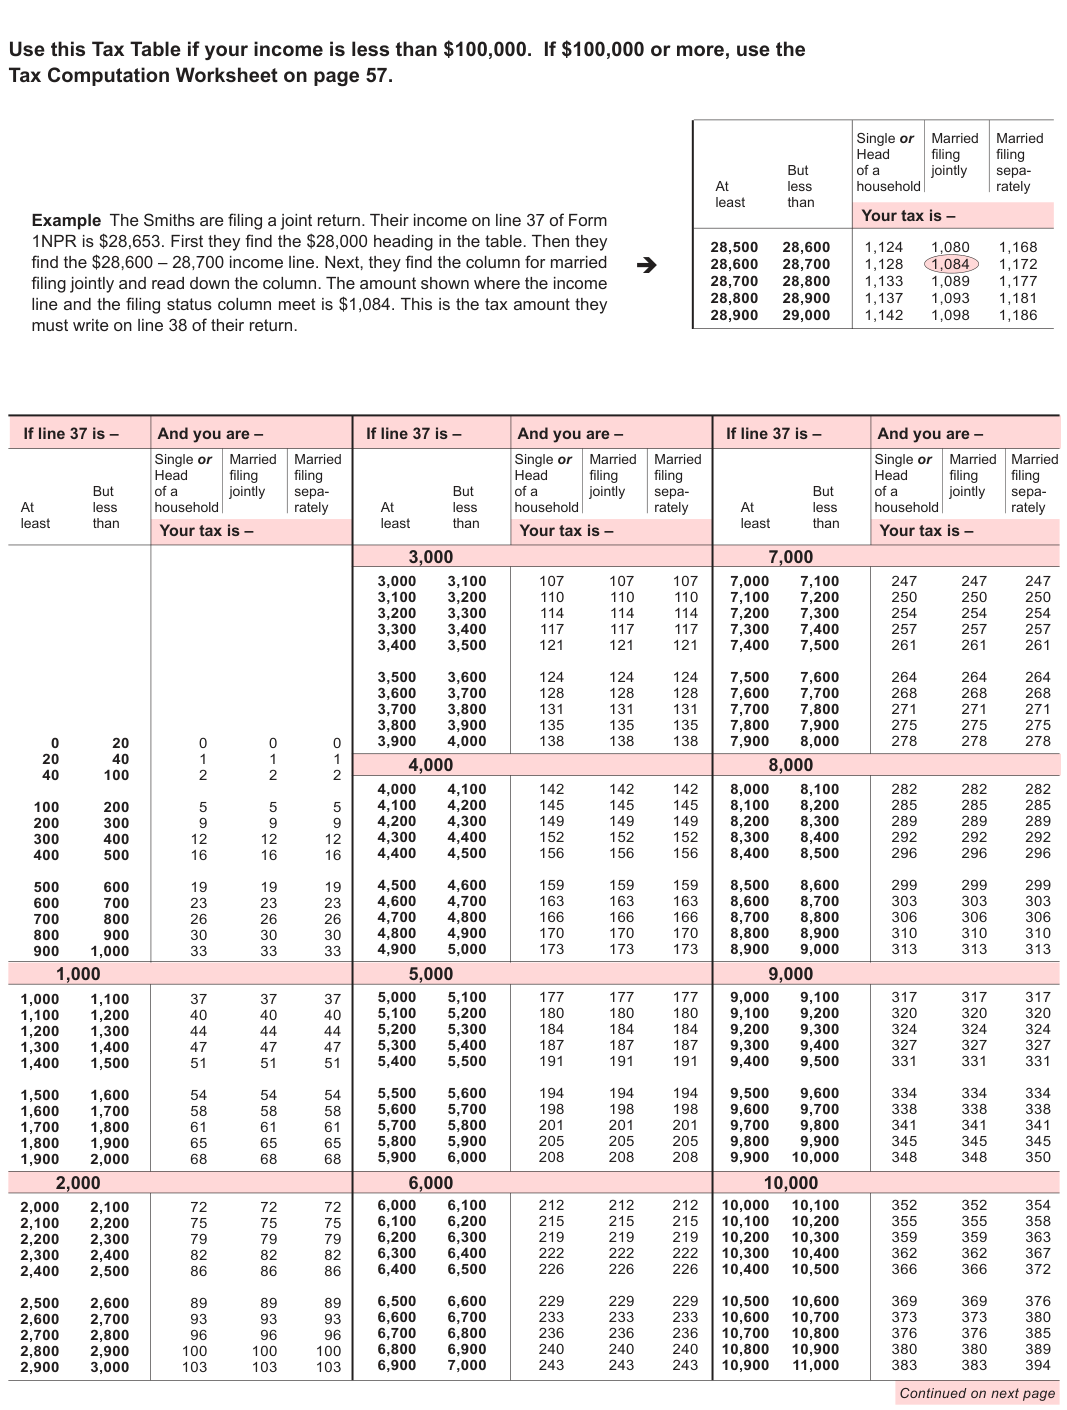
Text version of this table
se this Tax Table if your inc o me is les s than $100,000. If $10 0, 000 or more , use t he ax Com putation Worksheet o n page 5 7. Sin gle or Ma rried M arr ied He ad filin g fili ng But of a join tly se pa - A t less ho usehold rat el y l east than Exampl e The Smit hs are filing a jo int return. T heir inco me on line 3 7 of Fo rm Y Your tax is - – 1NPR is $28,653. F irst they find th e $28,000 heading in the table. Then th ey 2 8,500 2 8,600 1 ,124 1,0 80 1, 1 68 find the $28,600 – 28,700 incom e li ne. Next, t hey find th e column f or marri ed 2 8,600 2 8,700 1 ,128 1,0 84 1, 1 72 filing joi ntly and rea d down the co lu mn. The a mount sho wn where t he inco me 2 8,700 2 8,800 1 ,133 1,0 89 1, 1 77 line and the filing s tatus column m eet is $1,0 84. This is the tax am ount th ey 2 8,800 2 8,900 1 ,137 1,0 93 1, 1 81 must wr ite on line 3 8 of their retu rn . 2 8,900 2 9,000 1 ,142 1,0 98 1, 1 86 If line 37 is – An And you are - If line 37 is – A nd you are – If line 37 is – And you are – Sin gle or Married Married Sin gle or Ma rried Ma rried Single or Married M arried He ad filing filing He ad filin g filin g Head filing fili ng But of a jointly sepa- But of a join tly se pa- But of a jointly se pa- At less hou sehold rately At less ho usehold rat ely At less household ra tely least than least than least than Yo Your tax is - Y our tax i s – Your tax i s – 3,00 0 7, 000 3,000 3,100 107 107 107 7,000 7,100 247 247 247 3,100 3,200 110 110 110 7,100 7,200 250 250 250 3,200 3,300 114 114 114 7,200 7,300 254 254 254 3,300 3,400 117 117 117 7,300 7,400 257 257 257 3,400 3,500 121 121 121 7,400 7,500 261 261 261 3,500 3,600 124 124 124 7,500 7,600 264 264 264 3,600 3,700 128 128 128 7,600 7,700 268 268 268 3,700 3,800 131 131 131 7,700 7,800 271 271 271 3,800 3,900 135 135 135 7,800 7,900 275 275 275 0 20 0 0 0 3,900 4,000 138 138 138 7,900 8,000 278 278 278 20 40 1 1 1 4,00 0 8, 000 2 2 2 40 100 4,000 4,100 142 142 142 8,000 8,100 282 282 282 100 200 5 5 5 4,100 4,200 145 145 145 8,100 8,200 285 285 285 200 300 9 9 9 4,200 4,300 149 149 149 8,200 8,300 289 289 289 300 400 12 12 12 4,300 4,400 152 152 152 8,300 8,400 292 292 292 400 500 16 16 16 4,400 4,500 156 156 156 8,400 8,500 296 296 296 500 600 19 19 19 4,500 4,600 159 159 159 8,500 8,600 299 299 299 600 700 23 23 23 4,600 4,700 163 163 163 8,600 8,700 303 303 303 700 800 26 26 26 4,700 4,800 166 166 166 8,700 8,800 306 306 306 800 900 30 30 30 4,800 4,900 170 170 170 8,800 8,900 310 310 310 900 1,000 33 33 33 4,900 5,000 173 173 173 8,900 9,000 313 313 313 1,00 0 5,00 0 9, 000 1,000 1,100 37 37 37 5,000 5,100 177 177 177 9,000 9,100 317 317 317 1,100 1,200 40 40 40 5,100 5,200 180 180 180 9,100 9,200 320 320 320 1,200 1,300 44 44 44 5,200 5,300 184 184 184 9,200 9,300 324 324 324 1,300 1,400 47 47 47 5,300 5,400 187 187 187 9,300 9,400 327 327 327 1,400 1,500 51 51 51 5,400 5,500 191 191 191 9,400 9,500 331 331 331 1,500 1,600 54 54 54 5,500 5,600 194 194 194 9,500 9,600 334 334 334 1,600 1,700 58 58 58 5,600 5,700 198 198 198 9,600 9,700 338 338 338 1,700 1,800 61 61 61 5,700 5,800 201 201 201 9,700 9,800 341 341 341 1,800 1,900 65 65 65 5,800 5,900 205 205 205 9,800 9,900 345 345 345 1,900 2,000 68 68 68 5,900 6,000 208 208 208 9,900 10,000 348 348 350 2,00 0 6,00 0 10, 000 2,000 2,100 72 72 72 6,000 6,100 212 212 212 10,000 10,100 352 352 354 2,100 2,200 75 75 75 6,100 6,200 215 215 215 10,100 10,200 355 355 358 2,200 2,300 79 79 79 6,200 6,300 219 219 219 10,200 10,300 359 359 363 2,300 2,400 82 82 82 6,300 6,400 222 222 222 10,300 10,400 362 362 367 2,400 2,500 86 86 86 6,400 6,500 226 226 226 10,400 10,500 366 366 372 2,500 2,600 89 89 89 6,500 6,600 229 229 229 10,500 10,600 369 369 376 2,600 2,700 93 93 93 6,600 6,700 233 233 233 10,600 10,700 373 373 380 2,700 2,800 96 96 96 6,700 6,800 236 236 236 10,700 10,800 376 376 385 2,800 2,900 100 100 100 6,800 6,900 240 240 240 10,800 10,900 380 380 389 2,900 3,000 103 103 103 6,900 7,000 243 243 243 10,900 11,000 383 383 394 Continu ed on n ex t page
If line 37 is - And you are -
# Married Married
2025 Tax Table For Form 1NPR Filers - Continued And you are -If line 37 is - And you are - If line 37 is -Married Married If line 37 is - And you are -
# Married
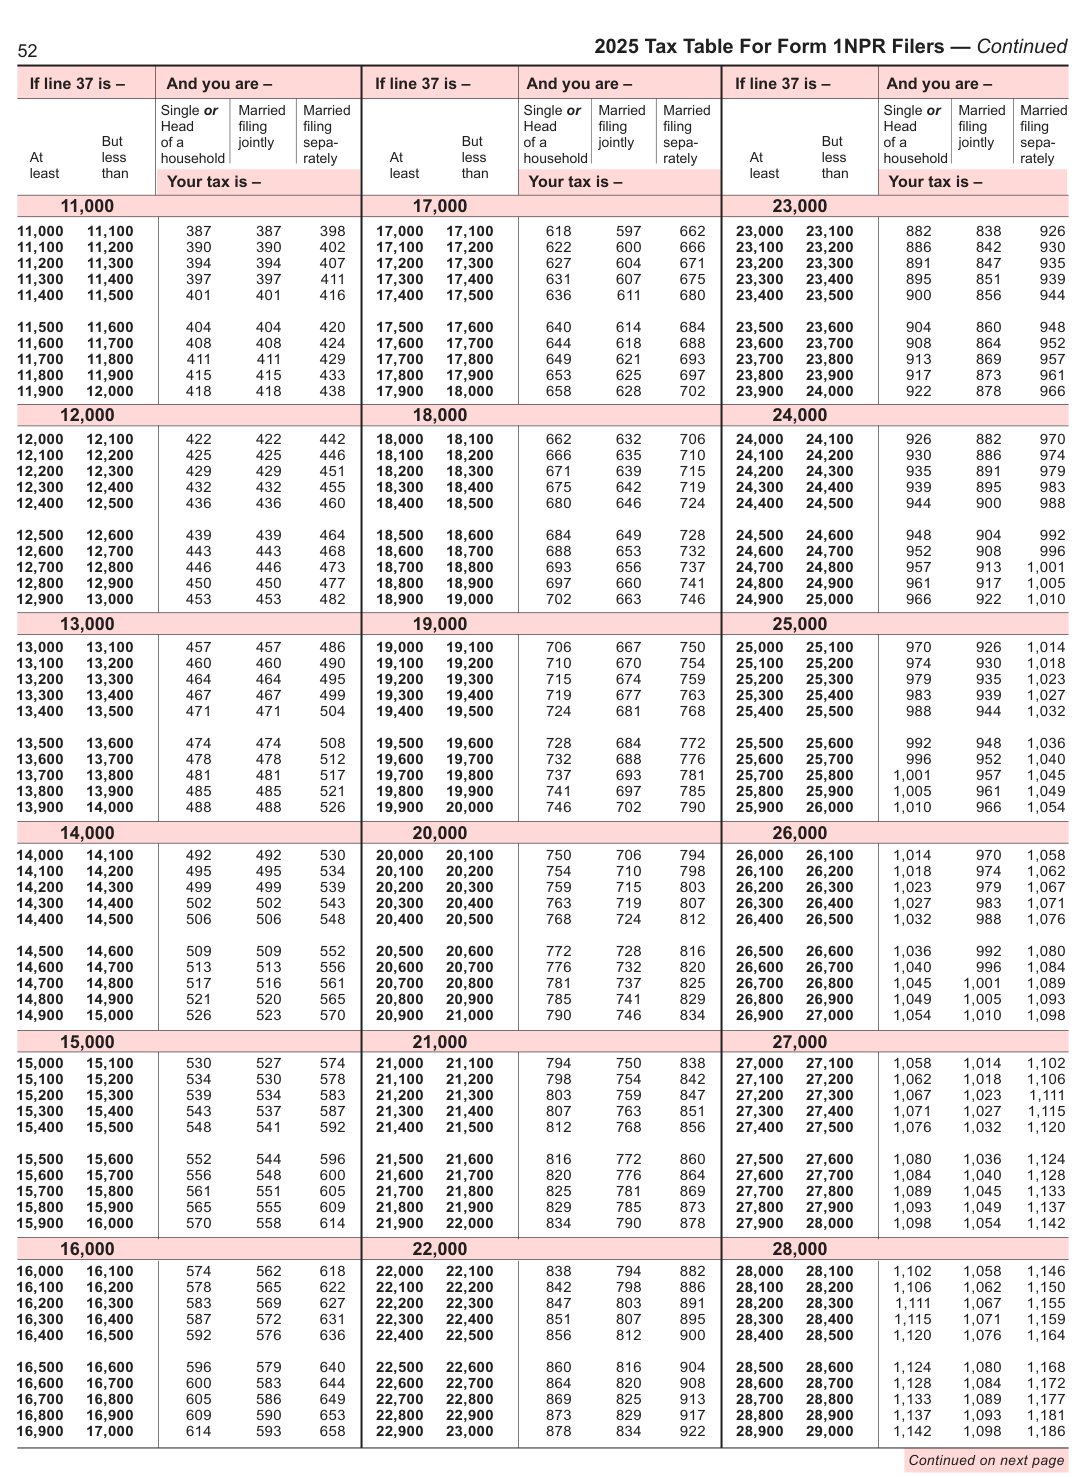
Text version of this table
52 20 25 Ta x Table For For m 1NPR Filers — Continued If line 3 7 is – An And you are - – If line 37 is – An d you are – If line 37 is – A nd you are – Sing le or Ma rried Ma rried Sin gle or Ma rried Ma rried S ingle or Ma rried Married Hea d filin g fili ng Hea d filin g fili ng H ead filin g filing But of a joi ntly se pa- But of a joi ntly se pa- But o f a joi ntly sepa- At At less hou sehold rat ely At less hou sehold rat ely At less h ousehold rately least than least than least than Yo Your tax is - – Yo ur tax is – Your tax is – 11, 000 17,0 0 0 23,0 0 0 11,000 11,100 387 387 398 17,000 17 ,100 618 597 662 23,000 23 ,100 882 838 926 11,100 11,200 390 390 402 17,100 17 ,200 622 600 666 23,100 23 ,200 886 842 930 11,200 11,300 394 394 407 17,200 17 ,300 627 604 671 23,200 23 ,300 891 847 935 11,300 11,400 397 397 411 17,300 17 ,400 631 607 675 23,300 23 ,400 895 851 939 11,400 11,500 401 401 416 17,400 17 ,500 636 611 680 23,400 23 ,500 900 856 944 11,500 11,600 404 404 420 17,500 17 ,600 640 614 684 23,500 23 ,600 904 860 948 11,600 11,700 408 408 424 17,600 17 ,700 644 618 688 23,600 23 ,700 908 864 952 11,700 11,800 411 411 429 17,700 17 ,800 649 621 693 23,700 23 ,800 913 869 957 11,800 11,900 415 415 433 17,800 17 ,900 653 625 697 23,800 23 ,900 917 873 961 11,900 12,000 418 418 438 17,900 18 ,000 658 628 702 23,900 24 ,000 922 878 966 12, 000 18,0 0 0 24,0 0 0 12,000 12,100 422 422 442 18,000 18 ,100 662 632 706 24,000 24 ,100 926 882 970 12,100 12,200 425 425 446 18,100 18 ,200 666 635 710 24,100 24 ,200 930 886 974 12,200 12,300 429 429 451 18,200 18 ,300 671 639 715 24,200 24 ,300 935 891 979 12,300 12,400 432 432 455 18,300 18 ,400 675 642 719 24,300 24 ,400 939 895 983 12,400 12,500 436 436 460 18,400 18 ,500 680 646 724 24,400 24 ,500 944 900 988 12,500 12,600 439 439 464 18,500 18 ,600 684 649 728 24,500 24 ,600 948 904 992 12,600 12,700 443 443 468 18,600 18 ,700 688 653 732 24,600 24 ,700 952 908 996 12,700 12,800 446 446 473 18,700 18 ,800 693 656 737 24,700 24 ,800 957 913 1,001 12,800 12,900 450 450 477 18,800 18 ,900 697 660 741 24,800 24 ,900 961 917 1,005 12,900 13,000 453 453 482 18,900 19 ,000 702 663 746 24,900 25 ,000 966 922 1,010 13, 000 19,0 0 0 25,0 0 0 13,000 13,100 457 457 486 19,000 19 ,100 706 667 750 25,000 25 ,100 970 926 1,014 13,100 13,200 460 460 490 19,100 19 ,200 710 670 754 25,100 25 ,200 974 930 1,018 13,200 13,300 464 464 495 19,200 19 ,300 715 674 759 25,200 25 ,300 979 935 1,023 13,300 13,400 467 467 499 19,300 19 ,400 719 677 763 25,300 25 ,400 983 939 1,027 13,400 13,500 471 471 504 19,400 19 ,500 724 681 768 25,400 25 ,500 988 944 1,032 13,500 13,600 474 474 508 19,500 19 ,600 728 684 772 25,500 25 ,600 992 948 1,036 13,600 13,700 478 478 512 19,600 19 ,700 732 688 776 25,600 25 ,700 996 952 1,040 13,700 13,800 481 481 517 19,700 19 ,800 737 693 781 25,700 25 ,800 1,001 957 1,045 13,800 13,900 485 485 521 19,800 19 ,900 741 697 785 25,800 25 ,900 1,005 961 1,049 13,900 14,000 488 488 526 19,900 20 ,000 746 702 790 25,900 26 ,000 1,010 966 1,054 14, 000 20,0 0 0 26,0 0 0 14,000 14,100 492 492 530 20,000 20 ,100 750 706 794 26,000 26 ,100 1,014 970 1,058 14,100 14,200 495 495 534 20,100 20 ,200 754 710 798 26,100 26 ,200 1,018 974 1,062 14,200 14,300 499 499 539 20,200 20 ,300 759 715 803 26,200 26 ,300 1,023 979 1,067 14,300 14,400 502 502 543 20,300 20 ,400 763 719 807 26,300 26 ,400 1,027 983 1,071 14,400 14,500 506 506 548 20,400 20 ,500 768 724 812 26,400 26 ,500 1,032 988 1,076 14,500 14,600 509 509 552 20,500 20 ,600 772 728 816 26,500 26 ,600 1,036 992 1,080 14,600 14,700 513 513 556 20,600 20 ,700 776 732 820 26,600 26 ,700 1,040 996 1,084 14,700 14,800 517 516 561 20,700 20 ,800 781 737 825 26,700 26 ,800 1,045 1, 001 1,089 14,800 14,900 521 520 565 20,800 20 ,900 785 741 829 26,800 26 ,900 1,049 1, 005 1,093 14,900 15,000 526 523 570 20,900 21 ,000 790 746 834 26,900 27 ,000 1,054 1, 010 1,098 15, 000 21,0 0 0 27,0 0 0 15,000 15,100 530 527 574 21,000 21 ,100 794 750 838 27,000 27 ,100 1,058 1, 014 1,102 15,100 15,200 534 530 578 21,100 21 ,200 798 754 842 27,100 27 ,200 1,062 1, 018 1,106 15,200 15,300 539 534 583 21,200 21 ,300 803 759 847 27,200 27 ,300 1,067 1, 023 1,111 15,300 15,400 543 537 587 21,300 21 ,400 807 763 851 27,300 27 ,400 1,071 1, 027 1,115 15,400 15,500 548 541 592 21,400 21 ,500 812 768 856 27,400 27 ,500 1,076 1, 032 1,120 15,500 15,600 552 544 596 21,500 21 ,600 816 772 860 27,500 27 ,600 1,080 1, 036 1,124 15,600 15,700 556 548 600 21,600 21 ,700 820 776 864 27,600 27 ,700 1,084 1, 040 1,128 15,700 15,800 561 551 605 21,700 21 ,800 825 781 869 27,700 27 ,800 1,089 1, 045 1,133 15,800 15,900 565 555 609 21,800 21 ,900 829 785 873 27,800 27 ,900 1,093 1, 049 1,137 15,900 16,000 570 558 614 21,900 22 ,000 834 790 878 27,900 28 ,000 1,098 1, 054 1,142 16, 000 22,0 0 0 28,0 0 0 16,000 16,100 574 562 618 22,000 22 ,100 838 794 882 28,000 28 ,100 1,102 1, 058 1,146 16,100 16,200 578 565 622 22,100 22 ,200 842 798 886 28,100 28 ,200 1,106 1, 062 1,150 16,200 16,300 583 569 627 22,200 22 ,300 847 803 891 28,200 28 ,300 1,111 1, 067 1,155 16,300 16,400 587 572 631 22,300 22 ,400 851 807 895 28,300 28 ,400 1,115 1, 071 1,159 16,400 16,500 592 576 636 22,400 22 ,500 856 812 900 28,400 28 ,500 1,120 1, 076 1,164 16,500 16,600 596 579 640 22,500 22 ,600 860 816 904 28,500 28 ,600 1,124 1, 080 1,168 16,600 16,700 600 583 644 22,600 22 ,700 864 820 908 28,600 28 ,700 1,128 1, 084 1,172 16,700 16,800 605 586 649 22,700 22 ,800 869 825 913 28,700 28 ,800 1,133 1, 089 1,177 16,800 16,900 609 590 653 22,800 22 ,900 873 829 917 28,800 28 ,900 1,137 1, 093 1,181 16,900 17,000 614 593 658 22,900 23 ,000 878 834 922 28,900 29 ,000 1,142 1, 098 1,186 Continued on next page
Single or filing filing filing filing Head Head
# But But sepajointly
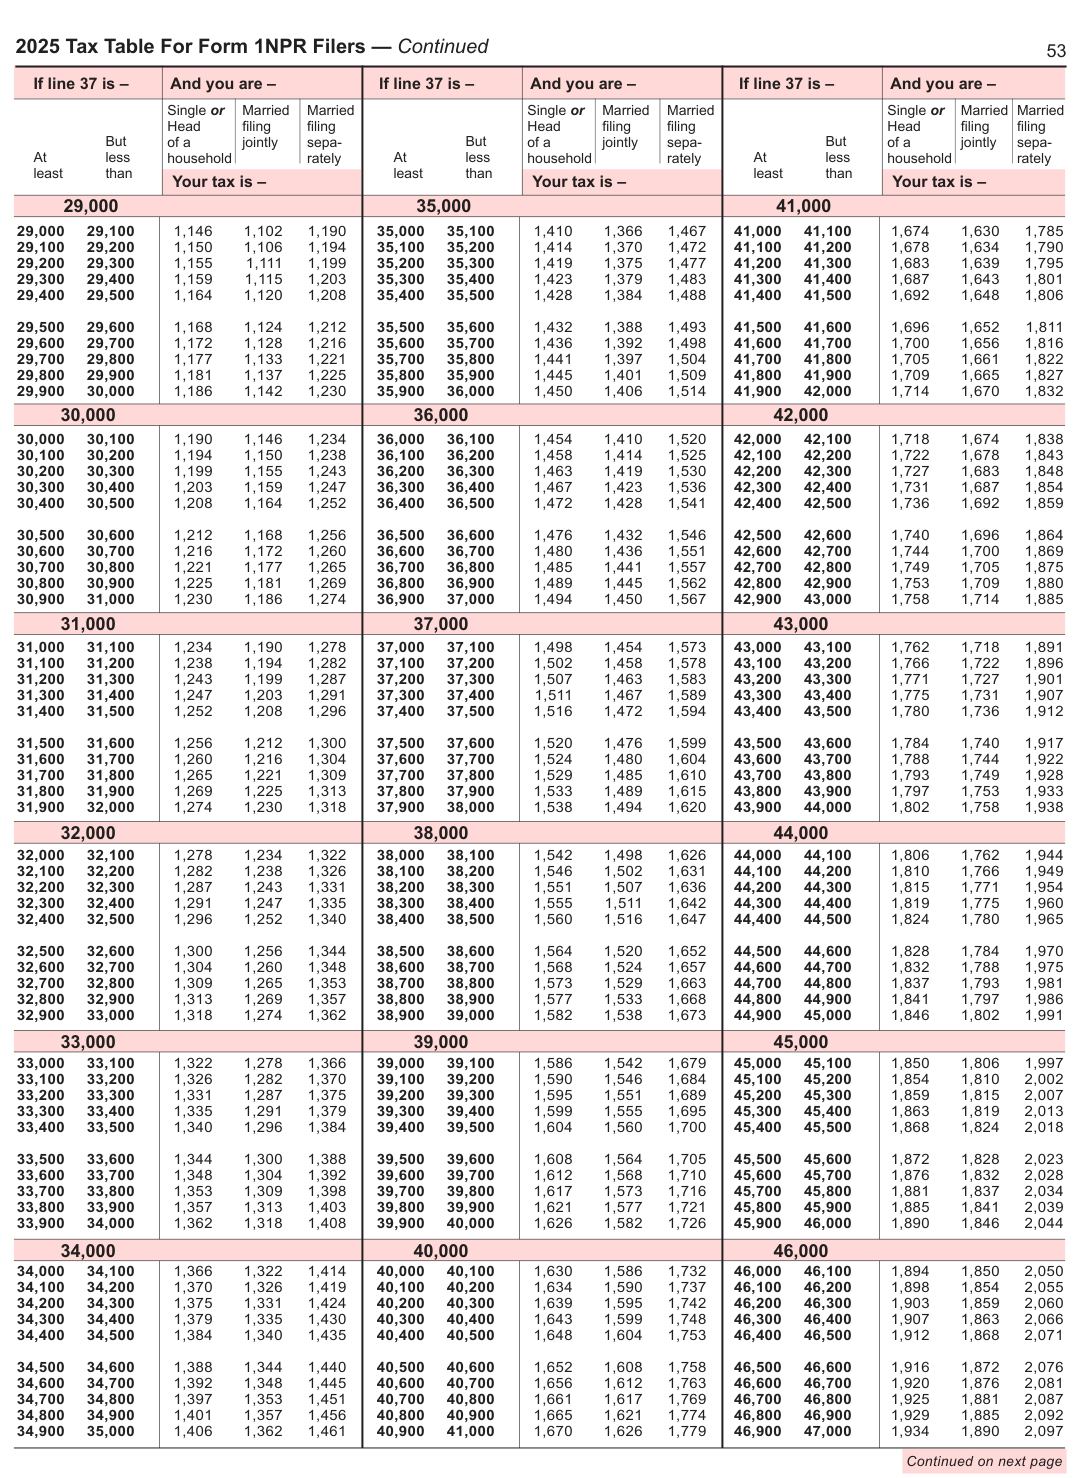
Text version of this table
| 2025 Ta | x Table F | or Form | 1NPR | Filers | — Conti | nued | 53 | |||||||
| If line 3 | 7 is – | And you | are – | If line 37 | is – | And you | are – | If line 37 | is – | And you | are – | |||
| Single or | Married | Married | Single or | Married | Married | Single or | Married | Married | ||||||
| Head | filing | filing | Head | filing | filing | Head | filing | filing | ||||||
| But | of a | jointly | sepa- | But | of a | jointly | sepa- | But | of a | jointly | sepa- | |||
| At | less | household | rately | At | less | household | rately | At | less | household | rately | |||
| least | than | least | than | least | than | |||||||||
| Your tax is - | s – | Your tax i | s – | Your tax | is – | |||||||||
| 29, | 000 | 35,0 | 00 | 41, | 000 | |||||||||
| 29,000 | 29,100 | 1,146 | 1,102 | 1,190 | 35,000 | 35,100 | 1,410 | 1,366 | 1,467 | 41,000 | 41,100 | 1,674 | 1,630 | 1,785 |
| 29,100 | 29,200 | 1,150 | 1,106 | 1,194 | 35,100 | 35,200 | 1,414 | 1,370 | 1,472 | 41,100 | 41,200 | 1,678 | 1,634 | 1,790 |
| 29,200 | 29,300 | 1,155 | 1,111 | 1,199 | 35,200 | 35,300 | 1,419 | 1,375 | 1,477 | 41,200 | 41,300 | 1,683 | 1,639 | 1,795 |
| 29,300 | 29,400 | 1,159 | 1,115 | 1,203 | 35,300 | 35,400 | 1,423 | 1,379 | 1,483 | 41,300 | 41,400 | 1,687 | 1,643 | 1,801 |
| 29,400 | 29,500 | 1,164 | 1,120 | 1,208 | 35,400 | 35,500 | 1,428 | 1,384 | 1,488 | 41,400 | 41,500 | 1,692 | 1,648 | 1,806 |
| 29,500 | 29,600 | 1,168 | 1,124 | 1,212 | 35,500 | 35,600 | 1,432 | 1,388 | 1,493 | 41,500 | 41,600 | 1,696 | 1,652 | 1,811 |
| 29,600 | 29,700 | 1,172 | 1,128 | 1,216 | 35,600 | 35,700 | 1,436 | 1,392 | 1,498 | 41,600 | 41,700 | 1,700 | 1,656 | 1,816 |
| 29,700 | 29,800 | 1,177 | 1,133 | 1,221 | 35,700 | 35,800 | 1,441 | 1,397 | 1,504 | 41,700 | 41,800 | 1,705 | 1,661 | 1,822 |
| 29,800 | 29,900 | 1,181 | 1,137 | 1,225 | 35,800 | 35,900 | 1,445 | 1,401 | 1,509 | 41,800 | 41,900 | 1,709 | 1,665 | 1,827 |
| 29,900 | 30,000 | 1,186 | 1,142 | 1,230 | 35,900 | 36,000 | 1,450 | 1,406 | 1,514 | 41,900 | 42,000 | 1,714 | 1,670 | 1,832 |
| 30, | 000 | 36,0 | 00 | 42,0 | 00 | |||||||||
| 30,000 | 30,100 | 1,190 | 1,146 | 1,234 | 36,000 | 36,100 | 1,454 | 1,410 | 1,520 | 42,000 | 42,100 | 1,718 | 1,674 | 1,838 |
| 30,100 | 30,200 | 1,194 | 1,150 | 1,238 | 36,100 | 36,200 | 1,458 | 1,414 | 1,525 | 42,100 | 42,200 | 1,722 | 1,678 | 1,843 |
| 30,200 | 30,300 | 1,199 | 1,155 | 1,243 | 36,200 | 36,300 | 1,463 | 1,419 | 1,530 | 42,200 | 42,300 | 1,727 | 1,683 | 1,848 |
| 30,300 | 30,400 | 1,203 | 1,159 | 1,247 | 36,300 | 36,400 | 1,467 | 1,423 | 1,536 | 42,300 | 42,400 | 1,731 | 1,687 | 1,854 |
| 30,400 | 30,500 | 1,208 | 1,164 | 1,252 | 36,400 | 36,500 | 1,472 | 1,428 | 1,541 | 42,400 | 42,500 | 1,736 | 1,692 | 1,859 |
| 30,500 | 30,600 | 1,212 | 1,168 | 1,256 | 36,500 | 36,600 | 1,476 | 1,432 | 1,546 | 42,500 | 42,600 | 1,740 | 1,696 | 1,864 |
| 30,600 | 30,700 | 1,216 | 1,172 | 1,260 | 36,600 | 36,700 | 1,480 | 1,436 | 1,551 | 42,600 | 42,700 | 1,744 | 1,700 | 1,869 |
| 30,700 | 30,800 | 1,221 | 1,177 | 1,265 | 36,700 | 36,800 | 1,485 | 1,441 | 1,557 | 42,700 | 42,800 | 1,749 | 1,705 | 1,875 |
| 30,800 | 30,900 | 1,225 | 1,181 | 1,269 | 36,800 | 36,900 | 1,489 | 1,445 | 1,562 | 42,800 | 42,900 | 1,753 | 1,709 | 1,880 |
| 30,900 | 31,000 | 1,230 | 1,186 | 1,274 | 36,900 | 37,000 | 1,494 | 1,450 | 1,567 | 42,900 | 43,000 | 1,758 | 1,714 | 1,885 |
| 31, | 000 | 37,0 | 00 | 43,0 | 00 | |||||||||
| 31,000 | 31,100 | 1,234 | 1,190 | 1,278 | 37,000 | 37,100 | 1,498 | 1,454 | 1,573 | 43,000 | 43,100 | 1,762 | 1,718 | 1,891 |
| 31,100 | 31,200 | 1,238 | 1,194 | 1,282 | 37,100 | 37,200 | 1,502 | 1,458 | 1,578 | 43,100 | 43,200 | 1,766 | 1,722 | 1,896 |
| 31,200 | 31,300 | 1,243 | 1,199 | 1,287 | 37,200 | 37,300 | 1,507 | 1,463 | 1,583 | 43,200 | 43,300 | 1,771 | 1,727 | 1,901 |
| 31,300 | 31,400 | 1,247 | 1,203 | 1,291 | 37,300 | 37,400 | 1,511 | 1,467 | 1,589 | 43,300 | 43,400 | 1,775 | 1,731 | 1,907 |
| 31,400 | 31,500 | 1,252 | 1,208 | 1,296 | 37,400 | 37,500 | 1,516 | 1,472 | 1,594 | 43,400 | 43,500 | 1,780 | 1,736 | 1,912 |
| 31,500 | 31,600 | 1,256 | 1,212 | 1,300 | 37,500 | 37,600 | 1,520 | 1,476 | 1,599 | 43,500 | 43,600 | 1,784 | 1,740 | 1,917 |
| 31,600 | 31,700 | 1,260 | 1,216 | 1,304 | 37,600 | 37,700 | 1,524 | 1,480 | 1,604 | 43,600 | 43,700 | 1,788 | 1,744 | 1,922 |
| 31,700 | 31,800 | 1,265 | 1,221 | 1,309 | 37,700 | 37,800 | 1,529 | 1,485 | 1,610 | 43,700 | 43,800 | 1,793 | 1,749 | 1,928 |
| 31,800 | 31,900 | 1,269 | 1,225 | 1,313 | 37,800 | 37,900 | 1,533 | 1,489 | 1,615 | 43,800 | 43,900 | 1,797 | 1,753 | 1,933 |
| 31,900 | 32,000 | 1,274 | 1,230 | 1,318 | 37,900 | 38,000 | 1,538 | 1,494 | 1,620 | 43,900 | 44,000 | 1,802 | 1,758 | 1,938 |
| 32, | 000 | 38,0 | 00 | 44,0 | 00 | |||||||||
| 32,000 | 32,100 | 1,278 | 1,234 | 1,322 | 38,000 | 38,100 | 1,542 | 1,498 | 1,626 | 44,000 | 44,100 | 1,806 | 1,762 | 1,944 |
| 32,100 | 32,200 | 1,282 | 1,238 | 1,326 | 38,100 | 38,200 | 1,546 | 1,502 | 1,631 | 44,100 | 44,200 | 1,810 | 1,766 | 1,949 |
| 32,200 | 32,300 | 1,287 | 1,243 | 1,331 | 38,200 | 38,300 | 1,551 | 1,507 | 1,636 | 44,200 | 44,300 | 1,815 | 1,771 | 1,954 |
| 32,300 | 32,400 | 1,291 | 1,247 | 1,335 | 38,300 | 38,400 | 1,555 | 1,511 | 1,642 | 44,300 | 44,400 | 1,819 | 1,775 | 1,960 |
| 32,400 | 32,500 | 1,296 | 1,252 | 1,340 | 38,400 | 38,500 | 1,560 | 1,516 | 1,647 | 44,400 | 44,500 | 1,824 | 1,780 | 1,965 |
| 32,500 | 32,600 | 1,300 | 1,256 | 1,344 | 38,500 | 38,600 | 1,564 | 1,520 | 1,652 | 44,500 | 44,600 | 1,828 | 1,784 | 1,970 |
| 32,600 | 32,700 | 1,304 | 1,260 | 1,348 | 38,600 | 38,700 | 1,568 | 1,524 | 1,657 | 44,600 | 44,700 | 1,832 | 1,788 | 1,975 |
| 32,700 | 32,800 | 1,309 | 1,265 | 1,353 | 38,700 | 38,800 | 1,573 | 1,529 | 1,663 | 44,700 | 44,800 | 1,837 | 1,793 | 1,981 |
| 32,800 | 32,900 | 1,313 | 1,269 | 1,357 | 38,800 | 38,900 | 1,577 | 1,533 | 1,668 | 44,800 | 44,900 | 1,841 | 1,797 | 1,986 |
| 32,900 | 33,000 | 1,318 | 1,274 | 1,362 | 38,900 | 39,000 | 1,582 | 1,538 | 1,673 | 44,900 | 45,000 | 1,846 | 1,802 | 1,991 |
| 33, | 000 | 39,0 | 00 | 45,0 | 00 | |||||||||
| 33,000 | 33,100 | 1,322 | 1,278 | 1,366 | 39,000 | 39,100 | 1,586 | 1,542 | 1,679 | 45,000 | 45,100 | 1,850 | 1,806 | 1,997 |
| 33,100 | 33,200 | 1,326 | 1,282 | 1,370 | 39,100 | 39,200 | 1,590 | 1,546 | 1,684 | 45,100 | 45,200 | 1,854 | 1,810 | 2,002 |
| 33,200 | 33,300 | 1,331 | 1,287 | 1,375 | 39,200 | 39,300 | 1,595 | 1,551 | 1,689 | 45,200 | 45,300 | 1,859 | 1,815 | 2,007 |
| 33,300 | 33,400 | 1,335 | 1,291 | 1,379 | 39,300 | 39,400 | 1,599 | 1,555 | 1,695 | 45,300 | 45,400 | 1,863 | 1,819 | 2,013 |
| 33,400 | 33,500 | 1,340 | 1,296 | 1,384 | 39,400 | 39,500 | 1,604 | 1,560 | 1,700 | 45,400 | 45,500 | 1,868 | 1,824 | 2,018 |
| 33,500 | 33,600 | 1,344 | 1,300 | 1,388 | 39,500 | 39,600 | 1,608 | 1,564 | 1,705 | 45,500 | 45,600 | 1,872 | 1,828 | 2,023 |
| 33,600 | 33,700 | 1,348 | 1,304 | 1,392 | 39,600 | 39,700 | 1,612 | 1,568 | 1,710 | 45,600 | 45,700 | 1,876 | 1,832 | 2,028 |
| 33,700 | 33,800 | 1,353 | 1,309 | 1,398 | 39,700 | 39,800 | 1,617 | 1,573 | 1,716 | 45,700 | 45,800 | 1,881 | 1,837 | 2,034 |
| 33,800 | 33,900 | 1,357 | 1,313 | 1,403 | 39,800 | 39,900 | 1,621 | 1,577 | 1,721 | 45,800 | 45,900 | 1,885 | 1,841 | 2,039 |
| 33,900 | 34,000 | 1,362 | 1,318 | 1,408 | 39,900 | 40,000 | 1,626 | 1,582 | 1,726 | 45,900 | 46,000 | 1,890 | 1,846 | 2,044 |
| 34, | 000 | 40,0 | 00 | 46,0 | 00 | |||||||||
| 34,000 | 34,100 | 1,366 | 1,322 | 1,414 | 40,000 | 40,100 | 1,630 | 1,586 | 1,732 | 46,000 | 46,100 | 1,894 | 1,850 | 2,050 |
| 34,100 | 34,200 | 1,370 | 1,326 | 1,419 | 40,100 | 40,200 | 1,634 | 1,590 | 1,737 | 46,100 | 46,200 | 1,898 | 1,854 | 2,055 |
| 34,200 | 34,300 | 1,375 | 1,331 | 1,424 | 40,200 | 40,300 | 1,639 | 1,595 | 1,742 | 46,200 | 46,300 | 1,903 | 1,859 | 2,060 |
| 34,300 | 34,400 | 1,379 | 1,335 | 1,430 | 40,300 | 40,400 | 1,643 | 1,599 | 1,748 | 46,300 | 46,400 | 1,907 | 1,863 | 2,066 |
| 34,400 | 34,500 | 1,384 | 1,340 | 1,435 | 40,400 | 40,500 | 1,648 | 1,604 | 1,753 | 46,400 | 46,500 | 1,912 | 1,868 | 2,071 |
| 34,500 | 34,600 | 1,388 | 1,344 | 1,440 | 40,500 | 40,600 | 1,652 | 1,608 | 1,758 | 46,500 | 46,600 | 1,916 | 1,872 | 2,076 |
| 34,600 | 34,700 | 1,392 | 1,348 | 1,445 | 40,600 | 40,700 | 1,656 | 1,612 | 1,763 | 46,600 | 46,700 | 1,920 | 1,876 | 2,081 |
| 34,700 | 34,800 | 1,397 | 1,353 | 1,451 | 40,700 | 40,800 | 1,661 | 1,617 | 1,769 | 46,700 | 46,800 | 1,925 | 1,881 | 2,087 |
| 34,800 | 34,900 | 1,401 | 1,357 | 1,456 | 40,800 | 40,900 | 1,665 | 1,621 | 1,774 | 46,800 | 46,900 | 1,929 | 1,885 | 2,092 |
| 34,900 | 35,000 | 1,406 | 1,362 | 1,461 | 40,900 | 41,000 | 1,670 | 1,626 | 1,779 | 46,900 | 47,000 | 1,934 | 1,890 | 2,097 |
| Continu | ed on ne | xt page |
# But But sepajointly
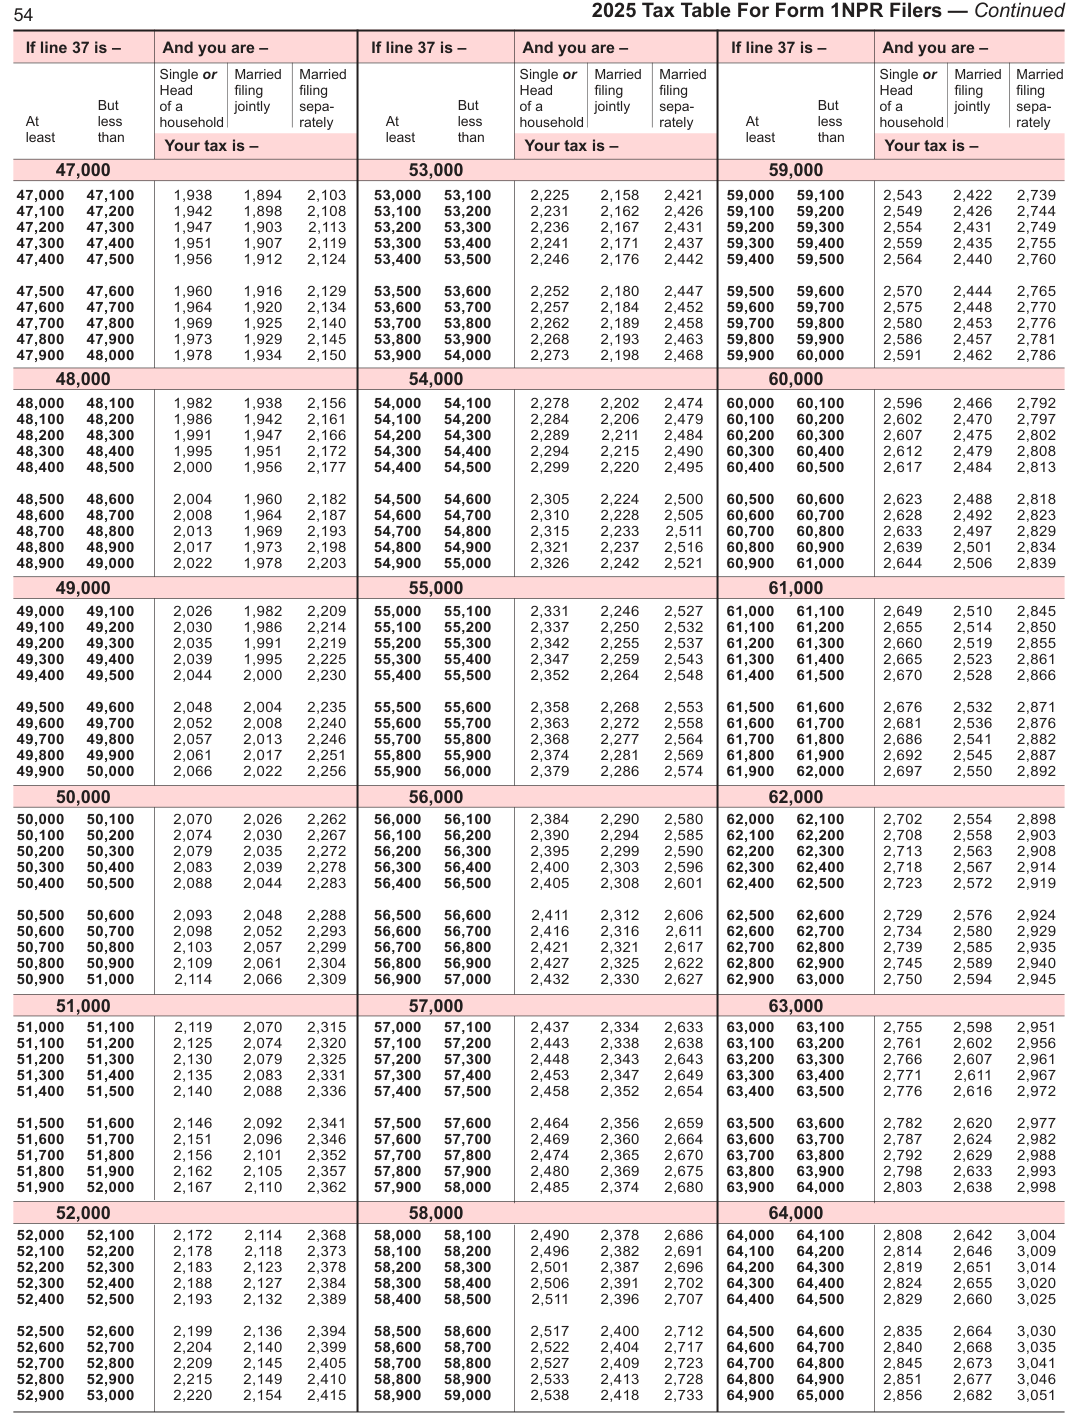
Text version of this table
| If line 37 | is – A | nd you | are – | I | f line 37 i | s – | And you | are – | If line 37 | is – | And you | are – | ||
| Si | ngle or | Married | Married | Single or | Married | Married | Single or | Married | Married | |||||
| H | ead | filing | filing | Head | filing | filing | Head | filing | filing | |||||
| But of | a | jointly | sepa- | But | of a | jointly | sepa- | But | of a | jointly | sepa- | |||
| At | less ho | usehold | rately | At | less | household | rately | At | less | household | rately | |||
| least | than | least | than | least | than | |||||||||
| Y | Your tax is - | s – | Your tax i | s – | Your tax | is – | ||||||||
| 47,0 | 00 | 53,0 | 00 | 59, | 000 | |||||||||
| 47,000 | 47,100 | 1,938 | 1,894 | 2,103 | 53,000 | 53,100 | 2,225 | 2,158 | 2,421 | 59,000 | 59,100 | 2,543 | 2,422 | 2,739 |
| 47,100 | 47,200 | 1,942 | 1,898 | 2,108 | 53,100 | 53,200 | 2,231 | 2,162 | 2,426 | 59,100 | 59,200 | 2,549 | 2,426 | 2,744 |
| 47,200 | 47,300 | 1,947 | 1,903 | 2,113 | 53,200 | 53,300 | 2,236 | 2,167 | 2,431 | 59,200 | 59,300 | 2,554 | 2,431 | 2,749 |
| 47,300 | 47,400 | 1,951 | 1,907 | 2,119 | 53,300 | 53,400 | 2,241 | 2,171 | 2,437 | 59,300 | 59,400 | 2,559 | 2,435 | 2,755 |
| 47,400 | 47,500 | 1,956 | 1,912 | 2,124 | 53,400 | 53,500 | 2,246 | 2,176 | 2,442 | 59,400 | 59,500 | 2,564 | 2,440 | 2,760 |
| 47,500 | 47,600 | 1,960 | 1,916 | 2,129 | 53,500 | 53,600 | 2,252 | 2,180 | 2,447 | 59,500 | 59,600 | 2,570 | 2,444 | 2,765 |
| 47,600 | 47,700 | 1,964 | 1,920 | 2,134 | 53,600 | 53,700 | 2,257 | 2,184 | 2,452 | 59,600 | 59,700 | 2,575 | 2,448 | 2,770 |
| 47,700 | 47,800 | 1,969 | 1,925 | 2,140 | 53,700 | 53,800 | 2,262 | 2,189 | 2,458 | 59,700 | 59,800 | 2,580 | 2,453 | 2,776 |
| 47,800 | 47,900 | 1,973 | 1,929 | 2,145 | 53,800 | 53,900 | 2,268 | 2,193 | 2,463 | 59,800 | 59,900 | 2,586 | 2,457 | 2,781 |
| 47,900 | 48,000 | 1,978 | 1,934 | 2,150 | 53,900 | 54,000 | 2,273 | 2,198 | 2,468 | 59,900 | 60,000 | 2,591 | 2,462 | 2,786 |
| 48,0 | 00 | 54,0 | 00 | 60, | 000 | |||||||||
| 48,000 | 48,100 | 1,982 | 1,938 | 2,156 | 54,000 | 54,100 | 2,278 | 2,202 | 2,474 | 60,000 | 60,100 | 2,596 | 2,466 | 2,792 |
| 48,100 | 48,200 | 1,986 | 1,942 | 2,161 | 54,100 | 54,200 | 2,284 | 2,206 | 2,479 | 60,100 | 60,200 | 2,602 | 2,470 | 2,797 |
| 48,200 | 48,300 | 1,991 | 1,947 | 2,166 | 54,200 | 54,300 | 2,289 | 2,211 | 2,484 | 60,200 | 60,300 | 2,607 | 2,475 | 2,802 |
| 48,300 | 48,400 | 1,995 | 1,951 | 2,172 | 54,300 | 54,400 | 2,294 | 2,215 | 2,490 | 60,300 | 60,400 | 2,612 | 2,479 | 2,808 |
| 48,400 | 48,500 | 2,000 | 1,956 | 2,177 | 54,400 | 54,500 | 2,299 | 2,220 | 2,495 | 60,400 | 60,500 | 2,617 | 2,484 | 2,813 |
| 48,500 | 48,600 | 2,004 | 1,960 | 2,182 | 54,500 | 54,600 | 2,305 | 2,224 | 2,500 | 60,500 | 60,600 | 2,623 | 2,488 | 2,818 |
| 48,600 | 48,700 | 2,008 | 1,964 | 2,187 | 54,600 | 54,700 | 2,310 | 2,228 | 2,505 | 60,600 | 60,700 | 2,628 | 2,492 | 2,823 |
| 48,700 | 48,800 | 2,013 | 1,969 | 2,193 | 54,700 | 54,800 | 2,315 | 2,233 | 2,511 | 60,700 | 60,800 | 2,633 | 2,497 | 2,829 |
| 48,800 | 48,900 | 2,017 | 1,973 | 2,198 | 54,800 | 54,900 | 2,321 | 2,237 | 2,516 | 60,800 | 60,900 | 2,639 | 2,501 | 2,834 |
| 48,900 | 49,000 | 2,022 | 1,978 | 2,203 | 54,900 | 55,000 | 2,326 | 2,242 | 2,521 | 60,900 | 61,000 | 2,644 | 2,506 | 2,839 |
| 49,0 | 00 | 55,0 | 00 | 61, | 000 | |||||||||
| 49,000 | 49,100 | 2,026 | 1,982 | 2,209 | 55,000 | 55,100 | 2,331 | 2,246 | 2,527 | 61,000 | 61,100 | 2,649 | 2,510 | 2,845 |
| 49,100 | 49,200 | 2,030 | 1,986 | 2,214 | 55,100 | 55,200 | 2,337 | 2,250 | 2,532 | 61,100 | 61,200 | 2,655 | 2,514 | 2,850 |
| 49,200 | 49,300 | 2,035 | 1,991 | 2,219 | 55,200 | 55,300 | 2,342 | 2,255 | 2,537 | 61,200 | 61,300 | 2,660 | 2,519 | 2,855 |
| 49,300 | 49,400 | 2,039 | 1,995 | 2,225 | 55,300 | 55,400 | 2,347 | 2,259 | 2,543 | 61,300 | 61,400 | 2,665 | 2,523 | 2,861 |
| 49,400 | 49,500 | 2,044 | 2,000 | 2,230 | 55,400 | 55,500 | 2,352 | 2,264 | 2,548 | 61,400 | 61,500 | 2,670 | 2,528 | 2,866 |
| 49,500 | 49,600 | 2,048 | 2,004 | 2,235 | 55,500 | 55,600 | 2,358 | 2,268 | 2,553 | 61,500 | 61,600 | 2,676 | 2,532 | 2,871 |
| 49,600 | 49,700 | 2,052 | 2,008 | 2,240 | 55,600 | 55,700 | 2,363 | 2,272 | 2,558 | 61,600 | 61,700 | 2,681 | 2,536 | 2,876 |
| 49,700 | 49,800 | 2,057 | 2,013 | 2,246 | 55,700 | 55,800 | 2,368 | 2,277 | 2,564 | 61,700 | 61,800 | 2,686 | 2,541 | 2,882 |
| 49,800 | 49,900 | 2,061 | 2,017 | 2,251 | 55,800 | 55,900 | 2,374 | 2,281 | 2,569 | 61,800 | 61,900 | 2,692 | 2,545 | 2,887 |
| 49,900 | 50,000 | 2,066 | 2,022 | 2,256 | 55,900 | 56,000 | 2,379 | 2,286 | 2,574 | 61,900 | 62,000 | 2,697 | 2,550 | 2,892 |
| 50,0 | 00 | 56,0 | 00 | 62, | 000 | |||||||||
| 50,000 | 50,100 | 2,070 | 2,026 | 2,262 | 56,000 | 56,100 | 2,384 | 2,290 | 2,580 | 62,000 | 62,100 | 2,702 | 2,554 | 2,898 |
| 50,100 | 50,200 | 2,074 | 2,030 | 2,267 | 56,100 | 56,200 | 2,390 | 2,294 | 2,585 | 62,100 | 62,200 | 2,708 | 2,558 | 2,903 |
| 50,200 | 50,300 | 2,079 | 2,035 | 2,272 | 56,200 | 56,300 | 2,395 | 2,299 | 2,590 | 62,200 | 62,300 | 2,713 | 2,563 | 2,908 |
| 50,300 | 50,400 | 2,083 | 2,039 | 2,278 | 56,300 | 56,400 | 2,400 | 2,303 | 2,596 | 62,300 | 62,400 | 2,718 | 2,567 | 2,914 |
| 50,400 | 50,500 | 2,088 | 2,044 | 2,283 | 56,400 | 56,500 | 2,405 | 2,308 | 2,601 | 62,400 | 62,500 | 2,723 | 2,572 | 2,919 |
| 50,500 | 50,600 | 2,093 | 2,048 | 2,288 | 56,500 | 56,600 | 2,411 | 2,312 | 2,606 | 62,500 | 62,600 | 2,729 | 2,576 | 2,924 |
| 50,600 | 50,700 | 2,098 | 2,052 | 2,293 | 56,600 | 56,700 | 2,416 | 2,316 | 2,611 | 62,600 | 62,700 | 2,734 | 2,580 | 2,929 |
| 50,700 | 50,800 | 2,103 | 2,057 | 2,299 | 56,700 | 56,800 | 2,421 | 2,321 | 2,617 | 62,700 | 62,800 | 2,739 | 2,585 | 2,935 |
| 50,800 | 50,900 | 2,109 | 2,061 | 2,304 | 56,800 | 56,900 | 2,427 | 2,325 | 2,622 | 62,800 | 62,900 | 2,745 | 2,589 | 2,940 |
| 50,900 | 51,000 | 2,114 | 2,066 | 2,309 | 56,900 | 57,000 | 2,432 | 2,330 | 2,627 | 62,900 | 63,000 | 2,750 | 2,594 | 2,945 |
| 51,0 | 00 | 57,0 | 00 | 63, | 000 | |||||||||
| 51,000 | 51,100 | 2,119 | 2,070 | 2,315 | 57,000 | 57,100 | 2,437 | 2,334 | 2,633 | 63,000 | 63,100 | 2,755 | 2,598 | 2,951 |
| 51,100 | 51,200 | 2,125 | 2,074 | 2,320 | 57,100 | 57,200 | 2,443 | 2,338 | 2,638 | 63,100 | 63,200 | 2,761 | 2,602 | 2,956 |
| 51,200 | 51,300 | 2,130 | 2,079 | 2,325 | 57,200 | 57,300 | 2,448 | 2,343 | 2,643 | 63,200 | 63,300 | 2,766 | 2,607 | 2,961 |
| 51,300 | 51,400 | 2,135 | 2,083 | 2,331 | 57,300 | 57,400 | 2,453 | 2,347 | 2,649 | 63,300 | 63,400 | 2,771 | 2,611 | 2,967 |
| 51,400 | 51,500 | 2,140 | 2,088 | 2,336 | 57,400 | 57,500 | 2,458 | 2,352 | 2,654 | 63,400 | 63,500 | 2,776 | 2,616 | 2,972 |
| 51,500 | 51,600 | 2,146 | 2,092 | 2,341 | 57,500 | 57,600 | 2,464 | 2,356 | 2,659 | 63,500 | 63,600 | 2,782 | 2,620 | 2,977 |
| 51,600 | 51,700 | 2,151 | 2,096 | 2,346 | 57,600 | 57,700 | 2,469 | 2,360 | 2,664 | 63,600 | 63,700 | 2,787 | 2,624 | 2,982 |
| 51,700 | 51,800 | 2,156 | 2,101 | 2,352 | 57,700 | 57,800 | 2,474 | 2,365 | 2,670 | 63,700 | 63,800 | 2,792 | 2,629 | 2,988 |
| 51,800 | 51,900 | 2,162 | 2,105 | 2,357 | 57,800 | 57,900 | 2,480 | 2,369 | 2,675 | 63,800 | 63,900 | 2,798 | 2,633 | 2,993 |
| 51,900 | 52,000 | 2,167 | 2,110 | 2,362 | 57,900 | 58,000 | 2,485 | 2,374 | 2,680 | 63,900 | 64,000 | 2,803 | 2,638 | 2,998 |
| 52,0 | 00 | 58,0 | 00 | 64, | 000 | |||||||||
| 52,000 | 52,100 | 2,172 | 2,114 | 2,368 | 58,000 | 58,100 | 2,490 | 2,378 | 2,686 | 64,000 | 64,100 | 2,808 | 2,642 | 3,004 |
| 52,100 | 52,200 | 2,178 | 2,118 | 2,373 | 58,100 | 58,200 | 2,496 | 2,382 | 2,691 | 64,100 | 64,200 | 2,814 | 2,646 | 3,009 |
| 52,200 | 52,300 | 2,183 | 2,123 | 2,378 | 58,200 | 58,300 | 2,501 | 2,387 | 2,696 | 64,200 | 64,300 | 2,819 | 2,651 | 3,014 |
| 52,300 | 52,400 | 2,188 | 2,127 | 2,384 | 58,300 | 58,400 | 2,506 | 2,391 | 2,702 | 64,300 | 64,400 | 2,824 | 2,655 | 3,020 |
| 52,400 | 52,500 | 2,193 | 2,132 | 2,389 | 58,400 | 58,500 | 2,511 | 2,396 | 2,707 | 64,400 | 64,500 | 2,829 | 2,660 | 3,025 |
| 52,500 | 52,600 | 2,199 | 2,136 | 2,394 | 58,500 | 58,600 | 2,517 | 2,400 | 2,712 | 64,500 | 64,600 | 2,835 | 2,664 | 3,030 |
| 52,600 | 52,700 | 2,204 | 2,140 | 2,399 | 58,600 | 58,700 | 2,522 | 2,404 | 2,717 | 64,600 | 64,700 | 2,840 | 2,668 | 3,035 |
| 52,700 | 52,800 | 2,209 | 2,145 | 2,405 | 58,700 | 58,800 | 2,527 | 2,409 | 2,723 | 64,700 | 64,800 | 2,845 | 2,673 | 3,041 |
| 52,800 | 52,900 | 2,215 | 2,149 | 2,410 | 58,800 | 58,900 | 2,533 | 2,413 | 2,728 | 64,800 | 64,900 | 2,851 | 2,677 | 3,046 |
| 52,900 | 53,000 | 2,220 | 2,154 | 2,415 | 58,900 | 59,000 | 2,538 | 2,418 | 2,733 | 64,900 | 65,000 | 2,856 | 2,682 | 3,051 |
# But But sepajointly
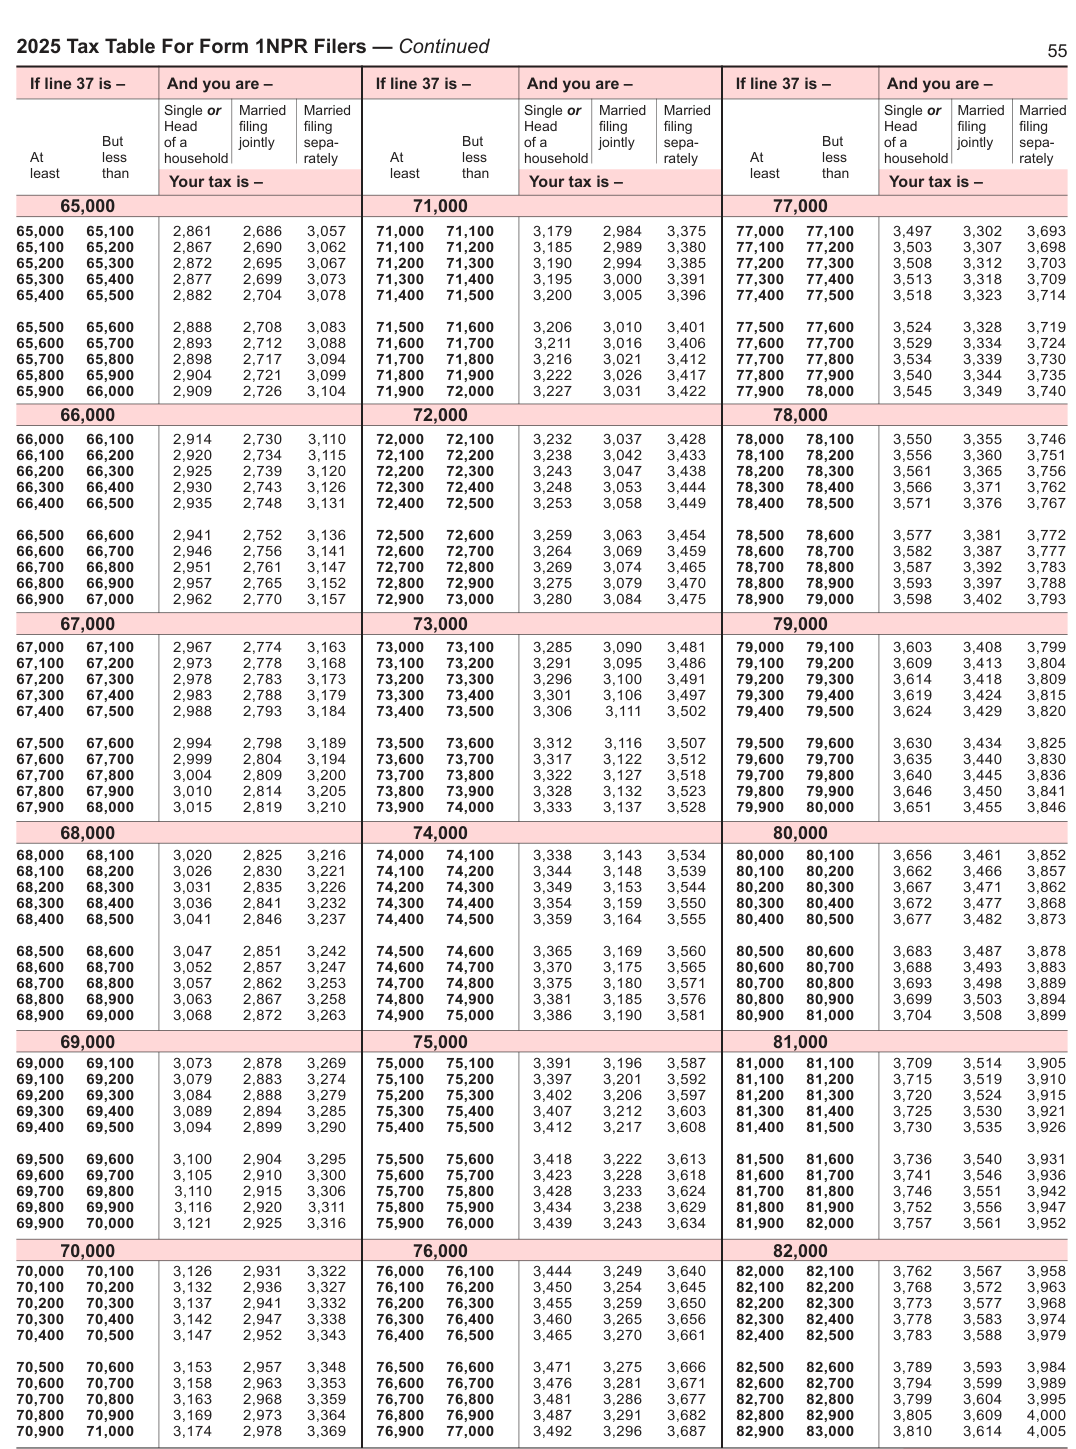
Text version of this table
| 2025 Ta | x | Table | F | or For | m 1NPR | Filers | — Conti | nu | ed | 55 | ||||||||||
| If line 3 | 7 i | s – | A | nd you | are – | If line 37 | is | – | A | nd you | are – | If line 37 | is | – | A | nd you | are – | |||
| S | ingle or | Married | Married | S | ingle or | Married | Married | S | ingle or | Married | Married | |||||||||
| H | ead | filing | filing | H | ead | filing | filing | H | ead | filing | filing | |||||||||
| But | o | f a | jointly | sepa- | But | o | f a | jointly | sepa- | But | o | f a | jointly | sepa- | ||||||
| At | less | h | ousehold | rately | At | less | h | ousehold | rately | At | less | h | ousehold | rately | ||||||
| least | than | least | than | least | than | |||||||||||||||
| Your tax is - | s – | Your tax i | s – | Your tax | is – | |||||||||||||||
| 65, | 00 | 0 | 71,0 | 0 | 0 | 77,0 | 0 | 0 | ||||||||||||
| 65,000 | 65 | ,100 | 2,861 | 2,686 | 3,057 | 71,000 | 71 | ,100 | 3,179 | 2,984 | 3,375 | 77,000 | 77 | ,100 | 3,497 | 3,302 | 3,693 | |||
| 65,100 | 65 | ,200 | 2,867 | 2,690 | 3,062 | 71,100 | 71 | ,200 | 3,185 | 2,989 | 3,380 | 77,100 | 77 | ,200 | 3,503 | 3,307 | 3,698 | |||
| 65,200 | 65 | ,300 | 2,872 | 2,695 | 3,067 | 71,200 | 71 | ,300 | 3,190 | 2,994 | 3,385 | 77,200 | 77 | ,300 | 3,508 | 3,312 | 3,703 | |||
| 65,300 | 65 | ,400 | 2,877 | 2,699 | 3,073 | 71,300 | 71 | ,400 | 3,195 | 3,000 | 3,391 | 77,300 | 77 | ,400 | 3,513 | 3,318 | 3,709 | |||
| 65,400 | 65 | ,500 | 2,882 | 2,704 | 3,078 | 71,400 | 71 | ,500 | 3,200 | 3,005 | 3,396 | 77,400 | 77 | ,500 | 3,518 | 3,323 | 3,714 | |||
| 65,500 | 65 | ,600 | 2,888 | 2,708 | 3,083 | 71,500 | 71 | ,600 | 3,206 | 3,010 | 3,401 | 77,500 | 77 | ,600 | 3,524 | 3,328 | 3,719 | |||
| 65,600 | 65 | ,700 | 2,893 | 2,712 | 3,088 | 71,600 | 71 | ,700 | 3,211 | 3,016 | 3,406 | 77,600 | 77 | ,700 | 3,529 | 3,334 | 3,724 | |||
| 65,700 | 65 | ,800 | 2,898 | 2,717 | 3,094 | 71,700 | 71 | ,800 | 3,216 | 3,021 | 3,412 | 77,700 | 77 | ,800 | 3,534 | 3,339 | 3,730 | |||
| 65,800 | 65 | ,900 | 2,904 | 2,721 | 3,099 | 71,800 | 71 | ,900 | 3,222 | 3,026 | 3,417 | 77,800 | 77 | ,900 | 3,540 | 3,344 | 3,735 | |||
| 65,900 | 66 | ,000 | 2,909 | 2,726 | 3,104 | 71,900 | 72 | ,000 | 3,227 | 3,031 | 3,422 | 77,900 | 78 | ,000 | 3,545 | 3,349 | 3,740 | |||
| 66, | 00 | 0 | 72,0 | 0 | 0 | 78,0 | 0 | 0 | ||||||||||||
| 66,000 | 66 | ,100 | 2,914 | 2,730 | 3,110 | 72,000 | 72 | ,100 | 3,232 | 3,037 | 3,428 | 78,000 | 78 | ,100 | 3,550 | 3,355 | 3,746 | |||
| 66,100 | 66 | ,200 | 2,920 | 2,734 | 3,115 | 72,100 | 72 | ,200 | 3,238 | 3,042 | 3,433 | 78,100 | 78 | ,200 | 3,556 | 3,360 | 3,751 | |||
| 66,200 | 66 | ,300 | 2,925 | 2,739 | 3,120 | 72,200 | 72 | ,300 | 3,243 | 3,047 | 3,438 | 78,200 | 78 | ,300 | 3,561 | 3,365 | 3,756 | |||
| 66,300 | 66 | ,400 | 2,930 | 2,743 | 3,126 | 72,300 | 72 | ,400 | 3,248 | 3,053 | 3,444 | 78,300 | 78 | ,400 | 3,566 | 3,371 | 3,762 | |||
| 66,400 | 66 | ,500 | 2,935 | 2,748 | 3,131 | 72,400 | 72 | ,500 | 3,253 | 3,058 | 3,449 | 78,400 | 78 | ,500 | 3,571 | 3,376 | 3,767 | |||
| 66,500 | 66 | ,600 | 2,941 | 2,752 | 3,136 | 72,500 | 72 | ,600 | 3,259 | 3,063 | 3,454 | 78,500 | 78 | ,600 | 3,577 | 3,381 | 3,772 | |||
| 66,600 | 66 | ,700 | 2,946 | 2,756 | 3,141 | 72,600 | 72 | ,700 | 3,264 | 3,069 | 3,459 | 78,600 | 78 | ,700 | 3,582 | 3,387 | 3,777 | |||
| 66,700 | 66 | ,800 | 2,951 | 2,761 | 3,147 | 72,700 | 72 | ,800 | 3,269 | 3,074 | 3,465 | 78,700 | 78 | ,800 | 3,587 | 3,392 | 3,783 | |||
| 66,800 | 66 | ,900 | 2,957 | 2,765 | 3,152 | 72,800 | 72 | ,900 | 3,275 | 3,079 | 3,470 | 78,800 | 78 | ,900 | 3,593 | 3,397 | 3,788 | |||
| 66,900 | 67 | ,000 | 2,962 | 2,770 | 3,157 | 72,900 | 73 | ,000 | 3,280 | 3,084 | 3,475 | 78,900 | 79 | ,000 | 3,598 | 3,402 | 3,793 | |||
| 67, | 00 | 0 | 73,0 | 0 | 0 | 79,0 | 0 | 0 | ||||||||||||
| 67,000 | 67 | ,100 | 2,967 | 2,774 | 3,163 | 73,000 | 73 | ,100 | 3,285 | 3,090 | 3,481 | 79,000 | 79 | ,100 | 3,603 | 3,408 | 3,799 | |||
| 67,100 | 67 | ,200 | 2,973 | 2,778 | 3,168 | 73,100 | 73 | ,200 | 3,291 | 3,095 | 3,486 | 79,100 | 79 | ,200 | 3,609 | 3,413 | 3,804 | |||
| 67,200 | 67 | ,300 | 2,978 | 2,783 | 3,173 | 73,200 | 73 | ,300 | 3,296 | 3,100 | 3,491 | 79,200 | 79 | ,300 | 3,614 | 3,418 | 3,809 | |||
| 67,300 | 67 | ,400 | 2,983 | 2,788 | 3,179 | 73,300 | 73 | ,400 | 3,301 | 3,106 | 3,497 | 79,300 | 79 | ,400 | 3,619 | 3,424 | 3,815 | |||
| 67,400 | 67 | ,500 | 2,988 | 2,793 | 3,184 | 73,400 | 73 | ,500 | 3,306 | 3,111 | 3,502 | 79,400 | 79 | ,500 | 3,624 | 3,429 | 3,820 | |||
| 67,500 | 67 | ,600 | 2,994 | 2,798 | 3,189 | 73,500 | 73 | ,600 | 3,312 | 3,116 | 3,507 | 79,500 | 79 | ,600 | 3,630 | 3,434 | 3,825 | |||
| 67,600 | 67 | ,700 | 2,999 | 2,804 | 3,194 | 73,600 | 73 | ,700 | 3,317 | 3,122 | 3,512 | 79,600 | 79 | ,700 | 3,635 | 3,440 | 3,830 | |||
| 67,700 | 67 | ,800 | 3,004 | 2,809 | 3,200 | 73,700 | 73 | ,800 | 3,322 | 3,127 | 3,518 | 79,700 | 79 | ,800 | 3,640 | 3,445 | 3,836 | |||
| 67,800 | 67 | ,900 | 3,010 | 2,814 | 3,205 | 73,800 | 73 | ,900 | 3,328 | 3,132 | 3,523 | 79,800 | 79 | ,900 | 3,646 | 3,450 | 3,841 | |||
| 67,900 | 68 | ,000 | 3,015 | 2,819 | 3,210 | 73,900 | 74 | ,000 | 3,333 | 3,137 | 3,528 | 79,900 | 80 | ,000 | 3,651 | 3,455 | 3,846 | |||
| 68, | 00 | 0 | 74,0 | 0 | 0 | 80,0 | 0 | 0 | ||||||||||||
| 68,000 | 68 | ,100 | 3,020 | 2,825 | 3,216 | 74,000 | 74 | ,100 | 3,338 | 3,143 | 3,534 | 80,000 | 80 | ,100 | 3,656 | 3,461 | 3,852 | |||
| 68,100 | 68 | ,200 | 3,026 | 2,830 | 3,221 | 74,100 | 74 | ,200 | 3,344 | 3,148 | 3,539 | 80,100 | 80 | ,200 | 3,662 | 3,466 | 3,857 | |||
| 68,200 | 68 | ,300 | 3,031 | 2,835 | 3,226 | 74,200 | 74 | ,300 | 3,349 | 3,153 | 3,544 | 80,200 | 80 | ,300 | 3,667 | 3,471 | 3,862 | |||
| 68,300 | 68 | ,400 | 3,036 | 2,841 | 3,232 | 74,300 | 74 | ,400 | 3,354 | 3,159 | 3,550 | 80,300 | 80 | ,400 | 3,672 | 3,477 | 3,868 | |||
| 68,400 | 68 | ,500 | 3,041 | 2,846 | 3,237 | 74,400 | 74 | ,500 | 3,359 | 3,164 | 3,555 | 80,400 | 80 | ,500 | 3,677 | 3,482 | 3,873 | |||
| 68,500 | 68 | ,600 | 3,047 | 2,851 | 3,242 | 74,500 | 74 | ,600 | 3,365 | 3,169 | 3,560 | 80,500 | 80 | ,600 | 3,683 | 3,487 | 3,878 | |||
| 68,600 | 68 | ,700 | 3,052 | 2,857 | 3,247 | 74,600 | 74 | ,700 | 3,370 | 3,175 | 3,565 | 80,600 | 80 | ,700 | 3,688 | 3,493 | 3,883 | |||
| 68,700 | 68 | ,800 | 3,057 | 2,862 | 3,253 | 74,700 | 74 | ,800 | 3,375 | 3,180 | 3,571 | 80,700 | 80 | ,800 | 3,693 | 3,498 | 3,889 | |||
| 68,800 | 68 | ,900 | 3,063 | 2,867 | 3,258 | 74,800 | 74 | ,900 | 3,381 | 3,185 | 3,576 | 80,800 | 80 | ,900 | 3,699 | 3,503 | 3,894 | |||
| 68,900 | 69 | ,000 | 3,068 | 2,872 | 3,263 | 74,900 | 75 | ,000 | 3,386 | 3,190 | 3,581 | 80,900 | 81 | ,000 | 3,704 | 3,508 | 3,899 | |||
| 69, | 00 | 0 | 75,0 | 0 | 0 | 81,0 | 0 | 0 | ||||||||||||
| 69,000 | 69 | ,100 | 3,073 | 2,878 | 3,269 | 75,000 | 75 | ,100 | 3,391 | 3,196 | 3,587 | 81,000 | 81 | ,100 | 3,709 | 3,514 | 3,905 | |||
| 69,100 | 69 | ,200 | 3,079 | 2,883 | 3,274 | 75,100 | 75 | ,200 | 3,397 | 3,201 | 3,592 | 81,100 | 81 | ,200 | 3,715 | 3,519 | 3,910 | |||
| 69,200 | 69 | ,300 | 3,084 | 2,888 | 3,279 | 75,200 | 75 | ,300 | 3,402 | 3,206 | 3,597 | 81,200 | 81 | ,300 | 3,720 | 3,524 | 3,915 | |||
| 69,300 | 69 | ,400 | 3,089 | 2,894 | 3,285 | 75,300 | 75 | ,400 | 3,407 | 3,212 | 3,603 | 81,300 | 81 | ,400 | 3,725 | 3,530 | 3,921 | |||
| 69,400 | 69 | ,500 | 3,094 | 2,899 | 3,290 | 75,400 | 75 | ,500 | 3,412 | 3,217 | 3,608 | 81,400 | 81 | ,500 | 3,730 | 3,535 | 3,926 | |||
| 69,500 | 69 | ,600 | 3,100 | 2,904 | 3,295 | 75,500 | 75 | ,600 | 3,418 | 3,222 | 3,613 | 81,500 | 81 | ,600 | 3,736 | 3,540 | 3,931 | |||
| 69,600 | 69 | ,700 | 3,105 | 2,910 | 3,300 | 75,600 | 75 | ,700 | 3,423 | 3,228 | 3,618 | 81,600 | 81 | ,700 | 3,741 | 3,546 | 3,936 | |||
| 69,700 | 69 | ,800 | 3,110 | 2,915 | 3,306 | 75,700 | 75 | ,800 | 3,428 | 3,233 | 3,624 | 81,700 | 81 | ,800 | 3,746 | 3,551 | 3,942 | |||
| 69,800 | 69 | ,900 | 3,116 | 2,920 | 3,311 | 75,800 | 75 | ,900 | 3,434 | 3,238 | 3,629 | 81,800 | 81 | ,900 | 3,752 | 3,556 | 3,947 | |||
| 69,900 | 70 | ,000 | 3,121 | 2,925 | 3,316 | 75,900 | 76 | ,000 | 3,439 | 3,243 | 3,634 | 81,900 | 82 | ,000 | 3,757 | 3,561 | 3,952 | |||
| 70, | 00 | 0 | 76,0 | 0 | 0 | 82,0 | 0 | 0 | ||||||||||||
| 70,000 | 70 | ,100 | 3,126 | 2,931 | 3,322 | 76,000 | 76 | ,100 | 3,444 | 3,249 | 3,640 | 82,000 | 82 | ,100 | 3,762 | 3,567 | 3,958 | |||
| 70,100 | 70 | ,200 | 3,132 | 2,936 | 3,327 | 76,100 | 76 | ,200 | 3,450 | 3,254 | 3,645 | 82,100 | 82 | ,200 | 3,768 | 3,572 | 3,963 | |||
| 70,200 | 70 | ,300 | 3,137 | 2,941 | 3,332 | 76,200 | 76 | ,300 | 3,455 | 3,259 | 3,650 | 82,200 | 82 | ,300 | 3,773 | 3,577 | 3,968 | |||
| 70,300 | 70 | ,400 | 3,142 | 2,947 | 3,338 | 76,300 | 76 | ,400 | 3,460 | 3,265 | 3,656 | 82,300 | 82 | ,400 | 3,778 | 3,583 | 3,974 | |||
| 70,400 | 70 | ,500 | 3,147 | 2,952 | 3,343 | 76,400 | 76 | ,500 | 3,465 | 3,270 | 3,661 | 82,400 | 82 | ,500 | 3,783 | 3,588 | 3,979 | |||
| 70,500 | 70 | ,600 | 3,153 | 2,957 | 3,348 | 76,500 | 76 | ,600 | 3,471 | 3,275 | 3,666 | 82,500 | 82 | ,600 | 3,789 | 3,593 | 3,984 | |||
| 70,600 | 70 | ,700 | 3,158 | 2,963 | 3,353 | 76,600 | 76 | ,700 | 3,476 | 3,281 | 3,671 | 82,600 | 82 | ,700 | 3,794 | 3,599 | 3,989 | |||
| 70,700 | 70 | ,800 | 3,163 | 2,968 | 3,359 | 76,700 | 76 | ,800 | 3,481 | 3,286 | 3,677 | 82,700 | 82 | ,800 | 3,799 | 3,604 | 3,995 | |||
| 70,800 | 70 | ,900 | 3,169 | 2,973 | 3,364 | 76,800 | 76 | ,900 | 3,487 | 3,291 | 3,682 | 82,800 | 82 | ,900 | 3,805 | 3,609 | 4,000 | |||
| 70,900 | 71 | ,000 | 3,174 | 2,978 | 3,369 | 76,900 | 77 | ,000 | 3,492 | 3,296 | 3,687 | 82,900 | 83 | ,000 | 3,810 | 3,614 | 4,005 |
# Married
of a less
At rately rately household household than least than least household than least Your tax is -Your tax is -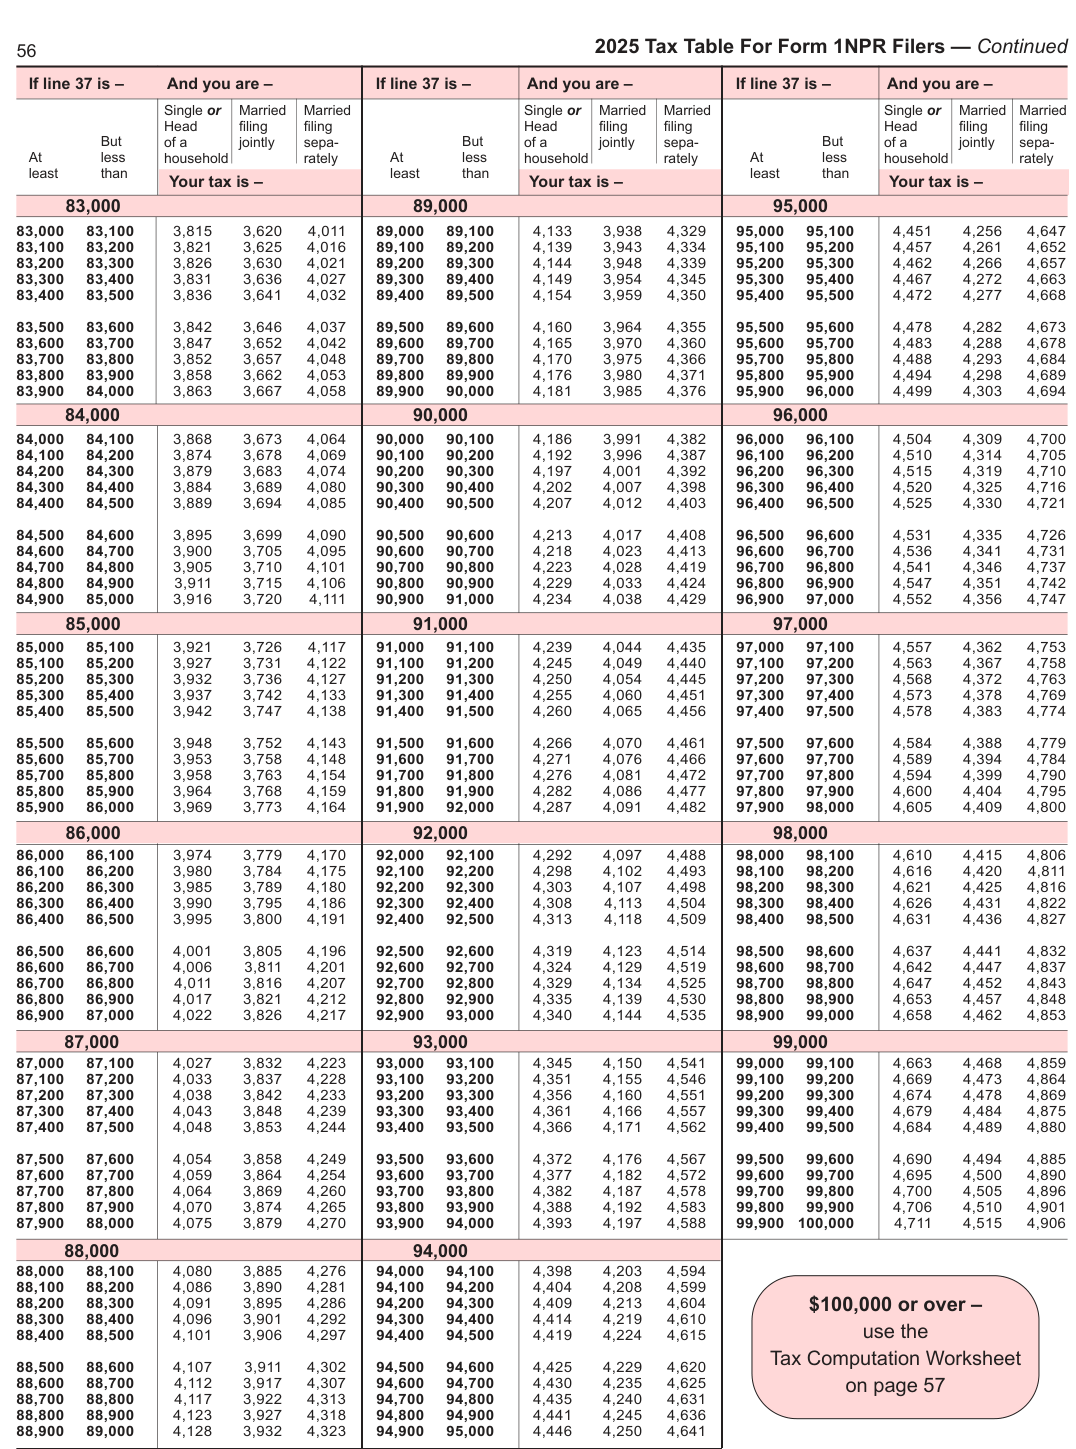
Text version of this table
56 2025 Ta x Table For Fo rm 1NPR Filers — Continued If line 3 7 is – A nd you are – If line 37 is – A nd you are – If line 37 is – And you are – S ingle or Married Married S ingle or Married Married Single or Ma rried Married H ead filing filing H ead filing filing Head filin g filing But o f a jointly sepa- But o f a jointly sepa- But of a joi ntly sepa- At less h ousehold rately At less h ousehold rately At less household rately least than least than least than Your tax is - s – Your tax i s – Your tax is – 83 ,000 89,0 0 0 95, 00 0 83,000 83,100 3,815 3,620 4,011 89,000 89 ,100 4,133 3,938 4,329 95,000 95 ,100 4,451 4, 256 4,647 83,100 83,200 3,821 3,625 4,016 89,100 89 ,200 4,139 3,943 4,334 95,100 95 ,200 4,457 4, 261 4,652 83,200 83,300 3,826 3,630 4,021 89,200 89 ,300 4,144 3,948 4,339 95,200 95 ,300 4,462 4, 266 4,657 83,300 83,400 3,831 3,636 4,027 89,300 89 ,400 4,149 3,954 4,345 95,300 95 ,400 4,467 4, 272 4,663 83,400 83,500 3,836 3,641 4,032 89,400 89 ,500 4,154 3,959 4,350 95,400 95 ,500 4,472 4, 277 4,668 83,500 83,600 3,842 3,646 4,037 89,500 89 ,600 4,160 3,964 4,355 95,500 95 ,600 4,478 4, 282 4,673 83,600 83,700 3,847 3,652 4,042 89,600 89 ,700 4,165 3,970 4,360 95,600 95 ,700 4,483 4, 288 4,678 83,700 83,800 3,852 3,657 4,048 89,700 89 ,800 4,170 3,975 4,366 95,700 95 ,800 4,488 4, 293 4,684 83,800 83,900 3,858 3,662 4,053 89,800 89 ,900 4,176 3,980 4,371 95,800 95 ,900 4,494 4, 298 4,689 83,900 84,000 3,863 3,667 4,058 89,900 90 ,000 4,181 3,985 4,376 95,900 96 ,000 4,499 4, 303 4,694 84 ,000 90,0 0 0 96, 00 0 84,000 84,100 3,868 3,673 4,064 90,000 90 ,100 4,186 3,991 4,382 96,000 96 ,100 4,504 4, 309 4,700 84,100 84,200 3,874 3,678 4,069 90,100 90 ,200 4,192 3,996 4,387 96,100 96 ,200 4,510 4, 314 4,705 84,200 84,300 3,879 3,683 4,074 90,200 90 ,300 4,197 4,001 4,392 96,200 96 ,300 4,515 4, 319 4,710 84,300 84,400 3,884 3,689 4,080 90,300 90 ,400 4,202 4,007 4,398 96,300 96 ,400 4,520 4, 325 4,716 84,400 84,500 3,889 3,694 4,085 90,400 90 ,500 4,207 4,012 4,403 96,400 96 ,500 4,525 4, 330 4,721 84,500 84,600 3,895 3,699 4,090 90,500 90 ,600 4,213 4,017 4,408 96,500 96 ,600 4,531 4, 335 4,726 84,600 84,700 3,900 3,705 4,095 90,600 90 ,700 4,218 4,023 4,413 96,600 96 ,700 4,536 4, 341 4,731 84,700 84,800 3,905 3,710 4,101 90,700 90 ,800 4,223 4,028 4,419 96,700 96 ,800 4,541 4, 346 4,737 84,800 84,900 3,911 3,715 4,106 90,800 90 ,900 4,229 4,033 4,424 96,800 96 ,900 4,547 4, 351 4,742 84,900 85,000 3,916 3,720 4,111 90,900 91 ,000 4,234 4,038 4,429 96,900 97 ,000 4,552 4, 356 4,747 85 ,000 91,0 0 0 97, 00 0 85,000 85,100 3,921 3,726 4,117 91,000 91 ,100 4,239 4,044 4,435 97,000 97 ,100 4,557 4, 362 4,753 85,100 85,200 3,927 3,731 4,122 91,100 91 ,200 4,245 4,049 4,440 97,100 97 ,200 4,563 4, 367 4,758 85,200 85,300 3,932 3,736 4,127 91,200 91 ,300 4,250 4,054 4,445 97,200 97 ,300 4,568 4, 372 4,763 85,300 85,400 3,937 3,742 4,133 91,300 91 ,400 4,255 4,060 4,451 97,300 97 ,400 4,573 4, 378 4,769 85,400 85,500 3,942 3,747 4,138 91,400 91 ,500 4,260 4,065 4,456 97,400 97 ,500 4,578 4, 383 4,774 85,500 85,600 3,948 3,752 4,143 91,500 91 ,600 4,266 4,070 4,461 97,500 97 ,600 4,584 4, 388 4,779 85,600 85,700 3,953 3,758 4,148 91,600 91 ,700 4,271 4,076 4,466 97,600 97 ,700 4,589 4, 394 4,784 85,700 85,800 3,958 3,763 4,154 91,700 91 ,800 4,276 4,081 4,472 97,700 97 ,800 4,594 4, 399 4,790 85,800 85,900 3,964 3,768 4,159 91,800 91 ,900 4,282 4,086 4,477 97,800 97 ,900 4,600 4, 404 4,795 85,900 86,000 3,969 3,773 4,164 91,900 92 ,000 4,287 4,091 4,482 97,900 98 ,000 4,605 4, 409 4,800 86 ,000 92,0 0 0 98, 00 0 86,000 86,100 3,974 3,779 4,170 92,000 92 ,100 4,292 4,097 4,488 98,000 98 ,100 4,610 4, 415 4,806 86,100 86,200 3,980 3,784 4,175 92,100 92 ,200 4,298 4,102 4,493 98,100 98 ,200 4,616 4, 420 4,811 86,200 86,300 3,985 3,789 4,180 92,200 92 ,300 4,303 4,107 4,498 98,200 98 ,300 4,621 4, 425 4,816 86,300 86,400 3,990 3,795 4,186 92,300 92 ,400 4,308 4,113 4,504 98,300 98 ,400 4,626 4, 431 4,822 86,400 86,500 3,995 3,800 4,191 92,400 92 ,500 4,313 4,118 4,509 98,400 98 ,500 4,631 4, 436 4,827 86,500 86,600 4,001 3,805 4,196 92,500 92 ,600 4,319 4,123 4,514 98,500 98 ,600 4,637 4, 441 4,832 86,600 86,700 4,006 3,811 4,201 92,600 92 ,700 4,324 4,129 4,519 98,600 98 ,700 4,642 4, 447 4,837 86,700 86,800 4,011 3,816 4,207 92,700 92 ,800 4,329 4,134 4,525 98,700 98 ,800 4,647 4, 452 4,843 86,800 86,900 4,017 3,821 4,212 92,800 92 ,900 4,335 4,139 4,530 98,800 98 ,900 4,653 4, 457 4,848 86,900 87,000 4,022 3,826 4,217 92,900 93 ,000 4,340 4,144 4,535 98,900 99 ,000 4,658 4, 462 4,853 87 ,000 93,0 0 0 99, 00 0 87,000 87,100 4,027 3,832 4,223 93,000 93 ,100 4,345 4,150 4,541 99,000 99 ,100 4,663 4, 468 4,859 87,100 87,200 4,033 3,837 4,228 93,100 93 ,200 4,351 4,155 4,546 99,100 99 ,200 4,669 4, 473 4,864 87,200 87,300 4,038 3,842 4,233 93,200 93 ,300 4,356 4,160 4,551 99,200 99 ,300 4,674 4, 478 4,869 87,300 87,400 4,043 3,848 4,239 93,300 93 ,400 4,361 4,166 4,557 99,300 99 ,400 4,679 4, 484 4,875 87,400 87,500 4,048 3,853 4,244 93,400 93 ,500 4,366 4,171 4,562 99,400 99 ,500 4,684 4, 489 4,880 87,500 87,600 4,054 3,858 4,249 93,500 93 ,600 4,372 4,176 4,567 99,500 99 ,600 4,690 4, 494 4,885 87,600 87,700 4,059 3,864 4,254 93,600 93 ,700 4,377 4,182 4,572 99,600 99 ,700 4,695 4, 500 4,890 87,700 87,800 4,064 3,869 4,260 93,700 93 ,800 4,382 4,187 4,578 99,700 99 ,800 4,700 4, 505 4,896 87,800 87,900 4,070 3,874 4,265 93,800 93 ,900 4,388 4,192 4,583 99,800 99 ,900 4,706 4, 510 4,901 87,900 88,000 4,075 3,879 4,270 93,900 94 ,000 4,393 4,197 4,588 99,900 100 ,000 4,711 4, 515 4,906 88 ,000 94,0 0 0 88,000 88,100 4,080 3,885 4,276 94,000 94 ,100 4,398 4,203 4,594 88,100 88,200 4,086 3,890 4,281 94,100 94 ,200 4,404 4,208 4,599 88,200 88,300 4,091 3,895 4,286 94,200 94 ,300 4,409 4,213 4,604 $ 100,00 0 or over – 88,300 88,400 4,096 3,901 4,292 94,300 94 ,400 4,414 4,219 4,610 88,400 88,500 4,101 3,906 4,297 94,400 94 ,500 4,419 4,224 4,615 us e the Tax C omputa tion Work sheet 88,500 88,600 4,107 3,911 4,302 94,500 94 ,600 4,425 4,229 4,620 88,600 88,700 4,112 3,917 4,307 94,600 94 ,700 4,430 4,235 4,625 on p age 57 88,700 88,800 4,117 3,922 4,313 94,700 94 ,800 4,435 4,240 4,631 88,800 88,900 4,123 3,927 4,318 94,800 94 ,900 4,441 4,245 4,636 88,900 89,000 4,128 3,932 4,323 94,900 95 ,000 4,446 4,250 4,641
# Tax Computation Worksheet
Caution Use the Tax Computation Worksheet to figure your tax if your taxable income is $100,000 or more.
Section A - Use if your filing status is Single or Head of household. Complete the row below that applies to you.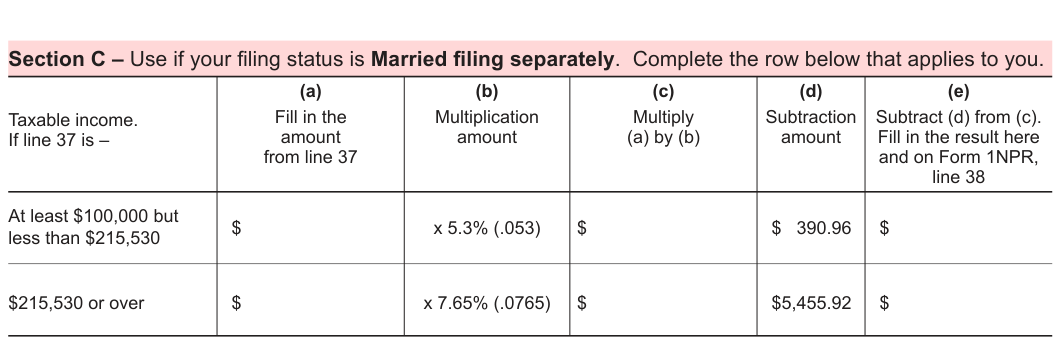
Text version of this table
Section C – Use if your filing status is Married filing separately. Complete the row below that applies to you. Taxable income. If line 37 is – (a) Fill in the amount from line 37 (b) Multiplication amount (c) Multiply (a) by (b) (d) Subtraction amount (e) Subtract (d) from (c). Fill in the result here and on Form 1NPR, line 38 At least $100,000 but less than $431,060 $ x 5.3% (.053) $ $ 390.96 $ $215,530 or over $ x 7.65% (.0765) $ $5,455.92 $
58 WISCONSIN SCHOOL DISTRICT NUMBER Appearing below is an alphabetical listing of Wisconsin school districts.
Full-year and part-year residents - refer to this listing and find the number of the district in which you lived on December 31, 2025. If you moved out of Wisconsin during 2025, fill in the number of the school district in which you lived before moving. Fill in this number in the name and address area of your return. Failure to include your school district number may delay the processing of your return and any refund due. Nonresidents - don't fill in this line.
The listing is divided into two sections. SECTION I lists all districts which operate high schools. SECTION II lists those districts which operate schools having only elementary grades.
Your school district will generally be the name of the municipality where the public high school is located which any children at your home would be entitled to attend. However, if such high school is a "union high school," refer to SECTION II and find the number of your elementary district.
The listing has the names of the school districts only to help you find your district number. Don't write in the name of your school district or the name of any specific school. Fill in only your school district's number on the school district line in the name and address area of your return.
For example:
- If you lived in the city of Milwaukee, you will fill in the number 3619 on the school district line.
- If you lived in the city of Hartford, you would refer to SECTION II and find the number 2443, which is the number for Jt. No. 1 Hartford elementary district.
The following are other factors to consider in determining your school district number:
- If you lived in one school district but worked in another, fill in the district number where you lived.
- If you were temporarily living away from your permanent home, fill in the district number of your permanent home.
Note If you can't identify your school district, contact your municipal clerk or local school for help.
# SECTION I - SCHOOL DISTRICTS OPERATING HIGH SCHOOLS
STEVENS POINT … 5607
STOCKBRIDGE … 5614
STOUGHTON … 5621
STRATFORD … 5628
STURGEON BAY … 5642
SUN PRAIRIE … 5656
SUPERIOR … 5663
SURING … 5670
THORP … 5726
THREE LAKES … 5733
TIGERTON … 5740
TOMAH … 5747
TOMAHAWK … 5754
TOMORROW RIVER … 0126
TRI-COUNTY … 4375
TURTLE LAKE … 5810
TWO RIVERS … 5824
UNION GROVE UHS … *
UNITY … 0238
VALDERS … 5866
VERONA … 5901
VIROQUA … 5985
WABENO … 5992
WASHBURN … 6027
WASHINGTON … 6069
WATERFORD UHS … *
WATERLOO … 6118
WATERTOWN … 6125
WAUKESHA … 6174
WAUNAKEE … 6181
WAUPACA … 6195
WAUPUN … 6216
WAUSAU … 6223
WAUSAUKEE … 6230
WAUTOMA … 6237
WAUWATOSA … 6244
WAUZEKA-STEUBEN … 6251
WEBSTER … 6293
# WEST ALLIS-WEST
MILWAUKEE … 6300
WEST BEND … 6307
WEST SALEM … 6370
WESTBY … 6321
WEST DE PERE … 6328
WESTFIELD … 6335
WESTON … 6354
# WEYAUWEGA-
FREMONT … 6384
WHITEFISH BAY … 6419
WHITEHALL … 6426
WHITE LAKE … 6440
WHITEWATER … 6461
WHITNALL … 6470
WILD ROSE … 6475
WILLIAMS BAY … 6482
WILMOT UHS … *
WINNECONNE … 6608
WINTER … 6615
WISCONSIN DELLS … 6678
WISCONSIN HEIGHTS...0469
WISCONSIN RAPIDS … 6685
WITTENBERG-
BIRNAMWOOD … 6692
# WONEWOC-UNION
CENTER … 6713
WRIGHTSTOWN … 6734
PESHTIGO … 4305
PEWAUKEE … 4312
PHELPS … 4330
PHILLIPS … 4347
PITTSVILLE … 4368
PLATTEVILLE … 4389
PLUM CITY … 4459
PLYMOUTH … 4473
PORTAGE … 4501
PORT EDWARDS … 4508
# PORT WASHINGTON-
SAUKVILLE … 4515
POTOSI … 4529
POYNETTE … 4536
PRAIRIE DU CHIEN … 4543
PRAIRIE FARM … 4557
PRENTICE … 4571
PRESCOTT … 4578
PRINCETON … 4606
PULASKI … 4613
RACINE … 4620
RANDOLPH … 4634
RANDOM LAKE … 4641
REEDSBURG … 4753
REEDSVILLE … 4760
RHINELANDER … 4781
RIB LAKE … 4795
RICE LAKE … 4802
RICHLAND … 4851
RIO … 4865
RIPON AREA … 4872
RIVERDALE … 3850
RIVER FALLS … 4893
RIVER RIDGE … 4904
RIVER VALLEY … 5523
ROSENDALE-
BRANDON … 4956
ROSHOLT … 4963
ROYALL … 1673
# SAINT CROIX
CENTRAL … 2422
SAINT CROIX FALLS … 5019
SAINT FRANCIS … 5026
SAUK PRAIRIE … 5100
SENECA … 5124
SEVASTOPOL … 5130
SEYMOUR … 5138
SHAWANO … 5264
SHEBOYGAN … 5271
SHEBOYGAN FALLS … 5278
SHELL LAKE … 5306
SHIOCTON … 5348
SHOREWOOD … 5355
SHULLSBURG … 5362
SIREN … 5376
SLINGER … 5390
SOLON SPRINGS … 5397
SOMERSET … 5432
SOUTH MILWAUKEE … 5439
SOUTH SHORE … 4522
SOUTHERN DOOR CO...5457
# SOUTHWESTERN
WISCONSIN … 2485
SPARTA … 5460
SPENCER … 5467
SPOONER … 5474
SPRING VALLEY … 5586
STANLEY-BOYD … 5593
MCFARLAND … 3381
MEDFORD … 3409
MELLEN … 3427
MELROSE-MINDORO … 3428
MENASHA … 3430
MENOMINEE INDIAN … 3434
MENOMONEE FALLS … 3437
MENOMONIE … 3444
MEQUON-
THIENSVILLE … 3479
MERCER … 3484
MERRILL … 3500
# MIDDLETON-CROSS
PLAINS … 3549
MILTON … 3612
MILWAUKEE … 3619
MINERAL POINT … 3633
MISHICOT … 3661
MONDOVI … 3668
MONONA GROVE … 3675
MONROE … 3682
MONTELLO … 3689
MONTICELLO … 3696
MOSINEE … 3787
MOUNT HOREB … 3794
MUKWONAGO … 3822
MUSKEGO-NORWAY … 3857
NECEDAH … 3871
NEENAH … 3892
NEILLSVILLE … 3899
NEKOOSA … 3906
NEW AUBURN … 3920
NEW BERLIN … 3925
NEW GLARUS … 3934
NEW HOLSTEIN … 3941
NEW LISBON … 3948
NEW LONDON … 3955
NEW RICHMOND … 3962
NIAGARA … 3969
NICOLET UHS … *
NORRIS … 3976
NORTH CRAWFORD … 2016
NORTH FOND DU LAC...3983
NORTHERN OZAUKEE..1945
NORTHLAND PINES … 1526
NORTHWOOD … 3654
NORWALK-ONTARIO-
WILTON … 3990
# OAK CREEK-
FRANKLIN … 4018
OAKFIELD … 4025
OCONOMOWOC … 4060
OCONTO … 4067
OCONTO FALLS … 4074
OMRO … 4088
ONALASKA … 4095
OOSTBURG … 4137
OREGON … 4144
OSCEOLA … 4165
OSHKOSH … 4179
OSSEO-FAIRCHILD … 4186
OWEN-WITHEE … 4207
PALMYRA-EAGLE … 4221
PARDEEVILLE … 4228
PARKVIEW … 4151
PECATONICA … 0490
PEPIN … 4270
GREENFIELD … 2303
GREEN LAKE … 2310
GREENWOOD … 2394
GRESHAM … 2415
HAMILTON … 2420
HARTFORD UHS … *
HAYWARD … 2478
HIGHLAND … 2527
HILBERT … 2534
HILLSBORO … 2541
HOLMEN … 2562
HORICON … 2576
HORTONVILLE AREA … 2583
HOWARD-SUAMICO … 2604
HOWARDS GROVE … 2605
HUDSON … 2611
HURLEY … 2618
HUSTISFORD … 2625
INDEPENDENCE … 2632
IOLA-SCANDINAVIA … 2639
IOWA-GRANT … 2646
ITHACA … 2660
JANESVILLE … 2695
JEFFERSON … 2702
JOHNSON CREEK … 2730
JUDA … 2737
KAUKAUNA … 2758
KENOSHA … 2793
KETTLE MORAINE … 1376
KEWASKUM … 2800
KEWAUNEE … 2814
KICKAPOO … 5960
KIEL … 2828
KIMBERLY … 2835
KOHLER … 2842
LA CROSSE … 2849
LADYSMITH … 2856
LA FARGE … 2863
# LAKE GENEVA-
GENOA CITY UHS … *
LAKE HOLCOMBE … 2891
LAKELAND UHS … *
LAKE MILLS … 2898
LANCASTER … 2912
LAONA … 2940
LENA … 2961
LITTLE CHUTE … 3129
LODI … 3150
LOMIRA … 3171
LOYAL … 3206
LUCK … 3213
LUXEMBURG-CASCO … 3220
MADISON … 3269
MANAWA … 3276
MANITOWOC … 3290
MAPLE … 3297
MARATHON CITY … 3304
MARINETTE … 3311
MARION … 3318
MARKESAN … 3325
MARSHALL … 3332
MARSHFIELD … 3339
MAUSTON … 3360
MAYVILLE … 3367
CLEAR LAKE … 1127
CLINTON … 1134
CLINTONVILLE … 1141
# COCHRANE-
FOUNTAIN CITY … 1155
COLBY … 1162
COLEMAN … 1169
COLFAX … 1176
COLUMBUS … 1183
CORNELL … 1204
CRANDON … 1218
CRIVITZ … 1232
CUBA CITY … 1246
CUDAHY … 1253
CUMBERLAND … 1260
D C EVEREST … 4970
DARLINGTON … 1295
DEERFIELD … 1309
DE FOREST … 1316
DELAVAN-DARIEN … 1380
DENMARK … 1407
DE PERE … 1414
DE SOTO … 1421
DODGELAND … 2744
DODGEVILLE … 1428
DRUMMOND … 1491
DURAND-ARKANSAW … 1499
EAST TROY … 1540
EAU CLAIRE … 1554
EDGAR … 1561
EDGERTON … 1568
ELCHO … 1582
ELEVA-STRUM … 1600
# ELKHART LAKE-
GLENBEULAH … 1631
ELKHORN … 1638
ELK MOUND … 1645
ELLSWORTH … 1659
ELMBROOK … 0714
ELMWOOD … 1666
EVANSVILLE … 1694
FALL CREEK … 1729
FALL RIVER … 1736
FENNIMORE … 1813
FLAMBEAU … 5757
FLORENCE CO … 1855
FOND DU LAC … 1862
FORT ATKINSON … 1883
FRANKLIN … 1900
FREDERIC … 1939
FREEDOM … 1953
# GALESVILLE-ETTRICK-
TREMPEALEAU … 2009
GERMANTOWN … 2058
GIBRALTAR … 2114
GILLETT … 2128
GILMAN … 2135
GILMANTON … 2142
GLENWOOD CITY … 2198
# GOODMAN-
ARMSTRONG … 2212
GRAFTON … 2217
GRANTON … 2226
GRANTSBURG … 2233
GREEN BAY … 2289
GREENDALE … 2296
ABBOTSFORD … 0007
ADAMS-FRIENDSHIP … 0014
ALBANY … 0063
ALGOMA … 0070
ALMA … 0084
ALMA CENTER … 0091
# ALMOND-
BANCROFT … 0105
ALTOONA … 0112
AMERY … 0119
ANTIGO … 0140
APPLETON … 0147
ARCADIA … 0154
ARGYLE … 0161
ARROWHEAD UHS … *
ASHLAND … 0170
ASHWAUBENON … 0182
ATHENS … 0196
AUBURNDALE … 0203
AUGUSTA … 0217
BALDWIN-WOODVILLE..0231
BANGOR … 0245
BARABOO … 0280
BARNEVELD … 0287
BARRON … 0308
BAYFIELD … 0315
BEAVER DAM … 0336
# BEECHER-DUNBAR-
PEMBINE … 4263
BELLEVILLE … 0350
BELMONT … 0364
BELOIT … 0413
BELOIT TURNER … 0422
BENTON … 0427
BERLIN … 0434
BIG FOOT UHS … *
BIRCHWOOD … 0441
BLACK HAWK … 2240
BLACK RIVER FALLS … 0476
BLAIR-TAYLOR … 0485
BLOOMER … 0497
BONDUEL … 0602
BOSCOBEL AREA … 0609
BOWLER … 0623
BOYCEVILLE … 0637
BRILLION … 0658
BRODHEAD … 0700
BROWN DEER … 0721
BRUCE … 0735
BURLINGTON … 0777
BUTTERNUT … 0840
CADOTT … 0870
CAMBRIA-FRIESLAND...0882
CAMBRIDGE … 0896
CAMERON … 0903
CAMPBELLSPORT … 0910
CASHTON … 0980
CASSVILLE … 0994
CEDARBURG … 1015
CEDAR GROVE-
BELGIUM … 1029
CENTRAL/WESTOSHA … *
CHEQUAMEGON … 1071
# CHETEK-
WEYERHAEUSER … 1080
CHILTON … 1085
CHIPPEWA FALLS … 1092
CLAYTON … 1120
School District No.
GLENDALE-
RIVER HILLS … 2184
HARTFORD, JT #1 … 2443
HARTLAND-
LAKESIDE, JT #3 … 2460
# HERMAN-NEOSHO-
RUBICON … 2525
HOLY HILL AREA … 2570
MINOCQUA, JT #1 … 3640
NORTH CAPE … 4690
NORTH LAKE … 3514
NORTH LAKELAND … 0616
NORWAY, JT #7 … 4011
PARIS, JT #1 … 4235
RANDALL, JT #1 … 4627
RAYMOND, #14 … 4686
UNION GROVE, JT #1 ...5859
WALWORTH, JT #1 … 6022
# WASHINGTON-
CALDWELL … 6104
WATERFORD, JT #1 … 6113
WHEATLAND, JT #1 … 6412
WOODRUFF, JT #1 … 6720
YORKVILLE, JT #2 … 6748
*This is a "Union High School" district. Refer to Section II of this listing and determine the number of your elementary school district.
# SECTION II - SCHOOL DISTRICTS OPERATING ONLY ELEMENTARY SCHOOLS
School District No. School District No. School District No. School District No. School District No.
LAC DU FLAMBEAU #1 .1848
LAKE COUNTRY … 3862
LAKE GENEVA, JT #1 … 2885
LINN, JT #4 … 3087
LINN, JT #6 … 3094
# MAPLE DALE-
INDIAN HILL … 1897
# MERTON COMMUNITY .3528
BRIGHTON, #1 … 0657
BRISTOL, #1 … 0665
DOVER, #1 … 1449
ERIN … 1687
FONTANA, JT #8 … 1870
FOX POINT, JT #2 … 1890
GENEVA, JT #4 … 2044
GENOA CITY, JT #2 … 2051
RICHMOND … 3122
SALEM … 5068
SHARON, JT #11 … 5258
SILVER LAKE, JT #1 … 5369
STONE BANK … 3542
SWALLOW … 3510
TREVOR-WILMOT … 5780
TWIN LAKES, #4 … 5817
# INDEX to Form 1NPR Instructions
Page
ABLE accounts … 22, 26
Address, where to file … 7
Adoption expenses … 26
Age … 11
Aliens … 3, 14, 15, 27
Alimony … 19, 25
Amended returns . . . 7, 8, 14, 44, 45, 46 Amount you owe … 46 Archer MSA deduction … 26 Armed forces personnel … 3 Assembling your return … 6 Basis of assets … 20, 22, 27 Business income or loss … 19 Business moving expenses … 22 Capital gain and loss … 20 College savings accounts . . . . . . . 22, 26 Column A and B instructions … 16 Combat zone death … 26 Copies of prior returns … 12 Credit card payments … 46 Credits Additional child and dependent care . 30 Angel investment … 10, 36, 38 Biodiesel fuel production … 35 Blind worker transportation services . 30 Business development … 23, 44, 45 Capital investment … 35 Community rehabilitation program . 23, 35 Dairy and livestock farm investment … 35 Development zones … 35 Early stage seed investment . 10, 35, 38 Earned income … 40 Economic development … 35 Electronic medical records … 36 Electronics and information technology manufacturing zone … 23, 44, 45 Employee college savings account contribution … 23, 35 Enterprise zone jobs … 23, 44, 45 Ethanol and biodiesel fuel pump … 35 Farmland preservation … 23, 40 Health insurance risk-sharing … 35 Historic rehabilitation . . . . . 9, 10, 35, 38 Homestead … 41, 45 Internet equipment … 36 Itemized deduction … 29 Low-income housing … 10, 35, 38 Manufacturer's sales tax … 35 Manufacturing and agriculture . . . 23, 35 Manufacturing investment … 35 Married couple … 34 Postsecondary education … 35 Repayment … 40 Research … 23, 35, 44 School property tax … 31 Tax paid to another state … 36 Technology zone … 35
Page
# Credits (continued)
Veterans and surviving spouses property tax … 41 Working families … 34 Death of a taxpayer … 12 Dependents … 4, 28 Differences in federal and Wisconsin law … 16 Disability income exclusion … 17, 26 Disaster relief work … 4, 17, 19 Disregarded entity … 7 Dividend income … 18 Domicile … 3 Donations … 37 Educator expenses … 23 Electronic filing … 6 Estimated tax … 11, 39, 45 Exemptions … 28 Extension of time to file … 5 Farm income or loss … 22 Farm loss carryover … 27 Filing assistance … 13 Filing status … 15 Forms-where to get … 13 Health savings accounts … 23 Income taxed by Wisconsin … 4 Installment payments … 47 Insurance policy sale … 27 Interest income … 18 Internal Revenue Service adjustments and amended returns . 11 Internet address … 13 IRA deduction … 25 IRA distributions … 20 Jury duty pay … 26 Legal residence (domicile) questionnaire … 16, 60 Long-term care insurance … 26, 29 Lump-sum distributions … 21, 22 Marital property income … 23, 27 Medical care insurance … 26, 29 Military pay … 26 Modifications … 22, 26 Moving expenses … 23 Name and address … 14 Net operating loss … 27 Olympic medals and prize money. 26, 27 Organ donation … 27, 37 Other adjustments … 26 Other gains or losses … 20 Other income … 22 Partnership, trust, or estate … 21 Passive foreign investment company . 22 Penalties Early withdrawal … 25 Fraudulent or reckless claim … 11 Inconsistent estate basis … 38 Not filing or filing incorrect return … 11 Other … 38
Page
Retirement plans, IRAs, and MSAs . . 38 Selling assets purchased from related person … 38 Pensions and annuities … 21 Physician or psychiatrist grant … 27 Private delivery services … 7 Private school tuition … 26 Publications … 13 Railroad retirement benefits … 26 Ratio … 27 Recoveries of federal itemized deductions … 27 Refund … 7, 8, 44 Refunds, state income taxes … 19 Related entity expenses … 22, 27 Related party sales … 27, 38 Rents, royalties, partnerships, estates, trusts, etc … 21 Repayment of income previously taxed . 27 Repayment of SUB benefits … 26 Reservists, performing artists and fee-basis government officials … 23 Residence, sale of … 20 Resident status … 3, 16 Retirement benefits … 21, 26 Rounding to whole dollars … 17 Sales and use tax due … 36 School district number … 15, 58 Self-employed health insurance … 25 Self-employed SEP and SIMPLE, etc. . 24 Self-employment tax, deduction … 24 Sign your return … 47 Social security benefits … 22 Social security number … 14 Special conditions … 14 Standard deduction … 28, 48 Student loan interest … 26 Tax … 29 Tax district … 15 Tax period … 14 Tax-option (S) corporation … 21 Tax table … 51 Third party designee … 47 Tips on paper filing … 6 Tuition and fees … 26 Underpayment interest … 45 Unemployment compensation … 22 Wages, residents of Illinois, Indiana, Kentucky, or Michigan … 17 Wages, salaries, tips, etc … 17 When to file … 5 Where to file … 7 Which form to file … 5 Who must file … 4 Withholding … 38
Full-year Wisconsin resident; did not change domicile from Wisconsin during 2025.
Changed legal residence from Wisconsin during 2025; have not moved back to Wisconsin.
Changed legal residence from Wisconsin during or before 2025; have moved back to Wisconsin.
Changed legal residence to Wisconsin from (state or country) on (date) during 2025; no previous Wisconsin residency. If you check this box, do not complete the rest of the questionnaire.
Was a nonresident of Wisconsin for all of 2025. Resident of
(Nonresident alien; please indicate country)
- a. On what date did you move from Wisconsin? b. When you moved from Wisconsin, did you intend to move back to Wisconsin? If yes, when? c. If you moved back to Wisconsin, indicate date and explain the circumstances under which you moved back to Wisconsin.
- Did you establish a legal residence in another state? If yes, in which state and on what date?
- After establishing legal residency in the new state, list the dates you were in Wisconsin.
- When were you physically present in your new state of legal residence (please list dates)?
- Did your spouse and dependent children (if any) move to your new state of legal residence? If yes, when?
- a. On what date did you begin working in your new state of legal residence? b. Was your job permanent, temporary, or seasonal? Check one and explain
- In your new state of legal residence, referred to in question 2, did you: a. Register to vote? If yes, when? If no, why not? b. Purchase a home? If yes, when? If no, why not? c. Obtain a driver's license? If yes, when? If no, why not? d. Register an auto or other vehicle? If yes, when? If no, why not? e. File resident income tax returns? If yes, what years filed? If no, why not?
- Since changing your legal residence from Wisconsin, have you: a. Performed services for income in Wisconsin? If yes, when? b. Purchased/renewed Wisconsin auto license plates? If yes, when? c. Renewed a Wisconsin driver's license? If yes, when? d. Voted in Wisconsin, in person or by absentee ballot? If yes, when? e. Attended or sent your children to Wisconsin schools? If yes, when? f. Purchased a Wisconsin resident hunting, fishing, or trapping license? If yes, when?
Type of license? County purchased in? g. Listed Wisconsin as your state of legal residence for purposes of your auto insurance? h. Listed Wisconsin as your state of legal residence for purposes of your will? i. Listed Wisconsin as your state of legal residence for purposes of any legal proceedings? If yes, when? j. Obtained or renewed any Wisconsin trade or professional licenses or union memberships? If yes, when?
- If you answered "yes" to any of the questions 8a through 8j, please explain why you have taken such action.
- Did you or your spouse own the real estate you occupied as your home while living in Wisconsin? If yes, have you disposed of it? If yes, when? If you still own the Wisconsin home, what use do you make of it and how often?
- If you established a legal residence in a new state but are using a Wisconsin address on your 2025 tax returns, please explain.
# Legal Residence (Domicile) Questionnaire
Your answers to these questions will be used to determine your legal residence. Certain types of income are either taxable or nontaxable to Wisconsin based upon whether you were a legal resident of Wisconsin at the time you received such income.
Form 1NPR may be returned to you or its processing delayed if the questionnaire is not completed. If the questionnaire does not fit your situation or you want to submit additional information, include an additional sheet describing your particular circumstances.
If you changed your legal residence from Wisconsin during 2024 or 2025 and you did not previously complete a questionnaire for that change, answer the following questions.
SOCIAL SECURITY NUMBER
NAME(S)
Please one: (If married filing joint return check one box for each spouse.)
I-151 Legal Residence Questionnaire Wisconsin Department of Revenue
Spouse
You
Source: view the official PDF
Nearby sections (16 sections)
- a-222 · A-222 — Power of Attorney
- a-771 · A-771 — Disclosure Authorization (Third-Party Access)
- form-1 · Form 1 — Wisconsin Income Tax (resident)
- form-1npr · Form 1NPR — Nonresident & Part-Year Resident Income Tax
- form-2 · Form 2 — Wisconsin Fiduciary Income Tax (Estates & Trusts)
- form-3 · Form 3 — Wisconsin Partnership Return
- form-4 · Form 4 — Wisconsin Corporation Franchise/Income Tax
- form-4t · Form 4T — Exempt Organization Business Franchise/Income
- form-5s · Form 5S — Tax-Option (S) Corporation
- form-6 · Form 6 — Combined Wisconsin Corporation Franchise/Income
- pw-1 · PW-1 — Nonresident Pass-Through Withholding
- pw-2 · PW-2 — Nonresident Withholding Exemption
- s-211 · S-211 — Sales and Use Tax Exemption Certificate
- schedule-3-et · Schedule 3-ET — PTET Election (Partnership)
- schedule-3k-1 · Schedule 3K-1 — Partner's Share of Income
- schedule-5k-1 · Schedule 5K-1 — Shareholder's Share (S-Corp)