New Jersey Division of Taxation Form Instructions
Instructions for Form NJ-1041 — Income Tax Return for Estates and Trusts
# Table of Contents
General Filing Information … 2 Who Must File … 2 Period Covered by Return … 3 When to File … 3 Extension of Time to File … 3 Name, Address, and Identification Number … 4 Income … 5
Schedule NJ-BUS-1 - Business Income Summary … 6 Schedule A - Net Gains or Income From Disposition of Property … 12 Schedule B - Beneficiaries' Shares of Income … 13 Schedule C - Credit for Income or Wage Taxes Paid by New Jersey
Estates or Trusts to Other Jurisdictions … 14 Schedule D - Allocation of Business Income to New Jersey … 15 Schedule E - New Jersey Income of Nonresident Estates and Trusts … 15 How to Pay … 16 Penalties, Interest, and Collection Fees … 16 Where to Mail … 17 Amended Return … 17
Schedule NJK-1 … 17 NJ-NR-A - Business Allocation Schedule … 18 Tax Table … 19 Tax Rate Schedules … 27 Information, Forms, and Assistance … 29
Things to Know Before Beginning the 2025 NJ-1041
# Definitions
Fiduciary means a guardian, trustee, executor, administrator, receiver, conservator, or any person acting in any trust or similar capacity.
The term estates refers only to the estates of deceased persons. The New Jersey Gross Income Tax liability for minors, persons adjudicated incompetent, or for any person who is suffering from some other legal disability must be calculated on the same form as that used for any other individual taxpayer, but it may be prepared in the name of the disabled individual and signed by the guardian or conservator.
# Who Must File a Return
Resident Estates and Trusts
The fiduciary of every resident estate or trust must file a
# New Jersey Gross Income Tax Fiduciary Return (Form
NJ-1041) if gross income, before exemptions or deductions, was more than $10,000 (prorated for the number of months covered by a part-year return) during the tax year.
A resident estate or trust is not subject to New Jersey tax if it:
- Does not have any tangible assets in New Jersey;
- Does not have any income from New Jersey sources; and
- Does not have any trustees or executors in New Jersey.
However, the fiduciary must file Form NJ-1041 for such estate or trust, enclose a statement certifying that the estate or trust is not subject to tax, and check the box on line 27.
Resident estate or trust means:
- The estate of a decedent who at their death was domiciled in New Jersey; or
- A trust, or a portion of a trust, consisting of property transferred by will of a decedent who at their death was domiciled in New Jersey; or
- A trust, or portion of a trust, consisting of the property of: a. A person domiciled in New Jersey at the time such property was transferred to the trust, if such trust or portion of a trust was then irrevocable, or if it was then revocable and has not subsequently become irrevocable; or b. A person domiciled in New Jersey at the time such trust, or portion of a trust, became irrevocable, if it was revocable when such property was transferred to the trust but has subsequently become irrevocable.
For the purposes of the foregoing, domicile is the place an individual regards as their permanent home—the place to which they intend to return after a period of absence. A domicile, once established, continues until a new, fixed, and permanent home is acquired. No change of domicile results from moving to a new location if the intention is to remain only for a limited time even if it is for a relatively long duration.
A resident estate or trust does not include charitable trusts or trusts that are part of a pension or profit-sharing plan.
Revocable/Irrevocable Trust. A trust or portion of a trust is revocable if it is subject to a power, exercisable immediately or at any future time, to revest title in the person whose property constitutes such trust or portion of a trust, and a trust or portion of a trust becomes irrevocable when the possibility that such power may be exercised has been terminated.
Grantor Trust. Grantor trusts are required to file a New Jersey Gross Income Tax Fiduciary Return. If the grantor trust income is reportable by or taxable to the grantor for federal income tax purposes, it also is taxable to the grantor for New Jersey Income Tax purposes. (See the line-by-line instructions for distributions.) Charitable Trust. A charitable trust is a trust operated exclusively for a religious, charitable, scientific, literary, or educational purpose. Income of a charitable trust is exempt from Income Tax. However, income received by a charitable trust that is not distributed or credited to its beneficiaries is subject to tax in the tax year of the trust.
If the terms of the governing instrument of an estate or trust require any amount of income to be accumulated and added to the principal for ultimate distribution to any religious, charitable, scientific, literary, or educational organization and such income is permanently and irrevocably set aside for such purposes, it will be treated as having been paid, credited, or required to be distributed to the charitable beneficiary. The same treatment is afforded to any income required to be held in trust for the use of any charitable beneficiary or organization.
In general, income that is deemed to have been paid, credited, or required to be distributed to a beneficiary is taxable to such beneficiary. However, if the beneficiary is an exempt charitable organization, no tax will be imposed. This is true even if the income is permanently and irrevocably set aside in an invested income account.
Nonresident Estates and Trusts
The fiduciary of every nonresident estate or trust that derived income from New Jersey sources must file a
# New Jersey Gross Income Tax Fiduciary Return (Form
NJ-1041) if the gross income received from all sources (both inside and outside New Jersey) during the tax year was more than $10,000 (prorated for the number of months covered by a part-year return) before exemptions or deductions.
A nonresident estate or trust does not include charitable trusts or pension or profit-sharing trusts. The residence of the fiduciary does not affect the nonresident classification of an estate or trust.
Gross income from sources within New Jersey for a nonresident estate or trust means those items of income and gain that are earned, received, or acquired from the following sources:
- By reason of ownership or disposition of any interest in real or tangible personal property in New Jersey; or
- In connection with a trade, profession, or occupation carried on in New Jersey or for the rendition of personal services performed in New Jersey; or
- As a distributive share of the income of a business, profession, enterprise, undertaking, or other activity as the result of work done, services rendered, or other business activities conducted in New Jersey except as allocated to another state; or
- From intangible personal property employed in a trade, profession, occupation, or business carried on in New Jersey; or
- Income of a New Jersey S corporation allocated to
New Jersey; or
- Net gambling winnings from New Jersey sources, including New Jersey Lottery winnings from prize amounts over $10,000.
Electing Small Business Trusts
A federal Electing Small Business Trust can make a New Jersey election to be taxed in the same manner as for federal tax purposes. See Form NJ-1041SB for election information, filing instructions, and tax forms.
# Period Covered by Return
The 2025 return filed by an administrator or an executor of an estate must cover the period from January 1, 2025, or fiscal year beginning in 2025, or the date of death of decedent (if death occurred after January 1, 2025) to the end of the tax year selected by the fiduciary when appropriate. The 2025 return filed by a trustee of a trust must cover the period beginning January 1, 2025.
The tax year for the estate or trust must be the same as for federal income tax purposes. The tax year cannot be longer than 12 months. All income received by the executor, administrator, or trustee in the tax year must be reported on the return.
# When to File
Form NJ-1041 must be filed on or before the 15th day of the fourth month following the close of the tax year of the estate or trust.
# Extension of Time to File
There is no extension of time to pay tax due - only to file. Penalties and interest will be charged if the tax is paid after the original due date.
You can receive a 5½-month extension of time to file if at least 80% of the tax liability calculated (line 29) is paid through withholdings, estimated, or other payments by the original due date, and
- You enclose a copy of your federal Application for Automatic Extension, if filed by paper, and check the box at the top of Form NJ‑1041 (or enter your confirmation number in the space provided at the top of Form NJ‑1041 if the extension application or payment was filed online or by phone); or
- You file Form NJ‑630, Application for Extension of Time to File New Jersey Gross Income Tax Return, by the original due date of the return. You can also file an extension application online until 11:59 p.m. on the original due date.
If you do not meet the requirements for an extension, or you do not file the return by the extended due date, we will deny your extension request and charge penalties and interest from the original due date of the return. (See "Penalties, Interest, and Collection Fees" on page 16.) You will not receive an approved copy of your extension request. We will notify you only if we deny your request, but not until after the return is actually filed.
# Filling Out the Form Properly
- Use only a 2025 return for the 2025 Tax Year.
- Use only blue or black ink.
- Do not use dollar signs or dashes.
- Do not report a loss on Form NJ-1041 (see page 5).
You will need your bank's 9-digit routing number and your account number to pay by e-check. Do not enter the check number as part of the account number. Note: The routing and account numbers may be in different places on your check.
- To request a refund, you must enter an amount on line 42.
- The name and federal employer identification number must be entered on all schedules accompanying the return.
# Rounding
Instead of making dollars-and-cents entries on your return, you can round and use whole dollar amounts. If you round, do so for all lines, and enter "00" after the decimal for cents.
Round amounts of 50 cents or more up to the next whole dollar. For example, $26.78 becomes $27.00.
Round amounts of less than 50 cents down to the next whole dollar. For example, $13.45 becomes $13.00.
Round the total, not the amounts used to calculate the total. For example, the sum of $13.45 and $46.24 is $59.69, which becomes $60.00.
# Number
Print or type the name of the estate or trust, the name and title of the fiduciary, complete address, and ZIP
Code. Check the "Change of Address" box if the address has changed since the last time a New Jersey return was filed. Enter the federal employer identification number in the space provided.
Lines 1-4 - Residency Status Indicate the residency status of the estate or trust by checking the appropriate box provided at each line. Indicate in the space provided the date of the decedent's death or the date the trust was created. If the estate or trust is a resident of a state other than New Jersey, enter the name of the state. In the space provided, indicate the type of trust (i.e., simple trust, complex trust, grantor type trust).
Line 5 - Estate Closed or Trust
# Terminated
If the estate was closed or the trust terminated, check the box and indicate the date of closing or termination.
Also write "final return" at the top of the form.
# Gubernatorial Elections Fund
A fiduciary can designate $1 to help candidates for Governor pay campaign expenses by checking the "Yes" box. Checking the "Yes" box will not reduce the refund or increase the amount owed.
For more information on the Gubernatorial Public Financing Program, contact the New Jersey Election Law Enforcement Commission at 609-292-8700 or online.
# Digital Assets
are any digital representations of value that are recorded on a cryptographically secured, distributed ledger or any similar technology. Digital assets include, but are not limited to, non-fungible tokens (NFTs) and virtual currencies, such as cryptocurrencies and stablecoins. If an asset has the characteristics of a digital asset, it is treated as a digital asset for Gross Income Tax purposes.
If the estate or trust either received (as a reward, award, or payment for property or services) or sold, exchanged, or otherwise disposed of a digital asset or any financial interest in any digital asset, check the "Yes" box. Otherwise, check the "No" box. If you answer yes, you must report the income in the appropriate category of income.
If the estate or trust disposed of any digital asset that was held as a capital asset, through a sale, trade, exchange, payment, or other transfer, use Schedule A to calculate the amount to report on line 9.
If the estate or trust received any digital asset(s) as compensation for services, report the income as you would report other wage income. If the estate or trust disposed of any digital asset(s) that you held for sale to customers in the ordinary course of a trade or business, report the income as you would report other business income.
If income was received in connection with digital assets that is not reported elsewhere on your return, include the amounts on line 13.
# Income
Estates and trusts (whether resident or nonresident) must report on lines 6 through 13 taxable income received from all sources (both inside and outside New Jersey) during the tax year. (Nonresident estates or trusts must complete lines 6-13 as if the income was earned by a resident estate or trust. Nonresident estates or trusts also must complete Schedule E to report their income from New Jersey sources. See the instructions for Schedule E on page 15.) Reporting Losses. If you have a net loss in any category of income, remember the following:
- Do not report a loss on the NJ-1041 (e.g., in parentheses or as a negative number);
- Net losses can be combined with gains in the same category of income. For example, you can subtract a loss from one partnership from a gain from another partnership during the tax year;
- Net losses in one category of income cannot be applied against income or gains in another on Form NJ-1041. For example, you cannot subtract a partnership loss from interest income;
- If there is a net loss in any income category, enter "0" on that line of your NJ-1041. Do not enter the amount of the loss in parentheses or as a negative number;
- No carryback or carryover of losses is allowed when reporting income on your NJ-1041.
Accounting Method. Use the same accounting method for New Jersey Income Tax that was used for federal income tax purposes. Income must be recognized and reported in the same period as it is recognized and reported for federal purposes.
Line 6 - Interest
Enter all taxable interest from sources both inside and outside New Jersey.
Common sources of taxable interest:
- Banks;
- Savings and loan associations;
- Credit unions;
- Checking accounts;
- Bonds and notes;
- Certificates of deposit;
- Life insurance dividends;
- Distributions from Coverdell education savings accounts (ESAs), but only the earnings portion;
- Ginnie Maes, Fannie Maes, Freddie Macs;
- Repurchase agreements;
- Obligations of other states and their political subdivisions, other than New Jersey;
- Any other interest not specifically exempt.
Amounts paid by a mutual fund or other regulated investment company are includable in gross income unless the fund is a qualified investment fund as defined by New Jersey law, or to the extent that the distributions are attributable to interest earned on federal obligations.
Do not include on this line:
- Interest that was earned and paid to a sole proprietorship, a partnership, or an S corporation. Report on Schedule NJ-BUS-1. Note: Interest paid or deemed to have been paid by a partnership or S corporation and reported on Form 1099 must be included as interest on line 6;
- Interest that was earned and paid to another estate or trust (other than a grantor trust). Report on line 13 (grantor trusts, see the instructions for Schedule B, line 47).
Forfeiture Penalty for Early Withdrawal. If a penalty is incurred for withdrawing a time deposit early, you can subtract the amount of the penalty from the interest income.
Tax-Exempt Interest Income. In the space provided, enter all tax-exempt interest, including the exempt portion of a distribution from a New Jersey qualified investment fund. If exempt interest is more than $10,000, you must enclose a listing of the amount received from each source.
For more information on tax-exempt interest income and New Jersey qualified investment funds, see GIT-5, Nontaxable Investment Income.
Line 7 - Dividends
Enter the dividends received from investments (e.g., from stocks, mutual funds) or other income-producing activities that do not constitute a trade or business. The total taxable dividends received, regardless of where earned, must be reported. For dividends received from a mutual fund or other regulated investment company, see the instructions for interest income at line 6.
Do not include on this line:
- Dividends that were earned and paid to a sole proprietorship, a partnership, or an S corporation.
Report on Schedule NJ-BUS-1;
- Dividends that were earned and paid to another estate or trust (other than a grantor trust). Report on line 13 (grantor trusts, see the instructions for Schedule B, line 47).
Distributions out of earnings and profits of corporations are required to be reported in the year received by the shareholder.
Tax-Free Distributions. A distribution that is a return of investment or capital and does not come out of earnings and profits is a nontaxable capital or tax-free distribution.
These distributions reduce the basis of the stock or investment, and are not taxable until the investment is fully recovered.
Capital gain dividends, under New Jersey law, are taxable in full as capital gains. Dividends reinvested in a public utility are taxable.
Line 8 - Net Profits From Business Complete Part I of Schedule NJ-BUS-1 and enter on line 8 the amount from line 4 of Part I. If the amount on line 4 is a loss, enter "0" on line 8. See instructions on page 6. Enclose Schedule NJ-BUS-1 and a copy of the federal Schedule C or F for each business with the return.
Line 9 - Net Gains or Income From
# Disposition of Property
Enter the amount from Schedule A, line 46. If the amount on line 46 is a loss, enter "0" on line 9. Enclose a copy of federal Schedule D. If the estate or trust sold real property in New Jersey, enclose the Settlement Statement (HUD-1) for each property sold.
Do not include on Schedule A:
- Gains/losses from the disposition of property owned by a sole proprietorship, a partnership, or an S corporation. Report on Schedule NJ-BUS-1;
- Gains/losses from the disposition of property owned by another estate or trust (other than a grantor trust). Report on line 13 (grantor trusts, see the instructions for Schedule B, line 47).
Line 10 - Net Gains or Income From Rents, Royalties, Patents, and Copyrights Complete Part II of Schedule NJ-BUS-1 and enter on line 10 the amount from line 4 of Part II. If the amount on line 4 is a loss, enter "0" on line 10. See instructions on page 7. Enclose Schedule NJ-BUS-1 and a copy of federal Schedule E with the return.
Line 11 - Distributive Share of
# Partnership Income
Complete Part III of Schedule NJ-BUS-1 and enter on line 11 the amount from line 4 of Part III. If the amount on line 4 is a loss, enter "0" on line 11. See instructions on page 8. Enclose Schedule NJ-BUS-1 and a copy of
Schedule NJK-1, Form NJ-1065, for each partnership with the return. If the estate or trust did not receive a Schedule NJK-1, a copy of the federal Schedule K-1 must be enclosed.
Line 12 - Net Pro Rata Share of S
# Corporation Income
Complete Part IV of Schedule NJ-BUS-1 and enter on line 12 the amount from line 4 of Part IV. If the amount on line 4 is a loss, enter "0" on line 12. See instructions on page 8. Enclose Schedule NJ-BUS-1 and a copy of Schedule NJ-K-1, Form CBT-100S, for each S corporation with the return. If the estate or trust did not receive a Schedule NJ-K-1, a copy of the federal Schedule K-1 must be enclosed.
# Schedule NJ-BUS-1
# Part I - Net Profits From Business
Report the net profits or loss from a business, trade, profession, or other activity carried on by the estate or trust. Make the following adjustments to federal Schedule C or F.
- Add any amounts deducted for taxes based on income.
- Subtract interest reported on federal Schedule C or F that is exempt for New Jersey purposes but taxable for federal purposes.
- Add interest not reported on federal Schedule C or F from states or political subdivisions outside New Jersey that is exempt for federal purposes.
- Add interest and dividends derived in the conduct of a trade or business.
- Add or subtract income or losses derived in the conduct of a trade or business from rentals, royalties, patents, or copyrights.
- Add or subtract gains or losses from the sale, exchange, or other disposition of the trade or business's property. Do not include New Jersey exempt securities.
- Deduct meal and entertainment expenses that constitute ordinary expenses incurred in the conduct of a trade or business but that were not allowed on the federal return.
- Deduct your qualified contributions to a self-employed 401(k) Plan. Contributions that exceeded the federal limits are not deductible for New Jersey purposes.
- Add or subtract the net adjustment from the Gross Income Tax Depreciation Adjustment Worksheet GIT-DEP, Part I, line 7.
- Cannabis licensees: Deduct expenses that would have been eligible to be claimed as a deduction for federal purposes but were disallowed because cannabis is a controlled substance under federal law.
Sole proprietorships providing primary care services in a qualified medical or dental practice that is located in or within five miles of a designated Health Enterprise Zone (HEZ) may be able to deduct a percentage of the net income from that practice on line 19. See Technical Bulletin TB-56 for eligibility requirements and instructions for calculating the HEZ deduction.
For an income-producing activity to constitute a business or profession, it must be a commercial enterprise regularly conducted for profit and meet the criteria listed in N.J.A.C. 18:35-1.1, Net Profits From Business.
Example
A trust invests in stock for its own financial benefit. It does not offer its investment services to others for a fee. It derives substantial income (gains from the sale of stock, interest, and dividends) from the investment activities. The trust's income is not net profits from a business or profession. It must report this income as gains from the sale of stock, interest, and dividends.
# Lines 1-3
For each business, enter the following information. If you need more space, enclose a statement with the return listing any additional businesses and the related profit or loss.
- Business name as listed on federal Schedule C or F
- Social Security number or federal employer identification number (EIN)
- Profit or (loss) as adjusted for New Jersey purposes
Line 4
Add the amounts in the Profit or (Loss) column and enter the total on line 4, netting profits with losses. Enter this amount on line 8, Form NJ-1041. If the netted amount is a loss, enter "0" on line 8.
Part II - Net Gains or Income From Rents, Royalties, Patents, and Copyrights Report net gains or income less net losses from rents, royalties, patents, and copyrights of the estate or trust.
Depreciation and Expense Deduction. New Jersey and federal depreciation and expense deduction limits are different.
A New Jersey depreciation adjustment may be needed for assets placed in service on or after January 1, 2004. Complete the Gross Income Tax Depreciation Adjustment Worksheet GIT‑DEP to calculate the adjustment.
Passive Losses. There is no distinction between active and passive losses for New Jersey purposes. You cannot carry back or carry forward such losses when reporting income on Form NJ-1041. You can deduct federal passive losses in full in the year incurred against any gain within the same category of income.
Do not include in Part II:
- Gains/losses from rents, royalties, patents, and copyrights from property owned by a sole proprietorship, a partnership, or an S corporation. Report in Parts I, III, or IV of Schedule NJ-BUS-1;
- Gains/losses from rents, royalties, patents, and copyrights from property owned by an estate or trust (other than a grantor trust). Report on line 13 (grantor trusts, see the instructions for Schedule B, line 47).
# Lines 1-3
For each source of income or loss, enter the following information. If you need more space, enclose a statement with the return listing any additional property and income or loss.
- Property name or description. For rental real estate, enter the physical address of the property
- Social Security number or federal employer identification number (EIN)
- Type of property. Enter the following number that corresponds with the type of property:
- Royalties
- Patents
# 4. Copyrights
- Gain or (loss) for each type of property.
Line 4
Add the amounts in the Income or (Loss) column and enter the total on line 4, netting gains with losses. Enter this amount on line 10, Form NJ-1041. If the netted amount is a loss, enter "0" on line 10.
Part III - Distributive Share of Partnership Income Report the estate's or trust's share of income or loss from partnership(s), whether or not the income was actually distributed.
# Lines 1-3
For each partnership, enter the following information. If you need more space, enclose a statement with the return listing any additional partnerships and the related income or loss.
- Partnership name as listed on Schedule NJK-1 (or federal Schedule K-1)
- Federal employer identification number (EIN)
- The estate's or trust's share of partnership income (or loss) as reported on the Schedule NJK-1 (column A of the line labeled Distributive Share of Partnership Income). If the estate or trust did not receive a Schedule NJK-1, enclose a copy of the federal Schedule K-1 and complete Reconciliation Worksheet A contained in GIT-9P, Partnership Income.
- Total amount of New Jersey Income Tax paid on behalf of the estate or trust by partnership(s) as shown on Schedule NJK-1, line 1, Part III, nonresident partner's share of New Jersey tax
- The estate's or trust's share of Pass-Through Business Alternative Income Tax as reported on Schedule PTE-K-1 or Schedule NJK-1 received from the partnership
Line 4
Add the amounts in the Share of Partnership Income or (Loss) column and enter the total on line 4, netting income with losses. Enter this amount on line 11, Form NJ-1041. If the netted amount is a loss, enter "0" on line 11.
Line 5
Add the amounts in the Share of tax paid on your behalf by Partnerships column and enter the total. Include this amount on line 35a, Form NJ-1041. See the instructions for line 35a.
Line 6
Add the amounts in the Share of Pass-Through Business Alternative Business Income Tax column and enter the total. Include this amount on line 36a, Form NJ-1041.
For more information, see GIT-9P, Partnership Income.
Part IV - Net Pro Rata Share of S Corporation Income Report the amount of the estate's or trust's net pro rata share of S corporation income or loss, whether or not the income was actually distributed.
# Lines 1-3
For each S corporation, enter the following information. If you need more space, enclose a statement with the return listing any additional S corporations and the related income or loss.
- S corporation name as listed on Schedule NJ-K-1 (or federal Schedule K-1)
- Federal employer identification number (EIN)
- Pro rata share of S corporation income or (usable loss) as reported on the Schedule NJ-K-1. If the estate or trust did not receive a Schedule NJ-K-1, enclose a copy of the federal Schedule K-1 and complete Reconciliation Worksheet B contained in GIT-9S, Income From S Corporations.
- The estate's or trust's share of Pass-Through Business Alternative Income Tax as reported on Schedule PTE-K-1 or Schedule NJ-K-1 received from the S corporation
Line 4
Add the amounts in the Pro Rata Share of S Corporation Income or (Usable Loss) column and enter the total on line 4, netting income with losses. Enter this amount on line 12, Form NJ-1041. If the netted amount is a loss, enter "0" on line 12.
Line 5
Add the amounts in the Share of Pass-Through Business Alternative Business Income Tax column and enter the total. Include this amount on line 36a, Form NJ-1041.
For more information, see GIT‑9S, Income From S Corporations.
Line 13 - Other Income
Enter the amount of taxable income for which a space is not provided elsewhere on the return. Also state the nature of this income. If additional space is needed, enclose a statement with the return.
# Line 14 - Gross Income
Add lines 6 through 13 and enter the total.
If the total is $10,000 or less (prorated for the number of months covered by a part-year return), there is no New Jersey tax liability and no return is required. If the return is being filed only for a refund of estimated payments made and/or other credits, complete Schedule B, Beneficiaries' Shares of Income, and line 15. Then continue completing the return at line 34.
Line 15 - Deduction for Distributions to
# Beneficiaries
Enter the amount from Schedule B, line 48A.
Line 16 - Total Income
Subtract line 15 from line 14 and enter the result.
# Nonresident Estates and Trusts Only:
Caution: Nonresident estates and trusts must complete Schedule E before completing line 16a. (See the instructions for Schedule E on page 15.) Line 16a - NJ Income from Schedule E, line 11 Enter on this line the total amount of income from New Jersey sources from Schedule E, line 11.
Line 17 - Income Commissions Enter commissions that are specifically related to income reported on line 14 and paid or accrued to the Executor or Trustee. Deductible commissions are those measured as a percentage of income. Fixed fee commissions are not deductible. Enclose a schedule showing the calculation of the commissions.
Line 18 - Exemption
Enter $1,000. If the return covers less than a full calendar year, prorate the exemption to reflect the period covered by the return.
Line 19 - Health Enterprise Zone
# Deduction
Eligible taxpayers providing primary care services at a qualified medical and/or dental practice located in or within five miles of a designated Health Enterprise Zone (HEZ), may be able to deduct a percentage of the net income from that practice.
Enter the HEZ deduction for a qualified practice as follows:
- Partners - Use the amount from Part III of the
Schedule NJK-1, Form NJ-1065, received from the practice;
- S corporation shareholders - Use the amount from Part V of the Schedule NJ-K-1, Form CBT-100S, received from the practice;
- Sole proprietors - Determine the allowable HEZ deduction and enclose a schedule showing how it was calculated.
For eligibility requirements and instructions for calculating the HEZ deduction, see Technical Bulletin TB-56.
Line 20 - Alternative Business Calculation
# Adjustment
If Schedule NJ-BUS-1 was completed and there was a loss on line 4 of any part, the estate or trust may be eligible for an income adjustment. An estate or trust that had a loss carryforward on Schedule NJ-BUS-2 from a prior year may also be eligible. Complete Schedule NJ-BUS-2 and enter on line 20 the amount from line 11 of the schedule.
Enclose Schedule NJ-BUS-2 with the return and keep a completed copy. The estate or trust may need the information to complete the return in future years.
Line 21 - NJBEST Deduction
If gross income was $200,000 or less, you can deduct up to $10,000 of contributions made during the year into an NJBEST (New Jersey Better Educational Savings Trust) account.
Line 22 - Total Deductions and
# Exemption
Add lines 17 through 21 and enter the total.
Line 23 - Taxable Income
Subtract line 22 from line 16 and enter the result.
Line 24 - Taxable Income
Enter on line 24 the taxable income from line 23.
# Nonresident Estates and Trusts Only:
Line 25 - Tax on Amount on Line 24 If the income on line 24 is less than $110,000, use the Tax Table on page 19. Otherwise, calculate the tax using the Tax Rate Schedule on page 27. Enter the tax on line 25.
Line 26 - Income Percentage
Divide the amount on line 16a by the amount on line 16.
Carry your result to four decimal places. For example, if the amounts used were $20,000 (line 16a) divided by $30,000 (line 16), the result would be 66.67% or .6667.
In certain situations, the income percentage can exceed 100%. For example, a nonresident estate or trust realizes a $50,000 gain from the sale of real property in New Jersey and sustains a $10,000 loss from the sale of property in Florida. This nonresident taxpayer (which has no other income) reports $40,000 as total income (line 16) and $50,000 as income from New Jersey sources (line 16a). The income percentage is 125% (or 1.25) calculated as follows:
$50,000 (line 16a) ÷ $40,000 (line 16).
Line 27 - Tax
Resident Estates and Trusts
If the income on line 24 is less than $110,000, use the Tax Table on page 19. Otherwise, calculate the tax using the Tax Rate Schedule on page 27. Enter the tax on line 27.
Note: A resident estate or trust that does not have any tangible assets in New Jersey or any income from New Jersey sources, and does not have any trustees or executors in New Jersey is not subject to New Jersey tax.
Check the box and enclose a statement with the return certifying that the estate or trust is not subject to tax.
Nonresident Estates and Trusts
Multiply the amount on line 25 by the income percentage on line 26 and enter the result.
Line 28 - Credit for Income or Wage
# Trusts to Other Jurisdictions
Enter the amount of credit allowed from Schedule C, line 53.
Line 29 - Balance of Tax
Subtract line 28 from line 27 and enter the result.
Line 30 - Sheltered Workshop Tax Credit Enter your Sheltered Workshop Tax Credit for the current year from Part IV, line 12 of Form GIT-317. Enclose Form GIT-317 with the return and keep a completed copy.
Line 31 - Balance of Tax After Credit Subtract line 30 from line 29 and enter the result.
Line 32 - Interest on Underpayment of
# Estimated Tax
New Jersey Income Tax is a pay-as-you-go tax. You must pay tax on the income as it is earned or received.
If you do not pay enough tax on the income throughout the year, the estate or trust may have to pay installment interest.
Installment interest may be charged if:
- The total tax is more than $400 (after subtracting withholdings and other credits); and
- You did not pay (by withholdinngs or estimated payments) at least 80% of the tax liability during the year.
To calculate the amount of interest for the underpayment of estimated tax, complete Form NJ-2210, Underpayment of Estimated Tax by Individuals, Estates, or Trusts.
Enter on line 32 the amount from line 19, Form NJ-2210, and check the box. Enclose Form NJ-2210 with the return.
Exceptions. Estimated tax payments are not required from:
- A decedent's estate for any tax year ending before the date that is two years after the decedent's death; or
- A trust that was treated as owned by the decedent if the trust will receive the residue of the decedent's estate under the will (or if no will is admitted to probate, the trust primarily responsible for paying debts, taxes, and expenses of administration) for any tax year ending before the date that is two years after the decedent's death.
For more information, see GIT-8, Estimating Income
Taxes.
Line 33 - Total Tax and Penalty Add lines 31 and 32 and enter the total.
Line 34 - New Jersey Income Tax
# Previously Paid
Include on this line:
- Estimated payments made for 2025. Include payments made in connection with the sale or transfer of real property in New Jersey. Enclose a copy of Form GIT/REP-1, Nonresident Seller's Tax Declaration, or GIT/REP-2, Nonresident Seller's Tax Prepayment Receipt, with the return.
- Amount paid with an application for an extension;
- Credit applied from the prior year. This is the amount carried forward on line 41 of the 2024 NJ-1041;
- Payments made by an S corporation on behalf of a nonresident/nonconsenting shareholder. Enclose a copy of Form NJ-1040-SC.
Do not include on this line:
- Prior year refunds;
- Tax paid on behalf of the estate or trust by partnership(s). Report amounts from Schedule
NJK-1, Form NJ-1065 in Part III of Schedule NJ-BUS-1. Report amounts from Schedule NJK-1, Form NJ-1041 on line 35a.
Tax Paid on Your Behalf by
# Partnership(s) (Lines 35a-c)
Line 35a. Enter the total amount of New Jersey Income Tax paid on behalf of the nonresident estate or trust by partnership(s), as shown on:
- Schedule NJ-BUS-1, Part III, line 5, total share of tax paid on your behalf by partnerships;
- Schedule NJK-1 (Form NJ-1041), Part II, tax paid by partnerships and distributed;
- Schedule NJK-1 (Form NJ-1041), Part III, tax paid by partnership(s) on behalf of trust;
Enclose a copy of each Schedule NJK‑1 (Form NJ-1065) for each partnership that paid tax on your behalf, and a copy of Schedule NJK-1 (Form NJ-1041) for each estate or trust that distributed tax paid by partnership(s) to you for which you are claiming a credit.
Note: Estimated payments, payments made on behalf of a nonresident/nonconsenting shareholder, and payments made in connection with a sale or transfer of real property in New Jersey cannot be distributed to a beneficiary.
The fiduciary of the estate or trust must claim any refund on Form NJ-1041.
Line 35b. Enter the amount from Schedule B, line 48C.
Line 35c. Subtract line 35b from line 35a and enter the result.
# Pass-Through Business Alternative
Income Tax Credit (Lines 36a-c) Line 36a. Enter the trust's share of tax from Schedule NJ-BUS-1, Part III, line 6; Schedule NJ-BUS-1, Part IV, line 5; or the tax distributed to the trust from the NJK-1 received from an estate or trust. Enclose Schedule NJ-BUS-1 and copies of the PTE-K-1(s), beneficiary
NJK-1(s), NJK-1(s) from partnerships, and NJ-K-1(s) from S corporations with the return.
Line 36b. Enter the amount from Schedule B, line 48D.
Line 36c. Subtract line 36b from line 36a.
Line 37 - Total New Jersey Income Tax
# Withheld
Enter the total New Jersey Income Tax withheld, as shown on any W‑2, W-2G, and/or 1099s issued to the estate or trust. All W-2 and 1099 statements must reflect the same federal employer identification number (FEIN) that is listed on the return. Enclose Forms W-2 and 1099 with the return.
Common forms include:
- Form W-2: Box 17 (Box 15 must indicate NJ);
- Form W-2G: Box 15 (Box 13 must indicate NJ);
- Form 1099-R: Box 14 (Box 15 must indicate NJ);
- Form 1099-MISC: Box 16 (Box 17 must indicate NJ);
- Form 1099-NEC: Box 5 (Box 6 must indicate NJ).
Do not include on this line:
- Tax paid on behalf of the nonresident estate or trust by partnership(s). Report these amounts in Part III of Schedule NJ-BUS-1;
- Estimated payments made in connection with a sale or transfer of real property in New Jersey. Report on line 34;
- Payments made by an S corporation on behalf of a nonresident/nonconsenting shareholder. Report on line 34.
Important: If a person received income in 2025 but died before filing a return, a New Jersey Income Tax return (Form NJ-1040 or Form NJ-1040NR) should be filed to report such income. Do not include on line 37 amounts withheld from income of a deceased taxpayer.
Line 38 - Total Payments and Credits Add lines 34, 35c, 36c, and 37 and enter the total.
Line 39 - Balance of Tax Due If line 33 is more than line 38, you have tax due. Subtract line 38 from line 33 and enter the result.
See "How to Pay" on page 16. If you do not file the return or make a payment on time, we may charge penalties and interest.
Note: If the amount on line 39 is more than $400, you may want to increase your estimated payments.
Line 40 - Overpayment
If line 38 is more than line 33, you have an overpayment.
Subtract line 33 from line 38 and enter the result.
Line 41 - Credit to 2026 Tax Enter the amount of overpayment from line 40 you want to credit to 2026. This amount will reduce the refund.
Line 42 - Refund
Subtract line 41 from line 40 and enter the result.
You must submit the return to claim a refund. If the refund is $1 or less, you must enclose a statement requesting it.
Time Period for Refunds. Generally, you have three years from the date the return was due (including extensions) to request a refund.
Schedule A - Net Gains or Income From Disposition of Property Report the estate's or trust's capital gains and income from the sale or exchange of property (both inside and outside New Jersey). You can deduct the expenses of the sale and the basis in the property from the sales price.
In general, when calculating the gain or loss, you will use the cost or adjusted basis that you used for federal purposes. However, in certain situations, you may use a different basis.
- Sale of interest in a partnership, a sole proprietorship, or rental property. You may be required to use a New Jersey adjusted basis.
- Sale of S corporation shares. You must use your New Jersey adjusted basis.
If the estate or trust sold or transferred real property in New Jersey and was required to make estimated tax payments in connection with the sale or transfer, include such payments on line 34. Enclose a copy of Form GIT/REP-1, Nonresident Seller's Tax Declaration, or GIT/REP-2, Nonresident Seller's Tax Prepayment Receipt, with the return.
Installment Sales. You must report all gains from installment sales in the same tax year as they are reported for federal purposes. If the New Jersey basis is different from the federal basis, a New Jersey installment sale calculation must be made and the New Jersey gain must be reported.
Depreciation and Expense Deduction. The basis to be used for calculating gain or loss is the cost or adjusted basis determined for federal income tax purposes. New Jersey and federal depreciation and expense deduction limits are different. A New Jersey depreciation adjustment may be required for assets placed in service on or after January 1, 2004. Complete the Gross Income Tax Depreciation Adjustment Worksheet GIT-DEP to calculate the adjustment.
Complete Liquidation. If the estate or trust had an interest in a partnership, sole proprietorship, or S corporation that sold or disposed of virtually all of its assets in conjunction with the complete liquidation of the entity, the estate's or trust's portion of the gain or loss from the entity's sale or disposition of its assets must be reported.
Line 43 - List of Transactions List any New Jersey taxable transaction(s) as reported for federal purposes, indicating the gain or loss for each transaction in column f. In listing the gain or loss on disposition of rental property, you must take into consideration the New Jersey adjustment from Worksheet GIT-DEP, Part I, line 6.
Do not include gains or losses from the sale of exempt obligations. See GIT-5, Nontaxable Investment Income.
There is no distinction between active and passive losses for New Jersey purposes. You cannot carry back or carry forward such losses when reporting income on Form NJ-1041. You can deduct federal passive losses in full in the year incurred against any gain within the same category of income, but only in the year that it occurred.
If you need more space, enclose a statement with the return listing any additional transactions.
Line 44 - Capital Gains Distributions Enter the capital gains distributions from Form 1099-DIV(s) or similar statement(s). Do not include capital gains from a New Jersey Qualified Investment Fund that are attributable to qualified exempt obligations or gains from mutual funds to the extent attributable to federal obligations. For more information on New Jersey qualified investment funds, see GIT-5, Nontaxable Investment Income.
Line 45 - Other Net Gains
Enter the net gains or income less net losses from disposition of property not included on lines 43 and 44.
Line 46 - Net Gains
Enter the total of lines 43, 44, and 45, netting gains with losses. Enter this amount on line 9. If zero or less, enter "0."
Schedule B - Beneficiaries' Shares of Income Line 47 - Beneficiaries' Shares of Income Enter the name and address, state of residence, and Social Security number of each beneficiary to whom estate or trust income was distributed or distributable during the tax year.
In column A, enter the actual amount of income distributed or required to be distributed to the beneficiaries.
For New Jersey nonresident beneficiaries, enter in column B the New Jersey source income distributed or required to be distributed. Do not include distributions of New Jersey tax-exempt income or corpus distributions.
In column C, enter the amount of tax paid by partnerships on behalf of the estate or trust and that was distributed to a nonresident beneficiary or grantor. Tax paid by partnerships can only be distributed to a nonresident beneficiary or grantor. Do not make an entry in column C for a New Jersey resident beneficiary or grantor.
If you need more space, enclose a statement with the return. Enclose a copy of New Jersey Schedule NJK-1(s).
Enter in column D the amount of Pass-Through Business Alternative Income Tax Credit that was distributed to the beneficiaries or the grantor.
Grantor Trusts Only:
If the income from a grantor trust is reportable by or taxable to the grantor for federal income tax purposes, it is also taxable to the grantor, and not the trust, for New Jersey Gross Income Tax purposes. Use the following instructions.
Line 47 - Beneficiaries' Shares of Income Enter the name and address, state of residence, and Social Security number of the taxable grantor.
In column A, enter the trust's gross income from line 14. For a New Jersey nonresident grantor, enter in column B the New Jersey source income included in the trust's gross income. If the grantor is a New Jersey resident, the total on line 48C should be listed on line 35a and on line 35c and can only be refunded to the nonresident trust. Enter the amount on line 48A on line 15. Line 16 (Total Income) should equal zero ("0").
Line 48A - Total Distributions to
# Beneficiaries
Enter the total of the income distributed or distributable.
Also enter this amount on line 15.
Line 48B - New Jersey Source Income
# Distributed
Enter the total New Jersey source income distributed or distributable. Also enter this amount on Schedule E, line 10.
Do not enter an amount for a nonresident beneficiary if the income being distributed to the nonresident beneficiary was received from a business entity (i.e., sole proprietorship, partnership, LLP, or LLC) located in New Jersey and the business entity's only activity is the purchase, holding, or sale of intangible personal property, such as commodities or securities, and such intangible personal property is not held for sale to customers. However, you must include this income in column A.
Line 48C - Tax Paid on Behalf of Estate or
# Trust by Partnerships and Distributed
Enter the total tax paid on behalf of the estate or trust by partnerships that was distributed to nonresident beneficiaries or grantor. Also enter this amount on line 35b.
Line 48D - Pass-Through Business
# Distributed
Enter the total Pass-Through Business Alternative Income Tax Credit that was distributed to the beneficiaries or the grantor. Also enter this amount on line 36b.
Schedule C - Credit for Income or Wage Taxes Paid by New
# Jurisdictions
A resident estate or trust may be eligible for a credit if it had income from outside New Jersey that was taxed by another jurisdiction and subject to New Jersey Income Tax in the same year. The fiduciary must complete this schedule to claim the credit. It is not necessarily a dollarfor-dollar credit. You cannot take a credit for taxes paid to the U.S. Government, Puerto Rico, or any other country or territory.
Note: New Jersey does not require that a copy of the income tax return(s) filed with the other jurisdiction(s) be submitted with Form NJ‑1041. However, taxpayers should keep complete copies of any returns filed with other jurisdiction(s), including Electronic Filing Income Tax Returns and associated schedules and worksheets that establish the nature and source of the income being taxed by the other jurisdiction. The taxpayer may be asked to submit copies of these or other documents.
Line 49 - Income Properly Taxed by Both
# New Jersey and Other Jurisdiction
Enter the amount of income received during the tax year, after the deduction of the actual amount of income distributed or required to be distributed, that was subject to tax by another jurisdiction. Any income included on line 49 must also be included on line 50 since the income has to be taxed by both New Jersey and the other jurisdiction. Therefore, the amount on line 49 cannot be more than the amount on line 50. Do not combine the same income subject to tax by more than one jurisdiction.
Line 50 - Income Subject to Tax by New
# Jersey
Enter the amount of income reported on line 16.
Line 51 - Maximum Allowable Credit Divide line 49 by line 50 and multiply the result by the New Jersey tax (line 27). This is the amount of maximum allowable credit.
Line 52 - Income Tax Paid to Other
# Jurisdiction
Enter the income or wage tax paid to the other jurisdiction on the income shown on line 49.
Line 53 - Credit Allowed
Enter the lesser of line 51 or line 52. Also enter this amount on line 28.
For more information, see GIT‑3W, Credit for Taxes Paid to Other Jurisdictions (Wage Income), and GIT‑3B, Credit for Taxes Paid to Other Jurisdictions (Business/
Nonwage Income).
Schedule D - Allocation of Business
# Income to New Jersey
Schedule D must be used by nonresident taxpayers who are required to complete and enclose a Gross Income Tax Business Allocation Schedule (Form NJ-NR-A). This schedule is completed only by nonresidents carrying on business both inside and outside New Jersey. (See the instructions for Form NJ‑NR‑A on page 18.) Schedule E - New Jersey Income of
Nonresident Estates and Trusts
The New Jersey Income Tax liability of a nonresident estate or trust is calculated on income from all sources and then prorated based on the percentage of the income that comes from New Jersey sources.
Nonresident estates must report their income from all sources (both inside and outside New Jersey) on lines 6-13 of Form NJ‑1041 and their income from New Jersey sources on lines 1-8 of Schedule E. These figures cannot be copied from the federal return.
Complete Schedule E before completing line 16a of Form NJ‑1041. If you complete Schedule E, enclose it with your Form NJ-1041.
Income From New Jersey Sources (Lines 1-8) For each category of income, enter the portion of the estate's or trust's income that comes from New Jersey sources.
Important: For every entry on lines 6-13 of Form NJ‑1041, there should be an entry on the corresponding line on Schedule E. If none of the income in a particular category is from New Jersey sources, enter "0" on the appropriate line on Schedule E.
Income or losses that a nonresident estate or trust receives from a business entity (i.e., sole proprietorship, nonunitary partnership, LLP, or LLC) located in New Jersey are not deemed to be derived from New Jersey sources if the business entity's sole activity is the purchase, holding, or sale of intangible personal property, such as commodities or securities, and such intangible personal property is not held for sale to customers. However, you must include this income on the appropriate line of Form NJ‑1041.
For example, income received from a nonunitary partnership engaged in such a business is not considered to be New Jersey source income and is not included on Schedule E, line 6. However, income received from all other nonunitary partnerships and all unitary partnerships must be included using the New Jersey source amounts reported on the NJK-1.
A nonresident estate or trust that carries on business both inside and outside New Jersey must allocate business income to determine the amount of income from New Jersey sources. Complete and enclose a separate Business Allocation Schedule (Form NJ‑NR‑A) for each business required to allocate. Also complete Schedule D, Form NJ‑1041.
Line 9 - Total Income From New Jersey Sources Add lines 1 throught 8 and enter the total.
Line 10 - New Jersey Source Income Distributed to Beneficiaries Enter the amount from Schedule B, line 48B.
Line 11 - New Jersey Income
Subtract line 10 from line 9. Enter the result here and on line 16a.
# Signature
The return must be signed and dated in blue or black ink by the individual fiduciary or by the authorized officer of the organization receiving or having custody or control and management of the income of the estate or trust.
# Paid Tax Preparer Information
Preparer Authorization. Division of Taxation personnel cannot discuss your return or enclosures with anyone other than you without your written authorization. If you want a Division of Taxation representative to discuss your tax return with the person who signed the return as "Preparer Other than Fiduciary," check the box above the preparer's signature line to give your permission.
Tax Preparers
Anyone who prepares a taxpayer's return for a fee must sign as "Preparer" and enter their Social Security number or federal preparer tax identification number. Include the company or corporation name and federal identification number, if applicable. A tax preparer who fails to sign the return or provide a tax identification number will be liable for a $25 penalty for each omission. Someone who prepares the return but does not charge you should not sign the return.
E-File Mandate. Preparers that reasonably expect to prepare 11 or more individual resident Income Tax returns (including those filed for trusts and estates) during the tax year must use electronic methods to file those returns if an electronic filing option is available. A tax preparer is liable for a penalty of $50 for each return they fail to file electronically when required to do so.
Opting Out of Electronic Filing. If your tax preparer is required to file all returns electronically but you want to file a paper return, you can opt out by enclosing Form NJ-1040-O, E-File Opt-Out Request Form, with your paper return. Both you and your preparer must sign the form, and your preparer must check the box next to their signature on your return to indicate that Form NJ-1040-O is enclosed.
# How to Pay
The balance of tax due can be paid either electronically (e-check or credit card) or by check or money order. Payments must be postmarked or submitted electronically by the original due date to avoid penalty and interest charges. If you are paying a balance due for 2025 and also making an estimated tax payment for 2026, make a separate payment for each transaction. If the amount due is less than $1, no payment is required.
Check or Money Order. If tax is due and you are sending the payment with the return, complete a payment voucher (Form NJ-1041-V), entering the amount of tax due in the boxes on the voucher. Form NJ-1041-V is available on the Division's website.
Make the check or money order payable to "State of New Jersey - TGI." Write the federal employer identification number on the check or money order. Send the check or money order and the payment voucher in the same envelope as the NJ‑1041 return. (See "Where to Mail the Return" on page 17.) Electronic Payments. Do not send in the payment voucher if you are paying electronically. When making your payment, you must enter the federal employer identification number and the date of the decedent's death or the date the trust was created or the account will not be properly credited.
- Electronic Check (E-Check). You can have the payment directly withdrawn from a bank account using our online e-check service. This option is available on the Division's website. Taxpayers who do not have internet access can pay by e-check by contacting the Division's Customer Service Center or visiting a Regional Information Center. (See page 29 for phone numbers or addresses.)
- Credit Card (Processing Fees Apply). You can use an American Express, Discover, MasterCard, or Visa credit card to make a payment. This option is available on the Division's website or by phone (1 (888) 673-7694). Credit card payments can also be made by contacting the Division's Customer Service Center or by visiting a Regional Information Center (see page 29 for phone numbers or addresses.)
# Penalties, Interest, and Collection Fees
If you do not file your return or make your payment on time, we may charge the following penalties and interest:
- Late Filing Penalty. When the return is filed after the original or extended due date, we will assess a penalty of 5% per month (or part of a month) up to a maximum of 25% of the outstanding tax balance.
You may also be charged a $100 penalty for each month the return is late.
- Late Payment Penalty. When you pay after the filing deadline, you may be charged a 5% penalty on the outstanding balance.
- Interest. We will assess interest at an annual rate of 3% above the prime rate each month (or part of a month) the tax is unpaid. At the end of each calendar year, any tax, penalties, and interest remaining unpaid will become part of the balance on which interest is charged. See Technical Bulletin TB-21(R) for current and previous years' interest rates.
# Schedule NJK-1
Beneficiaries are subject to New Jersey Income Tax on the net income from an estate or trust actually distributed or required to be distributed during the tax year. The fiduciary of an estate or trust must provide each beneficiary with a Schedule NJK-1, Form NJ-1041, listing the total income distributed and the New Jersey source income distributed.
Prepare a Schedule NJK-1 for each beneficiary using the information listed on Schedule B, Form NJ-1041, Beneficiaries' Shares of Income.
Tax Paid by Partnerships can only be distributed to a nonresident beneficiary or grantor and can only be claimed on a nonresident beneficiary's or grantor's Income Tax return.
For a grantor trust, in Part I, Beneficiary or Grantor Information, enter the grantor's information and New Jersey residency status. In Part I, Estate or Trust Information, enter the grantor trust's information and New Jersey residency status.
In Part III, Grantor's Share of Income, enter the grantor's income, gain, or loss by category as required to be reported for Gross Income Tax purposes. For a nonresident grantor, list the tax paid by partnership(s) on behalf of the trust from Schedule B, line 48C.
Do not include distributions of New Jersey tax-exempt income or corpus distributions.
Include the NJK-1(s) with Form NJ-1041.
Note: Estimated payments made on behalf of a nonresident/nonconsenting shareholder, payments made in connection with a sale or transfer of real property in New Jersey, or any estimated payments made by the estate or trust cannot be distributed to a beneficiary.
- Collection Fees. In addition, if a tax bill is sent to our collection agency, a referral cost recovery fee of 11% of the tax due will be added to the liability. If a certificate of debt is issued for an outstanding liability, a fee for the cost of collection of the tax may also be imposed.
# Where to Mail the Return
Mail Form NJ-1041 with related enclosures, payment voucher, and check or money order for any tax due to the address below. Send only one return per envelope.
Mail Form NJ‑1041 to:
State of New Jersey
Division of Taxation
Revenue Processing Center
PO Box 888
Trenton NJ 08646-0888
Do not staple, paper clip, tape, or use any other fastening device for your return and enclosures.
# Amended Return
File an amended return and pay any tax due if:
- An additional tax statement is received after the return is filed; or
- A mistake was made on a previously filed return; or
- There are any changes in the federal income tax that affect the New Jersey taxable income. The amended return must be filed within 90 days.
To file an amended fiduciary return, complete a new NJ-1041 and check the box at the top of the return. Enclose all supporting documents, schedules, and forms.
Do not use Form NJ-1040X to amend a fiduciary return.
An amended NJ-1041 that results in a refund must be filed within three years from the date the original return was filed or within two years from the time the tax was paid, whichever is later, to receive a refund. (A return filed before the due date or extended due date is considered to be filed on the due date or extended due date.)
# Privacy Act Notification
The Division of Taxation uses the federal employer identification number primarily to account for and give credit for tax payments. It also is used in the administration and enforcement of all tax laws for which we are responsible.
NJ-NR-A - Business Allocation Schedule If business activities are carried on both inside and outside New Jersey, use this form to determine the allocation factor.
This will be applied to the business's operational income to determine the amount from New Jersey sources.
The allocation factor uses market-based sourcing, not cost of performance, to determine the portion of the business income sourced to New Jersey. The allocation factor is calculated using a single sales factor formula rather than a threefactor formula. See N.J.A.C. 18:7-7.1 through N.J.A.C. 18:7-10.1 and Technical Bulletin TB-112(R), Gross Income Tax Allocation Sourcing for the Receipts of Business Income, for more information.
Only activities related to operational activity are to be used when calculating the allocation factor. Do not include nonoperational activity or income from nonunitary partnerships. Nonoperational income is income or loss generated by activities outside the regular trade or operating activities of a business. See N.J.S.A. 54:10A-6.1 for more information. Receipts from lower tier nonunitary partnerships do not flow through to the taxpayer and are not included on the NJ-NR-A. However, receipts from lower tier unitary partnerships flow through and are included in the receipts reported on the NJ-NR-A.
Be sure that Form NJ‑NR‑A is enclosed with Form NJ‑1041 and that the name and address on the Business Allocation
Schedule agree exactly with the name and address on the NJ-1041.
Lines 1-5 - Receipts
Receipts Allocated to New Jersey
- Receipts from sales of tangible personal property if the goods are shipped to points within New Jersey
- Receipts from the sale of goods if shipped to a New Jersey or a non-New Jersey customer where possession is transferred in New Jersey
- Receipts from the sale of goods shipped to a taxpayer from outside New Jersey to a New Jersey customer by a common carrier
- Services performed if the benefit of the service is received in New Jersey
- Rentals from property situated in New Jersey
- Royalties from the use in New Jersey of patents, copyrights, and trademarks
- All other business receipts earned in New Jersey Receipts Not Allocated to New Jersey. Receipts from the sale of goods shipped from outside New Jersey to a New Jersey location where the goods are picked up by a common carrier and transported to a customer outside New Jersey are not allocated to New Jersey.
Receipts From Sales of Capital Assets. Receipts from sales of capital assets not held for sale to customers in the regular course of business, either within or outside New Jersey, should be included in the numerator and the denominator based on the net gain recognized and not on gross selling prices. If the taxpayer's business is the buying and selling of real estate or of securities for trading purposes, gross receipts from the sales of such assets should be included in the numerator and the denominator of the receipts fraction.
Lines 6 - Total Receipts From All Sales, Services, and Other Business Transactions In New Jersey Add lines 1 through 5 and enter the total.
Line 7 - Total Receipts From All Sales, Services, and Other Business Transactions Everywhere Enter on line 7 the total receipts from all sales made, services performed, and business transactions conducted both inside and outside New Jersey during the period covered by the return.
Line 8 - Allocation Factor
Divide line 6 by line 7 and enter the result. Also enter this decimal on Schedule D, Form NJ‑1041.
# 2025 New Jersey Tax Table
Use this table if your taxable income on line 24 is less than $110,000. If your taxable income is $110,000 or more, you must use the Tax Rate Schedule on page 27 of this booklet.
Example: Mr. Evans is filing a fiduciary return for his mother's estate. The taxable income on line 24 of Form NJ‑1041 is $39,875. First he finds the $39,850-$39,900 income line. Next, he finds the column for "Your Tax Is:" and reads down the column. The amount shown where the income line meets the tax amount column is $713. This is the tax amount to be entered on line 27 of Form NJ‑1041 (nonresidents, line 25).
(Taxable Income) is—
But Less Than
At Least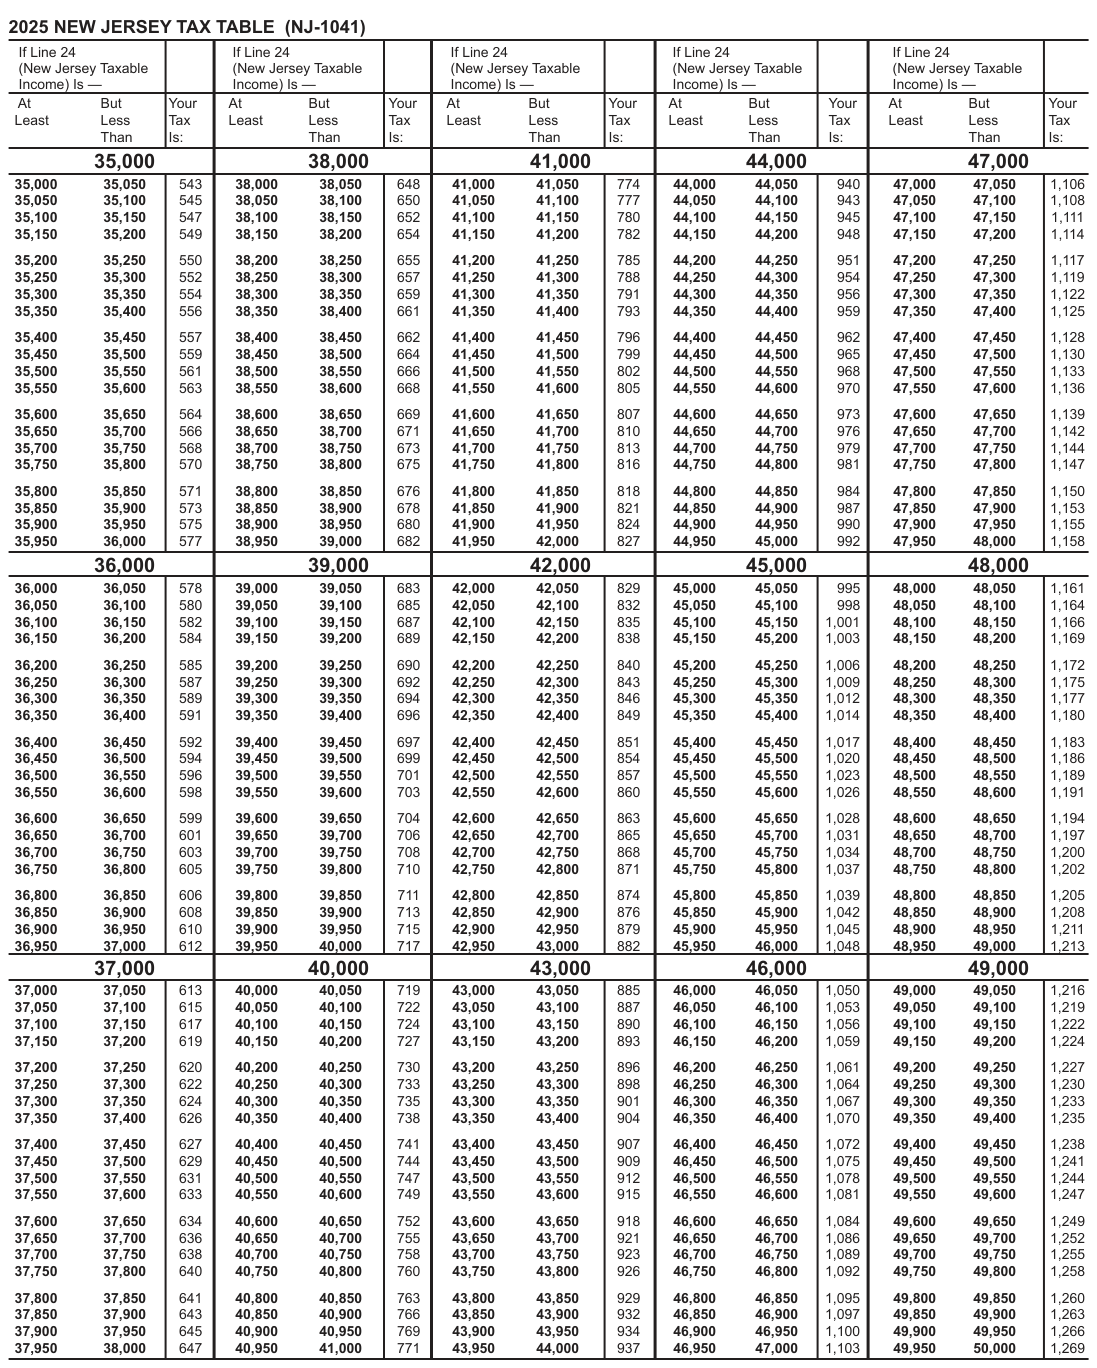
Text version of this table
If Line 24 (New Jersey Taxable Income) Is — If Line 24 (New Jersey Taxable Income) Is — If Line 24 (New Jersey Taxable Income) Is — If Line 24 (New Jersey Taxable Income) Is — If Line 24 (New Jersey Taxable Income) Is — At But Least Less Than Your Tax Is: At But Least Less Than Your Tax Is: At But Least Less Than Your Tax Is: At But Least Less Than Your Tax Is: At But Least Less Than Your Tax Is: 35,000 38,000 41,000 44,000 47,000 35,000 35,050 35,050 35,100 35,100 35,150 35,150 35,200 35,200 35,250 35,250 35,300 35,300 35,350 35,350 35,400 35,400 35,450 35,450 35,500 35,500 35,550 35,550 35,600 35,600 35,650 35,650 35,700 35,700 35,750 35,750 35,800 35,800 35,850 35,850 35,900 35,900 35,950 35,950 36,000 543 545 547 549 550 552 554 556 557 559 561 563 564 566 568 570 571 573 575 577 38,000 38,050 38,050 38,100 38,100 38,150 38,150 38,200 38,200 38,250 38,250 38,300 38,300 38,350 38,350 38,400 38,400 38,450 38,450 38,500 38,500 38,550 38,550 38,600 38,600 38,650 38,650 38,700 38,700 38,750 38,750 38,800 38,800 38,850 38,850 38,900 38,900 38,950 38,950 39,000 648 650 652 654 655 657 659 661 662 664 666 668 669 671 673 675 676 678 680 682 41,000 41,050 41,050 41,100 41,100 41,150 41,150 41,200 41,200 41,250 41,250 41,300 41,300 41,350 41,350 41,400 41,400 41,450 41,450 41,500 41,500 41,550 41,550 41,600 41,600 41,650 41,650 41,700 41,700 41,750 41,750 41,800 41,800 41,850 41,850 41,900 41,900 41,950 41,950 42,000 774 777 780 782 785 788 791 793 796 799 802 805 807 810 813 816 818 821 824 827 44,000 44,050 44,050 44,100 44,100 44,150 44,150 44,200 44,200 44,250 44,250 44,300 44,300 44,350 44,350 44,400 44,400 44,450 44,450 44,500 44,500 44,550 44,550 44,600 44,600 44,650 44,650 44,700 44,700 44,750 44,750 44,800 44,800 44,850 44,850 44,900 44,900 44,950 44,950 45,000 940 943 945 948 951 954 956 959 962 965 968 970 973 976 979 981 984 987 990 992 47,000 47,050 47,050 47,100 47,100 47,150 47,150 47,200 47,200 47,250 47,250 47,300 47,300 47,350 47,350 47,400 47,400 47,450 47,450 47,500 47,500 47,550 47,550 47,600 47,600 47,650 47,650 47,700 47,700 47,750 47,750 47,800 47,800 47,850 47,850 47,900 47,900 47,950 47,950 48,000 1,106 1,108 1,111 1,114 1,117 1,119 1,122 1,125 1,128 1,130 1,133 1,136 1,139 1,142 1,144 1,147 1,150 1,153 1,155 1,158 36,000 39,000 42,000 45,000 48,000 36,000 36,050 36,050 36,100 36,100 36,150 36,150 36,200 36,200 36,250 36,250 36,300 36,300 36,350 36,350 36,400 36,400 36,450 36,450 36,500 36,500 36,550 36,550 36,600 36,600 36,650 36,650 36,700 36,700 36,750 36,750 36,800 36,800 36,850 36,850 36,900 36,900 36,950 36,950 37,000 578 580 582 584 585 587 589 591 592 594 596 598 599 601 603 605 606 608 610 612 39,000 39,050 39,050 39,100 39,100 39,150 39,150 39,200 39,200 39,250 39,250 39,300 39,300 39,350 39,350 39,400 39,400 39,450 39,450 39,500 39,500 39,550 39,550 39,600 39,600 39,650 39,650 39,700 39,700 39,750 39,750 39,800 39,800 39,850 39,850 39,900 39,900 39,950 39,950 40,000 683 685 687 689 690 692 694 696 697 699 701 703 704 706 708 710 711 713 715 717 42,000 42,050 42,050 42,100 42,100 42,150 42,150 42,200 42,200 42,250 42,250 42,300 42,300 42,350 42,350 42,400 42,400 42,450 42,450 42,500 42,500 42,550 42,550 42,600 42,600 42,650 42,650 42,700 42,700 42,750 42,750 42,800 42,800 42,850 42,850 42,900 42,900 42,950 42,950 43,000 829 832 835 838 840 843 846 849 851 854 857 860 863 865 868 871 874 876 879 882 45,000 45,050 45,050 45,100 45,100 45,150 45,150 45,200 45,200 45,250 45,250 45,300 45,300 45,350 45,350 45,400 45,400 45,450 45,450 45,500 45,500 45,550 45,550 45,600 45,600 45,650 45,650 45,700 45,700 45,750 45,750 45,800 45,800 45,850 45,850 45,900 45,900 45,950 45,950 46,000 995 998 1,001 1,003 1,006 1,009 1,012 1,014 1,017 1,020 1,023 1,026 1,028 1,031 1,034 1,037 1,039 1,042 1,045 1,048 48,000 48,050 48,050 48,100 48,100 48,150 48,150 48,200 48,200 48,250 48,250 48,300 48,300 48,350 48,350 48,400 48,400 48,450 48,450 48,500 48,500 48,550 48,550 48,600 48,600 48,650 48,650 48,700 48,700 48,750 48,750 48,800 48,800 48,850 48,850 48,900 48,900 48,950 48,950 49,000 1,161 1,164 1,166 1,169 1,172 1,175 1,177 1,180 1,183 1,186 1,189 1,191 1,194 1,197 1,200 1,202 1,205 1,208 1,211 1,213 37,000 40,000 43,000 46,000 49,000 37,000 37,050 37,050 37,100 37,100 37,150 37,150 37,200 37,200 37,250 37,250 37,300 37,300 37,350 37,350 37,400 37,400 37,450 37,450 37,500 37,500 37,550 37,550 37,600 37,600 37,650 37,650 37,700 37,700 37,750 37,750 37,800 37,800 37,850 37,850 37,900 37,900 37,950 37,950 38,000 613 615 617 619 620 622 624 626 627 629 631 633 634 636 638 640 641 643 645 647 40,000 40,050 40,050 40,100 40,100 40,150 40,150 40,200 40,200 40,250 40,250 40,300 40,300 40,350 40,350 40,400 40,400 40,450 40,450 40,500 40,500 40,550 40,550 40,600 40,600 40,650 40,650 40,700 40,700 40,750 40,750 40,800 40,800 40,850 40,850 40,900 40,900 40,950 40,950 41,000 719 722 724 727 730 733 735 738 741 744 747 749 752 755 758 760 763 766 769 771 43,000 43,050 43,050 43,100 43,100 43,150 43,150 43,200 43,200 43,250 43,250 43,300 43,300 43,350 43,350 43,400 43,400 43,450 43,450 43,500 43,500 43,550 43,550 43,600 43,600 43,650 43,650 43,700 43,700 43,750 43,750 43,800 43,800 43,850 43,850 43,900 43,900 43,950 43,950 44,000 885 887 890 893 896 898 901 904 907 909 912 915 918 921 923 926 929 932 934 937 46,000 46,050 46,050 46,100 46,100 46,150 46,150 46,200 46,200 46,250 46,250 46,300 46,300 46,350 46,350 46,400 46,400 46,450 46,450 46,500 46,500 46,550 46,550 46,600 46,600 46,650 46,650 46,700 46,700 46,750 46,750 46,800 46,800 46,850 46,850 46,900 46,900 46,950 46,950 47,000 1,050 1,053 1,056 1,059 1,061 1,064 1,067 1,070 1,072 1,075 1,078 1,081 1,084 1,086 1,089 1,092 1,095 1,097 1,100 1,103 49,000 49,050 49,050 49,100 49,100 49,150 49,150 49,200 49,200 49,250 49,250 49,300 49,300 49,350 49,350 49,400 49,400 49,450 49,450 49,500 49,500 49,550 49,550 49,600 49,600 49,650 49,650 49,700 49,700 49,750 49,750 49,800 49,800 49,850 49,850 49,900 49,900 49,950 49,950 50,000 1,216 1,219 1,222 1,224 1,227 1,230 1,233 1,235 1,238 1,241 1,244 1,247 1,249 1,252 1,255 1,258 1,260 1,263 1,266 1,269
# Your At But Your
# Your At But Your
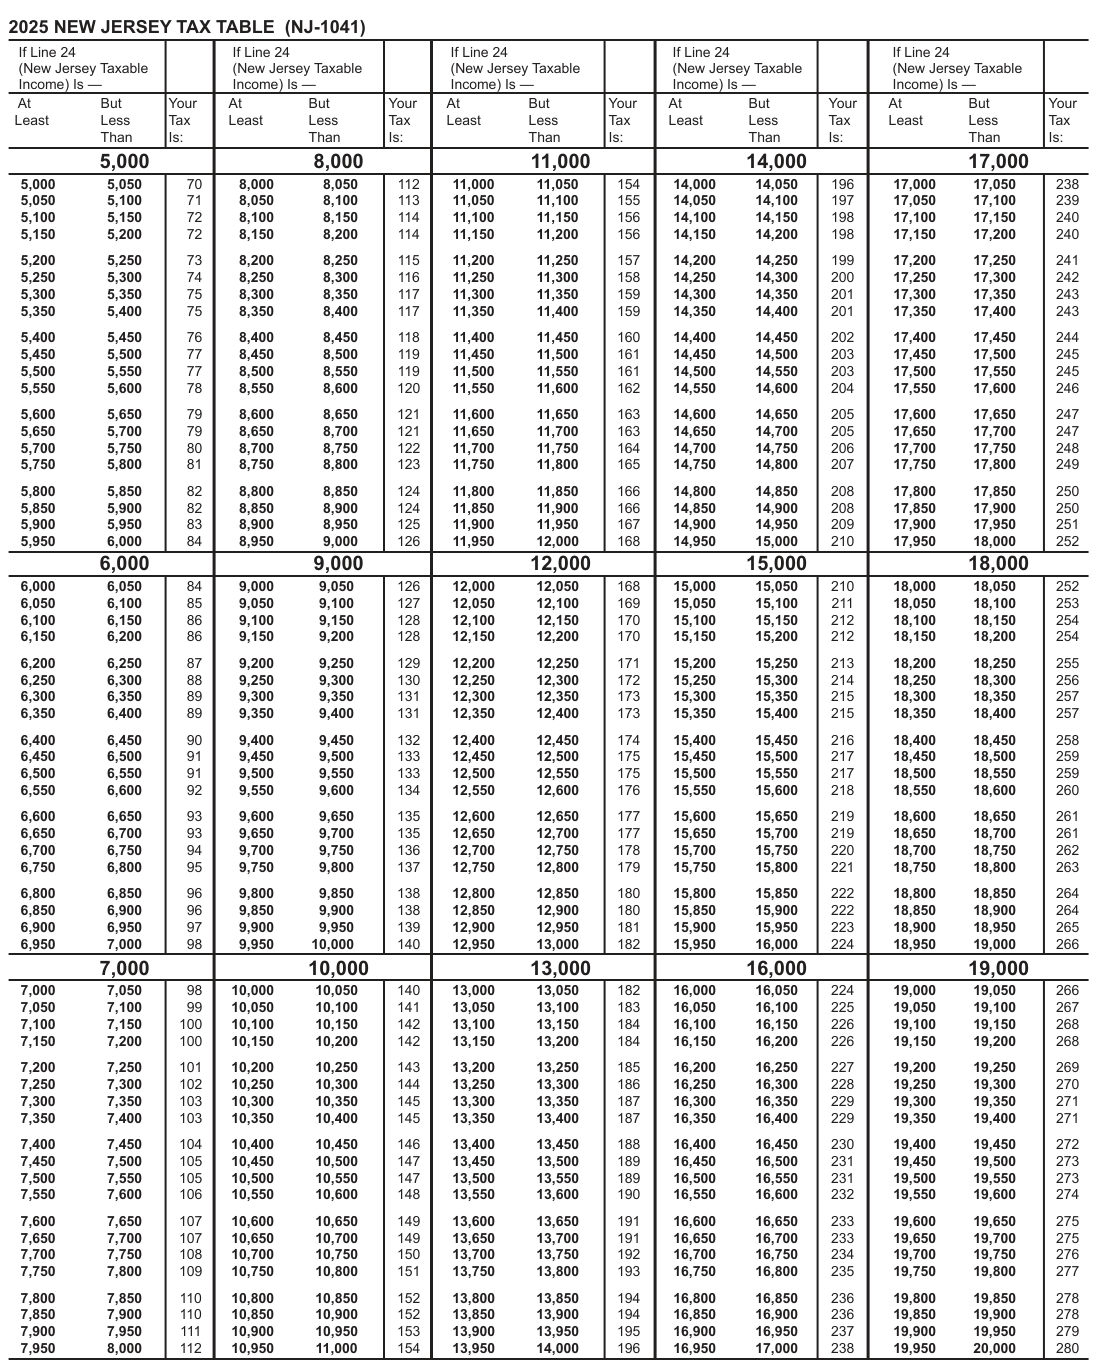
Text version of this table
| If Line 24 (New Jersey Taxable Income) Is — | If Line 24 (New Jersey Taxable Income) Is — | If Line 24 (New Jersey Taxable Income) Is — | If Line 24 (New Jersey Taxable Income) Is — | If Line 24 (New Jersey Taxable Income) Is — | |||||
| At But Least Less Than | Your Tax Is: | At But Least Less Than | Your Tax Is: | At But Least Less Than | Your Tax Is: | At But Least Less Than | Your Tax Is: | At But Least Less Than | Your Tax Is: |
| 5,000 | 8,000 | 11,000 | 14,000 | 17,000 | |||||
| 5,000 5,050 5,050 5,100 5,100 5,150 5,150 5,200 5,200 5,250 5,250 5,300 5,300 5,350 5,350 5,400 5,400 5,450 5,450 5,500 5,500 5,550 5,550 5,600 5,600 5,650 5,650 5,700 5,700 5,750 5,750 5,800 5,800 5,850 5,850 5,900 5,900 5,950 5,950 6,000 | 70 71 72 72 73 74 75 75 76 77 77 78 79 79 80 81 82 82 83 84 | 8,000 8,050 8,050 8,100 8,100 8,150 8,150 8,200 8,200 8,250 8,250 8,300 8,300 8,350 8,350 8,400 8,400 8,450 8,450 8,500 8,500 8,550 8,550 8,600 8,600 8,650 8,650 8,700 8,700 8,750 8,750 8,800 8,800 8,850 8,850 8,900 8,900 8,950 8,950 9,000 | 112 113 114 114 115 116 117 117 118 119 119 120 121 121 122 123 124 124 125 126 | 11,000 11,050 11,050 11,100 11,100 11,150 11,150 11,200 11,200 11,250 11,250 11,300 11,300 11,350 11,350 11,400 11,400 11,450 11,450 11,500 11,500 11,550 11,550 11,600 11,600 11,650 11,650 11,700 11,700 11,750 11,750 11,800 11,800 11,850 11,850 11,900 11,900 11,950 11,950 12,000 | 154 155 156 156 157 158 159 159 160 161 161 162 163 163 164 165 166 166 167 168 | 14,000 14,050 14,050 14,100 14,100 14,150 14,150 14,200 14,200 14,250 14,250 14,300 14,300 14,350 14,350 14,400 14,400 14,450 14,450 14,500 14,500 14,550 14,550 14,600 14,600 14,650 14,650 14,700 14,700 14,750 14,750 14,800 14,800 14,850 14,850 14,900 14,900 14,950 14,950 15,000 | 196 197 198 198 199 200 201 201 202 203 203 204 205 205 206 207 208 208 209 210 | 17,000 17,050 17,050 17,100 17,100 17,150 17,150 17,200 17,200 17,250 17,250 17,300 17,300 17,350 17,350 17,400 17,400 17,450 17,450 17,500 17,500 17,550 17,550 17,600 17,600 17,650 17,650 17,700 17,700 17,750 17,750 17,800 17,800 17,850 17,850 17,900 17,900 17,950 17,950 18,000 | 238 239 240 240 241 242 243 243 244 245 245 246 247 247 248 249 250 250 251 252 |
| 6,000 | 9,000 | 12,000 | 15,000 | 18,000 | |||||
| 6,000 6,050 6,050 6,100 6,100 6,150 6,150 6,200 6,200 6,250 6,250 6,300 6,300 6,350 6,350 6,400 6,400 6,450 6,450 6,500 6,500 6,550 6,550 6,600 6,600 6,650 6,650 6,700 6,700 6,750 6,750 6,800 6,800 6,850 6,850 6,900 6,900 6,950 6,950 7,000 | 84 85 86 86 87 88 89 89 90 91 91 92 93 93 94 95 96 96 97 98 | 9,000 9,050 9,050 9,100 9,100 9,150 9,150 9,200 9,200 9,250 9,250 9,300 9,300 9,350 9,350 9,400 9,400 9,450 9,450 9,500 9,500 9,550 9,550 9,600 9,600 9,650 9,650 9,700 9,700 9,750 9,750 9,800 9,800 9,850 9,850 9,900 9,900 9,950 9,950 10,000 | 126 127 128 128 129 130 131 131 132 133 133 134 135 135 136 137 138 138 139 140 | 12,000 12,050 12,050 12,100 12,100 12,150 12,150 12,200 12,200 12,250 12,250 12,300 12,300 12,350 12,350 12,400 12,400 12,450 12,450 12,500 12,500 12,550 12,550 12,600 12,600 12,650 12,650 12,700 12,700 12,750 12,750 12,800 12,800 12,850 12,850 12,900 12,900 12,950 12,950 13,000 | 168 169 170 170 171 172 173 173 174 175 175 176 177 177 178 179 180 180 181 182 | 15,000 15,050 15,050 15,100 15,100 15,150 15,150 15,200 15,200 15,250 15,250 15,300 15,300 15,350 15,350 15,400 15,400 15,450 15,450 15,500 15,500 15,550 15,550 15,600 15,600 15,650 15,650 15,700 15,700 15,750 15,750 15,800 15,800 15,850 15,850 15,900 15,900 15,950 15,950 16,000 | 210 211 212 212 213 214 215 215 216 217 217 218 219 219 220 221 222 222 223 224 | 18,000 18,050 18,050 18,100 18,100 18,150 18,150 18,200 18,200 18,250 18,250 18,300 18,300 18,350 18,350 18,400 18,400 18,450 18,450 18,500 18,500 18,550 18,550 18,600 18,600 18,650 18,650 18,700 18,700 18,750 18,750 18,800 18,800 18,850 18,850 18,900 18,900 18,950 18,950 19,000 | 252 253 254 254 255 256 257 257 258 259 259 260 261 261 262 263 264 264 265 266 |
| 7,000 | 10,000 | 13,000 | 16,000 | 19,000 | |||||
| 7,000 7,050 7,050 7,100 7,100 7,150 7,150 7,200 7,200 7,250 7,250 7,300 7,300 7,350 7,350 7,400 7,400 7,450 7,450 7,500 7,500 7,550 7,550 7,600 7,600 7,650 7,650 7,700 7,700 7,750 7,750 7,800 7,800 7,850 7,850 7,900 7,900 7,950 7,950 8,000 | 98 99 100 100 101 102 103 103 104 105 105 106 107 107 108 109 110 110 111 112 | 10,000 10,050 10,050 10,100 10,100 10,150 10,150 10,200 10,200 10,250 10,250 10,300 10,300 10,350 10,350 10,400 10,400 10,450 10,450 10,500 10,500 10,550 10,550 10,600 10,600 10,650 10,650 10,700 10,700 10,750 10,750 10,800 10,800 10,850 10,850 10,900 10,900 10,950 10,950 11,000 | 140 141 142 142 143 144 145 145 146 147 147 148 149 149 150 151 152 152 153 154 | 13,000 13,050 13,050 13,100 13,100 13,150 13,150 13,200 13,200 13,250 13,250 13,300 13,300 13,350 13,350 13,400 13,400 13,450 13,450 13,500 13,500 13,550 13,550 13,600 13,600 13,650 13,650 13,700 13,700 13,750 13,750 13,800 13,800 13,850 13,850 13,900 13,900 13,950 13,950 14,000 | 182 183 184 184 185 186 187 187 188 189 189 190 191 191 192 193 194 194 195 196 | 16,000 16,050 16,050 16,100 16,100 16,150 16,150 16,200 16,200 16,250 16,250 16,300 16,300 16,350 16,350 16,400 16,400 16,450 16,450 16,500 16,500 16,550 16,550 16,600 16,600 16,650 16,650 16,700 16,700 16,750 16,750 16,800 16,800 16,850 16,850 16,900 16,900 16,950 16,950 17,000 | 224 225 226 226 227 228 229 229 230 231 231 232 233 233 234 235 236 236 237 238 | 19,000 19,050 19,050 19,100 19,100 19,150 19,150 19,200 19,200 19,250 19,250 19,300 19,300 19,350 19,350 19,400 19,400 19,450 19,450 19,500 19,500 19,550 19,550 19,600 19,600 19,650 19,650 19,700 19,700 19,750 19,750 19,800 19,800 19,850 19,850 19,900 19,900 19,950 19,950 20,000 | 266 267 268 268 269 270 271 271 272 273 273 274 275 275 276 277 278 278 279 280 |
# Your At But Your
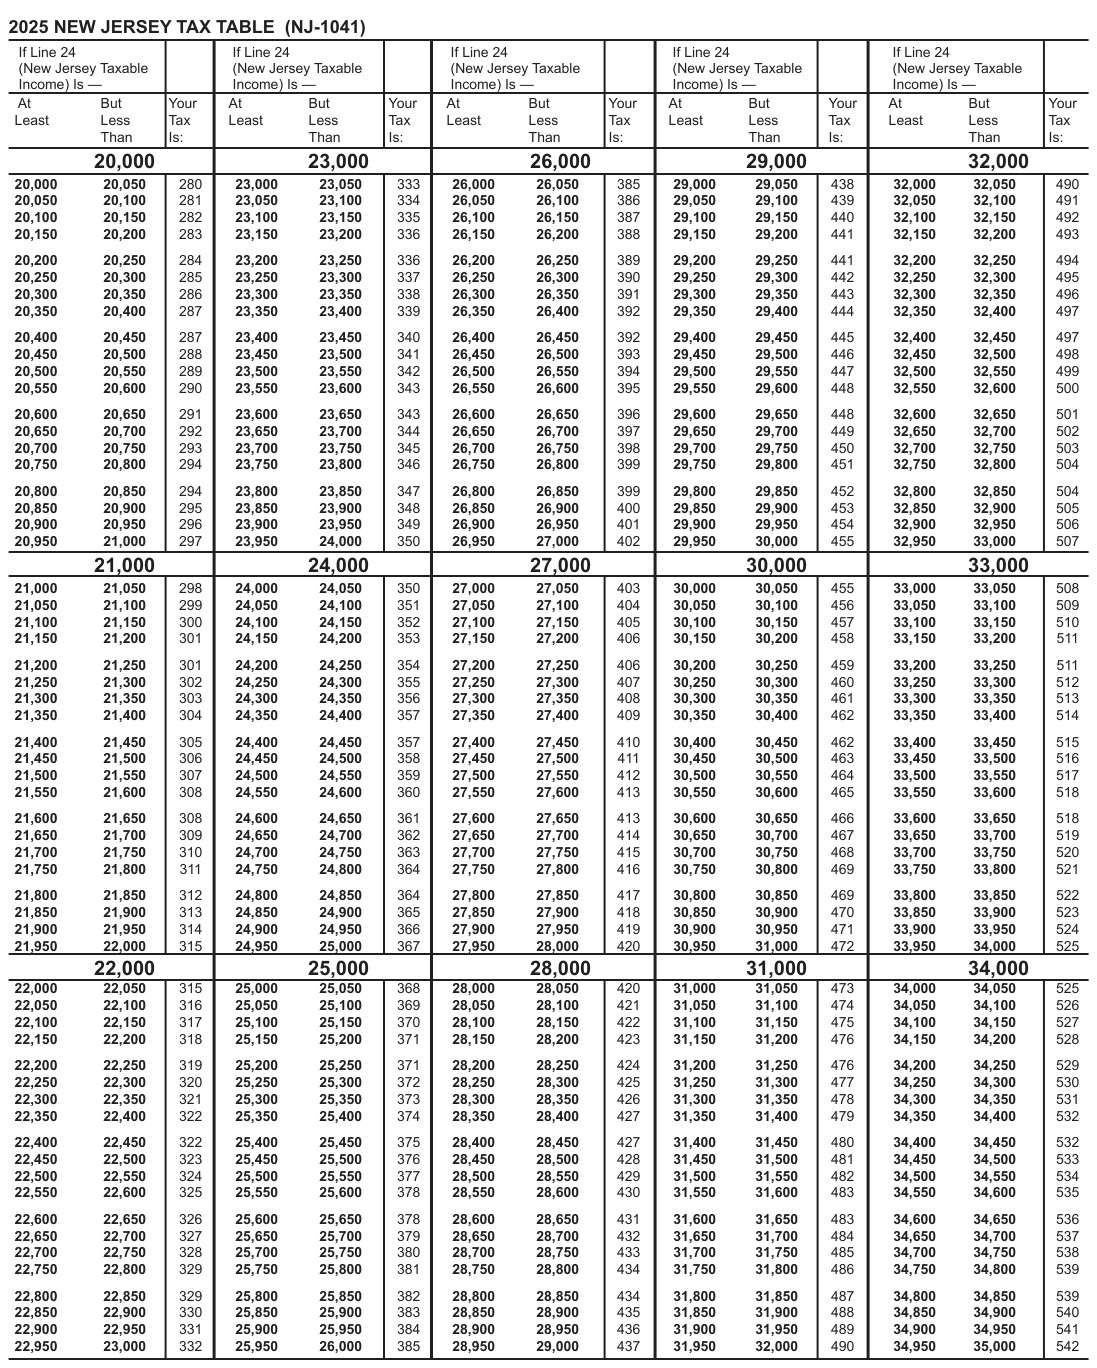
Text version of this table
| If Line 24 (New Jersey Taxable Income) Is — | If Line 24 (New Jersey Taxable Income) Is — | If Line 24 (New Jersey Taxable Income) Is — | If Line 24 (New Jersey Taxable Income) Is — | If Line 24 (New Jersey Taxable Income) Is — | |||||
| At But Least Less Than | Your Tax Is: | At But Least Less Than | Your Tax Is: | At But Least Less Than | Your Tax Is: | At But Least Less Than | Your Tax Is: | At But Least Less Than | Your Tax Is: |
| 20,000 | 23,000 | 26,000 | 29,000 | 32,000 | |||||
| 20,000 20,050 20,050 20,100 20,100 20,150 20,150 20,200 20,200 20,250 20,250 20,300 20,300 20,350 20,350 20,400 20,400 20,450 20,450 20,500 20,500 20,550 20,550 20,600 20,600 20,650 20,650 20,700 20,700 20,750 20,750 20,800 20,800 20,850 20,850 20,900 20,900 20,950 20,950 21,000 | 280 281 282 283 284 285 286 287 287 288 289 290 291 292 293 294 294 295 296 297 | 23,000 23,050 23,050 23,100 23,100 23,150 23,150 23,200 23,200 23,250 23,250 23,300 23,300 23,350 23,350 23,400 23,400 23,450 23,450 23,500 23,500 23,550 23,550 23,600 23,600 23,650 23,650 23,700 23,700 23,750 23,750 23,800 23,800 23,850 23,850 23,900 23,900 23,950 23,950 24,000 | 333 334 335 336 336 337 338 339 340 341 342 343 343 344 345 346 347 348 349 350 | 26,000 26,050 26,050 26,100 26,100 26,150 26,150 26,200 26,200 26,250 26,250 26,300 26,300 26,350 26,350 26,400 26,400 26,450 26,450 26,500 26,500 26,550 26,550 26,600 26,600 26,650 26,650 26,700 26,700 26,750 26,750 26,800 26,800 26,850 26,850 26,900 26,900 26,950 26,950 27,000 | 385 386 387 388 389 390 391 392 392 393 394 395 396 397 398 399 399 400 401 402 | 29,000 29,050 29,050 29,100 29,100 29,150 29,150 29,200 29,200 29,250 29,250 29,300 29,300 29,350 29,350 29,400 29,400 29,450 29,450 29,500 29,500 29,550 29,550 29,600 29,600 29,650 29,650 29,700 29,700 29,750 29,750 29,800 29,800 29,850 29,850 29,900 29,900 29,950 29,950 30,000 | 438 439 440 441 441 442 443 444 445 446 447 448 448 449 450 451 452 453 454 455 | 32,000 32,050 32,050 32,100 32,100 32,150 32,150 32,200 32,200 32,250 32,250 32,300 32,300 32,350 32,350 32,400 32,400 32,450 32,450 32,500 32,500 32,550 32,550 32,600 32,600 32,650 32,650 32,700 32,700 32,750 32,750 32,800 32,800 32,850 32,850 32,900 32,900 32,950 32,950 33,000 | 490 491 492 493 494 495 496 497 497 498 499 500 501 502 503 504 504 505 506 507 |
| 21,000 | 24,000 | 27,000 | 30,000 | 33,000 | |||||
| 21,000 21,050 21,050 21,100 21,100 21,150 21,150 21,200 21,200 21,250 21,250 21,300 21,300 21,350 21,350 21,400 21,400 21,450 21,450 21,500 21,500 21,550 21,550 21,600 21,600 21,650 21,650 21,700 21,700 21,750 21,750 21,800 21,800 21,850 21,850 21,900 21,900 21,950 21,950 22,000 | 298 299 300 301 301 302 303 304 305 306 307 308 308 309 310 311 312 313 314 315 | 24,000 24,050 24,050 24,100 24,100 24,150 24,150 24,200 24,200 24,250 24,250 24,300 24,300 24,350 24,350 24,400 24,400 24,450 24,450 24,500 24,500 24,550 24,550 24,600 24,600 24,650 24,650 24,700 24,700 24,750 24,750 24,800 24,800 24,850 24,850 24,900 24,900 24,950 24,950 25,000 | 350 351 352 353 354 355 356 357 357 358 359 360 361 362 363 364 364 365 366 367 | 27,000 27,050 27,050 27,100 27,100 27,150 27,150 27,200 27,200 27,250 27,250 27,300 27,300 27,350 27,350 27,400 27,400 27,450 27,450 27,500 27,500 27,550 27,550 27,600 27,600 27,650 27,650 27,700 27,700 27,750 27,750 27,800 27,800 27,850 27,850 27,900 27,900 27,950 27,950 28,000 | 403 404 405 406 406 407 408 409 410 411 412 413 413 414 415 416 417 418 419 420 | 30,000 30,050 30,050 30,100 30,100 30,150 30,150 30,200 30,200 30,250 30,250 30,300 30,300 30,350 30,350 30,400 30,400 30,450 30,450 30,500 30,500 30,550 30,550 30,600 30,600 30,650 30,650 30,700 30,700 30,750 30,750 30,800 30,800 30,850 30,850 30,900 30,900 30,950 30,950 31,000 | 455 456 457 458 459 460 461 462 462 463 464 465 466 467 468 469 469 470 471 472 | 33,000 33,050 33,050 33,100 33,100 33,150 33,150 33,200 33,200 33,250 33,250 33,300 33,300 33,350 33,350 33,400 33,400 33,450 33,450 33,500 33,500 33,550 33,550 33,600 33,600 33,650 33,650 33,700 33,700 33,750 33,750 33,800 33,800 33,850 33,850 33,900 33,900 33,950 33,950 34,000 | 508 509 510 511 511 512 513 514 515 516 517 518 518 519 520 521 522 523 524 525 |
| 22,000 | 25,000 | 28,000 | 31,000 | 34,000 | |||||
| 22,000 22,050 22,050 22,100 22,100 22,150 22,150 22,200 22,200 22,250 22,250 22,300 22,300 22,350 22,350 22,400 22,400 22,450 22,450 22,500 22,500 22,550 22,550 22,600 22,600 22,650 22,650 22,700 22,700 22,750 22,750 22,800 22,800 22,850 22,850 22,900 22,900 22,950 22,950 23,000 | 315 316 317 318 319 320 321 322 322 323 324 325 326 327 328 329 329 330 331 332 | 25,000 25,050 25,050 25,100 25,100 25,150 25,150 25,200 25,200 25,250 25,250 25,300 25,300 25,350 25,350 25,400 25,400 25,450 25,450 25,500 25,500 25,550 25,550 25,600 25,600 25,650 25,650 25,700 25,700 25,750 25,750 25,800 25,800 25,850 25,850 25,900 25,900 25,950 25,950 26,000 | 368 369 370 371 371 372 373 374 375 376 377 378 378 379 380 381 382 383 384 385 | 28,000 28,050 28,050 28,100 28,100 28,150 28,150 28,200 28,200 28,250 28,250 28,300 28,300 28,350 28,350 28,400 28,400 28,450 28,450 28,500 28,500 28,550 28,550 28,600 28,600 28,650 28,650 28,700 28,700 28,750 28,750 28,800 28,800 28,850 28,850 28,900 28,900 28,950 28,950 29,000 | 420 421 422 423 424 425 426 427 427 428 429 430 431 432 433 434 434 435 436 437 | 31,000 31,050 31,050 31,100 31,100 31,150 31,150 31,200 31,200 31,250 31,250 31,300 31,300 31,350 31,350 31,400 31,400 31,450 31,450 31,500 31,500 31,550 31,550 31,600 31,600 31,650 31,650 31,700 31,700 31,750 31,750 31,800 31,800 31,850 31,850 31,900 31,900 31,950 31,950 32,000 | 473 474 475 476 476 477 478 479 480 481 482 483 483 484 485 486 487 488 489 490 | 34,000 34,050 34,050 34,100 34,100 34,150 34,150 34,200 34,200 34,250 34,250 34,300 34,300 34,350 34,350 34,400 34,400 34,450 34,450 34,500 34,500 34,550 34,550 34,600 34,600 34,650 34,650 34,700 34,700 34,750 34,750 34,800 34,800 34,850 34,850 34,900 34,900 34,950 34,950 35,000 | 525 526 527 528 529 530 531 532 532 533 534 535 536 537 538 539 539 540 541 542 |
# Your At But Your
# Your At But Your
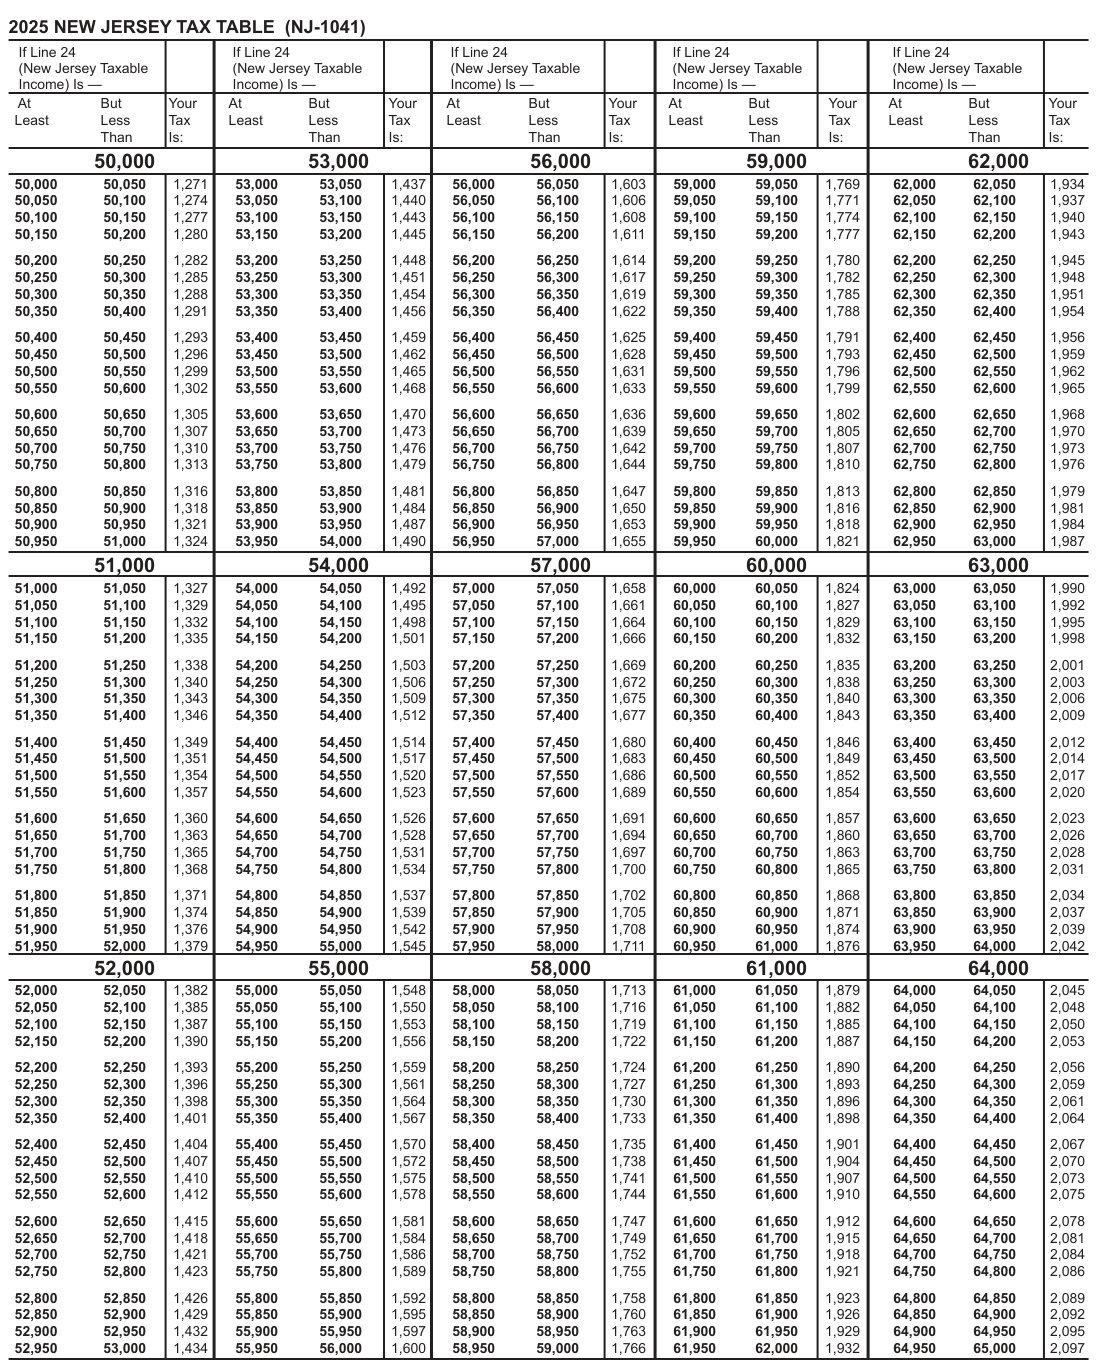
Text version of this table
| If Line 24 (New Jersey Taxable Income) Is — | If Line 24 (New Jersey Taxable Income) Is — | If Line 24 (New Jersey Taxable Income) Is — | If Line 24 (New Jersey Taxable Income) Is — | If Line 24 (New Jersey Taxable Income) Is — | |||||
| At But Least Less Than | Your Tax Is: | At But Least Less Than | Your Tax Is: | At But Least Less Than | Your Tax Is: | At But Least Less Than | Your Tax Is: | At But Least Less Than | Your Tax Is: |
| 50,000 | 53,000 | 56,000 | 59,000 | 62,000 | |||||
| 50,000 50,050 50,050 50,100 50,100 50,150 50,150 50,200 50,200 50,250 50,250 50,300 50,300 50,350 50,350 50,400 50,400 50,450 50,450 50,500 50,500 50,550 50,550 50,600 50,600 50,650 50,650 50,700 50,700 50,750 50,750 50,800 50,800 50,850 50,850 50,900 50,900 50,950 50,950 51,000 | 1,271 1,274 1,277 1,280 1,282 1,285 1,288 1,291 1,293 1,296 1,299 1,302 1,305 1,307 1,310 1,313 1,316 1,318 1,321 1,324 | 53,000 53,050 53,050 53,100 53,100 53,150 53,150 53,200 53,200 53,250 53,250 53,300 53,300 53,350 53,350 53,400 53,400 53,450 53,450 53,500 53,500 53,550 53,550 53,600 53,600 53,650 53,650 53,700 53,700 53,750 53,750 53,800 53,800 53,850 53,850 53,900 53,900 53,950 53,950 54,000 | 1,437 1,440 1,443 1,445 1,448 1,451 1,454 1,456 1,459 1,462 1,465 1,468 1,470 1,473 1,476 1,479 1,481 1,484 1,487 1,490 | 56,000 56,050 56,050 56,100 56,100 56,150 56,150 56,200 56,200 56,250 56,250 56,300 56,300 56,350 56,350 56,400 56,400 56,450 56,450 56,500 56,500 56,550 56,550 56,600 56,600 56,650 56,650 56,700 56,700 56,750 56,750 56,800 56,800 56,850 56,850 56,900 56,900 56,950 56,950 57,000 | 1,603 1,606 1,608 1,611 1,614 1,617 1,619 1,622 1,625 1,628 1,631 1,633 1,636 1,639 1,642 1,644 1,647 1,650 1,653 1,655 | 59,000 59,050 59,050 59,100 59,100 59,150 59,150 59,200 59,200 59,250 59,250 59,300 59,300 59,350 59,350 59,400 59,400 59,450 59,450 59,500 59,500 59,550 59,550 59,600 59,600 59,650 59,650 59,700 59,700 59,750 59,750 59,800 59,800 59,850 59,850 59,900 59,900 59,950 59,950 60,000 | 1,769 1,771 1,774 1,777 1,780 1,782 1,785 1,788 1,791 1,793 1,796 1,799 1,802 1,805 1,807 1,810 1,813 1,816 1,818 1,821 | 62,000 62,050 62,050 62,100 62,100 62,150 62,150 62,200 62,200 62,250 62,250 62,300 62,300 62,350 62,350 62,400 62,400 62,450 62,450 62,500 62,500 62,550 62,550 62,600 62,600 62,650 62,650 62,700 62,700 62,750 62,750 62,800 62,800 62,850 62,850 62,900 62,900 62,950 62,950 63,000 | 1,934 1,937 1,940 1,943 1,945 1,948 1,951 1,954 1,956 1,959 1,962 1,965 1,968 1,970 1,973 1,976 1,979 1,981 1,984 1,987 |
| 51,000 | 54,000 | 57,000 | 60,000 | 63,000 | |||||
| 51,000 51,050 51,050 51,100 51,100 51,150 51,150 51,200 51,200 51,250 51,250 51,300 51,300 51,350 51,350 51,400 51,400 51,450 51,450 51,500 51,500 51,550 51,550 51,600 51,600 51,650 51,650 51,700 51,700 51,750 51,750 51,800 51,800 51,850 51,850 51,900 51,900 51,950 51,950 52,000 | 1,327 1,329 1,332 1,335 1,338 1,340 1,343 1,346 1,349 1,351 1,354 1,357 1,360 1,363 1,365 1,368 1,371 1,374 1,376 1,379 | 54,000 54,050 54,050 54,100 54,100 54,150 54,150 54,200 54,200 54,250 54,250 54,300 54,300 54,350 54,350 54,400 54,400 54,450 54,450 54,500 54,500 54,550 54,550 54,600 54,600 54,650 54,650 54,700 54,700 54,750 54,750 54,800 54,800 54,850 54,850 54,900 54,900 54,950 54,950 55,000 | 1,492 1,495 1,498 1,501 1,503 1,506 1,509 1,512 1,514 1,517 1,520 1,523 1,526 1,528 1,531 1,534 1,537 1,539 1,542 1,545 | 57,000 57,050 57,050 57,100 57,100 57,150 57,150 57,200 57,200 57,250 57,250 57,300 57,300 57,350 57,350 57,400 57,400 57,450 57,450 57,500 57,500 57,550 57,550 57,600 57,600 57,650 57,650 57,700 57,700 57,750 57,750 57,800 57,800 57,850 57,850 57,900 57,900 57,950 57,950 58,000 | 1,658 1,661 1,664 1,666 1,669 1,672 1,675 1,677 1,680 1,683 1,686 1,689 1,691 1,694 1,697 1,700 1,702 1,705 1,708 1,711 | 60,000 60,050 60,050 60,100 60,100 60,150 60,150 60,200 60,200 60,250 60,250 60,300 60,300 60,350 60,350 60,400 60,400 60,450 60,450 60,500 60,500 60,550 60,550 60,600 60,600 60,650 60,650 60,700 60,700 60,750 60,750 60,800 60,800 60,850 60,850 60,900 60,900 60,950 60,950 61,000 | 1,824 1,827 1,829 1,832 1,835 1,838 1,840 1,843 1,846 1,849 1,852 1,854 1,857 1,860 1,863 1,865 1,868 1,871 1,874 1,876 | 63,000 63,050 63,050 63,100 63,100 63,150 63,150 63,200 63,200 63,250 63,250 63,300 63,300 63,350 63,350 63,400 63,400 63,450 63,450 63,500 63,500 63,550 63,550 63,600 63,600 63,650 63,650 63,700 63,700 63,750 63,750 63,800 63,800 63,850 63,850 63,900 63,900 63,950 63,950 64,000 | 1,990 1,992 1,995 1,998 2,001 2,003 2,006 2,009 2,012 2,014 2,017 2,020 2,023 2,026 2,028 2,031 2,034 2,037 2,039 2,042 |
| 52,000 | 55,000 | 58,000 | 61,000 | 64,000 | |||||
| 52,000 52,050 52,050 52,100 52,100 52,150 52,150 52,200 52,200 52,250 52,250 52,300 52,300 52,350 52,350 52,400 52,400 52,450 52,450 52,500 52,500 52,550 52,550 52,600 52,600 52,650 52,650 52,700 52,700 52,750 52,750 52,800 52,800 52,850 52,850 52,900 52,900 52,950 52,950 53,000 | 1,382 1,385 1,387 1,390 1,393 1,396 1,398 1,401 1,404 1,407 1,410 1,412 1,415 1,418 1,421 1,423 1,426 1,429 1,432 1,434 | 55,000 55,050 55,050 55,100 55,100 55,150 55,150 55,200 55,200 55,250 55,250 55,300 55,300 55,350 55,350 55,400 55,400 55,450 55,450 55,500 55,500 55,550 55,550 55,600 55,600 55,650 55,650 55,700 55,700 55,750 55,750 55,800 55,800 55,850 55,850 55,900 55,900 55,950 55,950 56,000 | 1,548 1,550 1,553 1,556 1,559 1,561 1,564 1,567 1,570 1,572 1,575 1,578 1,581 1,584 1,586 1,589 1,592 1,595 1,597 1,600 | 58,000 58,050 58,050 58,100 58,100 58,150 58,150 58,200 58,200 58,250 58,250 58,300 58,300 58,350 58,350 58,400 58,400 58,450 58,450 58,500 58,500 58,550 58,550 58,600 58,600 58,650 58,650 58,700 58,700 58,750 58,750 58,800 58,800 58,850 58,850 58,900 58,900 58,950 58,950 59,000 | 1,713 1,716 1,719 1,722 1,724 1,727 1,730 1,733 1,735 1,738 1,741 1,744 1,747 1,749 1,752 1,755 1,758 1,760 1,763 1,766 | 61,000 61,050 61,050 61,100 61,100 61,150 61,150 61,200 61,200 61,250 61,250 61,300 61,300 61,350 61,350 61,400 61,400 61,450 61,450 61,500 61,500 61,550 61,550 61,600 61,600 61,650 61,650 61,700 61,700 61,750 61,750 61,800 61,800 61,850 61,850 61,900 61,900 61,950 61,950 62,000 | 1,879 1,882 1,885 1,887 1,890 1,893 1,896 1,898 1,901 1,904 1,907 1,910 1,912 1,915 1,918 1,921 1,923 1,926 1,929 1,932 | 64,000 64,050 64,050 64,100 64,100 64,150 64,150 64,200 64,200 64,250 64,250 64,300 64,300 64,350 64,350 64,400 64,400 64,450 64,450 64,500 64,500 64,550 64,550 64,600 64,600 64,650 64,650 64,700 64,700 64,750 64,750 64,800 64,800 64,850 64,850 64,900 64,900 64,950 64,950 65,000 | 2,045 2,048 2,050 2,053 2,056 2,059 2,061 2,064 2,067 2,070 2,073 2,075 2,078 2,081 2,084 2,086 2,089 2,092 2,095 2,097 |
# Your At But Your
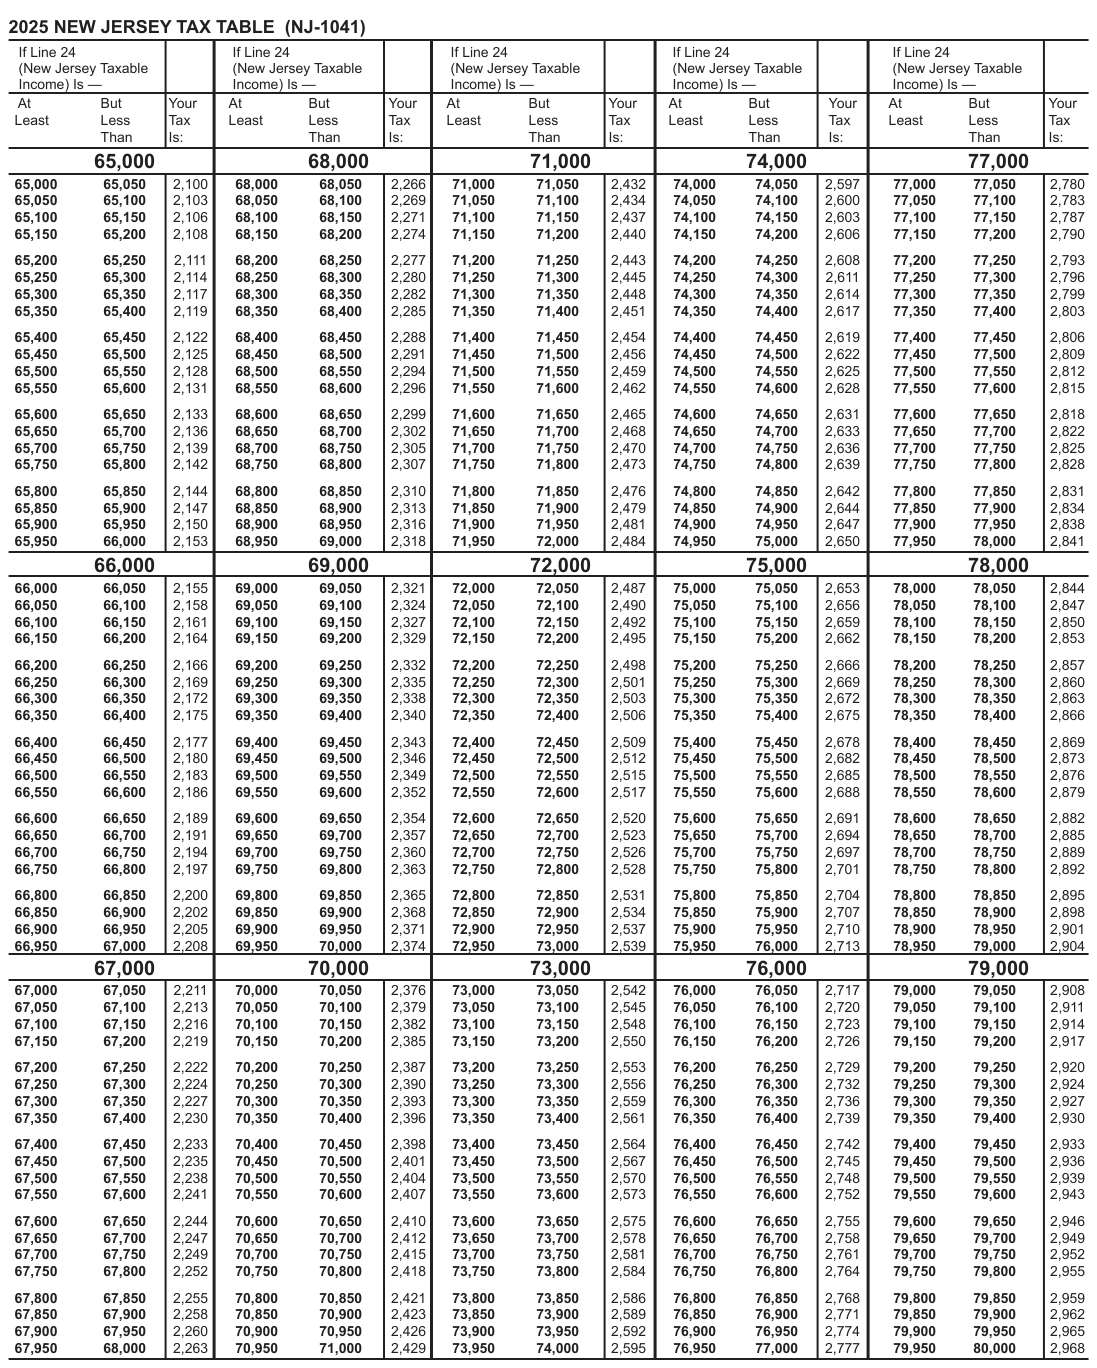
Text version of this table
| If Line 24 (New Jersey Taxable Income) Is — | If Line 24 (New Jersey Taxable Income) Is — | If Line 24 (New Jersey Taxable Income) Is — | If Line 24 (New Jersey Taxable Income) Is — | If Line 24 (New Jersey Taxable Income) Is — | |||||
| At But Least Less Than | Your Tax Is: | At But Least Less Than | Your Tax Is: | At But Least Less Than | Your Tax Is: | At But Least Less Than | Your Tax Is: | At But Least Less Than | Your Tax Is: |
| 65,000 | 68,000 | 71,000 | 74,000 | 77,000 | |||||
| 65,000 65,050 65,050 65,100 65,100 65,150 65,150 65,200 65,200 65,250 65,250 65,300 65,300 65,350 65,350 65,400 65,400 65,450 65,450 65,500 65,500 65,550 65,550 65,600 65,600 65,650 65,650 65,700 65,700 65,750 65,750 65,800 65,800 65,850 65,850 65,900 65,900 65,950 65,950 66,000 | 2,100 2,103 2,106 2,108 2,111 2,114 2,117 2,119 2,122 2,125 2,128 2,131 2,133 2,136 2,139 2,142 2,144 2,147 2,150 2,153 | 68,000 68,050 68,050 68,100 68,100 68,150 68,150 68,200 68,200 68,250 68,250 68,300 68,300 68,350 68,350 68,400 68,400 68,450 68,450 68,500 68,500 68,550 68,550 68,600 68,600 68,650 68,650 68,700 68,700 68,750 68,750 68,800 68,800 68,850 68,850 68,900 68,900 68,950 68,950 69,000 | 2,266 2,269 2,271 2,274 2,277 2,280 2,282 2,285 2,288 2,291 2,294 2,296 2,299 2,302 2,305 2,307 2,310 2,313 2,316 2,318 | 71,000 71,050 71,050 71,100 71,100 71,150 71,150 71,200 71,200 71,250 71,250 71,300 71,300 71,350 71,350 71,400 71,400 71,450 71,450 71,500 71,500 71,550 71,550 71,600 71,600 71,650 71,650 71,700 71,700 71,750 71,750 71,800 71,800 71,850 71,850 71,900 71,900 71,950 71,950 72,000 | 2,432 2,434 2,437 2,440 2,443 2,445 2,448 2,451 2,454 2,456 2,459 2,462 2,465 2,468 2,470 2,473 2,476 2,479 2,481 2,484 | 74,000 74,050 74,050 74,100 74,100 74,150 74,150 74,200 74,200 74,250 74,250 74,300 74,300 74,350 74,350 74,400 74,400 74,450 74,450 74,500 74,500 74,550 74,550 74,600 74,600 74,650 74,650 74,700 74,700 74,750 74,750 74,800 74,800 74,850 74,850 74,900 74,900 74,950 74,950 75,000 | 2,597 2,600 2,603 2,606 2,608 2,611 2,614 2,617 2,619 2,622 2,625 2,628 2,631 2,633 2,636 2,639 2,642 2,644 2,647 2,650 | 77,000 77,050 77,050 77,100 77,100 77,150 77,150 77,200 77,200 77,250 77,250 77,300 77,300 77,350 77,350 77,400 77,400 77,450 77,450 77,500 77,500 77,550 77,550 77,600 77,600 77,650 77,650 77,700 77,700 77,750 77,750 77,800 77,800 77,850 77,850 77,900 77,900 77,950 77,950 78,000 | 2,780 2,783 2,787 2,790 2,793 2,796 2,799 2,803 2,806 2,809 2,812 2,815 2,818 2,822 2,825 2,828 2,831 2,834 2,838 2,841 |
| 66,000 | 69,000 | 72,000 | 75,000 | 78,000 | |||||
| 66,000 66,050 66,050 66,100 66,100 66,150 66,150 66,200 66,200 66,250 66,250 66,300 66,300 66,350 66,350 66,400 66,400 66,450 66,450 66,500 66,500 66,550 66,550 66,600 66,600 66,650 66,650 66,700 66,700 66,750 66,750 66,800 66,800 66,850 66,850 66,900 66,900 66,950 66,950 67,000 | 2,155 2,158 2,161 2,164 2,166 2,169 2,172 2,175 2,177 2,180 2,183 2,186 2,189 2,191 2,194 2,197 2,200 2,202 2,205 2,208 | 69,000 69,050 69,050 69,100 69,100 69,150 69,150 69,200 69,200 69,250 69,250 69,300 69,300 69,350 69,350 69,400 69,400 69,450 69,450 69,500 69,500 69,550 69,550 69,600 69,600 69,650 69,650 69,700 69,700 69,750 69,750 69,800 69,800 69,850 69,850 69,900 69,900 69,950 69,950 70,000 | 2,321 2,324 2,327 2,329 2,332 2,335 2,338 2,340 2,343 2,346 2,349 2,352 2,354 2,357 2,360 2,363 2,365 2,368 2,371 2,374 | 72,000 72,050 72,050 72,100 72,100 72,150 72,150 72,200 72,200 72,250 72,250 72,300 72,300 72,350 72,350 72,400 72,400 72,450 72,450 72,500 72,500 72,550 72,550 72,600 72,600 72,650 72,650 72,700 72,700 72,750 72,750 72,800 72,800 72,850 72,850 72,900 72,900 72,950 72,950 73,000 | 2,487 2,490 2,492 2,495 2,498 2,501 2,503 2,506 2,509 2,512 2,515 2,517 2,520 2,523 2,526 2,528 2,531 2,534 2,537 2,539 | 75,000 75,050 75,050 75,100 75,100 75,150 75,150 75,200 75,200 75,250 75,250 75,300 75,300 75,350 75,350 75,400 75,400 75,450 75,450 75,500 75,500 75,550 75,550 75,600 75,600 75,650 75,650 75,700 75,700 75,750 75,750 75,800 75,800 75,850 75,850 75,900 75,900 75,950 75,950 76,000 | 2,653 2,656 2,659 2,662 2,666 2,669 2,672 2,675 2,678 2,682 2,685 2,688 2,691 2,694 2,697 2,701 2,704 2,707 2,710 2,713 | 78,000 78,050 78,050 78,100 78,100 78,150 78,150 78,200 78,200 78,250 78,250 78,300 78,300 78,350 78,350 78,400 78,400 78,450 78,450 78,500 78,500 78,550 78,550 78,600 78,600 78,650 78,650 78,700 78,700 78,750 78,750 78,800 78,800 78,850 78,850 78,900 78,900 78,950 78,950 79,000 | 2,844 2,847 2,850 2,853 2,857 2,860 2,863 2,866 2,869 2,873 2,876 2,879 2,882 2,885 2,889 2,892 2,895 2,898 2,901 2,904 |
| 67,000 | 70,000 | 73,000 | 76,000 | 79,000 | |||||
| 67,000 67,050 67,050 67,100 67,100 67,150 67,150 67,200 67,200 67,250 67,250 67,300 67,300 67,350 67,350 67,400 67,400 67,450 67,450 67,500 67,500 67,550 67,550 67,600 67,600 67,650 67,650 67,700 67,700 67,750 67,750 67,800 67,800 67,850 67,850 67,900 67,900 67,950 67,950 68,000 | 2,211 2,213 2,216 2,219 2,222 2,224 2,227 2,230 2,233 2,235 2,238 2,241 2,244 2,247 2,249 2,252 2,255 2,258 2,260 2,263 | 70,000 70,050 70,050 70,100 70,100 70,150 70,150 70,200 70,200 70,250 70,250 70,300 70,300 70,350 70,350 70,400 70,400 70,450 70,450 70,500 70,500 70,550 70,550 70,600 70,600 70,650 70,650 70,700 70,700 70,750 70,750 70,800 70,800 70,850 70,850 70,900 70,900 70,950 70,950 71,000 | 2,376 2,379 2,382 2,385 2,387 2,390 2,393 2,396 2,398 2,401 2,404 2,407 2,410 2,412 2,415 2,418 2,421 2,423 2,426 2,429 | 73,000 73,050 73,050 73,100 73,100 73,150 73,150 73,200 73,200 73,250 73,250 73,300 73,300 73,350 73,350 73,400 73,400 73,450 73,450 73,500 73,500 73,550 73,550 73,600 73,600 73,650 73,650 73,700 73,700 73,750 73,750 73,800 73,800 73,850 73,850 73,900 73,900 73,950 73,950 74,000 | 2,542 2,545 2,548 2,550 2,553 2,556 2,559 2,561 2,564 2,567 2,570 2,573 2,575 2,578 2,581 2,584 2,586 2,589 2,592 2,595 | 76,000 76,050 76,050 76,100 76,100 76,150 76,150 76,200 76,200 76,250 76,250 76,300 76,300 76,350 76,350 76,400 76,400 76,450 76,450 76,500 76,500 76,550 76,550 76,600 76,600 76,650 76,650 76,700 76,700 76,750 76,750 76,800 76,800 76,850 76,850 76,900 76,900 76,950 76,950 77,000 | 2,717 2,720 2,723 2,726 2,729 2,732 2,736 2,739 2,742 2,745 2,748 2,752 2,755 2,758 2,761 2,764 2,768 2,771 2,774 2,777 | 79,000 79,050 79,050 79,100 79,100 79,150 79,150 79,200 79,200 79,250 79,250 79,300 79,300 79,350 79,350 79,400 79,400 79,450 79,450 79,500 79,500 79,550 79,550 79,600 79,600 79,650 79,650 79,700 79,700 79,750 79,750 79,800 79,800 79,850 79,850 79,900 79,900 79,950 79,950 80,000 | 2,908 2,911 2,914 2,917 2,920 2,924 2,927 2,930 2,933 2,936 2,939 2,943 2,946 2,949 2,952 2,955 2,959 2,962 2,965 2,968 |
# Your At But Your
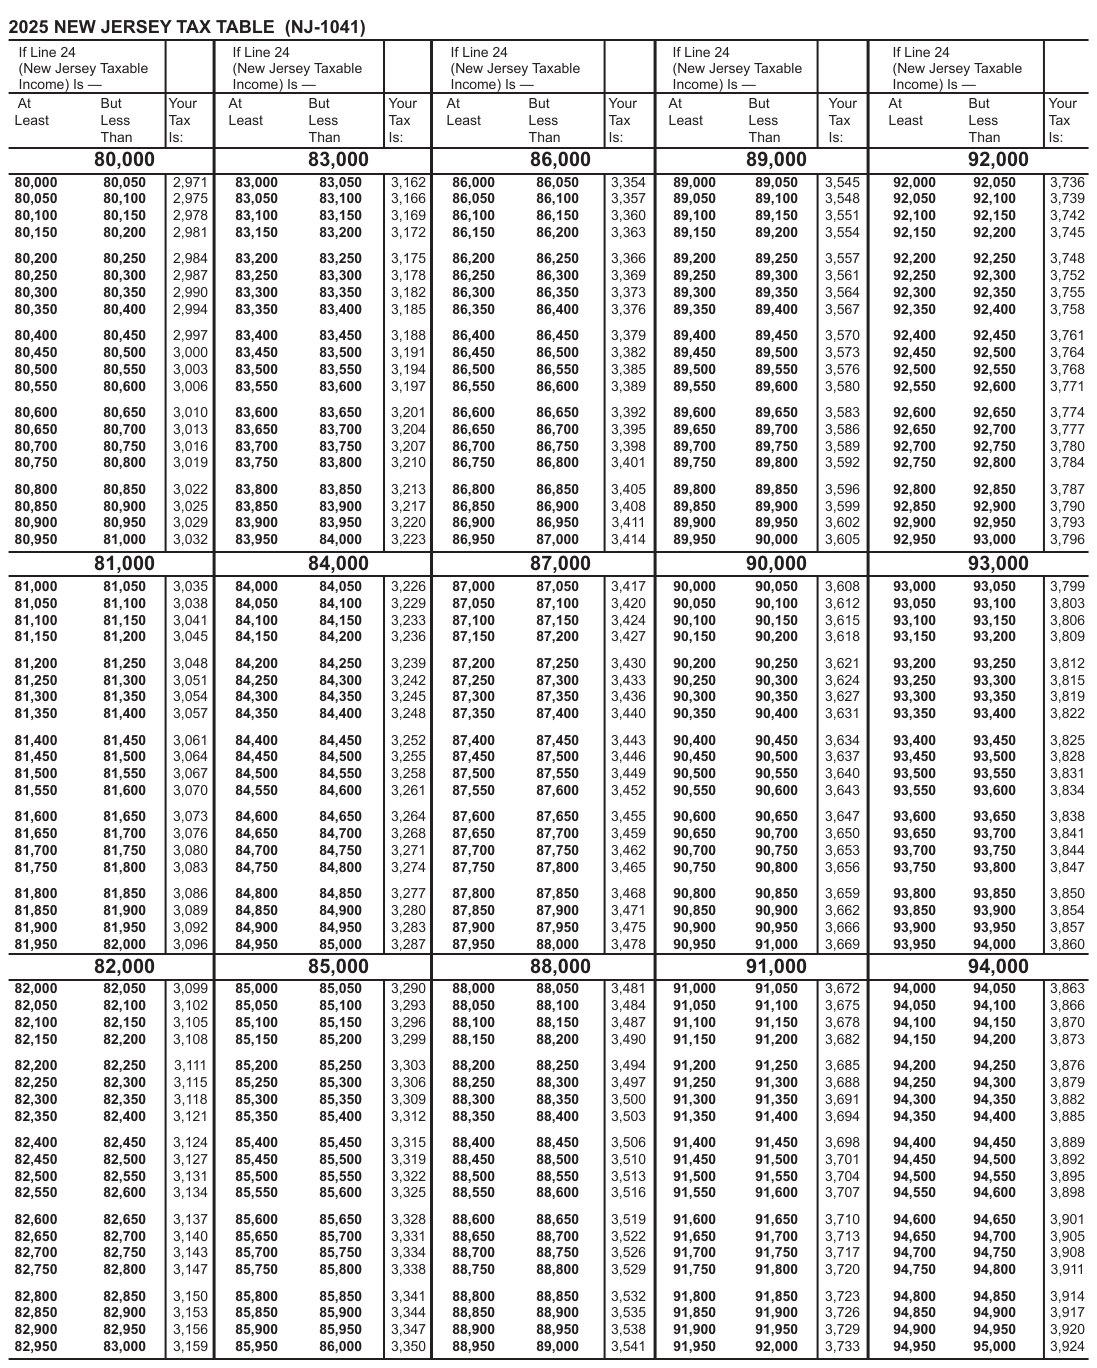
Text version of this table
| If Line 24 (New Jersey Taxable Income) Is — | If Line 24 (New Jersey Taxable Income) Is — | If Line 24 (New Jersey Taxable Income) Is — | If Line 24 (New Jersey Taxable Income) Is — | If Line 24 (New Jersey Taxable Income) Is — | |||||
| At But Least Less Than | Your Tax Is: | At But Least Less Than | Your Tax Is: | At But Least Less Than | Your Tax Is: | At But Least Less Than | Your Tax Is: | At But Least Less Than | Your Tax Is: |
| 80,000 | 83,000 | 86,000 | 89,000 | 92,000 | |||||
| 80,000 80,050 80,050 80,100 80,100 80,150 80,150 80,200 80,200 80,250 80,250 80,300 80,300 80,350 80,350 80,400 80,400 80,450 80,450 80,500 80,500 80,550 80,550 80,600 80,600 80,650 80,650 80,700 80,700 80,750 80,750 80,800 80,800 80,850 80,850 80,900 80,900 80,950 80,950 81,000 | 2,971 2,975 2,978 2,981 2,984 2,987 2,990 2,994 2,997 3,000 3,003 3,006 3,010 3,013 3,016 3,019 3,022 3,025 3,029 3,032 | 83,000 83,050 83,050 83,100 83,100 83,150 83,150 83,200 83,200 83,250 83,250 83,300 83,300 83,350 83,350 83,400 83,400 83,450 83,450 83,500 83,500 83,550 83,550 83,600 83,600 83,650 83,650 83,700 83,700 83,750 83,750 83,800 83,800 83,850 83,850 83,900 83,900 83,950 83,950 84,000 | 3,162 3,166 3,169 3,172 3,175 3,178 3,182 3,185 3,188 3,191 3,194 3,197 3,201 3,204 3,207 3,210 3,213 3,217 3,220 3,223 | 86,000 86,050 86,050 86,100 86,100 86,150 86,150 86,200 86,200 86,250 86,250 86,300 86,300 86,350 86,350 86,400 86,400 86,450 86,450 86,500 86,500 86,550 86,550 86,600 86,600 86,650 86,650 86,700 86,700 86,750 86,750 86,800 86,800 86,850 86,850 86,900 86,900 86,950 86,950 87,000 | 3,354 3,357 3,360 3,363 3,366 3,369 3,373 3,376 3,379 3,382 3,385 3,389 3,392 3,395 3,398 3,401 3,405 3,408 3,411 3,414 | 89,000 89,050 89,050 89,100 89,100 89,150 89,150 89,200 89,200 89,250 89,250 89,300 89,300 89,350 89,350 89,400 89,400 89,450 89,450 89,500 89,500 89,550 89,550 89,600 89,600 89,650 89,650 89,700 89,700 89,750 89,750 89,800 89,800 89,850 89,850 89,900 89,900 89,950 89,950 90,000 | 3,545 3,548 3,551 3,554 3,557 3,561 3,564 3,567 3,570 3,573 3,576 3,580 3,583 3,586 3,589 3,592 3,596 3,599 3,602 3,605 | 92,000 92,050 92,050 92,100 92,100 92,150 92,150 92,200 92,200 92,250 92,250 92,300 92,300 92,350 92,350 92,400 92,400 92,450 92,450 92,500 92,500 92,550 92,550 92,600 92,600 92,650 92,650 92,700 92,700 92,750 92,750 92,800 92,800 92,850 92,850 92,900 92,900 92,950 92,950 93,000 | 3,736 3,739 3,742 3,745 3,748 3,752 3,755 3,758 3,761 3,764 3,768 3,771 3,774 3,777 3,780 3,784 3,787 3,790 3,793 3,796 |
| 81,000 | 84,000 | 87,000 | 90,000 | 93,000 | |||||
| 81,000 81,050 81,050 81,100 81,100 81,150 81,150 81,200 81,200 81,250 81,250 81,300 81,300 81,350 81,350 81,400 81,400 81,450 81,450 81,500 81,500 81,550 81,550 81,600 81,600 81,650 81,650 81,700 81,700 81,750 81,750 81,800 81,800 81,850 81,850 81,900 81,900 81,950 81,950 82,000 | 3,035 3,038 3,041 3,045 3,048 3,051 3,054 3,057 3,061 3,064 3,067 3,070 3,073 3,076 3,080 3,083 3,086 3,089 3,092 3,096 | 84,000 84,050 84,050 84,100 84,100 84,150 84,150 84,200 84,200 84,250 84,250 84,300 84,300 84,350 84,350 84,400 84,400 84,450 84,450 84,500 84,500 84,550 84,550 84,600 84,600 84,650 84,650 84,700 84,700 84,750 84,750 84,800 84,800 84,850 84,850 84,900 84,900 84,950 84,950 85,000 | 3,226 3,229 3,233 3,236 3,239 3,242 3,245 3,248 3,252 3,255 3,258 3,261 3,264 3,268 3,271 3,274 3,277 3,280 3,283 3,287 | 87,000 87,050 87,050 87,100 87,100 87,150 87,150 87,200 87,200 87,250 87,250 87,300 87,300 87,350 87,350 87,400 87,400 87,450 87,450 87,500 87,500 87,550 87,550 87,600 87,600 87,650 87,650 87,700 87,700 87,750 87,750 87,800 87,800 87,850 87,850 87,900 87,900 87,950 87,950 88,000 | 3,417 3,420 3,424 3,427 3,430 3,433 3,436 3,440 3,443 3,446 3,449 3,452 3,455 3,459 3,462 3,465 3,468 3,471 3,475 3,478 | 90,000 90,050 90,050 90,100 90,100 90,150 90,150 90,200 90,200 90,250 90,250 90,300 90,300 90,350 90,350 90,400 90,400 90,450 90,450 90,500 90,500 90,550 90,550 90,600 90,600 90,650 90,650 90,700 90,700 90,750 90,750 90,800 90,800 90,850 90,850 90,900 90,900 90,950 90,950 91,000 | 3,608 3,612 3,615 3,618 3,621 3,624 3,627 3,631 3,634 3,637 3,640 3,643 3,647 3,650 3,653 3,656 3,659 3,662 3,666 3,669 | 93,000 93,050 93,050 93,100 93,100 93,150 93,150 93,200 93,200 93,250 93,250 93,300 93,300 93,350 93,350 93,400 93,400 93,450 93,450 93,500 93,500 93,550 93,550 93,600 93,600 93,650 93,650 93,700 93,700 93,750 93,750 93,800 93,800 93,850 93,850 93,900 93,900 93,950 93,950 94,000 | 3,799 3,803 3,806 3,809 3,812 3,815 3,819 3,822 3,825 3,828 3,831 3,834 3,838 3,841 3,844 3,847 3,850 3,854 3,857 3,860 |
| 82,000 | 85,000 | 88,000 | 91,000 | 94,000 | |||||
| 82,000 82,050 82,050 82,100 82,100 82,150 82,150 82,200 82,200 82,250 82,250 82,300 82,300 82,350 82,350 82,400 82,400 82,450 82,450 82,500 82,500 82,550 82,550 82,600 82,600 82,650 82,650 82,700 82,700 82,750 82,750 82,800 82,800 82,850 82,850 82,900 82,900 82,950 82,950 83,000 | 3,099 3,102 3,105 3,108 3,111 3,115 3,118 3,121 3,124 3,127 3,131 3,134 3,137 3,140 3,143 3,147 3,150 3,153 3,156 3,159 | 85,000 85,050 85,050 85,100 85,100 85,150 85,150 85,200 85,200 85,250 85,250 85,300 85,300 85,350 85,350 85,400 85,400 85,450 85,450 85,500 85,500 85,550 85,550 85,600 85,600 85,650 85,650 85,700 85,700 85,750 85,750 85,800 85,800 85,850 85,850 85,900 85,900 85,950 85,950 86,000 | 3,290 3,293 3,296 3,299 3,303 3,306 3,309 3,312 3,315 3,319 3,322 3,325 3,328 3,331 3,334 3,338 3,341 3,344 3,347 3,350 | 88,000 88,050 88,050 88,100 88,100 88,150 88,150 88,200 88,200 88,250 88,250 88,300 88,300 88,350 88,350 88,400 88,400 88,450 88,450 88,500 88,500 88,550 88,550 88,600 88,600 88,650 88,650 88,700 88,700 88,750 88,750 88,800 88,800 88,850 88,850 88,900 88,900 88,950 88,950 89,000 | 3,481 3,484 3,487 3,490 3,494 3,497 3,500 3,503 3,506 3,510 3,513 3,516 3,519 3,522 3,526 3,529 3,532 3,535 3,538 3,541 | 91,000 91,050 91,050 91,100 91,100 91,150 91,150 91,200 91,200 91,250 91,250 91,300 91,300 91,350 91,350 91,400 91,400 91,450 91,450 91,500 91,500 91,550 91,550 91,600 91,600 91,650 91,650 91,700 91,700 91,750 91,750 91,800 91,800 91,850 91,850 91,900 91,900 91,950 91,950 92,000 | 3,672 3,675 3,678 3,682 3,685 3,688 3,691 3,694 3,698 3,701 3,704 3,707 3,710 3,713 3,717 3,720 3,723 3,726 3,729 3,733 | 94,000 94,050 94,050 94,100 94,100 94,150 94,150 94,200 94,200 94,250 94,250 94,300 94,300 94,350 94,350 94,400 94,400 94,450 94,450 94,500 94,500 94,550 94,550 94,600 94,600 94,650 94,650 94,700 94,700 94,750 94,750 94,800 94,800 94,850 94,850 94,900 94,900 94,950 94,950 95,000 | 3,863 3,866 3,870 3,873 3,876 3,879 3,882 3,885 3,889 3,892 3,895 3,898 3,901 3,905 3,908 3,911 3,914 3,917 3,920 3,924 |
# Your At But Your
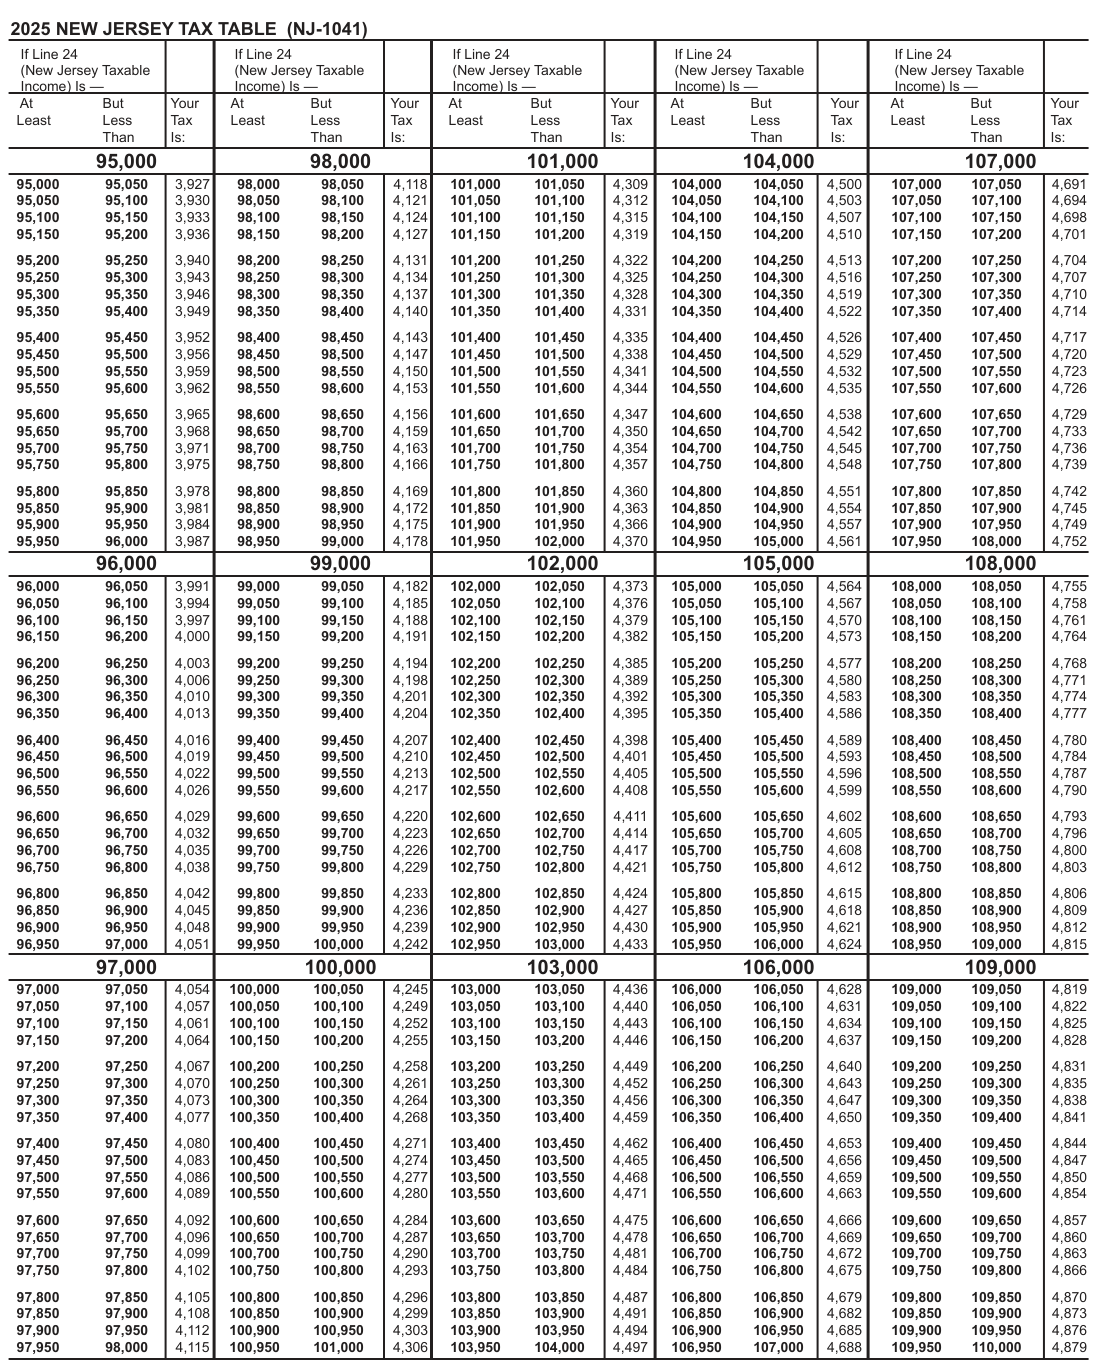
Text version of this table
| If Line 24 (New Jersey Taxable Income) Is — | If Line 24 (New Jersey Taxable Income) Is — | If Line 24 (New Jersey Taxable Income) Is — | If Line 24 (New Jersey Taxable Income) Is — | If Line 24 (New Jersey Taxable Income) Is — | |||||
| At But Least Less Than | Your Tax Is: | At But Least Less Than | Your Tax Is: | At But Least Less Than | Your Tax Is: | At But Least Less Than | Your Tax Is: | At But Least Less Than | Your Tax Is: |
| 95,000 | 98,000 | 101,000 | 104,000 | 107,000 | |||||
| 95,000 95,050 95,050 95,100 95,100 95,150 95,150 95,200 95,200 95,250 95,250 95,300 95,300 95,350 95,350 95,400 95,400 95,450 95,450 95,500 95,500 95,550 95,550 95,600 95,600 95,650 95,650 95,700 95,700 95,750 95,750 95,800 95,800 95,850 95,850 95,900 95,900 95,950 95,950 96,000 | 3,927 3,930 3,933 3,936 3,940 3,943 3,946 3,949 3,952 3,956 3,959 3,962 3,965 3,968 3,971 3,975 3,978 3,981 3,984 3,987 | 98,000 98,050 98,050 98,100 98,100 98,150 98,150 98,200 98,200 98,250 98,250 98,300 98,300 98,350 98,350 98,400 98,400 98,450 98,450 98,500 98,500 98,550 98,550 98,600 98,600 98,650 98,650 98,700 98,700 98,750 98,750 98,800 98,800 98,850 98,850 98,900 98,900 98,950 98,950 99,000 | 4,118 4,121 4,124 4,127 4,131 4,134 4,137 4,140 4,143 4,147 4,150 4,153 4,156 4,159 4,163 4,166 4,169 4,172 4,175 4,178 | 101,000 101,050 101,050 101,100 101,100 101,150 101,150 101,200 101,200 101,250 101,250 101,300 101,300 101,350 101,350 101,400 101,400 101,450 101,450 101,500 101,500 101,550 101,550 101,600 101,600 101,650 101,650 101,700 101,700 101,750 101,750 101,800 101,800 101,850 101,850 101,900 101,900 101,950 101,950 102,000 | 4,309 4,312 4,315 4,319 4,322 4,325 4,328 4,331 4,335 4,338 4,341 4,344 4,347 4,350 4,354 4,357 4,360 4,363 4,366 4,370 | 104,000 104,050 104,050 104,100 104,100 104,150 104,150 104,200 104,200 104,250 104,250 104,300 104,300 104,350 104,350 104,400 104,400 104,450 104,450 104,500 104,500 104,550 104,550 104,600 104,600 104,650 104,650 104,700 104,700 104,750 104,750 104,800 104,800 104,850 104,850 104,900 104,900 104,950 104,950 105,000 | 4,500 4,503 4,507 4,510 4,513 4,516 4,519 4,522 4,526 4,529 4,532 4,535 4,538 4,542 4,545 4,548 4,551 4,554 4,557 4,561 | 107,000 107,050 107,050 107,100 107,100 107,150 107,150 107,200 107,200 107,250 107,250 107,300 107,300 107,350 107,350 107,400 107,400 107,450 107,450 107,500 107,500 107,550 107,550 107,600 107,600 107,650 107,650 107,700 107,700 107,750 107,750 107,800 107,800 107,850 107,850 107,900 107,900 107,950 107,950 108,000 | 4,691 4,694 4,698 4,701 4,704 4,707 4,710 4,714 4,717 4,720 4,723 4,726 4,729 4,733 4,736 4,739 4,742 4,745 4,749 4,752 |
| 96,000 | 99,000 | 102,000 | 105,000 | 108,000 | |||||
| 96,000 96,050 96,050 96,100 96,100 96,150 96,150 96,200 96,200 96,250 96,250 96,300 96,300 96,350 96,350 96,400 96,400 96,450 96,450 96,500 96,500 96,550 96,550 96,600 96,600 96,650 96,650 96,700 96,700 96,750 96,750 96,800 96,800 96,850 96,850 96,900 96,900 96,950 96,950 97,000 | 3,991 3,994 3,997 4,000 4,003 4,006 4,010 4,013 4,016 4,019 4,022 4,026 4,029 4,032 4,035 4,038 4,042 4,045 4,048 4,051 | 99,000 99,050 99,050 99,100 99,100 99,150 99,150 99,200 99,200 99,250 99,250 99,300 99,300 99,350 99,350 99,400 99,400 99,450 99,450 99,500 99,500 99,550 99,550 99,600 99,600 99,650 99,650 99,700 99,700 99,750 99,750 99,800 99,800 99,850 99,850 99,900 99,900 99,950 99,950 100,000 | 4,182 4,185 4,188 4,191 4,194 4,198 4,201 4,204 4,207 4,210 4,213 4,217 4,220 4,223 4,226 4,229 4,233 4,236 4,239 4,242 | 102,000 102,050 102,050 102,100 102,100 102,150 102,150 102,200 102,200 102,250 102,250 102,300 102,300 102,350 102,350 102,400 102,400 102,450 102,450 102,500 102,500 102,550 102,550 102,600 102,600 102,650 102,650 102,700 102,700 102,750 102,750 102,800 102,800 102,850 102,850 102,900 102,900 102,950 102,950 103,000 | 4,373 4,376 4,379 4,382 4,385 4,389 4,392 4,395 4,398 4,401 4,405 4,408 4,411 4,414 4,417 4,421 4,424 4,427 4,430 4,433 | 105,000 105,050 105,050 105,100 105,100 105,150 105,150 105,200 105,200 105,250 105,250 105,300 105,300 105,350 105,350 105,400 105,400 105,450 105,450 105,500 105,500 105,550 105,550 105,600 105,600 105,650 105,650 105,700 105,700 105,750 105,750 105,800 105,800 105,850 105,850 105,900 105,900 105,950 105,950 106,000 | 4,564 4,567 4,570 4,573 4,577 4,580 4,583 4,586 4,589 4,593 4,596 4,599 4,602 4,605 4,608 4,612 4,615 4,618 4,621 4,624 | 108,000 108,050 108,050 108,100 108,100 108,150 108,150 108,200 108,200 108,250 108,250 108,300 108,300 108,350 108,350 108,400 108,400 108,450 108,450 108,500 108,500 108,550 108,550 108,600 108,600 108,650 108,650 108,700 108,700 108,750 108,750 108,800 108,800 108,850 108,850 108,900 108,900 108,950 108,950 109,000 | 4,755 4,758 4,761 4,764 4,768 4,771 4,774 4,777 4,780 4,784 4,787 4,790 4,793 4,796 4,800 4,803 4,806 4,809 4,812 4,815 |
| 97,000 | 100,000 | 103,000 | 106,000 | 109,000 | |||||
| 97,000 97,050 97,050 97,100 97,100 97,150 97,150 97,200 97,200 97,250 97,250 97,300 97,300 97,350 97,350 97,400 97,400 97,450 97,450 97,500 97,500 97,550 97,550 97,600 97,600 97,650 97,650 97,700 97,700 97,750 97,750 97,800 97,800 97,850 97,850 97,900 97,900 97,950 97,950 98,000 | 4,054 4,057 4,061 4,064 4,067 4,070 4,073 4,077 4,080 4,083 4,086 4,089 4,092 4,096 4,099 4,102 4,105 4,108 4,112 4,115 | 100,000 100,050 100,050 100,100 100,100 100,150 100,150 100,200 100,200 100,250 100,250 100,300 100,300 100,350 100,350 100,400 100,400 100,450 100,450 100,500 100,500 100,550 100,550 100,600 100,600 100,650 100,650 100,700 100,700 100,750 100,750 100,800 100,800 100,850 100,850 100,900 100,900 100,950 100,950 101,000 | 4,245 4,249 4,252 4,255 4,258 4,261 4,264 4,268 4,271 4,274 4,277 4,280 4,284 4,287 4,290 4,293 4,296 4,299 4,303 4,306 | 103,000 103,050 103,050 103,100 103,100 103,150 103,150 103,200 103,200 103,250 103,250 103,300 103,300 103,350 103,350 103,400 103,400 103,450 103,450 103,500 103,500 103,550 103,550 103,600 103,600 103,650 103,650 103,700 103,700 103,750 103,750 103,800 103,800 103,850 103,850 103,900 103,900 103,950 103,950 104,000 | 4,436 4,440 4,443 4,446 4,449 4,452 4,456 4,459 4,462 4,465 4,468 4,471 4,475 4,478 4,481 4,484 4,487 4,491 4,494 4,497 | 106,000 106,050 106,050 106,100 106,100 106,150 106,150 106,200 106,200 106,250 106,250 106,300 106,300 106,350 106,350 106,400 106,400 106,450 106,450 106,500 106,500 106,550 106,550 106,600 106,600 106,650 106,650 106,700 106,700 106,750 106,750 106,800 106,800 106,850 106,850 106,900 106,900 106,950 106,950 107,000 | 4,628 4,631 4,634 4,637 4,640 4,643 4,647 4,650 4,653 4,656 4,659 4,663 4,666 4,669 4,672 4,675 4,679 4,682 4,685 4,688 | 109,000 109,050 109,050 109,100 109,100 109,150 109,150 109,200 109,200 109,250 109,250 109,300 109,300 109,350 109,350 109,400 109,400 109,450 109,450 109,500 109,500 109,550 109,550 109,600 109,600 109,650 109,650 109,700 109,700 109,750 109,750 109,800 109,800 109,850 109,850 109,900 109,900 109,950 109,950 110,000 | 4,819 4,822 4,825 4,828 4,831 4,835 4,838 4,841 4,844 4,847 4,850 4,854 4,857 4,860 4,863 4,866 4,870 4,873 4,876 4,879 |
# 2025 New Jersey Tax Rate Schedule
STEP 1 STEP 2 STEP 3
Enter Your Multiply Your Subtract Your Tax
# If Taxable Income (line 24) is: Line 24
Over But not over
$ 0 $ 20,000
$ 20,000 $ 35,000
$ 35,000 $ 40,000
$ 40,000 $ 75,000
$ 75,000 $ 500,000
$ 500,000 $ 1,000,000
$ 1,000,000 and over
Line 24 by:
_ .014 = - $ 0 = _
_ .0175 = - $ 70.00 = _
_ .035 = - $ 682.50 = _
_ .05525 = - $ 1,492.50 = _
_ .0637 = - $ 2,126.25 = _
_ .0897 = - $ 15,126.25 = _
_ .1075 = - $ 32,926.25 = _ TaxTalk is the portion of the Automated Tax Information Select the 3‑digit number of the topic you want to hear.
System (ATIS) that provides recorded information to call- Then, from a touch-tone phone, call 1 (800) 323-4400 ers on a variety of New Jersey tax topics and affords them (within NJ, NY, PA, DE, and MD) or (609) 826-4400. Have the opportunity to request written information on certain paper and pencil available to take notes. Additional topics topics. TaxTalk is available 24 hours a day, 7 days a week.
NJ INCOME TAX INFORMATION FOR
INDIVIDUALS
Filing Your New Jersey Return
100 Who Must File
101 Military Personnel Resident Defined & Income Tax Filing Requirements 102 Military Personnel Nonresident Defined & Income Tax Filing Requirements 103 How and When to File an Extension 104 Military Extensions 105 How and When to Amend 106 Penalties, Interest & Collection Fees 108 Who is Required to Make Estimated Tax Payments 110 Interest on Underpayment of Estimated Tax Payments 112 Pennsylvania Residents Working in New Jersey/New Jersey Residents Working in Pennsylvania 114 Nonresidents may become available after the printing of this booklet.
# TaxTalk — Topic Codes
115 Nonresidents Selling Real Property 134 New Jersey Earned Income Tax in New Jersey - Estimated Tax Credit Payment Requirements 135 Property Tax Deduction or Credit 116 Mailing Your Return With Refunds 136 Deductions or No Tax Due 138 Reporting Wages 118 Mailing Your Return With 140 Nontaxable Income Payments Due 142 Reporting Capital Gain Income 119 Mailing Your Property Tax Credit 143 Reporting a Gain From the Sale Application Only (Without NJ-1040 of a Principal Residence (Main Tax Returns) Home) 120 How to Pay 144 Reporting Net Profits From Your Business
Completing Your New Jersey Return
145 Reporting Distributive Share of 121 Social Security Number
# Partnership Income
122 Filing Status
146 Reporting Net Pro Rata Share of S 123 Civil Union Partners
# Corporation Income
124 Part-Year Residents
147 Use Tax Due on Out-of-State 128 Deceased Taxpayers Purchases 130 Personal Exemptions 148 Withholdings and Payments 131 Domestic Partnership Exemption 150 Claiming Credit for Income 132 Dependent Exemptions or Wage Tax Paid to Another 133 Dependents Attending Colleges
# Jurisdiction
Exemptions
152 Claiming Excess Unemployment and Disability
Pension and IRA Information
154 Pension Income
156 Pension Exclusion
157 Employer Post-Retirement Contributions to Section 403(b) Plan 158 IRA Distributions 160 Establishing Your Roth IRA 162 Qualified Distributions From a Roth IRA 164 Nonqualified Distributions From a Roth IRA
NJ PROPERTY TAX RELIEF
PROGRAMS
ANCHOR Benefit
228 General Information on the
ANCHOR Benefit
231 ANCHOR Benefit Amounts
233 How to Check the Status of Your
ANCHOR Benefit
Senior Freeze/Property Tax
Reimbursement
216 General Information on the
Senior Freeze/Property Tax
Reimbursement
218 Eligibility Requirements 220 How to Apply for a Senior Freeze/ Property Tax Reimbursement
Property Tax Deduction or Credit
224 General Information on the
Property Tax Deduction or Credit
Stay NJ Property Tax Credit Program
226 General information on the Stay NJ Property Tax Credit Program
PAPERLESS FILING PROGRAMS
Online Income Tax Filing and Federal/
State E-File
300 Online Income Tax Filing and Federal/State E-File
NJ TAX AND FEE INFORMATION
FOR BUSINESSES
Business Registration
400 Starting a Business in New Jersey 401 How to File Taxes and Fees by Phone or Online 402 Small Business Workshops 410 Ending Your Tax Registration in New Jersey Income Tax Withholding Information for Businesses 412 Reporting and Remitting NJ Income Tax Withheld 414 Reconciling Tax Withheld With Form NJ-W-3 416 Employee's Withholding Allowance Certificates, Forms W-4 and NJ-W-4 420 Withholding New Jersey Income Taxes 421 Withholding New Jersey Income Taxes for Contractor Services 422 Penalties, Interest & Collection Fees
Sales and Use Tax Information for
Businesses
424 Collecting Sales Tax
426 Use Tax
428 Annual Use Tax
429 New Jersey Sales and Use Tax EZ File Systems for Filing Forms ST-50/ST-51 430 Filing Forms ST-50/ST-51 432 Pay Your Taxes Electronically 434 Penalties, Interest & Collection Fees 442 Urban Enterprise Zone
Lease and Rental Information for
Businesses
444 Lease and Rental Transactions 448 Domestic Security Fee
Other Fees and Taxes
449 9-1-1 System and Emergency Response Fee 454 Domestic Security Fee 456 Hotel/Motel State Occupancy Fee and Municipal Occupancy Tax 458 Litter Control Fee 459 Motor Vehicle Tire Fee CORPORATIONS & PARTNERSHIPS
Corporations
501 Starting a Corporation
502 Filing Responsibilities
503 Consequences of Not Dissolving a Corporation 504 Tax Rates and Accounting Periods
Partnerships
508 Partnership Information
510 Partnership Filing Requirements 511 Prepayment of Partnership Filing Fee
INFORMATION FOR INDIVIDUALS
ON SALES & USE TAX AND STATE
FEES
General Information on Sales and Use
Tax for Individuals
600 General Information on Sales and Use Tax for Individuals
Out-of-State Purchases
602 Out-of-State Purchases
Taxability of Leases and Rentals
608 Taxability of Leases and Rentals
Other Fees and Taxes
609 9-1-1 System and Emergency Response Fee 610 Atlantic City Luxury Tax, Sales Tax, and Other Fees 612 Atlantic City Casino Hotel Parking Fee 614 Cape May County Tourism Tax and Assessment 618 Domestic Security Fee 620 Hotel/Motel State Occupancy Fee and Municipal Occupancy Tax 621 Motor Vehicle Tire Fee
OTHER NJ TAX INFORMATION
New Jersey Division of Taxation
Regional Offices
704 Fair Lawn Office
705 Freehold Office
706 Cranford Office
708 Galloway Office
712 Trenton Office
Identity Theft
726 Identity Theft
Income Tax Refund Information
713 How to Check the Status of Your Income Tax Refund
Other Ways to Contact the Division
714 Other Ways to Contact the Division Taxpayers' Bill of Rights 718 Taxpayers' Bill of Rights
CATCH Program/Citizens Against Tax
Cheats
720 CATCH Program
Inheritance and Estate Tax
722 Inheritance and Estate Tax
When You Need Information by phone…
Call our Automated Tax Information System
1 (800) 323-4400 or (609) 826-4400.
Touch-tone phones only.
- Listen to recorded tax information on many topics.
- Order certain forms and publications through our automated message system.
Contact our Customer Service Center
(609) 292-6400 — Speak directly to a representative for tax information and assistance. See website for hours of operation.
Deaf, Hard of Hearing, Deaf-Blind, Speech
Disability
Visit njrelay.com or call 711. online…
Visit the New Jersey Division of Taxation
Website
Many State tax forms and publications are available on our website: nj.gov/taxation You can also reach us by email with general State tax questions at: nj.taxation@treas.nj.gov Do not include confidential information such as Social Security or federal tax identification numbers, liability or payment amounts, dates of birth, or bank account numbers in your email.
Subscribe to NJ Tax E-News, the Division of
Taxation's online information service, at:
nj.gov/treasury/taxation/listservice.shtml in person…
Visit a New Jersey Division of Taxation
Regional Information Center
Regional Information Centers provide individual assistance at various locations throughout the State.
Call the Automated Tax Information System or visit our website for the address of the center nearest you.
# To Get Forms…
- Call New Jersey's Forms Request System at 1 (800) 323-4400 or (609) 826-4400. Touch-tone phones only.
- Visit our website at: nj.gov/treasury/taxation/prntgit.shtml
- Write to: NJ Division of Taxation
Taxpayer Forms Services
PO Box 269
Trenton NJ 08695-0269
# Who Can Help…
In addition to assistance provided by the Division, other free tax assistance is available for senior citizens, disabled, non-English speaking, and low-income people.
Trained volunteers in the VITA (Volunteer Income Tax Assistance) and TCE (Tax Counseling for the Elderly) programs are available to help prepare both federal and State returns at locations throughout New Jersey.
For the location nearest you, contact the Division's Customer Service Center at (609) 292-6400 or the Internal Revenue Service.
# Paperless Filing
You can use NJ E-File to file Form NJ-1041 for 2025 electronically. Use tax software you purchase, go to a tax preparation website, or have a tax preparer file the return for you.
Source: view the official PDF
The source document contains 1 figure (charts or worksheet graphics) not reproduced in this text version. See the official PDF above.
Nearby sections (18 sections)
- cbt-100 · Instructions for Form CBT-100 — Corporation Business Tax…
- cbt-100s · Instructions for Form CBT-100S — S Corporation Business Tax…
- cbt-100u · Instructions for Form CBT-100U — Combined Corporation…
- cbt-150 · Instructions for Form CBT-150 — Estimated Tax Voucher
- nj-1040 · Instructions for Form NJ-1040 — Resident Income Tax Return
- nj-1040es · Form NJ-1040-ES — Gross Income Tax Declaration of Estimated…
- nj-1040nr · Instructions for Form NJ-1040NR — Nonresident Income Tax…
- nj-1041 · Instructions for Form NJ-1041 — Income Tax Return for Estates…
- nj-1065 · Instructions for Form NJ-1065 — Partnership Return
- nj-1080c · Form NJ-1080-C — Nonresident Composite Income Tax Return
- nj-1080c-instructions · Instructions for Form NJ-1080-C — Nonresident…
- nj-cbt-1065 · Instructions for Form NJ-CBT-1065 — Partnership Return…
- nj-wt · Form NJ-WT — Gross Income Tax Instructions for Employers
- pte-200-t · Form PTE-200-T — BAIT Application for Extension of Time to…
- pte-k-1 · Schedule PTE-K-1 — Member's Share of Tax (BAIT)
- schedule-njk-1 · Schedule NJK-1 — Partner's Share of Income (form +…
- st-18b · Form ST-18B — Annual Business Use Tax Return & Instructions
- su-4 · Publication S&U-4 — New Jersey Sales Tax Guide