New Jersey Division of Taxation Form Instructions
Instructions for Form CBT-150 — Estimated Tax Voucher
CBT-150 2026
# Who Must File
Taxpayers whose prior year tax liability is greater than $1,500 must make four 25% estimated tax payments in the fourth, sixth, ninth, and 12th months of its accounting period towards the current year's tax, except for taxpayers with gross receipts of $50 million or more for the prior privilege period must make installment payments as follows: 25% in the 4th month, 50% in the 6th month, and 25% in the 12th month. A taxpayer whose prior year tax liability is $1,500 from CBT-100, CBT-100U, or CBT-100S, may, in lieu of making these estimated tax payments, make a single estimated tax payment of 50% of the prior year's tax liability. This option must be made and the 50% payment must be remitted no later than the original due date of the prior year's tax return.
# Electronic Filing Mandate
All taxpayers and tax preparers must file Corporation Business Tax returns and make payments electronically.
This mandate includes all estimated payments. Visit the Division's website or check with your software provider to see if they support these filings.
# How to Determine Your Estimated Tax
Computation of the estimated tax must be made on the basis of a full accounting period. Taxpayers determine their expected liabilities on the basis of circumstances existing at the time prescribed for filing. Use the estimated tax worksheet on page 3 or 4, whichever is applicable, for computing each installment due.
# Estimated Tax Worksheet
A worksheet is provided to assist in computing the amounts of installment payments due for any taxpayer required to file a statement.
# CBT-100U, or CBT-100S
If the prior year's return is overpaid and the taxpayer elected to apply that overpayment as a credit to the current tax year, take credit for that amount when calculating the estimated payments. However, if the taxpayer elected to have any portion or all of the overpayment on the prior year's return refunded, this amount cannot be claimed as a credit.
# Calendar Year and Fiscal Year Taxpayers
All taxpayers should enter the appropriate tax year to which the remittance should be credited. Fiscal year taxpayers must also enter the beginning and ending dates of their accounting period.
# Underpayment of Estimated Tax
Any taxpayer who is required to file a statement of estimated tax must file each estimate together with remittance covering the estimated tax due on the required due date. Failure to remit such estimated payment or making an underpayment of such tax or any installment thereof, will result in the imposition of interest at an annual rate of 3% above the average predominant prime rate for each month or part of a month that the underpayment exists. The average predominant prime rate to be used is the rate as determined by the Board of Governors of the Federal Reserve System, quoted by commercial banks to large businesses on December 1st of the calendar year immediately preceding the calendar year in which the payment was due or as redetermined by the Director in accordance with N.J.S.A. 54:48-2. The interest rates assessed by the Division of Taxation are published on the Division's website.
In general, a taxpayer will be considered as having underpaid if the total amount of the estimated tax payments for the tax year are less than 90% of the total tax liability reported on the current year's tax return and less than 100% of the total tax liability reported on the prior year's tax return. The addition to the tax on any underpayment of any installment payment is computed on form CBT-160-A or CBT-160-B, whichever is applicable, and must be paid with the return.
# When to File
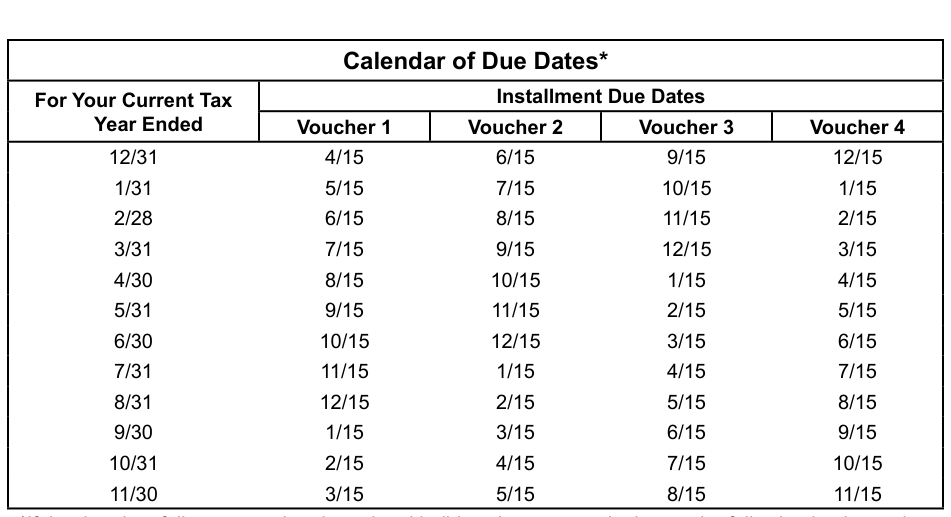
The appropriate estimated tax payment due dates for both calendar and fiscal year taxpayers can be found in the Calendar of Due Dates on page 2.
# How to Pay
You must pay your New Jersey estimated Corporation Business Tax electronically by e-check, electronic funds transfer (EFT), or credit card. Go to the Division of Taxation's website. Taxpayers that do not have access to the internet can call the Division's Customer Service Center at (609) 292-6400.
If you are not currently enrolled in the Electronic Funds Transfer program with the Division of Revenue and Enterprise Services, visit their website.
# Calendar of Due Dates*
Text version of this table
Calendar of Due Dates* For Your Current Tax Year Ended Installment Due Dates Voucher 1 Voucher 2 Voucher 3 Voucher 4 12/31 4/15 6/15 9/15 12/15 1/31 5/15 7/15 10/15 1/15 2/28 6/15 8/15 11/15 2/15 3/31 7/15 9/15 12/15 3/15 4/30 8/15 10/15 1/15 4/15 5/31 9/15 11/15 2/15 5/15 6/30 10/15 12/15 3/15 6/15 7/31 11/15 1/15 4/15 7/15 8/31 12/15 2/15 5/15 8/15 9/30 1/15 3/15 6/15 9/15 10/31 2/15 4/15 7/15 10/15 11/30 3/15 5/15 8/15 11/15
*If the due date falls on a weekend or a legal holiday, the payment is due on the following business day.
Amount of Installments Due. For taxpayers with gross receipts less than $50 million in the prior privilege period, a 25% installment payment of the current accounting year's estimated tax liability must be submitted with each of the four vouchers on or before the 15th day of the fourth, sixth, ninth, and 12th months of that year. Taxpayers with gross receipts of $50 million or more for the prior privilege period must pay a 25% installment in the fourth month, a 50% installment in the sixth month, and a 25% installment in the 12th month. If any due date prescribed for filing these installment vouchers falls on a Saturday, Sunday, or a legal holiday recognized by the State of New Jersey, the next succeeding business day will be considered the due date.
# Less Than $50,000,000 in the Prior Privilege Period
(Keep for your records - DO NOT FILE) 1.
2.
3.
4.
5.
Total estimated tax for the current year … 1.
Voucher 1 due (enter 25% of line 1) … 2.
Voucher 2 due (enter 25% of line 1) … 3.
Voucher 3 due (enter 25% of line 1) … 4.
Voucher 4 due (enter 25% of line 1) … 5.
Record of Estimated Tax Payments Voucher Number (a) Date (b) Amount (c) Overpayment Credit From Last Year's Return (d) Total Amount Paid and Credited For This Installment (Add (b) and (c))
Total
Amended Computation (Use if your estimated tax changes after you have filed one or more estimated tax vouchers.)
- Enter the amended estimated tax …
- Less (a) Amount of overpayment credit from last year's return (see instructions) …
(b) Previous estimated tax payment(s) made this year:
From Voucher 1 …
From Voucher 2 …
From Voucher 3 …
(c) Total lines 2a and 2b …
- Unpaid balance (subtract line 2c from line 1) …
- Unpaid balance to be paid as follows:
(a) On Voucher 2 if unused - 50% of amended estimated tax (line 1) less payments made (line 2c) …
(b) On Voucher 3 if unused - 75% of amended estimated tax (line 1) less payments made …
(c) On Voucher 4 - 100% of amended estimated tax (line 1) less payments made …
(d) Total of lines 4a, 4b, and 4c …
- Subtract line 4d from line 3. (If result is not zero, review calculations) …
Estimated Tax Worksheet for Taxpayers With Gross Receipts of $50,000,000 or More in the Prior Privilege Period (Keep for your records - DO NOT FILE) 1.
2.
3.
4.
Total estimated tax for the current year … 1.
Voucher 1 due (enter 25% of line 1) … 2.
Voucher 2 due (enter 50% of line 1) … 3.
Voucher 4 due (enter 25% of line 1) … 4.
Record of Estimated Tax Payments Voucher Number (a) Date (b) Amount (c) Overpayment Credit From Last Year's Return (d) Total Amount Paid and Credited For This Installment (Add (b) and (c))
Total
Amended Computation (Use if your estimated tax changes after you have filed one or more estimated tax vouchers.)
- Enter the amended estimated tax …
- Less (a) Amount of overpayment credit from last year's return (see instructions) …
(b) Previous estimated tax payment(s) made this year:
From Voucher 1 …
From Voucher 2 …
(c) Total lines 2a and 2b …
- Unpaid balance (subtract line 2c from line 1) …
- Unpaid balance to be paid as follows:
(a) On Voucher 2 if unused - 75% of amended estimated tax (line 1) less payments made (line 2c) …
(b) On Voucher 4 - 100% of amended estimated tax (line 1) less payments made …
(c) Total of lines 4a and 4b …
- Subtract line 4c from line 3. (If result is not zero, review calculations) …
Source: view the official PDF
Nearby sections (16 sections)
- cbt-100 · Instructions for Form CBT-100 — Corporation Business Tax…
- cbt-100s · Instructions for Form CBT-100S — S Corporation Business Tax…
- cbt-100u · Instructions for Form CBT-100U — Combined Corporation…
- cbt-150 · Instructions for Form CBT-150 — Estimated Tax Voucher
- nj-1040 · Instructions for Form NJ-1040 — Resident Income Tax Return
- nj-1040es · Form NJ-1040-ES — Gross Income Tax Declaration of Estimated…
- nj-1040nr · Instructions for Form NJ-1040NR — Nonresident Income Tax…
- nj-1041 · Instructions for Form NJ-1041 — Income Tax Return for Estates…
- nj-1065 · Instructions for Form NJ-1065 — Partnership Return
- nj-1080c · Form NJ-1080-C — Nonresident Composite Income Tax Return
- nj-1080c-instructions · Instructions for Form NJ-1080-C — Nonresident…
- nj-cbt-1065 · Instructions for Form NJ-CBT-1065 — Partnership Return…
- nj-wt · Form NJ-WT — Gross Income Tax Instructions for Employers
- pte-200-t · Form PTE-200-T — BAIT Application for Extension of Time to…
- pte-k-1 · Schedule PTE-K-1 — Member's Share of Tax (BAIT)
- schedule-njk-1 · Schedule NJK-1 — Partner's Share of Income (form +…