New Jersey Division of Taxation Form Instructions
Instructions for Form NJ-1040NR — Nonresident Income Tax Return
# Table of Contents
Who Must File … 2
Extension of Time to File … 3
Taxpayer Identification … 4
Part-Year Nonresidents … 4
Filing Status … 4
Exemptions … 5
Dependents' Information … 6
Digital Assets … 6
Income … 6
Schedule NJ-BUS-1 — Business Income Summary … 16
Retirement/Pension Exclusion and Other Retirement Income Exclusion … 19
Deductions … 23
Calculating Your Tax Liability … 25
Credits/Payments … 25
Estimated Tax … 26
Charitable Contributions … 28
Part I — Disposition of Property … 29
Part II — Allocation of Wage and Salary Income … 30
Part III — Allocation of Business Income to New Jersey … 30
How to Pay … 31
Penalties, Interest, and Collection Fees … 31
Where to Mail Your Return … 32
Military Personnel … 32
Pennsylvania Residents … 32
Tax Table … 35
Tax Rate Schedules … 44
Information, Forms, and Assistance … 45
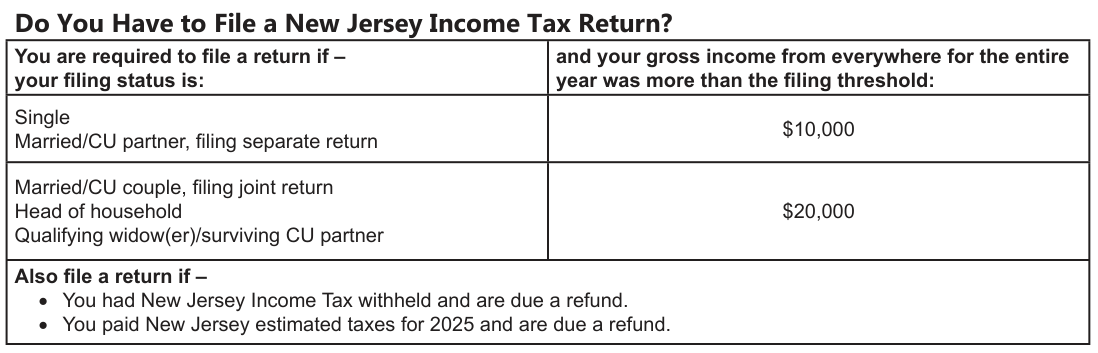
# Do You Have to File a New Jersey Income Tax Return?
You are required to file a return if -
Text version of this table
| You are required to file a return if – your filing status is: | and your gross income from everywhere for the entire year was more than the filing threshold: |
|---|---|
| Single Married/CU partner, filing separate return | $10,000 |
| Married/CU couple, filing joint return Head of household Qualifying widow(er)/surviving CU partner | $20,000 |
| Also file a return if – • You had New Jersey Income Tax withheld and are due a refund. • You paid New Jersey estimated taxes for 2025 and are due a refund. |
# Which Form to File
Military personnel and their spouses/civil union partners, see page 32.
Yes
Was New Jersey your domicile (see definition on page 3) for any part of the year?
No
No
Did you maintain a permanent* home
Yes in New Jersey for any part of the year?
Did you maintain a permanent* Yes home in New Jersey?
File Form NJ-1040
Part-year residents: If New Jersey
No was your domicile for only part of the year and you received income
No
Did you maintain a permanent from New Jersey sources while home outside New Jersey? you were a nonresident, also file Yes Yes Did you spend more than 30 days in New Jersey?
No
File Form NJ-1040NR if you had income from New Jersey sources.
No
File Form NJ-1040
Part-year residents: If you had a permanent home in New Jersey for only
Yes
Did you spend more than 183 part of the year and you received days in New Jersey? income from New Jersey sources while you were a nonresident, also file NJ-1040NR.
- A home is not permanent if it is maintained only for a temporary period to accomplish a particular purpose (e.g., temporary job assignment). A home used only for vacations is not a permanent home.
New Jersey Residents Working/Living Abroad. Use the chart above to determine if you are considered a New Jersey resident for tax purposes. New Jersey residents working or living abroad have the same filing and payment requirements as residents living in New Jersey.
Part-Year Residents. There is no part-year resident return. You may have to file both Form NJ-1040 to report income you received for the part of the year you were a resident and Form NJ-1040NR if you had income from New Jersey sources for the part of the year you were a nonresident.
# Your 2025 NJ-1040NR
Check the following items to avoid mistakes that delay returns and refunds.
# When to File
In general, your New Jersey Income Tax return is due when your federal income tax return is due. If you are a calendar year filer, your 2025 New Jersey Income Tax return is due by April 15, 2026. If you are a fiscal year filer, you must file your return by the 15th day of the fourth month following the close of the fiscal year.
Postmark Date
All New Jersey Income Tax returns postmarked on or before the due date of the return are considered filed on time. Tax returns postmarked after the due date are considered filed late. If the postmark date on your return is after the due date, the filing date for that return is the date we received your return, not the postmark date.
# Extension of Time to File
There is no extension of time to pay your tax due
- only to file. Penalties and interest will be charged if you pay your tax after April 15, 2026. (Military personnel and civilians providing support to the Armed Forces, see page 32.) You can receive a six-month extension of time to file if you pay at least 80% of your tax liability (line 42) through withholdings, estimated payments, or other payments by the original due date, and
- You enclose a copy of your federal Application for
Automatic Extension, if filed by paper, and check the box at the top of your NJ-1040NR (or enter your confirmation number in the space provided if you filed the extension application online or by phone); or
- You file Form NJ-630, Application for Extension of
Time to File New Jersey Gross Income Tax Return, by April 15, 2026. You can also file an extension application online until 11:59 p.m., April 15, 2026.
If you do not meet the requirements for an extension, or you do not file your return by the extended due date, we will deny your extension request and charge penalties and interest from the original due date of the return. (See "Penalties, Interest, and Collection Fees" on page 31.) You will not receive an approved copy of your extension request. We will notify you only if we deny your request, but not until after you actually file your return.
# Filling Out the Form Properly
- Use only a 2025 return for the 2025 Tax Year.
- Use only blue or black ink.
- Enter last name first on the return. This is different from the federal return.
- Use "State Wages" from box 16 of your W-2, not federal wages (box 1).
- Do not use dollar signs or dashes.
- Do not report a loss on Form NJ-1040NR (see page 6).
- To request a refund, you must enter an amount on line 64.
# Rounding
Instead of making dollars-and-cents entries on your return, you can round and use whole dollar amounts. If you round, do so for all lines, and enter "00" after the decimal for cents.
Round amounts of 50 cents or more up to the next whole dollar. For example, $26.78 becomes $27.00.
Round amounts of less than 50 cents down to the next whole dollar. For example, $13.45 becomes $13.00.
Round the total, not the amounts used to calculate the total. For example, the sum of $13.45 and $46.24 is $59.69, which becomes $60.00.
# Terms to Know
Domicile. A domicile is the place you consider your permanent home - the place where you intend to return after a period of absence (e.g., vacation, business assignment, educational leave). You have only one domicile, although you may have more than one place to live.
Your domicile does not change until you move to a new location with the intent to establish your permanent home there and to abandon your New Jersey domicile. Moving to a new location, even for a long time, does not change your domicile if you intend to return to New Jersey. Your home, whether inside or outside New Jersey, is not permanent if you maintain it only for a temporary period to accomplish a particular purpose (e.g., temporary job assignment). For more information, see publication GIT-6, Part-Year Residents and Nonresidents.
Spouse/Civil Union Partner. The term spouse also refers to a spouse who entered into a valid same-sex marriage in another state or foreign nation and a partner in a civil union (CU) recognized under New Jersey law.
# Name and Address
Print or type your name (last name first), complete address, and ZIP Code in the spaces provided. If you are filing jointly, include your spouse's name. Your refund and next year's form will be sent to the address you provide.
Change of Address. Check the "Change of Address" box if your address has changed since you last filed a New Jersey return.
Foreign Address. Check the box if your mailing address is outside the United States.
# State of Residency
Indicate the place outside New Jersey where you lived for the period covered by this return.
# NJ Residency Status
If you were a New Jersey resident for any part of the year, list the month, day, and year in the tax year your residency began and the month, day, and year in the tax year it ended. For example, if you moved to New Jersey August 4, 2025, enter 8/4/25 to 12/31/25.
You must file a nonresident return if you received income from a New Jersey source while you were a nonresident and your income for the entire year (not just your period of nonresidency) was more than the filing threshold for your filing status (see page 2). Only report income you earned while a nonresident of New Jersey.
You must prorate exemptions, deductions, credits, and the pension/retirement and other retirement income exclusions based on the number of months you were a nonresident. For this calculation, 15 days or more is considered a month. If you received income while you were a resident of New Jersey, you also may need to file a New Jersey resident return, Form NJ-1040.
Lines 1-5 - Filing Status
In general, you must use the same filing status as you do for federal purposes. Fill in only one box.
Single. Your filing status is single if you were not married or a partner in a civil union on the last day of the tax year, and you do not qualify to file as head of household or qualifying widow(er)/surviving CU partner.
Married/Civil Union Couples. If both you and your spouse were nonresidents for the entire tax year, and only one of you had income from New Jersey sources, that spouse can file a separate New Jersey return even if a joint federal return was filed. The spouse with income from New Jersey sources calculates income and exemptions as if a federal married, filing separate return had been filed. You have the option of filing a joint return, but in that case, your joint income would be reported in column A of Form NJ-1040NR.
If one spouse was a nonresident during the entire tax year and the other spouse was a resident during any part of the tax year, and both had income from New Jersey sources, they can file separate New Jersey returns (the nonresident files a nonresident return and the resident files a resident return). Each calculates income and exemptions as if a federal married, filing separate return had been filed. You have the option of filing a joint resident return, but in that case, your joint income would be taxed as if you both were residents.
If you are filing separately, enter your spouse's Social
Security number in the space provided under line 3.
Note: You can file jointly or separately only if you were married or a partner in a civil union on the last day of the tax year. Members of a domestic partnership cannot use the joint or separate filing statuses unless they entered into a legally sanctioned same-sex relationship outside New Jersey.
Head of Household. You can use this filing status if you meet the requirements to file as head of household for federal purposes. For more information, visit the IRS website.
Qualifying Widow(er)/Surviving CU Partner. You can use this filing status if your spouse died in 2023 or 2024 and you meet the requirements to file as Qualifying Surviving Spouse for federal purposes. For more information, visit the IRS website.
Civil Unions. Partners in a civil union must file their New
Jersey Income Tax returns using the same filing statuses as spouses under New Jersey Gross Income Tax Law. If you are a partner in a civil union, your New Jersey filing status may not match your federal filing status.
For more information, see GIT-4, Filing Status.
# Exemptions
Line 6 - Regular Exemptions
You can claim a $1,000 exemption for yourself and your spouse/CU partner (if filing a joint return) or your domestic partner. Check each box that applies. The box for "Yourself" is already checked. Add the number of boxes checked and enter the total in the box on line 6.
Note: The domestic partnership must be registered in
New Jersey by the last day of the tax year. You can only claim your domestic partner if they do not file a New Jersey return. You must enclose a copy of your Certificate of Domestic Partnership the first time you claim the exemption.
Line 7 - Age 65 or Older
You can claim an exemption if you were 65 or older on the last day of the tax year (born in 1960 or earlier). If you are filing jointly, your spouse also can take an exemption if they were 65 or older on the last day of the tax year. You cannot claim this exemption for your domestic partner or dependents. Check each box that applies. Add the number of boxes checked and enter the total in the box on line 7.
You must enclose proof of age such as a copy of a birth certificate, driver's license, or church records the first time you claim the exemption(s).
Line 8 - Blind or Disabled
You can claim an exemption if you were blind or disabled on the last day of the tax year. If you are filing jointly, your spouse also can take an exemption if they were blind or disabled on the last day of the tax year. You cannot claim this exemption for your domestic partner or dependents. Check each box that applies. Add the number of boxes checked and enter the total in the box on line 8.
You must enclose a copy of the doctor's certificate or other medical records evidencing legal blindness or total and permanent disability the first time you claim the exemption(s).
Line 9 - Veteran Exemptions
You can claim this exemption if you are a military veteran who was honorably discharged or released under honorable circumstances from active duty any time before the last day of the tax year. If you are filing jointly, your spouse can also take this exemption if they are a military veteran who meets the requirements. You cannot claim this exemption for your domestic partner or dependents. Add the number of boxes checked and enter the total in the box on line 9.
You must provide official documentation showing that you were honorably discharged or released under honorable circumstances from active duty the first time you claim the exemption(s). Your documentation must list your character of service (discharge).
A list of acceptable documentation and ways to submit it is available on our website.
Line 10 - Qualified Dependent Children
You can claim an exemption for each child who qualifies as your dependent for federal tax purposes. Enter the number of your dependent children on line 10.
Line 11 - Other Dependents
You can claim an exemption for each other dependent who qualifies as your dependent for federal tax purposes. Enter the number of your other dependents on line 11.
Line 12 - Dependents Attending College
You can claim an additional exemption for each dependent student if all the requirements below are met. You cannot claim this exemption for yourself, your spouse, or your domestic partner.
- Student must be claimed as a dependent on line 10 or 11.
- Student must be under age 22 on the last day of the tax year (born 2004 or later).
- Student must attend full-time. Full-time is determined by the school.
- Student must spend at least some part of each of five calendar months of the tax year at school.
- The educational institution must be an accredited college or post-secondary school, maintain a regular faculty and curriculum, and have a body of students in attendance.
- You must have paid one-half or more of the tuition and maintenance costs for the student. Financial aid received by the student is not calculated into your cost when totaling one-half of your dependent's tuition and maintenance. However, the money earned by students in college work study programs is income and is taken into account.
Enter the number of exemptions for your qualified dependents attending colleges on line 12.
Line 13a-13c - Totals
Add lines 6, 7, 8, and 12 and enter the total on line 13a.
Add lines 10 and 11 and enter that total on line 13b.
Enter the amount from line 9 on line 13c.
Line 14 - Dependent Information
Enter the full name, Social Security number, and birth year for each dependent child or other dependent you claimed on line 10 or 11.
Enter the same Social Security number, individual taxpayer identification number (ITIN), or adoption taxpayer identification number (ATIN) for each dependent that you entered on your federal return. If you do not provide a valid Social Security number, ITIN, or ATIN for a dependent, the exemption will be denied.
If you have more than four dependents, enter the information for your first four dependents on the lines provided. Enclose a statement listing the information for your additional dependents.
# Gubernatorial Elections Fund
If you would like to designate $1 to help candidates for
Governor pay campaign expenses, check the "Yes" box.
If you are filing a joint return, your spouse can also designate $1 to this fund. Checking the "Yes" box will not reduce your refund or increase the amount you owe.
For more information on the Gubernatorial Public Financing Program, contact the New Jersey Election Law Enforcement Commission at 609-292-8700 or online.
# Digital Assets
are any digital representations of value that are recorded on a cryptographically secured, distributed ledger or any similar technology. Digital assets include, but are not limited to, non-fungible tokens (NFTs) and virtual currencies, such as cryptocurrencies and stablecoins. If an asset has the characteristics of a digital asset, it is treated as a digital asset for Gross Income Tax purposes.
If you (or your spouse, if filing jointly) either received (as a reward, award, or payment for property or services) or sold, exchanged, or otherwise disposed of a digital asset, or any financial interest in any digital asset, check the "Yes" box. Otherwise, check the "No" box. If you answer yes, you must report the income in the appropriate category of income.
If you disposed of any digital asset that you held as a capital asset, through a sale, trade, exchange, payment, or other transfer, use Part I to calculate the amount to report on line 19.
If you received any digital asset(s) as compensation for services, report the income as you would report other wage income. If you disposed of any digital asset(s) that you held for sale to customers in the ordinary course of a trade or business, report the income as you would report other business income.
If you received income in connection with digital assets that is not reported elsewhere on your return, include the amounts on line 26.
# Driver's License Number
Enter your Driver's License or state Non-Driver Identification Card number including the two-letter abbreviation of the issuing state. Providing this information is voluntary. We may use this information to validate your identity in our effort to combat identity theft and fraudulent filing.
# Income Lines 15-27
Gross income means all income you received in the form of money, goods, property, and services unless specifically exempt by law.
In column A, you must report income from everywhere, whether from inside or outside New Jersey (worldwide), that would be taxable if you were a New Jersey resident.
If you are filing a joint return, report the income of both spouses in column A, even if only one had income from New Jersey.
In column B, enter your income from New Jersey sources. For every entry in column A, there must be an entry on that line in column B. If none of your income is from New Jersey sources, enter "0" in column B. Your final tax liability is based on the percentage of your income that is from New Jersey sources.
Report all income on the proper lines. For example, do not enter pension income on the wage line.
Accounting Method. Use the same accounting method for New Jersey Income Tax that you used for federal income tax purposes. Income must be recognized and reported in the same period as it is recognized and reported for federal purposes.
Reporting Losses. If you have a net loss in any category of income, remember the following:
- You cannot report a loss on your NJ-1040NR (e.g., in parentheses or as a negative number);
- You can net losses with gains in the same category of income. For example, you can subtract gambling losses from gambling winnings during the tax year;
- You cannot apply a net loss in one category of income against income or gains in a different category on your NJ-1040NR. For example, you cannot subtract gambling losses from your wages;
- If you have a net loss in any income category, make no entry on that line of your NJ-1040NR. Do not enter zero. Do not enter the amount of the loss in parentheses or as a negative number;
- No carryback or carryover of losses is allowed when reporting income on your NJ-1040NR.
# Examples of Taxable Income
New Jersey taxable income includes:
- Wages and other compensation;
- Interest and dividends (including interest paid on income tax refunds);
- Earnings on nonqualified distributions from (1) qualified tuition program accounts or (2) qualified state
# 529A Achieving a Better Life Experience program
(ABLE) accounts;
- Earnings on nonqualified distributions from
NJBEST accounts, and any portion of the distributions that are attributable to contributions previously deducted on a New Jersey Income Tax return;
- Net profits from business, trade, or profession;
- Net gains or income from sale or disposition of property;
- Pensions, annuities, and IRA withdrawals;
- Net distributive share of partnership income;
- Net pro rata share of S corporation income;
- Net rental, royalty, and copyright income;
- Net gambling winnings, including New Jersey Lottery winnings from prize amounts over $10,000;
- Alimony;
- Estate and trust income;
- Income in respect of a decedent;
- Prizes and awards, including scholarships and fellowships (unless they satisfy the conditions on page 19);
- Value of residence provided by employer;
- Fees for services rendered, including jury duty.
New Jersey taxable income also includes the following that are not subject to federal income tax:
- Interest from obligations of states and their political subdivisions, other than New Jersey and its political subdivisions;
- Income earned by a resident from foreign employment;
- Certain contributions to pensions and tax-deferred annuities;
- Employee contributions to federal Thrift Savings
Funds, 403(b), 457, SEP, or any other type of retirement plan other than 401(k) Plans.
# Examples of Exempt (Nonreportable) Income
Do not include the following income when determining if you must file a return. These items should not appear anywhere on your nonresident return.
- Federal Social Security
- Railroad Retirement (Tier 1 and Tier 2)
- United States military pensions and survivor's benefit payments
- Life insurance proceeds received because of a person's death
- Employee's death benefits
- Permanent and total disability, including VA benefits
- Temporary disability received from the State of New
Jersey or as third-party sick pay
- Workers' Compensation
- Election worker compensation
- Gifts and inheritances
- Qualifying scholarships or fellowship grants
- New Jersey Lottery winnings from prizes in the amount of $10,000 or less
- Unemployment Compensation received from the state (but not supplemental unemployment benefit payments)
- Family Leave Insurance (FLI) benefits
- Interest and capital gains from (1) obligations of the
State of New Jersey or any of its political subdivisions; or (2) direct federal obligations exempt under law, such as U.S. Savings Bonds and Treasury
# Bills, Notes, and Bonds
- Distributions paid by mutual funds to the extent the distributions are attributable to interest earned on federal obligations
- Certain distributions from New Jersey qualified investment funds
- Earnings on qualified distributions from (1) qualified tuition program accounts or (2) qualified state 529A Achieving a Better Life Experience program (ABLE) accounts
- Qualified distributions from NJBEST accounts
- Employer and employee contributions to 401(k)
Plans up to the federal limit (but not federal Thrift
# Savings Funds)
- Some benefits received from certain employerprovided cafeteria plans (but not salary reduction or premium conversion plans). See Technical Bulletin TB-39.
- Benefits received from certain employer-provided commuter transportation benefit plans (but not salary reduction plans). See Technical Bulletin TB-24(R).
- Contributions to and distributions from Archer
MSAs if they are excluded for federal income tax purposes
- Direct payments and benefits received under homeless persons assistance programs
- Income Tax refunds (New Jersey, federal, and other jurisdictions) but not interest paid on the refunds
- Paycheck Protection Program (PPP) loan amounts forgiven through the federal CARES Act or federal
# Paycheck Protection Program
- Economic Impact Payments (stimulus payments)
- Welfare
- Child support
- Amounts paid as reparations or restitution to Nazi
Holocaust victims
- Assistance from a charitable organization, whether in the form of cash or property
- Cancellation of debt
- Amounts received as damages for wrongful imprisonment
- Qualified disaster relief payments excluded under
IRC §139
- Payments from the September 11th Victim Compensation Fund
- Difficulty of Care payments that are excluded from federal taxable income
Line 15 - Wages, Salaries, Tips, etc.
# Column A
Enter the total of State wages, salaries, tips, bonuses, commissions, etc., from all employment both inside and outside New Jersey. Take the amount from box 16 of your W-2 (see sample below). Include all payments whether in cash, benefits, digital assets, or property.
If you were employed outside New Jersey, you may need to adjust your wages to reflect New Jersey tax law. For example, if you had a Section 125 cafeteria plan that is taxable for New Jersey purposes but is not included in box 16 of your W-2, you must add that amount back into your State wages.
Nonresident servicepersons, see page 32.
Retirement Plans. Under New Jersey law, contributions to retirement plans (other than 401(k) Plans) are included in State wages on the W-2 in the year the wages are earned. This may cause your State wages (box 16) to be higher than your federal wages (box 1).
Meals and/or Lodging. You can exclude meals and/or lodging reported as wages on your W-2 if:
- The meals and/or lodging were provided on the business premises of your employer; and
Sample W-2 (This form is for illustration only and is not reproducible.) a Employee's social security number 2 2 2 2 2 Void b Employer identification number (EIN) c Employer's name, address, and ZIP code d Control Number e Employee's first name and initial Last name f Employee's address and ZIP code
For Official Use Only
# OMB No. 1545-0008
1 Wages, tips, other compensation 2 Federal income tax withheld
Social security wages
3 4 Social security tax withheld
Medicare wages and tips
5 6 Medicare tax withheld
Social security tips
7 8 Allocated tips
9 10 Dependent care benefits
11 Nonqualified plans 12a See instructions for box 12
13 Statutory 12b
Retirement Third-party employee plan sick pay
14 12c
Other
UI/WF/SWF - $184.02
DI - $380.42
12d
DI P.P. #(Private Plan No.)
18 Local wages, tips, etc. 19 Local income tax
17 State income tax
15 State Employer's state ID number 16 State wages, tips, etc.
NJ 234-567-890/000 142,900.00
FLI P.P. #
FLI P.P. # (Private Plan No.)
(Private Plan No.)
Wage and Tax
# Form W-2 Statement
20 Locality name
6977.00
545.82 - FLI
545.82 - FLI
Department of the Treasury—Internal Revenue Service
# For Privacy Act and Paperwork Reduction
Act Notice, see the separate instructions.
- The meals and/or lodging were provided for the convenience of your employer; and
For lodging only:
- You were required to accept the lodging as a condition of your employment.
If you exclude the value of meals and/or lodging from your wages, you must enclose a signed statement explaining how you met these conditions. If you do not enclose the statement, your wages will be changed back to the full amount shown on your W-2.
New Jersey State Police officers cannot exclude food and maintenance payments received as part of their union contract. These payments do not meet the criteria above.
Employee Business Expenses. Employee business expenses are not deductible for New Jersey tax purposes.
However, you can exclude reimbursements for employee business expenses reported as wages on your W-2 if:
- The reimbursements are for job-related expenses;
- You are required to and do account for these expenses to your employer; and
- You are reimbursed by your employer in the exact amount of the allowable expenses.
If you received excludable reimbursements for employee business expenses that were included in wages on your W-2, enclose a statement explaining the amount you are excluding and your reasons. Also, enclose a copy of your federal Form 2106.
Federal Statutory Employees. If you are considered a "statutory employee" for federal tax purposes, you cannot deduct your business expenses unless you are self-employed or an independent contractor under New Jersey law. The federal label of "statutory employee" has no meaning for New Jersey tax purposes. Business expenses can only be deducted from the business income of a self-employed individual. See the instructions for Schedule NJ-BUS-1, Part I (Net Profits From Business) on page 16.
Moving Expenses. Moving expenses are not deductible for New Jersey Income Tax purposes.
You can, however, exclude reimbursements for the following moving expenses if you met the federal requirements to claim moving expenses that were in effect on December 31, 2017, and the expenses were included in wages on your W-2:
- The cost of moving your household goods and personal effects from the old home to the new home.
- The actual expenses you incurred for traveling, meals, and lodging when moving yourself and your family from your old home to your new home.
Reimbursements for any other moving expense cannot be excluded from income.
If you received excludable reimbursements for moving expenses that were included in wages on your W-2, enclose a statement explaining the amount you are excluding and your reasons.
Compensation for Injuries or Sickness. Certain amounts received for personal injuries or sickness are not subject to tax. You can exclude such amounts included as wages on your W-2 if:
- The payments were compensation for wage loss that resulted from absence due to your injury or sickness; and
- The payments were due and payable under an enforceable contractual obligation under the plan; and
- The payments were not related to sick leave wage continuation, which is largely discretionary and payments are made regardless of the reason for absence from work.
If such payments are included in wages on your W‑2, enclose Form NJ‑2440.
You must enclose all W-2s with your tax return. Do not attach them to your return.
# Column B
Enter the portion of your wages, salaries, etc., that comes from New Jersey sources. If zero, enter "0."
Pennsylvania residents, see page 33. Nonresident servicepersons and nonmilitary spouses of military personnel, see page 32.
If you had wage/salary income earned partly inside and partly outside New Jersey, and you cannot easily determine the amount of income from New Jersey, see Part II on page 30.
New Jersey imposes a convenience of the employer test for residents of states that impose a similar test. Under the convenience rule, a nonresident's wage/salary income from a New Jersey employer is taxable to New Jersey if they are working from an out-of-State location for their own convenience and not for the necessity of the employer. In this case, you must report the full amount of the wage/ salary income in column B. Do not complete Part II. More information is available on our website.
Check the box at line 15 if you complete lines 69-75
(Part II, Allocation of Wage and Salary Income Earned
Partly Inside and Outside New Jersey).
Do not use Part II if your wage/salary income is based on volume (the amount of sales or amount of business transacted). Instead, use the following formula:
NJ Vol.
# Vol. Income = line 15, col. B
Total Vol.
The location where the services or sales were actually performed is the deciding factor when determining where the business was transacted. Enclose an explanation of how you calculated the amount of wage/salary income.
Part-Year Nonresidents. Enter in column A the portion of your wages earned while you were a nonresident. Include wages from sources both inside and outside New Jersey.
Column B. Enter in column B the portion of your wages from New Jersey sources earned while you were a nonresident (unless you were a Pennsylvania resident).
Line 16 - Taxable Interest Income
# Column A
Enter all of your reportable interest from sources both inside and outside New Jersey.
Common sources of reportable interest:
- Banks;
- Savings and loan associations;
- Credit unions;
- Savings accounts;
- Checking accounts;
- Bonds and notes;
- Certificate of deposit;
- Life insurance dividends;
- Earnings on nonqualified distributions from qualified tuition program accounts including NJBEST (New Jersey Better Educational Savings Trust program) accounts;
- Earnings on nonqualified distributions from qualified state 529A ABLE (Achieving a Better Life Experience) accounts;
- Distributions from Coverdell education savings accounts (ESAs), but only the earnings portion;
- Ginnie Maes, Fannie Maes, Freddie Macs;
- Repurchase agreements;
- Obligations of states and their political subdivisions, other than New Jersey;
- Grantor trusts;
- Any other interest not specifically exempt.
Do not include on this line:
- Interest that was earned and paid to a sole proprietorship, a partnership, or an S corporation.
Report on Schedule NJ-BUS-1. Note: If you received a Form 1099 from a partnership or an
S corporation for interest paid or deemed to have been paid to you, you must include that interest on line 16, column A;
- Interest that was earned and paid to an estate or trust (other than a grantor trust). Report on line 26.
Forfeiture Penalty for Early Withdrawal. If you incur a penalty by withdrawing a time deposit early, you can subtract the amount of the penalty from your interest income.
If line 16, column A is more than $1,500, enclose a copy of Schedule B, federal
Form 1040.
Tax-Exempt Interest Income. Do not report tax-exempt interest on line 16. For more information on tax-exempt interest income and New Jersey qualified investment funds, see GIT-5, Nontaxable Investment Income.
Part-Year Nonresidents. Include only the interest you received while you were a nonresident of New
Jersey.
# Column B
Do not report interest from personal accounts. Only report on line 16, column B interest received as a result of a business or profession carried on in New Jersey and not reportable as net profits from business, distributive share of partnership income, net income from estates or trusts, or net pro rata share of S corporation income.
(See instructions for line 16, column A.)
Line 17 - Dividends
# Column A
Enter the dividends you received from investments (e.g., from stocks, mutual funds) or other income-producing activities that do not constitute a trade or business. The total taxable dividends received, regardless of where earned, must be included.
Do not include on this line:
- Dividends that were earned and paid to a sole proprietorship, a partnership, or an S corporation. Report on Schedule NJ-BUS-1. For more information on reporting partnership or S corporation income, see GIT-9P, Partnership Income, or GIT-9S, Income
From S Corporations;
- Dividends that were earned and paid to an estate or trust (other than a grantor trust). Report on line 26.
Capital Gains Distributions. Do not report capital gains distributions you received from mutual funds or other regulated investment companies on this line. Report this income on Part I, line 66.
Tax-Free Distributions. A distribution that is a return of your investment or capital and does not come from earnings or profits is a nontaxable capital or tax-free distribution. These distributions reduce the basis of the stock or investment and are not taxable until your investment is fully recovered.
Insurance Premiums. Dividends you received from insurance companies are not reportable unless the amount you received is more than the premiums paid. Any interest from accumulated insurance dividends is reportable, and you must include it on line 16, column A.
Part-Year Nonresidents. Include only the dividends you received while you were a nonresident of New
Jersey.
# Column B
Do not report dividends from personally held securities. Only report on line 17, column B dividends received as a result of a business or profession carried on in New Jersey and not reportable as net profits from business, distributive share of partnership income, net income from estates or trusts, or net pro rata share of S corporation income. (See instructions for line 17, column A.)
Line 18 - Net Profits From Business
# Column A
Complete Part I of Schedule NJ-BUS-1 and enter on line 18, column A, the amount from line 4 of Part I. If the amount on line 4 is a loss, enter "0" on line 18, column A.
See instructions on page 16.
Enclose Schedule NJ-BUS-1 and a copy of the federal Schedule C (or C-EZ or F) for each business with your return.
# Column B
Enter the portion of your business income that comes from New Jersey sources. If zero, enter "0." If you carry on business both inside and outside New Jersey, you must complete and enclose Form NJ-NR-A for each business.
Do not include in column B net profits (or losses) that you received from a business entity located in New Jersey if the business entity's only activity is the purchase, holding, or sale of intangible personal property (e.g., securities, commodities) that is not held for sale to customers. You must include those net profits in column A.
Line 19 - Net Gains or Income From
# Disposition of Property
Column A
Complete Part I and enter the amount from line 68. If the amount on line 68 is zero, enter "0" on line 19.
Do not include in Part I:
- Gains/losses from the disposition of property owned by a sole proprietorship, a partnership, or an S corporation. Report on Schedule NJ-BUS-1;
- Gains/losses from the disposition of property owned by an estate or trust (other than a grantor trust). Report on line 26.
Column B
Enter your net gains or income from New Jersey sources. If zero, enter "0."
Line 20 - Net Gains or Income From
# Rents, Royalties, Patents, and Copyrights
# Column A
Complete Part II of Schedule NJ-BUS-1 and enter on line 20 the amount from line 4 of Part II. If the net amount is a loss, enter "0" on line 20, column A. See instructions on page 16.
Enclose Schedule NJ-BUS-1 with your return.
# Column B
Enter your net gains or income from New Jersey sources. If zero, enter "0."
Line 21 - Net Gambling Winnings
# Column A
Enter your net gambling winnings from both inside and outside New Jersey. You can subtract gambling or lottery losses from your winnings that occur in the same year. If the net amount is zero or less, enter "0." If you net gambling winnings with gambling losses, include a statement to that effect.
Common types of gambling winnings include:
- All casino and track betting;
- New Jersey Lottery winnings (only individual prizes exceeding $10,000);
- Any multistate lottery in which New Jersey participates (Mega Millions, Powerball), but only individual prizes exceeding $10,000;
- All out-of-State lottery winnings regardless of amount;
- Bingo winnings.
If you net gambling winnings with gambling losses, you may be required to substantiate the losses used to offset your winnings. Acceptable proof of losses includes:
- Casino win/loss statements;
- Daily log or journal of wins and losses;
- Canceled checks;
- Losing racetrack pari-mutuel tickets;
- Losing lottery tickets.
For more information, see Technical Bulletin TB-20(R).
Part-Year Nonresidents. Include only amounts you received while you were a nonresident of New Jersey.
# Column B
Enter your net gambling winnings from New Jersey sources. Gambling losses from sources outside New
Jersey cannot be used to offset gambling winnings from
New Jersey sources. If zero, enter "0."
Line 22 - Taxable Pensions, Annuities, and IRA Distributions/Withdrawals
# Column A
Retirement income such as pensions, annuities, and certain IRA withdrawals is reportable on your New Jersey return. The New Jersey reportable amount may be different from the federal taxable amount. Enter the reportable amount on line 22, column A.
Common types of taxable retirement income:
- Pensions from the private sector;
- Federal, state, and local government, and teachers' pensions;
- Keogh Plan distributions;
- 401(k) Plan distributions;
- Early retirement benefits;
- Amounts reported as pension on Schedule NJK-1,
Partnership Return Form NJ-1065;
- Civil Service pensions and annuities, even if based on credit for military service. These are received from the U.S. Office of Personnel Management.
# Worksheet B
General Rule Method
- Your previously taxed contributions to the plan … 1. __
- Expected return on contract* … 2. __
- Percentage excludable (Divide line 1 by line 2) … 3. __%
- Amount received this year … 4. __
- Amount excludable (Multiply line 4 by line 3) … 5. __
- Reportable amount (Subtract line 5 from line 4.
Enter here and on line 22, column A, Form NJ-1040NR … 6. __
*The expected return on the contract is the amount receivable. If life expectancy is a factor under your plan, you must use federal actuarial tables to calculate the expected return. The federal actuarial tables are contained in the Internal Revenue Service's Publication 939, General Rule for Pensions and Annuities. Contact the IRS for this publication. If life expectancy is not a factor under your plan, the expected return is found by totaling the amounts to be received.
(Keep for your records)
Worksheet A
Which Pension Method to Use
- Amount of pension you will receive during the first three years (36 months) from the date of the first payment … 1. __
- Your contributions to the plan … 2. __
- Subtract line 2 from line 1 … 3. __
(a) If line 3 is "0" or more, and both you and your employer contributed to the plan, you can use the Three-Year Rule Method.
(b) If line 3 is less than "0," or your employer did not contribute to the plan, you must use the General Rule Method.
(Keep for your records)
# Worksheet C
IRA Withdrawals
# Part I - Calculating Taxable Amounts
- Value of IRA on 12/31/25.
Include contributions made for the tax year from 1/1/26 - 4/15/26 … 1. _ __
- Total distributions from IRA during the tax year. Do not include tax-free rollovers... 2. _ __
- Total Value of IRA. Add lines 1 and 2 … 3. _ __
Unrecovered Contributions:
Complete either line 4a or 4b. Then continue with line 5.
4a. First year of withdrawal from IRA:
Enter the total of IRA contributions that were previously taxed … 4a. _ __
4b. After first year of withdrawal from IRA:
Complete Part II. Enter amount of unrecovered contributions from line 14 … 4b. _ __
- Accumulated earnings in IRA on 12/31/25.
Subtract either line 4a or 4b from line 3 … 5. _ __
- Divide line 5 by line 3. (Enter the result as a decimal.) … 6. _ __
- Taxable portion of this year's withdrawal. Multiply line 2 by decimal amount on line 6. Enter here and on line 22, column A, Form NJ-1040NR … 7. _ __
# Part II - Unrecovered Contributions (For Second and Later Years)
See Part III if you did not complete Worksheet C in prior years.
- Last year's unrecovered contributions. From line 4 of last year's Worksheet C … 8. _ __
- Amount withdrawn last year. From line 2 of last year's Worksheet C … 9. _ __
- Taxable portion of last year's withdrawal. From line 7 of last year's Worksheet C … 10. _ __
- Contributions recovered last year. Subtract line 10 from line 9 … 11. _ __
- This year's unrecovered contributions. Subtract line 11 from line 8 … 12. _ __
- Contributions to IRA during current tax year. Do not include tax-free rollovers … 13. _ __
- Total unrecovered contributions. Add lines 12 and 13. Enter here and on line 4b...14. _ __
# Part III - Unrecovered Contributions (For Second and Later Years)
Complete this section only if you did not complete Worksheet C in prior years.
Calculate the amount of unrecovered contributions as follows: … _ __
- Total amount of withdrawals made from the IRA in previous years … 15. _ __
- Total of previous year withdrawal(s) already reported as income on prior
New Jersey tax returns … 16. _ __
- Contributions already recovered. Subtract line 16 from line 15 … 17. _ __
- Unrecovered contributions. Subtract line 17 from the total amount of contributions made to the IRA. Enter here and on line 4b … 18. _ __
(Keep for your records)
Common types of nonreportable retirement income (do not report on this return):
- Social Security benefits;
- Railroad Retirement benefits;
- Public or private disability pension benefits until the year you turn 65. Beginning with the year you turn 65, the benefits are treated as ordinary pension income;
- U.S. Military pensions and survivor's benefit payments (Most are received from the U.S. Department of Finance and Accounting Service.) Part-Year Nonresidents. Include only the reportable amounts you received while you were a nonresident of New Jersey.
# Types of Retirement Plans
Retirement plans are either noncontributory or contributory.
Noncontributory. You made no contributions to your plan. Amounts you receive from these plans are fully reportable. Enter the amount from your 1099-R on line 22, column A.
Contributory (Other Than IRAs). You made contributions to your plan. Contributions are usually made through payroll deductions and, in general, are taxed when they are made. Contributions made to a retirement plan (other than a 401(k) Plan) outside New Jersey are considered to have been previously taxed. These plans also may include employer contributions and earnings, which have not been taxed.
Since you have already been taxed on your contributions, you must determine the portion of your distribution that is reportable. There are two methods of calculating the reportable amount: Three-Year Rule Method and General Rule Method. To determine which method to use, complete Worksheet A on page 12 the year you begin receiving pension and annuity payments.
Note: If you received a distribution from a 401(k) Plan, do not complete Worksheet A. See the section on 401(k) Plans below. If you made a withdrawal from an IRA, do not complete Worksheet A or B. Instead, complete Worksheet C. See the section on IRAs below.
Three-Year Rule Method. Use this method if you will recover all your contributions within 36 months from the date you receive your first payment from the plan, and both you and your employer contributed to the plan.
Do not report pension and annuity payments as income on line 22 until you have recovered all of your contributions. Once you have recovered your contributions, the payments you receive are fully reportable and must be entered on line 22, column A.
General Rule Method. You must use this method if you will not recover your contributions within 36 months from the date you receive your first payment from the plan or if your employer did not contribute to the plan. Part of your pension is excludable and part is reportable every year.
The excludable amount represents your contributions.
Complete Worksheet B in the year you receive your first payment from the plan and keep it for your records. You will need it for calculations in future years. Recalculate the percentage on line 3 of Worksheet B only if your annual pension payments decrease.
# Lump-Sum Distributions and Rollovers
When you receive a lump-sum distribution of the entire balance from a qualified employee pension, annuity, profit-sharing, or other plan, any amount that exceeds your previously taxed contributions must be included in your income in the year received. New Jersey has no provision for income averaging of lump-sum distributions.
Enter the reportable amount on line 22, column A.
If you roll over a lump-sum distribution from an IRA or a qualified employee pension or annuity plan into an IRA or other eligible plan, do not report the rollover on line 22 if it qualifies for deferral for federal tax purposes. The amount rolled over (minus previously taxed contributions) will be reportable when it is withdrawn.
# 401(k) Plans
- Contributions made on or after January 1, 1984, were not taxed when they were made. If all of your contributions were made on or after that date, your distributions are fully reportable unless your contributions exceeded the federal limit. If your contributions exceeded the federal limit, you must calculate the reportable portion of your distributions using one of the methods described under contributory plans.
- Contributions made before January 1, 1984, were taxed when they were made. If you made contributions before that date, you must calculate the reportable portion of your distributions using one of the methods described under contributory plans.
For more information on pension and annuity income, see GIT-1 & 2, Retirement Income.
IRAs
Your IRA consists of contributions, earnings, and certain amounts rolled over from pension plans. In general, your contributions were taxed when they were made and are not reportable to New Jersey when you make a withdrawal. All the earnings and any amounts rolled over taxfree are reportable when withdrawn.
Use Worksheet C to calculate the reportable portion of your IRA withdrawal. If you made withdrawals from multiple IRAs, you can use a separate worksheet for each or combine all IRAs on one worksheet.
Lump-Sum Withdrawal. If you withdraw the total amount from an IRA, all the earnings and any amounts rolled over tax-free are reportable. You must report these amounts in the year you make the withdrawal.
Periodic Withdrawals. If you make withdrawals over a period of years, the part of the annual distribution that represents earnings is reportable. The amount reportable for New Jersey purposes may be different from the amount you report on your federal return.
For more information on IRA withdrawals, see GIT-1 & 2,
Retirement Income.
# Roth IRAs
Your contributions to a Roth IRA are reportable as part of your income when they are made. Distributions from a Roth IRA that meet the requirements of a qualified distribution are excludable. Do not include qualified distributions on Form NJ-1040NR. If you received a nonqualified distribution, you must report the earnings on line 22, column A. A distribution that is considered nonqualified for federal purposes is also considered nonqualified for New Jersey purposes.
If you converted an existing IRA to a rollover Roth IRA during Tax Year 2025, any amount from the existing IRA that would be reportable if withdrawn must be included on line 22, column A.
For more information on Roth IRAs, see Technical Bulletin TB-44.
Column B
You will not enter an amount on line 22, column B because pension, annuity, and IRA withdrawal income is not taxable to nonresidents.
Line 23 - Distributive Share of
# Partnership Income
Column A
Complete Part III of Schedule NJ-BUS-1 and enter on line 23, column A, the amount from line 4 of Part III. If the amount on line 4 is a loss, enter "0" on line 23, column A.
See instructions on page 17.
Enclose Schedule NJ-BUS-1 and a copy of Schedule NJK-1, Form NJ-1065, for each partnership with your return. If you did not receive a Schedule NJK-1, enclose a copy of the federal Schedule K-1.
Column B
Enter the portion of the partnership income that comes from New Jersey sources. If zero, enter "0."
Do not include in column B distributive share of partnership income that you received from a partnership, LLP, or LLC located in New Jersey if the business entity's only activity is the purchase, holding, or sale of intangible personal property, such as commodities or securities, and such intangible personal property is not held for sale to customers. You must include such partnership income in column A.
Line 24 - Net Pro Rata Share of S
# Corporation Income
Column A
Complete Part IV of Schedule NJ-BUS-1 and enter on line 24, column A, the amount from line 4 of Part IV. If the amount on line 4 is a loss, enter "0" on line 24, column A.
See instructions on page 18.
Enclose Schedule NJ-BUS-1 and a copy of Schedule NJ-K-1, Form CBT-100S, for each S corporation with your return. If you did not receive a Schedule NJ-K-1, enclose a copy of the federal Schedule K-1.
Column B
Enter the portion of the net pro rata share of S corporation income that comes from New Jersey sources. If zero, enter "0."
# Business Income Summary Schedule
# Part I - Net Profits From Business
Report the net profits or loss from your business, trade, or profession.
Make the following adjustments to your federal Schedule C (or C-EZ or F):
- Add any amount you deducted for taxes based on income.
- Subtract interest you reported on federal Schedule C (or C-EZ or F) that is exempt for New Jersey purposes but taxable for federal purposes.
- Add interest not reported on federal Schedule C (or C-EZ or F) from states or political subdivisions outside New Jersey that is exempt for federal purposes.
- Deduct meal and entertainment expenses that constitute ordinary expenses incurred in the conduct of a trade or business but that were not allowed on the federal return.
- Deduct your qualified contributions to a self-employed 401(k) Plan. Contributions that exceeded the federal limits are not deductible for New Jersey purposes.
- Add interest and dividends derived in the conduct of a trade or business.
- Add or subtract income or losses derived in the conduct of a trade or business from rentals, royalties, patents, or copyrights.
- Add or subtract gains or losses from the sale, exchange, or other disposition of the trade or business's property.
- Add or subtract the net adjustment from the Gross Income Tax Depreciation Adjustment Worksheet GIT-DEP, Part I, line 7.
- Cannabis licensees: Deduct expenses that would have been eligible to be claimed as a deduction for federal purposes but were disallowed because cannabis is a controlled substance under federal law.
If you are a sole proprietor who provides primary care services in a qualified medical or dental practice you own that is located in or within five miles of a designated Health Enterprise Zone (HEZ), you may be able to deduct a percentage of the net income from that practice on line 34. See Technical Bulletin TB-56 for eligibility requirements and instructions for calculating the HEZ deduction.
# Lines 1-3
For each business, enter the following information. If you need more space, enclose a statement with the return listing any additional businesses and the related profit or loss.
- Business name as listed on Schedule C, C-EZ, or F
- Social Security number or federal employer identification number (EIN)
- Profit or (loss) as adjusted for New Jersey purposes
Line 4
Add the amounts in the Profit or (Loss) column and enter the total on line 4, netting profits with losses. Enter this amount on line 18, column A. If the netted amount is a loss, make no entry on line 18, column A. On line 18, column B, enter the portion of this amount that is from New Jersey sources.
Part-Year Nonresidents. Include only the amounts you received while you were a nonresident of New Jersey.
Part II - Net Gains or Income From Rents, Royalties, Patents, and Copyrights
Report your net gains or income less net losses from rents, royalties, patents, and copyrights.
Depreciation and Expense Deduction. New Jersey and federal depreciation and expense deduction limits are different.
You may need to make adjustments to your federal basis for assets placed in service on or after January 1, 2004. Complete the Gross Income Tax Depreciation Adjustment Worksheet GIT-DEP to calculate the adjustment.
Passive Losses. There is no distinction between active and passive losses for New Jersey purposes. You cannot carry back or carry forward such losses when reporting income on Form NJ-1040NR. You can deduct federal passive losses in full in the year incurred against any gain within the same category of income.
Do not include in Part II:
- Gains/losses from rents, royalties, patents, and copyrights from property owned by a sole proprietorship, a partnership, or an S corporation. Report in Parts I, III, and/or IV of Schedule NJ-BUS-1;
- Gains/losses from rents, royalties, patents, and copyrights from property owned by an estate or trust (other than a grantor trust). Report on line 26.
# Lines 1-3
For each source of income or loss, enter the following information. If you need more space, enclose a statement with the return listing any additional property and income or loss.
- Property name or description. For rental real estate, enter the physical address of the property
- Social Security number or federal employer identification number (EIN)
- Type of property. Enter the following number that corresponds with the type of property:
- Royalties
- Patents
# 4. Copyrights
- Gain or (loss) from each type of property
Line 4
Add the amounts in the Income or (Loss) column and enter the total on line 4, netting gains with losses. Enter this amount on line 20, column A, Form NJ-1040NR. If the netted amount is a loss, enter "0" on line 20, column A. On line 20, column B, enter the portion of this amount that is from New Jersey sources.
Part-Year Nonresidents. Include only the amounts you received while you were a nonresident of New Jersey.
Part III - Distributive Share of Partnership Income
Report your share of income or loss from partnership(s), whether or not the income was actually distributed.
# Lines 1-3
For each partnership, enter the following information. If you need more space, enclose a statement with the return listing any additional partnerships and the related income or loss.
- Partnership name as listed on the Schedule NJK-1 (or federal Schedule K-1)
- Federal employer identification number (EIN)
- Your share of partnership income or (loss) as reported on the Schedule NJK-1 (column A of the line labeled Distributive Share of Partnership Income). If you did not receive an NJK-1, you must enclose a copy of the federal Schedule K-1 and complete Reconciliation Worksheet A in GIT-9P, Partnership Income
- Total amount of New Jersey Income Tax paid on your behalf by partnership(s) as reported on Schedule NJK-1, line 1, Part III, nonresident partner's share of New Jersey tax
- Your share of Pass-Through Business Alternative Income Tax as reported on Schedule PTE-K-1 or Schedule NJK-1 received from the partnership
Line 4
Add the amounts in the Share of Partnership Income or (Loss) column and enter the total on line 4, netting income with losses. Enter this amount on line 23, column A, Form NJ-1040NR. If the netted amount is a loss, enter "0" on line 23, column A. On line 23, column B, enter the portion of this amount that is from New Jersey sources.
Line 5
Add the amounts in the Share of tax paid on your behalf by Partnerships column and enter the total. Include this amount on line 52, Form NJ-1040NR. See the instructions for line 52.
Line 6
Add the amounts in the Share of Pass-Through Business Alternative Income Tax column and enter the total. Include this amount on line 56, Form NJ-1040NR.
For more information, see GIT-9P, Partnership Income.
Part-Year Nonresidents. Prorate your distributive share of partnership income based on the number of days in the partnership's fiscal year that you were a nonresident of New Jersey.
Part IV - Net Pro Rata Share of S Corporation Income
Report the amount of your net pro rata share of S corporation income or loss, whether or not the income was actually distributed.
# Lines 1-3
For each S corporation, enter the following information. If you need more space, enclose a statement with the return listing any additional S corporations and the related income or loss.
- S corporation name as listed on Schedule NJ-K-1 (or federal Schedule K-1)
- Federal employer identification number (EIN)
- Your pro rata share of S corporation income or (usable loss) as reported on the Schedule NJ-K-1. If you did not receive an NJ-K-1, you must enclose a copy of the federal Schedule K-1 and complete Reconciliation Worksheet B in
GIT-9S, Income From S Corporations.
- Your share of Pass-Through Business Alternative Income Tax as reported on Schedule PTE-K-1 or Schedule NJ-K-1 received from the S corporation.
Line 4
Add the amounts in the Pro Rata Share of S Corporation Income or (Usable Loss) column and enter the total on line 4, netting income with losses. Enter this amount on line 24, column A, Form NJ-1040NR. If the netted amount is a loss, enter "0" on line 24, column A. On line 24, column B, enter the portion of this amount that is from New Jersey sources
Line 5
Add the amounts in the Share of Pass-Through Business Alternative Income Tax column and enter the total. Include this amount on line 56, Form NJ-1040NR.
For more information, see GIT-9S, Income From S Corporations.
Part-Year Nonresidents. Prorate the pro rata share of S corporation income based on the number of days in the entity's fiscal year that you were a nonresident of New Jersey.
Line 25 - Alimony and Separate
# Maintenance Payments Received
# Column A
Enter any court-ordered alimony or separate maintenance payments you received. Do not include payments received for child support.
Part-Year Nonresidents. Include only those payments you received while you were a nonresident of New Jersey.
# Column B
You will not enter an amount on line 25, column B because alimony and separate maintenance payments are not taxable to nonresidents.
Line 26 - Other Income
# Column A
Include the following income on this line:
See each type of income listed below for required enclosures.
Amounts Received as Prizes and Awards. Any prize won in a raffle, drawing, TV show, radio show, contest, or any other event is reportable and must be included on this line in column A. Include any goods or services as income at fair market value.
Income in Respect of a Decedent. If you had the right to receive income that the deceased person would have received had they lived and it was not included on the decedent's final return, you must report it on your own return when you receive it. Enclose a listing of the income.
Income From Estates and Trusts. If you are a beneficiary who received income from an estate or trust, include the Total Distribution from Schedule NJK-1, Form NJ-1041 on this line. If you did not receive an NJK-1, adjust the income listed on the federal K-1 to reflect New Jersey tax law, then net the adjusted amounts and include the total on line 26. Enclose Schedule NJK-1 (or federal Schedule K-1) with your return.
If you have income from a grantor trust that is reportable for New Jersey purposes, do not include it on this line.
Report the income in the proper category (e.g., report taxable interest on line 16a). Enclose a copy of the New Jersey or federal Grantor Trust Attachment.
For more information on estates and trusts, including grantor trusts, see GIT-12, Estates and Trusts.
Scholarships and Fellowship Grants. This type of income is taxable unless the scholarship or grant meets all of the following conditions:
- The primary purpose of the grant is to further the recipient's education or training; and
- The grant does not represent payments for past, present, or future services that are subject to the direction or supervision of the grantor (e.g., a fellowship given in exchange for teaching); and
- The grant is not for the benefit of the grantor.
Residential Rental Value or Allowance Paid by Employer. If an employer provides you with a residence, enter either the rental value or the rental allowance paid by the employer.
The rental value or allowance is excludable and should not be reported if it meets all of the following conditions:
- The lodging is provided on the business premises of your employer; and
- The lodging is provided for the convenience of your employer; and
- You are required to accept the lodging as a condition of employment.
Other. Use this line for any other taxable income for which a place has not been provided somewhere else on the return. Income from both legal and illegal sources is subject to tax.
# Column B
Enter the portion of your other income that comes from
New Jersey sources. If zero, enter "0."
Amounts Received as Prizes and Awards. Do not include in column B a prize won in a raffle, drawing, television or radio quiz show, or contest. You must include these amounts in column A.
Income From Estates and Trusts. Include the Total
New Jersey Source Income Distributed reported on
Schedule NJK-1, Form NJ-1041. If you did not receive an NJK-1, adjust the income listed on the federal K-1 to reflect New Jersey tax law, then net the adjusted New Jersey source income amounts and include the total on line 26. Do not include in column B income you received from an estate or trust if the estate or trust received the income from a business entity (i.e., sole proprietorship, partnership, LLP, or LLC) located in New Jersey and the only activity of the business entity is the purchase, holding, or sale of intangible personal property, such as commodities or securities, and the intangible personal property is not held for sale to customers. You must include this income in column A.
Line 27 - Total Income
# Column A
Add lines 15 through 26, column A, and enter the total.
# Column B
Add lines 15 through 26, column B, and enter the total
Line 28a - Pension/Retirement Exclusion
# Column A
You can exclude all or part of the income reported on line
22 if you meet the following qualifications:
- You (and/or your spouse if filing jointly) were age 62 or older or blind/disabled as defined by Social Security guidelines on the last day of the tax year; and
- Your income on line 27, column A, is $150,000 or less (part-year nonresidents see below).
# Worksheet D
Other Retirement Income Exclusion
Age Requirement: 62 or older
Part-year nonresidents do not complete this worksheet. (See instructions on page 22.)
Is income on line 27, column A, NJ-1040NR MORE than $150,000?
Yes. You are not eligible to use any unclaimed portion of your maximum exclusion
Make no entry on line 28b, columns A and B unless you are eligible for the
Special Exclusion (see below).
No. Continue with line 1.
- Enter the amount of your maximum exclusion using the chart below … 1. __
- Enter the amount from line 28a, NJ-1040NR … 2. __
- Subtract line 2 from line 1 … 3. __ Is the amount on line 3 MORE than $0? Yes. Continue with line 4. No. You do not have any unused exclusion amount. Make no entry on line 28b, columns A and B unless you are eligible for the Special Exclusion (see below).
- Enter the amount from line 15, col. A, NJ-1040NR … 4. __
- Enter the amount from line 18, col. A, NJ-1040NR … 5. __
- Enter the amount from line 23, col. A, NJ-1040NR … 6. __
- Enter the amount from line 24, col. A, NJ-1040NR … 7. __
- Add lines 4, 5, 6, and 7 … 8. __
Is the amount on line 8 MORE than $3,000?
Yes. You are not eligible to use the unclaimed portion of your maximum exclusion.
Make no entry on line 28b, columns A and B unless you are eligible for the
Special Exclusion (see below).
No. Continue with line 9.
- Unclaimed Pension Exclusion. Enter the amount from line 3. Also include this amount on line 28b, column A and column B, NJ-1040NR … 9. __
Joint filers: If only one spouse is 62 or older, only the income of that spouse can be excluded.
Special Exclusion. If you (and your spouse if filing jointly) will never be able to receive Social Security or Railroad Retirement benefits because your employer did not participate in either program, you may qualify for this exclusion.
See GIT-1 & 2, Retirement Income, before entering an amount on line 28b.
Maximum Exclusion
Filing Status:
Income on line 27, column A:
$0 - $100,000 $100,001 - $125,000 $125,001 - $150,000
Married/CU couple, filing joint return $100,000 50% of line 27, col. A 25% of line 27, col. A
Single
Head of household
Qualifying widow(er)/surviving CU partner
$75,000 37.5% of line 27, col. A 18.75% of line 27, col. A
Married/CU partner, filing separate return $50,000 25% of line 27, col. A 12.5% of line 27, col. A
(Keep for your records)
# Worksheet E
Other Retirement Income Exclusion - Part-Year Residents
Age Requirement: 62 or older
Was your income for the entire year MORE than $150,000?
Yes. You are not eligible to use any unclaimed portion of your maximum exclusion
Make no entry on line 28b, columns A and B unless you are eligible for the
Special Exclusion (see below).
No. Continue with line 1.
- Enter the amount of your maximum exclusion calculated using the chart below.
If your income was $100,000 or less, you must prorate the maximum amount based on the number of months you were a New Jersey resident (do not prorate if your income was over $100,000) … 1. __
- Enter the amount from line 28a, NJ-1040NR … 2. __
- Subtract line 2 from line 1 … 3. __ Is the amount on line 3 MORE than $0? Yes. Continue with line 4. No. You do not have any unused exclusion amount. Make no entry on line 28b, columns A and B unless you are eligible for the Special Exclusion (see below).
Enter the following income for the entire year:
- Wages, salaries, tips, and other employee compensation … 4. __
- Net profits from business … 5. __
- Distributive share of partnership income … 6. __
- Net pro rata share of S corporation income … 7. __
- Add lines 4, 5, 6, and 7 … 8. __
Is the amount on line 8 MORE than $3,000?
Yes. You are not eligible to use any unclaimed portion of your maximum exclusion
Make no entry on line 28b, columns A and B unless you are eligible for the
Special Exclusion (see below).
No. Continue with line 9.
- Unclaimed Pension Exclusion. Enter the amount from line 3. Also include this amount on line 28b, column A and column B, NJ-1040NR … 9. __
Joint filers: If only one spouse is 62 or older, only the income of that spouse can be excluded.
Special Exclusion. If you (and your spouse if filing jointly) will never be able to receive Social Security or Railroad Retirement benefits because your employer did not participate in either program, you may qualify for this exclusion. See GIT-1 & 2, Retirement Income, before entering an amount on line 28b.
Maximum Exclusion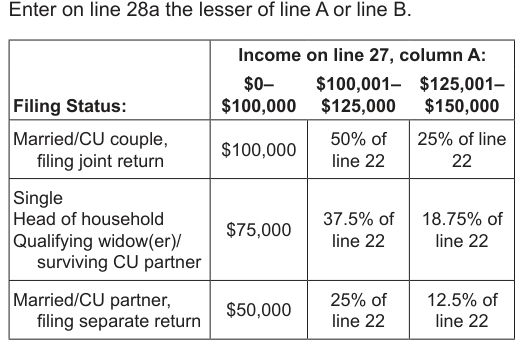
Text version of this table
Filing Status: Income on line 27, column A: $0– $100,001– $125,001– $100,000 $125,000 $150,000 Married/CU partner, filing separate return $100,000 50% of line 22 25% of line 22 Single Head of household Qualifying widow(er)/ surviving CU partner $75,000 37.5% of line 22 18.75% of line 22 Married/CU partner, filing separate return $50,000 25% of line 22 12.5% of line 22
For more information, see GIT-1 & 2, Retirement Income.
Part-Year Nonresidents. Your income for the entire year must have been $150,000 or less to qualify for the exclusion. If your income for the entire year is $0-$100,000, prorate the maximum exclusion amount from the chart above based on the number of months you were a nonresident and enter on line B above when calculating your exclusion. If your income for the entire year is over $100,000, do not prorate the exclusion amount.
Column B
You will not enter an amount on line 28a, column B because pension, annuity, and IRA withdrawal income is not taxable to nonresidents.
Line 28b - Other Retirement Income
# Exclusion
If you were 62 or older on the last day of the tax year, you may be able to use the other retirement income exclusion. If you are filing jointly and only one spouse is 62 or older, only the income of that spouse can be excluded.
You cannot exclude the income of the spouse who is younger than 62.
Unclaimed Exclusion. If you did not use your entire maximum exclusion on line 28a, you may be able to use the unclaimed portion. Complete Worksheet D to determine whether you have any exclusion remaining and meet the eligibility requirements and, if so, to calculate the amount to include on line 28b. Part-year nonresidents do not complete Worksheet D. Instead, use Worksheet E.
Special Exclusion. If you (and your spouse if filing jointly) will never be able to receive Social Security or Railroad Retirement benefits because your employer did not participate in either program, you may qualify for the Special Exclusion. If you qualify, you can claim $6,000 (married, filing joint; head of household; qualifying widow(er)) or $3,000 (single; married, filing separate).
Note: Do not claim the Special Exclusion if you (or your spouse if filing jointly) will ever be eligible for Social Security or Railroad Retirement benefits.
See GIT-1 & 2, Retirement Income, for more information.
Part-Year Nonresidents. If you did not use your entire prorated maximum exclusion on line 28a, you may be able to use the unclaimed portion. Complete Worksheet E to determine whether you have any exclusion remaining and meet the eligibility requirements and, if so, to calculate the amount to include on line 28b.
Line 28c - Total Exclusion Amount
# Column A
Add lines 28a and 28b, column A, and enter the total.
# Column B
Enter on line 28c, column B, the amount from line 28b, column B.
Line 29 - Gross Income
# Column A
Subtract line 28c, column A, from line 27, column A, and enter the result. If zero or less, enter "0."
Required to file a return
You are required to file a return if your income on line 29, column A is more than the filing threshold:
- $20,000 Married filing jointly, Head of Household, or Qualified Widow(er)
- $10,000 Single or married/CU partner filing separate return
Not required to file a return
You are not required to file a return if your income is at or below the filing threshold. However, you still need to file if you:
- Had New Jersey Income Tax withheld;
- Paid estimated taxes or had a credit from the prior year.
Enter zero on lines 39 and 40 and complete the return.
Withholding Exemption. If you do not expect to have a
# New Jersey Income Tax liability for 2026, complete Form
NJ-W4 and give it to your employer to claim an exemption from withholding.
Part-Year Nonresidents. If your income for the entire year was equal to or less than the filing threshold amount and you are filing to get a refund, you must enclose a copy of your federal return. If you did not file a federal return, include a statement to that effect.
# Column B
Subtract line 28c, column B, from line 27, column B, and enter the result. If zero or less, enter "0."
# Line 30 - Total Exemption Amount
Calculate your total exemption amount as follows:
From line 13a_ _ × $1,000 = _ _
From line 13b_ _ × $1,500 = _ _
From line 13c_ _ × $6,000 = _ _
# Total Exemption Amount________________________
Add the exemption amounts calculated above and enter the total on line 30.
Part-Year Nonresidents. Prorate the total calculated above for the time you were a nonresident of New Jersey and enter the amount on line 30. For this calculation, 15 days or more is considered a month.
# Line 31 - Medical Expenses
You can deduct certain unreimbursed medical expenses you paid during the year for yourself, your spouse or domestic partner, and any dependents you claim. You can only deduct expenses that are more than 2% of your gross income. In general, medical expenses allowed for federal tax purposes are allowed for New Jersey tax purposes. These can include:
- Physicians, dental, and other medical fees;
- Prescription eyeglasses and contact lenses;
- Hospital care;
- Nursing care;
- Medicines and drugs;
- Prosthetic devices;
- X-rays and other diagnostic services conducted by or directed by a physician or dentist;
- Amounts paid for transportation primarily for and essential to medical care;
- Insurance (including amounts paid as premiums under Part B of Title XVIII of the Social Security Act, relating to supplementary medical insurance for the aged) covering medical care.
You can also deduct qualified Archer MSA contributions and self-employed health insurance costs. Information is available on our website.
Use Worksheet F below to calculate your medical expenses deduction.
Note: For federal purposes you may be able to deduct amounts paid for health insurance for any child of yours who was under age 27 at the end of 2025. However, for New Jersey purposes you can deduct these amounts
# Worksheet F
Deduction for Medical Expenses
- Total unreimbursed medical expenses … 1.__
- Enter line 29, column A, Form NJ-1040NR_x .02 = … 2._
- Medical Expenses Deduction. Subtract line 2 from line 1 and enter result here.
If zero or less, enter zero … 3.__
- Enter the amount of your qualified Archer MSA contributions from federal Form 8853 … 4.__
- Enter the amount of your self-employed health insurance deduction … 5.__
- Total Deduction for Medical Expenses. Add lines 3, 4, and 5. Enter the result here and on line 31, Form NJ-1040NR. If zero, enter zero here and make no entry on line 31, Form NJ-1040NR … 6.__ (Keep for your records) only if the child was your dependent. For more information, see Technical Advisory Memorandum TAM 2011-14.
Part-Year Nonresidents. Include only those expenses you incurred and paid while you were a nonresident of New Jersey.
Line 32 - Alimony and Separate
# Maintenance Payments
Enter any court-ordered alimony or separate maintenance payments you made. Do not include child support payments.
Part-Year Residents. Include only those payments made while you were a nonresident of New Jersey.
Line 33 - Qualified Conservation
# Contribution
Enter any qualified contribution you made of real property (land) in New Jersey for conservation purposes (e.g., protection of natural habitat, farmland, forest, or open space). The deduction is the amount of the contribution allowed as a deduction in calculating your taxable income for federal purposes.
If you file federal Form 8283, enclose a copy with your return.
Part-Year Nonresidents. Include only those contributions you made while you were a nonresident of New Jersey.
Line 34 - Health Enterprise Zone
# Deduction
If you provide primary care services in a qualified medical or dental practice you own that is located in or within five miles of a designated Health Enterprise Zone (HEZ), you may be able to deduct a percentage of the net income from that practice.
Enter the HEZ deduction for a qualified practice as follows:
- Partners - Use the amount from Part III of the
Schedule NJK-1, Form NJ-1065, you received from the practice;
- S corporation shareholders - Use the amount from
Part V of the Schedule NJ-K-1, Form CBT-100S, you received from the practice;
- Sole proprietors - Determine your allowable HEZ deduction and enclose a schedule showing how you calculated it.
Note: Do not claim unreimbursed medical expenses, health insurance premiums, or other personal or business expenses as a deduction on this line.
For eligibility requirements and instructions for calculating the HEZ deduction, see Technical Bulletin TB-56.
Part-Year Nonresidents. If you are a partner or an
S corporation shareholder, you must prorate the deduction based on the number of days in the entity's fiscal year that you were a nonresident of New Jersey. If you are a sole proprietor, use only the receipts for your period of nonresidency when calculating the deduction.
Line 35 - Alternative Business Calculation
# Adjustment
If you completed Schedule NJ-BUS-1 and had a loss on line 4 of any part, you may be eligible for an income adjustment. You also may be eligible if you had a loss carryforward on Schedule NJ-BUS-2 from a prior year.
Complete Schedule NJ-BUS-2 and enter on line 35 the amount from line 11 of the schedule.
Enclose Schedule NJ-BUS-2 with your return and keep a copy for your records.
You may need the information to complete future returns.
Note: You must keep track of any unused losses that are carried forward. Unused losses can be carried forward for up to 20 years to calculate future adjustments.
Line 36 - Organ/Bone Marrow Donation
# Deduction
If you donated an organ or bone marrow to another person for transplantation, you can deduct up to $10,000 of unreimbursed expenses for travel, lodging, and lost wages related to the donation. This deduction is also available to your spouse (if filing jointly) or any dependents you claim on your return. You must take the deduction the year in which the transplant occurs. If you had unreimbursed expenses in the year prior to or in the year after the transplant, they must be claimed in the year they were incurred. The combined deduction amount cannot exceed $10,000.
You may be asked to provide documentation indicating that you are eligible to claim the deduction, such as employee pay statements and a letter from a physician.
A list of acceptable documentation is available on our website.
Line 37a-37c - New Jersey College
# Affordability Deductions
If your gross income was $200,000 or less, you may be eligible to deduct certain educational expenses.
Line 37a - You can deduct up to $10,000 of contributions made during the year into an NJBEST (New Jersey Better Educational Savings Trust) account.
Line 37b - You can deduct up to $2,500 of principal and interest paid during the year on an NJCLASS (New Jersey College Loans to Assist State Students) loan.
Line 37c - If you, your spouse, or your dependent enroll in or attend a New Jersey institution of higher education, you can deduct up to $10,000 for tuition costs paid during the year.
Married, Filing Separately. If you and your spouse file separate returns, the combined deduction amounts cannot exceed the amounts shown above.
Part-Year Nonresidents. You must use your income for the entire year when determining your eligibility.
Prorate your deduction based on the number of months you were a nonresident of New Jersey.
Line 38 - Total Exemptions and
# Deductions
Add lines 30 through 37c and enter the total.
Line 39 - Taxable Income
Subtract line 38 from line 29, column A, and enter the result. If line 39 is zero or less, enter "0."
Line 40 - Tax on Amount on Line 39
Calculate your tax using one of the following methods and enter the amount on line 40.
Tax Table. If line 39 is less than $100,000, you can use the New Jersey Tax Table on page 35 or the New Jersey Tax Rate Schedules on page 44 to find your tax. If you use the tax table, use the correct column for your filing Tax Rate Schedules. If line 39 is $100,000 or more, you must use the New Jersey Tax Rate Schedules on page 44. Use the correct schedule for your filing status.
Line 41 - Income Percentage
Divide the amount on line 29, column B by the amount on line 29, column A. Carry your result to four decimal places and enter the result. For example, if the amounts used were $20,000 (line 29, column B) divided by $30,000 (line 29, column A), the result would be 66.67% or .6667.
In certain situations the income percentage can be more than 100%. For example, a taxpayer realizes a $50,000 gain from the sale of real property in New Jersey and sustains a $10,000 loss from the sale of property in Florida. This nonresident (who has no other income) reports $40,000 as their income from everywhere (column A) and $50,000 as income from New Jersey sources (column B). The income percentage is 125% (or 1.25) calculated as follows: $50,000 (line 29, column B) divided by $40,000 (line 29, column A).
Line 42 - New Jersey Tax
Multiply the amount on line 40 by the income percentage on line 41, and enter the result.
Line 43 - Sheltered Workshop Tax Credit
Enter your Sheltered Workshop Tax Credit for the current year from Part IV, line 12 of Form GIT-317.
Enclose Form GIT-317 with your return.
Part-Year Nonresidents. Prorate your credit based on the number of months you were a nonresident of New Jersey.
Line 44 - Gold Star Family Counseling
# Credit
If you are a mental health care professional who provided counseling through the Gold Star Family Counseling program, complete the following calculation to determine the amount of your credit:
- Enter the number of hours of counseling you provided through the program …
- Enter the TRICARE rate for the service …
- Multiply line 1 by line 2.
Enter this amount on line 44 …
Part-Year Nonresidents. Include only the hours of counseling provided through the program while you were a nonresident of New Jersey.
Line 45 - Credit for Employer of Organ/
# Bone Marrow Donor
If you are an employer who provided paid time off to an employee who missed work to donate an organ or bone marrow for transplantation, you may be able to claim a credit. The paid time off must have been in addition to any other paid time off to which the employee was entitled. If you qualify, you can take a credit of 25% of the employee's salary for up to 30 days of time missed from work for each donation.
You may be asked to provide documentation indicating that you are eligible to claim the credit, such as employee pay statements and a letter from a physician.
A list of acceptable documentation is available on our website.
Line 46 - Total Credits
Add lines 43 through 45 and enter the total.
Line 47 - Balance of Tax After Credits
Subtract line 46 from line 42 and enter the result. If line 46 is blank, enter the amount from line 42.
Line 48 - Interest on Underpayment of
# Estimated Tax
New Jersey Income Tax is a pay-as-you-go tax. You must pay tax on your income as you earn or receive it. If you did not pay enough tax on your income throughout the year, you may have to pay installment interest.
Installment interest may be charged if:
- Your total tax is more than $400 (after subtracting withholdings and other credits); and
- You did not pay (by withholdings or estimated payments) at least 80% of your tax liability during the year.
To calculate the amount of interest for the underpayment of estimated tax, complete Form NJ-2210NR, Underpayment of Estimated Tax by Nonresident Individuals. Enter on line 48 the amount from line 19, Form NJ-2210NR, and check the box.
Enclose Form NJ-2210NR with your return.
For more information, see GIT-8, Estimating Income
Taxes.
Line 49 - Total Tax and Penalty
Add lines 47 and 48 and enter the total.
Line 50 - Total New Jersey Income Tax
# Withheld
Enter the total New Jersey Income Tax withheld as shown on all of your W-2s, W-2Gs, and/or 1099s on this line.
Common forms include:
- Form W-2: Box 17 (Box 15 must indicate NJ);
- Form W-2G: Box 15 (Box 13 must indicate NJ);
- Form 1099-R: Box 14 (Box 15 must indicate NJ);
- Form 1099-MISC: Box 16 (Box 17 must indicate
NJ);
- Form 1099-NEC: Box 5 (Box 6 must indicate NJ).
Do not include on this line:
- Tax paid on your behalf by partnership(s). Report these amounts in Part III of Schedule NJ-BUS-1;
- Estimated payments made in connection with a sale or transfer of real property in New Jersey. Report on line 51.
Enclose Forms W-2 and 1099 with your return.
Part-Year Nonresidents. You must determine from your W-2, W-2G, and/or 1099 statement(s) the amount of New Jersey Income Tax withheld from wages you earned or other payments you received while you were a nonresident. If your W-2 includes only wages you earned while you were a nonresident, report the total New Jersey tax withheld on the W-2. If your employer combined your resident and nonresident wages on the W-2, include only tax withheld while you were a nonresident of New Jersey.
Line 51 - New Jersey Estimated Tax
# Payments/Credit From 2024 Tax Return
Include on this line:
- Estimated tax payments made for 2025. Include payments made in connection with the sale or transfer of real property in New Jersey. Enclose a copy of Form GIT/REP-1, Nonresident Seller's Tax Declaration, or GIT/REP-2, Nonresident Seller's Tax Prepayment Receipt, with the return;
- Amount paid with your application for an extension;
- Credit applied from the prior year. This is the amount you chose to carry forward on line 60 of your 2024 NJ-1040NR.
- Payments made by an S corporation on behalf of a nonresident/nonconsenting shareholder. Enclose a copy of Form NJ-1040-SC.
Do not include on this line:
- Prior year refunds;
- Tax paid on your behalf by partnership(s). Report amounts from Schedule NJK-1, Form NJ-1065 in
Part III of Schedule NJ-BUS-1. Report amounts from Schedule NJK-1, Form NJ-1041 on line 52.
Payments Made Under Another Name or Social Security Number. If you changed your name (marriage, divorce, etc.), and you made estimated tax payments using your former name, enclose a statement explaining all the payments you and/or your spouse made for 2025 and the name(s) and Social Security number(s) under which you made payments.
If your spouse died during the year and amounts were paid/credited under both your Social Security numbers, enclose a statement listing the Social Security numbers and the amounts submitted under each.
Part-Year Nonresidents. Enter the amount of estimated payments you made to New Jersey while you were a nonresident. If you made estimated payments both as a resident and as a nonresident, enter only the payments you made to meet your tax liability while you were a nonresident.
Line 52 - Tax Paid on Your Behalf by
# Partnerships
Enter the total amount of New Jersey Income Tax paid on your behalf by partnership(s) as shown on:
- Schedule NJ-BUS-1, Part III, line 5, total share of tax paid on your behalf by partnerships;
- Schedule NJK-1 (Form NJ-1041), Part II, tax paid by partnerships and distributed;
- Schedule NJK-1 (Form NJ-1041), Part III, tax paid by partnerships on behalf of trust.
Enclose a copy of Schedule NJK-1
(Form NJ-1065) for each partnership that paid tax on your behalf, and a copy of Schedule NJK-1
(Form NJ-1041) for each estate or trust that distributed tax paid by partnership(s) to you for which you are claiming a credit.
Lines 53 through 55 - UI/WF/SWF, DI, and FLI Credits
If you had two or more employers and you contributed more than the maximum amount of unemployment insurance (UI)/workforce development partnership fund (WF)/ supplemental workforce fund (SWF) contributions, disability insurance (DI) contributions, and/or family leave insurance (FLI) contributions, you may be able to take credit for the excess withheld.
The maximum employee contributions were:
UI/WF/SWF - $184.02
DI - $380.42
FLI - $545.82
Complete Form NJ-2450 to calculate the excess contributions and report as follows:
Enter on line: Amount from Form NJ-2450:
53 Line 4
54 Line 5
55 Line 6
You must enclose Form NJ-2450 with your return.
If you had only one employer, you must contact that employer for the refund of any amount that was overwithheld. Do not complete Form NJ-2450.
If you had multiple employers but one employer withheld more than the maximum, do not enter more than the maximum amount for that employer on Form NJ-2450.
Any amounts over the maximum that were incorrectly withheld must be refunded by that particular employer.
If we deny your request, you must refile your claim through the Department of Labor and Workforce Development by completing Form UC-9A.
Line 56 - Pass-Through Business
# Alternative Income Tax Credit
Enter your share of tax from Schedule NJ-BUS-1,
Part III, line 6; Schedule NJ-BUS-1, Part IV, line 5; or from Schedule NJK-1 received from an estate or trust.
Enclose Schedule NJ-BUS-1 and a copy of your Schedule PTE-K-1, Schedule
NJK-1 from an estate or trust, NJK-1 from a partnership, and NJ-K-1 from an S corporation with your return.
Line 57 - Total Payments/Credits
Add lines 50 through 56 and enter the total.
Line 58 - Amount You Owe
If line 57 is less than line 49, you have tax due. Subtract line 57 from line 49 and enter the result. If you would like to make a donation to the Charitable Campaigns, continue with lines 61A-61F.
See "How to Pay" on page 31. If you do not file your return or make a payment on time, we may charge you penalties and interest. See page 31.
Note: If the amount on line 58 is more than $400, you may want to increase your estimated payments or contact your employer for Form NJ‑W4 to increase your withholdings.
Line 59 - Overpayment
If line 57 is more than line 49, you have an overpayment.
Subtract line 49 from line 57 and enter the result.
Line 60 - Credit to Your 2026 Tax
Enter the amount of your overpayment that you want to credit to your 2026 tax. This amount will reduce your refund.
Lines 61A through 61F - Charitable
# Contributions
You can make a donation to one or more of the following charities. The amount you donate will reduce your refund or increase your balance due.
To make a donation, check the appropriate box(es) and enter the amount you want to contribute on the corresponding line:
Line 61A - Endangered Wildlife Fund
Line 61B - Children's Trust Fund
Line 61C - Vietnam Veterans' Memorial Fund Line 61D - Breast Cancer Research Fund Line 61E - U.S.S. New Jersey Educational Museum Fund Line 61F - You can donate to one of the following funds on this line. Enter the code number in the boxes provided.
- Drug Abuse Education Fund (01)
- Korean Veterans' Memorial Fund (02)
- Organ and Tissue Donor Awareness Education Fund (03)
- NJ-AIDS Services Fund (04)
- Literacy Volunteers of America - New Jersey Fund (05)
- New Jersey Prostate Cancer Research Fund (06)
- World Trade Center Scholarship Fund (07)
- New Jersey Veterans Haven Support Fund (08)
- Community Food Pantry Fund (09)
- Cat and Dog Spay/Neuter Fund (10)
- New Jersey Lung Cancer Research Fund (11)
- Boys and Girls Clubs in New Jersey Fund (12)
- NJ National Guard State Family Readiness Council Fund (13)
- American Red Cross - NJ Fund (14)
- Girl Scouts Councils in New Jersey Fund (15)
- Homeless Veterans Grant Fund (16)
- Leukemia & Lymphoma Society New Jersey Fund (17)
- Northern New Jersey Veterans Memorial Cemetery Development Fund (18)
- New Jersey Farm to School and School Garden Fund (19)
- Local Library Support Fund (20)
- ALS Association Support Fund (21)
- Fund for the Support of New Jersey Nonprofit Veterans Organizations (22)
- New Jersey Yellow Ribbon Fund (23)
- Autism Programs Fund (24)
- Boy Scouts Councils in New Jersey Fund (25)
- NJ Memorials to War Veterans Maintenance Fund (26)
- Jersey Fresh Program Fund (27)
- NJ World War II Veterans' Memorial Fund (28)
- Meals on Wheels in New Jersey Fund (29)
- New Jersey Pediatric Cancer Research Fund (30)
- Special Olympics New Jersey Fund (31)
- New Jersey Ovarian Cancer Research Fund (32) More information on the charitable funds is available on our website.
Line 62 - Total Adjustments to Tax
# Due/Overpayment
Add lines 60 through 61F and enter the total.
Line 63 - Balance Due
Compare lines 58, 59, and 62 and complete line 63 as follows:
- If you have an amount on line 58, add lines 58 and
62 and enter the total.
- If you have an amount on line 59 but it is less than the amount on line 62, subtract line 59 from line 62 and enter the result.
- If you have no amount on lines 58 and 59 but you have an amount on line 62, enter the amount from line 62.
See "How to Pay" on page 31.
If you do not file your return or make a payment on time, we may charge you penalties and interest. See page 31.
Line 64 - Refund
If you have an amount on line 59, subtract line 62 from line 59 and enter the result.
You must submit your return to claim a refund. If the refund is $1 or less, you must enclose a statement requesting it.
Time Period for Refunds. Generally, you have three years from the date the return was due (including extensions) to request a refund.
Claims Against Your Refund (Set-Off/Offset Programs). Your refund can be used to pay debts you owe to:
- The State of New Jersey, including any of its agencies;
- The Internal Revenue Service;
- Another claimant state/city that has a personal income tax set-off agreement with New Jersey.
If we apply your refund or credit to any debts, we will notify you by mail.
# Disposition of Property
Report your capital gains and income from the sale or exchange of property (both inside and outside New Jersey). You can deduct the expenses of the sale and your basis in the property from the sales price.
In general, when calculating your gain or loss, you will use the cost or adjusted basis that you used for federal purposes. However, in certain situations, you may use a different basis.
- Sale of interest in a partnership, a sole proprietorship, or rental property. You may be required to use a New Jersey adjusted basis.
- Sale of S corporation shares. You must use your
New Jersey adjusted basis.
If you sold or transferred real property in New Jersey and made estimated tax payments in connection with the sale or transfer, include those payments on line 51.
Enclose a copy of Form GIT/REP-1, Nonresident Seller's
Tax Declaration, or GIT/REP-2, Nonresident Seller's Tax
Prepayment Receipt, with the return.
Sale of Principal Residence (Main Home). Capital gain is calculated the same way as for federal purposes. Any amount that is taxable for federal purposes is taxable for New Jersey purposes. For more information on reporting capital gains from the sale of a main home, visit the IRS website.
Installment Sales. You must report all gains from installment sales in the same year as they are reported for federal purposes. If the New Jersey basis is different from the federal basis, you must make a New Jersey installment sale calculation and report the New Jersey gain.
Depreciation and Expense Deduction. New Jersey and federal depreciation and expense deduction limits are different. A New Jersey depreciation adjustment may be required for assets placed in service on or after January 1, 2004. Complete the Gross Income Tax Depreciation Adjustment Worksheet GIT-DEP to calculate the adjustment.
Complete Liquidation. If you had an interest in a partnership, sole proprietorship, or S corporation that sold or disposed of virtually all of its assets in conjunction with the complete liquidation of the entity, you must report your portion of the gain or loss from the sale or disposition of those assets.
Line 65 - List of Transactions
List any reportable transaction(s) as reported on your federal Schedule D, indicating the gain or loss for each transaction in column f. In listing the gain or loss on disposition of rental property, you must take into consideration the New Jersey adjustment from Worksheet GIT-DEP, Part I, line 6.
Do not include gains or losses from the sale of exempt obligations. See GIT-5, Nontaxable Investment Income.
There is no distinction between active and passive losses for New Jersey purposes. You cannot carry back or carry forward such losses when reporting income on Form NJ-1040NR. You can deduct federal passive losses in full in the year incurred against any gain within the same category of income, but only in the year that it occurred.
If you need more space, enclose a statement with the return listing any additional transactions.
Line 66 - Capital Gains Distributions
Enter your capital gains distributions from Form
1099-DIV(s) or similar statement(s). Do not include capital gains from a New Jersey qualified investment fund that are attributable to qualified exempt obligations or gains from mutual funds to the extent attributable to federal obligations. For more information on New Jersey qualified investment funds, see GIT-5, Nontaxable Investment Income.
Line 67 - Other Net Gains
Enter the net gains or income less net losses from disposition of property not included on line 65 or 66 of Part I.
Line 68 - Net Gains
Enter the total of the amounts listed on line 65, column f and lines 66 and 67, netting gains with losses. If the netted amount is a loss, enter "0." Also enter this amount on line 19, column A. On line 19, column B, enter the net gains derived from New Jersey sources. If zero or less, enter "0."
Part-Year Nonresidents. Include only the amounts you received while you were a nonresident of New
Jersey.
Part II: Allocation of Wage and
Salary Income
Complete Part II if you have wage/salary income earned partly inside and partly outside New Jersey and you cannot readily determine the amount that is from New Jersey.
Do not use Part II if your wage/salary income is based on volume (the amount of sales or amount of business transacted). Instead, see the instructions for line 15, column B.
Do not complete Part II if you are a resident of a state that imposes a test similar to New
Jersey's convenience of the employer test.
If you are a resident of a state that imposes a similar test, and you had wage/salary income from a New Jersey employer but worked from an out-of-State location for your own convenience and not for the necessity of the employer, see the instructions for line 15, column B.
Check the box at line 15 if you complete this section.
Line 69 - Amount to be Allocated
Enter the amount reported at line 15, column A, that was earned partly inside and partly outside New Jersey.
Line 70 - Total Days
Full-year nonresidents, enter 365 (366 for leap years).
Part-Year Nonresidents. Enter the number of days for your period of nonresidence.
Line 71 - Nonworking Days
Enter the total number of nonworking days (Saturdays,
Sundays, holidays, sick leave, vacation, etc.) during the tax year covered by this return.
Line 72 - Total Days Worked
Subtract line 71 from line 70 and enter the result. This is the total number of days worked during the tax year covered by this return.
Line 73 - Days Worked Outside New
# Jersey
Enter the number of days worked outside New Jersey during the tax year covered by this return.
Line 74 - Days Worked in New Jersey
Subtract line 73 from line 72 and enter the result. This is the number of days you worked in New Jersey during the tax year covered by this return.
Line 75 - Allocation Factor
Divide line 74 by line 72. The result will be a decimal.
Multiply line 69 by the decimal. Include this amount on line 15, column B.
# Income to New Jersey
Complete Part III if you are required to complete and enclose a Gross Income Tax Business Allocation Schedule (Form NJ-NR-A). This schedule is completed by nonresident individuals, partnerships, estates, and trusts carrying on business both inside and outside New Jersey.
# Signature
Sign and date your return in blue or black ink. Both spouses must sign a joint return. The signature(s) on the form you file must be original; photocopied signatures are not acceptable. We cannot process a return without the proper signatures and will return it to you. This causes unnecessary processing delays and may result in penalties for late filing. If you are filing on behalf of a deceased taxpayer, see "Deceased Taxpayers" on page 33.
# Death Certificate
Check the box below the signature line if you are enclosing a death certificate.
# Paid Tax Preparer Information
Anyone who prepares a return for a fee must sign the return as a "Paid Preparer" and enter their Social Security number or federal preparer tax identification number.
Include the company or corporation name and federal identification number, if applicable. A tax preparer who fails to sign the return or provide a tax identification number may incur a $25 penalty for each omission. Someone who prepares your return but does not charge you should not sign your return.
Preparer Authorization. Division of Taxation personnel cannot discuss your return or enclosures with anyone other than you without your written authorization because of the strict provisions of confidentiality. If you want a Division of Taxation representative to discuss your tax return with the person who signed your return as your "Paid Tax Preparer," check the box above the preparer's signature line to give your permission.
E-File Mandate. Preparers that reasonably expect to prepare 11 or more individual resident Income Tax returns (including those filed for trusts and estates) during the tax year must use electronic methods to file those returns if an electronic filing option is available. A tax preparer is liable for a penalty of $50 for each return they fail to file electronically when required to do so.
# How to Pay
You can make your payment either electronically
(e-check or credit card) or by check or money order. Payments must be postmarked or submitted electronically by April 15, 2026, to avoid penalty and interest charges.
If you are paying a balance due for 2025 and also making an estimated tax payment for 2026, make a separate payment for each transaction. If you owe less than $1, you do not have to make a payment.
Check or Money Order. If you owe tax and are sending the payment with your return, complete a payment voucher (Form NJ-1040NR-V), entering the amount of tax due in the boxes on the voucher. Form NJ-1040NR-V is available on the Division's website.
Make your check or money order payable to State of
New Jersey - TGI. Write your Social Security number on the check or money order. If you are filing a joint return, include both Social Security numbers in the same order the names are listed on the return. Send your payment for the balance due with the voucher in the same envelope with your tax return. (See "Where to Mail Your Return" on page 32.) Electronic Payments. Do not send in the payment voucher if you are paying electronically. When making your payment, you must enter the Social Security number and date of birth of the first person listed on the tax return or your account will not be properly credited.
- Electronic Check (e-check). You can have your payment directly withdrawn from your bank account using our online e-check service. This option is available on our website. If you do not have internet access, you can make an e-check payment by contacting our Customer Service Center or by visiting a Regional Information Center. (See page 45 for phone numbers or addresses.)
- Credit Card (Processing Fees Apply). You can use an American Express, Discover, MasterCard, or Visa credit card to make your payment. This option is available on our website or by phone at 1 (888) 673-7694. You can also pay by credit card by contacting the Division's Customer Service or by visiting a Regional Information Center. (See page 45 for phone numbers or addresses.)
# Penalties, Interest, and Collection Fees
If you do not file your return or make your payment on time, we may charge you the following penalties and interest:
- Late Filing Penalty. When you file a return after the original or extended due date, we will assess a penalty of 5% per month (or part of a month) up to a maximum of 25% on the outstanding tax balance.
You may also be charged a $100 penalty for each month the return is late.
- Late Payment Penalty. When you pay after the filing deadline, you may be charged a 5% penalty on the outstanding balance.
- Interest. We will assess interest at an annual rate of 3% above the prime rate each month (or part of a month) the tax is unpaid. At the end of each calendar year, any tax, penalties, and interest remaining unpaid will become part of the balance on which interest is charged. See Technical Bulletin TB-21(R) for current and previous years' interest rates.
- Collection Fees. In addition, if your tax bill is sent to our collection agency, a referral cost recovery fee of 11% of the tax due will be added to your liability.
If a certificate of debt is issued for your outstanding liability, a fee for the cost of collection of the tax may also be imposed.
# Where to Mail Your Return
Mail your NJ-1040NR, related enclosures, payment voucher, and check or money order for any tax due.
Send only one return per envelope.
Mail Your Return to:
State of New Jersey
Division of Taxation
Revenue Processing Center
PO Box 244
Trenton NJ 08646-0244
Do not staple, paper clip, tape, or use any other fastening device for your return and enclosures.
# Military Personnel
A member of the Armed Forces whose domicile is outside New Jersey does not become a resident of this State when assigned to a duty station in New Jersey.
They are a nonresident for Income Tax purposes.
Income you receive as a nonresident from New Jersey sources other than military pay is taxable. Military pay is not taxable to a nonresident of New Jersey. Do not report military pay in Column A or Column B. Military pensions, mustering-out payments, and subsistence and housing allowances are not taxable and also should not be included.
For a more in-depth discussion of residency status and information on how to stop having New Jersey Income Tax withheld from your military pay, see GIT-6, Part-Year Residents and Nonresidents and GIT-7, Military
Personnel and Families.
Death Related to Duty
When a member of the Armed Forces serving in a combat zone or qualified hazardous duty area dies as a result of wounds, disease, or injury received there, no Income Tax is due for the year the death occurred, or for any earlier years served in the zone or area.
Spouses of Military Personnel
Federal law allows spouses of military personnel to choose the same legal residence as the service member for state and local tax purposes. The spouse does not have to actually live in the state or live with the service member spouse during the year.
If your spouse is a member of the military and you live in New Jersey but choose a different state as your legal residence, you are not subject to tax on wages earned in New Jersey. If you had New Jersey tax withheld in error or made estimated payments, file a New Jersey Nonresident Income Tax Return (Form NJ-1040NR) to get a refund. Enclose a statement explaining why your wages are exempt along with a copy of your spousal military identification card. Print military spouse at the top of the return. To stop New Jersey Income Tax withholding, file Form NJ-165, Employee's Certificate of Nonresidence in New Jersey, with your employer.
All other types of income from New Jersey, such as gain from sale of property located in New Jersey, are taxable. If you had other types of income, you must file a New Jersey nonresident return if required (see chart on page 2). Wages earned in New Jersey by a spouse who lives outside New Jersey also are subject to New Jersey Income Tax. If you live outside New Jersey, you cannot use form NJ-165 to claim an exemption from New Jersey Income Tax withholding on wages earned in this State as the spouse of a servicemember.
For more information on military spouses, see GIT-7,
Military Personnel and Families.
Military Extensions
If you are not able to file on time because of distance, injury, or hospitalization as a result of being on active duty with the Armed Forces of the United States, you will automatically receive a six-month extension by enclosing an explanation when filing the return.
Combat Zone. New Jersey allows extensions of time to file Income Tax returns and pay any tax due for members of the Armed Forces and civilians providing support to the Armed Forces serving in an area that has been declared a "combat zone" by executive order of the President of the United States or a "qualified hazardous duty area" by federal statute.
Once you leave the combat zone or qualified hazardous duty area, you have 180 days to file your tax return and pay tax due.
In addition, if you are hospitalized outside New Jersey as a result of injuries you received while serving in a combat zone or qualified hazardous duty area, you have 180 days from the time you leave the hospital or you leave the combat zone or hazardous duty area, whichever is later.
No interest or penalties will be assessed during a valid extension for service in a combat zone or qualified hazardous duty area. This extension also applies to your spouse if you file a joint return.
Enclose a statement of explanation with your return when you file that includes the reason for the extension.
For more information on military personnel, see GIT-7,
Military Personnel and Families.
# Pennsylvania Residents
As a result of the Reciprocal Personal Income Tax
Agreement between Pennsylvania and New Jersey, compensation paid to Pennsylvania residents employed in New Jersey is not subject to New Jersey Income Tax.
Compensation means salaries, wages, tips, fees, commissions, bonuses, and other remuneration received for services rendered as an employee.
If New Jersey Income Tax was withheld from your wages, you must file a New Jersey nonresident return to get a refund. To stop the withholding of New Jersey Income Tax, complete a New Jersey Employee's Certificate of Nonresidence in New Jersey (Form NJ‑165) and give it to your employer.
The Reciprocal Agreement covers compensation only. If you are self-employed or receive other income (for example, gain from sale of property) that is taxable in both states, you must file a New Jersey nonresident return and report the income received.
Column A. Complete column A, lines 15 through 27, showing income from everywhere.
Column B. When Pennsylvania residents complete column B, employee compensation from New Jersey sources should not be included on line 15. Pennsylvania residents enter "0" on line 15, column B.
Withholdings. If New Jersey Income Tax was withheld, enter the amount from your W-2s on line 50.
Signed Statement. Pennsylvania residents employed in
New Jersey who had New Jersey Income Tax withheld in error must enclose a signed Statement of New Jersey Nonresidency, which is available on our website.
# Deceased Taxpayers
If a person received income in 2025 but died before filing a return, the surviving spouse or personal representative (executor or administrator of an estate or anyone who is in charge of the decedent's personal property) should file the New Jersey return.
Filing Status. Use the same filing status that was used on the final federal income tax return, unless the decedent was a partner in a civil union. (See "Filing Status" on page 4.)
# Name and Address
- Joint return. Write the name and address of the decedent and the surviving spouse in the name and address fields. Print "Deceased" and the date of death above the decedent's name.
- Other filing status. Write the decedent's name in the name field and the personal representative's name and address in the remaining fields. Print "Deceased" and the date of death above the decedent's name.
Exemptions and Deductions. Prorate exemptions and deductions only if the decedent was a New Jersey resident for part of the year and a nonresident for part of the year.
Signatures
- Personal representative. A personal representative filing on behalf of a deceased taxpayer must sign the return in their official capacity. If it is a joint return, the surviving spouse also must sign.
- No personal representative. If filing a return when there is no personal representative for the deceased, the surviving spouse signs the return and writes "Filing as Surviving Spouse" or "Filing as Surviving Civil Union Partner" in the signature section.
- No personal representative and no surviving spouse. If there is no personal representative and there is no surviving spouse, the person in charge of the decedent's property must file and sign the return as "Personal Representative."
If there is a refund due and you want us to issue the check to the decedent's surviving spouse or estate:
- Check the box below the signature line; and
- Enclose a copy of the decedent's death certificate
(if an estate, also include the Surrogate's Short
Certificate).
Income in Respect of a Decedent. If you had the right to receive income that the deceased person would have received had they lived, and the income was not included on the decedent's final return, you must report it on your own return when you receive it. Include the income on line 26 as "Other" income.
# Amended Returns
File an amended return and pay any tax due if:
- You receive an additional tax statement (W-2 or
- You find that you made a mistake on your previously filed return; or
- There are any changes in your federal income tax that affect your New Jersey taxable income. The amended return must be filed within 90 days.
To file an amended nonresident return, complete a new
NJ-1040NR and check the box at the top of the return.
Enclose all supporting documents, schedules, and forms
(W-2, NJK-1, etc.) Do not use Form NJ‑1040X to amend a nonresident return.
# After You Complete the Form
- Do not staple, paper clip, tape, or use any other type of fastening device.
- Check name, address, and Social Security number, for accuracy.
- Send only one return per envelope.
- Enclose all supporting documents, forms, and schedules.
- Keep a copy of your return and all supporting documents, schedules, and worksheets until the statute of limitations has expired for each return. Generally, this is three years after the filing date or two years from the date the tax was paid, whichever is later.
- If you filed your original return and need to make changes or correct mistakes, you must file an amended Form NJ-1040NR.
# Privacy Act Notification
The Division of Taxation uses your Social Security number primarily to account for and give credit for tax payments.
We also use Social Security numbers to administer and enforce all tax laws for which we are responsible.
# Federal/State Tax Agreement
The Division of Taxation and the Internal Revenue Service have entered into a Federal/State Agreement to exchange Income Tax information in order to verify the accuracy and consistency of information reported on federal and New Jersey Income Tax returns.
# Fraudulent Return
You may be liable for a penalty up to $7,500, or imprisonment for three to five years, or both, if you deliberately fail to file a return, file a fraudulent return, or attempt to evade paying your tax.
October 21, 2025 10:04 AM
# 2025 New Jersey Tax Table
Use this table if your New Jersey taxable income on line 39 is less than $100,000. If your taxable income is $100,000 or more, you must use the Tax Rate Schedules on page 44.
Example: Mr. and Mrs. Evans are filing a joint return. They checked filing status "2," married/
CU couple, filing joint return. Their taxable income on line 39 of Form NJ-1040NR is $39,875.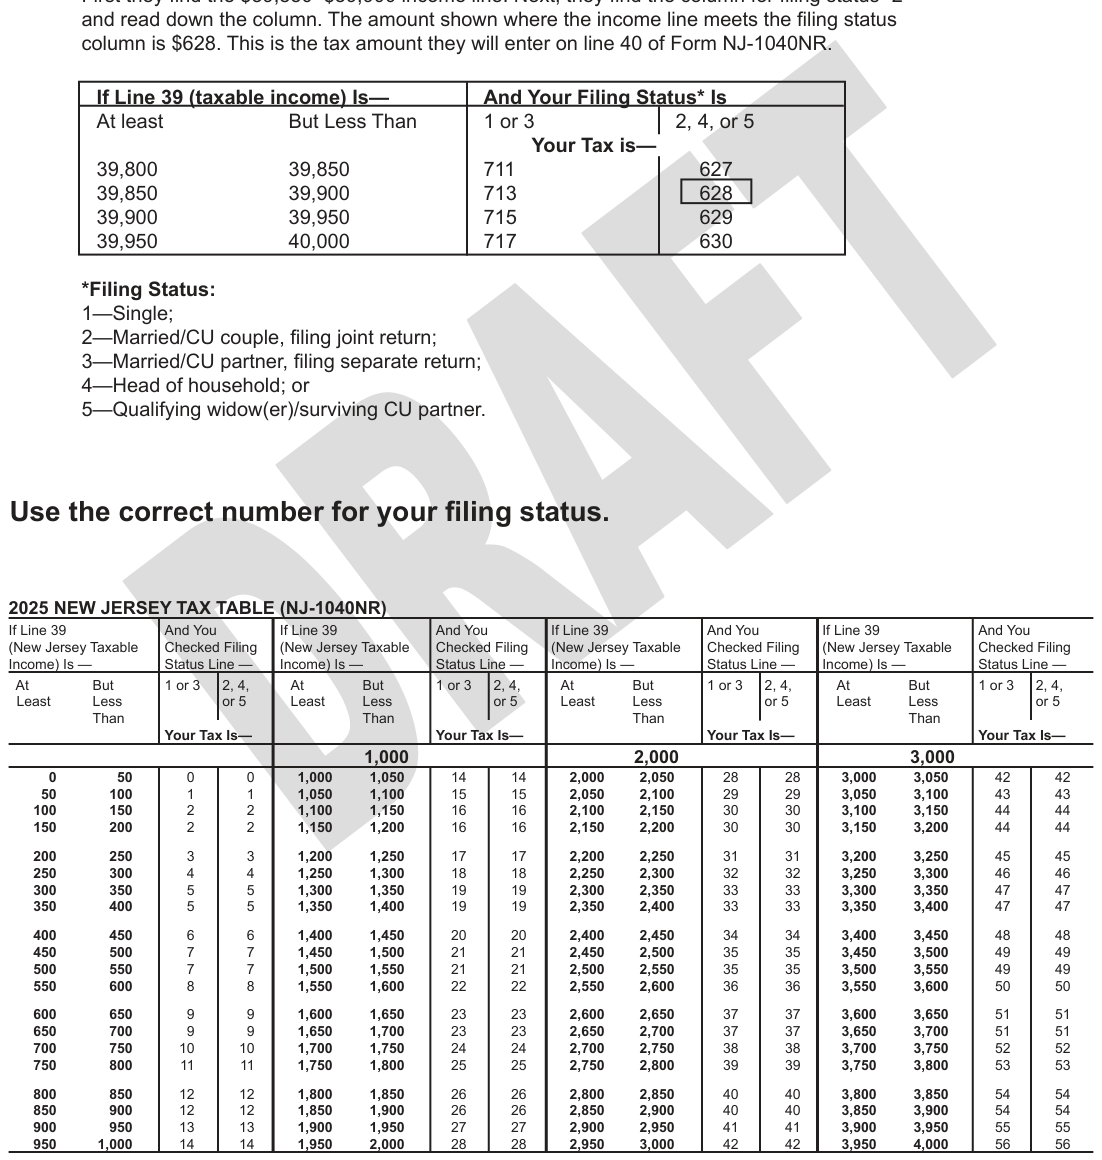
Text version of this table
column is $628. This is the tax amount they will enter on line 40 of Form NJ‑1040NR. If Line 39 (taxable income) Is— And Your Filing Status* Is At least But Less Than 1 or 3 2, 4, or 5 Your Tax is— 39,800 39,850 711 627 39,850 39,900 713 628 39,900 39,950 715 629 39,950 40,000 717 630 *Filing Status: 1—Single; 2—Married/CU couple, filing joint return; 3—Married/CU partner, filing separate return; 4—Head of household; or 5—Qualifying widow(er)/surviving CU partner. Use the correct number for your filing status. 2025 NEW JERSEY TAX TABLE (NJ-1040NR) If Line 39 (New Jersey Taxable Income) Is — And You Checked Filing Status Line — If Line 39 (New Jersey Taxable Income) Is — And You Checked Filing Status Line — If Line 39 (New Jersey Taxable Income) Is — And You Checked Filing Status Line — If Line 39 (New Jersey Taxable Income) Is — And You Checked Filing Status Line — At But Least Less Than 1 or 3 2, 4, or 5 Your Tax Is— At But Least Less Than 1 or 3 2, 4, or 5 Your Tax Is— At But Least Less Than 1 or 3 2, 4, or 5 Your Tax Is— At But Least Less Than 1 or 3 2, 4, or 5 Your Tax Is— 1,000 2,000 3,000 0 50 50 100 100 150 150 200 200 250 250 300 300 350 350 400 400 450 450 500 500 550 550 600 600 650 650 700 700 750 750 800 800 850 850 900 900 950 950 1,000 0 1 2 2 3 4 5 5 6 7 7 8 9 9 10 11 12 12 13 14 0 1 2 2 3 4 5 5 6 7 7 8 9 9 10 11 12 12 13 14 1,000 1,050 1,050 1,100 1,100 1,150 1,150 1,200 1,200 1,250 1,250 1,300 1,300 1,350 1,350 1,400 1,400 1,450 1,450 1,500 1,500 1,550 1,550 1,600 1,600 1,650 1,650 1,700 1,700 1,750 1,750 1,800 1,800 1,850 1,850 1,900 1,900 1,950 1,950 2,000 14 15 16 16 17 18 19 19 20 21 21 22 23 23 24 25 26 26 27 28 14 15 16 16 17 18 19 19 20 21 21 22 23 23 24 25 26 26 27 28 2,000 2,050 2,050 2,100 2,100 2,150 2,150 2,200 2,200 2,250 2,250 2,300 2,300 2,350 2,350 2,400 2,400 2,450 2,450 2,500 2,500 2,550 2,550 2,600 2,600 2,650 2,650 2,700 2,700 2,750 2,750 2,800 2,800 2,850 2,850 2,900 2,900 2,950 2,950 3,000 28 29 30 30 31 32 33 33 34 35 35 36 37 37 38 39 40 40 41 42 28 29 30 30 31 32 33 33 34 35 35 36 37 37 38 39 40 40 41 42 3,000 3,050 3,050 3,100 3,100 3,150 3,150 3,200 3,200 3,250 3,250 3,300 3,300 3,350 3,350 3,400 3,400 3,450 3,450 3,500 3,500 3,550 3,550 3,600 3,600 3,650 3,650 3,700 3,700 3,750 3,750 3,800 3,800 3,850 3,850 3,900 3,900 3,950 3,950 4,000 42 43 44 44 45 46 47 47 48 49 49 50 51 51 52 53 54 54 55 56 42 43 44 44 45 46 47 47 48 49 49 50 51 51 52 53 54 54 55 56
# Use the correct number for your filing status.
# Than Than
# Than Than
# Than Than
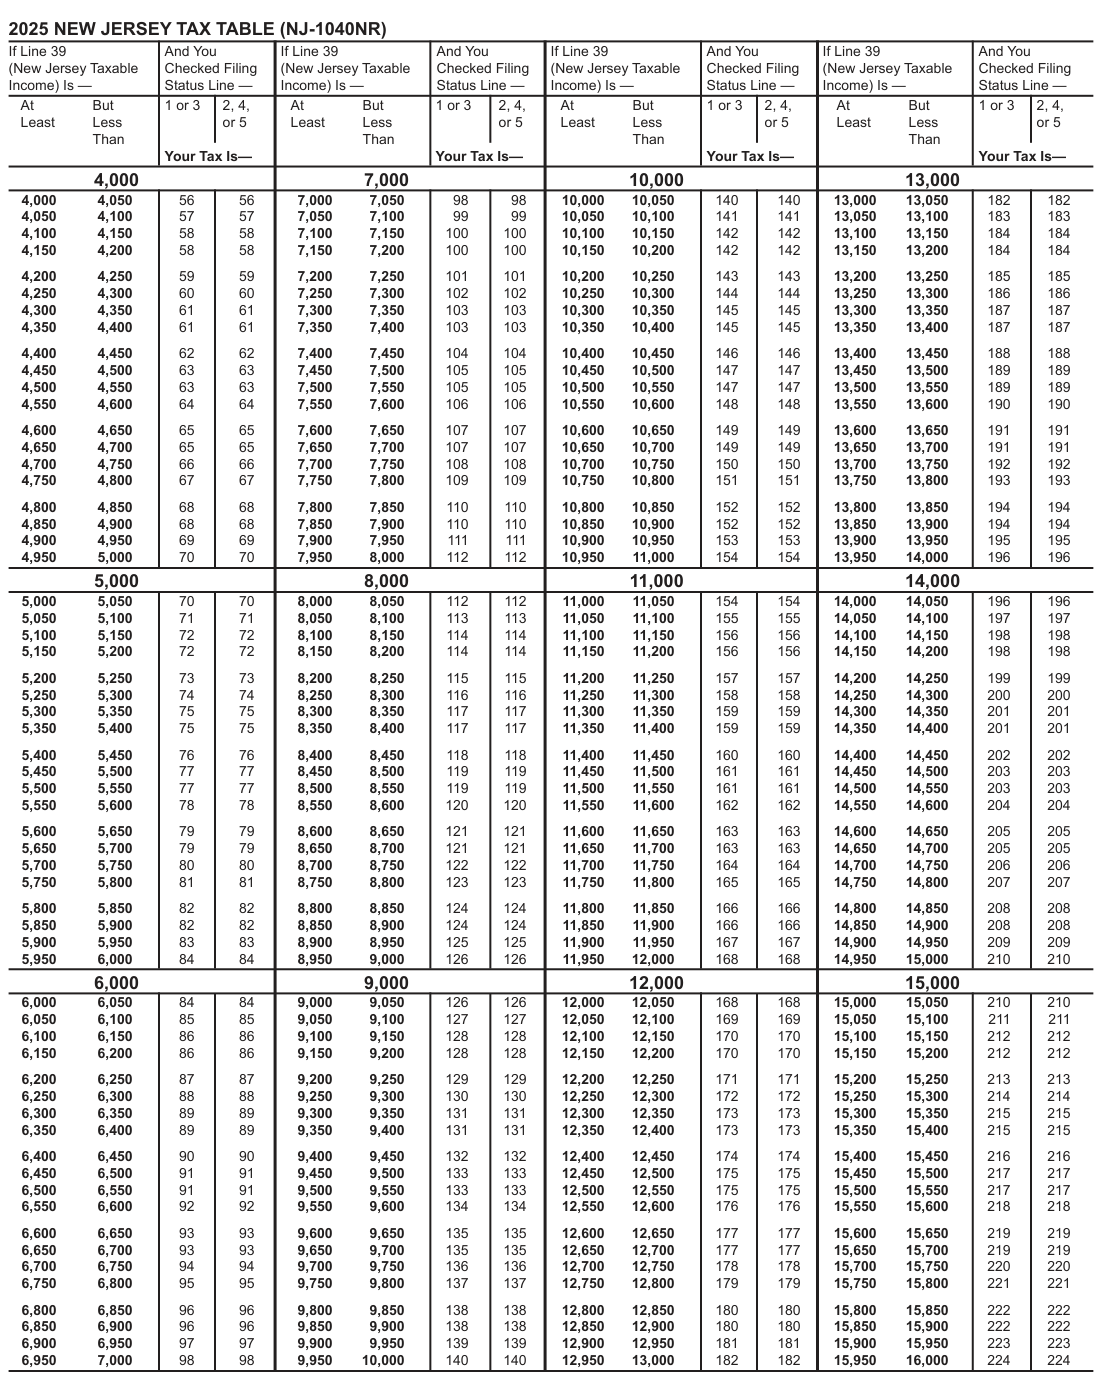
Text version of this table
| If Line 39 (New Jersey Taxable Income) Is — | And You Checked Filing Status Line — | If Line 39 (New Jersey Taxable Income) Is — | And You Checked Filing Status Line — | If Line 39 (New Jersey Taxable Income) Is — | And You Checked Filing Status Line — | If Line 39 (New Jersey Taxable Income) Is — | And You Checked Filing Status Line — | ||||
| At But Least Less Than | 1 or 3 2, 4, or 5 Your Tax Is— | At But Least Less Than | 1 or 3 2, 4, or 5 Your Tax Is— | At But Least Less Than | 1 or 3 2, 4, or 5 Your Tax Is— | At But Least Less Than | 1 or 3 2, 4, or 5 Your Tax Is— | ||||
| 4,000 | 7,000 | 10,000 | 13,000 | ||||||||
| 4,000 4,050 4,050 4,100 4,100 4,150 4,150 4,200 4,200 4,250 4,250 4,300 4,300 4,350 4,350 4,400 4,400 4,450 4,450 4,500 4,500 4,550 4,550 4,600 4,600 4,650 4,650 4,700 4,700 4,750 4,750 4,800 4,800 4,850 4,850 4,900 4,900 4,950 4,950 5,000 | 56 57 58 58 59 60 61 61 62 63 63 64 65 65 66 67 68 68 69 70 | 56 57 58 58 59 60 61 61 62 63 63 64 65 65 66 67 68 68 69 70 | 7,000 7,050 7,050 7,100 7,100 7,150 7,150 7,200 7,200 7,250 7,250 7,300 7,300 7,350 7,350 7,400 7,400 7,450 7,450 7,500 7,500 7,550 7,550 7,600 7,600 7,650 7,650 7,700 7,700 7,750 7,750 7,800 7,800 7,850 7,850 7,900 7,900 7,950 7,950 8,000 | 98 99 100 100 101 102 103 103 104 105 105 106 107 107 108 109 110 110 111 112 | 98 99 100 100 101 102 103 103 104 105 105 106 107 107 108 109 110 110 111 112 | 10,000 10,050 10,050 10,100 10,100 10,150 10,150 10,200 10,200 10,250 10,250 10,300 10,300 10,350 10,350 10,400 10,400 10,450 10,450 10,500 10,500 10,550 10,550 10,600 10,600 10,650 10,650 10,700 10,700 10,750 10,750 10,800 10,800 10,850 10,850 10,900 10,900 10,950 10,950 11,000 | 140 141 142 142 143 144 145 145 146 147 147 148 149 149 150 151 152 152 153 154 | 140 141 142 142 143 144 145 145 146 147 147 148 149 149 150 151 152 152 153 154 | 13,000 13,050 13,050 13,100 13,100 13,150 13,150 13,200 13,200 13,250 13,250 13,300 13,300 13,350 13,350 13,400 13,400 13,450 13,450 13,500 13,500 13,550 13,550 13,600 13,600 13,650 13,650 13,700 13,700 13,750 13,750 13,800 13,800 13,850 13,850 13,900 13,900 13,950 13,950 14,000 | 182 183 184 184 185 186 187 187 188 189 189 190 191 191 192 193 194 194 195 196 | 182 183 184 184 185 186 187 187 188 189 189 190 191 191 192 193 194 194 195 196 |
| 5,000 | 8,000 | 11,000 | 14,000 | ||||||||
| 5,000 5,050 5,050 5,100 5,100 5,150 5,150 5,200 5,200 5,250 5,250 5,300 5,300 5,350 5,350 5,400 5,400 5,450 5,450 5,500 5,500 5,550 5,550 5,600 5,600 5,650 5,650 5,700 5,700 5,750 5,750 5,800 5,800 5,850 5,850 5,900 5,900 5,950 5,950 6,000 | 70 71 72 72 73 74 75 75 76 77 77 78 79 79 80 81 82 82 83 84 | 70 71 72 72 73 74 75 75 76 77 77 78 79 79 80 81 82 82 83 84 | 8,000 8,050 8,050 8,100 8,100 8,150 8,150 8,200 8,200 8,250 8,250 8,300 8,300 8,350 8,350 8,400 8,400 8,450 8,450 8,500 8,500 8,550 8,550 8,600 8,600 8,650 8,650 8,700 8,700 8,750 8,750 8,800 8,800 8,850 8,850 8,900 8,900 8,950 8,950 9,000 | 112 113 114 114 115 116 117 117 118 119 119 120 121 121 122 123 124 124 125 126 | 112 113 114 114 115 116 117 117 118 119 119 120 121 121 122 123 124 124 125 126 | 11,000 11,050 11,050 11,100 11,100 11,150 11,150 11,200 11,200 11,250 11,250 11,300 11,300 11,350 11,350 11,400 11,400 11,450 11,450 11,500 11,500 11,550 11,550 11,600 11,600 11,650 11,650 11,700 11,700 11,750 11,750 11,800 11,800 11,850 11,850 11,900 11,900 11,950 11,950 12,000 | 154 155 156 156 157 158 159 159 160 161 161 162 163 163 164 165 166 166 167 168 | 154 155 156 156 157 158 159 159 160 161 161 162 163 163 164 165 166 166 167 168 | 14,000 14,050 14,050 14,100 14,100 14,150 14,150 14,200 14,200 14,250 14,250 14,300 14,300 14,350 14,350 14,400 14,400 14,450 14,450 14,500 14,500 14,550 14,550 14,600 14,600 14,650 14,650 14,700 14,700 14,750 14,750 14,800 14,800 14,850 14,850 14,900 14,900 14,950 14,950 15,000 | 196 197 198 198 199 200 201 201 202 203 203 204 205 205 206 207 208 208 209 210 | 196 197 198 198 199 200 201 201 202 203 203 204 205 205 206 207 208 208 209 210 |
| 6,000 | 9,000 | 12,000 | 15,000 | ||||||||
| 6,000 6,050 6,050 6,100 6,100 6,150 6,150 6,200 6,200 6,250 6,250 6,300 6,300 6,350 6,350 6,400 6,400 6,450 6,450 6,500 6,500 6,550 6,550 6,600 6,600 6,650 6,650 6,700 6,700 6,750 6,750 6,800 6,800 6,850 6,850 6,900 6,900 6,950 6,950 7,000 | 84 85 86 86 87 88 89 89 90 91 91 92 93 93 94 95 96 96 97 98 | 84 85 86 86 87 88 89 89 90 91 91 92 93 93 94 95 96 96 97 98 | 9,000 9,050 9,050 9,100 9,100 9,150 9,150 9,200 9,200 9,250 9,250 9,300 9,300 9,350 9,350 9,400 9,400 9,450 9,450 9,500 9,500 9,550 9,550 9,600 9,600 9,650 9,650 9,700 9,700 9,750 9,750 9,800 9,800 9,850 9,850 9,900 9,900 9,950 9,950 10,000 | 126 127 128 128 129 130 131 131 132 133 133 134 135 135 136 137 138 138 139 140 | 126 127 128 128 129 130 131 131 132 133 133 134 135 135 136 137 138 138 139 140 | 12,000 12,050 12,050 12,100 12,100 12,150 12,150 12,200 12,200 12,250 12,250 12,300 12,300 12,350 12,350 12,400 12,400 12,450 12,450 12,500 12,500 12,550 12,550 12,600 12,600 12,650 12,650 12,700 12,700 12,750 12,750 12,800 12,800 12,850 12,850 12,900 12,900 12,950 12,950 13,000 | 168 169 170 170 171 172 173 173 174 175 175 176 177 177 178 179 180 180 181 182 | 168 169 170 170 171 172 173 173 174 175 175 176 177 177 178 179 180 180 181 182 | 15,000 15,050 15,050 15,100 15,100 15,150 15,150 15,200 15,200 15,250 15,250 15,300 15,300 15,350 15,350 15,400 15,400 15,450 15,450 15,500 15,500 15,550 15,550 15,600 15,600 15,650 15,650 15,700 15,700 15,750 15,750 15,800 15,800 15,850 15,850 15,900 15,900 15,950 15,950 16,000 | 210 211 212 212 213 214 215 215 216 217 217 218 219 219 220 221 222 222 223 224 | 210 211 212 212 213 214 215 215 216 217 217 218 219 219 220 221 222 222 223 224 |
# Than Than
# Than Than
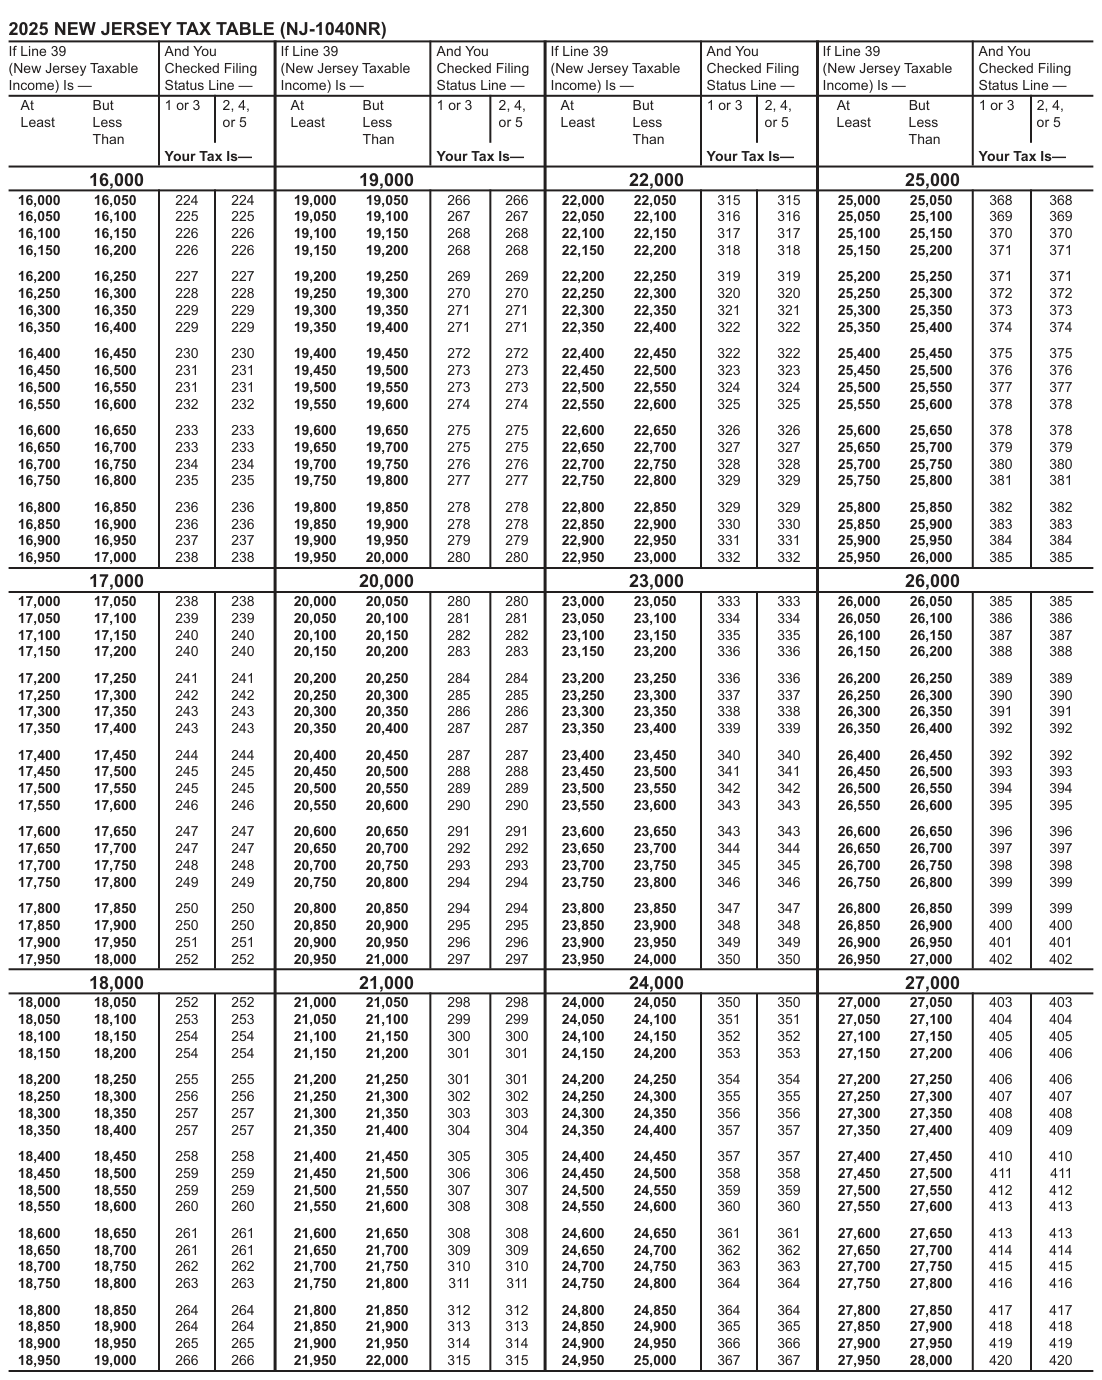
Text version of this table
| If Line 39 (New Jersey Taxable Income) Is — | And You Checked Filing Status Line — | If Line 39 (New Jersey Taxable Income) Is — | And You Checked Filing Status Line — | If Line 39 (New Jersey Taxable Income) Is — | And You Checked Filing Status Line — | If Line 39 (New Jersey Taxable Income) Is — | And You Checked Filing Status Line — | ||||
| At But Least Less Than | 1 or 3 2, 4, or 5 Your Tax Is— | At But Least Less Than | 1 or 3 2, 4, or 5 Your Tax Is— | At But Least Less Than | 1 or 3 2, 4, or 5 Your Tax Is— | At But Least Less Than | 1 or 3 2, 4, or 5 Your Tax Is— | ||||
| 16,000 | 19,000 | 22,000 | 25,000 | ||||||||
| 16,000 16,050 16,050 16,100 16,100 16,150 16,150 16,200 16,200 16,250 16,250 16,300 16,300 16,350 16,350 16,400 16,400 16,450 16,450 16,500 16,500 16,550 16,550 16,600 16,600 16,650 16,650 16,700 16,700 16,750 16,750 16,800 16,800 16,850 16,850 16,900 16,900 16,950 16,950 17,000 | 224 225 226 226 227 228 229 229 230 231 231 232 233 233 234 235 236 236 237 238 | 224 225 226 226 227 228 229 229 230 231 231 232 233 233 234 235 236 236 237 238 | 19,000 19,050 19,050 19,100 19,100 19,150 19,150 19,200 19,200 19,250 19,250 19,300 19,300 19,350 19,350 19,400 19,400 19,450 19,450 19,500 19,500 19,550 19,550 19,600 19,600 19,650 19,650 19,700 19,700 19,750 19,750 19,800 19,800 19,850 19,850 19,900 19,900 19,950 19,950 20,000 | 266 267 268 268 269 270 271 271 272 273 273 274 275 275 276 277 278 278 279 280 | 266 267 268 268 269 270 271 271 272 273 273 274 275 275 276 277 278 278 279 280 | 22,000 22,050 22,050 22,100 22,100 22,150 22,150 22,200 22,200 22,250 22,250 22,300 22,300 22,350 22,350 22,400 22,400 22,450 22,450 22,500 22,500 22,550 22,550 22,600 22,600 22,650 22,650 22,700 22,700 22,750 22,750 22,800 22,800 22,850 22,850 22,900 22,900 22,950 22,950 23,000 | 315 316 317 318 319 320 321 322 322 323 324 325 326 327 328 329 329 330 331 332 | 315 316 317 318 319 320 321 322 322 323 324 325 326 327 328 329 329 330 331 332 | 25,000 25,050 25,050 25,100 25,100 25,150 25,150 25,200 25,200 25,250 25,250 25,300 25,300 25,350 25,350 25,400 25,400 25,450 25,450 25,500 25,500 25,550 25,550 25,600 25,600 25,650 25,650 25,700 25,700 25,750 25,750 25,800 25,800 25,850 25,850 25,900 25,900 25,950 25,950 26,000 | 368 369 370 371 371 372 373 374 375 376 377 378 378 379 380 381 382 383 384 385 | 368 369 370 371 371 372 373 374 375 376 377 378 378 379 380 381 382 383 384 385 |
| 17,000 | 20,000 | 23,000 | 26,000 | ||||||||
| 17,000 17,050 17,050 17,100 17,100 17,150 17,150 17,200 17,200 17,250 17,250 17,300 17,300 17,350 17,350 17,400 17,400 17,450 17,450 17,500 17,500 17,550 17,550 17,600 17,600 17,650 17,650 17,700 17,700 17,750 17,750 17,800 17,800 17,850 17,850 17,900 17,900 17,950 17,950 18,000 | 238 239 240 240 241 242 243 243 244 245 245 246 247 247 248 249 250 250 251 252 | 238 239 240 240 241 242 243 243 244 245 245 246 247 247 248 249 250 250 251 252 | 20,000 20,050 20,050 20,100 20,100 20,150 20,150 20,200 20,200 20,250 20,250 20,300 20,300 20,350 20,350 20,400 20,400 20,450 20,450 20,500 20,500 20,550 20,550 20,600 20,600 20,650 20,650 20,700 20,700 20,750 20,750 20,800 20,800 20,850 20,850 20,900 20,900 20,950 20,950 21,000 | 280 281 282 283 284 285 286 287 287 288 289 290 291 292 293 294 294 295 296 297 | 280 281 282 283 284 285 286 287 287 288 289 290 291 292 293 294 294 295 296 297 | 23,000 23,050 23,050 23,100 23,100 23,150 23,150 23,200 23,200 23,250 23,250 23,300 23,300 23,350 23,350 23,400 23,400 23,450 23,450 23,500 23,500 23,550 23,550 23,600 23,600 23,650 23,650 23,700 23,700 23,750 23,750 23,800 23,800 23,850 23,850 23,900 23,900 23,950 23,950 24,000 | 333 334 335 336 336 337 338 339 340 341 342 343 343 344 345 346 347 348 349 350 | 333 334 335 336 336 337 338 339 340 341 342 343 343 344 345 346 347 348 349 350 | 26,000 26,050 26,050 26,100 26,100 26,150 26,150 26,200 26,200 26,250 26,250 26,300 26,300 26,350 26,350 26,400 26,400 26,450 26,450 26,500 26,500 26,550 26,550 26,600 26,600 26,650 26,650 26,700 26,700 26,750 26,750 26,800 26,800 26,850 26,850 26,900 26,900 26,950 26,950 27,000 | 385 386 387 388 389 390 391 392 392 393 394 395 396 397 398 399 399 400 401 402 | 385 386 387 388 389 390 391 392 392 393 394 395 396 397 398 399 399 400 401 402 |
| 18,000 | 21,000 | 24,000 | 27,000 | ||||||||
| 18,000 18,050 18,050 18,100 18,100 18,150 18,150 18,200 18,200 18,250 18,250 18,300 18,300 18,350 18,350 18,400 18,400 18,450 18,450 18,500 18,500 18,550 18,550 18,600 18,600 18,650 18,650 18,700 18,700 18,750 18,750 18,800 18,800 18,850 18,850 18,900 18,900 18,950 18,950 19,000 | 252 253 254 254 255 256 257 257 258 259 259 260 261 261 262 263 264 264 265 266 | 252 253 254 254 255 256 257 257 258 259 259 260 261 261 262 263 264 264 265 266 | 21,000 21,050 21,050 21,100 21,100 21,150 21,150 21,200 21,200 21,250 21,250 21,300 21,300 21,350 21,350 21,400 21,400 21,450 21,450 21,500 21,500 21,550 21,550 21,600 21,600 21,650 21,650 21,700 21,700 21,750 21,750 21,800 21,800 21,850 21,850 21,900 21,900 21,950 21,950 22,000 | 298 299 300 301 301 302 303 304 305 306 307 308 308 309 310 311 312 313 314 315 | 298 299 300 301 301 302 303 304 305 306 307 308 308 309 310 311 312 313 314 315 | 24,000 24,050 24,050 24,100 24,100 24,150 24,150 24,200 24,200 24,250 24,250 24,300 24,300 24,350 24,350 24,400 24,400 24,450 24,450 24,500 24,500 24,550 24,550 24,600 24,600 24,650 24,650 24,700 24,700 24,750 24,750 24,800 24,800 24,850 24,850 24,900 24,900 24,950 24,950 25,000 | 350 351 352 353 354 355 356 357 357 358 359 360 361 362 363 364 364 365 366 367 | 350 351 352 353 354 355 356 357 357 358 359 360 361 362 363 364 364 365 366 367 | 27,000 27,050 27,050 27,100 27,100 27,150 27,150 27,200 27,200 27,250 27,250 27,300 27,300 27,350 27,350 27,400 27,400 27,450 27,450 27,500 27,500 27,550 27,550 27,600 27,600 27,650 27,650 27,700 27,700 27,750 27,750 27,800 27,800 27,850 27,850 27,900 27,900 27,950 27,950 28,000 | 403 404 405 406 406 407 408 409 410 411 412 413 413 414 415 416 417 418 419 420 | 403 404 405 406 406 407 408 409 410 411 412 413 413 414 415 416 417 418 419 420 |
# Than Than
# Than Than
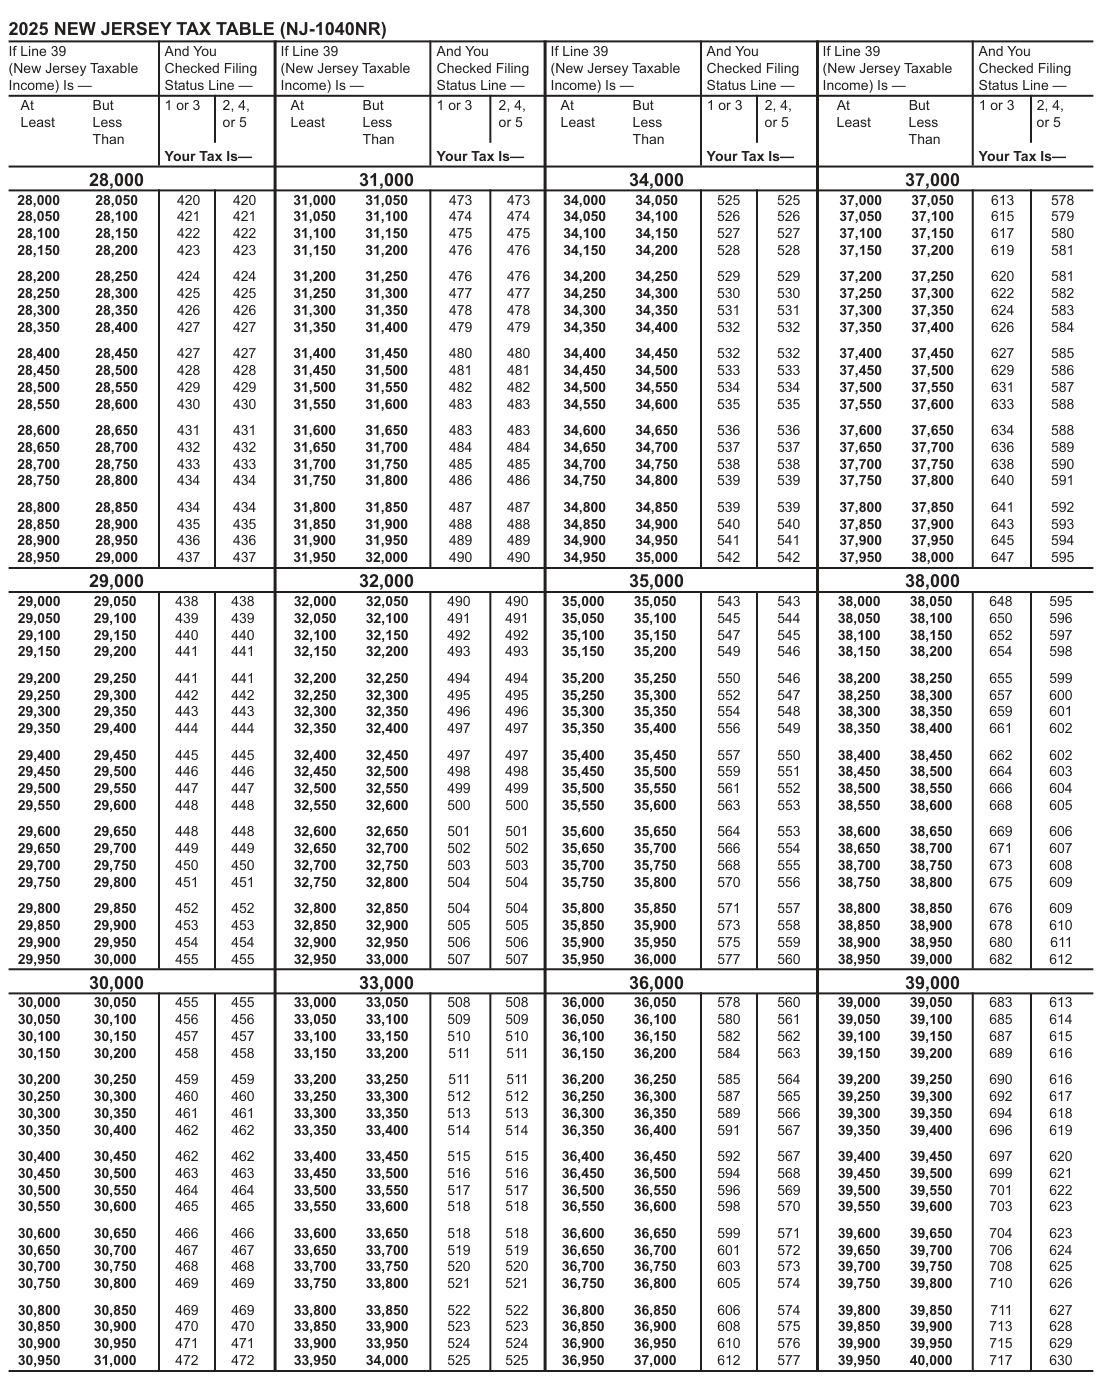
Text version of this table
| If Line 39 (New Jersey Taxable Income) Is — | And You Checked Filing Status Line — | If Line 39 (New Jersey Taxable Income) Is — | And You Checked Filing Status Line — | If Line 39 (New Jersey Taxable Income) Is — | And You Checked Filing Status Line — | If Line 39 (New Jersey Taxable Income) Is — | And You Checked Filing Status Line — | ||||
| At But Least Less Than | 1 or 3 2, 4, or 5 Your Tax Is— | At But Least Less Than | 1 or 3 2, 4, or 5 Your Tax Is— | At But Least Less Than | 1 or 3 2, 4, or 5 Your Tax Is— | At But Least Less Than | 1 or 3 2, 4, or 5 Your Tax Is— | ||||
| 28,000 | 31,000 | 34,000 | 37,000 | ||||||||
| 28,000 28,050 28,050 28,100 28,100 28,150 28,150 28,200 28,200 28,250 28,250 28,300 28,300 28,350 28,350 28,400 28,400 28,450 28,450 28,500 28,500 28,550 28,550 28,600 28,600 28,650 28,650 28,700 28,700 28,750 28,750 28,800 28,800 28,850 28,850 28,900 28,900 28,950 28,950 29,000 | 420 421 422 423 424 425 426 427 427 428 429 430 431 432 433 434 434 435 436 437 | 420 421 422 423 424 425 426 427 427 428 429 430 431 432 433 434 434 435 436 437 | 31,000 31,050 31,050 31,100 31,100 31,150 31,150 31,200 31,200 31,250 31,250 31,300 31,300 31,350 31,350 31,400 31,400 31,450 31,450 31,500 31,500 31,550 31,550 31,600 31,600 31,650 31,650 31,700 31,700 31,750 31,750 31,800 31,800 31,850 31,850 31,900 31,900 31,950 31,950 32,000 | 473 474 475 476 476 477 478 479 480 481 482 483 483 484 485 486 487 488 489 490 | 473 474 475 476 476 477 478 479 480 481 482 483 483 484 485 486 487 488 489 490 | 34,000 34,050 34,050 34,100 34,100 34,150 34,150 34,200 34,200 34,250 34,250 34,300 34,300 34,350 34,350 34,400 34,400 34,450 34,450 34,500 34,500 34,550 34,550 34,600 34,600 34,650 34,650 34,700 34,700 34,750 34,750 34,800 34,800 34,850 34,850 34,900 34,900 34,950 34,950 35,000 | 525 526 527 528 529 530 531 532 532 533 534 535 536 537 538 539 539 540 541 542 | 525 526 527 528 529 530 531 532 532 533 534 535 536 537 538 539 539 540 541 542 | 37,000 37,050 37,050 37,100 37,100 37,150 37,150 37,200 37,200 37,250 37,250 37,300 37,300 37,350 37,350 37,400 37,400 37,450 37,450 37,500 37,500 37,550 37,550 37,600 37,600 37,650 37,650 37,700 37,700 37,750 37,750 37,800 37,800 37,850 37,850 37,900 37,900 37,950 37,950 38,000 | 613 615 617 619 620 622 624 626 627 629 631 633 634 636 638 640 641 643 645 647 | 578 579 580 581 581 582 583 584 585 586 587 588 588 589 590 591 592 593 594 595 |
| 29,000 | 32,000 | 35,000 | 38,000 | ||||||||
| 29,000 29,050 29,050 29,100 29,100 29,150 29,150 29,200 29,200 29,250 29,250 29,300 29,300 29,350 29,350 29,400 29,400 29,450 29,450 29,500 29,500 29,550 29,550 29,600 29,600 29,650 29,650 29,700 29,700 29,750 29,750 29,800 29,800 29,850 29,850 29,900 29,900 29,950 29,950 30,000 | 438 439 440 441 441 442 443 444 445 446 447 448 448 449 450 451 452 453 454 455 | 438 439 440 441 441 442 443 444 445 446 447 448 448 449 450 451 452 453 454 455 | 32,000 32,050 32,050 32,100 32,100 32,150 32,150 32,200 32,200 32,250 32,250 32,300 32,300 32,350 32,350 32,400 32,400 32,450 32,450 32,500 32,500 32,550 32,550 32,600 32,600 32,650 32,650 32,700 32,700 32,750 32,750 32,800 32,800 32,850 32,850 32,900 32,900 32,950 32,950 33,000 | 490 491 492 493 494 495 496 497 497 498 499 500 501 502 503 504 504 505 506 507 | 490 491 492 493 494 495 496 497 497 498 499 500 501 502 503 504 504 505 506 507 | 35,000 35,050 35,050 35,100 35,100 35,150 35,150 35,200 35,200 35,250 35,250 35,300 35,300 35,350 35,350 35,400 35,400 35,450 35,450 35,500 35,500 35,550 35,550 35,600 35,600 35,650 35,650 35,700 35,700 35,750 35,750 35,800 35,800 35,850 35,850 35,900 35,900 35,950 35,950 36,000 | 543 545 547 549 550 552 554 556 557 559 561 563 564 566 568 570 571 573 575 577 | 543 544 545 546 546 547 548 549 550 551 552 553 553 554 555 556 557 558 559 560 | 38,000 38,050 38,050 38,100 38,100 38,150 38,150 38,200 38,200 38,250 38,250 38,300 38,300 38,350 38,350 38,400 38,400 38,450 38,450 38,500 38,500 38,550 38,550 38,600 38,600 38,650 38,650 38,700 38,700 38,750 38,750 38,800 38,800 38,850 38,850 38,900 38,900 38,950 38,950 39,000 | 648 650 652 654 655 657 659 661 662 664 666 668 669 671 673 675 676 678 680 682 | 595 596 597 598 599 600 601 602 602 603 604 605 606 607 608 609 609 610 611 612 |
| 30,000 | 33,000 | 36,000 | 39,000 | ||||||||
| 30,000 30,050 30,050 30,100 30,100 30,150 30,150 30,200 30,200 30,250 30,250 30,300 30,300 30,350 30,350 30,400 30,400 30,450 30,450 30,500 30,500 30,550 30,550 30,600 30,600 30,650 30,650 30,700 30,700 30,750 30,750 30,800 30,800 30,850 30,850 30,900 30,900 30,950 30,950 31,000 | 455 456 457 458 459 460 461 462 462 463 464 465 466 467 468 469 469 470 471 472 | 455 456 457 458 459 460 461 462 462 463 464 465 466 467 468 469 469 470 471 472 | 33,000 33,050 33,050 33,100 33,100 33,150 33,150 33,200 33,200 33,250 33,250 33,300 33,300 33,350 33,350 33,400 33,400 33,450 33,450 33,500 33,500 33,550 33,550 33,600 33,600 33,650 33,650 33,700 33,700 33,750 33,750 33,800 33,800 33,850 33,850 33,900 33,900 33,950 33,950 34,000 | 508 509 510 511 511 512 513 514 515 516 517 518 518 519 520 521 522 523 524 525 | 508 509 510 511 511 512 513 514 515 516 517 518 518 519 520 521 522 523 524 525 | 36,000 36,050 36,050 36,100 36,100 36,150 36,150 36,200 36,200 36,250 36,250 36,300 36,300 36,350 36,350 36,400 36,400 36,450 36,450 36,500 36,500 36,550 36,550 36,600 36,600 36,650 36,650 36,700 36,700 36,750 36,750 36,800 36,800 36,850 36,850 36,900 36,900 36,950 36,950 37,000 | 578 580 582 584 585 587 589 591 592 594 596 598 599 601 603 605 606 608 610 612 | 560 561 562 563 564 565 566 567 567 568 569 570 571 572 573 574 574 575 576 577 | 39,000 39,050 39,050 39,100 39,100 39,150 39,150 39,200 39,200 39,250 39,250 39,300 39,300 39,350 39,350 39,400 39,400 39,450 39,450 39,500 39,500 39,550 39,550 39,600 39,600 39,650 39,650 39,700 39,700 39,750 39,750 39,800 39,800 39,850 39,850 39,900 39,900 39,950 39,950 40,000 | 683 685 687 689 690 692 694 696 697 699 701 703 704 706 708 710 711 713 715 717 | 613 614 615 616 616 617 618 619 620 621 622 623 623 624 625 626 627 628 629 630 |
# Than Than
# Than Than
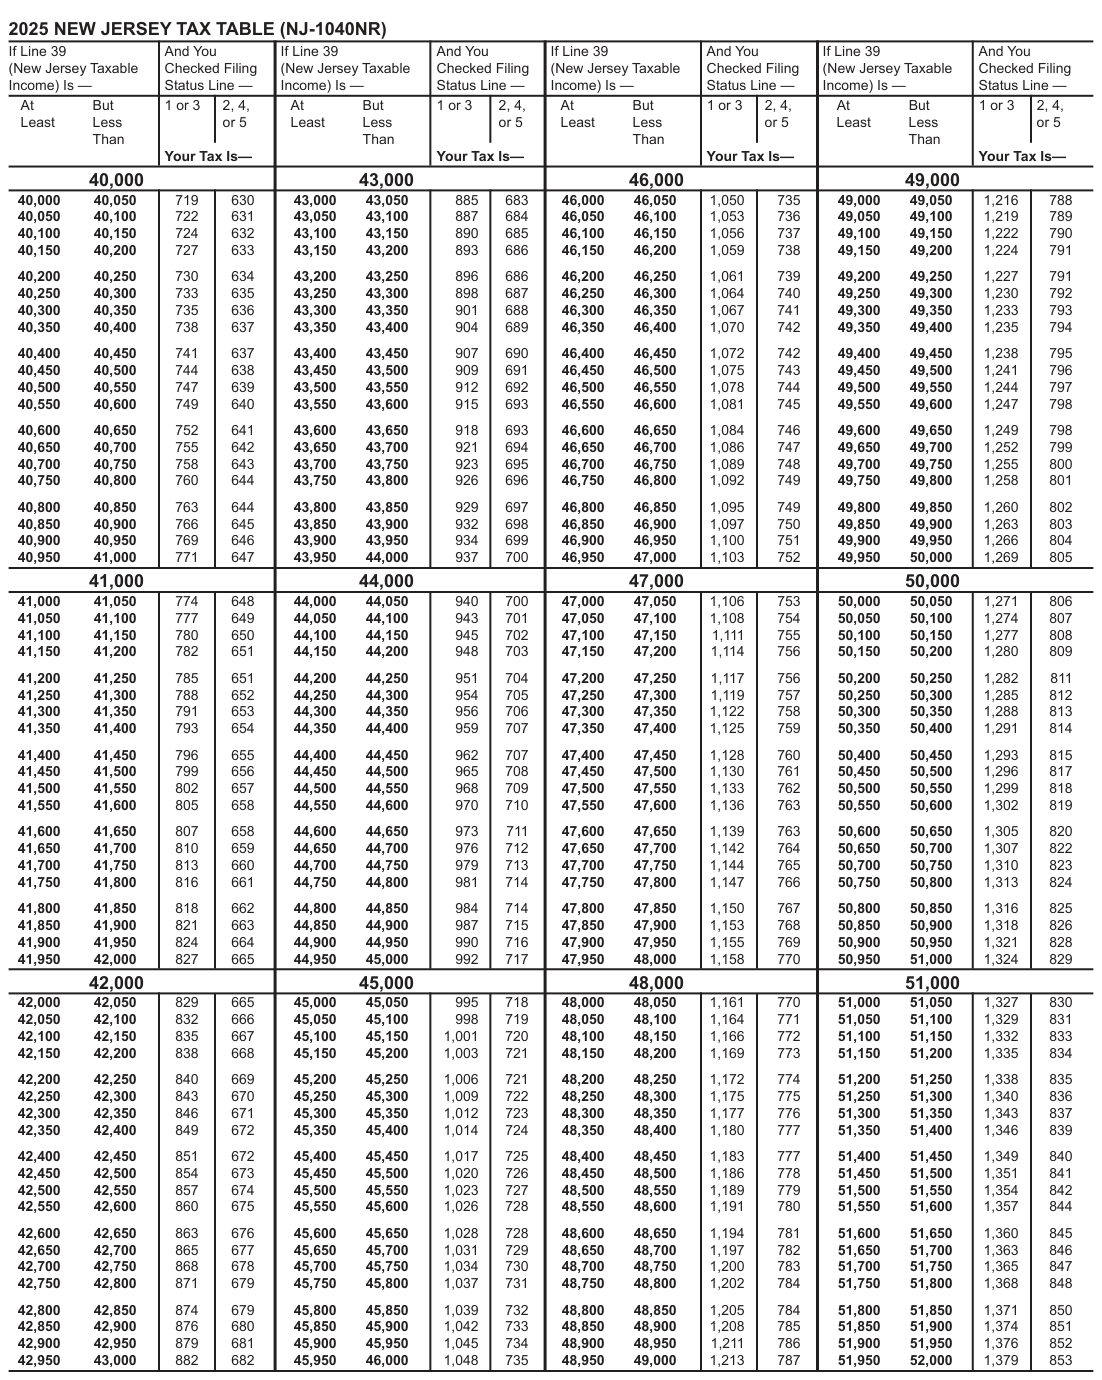
Text version of this table
| If Line 39 (New Jersey Taxable Income) Is — | And You Checked Filing Status Line — | If Line 39 (New Jersey Taxable Income) Is — | And You Checked Filing Status Line — | If Line 39 (New Jersey Taxable Income) Is — | And You Checked Filing Status Line — | If Line 39 (New Jersey Taxable Income) Is — | And You Checked Filing Status Line — | ||||
| At But Least Less Than | 1 or 3 2, 4, or 5 Your Tax Is— | At But Least Less Than | 1 or 3 2, 4, or 5 Your Tax Is— | At But Least Less Than | 1 or 3 2, 4, or 5 Your Tax Is— | At But Least Less Than | 1 or 3 2, 4, or 5 Your Tax Is— | ||||
| 40,000 | 43,000 | 46,000 | 49,000 | ||||||||
| 40,000 40,050 40,050 40,100 40,100 40,150 40,150 40,200 40,200 40,250 40,250 40,300 40,300 40,350 40,350 40,400 40,400 40,450 40,450 40,500 40,500 40,550 40,550 40,600 40,600 40,650 40,650 40,700 40,700 40,750 40,750 40,800 40,800 40,850 40,850 40,900 40,900 40,950 40,950 41,000 | 719 722 724 727 730 733 735 738 741 744 747 749 752 755 758 760 763 766 769 771 | 630 631 632 633 634 635 636 637 637 638 639 640 641 642 643 644 644 645 646 647 | 43,000 43,050 43,050 43,100 43,100 43,150 43,150 43,200 43,200 43,250 43,250 43,300 43,300 43,350 43,350 43,400 43,400 43,450 43,450 43,500 43,500 43,550 43,550 43,600 43,600 43,650 43,650 43,700 43,700 43,750 43,750 43,800 43,800 43,850 43,850 43,900 43,900 43,950 43,950 44,000 | 885 887 890 893 896 898 901 904 907 909 912 915 918 921 923 926 929 932 934 937 | 683 684 685 686 686 687 688 689 690 691 692 693 693 694 695 696 697 698 699 700 | 46,000 46,050 46,050 46,100 46,100 46,150 46,150 46,200 46,200 46,250 46,250 46,300 46,300 46,350 46,350 46,400 46,400 46,450 46,450 46,500 46,500 46,550 46,550 46,600 46,600 46,650 46,650 46,700 46,700 46,750 46,750 46,800 46,800 46,850 46,850 46,900 46,900 46,950 46,950 47,000 | 1,050 1,053 1,056 1,059 1,061 1,064 1,067 1,070 1,072 1,075 1,078 1,081 1,084 1,086 1,089 1,092 1,095 1,097 1,100 1,103 | 735 736 737 738 739 740 741 742 742 743 744 745 746 747 748 749 749 750 751 752 | 49,000 49,050 49,050 49,100 49,100 49,150 49,150 49,200 49,200 49,250 49,250 49,300 49,300 49,350 49,350 49,400 49,400 49,450 49,450 49,500 49,500 49,550 49,550 49,600 49,600 49,650 49,650 49,700 49,700 49,750 49,750 49,800 49,800 49,850 49,850 49,900 49,900 49,950 49,950 50,000 | 1,216 1,219 1,222 1,224 1,227 1,230 1,233 1,235 1,238 1,241 1,244 1,247 1,249 1,252 1,255 1,258 1,260 1,263 1,266 1,269 | 788 789 790 791 791 792 793 794 795 796 797 798 798 799 800 801 802 803 804 805 |
| 41,000 | 44,000 | 47,000 | 50,000 | ||||||||
| 41,000 41,050 41,050 41,100 41,100 41,150 41,150 41,200 41,200 41,250 41,250 41,300 41,300 41,350 41,350 41,400 41,400 41,450 41,450 41,500 41,500 41,550 41,550 41,600 41,600 41,650 41,650 41,700 41,700 41,750 41,750 41,800 41,800 41,850 41,850 41,900 41,900 41,950 41,950 42,000 | 774 777 780 782 785 788 791 793 796 799 802 805 807 810 813 816 818 821 824 827 | 648 649 650 651 651 652 653 654 655 656 657 658 658 659 660 661 662 663 664 665 | 44,000 44,050 44,050 44,100 44,100 44,150 44,150 44,200 44,200 44,250 44,250 44,300 44,300 44,350 44,350 44,400 44,400 44,450 44,450 44,500 44,500 44,550 44,550 44,600 44,600 44,650 44,650 44,700 44,700 44,750 44,750 44,800 44,800 44,850 44,850 44,900 44,900 44,950 44,950 45,000 | 940 943 945 948 951 954 956 959 962 965 968 970 973 976 979 981 984 987 990 992 | 700 701 702 703 704 705 706 707 707 708 709 710 711 712 713 714 714 715 716 717 | 47,000 47,050 47,050 47,100 47,100 47,150 47,150 47,200 47,200 47,250 47,250 47,300 47,300 47,350 47,350 47,400 47,400 47,450 47,450 47,500 47,500 47,550 47,550 47,600 47,600 47,650 47,650 47,700 47,700 47,750 47,750 47,800 47,800 47,850 47,850 47,900 47,900 47,950 47,950 48,000 | 1,106 1,108 1,111 1,114 1,117 1,119 1,122 1,125 1,128 1,130 1,133 1,136 1,139 1,142 1,144 1,147 1,150 1,153 1,155 1,158 | 753 754 755 756 756 757 758 759 760 761 762 763 763 764 765 766 767 768 769 770 | 50,000 50,050 50,050 50,100 50,100 50,150 50,150 50,200 50,200 50,250 50,250 50,300 50,300 50,350 50,350 50,400 50,400 50,450 50,450 50,500 50,500 50,550 50,550 50,600 50,600 50,650 50,650 50,700 50,700 50,750 50,750 50,800 50,800 50,850 50,850 50,900 50,900 50,950 50,950 51,000 | 1,271 1,274 1,277 1,280 1,282 1,285 1,288 1,291 1,293 1,296 1,299 1,302 1,305 1,307 1,310 1,313 1,316 1,318 1,321 1,324 | 806 807 808 809 811 812 813 814 815 817 818 819 820 822 823 824 825 826 828 829 |
| 42,000 | 45,000 | 48,000 | 51,000 | ||||||||
| 42,000 42,050 42,050 42,100 42,100 42,150 42,150 42,200 42,200 42,250 42,250 42,300 42,300 42,350 42,350 42,400 42,400 42,450 42,450 42,500 42,500 42,550 42,550 42,600 42,600 42,650 42,650 42,700 42,700 42,750 42,750 42,800 42,800 42,850 42,850 42,900 42,900 42,950 42,950 43,000 | 829 832 835 838 840 843 846 849 851 854 857 860 863 865 868 871 874 876 879 882 | 665 666 667 668 669 670 671 672 672 673 674 675 676 677 678 679 679 680 681 682 | 45,000 45,050 45,050 45,100 45,100 45,150 45,150 45,200 45,200 45,250 45,250 45,300 45,300 45,350 45,350 45,400 45,400 45,450 45,450 45,500 45,500 45,550 45,550 45,600 45,600 45,650 45,650 45,700 45,700 45,750 45,750 45,800 45,800 45,850 45,850 45,900 45,900 45,950 45,950 46,000 | 995 998 1,001 1,003 1,006 1,009 1,012 1,014 1,017 1,020 1,023 1,026 1,028 1,031 1,034 1,037 1,039 1,042 1,045 1,048 | 718 719 720 721 721 722 723 724 725 726 727 728 728 729 730 731 732 733 734 735 | 48,000 48,050 48,050 48,100 48,100 48,150 48,150 48,200 48,200 48,250 48,250 48,300 48,300 48,350 48,350 48,400 48,400 48,450 48,450 48,500 48,500 48,550 48,550 48,600 48,600 48,650 48,650 48,700 48,700 48,750 48,750 48,800 48,800 48,850 48,850 48,900 48,900 48,950 48,950 49,000 | 1,161 1,164 1,166 1,169 1,172 1,175 1,177 1,180 1,183 1,186 1,189 1,191 1,194 1,197 1,200 1,202 1,205 1,208 1,211 1,213 | 770 771 772 773 774 775 776 777 777 778 779 780 781 782 783 784 784 785 786 787 | 51,000 51,050 51,050 51,100 51,100 51,150 51,150 51,200 51,200 51,250 51,250 51,300 51,300 51,350 51,350 51,400 51,400 51,450 51,450 51,500 51,500 51,550 51,550 51,600 51,600 51,650 51,650 51,700 51,700 51,750 51,750 51,800 51,800 51,850 51,850 51,900 51,900 51,950 51,950 52,000 | 1,327 1,329 1,332 1,335 1,338 1,340 1,343 1,346 1,349 1,351 1,354 1,357 1,360 1,363 1,365 1,368 1,371 1,374 1,376 1,379 | 830 831 833 834 835 836 837 839 840 841 842 844 845 846 847 848 850 851 852 853 |
# Than Than
# Than Than
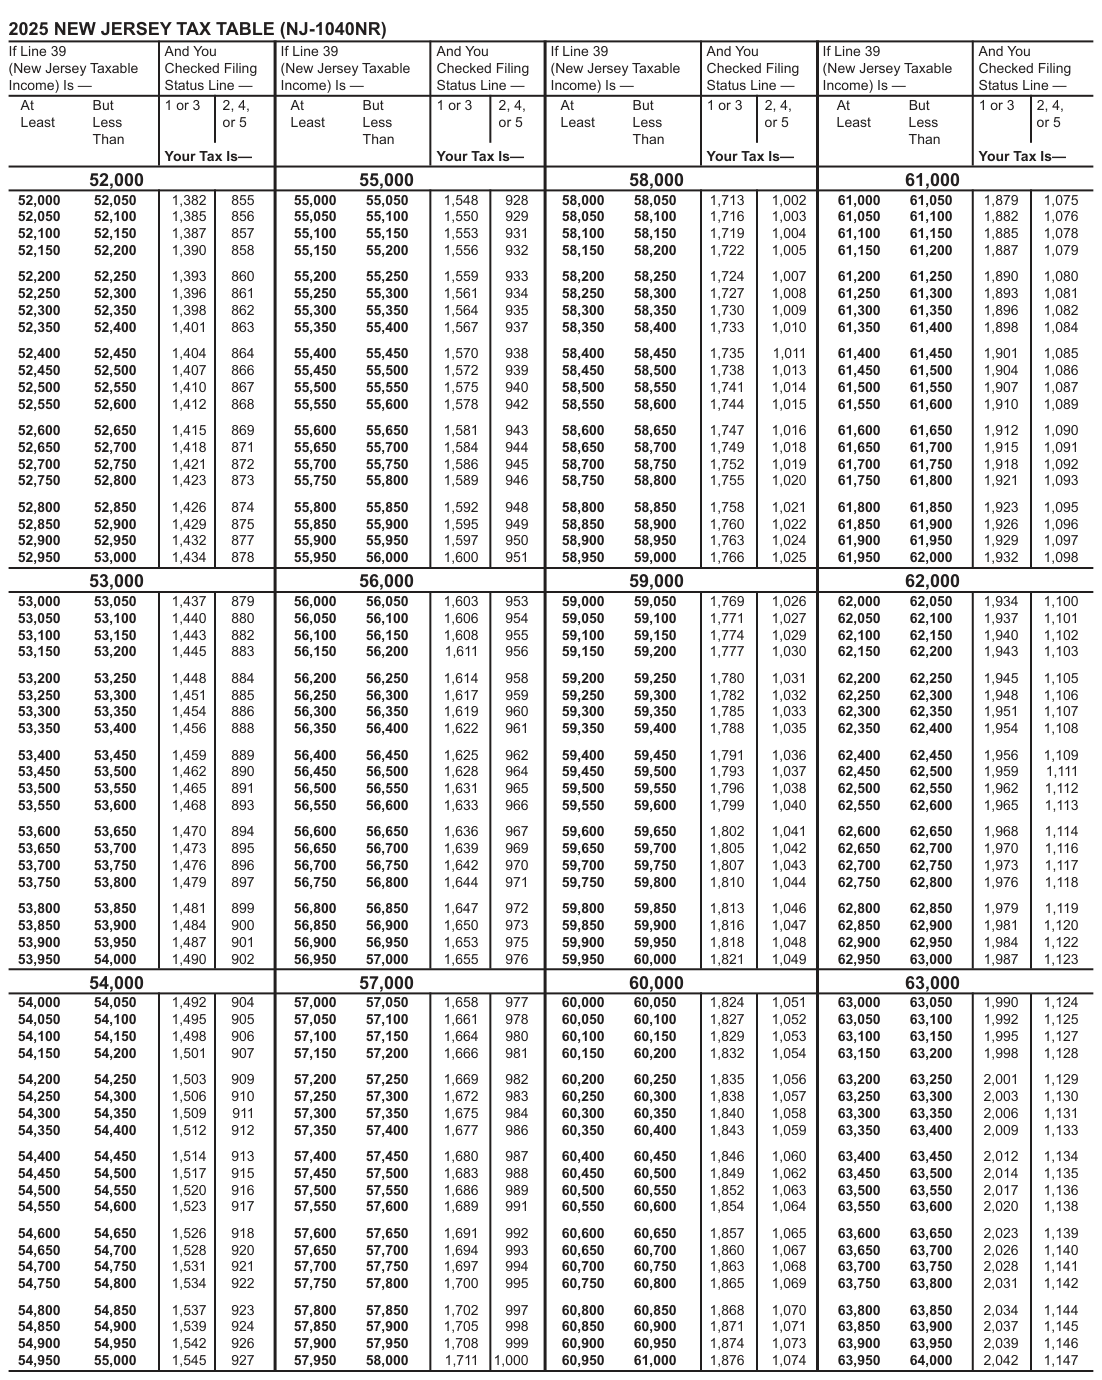
Text version of this table
| If Line 39 (New Jersey Taxable Income) Is — | And You Checked Filing Status Line — | If Line 39 (New Jersey Taxable Income) Is — | And You Checked Filing Status Line — | If Line 39 (New Jersey Taxable Income) Is — | And You Checked Filing Status Line — | If Line 39 (New Jersey Taxable Income) Is — | And You Checked Filing Status Line — | ||||
| At But Least Less Than | 1 or 3 2, 4, or 5 Your Tax Is— | At But Least Less Than | 1 or 3 2, 4, or 5 Your Tax Is— | At But Least Less Than | 1 or 3 2, 4, or 5 Your Tax Is— | At But Least Less Than | 1 or 3 2, 4, or 5 Your Tax Is— | ||||
| 52,000 | 55,000 | 58,000 | 61,000 | ||||||||
| 52,000 52,050 52,050 52,100 52,100 52,150 52,150 52,200 52,200 52,250 52,250 52,300 52,300 52,350 52,350 52,400 52,400 52,450 52,450 52,500 52,500 52,550 52,550 52,600 52,600 52,650 52,650 52,700 52,700 52,750 52,750 52,800 52,800 52,850 52,850 52,900 52,900 52,950 52,950 53,000 | 1,382 1,385 1,387 1,390 1,393 1,396 1,398 1,401 1,404 1,407 1,410 1,412 1,415 1,418 1,421 1,423 1,426 1,429 1,432 1,434 | 855 856 857 858 860 861 862 863 864 866 867 868 869 871 872 873 874 875 877 878 | 55,000 55,050 55,050 55,100 55,100 55,150 55,150 55,200 55,200 55,250 55,250 55,300 55,300 55,350 55,350 55,400 55,400 55,450 55,450 55,500 55,500 55,550 55,550 55,600 55,600 55,650 55,650 55,700 55,700 55,750 55,750 55,800 55,800 55,850 55,850 55,900 55,900 55,950 55,950 56,000 | 1,548 1,550 1,553 1,556 1,559 1,561 1,564 1,567 1,570 1,572 1,575 1,578 1,581 1,584 1,586 1,589 1,592 1,595 1,597 1,600 | 928 929 931 932 933 934 935 937 938 939 940 942 943 944 945 946 948 949 950 951 | 58,000 58,050 58,050 58,100 58,100 58,150 58,150 58,200 58,200 58,250 58,250 58,300 58,300 58,350 58,350 58,400 58,400 58,450 58,450 58,500 58,500 58,550 58,550 58,600 58,600 58,650 58,650 58,700 58,700 58,750 58,750 58,800 58,800 58,850 58,850 58,900 58,900 58,950 58,950 59,000 | 1,713 1,716 1,719 1,722 1,724 1,727 1,730 1,733 1,735 1,738 1,741 1,744 1,747 1,749 1,752 1,755 1,758 1,760 1,763 1,766 | 1,002 1,003 1,004 1,005 1,007 1,008 1,009 1,010 1,011 1,013 1,014 1,015 1,016 1,018 1,019 1,020 1,021 1,022 1,024 1,025 | 61,000 61,050 61,050 61,100 61,100 61,150 61,150 61,200 61,200 61,250 61,250 61,300 61,300 61,350 61,350 61,400 61,400 61,450 61,450 61,500 61,500 61,550 61,550 61,600 61,600 61,650 61,650 61,700 61,700 61,750 61,750 61,800 61,800 61,850 61,850 61,900 61,900 61,950 61,950 62,000 | 1,879 1,882 1,885 1,887 1,890 1,893 1,896 1,898 1,901 1,904 1,907 1,910 1,912 1,915 1,918 1,921 1,923 1,926 1,929 1,932 | 1,075 1,076 1,078 1,079 1,080 1,081 1,082 1,084 1,085 1,086 1,087 1,089 1,090 1,091 1,092 1,093 1,095 1,096 1,097 1,098 |
| 53,000 | 56,000 | 59,000 | 62,000 | ||||||||
| 53,000 53,050 53,050 53,100 53,100 53,150 53,150 53,200 53,200 53,250 53,250 53,300 53,300 53,350 53,350 53,400 53,400 53,450 53,450 53,500 53,500 53,550 53,550 53,600 53,600 53,650 53,650 53,700 53,700 53,750 53,750 53,800 53,800 53,850 53,850 53,900 53,900 53,950 53,950 54,000 | 1,437 1,440 1,443 1,445 1,448 1,451 1,454 1,456 1,459 1,462 1,465 1,468 1,470 1,473 1,476 1,479 1,481 1,484 1,487 1,490 | 879 880 882 883 884 885 886 888 889 890 891 893 894 895 896 897 899 900 901 902 | 56,000 56,050 56,050 56,100 56,100 56,150 56,150 56,200 56,200 56,250 56,250 56,300 56,300 56,350 56,350 56,400 56,400 56,450 56,450 56,500 56,500 56,550 56,550 56,600 56,600 56,650 56,650 56,700 56,700 56,750 56,750 56,800 56,800 56,850 56,850 56,900 56,900 56,950 56,950 57,000 | 1,603 1,606 1,608 1,611 1,614 1,617 1,619 1,622 1,625 1,628 1,631 1,633 1,636 1,639 1,642 1,644 1,647 1,650 1,653 1,655 | 953 954 955 956 958 959 960 961 962 964 965 966 967 969 970 971 972 973 975 976 | 59,000 59,050 59,050 59,100 59,100 59,150 59,150 59,200 59,200 59,250 59,250 59,300 59,300 59,350 59,350 59,400 59,400 59,450 59,450 59,500 59,500 59,550 59,550 59,600 59,600 59,650 59,650 59,700 59,700 59,750 59,750 59,800 59,800 59,850 59,850 59,900 59,900 59,950 59,950 60,000 | 1,769 1,771 1,774 1,777 1,780 1,782 1,785 1,788 1,791 1,793 1,796 1,799 1,802 1,805 1,807 1,810 1,813 1,816 1,818 1,821 | 1,026 1,027 1,029 1,030 1,031 1,032 1,033 1,035 1,036 1,037 1,038 1,040 1,041 1,042 1,043 1,044 1,046 1,047 1,048 1,049 | 62,000 62,050 62,050 62,100 62,100 62,150 62,150 62,200 62,200 62,250 62,250 62,300 62,300 62,350 62,350 62,400 62,400 62,450 62,450 62,500 62,500 62,550 62,550 62,600 62,600 62,650 62,650 62,700 62,700 62,750 62,750 62,800 62,800 62,850 62,850 62,900 62,900 62,950 62,950 63,000 | 1,934 1,937 1,940 1,943 1,945 1,948 1,951 1,954 1,956 1,959 1,962 1,965 1,968 1,970 1,973 1,976 1,979 1,981 1,984 1,987 | 1,100 1,101 1,102 1,103 1,105 1,106 1,107 1,108 1,109 1,111 1,112 1,113 1,114 1,116 1,117 1,118 1,119 1,120 1,122 1,123 |
| 54,000 | 57,000 | 60,000 | 63,000 | ||||||||
| 54,000 54,050 54,050 54,100 54,100 54,150 54,150 54,200 54,200 54,250 54,250 54,300 54,300 54,350 54,350 54,400 54,400 54,450 54,450 54,500 54,500 54,550 54,550 54,600 54,600 54,650 54,650 54,700 54,700 54,750 54,750 54,800 54,800 54,850 54,850 54,900 54,900 54,950 54,950 55,000 | 1,492 1,495 1,498 1,501 1,503 1,506 1,509 1,512 1,514 1,517 1,520 1,523 1,526 1,528 1,531 1,534 1,537 1,539 1,542 1,545 | 904 905 906 907 909 910 911 912 913 915 916 917 918 920 921 922 923 924 926 927 | 57,000 57,050 57,050 57,100 57,100 57,150 57,150 57,200 57,200 57,250 57,250 57,300 57,300 57,350 57,350 57,400 57,400 57,450 57,450 57,500 57,500 57,550 57,550 57,600 57,600 57,650 57,650 57,700 57,700 57,750 57,750 57,800 57,800 57,850 57,850 57,900 57,900 57,950 57,950 58,000 | 1,658 1,661 1,664 1,666 1,669 1,672 1,675 1,677 1,680 1,683 1,686 1,689 1,691 1,694 1,697 1,700 1,702 1,705 1,708 1,711 | 977 978 980 981 982 983 984 986 987 988 989 991 992 993 994 995 997 998 999 1,000 | 60,000 60,050 60,050 60,100 60,100 60,150 60,150 60,200 60,200 60,250 60,250 60,300 60,300 60,350 60,350 60,400 60,400 60,450 60,450 60,500 60,500 60,550 60,550 60,600 60,600 60,650 60,650 60,700 60,700 60,750 60,750 60,800 60,800 60,850 60,850 60,900 60,900 60,950 60,950 61,000 | 1,824 1,827 1,829 1,832 1,835 1,838 1,840 1,843 1,846 1,849 1,852 1,854 1,857 1,860 1,863 1,865 1,868 1,871 1,874 1,876 | 1,051 1,052 1,053 1,054 1,056 1,057 1,058 1,059 1,060 1,062 1,063 1,064 1,065 1,067 1,068 1,069 1,070 1,071 1,073 1,074 | 63,000 63,050 63,050 63,100 63,100 63,150 63,150 63,200 63,200 63,250 63,250 63,300 63,300 63,350 63,350 63,400 63,400 63,450 63,450 63,500 63,500 63,550 63,550 63,600 63,600 63,650 63,650 63,700 63,700 63,750 63,750 63,800 63,800 63,850 63,850 63,900 63,900 63,950 63,950 64,000 | 1,990 1,992 1,995 1,998 2,001 2,003 2,006 2,009 2,012 2,014 2,017 2,020 2,023 2,026 2,028 2,031 2,034 2,037 2,039 2,042 | 1,124 1,125 1,127 1,128 1,129 1,130 1,131 1,133 1,134 1,135 1,136 1,138 1,139 1,140 1,141 1,142 1,144 1,145 1,146 1,147 |
# Than Than
# Than Than
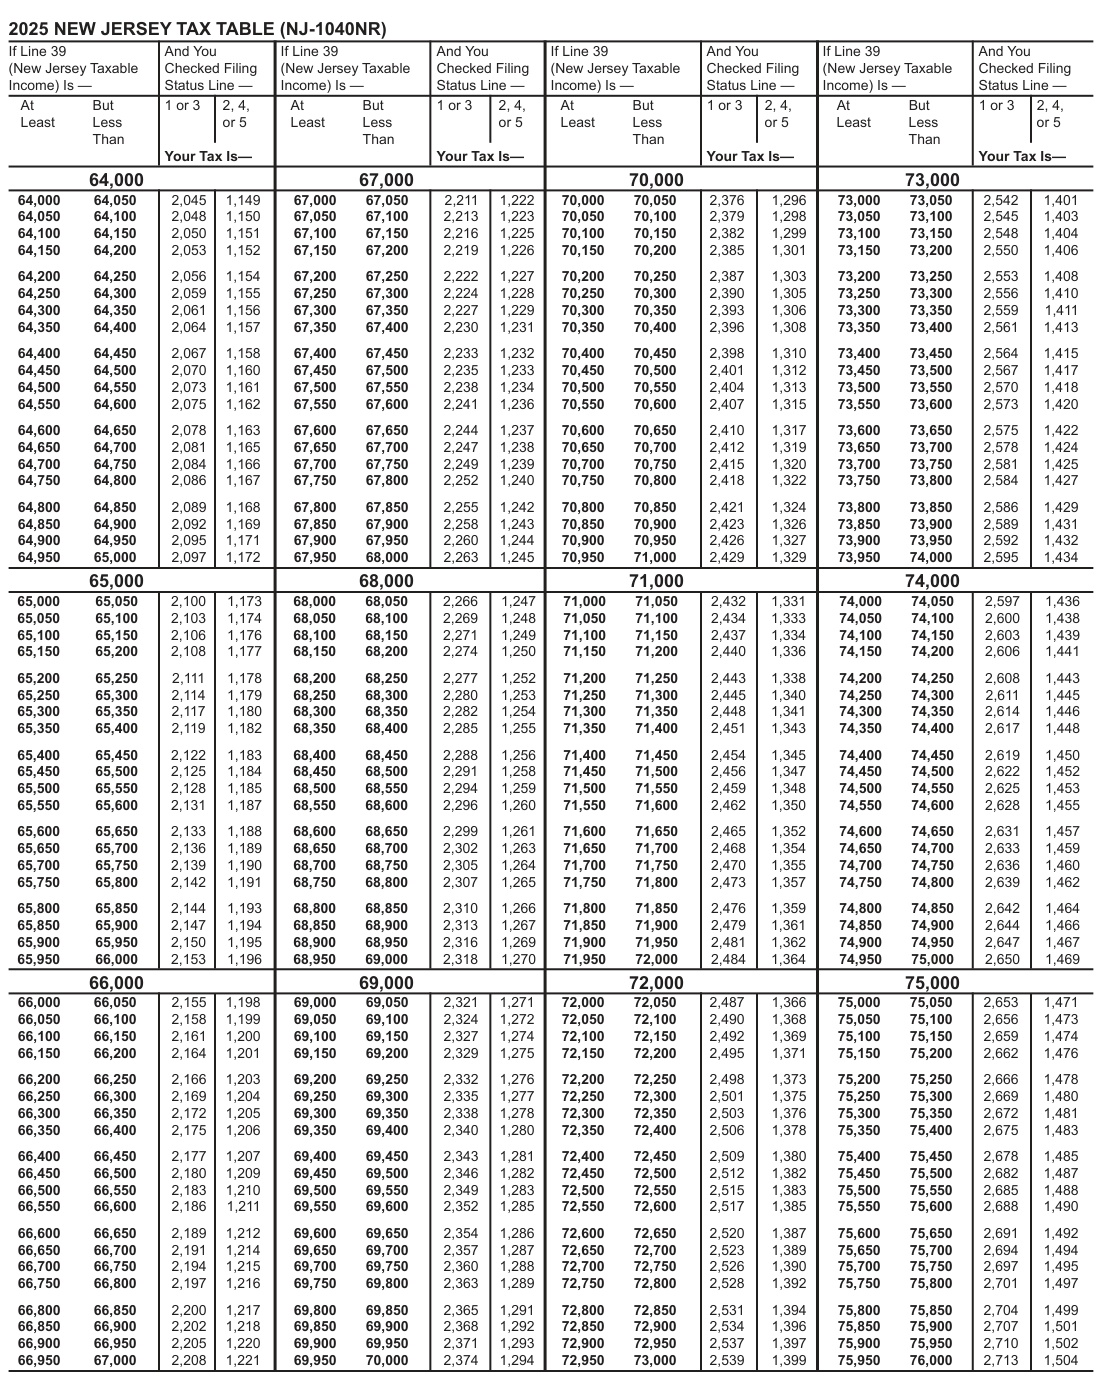
Text version of this table
| If Line 39 (New Jersey Taxable Income) Is — | And You Checked Filing Status Line — | If Line 39 (New Jersey Taxable Income) Is — | And You Checked Filing Status Line — | If Line 39 (New Jersey Taxable Income) Is — | And You Checked Filing Status Line — | If Line 39 (New Jersey Taxable Income) Is — | And You Checked Filing Status Line — | ||||
| At But Least Less Than | 1 or 3 2, 4, or 5 Your Tax Is— | At But Least Less Than | 1 or 3 2, 4, or 5 Your Tax Is— | At But Least Less Than | 1 or 3 2, 4, or 5 Your Tax Is— | At But Least Less Than | 1 or 3 2, 4, or 5 Your Tax Is— | ||||
| 64,000 | 67,000 | 70,000 | 73,000 | ||||||||
| 64,000 64,050 64,050 64,100 64,100 64,150 64,150 64,200 64,200 64,250 64,250 64,300 64,300 64,350 64,350 64,400 64,400 64,450 64,450 64,500 64,500 64,550 64,550 64,600 64,600 64,650 64,650 64,700 64,700 64,750 64,750 64,800 64,800 64,850 64,850 64,900 64,900 64,950 64,950 65,000 | 2,045 2,048 2,050 2,053 2,056 2,059 2,061 2,064 2,067 2,070 2,073 2,075 2,078 2,081 2,084 2,086 2,089 2,092 2,095 2,097 | 1,149 1,150 1,151 1,152 1,154 1,155 1,156 1,157 1,158 1,160 1,161 1,162 1,163 1,165 1,166 1,167 1,168 1,169 1,171 1,172 | 67,000 67,050 67,050 67,100 67,100 67,150 67,150 67,200 67,200 67,250 67,250 67,300 67,300 67,350 67,350 67,400 67,400 67,450 67,450 67,500 67,500 67,550 67,550 67,600 67,600 67,650 67,650 67,700 67,700 67,750 67,750 67,800 67,800 67,850 67,850 67,900 67,900 67,950 67,950 68,000 | 2,211 2,213 2,216 2,219 2,222 2,224 2,227 2,230 2,233 2,235 2,238 2,241 2,244 2,247 2,249 2,252 2,255 2,258 2,260 2,263 | 1,222 1,223 1,225 1,226 1,227 1,228 1,229 1,231 1,232 1,233 1,234 1,236 1,237 1,238 1,239 1,240 1,242 1,243 1,244 1,245 | 70,000 70,050 70,050 70,100 70,100 70,150 70,150 70,200 70,200 70,250 70,250 70,300 70,300 70,350 70,350 70,400 70,400 70,450 70,450 70,500 70,500 70,550 70,550 70,600 70,600 70,650 70,650 70,700 70,700 70,750 70,750 70,800 70,800 70,850 70,850 70,900 70,900 70,950 70,950 71,000 | 2,376 2,379 2,382 2,385 2,387 2,390 2,393 2,396 2,398 2,401 2,404 2,407 2,410 2,412 2,415 2,418 2,421 2,423 2,426 2,429 | 1,296 1,298 1,299 1,301 1,303 1,305 1,306 1,308 1,310 1,312 1,313 1,315 1,317 1,319 1,320 1,322 1,324 1,326 1,327 1,329 | 73,000 73,050 73,050 73,100 73,100 73,150 73,150 73,200 73,200 73,250 73,250 73,300 73,300 73,350 73,350 73,400 73,400 73,450 73,450 73,500 73,500 73,550 73,550 73,600 73,600 73,650 73,650 73,700 73,700 73,750 73,750 73,800 73,800 73,850 73,850 73,900 73,900 73,950 73,950 74,000 | 2,542 2,545 2,548 2,550 2,553 2,556 2,559 2,561 2,564 2,567 2,570 2,573 2,575 2,578 2,581 2,584 2,586 2,589 2,592 2,595 | 1,401 1,403 1,404 1,406 1,408 1,410 1,411 1,413 1,415 1,417 1,418 1,420 1,422 1,424 1,425 1,427 1,429 1,431 1,432 1,434 |
| 65,000 | 68,000 | 71,000 | 74,000 | ||||||||
| 65,000 65,050 65,050 65,100 65,100 65,150 65,150 65,200 65,200 65,250 65,250 65,300 65,300 65,350 65,350 65,400 65,400 65,450 65,450 65,500 65,500 65,550 65,550 65,600 65,600 65,650 65,650 65,700 65,700 65,750 65,750 65,800 65,800 65,850 65,850 65,900 65,900 65,950 65,950 66,000 | 2,100 2,103 2,106 2,108 2,111 2,114 2,117 2,119 2,122 2,125 2,128 2,131 2,133 2,136 2,139 2,142 2,144 2,147 2,150 2,153 | 1,173 1,174 1,176 1,177 1,178 1,179 1,180 1,182 1,183 1,184 1,185 1,187 1,188 1,189 1,190 1,191 1,193 1,194 1,195 1,196 | 68,000 68,050 68,050 68,100 68,100 68,150 68,150 68,200 68,200 68,250 68,250 68,300 68,300 68,350 68,350 68,400 68,400 68,450 68,450 68,500 68,500 68,550 68,550 68,600 68,600 68,650 68,650 68,700 68,700 68,750 68,750 68,800 68,800 68,850 68,850 68,900 68,900 68,950 68,950 69,000 | 2,266 2,269 2,271 2,274 2,277 2,280 2,282 2,285 2,288 2,291 2,294 2,296 2,299 2,302 2,305 2,307 2,310 2,313 2,316 2,318 | 1,247 1,248 1,249 1,250 1,252 1,253 1,254 1,255 1,256 1,258 1,259 1,260 1,261 1,263 1,264 1,265 1,266 1,267 1,269 1,270 | 71,000 71,050 71,050 71,100 71,100 71,150 71,150 71,200 71,200 71,250 71,250 71,300 71,300 71,350 71,350 71,400 71,400 71,450 71,450 71,500 71,500 71,550 71,550 71,600 71,600 71,650 71,650 71,700 71,700 71,750 71,750 71,800 71,800 71,850 71,850 71,900 71,900 71,950 71,950 72,000 | 2,432 2,434 2,437 2,440 2,443 2,445 2,448 2,451 2,454 2,456 2,459 2,462 2,465 2,468 2,470 2,473 2,476 2,479 2,481 2,484 | 1,331 1,333 1,334 1,336 1,338 1,340 1,341 1,343 1,345 1,347 1,348 1,350 1,352 1,354 1,355 1,357 1,359 1,361 1,362 1,364 | 74,000 74,050 74,050 74,100 74,100 74,150 74,150 74,200 74,200 74,250 74,250 74,300 74,300 74,350 74,350 74,400 74,400 74,450 74,450 74,500 74,500 74,550 74,550 74,600 74,600 74,650 74,650 74,700 74,700 74,750 74,750 74,800 74,800 74,850 74,850 74,900 74,900 74,950 74,950 75,000 | 2,597 2,600 2,603 2,606 2,608 2,611 2,614 2,617 2,619 2,622 2,625 2,628 2,631 2,633 2,636 2,639 2,642 2,644 2,647 2,650 | 1,436 1,438 1,439 1,441 1,443 1,445 1,446 1,448 1,450 1,452 1,453 1,455 1,457 1,459 1,460 1,462 1,464 1,466 1,467 1,469 |
| 66,000 | 69,000 | 72,000 | 75,000 | ||||||||
| 66,000 66,050 66,050 66,100 66,100 66,150 66,150 66,200 66,200 66,250 66,250 66,300 66,300 66,350 66,350 66,400 66,400 66,450 66,450 66,500 66,500 66,550 66,550 66,600 66,600 66,650 66,650 66,700 66,700 66,750 66,750 66,800 66,800 66,850 66,850 66,900 66,900 66,950 66,950 67,000 | 2,155 2,158 2,161 2,164 2,166 2,169 2,172 2,175 2,177 2,180 2,183 2,186 2,189 2,191 2,194 2,197 2,200 2,202 2,205 2,208 | 1,198 1,199 1,200 1,201 1,203 1,204 1,205 1,206 1,207 1,209 1,210 1,211 1,212 1,214 1,215 1,216 1,217 1,218 1,220 1,221 | 69,000 69,050 69,050 69,100 69,100 69,150 69,150 69,200 69,200 69,250 69,250 69,300 69,300 69,350 69,350 69,400 69,400 69,450 69,450 69,500 69,500 69,550 69,550 69,600 69,600 69,650 69,650 69,700 69,700 69,750 69,750 69,800 69,800 69,850 69,850 69,900 69,900 69,950 69,950 70,000 | 2,321 2,324 2,327 2,329 2,332 2,335 2,338 2,340 2,343 2,346 2,349 2,352 2,354 2,357 2,360 2,363 2,365 2,368 2,371 2,374 | 1,271 1,272 1,274 1,275 1,276 1,277 1,278 1,280 1,281 1,282 1,283 1,285 1,286 1,287 1,288 1,289 1,291 1,292 1,293 1,294 | 72,000 72,050 72,050 72,100 72,100 72,150 72,150 72,200 72,200 72,250 72,250 72,300 72,300 72,350 72,350 72,400 72,400 72,450 72,450 72,500 72,500 72,550 72,550 72,600 72,600 72,650 72,650 72,700 72,700 72,750 72,750 72,800 72,800 72,850 72,850 72,900 72,900 72,950 72,950 73,000 | 2,487 2,490 2,492 2,495 2,498 2,501 2,503 2,506 2,509 2,512 2,515 2,517 2,520 2,523 2,526 2,528 2,531 2,534 2,537 2,539 | 1,366 1,368 1,369 1,371 1,373 1,375 1,376 1,378 1,380 1,382 1,383 1,385 1,387 1,389 1,390 1,392 1,394 1,396 1,397 1,399 | 75,000 75,050 75,050 75,100 75,100 75,150 75,150 75,200 75,200 75,250 75,250 75,300 75,300 75,350 75,350 75,400 75,400 75,450 75,450 75,500 75,500 75,550 75,550 75,600 75,600 75,650 75,650 75,700 75,700 75,750 75,750 75,800 75,800 75,850 75,850 75,900 75,900 75,950 75,950 76,000 | 2,653 2,656 2,659 2,662 2,666 2,669 2,672 2,675 2,678 2,682 2,685 2,688 2,691 2,694 2,697 2,701 2,704 2,707 2,710 2,713 | 1,471 1,473 1,474 1,476 1,478 1,480 1,481 1,483 1,485 1,487 1,488 1,490 1,492 1,494 1,495 1,497 1,499 1,501 1,502 1,504 |
# Than Than
# Than Than
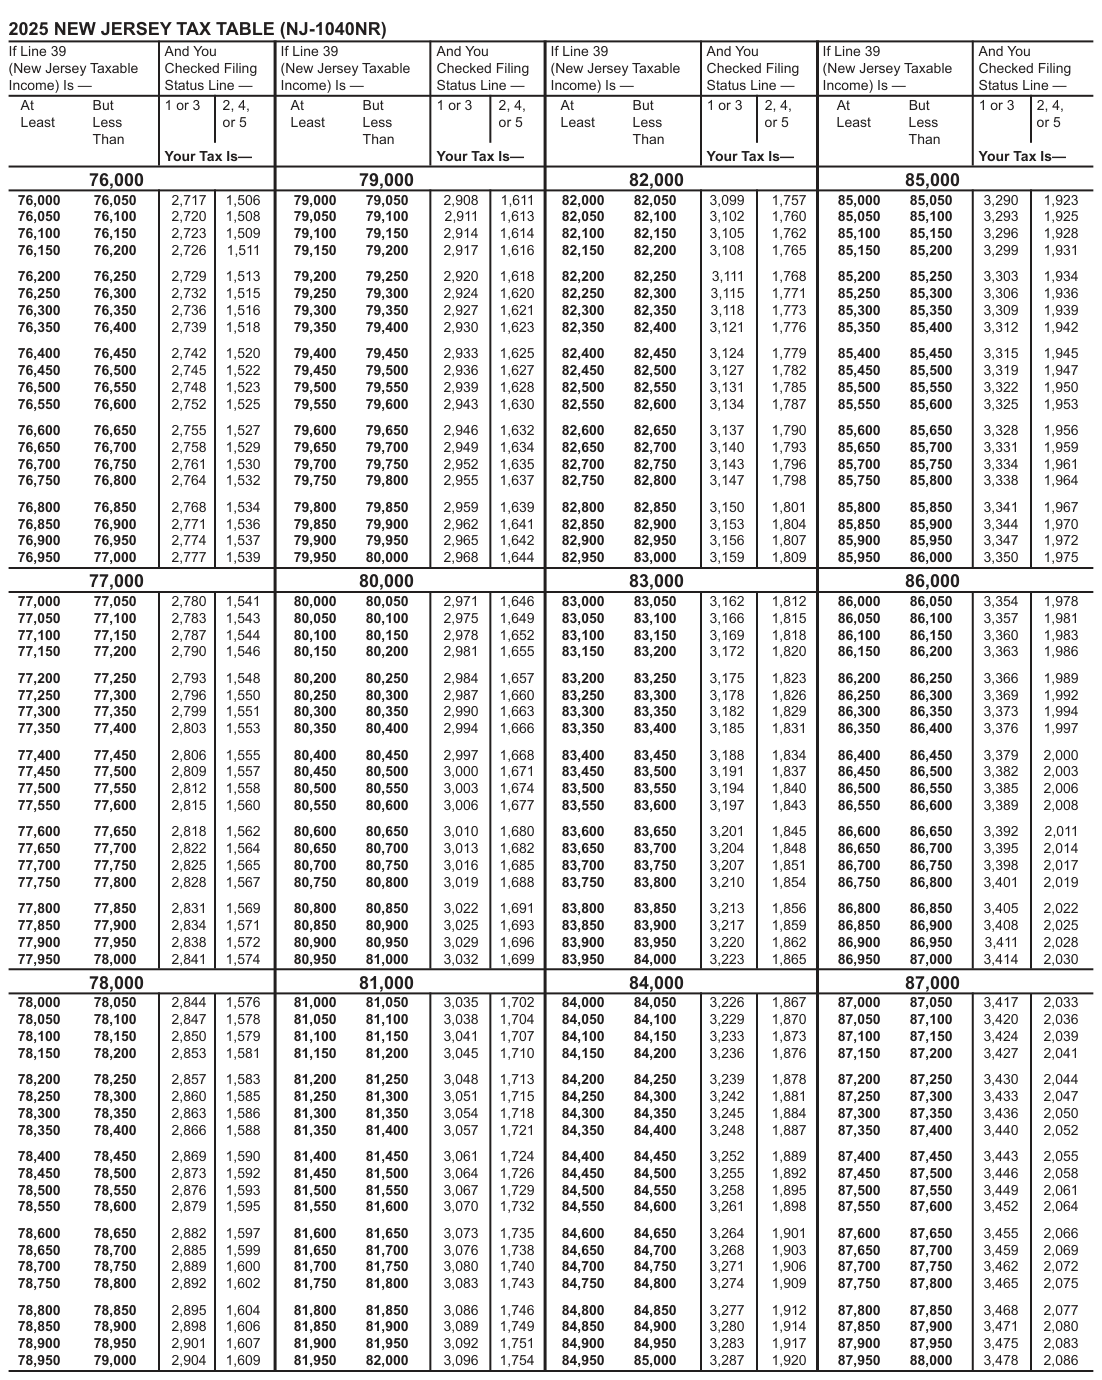
Text version of this table
| If Line 39 (New Jersey Taxable Income) Is — | And You Checked Filing Status Line — | If Line 39 (New Jersey Taxable Income) Is — | And You Checked Filing Status Line — | If Line 39 (New Jersey Taxable Income) Is — | And You Checked Filing Status Line — | If Line 39 (New Jersey Taxable Income) Is — | And You Checked Filing Status Line — | ||||
| At But Least Less Than | 1 or 3 2, 4, or 5 Your Tax Is— | At But Least Less Than | 1 or 3 2, 4, or 5 Your Tax Is— | At But Least Less Than | 1 or 3 2, 4, or 5 Your Tax Is— | At But Least Less Than | 1 or 3 2, 4, or 5 Your Tax Is— | ||||
| 76,000 | 79,000 | 82,000 | 85,000 | ||||||||
| 76,000 76,050 76,050 76,100 76,100 76,150 76,150 76,200 76,200 76,250 76,250 76,300 76,300 76,350 76,350 76,400 76,400 76,450 76,450 76,500 76,500 76,550 76,550 76,600 76,600 76,650 76,650 76,700 76,700 76,750 76,750 76,800 76,800 76,850 76,850 76,900 76,900 76,950 76,950 77,000 | 2,717 2,720 2,723 2,726 2,729 2,732 2,736 2,739 2,742 2,745 2,748 2,752 2,755 2,758 2,761 2,764 2,768 2,771 2,774 2,777 | 1,506 1,508 1,509 1,511 1,513 1,515 1,516 1,518 1,520 1,522 1,523 1,525 1,527 1,529 1,530 1,532 1,534 1,536 1,537 1,539 | 79,000 79,050 79,050 79,100 79,100 79,150 79,150 79,200 79,200 79,250 79,250 79,300 79,300 79,350 79,350 79,400 79,400 79,450 79,450 79,500 79,500 79,550 79,550 79,600 79,600 79,650 79,650 79,700 79,700 79,750 79,750 79,800 79,800 79,850 79,850 79,900 79,900 79,950 79,950 80,000 | 2,908 2,911 2,914 2,917 2,920 2,924 2,927 2,930 2,933 2,936 2,939 2,943 2,946 2,949 2,952 2,955 2,959 2,962 2,965 2,968 | 1,611 1,613 1,614 1,616 1,618 1,620 1,621 1,623 1,625 1,627 1,628 1,630 1,632 1,634 1,635 1,637 1,639 1,641 1,642 1,644 | 82,000 82,050 82,050 82,100 82,100 82,150 82,150 82,200 82,200 82,250 82,250 82,300 82,300 82,350 82,350 82,400 82,400 82,450 82,450 82,500 82,500 82,550 82,550 82,600 82,600 82,650 82,650 82,700 82,700 82,750 82,750 82,800 82,800 82,850 82,850 82,900 82,900 82,950 82,950 83,000 | 3,099 3,102 3,105 3,108 3,111 3,115 3,118 3,121 3,124 3,127 3,131 3,134 3,137 3,140 3,143 3,147 3,150 3,153 3,156 3,159 | 1,757 1,760 1,762 1,765 1,768 1,771 1,773 1,776 1,779 1,782 1,785 1,787 1,790 1,793 1,796 1,798 1,801 1,804 1,807 1,809 | 85,000 85,050 85,050 85,100 85,100 85,150 85,150 85,200 85,200 85,250 85,250 85,300 85,300 85,350 85,350 85,400 85,400 85,450 85,450 85,500 85,500 85,550 85,550 85,600 85,600 85,650 85,650 85,700 85,700 85,750 85,750 85,800 85,800 85,850 85,850 85,900 85,900 85,950 85,950 86,000 | 3,290 3,293 3,296 3,299 3,303 3,306 3,309 3,312 3,315 3,319 3,322 3,325 3,328 3,331 3,334 3,338 3,341 3,344 3,347 3,350 | 1,923 1,925 1,928 1,931 1,934 1,936 1,939 1,942 1,945 1,947 1,950 1,953 1,956 1,959 1,961 1,964 1,967 1,970 1,972 1,975 |
| 77,000 | 80,000 | 83,000 | 86,000 | ||||||||
| 77,000 77,050 77,050 77,100 77,100 77,150 77,150 77,200 77,200 77,250 77,250 77,300 77,300 77,350 77,350 77,400 77,400 77,450 77,450 77,500 77,500 77,550 77,550 77,600 77,600 77,650 77,650 77,700 77,700 77,750 77,750 77,800 77,800 77,850 77,850 77,900 77,900 77,950 77,950 78,000 | 2,780 2,783 2,787 2,790 2,793 2,796 2,799 2,803 2,806 2,809 2,812 2,815 2,818 2,822 2,825 2,828 2,831 2,834 2,838 2,841 | 1,541 1,543 1,544 1,546 1,548 1,550 1,551 1,553 1,555 1,557 1,558 1,560 1,562 1,564 1,565 1,567 1,569 1,571 1,572 1,574 | 80,000 80,050 80,050 80,100 80,100 80,150 80,150 80,200 80,200 80,250 80,250 80,300 80,300 80,350 80,350 80,400 80,400 80,450 80,450 80,500 80,500 80,550 80,550 80,600 80,600 80,650 80,650 80,700 80,700 80,750 80,750 80,800 80,800 80,850 80,850 80,900 80,900 80,950 80,950 81,000 | 2,971 2,975 2,978 2,981 2,984 2,987 2,990 2,994 2,997 3,000 3,003 3,006 3,010 3,013 3,016 3,019 3,022 3,025 3,029 3,032 | 1,646 1,649 1,652 1,655 1,657 1,660 1,663 1,666 1,668 1,671 1,674 1,677 1,680 1,682 1,685 1,688 1,691 1,693 1,696 1,699 | 83,000 83,050 83,050 83,100 83,100 83,150 83,150 83,200 83,200 83,250 83,250 83,300 83,300 83,350 83,350 83,400 83,400 83,450 83,450 83,500 83,500 83,550 83,550 83,600 83,600 83,650 83,650 83,700 83,700 83,750 83,750 83,800 83,800 83,850 83,850 83,900 83,900 83,950 83,950 84,000 | 3,162 3,166 3,169 3,172 3,175 3,178 3,182 3,185 3,188 3,191 3,194 3,197 3,201 3,204 3,207 3,210 3,213 3,217 3,220 3,223 | 1,812 1,815 1,818 1,820 1,823 1,826 1,829 1,831 1,834 1,837 1,840 1,843 1,845 1,848 1,851 1,854 1,856 1,859 1,862 1,865 | 86,000 86,050 86,050 86,100 86,100 86,150 86,150 86,200 86,200 86,250 86,250 86,300 86,300 86,350 86,350 86,400 86,400 86,450 86,450 86,500 86,500 86,550 86,550 86,600 86,600 86,650 86,650 86,700 86,700 86,750 86,750 86,800 86,800 86,850 86,850 86,900 86,900 86,950 86,950 87,000 | 3,354 3,357 3,360 3,363 3,366 3,369 3,373 3,376 3,379 3,382 3,385 3,389 3,392 3,395 3,398 3,401 3,405 3,408 3,411 3,414 | 1,978 1,981 1,983 1,986 1,989 1,992 1,994 1,997 2,000 2,003 2,006 2,008 2,011 2,014 2,017 2,019 2,022 2,025 2,028 2,030 |
| 78,000 | 81,000 | 84,000 | 87,000 | ||||||||
| 78,000 78,050 78,050 78,100 78,100 78,150 78,150 78,200 78,200 78,250 78,250 78,300 78,300 78,350 78,350 78,400 78,400 78,450 78,450 78,500 78,500 78,550 78,550 78,600 78,600 78,650 78,650 78,700 78,700 78,750 78,750 78,800 78,800 78,850 78,850 78,900 78,900 78,950 78,950 79,000 | 2,844 2,847 2,850 2,853 2,857 2,860 2,863 2,866 2,869 2,873 2,876 2,879 2,882 2,885 2,889 2,892 2,895 2,898 2,901 2,904 | 1,576 1,578 1,579 1,581 1,583 1,585 1,586 1,588 1,590 1,592 1,593 1,595 1,597 1,599 1,600 1,602 1,604 1,606 1,607 1,609 | 81,000 81,050 81,050 81,100 81,100 81,150 81,150 81,200 81,200 81,250 81,250 81,300 81,300 81,350 81,350 81,400 81,400 81,450 81,450 81,500 81,500 81,550 81,550 81,600 81,600 81,650 81,650 81,700 81,700 81,750 81,750 81,800 81,800 81,850 81,850 81,900 81,900 81,950 81,950 82,000 | 3,035 3,038 3,041 3,045 3,048 3,051 3,054 3,057 3,061 3,064 3,067 3,070 3,073 3,076 3,080 3,083 3,086 3,089 3,092 3,096 | 1,702 1,704 1,707 1,710 1,713 1,715 1,718 1,721 1,724 1,726 1,729 1,732 1,735 1,738 1,740 1,743 1,746 1,749 1,751 1,754 | 84,000 84,050 84,050 84,100 84,100 84,150 84,150 84,200 84,200 84,250 84,250 84,300 84,300 84,350 84,350 84,400 84,400 84,450 84,450 84,500 84,500 84,550 84,550 84,600 84,600 84,650 84,650 84,700 84,700 84,750 84,750 84,800 84,800 84,850 84,850 84,900 84,900 84,950 84,950 85,000 | 3,226 3,229 3,233 3,236 3,239 3,242 3,245 3,248 3,252 3,255 3,258 3,261 3,264 3,268 3,271 3,274 3,277 3,280 3,283 3,287 | 1,867 1,870 1,873 1,876 1,878 1,881 1,884 1,887 1,889 1,892 1,895 1,898 1,901 1,903 1,906 1,909 1,912 1,914 1,917 1,920 | 87,000 87,050 87,050 87,100 87,100 87,150 87,150 87,200 87,200 87,250 87,250 87,300 87,300 87,350 87,350 87,400 87,400 87,450 87,450 87,500 87,500 87,550 87,550 87,600 87,600 87,650 87,650 87,700 87,700 87,750 87,750 87,800 87,800 87,850 87,850 87,900 87,900 87,950 87,950 88,000 | 3,417 3,420 3,424 3,427 3,430 3,433 3,436 3,440 3,443 3,446 3,449 3,452 3,455 3,459 3,462 3,465 3,468 3,471 3,475 3,478 | 2,033 2,036 2,039 2,041 2,044 2,047 2,050 2,052 2,055 2,058 2,061 2,064 2,066 2,069 2,072 2,075 2,077 2,080 2,083 2,086 |
# Than Than
# Than Than
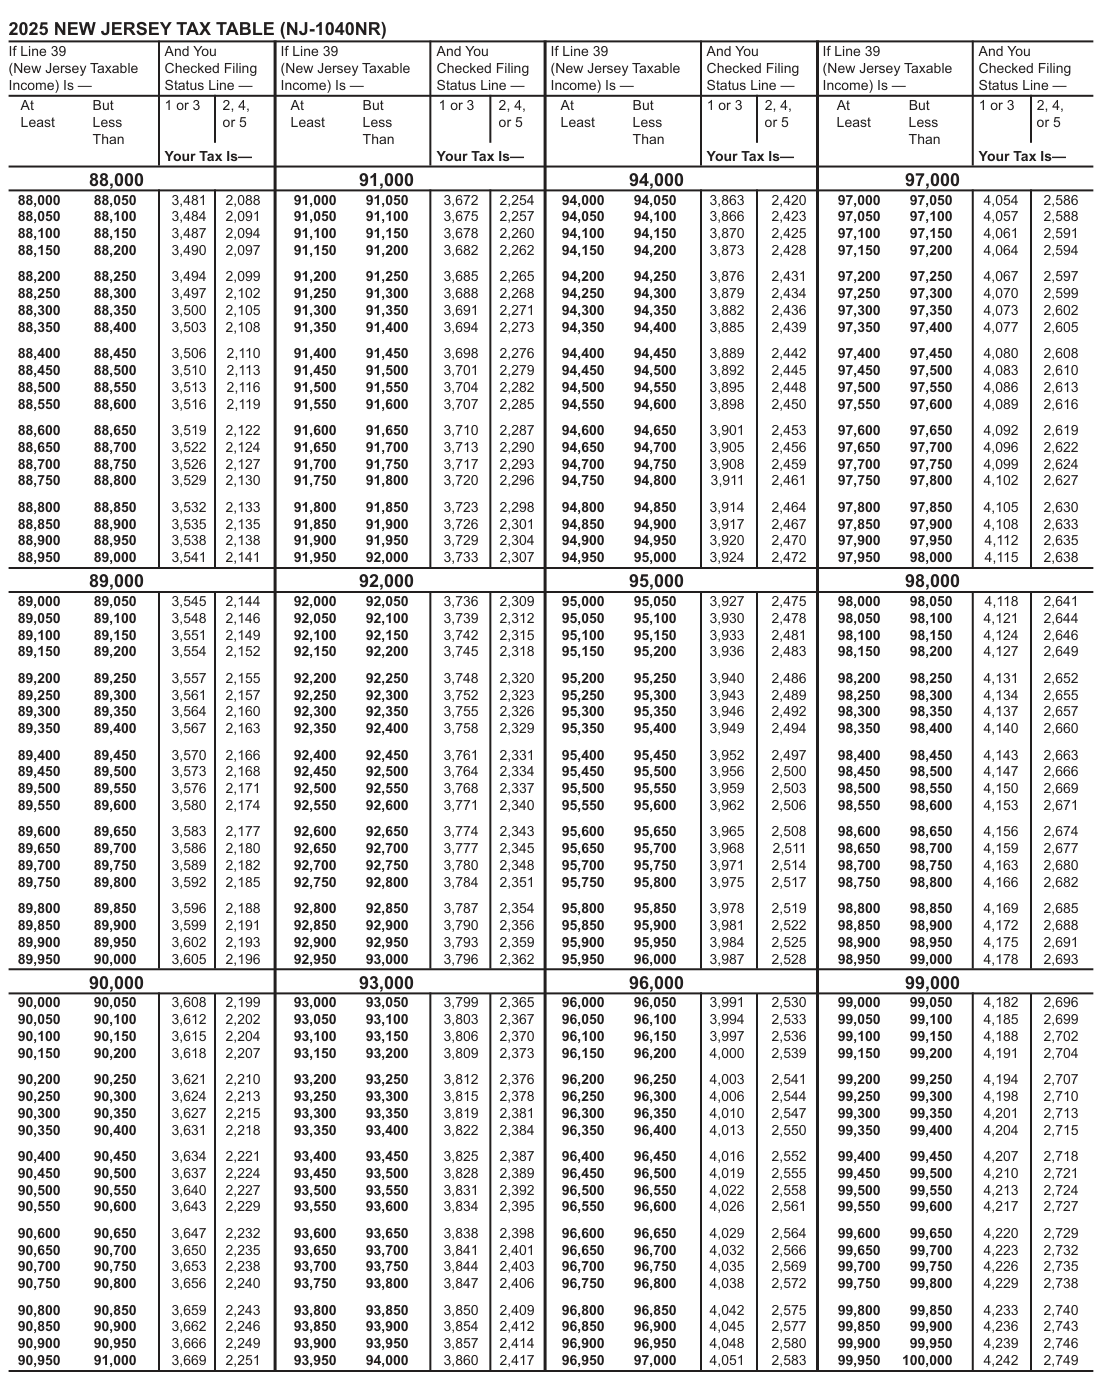
Text version of this table
| If Line 39 (New Jersey Taxable Income) Is — | And You Checked Filing Status Line — | If Line 39 (New Jersey Taxable Income) Is — | And You Checked Filing Status Line — | If Line 39 (New Jersey Taxable Income) Is — | And You Checked Filing Status Line — | If Line 39 (New Jersey Taxable Income) Is — | And You Checked Filing Status Line — | ||||
| At But Least Less Than | 1 or 3 2, 4, or 5 Your Tax Is— | At But Least Less Than | 1 or 3 2, 4, or 5 Your Tax Is— | At But Least Less Than | 1 or 3 2, 4, or 5 Your Tax Is— | At But Least Less Than | 1 or 3 2, 4, or 5 Your Tax Is— | ||||
| 88,000 | 91,000 | 94,000 | 97,000 | ||||||||
| 88,000 88,050 88,050 88,100 88,100 88,150 88,150 88,200 88,200 88,250 88,250 88,300 88,300 88,350 88,350 88,400 88,400 88,450 88,450 88,500 88,500 88,550 88,550 88,600 88,600 88,650 88,650 88,700 88,700 88,750 88,750 88,800 88,800 88,850 88,850 88,900 88,900 88,950 88,950 89,000 | 3,481 3,484 3,487 3,490 3,494 3,497 3,500 3,503 3,506 3,510 3,513 3,516 3,519 3,522 3,526 3,529 3,532 3,535 3,538 3,541 | 2,088 2,091 2,094 2,097 2,099 2,102 2,105 2,108 2,110 2,113 2,116 2,119 2,122 2,124 2,127 2,130 2,133 2,135 2,138 2,141 | 91,000 91,050 91,050 91,100 91,100 91,150 91,150 91,200 91,200 91,250 91,250 91,300 91,300 91,350 91,350 91,400 91,400 91,450 91,450 91,500 91,500 91,550 91,550 91,600 91,600 91,650 91,650 91,700 91,700 91,750 91,750 91,800 91,800 91,850 91,850 91,900 91,900 91,950 91,950 92,000 | 3,672 3,675 3,678 3,682 3,685 3,688 3,691 3,694 3,698 3,701 3,704 3,707 3,710 3,713 3,717 3,720 3,723 3,726 3,729 3,733 | 2,254 2,257 2,260 2,262 2,265 2,268 2,271 2,273 2,276 2,279 2,282 2,285 2,287 2,290 2,293 2,296 2,298 2,301 2,304 2,307 | 94,000 94,050 94,050 94,100 94,100 94,150 94,150 94,200 94,200 94,250 94,250 94,300 94,300 94,350 94,350 94,400 94,400 94,450 94,450 94,500 94,500 94,550 94,550 94,600 94,600 94,650 94,650 94,700 94,700 94,750 94,750 94,800 94,800 94,850 94,850 94,900 94,900 94,950 94,950 95,000 | 3,863 3,866 3,870 3,873 3,876 3,879 3,882 3,885 3,889 3,892 3,895 3,898 3,901 3,905 3,908 3,911 3,914 3,917 3,920 3,924 | 2,420 2,423 2,425 2,428 2,431 2,434 2,436 2,439 2,442 2,445 2,448 2,450 2,453 2,456 2,459 2,461 2,464 2,467 2,470 2,472 | 97,000 97,050 97,050 97,100 97,100 97,150 97,150 97,200 97,200 97,250 97,250 97,300 97,300 97,350 97,350 97,400 97,400 97,450 97,450 97,500 97,500 97,550 97,550 97,600 97,600 97,650 97,650 97,700 97,700 97,750 97,750 97,800 97,800 97,850 97,850 97,900 97,900 97,950 97,950 98,000 | 4,054 4,057 4,061 4,064 4,067 4,070 4,073 4,077 4,080 4,083 4,086 4,089 4,092 4,096 4,099 4,102 4,105 4,108 4,112 4,115 | 2,586 2,588 2,591 2,594 2,597 2,599 2,602 2,605 2,608 2,610 2,613 2,616 2,619 2,622 2,624 2,627 2,630 2,633 2,635 2,638 |
| 89,000 | 92,000 | 95,000 | 98,000 | ||||||||
| 89,000 89,050 89,050 89,100 89,100 89,150 89,150 89,200 89,200 89,250 89,250 89,300 89,300 89,350 89,350 89,400 89,400 89,450 89,450 89,500 89,500 89,550 89,550 89,600 89,600 89,650 89,650 89,700 89,700 89,750 89,750 89,800 89,800 89,850 89,850 89,900 89,900 89,950 89,950 90,000 | 3,545 3,548 3,551 3,554 3,557 3,561 3,564 3,567 3,570 3,573 3,576 3,580 3,583 3,586 3,589 3,592 3,596 3,599 3,602 3,605 | 2,144 2,146 2,149 2,152 2,155 2,157 2,160 2,163 2,166 2,168 2,171 2,174 2,177 2,180 2,182 2,185 2,188 2,191 2,193 2,196 | 92,000 92,050 92,050 92,100 92,100 92,150 92,150 92,200 92,200 92,250 92,250 92,300 92,300 92,350 92,350 92,400 92,400 92,450 92,450 92,500 92,500 92,550 92,550 92,600 92,600 92,650 92,650 92,700 92,700 92,750 92,750 92,800 92,800 92,850 92,850 92,900 92,900 92,950 92,950 93,000 | 3,736 3,739 3,742 3,745 3,748 3,752 3,755 3,758 3,761 3,764 3,768 3,771 3,774 3,777 3,780 3,784 3,787 3,790 3,793 3,796 | 2,309 2,312 2,315 2,318 2,320 2,323 2,326 2,329 2,331 2,334 2,337 2,340 2,343 2,345 2,348 2,351 2,354 2,356 2,359 2,362 | 95,000 95,050 95,050 95,100 95,100 95,150 95,150 95,200 95,200 95,250 95,250 95,300 95,300 95,350 95,350 95,400 95,400 95,450 95,450 95,500 95,500 95,550 95,550 95,600 95,600 95,650 95,650 95,700 95,700 95,750 95,750 95,800 95,800 95,850 95,850 95,900 95,900 95,950 95,950 96,000 | 3,927 3,930 3,933 3,936 3,940 3,943 3,946 3,949 3,952 3,956 3,959 3,962 3,965 3,968 3,971 3,975 3,978 3,981 3,984 3,987 | 2,475 2,478 2,481 2,483 2,486 2,489 2,492 2,494 2,497 2,500 2,503 2,506 2,508 2,511 2,514 2,517 2,519 2,522 2,525 2,528 | 98,000 98,050 98,050 98,100 98,100 98,150 98,150 98,200 98,200 98,250 98,250 98,300 98,300 98,350 98,350 98,400 98,400 98,450 98,450 98,500 98,500 98,550 98,550 98,600 98,600 98,650 98,650 98,700 98,700 98,750 98,750 98,800 98,800 98,850 98,850 98,900 98,900 98,950 98,950 99,000 | 4,118 4,121 4,124 4,127 4,131 4,134 4,137 4,140 4,143 4,147 4,150 4,153 4,156 4,159 4,163 4,166 4,169 4,172 4,175 4,178 | 2,641 2,644 2,646 2,649 2,652 2,655 2,657 2,660 2,663 2,666 2,669 2,671 2,674 2,677 2,680 2,682 2,685 2,688 2,691 2,693 |
| 90,000 | 93,000 | 96,000 | 99,000 | ||||||||
| 90,000 90,050 90,050 90,100 90,100 90,150 90,150 90,200 90,200 90,250 90,250 90,300 90,300 90,350 90,350 90,400 90,400 90,450 90,450 90,500 90,500 90,550 90,550 90,600 90,600 90,650 90,650 90,700 90,700 90,750 90,750 90,800 90,800 90,850 90,850 90,900 90,900 90,950 90,950 91,000 | 3,608 3,612 3,615 3,618 3,621 3,624 3,627 3,631 3,634 3,637 3,640 3,643 3,647 3,650 3,653 3,656 3,659 3,662 3,666 3,669 | 2,199 2,202 2,204 2,207 2,210 2,213 2,215 2,218 2,221 2,224 2,227 2,229 2,232 2,235 2,238 2,240 2,243 2,246 2,249 2,251 | 93,000 93,050 93,050 93,100 93,100 93,150 93,150 93,200 93,200 93,250 93,250 93,300 93,300 93,350 93,350 93,400 93,400 93,450 93,450 93,500 93,500 93,550 93,550 93,600 93,600 93,650 93,650 93,700 93,700 93,750 93,750 93,800 93,800 93,850 93,850 93,900 93,900 93,950 93,950 94,000 | 3,799 3,803 3,806 3,809 3,812 3,815 3,819 3,822 3,825 3,828 3,831 3,834 3,838 3,841 3,844 3,847 3,850 3,854 3,857 3,860 | 2,365 2,367 2,370 2,373 2,376 2,378 2,381 2,384 2,387 2,389 2,392 2,395 2,398 2,401 2,403 2,406 2,409 2,412 2,414 2,417 | 96,000 96,050 96,050 96,100 96,100 96,150 96,150 96,200 96,200 96,250 96,250 96,300 96,300 96,350 96,350 96,400 96,400 96,450 96,450 96,500 96,500 96,550 96,550 96,600 96,600 96,650 96,650 96,700 96,700 96,750 96,750 96,800 96,800 96,850 96,850 96,900 96,900 96,950 96,950 97,000 | 3,991 3,994 3,997 4,000 4,003 4,006 4,010 4,013 4,016 4,019 4,022 4,026 4,029 4,032 4,035 4,038 4,042 4,045 4,048 4,051 | 2,530 2,533 2,536 2,539 2,541 2,544 2,547 2,550 2,552 2,555 2,558 2,561 2,564 2,566 2,569 2,572 2,575 2,577 2,580 2,583 | 99,000 99,050 99,050 99,100 99,100 99,150 99,150 99,200 99,200 99,250 99,250 99,300 99,300 99,350 99,350 99,400 99,400 99,450 99,450 99,500 99,500 99,550 99,550 99,600 99,600 99,650 99,650 99,700 99,700 99,750 99,750 99,800 99,800 99,850 99,850 99,900 99,900 99,950 99,950 100,000 | 4,182 4,185 4,188 4,191 4,194 4,198 4,201 4,204 4,207 4,210 4,213 4,217 4,220 4,223 4,226 4,229 4,233 4,236 4,239 4,242 | 2,696 2,699 2,702 2,704 2,707 2,710 2,713 2,715 2,718 2,721 2,724 2,727 2,729 2,732 2,735 2,738 2,740 2,743 2,746 2,749 |
# Than Than
# New Jersey Tax Rate Schedules
FILING STATUS: Single
# Table A
Married/CU partner, filing separate return
STEP 1 STEP 2 STEP 3
Enter Multiply
If Taxable Income (Line 39) is: Line 39 Line 39 by: Subtract Your Tax
Over But not over
$ 0 $ 20,000 _ .014 = - $ 0 = _
$ 20,000 $ 35,000 _ .0175 = - $ 70.00 = _
$ 35,000 $ 40,000 _ .035 = - $ 682.50 = _
$ 40,000 $ 75,000 _ .05525 = - $ 1,492.50 = _
$ 75,000 $ 500,000 _ .0637 = - $ 2,126.25 = _
$ 500,000 $ 1,000,000 _ .0897 = - $ 15,126.25 = _
$ 1,000,000 and over _ .1075 = - $ 32,926.25 = _
FILING STATUS: Married/CU couple, filing joint return
# Table B
Head of household
Qualifying widow(er)/surviving CU partner
STEP 1 STEP 2 STEP 3
Enter Multiply
If Taxable Income (Line 39) is: Line 39 Line 39 by: Subtract Your Tax
Over But not over
$ 0 $ 20,000 _ .014 = - $ 0 = _
$ 20,000 $ 50,000 _ .0175 = - $ 70.00 = _
$ 50,000 $ 70,000 _ .0245 = - $ 420.00 = _
$ 70,000 $ 80,000 _ .035 = - $ 1,154.50 = _
$ 80,000 $ 150,000 _ .05525 = - $ 2,775.00 = _
$ 150,000 $ 500,000 _ .0637 = - $ 4,042.50 = _
$ 500,000 $ 1,000,000 _ .0897 = - $ 17,042.50 = _
$ 1,000,000 and over _ .1075 = - $ 34,842.50 = _
# 2025 NJ-1040NR Tax Rate Schedules
When You Need Information… by phone…
Call our Automated Tax Information System
1 (800) 323-4400 or (609) 826‑4400.
Touch-tone phones only.
- Listen to recorded tax information on many topics.
- Order certain forms and publications through our message system.
Contact our Customer Service Center
(609) 292-6400 - Speak directly to a representative for tax information and assistance. See website for hours of operation.
Deaf, Hard of Hearing, Deaf-Blind, Speech
Disability
Visit njrelay.com or call 711. online…
Visit the NJ Division of Taxation Website
Many State tax forms and publications are available on our website at: nj.gov/taxation
You can also reach us by email with general State tax questions at: nj.taxation@treas.nj.gov
Do not include confidential information such as Social Security or federal tax identification numbers, liability or payment amounts, dates of birth, or bank account numbers in your email.
Subscribe to NJ Tax E-News, the Division of Taxation's online information service, at: nj.gov/treasury/taxation/listservice.shtml in person…
Visit a Regional Information Center
Regional Information Centers provide individual assistance at various locations throughout the State. Call the Automated Tax Information System or visit our website for the address of the center nearest you.
# To Get Forms…
- Call New Jersey's Forms Request System at 1-800-323-4400 or (609) 826-4400. Touch-tone phones only
- Visit our website at:
nj.gov/treasury/taxation/prntgit.shtml
- Write to: NJ Division of Taxation
Taxpayer Forms Services
PO Box 269
Trenton, NJ 08695-0269
# Who Can Help…
Trained volunteers in the VITA (Volunteer Income Tax Assistance) and TCE (Tax Counseling for the Elderly) programs are available to help prepare both federal and State returns at locations throughout New Jersey. For the location nearest you, contact the Division's Customer Service Center at (609) 292-6400 or the Internal Revenue Service.
# Paperless Filing…
NJ E-File. You can use NJ E-File to file Form NJ-1040NR for
2025 electronically. Use tax software you purchase, go to a tax preparation website, or have a tax preparer file the return for you.
New Jersey Online Filing. Use the free New Jersey Online Filing Service to file your 2025 NJ-1040NR. Any nonresident or partyear resident can use it to file electronically for free.
Taxpayers' Bill of Rights
The New Jersey Taxpayers' Bill of Rights simplifies tax administration and ensures that all taxpayers are better informed and receive fair and equitable treatment during the tax collection process. Highlights of the Taxpayers' Bill of Rights include:
Service-
Division must respond to taxpayers' questions within a reasonable time period.
•
Notices of taxes and penalties due must clearly identify the purpose of the notice and must contain information about appeal
- procedures.
Appeals-
- Time to appeal to the Tax Court is generally 90 days.
Interest on Refunds-
Interest is paid at the prime rate on refunds for all taxes when the Division takes more than six months to send you a refund.
•
You can request that your overpayment of this year's tax be credited towards next year's tax liability; however, interest will not
- be paid on overpayments that are credited forward.
For more information on the rights and obligations of both taxpayers and the Division of Taxation under the Taxpayers' Bill of Rights, see publication ANJ-1, New Jersey Taxpayers' Bill of Rights.
Source: view the official PDF
Nearby sections (18 sections)
- cbt-100 · Instructions for Form CBT-100 — Corporation Business Tax…
- cbt-100s · Instructions for Form CBT-100S — S Corporation Business Tax…
- cbt-100u · Instructions for Form CBT-100U — Combined Corporation…
- cbt-150 · Instructions for Form CBT-150 — Estimated Tax Voucher
- nj-1040 · Instructions for Form NJ-1040 — Resident Income Tax Return
- nj-1040es · Form NJ-1040-ES — Gross Income Tax Declaration of Estimated…
- nj-1040nr · Instructions for Form NJ-1040NR — Nonresident Income Tax…
- nj-1041 · Instructions for Form NJ-1041 — Income Tax Return for Estates…
- nj-1065 · Instructions for Form NJ-1065 — Partnership Return
- nj-1080c · Form NJ-1080-C — Nonresident Composite Income Tax Return
- nj-1080c-instructions · Instructions for Form NJ-1080-C — Nonresident…
- nj-cbt-1065 · Instructions for Form NJ-CBT-1065 — Partnership Return…
- nj-wt · Form NJ-WT — Gross Income Tax Instructions for Employers
- pte-200-t · Form PTE-200-T — BAIT Application for Extension of Time to…
- pte-k-1 · Schedule PTE-K-1 — Member's Share of Tax (BAIT)
- schedule-njk-1 · Schedule NJK-1 — Partner's Share of Income (form +…
- st-18b · Form ST-18B — Annual Business Use Tax Return & Instructions
- su-4 · Publication S&U-4 — New Jersey Sales Tax Guide
# Social Security Number
You must enter your Social Security number in the spaces provided on the return. If you are filing jointly, enter both filers' numbers in the same order as the names.
If you (or your spouse) do not have a Social Security number, contact the Social Security Administration to apply for one. If you are not eligible for a Social Security number, contact the Internal Revenue Service to get an individual taxpayer identification number (ITIN) and enter your ITIN in the spaces provided for your Social Security number. If you (or your spouse) applied for but have not received an ITIN by the return due date, enclose a copy of your federal Form W-7.