Comptroller of Maryland Form Instructions
Form MW506NRS — Return of Income Tax Withholding for Nonresident Sale of Real Property
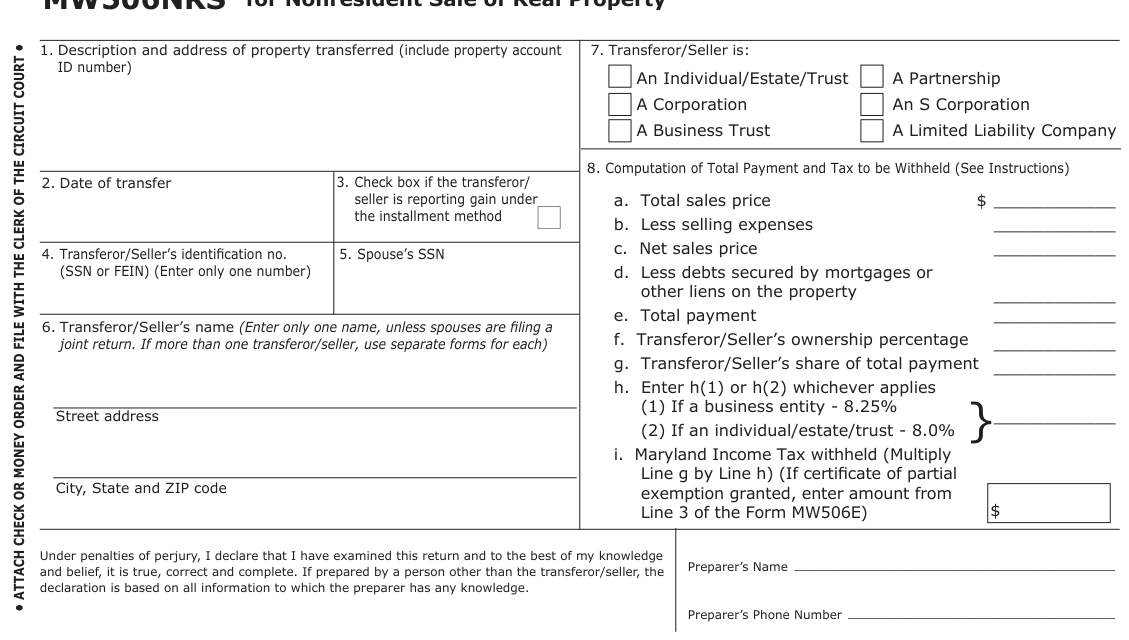
Text version of this table
| 1. Description and address of property transferred (include property account ID number) | 7. Transferor/Seller is: An Individual/Estate/Trust A Partnership A Corporation An S Corporation A Business Trust A Limited Liability Company | ||
| 8. Computation of Total Payment and Tax to be Withheld (See Instructions) a. Total sales price $_ ____________ b. Less selling expenses _ ____________ c. Net sales price _ ____________ d. Less debts secured by mortgages or other liens on the property _ ____________ e. Total payment _ ____________ f. Transferor/Seller’s ownership percentage _ ____________ g. Transferor/Seller’s share of total payment _ ____________ h. Enter h(1) or h(2) whichever applies (1) If a business entity - 8.25% } _ (2) If an individual/estate/trust - 8.0% ____________ i. Maryland Income Tax withheld (Multiply Line g by Line h) (If certifci ate of partial exemption granted, enter amount from Line 3 of the Form MW506E) $ | |||
| 2. Date of transfer | 3. Check box if the transferor/ seller is reporting gain under the installment method | ||
| 4. Transferor/Seller’s identification no. (SSN or FEIN) (Enter only one number) | 5. Spouse’s SSN | ||
| 6. Transferor/Seller’s name (Enter only one name, unless spouses are filing a joint return. If more than one transferor/seller, use separate forms for each) Street address City, State and ZIP code | |||
| Under penalties of perjury, I declare that I have examined this return and to the best of my knowledge and belief, it is true, correct and complete. If prepared by a person other than the transferor/seller, the declaration is based on all information to which the preparer has any knowledge. | Preparer’s Name_ __________________________________________ Preparer’s Phone Number_ ___________________________________ |
# City, State and ZIP code
# Preparer's Phone Number_ ___________________________________
Date
Copy A - For Comptroller of Maryland, Revenue Administration Division. (File with Clerk of the Circuit Court) Form MW506NRS is designed to assure the regular and timely collection of Maryland income tax due from nonresident sellers of real property located within the State. This form is used to determine the amount of income tax withholding due on the sale of property and provide for its collection at the time of the sale or transfer.
# Who must file Form MW506NRS
If the transferor/seller is a nonresident individual or nonresident entity, and is transferring an interest in real property located within the State of Maryland, unless the transaction is otherwise exempt from the income tax withholding requirement, the person responsible for closing must file Form MW506NRS with the deed or other instrument of transfer that will be filed with the Clerk of the Circuit Court for recordation. If there are multiple transferors/ sellers, a separate form must be completed for each nonresident individual or nonresident entity subject to the withholding requirements. The separate form requirement does not apply to spouses filing a joint Maryland income tax return.
A "nonresident entity" is defined to mean an entity that: (1) is not formed under the laws of Maryland more than 90 days before the date of sale of the property, and (2) is not qualified by or registered with the Department of Assessments and Taxation to do business in Maryland more than 90 days before the date of sale of the property.
# When to file Form MW506NRS
Unless the transaction is otherwise exempt from the income tax withholding requirement, the person responsible for closing must include with the deed or other instrument of transfer, a Form MW506NRS for each nonresident transferor/seller, when the deed or other instrument of transfer is presented to the Clerk of the Circuit Court for recordation.
# COM/RAD-308 01/22
What to file Do not enter the street address of the property being transferred.
Copies A and B of each Form MW506NRS must be Line 7. filed with the deed or other instrument of transfer Check the appropriate box for the when presented to the Clerk of the Circuit Court transferor/seller. for recordation. A separate check or money order Line 8. If a Certificate of Partial Exemption is in the aggregate amount of the tax due for each issued by the Comptroller, do not complete lines 8a nonresident transferor/seller with regard to a sale or though 8h. Instead, enter the amount from Line 3 of transfer of real property must be paid to the Clerk. the Form MW506E on Line 8i.
Give Copy C to the transferor/seller at closing. The Complete this section to determine the total issuer retains Copy D. payment allocable to the transferor/seller that is Specific Instructions subject to the income tax withholding requirements and the amount of tax required to be withheld. The Line 1. Enter the street address for the property total payment is computed by deducting from the as listed with the State Department of Assessments total sales price (including the fair market value of and Taxation (SDAT). If the property does not have a any property or other nonmonetary consideration street address, provide such descriptive information paid to or otherwise transferred to the transferor/ as is used by SDAT to identify the property. Also seller) the amount of any mortgages or other liens, include the SDAT property account ID number for the commission payable on account of the sale, and the parcel being transferred. If the property is made any other expenses due from the seller in connection up of more than one parcel and has more than with the sale. one account number, include all applicable account numbers. Line f. If there are multiple owners, enter the percentage of ownership of the transferor/ Line 2. Enter the date of transfer. The date of seller for whom this form is being filed. transfer is the effective date of the deed as defined in §3-201 of the Real Property Article, Annotated Code Line g. Multiply line e by line f to determine of Maryland. The effective date is the later of: (1) the the transferor/seller's share of the total date of the last acknowledgement; or (2) the date payment. stated in the deed.
Line h. Enter the applicable rate for the transferor/ Line 3. Check the box if the transferor/seller is seller. reporting the gain under the installment method.
# Payment of Tax
Lines 4, 5 and 6. Unless transferors/sellers Make check or money order payable to the Clerk of are spouses and filing a joint Maryland income the Circuit Court for the county or Baltimore City in tax return, a separate Form MW506NRS must be which the deed or other instrument of transfer will be completed for each transferor/seller that is entitled presented for recordation. to receive any part of the proceeds of the transfer.
Signature
Enter the tax identification number or social security Copy A of this return must be verified and signed number for the nonresident transferor/seller and the by the individual transferor/seller, an authorized social security number for the spouse, if applicable. person or officer of a business entity or the person (Do NOT enter the tax identification number on responsible for closing.
Copy B of Form MW506NRS.) Enter the name (or names, if spouses are filing a joint return) of the transferor/seller and the transferor/seller's address.
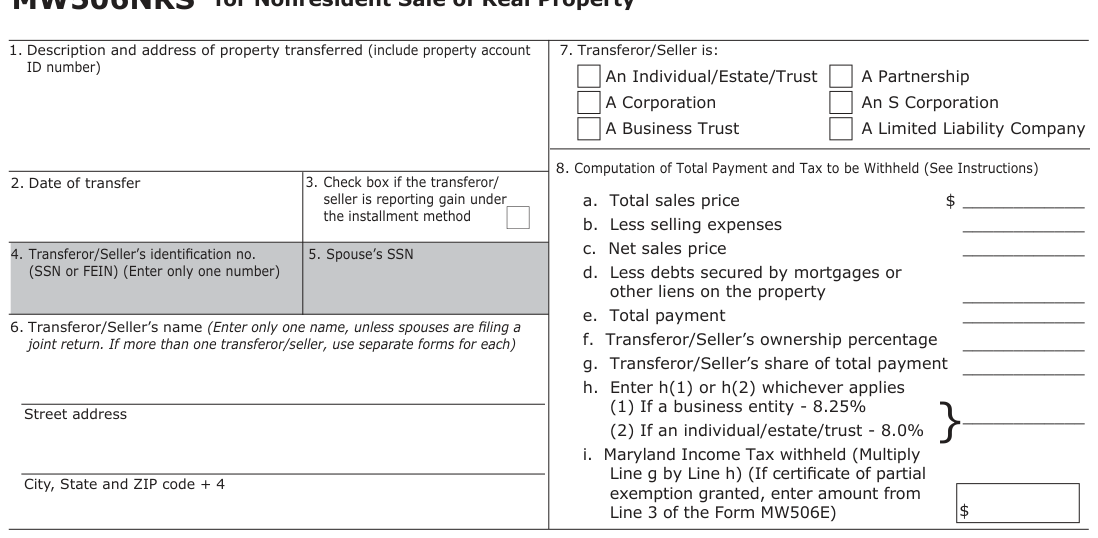
Text version of this table
| 1. Description and address of property transferred (include property account ID number) | 7. Transferor/Seller is: An Individual/Estate/Trust A Partnership A Corporation An S Corporation A Business Trust A Limited Liability Company | |
| 8. Computation of Total Payment and Tax to be Withheld (See Instructions) a. Total sales price $_ ____________ b. Less selling expenses _ ____________ c. Net sales price _ ____________ d. Less debts secured by mortgages or other liens on the property _ ____________ e. Total payment _ ____________ f. Transferor/Seller’s ownership percentage _ ____________ g. Transferor/Seller’s share of total payment _ ____________ h. Enter h(1) or h(2) whichever applies (1) If a business entity - 8.25% } _ (2) If an individual/estate/trust - 8.0% ____________ i. Maryland Income Tax withheld (Multiply Line g by Line h) (If certifci ate of partial exemption granted, enter amount from Line 3 of the Form MW506E) $ | ||
| 2. Date of transfer | 3. Check box if the transferor/ seller is reporting gain under the installment method | |
| 4. Transferor/Seller’s identification no. (SSN or FEIN) (Enter only one number) | 5. Spouse’s SSN | |
| 6. Transferor/Seller’s name (Enter only one name, unless spouses are filing a joint return. If more than one transferor/seller, use separate forms for each) Street address City, State and ZIP code + 4 |
# 4. Transferor/Seller's identification no. 5. Spouse's SSN
(SSN or FEIN) (Enter only one number) a. Total sales price $__ d. Less debts secured by mortgages or
• ATTACH CHECK OR MONEY ORDER AND FILE WITH THE CLERK OF THE CIRCUIT COURT •
}
$
Copy B - For Clerk of the Court regular and timely collection of Maryland income tax due from nonresident sellers of real property located within the State. This form is used to determine the amount of income tax withholding due on the sale of property and provide for its collection at the time of the sale or transfer.
A copy of each Copy A will be filed with Form MW508NRS on or before the 21st day of the month following the month in which the Form MW506NRS is filed with the Clerk of the Circuit Court. The Clerk of the Circuit Court shall remit the forms to the Comptroller of Maryland in accordance with the instructions for Form MW508NRS.
}
$
Copy C - For Transferor/Seller (Records Copy). regular and timely collection of Maryland income tax due from nonresident sellers of real property located within the State. This form is used to determine the amount of income tax withholding due on the sale of property and provide for its collection at the time of the sale or transfer.
Who must file
A nonresident individual or nonresident entity that sells real property located in Maryland must file a Maryland income tax return. The appropriate income tax return must be filed for the year in which the transfer of the real property occurred. The due date for each income tax return type can be found in the instructions to the specific income tax return.
The nonresident individual or nonresident entity must file the appropriate Maryland income tax return for the year in which the transfer of the property occurred. Do NOT submit Copy C of the Form MW506NRS with the return filed with the Comptroller of Maryland. See the specific instructions for the tax return being filed.
Specific Instructions for Transferor/Seller
How to claim the tax withheld
The manner in which the income tax withheld is claimed by the nonresident individual or nonresident entity depends on the type of
# Trusts and Estates
Maryland income tax return you are required to file. Follow the specific instructions below.
Trustees of trusts and personal representatives Claiming the income tax withheld on a line of estates are required to file a Maryland other than as described below may result in the Fiduciary Income Tax Return (Form 504). The withholding being denied. income tax withheld and reported on Line 8 of Individuals and Revocable Living Trusts the Form MW506NRS must be claimed as an estimated tax payment.
Nonresident individuals are required to file a
Nonresident Maryland Income Tax Return (Form 505). The income tax withheld and reported on Line 8 of the Form MW506NRS must be claimed as an estimated income tax payment.
C Corporations
C corporations are required to file a Maryland Corporation Income Tax Return (Form 500). The income tax withheld and reported on Line 8 of the Form MW506NRS must be claimed as an estimated income tax payment.
S Corporations, Partnerships and Limited
# Liability Companies and Business Trusts
S corporations, partnerships and limited liability companies and business trusts that elect to be treated as pass-through entities must file a Maryland Pass-Through Entity Income Tax Return (Form 510). The income tax withheld and reported on Line 8 of the Form MW506NRS must be claimed as an estimated income tax payment.
This tax, and any other tax paid with the Form 510 must be allocated to the nonresident shareholders, partners or members and reported on a modified federal Schedule K-1 or Maryland statement. All tax allocated to a nonresident shareholder, partner or member must be claimed as a nonresident tax paid by S corporations, or other unincorporated business entities.
}
$
Copy D - For Issuer regular and timely collection of Maryland income tax due from nonresident sellers of real property located within the State. This form is used to determine the amount of income tax withholding due on the sale of property and provide for its collection at the time of the sale or transfer.
# Who must file Form MW506NRS
If the transferor/seller is a nonresident individual or entity, and is transferring an interest in real property located within the State of Maryland, unless the transaction is otherwise exempt from the income tax withholding requirement, the person responsible for closing must file Form MW506NRS with the deed or other instrument of transfer that will be filed with the Clerk of the Circuit Court for recordation. If there are multiple transferors/sellers, a separate form must be completed for each nonresident individual or nonresident entity subject to the withholding requirements. The separate form requirement does not apply to spouses filing a joint Maryland income tax return.
# When to file Form MW506NRS
Unless the transaction is otherwise exempt from the income tax withholding requirement, the person responsible for closing must include with the deed or other instrument of transfer, a Form MW506NRS for each nonresident transferor/ seller, when the deed or other instrument of transfer is presented to the Clerk of the Circuit Court for recordation.
Copies A and B of each Form MW506NRS must be filed with the deed or other instrument of tax identification number on Copy B of Form transfer when presented to the Clerk of the MW506NRS.) Enter the name (or names, if Circuit Court for recordation. A separate check spouses filing a joint return) of the transferor/ or money order in the aggregate amount of the seller and the transferor/seller's address. Do tax due for each nonresident transferor/seller not enter the street address of the property with regard to a sale or transfer of real property being transferred. must be paid to the Clerk.
Line 7. Check the appropriate box for the Give Copy C to the transferor/seller at closing. transferor/seller.
The issuer retains Copy D.
Line 8. If a Certificate of Partial Exemption is Specific Instructions issued by the Comptroller, do not complete lines 8a though 8h. Instead, enter the amount from
Line 1. Enter the street address for the Line 3 of the Form MW506E on Line 8i. property as listed with the State Department of Assessments and Taxation (SDAT). If the Complete this section to determine the total property does not have a street address, payment allocable to the transferor/seller provide such descriptive information as is used that is subject to the income tax withholding by SDAT to identify the property. Also include requirements and the amount of tax required to the SDATproperty account ID number for the be withheld. The total payment is computed by parcel being transferred. If the property is made deducting from the total sales price (including up of more than one parcel and has more than the fair market value of any property or other one account number, include all applicable nonmonetary consideration paid to or otherwise account numbers. transferred to the transferor/seller) the amount of any mortgages or other liens, the commission Line 2. Enter the date of transfer. The date payable on account of the sale and any other of transfer is the effective date of the deed as expenses due from the seller in connection with defined in §3-201 of the Real Property Article, the sale.
Annotated Code of Maryland. The effective date is the later of: (1) the date of the last Line f. If there are multiple owners, enter acknowledgement; or (2) the date stated in the the percentage of ownership of the transferor/ deed. seller for whom this form is being filed.
Line 3. Check the box if the transferor/seller Line g. Multiply line e by line f to determine is reporting the gain under the installment the transferor/seller's share of the total method. payment.
Lines 4, 5 and 6. Unless transferors/sellers Line h. Enter the applicable rate for the are spouses and filing a joint Maryland income transferor/seller. tax return, a separate Form MW506NRS must Payment of Tax be completed for each transferor/seller that is Make check or money order payable to the Clerk entitled to receive any part of the proceeds of of the Circuit Court for the county or Baltimore the transfer. Enter the tax identification number City in which the deed or other instrument of or social security number for the nonresident transfer will be presented for recordation. transferor/seller and the social security number for the spouse, if applicable. (Do NOT enter the
Source: view the official PDF
Nearby sections (17 sections)
- 500e · Form 500E — Application for Extension to File Corporation Income…
- 500up · Form 500UP — Underpayment of Estimated Income Tax by…
- 502 · Form 502 — Maryland Resident Income Tax Return (Resident Booklet,…
- 502cr · Form 502CR — Income Tax Credits for Individuals (with…
- 502up · Form 502UP — Underpayment of Estimated Income Tax by Individuals
- 502x · Form 502X — Maryland Amended Tax Return (with instructions)
- 504 · Form 504 — Maryland Fiduciary Income Tax Return (Fiduciary…
- 505 · Form 505 — Maryland Nonresident Income Tax Return (Nonresident…
- 505x · Form 505X — Maryland Nonresident Amended Tax Return (with…
- 510 · Form 510 — Pass-Through Entity Income Tax Return (with…
- 510c · Form 510C — Maryland Composite Pass-Through Entity Income Tax…
- 511 · Form 511 — Pass-Through Entity Election Income Tax Return (PTE…
- mw506nrs · Form MW506NRS — Return of Income Tax Withholding for…
- mw507 · Form MW507 — Employee's Maryland Withholding Exemption…
- mw508 · Form MW508 — Annual Employer Withholding Reconciliation Return
- pv · Form PV — Personal Tax Payment Voucher
- sut202 · Form 202 — Maryland Sales and Use Tax Return (instructions)