Comptroller of Maryland Form Instructions
Form 500UP — Underpayment of Estimated Income Tax by Corporations and PTEs
# UNDERPAYMENT OF
MARYLAND
FORM ESTIMATED INCOME TAX
# ENTITIES
ATTACH TO FORMS 500, 510 OR 511.
OR FISCAL YEAR BEGINNING 2024, ENDING
Federal Employer Identification Number (9 digits) Name as shown on Forms 500, 510 or 511
IMPORTANT: REVIEW THE INSTRUCTIONS BEFORE COMPLETING THIS FORM.
EXCEPTIONS WHICH AVOID INTEREST AND PENALTY
NO INTEREST OR PENALTY IS DUE AND THIS FORM SHOULD NOT BE FILED IF:
A. The tax developed for the current tax year is $1,000 or less; or, Four payments of not less than 25% of the required estimated tax were filed on or before the 15th day of the 4th, 6th, 9th
B. and 12th months of the tax year and total either (1) 90% of the tax developed for the current tax year or (2) 110% of the tax that was developed for the prior tax year; or,
C. If the entity has a short tax period of less than 4 months.
CALCULATION OF INTEREST AND PENALTY
Tax for current tax year (line 14 of Form 500 or line 15 of Form 510 or line 12 of Form 511)
- less any Business Tax Credits or Heritage Structure Rehabilitation Tax Credits (or credit for tax paid on behalf of nonresident/resident entities by a pass-through entity). . . . . . . . . . . . 1.
Enter 90% of the amount on line 1. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . 2.
2.
Tax for prior tax year (line 14 of prior year Form 500, or line 15 of Form 510, or line 12
3a. of Form 511) less any Business Tax Credits or Heritage Structure Rehabilitation Tax Credits.. 3a.
Multiply line 3a by 110%. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . 3b.
3b.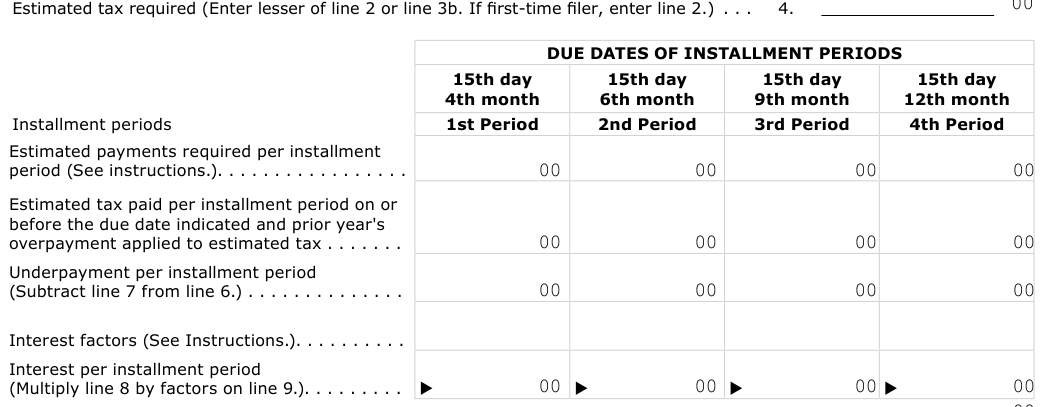
Text version of this table
DUE DATES OF INSTALLMENT PERIODS 15th day 4th month 15th day 6th month 15th day 9th month 15th day 12th month 1st Period 2nd Period 3rd Period 4th Period 00 00 00 00 00 00 00 00 00 00 00 00 00 00 00 00
Total interest (Add all amounts on line 10.). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . 11.
11.
Penalty (See instructions.). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . 12.
12.
- Total interest and penalty (Add lines 11 and 12.) Also enter this amount on line 18 of Form 500 or line 19 of Form 510 or line 16 of Form 511.. . . . . . . . . . . . . . . . . . . . . . . . . 13.
COM/RAD-005 08/24
MARYLAND UNDERPAYMENT OF ESTIMATED
FORM
# INSTRUCTIONS
GENERAL INSTRUCTIONS
Purpose of Form Form 500UP is used by a corporation or a pass-through entity to calculate the amount of interest and penalty for failure to pay the required amount of estimated income tax when due.
NOTE: Form 500UP is not required. The Revenue Administration Division will calculate the interest and penalty and notify the entity of any balance due.
General Requirements Every corporation or pass-through entity that reasonably expects its Maryland taxable income to develop a tax in excess of $1,000 for the tax year or period must make estimated income tax payments. The total estimated tax payments for the year must be at least 90% of the tax developed for the current tax year or 110% of the tax that was developed for the prior tax year. At least 25% of the total estimated tax must be remitted by each of the four installment due dates. Corporations may not use the annualization method.
In the case of a short tax period, the total estimated tax required is the same as for a regular tax year: 90% of the tax developed for the current (short) tax year or 110% of the tax that was developed for the prior tax year. The minimum estimated tax payment for each of the installment due dates is the total estimated tax required divided by the number of installment due dates occurring during the short tax year.
However, if the entity has a short tax period of less than 4 months, it does not have to pay estimated tax nor file Form 500UP.
Maryland law provides for the accrual of interest and imposition of penalty for failure to pay the required amount of estimated tax when due.
When and Where to File File Form 500UP by the original or extended due date for filing the Form 500 - Corporation Income Tax Return or Form 510 - Pass - Through Entity Income Tax Return or Form 511 - Pass - Through Entity Election Income Tax Return. If used, Form 500UP must be attached to Form 500 or Form 510 or Form 511 and filed with the Comptroller of Maryland, Revenue Administration Division, 110 Carroll Street, Annapolis, Maryland 21411-0001.
SPECIFIC INSTRUCTIONS
Name and Other Information Type or print the name as shown on Form 500, Form 510, or Form 511 in the designated area. Enter the Federal Employer Identification Number (FEIN).
If a FEIN has not been secured, enter "APPLIED FOR" followed by the date of application. If a FEIN has not been applied for, do so immediately.
Tax Year or Period Enter the beginning and ending dates in the space provided at the top of Form 500UP. The form used for filing must reflect the preprinted tax year in which the corporation's tax year begins.
Calculation of Interest and Penalty Enter the amounts as required for lines 1 through 13.
Instructions for Line 6: The first period extends from the beginning of the entity's fiscal year to the last day of the third month. The second period extends from the beginning of the fiscal year to the last day of the sixth month. The third period extends from the beginning of the fiscal year to the last day of the ninth month. The fourth period extends from the beginning of the fiscal year to the last day of the twelfth month. Therefore, enter 1/4 of the estimated tax required on line 4 in the first column of line 6, 1/2 in the second column, 3/4 in the third column and an amount equal to line 4 in the COM/RAD-005 08/24 fourth column. For Pass-Through Entities (PTE), see specific instructions.
Instructions for Line 7: Enter all payments made by the due date of the fourth quarterly estimated tax payment in the appropriate column according to the instructions for line 6.
That is, all payments made by the 15th day of the fourth month of the entity's fiscal year should be entered in the first column. All payments made by the 15th day of the sixth month (including those shown in the first column) should be entered in the second column. All payments made by the 15th day of the ninth month should be entered in the third column and all payments made by the fourth quarter due date should be entered in the fourth column.
Instructions for Line 9: The interest factors for calendar year are as follow: For corporations, 1st period - .0167; 2nd period - . 0250; 3rd period - . 0250; and 4th period - .0378.
For S corporations, 1st period - .0167; 2nd period - . 0252;
3rd period - .0249; and 4th period - .0374. For partnerships or limited liability companies, 1st period - .0167; 2nd period
- . 0252; 3rd period - .0340; and 4th period - .0283.
The factors represent the interest rate for the portion of the year between the due date of each quarter and the due date of the next quarter. Interest is computed at a rate of 0.8339% per month for due dates prior to January 1, 2025. Interest is computed at a rate of 0.9568% per month after December 31,
- For more information, visit marylandtaxes.gov If your estimated tax payment was not timely, but was paid earlier than the due date of the next quarter, adjust the factor as follows for calendar year filers:
1st Period - For payments due by April 15, 2024 that were not paid by July 15, 2024 but paid earlier than June 15, 2024, count the number of months from the due date of April 15, 2024 that the payment was late. Treat a partial month as one month. Divide that number by twelve and multiply it by the 10.0075% annual rate. Apply this adjusted factor to the underpaid amount on line 8.
2nd Period - For payments due by June 15, 2024 that were not paid by July 15, 2024 but paid earlier than September 15, 2024, count the number of months from the due date of June 15, 2024 that the payment was late. Treat a partial month as one month. Divide that number by twelve and multiply it by the 10.0075% annual rate. Apply this adjusted factor to the underpaid amount on line 8.
3rd Period - Corporations and S Corporations - For payments due by September 15, 2024 that were not paid by September 15, 2024 but paid earlier than December 15, 2024, count the number of months from the due date of September 15, 2024 that the payment was late. Treat a partial month as one month. Divide that number by twelve and multiply it by the 10.0075% annual rate. Apply this adjusted factor to the underpaid amount on line 8.
Other PTEs - For payments due by September 15, 2024 that were not paid by September 15, 2024 but paid earlier than December 15, 2024, count the number of months from the due date of September 15, 2024 that the payment was late.
Treat a partial month as one month. Divide that number by twelve and multiply it by the 10.0075% annual rate. Apply this adjusted factor to the underpaid amount on line 8. For payments made on or later than December 15, 2024, apply the interest factor of .0249 to the underpaid amount on line 8.
4th Period -Corporations - For payments due by December 15, 2024 that were not paid by December 15, 2024 but paid earlier than April 15, 2025, determine when
MARYLAND
FORM
# INSTRUCTIONS
COM/RAD-005 08/24 the payment was made and apply the appropriate factor below to the underpaid amount on line 8.
- For payments made after December 15, 2024 but before January 15, 2025, apply the adjusted factor of .0091 to the underpaid amount on line 8.
- For payments made after January 15, 2025 but before February 15, 2025, apply the adjusted factor of .0187 to the underpaid amount on line 8.
- For payments made after February 15, 2025 but before March 15, 2025, apply the adjusted factor of .0282 to the underpaid amount on line 8.
- For payments made after March 15, 2025 but before April 15, 2025, apply the interest factor of .0378 to the underpaid amount on line 8.
4th Period - S-Corporations - For payments due by December 15, 2024 that were not paid by December 15, 2024 but paid earlier than April 15, 2025, determine when the payment was made and apply the appropriate factor below to the underpaid amount on line 8
- For payments made after December 15, 2024 but before January 15, 2025, apply the adjusted factor of .0091 to the underpaid amount on line 8.
- For payments made after January 15, 2025 but before February 15, 2025, apply the adjusted factor of .0188 to the underpaid amount on line 8.
- For payments made after February 15, 2025 but before March 15, 2025, apply the adjusted factor of .0276 to the underpaid amount on line 8.
- For payments made after March 15, 2025 but before April 15, 2025, apply the interest factor of .0374 to the underpaid amount on line 8.
Other PTEs - For payments due by January 15, 2025 that were not paid by January 15, 2025 but paid earlier than April 15, 2025, count the number of months from the due date of January 15, 2025 that the payment was late. Treat a partial month as one month. Divide that number by twelve and multiply it by the 11.4825% annual rate. Apply this adjusted factor to the underpaid amount on line 8.
Instructions for Line 12: Penalty for underpayment of estimated tax is due for any quarter where timely payments are less than 50% of one-quarter of the annual estimated tax required (line 4). Calculate the penalty by adding the underpayments in all applicable quarters (do not use cumulative amounts from line 8) and multiplying the total by 10%. Enter the result on line 12.
Pass-Through Entities The due dates of estimated payments and annual returns for S corporations are the same as the due dates for corporations. For other PTEs, the due date, for the fourth quarterly payment is the 15th day of the month following the close of the tax year (January 15 for calendar year filers). This difference will cause variations in the interest factors.
Partnerships and limited liability companies electing to annualize must allocate to each period (and enter on line 6) a payment amount based on the income received between the dates for each installment period. If the interest calculated on line 11 is zero because the income was not received evenly throughout the year, enter code number "301" on one of the lines marked "code number" on the front of Form 510 or Form 511, and attach this form to the return.
Source: view the official PDF
Nearby sections (15 sections)
- 500 · Form 500 — Maryland Corporation Income Tax Return (Corporate…
- 500e · Form 500E — Application for Extension to File Corporation Income…
- 500up · Form 500UP — Underpayment of Estimated Income Tax by…
- 502 · Form 502 — Maryland Resident Income Tax Return (Resident Booklet,…
- 502cr · Form 502CR — Income Tax Credits for Individuals (with…
- 502up · Form 502UP — Underpayment of Estimated Income Tax by Individuals
- 502x · Form 502X — Maryland Amended Tax Return (with instructions)
- 504 · Form 504 — Maryland Fiduciary Income Tax Return (Fiduciary…
- 505 · Form 505 — Maryland Nonresident Income Tax Return (Nonresident…
- 505x · Form 505X — Maryland Nonresident Amended Tax Return (with…
- 510 · Form 510 — Pass-Through Entity Income Tax Return (with…
- 510c · Form 510C — Maryland Composite Pass-Through Entity Income Tax…
- 511 · Form 511 — Pass-Through Entity Election Income Tax Return (PTE…
- mw506nrs · Form MW506NRS — Return of Income Tax Withholding for…
- mw507 · Form MW507 — Employee's Maryland Withholding Exemption…