Comptroller of Maryland Form Instructions
Form 504 — Maryland Fiduciary Income Tax Return (Fiduciary Booklet, instructions)
Brooke E. Lierman, Comptroller
MARYLAND
2 0 2 4
# MARYLAND
2 0 2 4
Instructions for filing fiduciary income tax returns for calendar year or any other tax year or period beginning in 2024
Instruction Page
- WHO MUST FILE? … 1
- USE OF FEDERAL RETURN. . . . . . 1
- NAME, ADDRESS AND OTHER
INFORMATION … 1
- TYPE OF ENTITY … 2
- DECEDENT'S ESTATE
INFORMATION … 2
- RESIDENT STATUS … 2
- MARYLAND MODIFICATIONS . . . . 3
- NONRESIDENT BENEFICIARY
DEDUCTION … 4
- INCOME … 5
- EXEMPTION … 5
- FIGURE YOUR MARYLAND
TAXABLE INCOME … 5
- MARYLAND TAX … 5
- INSTRUCTIONS FOR MARYLAND
FORM 504NR … 6
- SPECIAL NONRESIDENT TAX . . . . 6
- LOCAL INCOME TAX … 6
- TOTAL MARYLAND TAX, LOCAL
TAX AND CONTRIBUTIONS . . . . . 7
- TAXES PAID AND CREDITS . . . . . 7
- OVERPAYMENT OR BALANCE DUE. 8
- TELEPHONE NUMBER, CODE
NUMBERS, SIGNATURES AND
ATTACHMENTS … 9
- MAILING YOUR RETURN . . . . . . . 9
- PAYMENT INSTRUCTIONS . . . . . . 9
- DUE DATE … 9
- EXTENSION OF TIME TO FILE. . . . 9
- FISCAL YEAR … 9
- AMENDED RETURNS … 9
- SPECIAL INSTRUCTIONS FOR
BANKRUPTCY ESTATES. . . . . . . 10
- QUALIFIED FUNERAL TRUST . . . 10
- PRIVACY ACT INFORMATION. . . 10
Read this before filling out your forms!
- The top state income tax rate for resident fiduciaries is 5.75 percent for tax year
- For nonresident fiduciaries there is an additional income tax rate of 2.25 percent.
- Form 504NR is a required attachment for nonresident fiduciaries who have any modifications to the federal income, as well as to allow a nonresident fiduciary to adjust the Maryland tax based upon non-Maryland income received. See instructions relating to Form 504NR.
- Nonresident fiduciary members of a pass-through entity who have had tax paid for them may claim the credit on Form 504.
- Fiduciaries required to file federal Form 990-T are required to file and pay income tax to Maryland on their unrelated business income attributable to Maryland sources.
- A contribution can be made to four programs on your return: The Chesapeake Bay and Endangered Species Trust Fund, the Developmental Disabilities Services and Support Fund, the Maryland Cancer Fund and the Fair Campaign Financing Fund.
- Resident fiduciaries must include an addition for the amount of income of an Electing Small Business Trust (ESBT) that is subject to the special taxing rules under Internal Revenue Code Section 641(c). Nonresident fiduciaries must include this income as an addition to the extent the ESBT income is allocable to Maryland.
# WHAT'S NEW FOR 2024
- Police Auxiliary and Reserve Volunteers Subtraction Modification - Senate Bill 108/House Bill 646: This bill combines the existing subtraction for volunteer fire, rescue, or emergency medical services with the existing subtraction for police auxiliary or reserve volunteers. The subtraction amount for all volunteers is $7,000. Reporting requirements remain the same for qualifying organizations.
• Donations to Diaper Banks and Other Charitable Entities Sunset Extension
- House Bill 490: This bill extends the sunset date of the diaper bank income tax subtraction through tax year 2026.
- State Law Enforcement Officers Subtraction Modification - Senate Bill 822:
This bill expands the current subtraction for income earned by a law enforcement officer to any State law enforcement officer residing in a political subdivision in which the crime rate exceeds the State's crime rate.
• Law Enforcement Officers and Fire Fighters Death Benefit Subtraction
Modification- Senate Bill 897/House Bill 1064: This emergency bill expands the existing subtraction to include a payment of a death benefit under a collective bargaining agreement from a Maryland county or municipality to the beneficiary of a law enforcement officer or firefighter who has died in the line of duty.
- Maryland Protecting Opportunities and Regional Trade (PORT) Act -Senate Bill 1188/House Bill 1526: This bill creates a new subtraction for benefit payments made to an individual or family member of an individual injured or killed in the collapse of the Francis Scott Key Bridge and tuition assistance provided to students through the Fallen Transportation Workers Scholarship Fund.
- Horse Racing Facility Ownership and Construction - House Bill 1524: This bill amends the subtraction for income recognized before, on, or after June 1, 2024, from the sale of property within or the expenditure of government funds on Laurel Park in Anne Arundel County, Pimlico Race Course in Baltimore City, or Bowie Race Course Training Center in Prince George's County.
- Venison Donation Income Tax Credit - Senate Bill 440/House Bill 447:
This bill provides an income tax credit for up to $75 per deer ($300 maximum) in expenses incurred to butcher and process an antlerless deer for human consumption if harvested and donated to an IRC §501(c)(3) nonprofit organization. The total annual credit may exceed $300 if the individual has a deer management permit.
- Catalytic Revitalization Project Tax Credit Alterations - Senate Bill 394:
This bill specifies the credit certificate may now be issued by the Maryland Department of Housing and Community Development in one of two ways: (1) for a project issued a single tax credit on completion, the taxpayer may claim a credit of 20% of the amount stated on the certificate for 5 consecutive years; and (2) for a phased project issued on completion of a phase, the taxpayer may claim 100% of the amount stated on the certificate.
• New Local Tax Brackets:
Anne Arundel Co. The local tax rates for taxable year 2024 areas follows:
(1) .0270 of a fiduciary's Maryland taxable income of $1 through $50,000;
(2) .0281 of a fiduciary's Maryland taxable income of $50,001 through $400,000; and
(3) .0320 of a fiduciary's Maryland taxable income of over $400,000.
Frederick Co. The local tax rates for taxable year 2024 areas follows: i Use blue or black ink when completing your forms and checks. To avoid delays in the processing of your return: do not print returns on colored paper; do not write on, staple, or punch holes in the barcode.
# MARYLAND FIDUCIARY TAX RETURN
(1) .0225 for fiduciary taxpayers who have a net taxable income between $1 and not exceeding $25,000;
(2) .0275 for fiduciary taxpayers who have a net taxable income between $25,001 and not exceeding $50,000;
(3) .0296 for fiduciary taxpayers who have a net taxable income between $50,001 and not exceeding $150,000; and
(4) .0320 for fiduciary taxpayers who have a net taxable income of $150,001 or more.
# FORMS REQUEST
Forms can be requested by mail or by phone as follows:
By Email … taxforms@marylandtaxes.gov.
By phone … 410-260-7951
# FREE STATE TAX ASSISTANCE
By Email … taxhelp@marylandtaxes.gov.
Email your tax questions.
By phone … 1-800-MDTAXES from Central Maryland … 410-260-7980 February 1 - April 15, 2025, Monday - Friday, 8:30a.m. - 6:00p.m.
Filing electronically The State of Maryland participates in the Federal/State Modernized e-File program to file Fiduciary returns electronically. For the list of Software Vendors approved for e-filing Maryland returns or for additional program information, visit marylandtaxes.gov. You may also contact our e-File Helpdesk by emailing efil@marylandtaxes.gov or calling 410-260-7753. ii
# Purpose of Form
Maryland follows federal income tax treatment for fiduciaries of trusts and estates. Generally, under federal income tax rules, any income distributed by the fiduciary of the trust or estate during the tax year is not taxable to the trust or estate.
Instead, that income is taxable to the beneficiary. Any income not distributed or partially distributed by the fiduciary of the trust or estate during the tax year is taxable to the fiduciary.
Fiduciary Income Tax Return, Form 504, is used to report and pay the Maryland income tax on the income taxable to the fiduciary of the trust or estate.
Maryland taxes the portion of an Electing Small Business Trust (ESBT), that consists of stock in one or more S corporations, that is subject to special taxing rules on the federal Form 1041.
See Instructions 4 and 10, as well as Administrative Release 16 for more information.
# Due Date
Your return is due by April 15, 2025. If you are a fiscal year taxpayer, see Instruction 24.
If the due date falls on a Saturday, Sunday or legal holiday, the return must be filed by the next business day.
Completing the return
You must write legibly using blue or black ink when completing your return. DO NOT use pencil or red ink. Submit the original form, not a photocopy. If no entry is needed for a specific line, leave blank. Do not enter words such as "none" or "zero" and do not draw a line to indicate no entry. Failure to follow these instructions may delay the processing of your return.
You may round off all cents to the nearest whole dollar. Fifty cents and above should be rounded to the next higher dollar.
State calculations are rounded to the nearest penny.
Penalties
There are severe penalties for failing to file a tax return, failing to pay any tax when due, filing a false or fraudulent return or making a false certification. The penalties include criminal fines, imprisonment and a penalty on your taxes. In addition, interest is charged on amounts not paid when due.
To collect unpaid taxes, the Comptroller is directed to enter liens against the salary, wages or property of delinquent taxpayers.
Substitute forms
You may file your Maryland income tax return on a computerprepared or computer-generated substitute form provided the form is approved in advance by the Revenue Administration Division. The fact that a software package is available for retail purchase does not guarantee that it has been approved for use.
For additional information or to see a list of Approved Software Vendors for Maryland Substitute Tax Forms, visit marylandtaxes.gov.
Who must file?
A fiduciary must file a Maryland fiduciary tax return (Form 504) if the fiduciary:
- Is required to file a federal fiduciary income tax return or is exempt from tax under Sections 408(e)(1) or 501 of the Internal Revenue Code (IRC), but is required to file federal Form 990-T to report unrelated business taxable income, and
- Has Maryland taxable income.
Form 504 is used by both resident and nonresident fiduciaries.
Who is a fiduciary?
"Fiduciary" means any person by whom the legal title to real or personal property is held for the use and benefit of another and includes a trustee of a trust and a personal representative of an estate.
Although you may be required to file a federal income tax return, you are not required to file the Maryland fiduciary return if you are:
- An agent holding custody or possession of property owned by your principal; or,
- A guardian.
Instead, file the applicable income tax return of the principal or, in the case of guardian, the return of the minor or disabled person.
Who is a resident fiduciary?
A personal representative of an estate is considered a resident fiduciary if the decedent was domiciled in Maryland on the date of the decedent's death.
Fiduciaries other than personal representatives are considered residents of Maryland if:
- The trust was created by the will of a decedent who was domiciled in Maryland on the date of death;
- The trust consists of property transferred by the will of a decedent who was domiciled in Maryland on the date of death;
- The creator or grantor of the trust is a current resident of Maryland; or,
- The trust is principally administered in Maryland.
A resident fiduciary is taxable on all its income from whatever source derived.
Who is a nonresident fiduciary?
A nonresident fiduciary is a fiduciary who is not included in the above definition of a resident fiduciary. See Administrative Release 16 at marylandtaxes.gov.
A nonresident fiduciary is taxable only on income from sources within Maryland. See Instruction 7, Form 504 Schedule A -Fiduciary's Share of Maryland Modifications, and complete Forms 504 and 504NR.
Use of federal return
You will need information from your federal fiduciary return to complete your Maryland return. Therefore, complete your federal fiduciary return before you continue beyond this point.
Maryland law requires that you start with the federal taxable income reported on your federal fiduciary return. All items reported on your Maryland return are subject to verification, audit, and revision by the Comptroller's Office.
# Name, Address and Other Information
Print or type the required information in the designated areas.
Enter the Federal Employer Identification Number (FEIN) of the estate or trust in the space provided.
Type of entity
Check the box(es) on the return corresponding to your federal return. The types of entities are described below:
# Decedent's Estate
An estate of a deceased person is a taxable entity separate from the decedent. It generally continues to exist until the final distribution of the assets of the estate is made to the heirs and other beneficiaries. The income earned from the property of the estate during the period of administration or settlement must be accounted for and reported by the estate.
# Simple Trust
A trust may qualify as a simple trust if:
- The trust instrument requires that all income must be distributed currently;
- The trust instrument does not provide that any amounts are to be paid, permanently set aside, or used for charitable purposes; and
- The trust does not distribute amounts allocated to the corpus of the trust.
Because the income is distributed each year, the fiduciary may be required to file a fiduciary return, but there is no taxable income. A fiduciary is required to file a fiduciary return if the trust is a member of a pass-through entity (PTE) and nonresident PTE tax was paid on its behalf.
# Complex Trust
If some or none of the income is distributed, the trust is called a complex trust.
Because the trust is retaining all or part of the income, the fiduciary must file a fiduciary tax return to determine the taxable income from which to develop both State and local tax due.
# Grantor Trust
Income earned by a grantor trust is taxable to the grantor, not the beneficiary, if the grantor keeps certain control over the trust. This rule applies if the property (or income from the property) put into the trust will or may revert (be returned) to the grantor or the grantor's spouse. The grantor is the one who transferred property to the trust.
Generally, a trust is a grantor trust if the grantor has a reversionary interest valued (on the date of transfer) at more than 5% of the value of the transferred property.
# Bankruptcy Estate
The bankruptcy trustee or debtor-in-possession must file Form 504 for the estate of an individual involved in bankruptcy proceedings under Chapter 7 or 11 of Title 11 of the United States Code, if the estate was required to file federal Form 1041. See
# Instruction 26. Qualified Funeral Trust
Maryland recognizes and follows federal law in the treatment of qualified funeral trusts. Maryland accepts the filing of composite returns for such trusts.
In most, if not all, cases, the income of each individual trust account does not exceed $1,000. Therefore, the applicable state tax rate is 2%, and the applicable local tax rate is the rate for the situs of the fiduciary filing the composite return.
For example, if the funeral home is located in Baltimore County, then the local rate for Baltimore County would apply to each trust included in the composite return. See Instruction 27.
Electing Small Business Trust (ESBT)
Electing Small Business Trust (ESBT) is a trust that computes tax on the S-portion of income on a separate federal schedule pursuant to IRC 641(c), instead of including this income in the trust's federal adjusted gross income. This S-portion of income is an addition modification. See Instruction 10.
Other
Check box 8 if you are the fiduciary filing for one of the following entities:
• Pooled Income Fund
A pooled income fund is a split-interest trust with a remainder interest for a public charity and a life income interest retained by the donor or for another person. The property is held in a pool with other pooled income fund property and does not include any tax-exempt securities.
The income for a retained life interest is figured using the yearly rate of return earned by the trust.
• Qualified Disabilities Trust Fund
A trust created solely for an individual under 65 years of age who is disabled.
• Alaskan Native Settlement Trust
A settlement trust created within the meaning of the Alaska Native Claims Settlement Act.
- Tax-Exempt Trust with Unrelated Business Taxable
Income required to file federal Form 990-T
If the fiduciaries for the following entity types are required to file federal Form 990-T, they are required to file and pay income tax to Maryland on their unrelated business taxable income attributable to Maryland sources:
° Tax-exempt charitable trusts
° Individual Retirement Accounts (IRAs)
° Simplified Employee Pensions (SEPs)
° Simple Retirement Accounts (SIMPLE)
° Roth IRAs
° Coverdell Education Savings Accounts (ESAs)
° Archer Medical Savings Accounts
° Qualified tuition programs (Section 529 Plans)
° Health Savings Accounts (HSAs)
Decedent's estate information
If the fiduciary return is for a decedent's estate, enter the following in the appropriate sections for Date of death, Domicile state of decedent, and Decedent's Social Security Number.
Check the box if this is the final return. If the return is not for a calendar year, enter the fiscal year's beginning and ending dates at the top of the form.
Resident status
Read the instructions describing who is a resident fiduciary and then check the appropriate box.
If the return is for a resident fiduciary, provide the entity's subdivision code, county, and city, town or taxing area.
If you are a personal representative of an estate enter the county (or Baltimore City) in which the decedent was domiciled on the decedent's date of death. Also complete the decedent's estate information.
If you are a fiduciary, other than a personal representative, enter the county (or Baltimore City) in which the trust is princi- pally administered. of these items are passed on to the beneficiaries on their Maryland Schedules K-1 (504). Form 504 Schedule A is used If the trust is not principally administered in Maryland, enter to determine the proper retention and/or allocation of these the county (or Baltimore City) in which the decedent was items. domiciled if the trust was created by the will of the decedent or If the fiduciary distributes all of the income for the tax year, the trust consists of property transferred by the will of the decedent. then the fiduciary is not required to complete lines 1 through 10g of Form 504 Schedule A. If the fiduciary makes no distribu-If the trust is not principally administered in Maryland but the tion of income (i.e. retains 100%), complete lines 1 through 8 creator or grantor of the trust is a current resident of of Form 504 Schedule A, and enter the amount from line 8 of Maryland, enter the county (or Baltimore City) in which the Form 504 Schedule A on line 5 of page 1 of Form 504. If the creator or grantor resides. See List 6A of incorporated cities, fiduciary makes a partial distribution of income during the tax towns and taxing areas to determine the subdivision code. year, complete lines 1 through 8 of Form 504 Schedule A, as well as either lines 9a through 9d or 10a through 10g. Enter the
Form 504 Schedule A - Fiduciary's Share Of
Maryland Modifications amount from line 9d or 10f of Form 504 Schedule A on line 5 of page 1 of Form 504.
Complete Form 504 Schedule A before you begin to complete
Note: A fiduciary may not distribute to any beneficiary any Form 504 as the information contained on this schedule is used to fill in certain lines on page 1 of the return. part of the S-portion of income of an ESBT.
With the exception of the S-portion of income of an ESBT, fidu-Fiduciary's Maryland modifications. Certain items must be ciaries generally are permitted those additions and subtractions added to or subtracted from federal taxable income to deterallowed individuals. mine the Maryland adjusted gross income of a fiduciary. Some
LIST OF INCORPORATED CITIES, TOWNS AND TAXING AREAS IN MARYLAND (6A)
Political Subdivision Code Political Subdivision Code ALLEGANY Town of Manchester . . . 0702 COUNTY … 0100 Town of Mt. Airy . . . . . 0703 Town of Barton . . . . . . 0101 Town of New Windsor . 0704 Bel Air … 0112 Town of Sykesville . . . . 0705 Bowling Green . . . . . . 0115 City of Taneytown . . . . 0706 Cresaptown … 0108 Town of Union Bridge . . 0707 City of Cumberland . . . 0102 City of Westminster . . . 0709 Ellerslie … 0113
CECIL COUNTY . . . . . 0800
City of Frostburg . . . . . 0103
Town of Cecilton . . . . . 0801
LaVale … 0110
Town of Charlestown . . 0802
Town of Lonaconing . . . 0104
Town of Chesapeake
Town of Luke … 0105
City … 0803
McCoole … 0114
Town of Elkton . . . . . . 0804
Town of Midland . . . . . 0106
Town of North East . . . 0805
Mt. Savage … 0111
Town of Perryville . . . . 0806
Potomac Park … 0109
Town of Port Deposit . . 0807
Town of Westernport . . 0107
Town of Rising Sun . . . 0808
ANNE ARUNDEL
CHARLES
COUNTY … 0200
COUNTY … 0900
City of Annapolis . . . . . 0201
Town of Indian Head . . 0901
Town of Highland
Town of La Plata . . . . . 0902
Beach … 0203
Port Tobacco Village . . . 0903
# BALTIMORE DORCHESTER
COUNTY … 0300
COUNTY … 1000
(No incorporated cities or
Town of Brookview . . . 1008 towns)
City of Cambridge . . . . 1001
BALTIMORE CITY . . . 0400 Town of Church Creek . 1002 Town of East
# CALVERT
New Market . . . . . . 1003
COUNTY … 0500
Town of Eldorado . . . . 1007
Town of Chesapeake
Town of Galestown . . . 1009
Beach … 0501
Town of Hurlock . . . . . 1004
Town of North Beach . . 0502
Town of Secretary . . . . 1005
Town of Vienna . . . . . . 1006
CAROLINE
COUNTY … 0600
# FREDERICK
Town of Denton . . . . . . 0602
COUNTY … 1100
Town of Federalsburg . . 0603
City of Brunswick . . . . 1101
Town of Goldsboro . . . . 0604
Town of Burkittsville . . 1102
Town of Greensboro . . 0605
Town of Emmitsburg . . 1103
Town of Henderson . . . 0611
City of Frederick . . . . . 1104
Town of Hillsboro … 0606
Town of Middletown . . . 1106
Town of Marydel . . . . . 0607
Town of Mt. Airy . . . . . 1114
Town of Preston . . . . . 0608
Town of Myersville . . . . 1107
Town of Ridgely . . . . . 0609
Town of New Market . . 1108
Town of Templeville . . . 0610
Village of Rosemont . . . 1113
Town of Thurmont . . . .1110
# CARROLL
Town of Walkersville . .1111
COUNTY … 0700
Town of Woodsboro . . .1112
Town of Hampstead . . . 0701
Political Subdivision Code Political Subdivision Code Political Subdivision Code
ST. MARY'S
GARRETT COUNTY . . 1200 Town of Oakmont . . . . 1619 COUNTY … 1900 Town of Accident . . . . . 1201 Town of Poolesville . . . 1608 Town of Deer Park . . . . 1203 City of Rockville . . . . . 1609 Town of Leonardtown . . 1902 Town of Friendsville . . . 1204 Town of Somerset . . . . 1610
# SOMERSET
Town of Grantsville . . . 1205 City of Takoma Park . . . 1611 COUNTY … 2000 Town of Kitzmiller . . . . 1206 Town of Washington City of Crisfield . . . . . . 2001 Town of Loch Lynn Grove … 1612 Town of Princess Anne . 2002 Heights … 1207 PRINCE GEORGE'S
Town of Mountain TALBOT
COUNTY … 1700
Lake Park … 1208 COUNTY … 2100
Town of Berwyn
Town of Oakland . . . . . 1209 Town of Easton . . . . . . 2101 Heights … 1701 Town of Oxford . . . . . . 2102 HARFORD COUNTY . . 1300 Town of Bladensburg . . 1702 Town of Queen Anne . . 2105 City of Aberdeen . . . . . 1301 City of Bowie … 1704 Town of St. Michaels . . 2103 Town of Bel Air . . . . . . 1302 Town of Brentwood . . . 1705 Town of Trappe . . . . . . 2104 City of Havre de Grace . 1303 Town of Capitol Heights 1706 Town of Cheverly . . . . 1707 WASHINGTON
HOWARD COUNTY . . 1400
City of College Park . . . 1725 COUNTY … 2200
(No incorporated cities or
Town of Colmar Manor . 1708 Town of Boonsboro . . . 2201 towns) Town of Cottage City . . 1709 Town of Clearspring . . . 2202 City of District Heights . 1710 KENT COUNTY . . . . . 1500 Town of Funkstown . . . 2203 Town of Eagle Harbor . . 1711 Town of Betterton . . . . 1501 City of Hagerstown . . . 2204 Town of Edmonston . . . 1712 Town of Chestertown . . 1502 Town of Hancock . . . . . 2205 Town of Fairmount
Town of Galena . . . . . . 1503 Town of Keedysville . . . 2206 Heights … 1713 Town of Millington . . . . 1504 Town of Sharpsburg . . . 2207 Town of Forest Heights 1728 Town of Rock Hall . . . . 1505 Town of Smithsburg . . . 2208 City of Glenarden . . . . 1730 Town of Williamsport . . 2209
# MONTGOMERY
City of Greenbelt . . . . . 1714
COUNTY … 1600 WICOMICO
City of Hyattsville . . . . 1715
COUNTY … 2300
Town of Barnesville . . . 1601
Town of Landover Hills . 1726
Town of Brookeville . . . 1602 Town of Delmar … 2301 City of Laurel … 1716 Town of Chevy Chase . . 1615 City of Fruitland . . . . . 2308
Town of Morningside . . 1727
Section 3 of the Village Town of Hebron . . . . . . 2302 City of Mt. Rainier . . . . 1717 of Chevy Chase . . . . 1614 Town of Mardela
City of New Carrollton . 1729
Section 5 of the Village Springs … 2303
Town of North of Chevy Chase . . . . 1616 Town of Pittsville . . . . . 2307 Brentwood … 1718 Town of Chevy City of Salisbury . . . . . 2304
Town of Riverdale Park 1720
Chase View . . . . . . 1617 Town of Sharptown . . . 2305
City of Seat Pleasant . . 1721
Chevy Chase Village . . 1613 Town of Willards . . . . . 2306
Town of University Park 1723
Village of Drummond . . 1623
Town of Upper Marlboro 1724 WORCESTER
Village of Friendship
COUNTY … 2400
QUEEN ANNE'S
Heights … 1621
Town of Berlin … 2401
COUNTY … 1800
City of Gaithersburg . . 1603
Town of Ocean City . . . 2402
Town of Barclay . . . . . 1805
Town of Garrett Park . . 1604
Pocomoke City . . . . . . 2403
Town of Centreville . . . 1801
Town of Glen Echo . . . . 1605
Town of Snow Hill . . . . 2404
Town of Church Hill . . . 1802
Town of Kensington . . . 1606
Town of Millington . . . . 1808
Town of Laytonsville . . 1607
Town of Queen Anne . . 1807
Village of Martin's
Town of Queenstown . . 1803
Additions … 1622
Town of Sudlersville . . . 1804
Village of North
Town of Templeville . . . 1806
Chevy Chase . . . . . 1618
# Lines 1 through 8 of Form 504 Schedule A
For resident fiduciaries, the addition and subtraction modifications to income provided in Form 502 instruction booklet for resident individuals apply. For nonresident fiduciaries, the addition and subtraction modifications to income provided in the Nonresident Income Tax Return Instructions apply. For a nonresident fiduciary:
- Any income derived from real property or tangible personal property located in Maryland;
- Income derived from a business wholly or partially carried on in Maryland and in which the trust or estate is a partner, member, or shareholder of the pass-through entity (a business entity taxable at the federal level as partnership or S corporation);
- Income from an occupation, profession or trade wholly or partially carried on in Maryland; and
- Income from Maryland State Lottery prizes or winnings from any other wagering is taxable in Maryland. In addition, a nonresident fiduciary can only claim losses generated in Maryland.
Addition Modifications include but are not limited to the following:
Interest on state and local obligations other than
Maryland. Resident fiduciaries must enter on line 1 the total amount of interest received (less related expenses) on obligations of any state or political subdivision thereof (except the State of Maryland and its political subdivisions).
Income taxes deducted on federal return. All fiduciaries must enter on line 2 the total of income taxes imposed by the State of Maryland, any political subdivision thereof, any other state or subdivision of any other state, or the District of Columbia to the extent included on line 11 of the federal Form 1041.
Other additions. Include on line 3 of Form 504 Schedule A any other Maryland additions that must be reported. Attach a statement explaining the additions that are included on this line. Do not include income from an Electing Small Business Trust (ESBT) as an addition on Form 504 Schedule A.
Resident fiduciary members of pass-through entities that are taxed on net income at the entity level in another state. For this addition to apply, the resident fiduciary must be a member of a pass-through entity that (1) pays tax at the entity level in another state and (2) deducts the tax paid to the other state in determining its (the pass-through entity's) income under the Internal Revenue Code. A fiduciary member of such a passthrough entity who claims a credit for taxes paid to another state on form 502CR, Part A, must include in the addition modification the portion of the credit for taxes paid to another state that represents tax the out-of-state pass-through entity paid on the member's pro rata share of income in that state and passed through to the member. For more information, see Administrative Release 42.
Capital losses from sale of certain trust property. For a resident fiduciary, include on line 3 any capital loss derived from the sale or other disposition of intangible personal property that is held in trust, if the proceeds are added to the principal of the trust, and if all the remaindermen in being are nonresidents during the entire tax year or corporations not doing business in Maryland.
Non-Maryland loss. For a nonresident fiduciary, include on line 3 of Form 504 Schedule A net non-Maryland loss.
Subtraction Modifications include but are not limited to the following:
Income from U.S. Government obligations. Enter on line 5 of Form 504 Schedule A interest from U.S. Savings Bonds and other U.S. obligations. Capital gains from the sale or exchange of U.S. obligations should be included as well. Dividends from mutual funds that invest in U.S. Government obligations should also be included on this line; however, only that portion of dividends attributable to interest from U.S. Government obligations may be subtracted. You cannot subtract income from
# Government National Mortgage Association securities. See
Administrative Release 10 and 13.
Other subtractions. Include on line 6 of Form 504 Schedule A any other Maryland subtractions that may be claimed. Attach a statement explaining the subtractions that are included on this line.
NOTE: Non-Maryland source income included in the federal taxable income of a fiduciary is not a subtraction modification on Form 504. For a nonresident fiduciary, non-Maryland source income is excluded from the Maryland taxable income calculation on Form 504NR. See Instruction 13.
Fiduciary's share of net Maryland modifications
Only the fiduciary's allocable portion of the Maryland modifications should be used. Complete lines 1 through 8, and lines 9a through 9d or lines 10a through 10g to determine this amount.
Note: You may choose either Method 1 or 2 - you may not use both methods.
Method 1, (Formula Method). Line 9a. Enter the federal distributable net income (DNI) from federal Form 1041.
Line 9b. Enter the fiduciary's share of DNI (that portion of the DNI that was not deducted or distributed to the beneficiaries).
Line 9c. Divide the fiduciary's share of the DNI (line 9b) by the DNI (line 9a) to determine the fiduciary's percentage of the DNI and enter the result on line 9c.
Line 9d. Multiply the fiduciary's percentage of DNI (line 9c) by the net Maryland modification on line 8 of Form 504 Schedule A to compute the fiduciary's share of net Maryland modifications. Enter the result on line 9d and on Form 504, line 5 on page 1.
Method 2, (Alternative Method). Lines 10a through 10e allocate the net Maryland modifications on line 8 of Form 504 Schedule A to the beneficiaries in accordance with the allocation of income to the beneficiaries. If the estate or trust has more than four (4) beneficiaries, attach an additional sheet providing the additional beneficiaries' allocations; the total from the allocations on the attached sheet is entered on line 10e.
Line 10f. Enter the net Maryland modifications on line 8 of Form 504 Schedule A allocated to the fiduciary.
Line 10g. Enter the total from lines 10a through 10f, Column
(C) on line 10g, this total must equal the net Maryland modifications reported on line 8 of Form 504 Schedule A.
Nonresident beneficiary deduction
Nonresident individuals who have intangible income from sources within Maryland are not subject to tax on such income in Maryland. There are some fiduciaries that accumulate intangible income in the trust to be distributed later to nonresident beneficiaries. Because this income is not taxable to a nonresident, there is a provision that permits the fiduciary to subtract intangible income accumulated for later distribution to a nonresident beneficiary.
A fiduciary with a nonresident beneficiary may enter such income on line 11 of Form 504 Schedule A, to the extent included in the federal taxable income of the fiduciary, if the income is derived from intangible personal property and if that income is held in trust for the benefit of and being accumulated for a nonresident individual or a corporation that is not doing business in Maryland.
A fiduciary with a nonresident beneficiary may also enter on line 11 of Form 504 Schedule A, to the extent included in the federal taxable income of the resident fiduciary, capital gain income derived from the sale or other disposition of intangible personal property if that income is held in trust; if the proceeds from that sale or other disposition of the intangible personal property are added to the principal of the trust; and if all of the remaindermen of the trust in being are nonresidents during the entire tax year or corporations not doing business in Maryland.
The amount that is included on line 11 of Form 504 Schedule A must actually be for the benefit of and attributable exclusively to the nonresident beneficiary or corporation not doing business in Maryland for which the nonresident beneficiary subtraction is being claimed. Also, the remaindermen for which the nonresident beneficiary subtraction is being claimed cannot be unborn or unascertained persons or persons with contingent interests. In addition, the nonresident beneficiary cannot possess an inter vivos power of appointment over such income, nor can the fiduciary possess a discretionary power to distribute such income of the trust to themselves, unless such discretionary power is limited to ascertainable standards as defined by Section 2041(b)(1)(A) of the Internal Revenue Code.
Do not enter on line 11 of Form 504 Schedule A income that has been distributed. Line 11 is to be used only when income from intangible personal property is accumulated for a nonresident beneficiary. If line 11 is greater than zero, attach to Form 504 a copy of the federal Form 1041 and all schedules relating to the type(s) and source(s) of income included on line 11. Also, attach Form 504NBD listing all beneficiaries, their domiciliary addresses and applicable tax identification numbers, whether they are income beneficiaries, remaindermen or both, and the amount of intangible income accumulated for each beneficiary. If claiming the deduction on behalf of remaindermen, the deduction cannot be divided between resident and nonresident remaindermen. All remaindermen must be nonresidents of Maryland. If one remainderman is a Maryland resident, the deduction cannot be claimed.
Identify all persons with a power of appointment over the trust property. See Administrative Release 16.
Enter on line 12 of Form 504 Schedule A, expenses allocable to this income. Subtract line 12 from line 11 to arrive at the amount of the nonresident beneficiary subtraction and enter this amount on line 13 of Form 504 Schedule A. Enter the amount from line 13 of Form 504 Schedule A on line 7 of Form 504 page 1.
Income
Enter the figure for federal taxable income from your federal fiduciary income tax return on line 1 of page 1 of Form 504.
For a fiduciary exempt from taxation under IRC Sections 408(e)(1) or 501, enter on line 1 of Form 504 the fiduciary's unrelated business taxable income (as defined under IRC
# Section 512.)
Note to members of electing pass-through entities that file Form 511 A trust that is a member of a pass-through entity that elects to pay tax on all members' distributive or pro rata share of income ("electing pass-through entity") must add back to income the amount of the credit received for the tax paid by the electing pass-through entity. Enter the total of federal taxable income plus the amounts from Maryland Schedule K-1 (510/511), Part D, Lines 2 and 4 on Line 1.
All items reported on the Maryland return are subject to verification, audit, and revision by the Comptroller's Office.
Exemption, Electing Small Business Income and
# Standard & Itemized Deduction
On line 2 of Form 504, enter the amount of exemption that was claimed on the federal return.
Enter on line 3 the amount of income of the ESBT that consists of stock in one or more S corporations subject to the special taxing rules under IRC Section 641(c). This is the portion of income upon which a tax was calculated and carried to federal Form 1041, Schedule G, and identified as attributable to Section 641(c). Attach a schedule or statement to Form 504 showing computation of this income. Do not allocate or prorate this income.
Enter on Form 504, line 4, the sum of lines 1 through 3.
A Maryland exemption of $600 is allowed for a personal representative filing for a decedent's estate (entity type 1). A fiduciary other than a personal representative (entity types 2 through 8) may deduct $200 as an exemption. These Maryland exemptions are claimed on Form 504, line 9.
The fiduciary is NOT allowed a standard deduction or itemized deductions.
Figure your Maryland net taxable income
Resident and nonresident fiduciaries, complete Form 504 lines 1 through 10. Line 10 is your Maryland net taxable income. For a nonresident fiduciary, the Maryland net taxable income from Maryland sources is calculated on Form 504NR, line 17e.
Maryland tax and nonrefundable tax credits
Compute the tax in accordance with the 2023 FIDUCIARY TAX RATE SCHEDULE (12A) and enter the tax on line 11.
Nonresident fiduciaries should read and refer to Instructions 7 and 13 for information on Form 504NR before continuing; for Form 504 line 11, enter the Maryland tax from Form 504NR, line 21.
If the fiduciary is a resident and must pay income tax to another state, complete Form 502CR, Part A and Part AA and enter the result on Form 504, line 14.
NOTE: You must attach Form 502CR and a copy of the tax return filed in the other state or locality. If this is not attached, no credit will be allowed. If any credit is being claimed for Preservation and Conservation Easements on Form 502CR, complete Form 502CR, Parts F and AA and enter the result on line 14. If both credits are applicable, enter the sum on line 14.
Also enter the sum on any nonrefundable Business Income Tax Credits from Part AAA of Form 504CR on line 15 of Form 504.
Form 504CR and any required certification must be attached to Form 504 or the requested credit will not be approved.
# 2024 Fiduciary Tax Rate Schedule (12A)
For taxpayers filing as Single, Married Filing Separately, or Dependent. This rate is also used for taxpayers filing as Fiduciaries.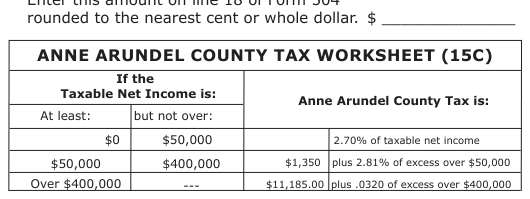
Text version of this table
ANNE ARUNDEL COUNTY TAX WORKSHEET (15C) If the Taxable Net Income is: Anne Arundel County Tax is: At least: but not over: $0 $50,000 2.70% of taxable net income $50,000 $400,000 $1,350 plus 2.81% of excess over $50,000 Over $400,000 --- $11,185.00 plus .0320 of excess over $400,000
$0 $1,000 2.00% of taxable net income
$1,000 $2,000 $20.00 plus 3.00% of excess over $1,000 $2,000 $3,000 $50.00 plus 4.00% of excess over $2,000 $3,000 $100,000 $90.00 plus 4.75% of excess over $3,000 $100,000 $125,000 $4,697.50 plus 5.00% of excess over $100,000 $125,000 $150,000 $5,947.50 plus 5.25% of excess over $125,000 $150,000 $250,000 $7,260.00 plus 5.50% of excess over $150,000 $250,000 -- $12,760.00 plus 5.75% of excess over $250,000
Instructions for Maryland Form 504NR
# Maryland Fiduciary Nonresident Income Tax Calculation. Form
504NR must be filed by all nonresident fiduciaries who have:
- Any modifications to their federal income, or,
- Income from non-Maryland sources.
Form 504NR is a required attachment to Form 504 for all nonresident fiduciaries meeting the above criteria. Also see the Tax Preparer's Checklist and instructions for more details on Page 3 of Form 504NR.
# Part I - Reconciliation of Maryland and Federal Income
(Loss)
On Form 504NR, complete lines 1 through 14 of the Federal Income (Loss) column (Column A) using the figures from your federal fiduciary income tax return. Column (A) of line 14 on Form 504NR should equal the sum of lines 1 and 2 on Form
- Enter in the Non-Maryland source columns (Columns B and C) all income or loss from non-Maryland sources. Enter in the Maryland source columns (Columns D and E) all income or loss from Maryland sources.
NOTE: The total Non-Maryland source income plus the total Maryland source income must equal the total federal income (loss). The sum of Columns (B) through (E) must equal
Column (A) on Line 14 on Form 504NR.
Form 504NR, Line 15. Add the amounts of income (loss) in Column (B), line 14 to the income (loss) in Column (C) to arrive at the total non-Maryland source income (loss). Then, calculate an income factor by dividing the total non-Maryland source income (loss) by the federal income (loss); carried to six decimal places. This factor cannot exceed 1 (100%) and cannot be less than zero (0%); if greater than 1, enter 1.000000; if less than zero (0), enter 0.
# Part II - Calculation of Nonresident Maryland Income
Tax
Form 504NR, Line 16:
Line 16a. Enter the fiduciary's share of the net Maryland modifications from Form 504, line 5.
Line 16b. Multiply the fiduciary's share of the net Maryland modifications (line 16a) by the income factor on line 16 to arrive at the net modification amount attributable to non-Maryland sources. In the alternative, allocate the fiduciary's share of the net Maryland modifications based on the net applicable Maryland modifications attributable to non-Maryland sources.
Line 16c. The fiduciary's share of the net Maryland modifications attributable to Maryland sources is the difference between 16a and 16b. Enter this difference on line 16c.
Line 16d. Enter the Income from ESBT from Form 504, line 3 Line 16e. Enter the non-Maryland ESBT income included on line 16d (attach schedule showing computation).
Line 16f. Net Maryland ESBT income. Subtract line 16e from
16d. If less than zero, enter zero.
Form 504NR, Line 17:
Line 17a. Enter the fiduciary's share of distributable Maryland source income or loss from line 15 Column D on line 17a.
Line 17b. Enter the fiduciary's share of non-distributable taxable net income from Maryland source from line 15 Column E on line 17b.
Line 17c. Add lines 16c, 16f, 17a, and 17b to arrive at the fiduciary's Maryland net taxable income before exemption deduction and enter on line 17c.
Line 17d. Enter the Maryland exemption amount from Form 504, line 9.
Line 17e. Subtract line 17d from line 17c. This is the fiduciary's Maryland net taxable income. Enter this amount on line 17e.
Form 504NR, Line 18. Enter the taxable net income from Form 504, line 10.
Form 504NR, Line 19. Calculate the tax on this amount using Tax Rate Schedule 12A in Instruction 12.
Form 504NR, Line 20. Calculate the Maryland Nonresident Factor by dividing the amount on line 17e by line 18. Carry to six decimal places.
Form 504NR, Line 21. Multiply line 20 by the tax shown on line 19 to arrive at the Maryland tax. Also enter this tax amount on line 11 of Form 504.
Form 504NR, Line 22. Multiply the taxable net income on line 17e by 2.25% (0.0225) to calculate the Special Nonresident tax; also enter this tax amount on line 12 of Form 504.
After you enter the tax amounts from Form 504NR on lines 11 and 12 of Form 504, complete the remainder of Form 504 following the instructions in the booklet.
Special nonresident tax
Nonresident fiduciaries enter on Form 504, line 12, the amount from Form 504NR, line 22. Resident fiduciaries should enter -0- on line 12 of Form 504
Local income tax
The counties of Maryland and Baltimore City are empowered to levy a local income tax that is collected by the Comptroller with the State tax. You must use the local tax rate in effect for the county that you entered on the front page of the form. See the LOCAL TAX RATE CHART (15A) and
LOCAL TAX WORKSHEET (15B) (For Anne Arundel
County residents use the ANNE ARUNDEL COUNTY TAX
WORKSHEET (15C)).
If the fiduciary is a resident and completed Form 502CR, Part A because it paid income tax to another state or locality and credit for the Maryland local tax exists, enter the result from Part BB of Form 502CR on Form 504, line 19.
2024 LOCAL TAX RATE CHART (15A)
Subdivision Rate
Baltimore City … 0320
Allegany County … 0303
Anne Arundel County … See below*
Baltimore County … 0320
Calvert County … 0300
Caroline County … 0320
Carroll County … 0303
Cecil County … 0275
Charles County … 0303
Dorchester County … 0320
Frederick County … See below
Garrett County … 0265
Harford County … 0306
Howard County … 0320
Kent County … 0320
Montgomery Count … 0320
Prince George's County … 0320
Queen Anne's County … 0320
St. Mary's County … 0300
Somerset County … 0320
Talbot County … 0240
Washington County … 0295
Wicomico County … 0320
Worcester County … 0225
NOTE
* Anne Arundel Co. The local tax rates for taxable year 2024 for a fiduciary is as follows:
(1) For a filer with taxable net income of at least $1 but not over $50,000, 2.7% the filer's taxable net income;
(2) For a filer with taxable net income of at least $50,001 but not over $400,000, $1,350 plus 2.81% of the filer's taxable net income over $50,000; and
(3) For a filer with taxable net income of at least $400,001, $11,185 plus 3.2% of the filer's taxable net income over $400,000.
Frederick Co. The local tax rates for taxable year 2024 for a fiduciary is as follows:
(1) .0225 for fiduciary taxpayers who have a net taxable income between $1 and not exceeding $25,000;
(2) .0275 for fiduciary taxpayers who have a net taxable income between $25,001 and not exceeding $50,000;
(3) .0296 for fiduciary taxpayers who have a net taxable income between $50,001 and not exceeding $150,000; and
(4) .0320 for fiduciary taxpayers who have a net taxable income of $150,001 or more;
LOCAL TAX WORKSHEET (15B)
Multiply the taxable net income by the tax rate from the LOCAL TAX RATE CHART (15A) for the county in which the fiduciary was a resident on the last day of the taxable period. Enter the result on line 18 of Form 504. This is the fiduciary local income tax.
- Taxable net income from line 10 of Form 504 … $ __
- Local tax rate from Local Tax
.0
Rate Chart … __
- Local income tax (Multiply line 1 by line 2.)
Enter this amount on line 18 of Form 504 rounded to the nearest cent or whole dollar.. $ __
ANNE ARUNDEL COUNTY TAX WORKSHEET (15C)
If the
Taxable Net Income is:
Anne Arundel County Tax is:
At least: but not over:
$0 $50,000 2.70% of taxable net income
$400,000 plus 2.81% of excess over $50,000
$50,000 $1,350
Over $400,000 --- plus .0320 of excess over $400,000 $11,185.00
Total Maryland tax, local tax and contributions
Add lines 17 and 20, and enter the result on line 21. Add to your tax any contributions from lines 22, 23, 24 and 25. Enter the total on line 26.
Chesapeake Bay and Endangered Species Fund
You may contribute any amount you wish to this fund. The amount contributed will reduce your refund or increase your balance due.
Developmental Disabilities Services and Support Fund
You may contribute any amount you wish to this fund. The amount contributed will reduce your refund or increase your balance due.
# Maryland Cancer Fund
You may contribute any amount you wish to this fund. The amount contributed will reduce your refund or increase your balance due.
# Fair Campaign Financing Fund
You may contribute any amount you wish to this fund. The amount contributed will reduce your refund or increase your balance due.
IMPORTANT: If there are not sufficient credits or other payments to satisfy your tax and the contribution you have designated, the contribution amounts will be reduced. If you have entered amounts for contribution to multiple funds, any reduction will be applied proportionately.
Taxes paid and refundable credits
Write your taxes paid and tax credits on lines 27-30 of Form 504.
Add lines 27 through 30 and enter the total on line 31.
Taxes paid
If Maryland tax was withheld from wages (or other compensation) paid to a decedent's estate, enter the amount on line 27 and attach the wage and tax statement, or Form 1099.
If you participated in a nonresident real estate transaction, you must report any income tax withheld on your behalf as an estimated payment.
Enter on line 28 the total of Maryland estimated tax payments, any taxes withheld from a nonresident real estate transaction and any payment made with a request for an extension of time to file the return. See instructions on Form 504E.
Credits
If the estate or trust was a member of a pass-through entity
(PTE) doing business in Maryland and the PTE paid nonresident tax on its behalf, enter the amount on line 29. You must attach a Maryland Schedule K-1 (510/511) from the PTE showing the amount of tax paid on behalf of the estate or trust.
This credit may be passed through the nonresident fiduciary and claimed by the beneficiary on its applicable Maryland income tax return in an amount proportionate to the distribution of income by the nonresident fiduciary to that beneficiary.
DO NOT include the amount on line 29 if the fiduciary elects to pass this credit through to the beneficiaries.
Include the Maryland Schedule K-1 (504), as well as Maryland Schedule K-1 (510/511) showing the amount of tax paid by the PTE on behalf of the trust being passed through to the beneficiary. The statement must also include the names and FEINs of PTEs paying tax.
If the estate or trust participated in a nonresident real estate transaction as a member of a PTE that paid taxes on its behalf using Form MW506NRS, report this payment on line 29.
Add the total of business income tax credits from Form 504CR, Part CCC, Line 11 to Line 30 of Form 504. Complete and submit Form 504CR with Form 504. For additional information regarding any of the Business Income Tax credits, see the instructions provided on Form 504CR. Also, add to line 30 any Maryland Historic Revitalization Tax Credit from Form 502S.
Overpayment or balance due
Calculate the Balance Due (line 32 of Form 504) or Overpayment (line 33 of Form 504).
Part or all of any overpayment may be applied to 2025 estimated tax by completing line 34. Subtract line 34 from the overpayment (line 33). This is the amount of the refund.
# Underpayment of Estimated Tax
All taxpayers should refer to Form 504UP to determine if they owe interest because they paid too little estimated tax during the year.
If you owe interest, complete Form 504UP and write the amount of interest (line 15 of Form 504UP) in the appropriate box on line 36 of Form 504. Attach Form 504UP.
Generally, you do not owe interest if: a. You owe less than $500 tax on income which is not subject to Maryland withholding; or, b. Each current year payment, made quarterly as required, is equal to or more than one-fourth of 110% of last year's taxes that were developed; or, c. You made quarterly payments during the year which equal 90% of this year's tax; or, d. The year ends less than two years after the decedent's date of death.
If after completing Form 504UP there is no interest due or you meet exception "d," see Instruction 19 for additional information regarding code numbers.
# Interest for Late Filing
Interest is due at the rate of 11.4825% annually or 0.9568% per month for any month or part of a month that a tax is paid after the original due date of the 2024 return but before January 1, 2026. For assistance in calculating interest for tax paid on or after January 1, 2026, visit marylandtaxes.gov.
- Penalty up to 10% may be assessed by the Comptroller of Maryland for failing to pay any tax, or failing to file a tax return, when due.
Total Interest
Enter the total interest for underpayment of estimated tax and interest for late filing on line 36.
# OVERPAYMENT
If you must pay interest for underpayment of estimated tax, enter the amount of interest from Line 15 of Form 504UP on Line
- Subtract Lines 34 and 36 from your overpayment (Line 33).
This is the amount of your refund. Write this amount on Line 35.
No refunds of less than $1.00 will be sent. If the amount on Line 36 is more than the overpayment on Line 33 of Form 504, enter zero (0) on Lines 34 and 35. Then subtract Line 32 from Line 36 and enter the result on Line 37. If you prefer, you may leave Line 36 blank and the Revenue Administration Division will calculate the interest charges and send you a bill. See Instructions 19 and 20 regarding signatures, attachments, and mailing.
Direct Deposit of Refund
To comply with banking and National Automated Clearing House Association (NACHA) rules, we ask you to indicate by checking the appropriate box on your return if the state refund is going to an account outside the United States. If you indicate that this is the case, STOP! do not enter your routing and account numbers, as the direct deposit option is not available to you. We will send you a paper check.
By choosing direct deposit of your refund and checking the appropriate box, you authorize the State of Maryland to disclose to your bank, to the State's depository bank and their financial partners, and NACHA any tax return information, such as your name, and the name(s) as it appears on the bank account to make the deposit. Complete lines 38a, b, c, and d of Form 504 if you want us to deposit your refund directly into your account at a bank or other financial institution (such as a mutual fund, brokerage firm or credit union) in the United States.
Splitting Your Direct Deposit
If you would like to deposit portions of your refund to multiple accounts, do not complete any direct deposit information on your return. Instead, you must enter code number 588 on one of the code number lines on your return, and complete and attach Form 588.
NOTE: You may not use Form 588 if you are filing Form 502INJ, Injured Spouse Claim Form, or if you plan to deposit your refund in a bank outside the United States.
Individual taxpayers now have the option to use all or part of their income tax refund to purchase U.S. Series I Savings Bonds. See Form 588 for additional details.
Check with your financial institution to make sure ! your direct deposit will be accepted and to get the correct routing and account numbers. If you enter the incorrect account or omit any required CAUTION information, the State of Maryland will not be responsible for recovering that refund and/or for making direct deposit payment electronically
# Line 38a
Check the appropriate box to identify the type of account that will be used (checking or savings). You must check one box only or a refund check will be mailed.
# Line 38b
The routing number must be nine digits. If the first two digits are not 01 through 12 or 21 through 32, the direct deposit will be rejected and a check sent instead. If you are not sure of the correct routing number, contact your financial institution.
If you are not sure of the correct routing number or if your check states that it is payable through a financial institution different from the one at which you have your checking account, contact your financial institution for the correct routing number.
# Line 38c
The account number can be up to 17 characters (both numbers and letters). Omit spaces, hyphens and special symbols. Enter the number from left to right.
If we are notified by the financial institution that the direct deposit is not successful, a refund check will be mailed to you.
Have a bank statement for the account available if you contact us concerning the direct deposit of your refund.
Line 38d.
You must indicate the full name as it appears on the bank account.
Disclosure
By requesting a direct deposit of your Maryland tax refund and entering your bank account number, routing number, account type, and name(s) as it appears on your bank account and on your income tax return, you authorize the Comptroller's Office to disclose this information regarding your refund amount to the Maryland State Treasurer's Office (who performs banking services for the Comptroller's Office).
Telephone number, code numbers, signatures and attachments Enter your telephone number and sign and date your return. Be sure to attach all required forms, schedules and statements.
# Code Numbers
IMPORTANT: If you complete Form 504UP and, because of the timing of the distributions of income, have no interest due, attach the form to your fiduciary return and write code number 301 on one of the lines marked CODE NUMBER at the bottom of Form 504.
If you use the annualization method to calculate interest for underpayment of estimated tax, attach Form 504UP to your fiduciary return and write code number 301 on one of the lines marked CODE NUMBER at the bottom of Form 504. For the Revenue Administration Division to recognize your use of this calculation method, you must enter the code number and attach the form, even if there is no interest due.
If the return is for a decedent's estate within two years of the date of death, enter 301 on one of the CODE NUMBER lines.
Do not attach Form 504UP.
# Tax Preparers
If another person prepared your return, that person must also print name and sign the return and enter their Preparer's Tax Identification Number (PTIN). The preparer declares that the return is based on all information required to be reported of which the preparer has knowledge, under penalties of perjury.
Penalties may be imposed for tax preparers who fail to sign the tax return and provide their PTIN. At the bottom of the return at the signature area, we have provided a check box for you to authorize your preparer to discuss your return with us.
Signature and verification
This return must be verified and signed by the individual fiduciary or an authorized officer of a corporate fiduciary. If two or more individuals act jointly as fiduciaries, the return may be verified and signed by either.
Attachments
Be sure to attach wage and tax statements (Forms W-2, W-2G and 1099(s)) to the front of your return if Maryland tax is withheld. Complete and attach Maryland Schedule K-1 (504) for each beneficiary. See Administrative Release 16. Also attach all forms, schedules and statements required by these instructions. Place your check or money order on top of the wage and tax statements and fasten with one staple on the front of your tax return.
Mail your return
Mail your return to:
Revenue Administration Division
110 Carroll Street
Annapolis, Maryland 21411-0001
Private Delivery Services
If you wish to send your items by a private delivery service (such as FedEx or UPS) instead of the U.S. Postal Service, use the following address:
Private Delivery Service Address:
Revenue Administration Division
110 Carroll Street
Annapolis, Maryland 21411-0001
410-260-7980
# ELECTRONIC FILING AND PAYMENT ELECTRONICALLY FILING YOUR RETURN
The fastest way to file your return, and receive your refund is to file electronically and request direct deposit. If you request direct deposit on your electronic return, your refund should be in your bank account within 72 hours of acknowledgment from the Revenue Administration Division. You may request electronic funds withdrawal (direct debit) payments on your electronic return.
You may file your return electronically through your personal computer.
Do not send a paper copy of the return if you electronically filed.
For more information, visit marylandtaxes.gov.
# PAYMENT BY CHECK OR MONEY ORDER
Make checks or money orders payable to Comptroller of
Maryland. On your check or money order, in blue or black ink only, you must include the Federal Employer Identification Number, tax year, and tax type. Failure to include this information will delay the processing of your payment.
DO NOT SEND CASH.
Due Date
Returns must be mailed by April 15, 2025, for calendar year taxpayers. Fiduciaries filing on a fiscal year basis should see
# Instruction 24. Extension of time to file
Follow the instructions on Form 504E to request an automatic extension of the time to file your 2024 return. Filing this form extends the time to file your return, but does not extend the time to pay your taxes. Payment of the expected tax due is required with Form 504E by April 15, 2025.
Fiscal year
You must file your Maryland return using the same tax year and the same basis (cash or accrual) as you used on your federal return.
To file a fiscal year return, complete the fiscal year information at the top of Form 504 and print "FY" in bold letters in the upper left corner of the form. Whenever the term "tax year" appears in these instructions, fiscal year taxpayers should understand the term to mean "fiscal year." Use the 2024 forms for fiscal years that begin during calendar year 2024. Fiscal year returns are due on the 15th day of the 4th month following the close of the fiscal year. If you are filing on a fiscal year basis, file Form 504E by the regular due date of your return.
Amended returns
If you need to change a return that you have already filed, or if the Internal Revenue Service changes your return, you must file an amended return.
NOTE: Changes made as part of an amended return are subject to audit for up to three years from the date the amended return is filed.
Use Form 504 and Form 504NR, if applicable, to file an amended return. Be sure to check the AMENDED RETURN box and draw a line through any barcode on the front of the return. An explanation must be provided on page two of the amended Form 504. A copy of the
amended federal return must be attached.
# Changes to Your Federal Return
If the Internal Revenue Service makes any changes to your federal return, you must notify the State of Maryland. Send notification to the Maryland Revenue Administration Division within 90 days of the final determination of the changes by the IRS.
If you file an amended federal fiduciary return that changes your fiduciary return, you must file an amended Maryland return.
# If Your Original Return Showed a Refund
If you expect a refund from your original return, do not file an amended return until you have received your refund check. Cash the check. Do not return it. If your amended return shows a smaller refund, send a check for the difference with the amended return. If your amended return shows a larger refund, the Revenue Administration Division will issue an additional refund check.
# Additional Information
Do not file an amended return until sufficient time has passed to allow the original return to be processed. For current year returns, allow at least six weeks.
Generally, a claim for a refund or overpayment credit must be filed within three years from the date the original return was filed or within two years from the date the tax was paid, whichever is later. An original return filed early is considered filed on the date it was due.
A claim for refund based on a federal net operating loss carryback must be filed within three years from the due date of the return for the tax year of the net operating loss.
If the claim for refund resulted from a federal adjustment or final decision of a federal court that is more than three years from the date of filing the return or more than two years from the time the tax was paid, a claim for refund must be filed within one year from the date of the adjustment or final decision.
If the claim for refund resulted from a notification received from another state for income taxes due that is more than three years from the date of filing the return or more than two years from the time the tax was paid, a claim for refund resulting from a credit for taxes paid to that state must be filed within one year of the date of the notification that the other state's tax was due.
If the claim for refund or credit for overpayment resulted from a final determination made by an administrative board or an appeal of a decision of an administrative board, that is more than three years from the date of filing the return or more than two years from the time the tax was paid, the claim for refund must be filed within one year of the date of the final decision of the administrative board or final decision of the highest court to which an appeal of the administrative board is taken.
No refund for less than $1.00 will be issued. No payment of less than $1.00 is required.
Special instructions for bankruptcy estates
A bankruptcy estate is created for an individual under Chapter 7 (a liquidation) or Chapter 11 (a reorganization) under Title 11 of the United States Code. The bankruptcy estate is treated as a separate taxable entity. A separate taxable entity is not created when an individual is in a state receivership.
The fiduciary of a Chapter 7 or a Chapter 11 bankruptcy estate is required to file the estate's return and must file a Maryland return if the fiduciary or trustee is required to file a federal return and has Maryland taxable income. The fiduciary must use the Maryland Fiduciary Return, Form 504.
For an individual, the fiduciary return is the mechanism for paying the tax. The calculation is done on the individual income tax return, Form 502, and the tax is carried to the fiduciary return. The fiduciary of an individual bankrupt debtor should attach the completed Form 502 to Form 504. Draw a line through any barcodes on Form 502 and write "Bankruptcy Estate" in the name and address area.
A trustee of a corporate debtor or other bankrupt entity, who has possession of the bankrupt estate by court order or who holds title to all or substantially all of the property of a bankrupt entity, must file the income tax return for the entity. The fiduciary would be required to file a Maryland income tax return, if the fiduciary is obligated to file a federal return on behalf of the bankrupt entity and also has Maryland taxable income.
The fiduciary should attach a notice of the filing of the bankruptcy estate, which is issued by the applicable bankruptcy court, to the return.
Qualified funeral trusts
A fiduciary may file a composite fiduciary income tax return reporting the income of the funeral trusts administered by that fiduciary, instead of one fiduciary return for each trust. Check Entity Type Box 6. Attach a schedule showing the name, income, state tax and local tax of each individual trust. Add the state tax amounts and enter on line 11. Add any special nonresident tax on line 12, if a nonresident fiduciary is included in the qualified funeral trust. Add the local tax amounts and enter on line 18.
Complete Form 504 according to Instructions 16 through 19.
Privacy act information
The Tax-General Article of the Annotated Code of Maryland authorizes the Revenue Administration Division to request information on tax returns to administer the income tax laws of Maryland, including determination and collection of correct taxes. Code Section 10-804 provides that you must include your federal identification number on the return you file. This is so we know who you are and can process your return and documents.
If you fail to provide all or part of the requested information, then exemptions, exclusions, credits, deductions or adjustments may be disallowed and you may owe more tax. In addition, the law provides penalties for failing to supply information required by law or regulations.
You may look at any records held by the Revenue
Administration Division which contain personal information about you. You may inspect such records, and you have certain rights to amend or correct them.
As authorized by law, information furnished to the Revenue Administration Division may be given to the United States Internal Revenue Service, a proper official of any state that exchanges tax information with Maryland and to an officer of this State having a right to the information in that officer's official capacity. The information may be obtained in accordance with a proper legislative or judicial order.
# REGISTRATION & TAXES
Registration and Licensing All new businesses
(corporations, S corporations, partnerships, limited liability companies, business trusts, and sole proprietorships) can file a single application with the Central Registration Unit of the Revenue Administration Division of the Comptroller's Office to establish accounts for employer income tax withholding, sales and use tax, admissions and amusement tax, tire recycling fee, motor fuel tax, alcohol tax, and tobacco tax. The Revenue Administration Division offers assistance for filing applications and establishing accounts.
The Central Registration Unit assigns a single state identification number for the taxes listed above. Register online at Maryland Tax Connect.
For more information, visit marylandtaxes.gov.
To obtain a direct wine shipper's permit and a common carrier permit, businesses may apply with the Licensing Unit of the Maryland Alcohol, Tobacco, & Cannabis Commission.
Corporation Income Tax The corporation income tax applies to every Maryland corporation and every other corporation which has a nexus with Maryland. Nexus is the term used to indicate a taxable connection between a corporation and a taxing authority. If a corporation conducts business activity within Maryland and exceeds the provisions of U.S.C.A. Title 15, Section 381 of the Interstate Commerce Act (P.L. 86-272) it has a nexus and must file an income tax return.
The tax is based on federal taxable income after state modifications. Corporations engaged in multistate operations must allocate income using an apportionment formula, generally consisting of receipts, property and payroll factors.
The tax is imposed at a flat rate of 8.25% of Maryland taxable income.
Employer Withholding of Income Tax Employers making payments to individuals of salaries, wages or compensation for personal services must withhold income tax and remit the withholding to the Revenue Administration Division. The amount of tax to be withheld is prescribed in published tables which are based on the individual income tax rates.
Sales and Use Tax This tax applies to businesses selling in Maryland or purchasing out of state for Maryland use.
The general Maryland sales and use tax rate is 6%. Most sales of food by substantial grocery or market businesses are not subject to tax. Specific prepared foods purchased in grocery stores are subject to tax. Other exemptions include all sales solely for resale, medicine, energy for residential use, manufacturing machinery and equipment, and certain agricultural equipment and supplies. For exemptions not listed, visit marylandtaxes.gov.
Electronic Smoking Devices and Vaping Liquid A rate of 20% is imposed on the sale of electronic smoking devices (ESDs). A rate of 20% is imposed on the sale of vaping liquid over 5mL. A rate of 60% is imposed on the sale of vaping liquid 5mL or less.
Tobacco Pipes A rate of 12% is imposed on the sale of tobacco pipes.
Truck Rentals and Peer-to-Peer Car Sharing A rate of 8% is imposed on car and motorcycle rentals and peer-to peer car sharing.
# Car and Motorcycle Rentals and Peer-to-Peer Car
Sharing A rate of 11.5% is imposed on car and motorcycle rentals and peer-to-peer car sharing.
Alcoholic Beverages and Cannabis A rate of 9% is imposed on the sale of alcoholic beverages and cannabis.
911 Fee Surcharge Seller s of prepaid wireless telecommunications services are required to report and remit to the Comptroller all Prepaid Wireless E-9-1-1 Fees collected by the seller for retail transactions of prepaid wireless telecommunications. The Prepaid Wireless E-9-1-1 Fee is 60 cents per retail transaction. The seller must report the fees collected on a Maryland Sales and Use Tax return, although the Prepaid Wireless E-9-1-1 Fee itself is not subject to Maryland sales and use tax.
9-8-8 Fee A 9-8-8 fee is imposed on each telephone service or other communications service that connects an individual dialing the digits 9-8-8 to the 988 Suicide and Crisis Lifeline.
The 9-8-8 Fee is 25 cents per month payable when the bill for switched local exchange access service, CMRS, or other 9-8-8-accessible service is due. Telephone Companies and 9-8-8 Service Carriers are required to add the 9-8-8 fee to all current bills, and to collect and remit to the Comptroller all 9-8-8 fees monthly.
Motor Fuel Tax Generally, this tax applies to businesses selling or using motor fuel in Maryland.
The Maryland motor fuel tax rate is currently 46.10¢ per gallon of gasoline and 46.85¢ per gallon of diesel fuel. There are other requirements for motor carriers, dealers, special fuel users, sellers and service station operators.
# Maryland implemented the International Fuel Tax Agreement
(IFTA) for motor carriers on 1/1/96.
Alcohol and Tobacco Tax These taxes apply to businesses manufacturing, selling, distributing or storing alcoholic beverages or selling and/or distributing cigarettes and other tobacco products in Maryland.
The Maryland excise tax rates on alcoholic beverages are $1.50 per gallon of distilled spirits, 40¢ per gallon of wine, and 9¢ per gallon of beer. Effective July 1st, 2024, reference tax aler t for details:ht tps:// HYPERL INK "ht tp://www. marylandtaxes.gov/forms/" www.marylandtaxes.gov/forms/ Tax_Publications/Tax_Alerts/Tax-Alert-Cigarettes-OT-ESDs-Tax-Rate-Changes.pdf Admissions and Amusement Tax This tax is imposed on a variety of activities, such as admission to any place, including motion pictures, athletic events, races, shows or exhibits. Also subject to this tax are receipts from athletic equipment rentals, bingo, coin-operated amusement devices, boat rides and excursions, amusement rides, golf green fees, golf cart rentals, skating, bowling shoe rentals, lift tickets, riding academies, horse rentals, and merchandise, refreshments, or a service sold or served in connection with entertainment.
The admissions and amusement tax is a local tax collected by the Comptroller's Office on behalf of Maryland's counties, Baltimore City, other incorporated cities and towns. The tax is set by the localities at rates varying from one-half of 1% to 10% of the admissions and amusement receipts. When the gross receipts are also subject to the sales and use tax, the combined tax rate may not exceed 11%.
A separate State admissions and amusement tax is imposed on the net proceeds from electronic bingo or electronic tip jars. When the net proceeds are also subject to a local tax, the combined tax rate may not exceed 35%.
Digital Advertising Gross Revenues Tax Quarterly estimated tax returns for this tax type must be filed by every person that reasonably expects its Maryland gross revenues attributable to digital advertising services, including banner advertising, search engine advertising, interstitial advertising, and other comparable advertising services, to exceed $1,000,000 for the calendar year. The applicable tax rate depends on the person's global annual gross revenues and ranges from 2.5% to 10% of annual gross revenues derived from digital advertising services in Maryland. Annual returns are due by April 15 of the next calendar year.
Tire Recycling Fee This fee applies to tire wholesalers or a tire retailer who buys tires from out-of-state sources.
Registration and payment of the fee is handled by the Revenue Administration Division.
Utility Surcharges These surcharges are collected by electric companies that deliver electricity in Maryland and by telephone companies doing business in Maryland. The electricity surcharges are then paid to the Comptroller for deposit in the Environmental Trust and Universal Service Program Funds. The telecommunications surcharges are paid to the Comptroller for deposit in the 911 Emergency
# Telephone System and Communications Access of Maryland
Funds.
The utility surcharges are collected by the Revenue Administration Division.
Direct Wine Shipper's Permit This permit is required for all in-state and out-of-state wine manufacturers that ship wine, including pomace brandy, directly to a Maryland consumer through a common carrier, such as Federal Express or UPS.
Common Carrier Permit This permit is required for a common carrier to deliver wine to a Maryland consumer.
OTHER REGISTRATIONS & TAXES
New Corporations In addition to registering with the Central Registration Unit of the Comptroller's Office, all corporations doing business in Maryland must register with the Department of Assessments and Taxation. This is also the office to contact to form a new corporation.
Bay Restoration Fee This fee is collected by all non-exempt local governmental entities, billing authorities, drinking water and sewage water treatment plant owners, who provide water or sewage services to residential, multi-residential, and nonresidential users. County governments are responsible for collecting a septic fee from owners of private wells and septic systems. The fees are remitted by these entities quarterly to the Comptroller for deposit to the Bay Restoration Fund.
Public Service Company Franchise Tax In addition to corporation income tax, public service companies are subject to the franchise tax on gross receipts. This tax is administered by the Department of Assessments and Taxation.
Insurance Company Premium Tax Insurance companies are exempt from the corporation income tax but are subject to the premium tax that is administered by the Maryland Insurance Administration.
Unemployment Insurance Employers are subject to the Maryland Department of Labor's unemployment insurance requirements and must visit the Maryland Department of Labor website at:employer.beacon.labor.md.gov/ to establish an account.
Workers' Compensation Employers in Maryland must provide Workers' Compensation Insurance for all employees.
Employers may obtain coverage from a private insurance company, by becoming self-insured or by contacting the State Injured Workers' Insurance Fund. Employers believing they are not required to obtain this insurance may contact the Workers' Compensation Commission for certification of compliance.
Business Licenses Licenses are required for certain businesses to operate in Maryland. To determine if a license is necessary, contact the Clerk of the Circuit Court in the Maryland county (or Baltimore City) where the business operates. A circuit court is located in each of those jurisdictions.
# OTHER REQUIREMENTS
Bulk Sales When an existing business is bought, the purchaser must pay a 6% bulk sales and use tax on the price of tangible personal property, such as furniture and fixtures, that is part of the business. This tax is collected by the Compliance Division of the Comptroller's Office.
Dissolution of Corporation Articles of Dissolution must be filed with the Department of Assessments and Taxation for the dissolution of a corporation. A tax clearance certificate is no longer required for the dissolution of a corporation.
Unclaimed Property Unclaimed funds such as wages, insurance benefits, bank accounts or security deposits must be reported if they remain unclaimed for three years. This property must be reported to the Compliance Division.
NOTE: The information provided on this page is a brief summary of the various Maryland business requirements and is based on the law in effect as of 7/1/20. For additional information, see the next page for the addresses and phone numbers of the Maryland agencies most frequently contacted by businesses.
Source: view the official PDF
The source document contains 4 figures (charts or worksheet graphics) not reproduced in this text version. See the official PDF above.
Nearby sections (18 sections)
- 500 · Form 500 — Maryland Corporation Income Tax Return (Corporate…
- 500e · Form 500E — Application for Extension to File Corporation Income…
- 500up · Form 500UP — Underpayment of Estimated Income Tax by…
- 502 · Form 502 — Maryland Resident Income Tax Return (Resident Booklet,…
- 502cr · Form 502CR — Income Tax Credits for Individuals (with…
- 502up · Form 502UP — Underpayment of Estimated Income Tax by Individuals
- 502x · Form 502X — Maryland Amended Tax Return (with instructions)
- 504 · Form 504 — Maryland Fiduciary Income Tax Return (Fiduciary…
- 505 · Form 505 — Maryland Nonresident Income Tax Return (Nonresident…
- 505x · Form 505X — Maryland Nonresident Amended Tax Return (with…
- 510 · Form 510 — Pass-Through Entity Income Tax Return (with…
- 510c · Form 510C — Maryland Composite Pass-Through Entity Income Tax…
- 511 · Form 511 — Pass-Through Entity Election Income Tax Return (PTE…
- mw506nrs · Form MW506NRS — Return of Income Tax Withholding for…
- mw507 · Form MW507 — Employee's Maryland Withholding Exemption…
- mw508 · Form MW508 — Annual Employer Withholding Reconciliation Return
- pv · Form PV — Personal Tax Payment Voucher
- sut202 · Form 202 — Maryland Sales and Use Tax Return (instructions)