Virginia Department of Taxation Form Instructions
VA Tax Form EMPLOYER-WITHHOLDING-INSTRUCTIONS
Virginia Employer Withholding Instructions
Income Tax Withholding Guide for Employers tax.virginia.gov
# Table of Contents
Introduction … 5
Introducing RetirePath Virginia … 5 New: Increase in Standard Deduction … 5 Important Due Date for Forms VA-6, W-2, and 1099 … 5 Where to Get Assistance … 5 Online File and Pay Options … 6 Registering for a Withholding Tax Account … 7 Who Must Register … 7 When to Register … 7 Filing Frequency Status … 7 Your Virginia Account Number … 7 Registration Changes … 8 When to File … 8 Virginia Withholding Tax Forms and Due Dates … 9 Who Must Withhold Virginia Income Tax … 10 Who is an Employer … 10 Conformity to Federal Definitions … 10 Courtesy Filers … 10 Who is an Employee … 11 Taxable and Exempt Payments … 11 Payments Subject to Withholding … 11 Payments Exempt from Withholding … 11 Payments to Nonresidents under Reciprocity Agreements … 12 Payments to Other Nonresidents … 12 Partially Exempt Employment … 13 Employee Withholding Exemption Certificates … 13 Use of Exemption Certificates … 13 Filing Exemption Certificates … 13 Claiming Exemptions … 13 Additional Withholding … 14 Exemption from Withholding … 14 How to File and Pay the Tax … 14 Electronic Filing and Payment Requirements … 14 How Often to File … 14 Semi-Weekly Filing … 15
Monthly Filing … 16
Quarterly Filing … 16
Seasonal Filing … 16
Annual Summary … 17
Adjustments to Returns … 17
Record Keeping Requirements … 18 How to Compute the Tax … 18 Tax Tables and Formula … 18 Determining the Payroll Period … 19 Using the Daily or Miscellaneous Withholding Table … 19 Nonperiodic Payments … 19 Other Methods for Computing the Tax … 20 Withholding Tables for Wages Paid after July 1, 2025 … 21 Formula for Computing Tax to be Withheld … 21
# Introduction
This publication contains general information regarding the withholding of Virginia income tax from wages. You should use this booklet as a reference guide, not as a substitute for the complete tax law provided by the Code of Virginia or the regulations and public documents published by Virginia Tax.
# Introducing RetirePath Virginia
RetirePath Virginia is open for registration. The Commonwealth's new retirement savings program is a simple solution for eligible businesses, with no employer fees or fiduciary responsibilities. Under state law, certain Virginia businesses are required to either register for RetirePath or offer their own qualified retirement plan.
RetirePath is voluntary for employees. Individuals who are self-employed or don't work for a participating employer can independently open an account. Learn more at RetirePathVA.com.
# New: Increase in Standard Deduction
Legislation enacted during the 2025 General Assembly session increases the standard deduction from $8,500 to $8,750 for single filers and from $17,000 to $17,500 for married filers filing jointly. Under this Act, the increase in the standard deduction is scheduled to sunset after Taxable Year 2026 and revert to the standard deduction amounts that applied prior to Taxable Year 2019: $3,000 for single filers and $6,000 for married couples filing jointly.
# Important Due Date for Forms VA-6, W-2, and 1099
The due date for the Employer's Annual Summary of Virginia Income Tax Withheld (Form VA-6 or Form VA-6H) along with required wage statements (Forms W-2 and 1099) is January 31. If a business closes, these forms must be filed within 30 days after the last month in which wages were paid.
# Where to Get Assistance
Visit our website at tax.virginia.gov to:
Download forms and instructions Get filing information Review answers to frequently asked questions File electronically using online services for Businesses Update registration information using online services for Businesses Call Virginia Tax Customer Service for Businesses: 804.367.8037. Tenemos servicio disponible en Español.
# Online File and Pay Options
Virginia Tax offers free online filing and ACH Debit payment options. Each option allows you to schedule your payment on a date that you specify and provides immediate filing and payment confirmation. If you prefer to make payments by ACH Credit, use our online services for businesses or Web Upload to submit the required reconciliation Forms VA-6 and/or VA-16, as applicable. See below for details.
- eForms - an easy option for all taxpayers. Whether you have little to no computer experience or you are an expert, eForms is the easiest and fastest way to file and pay electronically.
Prepare your return without having to enroll or login Fill in the fields on a return that looks just like the paper return, with eForms performing some of the calculations for you Save time by storing your account and banking information for your next filing Go to tax.virginia.gov/eforms
- Online Services for Businesses - for the taxpayer who wants to do more than file and pay electronically.
With an online account you can update your contact and address information, add new business locations, and more.
Enroll and login with the user ID and password that you select Save time by storing your account and banking information for your next filing File returns and make payments electronically, with our system performing the calculations for you View up to 14 months of your filing history Go to business.tax.virginia.gov
- Web Upload - for the taxpayer with computer experience. With this option, you can send tax return and payment files from your computer directly to Virginia Tax.
Enroll and login with the user ID and password that you select Use a variety of file types, including Excel View up to 24 months of uploaded file information File Form W-2 Go to tax.virginia.gov/webupload
- ACH Credit - to make electronic payments directly into the state's bank account.
You must contact your financial institution and make arrangements to credit the state's bank account with funds from your bank account.
Your financial institution will advise you of ACH origination services offered and any associated costs.
All of Virginia Tax's online services are free, secure, easy to use, and available 24/7 at tax.virginia.gov
# Who Must Register
You must have a Virginia withholding account if you have an employee who is earning income while in Virginia.
This includes a person or business that pays wages or salaries for services performed in Virginia or pays pensions or annuities to Virginia residents. Visit our website at virginia.gov/ireg to register your business. You may also register with the Virginia Employment Commission (VEC) at the same time you register your business online with us. Registering online is fast, easy, secure, and most of all reduces errors. You also have the ability to save your registration and complete it at a later time. If you prefer to register on paper, complete Form R-1 (Registration Application). For faster processing, provide all of the requested information.
# When to Register
You should register your business before you begin withholding wages. If you have not registered by the date that your first tax payment is due, send the payment with Form R-1 and a letter explaining what period the payment covers.
# Filing Frequency Status
Text version of this table
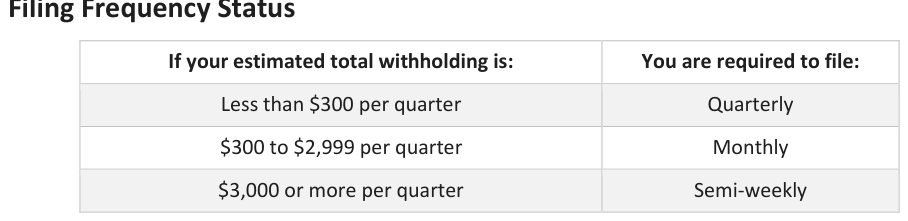
If your estimated total withholding is: You are required to file: Less than $300 per quarter Quarterly $300 to $2,999 per quarter Monthly $3,000 or more per quarter Semi-weekly
After you have registered, we will review your account each year and adjust your filing status accordingly. If your filing frequency changes, we will send you a letter of notification for the appropriate filing frequency. Filing status changes are effective on January 1 of each year and remain in effect until the following January 1.
For businesses that are operating on a seasonal basis or paying wages or salaries only during certain months of the year, complete the "Seasonal Business" section when registering using iReg or on Form R-1. Your business will be assigned a seasonal filing status.
# Your Virginia Account Number
The Virginia account number assigned by Virginia Tax will serve as the identification number for your withholding tax account and for your other major business tax accounts. Please use your account number on any returns, checks, or correspondence that you send to us.
Because your registration information also includes your Federal Employer's Identification Number (FEIN), it is helpful if you also include that number on forms and correspondence. If the Internal Revenue Service assigns a new FEIN to your business because of a reorganization, change in business type, or change of ownership, you must file Form R-1 and obtain a new Virginia account number.
If you have more than one account number and do not know which one is correct, please contact us at 804.367.8037. If you acquire another employer's business, do not use that employer's account number. Instead, complete Form R-1 and file it with a statement explaining the change in ownership.
# Registration Changes
Report all changes to your business by updating your account online at business.tax.virginia.gov. You can make any of the following changes:
Update addresses
End liability for a specific tax type Update contacts Add a new tax type to an existing account Close your business If you prefer to submit changes on paper, submit Form R-3, which can be downloaded from Virginia Tax's website at tax.virginia.gov. Do not use Form R-3 to report a name change that results from a change in ownership. Instead, file Form R-3 to close the former owner's account and file Form R-1 to obtain a Virginia account number for the new owner. In the case of a corporate merger, you should attach a copy of the merger statement to Form R-3.
# When to File
For timely filing, your return must be postmarked or received on or before the due date.
Electronic Filing - Withholding filers must file forms and payments electronically. Use eForms, online services for businesses, or Web Upload. When you use an online account, we will process your return immediately, and you can opt to schedule your payment at a future date. When using Web Upload, both return and payment can be held and processed on a future date. Be sure to file by the due date to avoid late filing penalties and interest.
You may request a temporary waiver by submitting an Electronic Filing Waiver Request, citing your specific hardship. All waivers are temporary and must be renewed annually.
Filing by Mail - When you submit a payment or return by mail or commercial delivery service, we will consider it timely provided that either the envelope shows a postmark or bears a confirmation of shipment on or before midnight of the day the return must be filed. Visit Virginia Tax's website at tax.virginia.gov to learn more.
# Virginia Withholding Tax Forms and Due Dates
Form Title and Description
EMPLOYER FORMS iReg Online registration Used to register your business for withholding tax online at our website - tax.virginia.gov.
R-1 Registration Application Used to register your business for withholding tax.
R-1H Household Employer Registration Form Used by employers of household service employees to register for withholding tax.
R-3 Registration Change Request Used to report a change of name or address, or to notify Virginia Tax that an employer is no longer liable for withholding. File before the effective date of the change. If you do not have Form R-3, send us a letter.
VA-5 Employer's Return of Virginia Income Tax Withheld Used by quarterly, monthly and seasonal filers. Quarterly returns are due on April 30, July 31, October 31, and January 31. Monthly returns are due by the 25th day of the following month. Seasonal returns are due on the same dates as monthly returns, for each month that the business has employees.
VA-15 Employer's Payment of Virginia Income Tax Withheld Used by semi-weekly filers. Payments are due within 3 banking days of any federal cutoff date (generally Tuesdays and Fridays) if the accumulated tax liability exceeds $500. If the due date falls within 3 days of the due date for Form VA-16, your payment must accompany the Form VA-16 submission.
VA-16 Employer's Payments Quarterly Reconciliation and Return of Virginia Income Tax Withheld Used by semi-weekly filers to reconcile payments for each calendar quarter.
VA-6 Employer's Annual Reconciliation of Virginia Income Tax Withheld Annual or final summary of payments for the year. Form VA-6 is due by January 31 each year or within 30 days after the last payment of wages. Forms W-2 must be sent electronically using Web Upload.
Forms W-2, W-2C, W-2G, or 1099 information must be submitted if Virginia income tax withheld is reflected on the statements. Note: Form W-2 and Form VA-6 information are 2 separate statements.
Uploading Form W-2 data to Web Upload will NOT automatically create your Form VA-6. See instructions for filing electronically at tax.virginia.gov.
VA-6H Household Employer's Annual Summary of Virginia Income Tax Withheld For household employers who elect to file their withholding tax returns on an annual basis. Form VA-6H is due by January 31 each year. When filing Form VA-6H, Wage and Tax Statements (Form W-2) must also be submitted electronically for each employee using Web Upload or eForms.
# EMPLOYEE FORMS
VA-4 Virginia Employee's Withholding Exemption Certificate Used to report the number of exemptions that an employee is entitled to claim. Obtain 1 Form VA-4 from each employee on the date employment begins.
VA-4P Withholding Exemption Certificate for Recipients of Pension and Annuity Payments Used to report the number of exemptions that a pension or annuity for recipients of pension is entitled to claim. Obtain 1 from each recipient before annuity payments begin.
# Who is an Employer
As a general rule, any person or entity that meets the definition of "employer," which is described below, must withhold Virginia income tax. An employer is generally a person or entity that pays wages to employees for services performed in Virginia or makes pension or annuity payments to residents of Virginia.
The term "employer" includes the following:
An individual, fiduciary, partnership, association, joint enterprise, or corporation for whom an employee performs services The Commonwealth of Virginia, or any political subdivision thereof, or any agency or instrumentality thereof The United States or any agency or instrumentality thereof Payers of pensions or annuities to residents of Virginia, except that financial institutions are not considered employers with respect to payments from Individual Retirement Accounts (IRA) or simplified employee pension funds (SEP)
An employer is generally subject to the Virginia withholding requirements if the employer is:
A resident of Virginia
Doing business in Virginia Domesticated under the laws of Virginia relating to the domestication of foreign corporations Making payments of wages or salaries to employees for services performed in Virginia Making pension or annuity payments to residents of Virginia
# Conformity to Federal Definitions
The determination of whether an employer-employee relationship exists for purposes of Virginia withholding requirements is made under federal law (Treas. Reg. § 31.3401(c)-1). Anyone classified as an employer for federal purposes is also an employer for Virginia purposes. Effective Jan. 1, 2021, employers are subject to a civil monetary penalty for employee misclassification. In addition to the penalties, if misclassifications are found during a second audit, then that employer will be barred from certain government contracts. Businesses found to be in violation are also liable for withholding taxes for any individual who was improperly classified for the period they were employed, as well as penalties and interest on those taxes.
# Courtesy Filers
An employer who is not otherwise subject to the Virginia withholding requirements, but wishes to withhold Virginia income tax as a courtesy to employees who reside in Virginia, may register for an account number. Once registered, the employer will be subject to the same filing requirements as all other Virginia employers.
# Who is an Employee
The term "employee" includes:
An individual (resident or nonresident) who performs or performed services in Virginia for wages A resident of Virginia who performs or performed services outside Virginia for wages An officer, employee, or elected official of the United States, or any other state or territory, or any political subdivision thereof, or the District of Columbia, or any instrumentality or agency of the governments listed An officer of a corporation A resident of Virginia who receives pension or annuity payments
An employee is generally subject to Virginia income tax withholding if any of the following conditions are met:
The individual receives taxable wages for services performed in Virginia and is not eligible for an exemption from withholding The individual is a resident of Virginia who receives taxable wages for services performed outside Virginia and does not qualify for an exemption from withholding The individual is a resident of Virginia and receives pension or annuity payments or both from which federal income tax has been withheld (except IRA and SEP payments) and is not eligible for an exemption from withholding See "How to Compute the Tax" for additional information.
# Payments Subject to Withholding
Virginia law conforms to the federal definition of income subject to withholding. Virginia withholding is generally required on any payment for which federal withholding is required. This includes most wages, pensions and annuities, gambling winnings, vacation pay, bonuses, and certain expense reimbursements.
# Payments Exempt from Withholding
Payments that are exempt from federal withholding are also exempt from Virginia withholding. In addition, the following payments are exempt from Virginia withholding:
Payments made for acting in or serving as a crew member for movies, television series, commercials, or promotional films that are filmed totally or partially in Virginia by an employer that conducts business in Virginia for less than 90 days and that edits, processes, and markets the completed project outside Virginia
Payments made from an IRA or SEP Payments made to nonresident employees of rail carriers, motor carriers, and water carriers Payments made to resident and nonresident merchant seamen
# Payments to Nonresidents under Reciprocity Agreements
When you make wage or salary payments to a nonresident for services performed in Virginia, you typically must withhold Virginia income tax in the same manner as you would for a resident. Virginia has entered into reciprocity agreements with other states for individuals who earn income in states other than their states of residence. The agreements allow those individuals to be taxed only by their state of residence on earned or business income, provided that certain conditions are met. The terms of the agreements eliminate a nonresident's liability for Virginia income tax, as well as the requirement for withholding from payments made for services performed in Virginia. Current reciprocity agreements affect Virginia withholding requirements for residents of the following states: Kentucky, the District of Columbia, Maryland, West Virginia and Pennsylvania.
Withholding provisions for residents of these states who work in Virginia are described below.
Kentucky and the District of Columbia:
Wage and salary payments to residents of these states are not subject to Virginia withholding if the employees commute daily to a place of employment in Virginia.
Maryland, West Virginia, and Pennsylvania:
Wage and salary payments made to residents of these states are not subject to Virginia withholding if the employees meet the following conditions:
The employee maintains a legal domicile in another state and lives in Virginia for less than 183 days of the taxable year (or does not live in Virginia at all) The only Virginia source income received during the year was from salaries or wages The Virginia source income is subject to taxation by the individual's state of residence Any nonresident who is exempt from Virginia withholding under a reciprocity agreement must indicate this on the Form VA-4, Employee's Exemption Certificate, filed with their employer.
# Payments to Other Nonresidents
Payments to the following nonresidents for services performed in Virginia are subject to withholding:
Residents of non-reciprocity states. This includes residents of neighboring states (Tennessee and North Carolina) for which Virginia has no reciprocity agreement in place, as well as residents of other states who are working in Virginia on a temporary basis Residents of Kentucky, the District of Columbia, Maryland, West Virginia, and Pennsylvania who do not meet the conditions for exemption under Virginia's reciprocity agreements with those states
# Partially Exempt Employment
If an employee performs both taxable and nontaxable services for an employer, the entire payment for those services is subject to Virginia withholding if at least one-half of the services are taxable. If less than one-half of the employee's time is spent in services not subject to withholding, the entire payment is exempt.
# Use of Exemption Certificates
To compute Virginia withholding tax for payments made to an employee, you need to know the number of personal exemptions that the employee can claim. The employee gives you this information on Form VA-4, Virginia Employee's Income Tax Withholding Exemption Certificate. An employee would also use Form VA-4 to tell an employer that he or she is exempt from Virginia withholding. Recipients of pension and annuity payments use a different certificate, Form VA-4P, to report their exemption information to their payers.
Keep exemption certificates in your records to support your computation of Virginia withholding tax for each employee. Do not send the certificates to Virginia Tax.
You must use the Virginia exemption certificates for computing Virginia withholding. You may not substitute federal certificates (Forms W-4 or W-4P).
# Filing Exemption Certificates
Employees must file Form VA-4 with you when their employment begins. Form VA-4P should be filed before pension or annuity distributions begin. If no Form VA-4 or VA-4P is filed, withhold Virginia income tax as if no exemptions had been claimed. A new Form VA-4 or Form VA-4P must be filed if the employee's allowable number of exemptions changes or if an employee that was previously exempt from Virginia income tax becomes subject to the tax. The form should be filed within 10 days of the employee's change in status. Note: Employers may establish a system to electronically receive Forms VA-4 from employees, provided the system meets Internal Revenue Service requirements as specified in Treas. Reg. § 31.3402(f)(5)-1(c).
# Claiming Exemptions
The employee must complete the Personal Exemption Worksheet to determine the allowable number of exemptions for withholding purposes. An employee may not claim more than the number of personal exemptions that he or she is entitled to claim for purposes of filing an individual income tax return, unless Virginia Tax has authorized additional exemptions in writing.
In cases where an employee will be claiming a large amount of itemized deductions on their income tax return, basing the withholding computation on the usual number of allowable exemptions may result in withholding too much tax. If an employee can show that such withholding has resulted in a refund of $300 or more for the preceding tax year, they may write to the Department of Taxation, P.O. Box 1115, Richmond, VA 23218-1115 to request permission to claim additional withholding exemptions. The letter should include the employee's name, Social Security number, estimated Virginia taxable income for the year, gross wages per pay period, and number of pay periods.
If you believe that an employee has claimed too many exemptions, please send a copy of the employee's Form VA-4 to the Department of Taxation, P.O. Box 1115, Richmond, VA 23218-1115, and request a review of the information. We will notify you in writing whether you may accept the Form VA-4 as filed or whether the employee must file a new Form VA-4.
# Additional Withholding
If an employee wants to have an additional amount of tax withheld from each paycheck, and you agree to do so, the employee must indicate the additional amount on Form VA-4 or Form VA-4P. If you do not agree to withhold additional tax, the employee may need to make estimated tax payments.
# Exemption from Withholding
An employee is exempt from Virginia withholding if he or she meets any of the conditions listed on Form VA-4 or VA-4P. The employee must file a new certificate each year to certify the exemption. Be sure to keep copies of any certificate claiming exemption from withholding.
# Electronic Filing and Payment Requirements
All employers are required to submit all returns and payments electronically. Virginia Tax offers the following filing options: eForms, online services for Businesses, and Web Upload. You must submit return and payment information using these systems or by making payments via ACH Credit. You can download an Electronic Payment Guide from our website at tax.virginia.gov.
# How Often to File
Your filing status is determined by the average amount of income tax that you withhold each month. When you register your business for withholding tax, you are asked to estimate this figure so that Virginia Tax can assign a filing status. Based on that information, we assign a quarterly, monthly, semi-weekly, or seasonal filing status. In addition, all employers must file an annual summary. You are not responsible for monitoring your monthly tax liability to see if a status change is needed. Virginia Tax reviews each account annually and makes any necessary changes. We usually mail notices of change in filing status during December of each year and they become effective on January 1.
Liability for Filing
After you register for a withholding tax account, you must file a return for every period during which the account remains open, even if there is no tax due. If you do not expect to pay wages for an extended period of time, you may want to close the account until you begin paying wages again.
Extensions of Time for Filing and Payment
Virginia Tax will grant a reasonable extension of time for filing and/or payment when good cause exists. You must apply for an extension in writing before the due date of the applicable return. If the time for payment is extended, we will assess interest on the tax due from the original due date through the date of payment.
# Semi-Weekly Filing
If your average monthly liability is $1,000 or more, Virginia Tax will assign a semi-weekly filing status to your account. If the Virginia income tax withheld as of the close of any federal deposit period is more than $500, a payment must be made within 3 banking days. Federal cutoff days for withholding deposits are generally Tuesday and Friday of each week. At the end of each calendar quarter, you are required to submit a reconciliation on Form VA-16, along with payment of any remaining tax due for the quarter. In addition, if the due date for Form VA-16 falls within 3 days of the due date of a current month's semi-weekly payment, the current payment is included on Form VA-16. Form VA-16 is due the last day of the month following the close of the quarterly filing period.
Special Rule for Semi-Weekly Filers
Semi-weekly filers are required to file a summary for each calendar quarter on Form VA-16. The total payments made for the quarter are subtracted from the actual tax withheld, and any remaining balance due is paid with the return. Semi-weekly filers are subject to a 6% underpayment penalty if at least 90% of the total tax liability for the quarterly period has not been paid within 3 banking days after the close of the semi-weekly deposit period that covers the quarterly period end date.
Waiver
Certain employers may request a waiver from Virginia semi-weekly income tax withholding requirements. If the Tax Commissioner grants a waiver, the employer will be allowed to file withholding returns and pay the withholding tax on a monthly basis. An employer must have no more than 5 employees who are subject to Virginia income tax withholding and must submit a request in writing to Virginia Tax no later than December 15 of the year prior to the year for which a waiver is being requested. To meet the employment requirement, an employer must certify that it employed an average number of no more than 5 employees during the current year, and that it does not foresee a change in the average number of employees during the upcoming year. The request must also set forth in detail the reasons for the waiver. Waiver requests should be submitted to: Virginia Department of Taxation, Employer Withholding Waiver Request, P.O. Box 1114, Richmond, Virginia 23218- 1114 or fax to 804.367.2603.
Virginia Tax will notify the employer in writing whether the Tax Commissioner has granted such a request. If so, the employer will be allowed to file withholding returns and pay the withholding tax on a monthly basis for the following calendar year. You must submit waiver requests each year by December 15 of the year prior to the year for which a waiver is being requested. For more information, contact us at 804.367.8037 or visit tax.virginia.gov.
# Monthly Filing
If your average monthly withholding tax liability is at least $100 but less than $1,000, Virginia Tax will assign a monthly filing status to your account. Submit Form VA-5 and pay by the 25th day of the following month. A list of the due dates for monthly returns is shown below.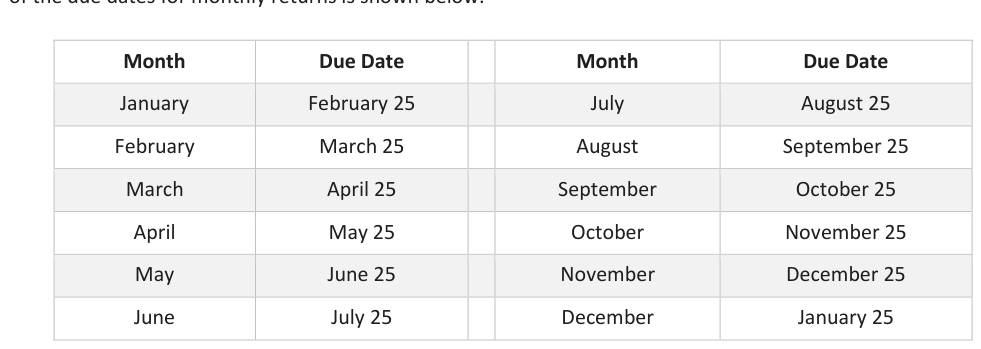
Text version of this table
Month Due Date Month Due Date January February 25 July August 25 February March 25 August September 25 March April 25 September October 25 April May 25 October November 25 May June 25 November December 25 June July 25 December January 25
You must submit a return for each month even if there is no tax due. Any tax due must be paid by the due date.
# Quarterly Filing
If the average monthly withholding tax liability is less than $100, Virginia Tax will assign a quarterly filing status to your account. Submit Form VA-5 and pay by the last day of the following month. A list of the due dates for quarterly returns is shown below.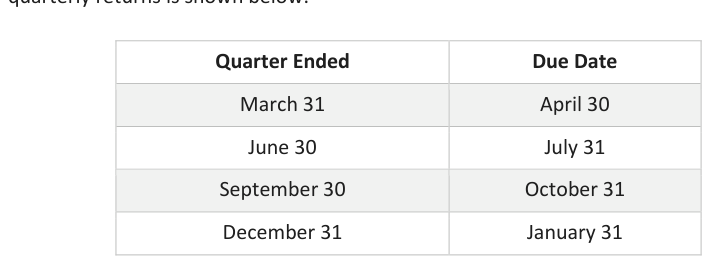
Text version of this table
Quarter Ended Due Date March 31 April 30 June 30 July 31 September 30 October 31 December 31 January 31
You must submit a return for each quarter even if there is no tax due
# Seasonal Filing
As a seasonal filer, you are required to submit returns for the months that you designated when you registered, even if there is no tax due. Seasonal returns are submitted using Form VA-5 and are due on the 25th of the following month for each month that the business has an employee. To change the designated months, write to the Registration Unit, P.O. Box 1114, Richmond, VA 23218-1114.
# Annual Summary
Form VA-6. Every employer must submit Form VA-6, Annual Summary online using eForms, online services for Businesses, or Web Upload at tax.virginia.gov. Form VA-6 is due on January 31. If you close your account before the end of the year, you must file Form VA-6 within 30 days of the last month in which you pay wages. All employers must submit their VA-6 electronically.
Federal Income Statements. You must submit any federal income statements (Forms W-2 and 1099) that reflect Virginia withholding. Beginning in December 2021, a new Form W-2C layout must be used to correct W-2 information via Web Upload and eForms. Forms W-2, W-2C, 1099- MISC, 1099-NEC, and 1099-R may be submitted using Web Upload or eForms. If you have other federal series forms, such as the Forms W-2G or 1099-INT that reflect Virginia withholding, you must submit these on paper.
Web Upload Reporting. You may file Forms W-2, W-2C, 1099-MISC, 1099-NEC, 1099-R, and 1099-K electronically via the Web Upload system and receive immediate validation/feedback on your submitted data.
Files must be formatted according to the SSA's EFW2 and the IRS's Publication 1220. The state code of (51) should be used to indicate Virginia income tax withheld. Details for filing by Web Upload can be found at tax.virginia.gov/web-upload. Note: Submitting Form W-2 information to Virginia Tax does not take the place of filing state employment data. You must transmit that information separately to the VEC. eForms. Virginia's eForms system is a free and secure system using fillable electronic forms to electronically file your wage and tax statements. Use eForms to enter your W-2, W-2C, or 1099 information and submit it electronically to Virginia Tax. With eForms, you can file directly from your web browser without signing up for an account. You can find details for submitting data using eForms at tax.virginia.gov/eforms.
Form 1099 Requirements. You are required to file Forms 1099 with Virginia Tax when the forms show Virginia income tax withheld. See Tax Bulletin 20-10 for Form 1099-K reporting requirements.
Help prevent refund fraud and identity theft. Since we use employer withholding records to combat refund fraud and identity theft, the delay in receipt of records can impact the processing of individual income tax returns. Without a payer copy on record, we may contact recipients to provide additional documentation to substantiate their Virginia withholding claims and refund entitlements.
# Adjustments to Returns
If you overpay your withholding tax, you may claim a credit on your return for the next period or request a refund. Refund requests should be mailed to Department of Taxation, P.O. Box 1115, Richmond, VA 23218-1115.
Virginia Tax will allow a refund only if the tax in question was not actually withheld from an employee's wages.
Claims for credit or refund must be filed within 3 years from the due date of the return for the period in which the overpayment occurred. If you underpay your tax, report the underpayment on your next return and attach a detailed explanation. If the underpayment is not discovered until the end of the calendar year, you should pay the tax with your annual summary, Form VA-6.
# Late Filing Penalty
The penalty for filing a withholding return after the due date is 6% of the tax due for every month or part of a month that the return is late. The maximum penalty is 30% of the tax due. The minimum penalty is $10.00. The minimum penalty applies even if there is no tax due.
# Late Payment Penalty
The penalty for late payment of withholding tax is the same as the late filing penalty (6% per month), and the same minimum and maximum amounts apply. However, the late payment penalty does not apply to any month for which the late filing penalty has already been assessed. Therefore, the total combined penalties for late filing and late payment cannot exceed 30% of the tax due, and the minimum penalty of $10.00 can be assessed only once.
Interest
If tax is paid after the due date, even with an approved extension, interest is accrued on the tax due from the due date through the date of payment. The interest rate is the federal underpayment rate established under Internal Revenue Code § 6621, plus 2%.
# Record Keeping Requirements
Your withholding tax records should include:
The amounts and dates of wage payments made to each employee The amounts and dates of all Virginia income tax withheld from each employee The name, address, social security number, and period of employment for each employee An exemption certificate (Form VA-4 or VA-4P) for each employee Your account number and the amounts and dates of all tax payments made to the Department; and A list of employees claiming exemption from withholding, including Social Security numbers Keep all records for at least 3 years after the due date to which they relate or the date the tax was paid, whichever is later.
# Tax Tables and Formula
Tables for computing the tax, based on weekly, bi-weekly, semi-monthly, monthly, and daily or miscellaneous pay periods are provided starting on Page 21. To use a table, select the appropriate wage bracket in the lefthand column, then the number of exemptions from the top of the table to arrive at the amount of tax to be withheld. The tax amounts listed in the tables are rounded to the nearest dollar. To compute the exact amount of tax to be withheld, use the formula on Page 21.
# Determining the Payroll Period
For purposes of computing withholding, "payroll period" means the period of service (daily, weekly, monthly, etc.) for which you normally pay wages. You should use the same period that you use for federal withholding tax purposes. If you have a regular payroll period, use that period for computing the tax, even if your employee does not work for the entire period. If you do not have a regular payroll period in place, compute the tax using the Daily or Miscellaneous Withholding Tax Table. Special instructions for using that table are given below.
For a period of less than 1 week, you may compute the tax using a weekly payroll period, provided that the employee signs a statement certifying that they have not worked for any other employer for wages subject to withholding in that calendar week.
# Using the Daily or Miscellaneous Withholding Table
To compute the tax using the Daily or Miscellaneous Withholding Tax Table: a. Count the number of days in the period covered by the payment, including Saturdays, Sundays, and holidays. If the wages are not related to a specific period of time (for example, commissions paid upon completion of a sale), count the number of days back from the payment date to the latest of the following dates: i. The last wage payment made to that employee in the same calendar year ii. The date employment began, if that date falls in the same calendar year iii. January 1 of the year in which you are making the payment b. Divide the wage payment by the number of days computed under a. This is the average daily wage. c. Locate the average daily wage amount in the left column of the Daily or Miscellaneous Withholding Tax Table, then compute the daily tax by selecting the appropriate number of exemptions from the top of the table. d. Multiply the daily tax by the number of days computed under a to compute the tax for the pay period.
# Nonperiodic Payments
Pension and Annuity Payments. If the payment is subject to mandatory federal withholding of 20% or 28% or if payments are not made on a regular basis, withhold Virginia tax at a rate of 4%.
Vacation Pay and Bonuses. If vacation pay or bonuses are included with a regular wage payment, add those amounts to the gross wages for the period and withhold tax on the entire total using the withholding tax tables or formula. If the payments are not included with regular wage payments, compute the tax as described in the "Supplemental Wage Payments" section.
Supplemental Wage Payments. Add supplemental payments (such as commissions, overtime, back pay, and certain reimbursements) that are included with a regular wage payment to the gross wages and withhold tax on the entire total, using the withholding tax tables or the formula.
If the supplemental wage payment is made separately, compute the tax as follows:
a. Add the supplemental wage payment to the regular wages for the current payroll period or to the wages for the last regular payroll period in the same calendar year. b. Compute the tax on the total from a using the withholding tax tables or formula. c. Compute the tax on the regular wages alone. d. Subtract the tax computed in c from the tax computed in b. This is the amount that should be withheld from the supplemental payment.
However, if supplemental wage payments are paid and tax has been withheld from the employee's regular wages, the employer may determine the tax to be withheld by using a flat percentage rate of 5.75%, without allowance for exemption and without reference to any regular payment of wages.
# Other Methods for Computing the Tax
Virginia law allows the Tax Commissioner to approve the use of computation methods other than the formula and tables provided in this booklet. To apply for permission to use an alternative method, write to the Tax Commissioner, Virginia Tax, P.O. Box 2475, Richmond, VA 23218-2475. The requested method must result in substantially the same amount of tax withheld as you would compute using the tables or formula. Because of several differences between Virginia and federal income tax laws, it is not possible to correctly compute the Virginia tax to be withheld by using a method comparable to the federal "percentage method" or by using a set % of the federal tax withheld.
Withholding Tables for Wages Paid after July 1, 2025
The amounts in the tables are approximate. Use the formula below for exact amounts.
The tables include increases in the standard deduction from $8,500 to $8,750 for single filers and from $17,000 to $17,500 for married filers filing jointly. If you are an employer properly using a prior version of these tables, you may begin using these updated tables for wages paid on any date after July 1, 2025.
The increase in the standard deduction is scheduled to sunset after Taxable Year 2026 and revert to the standard deduction amounts that applied prior to Taxable Year 2019: $3,000 for single filers and $6,000 for married couples filing jointly.
# Formula for Computing Tax to be Withheld
Legend
G = Gross pay for pay period P = Number of pay periods per year A = Annualized gross pay (G x P) E1 = Personal and Dependent Exemptions E2 = Age 65 and Over & Blind Exemptions T = Annualized taxable income W = Annualized tax to be withheld W/H = Tax to be withheld for pay period
Formula
Effective for wages paid after July 1, 2025
(for Taxable Year 2025 and after filers)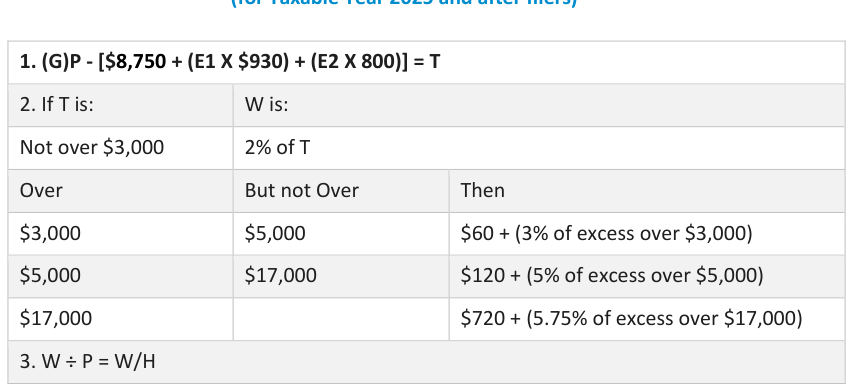
Text version of this table
1. (G)P - [$8,750 + (E1 X $930) + (E2 X 800)] = T 2. If T is: W is: Not over $3,000 2% of T Over But not Over Then $3,000 $5,000 $60 + (3% of excess over $3,000) $5,000 $17,000 $120 + (5% of excess over $5,000) $17,000 $720 + (5.75% of excess over $17,000) 3. W ÷ P = W/H
Example:
John claims exemptions for himself, his spouse, and their three children for withholding tax purposes. He is paid on a semi-monthly basis, and his gross wages for this pay period were $2,649.
- (G)P - [$8,750 + ($930)E1] = T ($2,649)24 - [$8,750 + ($930)5] = T $63,576 - $13,400 = $50,176
- T is over $17,000
$720 + 5.75% of $33,176 = W
$720 + $1,908 = $2,628
- W ÷ P = W/H
$2,628 ÷ 24 = $109.50
The tax to be withheld for the current period is $109.50.
Pay Period Conversion Table (P)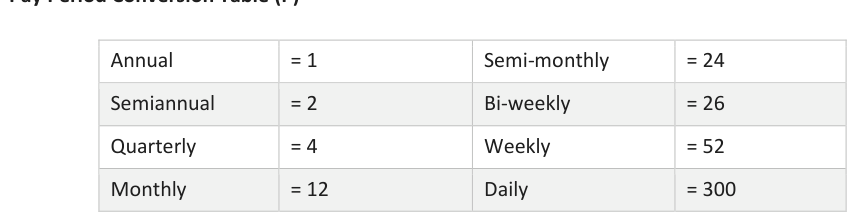
Text version of this table
Annual = 1 Semi-monthly = 24 Semiannual = 2 Bi-weekly = 26 Quarterly = 4 Weekly = 52 Monthly = 12 Daily = 300
# For Wages Paid After July 1, 2025
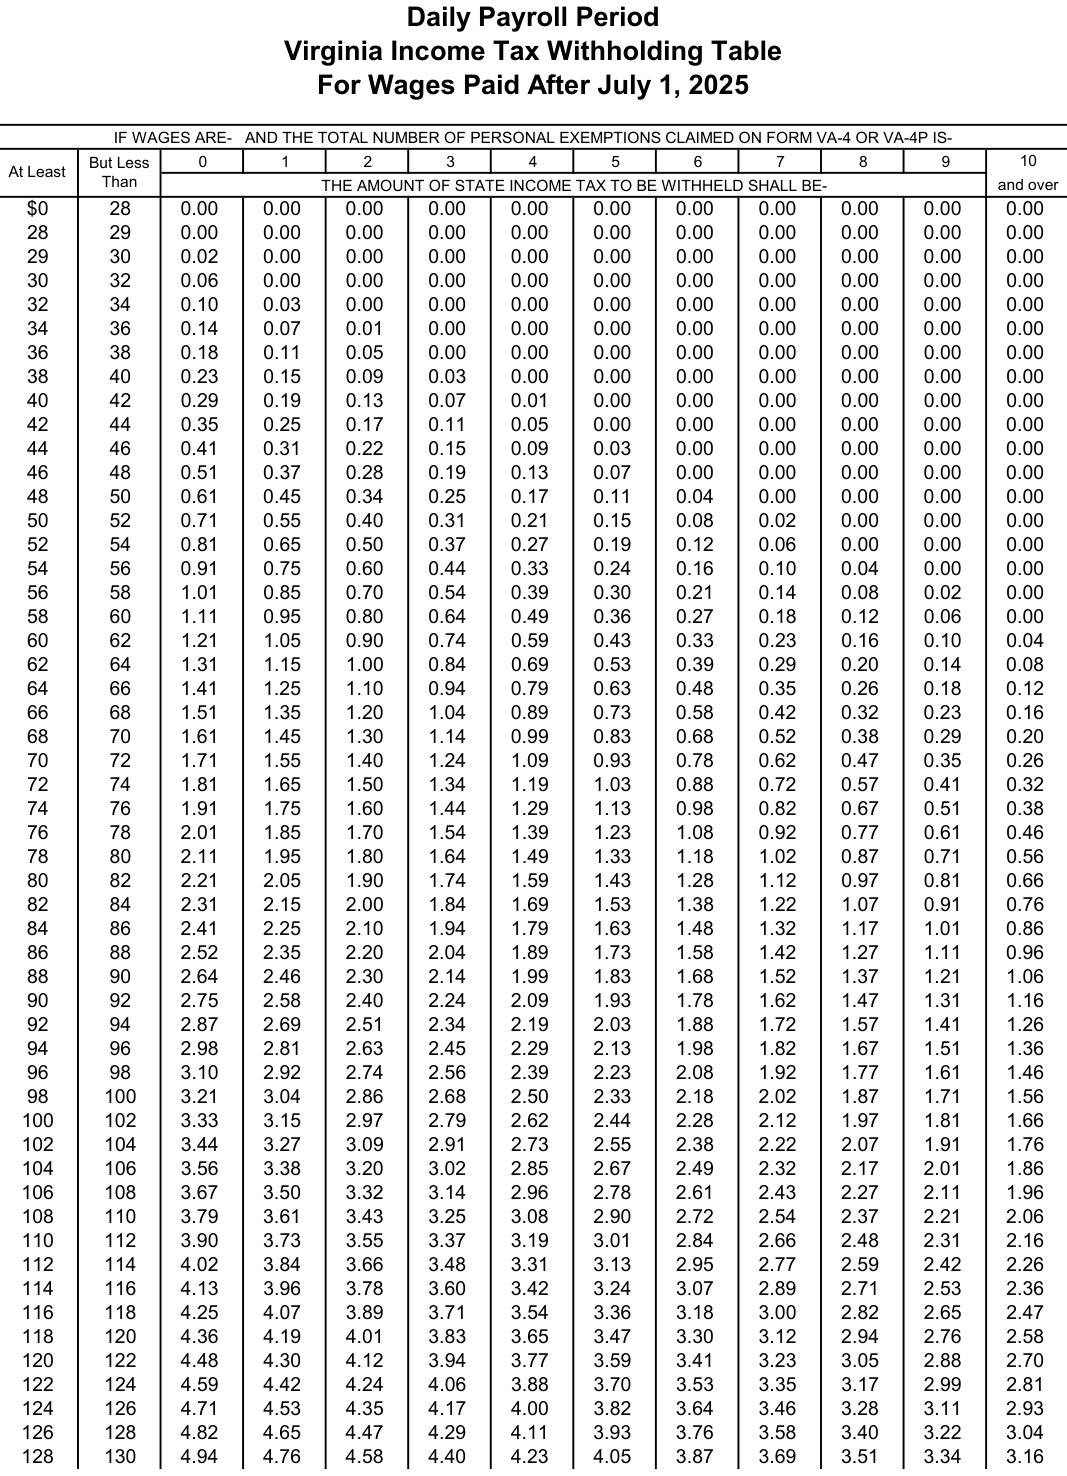
Text version of this table
| Virginia Inc | ome T | ax Wit | hholdi | ng Ta | ble | ||||||
| For Wag | es Pai | d After | July 1 | , 2025 | |||||||
| IF WAGE | S ARE- AND | THE TOTAL NUMBE | R OF PERS | ONAL EXE | MPTIONS C | LAIMED O | N FORM VA- | 4 OR VA-4P | IS- | ||
| B Least | ut Less | 0 | 1 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
| Than | THE AMOUNT | OF STATE | INCOME TA | X TO BE W | ITHHELD | SHALL BE- | a | nd ov | |||
| $0 | 28 | 0.00 0. | 00 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 28 | 29 | 0.00 0. | 00 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 29 | 30 | 0.02 0. | 00 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 30 | 32 | 0.06 0. | 00 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 32 | 34 | 0.10 0. | 03 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 34 | 36 | 0.14 0. | 07 0.01 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 36 | 38 | 0.18 0. | 11 0.05 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 38 | 40 | 0.23 0. | 15 0.09 | 0.03 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 40 | 42 | 0.29 0. | 19 0.13 | 0.07 | 0.01 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 42 | 44 | 0.35 0. | 25 0.17 | 0.11 | 0.05 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 44 | 46 | 0.41 0. | 31 0.22 | 0.15 | 0.09 | 0.03 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 46 | 48 | 0.51 0. | 37 0.28 | 0.19 | 0.13 | 0.07 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 48 | 50 | 0.61 0. | 45 0.34 | 0.25 | 0.17 | 0.11 | 0.04 | 0.00 | 0.00 | 0.00 | 0.00 |
| 50 | 52 | 0.71 0. | 55 0.40 | 0.31 | 0.21 | 0.15 | 0.08 | 0.02 | 0.00 | 0.00 | 0.00 |
| 52 | 54 | 0.81 0. | 65 0.50 | 0.37 | 0.27 | 0.19 | 0.12 | 0.06 | 0.00 | 0.00 | 0.00 |
| 54 | 56 | 0.91 0. | 75 0.60 | 0.44 | 0.33 | 0.24 | 0.16 | 0.10 | 0.04 | 0.00 | 0.00 |
| 56 | 58 | 1.01 0. | 85 0.70 | 0.54 | 0.39 | 0.30 | 0.21 | 0.14 | 0.08 | 0.02 | 0.00 |
| 58 | 60 | 1.11 0. | 95 0.80 | 0.64 | 0.49 | 0.36 | 0.27 | 0.18 | 0.12 | 0.06 | 0.00 |
| 60 | 62 | 1.21 1. | 05 0.90 | 0.74 | 0.59 | 0.43 | 0.33 | 0.23 | 0.16 | 0.10 | 0.04 |
| 62 | 64 | 1.31 1. | 15 1.00 | 0.84 | 0.69 | 0.53 | 0.39 | 0.29 | 0.20 | 0.14 | 0.08 |
| 64 | 66 | 1.41 1. | 25 1.10 | 0.94 | 0.79 | 0.63 | 0.48 | 0.35 | 0.26 | 0.18 | 0.12 |
| 66 | 68 | 1.51 1. | 35 1.20 | 1.04 | 0.89 | 0.73 | 0.58 | 0.42 | 0.32 | 0.23 | 0.16 |
| 68 | 70 | 1.61 1. | 45 1.30 | 1.14 | 0.99 | 0.83 | 0.68 | 0.52 | 0.38 | 0.29 | 0.20 |
| 70 | 72 | 1.71 1. | 55 1.40 | 1.24 | 1.09 | 0.93 | 0.78 | 0.62 | 0.47 | 0.35 | 0.26 |
| 72 | 74 | 1.81 1. | 65 1.50 | 1.34 | 1.19 | 1.03 | 0.88 | 0.72 | 0.57 | 0.41 | 0.32 |
| 74 | 76 | 1.91 1. | 75 1.60 | 1.44 | 1.29 | 1.13 | 0.98 | 0.82 | 0.67 | 0.51 | 0.38 |
| 76 | 78 | 2.01 1. | 85 1.70 | 1.54 | 1.39 | 1.23 | 1.08 | 0.92 | 0.77 | 0.61 | 0.46 |
| 78 | 80 | 2.11 1. | 95 1.80 | 1.64 | 1.49 | 1.33 | 1.18 | 1.02 | 0.87 | 0.71 | 0.56 |
| 80 | 82 | 2.21 2. | 05 1.90 | 1.74 | 1.59 | 1.43 | 1.28 | 1.12 | 0.97 | 0.81 | 0.66 |
| 82 | 84 | 2.31 2. | 15 2.00 | 1.84 | 1.69 | 1.53 | 1.38 | 1.22 | 1.07 | 0.91 | 0.76 |
| 84 | 86 | 2.41 2. | 25 2.10 | 1.94 | 1.79 | 1.63 | 1.48 | 1.32 | 1.17 | 1.01 | 0.86 |
| 86 | 88 | 2.52 2. | 35 2.20 | 2.04 | 1.89 | 1.73 | 1.58 | 1.42 | 1.27 | 1.11 | 0.96 |
| 88 | 90 | 2.64 2. | 46 2.30 | 2.14 | 1.99 | 1.83 | 1.68 | 1.52 | 1.37 | 1.21 | 1.06 |
| 90 | 92 | 2.75 2. | 58 2.40 | 2.24 | 2.09 | 1.93 | 1.78 | 1.62 | 1.47 | 1.31 | 1.16 |
| 92 | 94 | 2.87 2. | 69 2.51 | 2.34 | 2.19 | 2.03 | 1.88 | 1.72 | 1.57 | 1.41 | 1.26 |
| 94 | 96 | 2.98 2. | 81 2.63 | 2.45 | 2.29 | 2.13 | 1.98 | 1.82 | 1.67 | 1.51 | 1.36 |
| 96 | 98 | 3.10 2. | 92 2.74 | 2.56 | 2.39 | 2.23 | 2.08 | 1.92 | 1.77 | 1.61 | 1.46 |
| 98 | 100 | 3.21 3. | 04 2.86 | 2.68 | 2.50 | 2.33 | 2.18 | 2.02 | 1.87 | 1.71 | 1.56 |
| 100 | 102 | 3.33 3. | 15 2.97 | 2.79 | 2.62 | 2.44 | 2.28 | 2.12 | 1.97 | 1.81 | 1.66 |
| 102 | 104 | 3.44 3. | 27 3.09 | 2.91 | 2.73 | 2.55 | 2.38 | 2.22 | 2.07 | 1.91 | 1.76 |
| 104 | 106 | 3.56 3. | 38 3.20 | 3.02 | 2.85 | 2.67 | 2.49 | 2.32 | 2.17 | 2.01 | 1.86 |
| 106 | 108 | 3.67 3. | 50 3.32 | 3.14 | 2.96 | 2.78 | 2.61 | 2.43 | 2.27 | 2.11 | 1.96 |
| 108 | 110 | 3.79 3. | 61 3.43 | 3.25 | 3.08 | 2.90 | 2.72 | 2.54 | 2.37 | 2.21 | 2.06 |
| 110 | 112 | 3.90 3. | 73 3.55 | 3.37 | 3.19 | 3.01 | 2.84 | 2.66 | 2.48 | 2.31 | 2.16 |
| 112 | 114 | 4.02 3. | 84 3.66 | 3.48 | 3.31 | 3.13 | 2.95 | 2.77 | 2.59 | 2.42 | 2.26 |
| 114 | 116 | 4.13 3. | 96 3.78 | 3.60 | 3.42 | 3.24 | 3.07 | 2.89 | 2.71 | 2.53 | 2.36 |
| 116 | 118 | 4.25 4. | 07 3.89 | 3.71 | 3.54 | 3.36 | 3.18 | 3.00 | 2.82 | 2.65 | 2.47 |
| 118 | 120 | 4.36 4. | 19 4.01 | 3.83 | 3.65 | 3.47 | 3.30 | 3.12 | 2.94 | 2.76 | 2.58 |
| 120 | 122 | 4.48 4. | 30 4.12 | 3.94 | 3.77 | 3.59 | 3.41 | 3.23 | 3.05 | 2.88 | 2.70 |
| 122 | 124 | 4.59 4. | 42 4.24 | 4.06 | 3.88 | 3.70 | 3.53 | 3.35 | 3.17 | 2.99 | 2.81 |
| 124 | 126 | 4.71 4. | 53 4.35 | 4.17 | 4.00 | 3.82 | 3.64 | 3.46 | 3.28 | 3.11 | 2.93 |
| 126 | 128 | 4.82 4. | 65 4.47 | 4.29 | 4.11 | 3.93 | 3.76 | 3.58 | 3.40 | 3.22 | 3.04 |
| 128 | 130 | 4.94 4. | 76 4.58 | 4.40 | 4.23 | 4.05 | 3.87 | 3.69 | 3.51 | 3.34 | 3.16 |
# For Wages Paid After July 1, 2025
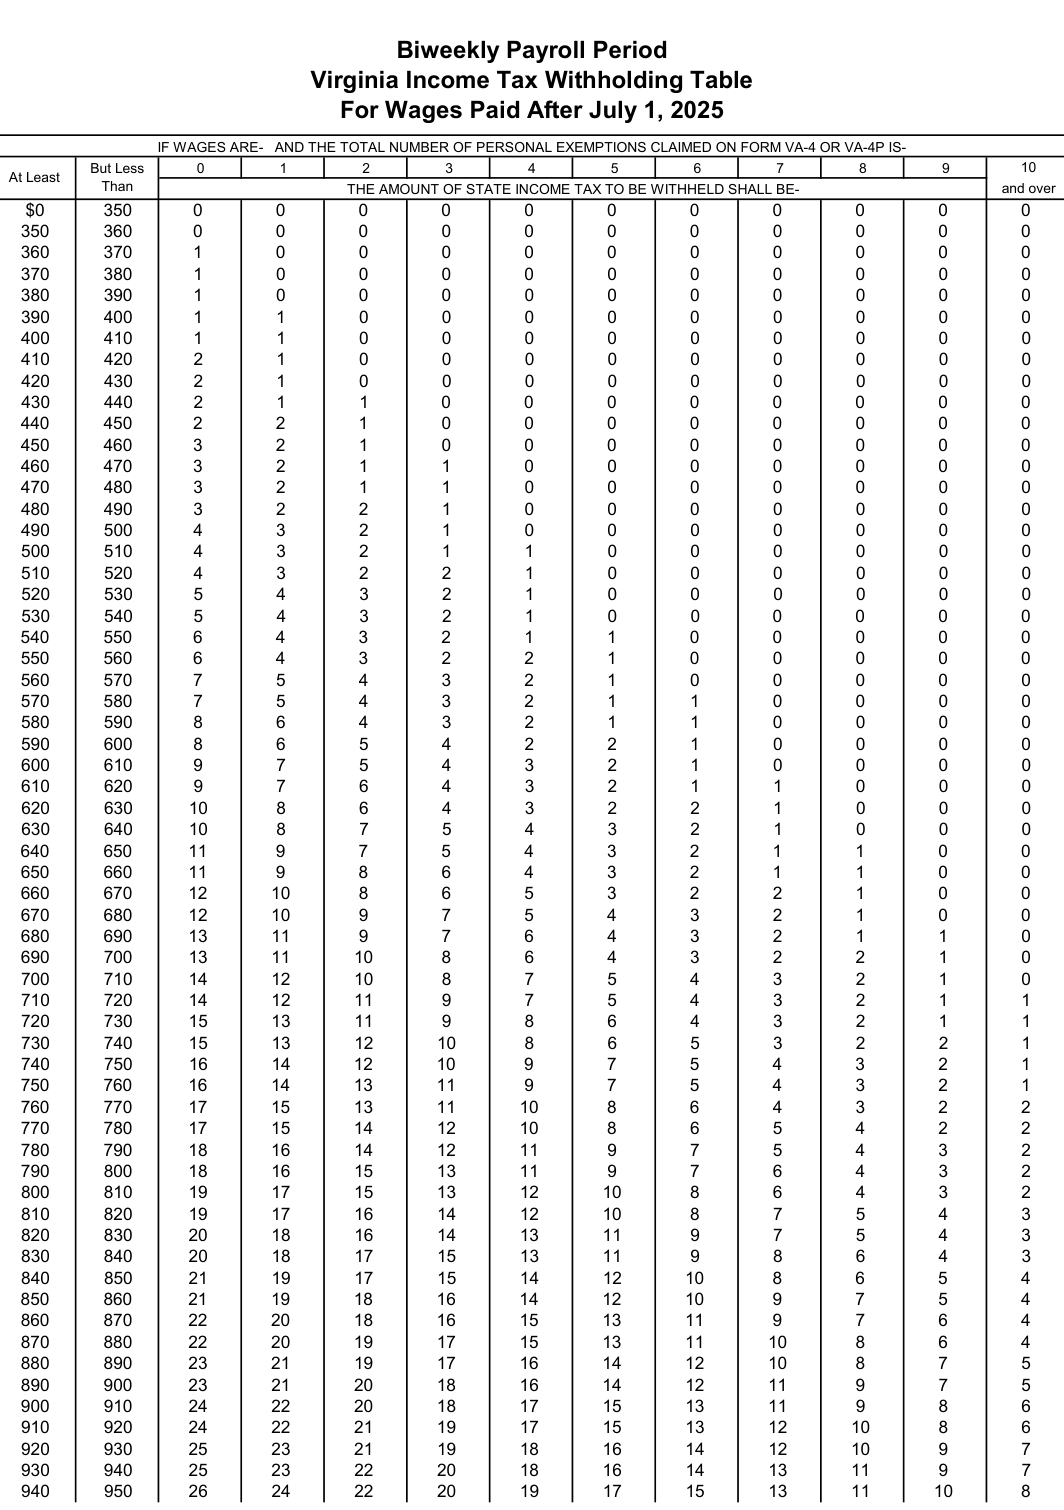
Text version of this table
| Biweekly P | ay | roll Period | ||||||||||
| Vir | ginia | Income Ta | x | Withholding | Table | |||||||
| For | Wages Paid | A | fter July 1, 2 | 025 | ||||||||
| IF | WAGES ARE- | AND THE | TOTAL N | UMBER OF PERS | ONA | L EXEMPTIONS CLAIM | ED ON FOR | M VA-4 OR V | A-4P IS- | |||
| B Least | ut Less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
| Than | THE AM | OUNT OF STATE I | NCO | ME TAX TO BE WITH | HELD SHAL | L BE- | an | d o | ||||
| $0 | 350 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 350 | 360 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 360 | 370 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 370 | 380 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 380 | 390 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 390 | 400 | 1 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 400 | 410 | 1 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 410 | 420 | 2 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 420 | 430 | 2 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 430 | 440 | 2 | 1 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 440 | 450 | 2 | 2 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 450 | 460 | 3 | 2 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 460 | 470 | 3 | 2 | 1 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 470 | 480 | 3 | 2 | 1 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 480 | 490 | 3 | 2 | 2 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 490 | 500 | 4 | 3 | 2 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 500 | 510 | 4 | 3 | 2 | 1 | 1 | 0 | 0 | 0 | 0 | 0 | 0 |
| 510 | 520 | 4 | 3 | 2 | 2 | 1 | 0 | 0 | 0 | 0 | 0 | 0 |
| 520 | 530 | 5 | 4 | 3 | 2 | 1 | 0 | 0 | 0 | 0 | 0 | 0 |
| 530 | 540 | 5 | 4 | 3 | 2 | 1 | 0 | 0 | 0 | 0 | 0 | 0 |
| 540 | 550 | 6 | 4 | 3 | 2 | 1 | 1 | 0 | 0 | 0 | 0 | 0 |
| 550 | 560 | 6 | 4 | 3 | 2 | 2 | 1 | 0 | 0 | 0 | 0 | 0 |
| 560 | 570 | 7 | 5 | 4 | 3 | 2 | 1 | 0 | 0 | 0 | 0 | 0 |
| 570 | 580 | 7 | 5 | 4 | 3 | 2 | 1 | 1 | 0 | 0 | 0 | 0 |
| 580 | 590 | 8 | 6 | 4 | 3 | 2 | 1 | 1 | 0 | 0 | 0 | 0 |
| 590 | 600 | 8 | 6 | 5 | 4 | 2 | 2 | 1 | 0 | 0 | 0 | 0 |
| 600 | 610 | 9 | 7 | 5 | 4 | 3 | 2 | 1 | 0 | 0 | 0 | 0 |
| 610 | 620 | 9 | 7 | 6 | 4 | 3 | 2 | 1 | 1 | 0 | 0 | 0 |
| 620 | 630 | 10 | 8 | 6 | 4 | 3 | 2 | 2 | 1 | 0 | 0 | 0 |
| 630 | 640 | 10 | 8 | 7 | 5 | 4 | 3 | 2 | 1 | 0 | 0 | 0 |
| 640 | 650 | 11 | 9 | 7 | 5 | 4 | 3 | 2 | 1 | 1 | 0 | 0 |
| 650 | 660 | 11 | 9 | 8 | 6 | 4 | 3 | 2 | 1 | 1 | 0 | 0 |
| 660 | 670 | 12 | 10 | 8 | 6 | 5 | 3 | 2 | 2 | 1 | 0 | 0 |
| 670 | 680 | 12 | 10 | 9 | 7 | 5 | 4 | 3 | 2 | 1 | 0 | 0 |
| 680 | 690 | 13 | 11 | 9 | 7 | 6 | 4 | 3 | 2 | 1 | 1 | 0 |
| 690 | 700 | 13 | 11 | 10 | 8 | 6 | 4 | 3 | 2 | 2 | 1 | 0 |
| 700 | 710 | 14 | 12 | 10 | 8 | 7 | 5 | 4 | 3 | 2 | 1 | 0 |
| 710 | 720 | 14 | 12 | 11 | 9 | 7 | 5 | 4 | 3 | 2 | 1 | 1 |
| 720 | 730 | 15 | 13 | 11 | 9 | 8 | 6 | 4 | 3 | 2 | 1 | 1 |
| 730 | 740 | 15 | 13 | 12 | 10 | 8 | 6 | 5 | 3 | 2 | 2 | 1 |
| 740 | 750 | 16 | 14 | 12 | 10 | 9 | 7 | 5 | 4 | 3 | 2 | 1 |
| 750 | 760 | 16 | 14 | 13 | 11 | 9 | 7 | 5 | 4 | 3 | 2 | 1 |
| 760 | 770 | 17 | 15 | 13 | 11 | 10 | 8 | 6 | 4 | 3 | 2 | 2 |
| 770 | 780 | 17 | 15 | 14 | 12 | 10 | 8 | 6 | 5 | 4 | 2 | 2 |
| 780 | 790 | 18 | 16 | 14 | 12 | 11 | 9 | 7 | 5 | 4 | 3 | 2 |
| 790 | 800 | 18 | 16 | 15 | 13 | 11 | 9 | 7 | 6 | 4 | 3 | 2 |
| 800 | 810 | 19 | 17 | 15 | 13 | 12 | 10 | 8 | 6 | 4 | 3 | 2 |
| 810 | 820 | 19 | 17 | 16 | 14 | 12 | 10 | 8 | 7 | 5 | 4 | 3 |
| 820 | 830 | 20 | 18 | 16 | 14 | 13 | 11 | 9 | 7 | 5 | 4 | 3 |
| 830 | 840 | 20 | 18 | 17 | 15 | 13 | 11 | 9 | 8 | 6 | 4 | 3 |
| 840 | 850 | 21 | 19 | 17 | 15 | 14 | 12 | 10 | 8 | 6 | 5 | 4 |
| 850 | 860 | 21 | 19 | 18 | 16 | 14 | 12 | 10 | 9 | 7 | 5 | 4 |
| 860 | 870 | 22 | 20 | 18 | 16 | 15 | 13 | 11 | 9 | 7 | 6 | 4 |
| 870 | 880 | 22 | 20 | 19 | 17 | 15 | 13 | 11 | 10 | 8 | 6 | 4 |
| 880 | 890 | 23 | 21 | 19 | 17 | 16 | 14 | 12 | 10 | 8 | 7 | 5 |
| 890 | 900 | 23 | 21 | 20 | 18 | 16 | 14 | 12 | 11 | 9 | 7 | 5 |
| 900 | 910 | 24 | 22 | 20 | 18 | 17 | 15 | 13 | 11 | 9 | 8 | 6 |
| 910 | 920 | 24 | 22 | 21 | 19 | 17 | 15 | 13 | 12 | 10 | 8 | 6 |
| 920 | 930 | 25 | 23 | 21 | 19 | 18 | 16 | 14 | 12 | 10 | 9 | 7 |
| 930 | 940 | 25 | 23 | 22 | 20 | 18 | 16 | 14 | 13 | 11 | 9 | 7 |
| 940 | 950 | 26 | 24 | 22 | 20 | 19 | 17 | 15 | 13 | 11 | 10 | 8 |
# At Least
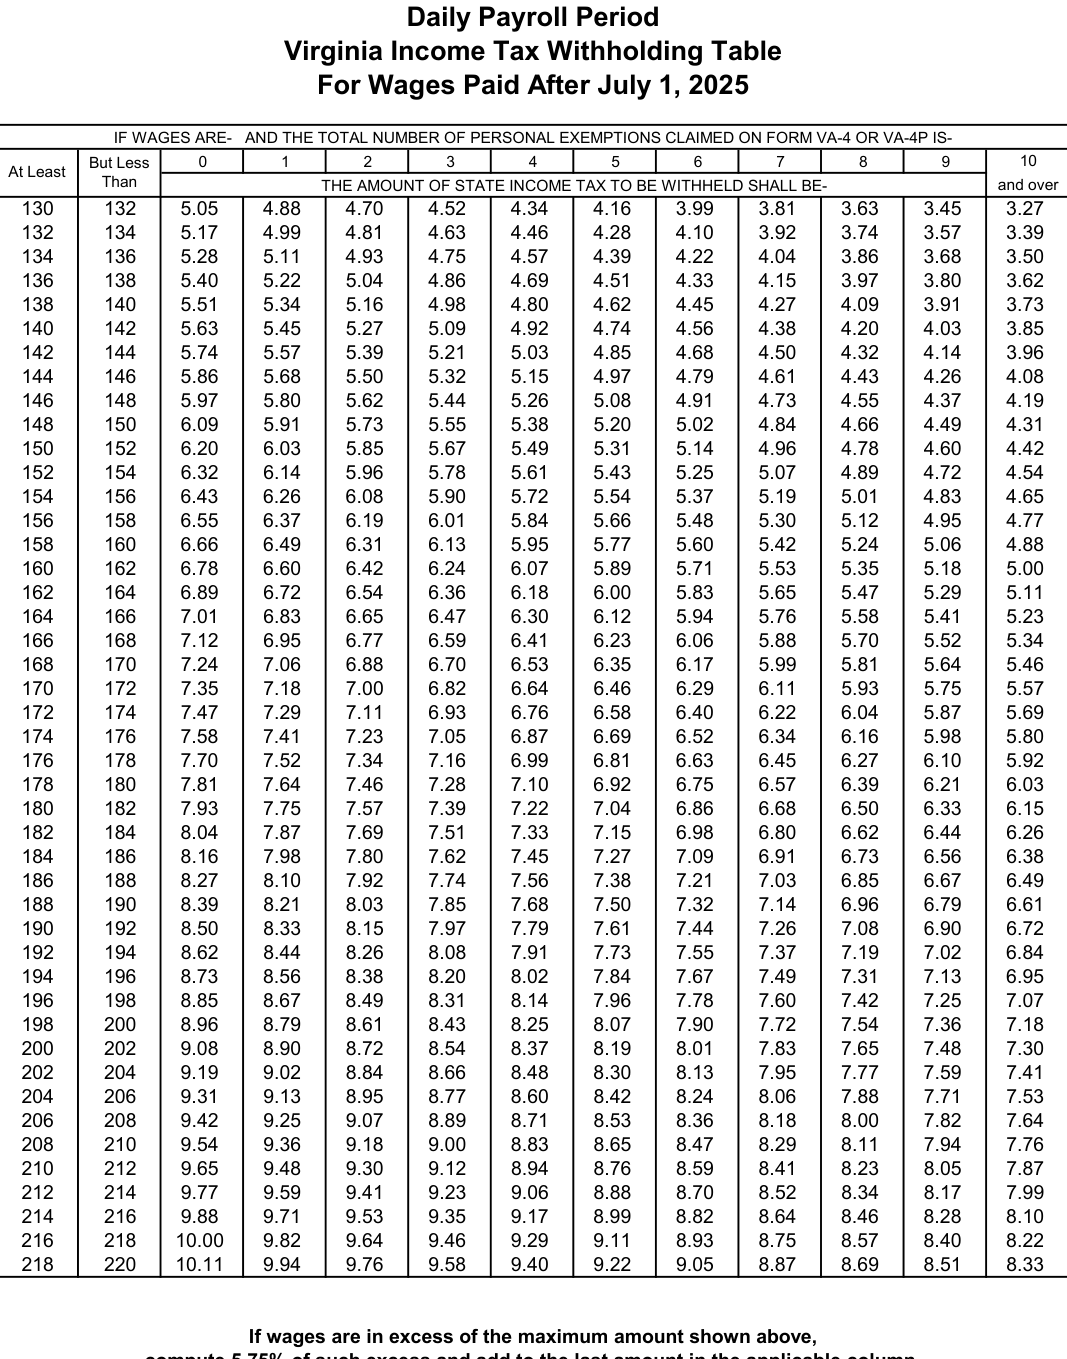
Text version of this table
| Virginia Inc | ome T | ax Wit | hholdi | ng Ta | ble | ||||||
| For Wag | es Pai | d After | July 1 | , 2025 | |||||||
| IF WAGE | S ARE- AND | THE TOTAL NUMBE | R OF PERS | ONAL EXE | MPTIONS C | LAIMED O | N FORM VA- | 4 OR VA-4P | IS- | ||
| B Least | ut Less | 0 | 1 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
| Than | THE AMOUNT | OF STATE | INCOME TA | X TO BE W | ITHHELD | SHALL BE- | a | nd ov | |||
| 130 | 132 | 5.05 4. | 88 4.70 | 4.52 | 4.34 | 4.16 | 3.99 | 3.81 | 3.63 | 3.45 | 3.27 |
| 132 | 134 | 5.17 4. | 99 4.81 | 4.63 | 4.46 | 4.28 | 4.10 | 3.92 | 3.74 | 3.57 | 3.39 |
| 134 | 136 | 5.28 5. | 11 4.93 | 4.75 | 4.57 | 4.39 | 4.22 | 4.04 | 3.86 | 3.68 | 3.50 |
| 136 | 138 | 5.40 5. | 22 5.04 | 4.86 | 4.69 | 4.51 | 4.33 | 4.15 | 3.97 | 3.80 | 3.62 |
| 138 | 140 | 5.51 5. | 34 5.16 | 4.98 | 4.80 | 4.62 | 4.45 | 4.27 | 4.09 | 3.91 | 3.73 |
| 140 | 142 | 5.63 5. | 45 5.27 | 5.09 | 4.92 | 4.74 | 4.56 | 4.38 | 4.20 | 4.03 | 3.85 |
| 142 | 144 | 5.74 5. | 57 5.39 | 5.21 | 5.03 | 4.85 | 4.68 | 4.50 | 4.32 | 4.14 | 3.96 |
| 144 | 146 | 5.86 5. | 68 5.50 | 5.32 | 5.15 | 4.97 | 4.79 | 4.61 | 4.43 | 4.26 | 4.08 |
| 146 | 148 | 5.97 5. | 80 5.62 | 5.44 | 5.26 | 5.08 | 4.91 | 4.73 | 4.55 | 4.37 | 4.19 |
| 148 | 150 | 6.09 5. | 91 5.73 | 5.55 | 5.38 | 5.20 | 5.02 | 4.84 | 4.66 | 4.49 | 4.31 |
| 150 | 152 | 6.20 6. | 03 5.85 | 5.67 | 5.49 | 5.31 | 5.14 | 4.96 | 4.78 | 4.60 | 4.42 |
| 152 | 154 | 6.32 6. | 14 5.96 | 5.78 | 5.61 | 5.43 | 5.25 | 5.07 | 4.89 | 4.72 | 4.54 |
| 154 | 156 | 6.43 6. | 26 6.08 | 5.90 | 5.72 | 5.54 | 5.37 | 5.19 | 5.01 | 4.83 | 4.65 |
| 156 | 158 | 6.55 6. | 37 6.19 | 6.01 | 5.84 | 5.66 | 5.48 | 5.30 | 5.12 | 4.95 | 4.77 |
| 158 | 160 | 6.66 6. | 49 6.31 | 6.13 | 5.95 | 5.77 | 5.60 | 5.42 | 5.24 | 5.06 | 4.88 |
| 160 | 162 | 6.78 6. | 60 6.42 | 6.24 | 6.07 | 5.89 | 5.71 | 5.53 | 5.35 | 5.18 | 5.00 |
| 162 | 164 | 6.89 6. | 72 6.54 | 6.36 | 6.18 | 6.00 | 5.83 | 5.65 | 5.47 | 5.29 | 5.11 |
| 164 | 166 | 7.01 6. | 83 6.65 | 6.47 | 6.30 | 6.12 | 5.94 | 5.76 | 5.58 | 5.41 | 5.23 |
| 166 | 168 | 7.12 6. | 95 6.77 | 6.59 | 6.41 | 6.23 | 6.06 | 5.88 | 5.70 | 5.52 | 5.34 |
| 168 | 170 | 7.24 7. | 06 6.88 | 6.70 | 6.53 | 6.35 | 6.17 | 5.99 | 5.81 | 5.64 | 5.46 |
| 170 | 172 | 7.35 7. | 18 7.00 | 6.82 | 6.64 | 6.46 | 6.29 | 6.11 | 5.93 | 5.75 | 5.57 |
| 172 | 174 | 7.47 7. | 29 7.11 | 6.93 | 6.76 | 6.58 | 6.40 | 6.22 | 6.04 | 5.87 | 5.69 |
| 174 | 176 | 7.58 7. | 41 7.23 | 7.05 | 6.87 | 6.69 | 6.52 | 6.34 | 6.16 | 5.98 | 5.80 |
| 176 | 178 | 7.70 7. | 52 7.34 | 7.16 | 6.99 | 6.81 | 6.63 | 6.45 | 6.27 | 6.10 | 5.92 |
| 178 | 180 | 7.81 7. | 64 7.46 | 7.28 | 7.10 | 6.92 | 6.75 | 6.57 | 6.39 | 6.21 | 6.03 |
| 180 | 182 | 7.93 7. | 75 7.57 | 7.39 | 7.22 | 7.04 | 6.86 | 6.68 | 6.50 | 6.33 | 6.15 |
| 182 | 184 | 8.04 7. | 87 7.69 | 7.51 | 7.33 | 7.15 | 6.98 | 6.80 | 6.62 | 6.44 | 6.26 |
| 184 | 186 | 8.16 7. | 98 7.80 | 7.62 | 7.45 | 7.27 | 7.09 | 6.91 | 6.73 | 6.56 | 6.38 |
| 186 | 188 | 8.27 8. | 10 7.92 | 7.74 | 7.56 | 7.38 | 7.21 | 7.03 | 6.85 | 6.67 | 6.49 |
| 188 | 190 | 8.39 8. | 21 8.03 | 7.85 | 7.68 | 7.50 | 7.32 | 7.14 | 6.96 | 6.79 | 6.61 |
| 190 | 192 | 8.50 8. | 33 8.15 | 7.97 | 7.79 | 7.61 | 7.44 | 7.26 | 7.08 | 6.90 | 6.72 |
| 192 | 194 | 8.62 8. | 44 8.26 | 8.08 | 7.91 | 7.73 | 7.55 | 7.37 | 7.19 | 7.02 | 6.84 |
| 194 | 196 | 8.73 8. | 56 8.38 | 8.20 | 8.02 | 7.84 | 7.67 | 7.49 | 7.31 | 7.13 | 6.95 |
| 196 | 198 | 8.85 8. | 67 8.49 | 8.31 | 8.14 | 7.96 | 7.78 | 7.60 | 7.42 | 7.25 | 7.07 |
| 198 | 200 | 8.96 8. | 79 8.61 | 8.43 | 8.25 | 8.07 | 7.90 | 7.72 | 7.54 | 7.36 | 7.18 |
| 200 | 202 | 9.08 8. | 90 8.72 | 8.54 | 8.37 | 8.19 | 8.01 | 7.83 | 7.65 | 7.48 | 7.30 |
| 202 | 204 | 9.19 9. | 02 8.84 | 8.66 | 8.48 | 8.30 | 8.13 | 7.95 | 7.77 | 7.59 | 7.41 |
| 204 | 206 | 9.31 9. | 13 8.95 | 8.77 | 8.60 | 8.42 | 8.24 | 8.06 | 7.88 | 7.71 | 7.53 |
| 206 | 208 | 9.42 9. | 25 9.07 | 8.89 | 8.71 | 8.53 | 8.36 | 8.18 | 8.00 | 7.82 | 7.64 |
| 208 | 210 | 9.54 9. | 36 9.18 | 9.00 | 8.83 | 8.65 | 8.47 | 8.29 | 8.11 | 7.94 | 7.76 |
| 210 | 212 | 9.65 9. | 48 9.30 | 9.12 | 8.94 | 8.76 | 8.59 | 8.41 | 8.23 | 8.05 | 7.87 |
| 212 | 214 | 9.77 9. | 59 9.41 | 9.23 | 9.06 | 8.88 | 8.70 | 8.52 | 8.34 | 8.17 | 7.99 |
| 214 | 216 | 9.88 9. | 71 9.53 | 9.35 | 9.17 | 8.99 | 8.82 | 8.64 | 8.46 | 8.28 | 8.10 |
| 216 | 218 | 10.00 9. | 82 9.64 | 9.46 | 9.29 | 9.11 | 8.93 | 8.75 | 8.57 | 8.40 | 8.22 |
| 218 | 220 | 10.11 9. | 94 9.76 | 9.58 | 9.40 | 9.22 | 9.05 | 8.87 | 8.69 | 8.51 | 8.33 |
| If w | ages are in exce | ss of the | maximu | m amoun | t shown | above, |
# For Wages Paid After July 1, 2025
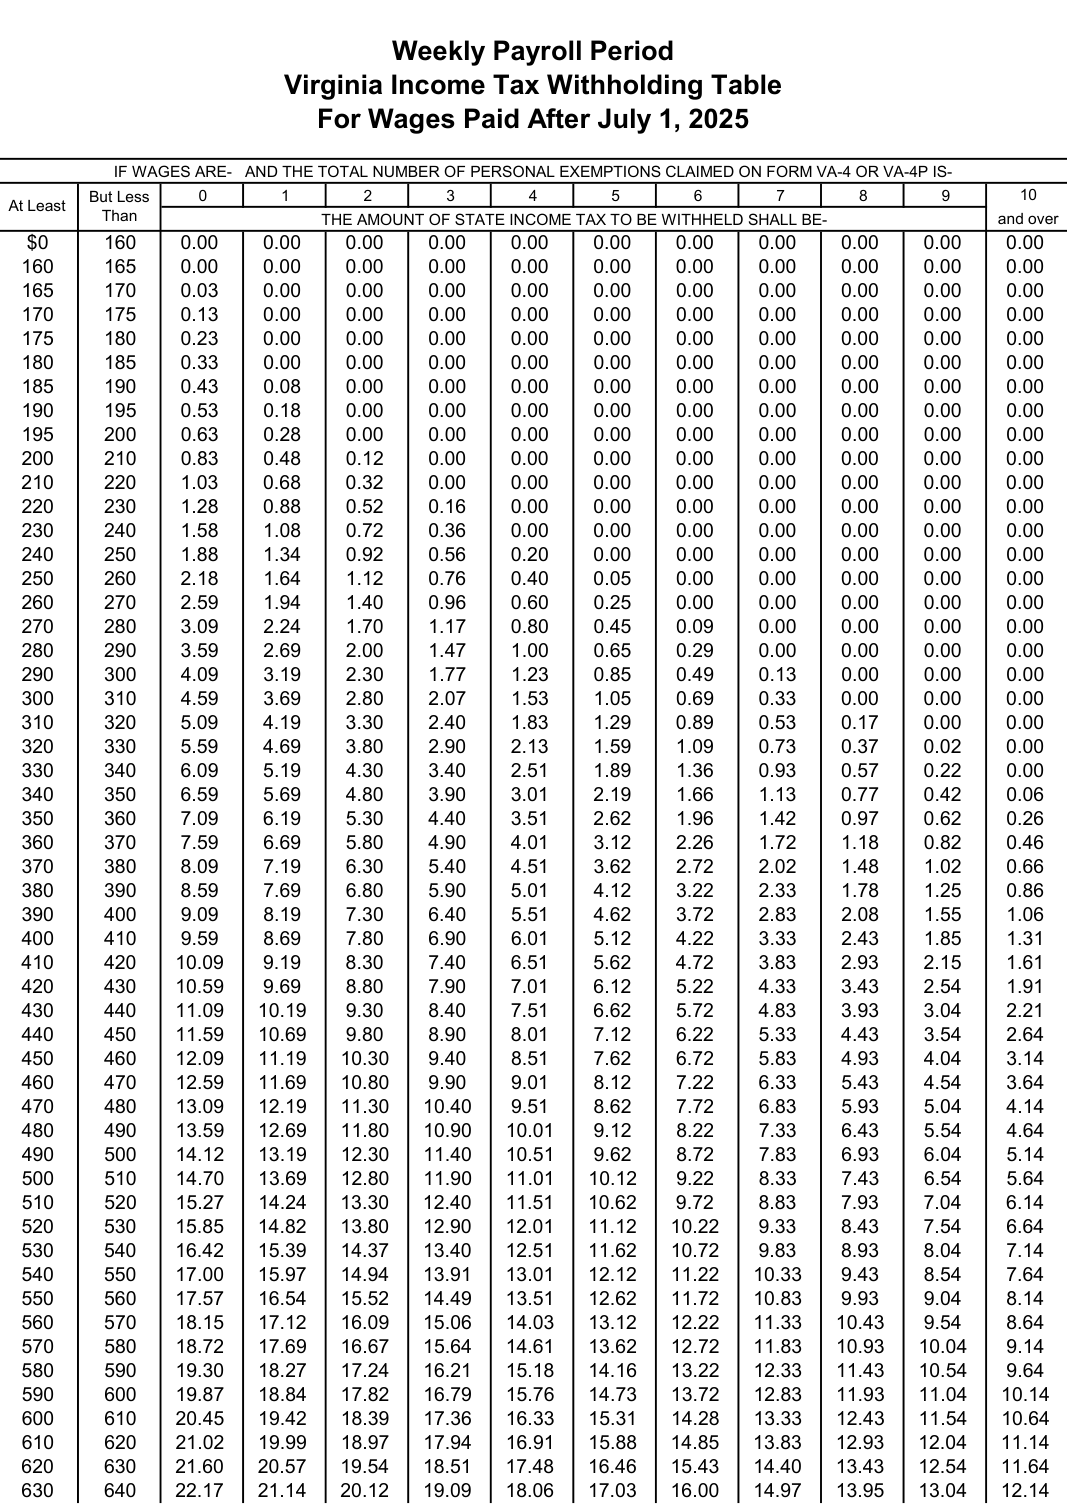
Text version of this table
| W | eekly P | ayroll | Period | |||||||||||
| Virg | inia | Inc | ome T | ax Wit | hholdi | ng Tab | le | |||||||
| F | or W | ag | es Pai | d After | July 1 | , 2025 | ||||||||
| IF WAGE | S ARE- A | ND | THE TO | TAL NU | MB | ER OF PER | SONAL EXE | MPTIONS | CLAIMED O | N FORM VA | -4 OR VA-4 | P IS- | ||
| B Least | ut Less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 | ||
| Than | TH | E AMO | UNT | OF STATE | INCOME T | AX TO BE W | ITHHELD S | HALL BE- | and ove | |||||
| $0 | 160 | 0.00 | 0. | 00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 160 | 165 | 0.00 | 0. | 00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 165 | 170 | 0.03 | 0. | 00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 170 | 175 | 0.13 | 0. | 00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 175 | 180 | 0.23 | 0. | 00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 180 | 185 | 0.33 | 0. | 00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 185 | 190 | 0.43 | 0. | 08 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 190 | 195 | 0.53 | 0. | 18 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 195 | 200 | 0.63 | 0. | 28 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 200 | 210 | 0.83 | 0. | 48 | 0.12 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 210 | 220 | 1.03 | 0. | 68 | 0.32 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 220 | 230 | 1.28 | 0. | 88 | 0.52 | 0.16 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 230 | 240 | 1.58 | 1. | 08 | 0.72 | 0.36 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 240 | 250 | 1.88 | 1. | 34 | 0.92 | 0.56 | 0.20 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 250 | 260 | 2.18 | 1. | 64 | 1.12 | 0.76 | 0.40 | 0.05 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 260 | 270 | 2.59 | 1. | 94 | 1.40 | 0.96 | 0.60 | 0.25 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 270 | 280 | 3.09 | 2. | 24 | 1.70 | 1.17 | 0.80 | 0.45 | 0.09 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 280 | 290 | 3.59 | 2. | 69 | 2.00 | 1.47 | 1.00 | 0.65 | 0.29 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 290 | 300 | 4.09 | 3. | 19 | 2.30 | 1.77 | 1.23 | 0.85 | 0.49 | 0.13 | 0.00 | 0.00 | 0.00 | |
| 300 | 310 | 4.59 | 3. | 69 | 2.80 | 2.07 | 1.53 | 1.05 | 0.69 | 0.33 | 0.00 | 0.00 | 0.00 | |
| 310 | 320 | 5.09 | 4. | 19 | 3.30 | 2.40 | 1.83 | 1.29 | 0.89 | 0.53 | 0.17 | 0.00 | 0.00 | |
| 320 | 330 | 5.59 | 4. | 69 | 3.80 | 2.90 | 2.13 | 1.59 | 1.09 | 0.73 | 0.37 | 0.02 | 0.00 | |
| 330 | 340 | 6.09 | 5. | 19 | 4.30 | 3.40 | 2.51 | 1.89 | 1.36 | 0.93 | 0.57 | 0.22 | 0.00 | |
| 340 | 350 | 6.59 | 5. | 69 | 4.80 | 3.90 | 3.01 | 2.19 | 1.66 | 1.13 | 0.77 | 0.42 | 0.06 | |
| 350 | 360 | 7.09 | 6. | 19 | 5.30 | 4.40 | 3.51 | 2.62 | 1.96 | 1.42 | 0.97 | 0.62 | 0.26 | |
| 360 | 370 | 7.59 | 6. | 69 | 5.80 | 4.90 | 4.01 | 3.12 | 2.26 | 1.72 | 1.18 | 0.82 | 0.46 | |
| 370 | 380 | 8.09 | 7. | 19 | 6.30 | 5.40 | 4.51 | 3.62 | 2.72 | 2.02 | 1.48 | 1.02 | 0.66 | |
| 380 | 390 | 8.59 | 7. | 69 | 6.80 | 5.90 | 5.01 | 4.12 | 3.22 | 2.33 | 1.78 | 1.25 | 0.86 | |
| 390 | 400 | 9.09 | 8. | 19 | 7.30 | 6.40 | 5.51 | 4.62 | 3.72 | 2.83 | 2.08 | 1.55 | 1.06 | |
| 400 | 410 | 9.59 | 8. | 69 | 7.80 | 6.90 | 6.01 | 5.12 | 4.22 | 3.33 | 2.43 | 1.85 | 1.31 | |
| 410 | 420 | 10.09 | 9. | 19 | 8.30 | 7.40 | 6.51 | 5.62 | 4.72 | 3.83 | 2.93 | 2.15 | 1.61 | |
| 420 | 430 | 10.59 | 9. | 69 | 8.80 | 7.90 | 7.01 | 6.12 | 5.22 | 4.33 | 3.43 | 2.54 | 1.91 | |
| 430 | 440 | 11.09 | 10 | .19 | 9.30 | 8.40 | 7.51 | 6.62 | 5.72 | 4.83 | 3.93 | 3.04 | 2.21 | |
| 440 | 450 | 11.59 | 10 | .69 | 9.80 | 8.90 | 8.01 | 7.12 | 6.22 | 5.33 | 4.43 | 3.54 | 2.64 | |
| 450 | 460 | 12.09 | 11 | .19 | 10.30 | 9.40 | 8.51 | 7.62 | 6.72 | 5.83 | 4.93 | 4.04 | 3.14 | |
| 460 | 470 | 12.59 | 11 | .69 | 10.80 | 9.90 | 9.01 | 8.12 | 7.22 | 6.33 | 5.43 | 4.54 | 3.64 | |
| 470 | 480 | 13.09 | 12 | .19 | 11.30 | 10.40 | 9.51 | 8.62 | 7.72 | 6.83 | 5.93 | 5.04 | 4.14 | |
| 480 | 490 | 13.59 | 12 | .69 | 11.80 | 10.90 | 10.01 | 9.12 | 8.22 | 7.33 | 6.43 | 5.54 | 4.64 | |
| 490 | 500 | 14.12 | 13 | .19 | 12.30 | 11.40 | 10.51 | 9.62 | 8.72 | 7.83 | 6.93 | 6.04 | 5.14 | |
| 500 | 510 | 14.70 | 13 | .69 | 12.80 | 11.90 | 11.01 | 10.12 | 9.22 | 8.33 | 7.43 | 6.54 | 5.64 | |
| 510 | 520 | 15.27 | 14 | .24 | 13.30 | 12.40 | 11.51 | 10.62 | 9.72 | 8.83 | 7.93 | 7.04 | 6.14 | |
| 520 | 530 | 15.85 | 14 | .82 | 13.80 | 12.90 | 12.01 | 11.12 | 10.22 | 9.33 | 8.43 | 7.54 | 6.64 | |
| 530 | 540 | 16.42 | 15 | .39 | 14.37 | 13.40 | 12.51 | 11.62 | 10.72 | 9.83 | 8.93 | 8.04 | 7.14 | |
| 540 | 550 | 17.00 | 15 | .97 | 14.94 | 13.91 | 13.01 | 12.12 | 11.22 | 10.33 | 9.43 | 8.54 | 7.64 | |
| 550 | 560 | 17.57 | 16 | .54 | 15.52 | 14.49 | 13.51 | 12.62 | 11.72 | 10.83 | 9.93 | 9.04 | 8.14 | |
| 560 | 570 | 18.15 | 17 | .12 | 16.09 | 15.06 | 14.03 | 13.12 | 12.22 | 11.33 | 10.43 | 9.54 | 8.64 | |
| 570 | 580 | 18.72 | 17 | .69 | 16.67 | 15.64 | 14.61 | 13.62 | 12.72 | 11.83 | 10.93 | 10.04 | 9.14 | |
| 580 | 590 | 19.30 | 18 | .27 | 17.24 | 16.21 | 15.18 | 14.16 | 13.22 | 12.33 | 11.43 | 10.54 | 9.64 | |
| 590 | 600 | 19.87 | 18 | .84 | 17.82 | 16.79 | 15.76 | 14.73 | 13.72 | 12.83 | 11.93 | 11.04 | 10.14 | |
| 600 | 610 | 20.45 | 19 | .42 | 18.39 | 17.36 | 16.33 | 15.31 | 14.28 | 13.33 | 12.43 | 11.54 | 10.64 | |
| 610 | 620 | 21.02 | 19 | .99 | 18.97 | 17.94 | 16.91 | 15.88 | 14.85 | 13.83 | 12.93 | 12.04 | 11.14 | |
| 620 | 630 | 21.60 | 20 | .57 | 19.54 | 18.51 | 17.48 | 16.46 | 15.43 | 14.40 | 13.43 | 12.54 | 11.64 | |
| 630 | 640 | 22.17 | 21 | .14 | 20.12 | 19.09 | 18.06 | 17.03 | 16.00 | 14.97 | 13.95 | 13.04 | 12.14 |
# For Wages Paid After July 1, 2025
# At Least
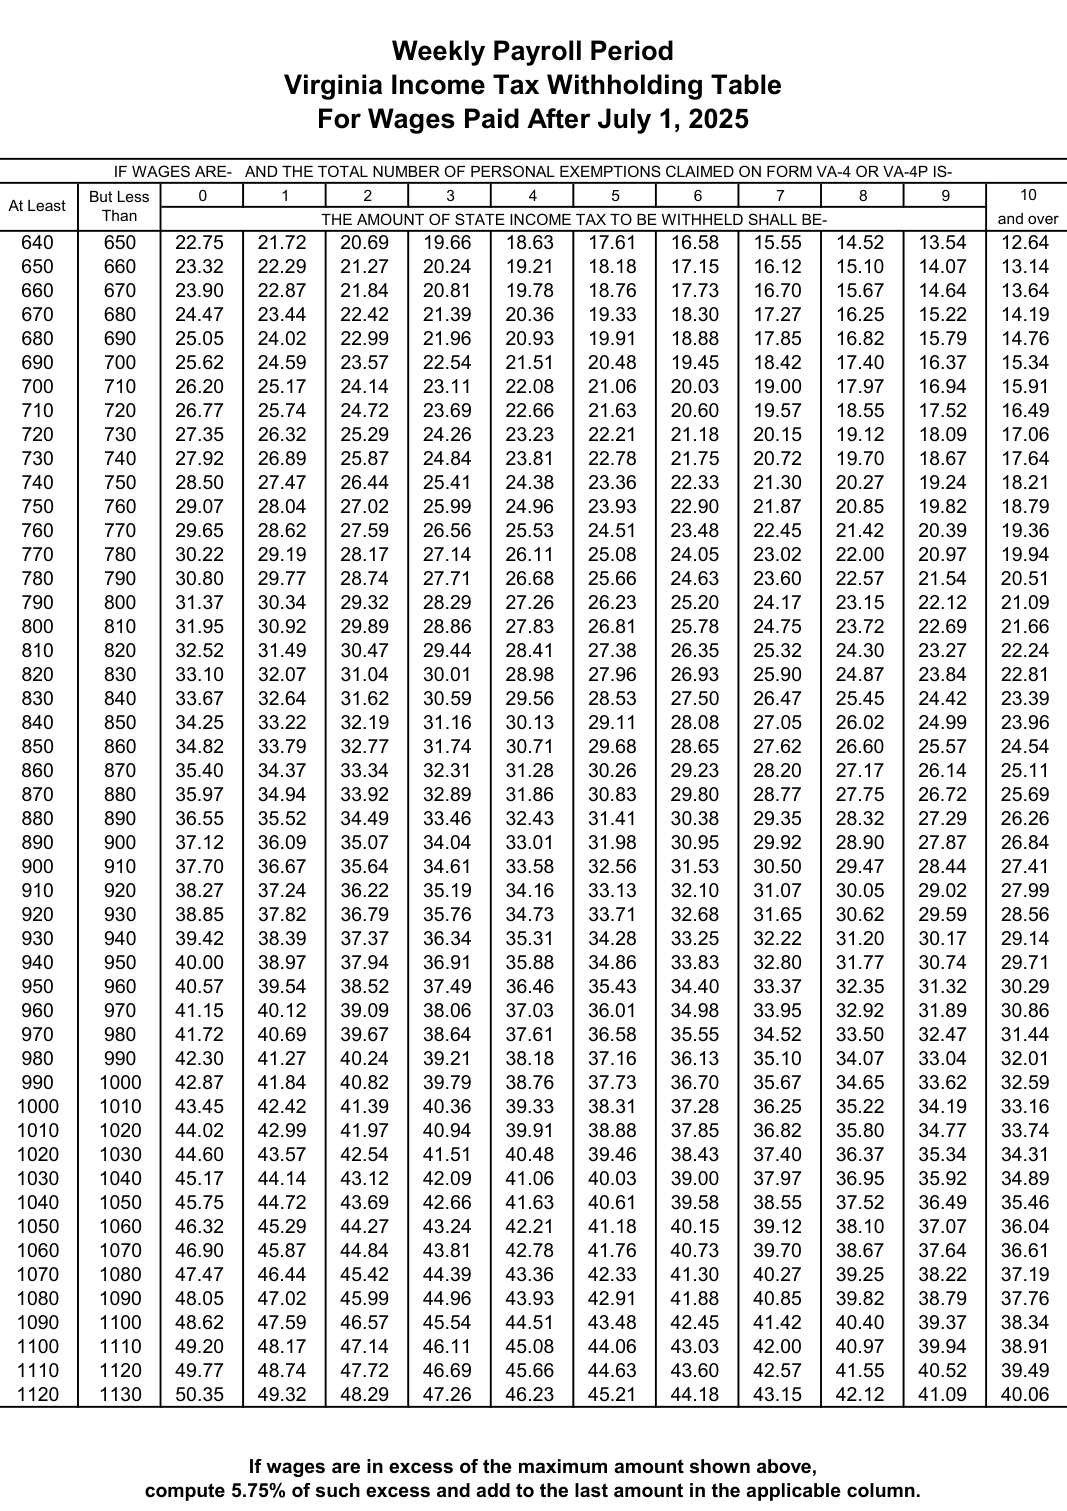
Text version of this table
| W | eekly P | ayroll | Period | |||||||||||
| Virg | inia | Inc | ome T | ax Wit | hholdin | g Tab | le | |||||||
| F | or W | ag | es Pai | d After | July 1, | 2025 | ||||||||
| IF W | AGES ARE- A | ND | THE TO | TAL NU | MB | ER OF PER | SONAL EXE | MPTIONS CL | AIMED O | N FORM VA | -4 OR VA-4 | P IS- | ||
| B t Least | ut Les | s 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 | ||
| Than | TH | E AMO | UNT | OF STATE | INCOME T | AX TO BE WIT | HHELD S | HALL BE- | and ove | |||||
| 640 | 650 | 22.75 | 21 | .72 | 20.69 | 19.66 | 18.63 | 17.61 16 | .58 | 15.55 | 14.52 | 13.54 | 12.64 | |
| 650 | 660 | 23.32 | 22 | .29 | 21.27 | 20.24 | 19.21 | 18.18 17 | .15 | 16.12 | 15.10 | 14.07 | 13.14 | |
| 660 | 670 | 23.90 | 22 | .87 | 21.84 | 20.81 | 19.78 | 18.76 17 | .73 | 16.70 | 15.67 | 14.64 | 13.64 | |
| 670 | 680 | 24.47 | 23 | .44 | 22.42 | 21.39 | 20.36 | 19.33 18 | .30 | 17.27 | 16.25 | 15.22 | 14.19 | |
| 680 | 690 | 25.05 | 24 | .02 | 22.99 | 21.96 | 20.93 | 19.91 18 | .88 | 17.85 | 16.82 | 15.79 | 14.76 | |
| 690 | 700 | 25.62 | 24 | .59 | 23.57 | 22.54 | 21.51 | 20.48 19 | .45 | 18.42 | 17.40 | 16.37 | 15.34 | |
| 700 | 710 | 26.20 | 25 | .17 | 24.14 | 23.11 | 22.08 | 21.06 20 | .03 | 19.00 | 17.97 | 16.94 | 15.91 | |
| 710 | 720 | 26.77 | 25 | .74 | 24.72 | 23.69 | 22.66 | 21.63 20 | .60 | 19.57 | 18.55 | 17.52 | 16.49 | |
| 720 | 730 | 27.35 | 26 | .32 | 25.29 | 24.26 | 23.23 | 22.21 21 | .18 | 20.15 | 19.12 | 18.09 | 17.06 | |
| 730 | 740 | 27.92 | 26 | .89 | 25.87 | 24.84 | 23.81 | 22.78 21 | .75 | 20.72 | 19.70 | 18.67 | 17.64 | |
| 740 | 750 | 28.50 | 27 | .47 | 26.44 | 25.41 | 24.38 | 23.36 22 | .33 | 21.30 | 20.27 | 19.24 | 18.21 | |
| 750 | 760 | 29.07 | 28 | .04 | 27.02 | 25.99 | 24.96 | 23.93 22 | .90 | 21.87 | 20.85 | 19.82 | 18.79 | |
| 760 | 770 | 29.65 | 28 | .62 | 27.59 | 26.56 | 25.53 | 24.51 23 | .48 | 22.45 | 21.42 | 20.39 | 19.36 | |
| 770 | 780 | 30.22 | 29 | .19 | 28.17 | 27.14 | 26.11 | 25.08 24 | .05 | 23.02 | 22.00 | 20.97 | 19.94 | |
| 780 | 790 | 30.80 | 29 | .77 | 28.74 | 27.71 | 26.68 | 25.66 24 | .63 | 23.60 | 22.57 | 21.54 | 20.51 | |
| 790 | 800 | 31.37 | 30 | .34 | 29.32 | 28.29 | 27.26 | 26.23 25 | .20 | 24.17 | 23.15 | 22.12 | 21.09 | |
| 800 | 810 | 31.95 | 30 | .92 | 29.89 | 28.86 | 27.83 | 26.81 25 | .78 | 24.75 | 23.72 | 22.69 | 21.66 | |
| 810 | 820 | 32.52 | 31 | .49 | 30.47 | 29.44 | 28.41 | 27.38 26 | .35 | 25.32 | 24.30 | 23.27 | 22.24 | |
| 820 | 830 | 33.10 | 32 | .07 | 31.04 | 30.01 | 28.98 | 27.96 26 | .93 | 25.90 | 24.87 | 23.84 | 22.81 | |
| 830 | 840 | 33.67 | 32 | .64 | 31.62 | 30.59 | 29.56 | 28.53 27 | .50 | 26.47 | 25.45 | 24.42 | 23.39 | |
| 840 | 850 | 34.25 | 33 | .22 | 32.19 | 31.16 | 30.13 | 29.11 28 | .08 | 27.05 | 26.02 | 24.99 | 23.96 | |
| 850 | 860 | 34.82 | 33 | .79 | 32.77 | 31.74 | 30.71 | 29.68 28 | .65 | 27.62 | 26.60 | 25.57 | 24.54 | |
| 860 | 870 | 35.40 | 34 | .37 | 33.34 | 32.31 | 31.28 | 30.26 29 | .23 | 28.20 | 27.17 | 26.14 | 25.11 | |
| 870 | 880 | 35.97 | 34 | .94 | 33.92 | 32.89 | 31.86 | 30.83 29 | .80 | 28.77 | 27.75 | 26.72 | 25.69 | |
| 880 | 890 | 36.55 | 35 | .52 | 34.49 | 33.46 | 32.43 | 31.41 30 | .38 | 29.35 | 28.32 | 27.29 | 26.26 | |
| 890 | 900 | 37.12 | 36 | .09 | 35.07 | 34.04 | 33.01 | 31.98 30 | .95 | 29.92 | 28.90 | 27.87 | 26.84 | |
| 900 | 910 | 37.70 | 36 | .67 | 35.64 | 34.61 | 33.58 | 32.56 31 | .53 | 30.50 | 29.47 | 28.44 | 27.41 | |
| 910 | 920 | 38.27 | 37 | .24 | 36.22 | 35.19 | 34.16 | 33.13 32 | .10 | 31.07 | 30.05 | 29.02 | 27.99 | |
| 920 | 930 | 38.85 | 37 | .82 | 36.79 | 35.76 | 34.73 | 33.71 32 | .68 | 31.65 | 30.62 | 29.59 | 28.56 | |
| 930 | 940 | 39.42 | 38 | .39 | 37.37 | 36.34 | 35.31 | 34.28 33 | .25 | 32.22 | 31.20 | 30.17 | 29.14 | |
| 940 | 950 | 40.00 | 38 | .97 | 37.94 | 36.91 | 35.88 | 34.86 33 | .83 | 32.80 | 31.77 | 30.74 | 29.71 | |
| 950 | 960 | 40.57 | 39 | .54 | 38.52 | 37.49 | 36.46 | 35.43 34 | .40 | 33.37 | 32.35 | 31.32 | 30.29 | |
| 960 | 970 | 41.15 | 40 | .12 | 39.09 | 38.06 | 37.03 | 36.01 34 | .98 | 33.95 | 32.92 | 31.89 | 30.86 | |
| 970 | 980 | 41.72 | 40 | .69 | 39.67 | 38.64 | 37.61 | 36.58 35 | .55 | 34.52 | 33.50 | 32.47 | 31.44 | |
| 980 | 990 | 42.30 | 41 | .27 | 40.24 | 39.21 | 38.18 | 37.16 36 | .13 | 35.10 | 34.07 | 33.04 | 32.01 | |
| 990 | 1000 | 42.87 | 41 | .84 | 40.82 | 39.79 | 38.76 | 37.73 36 | .70 | 35.67 | 34.65 | 33.62 | 32.59 | |
| 1000 | 1010 | 43.45 | 42 | .42 | 41.39 | 40.36 | 39.33 | 38.31 37 | .28 | 36.25 | 35.22 | 34.19 | 33.16 | |
| 1010 | 1020 | 44.02 | 42 | .99 | 41.97 | 40.94 | 39.91 | 38.88 37 | .85 | 36.82 | 35.80 | 34.77 | 33.74 | |
| 1020 | 1030 | 44.60 | 43 | .57 | 42.54 | 41.51 | 40.48 | 39.46 38 | .43 | 37.40 | 36.37 | 35.34 | 34.31 | |
| 1030 | 1040 | 45.17 | 44 | .14 | 43.12 | 42.09 | 41.06 | 40.03 39 | .00 | 37.97 | 36.95 | 35.92 | 34.89 | |
| 1040 | 1050 | 45.75 | 44 | .72 | 43.69 | 42.66 | 41.63 | 40.61 39 | .58 | 38.55 | 37.52 | 36.49 | 35.46 | |
| 1050 | 1060 | 46.32 | 45 | .29 | 44.27 | 43.24 | 42.21 | 41.18 40 | .15 | 39.12 | 38.10 | 37.07 | 36.04 | |
| 1060 | 1070 | 46.90 | 45 | .87 | 44.84 | 43.81 | 42.78 | 41.76 40 | .73 | 39.70 | 38.67 | 37.64 | 36.61 | |
| 1070 | 1080 | 47.47 | 46 | .44 | 45.42 | 44.39 | 43.36 | 42.33 41 | .30 | 40.27 | 39.25 | 38.22 | 37.19 | |
| 1080 | 1090 | 48.05 | 47 | .02 | 45.99 | 44.96 | 43.93 | 42.91 41 | .88 | 40.85 | 39.82 | 38.79 | 37.76 | |
| 1090 | 1100 | 48.62 | 47 | .59 | 46.57 | 45.54 | 44.51 | 43.48 42 | .45 | 41.42 | 40.40 | 39.37 | 38.34 | |
| 1100 | 1110 | 49.20 | 48 | .17 | 47.14 | 46.11 | 45.08 | 44.06 43 | .03 | 42.00 | 40.97 | 39.94 | 38.91 | |
| 1110 | 1120 | 49.77 | 48 | .74 | 47.72 | 46.69 | 45.66 | 44.63 43 | .60 | 42.57 | 41.55 | 40.52 | 39.49 | |
| 1120 | 1130 | 50.35 | 49 | .32 | 48.29 | 47.26 | 46.23 | 45.21 44 | .18 | 43.15 | 42.12 | 41.09 | 40.06 | |
| If | w | ages a | re in | exc | ess of th | e maximu | m amount | shown | above, | |||||
| compute 5.7 | 5% | of su | ch ex | ces | s and add | to the la | st amount | in the a | pplicabl | e column. |
# For Wages Paid After July 1, 2025
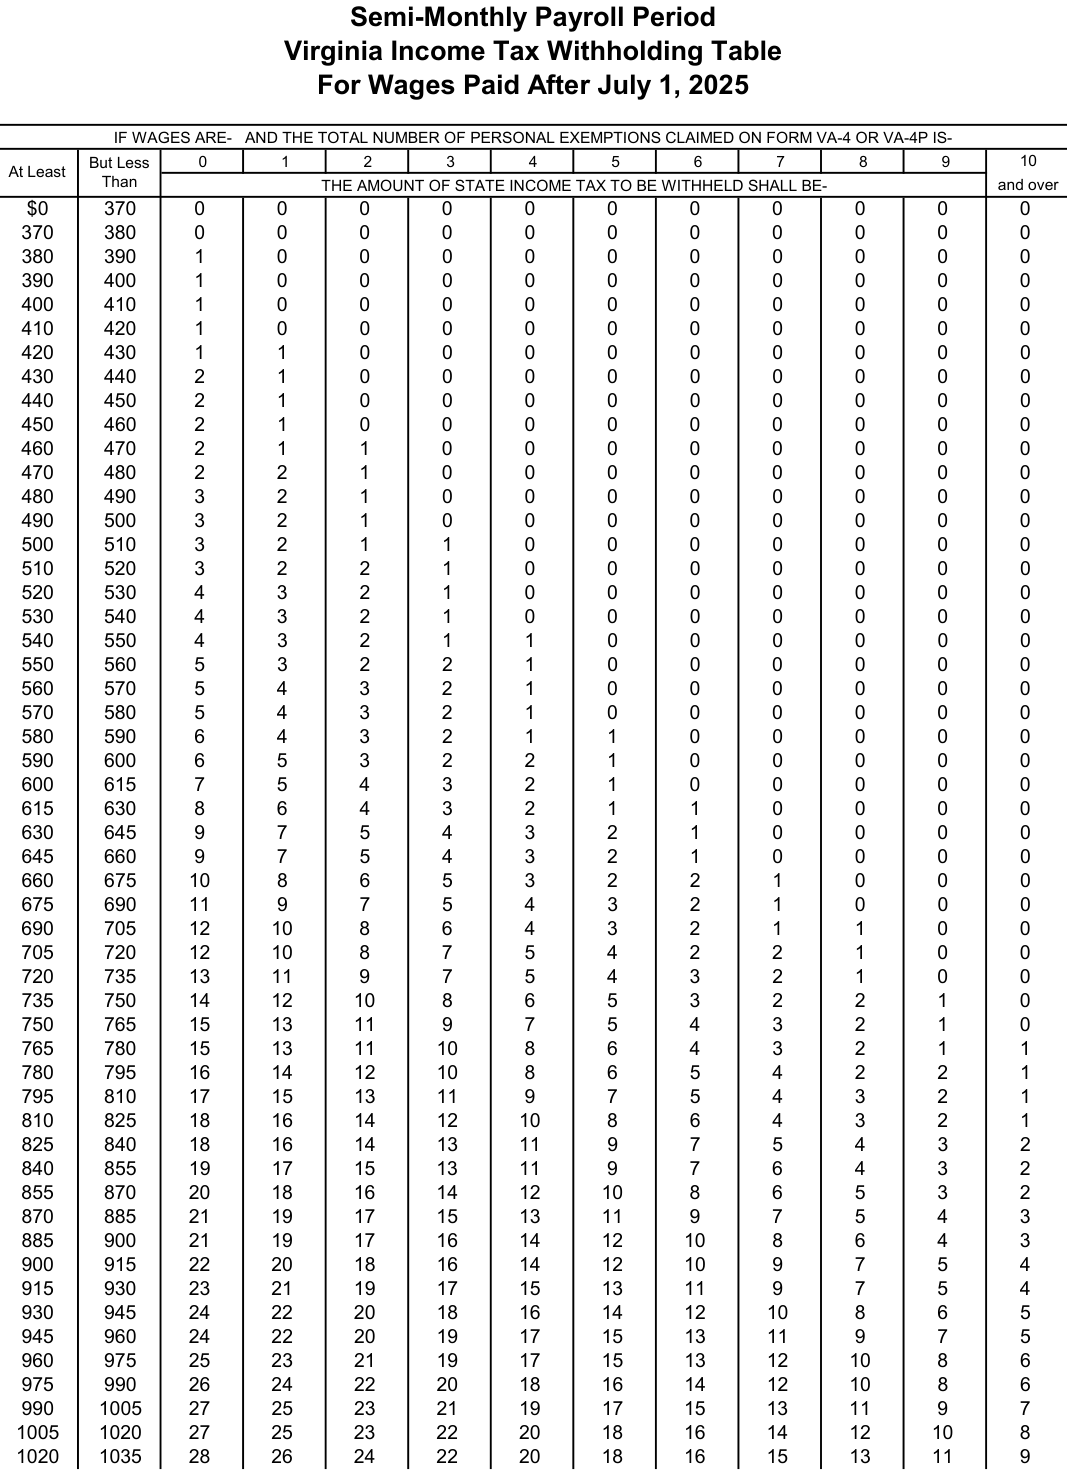
Text version of this table
| Virgin | ia Inc | ome Ta | x | Withholding Tabl | e | |||||||
| Fo | r Wage | s Paid | A | fter July 1, 2025 | ||||||||
| IF WAGES | ARE- AN | D | THE TOT | AL NUMBER | OF PERSO | NA | L EXEMPTIONS CLAIMED ON | FORM VA-4 | OR VA-4P | IS- | ||
| B t Least | ut Less | 0 | 1 | 2 | 3 | 4 | 5 6 | 7 | 8 | 9 | 10 | |
| Than | THE | AMOUNT O | F STATE I | NCO | ME TAX TO BE WITHHELD SH | ALL BE- | and | o | ||||
| $0 | 370 | 0 | 0 | 0 | 0 | 0 | 0 0 | 0 | 0 | 0 | 0 | |
| 370 | 380 | 0 | 0 | 0 | 0 | 0 | 0 0 | 0 | 0 | 0 | 0 | |
| 380 | 390 | 1 | 0 | 0 | 0 | 0 | 0 0 | 0 | 0 | 0 | 0 | |
| 390 | 400 | 1 | 0 | 0 | 0 | 0 | 0 0 | 0 | 0 | 0 | 0 | |
| 400 | 410 | 1 | 0 | 0 | 0 | 0 | 0 0 | 0 | 0 | 0 | 0 | |
| 410 | 420 | 1 | 0 | 0 | 0 | 0 | 0 0 | 0 | 0 | 0 | 0 | |
| 420 | 430 | 1 | 1 | 0 | 0 | 0 | 0 0 | 0 | 0 | 0 | 0 | |
| 430 | 440 | 2 | 1 | 0 | 0 | 0 | 0 0 | 0 | 0 | 0 | 0 | |
| 440 | 450 | 2 | 1 | 0 | 0 | 0 | 0 0 | 0 | 0 | 0 | 0 | |
| 450 | 460 | 2 | 1 | 0 | 0 | 0 | 0 0 | 0 | 0 | 0 | 0 | |
| 460 | 470 | 2 | 1 | 1 | 0 | 0 | 0 0 | 0 | 0 | 0 | 0 | |
| 470 | 480 | 2 | 2 | 1 | 0 | 0 | 0 0 | 0 | 0 | 0 | 0 | |
| 480 | 490 | 3 | 2 | 1 | 0 | 0 | 0 0 | 0 | 0 | 0 | 0 | |
| 490 | 500 | 3 | 2 | 1 | 0 | 0 | 0 0 | 0 | 0 | 0 | 0 | |
| 500 | 510 | 3 | 2 | 1 | 1 | 0 | 0 0 | 0 | 0 | 0 | 0 | |
| 510 | 520 | 3 | 2 | 2 | 1 | 0 | 0 0 | 0 | 0 | 0 | 0 | |
| 520 | 530 | 4 | 3 | 2 | 1 | 0 | 0 0 | 0 | 0 | 0 | 0 | |
| 530 | 540 | 4 | 3 | 2 | 1 | 0 | 0 0 | 0 | 0 | 0 | 0 | |
| 540 | 550 | 4 | 3 | 2 | 1 | 1 | 0 0 | 0 | 0 | 0 | 0 | |
| 550 | 560 | 5 | 3 | 2 | 2 | 1 | 0 0 | 0 | 0 | 0 | 0 | |
| 560 | 570 | 5 | 4 | 3 | 2 | 1 | 0 0 | 0 | 0 | 0 | 0 | |
| 570 | 580 | 5 | 4 | 3 | 2 | 1 | 0 0 | 0 | 0 | 0 | 0 | |
| 580 | 590 | 6 | 4 | 3 | 2 | 1 | 1 0 | 0 | 0 | 0 | 0 | |
| 590 | 600 | 6 | 5 | 3 | 2 | 2 | 1 0 | 0 | 0 | 0 | 0 | |
| 600 | 615 | 7 | 5 | 4 | 3 | 2 | 1 0 | 0 | 0 | 0 | 0 | |
| 615 | 630 | 8 | 6 | 4 | 3 | 2 | 1 1 | 0 | 0 | 0 | 0 | |
| 630 | 645 | 9 | 7 | 5 | 4 | 3 | 2 1 | 0 | 0 | 0 | 0 | |
| 645 | 660 | 9 | 7 | 5 | 4 | 3 | 2 1 | 0 | 0 | 0 | 0 | |
| 660 | 675 | 10 | 8 | 6 | 5 | 3 | 2 2 | 1 | 0 | 0 | 0 | |
| 675 | 690 | 11 | 9 | 7 | 5 | 4 | 3 2 | 1 | 0 | 0 | 0 | |
| 690 | 705 | 12 | 1 | 0 | 8 | 6 | 4 | 3 2 | 1 | 1 | 0 | 0 |
| 705 | 720 | 12 | 1 | 0 | 8 | 7 | 5 | 4 2 | 2 | 1 | 0 | 0 |
| 720 | 735 | 13 | 1 | 1 | 9 | 7 | 5 | 4 3 | 2 | 1 | 0 | 0 |
| 735 | 750 | 14 | 1 | 2 | 10 | 8 | 6 | 5 3 | 2 | 2 | 1 | 0 |
| 750 | 765 | 15 | 1 | 3 | 11 | 9 | 7 | 5 4 | 3 | 2 | 1 | 0 |
| 765 | 780 | 15 | 1 | 3 | 11 | 10 | 8 | 6 4 | 3 | 2 | 1 | 1 |
| 780 | 795 | 16 | 1 | 4 | 12 | 10 | 8 | 6 5 | 4 | 2 | 2 | 1 |
| 795 | 810 | 17 | 1 | 5 | 13 | 11 | 9 | 7 5 | 4 | 3 | 2 | 1 |
| 810 | 825 | 18 | 1 | 6 | 14 | 12 | 10 | 8 6 | 4 | 3 | 2 | 1 |
| 825 | 840 | 18 | 1 | 6 | 14 | 13 | 11 | 9 7 | 5 | 4 | 3 | 2 |
| 840 | 855 | 19 | 1 | 7 | 15 | 13 | 11 | 9 7 | 6 | 4 | 3 | 2 |
| 855 | 870 | 20 | 1 | 8 | 16 | 14 | 12 | 10 8 | 6 | 5 | 3 | 2 |
| 870 | 885 | 21 | 1 | 9 | 17 | 15 | 13 | 11 9 | 7 | 5 | 4 | 3 |
| 885 | 900 | 21 | 1 | 9 | 17 | 16 | 14 | 12 10 | 8 | 6 | 4 | 3 |
| 900 | 915 | 22 | 2 | 0 | 18 | 16 | 14 | 12 10 | 9 | 7 | 5 | 4 |
| 915 | 930 | 23 | 2 | 1 | 19 | 17 | 15 | 13 11 | 9 | 7 | 5 | 4 |
| 930 | 945 | 24 | 2 | 2 | 20 | 18 | 16 | 14 12 | 10 | 8 | 6 | 5 |
| 945 | 960 | 24 | 2 | 2 | 20 | 19 | 17 | 15 13 | 11 | 9 | 7 | 5 |
| 960 | 975 | 25 | 2 | 3 | 21 | 19 | 17 | 15 13 | 12 | 10 | 8 | 6 |
| 975 | 990 | 26 | 2 | 4 | 22 | 20 | 18 | 16 14 | 12 | 10 | 8 | 6 |
| 990 | 1005 | 27 | 2 | 5 | 23 | 21 | 19 | 17 15 | 13 | 11 | 9 | 7 |
| 1005 | 1020 | 27 | 2 | 5 | 23 | 22 | 20 | 18 16 | 14 | 12 | 10 | 8 |
| 1020 | 1035 | 28 | 2 | 6 | 24 | 22 | 20 | 18 16 | 15 | 13 | 11 | 9 |
# For Wages Paid After July 1, 2025
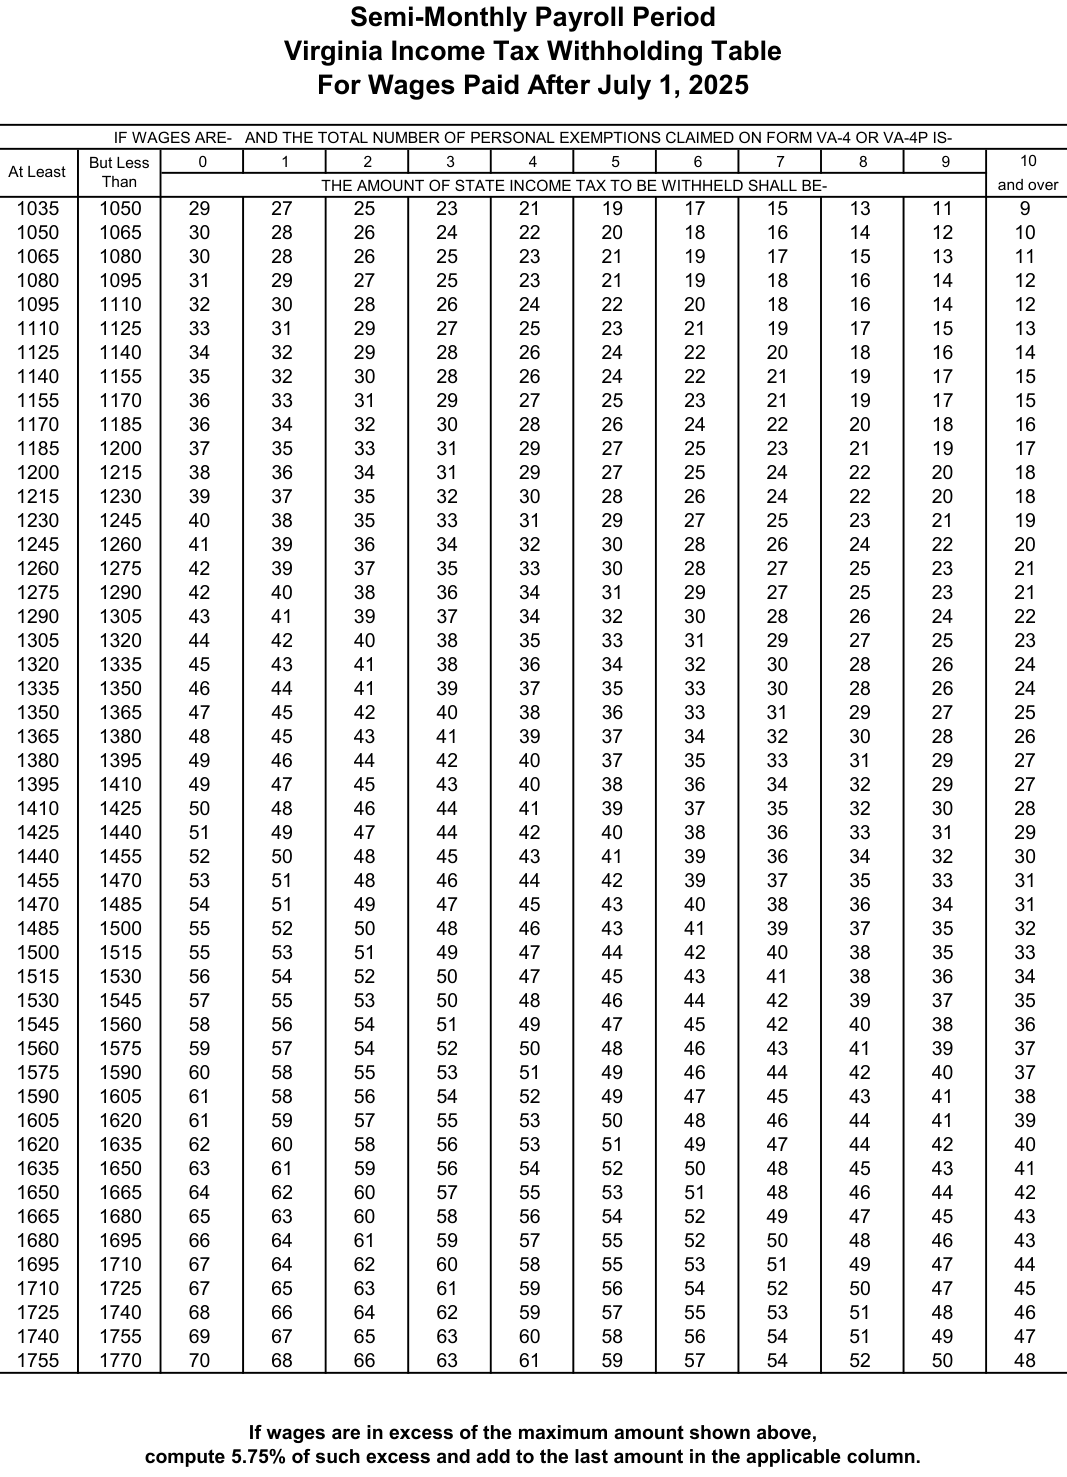
Text version of this table
| Virgin | ia Inc | ome | Tax | Withholding Tabl | e | |||||||
| Fo | r Wage | s Pa | id A | fter July 1, 2025 | ||||||||
| IF WAGES | ARE- AN | D | THE TOT | AL NUMBER | OF PE | RSONA | L EXEMPTIONS CLAIMED ON | FORM VA-4 | OR VA-4P | IS- | ||
| B t Least | ut Less | 0 | 1 | 2 | 3 | 4 | 5 6 | 7 | 8 | 9 | 10 | |
| Than | THE | AMOUNT O | F STAT | E INCO | ME TAX TO BE WITHHELD SH | ALL BE- | an | d o | ||||
| 1035 | 1050 | 29 | 2 | 7 | 25 | 23 | 21 | 19 17 | 15 | 13 | 11 | 9 |
| 1050 | 1065 | 30 | 2 | 8 | 26 | 24 | 22 | 20 18 | 16 | 14 | 12 | 10 |
| 1065 | 1080 | 30 | 2 | 8 | 26 | 25 | 23 | 21 19 | 17 | 15 | 13 | 11 |
| 1080 | 1095 | 31 | 2 | 9 | 27 | 25 | 23 | 21 19 | 18 | 16 | 14 | 12 |
| 1095 | 1110 | 32 | 3 | 0 | 28 | 26 | 24 | 22 20 | 18 | 16 | 14 | 12 |
| 1110 | 1125 | 33 | 3 | 1 | 29 | 27 | 25 | 23 21 | 19 | 17 | 15 | 13 |
| 1125 | 1140 | 34 | 3 | 2 | 29 | 28 | 26 | 24 22 | 20 | 18 | 16 | 14 |
| 1140 | 1155 | 35 | 3 | 2 | 30 | 28 | 26 | 24 22 | 21 | 19 | 17 | 15 |
| 1155 | 1170 | 36 | 3 | 3 | 31 | 29 | 27 | 25 23 | 21 | 19 | 17 | 15 |
| 1170 | 1185 | 36 | 3 | 4 | 32 | 30 | 28 | 26 24 | 22 | 20 | 18 | 16 |
| 1185 | 1200 | 37 | 3 | 5 | 33 | 31 | 29 | 27 25 | 23 | 21 | 19 | 17 |
| 1200 | 1215 | 38 | 3 | 6 | 34 | 31 | 29 | 27 25 | 24 | 22 | 20 | 18 |
| 1215 | 1230 | 39 | 3 | 7 | 35 | 32 | 30 | 28 26 | 24 | 22 | 20 | 18 |
| 1230 | 1245 | 40 | 3 | 8 | 35 | 33 | 31 | 29 27 | 25 | 23 | 21 | 19 |
| 1245 | 1260 | 41 | 3 | 9 | 36 | 34 | 32 | 30 28 | 26 | 24 | 22 | 20 |
| 1260 | 1275 | 42 | 3 | 9 | 37 | 35 | 33 | 30 28 | 27 | 25 | 23 | 21 |
| 1275 | 1290 | 42 | 4 | 0 | 38 | 36 | 34 | 31 29 | 27 | 25 | 23 | 21 |
| 1290 | 1305 | 43 | 4 | 1 | 39 | 37 | 34 | 32 30 | 28 | 26 | 24 | 22 |
| 1305 | 1320 | 44 | 4 | 2 | 40 | 38 | 35 | 33 31 | 29 | 27 | 25 | 23 |
| 1320 | 1335 | 45 | 4 | 3 | 41 | 38 | 36 | 34 32 | 30 | 28 | 26 | 24 |
| 1335 | 1350 | 46 | 4 | 4 | 41 | 39 | 37 | 35 33 | 30 | 28 | 26 | 24 |
| 1350 | 1365 | 47 | 4 | 5 | 42 | 40 | 38 | 36 33 | 31 | 29 | 27 | 25 |
| 1365 | 1380 | 48 | 4 | 5 | 43 | 41 | 39 | 37 34 | 32 | 30 | 28 | 26 |
| 1380 | 1395 | 49 | 4 | 6 | 44 | 42 | 40 | 37 35 | 33 | 31 | 29 | 27 |
| 1395 | 1410 | 49 | 4 | 7 | 45 | 43 | 40 | 38 36 | 34 | 32 | 29 | 27 |
| 1410 | 1425 | 50 | 4 | 8 | 46 | 44 | 41 | 39 37 | 35 | 32 | 30 | 28 |
| 1425 | 1440 | 51 | 4 | 9 | 47 | 44 | 42 | 40 38 | 36 | 33 | 31 | 29 |
| 1440 | 1455 | 52 | 5 | 0 | 48 | 45 | 43 | 41 39 | 36 | 34 | 32 | 30 |
| 1455 | 1470 | 53 | 5 | 1 | 48 | 46 | 44 | 42 39 | 37 | 35 | 33 | 31 |
| 1470 | 1485 | 54 | 5 | 1 | 49 | 47 | 45 | 43 40 | 38 | 36 | 34 | 31 |
| 1485 | 1500 | 55 | 5 | 2 | 50 | 48 | 46 | 43 41 | 39 | 37 | 35 | 32 |
| 1500 | 1515 | 55 | 5 | 3 | 51 | 49 | 47 | 44 42 | 40 | 38 | 35 | 33 |
| 1515 | 1530 | 56 | 5 | 4 | 52 | 50 | 47 | 45 43 | 41 | 38 | 36 | 34 |
| 1530 | 1545 | 57 | 5 | 5 | 53 | 50 | 48 | 46 44 | 42 | 39 | 37 | 35 |
| 1545 | 1560 | 58 | 5 | 6 | 54 | 51 | 49 | 47 45 | 42 | 40 | 38 | 36 |
| 1560 | 1575 | 59 | 5 | 7 | 54 | 52 | 50 | 48 46 | 43 | 41 | 39 | 37 |
| 1575 | 1590 | 60 | 5 | 8 | 55 | 53 | 51 | 49 46 | 44 | 42 | 40 | 37 |
| 1590 | 1605 | 61 | 5 | 8 | 56 | 54 | 52 | 49 47 | 45 | 43 | 41 | 38 |
| 1605 | 1620 | 61 | 5 | 9 | 57 | 55 | 53 | 50 48 | 46 | 44 | 41 | 39 |
| 1620 | 1635 | 62 | 6 | 0 | 58 | 56 | 53 | 51 49 | 47 | 44 | 42 | 40 |
| 1635 | 1650 | 63 | 6 | 1 | 59 | 56 | 54 | 52 50 | 48 | 45 | 43 | 41 |
| 1650 | 1665 | 64 | 6 | 2 | 60 | 57 | 55 | 53 51 | 48 | 46 | 44 | 42 |
| 1665 | 1680 | 65 | 6 | 3 | 60 | 58 | 56 | 54 52 | 49 | 47 | 45 | 43 |
| 1680 | 1695 | 66 | 6 | 4 | 61 | 59 | 57 | 55 52 | 50 | 48 | 46 | 43 |
| 1695 | 1710 | 67 | 6 | 4 | 62 | 60 | 58 | 55 53 | 51 | 49 | 47 | 44 |
| 1710 | 1725 | 67 | 6 | 5 | 63 | 61 | 59 | 56 54 | 52 | 50 | 47 | 45 |
| 1725 | 1740 | 68 | 6 | 6 | 64 | 62 | 59 | 57 55 | 53 | 51 | 48 | 46 |
| 1740 | 1755 | 69 | 6 | 7 | 65 | 63 | 60 | 58 56 | 54 | 51 | 49 | 47 |
| 1755 | 1770 | 70 | 6 | 8 | 66 | 63 | 61 | 59 57 | 54 | 52 | 50 | 48 |
| If | w | ages ar | e in exce | ss of t | he ma | ximum amount shown a | bove, | |||||
| com | pute 5.75 | % | of suc | h excess | and ad | d to t | he last amount in the ap | plicable | column. |
# For Wages Paid After July 1, 2025
# For Wages Paid After July 1, 2025
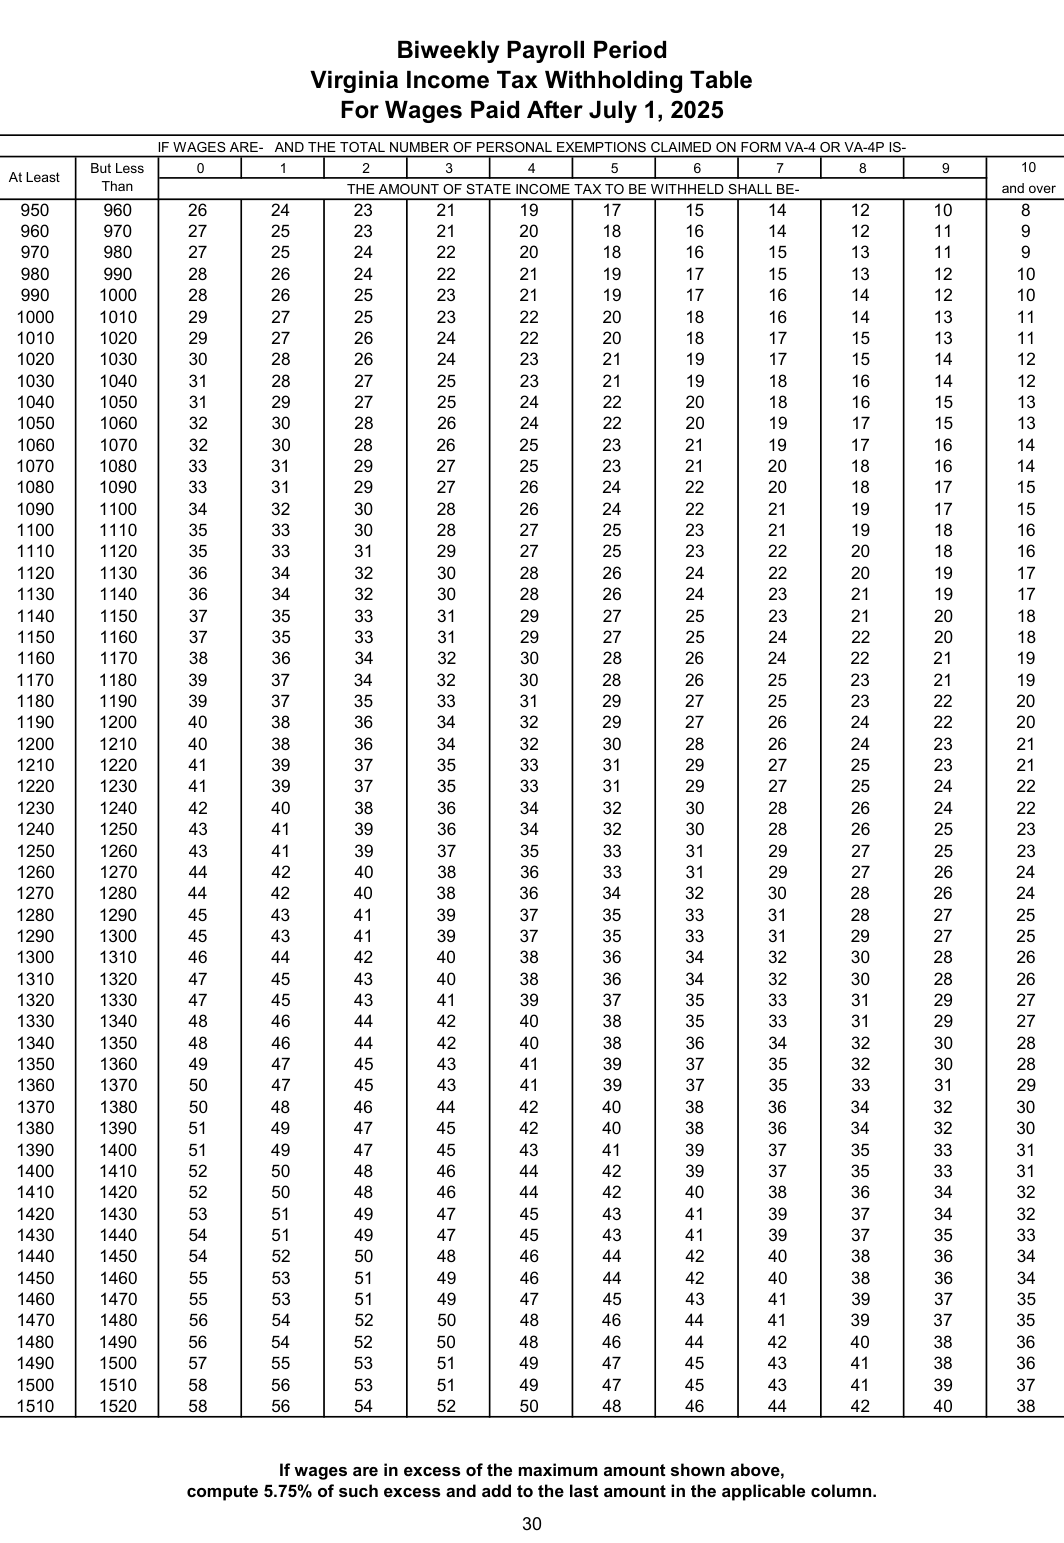
Text version of this table
| Biweekly P | ayroll P | eriod | ||||||||||
| Vir | ginia | Income T | ax With | holdin | g Table | |||||||
| For | Wages Paid | After J | uly 1, | 2025 | ||||||||
| IF | WAGES ARE- | AND THE | TOTAL N | UMBER OF PERS | ONAL EXEMP | TIONS CL | AIMED ON FOR | M VA-4 OR V | A-4P IS- | |||
| B t Least | ut Less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
| Than | THE AM | OUNT OF STATE | INCOME TAX | TO BE WI | THHELD SHAL | L BE- | an | d o | ||||
| 950 | 960 | 26 | 24 | 23 | 21 | 19 | 17 | 15 | 14 | 12 | 10 | 8 |
| 960 | 970 | 27 | 25 | 23 | 21 | 20 | 18 | 16 | 14 | 12 | 11 | 9 |
| 970 | 980 | 27 | 25 | 24 | 22 | 20 | 18 | 16 | 15 | 13 | 11 | 9 |
| 980 | 990 | 28 | 26 | 24 | 22 | 21 | 19 | 17 | 15 | 13 | 12 | 10 |
| 990 | 1000 | 28 | 26 | 25 | 23 | 21 | 19 | 17 | 16 | 14 | 12 | 10 |
| 1000 | 1010 | 29 | 27 | 25 | 23 | 22 | 20 | 18 | 16 | 14 | 13 | 11 |
| 1010 | 1020 | 29 | 27 | 26 | 24 | 22 | 20 | 18 | 17 | 15 | 13 | 11 |
| 1020 | 1030 | 30 | 28 | 26 | 24 | 23 | 21 | 19 | 17 | 15 | 14 | 12 |
| 1030 | 1040 | 31 | 28 | 27 | 25 | 23 | 21 | 19 | 18 | 16 | 14 | 12 |
| 1040 | 1050 | 31 | 29 | 27 | 25 | 24 | 22 | 20 | 18 | 16 | 15 | 13 |
| 1050 | 1060 | 32 | 30 | 28 | 26 | 24 | 22 | 20 | 19 | 17 | 15 | 13 |
| 1060 | 1070 | 32 | 30 | 28 | 26 | 25 | 23 | 21 | 19 | 17 | 16 | 14 |
| 1070 | 1080 | 33 | 31 | 29 | 27 | 25 | 23 | 21 | 20 | 18 | 16 | 14 |
| 1080 | 1090 | 33 | 31 | 29 | 27 | 26 | 24 | 22 | 20 | 18 | 17 | 15 |
| 1090 | 1100 | 34 | 32 | 30 | 28 | 26 | 24 | 22 | 21 | 19 | 17 | 15 |
| 1100 | 1110 | 35 | 33 | 30 | 28 | 27 | 25 | 23 | 21 | 19 | 18 | 16 |
| 1110 | 1120 | 35 | 33 | 31 | 29 | 27 | 25 | 23 | 22 | 20 | 18 | 16 |
| 1120 | 1130 | 36 | 34 | 32 | 30 | 28 | 26 | 24 | 22 | 20 | 19 | 17 |
| 1130 | 1140 | 36 | 34 | 32 | 30 | 28 | 26 | 24 | 23 | 21 | 19 | 17 |
| 1140 | 1150 | 37 | 35 | 33 | 31 | 29 | 27 | 25 | 23 | 21 | 20 | 18 |
| 1150 | 1160 | 37 | 35 | 33 | 31 | 29 | 27 | 25 | 24 | 22 | 20 | 18 |
| 1160 | 1170 | 38 | 36 | 34 | 32 | 30 | 28 | 26 | 24 | 22 | 21 | 19 |
| 1170 | 1180 | 39 | 37 | 34 | 32 | 30 | 28 | 26 | 25 | 23 | 21 | 19 |
| 1180 | 1190 | 39 | 37 | 35 | 33 | 31 | 29 | 27 | 25 | 23 | 22 | 20 |
| 1190 | 1200 | 40 | 38 | 36 | 34 | 32 | 29 | 27 | 26 | 24 | 22 | 20 |
| 1200 | 1210 | 40 | 38 | 36 | 34 | 32 | 30 | 28 | 26 | 24 | 23 | 21 |
| 1210 | 1220 | 41 | 39 | 37 | 35 | 33 | 31 | 29 | 27 | 25 | 23 | 21 |
| 1220 | 1230 | 41 | 39 | 37 | 35 | 33 | 31 | 29 | 27 | 25 | 24 | 22 |
| 1230 | 1240 | 42 | 40 | 38 | 36 | 34 | 32 | 30 | 28 | 26 | 24 | 22 |
| 1240 | 1250 | 43 | 41 | 39 | 36 | 34 | 32 | 30 | 28 | 26 | 25 | 23 |
| 1250 | 1260 | 43 | 41 | 39 | 37 | 35 | 33 | 31 | 29 | 27 | 25 | 23 |
| 1260 | 1270 | 44 | 42 | 40 | 38 | 36 | 33 | 31 | 29 | 27 | 26 | 24 |
| 1270 | 1280 | 44 | 42 | 40 | 38 | 36 | 34 | 32 | 30 | 28 | 26 | 24 |
| 1280 | 1290 | 45 | 43 | 41 | 39 | 37 | 35 | 33 | 31 | 28 | 27 | 25 |
| 1290 | 1300 | 45 | 43 | 41 | 39 | 37 | 35 | 33 | 31 | 29 | 27 | 25 |
| 1300 | 1310 | 46 | 44 | 42 | 40 | 38 | 36 | 34 | 32 | 30 | 28 | 26 |
| 1310 | 1320 | 47 | 45 | 43 | 40 | 38 | 36 | 34 | 32 | 30 | 28 | 26 |
| 1320 | 1330 | 47 | 45 | 43 | 41 | 39 | 37 | 35 | 33 | 31 | 29 | 27 |
| 1330 | 1340 | 48 | 46 | 44 | 42 | 40 | 38 | 35 | 33 | 31 | 29 | 27 |
| 1340 | 1350 | 48 | 46 | 44 | 42 | 40 | 38 | 36 | 34 | 32 | 30 | 28 |
| 1350 | 1360 | 49 | 47 | 45 | 43 | 41 | 39 | 37 | 35 | 32 | 30 | 28 |
| 1360 | 1370 | 50 | 47 | 45 | 43 | 41 | 39 | 37 | 35 | 33 | 31 | 29 |
| 1370 | 1380 | 50 | 48 | 46 | 44 | 42 | 40 | 38 | 36 | 34 | 32 | 30 |
| 1380 | 1390 | 51 | 49 | 47 | 45 | 42 | 40 | 38 | 36 | 34 | 32 | 30 |
| 1390 | 1400 | 51 | 49 | 47 | 45 | 43 | 41 | 39 | 37 | 35 | 33 | 31 |
| 1400 | 1410 | 52 | 50 | 48 | 46 | 44 | 42 | 39 | 37 | 35 | 33 | 31 |
| 1410 | 1420 | 52 | 50 | 48 | 46 | 44 | 42 | 40 | 38 | 36 | 34 | 32 |
| 1420 | 1430 | 53 | 51 | 49 | 47 | 45 | 43 | 41 | 39 | 37 | 34 | 32 |
| 1430 | 1440 | 54 | 51 | 49 | 47 | 45 | 43 | 41 | 39 | 37 | 35 | 33 |
| 1440 | 1450 | 54 | 52 | 50 | 48 | 46 | 44 | 42 | 40 | 38 | 36 | 34 |
| 1450 | 1460 | 55 | 53 | 51 | 49 | 46 | 44 | 42 | 40 | 38 | 36 | 34 |
| 1460 | 1470 | 55 | 53 | 51 | 49 | 47 | 45 | 43 | 41 | 39 | 37 | 35 |
| 1470 | 1480 | 56 | 54 | 52 | 50 | 48 | 46 | 44 | 41 | 39 | 37 | 35 |
| 1480 | 1490 | 56 | 54 | 52 | 50 | 48 | 46 | 44 | 42 | 40 | 38 | 36 |
| 1490 | 1500 | 57 | 55 | 53 | 51 | 49 | 47 | 45 | 43 | 41 | 38 | 36 |
| 1500 | 1510 | 58 | 56 | 53 | 51 | 49 | 47 | 45 | 43 | 41 | 39 | 37 |
| 1510 | 1520 | 58 | 56 | 54 | 52 | 50 | 48 | 46 | 44 | 42 | 40 | 38 |
| If wage | s are in | excess of the | maximum | amount | shown abov | e, | ||||||
| compute 5 | .75% of | such e | xcess and add | to the last | amount | in the applic | able colu | mn. | ||||
| 30 |
# For Wages Paid After July 1, 2025
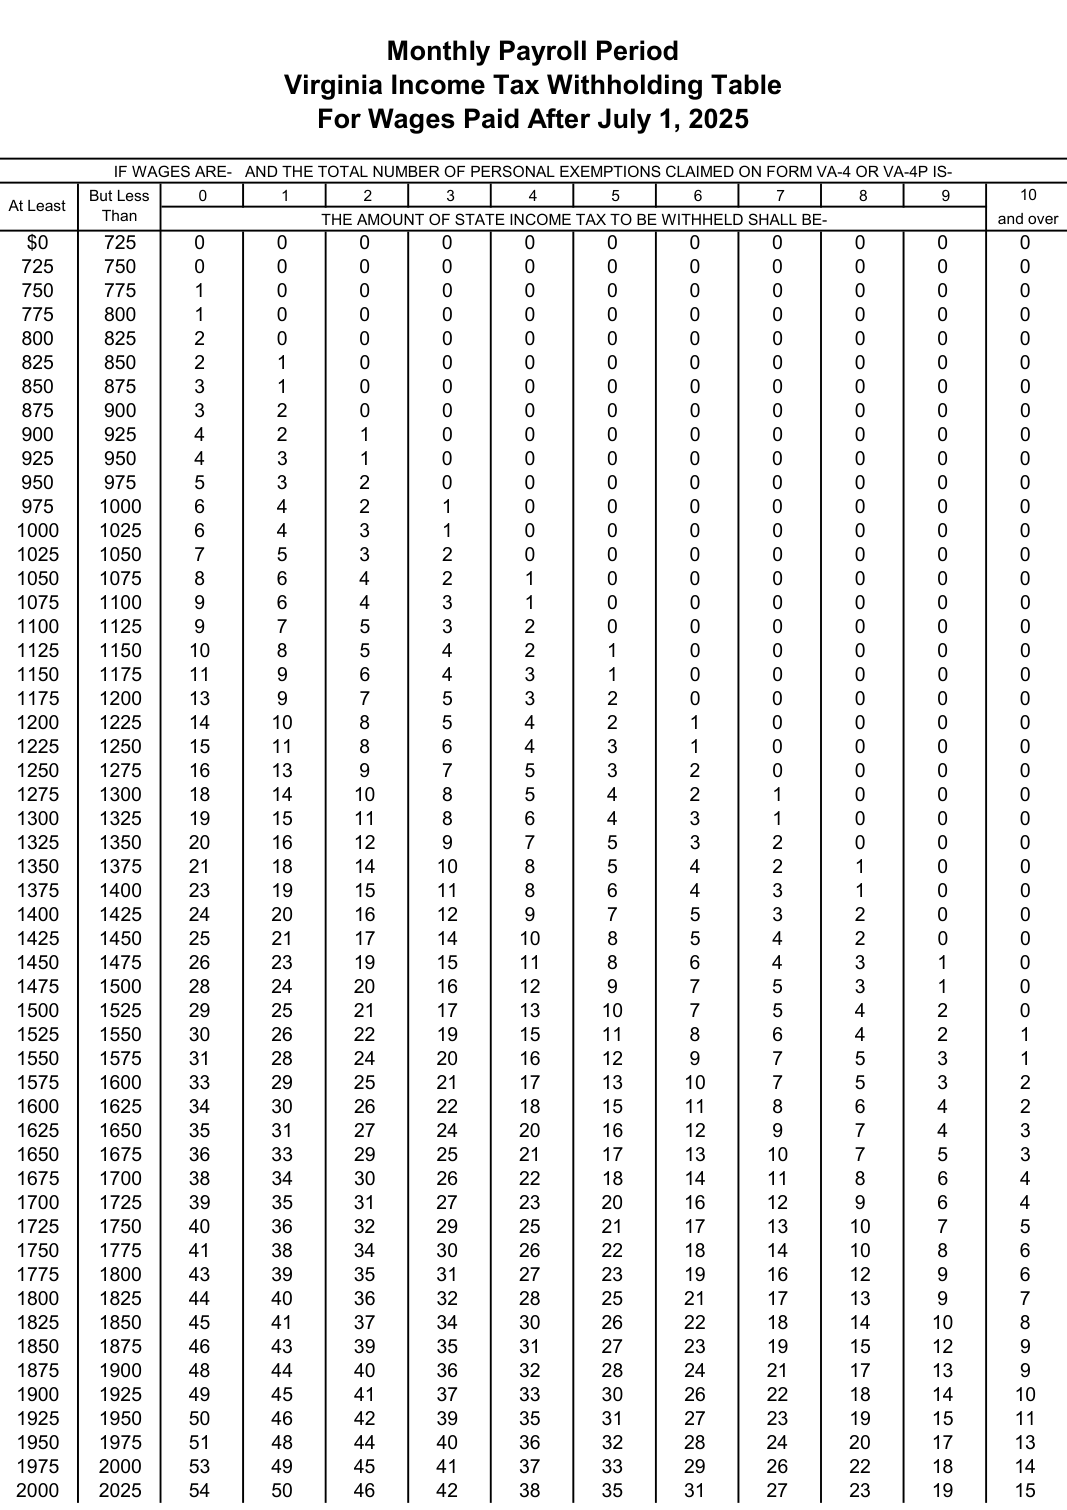
Text version of this table
| Mon | thly P | ay | roll Period | ||||||||||
| Virgin | ia | Inc | ome Ta | x | Withholding Tabl | e | |||||||
| Fo | r W | age | s Paid | A | fter July 1, 2025 | ||||||||
| IF WAGES | ARE- AN | D | THE TOT | AL N | UMBER | OF PERSO | NA | L EXEMPTIONS CLAIMED ON | FORM VA-4 | OR VA-4P | IS- | ||
| B t Least | ut Less | 0 | 1 | 2 | 3 | 4 | 5 6 | 7 | 8 | 9 | 10 | ||
| Than | THE | AMO | UNT O | F STATE I | NCO | ME TAX TO BE WITHHELD SH | ALL BE- | an | d o | ||||
| $0 | 725 | 0 | 0 | 0 | 0 | 0 | 0 0 | 0 | 0 | 0 | 0 | ||
| 725 | 750 | 0 | 0 | 0 | 0 | 0 | 0 0 | 0 | 0 | 0 | 0 | ||
| 750 | 775 | 1 | 0 | 0 | 0 | 0 | 0 0 | 0 | 0 | 0 | 0 | ||
| 775 | 800 | 1 | 0 | 0 | 0 | 0 | 0 0 | 0 | 0 | 0 | 0 | ||
| 800 | 825 | 2 | 0 | 0 | 0 | 0 | 0 0 | 0 | 0 | 0 | 0 | ||
| 825 | 850 | 2 | 1 | 0 | 0 | 0 | 0 0 | 0 | 0 | 0 | 0 | ||
| 850 | 875 | 3 | 1 | 0 | 0 | 0 | 0 0 | 0 | 0 | 0 | 0 | ||
| 875 | 900 | 3 | 2 | 0 | 0 | 0 | 0 0 | 0 | 0 | 0 | 0 | ||
| 900 | 925 | 4 | 2 | 1 | 0 | 0 | 0 0 | 0 | 0 | 0 | 0 | ||
| 925 | 950 | 4 | 3 | 1 | 0 | 0 | 0 0 | 0 | 0 | 0 | 0 | ||
| 950 | 975 | 5 | 3 | 2 | 0 | 0 | 0 0 | 0 | 0 | 0 | 0 | ||
| 975 | 1000 | 6 | 4 | 2 | 1 | 0 | 0 0 | 0 | 0 | 0 | 0 | ||
| 1000 | 1025 | 6 | 4 | 3 | 1 | 0 | 0 0 | 0 | 0 | 0 | 0 | ||
| 1025 | 1050 | 7 | 5 | 3 | 2 | 0 | 0 0 | 0 | 0 | 0 | 0 | ||
| 1050 | 1075 | 8 | 6 | 4 | 2 | 1 | 0 0 | 0 | 0 | 0 | 0 | ||
| 1075 | 1100 | 9 | 6 | 4 | 3 | 1 | 0 0 | 0 | 0 | 0 | 0 | ||
| 1100 | 1125 | 9 | 7 | 5 | 3 | 2 | 0 0 | 0 | 0 | 0 | 0 | ||
| 1125 | 1150 | 10 | 8 | 5 | 4 | 2 | 1 0 | 0 | 0 | 0 | 0 | ||
| 1150 | 1175 | 11 | 9 | 6 | 4 | 3 | 1 0 | 0 | 0 | 0 | 0 | ||
| 1175 | 1200 | 13 | 9 | 7 | 5 | 3 | 2 0 | 0 | 0 | 0 | 0 | ||
| 1200 | 1225 | 14 | 1 | 0 | 8 | 5 | 4 | 2 1 | 0 | 0 | 0 | 0 | |
| 1225 | 1250 | 15 | 1 | 1 | 8 | 6 | 4 | 3 1 | 0 | 0 | 0 | 0 | |
| 1250 | 1275 | 16 | 1 | 3 | 9 | 7 | 5 | 3 2 | 0 | 0 | 0 | 0 | |
| 1275 | 1300 | 18 | 1 | 4 | 10 | 8 | 5 | 4 2 | 1 | 0 | 0 | 0 | |
| 1300 | 1325 | 19 | 1 | 5 | 11 | 8 | 6 | 4 3 | 1 | 0 | 0 | 0 | |
| 1325 | 1350 | 20 | 1 | 6 | 12 | 9 | 7 | 5 3 | 2 | 0 | 0 | 0 | |
| 1350 | 1375 | 21 | 1 | 8 | 14 | 10 | 8 | 5 4 | 2 | 1 | 0 | 0 | |
| 1375 | 1400 | 23 | 1 | 9 | 15 | 11 | 8 | 6 4 | 3 | 1 | 0 | 0 | |
| 1400 | 1425 | 24 | 2 | 0 | 16 | 12 | 9 | 7 5 | 3 | 2 | 0 | 0 | |
| 1425 | 1450 | 25 | 2 | 1 | 17 | 14 | 10 | 8 5 | 4 | 2 | 0 | 0 | |
| 1450 | 1475 | 26 | 2 | 3 | 19 | 15 | 11 | 8 6 | 4 | 3 | 1 | 0 | |
| 1475 | 1500 | 28 | 2 | 4 | 20 | 16 | 12 | 9 7 | 5 | 3 | 1 | 0 | |
| 1500 | 1525 | 29 | 2 | 5 | 21 | 17 | 13 | 10 7 | 5 | 4 | 2 | 0 | |
| 1525 | 1550 | 30 | 2 | 6 | 22 | 19 | 15 | 11 8 | 6 | 4 | 2 | 1 | |
| 1550 | 1575 | 31 | 2 | 8 | 24 | 20 | 16 | 12 9 | 7 | 5 | 3 | 1 | |
| 1575 | 1600 | 33 | 2 | 9 | 25 | 21 | 17 | 13 10 | 7 | 5 | 3 | 2 | |
| 1600 | 1625 | 34 | 3 | 0 | 26 | 22 | 18 | 15 11 | 8 | 6 | 4 | 2 | |
| 1625 | 1650 | 35 | 3 | 1 | 27 | 24 | 20 | 16 12 | 9 | 7 | 4 | 3 | |
| 1650 | 1675 | 36 | 3 | 3 | 29 | 25 | 21 | 17 13 | 10 | 7 | 5 | 3 | |
| 1675 | 1700 | 38 | 3 | 4 | 30 | 26 | 22 | 18 14 | 11 | 8 | 6 | 4 | |
| 1700 | 1725 | 39 | 3 | 5 | 31 | 27 | 23 | 20 16 | 12 | 9 | 6 | 4 | |
| 1725 | 1750 | 40 | 3 | 6 | 32 | 29 | 25 | 21 17 | 13 | 10 | 7 | 5 | |
| 1750 | 1775 | 41 | 3 | 8 | 34 | 30 | 26 | 22 18 | 14 | 10 | 8 | 6 | |
| 1775 | 1800 | 43 | 3 | 9 | 35 | 31 | 27 | 23 19 | 16 | 12 | 9 | 6 | |
| 1800 | 1825 | 44 | 4 | 0 | 36 | 32 | 28 | 25 21 | 17 | 13 | 9 | 7 | |
| 1825 | 1850 | 45 | 4 | 1 | 37 | 34 | 30 | 26 22 | 18 | 14 | 10 | 8 | |
| 1850 | 1875 | 46 | 4 | 3 | 39 | 35 | 31 | 27 23 | 19 | 15 | 12 | 9 | |
| 1875 | 1900 | 48 | 4 | 4 | 40 | 36 | 32 | 28 24 | 21 | 17 | 13 | 9 | |
| 1900 | 1925 | 49 | 4 | 5 | 41 | 37 | 33 | 30 26 | 22 | 18 | 14 | 10 | |
| 1925 | 1950 | 50 | 4 | 6 | 42 | 39 | 35 | 31 27 | 23 | 19 | 15 | 11 | |
| 1950 | 1975 | 51 | 4 | 8 | 44 | 40 | 36 | 32 28 | 24 | 20 | 17 | 13 | |
| 1975 | 2000 | 53 | 4 | 9 | 45 | 41 | 37 | 33 29 | 26 | 22 | 18 | 14 | |
| 2000 | 2025 | 54 | 5 | 0 | 46 | 42 | 38 | 35 31 | 27 | 23 | 19 | 15 |
# For Wages Paid After July 1, 2025
# At Least
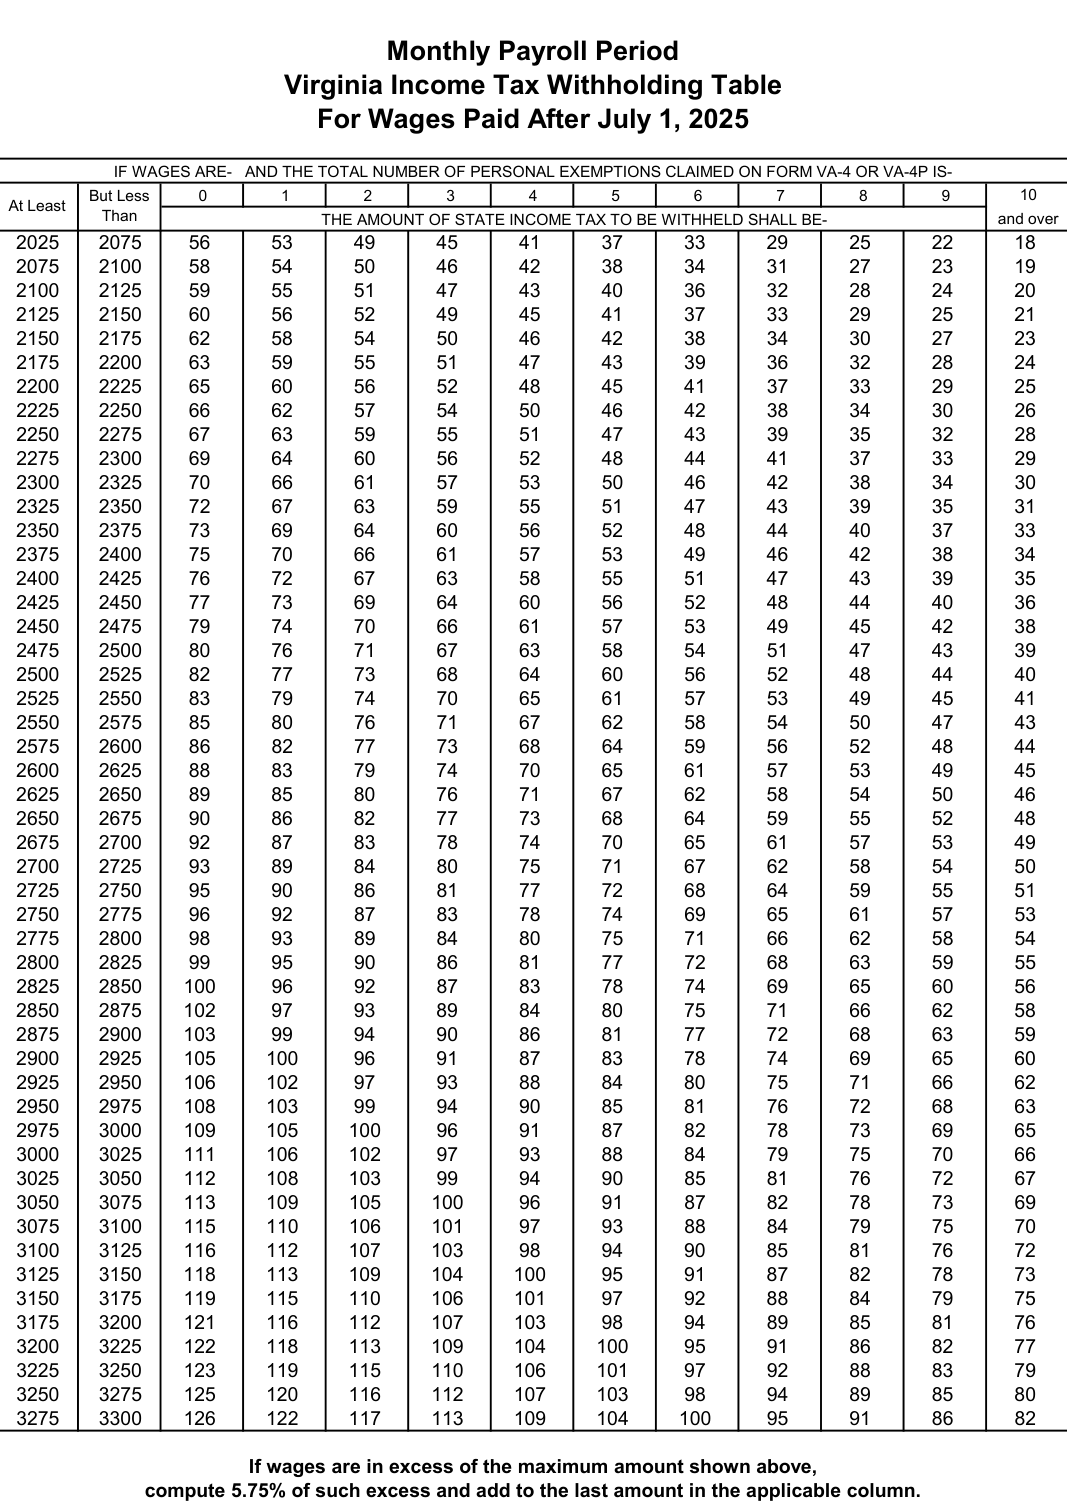
Text version of this table
| Mo | nthly P | ay | roll Period | ||||||||||
| Virgi | nia | Inc | ome T | ax | Withholding Tabl | e | |||||||
| Fo | r W | ag | es Paid | A | fter July 1, 2025 | ||||||||
| IF WAGE | S ARE- AN | D | THE TOT | AL N | UMBE | R OF PERS | ONA | L EXEMPTIONS CLAIMED ON | FORM VA-4 | OR VA-4P | IS- | ||
| B t Least | ut Less | 0 | 1 | 2 | 3 | 4 | 5 6 | 7 | 8 | 9 | 10 | ||
| Than | THE | AMO | UNT | OF STATE I | NCO | ME TAX TO BE WITHHELD SH | ALL BE- | an | d o | ||||
| 2025 | 2075 | 56 | 5 | 3 | 49 | 45 | 41 | 37 33 | 29 | 25 | 22 | 18 | |
| 2075 | 2100 | 58 | 5 | 4 | 50 | 46 | 42 | 38 34 | 31 | 27 | 23 | 19 | |
| 2100 | 2125 | 59 | 5 | 5 | 51 | 47 | 43 | 40 36 | 32 | 28 | 24 | 20 | |
| 2125 | 2150 | 60 | 5 | 6 | 52 | 49 | 45 | 41 37 | 33 | 29 | 25 | 21 | |
| 2150 | 2175 | 62 | 5 | 8 | 54 | 50 | 46 | 42 38 | 34 | 30 | 27 | 23 | |
| 2175 | 2200 | 63 | 5 | 9 | 55 | 51 | 47 | 43 39 | 36 | 32 | 28 | 24 | |
| 2200 | 2225 | 65 | 6 | 0 | 56 | 52 | 48 | 45 41 | 37 | 33 | 29 | 25 | |
| 2225 | 2250 | 66 | 6 | 2 | 57 | 54 | 50 | 46 42 | 38 | 34 | 30 | 26 | |
| 2250 | 2275 | 67 | 6 | 3 | 59 | 55 | 51 | 47 43 | 39 | 35 | 32 | 28 | |
| 2275 | 2300 | 69 | 6 | 4 | 60 | 56 | 52 | 48 44 | 41 | 37 | 33 | 29 | |
| 2300 | 2325 | 70 | 6 | 6 | 61 | 57 | 53 | 50 46 | 42 | 38 | 34 | 30 | |
| 2325 | 2350 | 72 | 6 | 7 | 63 | 59 | 55 | 51 47 | 43 | 39 | 35 | 31 | |
| 2350 | 2375 | 73 | 6 | 9 | 64 | 60 | 56 | 52 48 | 44 | 40 | 37 | 33 | |
| 2375 | 2400 | 75 | 7 | 0 | 66 | 61 | 57 | 53 49 | 46 | 42 | 38 | 34 | |
| 2400 | 2425 | 76 | 7 | 2 | 67 | 63 | 58 | 55 51 | 47 | 43 | 39 | 35 | |
| 2425 | 2450 | 77 | 7 | 3 | 69 | 64 | 60 | 56 52 | 48 | 44 | 40 | 36 | |
| 2450 | 2475 | 79 | 7 | 4 | 70 | 66 | 61 | 57 53 | 49 | 45 | 42 | 38 | |
| 2475 | 2500 | 80 | 7 | 6 | 71 | 67 | 63 | 58 54 | 51 | 47 | 43 | 39 | |
| 2500 | 2525 | 82 | 7 | 7 | 73 | 68 | 64 | 60 56 | 52 | 48 | 44 | 40 | |
| 2525 | 2550 | 83 | 7 | 9 | 74 | 70 | 65 | 61 57 | 53 | 49 | 45 | 41 | |
| 2550 | 2575 | 85 | 8 | 0 | 76 | 71 | 67 | 62 58 | 54 | 50 | 47 | 43 | |
| 2575 | 2600 | 86 | 8 | 2 | 77 | 73 | 68 | 64 59 | 56 | 52 | 48 | 44 | |
| 2600 | 2625 | 88 | 8 | 3 | 79 | 74 | 70 | 65 61 | 57 | 53 | 49 | 45 | |
| 2625 | 2650 | 89 | 8 | 5 | 80 | 76 | 71 | 67 62 | 58 | 54 | 50 | 46 | |
| 2650 | 2675 | 90 | 8 | 6 | 82 | 77 | 73 | 68 64 | 59 | 55 | 52 | 48 | |
| 2675 | 2700 | 92 | 8 | 7 | 83 | 78 | 74 | 70 65 | 61 | 57 | 53 | 49 | |
| 2700 | 2725 | 93 | 8 | 9 | 84 | 80 | 75 | 71 67 | 62 | 58 | 54 | 50 | |
| 2725 | 2750 | 95 | 9 | 0 | 86 | 81 | 77 | 72 68 | 64 | 59 | 55 | 51 | |
| 2750 | 2775 | 96 | 9 | 2 | 87 | 83 | 78 | 74 69 | 65 | 61 | 57 | 53 | |
| 2775 | 2800 | 98 | 9 | 3 | 89 | 84 | 80 | 75 71 | 66 | 62 | 58 | 54 | |
| 2800 | 2825 | 99 | 9 | 5 | 90 | 86 | 81 | 77 72 | 68 | 63 | 59 | 55 | |
| 2825 | 2850 | 100 | 9 | 6 | 92 | 87 | 83 | 78 74 | 69 | 65 | 60 | 56 | |
| 2850 | 2875 | 102 | 9 | 7 | 93 | 89 | 84 | 80 75 | 71 | 66 | 62 | 58 | |
| 2875 | 2900 | 103 | 9 | 9 | 94 | 90 | 86 | 81 77 | 72 | 68 | 63 | 59 | |
| 2900 | 2925 | 105 | 1 | 00 | 96 | 91 | 87 | 83 78 | 74 | 69 | 65 | 60 | |
| 2925 | 2950 | 106 | 1 | 02 | 97 | 93 | 88 | 84 80 | 75 | 71 | 66 | 62 | |
| 2950 | 2975 | 108 | 1 | 03 | 99 | 94 | 90 | 85 81 | 76 | 72 | 68 | 63 | |
| 2975 | 3000 | 109 | 1 | 05 | 100 | 96 | 91 | 87 82 | 78 | 73 | 69 | 65 | |
| 3000 | 3025 | 111 | 1 | 06 | 102 | 97 | 93 | 88 84 | 79 | 75 | 70 | 66 | |
| 3025 | 3050 | 112 | 1 | 08 | 103 | 99 | 94 | 90 85 | 81 | 76 | 72 | 67 | |
| 3050 | 3075 | 113 | 1 | 09 | 105 | 100 | 96 | 91 87 | 82 | 78 | 73 | 69 | |
| 3075 | 3100 | 115 | 1 | 10 | 106 | 101 | 97 | 93 88 | 84 | 79 | 75 | 70 | |
| 3100 | 3125 | 116 | 1 | 12 | 107 | 103 | 98 | 94 90 | 85 | 81 | 76 | 72 | |
| 3125 | 3150 | 118 | 1 | 13 | 109 | 104 | 100 | 95 91 | 87 | 82 | 78 | 73 | |
| 3150 | 3175 | 119 | 1 | 15 | 110 | 106 | 101 | 97 92 | 88 | 84 | 79 | 75 | |
| 3175 | 3200 | 121 | 1 | 16 | 112 | 107 | 103 | 98 94 | 89 | 85 | 81 | 76 | |
| 3200 | 3225 | 122 | 1 | 18 | 113 | 109 | 104 | 100 95 | 91 | 86 | 82 | 77 | |
| 3225 | 3250 | 123 | 1 | 19 | 115 | 110 | 106 | 101 97 | 92 | 88 | 83 | 79 | |
| 3250 | 3275 | 125 | 1 | 20 | 116 | 112 | 107 | 103 98 | 94 | 89 | 85 | 80 | |
| 3275 | 3300 | 126 | 1 | 22 | 117 | 113 | 109 | 104 100 | 95 | 91 | 86 | 82 | |
| If | w | ages ar | e in | exce | ss of the | ma | ximum amount shown a | bove, | |||||
| com | pute 5.75 | % | of suc | h ex | cess | and add | to t | he last amount in the ap | plicable | column. |
Source: view the official PDF
The source document contains 1 figure (charts or worksheet graphics) not reproduced in this text version. See the official PDF above.
Nearby sections (13 sections)
- employer-withholding-instructions · Virginia Employer Withholding…
- form-500 · Instructions for Form 500 — Corporation Income Tax Return
- form-500cr · Instructions for Form 500CR — Credit Computation Schedule…
- form-502 · Instructions for Form 502 — Pass-Through Entity Income Tax…
- form-502ptet · Form 502PTET — Pass-Through Entity Tax (PTET)…
- form-760 · Instructions for Form 760 — Resident Individual Income Tax…
- form-760py · Instructions for Form 760PY — Part-Year Resident…
- form-763 · Instructions for Form 763 — Nonresident Individual Income…
- form-765 · Instructions for Form 765 — Unified Nonresident Individual…
- form-770 · Instructions for Form 770 — Fiduciary Income Tax Return
- form-st-9 · Form ST-9 — Retail Sales and Use Tax Return (form +…
- form-va-4 · Form VA-4 — Employee's Virginia Income Tax Withholding…
- form-va-5-monthly · Form VA-5 (Monthly) — Employer's Return of Virginia…