Publication 14 — Utah Withholding Tax Guide
!
Effective June 1, 2023
!"# $%
&!' (!
)!*" )+,,&
('!!!'!+ -.!
!"# $%
& "
Contents
Electronic Filing Requirements … 2 General Information … 2 Employment Tax Workshops … 2 Who Must Withhold Taxes … 2 Employer Withholding Exemption … 2 Employee Withholding Exclusions … 2 Nonresident Employees Working Temporarily in Utah … 2 Interstate Transportation Wages … 3 Active Duty Service Member's Nonresident Spouse Wages 3 Definitions … 3 Wages … 3 Utah Taxable Wages … 3 Household Employees … 3 How to Get a Withholding Account … 3 Federal Employer Identification Number … 3 Bond Requirements for Utah … 3 How Much to Withhold … 3 How to File Returns … 3 Filing with No Tax Liability (Zero Returns) … 3 Amended Returns … 3 How to Make Payments … 4 Payroll Service Providers … 4 Liability … 4 Annual Reconciliation … 4 Amended Reconciliations … 4 Late and/or Incorrect Filings … 4 Balancing the Reconciliation … 4 Withholding Filing Record … 5 Due Dates … 5 Annual Returns with Annual Payments … 5 Quarterly Returns with Quarterly Payments … 5 Quarterly Returns with Monthly Payments … 5 Annual Reconciliations, W-2s and 1099s … 5 Filing Status Changes … 5 W-2 and 1099 Requirements … 5 Amending W-2s … 5 Penalties and Interest … 5 Late Filing and Late Payments … 5 Annual Reconciliation … 6 Interest … 6 Changing or Closing an Account … 6 Agencies … 6 Internal Revenue Service … 6 Utah State Tax Commission … 6 Social Security Administration … 6 Utah Dept. of Workforce Services … 6 Labor Commission of Utah … 6 Utah Withholding Taxes Calendar … 7 Utah Withholding Schedules … 8 Instructions … 8 Utah Schedules 1-4 - Weekly, Biweekly, Semimonthly, Monthly … 9 Utah Schedules 5-8 - Quarterly, Semiannual, Annual, Daily … 10 Examples of Utah Withholding Calculations … 11 Utah Withholding Tables … 12 Weekly and Biweekly Payroll Periods … 12 Semimonthly and Monthly Payroll Periods … 13 Quarterly and Semiannual Payroll Periods … 14 Annual and Daily/Miscellaneous Payroll Periods … 15 E-Verify for Employers Employers can help prevent identity theft by verifying the social security numbers of job applicants. E-Verify is a free service of the U.S. Department of Homeland Security that verifies employment eligibility through the Internet. Employers can use E-Verify at dhs.gov/E-Verify.
Electronic Filing Requirements
- You must file Utah withholding tax returns, W-2s and 1099s (with Utah tax withheld) electronically.
- Your annual reconciliation is combined with your fourth quarter return (quarterly filers) or your annual return (annual filers).
- File and amend returns electronically on our secure website at tap.utah.gov. We will reject any withholding forms received on paper.
- You may pay withholding tax online or by check. If paying by check, print a payment coupon (TC-941PC) from Important Reminders
- It is a class B misdemeanor to have Utah employees without a withholding license. See How to Get a Withholding Account, below.
- If you file federal form 944, Employer's Annual Federal Tax Return, you may file and pay your Utah withholding tax annually.
- If you do not meet the criteria in Utah Code §§59-10-402, 404 and 405, you are not required to have a Utah withholding account or to withhold Utah tax. Also, if you are not required to withhold Utah tax on a form 1099, you are not required to submit the 1099 form or to report the wages or compensation on your Utah withholding or reconciliation forms.
- If you withheld tax from a nonresident professional athlete, you must complete the Worksheet for Nonresident Professional Athletes when you electronically file your annual reconciliation. Download the worksheet at General Information This publication includes:
- requirements for filing and paying Utah withholding tax,
- requirements for filing the Utah annual reconciliation,
- requirements for electronic filing,
- withholding tax schedules for calculating Utah withholding tax from employees' wages, and
- Utah withholding tax tables for quick lookup.
For questions about Utah withholding tax, see tax.utah.gov, or call us at 801-297-2200 (1-800-662-4335 outside the Salt Lake area).
This publication does not cover Utah withholding requirements for mineral production or pass-through entities. See tax.utah.gov/withholding and This publication does not cover federal withholding requirements. Contact the Internal Revenue Service (IRS) (see Agencies, below).
# Employment Tax Workshops
The Tax Commission (together with the IRS, Workforce
# Services, and the Labor Commission) holds Employment Tax
Workshops sponsored by the Utah Small Business Development Centers (SBDC). These workshops teach employers how to withhold federal and state income taxes and explain federal and state filing and paying requirements. See Agencies, below, for more information.
# Who Must Withhold Taxes
You must withhold Utah income tax (unless the employee has filed a withholding exemption certificate) if you:
- pay wages to any employee for work done in Utah;
- pay wages to Utah resident employees for work done outside Utah (you may reduce the Utah tax by any tax withheld by the other state); or
- make payments reported on forms 1099 (or as required under Utah Code §59-10-405).
# Employer Withholding Exemption
You may be exempt from Utah withholding requirements if you do business in Utah for 60 days or less in a calendar year and have Tax Commission approval. If you do business for more than 60 days, you must withhold taxes for the entire period unless you can show good cause. In that case, the Tax Commission may extend the exemption for 30 days. See Utah Code §59-10-402(2).
Submit exemption requests to:
Waivers
210 N 1950 W
Salt Lake City, UT 84134-2000
Note: This exemption is for the employer, not the employee.
The employee must still file and pay Utah tax on all Utah wages. Report Utah wages on form W-2, box 16.
Employee Withholding Exclusions
Nonresident Employees Working
# Temporarily in Utah
The wages of certain non-residents working temporarily in Utah are exempt from Utah withholding requirements. See Utah Code §§59-10-402 and 59-10-117.5.
Do not withhold Utah taxes for or report wages as Utah wages of a non-resident employee who:
- has no other sources of Utah income,
- works in Utah for 20 days or less, and
- is a resident of a state that either: a) does not have an income tax, or b) exempts the wages of nonresidents from taxation with an exclusion similar to this one.
This exclusion does not apply to:
- professional athletes;
- professional entertainers;
- prominent persons who perform services on a per-event basis;
- real property laborers; or
- any employee who, during the year prior to the current tax year, was either a key employee or, in the case of a noncorporate employer, an employee/officer who is one of the 50 highest-paid employees (see definitions in IRC §416(i))
# Interstate Transportation Wages
Wages of interstate transportation employees are taxable only in the state of their residency (see Public Law 101-322).
To qualify, the employee must:
- work for an interstate railroad, interstate motor carrier or interstate private carrier;
- be a nonresident of Utah;
- have regularly assigned duties in more than one state;
- be subject to the jurisdiction of the U.S. Secretary of Transportation; and
- be an operator, mechanic or someone directly responsible for the safety of a motor vehicle.
"On-call" or "as-needed" duties are not considered "regularly assigned duties."
A qualified employee must give the employer federal form
# W-4, Employee's Withholding Certificate and write "Utah
Only - Exempt, Interstate Transportation" under box 4c.
The employee must notify the employer immediately if they no longer qualify for the exclusion.
Do not report the employee's wages as Utah wages in box 16 of form W-2 and do not withhold any Utah tax on the wages.
See General Instructions on federal form W-4.
Active Duty Service MemberÊs Nonresident
# Spouse Wages
If a nonresident active duty military service member and a nonmilitary spouse have the same domicile and the service member moves to Utah under military orders, the spouse's domicile does not change when moving to live with the service member.
All of the spouse's income is exempt from Utah income tax.
A qualified spouse receiving employee wages should give his or her employer a federal form W-4, Employee's Withholding Certificate, with the following change:
- Write "Utah Only - Exempt, Military Spouse" under box 4c.
Do not withhold any Utah tax on wages paid to a qualified spouse. Even though the Utah wages are tax-exempt, report them on form W-2, box 16.
A qualified spouse must notify their employer immediately if they no longer qualify for the exclusion.
Definitions
Wages
Wages are payments or compensation for services performed by an employee for an employer. This includes payments in a form other than cash. Utah defines wages by the Internal Revenue Code, Section 3401(a).
Utah Taxable Wages
Utah calculates withholding tax based on wages subject to federal withholding tax (as defined by the IRS). No subtraction is made for personal or other withholding allowances claimed on federal form W-4.
Household Employees
Household employees provide domestic services in private homes, college clubs, fraternities, and sororities. Utah income tax may be withheld from household employees' wages if both the employer and the employee agree.
# How to Get a Withholding Account
If you must withhold Utah taxes, you have several options to get a withholding tax account:
- Online using Taxpayer Access Point at tap.utah.gov ("Apply for a Tax Account (TC-69)" link),
- Online using the OneStop Online Business Registration at osbr.utah.gov (multiple Utah agencies), or
- Submitting form TC-69, Utah State Business and Tax Registration (Tax Commission only). Get forms online at
# Federal Employer Identification Number
Employers must get a federal employer identification number
(EIN) from the IRS before registering in Utah.
You can request an EIN through the IRS's Online EIN Application at www.irs.gov. Contact the IRS at 1-800-829-4933 for more information.
If you change your EIN with the IRS, you must also change your Utah withholding account number (file form TC-69 and include Schedule WTH).
If you changed the EIN and Utah withholding account numbers during the year, you may need to file form TC-941D, Discrepancy Report. See Balancing the Reconciliation below.
Bond Requirements for Utah
You may have to post a bond of $25,000 to $500,000 if you have a history of filing or paying late. See Utah Code §59-10-405.5(6).
How Much to Withhold
Withhold amounts based on your employee's federal W-4 form and the Utah withholding schedules or tables in this publication. See Utah Rules R865-9I-14 and 15.
# How to File Returns
You must file returns electronically and pay all amounts withheld to the Tax Commission by the due dates.
You must file a return for each filing period, even if you don't withhold taxes during a period. We may assess a non-filing penalty if you make a payment without filing a return.
See detailed filing instructions and file returns online at tap.utah.gov. Also see tax.utah.gov/withhold/ti-02.pdf.
# Filing with No Tax Liability (Zero Returns)
If there is no withholding for the period, you must file a return showing zeros. Failing to do so will result in an estimated tax assessment.
If you have no withholding for the entire year, you must still file an annual reconciliation (as part of the fourth quarter return) by January 31 of the following year. Failure to do so may result in penalties.
# Amended Returns
An amended return replaces a previously filed return.
Enter the total corrected amounts, not the amount of the adjustment.
File amended returns online at tap.utah.gov. Reopen the return in your online account, click the amended box, make any corrections, and resubmit the return.
Pay any additional taxes you owe (see How to Make Payments, below). Include interest calculated from the original due date to your payment date. Find interest rates in Pub 58, Utah Interest and Penalties, at tax.utah.gov/forms.
# How to Make Payments
NOTE: Payments do not count as returns.
Pay online at tap.utah.gov, or mail your payment with payment coupon TC-941PC. Print payment coupons at Pay online using:
- Electronic Funds Transfer (EFT) ACH Credit - You initiate this payment through your financial institution (they may charge a transaction fee). See Electronic Funds Transfer - EFT, at tax.utah.gov/billing.
- ACH Debit Requests - You authorize the Tax Commission to initiate this payment (there is no transaction fee).
Go to tap.utah.gov for more information.
- Credit Card - Pay electronically with a credit card at tap.utah.gov. You will be charged a convenience fee for this service.
# Payroll Service Providers
may handle all withholding record keeping, payments and reconciliations for an employer.
However, the employer is responsible if returns and payments are not submitted on time.
Liability
Employers are liable for the tax required to be withheld
- not their employees. If you fail to pay any of the withheld taxes, we may put a lien on your business assets and personal property.
Annual Reconciliation
You must file an annual reconciliation for each year (or partial year) you have a withholding tax account, even if you have no employees or withholding to report for the year. Both quarterly and annual filers must file annual reconciliations.
# Tax years starting 2018
Your reconciliation is combined with your fourth quarter withholding tax return (quarterly filers) or your annual withholding tax return (annual filers).
# Tax years before 2018
If reconciling a tax year before 2018, you must file the reconciliation return in addition to and separately from your quarterly or annual withholding return(s).
See Online Filing and Paying of Withholding and Mineral Production Taxes at tax.utah.gov/developers/withholding for step-by-step annual reconciliation instructions.
Amended Reconciliations
An amended reconciliation replaces a previously filed reconciliation. Amend online at tap.utah.gov. Reopen the reconciliation in your online account, click the amended box, make any corrections, and resubmit the reconciliation. Submit only new or corrected W-2s and 1099s.
Late and/or Incorrect Filings We will assess a penalty if you:
- fail to file a complete an accurate reconciliation by January 31 (see Due Dates),
- do not correctly prepare your W-2s or 1099s (see W-2 and 1099 Requirements), or
- are an employer and do not file electronically.
See Penalties and Interest, below.
Also see Online Filing and Paying of Withholding Tax, at Balancing the Reconciliation If the total Utah taxes withheld as reported on forms W-2 and 1099 does not match the total Utah taxes reported on your quarterly or annual withholding return(s), your reconciliation is unbalanced and must be fixed.
# Single Account Number
If you file Utah withholding under a single account number, balance your reconciliation following these steps:
- Review your records and find the error.
- File an amended withholding tax return(s) to correct the error.
- File your reconciliation showing the corrected amounts and ensure that everything balances. Withholding reported for all periods must equal the Utah withholding shown on all W-2 and 1099 forms.
- If you underpaid one or more periods, pay the additional tax due with the amended return, plus interest from the original due date for the period. See Pub 58, Utah Interest and Penalties. Pay online at tap.utah.gov, or if you are mailing a check, include the TC-941PC payment coupon.
- If you overpaid one or more periods, send a letter to the Tax Commission with your account number, name, contact information, an explanation of the error, and if you would like the overpayment refunded or applied to another tax period.
# Multiple Account Numbers
If you reported and paid Utah withholding tax under multiple account numbers, balance your reconciliation following these steps:
- On forms W-2 and 1099, use the Utah account number directly associated with the EIN also used on the withholding documents.
- File a reconciliation for each account, reporting what was filed and paid in the quarters for the account.
- On the reconciliation for each account, report and electronically file the state copy of the W-2s and 1099s issued for the account.
- Complete and submit a paper form TC-941D, Discrepancy Report, to show that the total amounts of Utah tax withheld on all your account balances with the W-2s and 1099s issued.
Fax the completed TC-941D to 801-297-6357, or mail to:
Technical Research Unit
210 N 1950 W
Salt Lake City, UT 84134-7000
Withholding Filing Record
Keep a record of taxes withheld and paid to the Tax Commission for at least four years from the due date of the income tax return reporting wages.
# Due Dates
Anything with a due date that falls on a Saturday, Sunday or legal holiday is due the next business day.
Utah does not follow the federal withholding payment periods.
Utah only requires that payments be made monthly, quarterly or annually. The IRS semiweekly deposit and $100,000 next day deposit rules do not apply to Utah withholding taxes.
# Annual Returns with Annual Payments
If you report federal household employment taxes for household employees on federal form 1040, Schedule H, or file federal form 944, you can pay Utah withholding taxes for these same employees annually. The Utah return and payment are due January 31 after the year wages were paid.
Quarterly Returns with Quarterly Payments If you withhold less than $1,000 each month, file and pay your Utah withholding taxes quarterly. Quarterly returns and payments are due by the last day of the month after the quarter ends, as follows:
Quarterly Filing Period Due Date January - March April 30 April - June July 31 July - September October 31 October - December January 31 Quarterly filers may voluntarily change to quarterly returns with monthly payments. See Filing Status Changes in this publication.
Quarterly Returns with Monthly Payments If you withhold $1,000 or more each month, you must file quarterly, but pay your Utah withholding taxes monthly. Payments are due the last day of the following month:
Monthly Pmt. Period Due Date
January February 28 (or 29)
February March 31
March April 30
April May 31
May June 30
June July 31
July August 31
August September 30
September October 31
October November 30
November December 31
December January 31
# Annual Reconciliations, W-2s and 1099s
You must file electronically by January 31.
File copies of all forms W-2 and 1099 issued to employees and payees with your reconciliation.
Note: We will not issue income tax refunds to your employees before March 1 unless you electronically file your complete reconciliation by January 31 (see Utah Code §59-10-529.1). You must file an annual reconciliation if your account is open for any part of the year.
# Filing Status Changes
The Tax Commission reviews each withholding account annually to determine if the reporting and payment periods should change (based on the previous year's filings). Quarterly payers may voluntarily change to paying monthly by submitting a written request by fax to 801-297-7579 or by mail to:
Exceptions Processing
210 N 1950 W
Salt Lake City, UT 84134-3310
# W-2 and 1099 Requirements
By January 31 you must give all employees a legible W-2 or 1099 form showing taxes withheld during the previous year.
In addition to federal requirements, wage and earning documents reporting Utah income or withholding must include the following information:
- Your federal Employer Identification Number (EIN).
- The recipient's federal Employer Identification Number (EIN or SSN).
- Your Utah withholding account number - the 14-digit number ending in WTH. (If this number won't fit in the space on your W-2 form, you may leave out the dashes in the account number.)
- The amount of income from Utah sources.
- The amount of Utah taxes withheld, if any.
Failure to provide all required information on W-2s and 1099s may result in penalties.
For other Utah withholding requirements information, call 801-297-3811 or TDD 801-297-2020.
# Amending W-2s
You must file electronically.
If you reported incorrect information on an employee's W-2, you must file a corrected W-2. File the correction as a W-2c.
Only file W-2cs for the W-2s you are correcting. When entering the data on the W-2c, only enter information in the fields you are changing.
Penalties and Interest
Late Filing and Late Payments We may assess late filing and late payment penalties on non- and late-filed returns and payments made after the due date. See Pub 58, Utah Interest and Penalties.
The withholding penalty structure is:
Days Late Penalty Amount - Greater of 1-5 $20 or 2% of the outstanding tax 6-15 $20 or 5% of the outstanding tax 16 or more $20 or 10% of the outstanding tax Penalties are assessed for failing to file a tax due return and failing to pay tax due. A second penalty will be applied if the tax is still unpaid 90 days after the due date.
Submitting incorrect forms or forms with missing information may also result in penalties. See Pub 58, Utah Interest and Penalties.
# Annual Reconciliation
We may assess penalties if you fail to file an annual reconciliation electronically, accurately and completely by January 31 (see Utah Code §§59-1-401(8) and 59-1-401(13)).
The penalties are:
- $50 for an annual reconciliation filed more than 14 days late; or
- $30 for each W-2 and 1099 between 15 and 30 days late (up to $75,000);
- $60 for each W-2 and 1099 filed between 31 days late and June 1 (up to $200,000); and
- $100 for each W-2 and 1099 filed after June 1 (up to $500,000).
Interest
The interest rate for all taxes and fees is two percentage points above the federal short-term rate for the prior fourth calendar quarter. See Pub 58, Utah Interest and Penalties.
# Changing or Closing an Account
Use TC-69C, Notice of Change for a Tax Account, to:
- Report changes to your business or mailing address
- Change your business name
- Notify the Tax Commission you have changed your business ownership status
- Close your account
Get forms online at tax.utah.gov/forms.
You must close your Utah withholding account and open a new account if your EIN changes with the IRS (for example, you change from a sole proprietor to partnership). Use form TC-69 to open an account with your new EIN.
You must close your account if you sell your business or stop doing business in Utah. If you do not close your account, we will assess an estimated tax, including late penalties and interest. Withholding licenses are not transferable.
Agencies
Contact the following agencies for more information about state and federal withholding requirements.
Internal Revenue Service
# Self-Employment Tax
801-799-6963
1-800-829-1040 (for individuals) 1-800-829-4933 (for businesses) www.irs.gov
# Forms and Publications
1-800-829-3676 www.irs.gov/Forms-&-Pubs
# Utah Income Tax Withholding
801-297-2200
1-800-662-4335
# Employment Tax Workshops
Small Business Development Center clients.utahsbdc.org/events.aspx 801-957-5441 Social Security Administration 866-851-5275 1-800-772-1213 socialsecurity.gov/employer Utah Dept. of Workforce Services
# Unemployment Compensation
801-526-9235
1-800-222-2857 jobs.utah.gov/ui/jobseeker/contactus.html Labor Commission of Utah Worker's Compensation 801-530-6800 1-800-530-5090 laborcommission.utah.gov
Utah Withholding Taxes Calendar The following is a list of important Utah withholding tax NOTE: Returns and full payment must be submitted by the dates. (See federal dates in IRS Publication 15.) due date (or next business day if the due date falls on Saturday, Sunday or a legal holiday).
All Employers
Due Date Monthly Payers Quarterly Payers Annual Payers Give forms W-2 and 1099
January 31
Electronically file fourth Electronically file and Electronically file and pay to employees and payees. quarter return and pay December withholding tax onpay fourth quarter with- annual withholding tax onholding tax online at line at tap.utah.gov, or pay Electronically file annual line at tap.utah.gov, or pay tap.utah.gov, or pay by by check with TC-941PC reconciliation (including by check with TC-941PC check with TC-941PC W-2s and 1099s).
February 28
March 31 end of first quarter
April 30
May 31
June 30 end of second quarter
July 31
August 31
September 30 end of third quarter
October 31
November 30
December 31 end of fourth quarter Pay January withholding tax online at tap.utah.gov, or by check with TC-941PC Pay February withholding tax online at tap.utah.gov, or by check with TC-941PC Electronically file first quarter return and pay March withholding tax online at tap.utah.gov, or pay by check with Pay April withholding tax online at tap.utah.gov, or by check with TC-941PC Pay May withholding tax online at tap.utah.gov, or by check with TC-941PC Electronically file second quarter return and pay June withholding tax online at tap.utah.gov, or pay by check with TC-941PC Pay July withholding tax online at tap.utah.gov, or by check with TC-941PC Pay August withholding tax online at tap.utah.gov, or by check with TC-941PC Electronically file third quarter return and pay September withholding tax online at tap.utah.gov, or pay by check with Pay October withholding tax online at tap.utah.gov, or by check with TC-941PC Pay November withholding tax online at tap.utah.gov, or by check with TC-941PC Electronically file and pay first quarter withholding tax online at tap.utah. gov, or pay by check with Electronically file and pay second quarter withholding tax online at tap.utah. gov, or pay by check with Electronically file and pay third quarter withholding tax online at tap.utah. gov, or pay by check with
Utah Withholding Schedules
Instructions
Follow the instructions below to compute the employee's Utah income tax withholding.
Number of pay
If pay period is periods annually Use schedule Weekly 52 Schedule 1 Biweekly 26 Schedule 2 Semimonthly 24 Schedule 3
- Find the appropriate Utah Schedule based on the payroll period (see following chart) and the employee's filing status shown on federal W-4 form. a) Enter on line 1 the Utah taxable wages. b) Follow the instructions for each line to complete the withholding tax calculation.
Monthly 12 Schedule 4
Quarterly 4 Schedule 5
Semiannual 2 Schedule 6
Annual 1 Schedule 7
Daily Daily Schedule 8
- Line 7 of the calculation is the Utah withholding tax for the pay period.
See examples, below.
If you have questions about the withholding schedules, contact:
Taxpayer Services
210 North 1950 West
Salt Lake City, UT 84134
801-297-7705
1-800-662-4335 ext. 7705
8WDK6FKHGXOH :((./<Payroll Period (52 pay periods per year)
# Single
- Utah taxable wages
- Multiply line 1 by .0465 (4.65%)
- Base allowance 8
- Line 1 minus $161 (not less than 0)
- Multiply line 4 by .013 (1.3%)
- Line 3 minus line 5 (not less than 0)
- Withholding tax line 2 minus line 6 (not less than 0) 8WDK6FKHGXOH
# Married
- Utah taxable wages
- Multiply line 1 by .0465 (4.65%)
- Base allowance 16
- Line 1 minus $322 (not less than 0)
- Multiply line 4 by .013 (1.3%)
- Line 3 minus line 5 (not less than 0)
- Withholding tax line 2 minus line 6 (not less than 0) %,:((./<Payroll Period (26 pay periods per year)
# Single
- Utah taxable wages
- Multiply line 1 by .0465 (4.65%)
- Base allowance 16
- Line 1 minus $322 (not less than 0)
- Multiply line 4 by .013 (1.3%)
- Line 3 minus line 5 (not less than 0)
- Withholding tax line 2 minus line 6 (not less than 0) 8WDK6FKHGXOH
# Married
- Utah taxable wages
- Multiply line 1 by .0465 (4.65%)
- Base allowance 32
- Line 1 minus $644 (not less than 0)
- Multiply line 4 by .013 (1.3%)
- Line 3 minus line 5 (not less than 0)
- Withholding tax line 2 minus line 6 (not less than 0) 6(0,0217+/<Payroll Period (24 pay periods per year)
# Single
- Utah taxable wages
- Multiply line 1 by .0465 (4.65%)
- Base allowance 17
- Line 1 minus $349 (not less than 0)
- Multiply line 4 by .013 (1.3%)
- Line 3 minus line 5 (not less than 0)
- Withholding tax line 2 minus line 6 (not less than 0) 8WDK6FKHGXOH
# Married
- Utah taxable wages
- Multiply line 1 by .0465 (4.65%)
- Base allowance 35
- Line 1 minus $698 (not less than 0)
- Multiply line 4 by .013 (1.3%)
- Line 3 minus line 5 (not less than 0)
- Withholding tax line 2 minus line 6 (not less than 0) 0217+/<Payroll Period (12 pay periods per year)
# Single
- Utah taxable wages
- Multiply line 1 by .0465 (4.65%)
- Base allowance 35
- Line 1 minus $698 (not less than 0)
- Multiply line 4 by .013 (1.3%)
- Line 3 minus line 5 (not less than 0)
- Withholding tax line 2 minus line 6 (not less than 0)
# Married
- Utah taxable wages
- Multiply line 1 by .0465 (4.65%)
- Base allowance 69
- Line 1 minus $1,395 (not less than 0)
- Multiply line 4 by .013 (1.3%)
- Line 3 minus line 5 (not less than 0)
- Withholding tax line 2 minus line 6 (not less than 0)
8WDK6FKHGXOH 48$57(5/<Payroll Period (4 pay periods per year)
# Single
- Utah taxable wages
- Multiply line 1 by .0465 (4.65%)
- Base allowance 104
- Line 1 minus $2,093 (not less than 0)
- Multiply line 4 by .013 (1.3%)
- Line 3 minus line 5 (not less than 0)
- Withholding tax line 2 minus line 6 (not less than 0) 8WDK6FKHGXOH
# Married
- Utah taxable wages
- Multiply line 1 by .0465 (4.65%)
- Base allowance 208
- Line 1 minus $4,186 (not less than 0)
- Multiply line 4 by .013 (1.3%)
- Line 3 minus line 5 (not less than 0)
- Withholding tax line 2 minus line 6 (not less than 0) 6(0,$118$/Payroll Period (2 pay periods per year)
# Single
- Utah taxable wages
- Multiply line 1 by .0465 (4.65%)
- Base allowance 208
- Line 1 minus $4,186 (not less than 0)
- Multiply line 4 by .013 (1.3%)
- Line 3 minus line 5 (not less than 0)
- Withholding tax line 2 minus line 6 (not less than 0) 8WDK6FKHGXOH
# Married
- Utah taxable wages
- Multiply line 1 by .0465 (4.65%)
- Base allowance 415
- Line 1 minus $8,371 (not less than 0)
- Multiply line 4 by .013 (1.3%)
- Line 3 minus line 5 (not less than 0)
- Withholding tax line 2 minus line 6 (not less than 0) $118$/Payroll Period (1 pay period per year)
# Single
- Utah taxable wages
- Multiply line 1 by .0465 (4.65%)
- Base allowance 415
- Line 1 minus $8,371 (not less than 0)
- Multiply line 4 by .013 (1.3%)
- Line 3 minus line 5 (not less than 0)
- Withholding tax line 2 minus line 6 (not less than 0) 8WDK6FKHGXOH
# Married
- Utah taxable wages
- Multiply line 1 by .0465 (4.65%)
- Base allowance 830
- Line 1 minus $16,742 (not less than 0)
- Multiply line 4 by .013 (1.3%)
- Line 3 minus line 5 (not less than 0)
- Withholding tax line 2 minus line 6 (not less than 0) '$,/<or 0,6&(//$1(286 Payroll Period
# Single
- Utah taxable wages
- Multiply line 1 by .0465 (4.65%)
- Base allowance 2
- Line 1 minus $32 (not less than 0)
- Multiply line 4 by .013 (1.3%)
- Line 3 minus line 5 (not less than 0)
- Withholding tax line 2 minus line 6 (not less than 0)
# Married
- Utah taxable wages
- Multiply line 1 by .0465 (4.65%)
- Base allowance 3
- Line 1 minus $64 (not less than 0)
- Multiply line 4 by .013 (1.3%)
- Line 3 minus line 5 (not less than 0)
- Withholding tax line 2 minus line 6 (not less than 0)
Examples of Utah Withholding Calculations The following examples show different combinations of pay period, taxable wages and filing status.
# Example 1 - Use Schedule 1, Weekly/Single
Payroll Period Weekly
Filing Status Single
Utah Taxable Wages $400
- Utah taxable wages
- Multiply line 1 by .0465 (4.65%)
- Base allowance
- Line 1 less $161 (not less than 0)
- Multiply line 4 by .013 (1.3%)
- Line 3 less line 5 (not less than 0)
- Withholding tax - line 2 less line 6
# Example 4 - Use Schedule 4, Monthly/Married
Payroll Period Monthly
Filing Status Married
Utah Taxable Wages $2,500
- Utah taxable wages 2,500
- Multiply line 1 by .0465 (4.65%) 116
- Base allowance 69
- Line 1 less $1,395 (not less than 0) 1,105
- Multiply line 4 by .013 (1.3%) 14
- Line 3 less line 5 (not less than 0) 55
- Withholding tax - line 2 less line 6 61
# Example 2 - Use Schedule 2, Biweekly/Single
Payroll Period Biweekly
Filing Status Single
Utah Taxable Wages $1,000
- Utah taxable wages
- Multiply line 1 by .0465 (4.65%)
- Base allowance
- Line 1 less $322 (not less than 0)
- Multiply line 4 by .013 (1.3%)
- Line 3 less line 5 (not less than 0)
- Withholding tax - line 2 less line 6 1,000
# Example 5 - Use Schedule 5, Quarterly/Single
Payroll Period Quarterly
Filing Status Single
Utah Taxable Wages $8,000
- Utah taxable wages 8,000
- Multiply line 1 by .0465 (4.65%) 372
- Base allowance 104
- Line 1 less $2,093 (not less than 0) 5,907
- Multiply line 4 by .013 (1.3%) 77
- Line 3 less line 5 (not less than 0) 27
- Withholding tax - line 2 less line 6 345 Example 3 - Use Schedule 3, Semimonthly/Married Example 6 - Use Schedule 8, Daily/Married
Semimonthly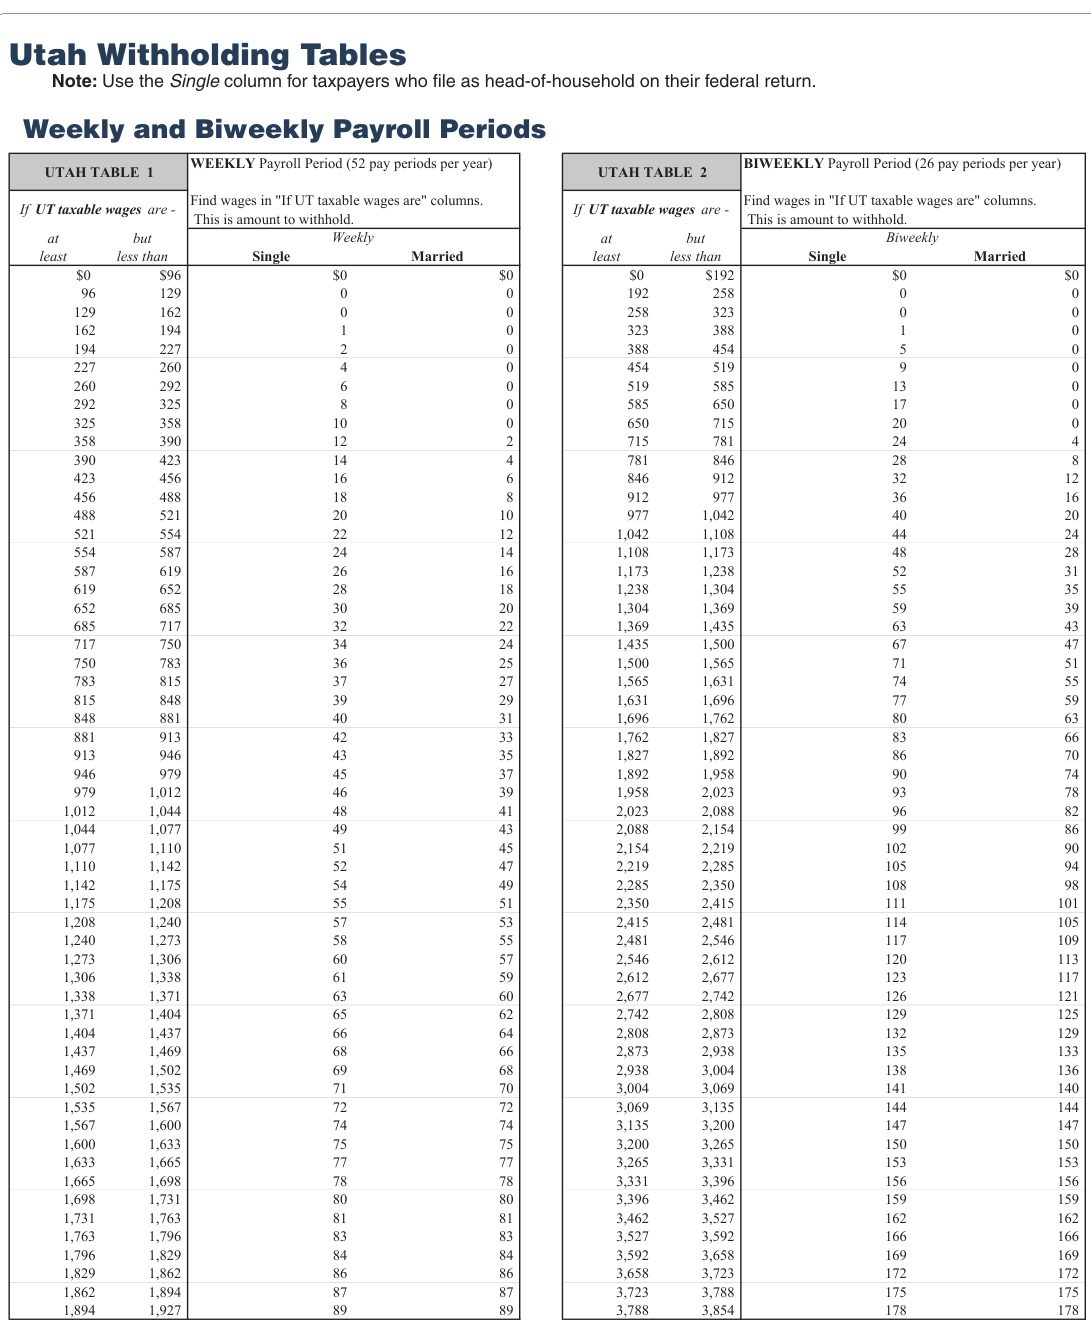
Text version of this table
ah Wit hholding Ta bles Note: Use t he Single column fo r tax payers who file as h ead-of-househo ld on their federal return. eekly a nd Biweek ly Payroll Period Daily ods WEEKLY Payroll Perio d (52 pay periods per year) BIWEEKLY Payr oll Period (26 pay periods per year ) TAH TABLE 1 UT AH TABLE 2 1. Utah taxable wages 150 Find wages in "If U are - T tax able wages are" columns. If UT t axable wages Find wages in "If are - UT taxable wages are" columns. This is amount to withh old. This is amount to withhold. t bu t Weekly at bu t Biweekly ast less t han Single Married leas t less t han Single Married $0 $96 $0 $0 $0 $192 $0 $0 96 129 0 0 192 258 0 0 129 162 0 0 258 323 0 0 162 194 1 0 323 388 1 0 194 227 2 0 388 454 5 0 227 260 4 0 454 519 9 0 260 292 6 0 519 585 13 0 292 325 8 0 585 650 17 0 325 358 10 0 650 715 20 0 358 390 12 2 715 781 24 4 390 423 14 4 781 846 28 8 423 456 16 6 846 912 32 12 456 488 18 8 912 977 36 16 488 521 20 10 977 1,042 40 20 521 554 22 12 1,042 1,108 44 24 554 587 24 14 1,108 1,173 48 28 587 619 26 16 1,173 1,238 52 31 619 652 28 18 1,238 1,304 55 35 652 685 30 20 1,304 1,369 59 39 685 717 32 22 1,369 1,435 63 43 717 750 34 24 1,435 1,500 67 47 750 783 36 25 1,500 1,565 71 51 783 815 37 27 1,565 1,631 74 55 815 848 39 29 1,631 1,696 77 59 848 881 40 31 1,696 1,762 80 63 881 913 42 33 1,762 1,827 83 66 913 946 43 35 1,827 1,892 86 70 946 979 45 37 1,892 1,958 90 74 979 1,012 46 39 1,958 2,023 93 78 1,012 1,044 48 41 2,023 2,088 96 82 1,044 1,077 49 43 2,088 2,154 99 86 1,077 1,110 51 45 2,154 2,219 102 90 1,110 1,142 52 47 2,219 2,285 105 94 1,142 1,175 54 49 2,285 2,350 108 98 1,175 1,208 55 51 2,350 2,415 111 101 1,208 1,240 57 53 2,415 2,481 114 105 1,240 1,273 58 55 2,481 2,546 117 109 1,273 1,306 60 57 2,546 2,612 120 113 1,306 1,338 61 59 2,612 2,677 123 117 1,338 1,371 63 60 2,677 2,742 126 121 1,371 1,404 65 62 2,742 2,808 129 125 1,404 1,437 66 64 2,808 2,873 132 129 1,437 1,469 68 66 2,873 2,938 135 133 1,469 1,502 69 68 2,938 3,004 138 136 1,502 1,535 71 70 3,004 3,069 141 140 1,535 1,567 72 72 3,069 3,135 144 144 1,567 1,600 74 74 3,135 3,200 147 147 1,600 1,633 75 75 3,200 3,265 150 150 1,633 1,665 77 77 3,265 3,331 153 153 1,665 1,698 78 78 3,331 3,396 156 156 1,698 1,731 80 80 3,396 3,462 159 159 1,731 1,763 81 81 3,462 3,527 162 162 1,763 1,796 83 83 3,527 3,592 166 166 1,796 1,829 84 84 3,592 3,658 169 169 1,829 1,862 86 86 3,658 3,723 172 172 1,862 1,894 87 87 3,723 3,788 175 175 1,894 1,927 89 89 3,788 3,854 178 178
# Single
# Married
# Single Married
# Semimonthly and Monthly Payroll Periods
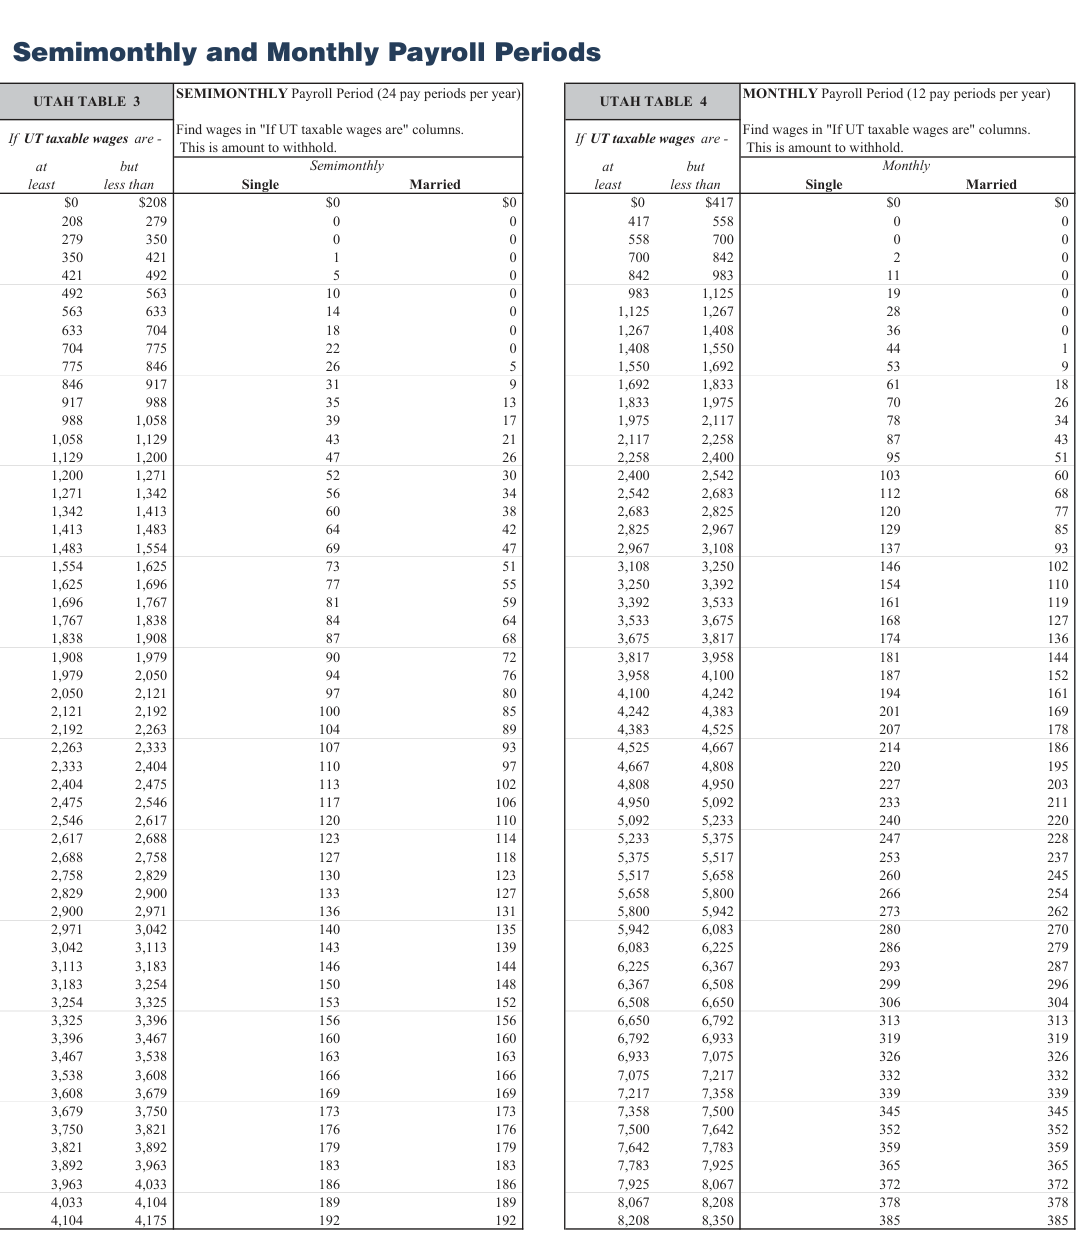
Text version of this table
| mimo | nthly and Mon | thly | Payroll | Periods | ||||
| SEMIMONTHLY Payr | oll Period (2 | 4 pay periods per | year) | MONTHLY Payroll Pe | riod (12 pay periods per year | ) | ||
| AH TABLE | 3 | UT | AH TABLE | 4 | ||||
| axable wages | Find wages in "If UT tax are - | able wages | are" columns. | If UT t | axable wages | Find wages in "If UT ta are - | xable wages are" columns. | |
| This is amount to withh | old. | This is amount to withh | old. | |||||
| bu | t S | emimonthly | at | bu | t | Monthly | ||
| t less t | han Single | Married | leas | t less t | han Single | Married | ||
| $0 | $208 | $0 | $0 | $0 | $417 | $0 | $0 | |
| 208 | 279 | 0 | 0 | 417 | 558 | 0 | 0 | |
| 279 | 350 | 0 | 0 | 558 | 700 | 0 | 0 | |
| 350 | 421 | 1 | 0 | 700 | 842 | 2 | 0 | |
| 421 | 492 | 5 | 0 | 842 | 983 | 11 | 0 | |
| 492 | 563 | 10 | 0 | 983 | 1,125 | 19 | 0 | |
| 563 | 633 | 14 | 0 | 1,125 | 1,267 | 28 | 0 | |
| 633 | 704 | 18 | 0 | 1,267 | 1,408 | 36 | 0 | |
| 704 | 775 | 22 | 0 | 1,408 | 1,550 | 44 | 1 | |
| 775 | 846 | 26 | 5 | 1,550 | 1,692 | 53 | 9 | |
| 846 | 917 | 31 | 9 | 1,692 | 1,833 | 61 | 18 | |
| 917 | 988 | 35 | 13 | 1,833 | 1,975 | 70 | 26 | |
| 988 | 1,058 | 39 | 17 | 1,975 | 2,117 | 78 | 34 | |
| 1,058 | 1,129 | 43 | 21 | 2,117 | 2,258 | 87 | 43 | |
| 1,129 | 1,200 | 47 | 26 | 2,258 | 2,400 | 95 | 51 | |
| 1,200 | 1,271 | 52 | 30 | 2,400 | 2,542 | 103 | 60 | |
| 1,271 | 1,342 | 56 | 34 | 2,542 | 2,683 | 112 | 68 | |
| 1,342 | 1,413 | 60 | 38 | 2,683 | 2,825 | 120 | 77 | |
| 1,413 | 1,483 | 64 | 42 | 2,825 | 2,967 | 129 | 85 | |
| 1,483 | 1,554 | 69 | 47 | 2,967 | 3,108 | 137 | 93 | |
| 1,554 | 1,625 | 73 | 51 | 3,108 | 3,250 | 146 | 102 | |
| 1,625 | 1,696 | 77 | 55 | 3,250 | 3,392 | 154 | 110 | |
| 1,696 | 1,767 | 81 | 59 | 3,392 | 3,533 | 161 | 119 | |
| 1,767 | 1,838 | 84 | 64 | 3,533 | 3,675 | 168 | 127 | |
| 1,838 | 1,908 | 87 | 68 | 3,675 | 3,817 | 174 | 136 | |
| 1,908 | 1,979 | 90 | 72 | 3,817 | 3,958 | 181 | 144 | |
| 1,979 | 2,050 | 94 | 76 | 3,958 | 4,100 | 187 | 152 | |
| 2,050 | 2,121 | 97 | 80 | 4,100 | 4,242 | 194 | 161 | |
| 2,121 | 2,192 | 100 | 85 | 4,242 | 4,383 | 201 | 169 | |
| 2,192 | 2,263 | 104 | 89 | 4,383 | 4,525 | 207 | 178 | |
| 2,263 | 2,333 | 107 | 93 | 4,525 | 4,667 | 214 | 186 | |
| 2,333 | 2,404 | 110 | 97 | 4,667 | 4,808 | 220 | 195 | |
| 2,404 | 2,475 | 113 | 102 | 4,808 | 4,950 | 227 | 203 | |
| 2,475 | 2,546 | 117 | 106 | 4,950 | 5,092 | 233 | 211 | |
| 2,546 | 2,617 | 120 | 110 | 5,092 | 5,233 | 240 | 220 | |
| 2,617 | 2,688 | 123 | 114 | 5,233 | 5,375 | 247 | 228 | |
| 2,688 | 2,758 | 127 | 118 | 5,375 | 5,517 | 253 | 237 | |
| 2,758 | 2,829 | 130 | 123 | 5,517 | 5,658 | 260 | 245 | |
| 2,829 | 2,900 | 133 | 127 | 5,658 | 5,800 | 266 | 254 | |
| 2,900 | 2,971 | 136 | 131 | 5,800 | 5,942 | 273 | 262 | |
| 2,971 | 3,042 | 140 | 135 | 5,942 | 6,083 | 280 | 270 | |
| 3,042 | 3,113 | 143 | 139 | 6,083 | 6,225 | 286 | 279 | |
| 3,113 | 3,183 | 146 | 144 | 6,225 | 6,367 | 293 | 287 | |
| 3,183 | 3,254 | 150 | 148 | 6,367 | 6,508 | 299 | 296 | |
| 3,254 | 3,325 | 153 | 152 | 6,508 | 6,650 | 306 | 304 | |
| 3,325 | 3,396 | 156 | 156 | 6,650 | 6,792 | 313 | 313 | |
| 3,396 | 3,467 | 160 | 160 | 6,792 | 6,933 | 319 | 319 | |
| 3,467 | 3,538 | 163 | 163 | 6,933 | 7,075 | 326 | 326 | |
| 3,538 | 3,608 | 166 | 166 | 7,075 | 7,217 | 332 | 332 | |
| 3,608 | 3,679 | 169 | 169 | 7,217 | 7,358 | 339 | 339 | |
| 3,679 | 3,750 | 173 | 173 | 7,358 | 7,500 | 345 | 345 | |
| 3,750 | 3,821 | 176 | 176 | 7,500 | 7,642 | 352 | 352 | |
| 3,821 | 3,892 | 179 | 179 | 7,642 | 7,783 | 359 | 359 | |
| 3,892 | 3,963 | 183 | 183 | 7,783 | 7,925 | 365 | 365 | |
| 3,963 | 4,033 | 186 | 186 | 7,925 | 8,067 | 372 | 372 | |
| 4,033 | 4,104 | 189 | 189 | 8,067 | 8,208 | 378 | 378 | |
| 4,104 | 4,175 | 192 | 192 | 8,208 | 8,350 | 385 | 385 |
# Single Married
# Single Married
# Quarterly and Semiannual Payroll Periods
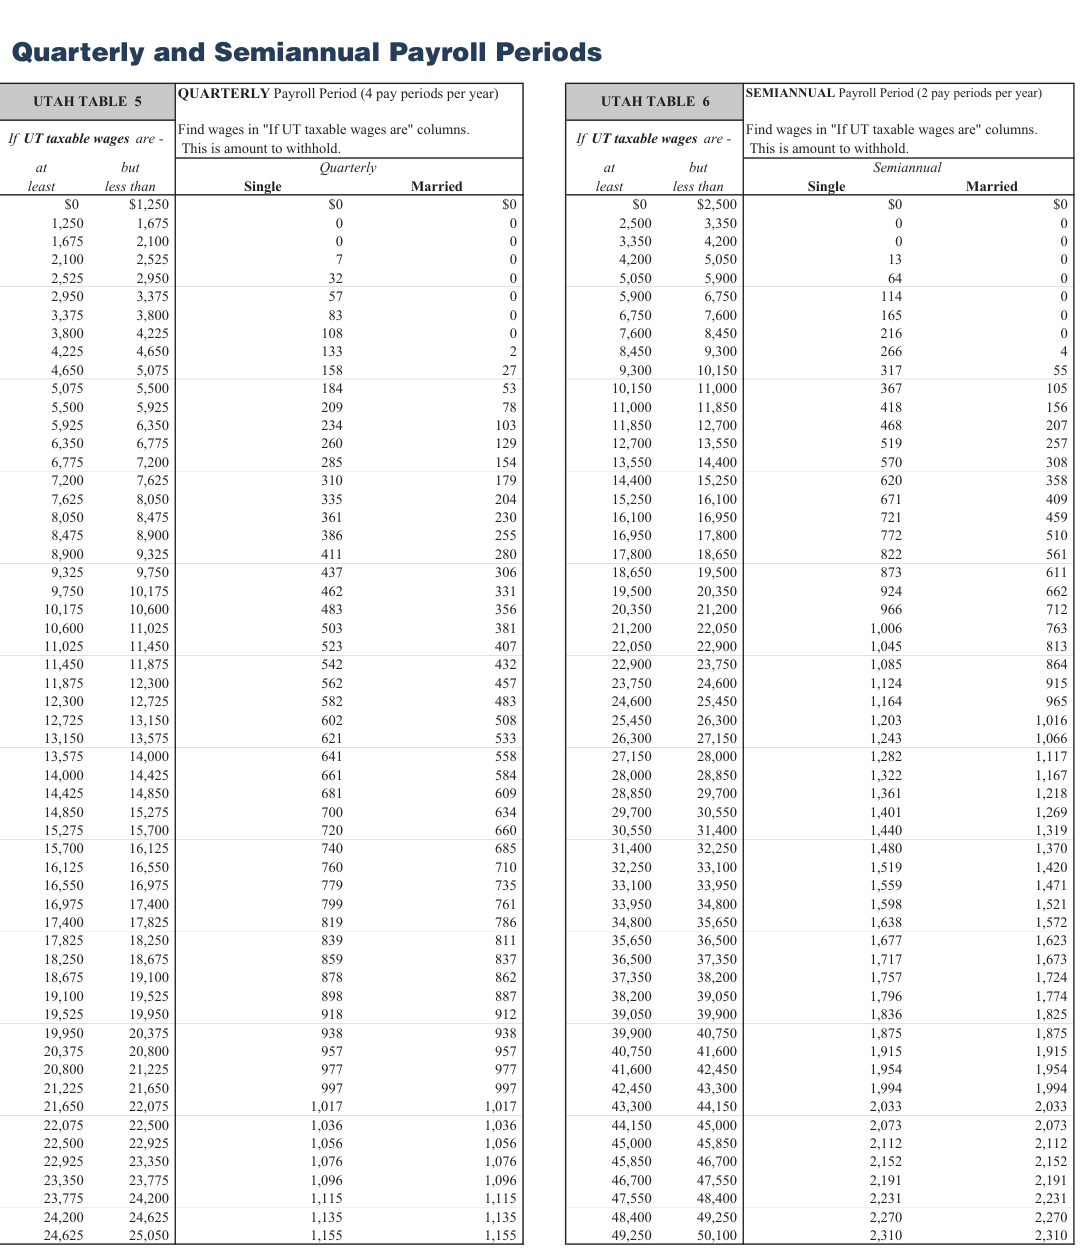
Text version of this table
| arterl | y | and Semi | annual Payroll | Periods | ||||
| QUARTERLY Pa | yroll Period (4 pay periods per ye | ar) | SEMIANNUAL Payro | ll Period (2 pay periods per yea | r) | |||
| TAH TABLE | 5 | U | TAH TABLE | 6 | ||||
| taxable wages | are | Find wages in "If - | UT taxable wages are" columns. | If UT | taxable wages | Find wages in "If UT are - | taxable wages are" columns | . |
| This is amount to | withhold. | This is amount to wi | thhold. | |||||
| t b | ut | Quarterly | a | t b | ut | Semiannual | ||
| st less | than | Single | Married | lea | st less | than Single | Married | |
| $0 | $1,2 | 50 | $0 | $0 | $0 | $2,500 | $0 | $0 |
| 1,250 | 1,6 | 75 | 0 | 0 | 2,500 | 3,350 | 0 | 0 |
| 1,675 | 2,1 | 00 | 0 | 0 | 3,350 | 4,200 | 0 | 0 |
| 2,100 | 2,5 | 25 | 7 | 0 | 4,200 | 5,050 | 13 | 0 |
| 2,525 | 2,9 | 50 | 32 | 0 | 5,050 | 5,900 | 64 | 0 |
| 2,950 | 3,3 | 75 | 57 | 0 | 5,900 | 6,750 | 114 | 0 |
| 3,375 | 3,8 | 00 | 83 | 0 | 6,750 | 7,600 | 165 | 0 |
| 3,800 | 4,2 | 25 | 108 | 0 | 7,600 | 8,450 | 216 | 0 |
| 4,225 | 4,6 | 50 | 133 | 2 | 8,450 | 9,300 | 266 | 4 |
| 4,650 | 5,0 | 75 | 158 | 27 | 9,300 | 10,150 | 317 | 55 |
| 5,075 | 5,5 | 00 | 184 | 53 | 10,150 | 11,000 | 367 | 105 |
| 5,500 | 5,9 | 25 | 209 | 78 | 11,000 | 11,850 | 418 | 156 |
| 5,925 | 6,3 | 50 | 234 | 103 | 11,850 | 12,700 | 468 | 207 |
| 6,350 | 6,7 | 75 | 260 | 129 | 12,700 | 13,550 | 519 | 257 |
| 6,775 | 7,2 | 00 | 285 | 154 | 13,550 | 14,400 | 570 | 308 |
| 7,200 | 7,6 | 25 | 310 | 179 | 14,400 | 15,250 | 620 | 358 |
| 7,625 | 8,0 | 50 | 335 | 204 | 15,250 | 16,100 | 671 | 409 |
| 8,050 | 8,4 | 75 | 361 | 230 | 16,100 | 16,950 | 721 | 459 |
| 8,475 | 8,9 | 00 | 386 | 255 | 16,950 | 17,800 | 772 | 510 |
| 8,900 | 9,3 | 25 | 411 | 280 | 17,800 | 18,650 | 822 | 561 |
| 9,325 | 9,7 | 50 | 437 | 306 | 18,650 | 19,500 | 873 | 611 |
| 9,750 | 10,1 | 75 | 462 | 331 | 19,500 | 20,350 | 924 | 662 |
| 10,175 | 10,6 | 00 | 483 | 356 | 20,350 | 21,200 | 966 | 712 |
| 10,600 | 11,0 | 25 | 503 | 381 | 21,200 | 22,050 | 1,006 | 763 |
| 11,025 | 11,4 | 50 | 523 | 407 | 22,050 | 22,900 | 1,045 | 813 |
| 11,450 | 11,8 | 75 | 542 | 432 | 22,900 | 23,750 | 1,085 | 864 |
| 11,875 | 12,3 | 00 | 562 | 457 | 23,750 | 24,600 | 1,124 | 915 |
| 12,300 | 12,7 | 25 | 582 | 483 | 24,600 | 25,450 | 1,164 | 965 |
| 12,725 | 13,1 | 50 | 602 | 508 | 25,450 | 26,300 | 1,203 | 1,016 |
| 13,150 | 13,5 | 75 | 621 | 533 | 26,300 | 27,150 | 1,243 | 1,066 |
| 13,575 | 14,0 | 00 | 641 | 558 | 27,150 | 28,000 | 1,282 | 1,117 |
| 14,000 | 14,4 | 25 | 661 | 584 | 28,000 | 28,850 | 1,322 | 1,167 |
| 14,425 | 14,8 | 50 | 681 | 609 | 28,850 | 29,700 | 1,361 | 1,218 |
| 14,850 | 15,2 | 75 | 700 | 634 | 29,700 | 30,550 | 1,401 | 1,269 |
| 15,275 | 15,7 | 00 | 720 | 660 | 30,550 | 31,400 | 1,440 | 1,319 |
| 15,700 | 16,1 | 25 | 740 | 685 | 31,400 | 32,250 | 1,480 | 1,370 |
| 16,125 | 16,5 | 50 | 760 | 710 | 32,250 | 33,100 | 1,519 | 1,420 |
| 16,550 | 16,9 | 75 | 779 | 735 | 33,100 | 33,950 | 1,559 | 1,471 |
| 16,975 | 17,4 | 00 | 799 | 761 | 33,950 | 34,800 | 1,598 | 1,521 |
| 17,400 | 17,8 | 25 | 819 | 786 | 34,800 | 35,650 | 1,638 | 1,572 |
| 17,825 | 18,2 | 50 | 839 | 811 | 35,650 | 36,500 | 1,677 | 1,623 |
| 18,250 | 18,6 | 75 | 859 | 837 | 36,500 | 37,350 | 1,717 | 1,673 |
| 18,675 | 19,1 | 00 | 878 | 862 | 37,350 | 38,200 | 1,757 | 1,724 |
| 19,100 | 19,5 | 25 | 898 | 887 | 38,200 | 39,050 | 1,796 | 1,774 |
| 19,525 | 19,9 | 50 | 918 | 912 | 39,050 | 39,900 | 1,836 | 1,825 |
| 19,950 | 20,3 | 75 | 938 | 938 | 39,900 | 40,750 | 1,875 | 1,875 |
| 20,375 | 20,8 | 00 | 957 | 957 | 40,750 | 41,600 | 1,915 | 1,915 |
| 20,800 | 21,2 | 25 | 977 | 977 | 41,600 | 42,450 | 1,954 | 1,954 |
| 21,225 | 21,6 | 50 | 997 | 997 | 42,450 | 43,300 | 1,994 | 1,994 |
| 21,650 | 22,0 | 75 | 1,017 | 1,017 | 43,300 | 44,150 | 2,033 | 2,033 |
| 22,075 | 22,5 | 00 | 1,036 | 1,036 | 44,150 | 45,000 | 2,073 | 2,073 |
| 22,500 | 22,9 | 25 | 1,056 | 1,056 | 45,000 | 45,850 | 2,112 | 2,112 |
| 22,925 | 23,3 | 50 | 1,076 | 1,076 | 45,850 | 46,700 | 2,152 | 2,152 |
| 23,350 | 23,7 | 75 | 1,096 | 1,096 | 46,700 | 47,550 | 2,191 | 2,191 |
| 23,775 | 24,2 | 00 | 1,115 | 1,115 | 47,550 | 48,400 | 2,231 | 2,231 |
| 24,200 | 24,6 | 25 | 1,135 | 1,135 | 48,400 | 49,250 | 2,270 | 2,270 |
| 24,625 | 25,0 | 50 | 1,155 | 1,155 | 49,250 | 50,100 | 2,310 | 2,310 |
# Single Married
# Single Married
# Annual and Daily/Miscellaneous Payroll Periods
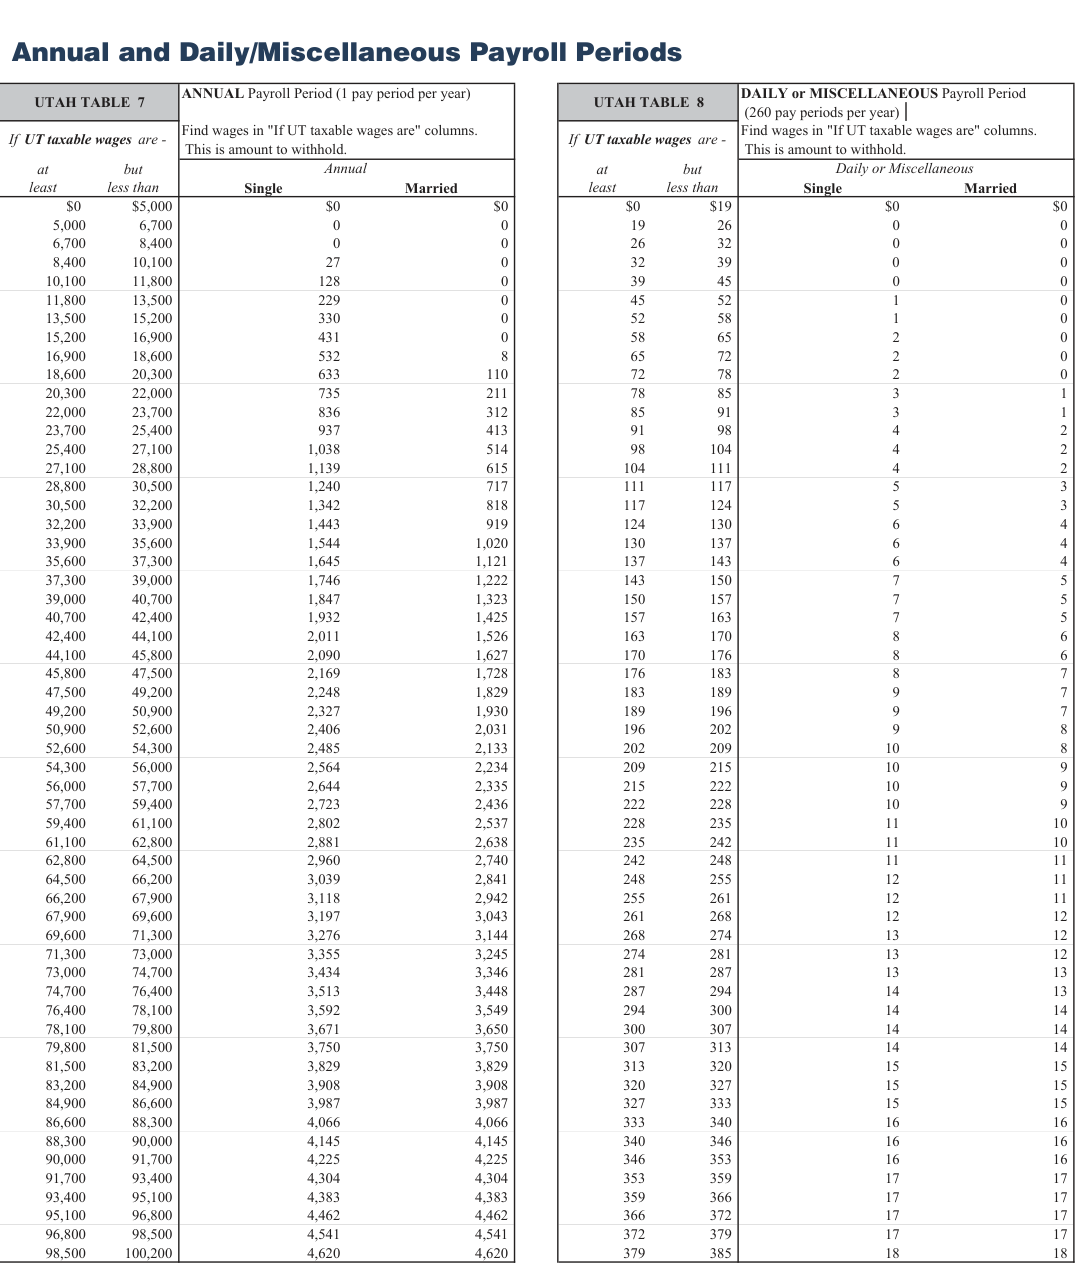
Text version of this table
nual and Daily/Mis cellaneous Payroll Per iods TAH TABL ANNUAL Payroll Pe E 7 riod (1 pay period per year) UTA H TABLE 8 DAILY o r MISCEL LANEOUS Payroll Period (260 pay periods per year) taxable wag Find wages in "If UT es are - taxable wages are" columns . If UT tax able wages ar Find wage e - s in "If UT taxable wages are" columns. This is amount to wi thhold. This is a mount to wit hhold. t but Annual at but Daily or Miscellaneous st le ss than Single Married least less tha n Single Married $0 $5,000 $0 $0 $0 $19 $0 $0 5,000 6,700 0 0 19 26 0 0 6,700 8,400 0 0 26 32 0 0 8,400 10,100 27 0 32 39 0 0 10,100 11,800 128 0 39 45 0 0 11,800 13,500 229 0 45 52 1 0 13,500 15,200 330 0 52 58 1 0 15,200 16,900 431 0 58 65 2 0 16,900 18,600 532 8 65 72 2 0 18,600 20,300 633 110 72 78 2 0 20,300 22,000 735 211 78 85 3 1 22,000 23,700 836 312 85 91 3 1 23,700 25,400 937 413 91 98 4 2 25,400 27,100 1,038 514 98 104 4 2 27,100 28,800 1,139 615 104 111 4 2 28,800 30,500 1,240 717 111 117 5 3 30,500 32,200 1,342 818 117 124 5 3 32,200 33,900 1,443 919 124 130 6 4 33,900 35,600 1,544 1,020 130 137 6 4 35,600 37,300 1,645 1,121 137 143 6 4 37,300 39,000 1,746 1,222 143 150 7 5 39,000 40,700 1,847 1,323 150 157 7 5 40,700 42,400 1,932 1,425 157 163 7 5 42,400 44,100 2,011 1,526 163 170 8 6 44,100 45,800 2,090 1,627 170 176 8 6 45,800 47,500 2,169 1,728 176 183 8 7 47,500 49,200 2,248 1,829 183 189 9 7 49,200 50,900 2,327 1,930 189 196 9 7 50,900 52,600 2,406 2,031 196 202 9 8 52,600 54,300 2,485 2,133 202 209 10 8 54,300 56,000 2,564 2,234 209 215 10 9 56,000 57,700 2,644 2,335 215 222 10 9 57,700 59,400 2,723 2,436 222 228 10 9 59,400 61,100 2,802 2,537 228 235 11 10 61,100 62,800 2,881 2,638 235 242 11 10 62,800 64,500 2,960 2,740 242 248 11 11 64,500 66,200 3,039 2,841 248 255 12 11 66,200 67,900 3,118 2,942 255 261 12 11 67,900 69,600 3,197 3,043 261 268 12 12 69,600 71,300 3,276 3,144 268 274 13 12 71,300 73,000 3,355 3,245 274 281 13 12 73,000 74,700 3,434 3,346 281 287 13 13 74,700 76,400 3,513 3,448 287 294 14 13 76,400 78,100 3,592 3,549 294 300 14 14 78,100 79,800 3,671 3,650 300 307 14 14 79,800 81,500 3,750 3,750 307 313 14 14 81,500 83,200 3,829 3,829 313 320 15 15 83,200 84,900 3,908 3,908 320 327 15 15 84,900 86,600 3,987 3,987 327 333 15 15 86,600 88,300 4,066 4,066 333 340 16 16 88,300 90,000 4,145 4,145 340 346 16 16 90,000 91,700 4,225 4,225 346 353 16 16 91,700 93,400 4,304 4,304 353 359 17 17 93,400 95,100 4,383 4,383 359 366 17 17 95,100 96,800 4,462 4,462 366 372 17 17 96,800 98,500 4,541 4,541 372 379 17 17 98,500 100,200 4,620 4,620 379 385 18 18
$19
# Single Married
Source: view the official PDF
Nearby sections (13 sections)
- pub-14 · Publication 14 — Utah Withholding Tax Guide
- pub-17 · Publication 17 — Waivers, Reasonable Cause
- pub-25 · Publication 25 — Sales and Use Tax General Information
- pub-33 · Publication 33 — Interest from U.S. Obligations, Individual…
- pub-42 · Publication 42 — Sales Tax for Sales, Installation and Repair…
- pub-57 · Publication 57 — Military Personnel Instructions
- pub-58 · Publication 58 — Utah Interest and Penalties
- pub-68 · Publication 68 — Pass-through Entity Withholding
- tc-109-inst · TC-109 Instructions — Fuels Tax Return Excel Template
- tc-20-inst · TC-20 Instructions — Utah Corporation Franchise & Income…
- tc-20mc-inst · TC-20MC Instructions — Tax Return for Misc. Corporations
- tc-20s-inst · TC-20S Instructions — Utah S Corporation Return
- tc-40-fullpacket · TC-40 Full Packet — Utah Individual Income Tax (form…