Nebraska Department of Revenue Forms & Instructions
NE Individual Income Tax Booklet — Form 1040N master instructions
# Nebraska
Individual Income Tax and Amended Return Booklet
# E-file your return.
NebFile offers FREE e-filing of your state return.
All taxpayers can use the Fed/State program to e-file federal and Nebraska tax returns.
File online by purchasing software from a retailer, or with an authorized tax return preparer.
When electronically submitting the return, use the electronic payment option to schedule a payment to pay the balance due or make estimated income tax payments. Or use the DOR e-pay system to schedule payments after e-filing the return.
For more information or to use any of DOR electronic services, go to revenue.nebraska.gov
# What's New?
Community Development Assistance Act (CDAA) (LB 650, 2025). Beginning January 1, 2026, the Community Development Assistance Act (CDAA) is reestablished and replaces the Creating High Impact Economic Futures (CHIEF) Act. Under the CDAA, business firms and individuals that contribute to a community betterment organization's program which is certified for tax credit status by the Nebraska Department of Economic Development (DED) during a tax year are eligible for the nonrefundable credit. Applications are approved by DED. The credit for each approved business firm or individual is limited to 40% of the contribution. Any unused credits may be carried forward to the next five tax years after the credit was first allowed. The total amount of approved credits is limited to $350,000 each State fiscal year.
Creating High Impact Economic Futures (CHIEF) Act (LB 650, 2025). The tax credits established under the CHIEF Act will not be allowed for calendar year 2026 or any year thereafter, except the tax credits allowed for calendar year 2025 that are unused may be carried forward for five years.
Food Bank, Food Pantry, Food Rescue Donation Tax Credit (LB 937, 2024; LB 208, 2025; and LB 650, 2025). For taxable years beginning on or after January 1, 2025, and before January 1, 2026, any grocery store retailer or restaurant that donates food or any agricultural producer that makes a qualifying agricultural food donation to a food bank, food pantry, or food rescue during the taxable year may be eligible for a nonrefundable tax credit. The nonrefundable credit equals the lesser of: u 50% of the value of the food donations or qualifying agricultural food donations made during the taxable year; or u $2,500.
If the donation was deducted as a charitable contribution on the taxpayer's federal return, the donation must be added back in the determination of Nebraska adjusted gross income or Nebraska taxable income before the certified credit amount can be claimed. The total amount of approved tax credits is limited to $500,000 for State fiscal year 2025-2026. Credit requests received on the day the annual limit is exceeded will be prorated and no additional credit requests will be approved for such fiscal year.
Foreign Adversarial Company (LB 644, 2025). A foreign adversarial company is ineligible to receive any benefits under an incentive program of the State of Nebraska.
Credits distributed from a foreign adversarial company are also ineligible for tax credit benefits.
See DOR's Foreign Adversarial Company Notice for additional information.
Individuals with Intellectual and Developmental Disabilities Support Act (LB 937, 2024). Beginning with tax year 2025, direct support professionals may be eligible for a refundable credit and employers may be eligible for three nonrefundable credits.
Direct support professionals may be eligible for a $500 refundable credit. A direct support professional is any individual who is employed in Nebraska and provides direct care support or any other form of treatment, services, or care for individuals with intellectual and developmental disabilities.
The credit is available to direct support professionals who: u Are employed as a direct support professional for at least 6 months during the taxable year; and u Worked at least 500 hours as a direct support professional during the taxable year.
The three nonrefundable employer credits are:
- Employers of one or more direct support professionals may apply for a nonrefundable income tax credit that equals $500 for each direct support professional who: u Is employed by the employer for at least six months during the taxable year; and u Worked at least 500 hours for the employer during the taxable year.
- Employers of one or more individuals receiving services pursuant to a Medicaid home and community-based services waiver may apply for a nonrefundable income tax credit that equals $1,000 for each qualified employee who: u Is employed by the employer for at least six months during the taxable year; and u Worked at least 200 hours for the employer during the taxable year.
- Employers that provide any of the following services to one or more individuals pursuant to a Medicaid home and community-based services waiver during the taxable year may apply for a nonrefundable income tax credit equal to $1,000 for each eligible individual who received such services from the employer during the taxable year: u Prevocational; u Supported employment - individual; u Small group vocational support; or u Supported employment - follow along.
Direct support professionals and employers must first apply to the DOR to receive approval of the credit prior to claiming it on their income tax return. The total amount of credits that may be approved for all tax credits under this act (including the refundable credit for direct support professionals) is limited to statutory limit established for each State fiscal year.
If an employer receiving the credit is a partnership, a limited liability company, an S corporation, or an estate or trust, the tax credit may be distributed in the same manner and proportion as the partner, member, shareholder, or beneficiary reports the partnership, limited liability company, subchapter S corporation, estate, or trust income.
Nebraska Biodiesel Tax Credit Act (LB 208, 2025 and LB 650, 2025). The Nebraska Department of Revenue (DOR) may approve up to $1 million in tax credits in State fiscal year 2024-25 and each fiscal year thereafter. Credit requests received on the day the annual limit is exceeded will be prorated and no additional credit requests will be approved for such fiscal year.
Nebraska Pregnancy Help Act (LB 937, 2024). Beginning with tax year 2025, individuals and entities that make cash contributions to pregnancy help organizations approved by DOR as eligible charitable organizations (approved PHOs) during the taxable year may qualify for a nonrefundable tax credit.
Taxpayers must notify the approved PHO of their intent to make a contribution and the amount to be claimed as a tax credit. The approved PHO notifies DOR of the intended contribution. If tax credits are available, DOR will notify the approved PHO of the approved credit amount. Provided the contribution is timely made, the approved PHO should issue a receipt for the contribution made by the taxpayer to take the nonrefundable tax credit. The nonrefundable tax credit equals the lesser of: u The total amount of the contributions made to any approved PHO during the tax year and approved by DOR; or u 50% of the income tax liability of the taxpayer for such year.
Any unused credit may be carried forward five years. The credit cannot be carried back. A taxpayer may only claim a credit on the portion of the contribution not claimed as a charitable contribution on their federal return.
Married filing separate taxpayers may each claim one-half of the credit.
When the contribution is made by a partnership, limited liability company, or a subchapter S corporation, the credit must be attributed to each partner, member, or shareholder in the same proportion used to report the partnership's, limited liability company's, or S corporation's income or loss. Any credit not used by an estate or trust may be attributed to each beneficiary in the same proportion used to report the beneficiary's income from the estate or trust.
Nebraska Shortline Rail Modernization Act (LB 937, 2024 and LB 650, 2025). Beginning with tax year 2025, the Nebraska Shortline Rail Modernization Act provides a nonrefundable tax credit against income tax, franchise tax imposed by Neb. Rev. Stat. §§ 77-3801 to 77-3807, and premium taxes imposed by Neb. Rev. Stat. §§ 77-907 to 77-918 for qualified maintenance expenditures incurred by a Class III railroad. The credit is 50% of the qualified shortline railroad maintenance expenditures incurred during the tax year by the Class III railroad.
Qualified shortline railroad maintenance expenditures do not include expenditures used to generate a federal tax credit or expenditures funded by a federal grant. The amount of the credit cannot exceed an amount equal to $1,500 multiplied by the number of miles of railroad track owned or leased in the state by the applicant at the end of the taxable year. The total amount of tax credits allowed is limited to $500,000 in each State fiscal year.
To receive the tax credit, the Class III railroad must submit an application to the DOR after incurring the relevant qualified shortline railroad maintenance expenditures. The application must be submitted no later than May 1 of the calendar year immediately following the calendar year in which the expenditures were incurred. DOR will issue a tax credit certificate to the Class III railroad with an approved application. The Class III railroad will claim the credit by attaching the certification to the tax return. Any unused credit is carried forward and can be applied against the tax liability for the next five taxable years immediately following the taxable year in which the credit was first allowed.
The tax credits are transferable to another taxpayer by written agreement. No new applications for tax credits can be filed after December 31, 2033.
Relocation Incentive Act (LB 1023, 2024 and LB 650, 2025). Beginning with tax year 2025, a refundable credit is available to employers who pay relocation expenses for a qualified employee. A qualified employee is an individual who moves to Nebraska for the purpose of accepting a position of employment and receives an annual salary within the statutory annual wage income range for the applicable tax year. The credit is equal to the lesser of: u 50% of the relocation expenses paid during the tax year; or u $5,000 for each qualified employee.
Employers must first apply to the DOR to receive approval of the credit prior to claiming it on their income tax return. DOR may approve credits until the total amount of credits approved for the year reaches $1 million.
The refundable credit may be used to offset income taxes, franchise taxes imposed under Neb. Rev.
Stat. §§ 77-3801 to 77-3807, and premium taxes, including retaliatory taxes under Neb. Rev. Stat. §§ 44-150, 77-908, or 81-523.
The credit may be recaptured from the employer if the qualified employee moves out of Nebraska within two years after the employer claimed the credit. The recaptured amount is an underpayment of tax and is due and payable on the tax return due immediately following the qualified employee's loss of residency.
# Employee Nebraska Wage Exclusion
A qualified employee may make a one-time election to exclude his or her Nebraska source wages within two calendar years of becoming a Nebraska resident. A qualified employee is an individual who moves to Nebraska for the purpose of accepting a position of employment. The exclusion is available to qualified employees if the: u Election is made within two calendar years of becoming a Nebraska resident; u Wages were included in the employee's federal adjusted gross income; u Annual wage income of the position accepted is from $70,000 to $250,000 (2025 tax year); and u Employee was not a resident of Nebraska in the year prior to the year in which residency is claimed for the purposes of the exclusion.
For tax years beginning on or after January 1, 2026, the annual wage thresholds will be adjusted each tax year by the same percentage used to adjust the individual income tax brackets.
Any tax reduction resulting from the exclusion may be recaptured if the qualified employee does not maintain residency in Nebraska for two full calendar years following the calendar year in which the exclusion was taken. The recaptured amount is an underpayment of tax and is due and payable on the tax return due immediately following the loss of residency.
# Important Information For All Nebraska Filers
# Notification of Scam Text Messages
The Nebraska Department of Revenue (DOR) has been notified of scam text messages being sent asking individuals to click a link to receive their refund. While the cited Nebraska Revised Statute adds validity to the message, the embedded link will direct the taxpayer to a bogus site to enter their personal and/or banking information.
This scam has been reported in other parts of the country.
The DOR will never send a text to ask for personal tax return information.
If you receive a text message of this kind, DO NOT REPLY and please delete it.
If you have questions on the status of your State of Nebraska tax refund, please go to: https://revenue. nebraska.gov/individuals/refund-information As scammers develop more sophisticated schemes, staying informed is your best defense. The Nebraska Attorney General's Office offers free resources to help consumers recognize and avoid scams.
Visit ProtectTheGoodLife. Nebraska.gov. Identity theft is a persistent, evolving threat. The Nebraska Department of Revenue (DOR) utilizes fraud detection and verification processes to reduce refund fraud designed to protect all taxpayers filing Nebraska returns. These steps may increase the amount of time needed to process income tax returns and issue tax refunds. DOR is committed to processing the tax returns efficiently while safeguarding taxpayer information. Please allow a minimum of 30 days to receive your refund if you e-file an errorfree return. For paper returns, please allow a minimum of three months to receive your refund if you file an error-free return. Your refund will generally be issued by July 15, if your return is filed by the April 15th due date. See our website for additional identity theft information.
Complete Your Federal Return. Your federal return must be completed before starting your Nebraska return. This information is needed to complete your Nebraska return.
Federal Return. A copy of the federal return and supporting schedules, as filed with the IRS, must be attached to the Nebraska return.
Digital assets. Do not leave the question blank on the Nebraska return regarding transactions involving digital assets. If, in 2025, you engaged in any transaction involving digital assets, check the "Yes" box next to the question on digital assets on page 1 of Form 1040N directly below the social security number fields. Nebraska generally follows federal definitions. For additional information see the instructions for Federal Form 1040.
Complete Only the Lines on Nebraska Individual Income Tax Return, Form 1040N, That Apply to You. Leave the line blank if a line does not apply to your filing, except line 5 cannot be left blank.
Enter All Amounts as Whole Dollars. Do not include cents on the return or schedules. Do not change the pre-printed zeros in the cents column of the Form 1040N. Round any amount from 50 cents to 99 cents to the next higher dollar. Round any amount less than 50 cents to the next lower dollar.
Federal Forms W-2, W-2G, 1099-R, 1099-MISC, and 1099-NEC. A form should be received from your employer or payor by February 15 or by March 1 if furnished by a broker. If you have not received the form by the required date, you should immediately contact your employer or payor. Please verify that all information on these forms is correct, including the Social Security number. If the information on these forms is incorrect, obtain a corrected form from your employer or payor. A corrected form should be clearly marked "Corrected by Employer/Payor." If a wage and tax statement is lost or destroyed, request a substitute copy clearly marked "Reissued by Employer."
Balance Due. Any balance due must be paid in full with your return. All taxpayers are encouraged to make their tax payments electronically. There are many electronic payment methods available. Several software products offer the option of an electronic funds withdrawal (EFW) allowing you to schedule your payment when you file your return. Other options include DOR's e-pay system and paying by credit card. Electronic payment is fast, secure, and easy. See DOR's website for additional information about all available electronic payment options.
Use Tax. Use tax is due on all taxable purchases when Nebraska and any applicable local sales tax is not paid to the retailer. This often occurs when making purchases over the Internet or from out-ofstate retailers. Check your receipts for online purchases to see if tax was collected by the retailers. See the instructions for line 52, Form 1040N if the appropriate Nebraska and local sales taxes were not collected by a retailer on any of the purchases.
Due Date. Your income tax return is due on the 15th day of the 4th month after the close of the tax year (April 15th for calendar-year filers). If the due date falls on a Saturday, Sunday, or legal holiday, you must file your return by the first business day after the 15th day of the fourth month.
Penalty and Interest. Either or both may be imposed under the following circumstances:
- Failing to file a return and pay the tax due on or before the due date;
- Failing to pay the tax due on or before the due date;
- Failing to file an amended Nebraska income tax return when required;
- Preparing or filing a fraudulent income tax return; or
- Understating income on an income tax return.
Filing a false or fraudulent return is subject to penalty, even if the amounts reported are taken from your federal return. Unpaid tax is subject to interest at 8% from the original due date to the date the tax is paid. See the DOR Interest Rate Assessed on State Taxes Revenue Ruling for applicable interest rates.
Amended Nebraska Individual Income Tax Return, Form 1040N with the Amended Return Box
Checked. Beginning with the 2025 tax year use the Form 1040N if the information on a previously-filed Nebraska income tax return is incorrect, you must file the Nebraska Individual Income Tax Return, Form 1040N and check the "Amended Return" box, to report the corrected amounts.
An amended Form 1040N is filed when: u The 2025 federal income tax return, or another state's 2025 income tax return, is amended or corrected; or u The information on the 2025 Nebraska income tax return that was previously filed is not correct.
Form 1040N with the "Amended Return" box checked may only be filed after an original Nebraska individual income tax return has been filed.
An amended Nebraska income tax return must be filed within 60 days after filing an amended federal income tax return. However, if the amended federal income tax return requests a credit or refund, the amended Nebraska income tax return must be filed within 60 days after receipt of proof of federal acceptance of the credit or refund.
An amended Nebraska income tax return reporting a change or correction to another state's income tax return must also be filed within 60 days after the amended income tax return is filed with the other state, or the correction becomes final.
To establish timeliness of the refund claim, attach dated copies of: u The federal claim for refund; u The IRS audit determination; or u The amended federal or state income tax return.
Filing an amended Form 1040N to Claim a Credit or Refund. Unless otherwise provided by statute:
When claiming a credit or refund due to overpayment, an amended Form 1040N must be filed: u Within three years of the due date, the actual date of filing under an approved extension, or the date the original income tax return was filed; or u Within two years from the time the tax was paid; whichever is later.
When claiming a credit or refund of a refundable credit, an amended Form 1040N must be filed within three years of the due date, or the actual date of filing under an approved extension of the income tax return (whichever is later) for the year in which the refundable credit was allowable.
An amended Form 1040N must be filed to claim a refund resulting from a federal or state change within two years and 60 days following the final determination of the change (but not more than 10 years from the due date of the original income tax return in the case of a change made by another state).
If you file an amended federal income tax return which will result in a credit or refund, do not submit the Nebraska amended income tax return until you can attach proof of federal acceptance.
A hearing may be requested when filing for a refund on an amended Form 1040N by indicating the request in the Explanation of Changes section of the form or by attaching a request for hearing to the amended Form 1040N.
Federal Return. A copy of the federal return and supporting schedules, as filed with the IRS, must be attached to the amended Nebraska return.
Protective Claim. When an amended federal income tax return has been filed as a protective claim, an amended Nebraska income tax return filed as a protective claim is not necessary and should not be filed. The payment of a refund by the IRS on a protective claim is a federal change that must be reported within 60 days of the refund.
Nebraska Net Operating Loss (NOL). When carrying back a Nebraska NOL, you must attach a copy of the completed Nebraska Net Operating Loss Worksheet, Form NOL, and a copy of either Federal Form 1045 or 1040X and all supporting schedules. The Nebraska Net Operating Loss Worksheet, Form NOL, must be completed for the loss year and retained in your records until the loss is used. When the loss is used, you must attach a Form NOL for each previously established loss year being used. Any federal NOL deduction is entered on line 7 of the amended Schedule I, Form 1040N, and the amount of the Nebraska NOL deduction is entered on line 27 of Schedule I.
Amending an E-filed Return. E-filed income tax returns can be amended beginning with the 2025 tax year by e-filing or filing a paper Form 1040N with the Amended Return box checked. Amounts and other information needed for completing the amended income tax return should be available on saved or printed copies of the original Form 1040N return. If help is needed in completing the amended income tax return, contact Taxpayer Assistance (see contact information).
Taxpayer Assistance. Call Taxpayer Assistance at 800-742 7474 (NE and IA), or 402-471 5729. Visit the DOR's website for additional information.
Confidential Tax Information. Confidential tax information will be released only by a return telephone call, after the caller's identity has been established. A representative of a taxpayer requesting confidential tax information must have a Power of Attorney, Form 33, on file with the DOR before any information is released. An income tax return signed by the preparer is considered a limited power of attorney authorizing the DOR to release only the information contained on that tax return to the tax preparer.
If you paid but did not claim on your original return the community college property taxes on Nebraska real estate and this is the only change to your Nebraska individual income tax return, file an amended Nebraska Property Tax Incentive Act Credit Computation, Form PTCX. Do not file an amended Nebraska return.
A Nebraska Extension of Time. DOR accepts the federal extension of time to file. It is only necessary to file a Nebraska extension of time if you are making a tentative tax payment or when a federal extension is not filed. An extension of time to file does not stop interest from accruing on unpaid tax.
A six-month extension to file Form 1040N may only be obtained by:
- Attaching a copy of a timely-filed Application for Automatic Extension of Time to File U.S.
Individual Income Tax Return, Federal Form 4868, to the Nebraska return when filed;
- Attaching a schedule to your Nebraska return listing your federal confirmation number and providing an explanation that you received a federal extension;
- Filing a Nebraska Application for Extension of Time, Form 4868N, on or before the due date of the return, when you need to make a tentative Nebraska payment or if a federal extension was not requested; or
- Attaching a copy of the statement or letter submitted with your federal return requesting the automatic extension of time to file for a U.S. citizen residing outside the U.S. or Puerto Rico, to the Nebraska return when filed.
Note: If you have a combat zone-related or contingency operation-related extension, see DOR's website for Nebraska Income Tax for U.S. Servicemembers, Their Spouses, and Civilians Working with U.S.
Forces Information Guide.
If the extension documentation is not attached, a late filing penalty may be imposed. Any tax not paid by April 15 is subject to interest. An extension of time cannot exceed a total of six months after the original due date of the return.
Estimating Your 2026 Income Tax. The 2026 Nebraska Individual Estimated Income Tax Payment Vouchers booklet is available on DOR's website or you can contact DOR. You are encouraged to make estimated income tax payments using DOR's e-pay system or using the EFW option when e-filing your 2025 Nebraska return. The EFW option is offered by many software products.
Estimated Income Tax Payments and Penalty for Underpayment of Estimated Income Tax. You may owe a penalty if your estimated income tax payments did not total at least: u 90% of the tax shown on your 2025 Nebraska return; u 100% of the tax shown on your 2024 return; or u 110% of the tax shown on your 2024 return if AGI on the return was more than $150,000; or, if your filing status is married, filing separately, more than $75,000.
An individual who did not pay enough estimated income tax by any of the applicable due dates (April 15, June 15, September 15, and January 15), or who did not have enough state income tax withheld, will be assessed a penalty. This may be true even if you are due a refund. The underpayment penalty is calculated separately for each installment due date (four equal and timely payments). You may owe a penalty for an earlier payment that was due, even if you paid enough estimated income tax later to make up the underpayment.
Active Duty Military Servicemembers. Your active duty military pay is taxed only by the state where you are a legal resident. Your place of legal residence at the time of entry into the service is presumed to be your state of legal residence or domicile. Your state of legal residence stays the same until it is established in another state. Moving to a new location for a limited period of time, including a permanent change of station, does not change your legal residence. Nebraska income tax is imposed on the total federal adjusted gross income (AGI) of a Nebraska resident who is a member of the uniformed services, regardless of where the income is received.
The federal Veterans Auto and Education Improvement Act of 2022 amended the federal Servicemembers Civil Relief Act (SCRA) to provide an election to married servicemembers and spouses of servicemembers. The election applies to any taxable year of marriage, regardless of the date of the marriage for taxable years beginning on or after January 1, 2023. Military servicemembers and spouses of the servicemembers may elect to use for purposes of taxation: (a) the residence or domicile of the servicemember; (b) the residence or domicile of the spouse; or (c) the permanent duty station of the servicemember.
Check the box "Active Military" on Form 1040N if you or your spouse were active military servicemembers at any time during the tax year (including National Guard or Reserve personnel called to active duty). Taxpayers receiving combat pay have the same extended due date for filing a Nebraska return as for the federal return.
Military pay received by a nonresident servicemember stationed in Nebraska is not subject to Nebraska income tax. Other income derived from Nebraska sources by a servicemember, such as income earned from a separate job not connected with the servicemember's military service, is subject to Nebraska income tax. See special instructions for line 24, Nebraska Schedule I. The federal SCRA provides that Nebraska cannot tax the income of a nonresident servicemember's spouse when the spouse is a nonresident and is in Nebraska only in support of the servicemember. A Nebraska resident servicemember's spouse, who is also a Nebraska resident and who works and resides in another state, is required to file a Nebraska income tax return. More information is available in the instructions for line 24, Nebraska Schedule I, line 1, Nebraska Schedule III, and on DOR's website.
Foreign Income. Income earned by a Nebraska resident while living in another country is taxable by Nebraska. Individuals who previously filed as Nebraska residents continue to be Nebraska residents until they abandon their Nebraska domicile and a new domicile is established. Most taxpayers remain Nebraska residents and are required to file Nebraska returns, even while living in another country.
Deceased Taxpayer. A tax return must be filed and any liability must be paid if the deceased otherwise met the filing requirements. A deceased taxpayer's spouse, personal representative, or other person may file and sign a return for a taxpayer who died before filing a 2025 return. A personal representative is an executor, administrator, or anyone else who is in charge of the deceased taxpayer's property.
Additional documentation will be required when claiming a refund on behalf of a deceased taxpayer, unless the deceased is your spouse with whom you are filing as married, filing jointly for this tax year.
"DECEASED" must be written across the top of a paper return and the taxpayer's name and the date of death must be shown in the space provided. See additional instructions for deceased taxpayers in the "How to Complete your Form 1040N" section on page 11.
Fiscal Year Returns. The taxable year used for Nebraska must be the same as the taxable year used for federal income tax purposes. For fiscal years beginning after January 1, 2025, the 2025 Nebraska Tax Calculation Schedule or Tax Table, must be used without adjustment.
Due Date for Fiscal Year Returns. The due date for a fiscal year return is the 15th day of the fourth month following the end of the taxable year. If the due date falls on a Saturday, Sunday, or legal holiday, you must file your return by the first business day after the 15th day of the fourth month following the end of the taxable year.
Refer to instructions for line 36, Form 1040N, for additional information on a fiscal year taxpayer claiming the income tax withholding credit.
Taxpayers filing fiscal year returns may not e-file their Nebraska return.
See DOR's website for: Nebraska
Income Tax for U.S.
Servicemembers, Their Spouses, and
Civilians Working with U.S. Forces
Information Guide.
# Who Must File?
A Nebraska resident who: u Is required to file a federal individual income tax return reporting a federal tax liability before credits; or u Has $5,000 or more of net Nebraska adjustments to federal AGI including non-Nebraska state and local bond interest exempt from federal tax (see Nebraska Schedule I instructions).
A partial-year resident or a nonresident who: u Has income derived from or connected with Nebraska sources.
# Definitions
Domicile. Domicile is the place an individual has his or her permanent home. Even if the individual is absent at times, domicile is the place where the individual intends to return. Actual residence is not necessarily domicile. An individual establishes domicile in Nebraska on the date he or she arrives in the state for other than temporary or transitory purposes. Once domicile is established, it remains the individual's domicile until it is abandoned. Domicile in Nebraska is abandoned when an individual leaves the state, abandons the Nebraska domicile with no intention of maintaining his or her true, fixed, and permanent home in Nebraska; and establishes a domicile in another state while present in the other state for other than temporary or transitory purposes.
Partial-Year Resident. A partial-year resident is an individual who is a resident for part of the year, but less than the entire year. To be a partial-year resident, a taxpayer must change domicile during the year, either moving into or out of Nebraska.
Permanent Place of Abode. A permanent place of abode is a dwelling place permanently maintained by the taxpayer, whether or not it is owned by the taxpayer. A dwelling means a house, apartment, room, or other accommodation including those used for vacation purposes, suitable for human occupation. It does not include a vacation camp, cottage, or dwelling place occupied only temporarily.
Resident. A resident is an individual whose domicile is in Nebraska, or an individual who is physically present in this state and maintains a permanent place of abode within this state for an aggregate of more than six months. Nebraska residency will be determined by Nebraska law. If an individual maintains a permanent place of abode in Nebraska and is present in Nebraska for at least 183 days during the tax year, that individual is a Nebraska resident even if domiciled in another state. For this purpose, Nebraska considers any part of a day spent in Nebraska as a day spent in the state.
For additional information, refer to the Determining Residency Status for Nebraska Individual Income Tax Filing Information Guide on DOR's website.
# How to Complete your Form 1040N
Name and Address. When filing a paper return, enter or clearly print your name and correct mailing address information in the spaces provided. Include your spouse's name if filing a joint return.
Social Security Numbers. You must enter your Social Security number (SSN) or Individual Tax Identification Number (ITIN) on the form in the boxes indicated. Include your spouse's SSN or ITIN if filing a joint return.
The Privacy Act of 1974 provides that when DOR asks you for your Social Security number (SSN), you must first be told of DOR's legal right to ask for this information, why DOR is asking for it, and how it will be used. DOR must also tell you what would happen if it is not received and whether your response is voluntary, required to obtain a benefit, or mandatory under the law.
The legal right to ask for the information is Neb. Rev. Stat. § 77-27,119. This law says that you must include your SSN on your return. Your response is mandatory under this section. The SSN is needed to properly identify you and process your return and other documents. If the required SSNs are not provided the return is not considered to be filed.
Public High School District Data. All residents and partial-year residents domiciled in Nebraska on December 31, 2025, must enter the high school district code where you are domiciled (permanent residence). This information is also required if you reside outside Nebraska but are still domiciled in Nebraska. Nonresidents or partial-year residents not residing in Nebraska on December 31, 2025, do not enter a high school district code. This information is required by law to assist the Nebraska Department of Education in determining the state aid for Nebraska's K-12 public school systems.
Amended Return. Check the box "Amended Return" to the right of the High School District Code if you need to amend the previously filed Nebraska return. See additional information on page 7.
Digital Assest. Digital assets are any digital representations of value that are recorded on a cryptographically secured distributed ledger or any similar technology. For example, digital assets include non-fungible tokens (NFTs) and virtual currencies, such as cryptocurrencies and stablecoins. If a particular asset has the characteristics of a digital asset, it will be treated as a digital asset for federal income tax purposes. Check the "Yes" box next to the question on digital assets on page 1 of Form 1040N if at any time during 2025, you (a) received (as a reward, award, or payment for property or services); or (b) sold, exchanged, or otherwise disposed of a digital asset (or any financial interest in any digital asset).
Foreign Adversarial Company. A foreign adversarial company is ineligible to receive incentive benefits. Credits distributed from a foreign adversarial company are ineligible for tax credit benefits.
Failing to answer will result in denial or delay in processing the credits claimed. If you answer yes, see Foreign Adversarial Company Notice for additional information regarding the benefits and credits impacted.
Farmer/Rancher. Farmers or ranchers deriving at least two-thirds of their yearly gross income for the current or previous tax year from farming or ranching must check the box "Farmer/Rancher" below the SSN block. A farmer or rancher who files the 2025 Form 1040N and pays the Nebraska income tax due on or before March 1, 2026, is not required to make estimated income tax payments during 2025; otherwise, the entire amount of estimated income tax must be paid by January 15, 2026. If you file or pay after March 1, 2026, you may be assessed a penalty for failure to properly pay estimated income tax. An extension of time cannot be used to extend the March 1 filing date.
Active Military. Check the box "Active Military" below the SSN block only if you or your spouse were on active military duty status at any time during 2025. This includes National Guard/Reservists called to active duty during 2025.
Deceased. If the taxpayer or spouse is deceased, enter the first name of the deceased person and the date of death in the space provided. u A Surviving Spouse filing for a deceased taxpayer's refund must write "surviving spouse" in the signature block if you are filing a paper Form 1040N for the deceased. No further documentation is required. u When a court-appointed personal representative files an original or amended return on behalf of a deceased person, he or she must attach a copy of one of the following with the completed and signed Form 1040N:
- The court order showing proof of appointment (Letters of Appointment); or
- A copy of the probated will. u Other persons requesting a deceased taxpayer's refund should complete a Statement of Person Claiming a Refund Due to a Deceased Person, Form 1310N, and attach one the following:
- Death certificate (need not be certified); or
- Formal notification from the appropriate government office (for example, Department of Defense, Department of Health and Human Services, or Department of State) informing the next of kin of the deceased person's death.
Line 1 Federal Filing Status. Your Nebraska filing status is the same as your federal filing status.
There is an exception for married, filing jointly taxpayers where one spouse is a Nebraska resident and the other spouse is a nonresident or partial-year resident of Nebraska. These taxpayers may elect to file either a married, filing jointly return (both spouses are taxed as residents) or married, filing separately returns with Nebraska.
If you file a married, filing separately return for Nebraska, it must be calculated as if a married, filing separately federal return had been filed. The married, filing separately income, deductions, and exemptions must be used. The spouse's SSN and name must be entered on the married, filing separately line.
Nonresident military servicemembers should review line 24, Nebraska Schedule I instructions.
Amended Return to Change Filing Status. If filing an amended return, a married couple, with different residences, who filed separate Nebraska returns may elect, either before or after the original return is due, to file a married, filing jointly return in Nebraska. They are then taxed as though both were Nebraska residents during the time either was a resident.
A married couple with different residences who originally filed a married, filing jointly Nebraska return and wish to amend to married, filing separately returns must satisfy the following conditions:
- Both spouses must file a separate Nebraska return with a "married, filing separately" status.
The spouse whose Social Security number was listed first on the original return must file an amended Nebraska Individual Income Tax Return, Form 1040N.
The spouse whose Social Security number was listed as the spouse on the original return must file a Nebraska Individual Income Tax Return, Form 1040N.
- A copy of the actual federal married, filing jointly return and copies of federal returns recalculated on a married, filing separately basis must be attached to each of the spouse's returns.
- Each Nebraska return as required in "1" above, must include the full name and Social Security number of the other spouse.
- Both spouses must sign each Nebraska return as required in "1".
Line 2a Check the appropriate boxes if, during 2025:
Box 1. You were 65 or older (taxpayers born before January 2, 1961);
Box 2. You were blind;
Box 3. Your spouse was 65 or older (taxpayers born before January 2, 1961); or Box 4. Your spouse was blind.
Line 2b Check the appropriate boxes if someone, such as a parent, can claim you or your spouse as a dependent on their return.
Line 3 Type of Return. Check the appropriate box if, during 2025:
Box 1. You were a resident;
Box 2. You were a partial-year resident; or Box 3. You were a nonresident.
Partial-year residents must also complete dates of residency. Nonresidents and partial-year residents must complete and attach Form 1040N, Schedule III, even if all income is earned in Nebraska. If one spouse is a full-year resident and the other is a nonresident or partial-year resident, and they elect to file a married, filing jointly return, a resident return must be filed and Schedule III cannot be used. For additional information, refer to the Determining Residency Status for Nebraska Individual Income Tax Filing Information Guide. Military servicemembers and their spouses can refer to the Nebraska Income Tax for U.S. Servicemembers, Their Spouses, and Civilians Working with U.S. Forces information guide on DOR's website.
Line 4a Enter 1 in line 4a for yourself. You cannot enter a 1 in line 4a if you are claimed by another taxpayer for child tax credit or dependent tax credit purposes. The box should be left blank if a 1 is not entered.
Line 4b If your status is married, filing jointly enter 1 in line 4b for your spouse. You cannot enter a 1 in line 4b if your spouse is claimed by another taxpayer for federal child tax credit or dependent tax credit purposes. The box should be left blank if a 1 is not entered.
Line 4c Enter the dependents' names and social security numbers listed in columns 1 and 2 of the Federal Form 1040 or 1040-SR that qualify for the child tax credit or dependent tax credit. If you have more than three dependents, attach a listing for the remaining dependents using the same format as line 4c.
Line 4 Total Nebraska Personal Exemptions. Add lines 4a, 4b, and 4c and enter the result on line 4.
If you filed a married, filing jointly federal return and elect to file married, filing separately for Nebraska because one spouse is a resident of Nebraska and the other is not, a federal return must be computed for each taxpayer as if married, filing separately federal returns had been filed. The taxpayer claiming the child tax credit or dependent credit on the reworked federal return must have earned more than half of the income used to support the family. For example, if a couple has three children, a taxpayer earning one-third of the income cannot claim any of the family's three children. Support payments are presumed to go to all children equally. The recalculated federal return information is used to determine the Nebraska personal exemptions that can be claimed on each married, filing separately Nebraska return.
Line 5 Federal Adjusted Gross Income (AGI). This is the amount reported on your federal return as AGI.
Enter the amount from Federal Form 1040 or 1040-SR, page 1, line 11a. Do not leave line 5 blank on the Nebraska individual income tax return.
Special Circumstances.
If you were not required to file a federal return, but must file a Nebraska return to report state and local bond interest of $5,000 or more, you must enter all income that would have been included in federal AGI. This includes both earned income (such as wages), retirement income (such as 401K distributions, pensions, etc.), and investment income (such as dividends, bank interest, etc.).
Nonresidents and partial-year residents must include your total federal AGI on line 5, Form 1040N, not just your Nebraska source income. When completing Nebraska Schedule III, you will report Nebraska income and apportion your tax liability based on a calculated ratio of Nebraska income to total income.
Line 6 Nebraska Standard Deduction. Enter your Nebraska standard deduction. If you use the standard deduction on the federal return, you must use the Nebraska standard deduction on the Nebraska return. All taxpayers that claimed itemized deductions on their federal return are allowed the larger of the Nebraska standard deduction or federal itemized deductions, minus state and local income taxes claimed on Federal Schedule A.
If you or your spouse cannot be claimed by another taxpayer for the federal child tax credit or dependent tax credit, enter the appropriate Nebraska standard deduction from the following chart. Do not enter the amount of your federal itemized deductions.
If you or your spouse can be claimed by another taxpayer for federal child tax credit or dependent tax credit purposes, your standard deduction is the smaller of the federal standard deduction allowed on line 12e of the Federal Form 1040 or 1040-SR, or the Nebraska standard deduction from the following chart.
Nebraska Standard Deduction Chart
See instructions above if you or your spouse can be claimed by another taxpayer for child or dependent tax credit purposes.
Number of Boxes Standard
Filing Status Checked on Line 2a Deduction
Single 0 $8,600
1 $10,600
2 $12,600
Married, Filing Jointly 0 $ 17,200 1 $18,850 2 $20,500 3 $22,150 4 $23,800 Qualifying surviving spouse 0 $ 17,200 1 $18,850 2 $20,500
Married, Filing Separately 0 $8,600 1 $10,250 2 $11,900 3 $13,550 4 $15,200 If married, filing separately, the additional amounts for spouse 65 and over and blind apply only if the primary taxpayer can claim a personal exemption for his or her spouse.
# Head of Household 0 $12,600
1 $14,600
2 $16,600
Line 7 Total Itemized Deductions. If you itemized deductions on your federal return, enter the amount from line 17 of Schedule A, Federal Form 1040. If you did not itemize deductions on your federal return, skip lines 7 through 9 and enter the line 6 amount on line 10. State and local personal property taxes are limited to the amount of motor vehicle taxes paid upon registration. Only motor vehicle tax based on the value of the vehicle and paid every year upon renewal of the vehicle registration is allowable. For Nebraska residents, the statement or registration receipt from the county treasurer shows the amount of motor vehicle tax paid.
Line 8 State and Local Income Taxes. If you itemized deductions on your federal return, you must enter the amount of state and local income taxes reported on Federal Schedule A, line 5a even if the total amount of state and local taxes was limited to $40,000 ($20,000 married, filing separately) on Federal Schedule A, line 5e. If you entered general sales taxes on Federal Schedule A, line 5a, do not enter an amount on line 8.
Line 9 Nebraska Itemized Deductions. Line 7 minus line 8.
Line 10 Nebraska Deductions. Enter line 6 or line 9, whichever is greater.
Line 11 Nebraska Income Before Adjustments. Line 5 minus line 10.
Line 12 Adjustments Increasing Federal AGI. Enter amount from line 13 of Nebraska Schedule I. See Schedule I instructions for additional information.
Line 13 Adjustments Decreasing Federal AGI. Enter the amount from line 44 of Nebraska Schedule I. See Schedule I instructions for additional information.
Amended Return. Must include amended Schedule I when an amount different from the amount reported on the previous return filed.
Line 14 Nebraska Taxable Income. If you do not have adjustments to federal AGI, enter the line 11 amount on line 14. If you have adjustments, line 14 equals line 11 plus line 12 minus line 13.
Line 15 Nebraska Income Tax. Nonresidents and partial-year residents, enter the amount from line 9, Nebraska Schedule III. Paper filers may use the Nebraska Tax Table. Electronic filers must use the Nebraska Tax Calculation Schedule.
Line 16 Nebraska Other Tax. You are required to calculate Nebraska other tax if you were required to pay: u Federal tax on lump-sum distributions of qualified retirement plans; and/or u Federal tax on early distributions of qualified retirement plans.
The Nebraska other tax is 29.6% of the federal other tax on the items shown above.
Residents use the calculation from line 16 of Form 1040N to calculate the amount of total other taxes.
Partial-year residents and nonresidents use line 10, Nebraska Schedule III to calculate the amount of other tax due. The other tax is 29.6% of the federal other tax multiplied by the ratio from line 4,
Nebraska Schedule III. Amended Return. Paper filers attach a copy of your Federal Form 4972 or Form 5329 if you are amending the tax previously reported. If Form 5329 is not required, attach Form 1040 and Federal Schedule 2.
Line 17 Total Nebraska Tax. Enter the total of lines 15 and 16.
Amended Return. If line 17 is changed, and you had previously claimed a credit for tax paid to another state, enter the revised tax amount on line 1 of the amended Nebraska Schedule II, Form 1040N and complete the rest of the Nebraska Schedule II.
Line 18 Nebraska Personal Exemption Credit for Residents Only. Residents may claim a $171 credit for each Nebraska personal exemption reported on line 4, Form 1040N. Multiply $171 by the number of Nebraska exemptions on line 4, Form 1040N. Nonresidents and partial-year residents will claim this credit on line 7, Nebraska Schedule III.
Line 19 Credit for Tax Paid to Another State. Enter the amount from line 6, Nebraska Schedule II. Attach a complete copy of the other state's return, including schedules. (For instructions on what lines to use from the other state's return, refer to the Conversion Chart on DOR's website).
A separate Schedule II must be completed for each state. Nebraska law does not allow credit for taxes paid to a foreign country or its political subdivisions. Dual state residents must refer to the Special Conversion Chart instructions to properly calculate tax paid to another state.
The Special Conversion Chart instructions must be used when Nebraska residents claiming the decreasing adjustment for S corporation or LLC non-Nebraska income are taxed in several states and the apportionment computations for the taxing states exceed 100% of the S corporation or LLC non-Nebraska income.
Please note: This situation is rare and generally, the adjustment on Nebraska Schedule I removing the non-Nebraska income from being taxed by Nebraska is sufficient and apportionment will not exceed 100% in the other states.
Amended Return. If line 19 is changed, complete an amended Nebraska Schedule II, Form 1040N to determine the amount to enter on line 19. If the other state's income tax return is amended or changed by the other state, file an amended Form 1040N including an amended Schedule II to report the change.
Explain any change in detail in the Explanation of Changes section. Include a complete copy of the other state's income tax return. (see Schedule II instructions).
Line 20 Credit for the Elderly or the Disabled. Residents enter the amount of Credit for the Elderly or the Disabled included in line 6d of Schedule 3, Federal Form 1040. If the federal credit has been limited by your federal tax liability, use the lesser amount. Attach Federal Schedule R. Partial-year residents use line 6b, Schedule III, to report Credit for the Elderly or Disabled. Nonresidents may not claim this credit.
Amended Return. If you are correcting this credit, the change must be explained in detail in the Explanation of Changes section. Paper filers attach a copy of the corrected Federal Schedule R.
Line 21 Community Development Assistance Act (CDAA) Credit. Enter the credit allowable for contributions to approved projects of community betterment organizations recognized by the Nebraska Department of Economic Development (NDED). Nebraska Community Development Assistance Act Credit Computation, Form CDN, must be attached to the Form 1040N.
Amended Return. Paper filers claiming an amount or amending the amount previously claimed, must attach the Form CDN.
Line 22 Form 3800N Nonrefundable Credit. Enter the total of nonrefundable credits from the Nebraska Incentives Credit Computation, Form 3800N. Attach Form 3800N. Required supporting documentation may be submitted as an attached PDF document when e-filing your return if your software supports these types of attachments. If the supporting documentation is not received with the return, DOR may request the required documentation during the processing of your return. Your income tax refund may be delayed if the business entity that distributed the Form 3800N credit to you has not filed its entity income tax return.
Amended Return. If you are correcting the amount of any of the nonrefundable Form 3800N credits, copies of the original and corrected credit computations (Form 3800N) must be attached if you are a paper filer. E-filed returns submit as an attached PDF document if your software supports these types of attachments.
Line 23 Nebraska Child/Dependent Care Nonrefundable Credit. Resident taxpayers with AGI greater than $29,000 can claim this credit (if AGI is $29,000 or less, see line 48 instructions). Multiply the amount on line 2 of Schedule 3, Federal Form 1040 by 25% (.25). Partial-year residents use line 6c, Schedule III, to claim this credit, if applicable. Nonresidents may not claim this credit. Include a copy of Federal Form 2441. If Federal Form 2441 is not received, the credit will be disallowed. Taxpayers who are filing married, filing jointly federally, but filing married, filing separately on their Nebraska return cannot claim this Nebraska credit.
Amended Return. Paper filers correcting this credit, must attach the Federal Form 2441 to substantiate the amount claimed. The change must be explained in detail in the Explanation of Changes section.
Line 24 Credit for Financial Institution Tax. Enter the amount of the tax credit available to you from the 2025 Statement of Nebraska Financial Institution Tax Credit, Form NFC, supplied by the financial institution in which you are a shareholder. You must include a copy of the 2025 Form NFC to claim the credit. This credit amount must also be added back to your income on line 4 of Nebraska Schedule I and included on line 1 of Nebraska Schedule III, if applicable. Required supporting documentation may be submitted as an attached PDF document when e-filing your return, if your software supports these types of attachments. If the supporting documentation is not received with the return, DOR may request the required documentation when processing your return. This may result in a delayed refund.
Amended Return. Paper filers attach supporting documentation if this credit is changed. E-filed returns attach the documentation as a PDF attachment.
Line 25 Employer's Credit for Expenses Incurred for TANF (ADC) Recipients. An employer may claim an income tax credit equal to 20% of the employer's qualified expenses for eligible employees. An eligible employee is defined as a parent or caretaker relative who is a member of a unit that received benefits under the state or federally funded TANF program for any nine months of the eighteen-month period immediately prior to the employee's hiring date, and whose hiring date is on or after the first day of the tax year for which the credit is claimed. Qualified expenses are tuition at Nebraska public institutions for postsecondary education; the costs of a high school equivalency program; and the cost for transportation of eligible employees to and from work. Enter the total credit from line 2, Nebraska Form TANF. Attach the Form TANF.
Line 26 Designated Extremely Blighted Area Tax Credit. An individual may claim a $5,000 tax credit in the year the individual purchased a residence upon meeting all the following requirements: u Residence is located in a designated extremely blighted area; u Residence is the buyer's primary residence; u Buyer did not purchase the residence from a family member or spouse's family member.
Complete and attach the Form 1040N-EB. The buyer may carryforward any unused credit to subsequent years until the credit is used. The credit allowed is subject to recapture if the individual claiming the credit sells or transfers the residence or no longer uses the residence as a primary residence within five years after the end of the taxable year the credit was claimed. When the nonrefundable tax credit is recaptured, the individual must file an amended return for the initial year the credit was claimed and each subsequent year the tax credit was carried forward and used. If it is a recapture event, do not enter an amount. Leave the line blank to remove the credit previously claimed.
Line 27 Nebraska Employer Tax Credit for Employing Convicted Felons. Enter the certified credit amount and the certificate number from the Nebraska Employer Tax Credit Application for Employing Convicted Felons, Form ETC-A. The employer must file an application with DOR and be approved to receive the tax credit prior to claiming the credit. If approved for more than one certificate number, you must attach a schedule listing each certificate number and approved amount.
Line 28 School Readiness Tax Credit for providers. This nonrefundable income tax credit is available to an individual or may be distributed to an individual who is a shareholder, partner, beneficiary or member of an S corporation, partnership, fiduciary or limited liability company that owns or operates an eligible childcare or education program that serves children who participate in the childcare subsidy program established in Neb. Rev. Stat. § 68-1202. Applications for the School Readiness Tax Credit for Childcare and Education Provider, Form SR-3604, must be submitted electronically through the Electronic Document & Application Submission Hub (eDASH). DOR will publicize on our website the date the applications will be available for submission. Sign up for a free subscription service at the DOR's website to receive email updates regarding the applications availability. The credit may only be claimed after the application has been approved in writing by DOR. Enter the certificate number and the credit amount from your approved Form SR-3604. If the tax credit was distributed, enter the certificate number and credit amount from the Schedule K-1N. Paper filers attach the Schedule K-1N from the distributing entity. When e-filing a return, submit the Schedule K-1N as an attached PDF document. For more information about this credit, go to School Readiness Tax Credit Act.
Line 29 Child Care Tax Credit for contributors. The nonrefundable credit may only be claimed after the application has been approved in writing by DOR. Enter the approved child care tax credit amount and certificate number from Form CCTC-A. An individual may only claim a credit on the portion of the contribution that was not deducted as a charitable contribution on their federal return. The taxpayer may carry forward the excess credit for up to five taxable years after the taxable year in which the credit was first allowed. Taxpayers must use the carryover credit in the earliest taxable year possible.
Line 30 Opportunity Scholarships Act credit for contributors. Enter the carryforward credit not used on the 2024 Form 1040N. The granting of the tax credit for the contributions was limited to the 2024 tax year. The unused tax credits granted in 2024 may be carried forward five years from the year granted.
Taxpayers must use the carryover credit in the earliest taxable year possible.
Line 31 Creating High Impact Economic Futures (CHIEF) Credit. This nonrefundable credit is allowable for contributions to community betterment organization programs or projects certified for tax credit status by the Nebraska Department of Economic Development. The credit must be claimed on the tax return for the year in which the contribution was made. The granting of the tax credit for the contributions was limited to the 2025 tax year. The unused tax credits granted in 2025 may be carried forward five years from the year granted. Attach Form 1879NTC.
More detailed information on this credit can be obtained by contacting:
# Nebraska Department of Economic Development
245 Fallbrook Blvd, Suite 002
Lincoln NE 68521 https://opportunity.nebraska.gov/programs/incentives/chief/
Line 32 Family Caregiver Tax Credit Act. The nonrefundable tax credit is for eligible family caregivers providing care and support to an eligible family member. The family caregiver must apply for the tax credit with DOR. The credit may only be claimed after the Family Caregiver Tax Credit Application, Form 3165 has been approved in writing by DOR. The approved tax credit must be claimed in the year the uncompensated expenses were incurred. Enter the certificate number and amount from the approved application. Any unused credit cannot be carried forward.
Line 33 Pregnancy Help Act Credit for contributors. Enter the lesser of the amount of contributions made to an approved Pregnancy Help Organization and verified by DOR or 50% of the income tax liability (line 15, Form 1040N). Any unused credit may be carried forward for the next five years after the credit was first allowed. The tax credit cannot be carried back. A taxpayer may only claim a credit on the portion of the contribution that was not claimed as a charitable contribution on their federal return.
Line 34 Total Nonrefundable Credits. Add lines 18 through 33.
Line 35 Nebraska Tax After Nonrefundable Credits. Do not complete the worksheet below if the result of line 12 minus line 13 is $5,000 or more. Otherwise, if your federal tax liability is -0- or is less than your Nebraska tax, complete the Federal Tax Liability Worksheet below. On line 35, enter the smaller of the amounts from line 2 or line 3 of the worksheet. If entering federal tax liability, attach a copy of your federal return.
Line 36 Nebraska Income Tax Withheld on Federal Forms W-2. Use line 36 to enter the total Nebraska income tax withholding from Federal Forms W-2. Do not use state wages. Your income tax withholding credit will not be allowed if you do not attach the proper forms to a paper filed return or if the form shows income tax withholding from a state other than Nebraska.
A fiscal year taxpayer who receives Federal Forms W-2 issued on a calendar-year basis must attach any 2025 Federal Forms W-2 to the 2025 Form 1040N for the fiscal year beginning in 2025. If you receive any 2026 Federal Forms W-2 before filing your 2025 Form 1040N, save them to attach to the 2026 Form 1040N. Amended Return. Paper filers changing the amount of income tax withheld and claimed on line 36, must attach a Nebraska copy of any additional or corrected Wage and Tax Statements, Federal Forms W-2. When e-filing a return submit the additional or corrected Wage and Tax Statements, Federal Forms W-2 as an attached PDF document.
Line 37 Nebraska Income Tax Withheld on Federal Forms W-2G, 1099-R, 1099-MISC, 1099-NEC, etc.
Use line 37 to enter the total Nebraska income tax withholding from federal forms other than Form W-2. Must attach all federal forms that show Nebraska income tax withheld.
Amended Return. Paper filers correcting the amount of income tax withheld and claimed on line 37, must attach a Nebraska copy of any additional or corrected federal forms.
# Federal Tax Liability Worksheet
- Nebraska Adjustments to AGI a. Amount of adjustments increasing federal AGI (line 12, Form 1040N) … 1a. _ _ b. Amount of adjustments decreasing federal AGI (line 13, Form 1040N) … 1b. _ Net adjustments to federal AGI (line 1a minus line 1b) … 1. _ _ If the amount on line 1 is $5,000 or more Stop. Line 35 of Form 1040N must be the mathematical result of line 17 minus line 34.
- Nebraska Tax after Nonrefundable Credits a. Nebraska tax, line 17 of Form 1040N … 2a. $_ _ b. Total Nonrefundable Credits, line 34 of Form 1040N … 2b. Line 2a minus line 2b … 2. _ If the amount on line 2 is zero or less, enter -0- on line 35 of Form 1040N; and Stop here. Do not complete the remainder of the Worksheet.
- Federal tax before credits: a. Line 16 of Form 1040 or 1040-SR, page 2 … 3a. _ b. Line 2 of Form 1040 Schedule 2 … 3b. c. Line 8 of Form 1040 Schedule 2 … 3c. d. Total tax-Form 1040 or 1040-SR (add lines 3a, 3b, and 3c) … 3d _ Total federal tax (enter tax from line 3d) … 3. _ On line 35, enter the smaller of the amounts from line 2 or line 3 of this worksheet, and check the federal tax box if line 3 is used.
You MUST attach all
Forms W-2G, 1099-R,
1099-MISC, 1099-NEC.
You MUST attach all
Forms W-2.
Line 38 Nebraska Income Tax Withheld from Nebraska Schedules K-1N. Nonresidents claiming credit for Nebraska income tax withholding reported by a partnership, limited liability company, S corporation, estate, or trust must attach a copy of the appropriate Schedule K-1N. The tax year ending date on the Schedule K-1N must be the same as the tax year of the individual's return being filed.
Line 39 .Pass-Through Entity Tax (PTET). Individuals claiming credit for the PTET credit received from an electing partnership or S corporation in which you hold an ownership interest, must attach a copy of the appropriate Schedule K-1N. Enter the pass-through entity's name in 39a, Nebraska ID Number in 39b, and the amount of the credit in 39c. If the PTET credit was received from multiple pass-through entities, attach a schedule listing the name, Nebraska ID number, and amount of credit from each PTET.
Required supporting documentation may be submitted as an attached PDF document when e-filing your return, if your software supports these types of attachments. If the supporting documentation is not received with the return, DOR may request the required documentation during the processing of your return. This may result in a delayed, reduced, or disallowed refund.
Line 40 2025 Estimated Tax Payments. Report your 2025 estimated income tax payments and any tax year 2024 carryover on this line. Include any payments submitted with an extension request.
If you file a married, filing jointly return, the name and SSN of the spouse whose SSN was used to make the 2025 estimated income tax payments should be listed first in the name and SSN area on the
Form 1040N. You are encouraged to make your estimated income tax payments using DOR's e-pay system, or the EFW option when e-filing your 2025 Nebraska return, which allows you to schedule all four of your estimated income tax payments at one time. A Form 1040N-ES payment voucher should NOT be mailed in when you pay electronically.
Distributors and operators of cash devices will enter the total of their required quarterly income tax payments made with the total of any estimated tax payments made.
Line 41 Form 3800N Refundable Credit. Enter the total of refundable credits calculated on Form 3800N.
Attach Form 3800N. Required supporting documentation may be submitted as an attached PDF document when e-filing your return, if your software supports these types of attachments. If the supporting documentation is not received with the return, DOR may request the required documentation in order to process your return. This may result in a delayed refund. Your income tax refund may also be delayed if the business entity that distributed the Form 3800N credit to you has not yet filed its entity income tax return.
Line 42 Nebraska Child/Dependent Care Refundable Credit (AGI $29,000 or Less and Full-Year or Partial-Year Resident). Attach the Nebraska Child And Dependent Care Expenses, Form 2441N, to your Nebraska return. If Form 2441N is not received, the credit will be disallowed. Taxpayers who file married, filing jointly federally, but file married, filing separately on their Nebraska return cannot claim this Nebraska credit.
Note: The Federal Form 2441 will not be accepted when claiming the Nebraska child/dependent care refundable credit. Nebraska Form 2441N must be completed and attached.
Line 43 Beginning Farmer Credit (NDA NextGen). Enter the credit granted to eligible claimants who receive a Statement of Nebraska Tax Credit, Form 1099 BFC, from the Nebraska Department of Agriculture (NDA). For further information, contact NextGen, which administers the Beginning Farmer Tax Credit Act through the NDA at 402-471-4876, nextgen.nebraska.gov.
# Line 44
Nebraska Earned Income Credit. Paper filers must attach a copy of pages 1 and 2 of Federal Form 1040 or pages 1, 2, and 3 of Federal Form 1040-SR to your Nebraska return. Nebraska residents and partial-year residents who have a federal earned income credit are allowed a state credit equal to 10% of the federal credit. Complete the federal credit information from line 27a (Form 1040 or 1040-SR, page 2). Enter the number of qualifying children using information from Federal Schedule EIC (Form 1040). If you are a nonresident, you cannot claim this credit.
If you file a Nebraska married, filing separately return, your ability to claim this credit depends on whether you are allowed the federal EIC on your federal married, filing separately return.
Partial-year residents enter amount calculated on line 12, Nebraska Schedule III.
Attach Form 3800N
You MUST attach all the Schedules K-1N.
You MUST attach a copy of the Schedule K-1N.
Line 45 Credit for Community College Property Taxes. Enter the credit calculated on line 1 of the Form
PTC. The completed Form PTC is required to be filed with the return when claiming the credit.
Line 46 Credit for Qualified Volunteer Emergency Responders. A $250 income tax credit is available to each qualified volunteer who has been certified by the volunteer department's certification administrator and this certification has been sent to DOR by February 15 of the year following qualification.
DOR must have received certification of the qualified volunteer for at least two years to claim the tax credit. A qualified volunteer is an emergency responder, rescue squad member, or volunteer firefighter who has accumulated at least 50 points during each year of service. Additional information can be found on DOR's Volunteer Emergency Responders Incentive Act General Information page.
Line 47 Stillborn Child Tax Credit. A parent who experienced the stillbirth of a child in Nebraska may qualify for a $2,000 income tax credit upon meeting all the following requirements: u The parent would have been eligible to claim the stillborn child as dependent if the child had been born alive. u The Birth Resulting in a Stillbirth Certificate issued by the Nebraska Department of Health & Human Services must be attached when claiming the credit. u The stillborn child advanced to at least the twentieth week of gestation. u This credit must be claimed for the taxable year in which the stillbirth occurred.
Only one credit is allowed per stillborn child. If you experienced more than one birth of a stillborn child, attach the Birth Resulting in a Stillbirth Certificate for each child and allow $2,000 for each stillborn child, entering the total on line 47.
Line 48 Child Care Tax Credit for parent or legal guardian. Prior to claiming the tax credit, the parent or legal guardian must submit the Child Care Refundable Tax Credit Application, Form 7203 to DOR. After the Form 7203 is reviewed, DOR will notify the parent or legal guardian of the reserved tax credit and the assigned certificate number to claim the tax credit. To claim the tax credit, the certificate number must be entered. The information on the individual income tax return must support the information submitted on the Form 7203. The tax credit amount claimed cannot exceed the amount reserved from the submitted Form 7203. Do not claim this credit if your federal AGI reported on line 5 exceeds $150,000.
Line 49 School Readiness tax credit for qualified staff member. An income tax credit is available to an individual who is employed with, or who is a self-employed individual providing child care and early childhood education for, an eligible program for at least six months during the taxable year and who is classified in the Nebraska Early Childhood Professional Record System. Applications for the School Readiness Tax Credit - Staff Member, Form SR-3605, must be submitted electronically through the Electronic Document & Application Submission Hub (eDASH). DOR will publicize on our website the date the applications will be available for submission. Sign up for a free subscription service at the DOR's website to receive email updates regarding the applications availability. The credit may only be claimed after the application has been approved in writing by DOR. Enter the certificate number and the credit amount from your approved Form SR-3605. For additional information, see DOR's website.
Nebraska Earned Income Worksheet for Taxpayers Claiming a Net Operating Loss Deduction (NOL) Complete this worksheet only if you are claiming an NOL carryforward on Federal Form 1040 or 1040-SR.
- Earned Income. Enter the amount from the line 27a, Form 1040 or 1040-SR instructions, Step 5, line 5. . . . . 1. $__
- Federal Net Operating Loss (NOL) Carryforward, from line 8a, Schedule 1, Federal Form 1040 … 2. $__
- Earned income plus Federal NOL Carryforward.
Line 1 plus line 2 … 3. $__
If line 3 is less than:
$61,555 ($68,675 if married, filing jointly) for three or more qualifying children;
$57,310 ($64,430 if married, filing jointly) for two qualifying children;
$50,434 ($57,554 if married, filing jointly) for one qualifying child; or $19,104 ($26,214 if married, filing jointly) for no qualifying children, calculate the Nebraska earned income credit on line 44, Form 1040N using the amount from line 27a, Federal Form 1040 or 1040-SR. If line 3 equals or exceeds the respective amounts, you do not qualify for the Nebraska earned income credit and line 44, Form 1040N should be -0-.
Line 50 Reverse Osmosis System Tax Credit. The credit may only be claimed after the application has been approved in writing by DOR. Enter the certificate number from the approved Form 1040N-OS.
Additional information may be found on DOR's website.
Line 51 Intellectual and Developmental Disabilities Direct Support Professional Tax Credit. This is a refundable credit for an individual that worked at least six months and 500 hours during the taxable year as a direct support professional. The Intellectual and Developmental Disabilities Direct Support Professional Tax Credit Application, Form 3157-A and the Intellectual and Developmental Disabilities Direct Support Professional Employer Verification, Form 3157-E must be submitted to apply for the credit. Enter the certificate number and credit amount from your approved Form 3157-A. The application forms must be submitted electronically through the Electronic Document & Application Submission Hub (eDASH). DOR will publicize on our website the date the applications will be available for submission. Sign up for a free subscription service at the DOR's website to receive email updates regarding the applications availability. See DOR's website for additional information.
Line 54 Amended Return Only. Overpayment allowed on original return, plus additional overpayments of tax allowed after it was filed. Enter the amount of overpayment allowed on your original income tax return, previous amended income tax returns, or as later corrected by the DOR. This includes:
Amounts refunded;
Amount applied to 2025 estimated income tax; and Donations to the Wildlife Conservation Fund.
Do not include interest received on any refund.
Line 55 Actual tax paid, line 53 minus line 54 (Original returns enter line 53).
Line 56 Penalty for Underpayment of Estimated Tax. Use Nebraska Individual Underpayment of Estimated Tax, Form 2210N, to determine if you owe this penalty. Also, see page 8 of these instructions. If you are required to calculate a Form 2210N penalty, report it on line 56, check the box, and attach Form 2210N to your return. Do not include any late filing penalty on this line.
Amended Return Only. A penalty for underpayment of estimated tax calculated on Form 2210N and reported on an original income tax return cannot be changed unless an amended return is filed on or before the due date of the original income tax return (including any extended due date). Any change being made by the due date should be entered here.
Line 57 Total Tax and Penalty for Underpayment of Estimated Tax. Add lines 35 and 56.
Line 58 Use Tax. Use tax is due on all taxable purchases when Nebraska and any applicable local sales tax is not paid. You may owe use tax if you have not paid the Nebraska sales tax or any applicable local sales tax on purchases delivered into Nebraska from out-of-state, mail order, or Internet sellers. Nebraska law requires that if sales tax is not collected by the seller on any taxable sale, the purchaser must remit the applicable use tax directly to the state. See the Nebraska Use Tax Information Guide for additional information.
Enter your total taxable 2025 purchases if Nebraska sales tax was not collected by the seller. Multiply this amount by 5.5% (.055). If local tax applies, enter your local code from the local sales and use tax codes and rates schedule on page 50 of these instructions, and multiply your total taxable purchases by the local rate (.005, .010, .015, .0175, or .02). Add the state and local tax amounts together and enter on line 58. You can also report only local tax not paid if your vendor charged you the state tax but not the local tax.
Example. You purchase a computer from a seller in South Dakota over the Internet for $1,470 plus $30 shipping and handling charges. Both charges are taxable. The computer is shipped to you in Scottsbluff, Nebraska and no tax is charged or collected by the seller. Your state tax is $83 ($1,500 X 5.5% = $83) and the local tax is $23 ($1,500 X 1.5% = $23). The total use tax owed is $106 ($83 + $23 = $106). When calculating state and local tax, round your results, and then add them together to arrive at your line 54 entry. Round any amount from 50 cents to 99 cents to the next higher dollar. Round any amount less than 50 cents to the next lower dollar.
Note: If you owe use tax to more than one Nebraska local jurisdiction, do not report use tax here.
Instead, report state and local use taxes by filing the Nebraska Individual Use Tax Return, Form 3.
Special state sales and use tax rates apply for your taxable purchases if made inside a good life district
(GLD) that is within city boundaries. If Nebraska sales tax was not collected by the seller for purchases in the GLD within city limits, file the Nebraska Individual Use Tax Return, Form 3 to report the correct GLD code and calculate the applicable state use tax.
Amended Return Only. Use Tax Reported on original return cannot be changed on an amended
Form 1040N. Enter the same amount of use tax reported on the original Form 1040N. An amended Form 1040N cannot be used to change the amount of Nebraska or local use tax reported on the original Form 1040N. Review the following options for changing the use tax reported, and choose the instructions that apply to your situation:
If use tax was not reported on the Form 1040N, but you have use tax to report, file the Nebraska Individual Use Tax Return, Form 3;
If the amount of use tax reported on the Form 1040N needs to be increased, file the Nebraska Individual Use Tax Return, Form 3, and write "Amended" across the top of the return;
If the amount of use tax reported on the Form 1040N needs to be decreased and has not yet been paid, file the Nebraska Individual Use Tax Return, Form 3, and write "Amended" across the top of the return; or If the amount of use tax reported and paid on the Form 1040N needs to be decreased, file a Claim for Overpayment of Sales and Use Tax, Form 7.
Line 59 Total Amount Due. If line 55 is less than the total of lines 57 and 58, subtract line 55 from the total of lines 57 and 58. Enter the amount owed, including the applicable underpayment of estimated income tax penalty. A balance due of less than $2 need not be paid. Unpaid tax is subject to interest at 8% from the original due date to the date the tax is paid. See the DOR Interest Rate Assessed on State Taxes Revenue Ruling for applicable interest rates.
Electronic Funds Withdrawal (EFW). With this payment option, you provide your payment information within your electronically-filed return. Your payment will automatically be withdrawn from your bank account on the date you specify.
Cancel a payment. To cancel a scheduled EFW payment, contact our Taxpayer Assistance office at 800-742-7474 (NE and IA) or 402-471-5729 before 4:00 pm Central Time at least two business days prior to your scheduled payment date. You may cancel a payment scheduled through Nebraska e-pay by logging into the e-pay program from our website and selecting "cancel payment." To cancel a credit card payment, contact ACI Payments, Inc.
Nebraska e-pay. Nebraska e-pay is DOR's web-based electronic payment system for single payments. You enter your payment and bank account information, and choose a date to have your account debited. You will receive an email confirmation for each payment scheduled.
Credit Card. Secure credit card payments can be initiated through ACI Payments, Inc. at acipayonline.com; or via phone at 800-272-9829. A convenience fee is charged to the card you use. This fee is paid to the credit card vendor, not the state, and will appear on your credit card statement separately from the payment to DOR. At the end of your transaction, you will be given a confirmation number. Keep this number for your records. If you are making your credit card payment by phone, you will need to provide the Nebraska Jurisdiction Code, which is 3700.
Check or Money Order. If you are not using one of the electronic payment options described above, include a check or money order payable to the "Nebraska Department of Revenue." Checks written to DOR may be presented for payment electronically.
Payment Plan. If you are unable to pay the full amount of tax due, you should file your Nebraska income tax return and pay as much as you can by the filing date. You will receive a balance due notice in the mail. When that is received you can go online to set up a payment plan for the remaining balance, subject to applicable fees. Interest on unpaid tax will accrue.
Please see our website at revenue.nebraska.gov/individuals/request-individual-tax-payment-plan.
Line 60 Overpayment. If line 55 is more than the total of lines 57 and 58, subtract this total from line 55 and enter your overpayment.
Line 61 2026 Estimated Tax. Original Returns Only, skip line 61 if you are filing an amended return.
Enter the amount of overpayment from line 60 you want applied to your 2026 estimated income tax.
Line 62 Wildlife Conservation Fund. Original Returns Only, skip line 62 if you are filing an amended return. You may contribute $1 or more of your refund to this fund. Your contributions are used by the Nebraska Game and Parks Commission to protect and manage Nebraska's nongame and at-risk birds, mammals, amphibians, fish, reptiles, plants, and invertebrates. The fund will help prevent species from becoming endangered by managing, restoring, and protecting their habitat.
If you are not entitled to a refund, you may still send your tax-deductible contribution directly to the Wildlife Conservation Fund at outdoornebraska.gov/wildlifeconservationfund. For more information, contact the Nebraska Game and Parks Commission, Wildlife Division, PO Box 30370, 2200 North 33rd Street, Lincoln, NE 68503-0370, call 402-471-0641, or visit outdoornebraska.gov.
Line 63 Amount You Want Refunded to You. For original returns, line 60 minus lines 61 and 62. For amended return, enter amount from line 60. Amounts less than $2 will not be refunded. Refunds on amended returns are not applied to estimated tax. If you are owed interest on a refund, it will be calculated by the DOR and added to the amount shown on line 63.
If a taxpayer has any existing tax liabilities owed to DOR, the federal government, or other state agencies, any overpayment shown on this return may be applied to satisfy that liability. You will receive a letter explaining any amounts retained.
You can check the status of your refund at revenue.nebraska.gov/individuals/refund-information or by calling DOR's refund line 800-742-7474 (NE and IA) or 402-471-5729.
Refunds resulting from paper-filed returns will not be paid interest. Unless prohibited by statute, refunds not processed within 90 days on e-filed amended returns may qualify for interest payable.
Nebraska law provides:
"If the Tax Commissioner approves and implements an electronic form or method for filing the return and the return is not filed electronically, no interest shall be allowed under this section on overpayment."
Neb. Rev. Stat. § 77-2794(3)(b).
The Tax Commissioner has approved and implemented e-filing methods for original individual income tax returns.
Amended Returns. Complete the section after line 63 before completing the direct deposit information.
Select the boxes to identify reasons for amending the previous return filed. Amended returns must complete the Explanation of Changes section.
Line 64 Direct Deposit Your Refund. To have your refund directly deposited into your checking or savings account, enter the routing number and account number found on the bottom of the checks used with the account. The routing number is listed first and must be nine digits. The account number is listed to the right of the routing number and can be up to 17 digits. Also complete line 64b, Type of Account.
Incorrect banking information will cause your refund to be issued as a paper warrant. Always double check that you entered the correct banking information, since this cannot be changed by DOR.
Box 64d is used to comply with banking rules regarding International ACH Transactions (IATs). The box must be checked whenever a refund will go to a bank account outside the U.S. or if a refund is sent to a bank account inside the territorial jurisdiction of the U.S. and 100% of the original refund is later transferred to a bank outside of the U.S. These refunds cannot be processed as direct deposits and instead will be mailed. sign Sign and Date Your Tax Return. Include a daytime phone number in case DOR needs to contact here you about your account.
Email. By entering an email address, the taxpayer acknowledges that DOR may contact the taxpayer by email. The taxpayer accepts any risk to confidentiality associated with this method of communication.
DOR will send all confidential information by secure email or the State of Nebraska's file share system.
If you do not wish to be contacted by email, write "Opt Out" on the line labeled "email address."
A married, filing jointly return must be signed by both spouses. If another person signs the return for the taxpayer, a copy of a Power of Attorney, Form 33 or court order authorizing the person to sign the return must be on file with DOR or attached to the return.
An unsigned return delays processing.
The act of e-filing a return is your signature. By e-filing the return, taxpayers and their tax preparer, if applicable, are declaring under penalties of perjury, that they have examined the electronic return, and to the best of their knowledge and belief, it is true, correct, and complete.
Paid Preparer's Use Only. Any person who is paid for preparing a taxpayer's return must sign the return as preparer. Additionally, the preparer must enter his or her Preparer Tax ID Number (PTIN) and Federal Employer ID Number (EIN). See DOR's website for preparer e-file mandates.
Filing on Behalf of a Deceased Taxpayer. A spouse claiming a refund on a married, filing jointly return with a deceased spouse should not file Form 1310N. Paper filers sign the Form 1040N as "surviving spouse" for the deceased taxpayer. All others must submit the Form 1310N if a refund is being claimed on behalf of a deceased taxpayer.
22 revenue.nebraska.gov
# Nebraska Schedule I Instructions
# Part A - Adjustments Increasing Federal AGI
Line 1 Interest Income from All State and Local Obligations Exempt from Federal Tax. List the name of each state or local obligation exempt from federal tax on line 1a, Schedule I. For Nebraska bonds, enter the total amount of interest or dividend income from the obligation listed on line 1a. For non-Nebraska obligations enter the total interest or dividend income, less the related expenses that were not previously deducted. Add the amounts on lines 1b and enter the total on line 1, Schedule I. Attach a schedule, if necessary, listing all the obligations. The information and related amounts entered on lines 1a and 1b must also include amounts from a regulated investment company (including certain mutual funds) attributable to state and local obligations.
To determine whether or not specific bond interest is taxable, you should contact the local government entity or underwriter of the bond issuance. The prospectus is required to contain information regarding tax status. Generally, tax increment financing (TIF) bonds are considered local government obligations and are not taxable federally.
Line 2 Exempt Interest Income from Nebraska Obligations. List the name of each federally tax exempt bond issued by a Nebraska state or local government subdivision on line 2a and the associated amount on line 2b. Then calculate the total by adding all amounts on lines 2b. Attach a schedule, if necessary, listing all the obligations. Income amounts from regulated investment companies attributable to Nebraska source bonds are also included on line 2b.
Build America Bonds. Any federally taxable interest received in 2025 on a Build America Bond previously issued by a Nebraska governmental subdivision may be deducted on line 30, Schedule I, Interest From Federally Taxable Build America Bonds Issued by Nebraska Governmental Units.
Nebraska Highway Bond Act. Any federally taxable interest received in 2025 under the Nebraska Highway Bond Act may be deducted on line 37, Schedule I.
Line 3 Total Taxable Interest Income. Enter the result of line 1 minus line 2.
Line 4 Financial Institution Tax Credit Claimed. Shareholders receiving a Statement of Nebraska Financial Institution Tax Credit, Form NFC, must enter the amount of the tax credit available to you as stated on the 2025 Form NFC on both line 24, Form 1040N, and line 4, Schedule I. A copy of Form NFC must be attached to your return. Required supporting documentation may be submitted as an attached PDF document when e-filing your return if your software supports these types of attachments. If the supporting documentation is not received with the return, DOR may request the required documentation during the processing of your return. This may result in a delayed refund.
Line 5 Nebraska College Savings Program Recapture. If you cancel your Nebraska College Savings Program account or withdraw funds for a non-qualified purpose, the amounts previously claimed as deductions are subject to recapture. Nebraska considers K-12 tuition a non-qualified use of College Savings Program funds. Qualified withdrawals are restricted to paying qualified expenses at schools for higher education (colleges, universities, technical schools, and graduate programs). A federally qualified rollover to a Section 529 plan issued by a state (or entity) other than Nebraska is considered to be a cancellation subject to recapture. The total maximum recapture is the lesser of
(i) the amount previously deducted on all Nebraska returns prior to the cancellation of the college savings program account, or (ii) the amount received upon the cancellation or non-qualified withdrawal of funds. Enter the calculated recapture amount on line 5.
Line 6 Nebraska Enable Plan Recapture. If you cancel your Enable Savings Plan account or make an unqualified withdrawal, the amounts previously claimed as deductions on the account owner's return are subject to recapture. Only the account owner is subject to recapture. The maximum recapture is the lesser of (i) the amount previously deducted on all Nebraska returns prior to the cancellation of the Enable Savings Plan account, or (ii) the amount received upon the cancellation or unqualified withdrawals of funds. Enter the calculated recapture amount on line 6.
Line 7 Federal Net Operating Loss Deduction. Enter the amount of the federal net operating loss carryforward deduction claimed on your federal return. You must include this loss as an increase to AGI. A previously established Nebraska net operating loss may be deducted on line 27, Nebraska Schedule I. Line 8 S Corporation and Limited Liability Company (LLC) Non-Nebraska Loss. Enter the amount of loss from an S corporation or LLC that is not from Nebraska sources. You must include this loss as an increase to AGI.
Line 9 Nebraska PTET Deduction. Enter the Nebraska state and local income, sales, and use taxes deducted under section 164 of the IRC from the Nebraska Schedules K-1N.
Line 10 Relocation Incentive Act (Act) Employee Recapture. If you previously excluded Nebraska source wages under the Act but did not maintain your residence in Nebraska for two full calendar years, the exclusion is subject to recapture. Enter the recaptured amount. The recaptured amount is an underpayment of tax and is due and payable on the tax return due immediately following the loss of residency.
Line 11 Loss on the sale or exchange of gold or silver bullion included in Federal AGI. Add the amount of any net capital loss that is derived from the sale or exchange of gold or silver bullion to the extent included in the federal AGI. Do not add if the loss is derived from the sale of bullion as a taxable distribution from any retirement plan account that holds gold or silver bullion.
Line 12 Food Bank, Food Pantry, Food Rescue Donation amount deducted as a charitable contribution on the federal return. If the food donation was deducted as a charitable contribution on the taxpayer's federal return and you are claiming the food donation tax credit for the same donation, the donation amount used to calculate the certified credit must be added back as an increase to the federal AGI.
Line 13 Total Adjustments Increasing Federal AGI. Add lines 3 through 12, enter here and on line 13, Form 1040N.
# Part B - Adjustments Decreasing Federal AGI
Line 14 State Income Tax Refund Deduction. Enter the amount shown on line 1, Schedule 1, of your Federal Form 1040.
Line 15 U.S. Government Obligations Exempt for State Purposes. Enter the amount of interest or dividend income included in federal AGI from U.S. government obligations exempt from Nebraska tax. List the types of obligations on line 15a and the associated amounts of interest or dividend income received from each on line 15b. Then calculate the total by adding all amounts on lines 15b. Attach a schedule, if necessary, listing all the obligations for which a deduction is claimed. Capital gains from the sale of U.S. obligations are not deductible. For additional information, see the Taxability of Interest and Dividend Income From State, Local, and U.S. Government Obligations Information Guide.
Line 16 Regulated Investment Company Dividends from U.S. Obligations. Enter the amount of government money market or mutual fund dividends issued by regulated investment companies that are obligations of the U.S. government.
The fund must issue you a statement showing the percent of the dividend that represents exempt U.S. government obligations. You must list the name of the fund on line 16a, the total amount of the dividend paid by the fund on line 16b, and the percentage of dividend attributable to U.S. government obligations on line 16c. You then calculate the amount of dividend attributable to U.S. government obligations on line 16d.
Total all calculated dividend amounts on lines 16d and enter the result on line 16. Attach a schedule, if necessary, listing all the obligations and calculations.
Line 18 Benefits Paid by the Railroad Retirement Board. Enter any federally taxed retirement benefits paid by the Railroad Retirement Board (RRB), such as Tier I and Tier II benefits, railroad retirement sick pay, disability, and unemployment benefits, included in federal AGI. List the name of the benefit paid on line 18a and the related amount on line 18b. Filers must attach a copy of Forms RRB-1099, RRB-1099-R, 1099-G, and W-2 from U.S. Railroad Retirement Board Sickness and Unemployment Benefits Section. Paper filers must attach a copy of pages 1 and 2 of Federal Form 1040 or pages 1, 2, and 3 of Federal Form 1040-SR to your Nebraska return.
You must do a computation to determine the Tier I amount if you received both Form SSA-1099 for social security benefits AND Form RRB-1099 for Railroad Retirement Board Tier I payments because the Social Security Benefits Worksheet in the federal tax booklet adds the benefits together to calculate the taxable benefits entered on line 6b of the Federal Form 1040 or 1040-SR.
Use the total amount of Tier I benefits divided by the total benefit amount reported on line 6a of the Federal Form 1040 or 1040-SR to calculate a ratio to six decimal places, then round to five decimals.
For example, .454467, would be rounded to .45447 (45.447%). Multiply this ratio by the amount on line 6b of the Federal Form 1040 or 1040-SR. Enter the result for the Tier I amount on the Nebraska Schedule I.
Line 19 Special Capital Gains/Extraordinary Dividend Deduction. This deduction is available only to Nebraska residents, or partial-year resident while a resident. Enter the amount of the special capital gains or extraordinary dividend. Refer to the Special Capital Gains Election and Computation, Form 4797N, for additional information. The Form 4797N, a copy of Federal Schedule D, and either Sales and Other Dispositions of Capital Assets, Federal Form 8949 or Part IV of Form 4797N, must be attached to your Form 1040N to document your deduction.
Note: If claiming the Extraordinary Dividend Deduction, a copy of Federal Schedule B is required.
Required supporting documentation may be submitted as an attached PDF document when e-filing your return if your software supports these types of attachments. If the supporting documentation is not received with the return, DOR may request the required documentation when processing your return.
This may result in a delayed refund.
Line 20 Nebraska College Savings Program Contribution. If during 2025 you, as an account owner or parent/ guardian custodian of an UGMA/UTMA account, made contributions to one or more college savings accounts established under the Nebraska Educational Savings Plan Trust, then enter the amount of your contributions, up to a maximum of $10,000 ($5,000 if married, filing separately) on line 20.
The Nebraska Educational Savings Plan Trust includes the following Plans: u NEST Direct College Savings Plan; u NEST Advisor College Savings Plan; u Bloomwell 529 Education Savings Plan; and u State Farm 529 Savings Plan.
Only the account owner or parent/guardian custodian of an UGMA/UTMA account who made the contributions may claim this deduction. You cannot deduct contributions made to other states' 529 college savings plans on line 20. However, if an account in another state's plan is rolled over to a Plan in the Nebraska Educational Savings Plan Trust, the amount received in a qualified rollover, up to a maximum of $10,000 ($5,000 if married, filing separately), is eligible for the deduction.
Any withdrawals from the Nebraska College Savings Program to pay K-12 expenses are non-qualified withdrawals and subject to recapture to the extent of any state income tax deductions previously claimed on the Nebraska income tax return. Nebraska law considers K-12 tuition a non-qualified use of Nebraska College Savings Program accounts even though these withdrawals are permissible under federal law.
Qualified withdrawals from the Nebraska College Savings Program accounts must be used to pay qualified expenses at an eligible educational institution (college, university, technical school, trade school, graduate program). In addition, qualified apprenticeship program expenses and payments on qualified education loans of the beneficiary or the beneficiary's sibling (subject to an aggregate lifetime limit of $10,000 per individual) are treated as qualified expenses. For questions about the Nebraska College Savings Program, go to treasurer.nebraska.gov, or contact the State Treasurer's Office at 402-471-2455.
Line 21 Employer Contribution to the Nebraska Educational Savings Plan. Enter the amount included in federal AGI of the contribution made by your employer into a Nebraska educational savings plan trust account owned by you. The employer contribution amount entered on line 21 cannot exceed $10,000 ($5,000 if married, filing separately).
For questions about the Nebraska College Savings Program, go to treasurer.nebraska.gov, or contact the State Treasurer's Office at 402-471-2455.
Line 22 Nebraska Enable Plan Contributions. If during 2025, you made contributions to one or more Enable Savings Plan accounts, enter the account numbers or UGift codes you contributed to and the amount of your contributions, up to a maximum of $10,000 ($5,000 if married, filing separately) on line 22.
You cannot deduct contributions made to other 529A (ABLE) savings plans on line 22. For questions about the Enable Savings Plan, go to treasurer.nebraska.gov, or contact the State Treasurer's Office at 402-450-3134.
Line 23 S Corporation and LLC Non-Nebraska Income. Enter the amount of S corporation or LLC income that is not from Nebraska sources. Attach the Federal Schedule K-1 and Nebraska Schedule K-1N received from the S corporation or LLC. Non-Nebraska income from disregarded LLCs may also be included here. In this instance, there will not be a Federal Schedule K-1 issued. Non-Nebraska income from partnerships, limited liability partnerships, trusts, and other entities cannot be deducted.
Line 24 Nonresident Military Servicemember Active Duty Pay. Enter the amount of nonresident military servicemember active duty pay included in the servicemember's federal AGI. The 2025 Form W-2 issued by the uniformed services to the servicemember must be attached to Form 1040N. The Form W-2 must identify the income as attributable to a state other than Nebraska in box 15. If "NE" is shown on the Form W-2, the adjustment will only be allowed if filing a nonresident return with a filing status of married, filing jointly, and the servicemember and their spouse elect under the federal Veterans Auto and Education Improvement Act of 2022 to use for tax purposes the residence or domicile of the servicemember or spouse; or the permanent duty station of the servicemember that is a state other than Nebraska. Only active duty military service compensation can be deducted on line 24.
Line 25 Income Earned by a Native American Indian in Indian Country. Native American Indians residing in Indian country with income derived from sources within Indian country may deduct this income on line 25.
Line 26 Claim of Right Repayment. Enter the amount required to be included on your federal return for a claim of right repayment.
Line 27 Nebraska NOL Carryforward. Enter the amount of a Nebraska net operating loss carried forward from an earlier year. The Nebraska Net Operating Loss Worksheet, Form NOL, must be completed for the loss year and retained in the taxpayer's records until the loss is used. When the loss is claimed, you must attach a completed Form NOL for each previously established loss year being claimed.
Line 28 Nebraska Agricultural Revenue Bond Interest. Enter the amount of interest income from Nebraska Agricultural Revenue Bonds that is included in federal AGI.
Line 29 Federally Taxable Nebraska Investment Finance Authority (NIFA) Bond Interest. Enter total federally taxable NIFA bond income included in federal AGI.
Line 30 Interest from Federally Taxable Build America Bonds Issued by Nebraska Governmental Units.
Enter the amount of interest from these bonds that is included in federal AGI. This includes interest from NPPD taxable General Revenue Bonds issued June, 2009, 2010 Series A. For additional information, see the Taxability of Interest and Dividend Income From State, Local, and U.S. Government Obligations
Information Guide.
Line 31 Social Security Income. Enter the amount of Social Security income included in federal AGI. The entire social security benefit amount included in the federal AGI can be excluded and no longer has a federal AGI threshold.
The amount claimed cannot exceed the amount shown on line 6b, Federal Form 1040 or 1040-SR, page 1. Paper filers must attach a copy of pages 1 and 2 of Federal Form 1040 or pages 1, 2, and 3 of Federal Form 1040-SR to your Nebraska return.
Line 32 Military Retirement. All military retirees are allowed to exclude 100% of the military retirement benefits from the income subject to Nebraska income tax to the extent included in federal AGI. Enter the amount of military pension included on line 5b, Federal Form 1040 or 1040-SR, page 1. Paper filers must attach a copy of pages 1 and 2 of Federal Form 1040 or pages 1, 2, and 3 of Federal 1040-SR to your Nebraska return.
Military retirement benefits attributable to service in uniformed services include military retirement benefits reported on the IRS Form 1099-R issued by either the U.S. Department of Defense or the U.S.
Office of Personnel Management (OPM).
If the Form 1099-R was issued by OPM, attach documentation from the U.S. Government to support the amount of retirement benefits related to your uniformed service versus your civilian service.
Military retirees of the U.S. Coast Guard, an officer of the Commissioned Corps of the U.S. Public Health Service (USPHS), and an officer of the U.S. National Oceanic and Atmospheric Administration Commissioned Officer Corps (NOAA) may receive qualifying military retirement benefits. The retirement benefit income for U.S. Coast Guard, USPHS, and NOAA retirees may be reported by a payor other than the U.S. Department of Defense or OPM. For example, a Form 1099-R received from the Commanding Officer (RAS), USCG Pay & Personnel Center for military retirement benefits from the U.S. Coast Guard qualifies for the exclusion.
Line 33 Dividends Received or Deemed to be Received from Corporations not Subject to the IRC.
This deduction is generally limited to dividends received or deemed to be received from foreign corporations. Attach statement or tax form issued by the payor supporting this deduction.
Dividends received from domestic corporations are not deductible.
Line 34 Segal AmeriCorp Education Award. Enter the amount of the Segal AmeriCorp Education Award included in federal AGI. The Form 1099-MISC must be attached to Form 1040N when your education award and interest payments total more than $600 in a calendar year. All education award and interest payments are subject to federal income tax, even if they do not total $600.
Line 35 Firefighter Cancer Benefits Act. Attach supporting documentation for amounts received by or on behalf of a firefighter for cancer benefits paid under the Firefighter Cancer Benefits Act.
Line 36 Health Insurance Premiums Paid by Retired Law Enforcement Officers and Professional Firefighters. This deduction requires the retired individual to have been employed full time as a firefighter or certified law enforcement officer for at least 20 years and who is at least 60 years of age as of the end of the 2025 taxable year. Must attach documentation from the human resource department indicating number of years employed full time as a certified law enforcement officer or firefighter and position held, or similar documentation from employers. In addition to proof of full time employment as a certified law enforcement officer or firefighter, the retiree must submit a copy of the health insurance premium notice or other documentation substantiating the amount of the deduction entered.
The deduction amount must not have reduced your income reported on the federal individual income tax return.
Line 37 Interest from Federally Taxable Bonds Issued under the Nebraska Highway Bond Act (Act).
Interest from the Nebraska Highway Bonds issued under the Act may be deducted on this line if taxed federally.
Line 38 Civil Service Retirement Annuities received for being employed by federal government. The decreasing adjustment is limited to annuities received under the Civil Service Retirement System
(CSRS) that were earned from employment with the federal government to the extent included in the federal AGI. The amount claimed must be included on line 5b, Federal Form 1040 or 1040-SR, page 1.
Paper filers must attach a copy of pages 1 and 2 of Federal Form 1040 or pages 1, 2, and 3 of Federal Form 1040-SR to your Nebraska return. Also, documentation identifying the annuity benefits from CSRS must be attached.
Generally, if your benefits are paid under the CSRS or FERS by looking at the first digit of the account number on your CSA-1099, if you received one. u If the first digit is 0, 1, 2, 3, or 4, the benefits are paid out of CSRS. Attach the Form CSA1099-R to your return. u If the first digit is 7 or 9, the benefits are paid out of FERS and don't qualify. u If the first digit is 8, look at your Notice of Annuity Adjustment from the Office of Personnel Management. The notice shows how much of your benefits are paid from CSRS and how much are paid from FERS.
Only the portion paid from CSRS qualifies for this deduction. Attach the Notice of Annuity Adjustment from the Office of Personnel Management and your calculation to your return.
Note: The exclusion does not apply to annuities received under the Federal Employees Retirement
System (FERS). Do not include income from FERS annuities.
Line 39 Interest and principal balance of medical debt discharged under the Medical Debt Relief Act (Act).
Under the Act, the Nebraska State Treasurer (STO) contracts with a medical debt relief coordinator to negotiate discharge of medical debt. Only the interest and principal balance discharged under the Act and included in federal AGI qualifies for the decreasing adjustment. The amount must be included in the federal AGI and documentation indicating the debt was canceled under the Act must be attached.
Line 40 Contributions to the Medical Debt Relief Fund. Only contributions made under the Act administered by the STO may take the decreasing adjustment. Attach information from STO indicating the contribution.
Line 41 Nebraska National Guard income exclusion included in Federal AGI. The 100% National Guard income exclusion is limited to Nebraska National Guard members to the extent the income is included in the federal AGI and the income is received from one of the following sources: u Serving in a 32 U.S.C. duty status such as members attending drills, annual training, and military schools and members who are serving in a 32 U.S.C. active guard reserve or active duty for operational support duty status; u Employment as a 32 U.S.C. federal dual-status technician with the Nebraska National Guard; or u A state active duty (SAD) status.
The exclusion does not include other state's National Guard. Do not include income from Title 10 miliary duty. Submit official documentation from the Nebraska National Guard to support the exclusion taken on the Nebraska Schedule I. Income received under 10 U.S.C. cannot be excluded. If your tax statement includes income received for both Title 32 and Title 10, you must do a computation to determine the Title 32 adjustment amount claimed on the Nebraska Schedule
I and attach documentation to support the amount claimed on this line for the exclusion.
Line 42 Relocation Incentive Act employee wage exclusion. An individual must have moved to Nebraska for the purpose of accepting a position of employment and meet all the requirements to be a qualified employee under the Relocation Incentive Act (Act). The qualified employee can make the one-time election and take the exclusion, if all of the following requirements have been met: u Election is made within two calendar years of becoming a Nebraska resident; u Wages were included in the employee's federal AGI; u Annual wage income of the position accepted is from $70,000 to $250,000 (2025 tax year); and u Employee was not a resident of Nebraska in the year prior to the year in which residency is claimed for the purposes of the exclusion.
If the Nebraska source income on Form W-2 is not between $70,000 to $250,000, a letter from the employer's human resources department must be submitted verifying the annual wage income amount meets the wage requirement under the Act and to support the exclusion of the wages included in the employee's federal AGI.
Note: Provisions in the Relocation Incentive Act are impacted by Neb. Rev. Stat. § 77-3,114. An employee that is employed by a foreign adversarial company cannot take this exclusion. See the Foreign Adversarial Company Notice on DOR's website.
The exclusion is subject to recapture if the qualified employee does not maintain residency in
Nebraska for two full calendar years following the calendar year in which the exclusion was taken.
Line 43 Gain on the Sale or Exchange of Bullion. Subtract the amount of any net capital gain that is derived from the sale or exchange of gold or silver bullion to the extent included in the federal AGI. Submit Form 1099-B or other documentation to support the excluded amount and identify the sale or exchange as gold or silver bullion. Do not subtract if the gain is derived from the sale of bullion as a taxable distribution from any retirement plan account that holds gold or silver bullion.
Line 44 Total Adjustments Decreasing Federal AGI. Total lines 14 and 17 through 43, enter here, and on line 13, Form 1040N.
Full-year Nebraska residents claiming a credit for income tax paid to another state, political subdivision of another state, or the District of Columbia must complete Nebraska Schedule II. Partial-year residents must use Nebraska Schedule III. A separate Schedule II must be completed for each state where income tax was paid. The total credits cannot exceed the Nebraska tax liability. If some income is subject to an income tax of both another state and a political subdivision in that state, complete only one Nebraska Schedule II and combine the state and political subdivision income taxes paid.
Credit for Income Tax Paid to Another State. A credit will not be allowed unless you attach a complete copy of the other state's or political subdivision's tax return, including all schedules. If the tax is not reported on an income tax return, attach a copy of a letter or statement from the other state or political subdivision showing the income and the tax paid. For political subdivisions that do not require a return, attach the Form W-2 showing the subdivision's tax withheld.
Nebraska law does not allow credit for taxes paid to a foreign country or its political subdivisions.
The Special Conversion Chart instructions must be used when Nebraska residents claiming the decreasing adjustment for S corporation or LLC non-Nebraska income is taxed in several states and the apportionment computations for the taxing states exceed 100% of the S corporation or LLC non-Nebraska income.
Please note: This situation is rare and generally, the adjustment on Nebraska Schedule I removing the non-Nebraska income from being taxed by Nebraska is sufficient and apportionment will not exceed 100% in the other states.
Line 1 Total Nebraska Tax. Enter the amount from line 17, Form 1040N.
Line 2 Adjusted Gross Income Derived From Another State. Refer to the Conversion Chart. Enter the amount shown on the return filed with the other state as AGI, or gross income derived from sources within that state. Do not include any income from S corporations or LLCs reported on line 23, Nebraska Schedule I, or income that is not included in federal AGI after Nebraska adjustments from lines 12 and 13, Form 1040N.
Line 3 Calculate the Ratio. Calculate the ratio to six decimal places, and then round to five decimals. For example, if your division result is .123467, round to .12347 (12.347%).
Line 4 Calculated Tax Credit. Multiply the ratio (line 3) by the total Nebraska tax (line 1), Nebraska Schedule II.
Line 5 Tax Due and Paid to Another State. Refer to the Conversion Chart. Enter the amount shown on the return filed with the other state as tax paid to that state. Do not enter the total of the other state's tax withheld. For tax paid to a political subdivision of another state that does not require filing an annual income tax return, enter the income tax withholding for that subdivision.
If you and your spouse file married, filing separately in Nebraska, but file married, filing jointly in another state, attach a calculation of each spouse's share of the total tax paid to the other state. Use the net income of each spouse that is taxed by the other state in the calculation.
Line 6 Allowable Tax Credit. Enter the amount from line 1, 4, or 5, Nebraska Schedule II, whichever is least. Also enter this amount on line 19 of Form 1040N.
# Nebraska Schedule II Instructions
Note: When completing lines 2 and 5 of Nebraska Schedule II, refer to the Conversion Chart on DOR's website.
# Nebraska Schedule III Instructions
Taxpayers filing a nonresident or partial-year resident return must complete Nebraska Schedule III to calculate the tax on their income derived from or connected with Nebraska sources.
Line 1 Income Derived from Nebraska Sources. Enter the total of all income from Nebraska sources. Include all sources and amounts of income and deductions, as they were stated on the federal return. If more space is needed, attach a list of all income sources to Nebraska Schedule III. Partial-year residents must include all items of Nebraska income for a nonresident, plus all income earned while a Nebraska resident that is not taxed by another state. This includes dividends, interest, pension income, sales of intangibles, and wages earned outside Nebraska.
Detailed information on the types of income that must be listed and included on line 1, Schedule III is available on DOR's website. A partial list is shown below: u Wages, salaries, tips, and commissions; u Severance pay associated with Nebraska employment; u Dividends, interest, and other passive income; u Business income; u Farming and ranching income; u Partnership, S corporation, LLC, estate, or trust income; u Gain or loss; u Rent and royalty income; u Lottery prizes; u Net operating loss carryforward; and u Financial institution tax credit claimed.
Income of a Servicemember's Spouse. Under the federal Servicemembers Civil Relief Act (SCRA), Nebraska cannot tax the income of a nonresident servicemember's spouse when the spouse is a nonresident of Nebraska and is in this state only in support of the servicemember. The Veterans Auto and Education Improvement Act of 2022 amended the SCRA to provide an election for married military servicemembers and spouses of servicemembers that applies to any taxable year of marriage, regardless of the date of the marriage, for taxable years beginning on or after January 1, 2023. Military servicemembers and spouses of military servicemembers may elect to use for purposes of taxation: (a) the residence or domicile of the military servicemember; (b) the residence or domicile of the spouse; or (c) the permanent duty station of the military servicemember. The income earned from services performed by the nonresident spouse should not be included as Nebraska source income on line 1, Schedule III. For more information, see the Nebraska Income Tax for U.S. Servicemembers, Their Spouses, and Civilians Working https//revenue.nebraska.gov/files/doc/info/8-364.pdfwith U.S. Forces Information Guide. Line 2 Adjustments as Applied to Nebraska Income. If you claimed adjustments to income on Part II, Schedule 1, Federal Form 1040, a portion of these amounts may be allowable as a deduction on line 2, Schedule III. List the type of adjustment on line 2a and the corresponding amount on line 2b, Schedule
III. For additional information see the Additional Schedule III Instructions beginning on page 32 of these instructions.
Line 4 Ratio, Nebraska's Share of the Total Income. Use the equation to calculate a ratio that represents Nebraska's share of total income. Calculate the ratio to six decimal places and then round to five decimals. For example, if the line 4, Schedule III result is .123467, round to .12347 (12.347%) before computing line 9, Schedule III. Even if line 5, Form 1040N and line 1, Schedule III are negative numbers, the ratio computed in line 4, Schedule III cannot exceed 100%. If the ratio is 100% or more, report 1.00000.
Line 5 Nebraska Taxable Income. Enter the amount from line 14, Form 1040N. Line 6 Nebraska Tax Calculation. Paper filers use the Nebraska Tax Table and the income shown on line 5, Schedule III, to find the tax amount to enter on line 6, Schedule III. Electronic filers must use the Nebraska Tax Calculation Schedule to calculate tax on Nebraska Taxable Income.
Partial-year Residents enter your Nebraska credit for the elderly or disabled, or credit for child/ dependent care expenses. See applicable instructions for lines 20, 23, and 42, Form 1040N. Partial-year residents with federal AGI of $29,000 or less cannot claim child care credit here, and must instead complete line 12, Form 2441N, to calculate the amount to enter on line 42, Form 1040N.
Calculate the Nebraska earned income credit on lines 11 and 12, Schedule III.
Nonresidents are not allowed any credits on the line 6, Schedule III calculation.
Line 7 Nebraska Personal Exemption Credit. Enter your credit for personal exemptions. ($171 multiplied by the number of exemptions shown on line 4, Form 1040N). Do not enter on line 18, Form 1040N.
30 revenue.nebraska.gov
Line 8 Tax After Nebraska Personal Exemption Credit. Line 6, Schedule III, minus line 7, Schedule III.
Line 9 Nebraska Income Tax. Multiply line 8, Schedule III, by the ratio you computed on line 4, Schedule III.
Line 10 Nebraska Other Tax. Complete all of lines 10a-f, Schedule III, that are applicable to your tax calculation. See line 16, Form 1040N instructions.
Lines 11 and 12 Earned Income Credit. Partial-year residents may claim this credit by entering the number of qualifying children on line 11a, Schedule III, and the federal earned income credit information on line 11b, Schedule III. The allowable Nebraska credit is 10% of the federal earned income credit multiplied by the ratio calculated on line 4, Schedule III. Enter the result on line 12, Schedule III, and on line 44, Form 1040N. To receive this credit, paper filers must attach a copy of pages 1 and 2 of their federal return. Nonresidents cannot claim the Nebraska earned income credit.
# Adjustments as Applied to Nebraska Income
# Line 11
# Line 13
# Line 14
# Line 15
# Line 16
# Line 17
# Line 18
# Line 19
# Line 20
# Line 21
# Line 22
# Line 23
# Line 24
# Line 24a
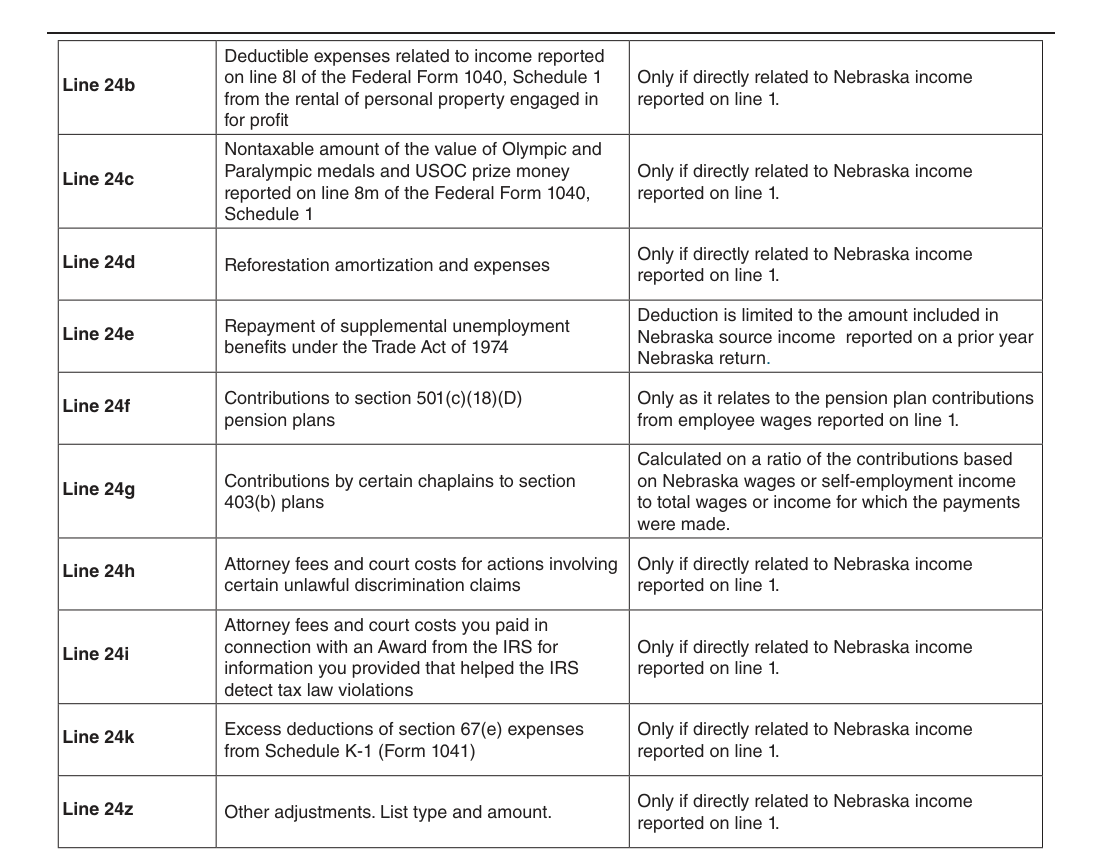
Text version of this table
| Line 24b | Deductible expenses related to income reported on line 8l of the Federal Form 1040, Schedule 1 from the rental of personal property engaged in for profti | Only if directly related to Nebraska income reported on line 1. |
| Nontaxable amount of the value of Olympic and | ||
| Line 24c | Paralympic medals and USOC prize money reported on line 8m of the Federal Form 1040, | Only if directly related to Nebraska income reported on line 1. |
| Schedule 1 | ||
| Line 24d | Reforestation amortization and expenses | Only if directly related to Nebraska income reported on line 1. |
| Line 24e | Repayment of supplemental unemployment beneftis under the Trade Act of 1974 | Deduction is limited to the amount included in Nebraska source income reported on a prior year Nebraska return. |
| Line 24f | Contributions to section 501(c)(18)(D) pension plans | Only as it relates to the pension plan contributions from employee wages reported on line 1. |
| Line 24g | Contributions by certain chaplains to section 403(b) plans | Calculated on a ratio of the contributions based on Nebraska wages or self-employment income to total wages or income for which the payments were made. |
| Line 24h | Attorney fees and court costs for actions involving certain unlawful discrimination claims | Only if directly related to Nebraska income reported on line 1. |
| Line 24i | Attorney fees and court costs you paid in connection with an Award from the IRS for information you provided that helped the IRS detect tax law violations | Only if directly related to Nebraska income reported on line 1. |
| Line 24k | Excess deductions of section 67(e) expenses from Schedule K-1 (Form 1041) | Only if directly related to Nebraska income reported on line 1. |
| Line 24z | Other adjustments. List type and amount. | Only if directly related to Nebraska income reported on line 1. |
# Line 24g
# Line 24z
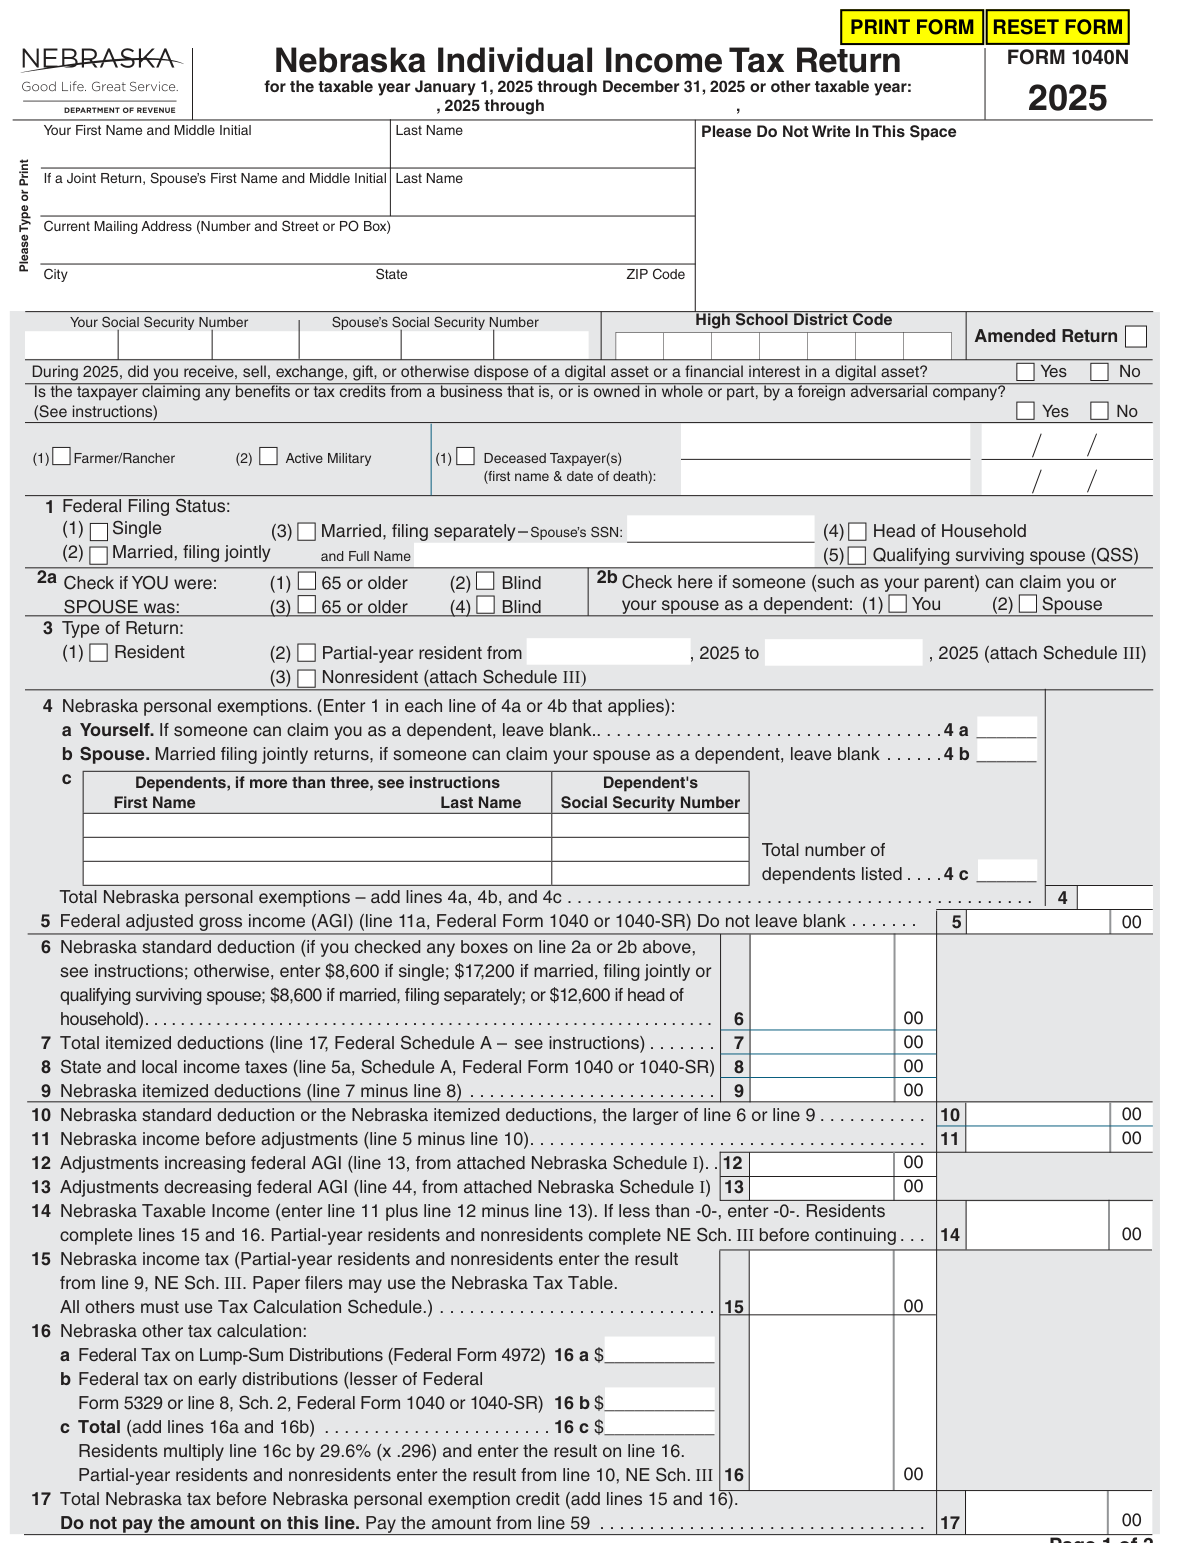
Text version of this table
| PRINT FORM Nebraska Individual Income Tax Return for the taxable year January 1, 2025 through December 31, 2025 or other taxable year: , 2025 through , | PRINT FORM | RESET FORM | ||
| Your First Name and Middle Initial nt | Last Name | Please Do Not Write In This Space | ||
| If a Joint Return, Spouse’s First Name and Middle Initial Last Name Prior Type Current Mailing Address (Number and Street or PO Box) Please City State ZIP Code | Last Name | |||
| Your Social Security Number Spouse’s Social Security Number High School District Code Amended Return During 2025, did you receive, sell, exchange, gift, or otherwise dispose of a digital asset or a financial interest in a digital asset? Yes No Is the taxpayer claiming any beneftis or tax credits from a business that is, or is owned in whole or part, by a foreign adversarial company? (See instructions) Yes No (1) Farmer/Rancher (2) Active Military (1) Deceased Taxpayer(s) (first name & date of death): 1 Federal Filing Status: (1) Single (3) Married, fliing separately – Spouse’s SSN: (4) Head of Household (2) Married, fliing jointly and Full Name (5) Qualifying surviving spouse (QSS) 2a Check if YOU were: (1) 65 or older (2) Blind 2bCheck here if someone (such as your parent) can claim you or SPOUSE was: (3) 65 or older (4) Blind your spouse as a dependent: (1) You (2) Spouse 3 Type of Return: (1) Resident (2) Partial-year resident from / , 2025 to / , 2025 (attach Schedule III) (3) Nonresident (attach Schedule III) 4 Nebraska personal exemptions. (Enter 1 in each line of 4a or 4b that applies): a Yourself. If someone can claim you as a dependent, leave blank. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . 4 a _ ______ b Spouse. Married fliing jointly returns, if someone can claim your spouse as a dependent, leave blank. . . . . . 4 b _ ______ c Dependents, if more than three, see instructions Dependent's First Name Last Name Social Security Number Total number of dependents listed. . . . 4 c _ ______ . 4 5 00 6 Nebraska standard deduction (if you checked any boxes on line 2a or 2b above, see instructions; otherwise, enter $8,600 if single; $17,200 if married, fliing jointly or qualifying surviving spouse; $8,600 if married, fliing separately; or $12,600 if head of household) . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . 6 00 7 Total itemized deductions (line 17, Federal Schedule A – see instructions) . . . . . . 7 00 8 State and local income taxes (line 5a, Schedule A, Federal Form 1040 or 1040-SR) 8 00 9 Nebraska itemized deductions (line 7 minus line 8) . . . . . . . . . . . . . . . . . . . . . . . . . 9 00 10 Nebraska standard deduction or the Nebraska itemized deductions, the larger of line 6 or line 9 . . . . . . . . . . . 10 00 11 Nebraska income before adjustments (line 5 minus line 10) . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . 11 00 12 Adjustments increasing federal AGI (line 13, from attached Nebraska Schedule I). . 12 00 13 Adjustments decreasing federal AGI (line 44, from attached Nebraska Schedule I) 13 00 14 Nebraska Taxable Income (enter line 11 plus line 12 minus line 13). If less than -0-, enter -0-. Residents complete lines 15 and 16. Partial-year residents and nonresidents complete NE Sch. III before continuing . . . 14 00 15 Nebraska income tax (Partial-year residents and nonresidents enter the result from line 9, NE Sch. III. Paper filers may use the Nebraska Tax Table. All others must use Tax Calculation Schedule. ) . . . . . . . . . . . . . . . . . . . . . . . . . . . . 15 00 16 Nebraska other tax calculation: a Federal Tax on Lump-Sum Distributions (Federal Form 4972). 16 a $_ __________ b Federal tax on early distributions (lesser of Federal Form 5329 or line 8, Sch. 2, Federal Form 1040 or 1040-SR) .16 b $_ __________ c Total (add lines 16a and 16b) . . . . . . . . . . . . . . . . . . . . . . . 16 c $_ __________ Residents multiply line 16c by 29. 6% (x . 296) and enter the result on line 16. Partial-year residents and nonresidents enter the result from line 10, NE Sch. III. . 16 00 17 Total Nebraska tax before Nebraska personal exemption credit (add lines 15 and 16). Do not pay the amount on this line. Pay the amount from line 59 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . 17 00 |
# Amended Return
# Nonresident (attach Schedule III)
(3)
4 Nebraska personal exemptions. (Enter 1 in each line of 4a or 4b that applies):
/ a Yourself. If someone can claim you as a dependent, leave blank. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . 4 a _ b Spouse. Married filing jointly returns, if someone can claim your spouse as a dependent, leave blank. . . . . . 4 b _ c Dependents, if more than three, see instructions Dependent's
# 39 Total Pass-Through Entity Tax (PTET) credit from Schedules K-1N
(attach 2025 Schedules K-1N, see instructions) a Name:_ b Nebraska ID Number: c Amount: . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . 39 40 2025 estimated income tax payments (include any 2024 overpayment credited to 2025 and any payments submitted with an extension request). . . . . . . . . . . . . . . . . . . 40 41 Form 3800N refundable credit (attach Form 3800N). . . . . . . . . . . . . . . . . . . . . . . . . . . . 41 42 Nebraska child/dependent care refundable credit, if line 5 is $29,000 or less (attach a copy of Form 2441N) . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . 42 43 Beginning Farmer credit from Form 1099 BFC (NDA NextGen) . . . . . . . . . . . . . . . 43 44 Nebraska earned income credit. Enter number of qualifying children 97 Federal credit 98 $ _. 00 x . 10 (10%) (see instructions) . . . . . . . . . . . . . 44 45 Credit for community college property taxes (attach Form PTC) . . . . . . . . . . . . . . 45 46 Credit for qualified Volunteer Emergency Responders (see instructions) . . . . . . . . . 46 47 Stillborn child tax credit (attach Birth Resulting in Stillbirth Certificate and see instructions) . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . 47 48 Child Care Tax Credit for parent or legal guardian.
Enter certificate number from Form 7203____ . . . . . . . . . . . . . . . . . . . . 48 49 School Readiness Tax Credit for qualified staff member.
Enter certificate number from Form SR-3605____ . . . . . . . . . . . . 49 50 Reverse Osmosis System Tax Credit.
Enter certificate number from Form 1040N-OS____ . . . . . . . . . . . 50 51 Intellectual and Developmental Disabilities Direct Support Professional Tax Credit.
Enter certificate number from Form 3157-A____ . . . . . . . . . . . . . . 51 52 Amount paid with original return, plus additional tax payments made after it was filed (Amended Return Only). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . 52 53 Total payments and refundable credits (add lines 36 through 52). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . 53 54 Overpayment allowed on original return, plus additional overpayments of tax allowed after it was filed (Amended Return Only). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . 54 55 Actual tax paid, line 53 minus line 54 (Original returns enter line 53). . . . . . . . . . . . . . 55
Page 2 of 3.
56 Penalty for underpayment of estimated tax (see instructions). If you calculated a Form 2210N penalty of -0- or greater, or used the annualized income method, attach Form 2210N, and check this box 96 . . . . . . . . . . 56 57 Total tax and penalty for underpayment of estimated tax. Add lines 35 and 56 . . . . . . . . . . . . . . . . . . . . . . 57 58 Use tax due on taxable purchases where applicable sales tax was not collected. (see instructions) Enter purchases subject to state tax 91 $ _ State tax 92 $ _ (purchases x 5. 5%);
Enter purchases subject to local tax 93 $ _ Local tax 94 $ (purchases x local rate of %) 95 Local code_ (see local rate schedule);
Add state and local taxes and enter on line 58. If no use tax is due, enter -0- on line 58 . . . . . . . . . . . . . . . . . . . 58
59 Total amount due. If line 55 is less than total of lines 57 and 58, subtract line 55 from total of lines 57 and 58 59 60 Overpayment. If line 55 is more than the total of lines 57 and 58, subtract the total of lines 57 and 58 from line 55. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . 60 61 Amount of line 60 to be applied to your 2026 estimated tax (Original return only) 61 62 Wildlife Conservation Fund donation of $1 or more (Original return only) . . . 62 63 Amount of line 60 you want refunded to you (line 60 minus lines 61 and 62) Your refund will generally be issued by July 15, if your paper return is filed by April 15 (see instructions). Allow three months for an amended return . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . 63
# Complete FOR AMENDED RETURNS ONLY
Are you filing this amended return because: a. The Nebraska Department of Revenue (DOR) has notified you that your return will be audited? b. The Internal Revenue Service (IRS) has corrected your federal return?
If Yes, identify office:
Are you filing for a refund based on:
NO
YES a. The filing of a federal amended return or claim for refund?
NO
YES
Attach copies of Federal Form 1045 or 1040X and supporting schedules.
NO
YES b. Carryback of a net operating loss or IRC § 1256 loss?
NO
YES
If Yes, year of loss: Amount: $
Attach copies of Federal Form 1045 or 1040X with supporting schedules, Attach a copy of changes from the Internal Revenue Service.
Reasons for Amending
Only Federal change (no NE change) Federal Filing Status change (single, MFJ, MFS, HOH, QSS) K-1N Change and a completed Nebraska NOL Worksheet.
Childcare Credit Change Dependent or personal exemption count change (line 4) Earned Income Credit Change Other Credit Adjustment Property Tax Credit Change (include Other Reason for Amending (explain below) previously claimed parcels on Form PTC).
Use Form PTCX if this is the only change.
Explanation of Changes (Reference change and line number. If necessary attach additional sheets for explanation):
64a Routing Number
64c Account Number
64b Type of Account 1 = Checking 2 = Savings Check this box if this refund will go to a bank account outside the United States.
Under penalties of perjury, I declare that, as taxpayer or preparer, I have examined this return and to the best of my knowledge and belief, it is true, correct, and complete. sign here Your Signature Keep a copy of this return for Date Email Address Spouse's Signature (if filing jointly, both must sign) your records. paid preparer's Preparer's Signature use only Daytime Phone Date Preparer's PTIN Print Firm's Name (or your name if self-employed), Address and ZIP Code EIN Daytime Phone
A copy of the federal return and schedules must be attached to this return.
E-file your return. NebFile offers FREE e-filing of your original state return for most Nebraska residents.
Mail returns requesting a refund to: Nebraska Department of Revenue, PO Box 98912, Lincoln, NE 68509-8912.
Mail returns not requesting a refund to: Nebraska Department of Revenue, PO Box 98934, Lincoln, NE 68509-8934.
Page 3 of 3.
RESET FORM
PRINT FORM
Nebraska Schedule I - Nebraska Adjustments to Income Name on Form 1040N Name on Form 1040N
Schedule I
(Nebraska Schedule II reverse side.)
• Attach this page to Form 1040N.
Social Security Number
Social Security Number
Part A - Adjustments Increasing Federal AGI 1 Interest income from all state and local obligations exempt from federal tax a List type: b Amount: $ Total interest income exempt from federal tax. Enter total of lines 1b … 2 Exempt interest income from Nebraska obligations a List type: b Amount: $ Total exempt interest income from Nebraska obligations. Enter total of lines 2b … 3 Total taxable interest income. Enter the result of line 1 minus line 2 … 3 4 Financial Institution Tax Credit claimed. Enter amount from line 24, Form 1040N … 00 5 Nebraska College Savings Program recapture (see instructions) … 00 6 Nebraska Enable plan recapture … 00 7 Federal net operating loss deduction … 7 8 S corporation or LLC Non-Nebraska loss … 8 9 Nebraska PTET deducted under section 164 of the IRC (from Schedules K-1N) … 9 00 10 Relocation Incentive Act employee recapture (see instructions) … 10 00 11 Loss on the sale or exchange of gold or silver bullion included in Federal AGI (see instructions) … 11 00 12 Food Bank, Food Pantry, Food Rescue Donation amount deducted as a charitable contribution on the federal return (see instructions) … 00 13 Total adjustments increasing federal AGI (total lines 3 through 12). Enter here and on line 12, Form 1040N … 13 00 Part B - Adjustments Decreasing Federal AGI 14 State income tax refund deduction. Enter line 1, Schedule 1, Federal Form 1040 or 1040-SR … 14 15 U.S. government obligations exempt for state purposes (list below or attach schedule) a List type: b Amount: $ Total U.S. government obligations exempt for state purposes. Enter total of lines 15b … 15 16 List fund name, total dividend, and percent of regulated investment company dividends from a U.S. obligation: b Total dividend: $ x c . % = d $ Total regulated investment company dividends. Enter total of lines 16d … 16 17 Total U.S. government obligations. Enter total of lines 15 and 16 … 17 18 Benefits paid by the Railroad Retirement Board (RRB) included in the federal AGI. Attach all Forms 1099 & W-2 from the RRB. a List type: b Amount: $ Total benefits paid by the RRB included in federal AGI. Enter total of lines 18b … 18 19 Special capital gains/extraordinary dividend deduction [attach Form 4797N; a copy of Federal Schedule D; and Form 8949 (or Federal Schedule B when claiming extraordinary dividend deduction)] (see instructions) … 19 00 20 Nebraska College Savings Program contribution (see instructions) … 20 21 Employer contribution to the Nebraska Educational Savings Plan (see instructions) … 21 22 Nebraska Enable plan contributions. List the account number and annual contribution amount for each account you contributed to during this tax year (list below or attach schedule) a Account Number: b Amount: $ Enter total Nebraska Enable plan contributions … 22 23 S corp and LLC Non-Nebraska income (attach Federal schedules K-1 and Nebraska Schedules K-1N) … 23 24 Nonresident military servicemember active duty pay (attach active duty Form W-2, identifying the income as attributable to another state, see instructions) … 24 00 25 Income earned by a Native American Indian in Indian country … 25 00 26 Claim of right repayment … 26 27 Nebraska NOL carryforward (attach the Nebraska NOL Worksheet for each loss year claimed on this line) … 27 28 Nebraska agricultural revenue bond interest … 28 29 Interest from federally taxable Nebraska Investment Finance Association (NIFA) bonds … 29 30 Interest from federally taxable Build America Bonds issued by Nebraska governmental units … 30 31 Social Security included in Federal AGI (see instructions) … 31 00 32 Military retirement benefits (Attach supporting documentation, see instructions) … 32 00 33 Dividends received or deemed to be received from corporations not subject to the IRC (Attach supporting documentation) … 33 34 Segal AmeriCorps Education Award (attach Form 1099-MISC, see instructions) … 34 35 Cancer benefits received from the Firefighter Cancer Benefits Act (Attach supporting documentation, see instructions) … 35 36 Health insurance premiums paid by retired law enforcement officers and professional firefighters (see instructions) … 36 37 Interest from federally taxable bonds issued under the Nebraska Highway Bond Act … 37 00 38 Civil Service Retirement annuities received for being employed by federal gov't (Documentation needed - see instructions) … 38 00 39 Interest and principal balance of medical debt discharged under the Medical Debt Relief Act … 39 00 40 Contributions made to the Medical Debt Relief Fund … 40 00 41 Nebraska National Guard income exclusion included in Federal AGI (see instructions) … 41 00 42 Relocation Incentive Act employee wage exclusion (see instructions) … 42 43 Gain on the sale or exchange of bullion … 43 00 44 Total adjustments decreasing federal AGI (total lines 14 and 17 through 43). Enter here and on line 13, Form 1040N … 44 00
Schedule II
1 Total Nebraska tax (line 17, Form 1040N) … 1 2 Adjusted gross income derived from another state (do not enter amount of taxable income from the other state - use Conversion Chart on the DOR's website) … 2 3 Ratio
# Line 2
(Form 1040N, Line 5 + Line 12 - Line 13) + - 3 4 Calculated tax credit. Line 1 multiplied by line 3 ratio … 4 5 Tax due and paid to another state (do not enter amount withheld for the other state - use Conversion Chart on the DOR's website) … 5 6 Allowable tax credit (line 1, 4, or 5, whichever is least). Enter amount here and on line 19, Form 1040N … 6
• Complete a separate Schedule II for each state.
- A complete copy of the return filed with another state must be attached. If the entire return is not attached, credit for tax paid to another state will not be allowed. Name of state:
Nebraska Schedule II -
Credit for Tax Paid to Another State for FULL-YEAR RESIDENTS ONLY .
= = =
Name on Form 1040N Social Security Number Nebraska Schedule II - Credit for Tax Paid to Another State
Nebraska Schedule III - Computation of Nebraska Tax
Schedule III
- You must complete lines 1 through 14, Form 1040N. If you have state, local, or federal bond interest or other adjustments, complete Parts A and B of Nebraska Schedule I. Use Schedule III to calculate your Nebraska tax liability.
• You do not have to provide a copy of other state returns when filing Schedule III.
Nebraska Schedule III -
Computation of Nebraska Tax for PARTIAL-YEAR RESIDENTS AND NONRESIDENTS ONLY .
1 Income derived from Nebraska sources. Include income from wages, interest, dividends, business, farming, Nebraska unemployment payments, severance payments connected to Nebraska employment, partnerships, S corporations, limited liability companies, estates and trusts, gain or loss, rents, royalties, and financial institution tax credit amount. If there is no Nebraska income or loss, enter -0-. a List type: b Amount: $ List type: Amount:
Total income derived from Nebraska sources. Enter total of lines 1b … 1 2 Adjustments as applied to Nebraska income, if any (see instructions) a List type: b Amount: $ List type: Amount:
Total adjustment as applied to Nebraska income. Enter total of lines 2b … 2 3 Nebraska adjusted gross income (line 1 minus line 2) … 3 4 Ratio - Nebraska's share of the total income (calculate to six decimal places, and round to five): …
# Line 3
(Form 1040N, Line 5 + Line 12 - Line 13) + - 4 5 Nebraska Taxable Income (line 14, Form 1040N) … 5 6 Nebraska tax calculation (see instructions) a Tax on Nebraska Taxable Income from line 5 … 6 a_ $_ _ b Partial-year residents, enter Nebraska nonrefundable credit for the elderly or disabled... 6 b $_ c Partial-year residents, enter Nebraska child/dependent care nonrefundable credit … 6 c_ $_ d Subtotal credits (add lines 6b and 6c) … 6 d_ $_ Line 6a minus line 6d … 6 7 Multiply Nebraska personal exemption credit of $171 by the number of Nebraska personal exemptions on line 4, Form 1040N … 7 8 Tax after Nebraska personal exemption credit (line 6 minus line 7). If less than $0, enter -0- here, and if you have any other tax due, apply any unused Nebraska personal exemption credit against that tax on line 10e … 8 9 Nebraska income tax. Multiply line 8 by the ratio you computed on line 4. Enter result here and on line 15, Form 1040N … 9 10 Nebraska other tax calculation: a Federal Tax on Lump Sum Distributions (Form 4972) … 10 a $_ b Federal tax on early distributions (lesser of Form 5329 or line 8, Schedule 2, Federal Form 1040 or 1040-SR) … 10 b $_ c Subtotal (add lines 10a and 10b) … 10 c $_ d Tax calculation. Multiply line 10c by 29.6% (x .296) … 10 d $_ e Enter any unused Nebraska personal exemption credit from the calculation on line 8 .10 e $_ f Subtract line 10e from line 10d … 10 f $_ Multiply line 10f by line 4 ratio. Enter result here and on line 16, Form 1040N … 10 11 Earned income credit (Partial-Year Residents Only) a Number of qualifying children. Enter here and on line 44, box 97, Form 1040N … 11 a _ b Enter the federal earned income credit from federal tax return on line 11b and on line 44, box 98, Form 1040N … 11 b $_ __ Multiply line 11b amount by 10% (x .10). Enter the result here (see instructions) … 11 12 Nebraska earned income credit. Multiply line 11 by the ratio you computed on line 4.
Enter result here and on line 44, Form 1040N … 12 = = = Name on Form 1040N Social Security Number
# Nebraska Property Tax Credit
FORM PTC
Use this Form with the Forms noted below to claim the property tax credit. 2025 Enter the Part B information for each parcel from the Look-up Tool. Name on Tax Return Type of Nebraska Tax Return this Form is being filed with 1040N 1041N 1065N Social Security Number or Nebraska ID Number 1120N 1120NF 1120-SN Part A - Computation of the Credit 1 Credit for community college property taxes.
Enter the line 2a amount here and on Form 1040N, Form 1041N, Form 1120N, Form 1120-SN, Form 1065N, 1 00 or Form 1120NF as appropriate … Part B - Community College Property Taxes Paid in 2025 2 Community college property taxes paid in 2025.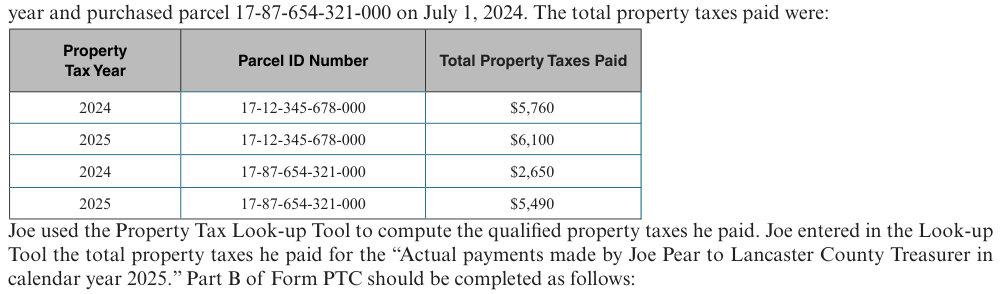
Nebraska Community College
(Must include the dashes for
Property Taxes You Paid
Lancaster County.)
Total eligible community college property taxes you paid in 2025 … 2a 00
# Instructions
If you paid Nebraska property taxes yourself directly or through your monthly payments into escrow, use this form to claim the property tax credit. Look up your parcel in the Nebraska Property Tax Look-up Tool (Look-up Tool) to complete line 2. Enter the line 2a amount on line 1.
Purpose. The Nebraska Property Tax Credit, Form PTC, is used to identify parcels and compute a tax credit for Nebraska community college property taxes (qualified property taxes) paid.
Nebraska Property Tax Look-up Tool. You can determine the amount of qualified property taxes paid on a parcel in the 2025 calendar year, by using the Nebraska Department of Revenue's (DOR's) Nebraska Property Tax Lookup Tool. DOR strongly recommends using this Look-up tool.
Qualified Property Taxes Paid. The qualified property taxes are paid on the date received by the county treasurer.
The date qualified property taxes were received is affected by the following rules.
- Mortgage Escrow Accounts. When your payment to a mortgage company includes an escrow for property taxes, the date the county treasurer receives payment from the escrow account is the date the qualified property taxes were paid;
- Parcel Sales - Property Taxes Funded. When you fund property taxes at closing, the related qualified property taxes were paid when received by the county treasurer. You may claim the allowable credit only for the calendar year that the county received the money from the escrow agent;
- Parcel Sales - Property Taxes Reimbursed. When the buyer reimburses the seller for property taxes that were already paid, the buyer cannot take the credit on any portion of the reimbursement because the county treasurer already received the taxes paid by the seller.
- County Treasurer Escrow Accounts. When you make partial property tax payments that are held in escrow by the county treasurer, qualified property taxes are paid when applied to the parcel in the records of the county treasurer.
- Tax Sale Certificate. The qualified property taxes are received by the county treasurer when collected from the person that purchased the tax sale certificate. Persons who redeem the tax certificate are repaying a loan to obtain a lien release. The redeemer cannot take the credit for the redemption.
The DOR obtains property tax data from each county treasurer. That data includes the amount of property taxes received during a calendar year. The DOR will use the county treasurer receipt data, unless you can show the county treasurer's data is incorrect.
Limitation on Qualified Property Taxes. Qualified property taxes paid do not include property taxes levied for bonded indebtedness, taxes levied as a result of an override of the limits on property tax levies approved by voters, or credits applied to the property taxes levied. The Look-up Tool automatically takes these items into account in computing the qualified property taxes paid.
Qualified property taxes paid do not include property taxes that were five years or more delinquent at the time of payment.
Enter All Qualified Property Tax Amounts as Whole Dollars. Round any amount from 50 cents to 99 cents to the next higher dollar. Round any amount less than 50 cents to the next lower dollar.
Records. All taxpayers must retain records for at least three years after filing the tax return claiming the credit for qualified property taxes paid. Taxpayers using the DOR's Look-up Tool should print or save the information provided by the Look-up Tool.
Who Must File. Form PTC must be filed by the individual, corporation, partnership, LLC, fiduciary, or financial institution that paid the tax and is claiming the credit.
When and Where to File. Form PTC must be filed with the Nebraska income tax or financial institution tax return on which the credit is claimed.
# How to Complete the Form PTC
Taxpayers claiming the credit should complete Part B before completing Part A. This form can be completed quickly and easily using the Look-up Tool.
# Part A - Computation of the Credit
Part A is used to compute the credit for qualified property taxes paid and reported in Part B.
# Part B - Community College Property Taxes Paid in 2025
Part B is used by individuals, C corporations, S corporations, partnerships, LLCs, financial institutions, and fiduciaries that paid qualified property taxes in 2025.
Fiscal Year and Short Year Filers. The credit may be claimed in the first income tax year that begins in the calendar year the qualified property taxes were paid.
Fiscal Year Filers. Taxpayer's with a fiscal year beginning in 2025 and ending in 2026 may complete Part B for qualified property taxes paid during the entire 2025 calendar year. The credit claimed in this fiscal year cannot include any qualified property taxes paid in 2026.
Short Year Filers. Taxpayers with a short period beginning in 2025 and ending in 2026. If this is the first short year beginning in 2025, complete Part B for qualified property taxes paid during the entire 2025 calendar year.
Taxpayers with a short period beginning and ending in 2025. If this is the first short year beginning in 2025, complete Part B for the qualified property taxes paid during the entire 2025 calendar year. You may have to file an extension to be sure that the information will be available in Look-up Tool at the time you file the first short year return. Taxpayers filing for the second short period beginning in 2025 cannot claim the credit on the second short period return.
Information must be entered separately for each parcel for which qualified property taxes were paid in calendar year
- A separate entry must also be made for each property tax year for which qualified property taxes were paid in
- If Part B does not have enough rows to include all the parcels or years for which you paid qualified property taxes, attach a schedule in the same format as Part B.
Example 1. Joe Pear owns two parcels in Lancaster County and paid property taxes on those parcels for the 2024 and 2025 property tax year during the 2025 calendar year. Joe owned parcel 17-12-345-678-000 for the entire 2025 calendar year and purchased parcel 17-87-654-321-000 on July 1, 2024. The total property taxes paid were:
Property
# Total Property Taxes Paid
$5,760
$6,100
$2,650
$5,490
Joe used the Property Tax Look-up Tool to compute the qualified property taxes he paid. Joe entered in the Look-up Tool the total property taxes he paid for the "Actual payments made by Joe Pear to Lancaster County Treasurer in calendar year 2025." Part B of Form PTC should be completed as follows:
Nebraska County Number
Property
(Do not enter county numbers
Tax Year from license plates.)
2024 55
2025 55
2024 55
2025 55
Nebraska Community College
(Include the dashes for
Property Taxes You Paid
# Lancaster County.)
17-12-345-678-000 259
17-12-345-678-000 275
17-87-654-321-000 119 00
17-87-654-321-000 247 00
900 00
Total eligible community college property taxes you paid in 2025 … Property Tax Year. Enter the property tax year for which the qualified property taxes were levied. Most taxpayers pay their property taxes in the year after the taxes were levied. If more than one year of property taxes were paid in the 2025 calendar year, a separate entry must be made for each property tax year. See example 1 above.
Nebraska County Number. Enter the number assigned to the county where the parcel is located. This number is provided by the Look-up Tool or may be found on the County Parcel ID Search. This number is not the same as the county number used for license plates. Do not enter the county number from a license plate.
Parcel ID Number. Enter the parcel ID number assigned by the county assessor to the parcel. This number may be found on the Real Estate Tax Statement issued by the county treasurer where the parcel is located. The parcel ID number may also be found using the Look-up Tool. Some counties use the term "property ID" rather than "parcel ID". Parcel ID numbers assigned by Lancaster County include dashes. The parcel ID number entered on Form PTC for parcels located in Lancaster County must include the dashes. The parcel ID numbers for the other 92 counties have either 9 or 10 digits and no dashes.
Qualified Property Taxes Paid. Enter the amount of qualified property taxes you paid on the parcel during the 2025 calendar year. This amount may be computed using the Look-up Tool or the taxpayer's records. Those records include, but are not be limited to, the Real Estate Tax Statement issued by the county treasurer where the parcel is located. Any property taxes paid that were delinquent for five years or more at the time of payment cannot be included in the tax credit calculation.
LB 34 enacted in the 2024 special session created the School District Property Tax Relief Act. This act provides property tax relief for school district taxes directly on the property tax statement reducing property taxes before they are paid, instead of refunding taxes after they are paid.
For tax years beginning on or after January 1, 2024, the Form PTC will only be used to claim a credit for community college property taxes paid.
Total Community College Property Taxes Paid in 2025. On line 2a enter the sum of the community college property taxes paid on the parcel or parcels listed in Part B.
# 2025 Public High School District Codes
High school district code information is required by law so the
All taxpayers who are Nebraska residents on
Nebraska Department of Education can determine state aid December 31, 2025, are required to enter the Public allocations to Nebraska's K-12 school systems.
High School District Code on Form 1040N.
Take the following steps: Example: Matt and Jill live in Banner County and the Bayard 21 high school district.
- On this 2025 Public High School District Codes listing, find your county of residence.
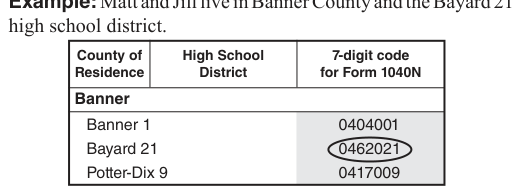
Text version of this table
| County of Residence | High School District | 7-digit code for Form 1040N |
| Banner | ||
| Banner 1 Bayard 21 Potter-Dix 9 | 0404001 0462021 0417009 |
- Find the high school district where you live.
- Find the seven-digit code for your high school district.
- Enter the seven-digit code for your high school district Potter-Dix 9 on Form 1040N.
They enter the following on their Form 1040N:
If you fail to include your high school district code on your return, processing of your return and any High School District Code refund may be delayed.
0 4 6 2 0 2 1
7-digit code
County of High School
High School
County of High School 7-digit code Residence District
County of
Residence District
7-digit code County of High School Residence District 7-digit code for Form 1040N Residence District for Form 1040N for Form 1040N
Adams
Adams Central High 90 0101090
Blue Hill 74 0191074
Brown
Ainsworth 10 for Form 1040N
Cedar (continued)
Laurel-Concord-
Cuming (continued)
Scribner-Snyder 62 2027062
Keya Paha Co High 100
Doniphan-Trumbull 126 0140126
Hastings 18 0101018
Kenesaw 3 0101003
Lawrence/Nelson 5 0165005
Minden R3 0150503
Sandy Creek 1C 0118501
Shelton 19 0110019
Silver Lake 123 0101123
Antelope
Boone Central 1 0206001
Creighton 13 0254013
Elgin 18 0202018
Elkhorn Valley 80 0259080
Neligh-Oakdale 9 0202009
Plainview 5 0270005
Summerland 115 0202115
Arthur
Rock Co High 100
Sandhills 71
Valentine High 6
Buffalo
Amherst 119
Ansley 44
Centura 100
Elm Creek 9
Gibbon 2
Kearney 7
Pleasanton 105
Ravenna 69
Shelton 19
Sumner-Eddyville-
Miller 101
Burt
Coleridge 54
Randolph 45
Wausa 76R
Wynot 101
Chase
Chase County
Schools 10
Perkins County
Schools 20
Wauneta-Palisade 536
Cherry
Cody-Kilgore 30
Gordon-Rushville
High Sch 10
Hyannis 11
Mullen 1
Thedford High 1
1414054 West Point 1 2020001
1414045 Wisner-Pilger 30 2020030 1454576 Custer Anselmo-Merna 15 2121015 Ansley 44 2121044 Arcadia 21 2188021 1515010 Arnold 89 2121089 Broken Bow 25 2121025 1568020 Callaway 180 2121180 1515536 Cozad 11 2124011 Gothenburg 20 2124020 Litchfield 15 2182015 Loup Co 25 2158025 Ord 5 2188005 Sandhills 71 2105071 Sargent 84 2121084 Sumner-Eddyville-Miller 101 2124101 Bancroft-Rosalie 20 Arthur Co High 500 0303500
Banner
Banner 1 0404001
Bayard 21 0462021
Logan View 594
Lyons-Decatur
Northeast 20
Oakland-Craig 14
Valentine High 6
Cheyenne
Creek Valley 25
Leyton 3
Potter-Dix 9
Dakota
Allen 70 2226070
Emerson-Hubbard 561 2226561
Homer 31 2222031
Tekamah-Herman 1
Potter-Dix 9 0417009
Blaine
Anselmo-Merna 15 0521015
Loup Co 25 0558025
Sandhills 71 0505071
Sargent 84 0521084
Butler
Centennial 67R
Columbus 1
David City 56
East Butler 2R
Sidney 1
Clay
Adams Central High 90
Blue Hill 74
Davenport 47
Doniphan-
Ponca 1 2226001
So Sioux City 11 2222011
Dawes
Chadron 2 2323002
Crawford 71 2323071
Hay Springs 3 2381003
Lakeview Community 5
Boone
Trumbull 126 Hemingford 10 2307010 Raymond Central 161 Boone Central 1 0606001 Central Valley 60 0639060 Elgin 18 0602018 Schuyler Central High 123 Seward 9 Harvard 11 Lawrence/Nelson 5 Sandy Creek 1C Shickley 54 Sioux Co High 500 2383500 1865005 Dawson Callaway 180 2421180 Cozad 11 2424011 Shelby-Rising City 32 Elkhorn Valley 80 0659080 Fullerton 1 0663001 Newman Grove 13 0659013
Cass
Sutton 2
Colfax
Elm Creek 9 2410009
Elwood 30 2437030
Ashland-Greenwood 1
Riverside 75 0606075
St. Edward 17 0606017
Conestoga 56
Clarkson 58
Howells-Dodge 70
1919058 Eustis-Farnam 95 2432095 1919070 Gothenburg 20 2424020 Elmwood-Murdock 97
Box Butte
Alliance 6 0707006
Bayard 21 0762021
Bridgeport 63 0762063
Hemingford 10 0707010
Boyd
Keya Paha Co High 100 0852100
Boyd County Sch 51 0808051
Louisville 32
Nebraska City 111
Plattsmouth 1
Syracuse-Dunbar-
Avoca 27
Waverly 145
Weeping Water 22
Cedar
Bloomfield 86R
Crofton 96
Leigh 39
North Bend
Central 595
Schuyler Central High 123
Cuming
Bancroft-Rosalie 20
Howells-Dodge 70
Logan View 594
Lyons-Decatur
Northeast 20
Oakland-Craig 14
1919039 Lexington 1 2424001
Overton 4 2424004
1927595 Sumner-Eddyville-
1919123 Miller 101 2424101
Deuel
2020020 Creek Valley 25 2525025
2019070 South Platte 95 2525095
2027594 Dixon
Allen 70 2626070
Emerson-Hubbard 561 2626561
Hartington-Newcastle 8 2614008
Hartington-Newcastle 8
1414008 Pender 1 2087001
# 2025 Public High School District Codes (continued)
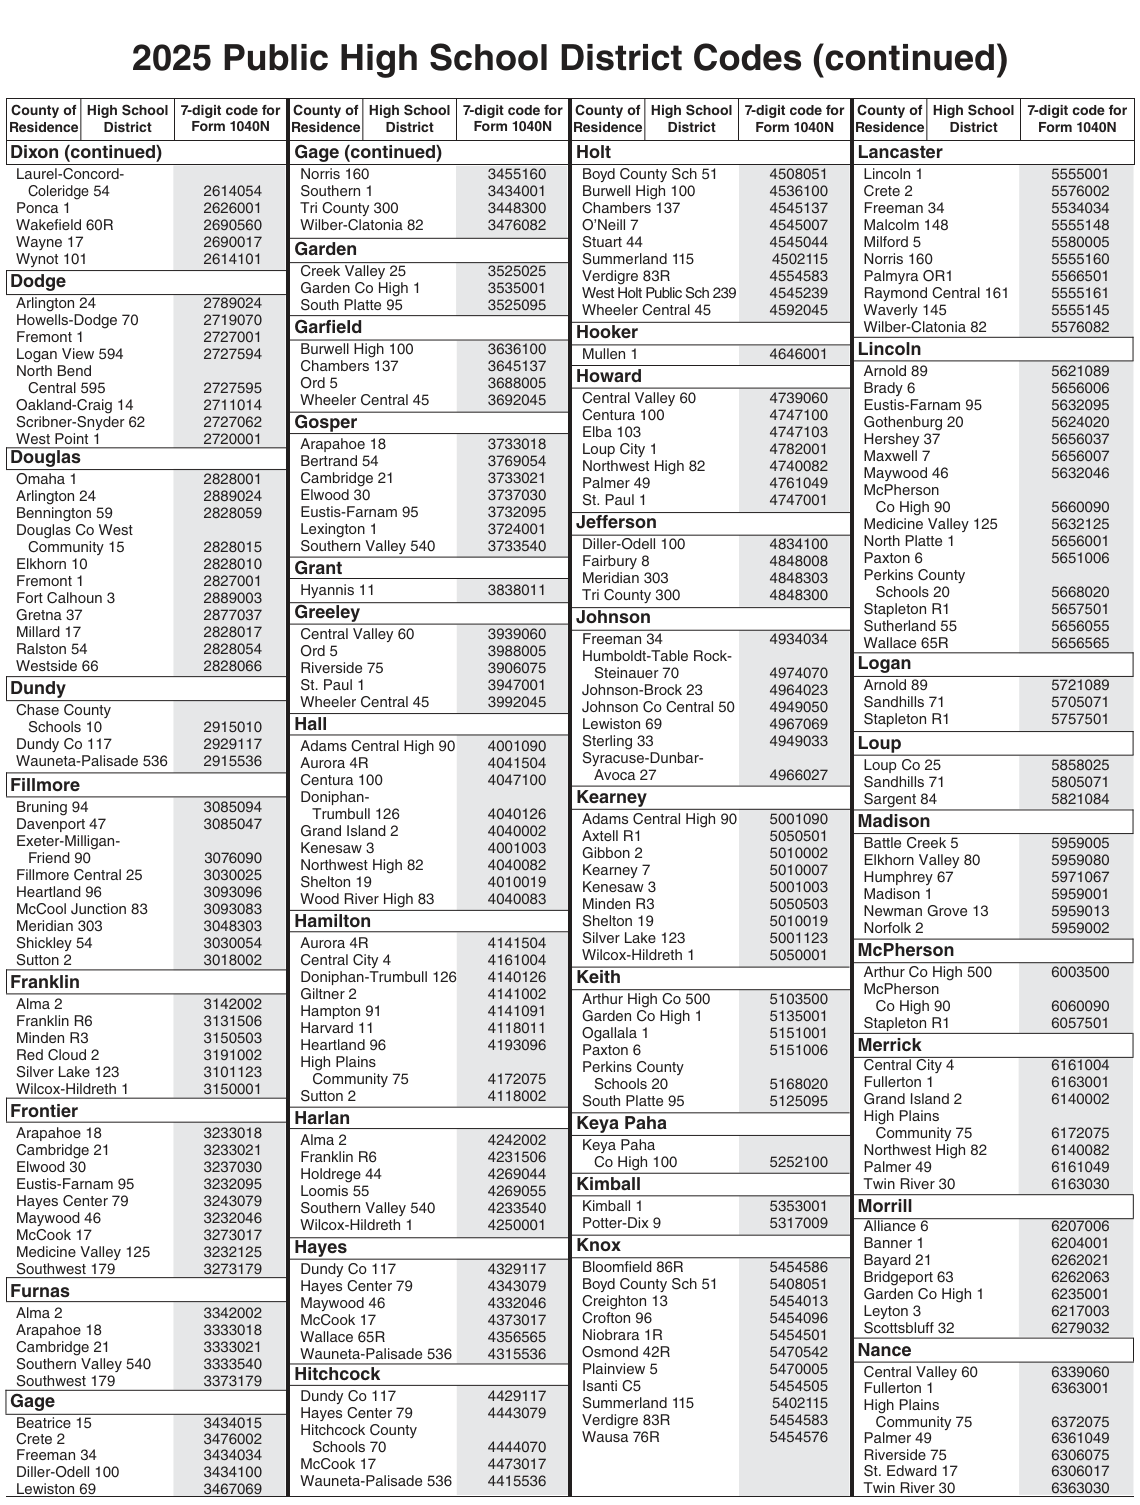
Text version of this table
| 2025 | Public Hig | h Sch | ool D | istrict | Cod | es (c | ontinue | d) | |||
| County of Hig | h S | chool 7-digit | code for County of High | School 7-di | git code for | County of High | School 7-di | git code for | County of High | School 7-di | git code |
| Residence D | ist | rict Form | 1040N Residence Dis | trict Fo | rm 1040N | Residence Di | strict Fo | rm 1040N | Residence Dis | trict Fo | rm 1040 |
| Dixon (conti | nu | ed) | Gage (contin | ued) | Holt | Lancaster | |||||
| Laurel-Concor | d- | Norris 160 | 3455160 | Boyd County S | ch 51 | 4508051 | Lincoln 1 | 5555001 | |||
| Coleridge 54 | 26 | 14054 Southern 1 | 3434001 | Burwell High 10 | 0 | 4536100 | Crete 2 | 5576002 | |||
| Ponca 1 | 26 | 26001 Tri County 300 | 3448300 | Chambers 137 | 4545137 | Freeman 34 | 5534034 | ||||
| Wakefield 60R | 26 | 90560 Wilber-Clatonia | 82 | 3476082 | O'Neill 7 | 4545007 | Malcolm 148 | 5555148 | |||
| Wayne 17 | 26 | 90017 Garden | Stuart 44 | 4545044 | Milford 5 | 5580005 | |||||
| Wynot 101 | 26 | 14101 | Summerland 11 | 5 | 4502115 | Norris 160 | 5555160 | ||||
| Dodge | Creek Valley 25 Garden Co Hig | h 1 | 3525025 3535001 | Verdigre 83R | 4554583 | Palmyra OR1 | 5566501 | ||||
| Arlington 24 Howells-Dodg | e 7 | 27 0 27 | 89024 South Platte 95 19070 | 3525095 | West Holt Public Wheeler Centra | Sch 239 l 45 | 4545239 4592045 | Raymond Centr Waverly 145 | al 161 | 5555161 5555145 | |
| Fremont 1 | 27 | Garfield 27001 | Hooker | Wilber-Clatonia | 82 | 5576082 | |||||
| Logan View 59 | 4 | 27 | 27594 Burwell High 10 | 0 | 3636100 | Mullen 1 | 4646001 | Lincoln | |||
| North Bend | Chambers 137 Ord 5 | 3645137 3688005 | Howard | Arnold 89 | 5621089 | ||||||
| Central 595 Oakland-Craig | 14 | 27 27 | 27595 11014 Wheeler Centra | l 45 | 3692045 | Central Valley 6 | 0 | 4739060 | Brady 6 Eustis-Farnam 9 | 5 | 5656006 5632095 |
| Scribner-Snyd | er | 62 27 | 27062 Gosper | Centura 100 | 4747100 | Gothenburg 20 | 5624020 | ||||
| West Point 1 | 27 | 20001 Arapahoe 18 | 3733018 | Elba 103 | 4747103 | Hershey 37 | 5656037 | ||||
| Douglas Omaha 1 | 28 | Bertrand 54 28001 Cambridge 21 | 3769054 3733021 | Loup City 1 Northwest High Palmer 49 | 82 | 4782001 4740082 4761049 | Maxwell 7 Maywood 46 McPherson | 5656007 5632046 | |||
| Arlington 24 Bennington 59 Douglas Co W | est | 28 28 | 89024 Elwood 30 28059 Eustis-Farnam Lexington 1 | 95 | 3737030 3732095 3724001 | St. Paul 1 Jefferson | 4747001 | Co High 90 Medicine Valley | 125 | 5660090 5632125 | |
| Community | 15 | 28 | 28015 Southern Valley | 540 | 3733540 | Diller-Odell 100 | 4834100 | North Platte 1 | 5656001 | ||
| Elkhorn 10 | 28 | 28010 Grant | Fairbury 8 | 4848008 | Paxton 6 Perkins County | 5651006 | |||||
| Fremont 1 Fort Calhoun 3 | 28 28 | 27001 Hyannis 11 89003 | 3838011 | Meridian 303 Tri County 300 | 4848303 4848300 | Schools 20 | 5668020 | ||||
| Gretna 37 | 28 | 77037 Greeley | Johnson | Stapleton R1 Sutherland 55 | 5657501 5656055 | ||||||
| Millard 17 Ralston 54 | 28 28 | 28017 Central Valley 6 28054 | 0 | 3939060 | Freeman 34 | 4934034 | Wallace 65R | 5656565 | |||
| Ord 5 | 3988005 | Humboldt-Table | Rock- | ||||||||
| Logan | |||||||||||
| Westside 66 | 28 | 28066 Riverside 75 | 3906075 | Steinauer 70 | 4974070 | ||||||
| Dundy | St. Paul 1 | 3947001 | Johnson-Brock | 23 | 4964023 | Arnold 89 | 5721089 | ||||
| Chase County | Wheeler Centra | l 45 | 3992045 | Johnson Co Ce | ntral 50 | 4949050 | Sandhills 71 | 5705071 | |||
| Hall | Lewiston 69 | 4967069 | Stapleton R1 | 5757501 | |||||||
| Schools 10 | 29 | 15010 | |||||||||
| Dundy Co 117 | 29 | 29117 Adams Central | High 90 | 4001090 | Sterling 33 | 4949033 | Loup | ||||
| Wauneta-Palis | ad | e 536 29 | 15536 Aurora 4R | 4041504 | Syracuse-Dunb | ar- | Loup Co 25 | 5858025 | |||
| Centura 100 | 4047100 | Avoca 27 | 4966027 | Sandhills 71 | 5805071 | ||||||
| Fillmore | Kearney | ||||||||||
| Bruning 94 | 30 | Doniphan- 85094 Trumbull 126 | 4040126 | Adams Central | High 90 | 5001090 | Sargent 84 | 5821084 | |||
| Davenport 47 Exeter-Milligan | - | 30 | 85047 Grand Island 2 | 4040002 | Axtell R1 | 5050501 | Madison Battle Creek 5 | 5959005 | |||
| Friend 90 | 30 | Kenesaw 3 76090 | 4001003 | Gibbon 2 | 5010002 | Elkhorn Valley 8 | 0 | 5959080 | |||
| Fillmore Centr Heartland 96 | al 2 | 5 30 30 | Northwest High 30025 Shelton 19 93096 Wood River Hig | 82 h 83 | 4040082 4010019 4040083 | Kearney 7 Kenesaw 3 Minden R3 | 5010007 5001003 5050503 | Humphrey 67 Madison 1 | 5971067 5959001 | ||
| McCool Juncti Meridian 303 | on | 83 30 30 | 93083 Hamilton 48303 | Shelton 19 Silver Lake 123 | 5010019 5001123 | Newman Grove Norfolk 2 | 13 | 5959013 5959002 | |||
| Shickley 54 Sutton 2 | 30 30 | 30054 Aurora 4R 18002 Central City 4 | 4141504 4161004 | Wilcox-Hildreth | 1 | 5050001 | McPherson | ||||
| Franklin | Doniphan-Trum | bull 126 | 4140126 | Keith | Arthur Co High | 500 | 6003500 | ||||
| Alma 2 | 31 | Giltner 2 42002 | 4141002 | Arthur High Co | 500 | 5103500 | McPherson Co High 90 | 6060090 | |||
| Franklin R6 Minden R3 Red Cloud 2 | 31 31 31 | Hampton 91 31506 Harvard 11 50503 Heartland 96 91002 High Plains | 4141091 4118011 4193096 | Garden Co Hig Ogallala 1 Paxton 6 | h 1 | 5135001 5151001 5151006 | Stapleton R1 Merrick Central City 4 | 6057501 6161004 | |||
| Silver Lake 12 Wilcox-Hildret Frontier Arapahoe 18 | 3 h 1 | 31 31 32 | 01123 Community 7 50001 Sutton 2 Harlan 33018 Alma 2 | 5 | 4172075 4118002 4242002 | Perkins County Schools 20 South Platte 95 Keya Paha Keya Paha | 5168020 5125095 | Fullerton 1 Grand Island 2 High Plains Community 75 | 6163001 6140002 6172075 | ||
| Cambridge 21 Elwood 30 | 32 32 | 33021 Franklin R6 37030 Holdrege 44 | 4231506 4269044 | Co High 100 | 5252100 | Northwest High Palmer 49 | 82 | 6140082 6161049 | |||
| Eustis-Farnam | 95 | 32 | 32095 Loomis 55 | 4269055 | Kimball | Twin River 30 | 6163030 | ||||
| Hayes Center | 79 | 32 | 43079 Southern Valley | 540 | 4233540 | Kimball 1 | 5353001 | Morrill | |||
| Maywood 46 | 32 | 32046 Wilcox-Hildreth | 1 | 4250001 | Potter-Dix 9 | 5317009 | Alliance 6 | 6207006 | |||
| McCook 17 Medicine Valle Southwest 179 | y 1 | 32 25 32 32 | 73017 Hayes 32125 73179 Dundy Co 117 | 4329117 | Knox Bloomfield 86R | 5454586 | Banner 1 Bayard 21 Bridgeport 63 | 6204001 6262021 6262063 | |||
| Furnas Alma 2 | 33 | Hayes Center 7 Maywood 46 42002 McCook 17 | 9 | 4343079 4332046 4373017 | Boyd County S Creighton 13 Crofton 96 | ch 51 | 5408051 5454013 5454096 | Garden Co High Leyton 3 | 1 | 6235001 6217003 | |
| Arapahoe 18 | 33 | 33018 Wallace 65R | 4356565 | Niobrara 1R | 5454501 | Scottsbluff 32 | 6279032 | ||||
| Cambridge 21 | 33 | 33021 Wauneta-Palisa | de 536 | 4315536 | Osmond 42R | 5470542 | Nance | ||||
| Southern Valle Southwest 179 | y 5 | 40 33 33 | 33540 Hitchcock 73179 | Plainview 5 | 5470005 | Central Valley 6 | 0 | 6339060 | |||
| Gage | Dundy Co 117 | 4429117 | Isanti C5 Summerland 11 | 5 | 5454505 5402115 | Fullerton 1 High Plains | 6363001 | ||||
| Hayes Center 7 | 9 | 4443079 | Verdigre 83R | 5454583 | Community 75 | 6372075 | |||||
| Beatrice 15 | 34 | 34015 | |||||||||
| Hitchcock Coun | ty | Wausa 76R | 5454576 | Palmer 49 | 6361049 | ||||||
| Crete 2 | 34 | 76002 | |||||||||
| Freeman 34 | 34 | Schools 70 34034 | 4444070 | Riverside 75 | 6306075 | ||||||
| Diller-Odell 10 | 0 | 34 | McCook 17 34100 | 4473017 | St. Edward 17 | 6306017 | |||||
| Wauneta-Palisa | de 536 | 4415536 | Twin River 30 | 6363030 | |||||||
| Lewiston 69 | 34 | 67069 |
# 2025 Public High School District Codes (continued)
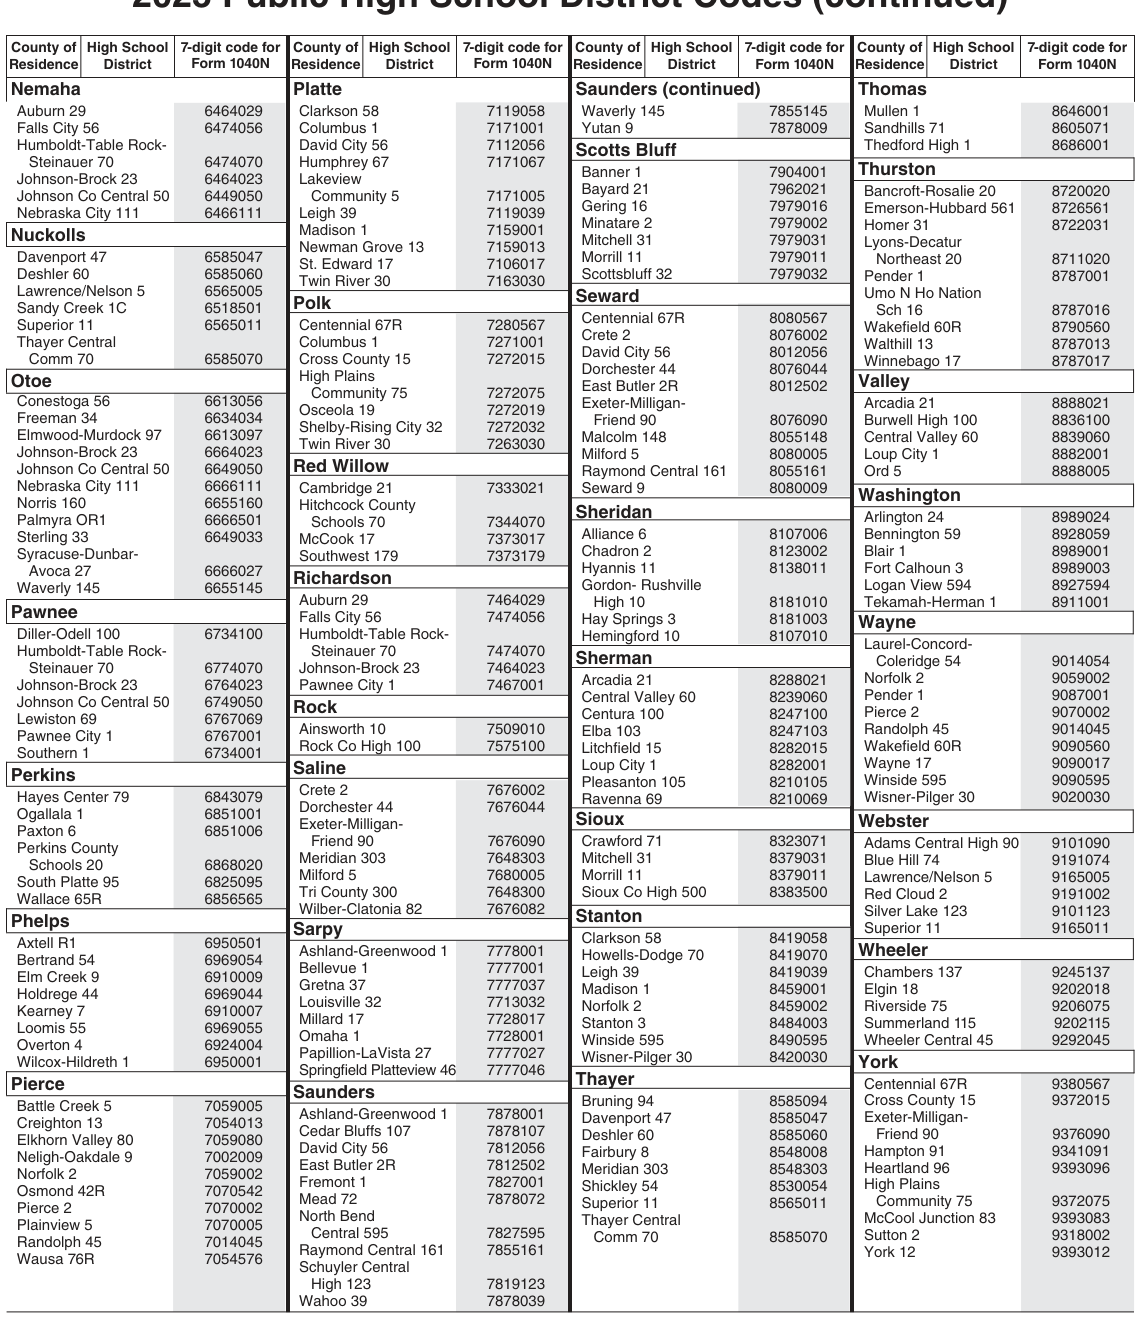
Text version of this table
| County of High | School 7-di | git code for | County of High | Scho | ol 7-di | git code for | County of Hi | gh School 7-di | git code for | County of H | igh S | chool 7-di | git code |
| Residence Dis | trict Fo | rm 1040N | Residence Di | strict | Fo | rm 1040N | Residence | District Fo | rm 1040N | Residence | Distr | ict Fo | rm 1040 |
| Nemaha | Platte | Saunders ( | continued) | Thomas | |||||||||
| Auburn 29 | 6464029 | Clarkson 58 | 7119058 | Waverly 145 | 7855145 | Mullen 1 | 8646001 | ||||||
| Falls City 56 | 6474056 | Columbus 1 | 7171001 | Yutan 9 | 7878009 | Sandhills 71 | 8605071 | ||||||
| Humboldt-Table | Rock- | David City 56 | 7112056 | Scotts Blu | ff | Thedford Hi | gh 1 | 8686001 | |||||
| Steinauer 70 Johnson-Brock | 23 | 6474070 6464023 | Humphrey 67 Lakeview | 7171067 | Banner 1 | 7904001 | Thurston | ||||||
| Johnson Co Ce | ntral 50 | 6449050 | Community 5 | 7171005 | Bayard 21 | 7962021 | Bancroft-Ro | salie | 20 | 8720020 | |||
| Nebraska City 1 | 11 | 6466111 | Leigh 39 | 7119039 | Gering 16 | 7979016 | Emerson-H | ubbar | d 561 | 8726561 | |||
| Nuckolls | Madison 1 | 7159001 | Minatare 2 Mitchell 31 | 7979002 7979031 | Homer 31 Lyons-Deca | tur | 8722031 | ||||||
| Davenport 47 | 6585047 | Newman Grove St. Edward 17 | 13 | 7159013 7106017 | Morrill 11 | 7979011 | Northeast | 20 | 8711020 | ||||
| Deshler 60 | 6585060 | Twin River 30 | 7163030 | Scottsbluff 3 | 2 | 7979032 | Pender 1 | 8787001 | |||||
| Lawrence/Nelso Sandy Creek 1C | n 5 | 6565005 6518501 | Polk | Seward | Umo N Ho Sch 16 | Nation | 8787016 | ||||||
| Superior 11 | 6565011 | Centennial 67R | 7280567 | Centennial 6 | 7R | 8080567 | |||||||
| Wakefield 6 | 0R | 8790560 | |||||||||||
| Thayer Central | Columbus 1 | 7271001 | Crete 2 | 8076002 | |||||||||
| Walthill 13 | 8787013 | ||||||||||||
| Comm 70 | 6585070 | Cross County 1 | 5 | 7272015 | David City 5 | 6 | 8012056 | ||||||
| High Plains | Dorchester 4 | 4 | 8076044 | Winnebago | 17 | 8787017 | |||||||
| Otoe Conestoga 56 | 6613056 | Community 7 | 5 | 7272075 | East Butler 2 | R | 8012502 | Valley | |||||
| Osceola 19 | 7272019 | Exeter-Millig | an- | Arcadia 21 | 8888021 | ||||||||
| Freeman 34 | 6634034 | ||||||||||||
| Shelby-Rising C | ity 32 | 7272032 | Friend 90 | 8076090 | Burwell Hig | h 100 | 8836100 | ||||||
| Elmwood-Murd | ock 97 | 6613097 | |||||||||||
| Twin River 30 | 7263030 | Malcolm 148 | 8055148 | Central Vall | ey 60 | 8839060 | |||||||
| Johnson-Brock | 23 | 6664023 | Milford 5 | 8080005 | Loup City 1 | 8882001 | |||||||
| Johnson Co Ce | ntral 50 | 6649050 | Red Willow | Raymond Ce | ntral 161 | 8055161 | Ord 5 | 8888005 | |||||
| Nebraska City 1 | 11 | 6666111 | |||||||||||
| Cambridge 21 | 7333021 | Seward 9 | 8080009 | Washingt | on | ||||||||
| Norris 160 | 6655160 | Hitchcock Coun | ty | ||||||||||
| Palmyra OR1 | 6666501 | Schools 70 | 7344070 | Sheridan | Arlington 24 | 8989024 | |||||||
| Sterling 33 | 6649033 | McCook 17 | 7373017 | Alliance 6 | 8107006 | Bennington | 59 | 8928059 | |||||
| Syracuse-Dunb | ar- | Southwest 179 | 7373179 | Chadron 2 | 8123002 | Blair 1 | 8989001 | ||||||
| Avoca 27 | 6666027 | Hyannis 11 | 8138011 | Fort Calhou | n 3 | 8989003 | |||||||
| Waverly 145 | 6655145 | Richardson | Gordon- Rus | hville | Logan View | 594 | 8927594 | ||||||
| Auburn 29 | 7464029 | High 10 | 8181010 | Tekamah-H | erma | n 1 | 8911001 | ||||||
| Pawnee | Falls City 56 | 7474056 | Hay Springs | 3 | 8181003 | Wayne | |||||||
| Diller-Odell 100 Humboldt-Table | Rock- | 6734100 | Humboldt-Table Steinauer 70 | Roc | k- | 7474070 | Hemingford | 10 | 8107010 | Laurel-Conc | ord- | ||
| Steinauer 70 | 6774070 | Johnson-Brock | 23 | 7464023 | Sherman | Coleridge | 54 | 9014054 | |||||
| Johnson-Brock | 23 | 6764023 | Pawnee City 1 | 7467001 | Arcadia 21 | 8288021 | Norfolk 2 | 9059002 | |||||
| Johnson Co Ce | ntral 50 | 6749050 | Rock | Central Valle Centura 100 | y 60 | 8239060 8247100 | Pender 1 Pierce 2 | 9087001 9070002 | |||||
| Lewiston 69 Pawnee City 1 | 6767069 6767001 | Ainsworth 10 | 7509010 | Elba 103 | 8247103 | Randolph 4 | 5 | 9014045 | |||||
| Southern 1 | 6734001 | Rock Co High 1 | 00 | 7575100 | Litchfield 15 | 8282015 | Wakefield 6 | 0R | 9090560 | ||||
| Perkins | Saline | Loup City 1 Pleasanton 1 | 05 | 8282001 8210105 | Wayne 17 Winside 59 | 5 | 9090017 9090595 | ||||||
| Hayes Center 7 | 9 | 6843079 | Crete 2 | 7676002 | Wisner-Pilg | er 30 | 9020030 | ||||||
| Ogallala 1 | 6851001 | Dorchester 44 | 7676044 | Ravenna 69 | 8210069 | ||||||||
| Paxton 6 | 6851006 | Exeter-Milligan- | Sioux | Webster | |||||||||
| Perkins County | Friend 90 | 7676090 | Crawford 71 | 8323071 | Adams Cen | tral H | igh 90 | 9101090 | |||||
| Schools 20 | 6868020 | Meridian 303 | 7648303 | Mitchell 31 | 8379031 | Blue Hill 74 | 9191074 | ||||||
| South Platte 95 | 6825095 | Milford 5 | 7680005 | Morrill 11 | 8379011 | Lawrence/N | elson | 5 | 9165005 | ||||
| Wallace 65R | 6856565 | Tri County 300 | 7648300 | Sioux Co Hig | h 500 | 8383500 | Red Cloud | 2 | 9191002 | ||||
| Phelps Axtell R1 Bertrand 54 Elm Creek 9 | 6950501 6969054 6910009 | Wilber-Clatonia Sarpy Ashland-Green Bellevue 1 Gretna 37 | 82 wood | 1 | 7676082 7778001 7777001 7777037 | Stanton Clarkson 58 Howells-Dod Leigh 39 | ge 70 | 8419058 8419070 8419039 | Silver Lake Superior 11 Wheeler Chambers 1 | 123 37 | 9101123 9165011 9245137 | ||
| Holdrege 44 Kearney 7 Loomis 55 Overton 4 Wilcox-Hildreth Pierce Battle Creek 5 Creighton 13 Elkhorn Valley 8 | 1 0 | 6969044 6910007 6969055 6924004 6950001 7059005 7054013 7059080 | Louisville 32 Millard 17 Omaha 1 Papillion-LaVist Springfeild Platt Saunders Ashland-Green Cedar Bluffs 10 David City 56 | a 27 eview wood 7 | 46 1 | 7713032 7728017 7728001 7777027 7777046 7878001 7878107 7812056 | Madison 1 Norfolk 2 Stanton 3 Winside 595 Wisner-Pilge Thayer Bruning 94 Davenport 4 Deshler 60 | r 30 7 | 8459001 8459002 8484003 8490595 8420030 8585094 8585047 8585060 | Elgin 18 Riverside 7 Summerlan Wheeler Ce York Centennial Cross Coun Exeter-Millig Friend 90 | 5 d 115 ntral 67R ty 15 an- | 45 | 9202018 9206075 9202115 9292045 9380567 9372015 9376090 |
| Neligh-Oakdale Norfolk 2 Osmond 42R Pierce 2 Plainview 5 Randolph 45 | 9 | 7002009 7059002 7070542 7070002 7070005 7014045 | East Butler 2R Fremont 1 Mead 72 North Bend Central 595 | 7812502 7827001 7878072 7827595 | Fairbury 8 Meridian 303 Shickley 54 Superior 11 Thayer Cent Comm 70 | ral | 8548008 8548303 8530054 8565011 8585070 | Hampton 91 Heartland 9 High Plains Communit McCool Jun Sutton 2 | 6 y 75 ction | 83 | 9341091 9393096 9372075 9393083 9318002 | ||
| Wausa 76R | 7054576 | Raymond Centr | al 16 | 1 | 7855161 | York 12 | 9393012 | ||||||
| Schuyler Centra | l | ||||||||||||
| High 123 | 7819123 | ||||||||||||
| Wahoo 39 | 7878039 |
# 2025 Nebraska Tax Table
Use your Nebraska taxable income found on line 14, Form 1040N.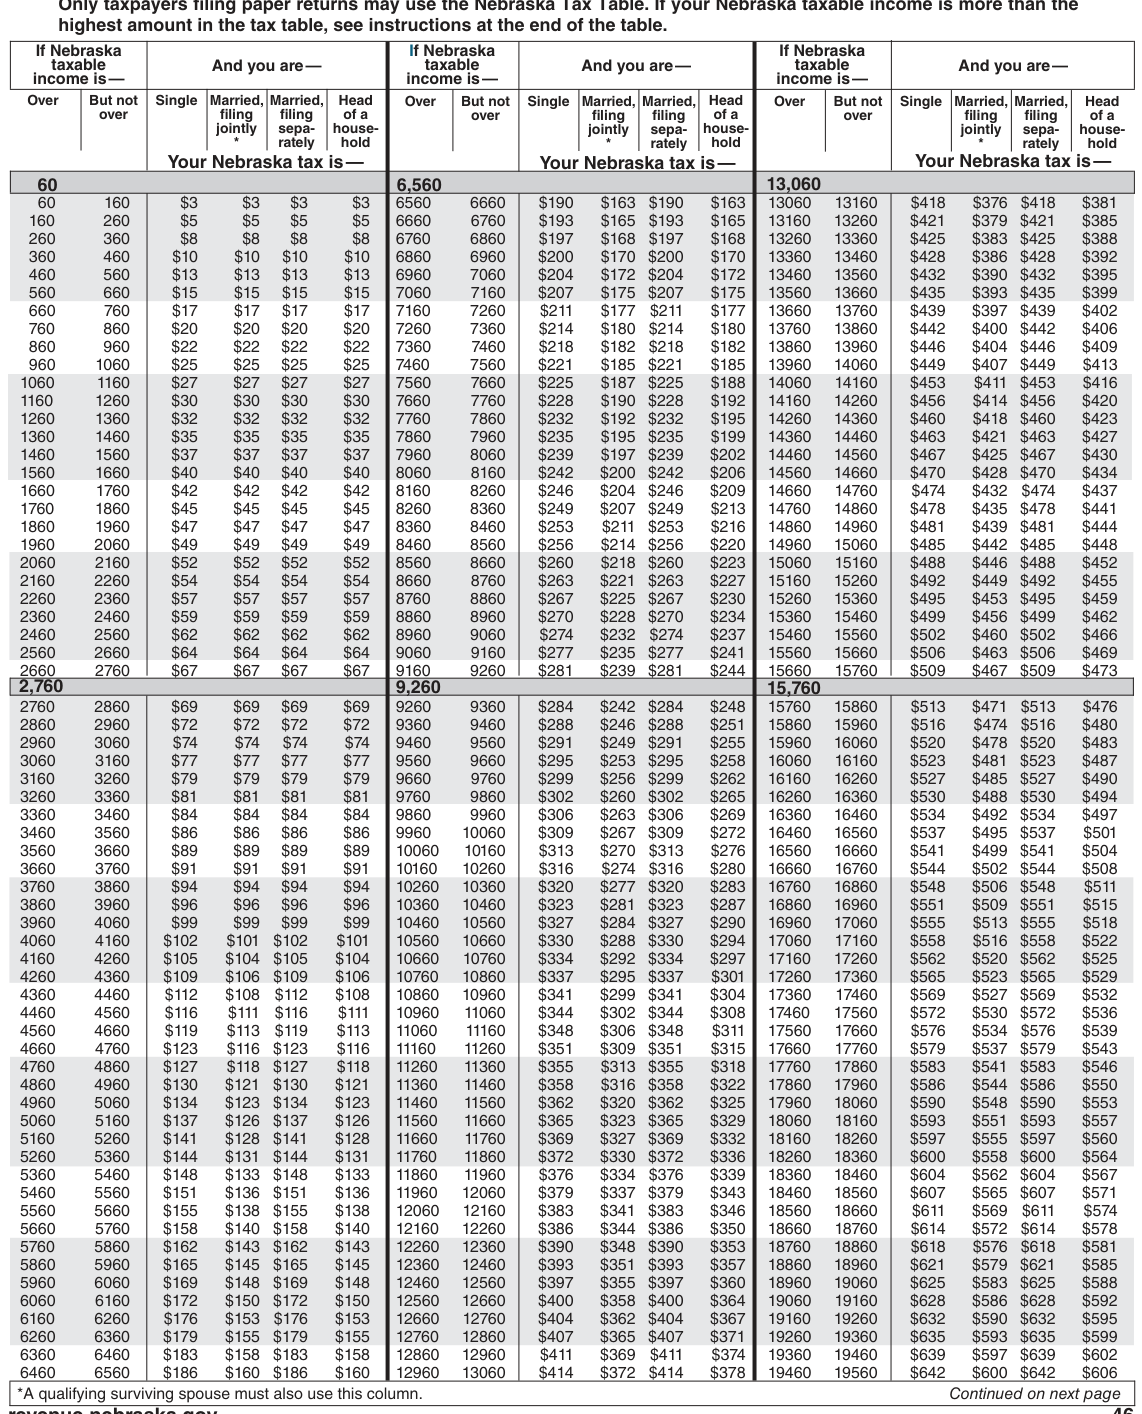
Text version of this table
If Nebraska taxable income is — And you are — If Nebraska taxable income is — And you are — If Nebraska taxable income is — And you are — Over But not over Single Married,Married, Head fliing fliing of a jointly sepa- house- * rately hold Your Nebraska tax is — Over But not over Single Married, Married, Head fliing fliing of a jointly sepa- house- * rately hold Your Nebraska tax is — Over But not over Single Married,Married, Head fliing fliing of a jointly sepa- house- * rately hold Your Nebraska tax is — 60 6,560 13,060 60 160 160 260 260 360 360 460 460 560 560 660 $3 $3 $3 $3 $5 $5 $5 $5 $8 $8 $8 $8 $10 $10 $10 $10 $13 $13 $13 $13 $15 $15 $15 $15 6560 6660 6660 6760 6760 6860 6860 6960 6960 7060 7060 7160 $190 $163 $190 $163 $193 $165 $193 $165 $197 $168 $197 $168 $200 $170 $200 $170 $204 $172 $204 $172 $207 $175 $207 $175 13060 13160 13160 13260 13260 13360 13360 13460 13460 13560 13560 13660 $418 $376 $418 $381 $421 $379 $421 $385 $425 $383 $425 $388 $428 $386 $428 $392 $432 $390 $432 $395 $435 $393 $435 $399 660 760 760 860 860 960 960 1060 $17 $17 $17 $17 $20 $20 $20 $20 $22 $22 $22 $22 $25 $25 $25 $25 7160 7260 7260 7360 7360 7460 7460 7560 $211 $177 $211 $177 $214 $180 $214 $180 $218 $182 $218 $182 $221 $185 $221 $185 13660 13760 13760 13860 13860 13960 13960 14060 $439 $397 $439 $402 $442 $400 $442 $406 $446 $404 $446 $409 $449 $407 $449 $413 1060 1160 1160 1260 1260 1360 1360 1460 1460 1560 1560 1660 $27 $27 $27 $27 $30 $30 $30 $30 $32 $32 $32 $32 $35 $35 $35 $35 $37 $37 $37 $37 $40 $40 $40 $40 7560 7660 7660 7760 7760 7860 7860 7960 7960 8060 8060 8160 $225 $187 $225 $188 $228 $190 $228 $192 $232 $192 $232 $195 $235 $195 $235 $199 $239 $197 $239 $202 $242 $200 $242 $206 14060 14160 14160 14260 14260 14360 14360 14460 14460 14560 14560 14660 $453 $411 $453 $416 $456 $414 $456 $420 $460 $418 $460 $423 $463 $421 $463 $427 $467 $425 $467 $430 $470 $428 $470 $434 1660 1760 1760 1860 1860 1960 1960 2060 $42 $42 $42 $42 $45 $45 $45 $45 $47 $47 $47 $47 $49 $49 $49 $49 8160 8260 8260 8360 8360 8460 8460 8560 $246 $204 $246 $209 $249 $207 $249 $213 $253 $211 $253 $216 $256 $214 $256 $220 14660 14760 14760 14860 14860 14960 14960 15060 $474 $432 $474 $437 $478 $435 $478 $441 $481 $439 $481 $444 $485 $442 $485 $448 2060 2160 2160 2260 2260 2360 2360 2460 2460 2560 2560 2660 $52 $52 $52 $52 $54 $54 $54 $54 $57 $57 $57 $57 $59 $59 $59 $59 $62 $62 $62 $62 $64 $64 $64 $64 8560 8660 8660 8760 8760 8860 8860 8960 8960 9060 9060 9160 $260 $218 $260 $223 $263 $221 $263 $227 $267 $225 $267 $230 $270 $228 $270 $234 $274 $232 $274 $237 $277 $235 $277 $241 15060 15160 15160 15260 15260 15360 15360 15460 15460 15560 15560 15660 $488 $446 $488 $452 $492 $449 $492 $455 $495 $453 $495 $459 $499 $456 $499 $462 $502 $460 $502 $466 $506 $463 $506 $469 2660 2760 $67 $67 $67 $67 9160 9260 $281 $239 $281 $244 15660 15760 $509 $467 $509 $473 2,760 9,260 15,760 2760 2860 2860 2960 2960 3060 3060 3160 3160 3260 3260 3360 $69 $69 $69 $69 $72 $72 $72 $72 $74 $74 $74 $74 $77 $77 $77 $77 $79 $79 $79 $79 $81 $81 $81 $81 9260 9360 9360 9460 9460 9560 9560 9660 9660 9760 9760 9860 $284 $242 $284 $248 $288 $246 $288 $251 $291 $249 $291 $255 $295 $253 $295 $258 $299 $256 $299 $262 $302 $260 $302 $265 15760 15860 15860 15960 15960 16060 16060 16160 16160 16260 16260 16360 $513 $471 $513 $476 $516 $474 $516 $480 $520 $478 $520 $483 $523 $481 $523 $487 $527 $485 $527 $490 $530 $488 $530 $494 3360 3460 3460 3560 3560 3660 3660 3760 $84 $84 $84 $84 $86 $86 $86 $86 $89 $89 $89 $89 $91 $91 $91 $91 9860 9960 9960 10060 10060 10160 10160 10260 $306 $263 $306 $269 $309 $267 $309 $272 $313 $270 $313 $276 $316 $274 $316 $280 16360 16460 16460 16560 16560 16660 16660 16760 $534 $492 $534 $497 $537 $495 $537 $501 $541 $499 $541 $504 $544 $502 $544 $508 3760 3860 3860 3960 3960 4060 4060 4160 4160 4260 4260 4360 $94 $94 $94 $94 $96 $96 $96 $96 $99 $99 $99 $99 $102 $101 $102 $101 $105 $104 $105 $104 $109 $106 $109 $106 10260 10360 10360 10460 10460 10560 10560 10660 10660 10760 10760 10860 $320 $277 $320 $283 $323 $281 $323 $287 $327 $284 $327 $290 $330 $288 $330 $294 $334 $292 $334 $297 $337 $295 $337 $301 16760 16860 16860 16960 16960 17060 17060 17160 17160 17260 17260 17360 $548 $506 $548 $511 $551 $509 $551 $515 $555 $513 $555 $518 $558 $516 $558 $522 $562 $520 $562 $525 $565 $523 $565 $529 4360 4460 4460 4560 4560 4660 4660 4760 $112 $108 $112 $108 $116 $111 $116 $111 $119 $113 $119 $113 $123 $116 $123 $116 10860 10960 10960 11060 11060 11160 11160 11260 $341 $299 $341 $304 $344 $302 $344 $308 $348 $306 $348 $311 $351 $309 $351 $315 17360 17460 17460 17560 17560 17660 17660 17760 $569 $527 $569 $532 $572 $530 $572 $536 $576 $534 $576 $539 $579 $537 $579 $543 4760 4860 4860 4960 4960 5060 5060 5160 5160 5260 5260 5360 $127 $118 $127 $118 $130 $121 $130 $121 $134 $123 $134 $123 $137 $126 $137 $126 $141 $128 $141 $128 $144 $131 $144 $131 11260 11360 11360 11460 11460 11560 11560 11660 11660 11760 11760 11860 $355 $313 $355 $318 $358 $316 $358 $322 $362 $320 $362 $325 $365 $323 $365 $329 $369 $327 $369 $332 $372 $330 $372 $336 17760 17860 17860 17960 17960 18060 18060 18160 18160 18260 18260 18360 $583 $541 $583 $546 $586 $544 $586 $550 $590 $548 $590 $553 $593 $551 $593 $557 $597 $555 $597 $560 $600 $558 $600 $564 5360 5460 5460 5560 5560 5660 5660 5760 $148 $133 $148 $133 $151 $136 $151 $136 $155 $138 $155 $138 $158 $140 $158 $140 11860 11960 11960 12060 12060 12160 12160 12260 $376 $334 $376 $339 $379 $337 $379 $343 $383 $341 $383 $346 $386 $344 $386 $350 18360 18460 18460 18560 18560 18660 18660 18760 $604 $562 $604 $567 $607 $565 $607 $571 $611 $569 $611 $574 $614 $572 $614 $578 5760 5860 5860 5960 5960 6060 6060 6160 6160 6260 6260 6360 $162 $143 $162 $143 $165 $145 $165 $145 $169 $148 $169 $148 $172 $150 $172 $150 $176 $153 $176 $153 $179 $155 $179 $155 12260 12360 12360 12460 12460 12560 12560 12660 12660 12760 12760 12860 $390 $348 $390 $353 $393 $351 $393 $357 $397 $355 $397 $360 $400 $358 $400 $364 $404 $362 $404 $367 $407 $365 $407 $371 18760 18860 18860 18960 18960 19060 19060 19160 19160 19260 19260 19360 $618 $576 $618 $581 $621 $579 $621 $585 $625 $583 $625 $588 $628 $586 $628 $592 $632 $590 $632 $595 $635 $593 $635 $599 6360 6460 6460 6560 $183 $158 $183 $158 $186 $160 $186 $160 12860 12960 12960 13060 $411 $369 $411 $374 $414 $372 $414 $378 19360 19460 19460 19560 $639 $597 $639 $602 $642 $600 $642 $606 *A qualifying surviving spouse must also use this column. Continued on next page
Your Nebraska tax is -
# If Nebraska taxable
And you are - And you are - income is -
Head
Married, Married, Over But not Single Married, Married, Head of a filing filing over filing filing of a housejointly sepa- jointly sepa- household
- rately * rately hold
2025 Nebraska Tax Table - continued If Nebraska If Nebraska taxable And you are - taxable income is - income is -
- rately hold
# If Nebraska
And you are - taxable And you are - income is -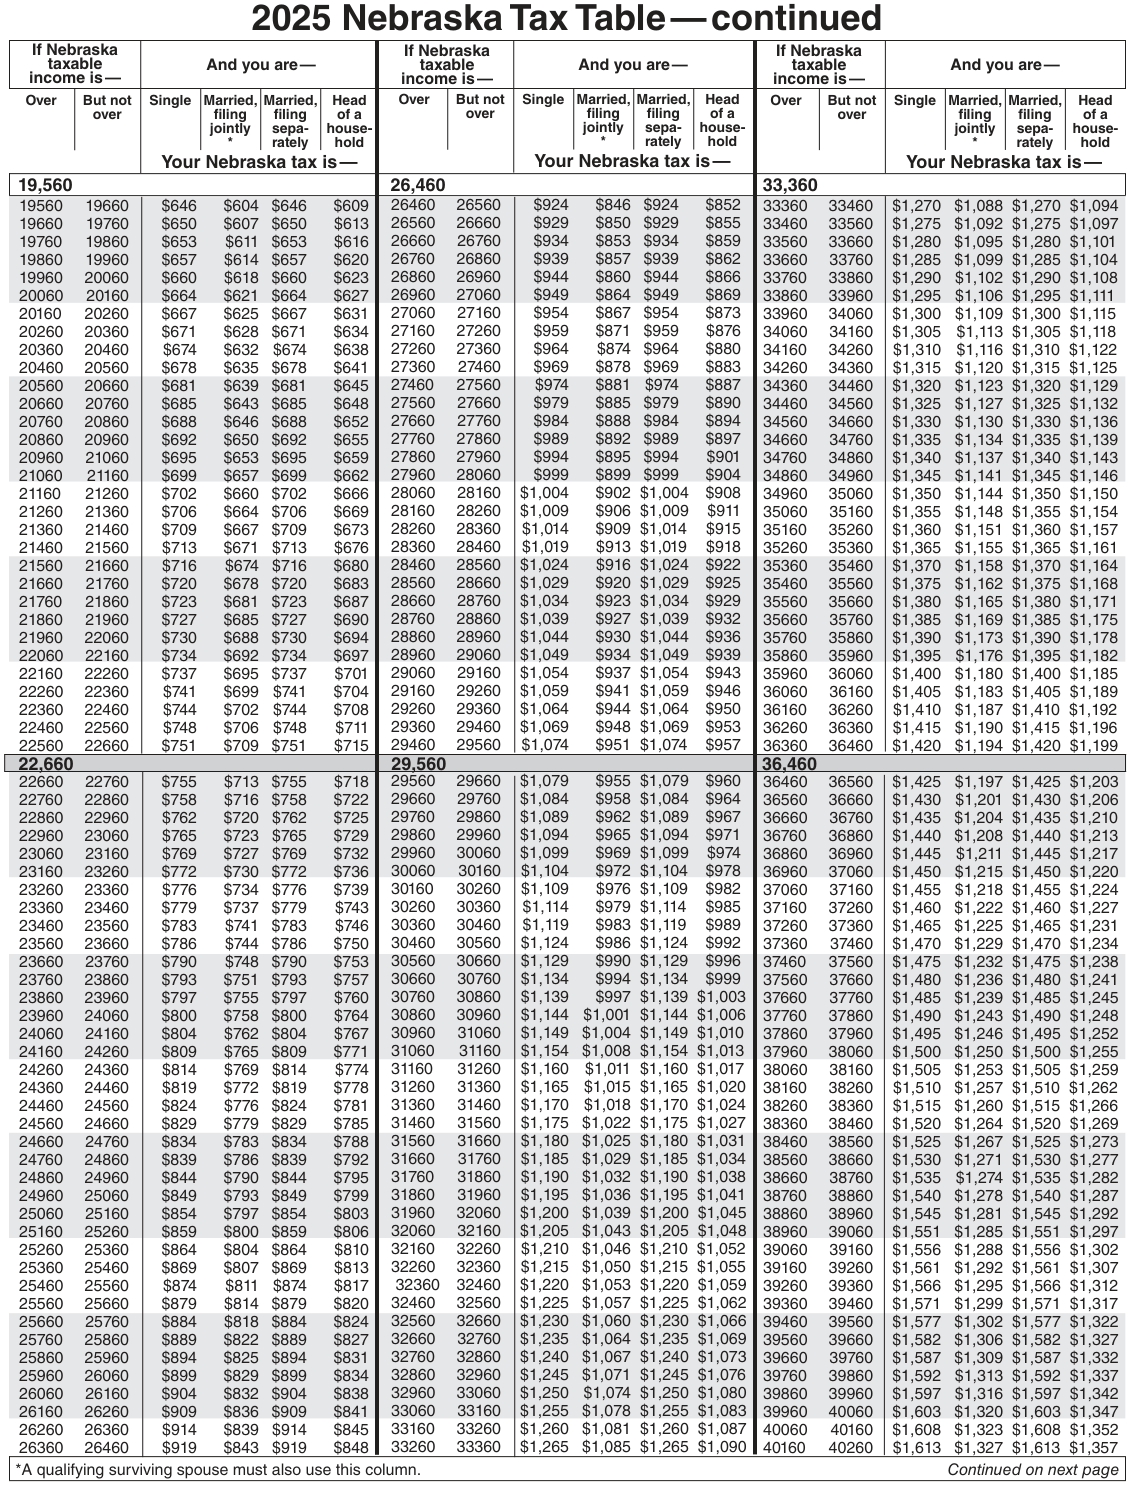
Text version of this table
If Nebraska taxable income is — And you are — If Nebraska taxable income is — And you are — If Nebraska taxable income is — And you are — Over But not over Single Married,Married, Head fliing fliing of a jointly sepa- house- * rately hold Your Nebraska tax is — Over But not over Single Married,Married, Head fliing fliing of a jointly sepa- house- * rately hold Your Nebraska tax is — Over But not over Single Married,Married, Head fliing fliing of a jointly sepa- house- * rately hold Your Nebraska tax is — 19,560 26,460 33,360 19560 19660 19660 19760 19760 19860 19860 19960 19960 20060 20060 20160 $646 $604 $646 $609 $650 $607 $650 $613 $653 $611 $653 $616 $657 $614 $657 $620 $660 $618 $660 $623 $664 $621 $664 $627 26460 26560 26560 26660 26660 26760 26760 26860 26860 26960 26960 27060 $924 $846 $924 $852 $929 $850 $929 $855 $934 $853 $934 $859 $939 $857 $939 $862 $944 $860 $944 $866 $949 $864 $949 $869 33360 33460 33460 33560 33560 33660 33660 33760 33760 33860 33860 33960 $1,270 $1,088 $1,270 $1,094 $1,275 $1,092 $1,275 $1,097 $1,280 $1,095 $1,280 $1,101 $1,285 $1,099 $1,285 $1,104 $1,290 $1,102 $1,290 $1,108 $1,295 $1,106 $1,295 $1,111 20160 20260 20260 20360 20360 20460 20460 20560 $667 $625 $667 $631 $671 $628 $671 $634 $674 $632 $674 $638 $678 $635 $678 $641 27060 27160 27160 27260 27260 27360 27360 27460 $954 $867 $954 $873 $959 $871 $959 $876 $964 $874 $964 $880 $969 $878 $969 $883 33960 34060 34060 34160 34160 34260 34260 34360 $1,300 $1,109 $1,300 $1,115 $1,305 $1,113 $1,305 $1,118 $1,310 $1,116 $1,310 $1,122 $1,315 $1,120 $1,315 $1,125 20560 20660 20660 20760 20760 20860 20860 20960 20960 21060 21060 21160 $681 $639 $681 $645 $685 $643 $685 $648 $688 $646 $688 $652 $692 $650 $692 $655 $695 $653 $695 $659 $699 $657 $699 $662 27460 27560 27560 27660 27660 27760 27760 27860 27860 27960 27960 28060 $974 $881 $974 $887 $979 $885 $979 $890 $984 $888 $984 $894 $989 $892 $989 $897 $994 $895 $994 $901 $999 $899 $999 $904 34360 34460 34460 34560 34560 34660 34660 34760 34760 34860 34860 34960 $1,320 $1,123 $1,320 $1,129 $1,325 $1,127 $1,325 $1,132 $1,330 $1,130 $1,330 $1,136 $1,335 $1,134 $1,335 $1,139 $1,340 $1,137 $1,340 $1,143 $1,345 $1,141 $1,345 $1,146 21160 21260 21260 21360 21360 21460 21460 21560 $702 $660 $702 $666 $706 $664 $706 $669 $709 $667 $709 $673 $713 $671 $713 $676 28060 28160 28160 28260 28260 28360 28360 28460 $1,004 $902 $1,004 $908 $1,009 $906 $1,009 $911 $1,014 $909 $1,014 $915 $1,019 $913 $1,019 $918 34960 35060 35060 35160 35160 35260 35260 35360 $1,350 $1,144 $1,350 $1,150 $1,355 $1,148 $1,355 $1,154 $1,360 $1,151 $1,360 $1,157 $1,365 $1,155 $1,365 $1,161 21560 21660 21660 21760 21760 21860 21860 21960 21960 22060 22060 22160 $716 $674 $716 $680 $720 $678 $720 $683 $723 $681 $723 $687 $727 $685 $727 $690 $730 $688 $730 $694 $734 $692 $734 $697 28460 28560 28560 28660 28660 28760 28760 28860 28860 28960 28960 29060 $1,024 $916 $1,024 $922 $1,029 $920 $1,029 $925 $1,034 $923 $1,034 $929 $1,039 $927 $1,039 $932 $1,044 $930 $1,044 $936 $1,049 $934 $1,049 $939 35360 35460 35460 35560 35560 35660 35660 35760 35760 35860 35860 35960 $1,370 $1,158 $1,370 $1,164 $1,375 $1,162 $1,375 $1,168 $1,380 $1,165 $1,380 $1,171 $1,385 $1,169 $1,385 $1,175 $1,390 $1,173 $1,390 $1,178 $1,395 $1,176 $1,395 $1,182 22160 22260 22260 22360 22360 22460 22460 22560 22560 22660 $737 $695 $737 $701 $741 $699 $741 $704 $744 $702 $744 $708 $748 $706 $748 $711 $751 $709 $751 $715 29060 29160 29160 29260 29260 29360 29360 29460 29460 29560 $1,054 $937 $1,054 $943 $1,059 $941 $1,059 $946 $1,064 $944 $1,064 $950 $1,069 $948 $1,069 $953 $1,074 $951 $1,074 $957 35960 36060 36060 36160 36160 36260 36260 36360 36360 36460 $1,400 $1,180 $1,400 $1,185 $1,405 $1,183 $1,405 $1,189 $1,410 $1,187 $1,410 $1,192 $1,415 $1,190 $1,415 $1,196 $1,420 $1,194 $1,420 $1,199 22,660 29,560 36,460 22660 22760 22760 22860 22860 22960 22960 23060 23060 23160 23160 23260 $755 $713 $755 $718 $758 $716 $758 $722 $762 $720 $762 $725 $765 $723 $765 $729 $769 $727 $769 $732 $772 $730 $772 $736 29560 29660 29660 29760 29760 29860 29860 29960 29960 30060 30060 30160 $1,079 $955 $1,079 $960 $1,084 $958 $1,084 $964 $1,089 $962 $1,089 $967 $1,094 $965 $1,094 $971 $1,099 $969 $1,099 $974 $1,104 $972 $1,104 $978 36460 36560 36560 36660 36660 36760 36760 36860 36860 36960 36960 37060 $1,425 $1,197 $1,425 $1,203 $1,430 $1,201 $1,430 $1,206 $1,435 $1,204 $1,435 $1,210 $1,440 $1,208 $1,440 $1,213 $1,445 $1,211 $1,445 $1,217 $1,450 $1,215 $1,450 $1,220 23260 23360 23360 23460 23460 23560 23560 23660 $776 $734 $776 $739 $779 $737 $779 $743 $783 $741 $783 $746 $786 $744 $786 $750 30160 30260 30260 30360 30360 30460 30460 30560 $1,109 $976 $1,109 $982 $1,114 $979 $1,114 $985 $1,119 $983 $1,119 $989 $1,124 $986 $1,124 $992 37060 37160 37160 37260 37260 37360 37360 37460 $1,455 $1,218 $1,455 $1,224 $1,460 $1,222 $1,460 $1,227 $1,465 $1,225 $1,465 $1,231 $1,470 $1,229 $1,470 $1,234 23660 23760 23760 23860 23860 23960 23960 24060 24060 24160 24160 24260 $790 $748 $790 $753 $793 $751 $793 $757 $797 $755 $797 $760 $800 $758 $800 $764 $804 $762 $804 $767 $809 $765 $809 $771 30560 30660 30660 30760 30760 30860 30860 30960 30960 31060 31060 31160 $1,129 $990 $1,129 $996 $1,134 $994 $1,134 $999 $1,139 $997 $1,139 $1,003 $1,144 $1,001 $1,144 $1,006 $1,149 $1,004 $1,149 $1,010 $1,154 $1,008 $1,154 $1,013 37460 37560 37560 37660 37660 37760 37760 37860 37860 37960 37960 38060 $1,475 $1,232 $1,475 $1,238 $1,480 $1,236 $1,480 $1,241 $1,485 $1,239 $1,485 $1,245 $1,490 $1,243 $1,490 $1,248 $1,495 $1,246 $1,495 $1,252 $1,500 $1,250 $1,500 $1,255 24260 24360 24360 24460 24460 24560 24560 24660 $814 $769 $814 $774 $819 $772 $819 $778 $824 $776 $824 $781 $829 $779 $829 $785 31160 31260 31260 31360 31360 31460 31460 31560 $1,160 $1,011 $1,160 $1,017 $1,165 $1,015 $1,165 $1,020 $1,170 $1,018 $1,170 $1,024 $1,175 $1,022 $1,175 $1,027 38060 38160 38160 38260 38260 38360 38360 38460 $1,505 $1,253 $1,505 $1,259 $1,510 $1,257 $1,510 $1,262 $1,515 $1,260 $1,515 $1,266 $1,520 $1,264 $1,520 $1,269 24660 24760 24760 24860 24860 24960 24960 25060 25060 25160 25160 25260 $834 $783 $834 $788 $839 $786 $839 $792 $844 $790 $844 $795 $849 $793 $849 $799 $854 $797 $854 $803 $859 $800 $859 $806 31560 31660 31660 31760 31760 31860 31860 31960 31960 32060 32060 32160 $1,180 $1,025 $1,180 $1,031 $1,185 $1,029 $1,185 $1,034 $1,190 $1,032 $1,190 $1,038 $1,195 $1,036 $1,195 $1,041 $1,200 $1,039 $1,200 $1,045 $1,205 $1,043 $1,205 $1,048 38460 38560 38560 38660 38660 38760 38760 38860 38860 38960 38960 39060 $1,525 $1,267 $1,525 $1,273 $1,530 $1,271 $1,530 $1,277 $1,535 $1,274 $1,535 $1,282 $1,540 $1,278 $1,540 $1,287 $1,545 $1,281 $1,545 $1,292 $1,551 $1,285 $1,551 $1,297 25260 25360 25360 25460 25460 25560 25560 25660 $864 $804 $864 $810 $869 $807 $869 $813 $874 $811 $874 $817 $879 $814 $879 $820 32160 32260 32260 32360 32360 32460 32460 32560 $1,210 $1,046 $1,210 $1,052 $1,215 $1,050 $1,215 $1,055 $1,220 $1,053 $1,220 $1,059 $1,225 $1,057 $1,225 $1,062 39060 39160 39160 39260 39260 39360 39360 39460 $1,556 $1,288 $1,556 $1,302 $1,561 $1,292 $1,561 $1,307 $1,566 $1,295 $1,566 $1,312 $1,571 $1,299 $1,571 $1,317 25660 25760 25760 25860 25860 25960 25960 26060 26060 26160 26160 26260 $884 $818 $884 $824 $889 $822 $889 $827 $894 $825 $894 $831 $899 $829 $899 $834 $904 $832 $904 $838 $909 $836 $909 $841 32560 32660 32660 32760 32760 32860 32860 32960 32960 33060 33060 33160 $1,230 $1,060 $1,230 $1,066 $1,235 $1,064 $1,235 $1,069 $1,240 $1,067 $1,240 $1,073 $1,245 $1,071 $1,245 $1,076 $1,250 $1,074 $1,250 $1,080 $1,255 $1,078 $1,255 $1,083 39460 39560 39560 39660 39660 39760 39760 39860 39860 39960 39960 40060 $1,577 $1,302 $1,577 $1,322 $1,582 $1,306 $1,582 $1,327 $1,587 $1,309 $1,587 $1,332 $1,592 $1,313 $1,592 $1,337 $1,597 $1,316 $1,597 $1,342 $1,603 $1,320 $1,603 $1,347 26260 26360 26360 26460 $914 $839 $914 $845 $919 $843 $919 $848 33160 33260 33260 33360 $1,260 $1,081 $1,260 $1,087 $1,265 $1,085 $1,265 $1,090 40060 40160 40160 40260 $1,608 $1,323 $1,608 $1,352 $1,613 $1,327 $1,613 $1,357 *A qualifying surviving spouse must also use this column. Continued on next page
2025 Nebraska Tax Table - continued
# If Nebraska If Nebraska If Nebraska taxable taxable
And you are - income is -
And you are - And you are - income is - income is -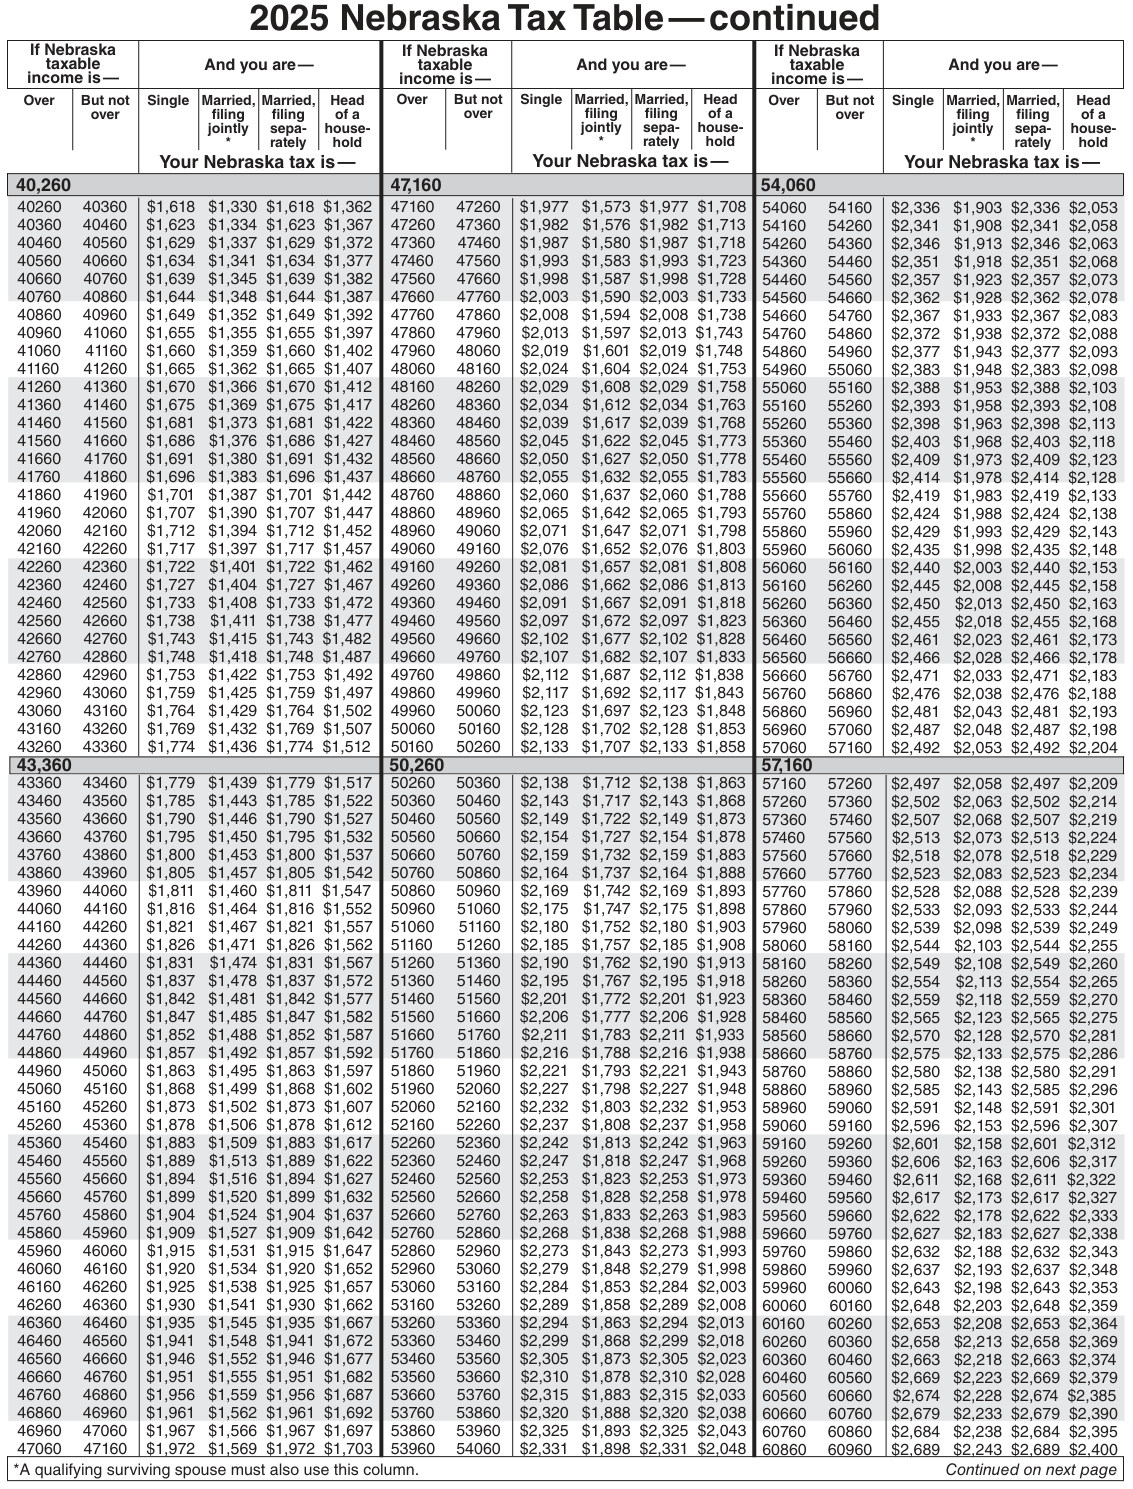
Text version of this table
If Nebraska taxable income is — And you are — If Nebraska taxable income is — And you are — If Nebraska taxable income is — And you are — Over But not over Single Married,Married, Head fliing fliing of a jointly sepa- house- * rately hold Your Nebraska tax is — Over But not over Single Married,Married, Head fliing fliing of a jointly sepa- house- * rately hold Your Nebraska tax is — Over But not over Single Married,Married, Head fliing fliing of a jointly sepa- house- * rately hold Your Nebraska tax is — 40,260 47,160 54,060 40260 40360 40360 40460 40460 40560 40560 40660 40660 40760 40760 40860 $1,618 $1,330 $1,618 $1,362 $1,623 $1,334 $1,623 $1,367 $1,629 $1,337 $1,629 $1,372 $1,634 $1,341 $1,634 $1,377 $1,639 $1,345 $1,639 $1,382 $1,644 $1,348 $1,644 $1,387 47160 47260 47260 47360 47360 47460 47460 47560 47560 47660 47660 47760 $1,977 $1,573 $1,977 $1,708 $1,982 $1,576 $1,982 $1,713 $1,987 $1,580 $1,987 $1,718 $1,993 $1,583 $1,993 $1,723 $1,998 $1,587 $1,998 $1,728 $2,003 $1,590 $2,003 $1,733 54060 54160 54160 54260 54260 54360 54360 54460 54460 54560 54560 54660 $2,336 $1,903 $2,336 $2,053 $2,341 $1,908 $2,341 $2,058 $2,346 $1,913 $2,346 $2,063 $2,351 $1,918 $2,351 $2,068 $2,357 $1,923 $2,357 $2,073 $2,362 $1,928 $2,362 $2,078 40860 40960 40960 41060 41060 41160 41160 41260 $1,649 $1,352 $1,649 $1,392 $1,655 $1,355 $1,655 $1,397 $1,660 $1,359 $1,660 $1,402 $1,665 $1,362 $1,665 $1,407 47760 47860 47860 47960 47960 48060 48060 48160 $2,008 $1,594 $2,008 $1,738 $2,013 $1,597 $2,013 $1,743 $2,019 $1,601 $2,019 $1,748 $2,024 $1,604 $2,024 $1,753 54660 54760 54760 54860 54860 54960 54960 55060 $2,367 $1,933 $2,367 $2,083 $2,372 $1,938 $2,372 $2,088 $2,377 $1,943 $2,377 $2,093 $2,383 $1,948 $2,383 $2,098 41260 41360 41360 41460 41460 41560 41560 41660 41660 41760 41760 41860 $1,670 $1,366 $1,670 $1,412 $1,675 $1,369 $1,675 $1,417 $1,681 $1,373 $1,681 $1,422 $1,686 $1,376 $1,686 $1,427 $1,691 $1,380 $1,691 $1,432 $1,696 $1,383 $1,696 $1,437 48160 48260 48260 48360 48360 48460 48460 48560 48560 48660 48660 48760 $2,029 $1,608 $2,029 $1,758 $2,034 $1,612 $2,034 $1,763 $2,039 $1,617 $2,039 $1,768 $2,045 $1,622 $2,045 $1,773 $2,050 $1,627 $2,050 $1,778 $2,055 $1,632 $2,055 $1,783 55060 55160 55160 55260 55260 55360 55360 55460 55460 55560 55560 55660 $2,388 $1,953 $2,388 $2,103 $2,393 $1,958 $2,393 $2,108 $2,398 $1,963 $2,398 $2,113 $2,403 $1,968 $2,403 $2,118 $2,409 $1,973 $2,409 $2,123 $2,414 $1,978 $2,414 $2,128 41860 41960 41960 42060 42060 42160 42160 42260 $1,701 $1,387 $1,701 $1,442 $1,707 $1,390 $1,707 $1,447 $1,712 $1,394 $1,712 $1,452 $1,717 $1,397 $1,717 $1,457 48760 48860 48860 48960 48960 49060 49060 49160 $2,060 $1,637 $2,060 $1,788 $2,065 $1,642 $2,065 $1,793 $2,071 $1,647 $2,071 $1,798 $2,076 $1,652 $2,076 $1,803 55660 55760 55760 55860 55860 55960 55960 56060 $2,419 $1,983 $2,419 $2,133 $2,424 $1,988 $2,424 $2,138 $2,429 $1,993 $2,429 $2,143 $2,435 $1,998 $2,435 $2,148 42260 42360 42360 42460 42460 42560 42560 42660 42660 42760 42760 42860 $1,722 $1,401 $1,722 $1,462 $1,727 $1,404 $1,727 $1,467 $1,733 $1,408 $1,733 $1,472 $1,738 $1,411 $1,738 $1,477 $1,743 $1,415 $1,743 $1,482 $1,748 $1,418 $1,748 $1,487 49160 49260 49260 49360 49360 49460 49460 49560 49560 49660 49660 49760 $2,081 $1,657 $2,081 $1,808 $2,086 $1,662 $2,086 $1,813 $2,091 $1,667 $2,091 $1,818 $2,097 $1,672 $2,097 $1,823 $2,102 $1,677 $2,102 $1,828 $2,107 $1,682 $2,107 $1,833 56060 56160 56160 56260 56260 56360 56360 56460 56460 56560 56560 56660 $2,440 $2,003 $2,440 $2,153 $2,445 $2,008 $2,445 $2,158 $2,450 $2,013 $2,450 $2,163 $2,455 $2,018 $2,455 $2,168 $2,461 $2,023 $2,461 $2,173 $2,466 $2,028 $2,466 $2,178 42860 42960 42960 43060 43060 43160 43160 43260 43260 43360 $1,753 $1,422 $1,753 $1,492 $1,759 $1,425 $1,759 $1,497 $1,764 $1,429 $1,764 $1,502 $1,769 $1,432 $1,769 $1,507 $1,774 $1,436 $1,774 $1,512 49760 49860 49860 49960 49960 50060 50060 50160 50160 50260 $2,112 $1,687 $2,112 $1,838 $2,117 $1,692 $2,117 $1,843 $2,123 $1,697 $2,123 $1,848 $2,128 $1,702 $2,128 $1,853 $2,133 $1,707 $2,133 $1,858 56660 56760 56760 56860 56860 56960 56960 57060 57060 57160 $2,471 $2,033 $2,471 $2,183 $2,476 $2,038 $2,476 $2,188 $2,481 $2,043 $2,481 $2,193 $2,487 $2,048 $2,487 $2,198 $2,492 $2,053 $2,492 $2,204 43,360 50,260 57,160 43360 43460 43460 43560 43560 43660 43660 43760 43760 43860 43860 43960 $1,779 $1,439 $1,779 $1,517 $1,785 $1,443 $1,785 $1,522 $1,790 $1,446 $1,790 $1,527 $1,795 $1,450 $1,795 $1,532 $1,800 $1,453 $1,800 $1,537 $1,805 $1,457 $1,805 $1,542 50260 50360 50360 50460 50460 50560 50560 50660 50660 50760 50760 50860 $2,138 $1,712 $2,138 $1,863 $2,143 $1,717 $2,143 $1,868 $2,149 $1,722 $2,149 $1,873 $2,154 $1,727 $2,154 $1,878 $2,159 $1,732 $2,159 $1,883 $2,164 $1,737 $2,164 $1,888 57160 57260 57260 57360 57360 57460 57460 57560 57560 57660 57660 57760 $2,497 $2,058 $2,497 $2,209 $2,502 $2,063 $2,502 $2,214 $2,507 $2,068 $2,507 $2,219 $2,513 $2,073 $2,513 $2,224 $2,518 $2,078 $2,518 $2,229 $2,523 $2,083 $2,523 $2,234 43960 44060 44060 44160 44160 44260 44260 44360 $1,811 $1,460 $1,811 $1,547 $1,816 $1,464 $1,816 $1,552 $1,821 $1,467 $1,821 $1,557 $1,826 $1,471 $1,826 $1,562 50860 50960 50960 51060 51060 51160 51160 51260 $2,169 $1,742 $2,169 $1,893 $2,175 $1,747 $2,175 $1,898 $2,180 $1,752 $2,180 $1,903 $2,185 $1,757 $2,185 $1,908 57760 57860 57860 57960 57960 58060 58060 58160 $2,528 $2,088 $2,528 $2,239 $2,533 $2,093 $2,533 $2,244 $2,539 $2,098 $2,539 $2,249 $2,544 $2,103 $2,544 $2,255 44360 44460 44460 44560 44560 44660 44660 44760 44760 44860 44860 44960 $1,831 $1,474 $1,831 $1,567 $1,837 $1,478 $1,837 $1,572 $1,842 $1,481 $1,842 $1,577 $1,847 $1,485 $1,847 $1,582 $1,852 $1,488 $1,852 $1,587 $1,857 $1,492 $1,857 $1,592 51260 51360 51360 51460 51460 51560 51560 51660 51660 51760 51760 51860 $2,190 $1,762 $2,190 $1,913 $2,195 $1,767 $2,195 $1,918 $2,201 $1,772 $2,201 $1,923 $2,206 $1,777 $2,206 $1,928 $2,211 $1,783 $2,211 $1,933 $2,216 $1,788 $2,216 $1,938 58160 58260 58260 58360 58360 58460 58460 58560 58560 58660 58660 58760 $2,549 $2,108 $2,549 $2,260 $2,554 $2,113 $2,554 $2,265 $2,559 $2,118 $2,559 $2,270 $2,565 $2,123 $2,565 $2,275 $2,570 $2,128 $2,570 $2,281 $2,575 $2,133 $2,575 $2,286 44960 45060 45060 45160 45160 45260 45260 45360 $1,863 $1,495 $1,863 $1,597 $1,868 $1,499 $1,868 $1,602 $1,873 $1,502 $1,873 $1,607 $1,878 $1,506 $1,878 $1,612 51860 51960 51960 52060 52060 52160 52160 52260 $2,221 $1,793 $2,221 $1,943 $2,227 $1,798 $2,227 $1,948 $2,232 $1,803 $2,232 $1,953 $2,237 $1,808 $2,237 $1,958 58760 58860 58860 58960 58960 59060 59060 59160 $2,580 $2,138 $2,580 $2,291 $2,585 $2,143 $2,585 $2,296 $2,591 $2,148 $2,591 $2,301 $2,596 $2,153 $2,596 $2,307 45360 45460 45460 45560 45560 45660 45660 45760 45760 45860 45860 45960 $1,883 $1,509 $1,883 $1,617 $1,889 $1,513 $1,889 $1,622 $1,894 $1,516 $1,894 $1,627 $1,899 $1,520 $1,899 $1,632 $1,904 $1,524 $1,904 $1,637 $1,909 $1,527 $1,909 $1,642 52260 52360 52360 52460 52460 52560 52560 52660 52660 52760 52760 52860 $2,242 $1,813 $2,242 $1,963 $2,247 $1,818 $2,247 $1,968 $2,253 $1,823 $2,253 $1,973 $2,258 $1,828 $2,258 $1,978 $2,263 $1,833 $2,263 $1,983 $2,268 $1,838 $2,268 $1,988 59160 59260 59260 59360 59360 59460 59460 59560 59560 59660 59660 59760 $2,601 $2,158 $2,601 $2,312 $2,606 $2,163 $2,606 $2,317 $2,611 $2,168 $2,611 $2,322 $2,617 $2,173 $2,617 $2,327 $2,622 $2,178 $2,622 $2,333 $2,627 $2,183 $2,627 $2,338 45960 46060 46060 46160 46160 46260 46260 46360 $1,915 $1,531 $1,915 $1,647 $1,920 $1,534 $1,920 $1,652 $1,925 $1,538 $1,925 $1,657 $1,930 $1,541 $1,930 $1,662 52860 52960 52960 53060 53060 53160 53160 53260 $2,273 $1,843 $2,273 $1,993 $2,279 $1,848 $2,279 $1,998 $2,284 $1,853 $2,284 $2,003 $2,289 $1,858 $2,289 $2,008 59760 59860 59860 59960 59960 60060 60060 60160 $2,632 $2,188 $2,632 $2,343 $2,637 $2,193 $2,637 $2,348 $2,643 $2,198 $2,643 $2,353 $2,648 $2,203 $2,648 $2,359 46360 46460 46460 46560 46560 46660 46660 46760 46760 46860 46860 46960 $1,935 $1,545 $1,935 $1,667 $1,941 $1,548 $1,941 $1,672 $1,946 $1,552 $1,946 $1,677 $1,951 $1,555 $1,951 $1,682 $1,956 $1,559 $1,956 $1,687 $1,961 $1,562 $1,961 $1,692 53260 53360 53360 53460 53460 53560 53560 53660 53660 53760 53760 53860 $2,294 $1,863 $2,294 $2,013 $2,299 $1,868 $2,299 $2,018 $2,305 $1,873 $2,305 $2,023 $2,310 $1,878 $2,310 $2,028 $2,315 $1,883 $2,315 $2,033 $2,320 $1,888 $2,320 $2,038 60160 60260 60260 60360 60360 60460 60460 60560 60560 60660 60660 60760 $2,653 $2,208 $2,653 $2,364 $2,658 $2,213 $2,658 $2,369 $2,663 $2,218 $2,663 $2,374 $2,669 $2,223 $2,669 $2,379 $2,674 $2,228 $2,674 $2,385 $2,679 $2,233 $2,679 $2,390 46960 47060 47060 47160 $1,967 $1,566 $1,967 $1,697 $1,972 $1,569 $1,972 $1,703 53860 53960 53960 54060 $2,325 $1,893 $2,325 $2,043 $2,331 $1,898 $2,331 $2,048 60760 60860 60860 60960 $2,684 $2,238 $2,684 $2,395 $2,689 $2,243 $2,689 $2,400 *A qualifying surviving spouse must also use this column. Continued on next page
# If Nebraska
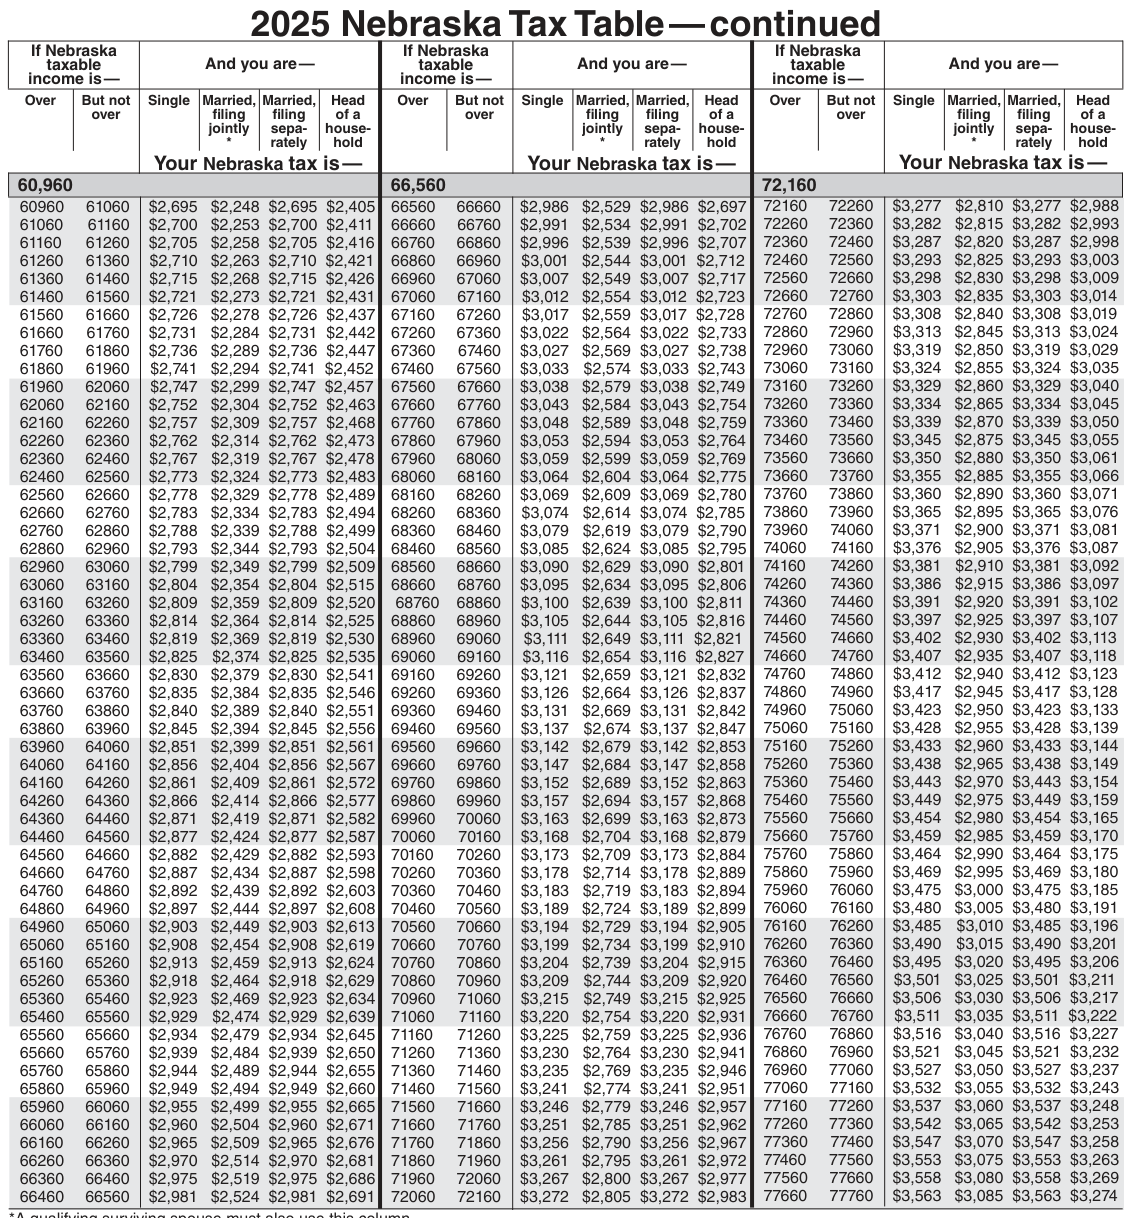
Text version of this table
| If Nebraska taxable income is — | And you are — | If Nebraska taxable income is — | And you are — | If Nebraska taxable income is — | And you are — |
|---|---|---|---|---|---|
| Over But not over | Single Married,Married, Head fliing fliing of a jointly sepa- house- * rately hold Your Nebraska tax is — | Over But not over | Single Married,Married, Head fliing fliing of a jointly sepa- house- * rately hold Your Nebraska tax is — | Over But not over | Single Married,Married, Head fliing fliing of a jointly sepa- house- * rately hold Your Nebraska tax is — |
| 60,960 | 66,560 | 72,160 | |||
| 60960 61060 61060 61160 61160 61260 61260 61360 61360 61460 61460 61560 | $2,695 $2,248 $2,695 $2,405 $2,700 $2,253 $2,700 $2,411 $2,705 $2,258 $2,705 $2,416 $2,710 $2,263 $2,710 $2,421 $2,715 $2,268 $2,715 $2,426 $2,721 $2,273 $2,721 $2,431 | 66560 66660 66660 66760 66760 66860 66860 66960 66960 67060 67060 67160 | $2,986 $2,529 $2,986 $2,697 $2,991 $2,534 $2,991 $2,702 $2,996 $2,539 $2,996 $2,707 $3,001 $2,544 $3,001 $2,712 $3,007 $2,549 $3,007 $2,717 $3,012 $2,554 $3,012 $2,723 | 72160 72260 72260 72360 72360 72460 72460 72560 72560 72660 72660 72760 | $3,277 $2,810 $3,277 $2,988 $3,282 $2,815 $3,282 $2,993 $3,287 $2,820 $3,287 $2,998 $3,293 $2,825 $3,293 $3,003 $3,298 $2,830 $3,298 $3,009 $3,303 $2,835 $3,303 $3,014 |
| 61560 61660 61660 61760 61760 61860 61860 61960 | $2,726 $2,278 $2,726 $2,437 $2,731 $2,284 $2,731 $2,442 $2,736 $2,289 $2,736 $2,447 $2,741 $2,294 $2,741 $2,452 | 67160 67260 67260 67360 67360 67460 67460 67560 | $3,017 $2,559 $3,017 $2,728 $3,022 $2,564 $3,022 $2,733 $3,027 $2,569 $3,027 $2,738 $3,033 $2,574 $3,033 $2,743 | 72760 72860 72860 72960 72960 73060 73060 73160 | $3,308 $2,840 $3,308 $3,019 $3,313 $2,845 $3,313 $3,024 $3,319 $2,850 $3,319 $3,029 $3,324 $2,855 $3,324 $3,035 |
| 61960 62060 62060 62160 62160 62260 62260 62360 62360 62460 62460 62560 | $2,747 $2,299 $2,747 $2,457 $2,752 $2,304 $2,752 $2,463 $2,757 $2,309 $2,757 $2,468 $2,762 $2,314 $2,762 $2,473 $2,767 $2,319 $2,767 $2,478 $2,773 $2,324 $2,773 $2,483 | 67560 67660 67660 67760 67760 67860 67860 67960 67960 68060 68060 68160 | $3,038 $2,579 $3,038 $2,749 $3,043 $2,584 $3,043 $2,754 $3,048 $2,589 $3,048 $2,759 $3,053 $2,594 $3,053 $2,764 $3,059 $2,599 $3,059 $2,769 $3,064 $2,604 $3,064 $2,775 | 73160 73260 73260 73360 73360 73460 73460 73560 73560 73660 73660 73760 | $3,329 $2,860 $3,329 $3,040 $3,334 $2,865 $3,334 $3,045 $3,339 $2,870 $3,339 $3,050 $3,345 $2,875 $3,345 $3,055 $3,350 $2,880 $3,350 $3,061 $3,355 $2,885 $3,355 $3,066 |
| 62560 62660 62660 62760 62760 62860 62860 62960 | $2,778 $2,329 $2,778 $2,489 $2,783 $2,334 $2,783 $2,494 $2,788 $2,339 $2,788 $2,499 $2,793 $2,344 $2,793 $2,504 | 68160 68260 68260 68360 68360 68460 68460 68560 | $3,069 $2,609 $3,069 $2,780 $3,074 $2,614 $3,074 $2,785 $3,079 $2,619 $3,079 $2,790 $3,085 $2,624 $3,085 $2,795 | 73760 73860 73860 73960 73960 74060 74060 74160 | $3,360 $2,890 $3,360 $3,071 $3,365 $2,895 $3,365 $3,076 $3,371 $2,900 $3,371 $3,081 $3,376 $2,905 $3,376 $3,087 |
| 62960 63060 63060 63160 63160 63260 63260 63360 63360 63460 63460 63560 | $2,799 $2,349 $2,799 $2,509 $2,804 $2,354 $2,804 $2,515 $2,809 $2,359 $2,809 $2,520 $2,814 $2,364 $2,814 $2,525 $2,819 $2,369 $2,819 $2,530 $2,825 $2,374 $2,825 $2,535 | 68560 68660 68660 68760 68760 68860 68860 68960 68960 69060 69060 69160 | $3,090 $2,629 $3,090 $2,801 $3,095 $2,634 $3,095 $2,806 $3,100 $2,639 $3,100 $2,811 $3,105 $2,644 $3,105 $2,816 $3,111 $2,649 $3,111 $2,821 $3,116 $2,654 $3,116 $2,827 | 74160 74260 74260 74360 74360 74460 74460 74560 74560 74660 74660 74760 | $3,381 $2,910 $3,381 $3,092 $3,386 $2,915 $3,386 $3,097 $3,391 $2,920 $3,391 $3,102 $3,397 $2,925 $3,397 $3,107 $3,402 $2,930 $3,402 $3,113 $3,407 $2,935 $3,407 $3,118 |
| 63560 63660 63660 63760 63760 63860 63860 63960 | $2,830 $2,379 $2,830 $2,541 $2,835 $2,384 $2,835 $2,546 $2,840 $2,389 $2,840 $2,551 $2,845 $2,394 $2,845 $2,556 | 69160 69260 69260 69360 69360 69460 69460 69560 | $3,121 $2,659 $3,121 $2,832 $3,126 $2,664 $3,126 $2,837 $3,131 $2,669 $3,131 $2,842 $3,137 $2,674 $3,137 $2,847 | 74760 74860 74860 74960 74960 75060 75060 75160 | $3,412 $2,940 $3,412 $3,123 $3,417 $2,945 $3,417 $3,128 $3,423 $2,950 $3,423 $3,133 $3,428 $2,955 $3,428 $3,139 |
| 63960 64060 64060 64160 64160 64260 64260 64360 64360 64460 64460 64560 | $2,851 $2,399 $2,851 $2,561 $2,856 $2,404 $2,856 $2,567 $2,861 $2,409 $2,861 $2,572 $2,866 $2,414 $2,866 $2,577 $2,871 $2,419 $2,871 $2,582 $2,877 $2,424 $2,877 $2,587 | 69560 69660 69660 69760 69760 69860 69860 69960 69960 70060 70060 70160 | $3,142 $2,679 $3,142 $2,853 $3,147 $2,684 $3,147 $2,858 $3,152 $2,689 $3,152 $2,863 $3,157 $2,694 $3,157 $2,868 $3,163 $2,699 $3,163 $2,873 $3,168 $2,704 $3,168 $2,879 | 75160 75260 75260 75360 75360 75460 75460 75560 75560 75660 75660 75760 | $3,433 $2,960 $3,433 $3,144 $3,438 $2,965 $3,438 $3,149 $3,443 $2,970 $3,443 $3,154 $3,449 $2,975 $3,449 $3,159 $3,454 $2,980 $3,454 $3,165 $3,459 $2,985 $3,459 $3,170 |
| 64560 64660 64660 64760 64760 64860 64860 64960 | $2,882 $2,429 $2,882 $2,593 $2,887 $2,434 $2,887 $2,598 $2,892 $2,439 $2,892 $2,603 $2,897 $2,444 $2,897 $2,608 | 70160 70260 70260 70360 70360 70460 70460 70560 | $3,173 $2,709 $3,173 $2,884 $3,178 $2,714 $3,178 $2,889 $3,183 $2,719 $3,183 $2,894 $3,189 $2,724 $3,189 $2,899 | 75760 75860 75860 75960 75960 76060 76060 76160 | $3,464 $2,990 $3,464 $3,175 $3,469 $2,995 $3,469 $3,180 $3,475 $3,000 $3,475 $3,185 $3,480 $3,005 $3,480 $3,191 |
| 64960 65060 65060 65160 65160 65260 65260 65360 65360 65460 65460 65560 | $2,903 $2,449 $2,903 $2,613 $2,908 $2,454 $2,908 $2,619 $2,913 $2,459 $2,913 $2,624 $2,918 $2,464 $2,918 $2,629 $2,923 $2,469 $2,923 $2,634 $2,929 $2,474 $2,929 $2,639 | 70560 70660 70660 70760 70760 70860 70860 70960 70960 71060 71060 71160 | $3,194 $2,729 $3,194 $2,905 $3,199 $2,734 $3,199 $2,910 $3,204 $2,739 $3,204 $2,915 $3,209 $2,744 $3,209 $2,920 $3,215 $2,749 $3,215 $2,925 $3,220 $2,754 $3,220 $2,931 | 76160 76260 76260 76360 76360 76460 76460 76560 76560 76660 76660 76760 | $3,485 $3,010 $3,485 $3,196 $3,490 $3,015 $3,490 $3,201 $3,495 $3,020 $3,495 $3,206 $3,501 $3,025 $3,501 $3,211 $3,506 $3,030 $3,506 $3,217 $3,511 $3,035 $3,511 $3,222 |
| 65560 65660 65660 65760 65760 65860 65860 65960 | $2,934 $2,479 $2,934 $2,645 $2,939 $2,484 $2,939 $2,650 $2,944 $2,489 $2,944 $2,655 $2,949 $2,494 $2,949 $2,660 | 71160 71260 71260 71360 71360 71460 71460 71560 | $3,225 $2,759 $3,225 $2,936 $3,230 $2,764 $3,230 $2,941 $3,235 $2,769 $3,235 $2,946 $3,241 $2,774 $3,241 $2,951 | 76760 76860 76860 76960 76960 77060 77060 77160 | $3,516 $3,040 $3,516 $3,227 $3,521 $3,045 $3,521 $3,232 $3,527 $3,050 $3,527 $3,237 $3,532 $3,055 $3,532 $3,243 |
| 65960 66060 66060 66160 66160 66260 66260 66360 66360 66460 66460 66560 | $2,955 $2,499 $2,955 $2,665 $2,960 $2,504 $2,960 $2,671 $2,965 $2,509 $2,965 $2,676 $2,970 $2,514 $2,970 $2,681 $2,975 $2,519 $2,975 $2,686 $2,981 $2,524 $2,981 $2,691 | 71560 71660 71660 71760 71760 71860 71860 71960 71960 72060 72060 72160 | $3,246 $2,779 $3,246 $2,957 $3,251 $2,785 $3,251 $2,962 $3,256 $2,790 $3,256 $2,967 $3,261 $2,795 $3,261 $2,972 $3,267 $2,800 $3,267 $2,977 $3,272 $2,805 $3,272 $2,983 | 77160 77260 77260 77360 77360 77460 77460 77560 77560 77660 77660 77760 | $3,537 $3,060 $3,537 $3,248 $3,542 $3,065 $3,542 $3,253 $3,547 $3,070 $3,547 $3,258 $3,553 $3,075 $3,553 $3,263 $3,558 $3,080 $3,558 $3,269 $3,563 $3,085 $3,563 $3,274 |
# Over $77,760
- Use the following worksheet if your Nebraska taxable income is more than the maximum amount included in the 2025 Nebraska Tax Table. The tax table shown above calculates tax to the midpoint of the bracket. The amounts shown below represent tax calculated on $77,760, the endpoint of the bracket.
Head of household
Married, filing separately
Married, filing jointly or qualifying surviving
Single
Add $3,276 plus 5.20% spouse
Add $3,566 plus 5.20% Add $3,566 plus 5.20% of the amount over $77,760.
Add $3,088 plus 5.20% of the amount over $77,760. of the amount over $77,760. of the amount over $77,760.
(Your taxable income - $77,760) x .0520 (Your taxable income - $77,760) x .0520 (Your taxable income - $77,760) x .0520 (Your taxable income - $77,760) x .0520
- $3,566 = Your Nebraska tax.
- $3,088 = Your Nebraska tax.
- $3,566 = Your Nebraska tax. + $3,276 = Your Nebraska tax.
This is your Nebraska income tax.
(Enter on line 15, Form 1040N; or if you are a nonresident or partial-year resident, enter on line 6a, Nebraska Schedule III.)
49 revenue.nebraska.gov
# Local Sales and Use Tax Codes and Rates
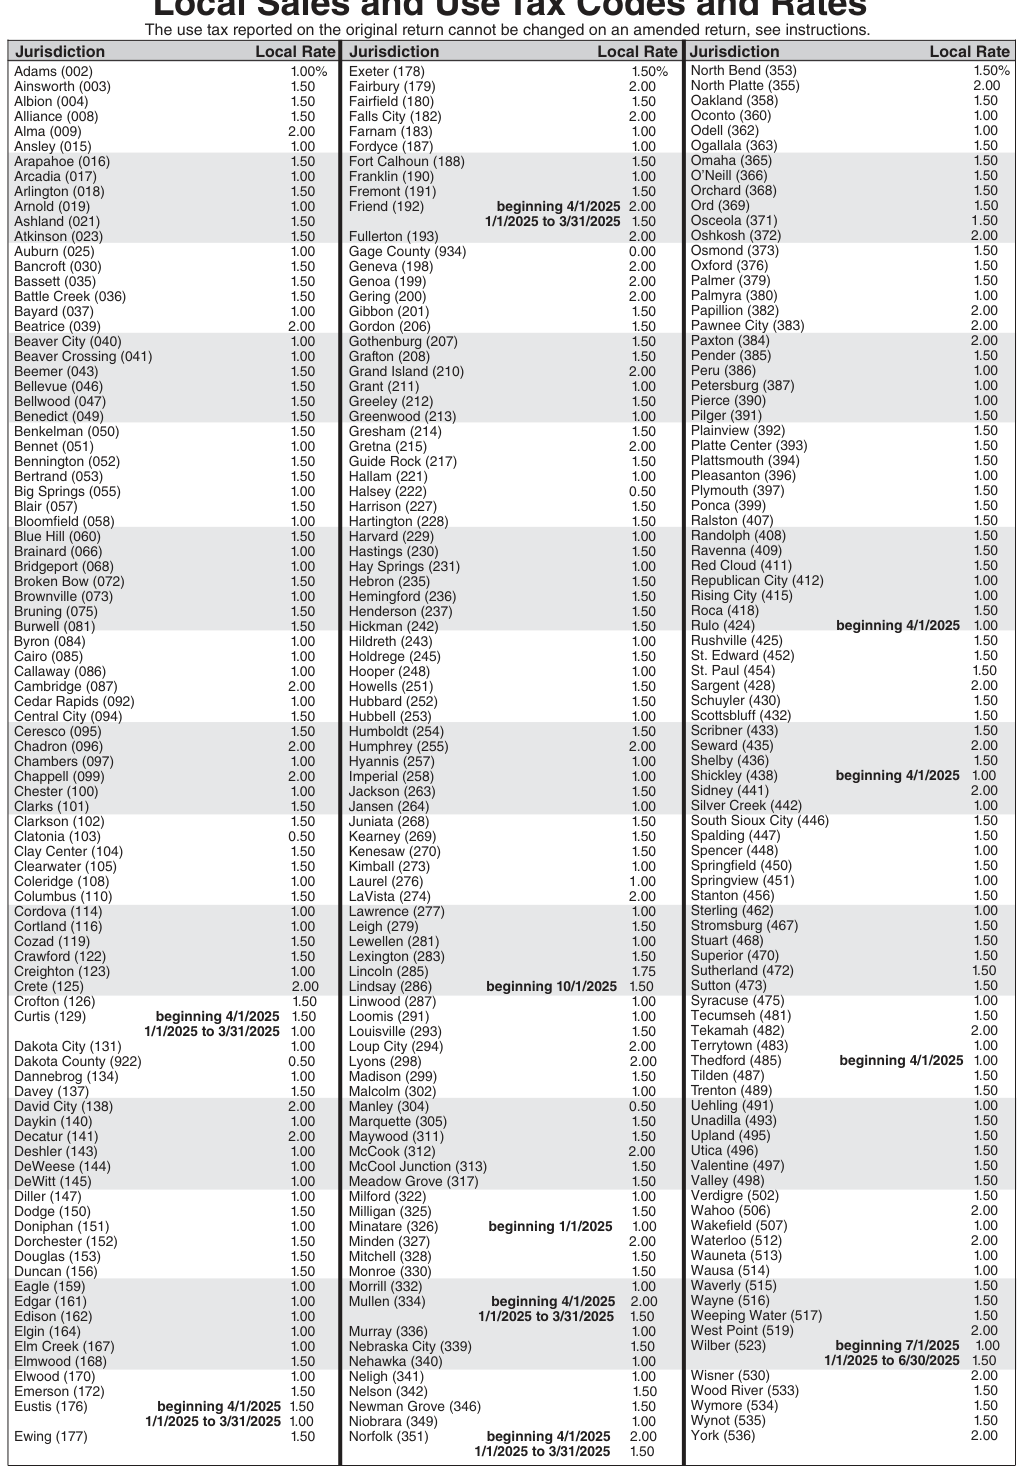
Text version of this table
| Jurisdiction Local Rate | Jurisdiction Local Rate | Jurisdiction Local Rate |
|---|---|---|
| Adams (002) 1.00% Ainsworth (003) 1.50 Albion (004) 1.50 Alliance (008) 1.50 Alma (009) 2.00 Ansley (015) 1.00 | Exeter (178) 1.50% Fairbury (179) 2.00 Fairfield (180) 1.50 Falls City (182) 2.00 Farnam (183) 1.00 Fordyce (187) 1.00 | North Bend (353) 1.50% North Platte (355) 2.00 Oakland (358) 1.50 Oconto (360) 1.00 Odell (362) 1.00 Ogallala (363) 1.50 |
| Arapahoe (016) 1.50 Arcadia (017) 1.00 Arlington (018) 1.50 Arnold (019) 1.00 Ashland (021) 1.50 Atkinson (023) 1.50 | Fort Calhoun (188) 1.50 Franklin (190) 1.00 Fremont (191) 1.50 Friend (192) beginning 4/1/2025 2.00 1/1/2025 to 3/31/2025 1.50 Fullerton (193) 2.00 | Omaha (365) 1.50 O’Neill (366) 1.50 Orchard (368) 1.50 Ord (369) 1.50 Osceola (371) 1.50 Oshkosh (372) 2.00 |
| Auburn (025) 1.00 Bancroft (030) 1.50 Bassett (035) 1.50 Battle Creek (036) 1.50 Bayard (037) 1.00 Beatrice (039) 2.00 | Gage County (934) 0.00 Geneva (198) 2.00 Genoa (199) 2.00 Gering (200) 2.00 Gibbon (201) 1.50 Gordon (206) 1.50 | Osmond (373) 1.50 Oxford (376) 1.50 Palmer (379) 1.50 Palmyra (380) 1.00 Papillion (382) 2.00 Pawnee City (383) 2.00 |
| Beaver City (040) 1.00 Beaver Crossing (041) 1.00 Beemer (043) 1.50 Bellevue (046) 1.50 Bellwood (047) 1.50 Benedict (049) 1.50 | Gothenburg (207) 1.50 Grafton (208) 1.50 Grand Island (210) 2.00 Grant (211) 1.00 Greeley (212) 1.50 Greenwood (213) 1.00 | Paxton (384) 2.00 Pender (385) 1.50 Peru (386) 1.00 Petersburg (387) 1.00 Pierce (390) 1.00 Pilger (391) 1.50 |
| Benkelman (050) 1.50 Bennet (051) 1.00 Bennington (052) 1.50 Bertrand (053) 1.50 Big Springs (055) 1.00 Blair (057) 1.50 Bloomfield (058) 1.00 | Gresham (214) 1.50 Gretna (215) 2.00 Guide Rock (217) 1.50 Hallam (221) 1.00 Halsey (222) 0.50 Harrison (227) 1.50 Hartington (228) 1.50 | Plainview (392) 1.50 Platte Center (393) 1.50 Plattsmouth (394) 1.50 Pleasanton (396) 1.00 Plymouth (397) 1.50 Ponca (399) 1.50 Ralston (407) 1.50 |
| Blue Hill (060) 1.50 Brainard (066) 1.00 Bridgeport (068) 1.00 Broken Bow (072) 1.50 Brownville (073) 1.00 Bruning (075) 1.50 Burwell (081) 1.50 | Harvard (229) 1.00 Hastings (230) 1.50 Hay Springs (231) 1.00 Hebron (235) 1.50 Hemingford (236) 1.50 Henderson (237) 1.50 Hickman (242) 1.50 | Randolph (408) 1.50 Ravenna (409) 1.50 Red Cloud (411) 1.50 Republican City (412) 1.00 Rising City (415) 1.00 Roca (418) 1.50 Rulo (424) beginning 4/1/2025 1.00 |
| Byron (084) 1.00 Cairo (085) 1.00 Callaway (086) 1.00 Cambridge (087) 2.00 Cedar Rapids (092) 1.00 Central City (094) 1.50 | Hildreth (243) 1.00 Holdrege (245) 1.50 Hooper (248) 1.00 Howells (251) 1.50 Hubbard (252) 1.50 Hubbell (253) 1.00 | Rushville (425) 1.50 St. Edward (452) 1.50 St. Paul (454) 1.50 Sargent (428) 2.00 Schuyler (430) 1.50 Scottsbluff (432) 1.50 |
| Ceresco (095) 1.50 Chadron (096) 2.00 Chambers (097) 1.00 Chappell (099) 2.00 Chester (100) 1.00 Clarks (101) 1.50 | Humboldt (254) 1.50 Humphrey (255) 2.00 Hyannis (257) 1.00 Imperial (258) 1.00 Jackson (263) 1.50 Jansen (264) 1.00 | Scribner (433) 1.50 Seward (435) 2.00 Shelby (436) 1.50 Shickley (438) beginning 4/1/2025 1.00 Sidney (441) 2.00 Silver Creek (442) 1.00 |
| Clarkson (102) 1.50 Clatonia (103) 0.50 Clay Center (104) 1.50 Clearwater (105) 1.50 Coleridge (108) 1.00 Columbus (110) 1.50 | Juniata (268) 1.50 Kearney (269) 1.50 Kenesaw (270) 1.50 Kimball (273) 1.00 Laurel (276) 1.00 LaVista (274) 2.00 | South Sioux City (446) 1.50 Spalding (447) 1.50 Spencer (448) 1.00 Springfield (450) 1.50 Springview (451) 1.00 Stanton (456) 1.50 |
| Cordova (114) 1.00 Cortland (116) 1.00 Cozad (119) 1.50 Crawford (122) 1.50 Creighton (123) 1.00 Crete (125) 2.00 | Lawrence (277) 1.00 Leigh (279) 1.50 Lewellen (281) 1.00 Lexington (283) 1.50 Lincoln (285) 1.75 Lindsay (286) beginning 10/1/2025 1.50 | Sterling (462) 1.00 Stromsburg (467) 1.50 Stuart (468) 1.50 Superior (470) 1.50 Sutherland (472) 1.50 Sutton (473) 1.50 |
| Crofton (126) 1.50 Curtis (129) beginning 4/1/2025 1.50 1/1/2025 to 3/31/2025 1.00 Dakota City (131) 1.00 Dakota County (922) 0.50 Dannebrog (134) 1.00 Davey (137) 1.50 | Linwood (287) 1.00 Loomis (291) 1.00 Louisville (293) 1.50 Loup City (294) 2.00 Lyons (298) 2.00 Madison (299) 1.50 Malcolm (302) 1.00 | Syracuse (475) 1.00 Tecumseh (481) 1.50 Tekamah (482) 2.00 Terrytown (483) 1.00 Thedford (485) beginning 4/1/2025 1.00 Tilden (487) 1.50 Trenton (489) 1.50 |
| David City (138) 2.00 Daykin (140) 1.00 Decatur (141) 2.00 Deshler (143) 1.00 DeWeese (144) 1.00 DeWitt (145) 1.00 | Manley (304) 0.50 Marquette (305) 1.50 Maywood (311) 1.50 McCook (312) 2.00 McCool Junction (313) 1.50 Meadow Grove (317) 1.50 | Uehling (491) 1.00 Unadilla (493) 1.50 Upland (495) 1.50 Utica (496) 1.50 Valentine (497) 1.50 Valley (498) 1.50 |
| Diller (147) 1.00 Dodge (150) 1.50 Doniphan (151) 1.00 Dorchester (152) 1.50 Douglas (153) 1.50 Duncan (156) 1.50 | Milford (322) 1.00 Milligan (325) 1.50 Minatare (326) beginning 1/1/2025 1.00 Minden (327) 2.00 Mitchell (328) 1.50 Monroe (330) 1.50 | Verdigre (502) 1.50 Wahoo (506) 2.00 Wakefield (507) 1.00 Waterloo (512) 2.00 Wauneta (513) 1.00 Wausa (514) 1.00 |
| Eagle (159) 1.00 Edgar (161) 1.00 Edison (162) 1.00 Elgin (164) 1.00 Elm Creek (167) 1.00 Elmwood (168) 1.50 | Morrill (332) 1.00 Mullen (334) beginning 4/1/2025 2.00 1/1/2025 to 3/31/2025 1.50 Murray (336) 1.00 Nebraska City (339) 1.50 Nehawka (340) 1.00 | Waverly (515) 1.50 Wayne (516) 1.50 Weeping Water (517) 1.50 West Point (519) 2.00 Wilber (523) beginning 7/1/2025 1.00 1/1/2025 to 6/30/2025 1.50 |
| Elwood (170) 1.00 Emerson (172) 1.50 Eustis (176) beginning 4/1/2025 1.50 1/1/2025 to 3/31/2025 1.00 Ewing (177) 1.50 | Neligh (341) 1.00 Nelson (342) 1.50 Newman Grove (346) 1.50 Niobrara (349) 1.00 Norfolk (351) beginning 4/1/2025 2.00 1/1/2025 to 3/31/2025 1.50 | Wisner (530) 2.00 Wood River (533) 1.50 Wymore (534) 1.50 Wynot (535) 1.50 York (536) 2.00 |
# Creighton (123)
# Lincoln (285)
PRSRT STD
U.S. POSTAGE
PAID
STATE OF
NEBRASKA revenue.nebraska.gov 800-742-7474 (NE and IA)
Source: view the official PDF
Nearby sections (10 sections)
- 941n · Form 941N — Nebraska Income Tax Withholding Return
- corp-booklet · NE Corporation Income Tax Booklet — Form 1120N
- form-12n · Form 12N — Nebraska Nonresident Income Tax Composite…
- form-13 · Form 13 — Nebraska Resale or Exempt Sale Certificate
- form-ptc · Form PTC — Nebraska Property Tax Incentive Act Credit…
- form-ptcx · Form PTCX — Amended Nebraska Property Tax Incentive Act…
- individual-income-tax-booklet · NE Individual Income Tax Booklet — Form…
- partnership-booklet · NE Return of Partnership Income Booklet — Form…
- s-corp-booklet · NE S Corporation Income Tax Booklet — Form 1120-SN
- tax-tables · 2025 Nebraska Tax Tables for Individual Income Tax
# Social Security Number
18 NE personal exemption credit for residents only ($171 times the number on line 4) . 18 19 Credit for tax paid to another state, line 6, Nebraska Schedule II (attach Nebraska Schedule II and a copy of the other state's return) . . . . . . . 19 20 Credit for the elderly or disabled (attach copy of Federal Schedule R) . . . . . . . . . . 20 21 Community Development Assistance Act credit (attach Form CDN) . . . . . . . . . . . . 21 22 Form 3800N nonrefundable credit (attach Form 3800N) . . . . . . . . . . . . . . . . . . . . . 22 23 Nebraska child/dependent care nonrefundable credit, only if line 5 is more than $29,000 (attach a copy of Federal Form 2441 and see instructions) . . . . 23 24 Credit for financial institution tax (attach Form NFC) . . . . . . . . . . . . . . . . . . . . . . . . 24 25 Employer's credit for expenses incurred for TANF (ADC) recipients (see instr. ) . . . 25 26 Designated extremely blighted area tax credit (attach Form 1040N-EB) . . . . . . . . . . 26 27 NE employer tax credit for employing convicted felons.
Enter certificate number from Form ETC-A __ . . . . . . . . 27 28 School Readiness Tax Credit for providers.
Enter certificate number from Form SR-3604 __ 28 29 Child Care Tax Credit for Contributors.
Enter certificate number from Form CCTC-A __ . . . . . . . . . . . 29 30 Opportunity Scholarships Act credit for contributors. . . . . . . . . . . . . . . . . . . . . . . . . . . . . 30 31 Creating High Impact Economic Futures (CHIEF) credit. . . . . . . . . . . . . . . . . . . . . . . . . 31 32 Family Caregiver Tax Credit Act.
Enter certificate number from Form 3165 __ . . . . . . . . . . . . . . 32 33 Nebraska Pregnancy Help Act Credit for contributors. . . . . . . . . . . . . . . . . . . . . . . . . . . 33 34 Total nonrefundable credits (add lines 18 through 33) . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . 34 35 Nebraska tax after nonrefundable credits. Subtract line 34 from line 17 (if line 34 is more than line 17, enter -0-) If the result is greater than your federal tax liability, see instructions. If entering federal tax, check box . . . . 35 36 Total Nebraska income tax withheld from Federal Forms W-2 (attach 2025 Forms, see instructions). . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . 36 37 Total Nebraska income tax withheld from Federal Forms W-2G, 1099-R, 1099-MISC, 1099-NEC, etc. (attach 2025 Forms, see instructions). . . . . . . . . . . . . . . . . . . . . . . . . . . 37 38 Total Nebraska income tax withheld from Nebraska Schedules K-1N (attach 2025 Forms, see instructions). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . 38