North Dakota Office of State Tax Commissioner Forms & Instructions
ND Individual Income Tax Booklet — Form ND-1 master instructions
A man and a woman looking at a laptop screen and smiling.
# North Dakota
INDIVIDUAL
INCOME TAX
# INSTRUCTIONS
Form ND-EZ individualtax@nd.gov
# Contents
Refund of local sales tax … Current page Use tax requirement … Current page Privacy Act information … Current page Electronic filing and direct deposit options … 1 Changes for 2025 … 2 General instructions for all filers Steps to completing your return … 4 Who must file a return … 4 Which form to use … 6 Reciprocity … 6 When and where to file … 7 Extension of time to file … 7 Penalty and interest … 7 Federal income tax return … 7 Changing your return … 7 Estimated tax requirement (for 2026) … 8 How to file a return for a deceased taxpayer … 8 Disclosure notification … 8 Instructions for Form ND-EZ … 9 Direct deposit of refund … 9 Balance due (payment options) … 10 Before you file-tips for trouble-free filing … 10 Instructions for Form ND-1 … 11 Direct deposit of refund … 15 Balance due (payment options) … 16 Before you file-tips for trouble-free filing … 16 List of school district codes … 19 2025 Tax Table … 20 How to assemble your North Dakota return … 28 Forms or assistance … 29 Check the status of your refund … 29 Request a copy of your return or other information … 29
# Taxpayer Bill of Rights
Obtain a copy of the
North Dakota Taxpayer Bill of Rights from our website at If you need a form or document mentioned in this booklet, you may obtain it from our website at tax.nd.gov, or request it by phone, e-mail, fax, or letter-see the back cover of this booklet for phone numbers and addresses.
# You might be eligible for a refund of local sales tax!
Most city and county local tax ordinances contain a local sales tax maximum, which varies among the local tax jurisdictions. If you pay local sales tax in excess of the jurisdiction's maximum amount, you may apply to the Office of State Tax Commissioner to obtain a refund of the excess local sales tax paid. For example, if you purchase $4,000 of furniture in a city having a 1% sales tax and a local sales tax maximum of $25, the retailer will collect $200 in state sales tax ($4,000 x 5%) and $40 in local sales tax ($4,000 x 1%) at the time of purchase. You may apply to the Office of State Tax Commissioner to obtain a refund of $15, which is the excess of the $40 local sales tax paid over the $25 local sales tax maximum. Apply for a Local Tax Refund on our North Dakota Taxpayer Access Point (ND TAP) at tax.nd.gov/LocalTaxRefund.
# Do you owe use tax?
If you purchased goods from a source outside North Dakota that you use or consume in North Dakota on which you did not pay North Dakota sales tax, you may have to pay state and local sales taxes to North Dakota.
Technically, what you have to pay is called a "use tax." The use tax applies to the same goods that are subject to North Dakota's sales tax. The use tax applies whether you purchased the goods in person at an out-of-state location, or by mail, phone, or over the Internet.
If you purchased the goods in another state and did not pay any sales tax to that state, you must pay the full use tax to North Dakota. However, if you did pay the other state's sales tax but paid less than what you would have paid in North Dakota, you must pay use tax to North Dakota equal to the difference. If you purchased the goods in another country, you must pay the full use tax to North Dakota regardless of whether you paid any tax to that country on the purchase.
If you owe use tax to North Dakota, you must file a North Dakota use tax return using the One Time Remittance Form. You can obtain it from our website at tax.nd.gov, or you may call us at 701-328-1246.
Privacy Act Notification. In compliance with the Privacy Act of 1974, disclosure of the individual's social security number on this form is required under N.D.C.C. §§ 57-01-15 and 57-38-31, and will be used for tax reporting, identification and administration of North Dakota tax laws. Disclosure is mandatory.
Failure to provide the social security number may delay or prevent the processing of this form.
28702 12-2025
Ready to give E-file a chance?
North Dakota participates in the Internal Revenue Service's (IRS) Federal/State Modernized E-file program. This allows you to file and pay both your federal and North Dakota income tax return at the same time.
No matter what method you use to file - tax preparer, software you purchase, or one of the Free File options, here are a few things to know:
- Direct Deposit - Use direct deposit for a safe, secure method of receiving your refund.
- Return Payments - If you owe money, you can make or schedule a payment when you e-file your return, so you can reap the benefits of filing early while enjoying the flexibility of making the payment on a date of your choosing up to the due date of your return.
- Amending a Return - Taxpayers can amend certain returns electronically; check with your tax preparer or software vendor for availability.
- Estimated Payments - Taxpayers can schedule estimates when they e-file their return. This information must be included when you submit your return, and your account will be debited on the dates you specify.
- Supporting Documents - If you are able, attach PDF copies of supporting documentation (only those items not required to be entered into the program). Doing so may help us process your return without requesting additional information.
# Do it yourself!
Check the list of do-it-yourself software on our website to see which vendor provides the product that meets your needs.
Free File provides taxpayers the opportunity to file their state and federal tax returns electronically. Free File is a public-private partnership between the IRS, states, and many tax software industry leaders who provide services for free.
Companies may charge a fee to file returns unless you meet the criteria set forth by each vendor to file for free.
If you file only your federal return electronically, you will need to file your state return on paper. Don't forget to include a printed copy of your federal income tax return.
# Did You Know?
94% of North Dakota tax filers e-filed their taxes for the 2024 tax year!
Use North Dakota Taxpayer Access Point (NDTAP) to see if you are eligible to use Free File:
Go to tap.tax.nd.gov
Under Individuals, select
Individual Income Tax Electronic Filing Options.
The American Association of Retired Persons (AARP) Foundation and the IRS offers free tax preparation to help taxpayers with their basic individual income tax returns.
Go to our website for more information.
Changes Affecting You and Your Income Tax -Developments, updates, and items of interest relating to individual income tax.
# Consent to Obtain Form 1099-G
Federal Taxable Income - One Big New for 2025 -
# Contribution Income Tax Credit
The 2025 Legislature passed Senate Bill 2282, which created a new income tax
# Beautiful Bill Act (OBBBA)
In July 2025, Congress passed H.R. 1, also known as the OBBBA. Among the changes were extensions of several tax provisions
# Electronically
The North Dakota Office of State Tax Department mails a paper Form 1099-G if there was an overpayment on the 2024 Form ND-EZ or Form ND-1 (last year's from the Tax Cuts and Jobs Act of 2017, along credit for certain employer paid child care reimbursements for its employees. Effective beginning with tax year 2025, employers can earn an income tax credit of 50% of the first $1,000 of child care contributions per employee.
- The credit may be earned by employer payments made directly to child care facilities or to employees for reimbursement of their child care costs for qualified child care.
- Qualified payments include those made to child care facilities licensed in North Dakota and payments to licensed facilities located within 10 miles of North Dakota.
See Schedule ECC and instructions for additional details.
# Pay:
The 2025 Legislature passed Senate Bill 2047 to exempt military pay from North Dakota income tax withholding provisions. Beginning with tax year 2026, income from military pay that qualifies for the military pay deduction is with several other new changes affecting both individual and business income taxes. The starting point for computing North Dakota taxable income perpetually conforms to the computation of federal taxable income.
As a result, the federal changes to income and deductions that impact the computation of federal taxable income are by default included in the starting point for computing North Dakota taxable income for all years.
Some of the federal changes affecting individuals are:
- Increased standard deduction across all filing statuses, with an additional $6,000 for some seniors.
- Increased state and local tax deduction to $40,000.
- Tip income and overtime pay exclusions.
Federal changes to federal income tax credits do not have any direct impact on the computation of North Dakota income tax credits.
Reminder - Contribution Tax
# Credit Documentation
If claiming a tax credit for a contribution, in addition to any required schedule, attach a return), you itemized deductions on your federal return using Schedule A, and you have not previously consented to receive a Form 1099-G electronically. If you have consented to receive Form 1099-G electronically, a paper 2025 Form 1099-G showing the overpayment amount will not be mailed to you. If this information is needed to complete your 2025 federal income tax return, it can be found on our website:
tax.nd.gov/individual/form-1099-g using the 1099-G Lookup Tool.
# Online Payment Options
North Dakota offers a variety of online payment options for submitting an estimated tax payment, extension payment, or payment of a balance due on a return.
For convenience, security, and reassurance knowing the payment was timely received by our office, you are encouraged to pay online with a free electronic check or a debit or credit card using North Dakota Taxpayer Access Point (ND TAP). To pay online, go to:
# Choosing a Tax Return Preparer
You are ultimately responsible for the accuracy of your tax return. Here are some tips to consider when selecting a tax return copy of the letter you received from the school no longer subject to North Dakota income tax withholding provisions. If a taxpayer wishes to have withholding deducted from the exempt pay, they can instruct the employer to do so.
# Exclusion:
If you are a retired military service member, or a surviving spouse of a deceased retired military service member, you may deduct the amount of taxable military retirement benefits that you reported on Form 1040 or Form 1040-SR, line 5b. Include benefits received as a retired member of the U.S. armed forces or its reserve components, Army National Guard, or Air Force National Guard.
"U.S. armed forces" means the Army, Navy, Air Force, Marine Corps, and Coast Guard.
Retirement benefits received for federal civil service employment as a dual status military technician under Title 32 or Title 10 are also eligible for this deduction. or charitable organization to substantiate your contribution and prevent delays in processing your return. Some commonly used credit Schedules are:
- Schedule ND-1PSC: Nonprofit private school tax credits for individuals.
- Schedule ND-1QEC: Qualified endowment fund tax credit.
- Schedule MCP: Contributions to a maternity home, child placing agency, or pregnancy help center. preparer:
- Choose a reputable tax professional. Do your research and ask trusted family or friends for recommendations.
- Make sure your preparer provides a copy of your tax returns for your records.
- Select a preparer based on your needs.
Some preparers are open seasonally and others are available year-round.
# Stay Informed
Individuals, businesses, or other interested persons may sign up to receive email notifications when a newsletter or other important information is issued by the Office of State Tax Commissioner. To sign up, go to tax.nd.gov and select "News Center" at the top of the page. Then select "Email Sign-Up".
# This page intentionally left blank.
General information for all filers Civilian spouse of U.S. armed forces service member-If you are a civilian spouse
# Steps to completing your return
Step Action
1 of a U.S. armed forces service member, you must file a 2025 North Dakota individual income tax return if both of the following Determine if you have to file a return … current page 2 apply:
Complete your federal return … page 7 3
- You are required to file a 2025 federal individual income tax return.
Determine which form to use … page 6 Have you considered e-filing your return? … page 1 4
- You were a full-year resident of North Dakota for the 2025 tax year.
Go to the applicable instructions -You are treated as a resident for this If using Form ND-EZ … page 9 purpose if you elect under the federal If using Form ND-1 … page 11 5 Servicemembers Civil Relief Act to be a North Dakota resident for state tax Assemble your completed return … page 28 6 purposes.
For more information, see the Civilian Read "Before you file" … page 10 or 16 7
Spouses of Military Service Members
File your return on or before April 15, 2026 - income tax guideline.
Where to file … page 7
Need an extension? … page 7
# Who must file a return
Full-year resident
If you were a full-year resident of North Dakota for the 2025 tax year and you are required to file a 2025 federal individual income tax return, you must file a 2025 North Dakota individual income tax return. This applies even if you worked outside North Dakota (including employment overseas) during the tax year or have income from sources outside North Dakota. You were a full-year resident of North Dakota if you were a resident of North Dakota for the entire tax year or meet the statutory 7-month rulesee "Statutory 7-month rule" on this page.
Definition of resident-In these instructions, the term "resident" refers to an individual who is a legal resident of North Dakota. Legal residence (which is also called domicile) means the place that is your permanent home to which you always intend to return whenever absent from it. If you have more than one physical place of abode, only one of them may be your legal residence. Legal residence is based on your intent and your actions.
Statutory 7-month rule-Even though you were not a resident of North Dakota for any part of the tax year-that is, you were a fullyear nonresident-you must file as a full-year resident of North Dakota if you maintain a permanent place of abode in North Dakota and spend in the aggregate more than 210 days of the tax year in North Dakota. A permanent place of abode means a house, apartment, or other dwelling containing cooking and bathroom facilities that is suitable for year-round living and is maintained on a permanent or indefinite basis. This 7-month rule does not apply if you were (1) a partyear resident of North Dakota, (2) a full-year nonresident serving in the U.S. armed forces, or (3) a full-year resident of Montana or Minnesota covered by reciprocity.
Resident in U.S. armed forces-If you were a full-year resident of North Dakota serving in the U.S. armed forces during the 2025 tax year and you are required to file a 2025 federal individual income tax return, you must file a 2025 North Dakota individual income tax return as a full-year resident. This applies regardless of where you were stationed during 2025.
Full-year nonresident
If you were a full-year nonresident of North Dakota for the 2025 tax year, you must file a 2025 North Dakota individual income tax return if both of the following apply:
- You are required to file a 2025 federal individual income tax return.
- You derived gross income from North Dakota sources during the 2025 tax year. (See the box on page 5 for what is included in gross income from North Dakota sources.) You were a full-year nonresident if you were not a resident of North Dakota for any part of the tax year and do not meet the statutory 7-month rule-see "Statutory 7-month rule" on this page.
Nonresident in U.S. armed forces-If you were a full-year nonresident of North Dakota serving in the U.S. armed forces during the 2025 tax year and you are required to file a 2025 federal individual income tax return, you must file a 2025 North Dakota individual income tax return as a full-year nonresident if you have gross income from North Dakota sources other than your military compensation.
Civilian spouse of U.S. armed forces Minnesota or Montana resident-If you North Dakota between the United States and a foreign service member-If you are a civilian spouse were a full-year resident of Minnesota for the of a U.S. armed forces service member, you are not required to file a 2025 North Dakota individual income tax return if all of the following apply:
2025 tax year, you do not have to file a 2025 North Dakota individual income tax return if both of the following apply: country specifically exempts income from taxation by a U.S. state, income tax treaties between the U.S. and foreign countries do not apply for North Dakota income tax purposes. Therefore, you may have to pay
- Your only gross income from North Dakota North Dakota income tax on gross income
- Your service member spouse's permanent sources was compensation for personal or duty station is in North Dakota. professional services. from North Dakota sources even though the income is exempt from U.S. income tax because of a treaty. For more information, see
- Your only gross income from North Dakota sources was wages for work performed in
- You returned to your home in Minnesota the guideline Income Taxation of Nonresident at least once each month during the time North Dakota. you worked in North Dakota.
If you were a full-year resident of Montana Aliens under "Guidelines" at tax.nd.gov.
Disaster recovery tax exemptions-Exemptions from state and local tax filing and
- You resided in North Dakota only because you wanted to live with your service member spouse.
- Both you and your service member spouse were full-year nonresidents of North Dakota for the 2025 tax year.
You are treated as a nonresident for this purpose if you elect under the federal Servicemembers Civil Relief Act to be a resident of a state other than North Dakota for state tax purposes.
For more information, see the Civilian Spouses of Military Service Members income for the 2025 tax year, you do not have to file a 2025 North Dakota individual income tax return if your only gross income from North Dakota sources was wages.
See "Reciprocity" on page 6 for more information.
Nonresident alien-If you were a nonresident alien of the United States and received gross income from North Dakota sources during the 2025 tax year, you must file a 2025 North Dakota individual income payment obligations are available to out-ofstate businesses and their employees who are in North Dakota on a temporary basis for the sole purpose of repairing or replacing natural gas, electrical, or telecommunication transmission property that is damaged, or under threat of damage, from a state-or presidentially-declared disaster or emergency.
For more information, go to tax.nd.gov.
Part-year resident tax return. Except where an income tax treaty tax guideline.
If you were a part-year resident of North Dakota for the 2025 tax year, you must file a 2025 North Dakota individual income tax return if both of the following apply:
- You are required to file a 2025 federal Gross income from North Dakota sources for nonresidents only For a nonresident, "gross income from North Dakota sources" includes the following:
Exceptions
Gross income from North Dakota sources does not include these items received while a nonresident of North Dakota: military pay, interest, dividends, pensions, annuities, gain from the sale or exchange of intangible property, compensation exempted under reciprocity with Minnesota or Montana, compensation exempted under federal military and interstate commerce laws, or compensation exempted under North Dakota's mobile workforce exemption.
Note: Interest, dividends, gains, and other income from intangible property are included in gross income from North Dakota sources if derived from a trade or business carried on in North Dakota, such as a sole proprietorship, partnership, or S corporation. individual income tax return.
- You derived gross income from (1) any source inside or outside North Dakota while you were a resident of North Dakota or (2) a North Dakota source while you were a nonresident of North Dakota. (See the box on this page for what is included in gross income from North Dakota sources while a nonresident.) You were a part-year resident of North Dakota if you were a resident of North Dakota for only part of the year. This generally applies if you moved into or out of North Dakota and the move constituted a change in your legal residence. See "Definition of resident" on page 4.
# Native Americans
If you are a Native American, you are not subject to North Dakota income tax and do not have to file a North Dakota income tax return if all of the following apply:
- You are enrolled as a member of a federally-recognized Indian tribe.
- You lived on any Indian reservation in North Dakota.
- You derived all of your income from sources on any Indian reservation in North Dakota.
If any of the above criteria are not met, you may be subject to North Dakota income tax. For more information, see the guideline Income Taxation of Native Americans under "Guidelines" at tax.nd.gov.
# Which form to use
If you are required to file a 2025 North Dakota individual income tax return, see the box on this page to determine whether you should use Form ND-EZ or Form ND-1.
# Reciprocity
North Dakota has income tax reciprocity agreements with the states of Minnesota and Montana. If certain conditions in the agreements are met, compensation for services is taxable only by the state of residence.
# Minnesota and Montana residents
If you are a resident of Minnesota and maintain a permanent home in Minnesota to which you return at least once each month during the time you work in North Dakota, the compensation you receive for personal or professional services performed in North Dakota is not taxable by North Dakota.
If you are a resident of Montana, wages you receive for work performed in North Dakota are not taxable by North Dakota.
If you received wages covered by reciprocity, and your employer withheld North Dakota income tax of $5.00 or more from them, you must file a North Dakota individual income tax return at the end of the tax year to obtain a refund of the amount withheld. If this applies to you and you do not have any other gross income from North Dakota sources, complete Form ND-1 as follows:
Which form to use-Form ND-EZ or Form ND-1?
Use Form ND-EZ … if you answer No to ALL of the questions below.
Use Form ND-1 … if you answer Yes to ANY of the questions below.
Note: If you are filing a joint return with your spouse, check "Yes" if the answer is "Yes" for either you or your spouse.
Yes No
- Were you a nonresident of North Dakota at any time in 2025? …
- Do you have any North Dakota addition adjustments?
(*See Form ND-1, lines 2-3) …
- Do you have any North Dakota subtraction adjustments?
(*See Form ND-1, lines 5-16) …
- Are you claiming any North Dakota tax credits?
(*See Form ND-1, lines 21-23) …
- Did you pay, or were you required to pay, North Dakota estimated income tax for 2025, or did you apply an overpayment (refund) from your 2024 North Dakota return as an estimated payment for 2025? (*See Form ND-1, line 27) …
- Are you going to use the 3-year income averaging method for farm income (on Schedule ND-1FA) to calculate your tax? …
- Are you going to make an extension payment on Form ND-1EXT?
* The references show where to find more information.
- Complete the applicable items at the top If you received wages covered by reciprocity and your employer withheld Minnesota or of Form ND-1, page 1 (through line E), as Montana income tax from them, you must file instructed. an income tax return with the applicable state
- For item F, fill in the circle next to "MN/MT to obtain a refund of the amount withheld. If RECIPROCITY" at the top of Form ND-1, your wages are covered by reciprocity and page 1. Also enter "MN" or "MT", you do not want your employer to withhold whichever applies, in the space under Minnesota or Montana tax from them, "State." you must give your employer a properly
- Leave lines 1 through 25 blank. completed Minnesota Form MW-R or Montana Form MT-R, whichever applies.
- Fill in the amount of the North Dakota For assistance and forms, contact: income tax withheld on lines 26, 28, 29,
North Dakota income tax from them, you must Email: obtain and complete Form NDW-R and give it DORCustomerAssistance@mt.gov to your employer.
Phone: 406-444-6900
Website: mtrevenue.gov
# North Dakota residents
If you are a resident of North Dakota and maintain a permanent home in North Dakota to which you return at least once each month during the time you work in Minnesota, the compensation that you receive for personal or professional services performed in Minnesota is not taxable by Minnesota. Also, wages you receive for work performed in Montana while a resident of North Dakota are not taxable by Montana.
# When and where to file
If you are filing on a calendar year basis, you must file your 2025 North Dakota individual income tax return on or before April 15, 2026.
If you are filing on a fiscal year basis, you must file on or before the 15th day of the fourth month following the close of your fiscal tax year. If the due date falls on a Saturday, Sunday or holiday, you have until the next day that is not a Saturday, Sunday, or holiday to file your return.
Mail your return to:
Office of State Tax Commissioner
P.O. Box 5621
Bismarck, ND 58506-5621
# Extension of time to file
You may obtain an extension of time to file your North Dakota individual income tax return by obtaining either a federal extension or a North Dakota extension.
# Federal extension
If you obtain an extension of time to file your federal return, it will be recognized for North Dakota individual income tax purposes.
This includes the automatic extension allowed for being outside the U.S. and Puerto Rico on April 15. You do not have to file a separate state extension form or notify the Office of State Tax Commissioner that you have obtained a federal extension prior to filing your North Dakota return. Fill in the circle next to "Extension" at the top of Form ND-EZ or Form ND-1, whichever applies.
# North Dakota extension
If you do not obtain a federal extension, but need additional time to file your North Dakota return, you may apply for a North Dakota extension by completing and filing Form 101.
This is not an automatic extension-you must have good cause to request a North Dakota extension. Form 101 must be postmarked on or before the due date of your return.
You will be notified whether your extension request is approved or rejected. If approved, fill in the circle next to "Extension" at the top of Form ND-EZ or Form ND-1, whichever applies.
# Extension interest
If you obtain an extension and file your North Dakota return on or before the extended due date, and you pay any tax balance due with the return, no penalty will be charged. Interest on any tax due on the return will be charged at the rate of 12% per year from the original due date of your return to the earlier of the date you file your return or the extended due date.
# Prepayment of tax due
If you are applying for an extension of time to file, you may prepay the tax that you expect to owe to avoid paying extension interest. For payment options, go to tax.nd.gov and select "Make A Payment." If submitting a payment by paper check or money order, you must complete and submit a 2025 Form ND-1EXT payment voucher with the payment.
Alternatively, you may submit a paper check or money order along with a letter containing the following:
- Your name.
- Your social security number.
- Your address and phone number.
- Statement that you are making a
2025 Form ND-1EXT payment.
If you prepay your tax, you must file Form ND-1 and claim the payment on page 2, line 27; you may not file Form ND-EZ.
# Penalty and interest
If you obtain an extension of time to file your return, you may pay the tax due by the extended due date of the return without penalty, but extension interest will apply-see "Extension interest" and "Prepayment of tax due" on this page.
If you file your return by its due date (or extended due date), but you do not pay all of the tax due on it by the return's due date (or extended due date), a penalty equal to 5% of the unpaid tax due or $5.00, whichever is greater, must be paid.
If you file your return after its due date (or extended due date), and there is an unpaid tax due on it, a penalty equal to 5% of the unpaid tax due or $5.00, whichever is greater, applies for the month the return was due, with an additional 5% of the unpaid tax due for each month (or fraction of a month) the return remains delinquent, not to exceed 25% of the tax due.
# North Dakota
In addition to any penalty, interest must be paid at the rate of 1% per month or fraction of a month, except for the month in which the tax was due, on any tax due that remains unpaid after the return's due date (or extended due date).
# Federal income tax return
You must complete your 2025 federal individual income tax return (Form 1040 or 1040-SR) before you complete your 2025 North Dakota individual income tax return.
Certain information from your federal return is needed to complete your North Dakota return.
If you are filing your North Dakota return on paper, you must attach a complete copy of your federal income tax return to your North Dakota return. A complete copy consists of Form 1040 or 1040-SR and all supplemental forms and schedules. You do not have to include depreciation schedules or any other statements that you may have prepared as supporting documentation to your federal return.
# Changing your return
If you need to change your North Dakota return after you file it, you must file an amended return. There is no special form for this purpose. See "How to prepare an amended return" on page 8.
If you paid too much tax because of an error in your return, you generally have three years after you file your original return to file an amended return to correct the error and claim a refund of the overpayment. For other time periods that may apply, see North Dakota Century Code § 57-38-40 or contact the Office of State Tax Commissioner.
Penalty and interest apply to additional tax due on an amended return.
# Change to federal return
By law, you must file an amended North Dakota return to report changes made to your federal return. This applies whether the changes are attributable to your filing of an amended federal return or an audit or correction by the IRS. The amended North Dakota return must be filed within 90 days after filing the amended federal return or within 90 days after the final determination of the IRS changes.
# How to prepare an amended return
- Obtain a blank Form ND-1 for the tax year affected by the changes.
- Enter your name, current address, social security number, and other information required at top of return.
- Fill in the circle next to "Amended return:
General" or "Amended return: Federal NOL," whichever applies, in the top righthand corner of the return. See "Amended return" on page 11 for more information.
- Complete the return through the net tax liability line.
- Leave the line for income tax withholding blank unless you are claiming an additional amount not previously claimed.
- On the "Total payments" line, enter the net tax liability shown on your original return or previously filed amended return. If the net tax liability has not been fully paid at the time the amended return is filed, only enter the amount of tax that has been paid.
- Complete the remaining portion of the return according to the instructions. On an amended return, you may not adjust the amount of any voluntary contribution, nor the amount of an overpayment applied to the next year's estimated tax.
- Attach a statement explaining why you are changing your return. If you are doing so because of changes you or the IRS made to your federal return, attach a copy of the amended federal return or IRS notice. If amending to claim a net operating loss carryback, attach Form 1045 or 1040X.
- Write "State Only Amended" at the top of Form ND-1 if filing a paper return.
(for 2026)
You must pay estimated North Dakota income tax for the 2026 tax year if all of the following conditions apply:
- You are required to pay estimated federal income tax for 2026.
- Your North Dakota net tax liability for 2025 is $1,000 or more. (If you are not required to file a North Dakota return for 2025, you do not have to pay estimated tax for 2026.)
- You expect to owe (after subtracting any estimated North Dakota income tax withholding) at least $1,000 in North Dakota income tax for 2025.
- You expect your North Dakota income tax withholding for 2026 to be less than the smaller of the following:
(a) 90% of your 2026 North Dakota net tax liability. Note: Substitute 66 2/3% if a qualified farmer-see instructions for 2026 Form ND-1ES.
(b) 100% of your 2025 North Dakota net tax liability. If you moved into North Dakota during 2025 and had no income from North Dakota prior to the move, this 100% threshold does not apply; you must satisfy the 90% threshold in part (a).
In general, one-fourth (25%) of the total estimated tax required to be paid for the 2026 tax year must be paid by April 15, June 15, and September 15, 2026, and January 15, 2027.
For payment options, go to tax.nd.gov and select "Make A Payment." If submitting a payment by paper check or money order, you must complete and submit a 2026 Form ND-1ES payment voucher with the payment.
How to file a return for a deceased taxpayer If a final federal income tax return is required to be filed for a decedent for the year of death, a final North Dakota income tax return also must be filed. A court-appointed personal representative is responsible for filing the decedent's final return, even if there is a surviving spouse. The information from the final federal return is used to complete the final North Dakota return, and the North Dakota return is to be signed in the same manner as required for federal income tax purposes. If there is a personal representative and no surviving spouse, a copy of the court document showing the appointment must be attached to the final return. If there is a surviving spouse and the final return will be filed on a joint basis, a refund will be mailed in both spouses' names.
If there is no surviving spouse and no personal representative has been appointed for the decedent, attach a copy of the death certificate and a copy of one of the following:
- Letter of Testamentary.
- Letter of Administration.
- Affidavit for Collection of Personal Property of Decedent.
For assistance, see back cover of booklet.
Fill in the circle for "Deceased" and enter the date of death next to the deceased taxpayer's name on Form ND-EZ or Form ND-1, whichever applies.
# Disclosure notification
Upon written request from the chairman of a North Dakota legislative standing committee or Legislative Management, the law requires the Office of State Tax Commissioner to disclose the amount of any deduction or credit claimed on a tax return. Any other confidential information, such as a taxpayer's name or social security number, may not be disclosed.
# North Dakota
2025 Form ND-EZ Instructions
Before you begin . . .
- Are you eligible to use Form ND-EZ? See "Which form to use" on page 6.
- Be sure to have a copy of your completed 2025 federal income tax return (Form 1040 or 1040-SR) at hand. You will need information from it to complete Form ND-EZ.
Note: A complete copy of your federal return must be filed with your state return.
# Name and address
Enter your full name and current address.
If you are married and filing a joint return, include your spouse's full name. If the taxpayer died during the 2025 tax year, fill in the circle for "Deceased" and enter the date of death.
# Form ND-EZ
Line 1b - Federal taxable income On Form 1040 or 1040-SR line 15, you are instructed to enter "-0-" for your federal taxable income if it calculates out to be less than zero. However, for purposes of completing Form ND-EZ, enter the negative number on line 1b. Enter a minus sign (-) to the left of the number. taxes withheld from mineral interest income, such as an oil or gas royalty, because they are not income taxes. Include a copy of the Form W-2, Form 1099, or North Dakota Schedule K-1.
Line 5 - Voluntary contribution of overpayment If you have an overpayment on line 4, you may make a voluntary contribution of part or all of it to any of the three funds on this line. Enter the amount you wish to contribute on the line to the right of the fund name. If contributing, you must contribute at least $1.00 to the fund. A contribution will reduce your refund.
Line 6 - Direct deposit of refund If you want us to deposit your refund directly into your bank account, complete items a, b, and c below line 6. Check with your financial institution to see if it will accept direct deposit and to obtain the correct routing and account numbers.
Routing number (Item b)-Enter the 9-digit routing number. The first two digits must be within the range of 01 through 12 or 21 through 32.
Account number (Item c)-Enter the account number. It may have up to 17 digits (both letters and numbers). Include hyphens, but omit special symbols.
If depositing into a checking account, see the sample check on page 10 for where to
Code
Source number of income
Farming, ranching, or agricultural production … 1 Retail, wholesale trade, and eating and drinking places … 2 Federal, state, county, or city government service … 3 Public or private education … 4 Accounting, legal, health, motel, and other personal or professional services not classified elsewhere … 5 Line 3 - Withholding Enter the North Dakota income tax withheld shown on a 2025 Form W-2, Form 1099, or North Dakota Schedule K-1. Also enter North Dakota income tax withheld shown on a 2024 North Dakota Schedule K-1 if the tax year of the partnership, S corporation, estate, or trust shown on the Schedule K-1 is a fiscal year ending in your 2025 tax year. Be sure the state identified on the Form W-2 or Form 1099 is North Dakota. Do not enter on this line North Dakota extraction or production find the routing and account numbers. If depositing into a savings account without a check writing feature, ask your financial institution for the correct account number to use.
Disclosure authorization. Fill in the circle
# Sample check for direct deposit (line 6)
Please note:
- Do not use the number on a deposit slip for the routing or account number.
- You will not receive notification of when the deposit is made by our office. Contact your bank or check your bank statement to verify the deposit.
- If the routing or account number is incorrect, or if your financial institution does not accept the direct deposit, a paper check will be issued.
- Due to electronic banking rules, the Office of State Tax Commissioner will not allow a direct deposit to or through a foreign financial institution. In this case, a paper check will be issued.
Line 8 - Voluntary contribution
If you have a tax due on line 7, you may make a voluntary contribution to any of the three funds on this line. Enter the amount you wish to contribute on the line to the right of the fund name. If contributing, you must contribute at least $1.00 to a fund. A contribution will increase your balance due.
Line 9 - Balance due
The balance due must be paid in full with your return. You may pay the balance due online with an electronic check or a debit or credit card. To pay online, go to tax.nd.gov and select "Make A Payment."
If you are filing a paper return and paying the balance due with a paper check or money order, complete a 2025 Form ND-1PRV payment voucher and enclose it with the payment.
However, if you are filing your return electronically, complete and submit a 2025 Form ND-1V with the paper check or money order. Make check or money order payable to "ND State Tax Commissioner," and write the last four digits of your social security number and "2025 Form ND-EZ" on your check or money order. A check must be drawn on a U.S. or Canadian bank, be in U.S. dollars, and use a standard 9-digit routing number. A check drawn on a foreign bank (except one in Canada) cannot be accepted.
# Signatures
Sign and date your return. If a joint return, both spouses must sign.
Form 1099-G consent and disclosure authorization At the bottom of Form ND-EZ (below line 9), fill in the applicable circle(s) to indicate if you want either or both of the following items to apply.
Form 1099-G consent. If there is an overpayment on your 2025 Form ND-EZ, line 4, federal tax law requires our office to file with the IRS and mail to you a Form 1099-G showing the overpayment amount. You may need this information when preparing your 2026 federal income tax return. Fill in the circle for this item if you want to obtain Form 1099-G electronically from our website instead of receiving it by mail. The 2026 Form 1099-G will be available on our website in January 2027. For more information, go to our website at tax.nd.gov. for this item if you want to authorize our office to communicate directly with your tax return preparer about your 2025 return. This may include requesting information needed to process the return and responding to inquiries from your preparer about correction notices you receive from us. The authorization does not allow your preparer to receive your refund check, to bind you in any way, or to legally represent you. The authorization only applies to the individual whose printed name and signature appear in the preparer's signature area, and it automatically expires on the due date (including extensions) for filing your 2026 return.
Before you file, did you-
Sign your return?
An unsigned return is incomplete.
Include a complete copy of your federal return?
Return is incomplete without it.
Write your social security number on return?
We use this number to identify your return.
Check your math?
Most common error made.
Include all Form W-2s?
Also include a copy of a 1099 or Schedule K-1 showing North Dakota withholding.
Use the correct postage?
Avoid mailing problems by using the correct postage.
Important! If your return is missing your signature or a copy of your federal return, it will be sent back to you. This may result in late filing and payment charges if you resubmit it after the due date.
For worry-free filing, file your return electronically-see page 1!
# North Dakota
2025 Form ND-1 Instructions
Before you begin . . .
- Be sure to have a copy of your completed 2025 federal income tax return (Form 1040 or 1040-SR) at hand. You will need information from it to complete Form ND-1.
Note: A complete copy of your federal return must be filed with your state return.
Nonresident of North Dakota for part or all of the 2025 tax year If you were a nonresident of North Dakota for part or all of the 2025 tax year, first complete Form ND-1 through line 19. Then complete Schedule ND-1NR to calculate the amount of your tax. On Schedule ND-1NR, you will indicate whether you were a nonresident for part or all of the tax year by filling in your residency information at the top of the schedule.
If you are married and filing a joint return, and either you or your spouse was a nonresident of North Dakota for part or all of the tax year, you must complete Schedule ND-1NR on a joint basis and attach it to Form ND-1.
On Schedule ND-1NR, each of you must indicate your residency status by filing in your residency information at the top of the schedule.
# Fiscal year filer only
If you are filing your 2025 federal income tax return (Form 1040 or 1040-SR) on a fiscal year basis, you must file your 2025 North Dakota income tax return for the same fiscal year. Enter in the spaces provided at the top of Form ND-1 the ending date of your fiscal tax year.
# Name and address
Enter your full name and current address.
If you are married and filing a joint return, include your spouse's full name. If the taxpayer died during the 2025 tax year, fill in the circle for "Deceased" and enter the date of death.
# Social security numbers
Enter your social security number (and your spouse's social security number, if married filing jointly).
Item A - Filing status
Fill in the circle next to the filing status that you used on your 2025 Form 1040 or 1040-SR.
Item B - School district code
Select the code number from the list of school district codes on page 19.
Item C - Income source code
Select from the following list the code number corresponding to the area from which you derived the majority of your North Dakota sourced income for the tax year.
Source Code number of income
Farming, ranching, or agricultural production … 1 Retail, wholesale trade, and eating and drinking places … 2 Federal, state, county, or city government service … 3 Public or private education … 4 Accounting, legal, health, motel, and other personal or professional services not classified elsewhere … 5 Construction … 6 Manufacturing … 7 Transportation, communication, and public utilities … 8 Exploration, development, and extraction of coal, oil, and natural gas … 9 Banking, insurance, real estate, and other financial services … 10 Military service … 11 Retirement (Pensions, annuities, IRAs, etc.) … 12 Item D - Amended return If you are filing this return to change a return you previously filed for the 2025 tax year, fill in the circle next to:
- Amended return: General- If you are changing the return for any reason other than a federal net operating loss carryback.
- Amended return: Federal NOL- If you are changing the return because of a federal net operating loss carryback.
See "Changing your return" on page 7 for more information.
Item E - Extension
Fill in the circle next to "Extension" only if you have an extension to file your North Dakota return. See "Extension of time to file" on page 7.
Item F - MN/MT reciprocity
Fill in the circle next to "MN/MT Reciprocity" only if you are a Minnesota or Montana resident who is filing this return solely to claim a refund of North Dakota income tax because of reciprocity. See page 6 for details.
Instructions for lines 1-37 of
Line 1b - Federal taxable income On Form 1040 or 1040-SR, line 15, you are instructed to enter "0" for your federal taxable income if it calculates out to be less than zero. However, for purposes of completing Form ND-1, enter the negative number on line 1b. Enter a minus sign (-) to the left of the number.
Line 2 - Contribution adjustment Enter on this line the amount, if any, from Schedule ND-1PG, line 15, or Schedule ND-1QEC, line 16.
However, if you are claiming a credit on both Schedule ND-1PG, line 7, and Schedule ND-1QEC, line 5, or you are claiming an endowment credit from a North Dakota Schedule K-1, obtain and complete the Contribution Adjustment Worksheet to calculate the amount to enter on this line. The worksheet is available online at tax.nd.gov. Include a copy of the worksheet.
If you claimed the standard deduction on your 2025 Form 1040 or 1040-SR, line 12, you do not have to make an adjustment on this line unless you are claiming a credit on Schedule ND-1QEC based on a contribution you made from an individual retirement account under I.R.C. § 408(d). See the instructions to Schedule ND-1QEC, line 13.
If you are only claiming an unused planned gift or endowment credit carried over from a prior tax year, and none of the contribution on which it is based was carried over and deducted on your 2025 Form 1040 or 1040-SR, no adjustment is required on this line.
Line 5 - U.S. obligation interest Enter the following on this line:
- Interest income from U.S. obligations.
- Interest income from other securities that Do not enter on this line interest income from securities of the Federal Home Loan Mortgage Corporation (Freddie Mac), Federal National Mortgage Association (Fannie Mae), and Government National Mortgage Association (Ginnie Mae), nor from a federal income tax refund or repurchase agreement.
Line 6 - Net long-term capital gain exclusion If your federal taxable income includes a net long-term capital gain (including a capital gain distribution from a mutual fund), you may be able to exclude 40 percent of the gain from your North Dakota taxable income. If you were a full-year nonresident or a partyear resident of North Dakota for the year, only a net long-term capital gain reportable to North Dakota is eligible for the exclusion.
A net long-term capital gain included in an amount entered on line 7, or 16 of Form ND-1 is not eligible for the exclusion.
Complete the worksheet on page 13 to calculate the amount to enter on this line.
Line 7 - Native American's exempt income If you are an enrolled member of a federallyrecognized Indian tribe who lived on any Indian reservation in North Dakota for all of 2025, enter on this line income you derived from sources on any Indian reservation in North Dakota. This includes the portion of the Standing Rock and Lake Traverse Indian Reservations situated in South Dakota.
Line 9 - Licensed peace officer retirement benefits exclusion Certain retirement benefits of a licensed peace officer are excludable from North Dakota taxable income. The exclusion is allowable for a retired licensed peace officer with a minimum of 20 years of service or that was retired disabled. If allowable, enter on this line the amount of taxable retirement benefits included in federal taxable income on Form 1040 or Form 1040-SR, line 5b. Only include benefits issued by your employer's retirement plan, generally found on Form 1099-R, box 2a. Attach Form 1099-R to your return.
For the first tax year claiming this exclusion, also provide the following with your return:
- If having at least 20 years of licensed status in North Dakota:
O Attach page 1 of your Peace Officer Standards and Training (POST) board training profile document.
A copy may be obtained from the
POST board.
- If meeting 20 years of licensed status attributable to service other states:
O Attach documentation from each official licensing board or jurisdiction to reflect the years or term of licensed service, totaling at least 20 years.
- For retired disabled:
O Attach the documentation from the employer's plan or medical is specifically exempted from state income tax by federal statute.
- The portion of dividend income from a mutual fund attributable to investment in U.S. obligations and other securities the interest from which is exempted from state income tax by federal statute.
Common sources of interest income that may be entered on this line include:
Do not enter income derived from nonreservation sources in North Dakota. If you lived in North Dakota in 2025, but you did not reside on an Indian reservation for part or all of 2025, do not enter income earned or received while living off the reservation.
Line 8 - U.S. Railroad Retirement
# Board benefits
Enter on this line the portion of any documentation to substantiate the individual became medically or physically disabled while employed as a licensed peace officer and unable to discharge the person's duties.
For additional information, please see Guideline - Income Tax: Licensed Peace Officer Retirement Exclusion on our website.
- U.S. savings bonds and Treasury bills and notes.
- Securities issued by: Banks for cooperatives Commodity Credit Corporation Federal Deposit Insurance Corporation Federal Farm Credit System Federal Home Loan Banks Federal Intermediate Credit Banks Federal Land Banks Federal Savings & Loan Insurance Corporations Student Loan Marketing Association unemployment, sick pay, or retirement benefits received from the U.S. Railroad Retirement Board that are taxable on your federal income tax return. The U.S. Railroad Retirement Board will be shown as the payer or employer on the Form 1099-G (unemployment), Form W-2 (sick pay), or Forms RRB-1099 and RRB-1099-R (retirement) issued to you.
Line 10 - Servicemember Civil
# Relief Act adjustment
If you were a full-year nonresident of North Dakota for the tax year, enter on this line compensation received for active duty in the U.S. armed forces or the commissioned corps of the Public Health Service or National Oceanic and Atmospheric Administration. If a part-year resident, only enter the amount received for service while a nonresident of North Dakota. Include a copy of Form W-2 showing the military pay.
Line 11 - Military pay exclusion Enter on this line the military pay you received as a member of the U.S. armed forces on active and reserve duty and a member of the national guard. The deduction is allowed to the extent the military pay is included in federal taxable income. Military pay for purposes of this deduction is all military pay, including federal pay for training, education, mobilization, and bonuses and state pay when called to state active duty. Include a copy of Form W-2 showing the military pay.
If you included wages as a Dual Status
Technician on line 11, include a copy of
Standard Form 50 (SF-50), Notification of
Personnel Action.
If you included income on line 10 for federal active duty pay under the Servicemember Civil Relief Act, do not include that income on line 11.
# Line 12 - ND College SAVE contribution deduction
If you made a contribution during the tax year to a North Dakota College SAVE account administered by the Bank of North Dakota, you are allowed a deduction for the contribution, up to a maximum of $5,000 ($10,000, if married filing jointly). You are allowed the deduction regardless of whether you or someone else owns the account. A
# North Dakota
Air Force, Marine Corps, and Coast Guard. rollover of funds from another I.R.C. § 529 Retirement benefits received for federal civil college savings plan into a North Dakota service employment as a dual status military College SAVE account does not qualify. technician under Title 32 or Title 10 are also eligible for this deduction. Include a copy of
# Line 13 - Qualified dividend
Form 1099-R. exclusion
If you were a full-year resident of North
# Line 15 - Social security benefit
Dakota during the tax year, multiply the exclusion qualified dividends from Form 1040 or Enter on this line the taxable portion of 1040-SR, line 3a, by 40 percent and enter the your Social Security benefit`s reported on result.
Form 1040 or 1040-SR, line 6b.
If you were a part-year resident or full-year Do not enter on this line taxable Tier 1 Social nonresident of North Dakota during the tax Security equivalent benefits reported on year, multiply the portion of the qualified a Form RRB-1099 from the U.S. Railroad dividends from Form 1040 or 1040-SR, Retirement Board; instead, enter the taxable line 3a, that are reported to North Dakota by portion of these benefits on Form ND-1, line 40% and enter the result.
8.
Note: Only include dividends that are If you receive both Tier 1 benefits reported on Schedule ND-1NR, line 2, (Form RRB-1099) and social security benefits column B.
(Form SSA-1099) determine the amount to enter on Form ND-1, lines 8 and 15, Line 14 - Military retirement benefit respectively, by multiplying the amount from exclusion Form 1040 or 1040-SR, line 6b, by a ratio equal to the gross amount of each type of If you are a retired military service member, benefit divided by the gross amount of both or a surviving spouse of a deceased retired benefits combined. military service member, enter on this line the amount of taxable military retirement benefits that you reported on Form 1040 or Form 1040-SR, line 5b. Include benefits received as a retired member of the U.S. armed forces or its reserve components, Army National Guard, or Air Force National Guard.
"U.S. armed forces" means the Army, Navy, Worksheet For Net Long-Term Capital Gain Exclusion (Form ND-1, Line 6) Capital gain distribution - If you reported capital gain distributions on Form 1040 or 1040-SR, line 7 (and you did not have to complete Schedule D), skip lines 1 and 2 and enter the distributions on line 3 of this worksheet.
- Enter amount from 2025 Schedule D (Form 1040), line 15. If zero or less, stop here; no exclusion is allowed … 1 __
- Enter amount from 2025 Schedule D (Form 1040), line 16. If zero or less, stop here; no exclusion is allowed … 2 __
- Enter the smaller of line 1 or line 2 … 3 __
- If a full-year resident, enter the amount from line 3 on line 5 and go to line 6.
- If a full-year nonresident or part-year resident, go to line 4.
- Complete lines 4a through 4d using only the capital gains and losses reportable to North Dakota: a. North Dakota net short-term capital gain (loss) … 4a _ b. North Dakota net long-term capital gain (loss) … 4b c. Combine lines 4a and 4b. If zero or less, enter -0- … 4c d. Enter the smaller of line 4b or line 4c … 4d _
- If a full-year resident, enter amount from line 3. Otherwise, enter smaller of line 3 or line 4d … 5 __
- Portion of line 5 included in an amount entered on Form ND-1, line 7, or 16 … 6 __
- Subtract line 6 from line 5 … 7 __
- Multiply line 7 by 40% (.40). Enter this amount on Form ND-1, line 6 … 8 __
Line 16 - Other additions/ subtractions See the instructions to Schedule ND-1SA for information about the following:
- Lump sum distribution from Federal
- Loss from S corporation taxed as C corporation
- Renaissance zone income exemption
- New or expanding business income exemption
- Human organ donor deduction
- Employee workforce recruitment exclusion
- Stillborn child deduction
- College expense reimbursement deduction
- Income from S corporation taxed as C corporation Enter on this line the total subtractions from Schedule ND-1SA.
Include Schedule ND-1SA.
Line 20 - Tax
If you were a full-year resident for the tax year, use the Tax Table on page 20 to calculate your tax. This also applies if you are married filing jointly and both you and your spouse were full-year residents for the tax year.
If you were a full-year nonresident or a part-year resident for the tax year, you must complete Schedule ND-1NR to calculate your tax. This also applies if you are married filing jointly and either you or your spouse was a nonresident for part or all of the tax year.
Include Schedule ND-1NR.
Farm income averaging - If you have farm income and used Schedule J (Form 1040) to calculate your federal income tax for 2025, you may be able to lower your North Dakota income tax by completing Schedule ND-1FA.
Include Schedule ND-1FA.
Sale of tax credit - If you received any proceeds from the sale of a North Dakota research expense tax credit to another taxpayer, you must obtain and complete Schedule ND-1CS to calculate your tax.
Include Schedule ND-1CS.
Line 21 - Credit for income tax paid to another state If you were a full-year resident or part-year resident of North Dakota who paid income tax to another state or local jurisdiction in that state, you may be eligible for an income tax credit. Obtain Schedule ND-1CR for more information. Include Schedule ND-1CR.
Marriage Penalty Credit Worksheet
Complete this worksheet to determine the amount to enter on Form ND-1, line 22.
- Is your filing status Married filing jointly? No. Stop; you do not qualify for the credit. Yes. Enter your taxable income from Form ND-1, line 18 … 1
- Is the amount on line 1 more than $81,036? No. Stop; you do not qualify for the credit. Yes. Go to line 3.
- a. Enter your qualified income … 3a _ b. Enter your spouse's qualified income … 3b _
- Enter the smaller of line 3a or line 3b … 4 __
- Is the amount on line 4 more than $47,550? No. Stop; you do not qualify for the credit.
15,750.00
Yes. Go to line 6 … 5
- Subtract line 5 from line 4 … 6 __
- Calculate the tax on the amount on line 6 using the Single tax rate schedule on page 27 … 7 __
- Subtract line 6 from line 1 … 8 __
- Calculate the tax on the amount on line 8 using the Single tax rate schedule on page 27 … 9 __
- Calculate the tax on the amount on line 1 using the Married filing jointly tax rate schedule on page 27 … 10 __
- Add lines 7 and 9 … 11 __
- Subtract line 11 from line 10. If result is zero or less, stop; you do not qualify for the credit … 12 __ 312.00
- Maximum credit … 13 __
- Enter smaller of line 12 or line 13 … 14 __ If you and your spouse are full-year residents, enter amount from line 14 on Form ND-1, line 22. Do not complete lines 15 and 16. If you completed Schedule ND-1NR, complete lines 15 and 16.
- Enter ratio from Schedule ND-1NR, line 20 … 15 __
You may be eligible for a tax credit if all of the following apply:
Although you meet all of the above conditions, your fact situation may not produce a credit
- You are married and filing a joint return under the calculation formula prescribed by with your spouse. law. Complete the worksheet on page 14 to
- Your joint North Dakota taxable income calculate the credit amount, if any, allowed to on line 18 of Form ND-1 is more than you.
$81,036.
- Both you and your spouse have qualified income. See "What's included in qualified income?" below.
# North Dakota
Sample check for direct deposit (line 32) Calculate qualified income for lines 3a and 3b of the worksheet by adding the following amounts separately for you and your spouse:
- Wages, salaries, tips, etc. reported on Form 1040 or 1040-SR, line 1z.
- Net self-employment income reported on Schedule SE (Form 1040 or 1040-SR), line 3, reduced by the self-employment tax deduction reported on Form 1040 or 1040-SR, Schedule 1, line 15.
- Taxable portion of IRAs, pensions, annuities, and social security benefits reported on Form 1040 or 1040-SR, lines 4b, 5b, and 6b. Reduce this total by amounts entered on Form ND-1, lines 8 and 15.
Line 23 - Other credits
For other credits that may apply to you, see Schedule ND-1TC and its instructions. Enter on this line the total credits from Schedule ND-1TC. Include Schedule ND-1TC.
Line 26 - Withholding
Enter the North Dakota income tax withholding shown on a 2025 Form W-2, Form 1099, or North Dakota Schedule K-1.
Also enter North Dakota income tax withholding shown on a 2024 North Dakota Schedule K-1 if the tax year of the partnership, S corporation, estate, or trust shown on the Schedule K-1 is a fiscal year ending in your 2025 tax year.
Be sure the state identified on the Form W-2 or Form 1099 is North Dakota. Do not enter on this line North Dakota extraction or production taxes withheld from mineral interest income, such as an oil or gas royalty, because they are not income taxes. Include a copy of the Form W-2, Form 1099, or North Dakota Schedule K-1.
Line 27 - Estimated tax payment
Enter on this line any estimated income tax payments made on a 2025 Form ND-1ES or Form ND-1EXT. Also enter the amount of an overpayment on your 2024 North Dakota income tax return that you elected to leave on deposit as an estimated payment for 2025.
Do not enter on this line North Dakota income tax withheld from a Form W-2, Form 1099, or North Dakota Schedule K-1; enter withheld tax on line 26.
Line 30 - Application of overpayment to 2026 If you have an overpayment on line 29, you may elect to apply part or all of it as an estimated payment toward your 2026 income tax liability. Once made, the election or the amount cannot be changed after you file your return.
Line 31 - Voluntary contribution of overpayment If you have an overpayment on line 29, you may make a voluntary contribution of part or all of it to any of the three funds on this line. Enter the amount you wish to contribute on the line to the right of the fund name. If contributing, you must contribute at least $1.00. A contribution will reduce your refund.
Line 32 - Direct deposit of refund If you want us to deposit your refund directly into your bank account, complete items a, b, and c below line 32. Check with your financial institution to see if it will accept direct deposit and to obtain the correct routing and account numbers.
Routing number (Item b)-Enter the 9-digit routing number. The first two digits must be within the range of 01 through 12 or 21 through 32.
Account number (Item c)-Enter the account number. It may have up to 17 digits (both letters and numbers). Include hyphens, but omit special symbols.
If depositing into a checking account, see the sample check on this page for where to find the routing and account numbers. If depositing into a savings account without a check writing feature, ask your financial institution for the correct account number to use.
Please note:
- Do not use the number on a deposit slip for the routing or account number.
- You will not receive notification of when the deposit is made by our office. Contact your bank or check your bank statement to verify the deposit.
- If the routing or account number is incorrect, or if your bank does not accept the direct deposit, a paper check will be issued.
- Due to changes in the electronic banking rules, the Office of State Tax Commissioner will not allow a direct deposit to or through a foreign financial institution. In this case, a paper check will be issued.
Line 34 - Penalty and interest
Our office will notify you of any penalty and interest owed for late filing or late payment, or interest owed on tax due during an extension period. However, you may calculate the amount of penalty, interest, or both, that you owe and pay it with your return. See "Penalty and interest" on page 7 for how to calculate penalty and interest.
Line 35 - Voluntary contribution If you have a tax due on line 33, you may make a voluntary contribution to any of the three funds on this line. Enter the amount you wish to contribute on the line to the right of the fund name. If contributing, you must contribute at least $1.00 to a fund. A contribution will increase your balance due.
Line 36 - Balance due
The balance due must be paid in full with your return. You may pay the balance due online with an electronic check or a debit or credit card. To pay online, go to tax.nd.gov and select "Make A Payment."
If you are filing a paper return and paying the balance due with a paper check or money order, complete a 2025 Form ND-1PRV payment voucher and enclose it with the payment.
However, if you are filing your return electronically, complete and submit a 2025 Form ND-1V with the paper check or money order. Make check or money order payable to "ND State Tax Commissioner," and write the last four digits of your social security number and "2025 Form ND-1" on your check or money order. A check must be drawn on a U.S. or Canadian bank, be in U.S. dollars, and use a standard 9-digit routing number. A check drawn on a foreign bank (except one in Canada) cannot be accepted.
Line 37 - Interest on underpaid estimated tax If you were required to pay estimated North Dakota income tax for 2025, but you did not pay enough or you paid it late, interest is charged on the underpayment or late payment. To determine if you owe interest, obtain and complete the 2025 Schedule ND-1UT.
# Signatures
Sign and date your return. If you are filing a joint return, both spouses must sign.
Form 1099-G consent and disclosure authorization At the bottom of Form ND-1, page 2 (below line 37), fill in the applicable circle(s) to indicate if you want either or both of the following items to apply.
Form 1099-G consent. If there is an overpayment on your 2025 Form ND-1, line 29, federal tax law requires our office to file with the IRS and mail to you a Form 1099-G showing the overpayment amount. You may need this information when preparing your 2026 federal income tax return. Fill in the circle for this item if you want to obtain Form 1099-G electronically from our website instead of receiving it by mail. The 2026 Form 1099-G will be available on our website in January 2027. For more information, go to our website at tax.nd.gov.
Disclosure authorization. Fill in the circle for this item if you want to authorize our office to communicate directly with your tax return preparer about your 2025 return. This may include requesting information needed to process the return and responding to inquiries from your preparer about correction notices you receive from us. The authorization does not allow your preparer to receive your refund check, to bind you in any way, or to legally represent you. The authorization only applies to the individual whose printed name and signature appear in the preparer's signature area, and it automatically expires on the due date (including extensions) for filing your 2026 return.
Before you file, did you-
Sign your return?
An unsigned return is incomplete.
Include a complete copy of your federal return?
Return is incomplete without it.
Write your social security number on return?
We use this number to identify your return.
Check your math?
This is one of the most common errors made.
Include all Form W-2s?
Also include a copy of a 1099 or Schedule K-1 showing North Dakota withholding.
Use the correct postage?
Avoid mailing problems by using the correct postage.
Important! If your return is missing your signature or a copy of your federal return, it will be sent back to you. This may result in late filing and payment charges if you resubmit it after the due date.
For worry-free filing, file your return electronically-see page 1!
Trees for North Dakota
Income Tax Check-Off
Each of us has the ability to play an important Each of us has the ability to play an role in the overall health and well-being of important role in the overall health and our forest resources. By making a donation well-being of our forest resources. By making a donation to the Trees for North to the Trees for North Dakota Trust Fund, Dakota Trust Fund, our collective efforts our collective efforts can make incredible can make incredible contributions to the contributions to the quality of life in quality of life in North Dakota for all who North Dakota for all who live and visit here. live and visit here.
The Community Family Forest grant The Community Family Forest grant program, funded by private donations to program, funded by private donations to the Trees for North Dakota Trust Fund, the Trees for North Dakota Trust Fund, helps communities across North Dakota helps communities across North Dakota diversify their tree resources, to make diversify their tree resources, to make their community forest more resilient to their community forest more resilient to damaging forest pests like the emerald damaging forest pests like emerald ash ash borer. Communities use these funds borer. Communities use these funds to to plant a variety of trees adapted to plant a variety of trees adapted to North Dakota's climate in places that need them North Dakota's climate in places that need most. Please consider donating today! them most. Please consider donating today!
To contribute to the Trees for
To contribute to the Trees for North
# North
Dakota Trust Fund, consult your tax Dakota Trust Fund, consult preparer or enter a voluntary contribution your tax preparer or enter a voluntary on the current North Dakota Individual contribution on the current North Dakota Income Tax Return (see below):
Individual Income Tax Return (see below):
# Form ND-EZ: Refund return (line 5)/Tax due (line 8)
)
Form ND-1: Refund return (line 31)/Tax due (line 35) Form ND-1: Refund return (Line 31)/Tax due (Line 35) North Dakota Forest Service • 307 1st Street East, Bottineau, ND 58318 • 701-228-5422 • www.ndsu.edu/ndfs
# Your contributions have helped fund projects including:
Conservation education projects to Schools and
# Communities
Species of concern habitat projects Grants to civic organizations for wildlife projects Watchable Wildlife recruitment and education programs For more information contact:
North Dakota Game and Fish Department 100 N. Bismarck Expressway Bismarck, ND 58501-5095 Web: gf.nd.gov Email: ndgf@nd.gov Photo by Sandra Johnson
# School district codes
For Item B at the top of Form ND-EZ or Form ND-1, enter the applicable school district code number-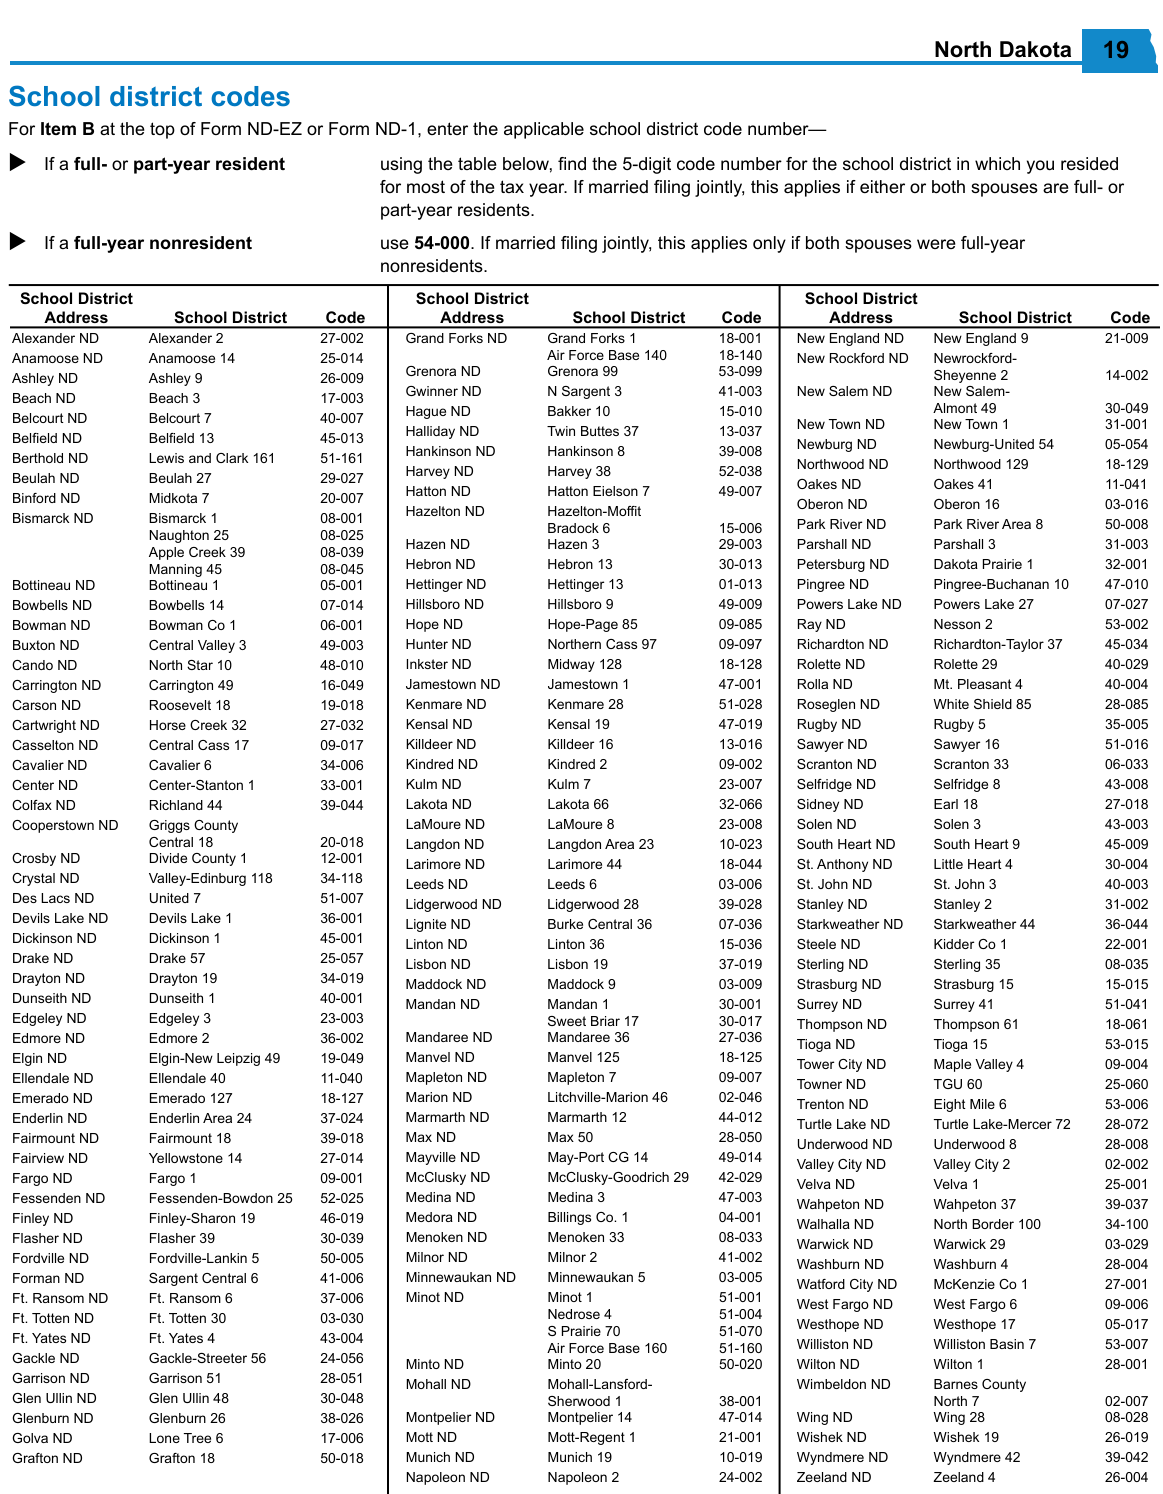
Text version of this table
North Dakota 19 School district co des For Item B a t the top of Form ND-EZ or Form ND-1, enter the applic able school district co de num ber— If a full‑ or part‑year resi dent using the table below , find the 5-digit code number for the scho ol distr ict in which you reside d for most of the tax ye ar. If married filing joi ntly, this applies if eit her or both spouses are full- or part-year residents. If a full- year nonresident use 54-000. If marrie d filing jointly, this app lies only if both spou ses w ere full‑year nonresidents. School Dist rict School District School Di strict Address School Di strict Code Address School District Code Addres s School District Code Alexander ND Alexander 2 27-002 Grand Forks ND Grand Forks 1 18-001 New England ND New England 9 21-009 Anamoose ND Anamoose 14 25-014 Air Force Base 140 18-140 New Rockford ND Newrockford- Ashley ND Ashley 9 26-009 Grenora ND Grenora 99 53-099 Sheyenne 2 14-002 Gwinner ND N Sargent 3 41-003 New Salem N D New Salem- Beach ND Beach 3 17-003 Hague ND Bakker 10 15-010 Almont 49 30-049 Belcourt ND Belcourt 7 40-007 New Town ND New Town 1 31-001 Belfield ND Belfield 13 45-013 Halliday ND Twin Buttes 37 13-037 Newburg ND Newburg-United 54 05-054 Berthold ND Lewis and Clark 161 51-161 Hankinson ND Hankinson 8 39-008 Northwood N D Northwood 129 18-129 Beulah ND Beulah 27 29-027 Harvey ND Harvey 38 52-038 Oakes ND Oakes 41 11-041 Binford ND Bismarck ND Midkota 7 Bismarck 1 20-007 08-001 Hatton ND Hazelton ND Hatton Eielson 7 Hazelton-Moffit 49-007 Oberon ND Oberon 16 03-016 Naughton 25 Apple Creek 39 08-025 08-039 Hazen ND Bradock 6 Hazen 3 15-006 29-003 Park River ND Parshall ND Park River Area 8 Parshall 3 50-008 31-003 Manning 45 08-045 Hebron ND Hebron 13 30-013 Petersburg N D Dakota Prairie 1 32-001 Bottineau ND Bottineau 1 05-001 Hettinger ND Hettinger 13 01-013 Pingree ND Pingree-Buchanan 10 47-010 Bowbells ND Bowbells 14 07-014 Hillsboro ND Hillsboro 9 49-009 Powers Lake ND Powers Lake 27 07-027 Bowman ND Bowman Co 1 06-001 Hope ND Hope-Page 85 09-085 Ray ND Nesson 2 53-002 Buxton ND Central Valley 3 49-003 Hunter ND Northern Cass 97 09-097 Richardton N D Richardton-Taylor 37 45-034 Cando ND North Star 10 48-010 Inkster ND Midway 128 18-128 Rolette ND Rolette 29 40-029 Carrington ND Carrington 49 16-049 Jamestown ND Jamestown 1 47-001 Rolla ND Mt. Pleasant 4 40-004 Carson ND Roosevelt 18 19-018 Kenmare ND Kenmare 28 51-028 Roseglen ND White Shield 85 28-085 Cartwright ND Horse Creek 32 27-032 Kensal ND Kensal 19 47-019 Rugby ND Rugby 5 35-005 Casselton ND Central Cass 17 09-017 Killdeer ND Killdeer 16 13-016 Sawyer ND Sawyer 16 51-016 Cavalier ND Cavalier 6 34-006 Kindred ND Kindred 2 09-002 Scranton ND Scranton 33 06-033 Center ND Center-Stanton 1 33-001 Kulm ND Kulm 7 23-007 Selfridge ND Selfridge 8 43-008 Colfax ND Richland 44 39-044 Lakota ND Lakota 66 32-066 Sidney ND Earl 18 27-018 Cooperstown N D Griggs County LaMoure ND LaMoure 8 23-008 Solen ND Solen 3 43-003 Central 18 20-018 Langdon ND Langdon Area 23 10-023 South Heart N D South Heart 9 45-009 Crosby ND Divide County 1 12-001 Larimore ND Larimore 44 18-044 St. Anthony N D Little Heart 4 30-004 Crystal ND Valley-Edinburg 118 34-118 Leeds ND Leeds 6 03-006 St. John ND St. John 3 40-003 Des Lacs ND United 7 51-007 Lidgerwood ND Lidgerwood 28 39-028 Stanley ND Stanley 2 31-002 Devils Lake ND Devils Lake 1 36-001 Lignite ND Burke Central 36 07-036 Starkweather ND Starkweather 44 36-044 Dickinson ND Dickinson 1 45-001 Linton ND Linton 36 15-036 Steele ND Kidder Co 1 22-001 Drake ND Drake 57 25-057 Lisbon ND Lisbon 19 37-019 Sterling ND Sterling 35 08-035 Drayton ND Drayton 19 34-019 Maddock ND Maddock 9 03-009 Strasburg ND Strasburg 15 15-015 Dunseith ND Dunseith 1 40-001 Mandan ND Mandan 1 30-001 Surrey ND Surrey 41 51-041 Edgeley ND Edgeley 3 23-003 Sweet Briar 17 30-017 Thompson N D Thompson 61 18-061 Mandaree ND Mandaree 36 27-036 Edmore ND Edmore 2 36-002 Tioga ND Tioga 15 53-015 Manvel ND Manvel 125 18-125 Elgin ND Elgin-New Leipz ig 49 19-049 Tower City ND Maple Valley 4 09-004 Mapleton ND Mapleton 7 09-007 Ellendale ND Ellendale 40 11-040 Towner ND TGU 60 25-060 Marion ND Litchville-Marion 46 02-046 Emerado ND Emerado 127 18-127 Trenton ND Eight Mile 6 53-006 Marmarth ND Marmarth 12 44-012 Enderlin ND Enderlin Area 24 37-024 Turtle Lake N D Turtle Lake-Mercer 72 28-072 Max ND Max 50 28-050 Fairmount ND Fairmount 18 39-018 Underwood N D Underwood 8 28-008 Mayville ND May-Port CG 14 49-014 Fairview ND Yellowstone 14 27-014 Valley City ND Valley City 2 02-002 McClusky ND McClusky-Goodrich 29 42-029 Fargo ND Fargo 1 09-001 Velva ND Velva 1 25-001 Medina ND Medina 3 47-003 Fessenden ND Fessenden-Bow don 25 52-025 Wahpeton ND Wahpeton 37 39-037 Medora ND Billings Co. 1 04-001 Finley ND Finley-Sharon 1 9 46-019 Walhalla ND North Border 100 34-100 Menoken ND Menoken 33 08-033 Flasher ND Flasher 39 30-039 Warwick ND Warwick 29 03-029 Milnor ND Milnor 2 41-002 Fordville ND Fordville-Lankin 5 50-005 Washburn ND Washburn 4 28-004 Minnewaukan ND Minnewaukan 5 03-005 Forman ND Sargent Central 6 41-006 Watford City ND McKenzie Co 1 27-001 Minot ND Minot 1 51-001 Ft. Ransom ND Ft. Ransom 6 37-006 West Fargo N D West Fargo 6 09-006 Ft. Totten ND Ft. Totten 30 03-030 Nedrose 4 51-004 S Prairie 70 51-070 Westhope ND Westhope 17 05-017 Ft. Yates ND Ft. Yates 4 43-004 Air Force Base 160 51-160 Williston ND Williston Basin 7 53-007 Gackle ND Gackle-Streeter 56 24-056 Minto ND Minto 20 50-020 Wilton ND Wilton 1 28-001 Garrison ND Garrison 51 28-051 Mohall ND Mohall-Lansford- Wimbeldon N D Barnes County Glen Ullin ND Glen Ullin 48 30-048 Sherwood 1 38-001 North 7 02-007 Glenburn ND Glenburn 26 38-026 Montpelier ND Montpelier 14 47-014 Wing ND Wing 28 08-028 Golva ND Lone Tree 6 17-006 Mott ND Mott-Regent 1 21-001 Wishek ND Wishek 19 26-019 Grafton ND Grafton 18 50-018 Munich ND Munich 19 10-019 Wyndmere N D Wyndmere 42 39-042 Napoleon ND Napoleon 2 24-002 Zeeland ND Zeeland 4 26-004
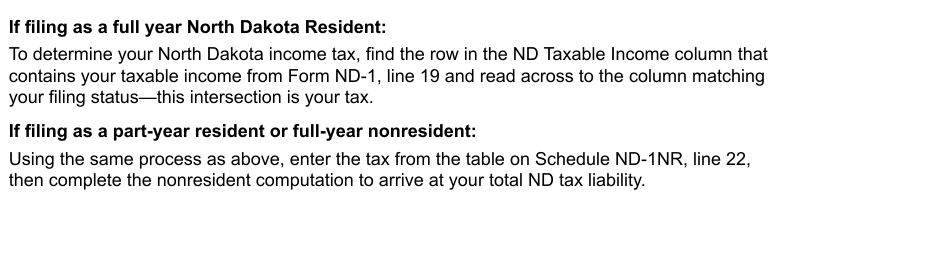
Text version of this table
| a Ibf lyeo Iunrc NoDme co ttaox tahbele column income is— | lumn that matcAhnidn gy our filing status is— |
|---|---|
| At But least less than edule ND‑1NR, x liability. | Single Married Married Head filing filing of jointly * sepa- house- line 22, rately hold Your tax is— |
| 91,850 91,900 91,900 91,950 91,950 92,000 | 846 213 1,002 525 847 214 1,003 526 848 215 1,004 527 |
# Table
$214.
At But Single Married Married Head filing filing of least less If filing as a part-year resident or full-year nonresident: jointly * sepa- house- than Using the same process as above, enter the tax from the table on Schedule ND-1NR, line 22, rately hold If either spouse is a part- or full-year nonresident, enter that same then complete the nonresident computation to arrive at your total ND tax liability. tax amount ($214 in the example) on Schedule ND-1NR, line 22, Your tax isthen complete the nonresident computation to arrive at your total ND tax liability.
If your ND
If your ND
91,850 91,900 846 213 1,002 525
91,900 91,950 847 214 1,003 526
91,950 92,000 848 215 1,004 527
If your ND
And your filing status is-
And your filing status is- taxable taxable income is- income is-At But Single At But Single Married Married Head least less least less filing filing of than than jointly * sepa- house- rately hold Your tax is-40,250 40,300 0 0 0 0 42,500 42,550 0 40,300 40,350 0 0 0 0 42,550 42,600 0 40,350 40,400 0 0 0 0 42,600 42,650 0 40,400 40,450 0 0 0 0 42,650 42,700 0 40,450 40,500 0 0 0 0 42,700 42,750 0 40,500 40,550 0 0 1 0 42,750 42,800 0 40,550 40,600 0 0 2 0 42,800 42,850 0 40,600 40,650 0 0 3 0 42,850 42,900 0 40,650 40,700 0 0 4 0 42,900 42,950 0 40,700 40,750 0 0 5 0 42,950 43,000 0 43,000 40,750 40,800 0 0 6 0 40,800 40,850 0 0 7 0 40,850 40,900 0 0 8 0 40,900 40,950 0 0 9 0 43,000 43,050 0 40,950 41,000 0 0 10 0 43,050 43,100 0 43,100 43,150 0 41,000 43,150 43,200 0 43,200 43,250 0 41,000 41,050 0 0 11 0 43,250 43,300 0 41,050 41,100 0 0 12 0 43,300 43,350 0 41,100 41,150 0 0 13 0 43,350 43,400 0 41,150 41,200 0 0 14 0 43,400 43,450 0 41,200 41,250 0 0 15 0 43,450 43,500 0 41,250 41,300 0 0 16 0 43,500 43,550 0 41,300 41,350 0 0 17 0 43,550 43,600 0 41,350 41,400 0 0 18 0 43,600 43,650 0 41,400 41,450 0 0 19 0 43,650 43,700 0 41,450 41,500 0 0 20 0 43,700 43,750 0 41,500 41,550 0 0 20 0 43,750 43,800 0 41,550 41,600 0 0 21 0 43,800 43,850 0 41,600 41,650 0 0 22 0 43,850 43,900 0 41,650 41,700 0 0 23 0 43,900 43,950 0 41,700 41,750 0 0 24 0 43,950 44,000 0 44,000 41,750 41,800 0 0 25 0 41,800 41,850 0 0 26 0 41,850 41,900 0 0 27 0 41,900 41,950 0 0 28 0 44,000 44,050 0 41,950 42,000 0 0 29 0 44,050 44,100 0 44,100 44,150 0 42,000 44,150 44,200 0 44,200 44,250 0 42,000 42,050 0 0 30 0 44,250 44,300 0 42,050 42,100 0 0 31 0 44,300 44,350 0 42,100 42,150 0 0 32 0 44,350 44,400 0 42,150 42,200 0 0 33 0 44,400 44,450 0 42,200 42,250 0 0 34 0 44,450 44,500 0 42,250 42,300 0 0 35 0 44,500 44,550 0 42,300 42,350 0 0 36 0 44,550 44,600 0 42,350 42,400 0 0 37 0 44,600 44,650 0 42,400 42,450 0 0 38 0 44,650 44,700 0 42,450 42,500 0 0 39 0 44,700 44,750 0 And your filing status is- taxable income is-Head Married Married Head At But Single Married Married of filing filing of least less filing filing house- jointly * sepa- house- than jointly * sepa- hold rately hold rately Your tax is- Your tax is-0 40 0 44,750 44,800 0 0 84 0 0 41 0 44,800 44,850 0 0 85 0 0 42 0 44,850 44,900 0 0 86 0 0 43 0 44,900 44,950 0 0 87 0 0 44 0 44,950 45,000 0 0 88 0 45,000 0 45 0 0 46 0 0 47 0 0 48 0 45,000 45,050 0 0 89 0 0 49 0 45,050 45,100 0 0 90 0 45,100 45,150 0 0 91 0 45,150 45,200 0 0 92 0 45,200 45,250 0 0 93 0 0 50 0 45,250 45,300 0 0 94 0 0 51 0 45,300 45,350 0 0 95 0 0 52 0 45,350 45,400 0 0 96 0 0 53 0 45,400 45,450 0 0 97 0 0 54 0 45,450 45,500 0 0 98 0 0 55 0 45,500 45,550 0 0 98 0 0 56 0 45,550 45,600 0 0 99 0 0 57 0 45,600 45,650 0 0 100 0 0 58 0 45,650 45,700 0 0 101 0 0 59 0 45,700 45,750 0 0 102 0 0 59 0 45,750 45,800 0 0 103 0 0 60 0 45,800 45,850 0 0 104 0 0 61 0 45,850 45,900 0 0 105 0 0 62 0 45,900 45,950 0 0 106 0 0 63 0 45,950 46,000 0 0 107 0 46,000 0 64 0 0 65 0 0 66 0 0 67 0 46,000 46,050 0 0 108 0 0 68 0 46,050 46,100 0 0 109 0 46,100 46,150 0 0 110 0 46,150 46,200 0 0 111 0 46,200 46,250 0 0 112 0 0 69 0 46,250 46,300 0 0 113 0 0 70 0 46,300 46,350 0 0 114 0 0 71 0 46,350 46,400 0 0 115 0 0 72 0 46,400 46,450 0 0 116 0 0 73 0 46,450 46,500 0 0 117 0 0 74 0 46,500 46,550 0 0 118 0 0 75 0 46,550 46,600 0 0 119 0 0 76 0 46,600 46,650 0 0 120 0 0 77 0 46,650 46,700 0 0 121 0 0 78 0 46,700 46,750 0 0 122 0 0 79 0 46,750 46,800 0 0 123 0 0 80 0 46,800 46,850 0 0 124 0 0 81 0 46,850 46,900 0 0 125 0 0 82 0 46,900 46,950 0 0 126 0 0 83 0 46,950 47,000 0 0 127 0
# North Dakota
If your ND
And your filing status is-
And your filing status is- taxable taxable income is- income is-
# Head At But Single
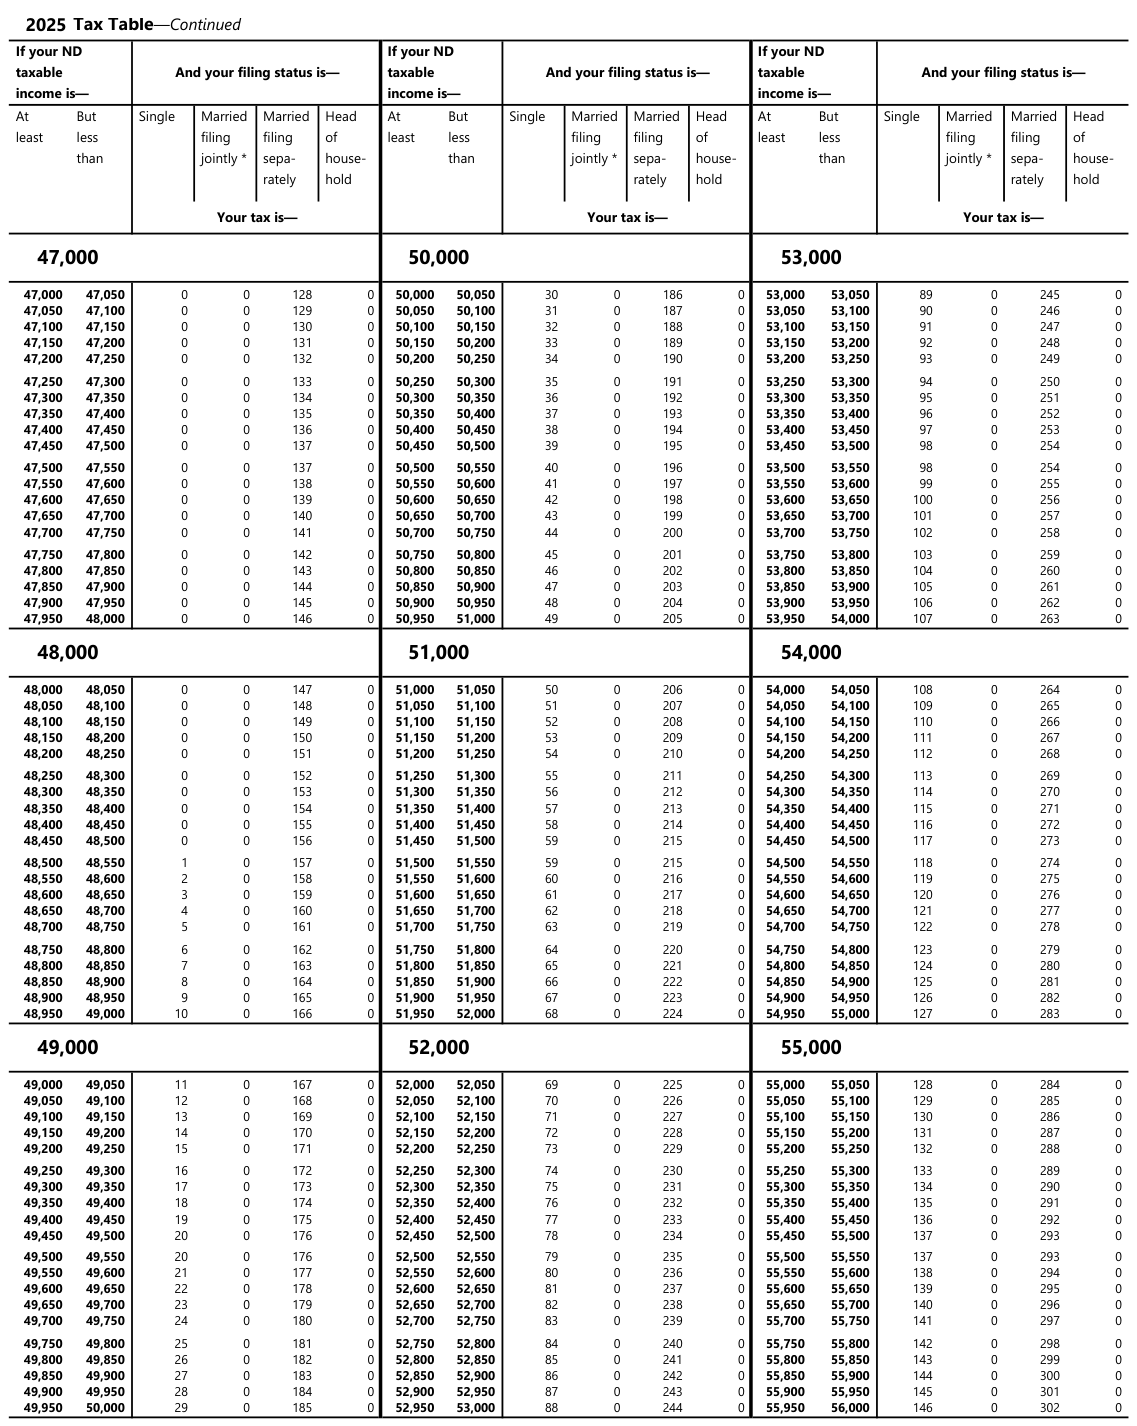
Text version of this table
| If your ND taxable income is— | And your filing status is— | If your ND taxable income is— | And your filing status is— | If your ND taxable income is— | And your filing status is— | |
| At But least less than | Single Married Married Head filing filing of jointly * sepa- house- rately hold Your tax is— | At But least less than | Single Married Married Head filing filing of jointly * sepa- house- rately hold Your tax is— | At But least less than | Single Married Married Head filing filing of jointly * sepa- house- rately hold Your tax is— | |
| 47,000 | 50,000 | 53,000 | ||||
| 47,000 47,050 47,050 47,100 47,100 47,150 47,150 47,200 47,200 47,250 47,250 47,300 47,300 47,350 47,350 47,400 47,400 47,450 47,450 47,500 47,500 47,550 47,550 47,600 47,600 47,650 47,650 47,700 47,700 47,750 47,750 47,800 47,800 47,850 47,850 47,900 47,900 47,950 47,950 48,000 | 0 0 128 0 0 0 129 0 0 0 130 0 0 0 131 0 0 0 132 0 0 0 133 0 0 0 134 0 0 0 135 0 0 0 136 0 0 0 137 0 0 0 137 0 0 0 138 0 0 0 139 0 0 0 140 0 0 0 141 0 0 0 142 0 0 0 143 0 0 0 144 0 0 0 145 0 0 0 146 0 | 50,000 50,050 50,050 50,100 50,100 50,150 50,150 50,200 50,200 50,250 50,250 50,300 50,300 50,350 50,350 50,400 50,400 50,450 50,450 50,500 50,500 50,550 50,550 50,600 50,600 50,650 50,650 50,700 50,700 50,750 50,750 50,800 50,800 50,850 50,850 50,900 50,900 50,950 50,950 51,000 | 30 0 186 0 31 0 187 0 32 0 188 0 33 0 189 0 34 0 190 0 35 0 191 0 36 0 192 0 37 0 193 0 38 0 194 0 39 0 195 0 40 0 196 0 41 0 197 0 42 0 198 0 43 0 199 0 44 0 200 0 45 0 201 0 46 0 202 0 47 0 203 0 48 0 204 0 49 0 205 0 | 53,000 53,050 53,050 53,100 53,100 53,150 53,150 53,200 53,200 53,250 53,250 53,300 53,300 53,350 53,350 53,400 53,400 53,450 53,450 53,500 53,500 53,550 53,550 53,600 53,600 53,650 53,650 53,700 53,700 53,750 53,750 53,800 53,800 53,850 53,850 53,900 53,900 53,950 53,950 54,000 | 89 0 245 0 90 0 246 0 91 0 247 0 92 0 248 0 93 0 249 0 94 0 250 0 95 0 251 0 96 0 252 0 97 0 253 0 98 0 254 0 98 0 254 0 99 0 255 0 100 0 256 0 101 0 257 0 102 0 258 0 103 0 259 0 104 0 260 0 105 0 261 0 106 0 262 0 107 0 263 0 | |
| 48,000 | 51,000 | 54,000 | ||||
| 48,000 48,050 48,050 48,100 48,100 48,150 48,150 48,200 48,200 48,250 48,250 48,300 48,300 48,350 48,350 48,400 48,400 48,450 48,450 48,500 48,500 48,550 48,550 48,600 48,600 48,650 48,650 48,700 48,700 48,750 48,750 48,800 48,800 48,850 48,850 48,900 48,900 48,950 48,950 49,000 | 0 0 147 0 0 0 148 0 0 0 149 0 0 0 150 0 0 0 151 0 0 0 152 0 0 0 153 0 0 0 154 0 0 0 155 0 0 0 156 0 1 0 157 0 2 0 158 0 3 0 159 0 4 0 160 0 5 0 161 0 6 0 162 0 7 0 163 0 8 0 164 0 9 0 165 0 10 0 166 0 | 51,000 51,050 51,050 51,100 51,100 51,150 51,150 51,200 51,200 51,250 51,250 51,300 51,300 51,350 51,350 51,400 51,400 51,450 51,450 51,500 51,500 51,550 51,550 51,600 51,600 51,650 51,650 51,700 51,700 51,750 51,750 51,800 51,800 51,850 51,850 51,900 51,900 51,950 51,950 52,000 | 50 0 206 0 51 0 207 0 52 0 208 0 53 0 209 0 54 0 210 0 55 0 211 0 56 0 212 0 57 0 213 0 58 0 214 0 59 0 215 0 59 0 215 0 60 0 216 0 61 0 217 0 62 0 218 0 63 0 219 0 64 0 220 0 65 0 221 0 66 0 222 0 67 0 223 0 68 0 224 0 | 54,000 54,050 54,050 54,100 54,100 54,150 54,150 54,200 54,200 54,250 54,250 54,300 54,300 54,350 54,350 54,400 54,400 54,450 54,450 54,500 54,500 54,550 54,550 54,600 54,600 54,650 54,650 54,700 54,700 54,750 54,750 54,800 54,800 54,850 54,850 54,900 54,900 54,950 54,950 55,000 | 108 0 264 0 109 0 265 0 110 0 266 0 111 0 267 0 112 0 268 0 113 0 269 0 114 0 270 0 115 0 271 0 116 0 272 0 117 0 273 0 118 0 274 0 119 0 275 0 120 0 276 0 121 0 277 0 122 0 278 0 123 0 279 0 124 0 280 0 125 0 281 0 126 0 282 0 127 0 283 0 | |
| 49,000 | 52,000 | 55,000 | ||||
| 49,000 49,050 49,050 49,100 49,100 49,150 49,150 49,200 49,200 49,250 49,250 49,300 49,300 49,350 49,350 49,400 49,400 49,450 49,450 49,500 49,500 49,550 49,550 49,600 49,600 49,650 49,650 49,700 49,700 49,750 49,750 49,800 49,800 49,850 49,850 49,900 49,900 49,950 49,950 50,000 | 11 0 167 12 0 168 13 0 169 14 0 170 15 0 171 16 0 172 17 0 173 18 0 174 19 0 175 20 0 176 20 0 176 21 0 177 22 0 178 23 0 179 24 0 180 25 0 181 26 0 182 27 0 183 28 0 184 29 0 185 | 0 0 0 0 0 0 0 0 0 0 0 0 0 0 0 0 0 0 0 0 | 52,000 52,050 52,050 52,100 52,100 52,150 52,150 52,200 52,200 52,250 52,250 52,300 52,300 52,350 52,350 52,400 52,400 52,450 52,450 52,500 52,500 52,550 52,550 52,600 52,600 52,650 52,650 52,700 52,700 52,750 52,750 52,800 52,800 52,850 52,850 52,900 52,900 52,950 52,950 53,000 | 69 0 225 0 70 0 226 0 71 0 227 0 72 0 228 0 73 0 229 0 74 0 230 0 75 0 231 0 76 0 232 0 77 0 233 0 78 0 234 0 79 0 235 0 80 0 236 0 81 0 237 0 82 0 238 0 83 0 239 0 84 0 240 0 85 0 241 0 86 0 242 0 87 0 243 0 88 0 244 0 | 55,000 55,050 55,050 55,100 55,100 55,150 55,150 55,200 55,200 55,250 55,250 55,300 55,300 55,350 55,350 55,400 55,400 55,450 55,450 55,500 55,500 55,550 55,550 55,600 55,600 55,650 55,650 55,700 55,700 55,750 55,750 55,800 55,800 55,850 55,850 55,900 55,900 55,950 55,950 56,000 | 128 0 284 0 129 0 285 0 130 0 286 0 131 0 287 0 132 0 288 0 133 0 289 0 134 0 290 0 135 0 291 0 136 0 292 0 137 0 293 0 137 0 293 0 138 0 294 0 139 0 295 0 140 0 296 0 141 0 297 0 142 0 298 0 143 0 299 0 144 0 300 0 145 0 301 0 146 0 302 0 |
# At But Single Married
If your ND If your ND
And your filing status is-
If your ND
And your filing status is- taxable taxable income is- income is-
# Head At But Single
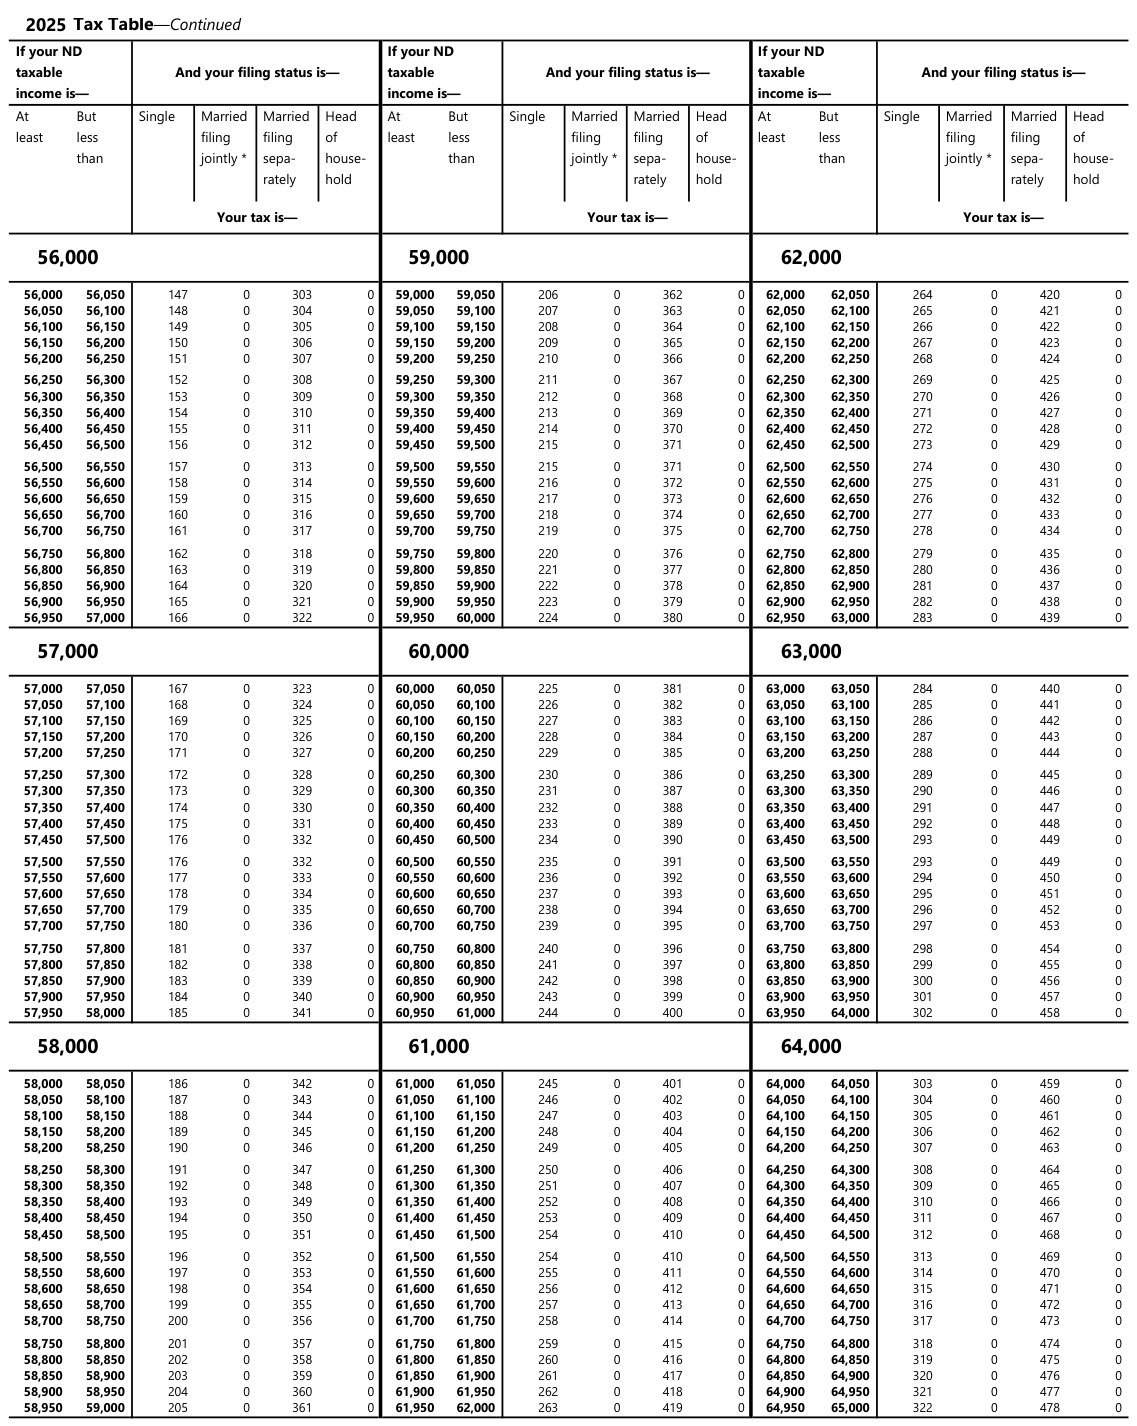
Text version of this table
| If your ND taxable income is— | And your filing status is— | If your ND taxable income is— | And your filing status is— | If your ND taxable income is— | And your filing status is— | |
| At But least less than | Single Married Married Head filing filing of jointly * sepa- house- rately hold Your tax is— | At But least less than | Single Married Married Head filing filing of jointly * sepa- house- rately hold Your tax is— | At But least less than | Single Married Married Head filing filing of jointly * sepa- house- rately hold Your tax is— | |
| 56,000 | 59,000 | 62,000 | ||||
| 56,000 56,050 56,050 56,100 56,100 56,150 56,150 56,200 56,200 56,250 56,250 56,300 56,300 56,350 56,350 56,400 56,400 56,450 56,450 56,500 56,500 56,550 56,550 56,600 56,600 56,650 56,650 56,700 56,700 56,750 56,750 56,800 56,800 56,850 56,850 56,900 56,900 56,950 56,950 57,000 | 147 0 303 0 148 0 304 0 149 0 305 0 150 0 306 0 151 0 307 0 152 0 308 0 153 0 309 0 154 0 310 0 155 0 311 0 156 0 312 0 157 0 313 0 158 0 314 0 159 0 315 0 160 0 316 0 161 0 317 0 162 0 318 0 163 0 319 0 164 0 320 0 165 0 321 0 166 0 322 0 | 59,000 59,050 59,050 59,100 59,100 59,150 59,150 59,200 59,200 59,250 59,250 59,300 59,300 59,350 59,350 59,400 59,400 59,450 59,450 59,500 59,500 59,550 59,550 59,600 59,600 59,650 59,650 59,700 59,700 59,750 59,750 59,800 59,800 59,850 59,850 59,900 59,900 59,950 59,950 60,000 | 206 0 362 0 207 0 363 0 208 0 364 0 209 0 365 0 210 0 366 0 211 0 367 0 212 0 368 0 213 0 369 0 214 0 370 0 215 0 371 0 215 0 371 0 216 0 372 0 217 0 373 0 218 0 374 0 219 0 375 0 220 0 376 0 221 0 377 0 222 0 378 0 223 0 379 0 224 0 380 0 | 62,000 62,050 62,050 62,100 62,100 62,150 62,150 62,200 62,200 62,250 62,250 62,300 62,300 62,350 62,350 62,400 62,400 62,450 62,450 62,500 62,500 62,550 62,550 62,600 62,600 62,650 62,650 62,700 62,700 62,750 62,750 62,800 62,800 62,850 62,850 62,900 62,900 62,950 62,950 63,000 | 264 0 420 0 265 0 421 0 266 0 422 0 267 0 423 0 268 0 424 0 269 0 425 0 270 0 426 0 271 0 427 0 272 0 428 0 273 0 429 0 274 0 430 0 275 0 431 0 276 0 432 0 277 0 433 0 278 0 434 0 279 0 435 0 280 0 436 0 281 0 437 0 282 0 438 0 283 0 439 0 | |
| 57,000 | 60,000 | 63,000 | ||||
| 57,000 57,050 57,050 57,100 57,100 57,150 57,150 57,200 57,200 57,250 57,250 57,300 57,300 57,350 57,350 57,400 57,400 57,450 57,450 57,500 57,500 57,550 57,550 57,600 57,600 57,650 57,650 57,700 57,700 57,750 57,750 57,800 57,800 57,850 57,850 57,900 57,900 57,950 57,950 58,000 | 167 0 323 0 168 0 324 0 169 0 325 0 170 0 326 0 171 0 327 0 172 0 328 0 173 0 329 0 174 0 330 0 175 0 331 0 176 0 332 0 176 0 332 0 177 0 333 0 178 0 334 0 179 0 335 0 180 0 336 0 181 0 337 0 182 0 338 0 183 0 339 0 184 0 340 0 185 0 341 0 | 60,000 60,050 60,050 60,100 60,100 60,150 60,150 60,200 60,200 60,250 60,250 60,300 60,300 60,350 60,350 60,400 60,400 60,450 60,450 60,500 60,500 60,550 60,550 60,600 60,600 60,650 60,650 60,700 60,700 60,750 60,750 60,800 60,800 60,850 60,850 60,900 60,900 60,950 60,950 61,000 | 225 0 381 0 226 0 382 0 227 0 383 0 228 0 384 0 229 0 385 0 230 0 386 0 231 0 387 0 232 0 388 0 233 0 389 0 234 0 390 0 235 0 391 0 236 0 392 0 237 0 393 0 238 0 394 0 239 0 395 0 240 0 396 0 241 0 397 0 242 0 398 0 243 0 399 0 244 0 400 0 | 63,000 63,050 63,050 63,100 63,100 63,150 63,150 63,200 63,200 63,250 63,250 63,300 63,300 63,350 63,350 63,400 63,400 63,450 63,450 63,500 63,500 63,550 63,550 63,600 63,600 63,650 63,650 63,700 63,700 63,750 63,750 63,800 63,800 63,850 63,850 63,900 63,900 63,950 63,950 64,000 | 284 0 440 0 285 0 441 0 286 0 442 0 287 0 443 0 288 0 444 0 289 0 445 0 290 0 446 0 291 0 447 0 292 0 448 0 293 0 449 0 293 0 449 0 294 0 450 0 295 0 451 0 296 0 452 0 297 0 453 0 298 0 454 0 299 0 455 0 300 0 456 0 301 0 457 0 302 0 458 0 | |
| 58,000 | 61,000 | 64,000 | ||||
| 58,000 58,050 58,050 58,100 58,100 58,150 58,150 58,200 58,200 58,250 58,250 58,300 58,300 58,350 58,350 58,400 58,400 58,450 58,450 58,500 58,500 58,550 58,550 58,600 58,600 58,650 58,650 58,700 58,700 58,750 58,750 58,800 58,800 58,850 58,850 58,900 58,900 58,950 58,950 59,000 | 186 0 342 187 0 343 188 0 344 189 0 345 190 0 346 191 0 347 192 0 348 193 0 349 194 0 350 195 0 351 196 0 352 197 0 353 198 0 354 199 0 355 200 0 356 201 0 357 202 0 358 203 0 359 204 0 360 205 0 361 | 0 0 0 0 0 0 0 0 0 0 0 0 0 0 0 0 0 0 0 0 | 61,000 61,050 61,050 61,100 61,100 61,150 61,150 61,200 61,200 61,250 61,250 61,300 61,300 61,350 61,350 61,400 61,400 61,450 61,450 61,500 61,500 61,550 61,550 61,600 61,600 61,650 61,650 61,700 61,700 61,750 61,750 61,800 61,800 61,850 61,850 61,900 61,900 61,950 61,950 62,000 | 245 0 401 0 246 0 402 0 247 0 403 0 248 0 404 0 249 0 405 0 250 0 406 0 251 0 407 0 252 0 408 0 253 0 409 0 254 0 410 0 254 0 410 0 255 0 411 0 256 0 412 0 257 0 413 0 258 0 414 0 259 0 415 0 260 0 416 0 261 0 417 0 262 0 418 0 263 0 419 0 | 64,000 64,050 64,050 64,100 64,100 64,150 64,150 64,200 64,200 64,250 64,250 64,300 64,300 64,350 64,350 64,400 64,400 64,450 64,450 64,500 64,500 64,550 64,550 64,600 64,600 64,650 64,650 64,700 64,700 64,750 64,750 64,800 64,800 64,850 64,850 64,900 64,900 64,950 64,950 65,000 | 303 0 459 0 304 0 460 0 305 0 461 0 306 0 462 0 307 0 463 0 308 0 464 0 309 0 465 0 310 0 466 0 311 0 467 0 312 0 468 0 313 0 469 0 314 0 470 0 315 0 471 0 316 0 472 0 317 0 473 0 318 0 474 0 319 0 475 0 320 0 476 0 321 0 477 0 322 0 478 0 |
# At But Single Married
If your ND If your ND
And your filing status is-
# North Dakota
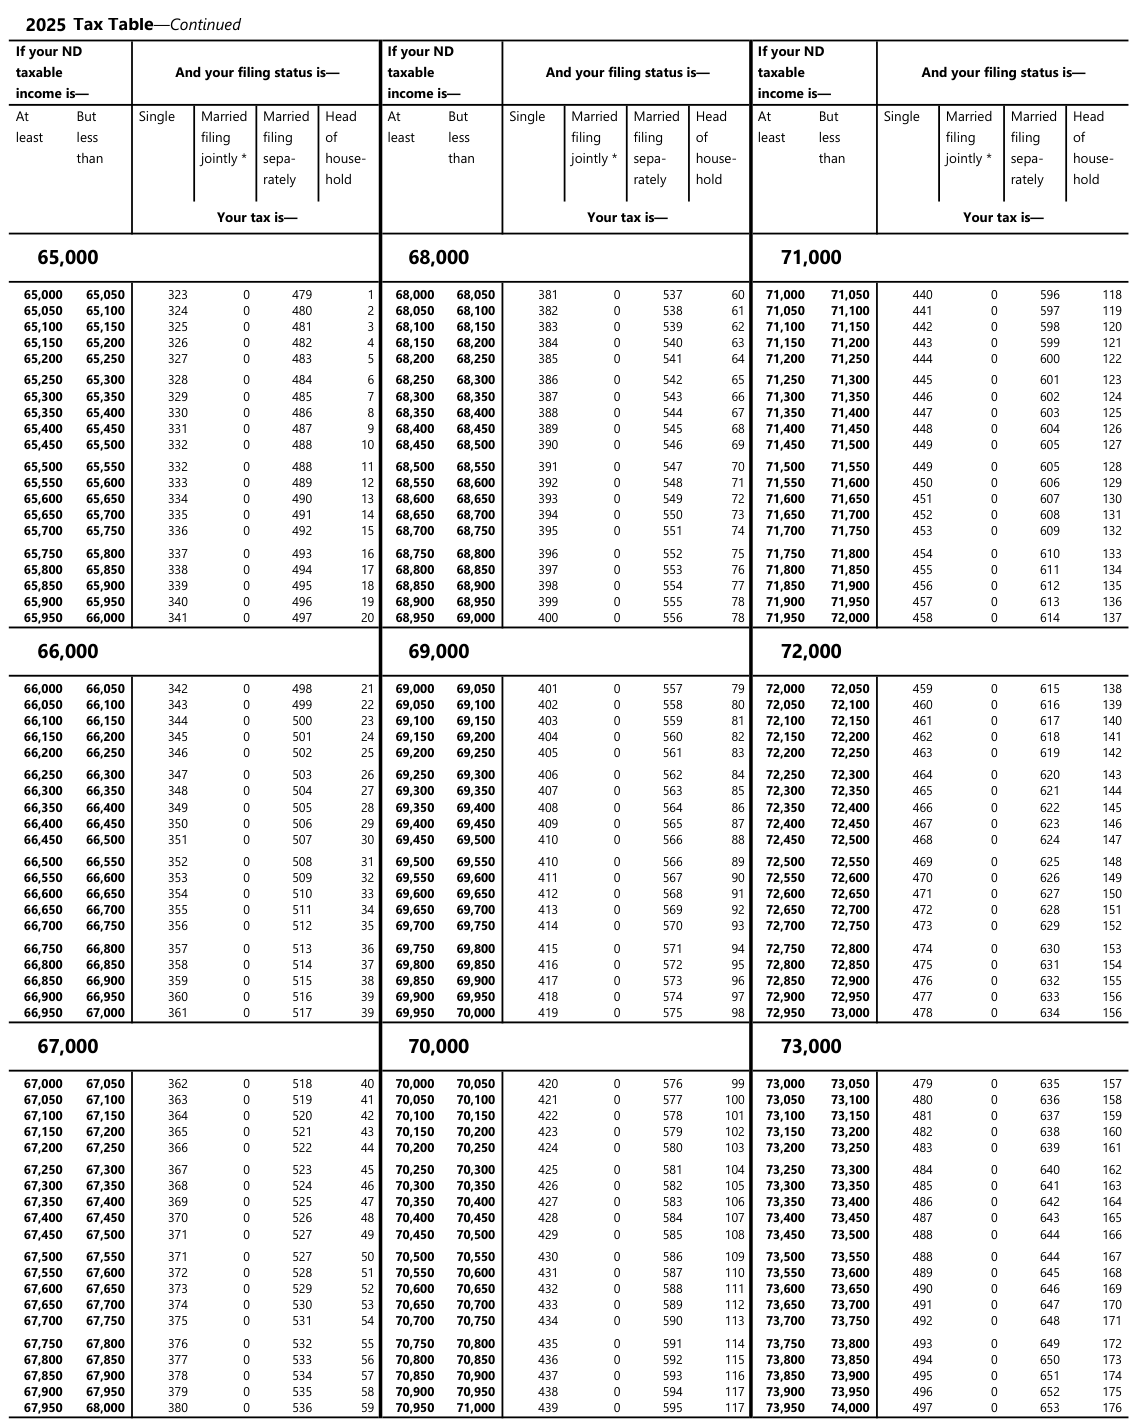
Text version of this table
If your ND taxable income is— And your filing status is— If your ND taxable income is— And your filing status is— If your ND taxable income is— And your filing status is— At But least less than Single Married Married Head filing filing of jointly * sepa- house- rately hold Your tax is— At But least less than Single Married Married Head filing filing of jointly * sepa- house- rately hold Your tax is— At But least less than Single Married Married Head filing filing of jointly * sepa- house- rately hold Your tax is— 65,000 68,000 71,000 65,000 65,050 65,050 65,100 65,100 65,150 65,150 65,200 65,200 65,250 65,250 65,300 65,300 65,350 65,350 65,400 65,400 65,450 65,450 65,500 65,500 65,550 65,550 65,600 65,600 65,650 65,650 65,700 65,700 65,750 65,750 65,800 65,800 65,850 65,850 65,900 65,900 65,950 65,950 66,000 323 0 479 1 324 0 480 2 325 0 481 3 326 0 482 4 327 0 483 5 328 0 484 6 329 0 485 7 330 0 486 8 331 0 487 9 332 0 488 10 332 0 488 11 333 0 489 12 334 0 490 13 335 0 491 14 336 0 492 15 337 0 493 16 338 0 494 17 339 0 495 18 340 0 496 19 341 0 497 20 68,000 68,050 68,050 68,100 68,100 68,150 68,150 68,200 68,200 68,250 68,250 68,300 68,300 68,350 68,350 68,400 68,400 68,450 68,450 68,500 68,500 68,550 68,550 68,600 68,600 68,650 68,650 68,700 68,700 68,750 68,750 68,800 68,800 68,850 68,850 68,900 68,900 68,950 68,950 69,000 381 0 537 60 382 0 538 61 383 0 539 62 384 0 540 63 385 0 541 64 386 0 542 65 387 0 543 66 388 0 544 67 389 0 545 68 390 0 546 69 391 0 547 70 392 0 548 71 393 0 549 72 394 0 550 73 395 0 551 74 396 0 552 75 397 0 553 76 398 0 554 77 399 0 555 78 400 0 556 78 71,000 71,050 71,050 71,100 71,100 71,150 71,150 71,200 71,200 71,250 71,250 71,300 71,300 71,350 71,350 71,400 71,400 71,450 71,450 71,500 71,500 71,550 71,550 71,600 71,600 71,650 71,650 71,700 71,700 71,750 71,750 71,800 71,800 71,850 71,850 71,900 71,900 71,950 71,950 72,000 440 0 596 118 441 0 597 119 442 0 598 120 443 0 599 121 444 0 600 122 445 0 601 123 446 0 602 124 447 0 603 125 448 0 604 126 449 0 605 127 449 0 605 128 450 0 606 129 451 0 607 130 452 0 608 131 453 0 609 132 454 0 610 133 455 0 611 134 456 0 612 135 457 0 613 136 458 0 614 137 66,000 69,000 72,000 66,000 66,050 66,050 66,100 66,100 66,150 66,150 66,200 66,200 66,250 66,250 66,300 66,300 66,350 66,350 66,400 66,400 66,450 66,450 66,500 66,500 66,550 66,550 66,600 66,600 66,650 66,650 66,700 66,700 66,750 66,750 66,800 66,800 66,850 66,850 66,900 66,900 66,950 66,950 67,000 342 0 498 21 343 0 499 22 344 0 500 23 345 0 501 24 346 0 502 25 347 0 503 26 348 0 504 27 349 0 505 28 350 0 506 29 351 0 507 30 352 0 508 31 353 0 509 32 354 0 510 33 355 0 511 34 356 0 512 35 357 0 513 36 358 0 514 37 359 0 515 38 360 0 516 39 361 0 517 39 69,000 69,050 69,050 69,100 69,100 69,150 69,150 69,200 69,200 69,250 69,250 69,300 69,300 69,350 69,350 69,400 69,400 69,450 69,450 69,500 69,500 69,550 69,550 69,600 69,600 69,650 69,650 69,700 69,700 69,750 69,750 69,800 69,800 69,850 69,850 69,900 69,900 69,950 69,950 70,000 401 0 557 79 402 0 558 80 403 0 559 81 404 0 560 82 405 0 561 83 406 0 562 84 407 0 563 85 408 0 564 86 409 0 565 87 410 0 566 88 410 0 566 89 411 0 567 90 412 0 568 91 413 0 569 92 414 0 570 93 415 0 571 94 416 0 572 95 417 0 573 96 418 0 574 97 419 0 575 98 72,000 72,050 72,050 72,100 72,100 72,150 72,150 72,200 72,200 72,250 72,250 72,300 72,300 72,350 72,350 72,400 72,400 72,450 72,450 72,500 72,500 72,550 72,550 72,600 72,600 72,650 72,650 72,700 72,700 72,750 72,750 72,800 72,800 72,850 72,850 72,900 72,900 72,950 72,950 73,000 459 0 615 138 460 0 616 139 461 0 617 140 462 0 618 141 463 0 619 142 464 0 620 143 465 0 621 144 466 0 622 145 467 0 623 146 468 0 624 147 469 0 625 148 470 0 626 149 471 0 627 150 472 0 628 151 473 0 629 152 474 0 630 153 475 0 631 154 476 0 632 155 477 0 633 156 478 0 634 156 67,000 70,000 73,000 67,000 67,050 67,050 67,100 67,100 67,150 67,150 67,200 67,200 67,250 67,250 67,300 67,300 67,350 67,350 67,400 67,400 67,450 67,450 67,500 67,500 67,550 67,550 67,600 67,600 67,650 67,650 67,700 67,700 67,750 67,750 67,800 67,800 67,850 67,850 67,900 67,900 67,950 67,950 68,000 362 0 518 363 0 519 364 0 520 365 0 521 366 0 522 367 0 523 368 0 524 369 0 525 370 0 526 371 0 527 371 0 527 372 0 528 373 0 529 374 0 530 375 0 531 376 0 532 377 0 533 378 0 534 379 0 535 380 0 536 40 41 42 43 44 45 46 47 48 49 50 51 52 53 54 55 56 57 58 59 70,000 70,050 70,050 70,100 70,100 70,150 70,150 70,200 70,200 70,250 70,250 70,300 70,300 70,350 70,350 70,400 70,400 70,450 70,450 70,500 70,500 70,550 70,550 70,600 70,600 70,650 70,650 70,700 70,700 70,750 70,750 70,800 70,800 70,850 70,850 70,900 70,900 70,950 70,950 71,000 420 0 576 99 421 0 577 100 422 0 578 101 423 0 579 102 424 0 580 103 425 0 581 104 426 0 582 105 427 0 583 106 428 0 584 107 429 0 585 108 430 0 586 109 431 0 587 110 432 0 588 111 433 0 589 112 434 0 590 113 435 0 591 114 436 0 592 115 437 0 593 116 438 0 594 117 439 0 595 117 73,000 73,050 73,050 73,100 73,100 73,150 73,150 73,200 73,200 73,250 73,250 73,300 73,300 73,350 73,350 73,400 73,400 73,450 73,450 73,500 73,500 73,550 73,550 73,600 73,600 73,650 73,650 73,700 73,700 73,750 73,750 73,800 73,800 73,850 73,850 73,900 73,900 73,950 73,950 74,000 479 0 635 157 480 0 636 158 481 0 637 159 482 0 638 160 483 0 639 161 484 0 640 162 485 0 641 163 486 0 642 164 487 0 643 165 488 0 644 166 488 0 644 167 489 0 645 168 490 0 646 169 491 0 647 170 492 0 648 171 493 0 649 172 494 0 650 173 495 0 651 174 496 0 652 175 497 0 653 176
And your filing status is-
And your filing status is- taxable taxable income is- income is-
# Single
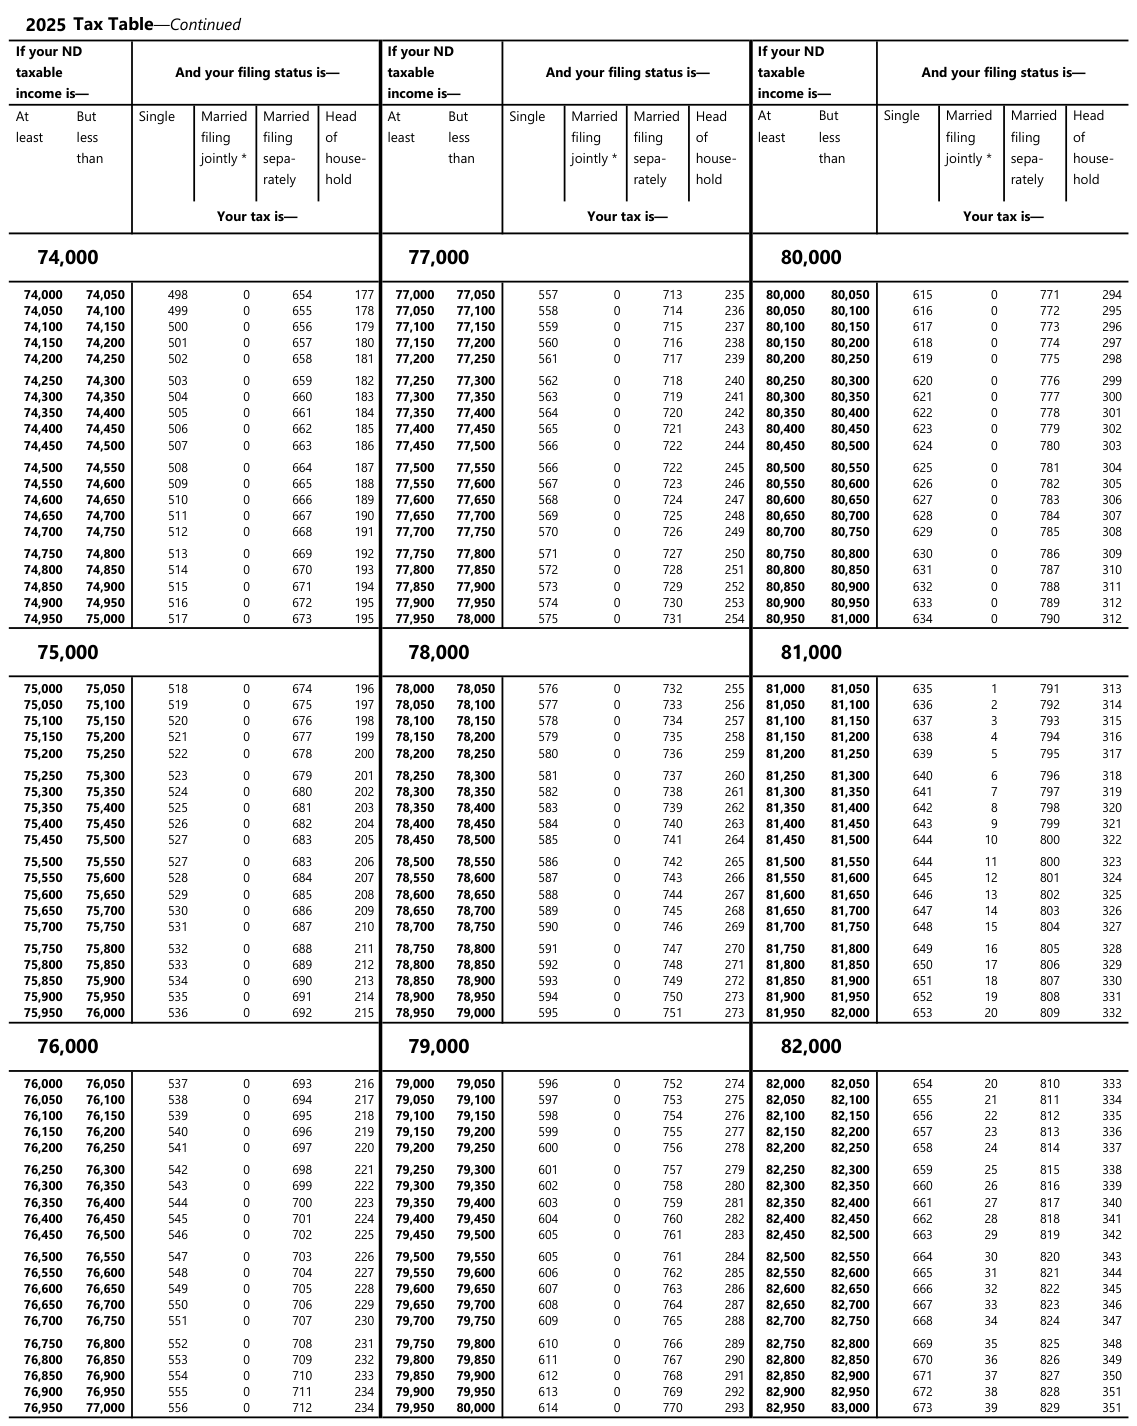
Text version of this table
| If your ND taxable income is— | And your filing status is— | If your ND taxable income is— | And your filing status is— | If your ND taxable income is— | And your filing status is— | |
| At But least less than | Single Married Married Head filing filing of jointly * sepa- house- rately hold Your tax is— | At But least less than | Single Married Married Head filing filing of jointly * sepa- house- rately hold Your tax is— | At But least less than | Single Married Married Head filing filing of jointly * sepa- house- rately hold Your tax is— | |
| 74,000 | 77,000 | 80,000 | ||||
| 74,000 74,050 74,050 74,100 74,100 74,150 74,150 74,200 74,200 74,250 74,250 74,300 74,300 74,350 74,350 74,400 74,400 74,450 74,450 74,500 74,500 74,550 74,550 74,600 74,600 74,650 74,650 74,700 74,700 74,750 74,750 74,800 74,800 74,850 74,850 74,900 74,900 74,950 74,950 75,000 | 498 0 654 177 499 0 655 178 500 0 656 179 501 0 657 180 502 0 658 181 503 0 659 182 504 0 660 183 505 0 661 184 506 0 662 185 507 0 663 186 508 0 664 187 509 0 665 188 510 0 666 189 511 0 667 190 512 0 668 191 513 0 669 192 514 0 670 193 515 0 671 194 516 0 672 195 517 0 673 195 | 77,000 77,050 77,050 77,100 77,100 77,150 77,150 77,200 77,200 77,250 77,250 77,300 77,300 77,350 77,350 77,400 77,400 77,450 77,450 77,500 77,500 77,550 77,550 77,600 77,600 77,650 77,650 77,700 77,700 77,750 77,750 77,800 77,800 77,850 77,850 77,900 77,900 77,950 77,950 78,000 | 557 0 713 235 558 0 714 236 559 0 715 237 560 0 716 238 561 0 717 239 562 0 718 240 563 0 719 241 564 0 720 242 565 0 721 243 566 0 722 244 566 0 722 245 567 0 723 246 568 0 724 247 569 0 725 248 570 0 726 249 571 0 727 250 572 0 728 251 573 0 729 252 574 0 730 253 575 0 731 254 | 80,000 80,050 80,050 80,100 80,100 80,150 80,150 80,200 80,200 80,250 80,250 80,300 80,300 80,350 80,350 80,400 80,400 80,450 80,450 80,500 80,500 80,550 80,550 80,600 80,600 80,650 80,650 80,700 80,700 80,750 80,750 80,800 80,800 80,850 80,850 80,900 80,900 80,950 80,950 81,000 | 615 0 771 294 616 0 772 295 617 0 773 296 618 0 774 297 619 0 775 298 620 0 776 299 621 0 777 300 622 0 778 301 623 0 779 302 624 0 780 303 625 0 781 304 626 0 782 305 627 0 783 306 628 0 784 307 629 0 785 308 630 0 786 309 631 0 787 310 632 0 788 311 633 0 789 312 634 0 790 312 | |
| 75,000 | 78,000 | 81,000 | ||||
| 75,000 75,050 75,050 75,100 75,100 75,150 75,150 75,200 75,200 75,250 75,250 75,300 75,300 75,350 75,350 75,400 75,400 75,450 75,450 75,500 75,500 75,550 75,550 75,600 75,600 75,650 75,650 75,700 75,700 75,750 75,750 75,800 75,800 75,850 75,850 75,900 75,900 75,950 75,950 76,000 | 518 0 674 196 519 0 675 197 520 0 676 198 521 0 677 199 522 0 678 200 523 0 679 201 524 0 680 202 525 0 681 203 526 0 682 204 527 0 683 205 527 0 683 206 528 0 684 207 529 0 685 208 530 0 686 209 531 0 687 210 532 0 688 211 533 0 689 212 534 0 690 213 535 0 691 214 536 0 692 215 | 78,000 78,050 78,050 78,100 78,100 78,150 78,150 78,200 78,200 78,250 78,250 78,300 78,300 78,350 78,350 78,400 78,400 78,450 78,450 78,500 78,500 78,550 78,550 78,600 78,600 78,650 78,650 78,700 78,700 78,750 78,750 78,800 78,800 78,850 78,850 78,900 78,900 78,950 78,950 79,000 | 576 0 732 255 577 0 733 256 578 0 734 257 579 0 735 258 580 0 736 259 581 0 737 260 582 0 738 261 583 0 739 262 584 0 740 263 585 0 741 264 586 0 742 265 587 0 743 266 588 0 744 267 589 0 745 268 590 0 746 269 591 0 747 270 592 0 748 271 593 0 749 272 594 0 750 273 595 0 751 273 | 81,000 81,050 81,050 81,100 81,100 81,150 81,150 81,200 81,200 81,250 81,250 81,300 81,300 81,350 81,350 81,400 81,400 81,450 81,450 81,500 81,500 81,550 81,550 81,600 81,600 81,650 81,650 81,700 81,700 81,750 81,750 81,800 81,800 81,850 81,850 81,900 81,900 81,950 81,950 82,000 | 635 1 791 313 636 2 792 314 637 3 793 315 638 4 794 316 639 5 795 317 640 6 796 318 641 7 797 319 642 8 798 320 643 9 799 321 644 10 800 322 644 11 800 323 645 12 801 324 646 13 802 325 647 14 803 326 648 15 804 327 649 16 805 328 650 17 806 329 651 18 807 330 652 19 808 331 653 20 809 332 | |
| 76,000 | 79,000 | 82,000 | ||||
| 76,000 76,050 76,050 76,100 76,100 76,150 76,150 76,200 76,200 76,250 76,250 76,300 76,300 76,350 76,350 76,400 76,400 76,450 76,450 76,500 76,500 76,550 76,550 76,600 76,600 76,650 76,650 76,700 76,700 76,750 76,750 76,800 76,800 76,850 76,850 76,900 76,900 76,950 76,950 77,000 | 537 0 693 538 0 694 539 0 695 540 0 696 541 0 697 542 0 698 543 0 699 544 0 700 545 0 701 546 0 702 547 0 703 548 0 704 549 0 705 550 0 706 551 0 707 552 0 708 553 0 709 554 0 710 555 0 711 556 0 712 | 216 217 218 219 220 221 222 223 224 225 226 227 228 229 230 231 232 233 234 234 | 79,000 79,050 79,050 79,100 79,100 79,150 79,150 79,200 79,200 79,250 79,250 79,300 79,300 79,350 79,350 79,400 79,400 79,450 79,450 79,500 79,500 79,550 79,550 79,600 79,600 79,650 79,650 79,700 79,700 79,750 79,750 79,800 79,800 79,850 79,850 79,900 79,900 79,950 79,950 80,000 | 596 0 752 274 597 0 753 275 598 0 754 276 599 0 755 277 600 0 756 278 601 0 757 279 602 0 758 280 603 0 759 281 604 0 760 282 605 0 761 283 605 0 761 284 606 0 762 285 607 0 763 286 608 0 764 287 609 0 765 288 610 0 766 289 611 0 767 290 612 0 768 291 613 0 769 292 614 0 770 293 | 82,000 82,050 82,050 82,100 82,100 82,150 82,150 82,200 82,200 82,250 82,250 82,300 82,300 82,350 82,350 82,400 82,400 82,450 82,450 82,500 82,500 82,550 82,550 82,600 82,600 82,650 82,650 82,700 82,700 82,750 82,750 82,800 82,800 82,850 82,850 82,900 82,900 82,950 82,950 83,000 | 654 20 810 333 655 21 811 334 656 22 812 335 657 23 813 336 658 24 814 337 659 25 815 338 660 26 816 339 661 27 817 340 662 28 818 341 663 29 819 342 664 30 820 343 665 31 821 344 666 32 822 345 667 33 823 346 668 34 824 347 669 35 825 348 670 36 826 349 671 37 827 350 672 38 828 351 673 39 829 351 |
# North Dakota
If your ND
And your filing status is-
And your filing status is- taxable taxable income is- income is-
# Single
# Single Married
At But least less of filing filing least less than house- sepa- jointly * than hold rately Your tax is-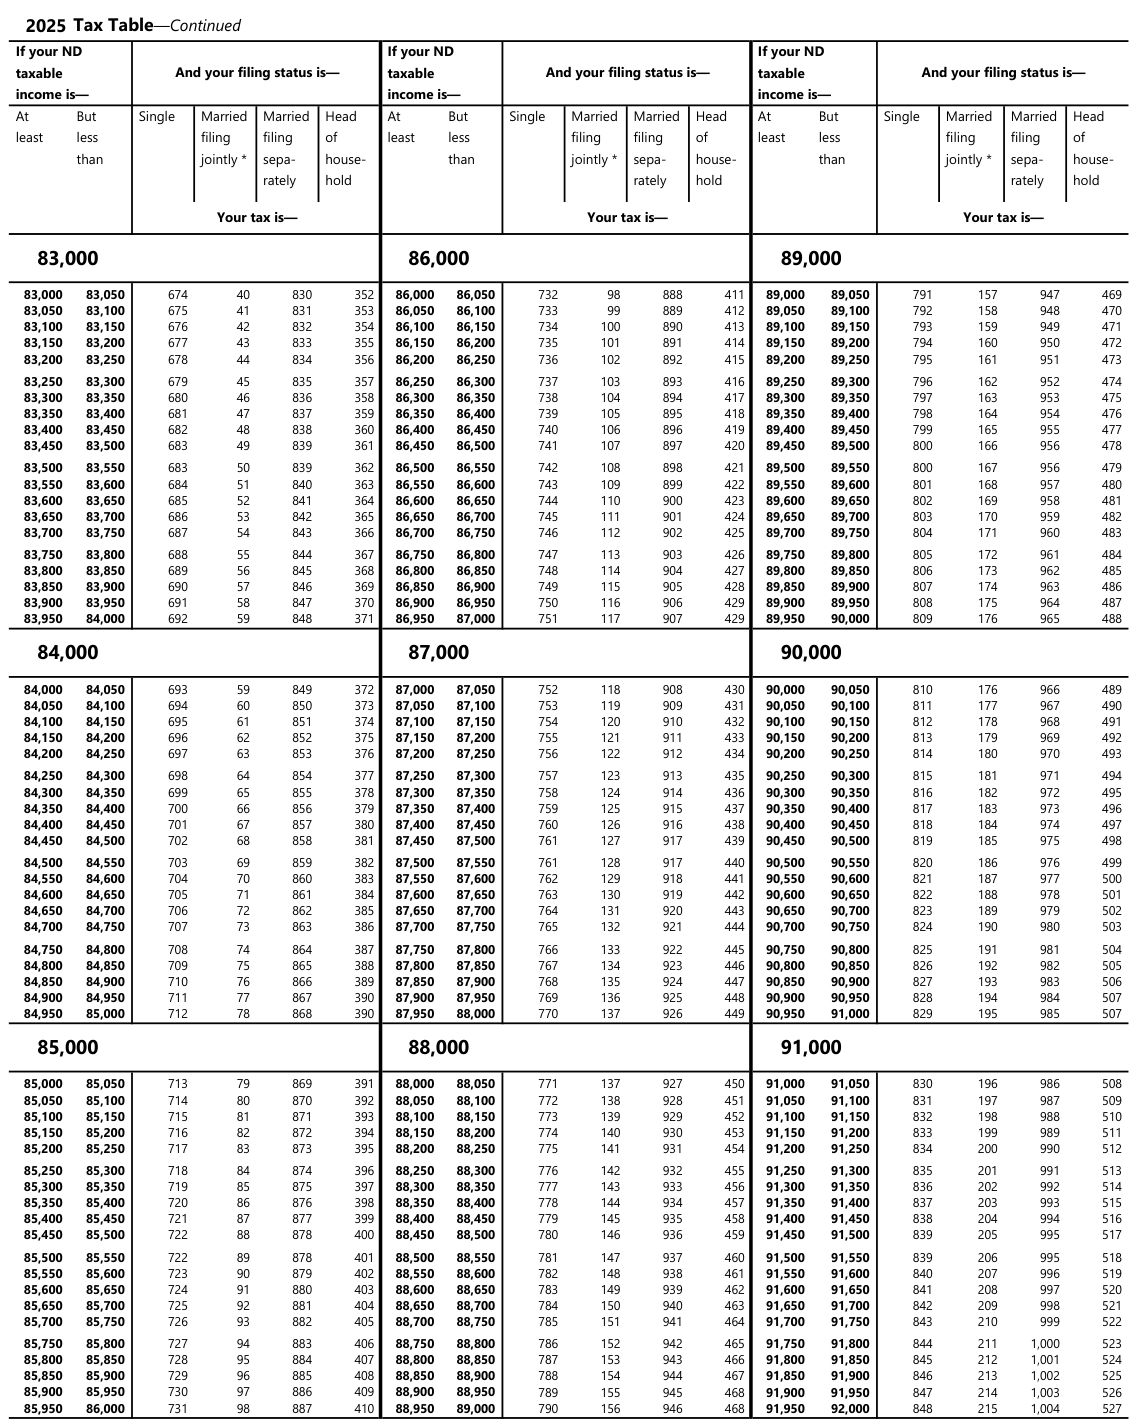
Text version of this table
If your ND taxable income is— And your filing status is— If your ND taxable income is— And your filing status is— If your ND taxable income is— And your filing status is— At But least less than Single Married Married Head filing filing of jointly * sepa- house- rately hold Your tax is— At But least less than Single Married Married Head filing filing of jointly * sepa- house- rately hold Your tax is— At But least less than Single Married Married Head filing filing of jointly * sepa- house- rately hold Your tax is— 83,000 86,000 89,000 83,000 83,050 83,050 83,100 83,100 83,150 83,150 83,200 83,200 83,250 83,250 83,300 83,300 83,350 83,350 83,400 83,400 83,450 83,450 83,500 83,500 83,550 83,550 83,600 83,600 83,650 83,650 83,700 83,700 83,750 83,750 83,800 83,800 83,850 83,850 83,900 83,900 83,950 83,950 84,000 674 40 830 352 675 41 831 353 676 42 832 354 677 43 833 355 678 44 834 356 679 45 835 357 680 46 836 358 681 47 837 359 682 48 838 360 683 49 839 361 683 50 839 362 684 51 840 363 685 52 841 364 686 53 842 365 687 54 843 366 688 55 844 367 689 56 845 368 690 57 846 369 691 58 847 370 692 59 848 371 86,000 86,050 86,050 86,100 86,100 86,150 86,150 86,200 86,200 86,250 86,250 86,300 86,300 86,350 86,350 86,400 86,400 86,450 86,450 86,500 86,500 86,550 86,550 86,600 86,600 86,650 86,650 86,700 86,700 86,750 86,750 86,800 86,800 86,850 86,850 86,900 86,900 86,950 86,950 87,000 732 98 888 411 733 99 889 412 734 100 890 413 735 101 891 414 736 102 892 415 737 103 893 416 738 104 894 417 739 105 895 418 740 106 896 419 741 107 897 420 742 108 898 421 743 109 899 422 744 110 900 423 745 111 901 424 746 112 902 425 747 113 903 426 748 114 904 427 749 115 905 428 750 116 906 429 751 117 907 429 89,000 89,050 89,050 89,100 89,100 89,150 89,150 89,200 89,200 89,250 89,250 89,300 89,300 89,350 89,350 89,400 89,400 89,450 89,450 89,500 89,500 89,550 89,550 89,600 89,600 89,650 89,650 89,700 89,700 89,750 89,750 89,800 89,800 89,850 89,850 89,900 89,900 89,950 89,950 90,000 791 157 947 469 792 158 948 470 793 159 949 471 794 160 950 472 795 161 951 473 796 162 952 474 797 163 953 475 798 164 954 476 799 165 955 477 800 166 956 478 800 167 956 479 801 168 957 480 802 169 958 481 803 170 959 482 804 171 960 483 805 172 961 484 806 173 962 485 807 174 963 486 808 175 964 487 809 176 965 488 84,000 87,000 90,000 84,000 84,050 84,050 84,100 84,100 84,150 84,150 84,200 84,200 84,250 84,250 84,300 84,300 84,350 84,350 84,400 84,400 84,450 84,450 84,500 84,500 84,550 84,550 84,600 84,600 84,650 84,650 84,700 84,700 84,750 84,750 84,800 84,800 84,850 84,850 84,900 84,900 84,950 84,950 85,000 693 59 849 372 694 60 850 373 695 61 851 374 696 62 852 375 697 63 853 376 698 64 854 377 699 65 855 378 700 66 856 379 701 67 857 380 702 68 858 381 703 69 859 382 704 70 860 383 705 71 861 384 706 72 862 385 707 73 863 386 708 74 864 387 709 75 865 388 710 76 866 389 711 77 867 390 712 78 868 390 87,000 87,050 87,050 87,100 87,100 87,150 87,150 87,200 87,200 87,250 87,250 87,300 87,300 87,350 87,350 87,400 87,400 87,450 87,450 87,500 87,500 87,550 87,550 87,600 87,600 87,650 87,650 87,700 87,700 87,750 87,750 87,800 87,800 87,850 87,850 87,900 87,900 87,950 87,950 88,000 752 118 908 430 753 119 909 431 754 120 910 432 755 121 911 433 756 122 912 434 757 123 913 435 758 124 914 436 759 125 915 437 760 126 916 438 761 127 917 439 761 128 917 440 762 129 918 441 763 130 919 442 764 131 920 443 765 132 921 444 766 133 922 445 767 134 923 446 768 135 924 447 769 136 925 448 770 137 926 449 90,000 90,050 90,050 90,100 90,100 90,150 90,150 90,200 90,200 90,250 90,250 90,300 90,300 90,350 90,350 90,400 90,400 90,450 90,450 90,500 90,500 90,550 90,550 90,600 90,600 90,650 90,650 90,700 90,700 90,750 90,750 90,800 90,800 90,850 90,850 90,900 90,900 90,950 90,950 91,000 810 176 966 489 811 177 967 490 812 178 968 491 813 179 969 492 814 180 970 493 815 181 971 494 816 182 972 495 817 183 973 496 818 184 974 497 819 185 975 498 820 186 976 499 821 187 977 500 822 188 978 501 823 189 979 502 824 190 980 503 825 191 981 504 826 192 982 505 827 193 983 506 828 194 984 507 829 195 985 507 85,000 88,000 91,000 85,000 85,050 85,050 85,100 85,100 85,150 85,150 85,200 85,200 85,250 85,250 85,300 85,300 85,350 85,350 85,400 85,400 85,450 85,450 85,500 85,500 85,550 85,550 85,600 85,600 85,650 85,650 85,700 85,700 85,750 85,750 85,800 85,800 85,850 85,850 85,900 85,900 85,950 85,950 86,000 713 79 869 714 80 870 715 81 871 716 82 872 717 83 873 718 84 874 719 85 875 720 86 876 721 87 877 722 88 878 722 89 878 723 90 879 724 91 880 725 92 881 726 93 882 727 94 883 728 95 884 729 96 885 730 97 886 731 98 887 391 392 393 394 395 396 397 398 399 400 401 402 403 404 405 406 407 408 409 410 88,000 88,050 88,050 88,100 88,100 88,150 88,150 88,200 88,200 88,250 88,250 88,300 88,300 88,350 88,350 88,400 88,400 88,450 88,450 88,500 88,500 88,550 88,550 88,600 88,600 88,650 88,650 88,700 88,700 88,750 88,750 88,800 88,800 88,850 88,850 88,900 88,900 88,950 88,950 89,000 771 137 927 450 772 138 928 451 773 139 929 452 774 140 930 453 775 141 931 454 776 142 932 455 777 143 933 456 778 144 934 457 779 145 935 458 780 146 936 459 781 147 937 460 782 148 938 461 783 149 939 462 784 150 940 463 785 151 941 464 786 152 942 465 787 153 943 466 788 154 944 467 789 155 945 468 790 156 946 468 91,000 91,050 91,050 91,100 91,100 91,150 91,150 91,200 91,200 91,250 91,250 91,300 91,300 91,350 91,350 91,400 91,400 91,450 91,450 91,500 91,500 91,550 91,550 91,600 91,600 91,650 91,650 91,700 91,700 91,750 91,750 91,800 91,800 91,850 91,850 91,900 91,900 91,950 91,950 92,000 830 196 986 508 831 197 987 509 832 198 988 510 833 199 989 511 834 200 990 512 835 201 991 513 836 202 992 514 837 203 993 515 838 204 994 516 839 205 995 517 839 206 995 518 840 207 996 519 841 208 997 520 842 209 998 521 843 210 999 522 844 211 1,000 523 845 212 1,001 524 846 213 1,002 525 847 214 1,003 526 848 215 1,004 527
# At But
If your ND If your ND
And your filing status is-
If your ND
And your filing status is- taxable taxable income is- income is-
# Head At But Single
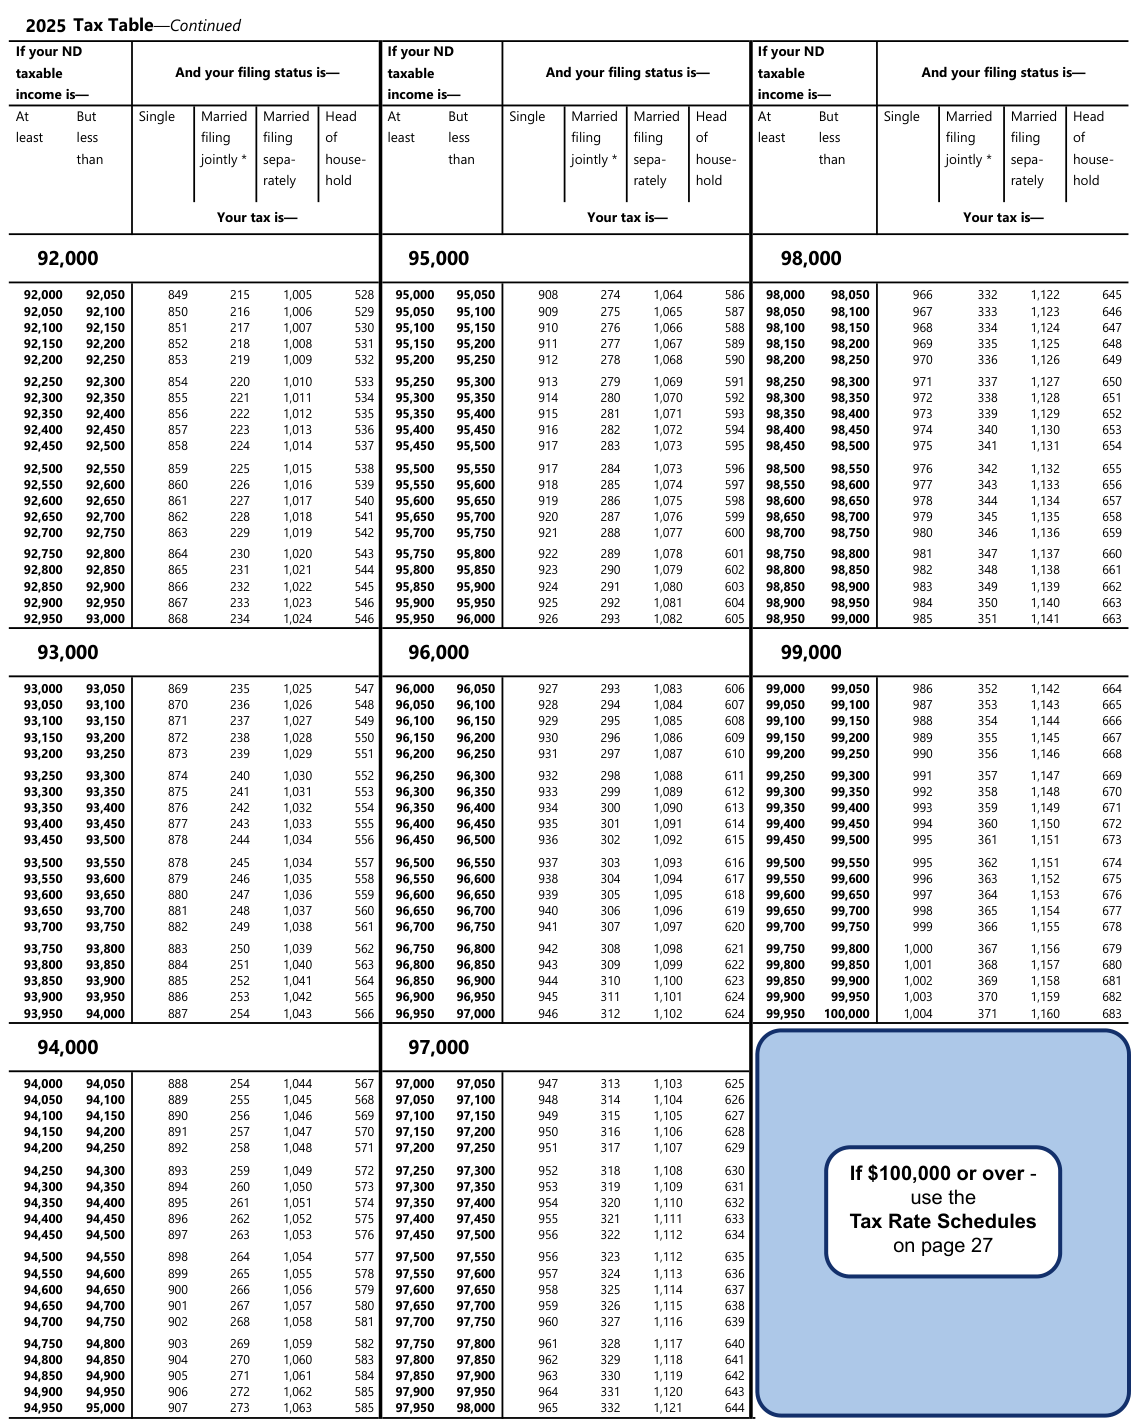
Text version of this table
If your ND taxable income is— And your filing status is— If your ND taxable income is— And your filing status is— If your ND taxable income is— And your filing status is— At But least less than Single Married Married Head filing filing of jointly * sepa- house- rately hold Your tax is— At But least less than Single Married Married Head filing filing of jointly * sepa- house- rately hold Your tax is— At But least less than Single Married Married Head filing filing of jointly * sepa- house- rately hold Your tax is— 92,000 95,000 98,000 92,000 92,050 92,050 92,100 92,100 92,150 92,150 92,200 92,200 92,250 92,250 92,300 92,300 92,350 92,350 92,400 92,400 92,450 92,450 92,500 92,500 92,550 92,550 92,600 92,600 92,650 92,650 92,700 92,700 92,750 92,750 92,800 92,800 92,850 92,850 92,900 92,900 92,950 92,950 93,000 849 215 1,005 528 850 216 1,006 529 851 217 1,007 530 852 218 1,008 531 853 219 1,009 532 854 220 1,010 533 855 221 1,011 534 856 222 1,012 535 857 223 1,013 536 858 224 1,014 537 859 225 1,015 538 860 226 1,016 539 861 227 1,017 540 862 228 1,018 541 863 229 1,019 542 864 230 1,020 543 865 231 1,021 544 866 232 1,022 545 867 233 1,023 546 868 234 1,024 546 95,000 95,050 95,050 95,100 95,100 95,150 95,150 95,200 95,200 95,250 95,250 95,300 95,300 95,350 95,350 95,400 95,400 95,450 95,450 95,500 95,500 95,550 95,550 95,600 95,600 95,650 95,650 95,700 95,700 95,750 95,750 95,800 95,800 95,850 95,850 95,900 95,900 95,950 95,950 96,000 908 274 1,064 586 909 275 1,065 587 910 276 1,066 588 911 277 1,067 589 912 278 1,068 590 913 279 1,069 591 914 280 1,070 592 915 281 1,071 593 916 282 1,072 594 917 283 1,073 595 917 284 1,073 596 918 285 1,074 597 919 286 1,075 598 920 287 1,076 599 921 288 1,077 600 922 289 1,078 601 923 290 1,079 602 924 291 1,080 603 925 292 1,081 604 926 293 1,082 605 98,000 98,050 98,050 98,100 98,100 98,150 98,150 98,200 98,200 98,250 98,250 98,300 98,300 98,350 98,350 98,400 98,400 98,450 98,450 98,500 98,500 98,550 98,550 98,600 98,600 98,650 98,650 98,700 98,700 98,750 98,750 98,800 98,800 98,850 98,850 98,900 98,900 98,950 98,950 99,000 966 332 1,122 645 967 333 1,123 646 968 334 1,124 647 969 335 1,125 648 970 336 1,126 649 971 337 1,127 650 972 338 1,128 651 973 339 1,129 652 974 340 1,130 653 975 341 1,131 654 976 342 1,132 655 977 343 1,133 656 978 344 1,134 657 979 345 1,135 658 980 346 1,136 659 981 347 1,137 660 982 348 1,138 661 983 349 1,139 662 984 350 1,140 663 985 351 1,141 663 93,000 96,000 99,000 93,000 93,050 93,050 93,100 93,100 93,150 93,150 93,200 93,200 93,250 93,250 93,300 93,300 93,350 93,350 93,400 93,400 93,450 93,450 93,500 93,500 93,550 93,550 93,600 93,600 93,650 93,650 93,700 93,700 93,750 93,750 93,800 93,800 93,850 93,850 93,900 93,900 93,950 93,950 94,000 869 235 1,025 547 870 236 1,026 548 871 237 1,027 549 872 238 1,028 550 873 239 1,029 551 874 240 1,030 552 875 241 1,031 553 876 242 1,032 554 877 243 1,033 555 878 244 1,034 556 878 245 1,034 557 879 246 1,035 558 880 247 1,036 559 881 248 1,037 560 882 249 1,038 561 883 250 1,039 562 884 251 1,040 563 885 252 1,041 564 886 253 1,042 565 887 254 1,043 566 96,000 96,050 96,050 96,100 96,100 96,150 96,150 96,200 96,200 96,250 96,250 96,300 96,300 96,350 96,350 96,400 96,400 96,450 96,450 96,500 96,500 96,550 96,550 96,600 96,600 96,650 96,650 96,700 96,700 96,750 96,750 96,800 96,800 96,850 96,850 96,900 96,900 96,950 96,950 97,000 927 293 1,083 606 928 294 1,084 607 929 295 1,085 608 930 296 1,086 609 931 297 1,087 610 932 298 1,088 611 933 299 1,089 612 934 300 1,090 613 935 301 1,091 614 936 302 1,092 615 937 303 1,093 616 938 304 1,094 617 939 305 1,095 618 940 306 1,096 619 941 307 1,097 620 942 308 1,098 621 943 309 1,099 622 944 310 1,100 623 945 311 1,101 624 946 312 1,102 624 99,000 99,050 99,050 99,100 99,100 99,150 99,150 99,200 99,200 99,250 99,250 99,300 99,300 99,350 99,350 99,400 99,400 99,450 99,450 99,500 99,500 99,550 99,550 99,600 99,600 99,650 99,650 99,700 99,700 99,750 99,750 99,800 99,800 99,850 99,850 99,900 99,900 99,950 99,950 100,000 986 352 1,142 664 987 353 1,143 665 988 354 1,144 666 989 355 1,145 667 990 356 1,146 668 991 357 1,147 669 992 358 1,148 670 993 359 1,149 671 994 360 1,150 672 995 361 1,151 673 995 362 1,151 674 996 363 1,152 675 997 364 1,153 676 998 365 1,154 677 999 366 1,155 678 1,000 367 1,156 679 1,001 368 1,157 680 1,002 369 1,158 681 1,003 370 1,159 682 1,004 371 1,160 683 94,000 97,000 IfI $f 1$0100,000,00 0o0r o ovrer - over — use the use the Tax Rate Schedules Tax Rate Schedules on page 27 on page 32 94,000 94,050 94,050 94,100 94,100 94,150 94,150 94,200 94,200 94,250 94,250 94,300 94,300 94,350 94,350 94,400 94,400 94,450 94,450 94,500 94,500 94,550 94,550 94,600 94,600 94,650 94,650 94,700 94,700 94,750 94,750 94,800 94,800 94,850 94,850 94,900 94,900 94,950 94,950 95,000 888 254 1,044 889 255 1,045 890 256 1,046 891 257 1,047 892 258 1,048 893 259 1,049 894 260 1,050 895 261 1,051 896 262 1,052 897 263 1,053 898 264 1,054 899 265 1,055 900 266 1,056 901 267 1,057 902 268 1,058 903 269 1,059 904 270 1,060 905 271 1,061 906 272 1,062 907 273 1,063 567 568 569 570 571 572 573 574 575 576 577 578 579 580 581 582 583 584 585 585 97,000 97,050 97,050 97,100 97,100 97,150 97,150 97,200 97,200 97,250 97,250 97,300 97,300 97,350 97,350 97,400 97,400 97,450 97,450 97,500 97,500 97,550 97,550 97,600 97,600 97,650 97,650 97,700 97,700 97,750 97,750 97,800 97,800 97,850 97,850 97,900 97,900 97,950 97,950 98,000 947 313 1,103 625 948 314 1,104 626 949 315 1,105 627 950 316 1,106 628 951 317 1,107 629 952 318 1,108 630 953 319 1,109 631 954 320 1,110 632 955 321 1,111 633 956 322 1,112 634 956 323 1,112 635 957 324 1,113 636 958 325 1,114 637 959 326 1,115 638 960 327 1,116 639 961 328 1,117 640 962 329 1,118 641 963 330 1,119 642 964 331 1,120 643 965 332 1,121 644
And your filing status is- taxable income is-
# At But Single Married Married Head
# 2025 Tax Rate Schedules
If your North Dakota taxable income is $100,000 or more, use the tax rate schedule below for your filing status to calculate your tax.
taxable income is:
Over But Not Over
Your tax is equal to:
$ 0 $ 48,475 … 0.00% of North Dakota taxable income 48,475 244,825 … $ 0.00 + 1.95% of amount over $ 48,475 244,825 … 3,828.83 + 2.50% of amount over 244,825
taxable income is:
Over But Not Over
Your tax is equal to:
$ 0 $ 80,975 … 0.00% of North Dakota taxable income 80,975 298,075 … $ 0.00 + 1.95% of amount over $ 80.975 298,075 … 4,233.45 + 2.50% of amount over 298,075
taxable income is:
Over But Not Over
Your tax is equal to:
$ 0 $ 40,475 … 0.00% of North Dakota taxable income 40,475 149,025 … $ 0.00 + 1.95% of amount over $ 40,475 149,025 … 2,116.73 + 2.50% of amount over 149,025
taxable income is:
Over But Not Over
Your tax is equal to:
$ 0 $ 64,950 … 0.00% of North Dakota taxable income 64,950 271,450 … $ 0.00 + 1.95% of amount over $ 64,950 271,450 … 4,026.75 + 2.50% of amount over 271,450
# How to assemble your return and avoid the most common filing problems
If filing Form ND-EZ, assemble your documents in the following order:
- Form ND-EZ
- All Form W-2s, and any Form 1099 and North Dakota Schedule K-1 showing North Dakota income tax withheld
- Copy of federal income tax return Leave documents loose in envelope; do not staple them.
If filing Form ND-1, assemble your documents in the following order:
- All Form W-2's, and any
- Form ND-1
Form 1099 and North Dakota
- Schedule ND-1NR
Schedule K-1 showing
- Schedule ND-1FA
North Dakota income tax withheld
- Schedule ND-1CR
- Copy of federal income tax return
- Schedule ND-1SA
- Supporting schedules required in
- Schedule ND-1TC instructions
- All other required North Dakota schedules and forms Leave documents loose in envelope; do not staple them.
Mail to:
Office of State Tax Commissioner PO Box 5621 Bismarck, ND 58506-5621 Two main reasons returns are sent back to taxpayers-
- Reason 1: Return is not signed.
- Reason 2: Copy of federal return is not enclosed.
The return is incomplete if unsigned or missing a copy of the federal return and will be sent back to you. This could result in late filing or payment charges.
Before sealing the envelope, have you done the following:
- Signed the return
- Enclosed complete copy of federal return
- Made a copy for your records
- Enclosed your check or money order payable to "North Dakota Office of State Tax Commissioner" along with a Form ND-1PRV
- Affixed adequate postage to envelope Need help with your federal return? The following information is provided as a convenience should you have any federal income tax questions.
# IRS internet (online) services
# IRS tax service
Service is available by appointment only.
Go to IRS's website at irs.gov to obtain tax forms and publications, check the Call 1-844-545-5640 to schedule an latest tax news, and access online tools that help you check on your refund or find answers to your federal tax questions.
Download the free IRS2Go app from Apple Apps Store or Google Play to:
Subscribe to filing season
Check status of federal tax updates or daily tax tips refund Connect with the IRS on Request transcript of tax return Facebook, X, Instagram, and or account information LinkedIn Find an IRS VITA or TCE Watch helpful videos on volunteer help site YouTube Get up-to-date IRS news Contact IRS.
# IRS telephone assistance
appointment. In North Dakota, IRS tax services are available at the following locations:
Bismarck
4503 N. Coleman Street
Suite 101
Fargo
Federal Building
657 2nd Avenue N.
Grand Forks
Federal Building
102 N. 4th Street
Federal tax questions … 1-800-829-1040
Minot
TTY/TDD for speech or hearing impaired persons … 1-800-829-4059 Federal Building
Location of nearest VITA or TCE volunteer help site … 1-800-906-9887 Suite 101
100 1st Street SW
# Do you need any forms?
Download and print the forms you need from our website: tax.nd.gov Or use this form to order any forms you need. Fill in the circle for each form that you want. You will receive two copies of each item you order.
2026 Form ND-1ES, Estimated income tax-individuals Form 101, Extension of time to file a North Dakota tax return Form ND-EZ, Individual income tax form (Short form) Form ND-1, Individual income tax form (Long form) Form ND-1EXT, Individual extension payment Form ND-1PRV, Paper return payment voucher Schedule ND-1AC, Adoption credit Schedule ND-1CR, Credit for income tax paid to another state or local jurisdiction Schedule ECC, Employer child care contribution credit Schedule ND-1FA, Tax under 3-year averaging method for elected farm income Schedule ND-1FC, Family member care tax credit Schedule MCP, Contributions to a Maternity Home, Child Placing Agency, Or Pregnancy Help Center Schedule ME, Credit for wages paid to mobilized employee Schedule ND-1NR, Tax calculation for nonresidents and part-year residents Schedule ND-1PG, Planned gift tax credit Schedule ND-1PSC, Nonprofit private school tax credits for individuals Schedule ND-1QEC, Qualified endowment fund tax credit Schedule RZ, Renaissance zone income exemption and tax credits Schedule ND-1SA, Statutory adjustments Schedule ND-1TC, Tax credits Schedule ND-1UT, Underpayment or late payment of estimated tax One time (use tax) remittance form [For individuals who buy goods from out-of-state retailers and pay less sales tax than North Dakota charges]
Claim for refund - Local sales and use tax paid beyond maximum tax [For individuals who paid local sales or use tax in excess of the maximum due]
Complete and mail to:
Attn: 2025 Forms Order
ND Office of State Tax Commissioner 600 E. Boulevard Ave. Dept. 127 Bismarck, ND 58505-0599 Name
Address
City State ZIP code
# Need assistance?
Website-tax.nd.gov
Email-Send your questions to
# individualtax@nd.gov
Call
Monday - Friday, 8 a.m. to 5 p.m. (Central Time) Toll free (in North Dakota): 1-877-328-7088 In the Bismarck-Mandan area, or from outside North Dakota:
For questions: 701-328-1247
For forms: 701-328-1243
If speech or hearing impaired, call Relay North Dakota at 1-800-366-6888 (and ask for 1-877-328-7088)
Mail
Individual Income Tax Section
Office of State Tax Commissioner 600 E. Boulevard Ave. Dept. 127 Bismarck, ND 58505-0599 Fax-Fax us at 1-701-328-1942 Walk-in or appointment service Walk-in or appointment service is available Monday through Friday, from 8:00 a.m. to 5:00 p.m., in our Bismarck office located in the State Capitol Building, 8th floor, at 600 E.
Boulevard Avenue. To assure availability and promptness of service, call in advance to make an appointment.
# Check refund status
To check the status of your refund, go to tax.nd.gov/refund and select "Refund?"
If you direct deposit your refund, first check with your bank to see if it has been deposited into your account. Refunds on electronically filed returns are generally issued within 7 business days or can take up to 6 weeks to process on paper returns.
# Request copy of return
To obtain a copy of your North Dakota individual income tax return, go to tax.nd.gov/individual-income-tax and select "Need a Copy of a Return".
Or submit a written request by mail or fax containing the following:
- Your name and current address
- Your social security number
- Tax year
- Description of information requested
- Your signature
- Daytime telephone number
Source: view the official PDF
The source document contains 11 figures (charts or worksheet graphics) not reproduced in this text version. See the official PDF above.
Nearby sections (25 sections)
- corp-income-tax-booklet · ND Corporate Income Tax Booklet — Form 40
- corp-income-tax-credits-booklet · ND Corporate Income Tax Credits…
- disabled-veterans-property-tax-credit · Application for Disabled…
- fiduciary-income-tax-booklet · ND Fiduciary Income Tax Booklet — Form 38
- form-301-ef · Form 301-EF — Annual Withholding Reconciliation
- form-38-es · Form 38-ES — Fiduciary Estimated Income Tax
- form-40-es · Form 40-ES — Corporate Estimated Income Tax
- form-58-es · Form 58-ES — Partnership Estimated Tax (PTE estimated)
- form-60-es · Form 60-ES — S Corporation Estimated Tax (PTE estimated)
- form-nd-1 · Form ND-1 — Individual Income Tax Return
- form-nd-1es · Form ND-1ES — Individual Estimated Income Tax
- form-ndw-m · Form NDW-M — Withholding Allowance Certificate for…
- individual-income-tax-booklet · ND Individual Income Tax Booklet — Form…
- partnership-income-tax-booklet · ND Partnership Income Tax Booklet —…
- property-tax-exemption · Application for Property Tax Exemption
- s-corp-income-tax-booklet · ND S Corporation Income Tax Booklet — Form…
- sales-tax-exemption-cert · Application for Sales Tax Exemption…
- schedule-nd-1fa · Schedule ND-1FA — Farm Income Averaging
- schedule-nd-1nr · Schedule ND-1NR — Nonresident and Part-Year Resident
- schedule-nd-1pg · Schedule ND-1PG — Planned Gift Income Tax Credit
- schedule-nd-1sa · Schedule ND-1SA — Statutory Adjustments
- schedule-nd-1ut · Schedule ND-1UT — Individual Use Tax
- schedule-nd-cr · Schedule ND-CR — Credit for Income Tax Paid to Another…
- schedule-rz-booklet · ND Schedule RZ — Renaissance Zone Credit Booklet
- withholding-rates-booklet · ND Income Tax Withholding Rates and…
# Social security numbers
Enter your social security number. If married filing jointly, also enter your spouse's social security number.
Item A - Filing status
Fill in the circle next to the filing status that you used on your 2024 Form 1040 or 1040-SR.
Item B - School district code
Select the code number from the list of school district codes on page 19.
Item C - Income source code
Select from the following list the code number corresponding to the area from which you derived the majority of your North Dakota sourced income for the tax year.
Construction … 6
Manufacturing … 7
Transportation, communication, and public utilities … 8 Exploration, development, and extraction of coal, oil, and natural gas … 9 Banking, insurance, real estate, and other financial services … 10 Military service … 11 Retirement (Pensions, annuities, IRAs, etc.) … 12 Item D - Extension Fill in the circle next to "Extension" only if you have an extension to file your North Dakota return. See "Extension of time to file" on page 7.
Instructions for lines 1-9 of