Minnesota Department of Revenue Form Instructions
Instructions for Form M1 — Individual Income Tax (2025)
# Income Tax
Forms and Instructions
# > Form M1
Minnesota Individual Income Tax Return
# > Schedule M1W
Minnesota Income Tax Withheld
# > Schedule M1MA
Marriage Credit
# > Schedule M1CWFC
Minnesota Child and Working Family Credits
# > Schedule M1C
Nonrefundable Credits
# > Schedule M1RENT
Renter's Credit
# > Schedule M1M
Income Additions and Subtractions
Text version of this table
To file el www.rev Go to www.revenue.state.mn.us to: • File and pay electronically • Get forms, instructions, and fact sheets • Get answers to your questions • Check on your refund • Get Form 1099-G refund information Call our automated system at 651-296-4444 or 1-800-657-3676 to: • Check on your refund • Get Form 1099-G refund information Questions? • Email at individual.incometax@state.mn. • Call 651-296-3781 or 1-800-652-9094 • Write to: Minnesota Department of Revenue Mail Station 5510 600 N. Robert St. St. Paul, MN 55146-5510 ectronically, go to enue.state.mn.us Inside This Booklet What’s New for 2025 . . . . . . . . . . . . . . . . . . . . . . 3-4 Information for Federal Return . . . . . . . . . . . . . . . .5 Use Tax Information . . . . . . . . . . . . . . . . . . . . . . . . .5 Filing Requirements/Residency . . . . . . . . . . . . . . 6-8 Getting Started . . . . . . . . . . . . . . . . . . . . . . . . . . . . .9 Filing Instructions . . . . . . . . . . . . . . . . . . . . . . . . . 10 Use of Information . . . . . . . . . . . . . . . . . . . . . . . . 10 Line Instructions . . . . . . . . . . . . . . . . . . . . . . . .11-21 Payment Options . . . . . . . . . . . . . . . . . . . . . . . . . 22 Penalty and Interest . . . . . . . . . . . . . . . . . . . . .22-23 us Other Information . . . . . . . . . . . . . . . . . . . . . . .24-25 Military Personnel . . . . . . . . . . . . . . . . . . . . . . . . . 26 Renter’s Credit Table . . . . . . . . . . . . . . . . . . . .27-31 Tax Tables . . . . . . . . . . . . . . . . . . . . . . . . . . . . .32-38 Tax Rate Schedules . . . . . . . . . . . . . . . . . . . . . . . . 39 How to Get Forms . . . . . . . . . . . . . . . . . . . . . . . . . 39 Where’s My Refund? We review every return to verify the information difef rent, so processing time will vary. To check yo My Refund into the Search box. With this system • See if we’ve received your return • Follow your return through the process • Understand the steps your return goes throug • See the actual date your refund was sent When you use Where’s My Refund, we ask for yo refund. and make sure the right refund goes to the right person. Each return is ur refund status, go to www.revenue.state.mn.us and type Where’s , you can: h before a refund is sent ur Social Security number, date of birth, and the exact amount of your Free Tax Help Free tax preparation is available from IRS-certifie older, with a disability, with annual income less t To find a volunteer tax preparation site: • Go to www.revenue.state.mn.us and enter F • Call 651-297-3724 or 1-800-657-3989 d volunteers at locations across Minnesota to assist individuals 60 or han $67,000, or speaking limited or no English. ree Tax Preparation into the Search box Note: If you need assistance in a language other interpreter services. Nota: Si usted necesita asistencia en un idioma q servicios de intérprete gratuitos. than English, call us at 651-296-3781 or 1-800-652-9094 for free ue no sea inglés, llámenos al 651-296-3781 o al 1-800-652-9094 para
# Inside This Booklet
- File and pay electronically
- Get forms, instructions, and fact sheets
- Get answers to your questions
- Check on your refund
- Get Form 1099-G refund information
- Check on your refund
- Get Form 1099-G refund information
# Questions?
- Email at individual.incometax@state.mn.us
- Call 651-296-3781 or 1-800-652-9094
- Write to:
# Minnesota Department of Revenue
Mail Station 5510
600 N. Robert St.
St. Paul, MN 55146-5510
Where's My Refund?
We review every return to verify the information and make sure the right refund goes to the right person. Each return is different, so processing time will vary. To check your refund status, go to www.revenue.state.mn.us and type Where's
My Refund into the Search box. With this system, you can:
- See if we've received your return
- Follow your return through the process
- Understand the steps your return goes through before a refund is sent
- See the actual date your refund was sent
When you use Where's My Refund, we ask for your Social Security number, date of birth, and the exact amount of your refund.
# Free Tax Help
- Go to www.revenue.state.mn.us and enter Free Tax Preparation into the Search box
- Call 651-297-3724 or 1-800-657-3989
Note: If you need assistance in a language other than English, call us at 651-296-3781 or 1-800-652-9094 for free interpreter services.
Nota: Si usted necesita asistencia en un idioma que no sea inglés, llámenos al 651-296-3781 o al 1-800-652-9094 para servicios de intérprete gratuitos.
Lub Ceeb Toom: Yog tias koj xav tau kev pab lwm hom lus uas tsis yog lus Askiv, hu rau peb ntawm 651-296-3781 lossis 1-800-652-9094 kom tau txais kev pa txhais lus dawb.
Xasuusin: Haddii aad caawimo ugu baahantahay luqad aan Ingiriisi ahayn, naga soo wac 651-296-3781 ama 1-800-652-9094 si aad u hesho adeegyo turjubaan bilaash ah.
Cover image: Deborah Rose, Minnesota Department of Natural Resources
What's new for 2025?
# Advance Payment of Child Tax Credit
Taxpayers may make an election to receive advance payments of their 2026 Child Tax Credit. You must be eligible for a 2025 child tax credit to receive advance payments for 2026. See Schedule M1CWFC, Minnesota Child and Working Family Credits, for more information on how to determine your eligibility for the credit and how to elect to receive advance payments.
# Reconciliation of Advance Payments of Child Tax Credit
Beginning with tax year 2025, taxpayers who made an election to receive advance payments of their 2025 Child Tax Credit on their 2024 income tax return, must file a 2025 Minnesota income tax return. You must file a Minnesota income tax return even if you are not otherwise required to file a return. Your 2025 refund will be reduced, or your tax liability will be increased by the amount of advance payments you are required to include on your 2025 return. See Schedule M1CWFC for more information.
# Coerced Debt Subtraction
If debt was incurred in your name, the debt was subsequently discharged by a court, and the court determined the discharged amount to be coerced debt, you are eligible to take a subtraction on Schedule M1M, Income Additions and Subtractions for the debt that was discharged and included in federal adjusted gross income.
# Consumer enforcement public compensation subtraction
If you received consumer enforcement public compensation from the consumer protection restitution account after being harmed by certain unlawful behaviors of others as determined by a court order, you may take the amount received as a subtraction on Schedule M1M, Income Additions and Subtractions to the extent it is included in federal adjusted gross income.
# Foreign service retirement subtraction
If you received a pension for foreign service, a portion of the amount of your federal pension compensation or other retirement pay received for foreign service may be taken as a subtraction on Schedule M1M, Income Additions and Subtractions.
Service Employees International Union (SEIU) stipend payment subtraction
If you are a member of SEIU and received stipend payments, you may be eligible to subtract the amount of federally taxable stipend payments you received from the Minnesota Department of Human Services on or after June 15, 2025, per a collective bargaining agreement between the Service Employees International Union (SEIU) Healthcare Minnesota & Iowa and the State of Minnesota.
Review the instructions for Schedule M1M for more information.
# Federal tax law enacted since May 1, 2023
Rules used to determine Minnesota Individual Income Tax are generally based on the Internal Revenue Code (IRC) as amended through May 1, 2023, with certain exceptions. Since that date Congress has enacted H.R. 1 of 2025. If you are affected by any of the provisions included on Schedule M1NC, Federal Adjustments, complete Schedule M1NC to make the necessary adjustments when you file Form M1.
What's new for 2025? (cont.)
# Standard Deduction
The standard deduction increased for each filing status. Determine your standard deduction on page 11. These are the standard deduction amounts determined for your filing status:
- $14,950 for Single
- $29,900 for Married Filing Jointly or Qualifying Surviving Spouse
- $14,950 for Married Filing Separately
- $22,500 for Head of Household
If you are married and filing a separate return, you may only claim the standard deduction if your spouse did not itemize deductions.
If you can be claimed as a dependent on another person's tax return, see the instructions for line 4 to determine your standard deduction amount.
The standard deduction is reduced by up to 80% if your adjusted gross income exceeds $238,950 ($119,475 if you are married and filing a separate return). If your adjusted gross income is equal to or more than $1,083,150, your standard deduction is reduced by 80%.
You may not claim the standard deduction if either of these apply:
- You are filing a return for a period of less than twelve months due to changes in the annual account period
- You are a nonresident alien of the United States
- An exception applies if you claim the standard deduction under a U.S. income tax treaty
# Itemized Deductions
Minnesota itemized deductions are reported on Schedule M1SA, Minnesota Itemized Deductions. For more information, see page 12.
You may itemize deductions on your Minnesota income tax return even if you claimed the standard deduction on your federal income tax return. Your itemized deductions are reduced if your adjusted gross income exceeds $238,950 ($119,475 if you are married and filing a separate return). If your adjusted gross income exceeds $1,083,150, you are limited to 20% of your itemized deductions.
# Dependent Exemptions
The dependent exemption amount is $5,200 for each qualifying dependent in 2025. Your total exemption amount is reduced if your income exceeds certain amounts based on your filing status:
- $358,550 for Married Filing Jointly or Qualifying Surviving Spouse
- $298,800 for Head of Household
- $239,050 for Single
- $179,275 for Married Filing Separately
See Schedule M1DQC, Dependents and Qualifying Children, to determine who qualifies. Use the worksheet for line 5 of the M1 to determine how much you can deduct. Enter information on dependents on Schedule M1DQC and provide a copy of the schedule with Form M1.
# CRP System Update for Property Owners/Managing Agents
All residential property owners and managers can use e-Services to create and manage Certificates of Rent Paid (CRPs) for Minnesota properties. There is no cost to use this service.
Beginning with rent paid in 2024, property owners and managing agents are required to use e-Services to create CRPs for their renters.
After creating a username, when you log in to e-Services you can import your data from a spreadsheet or use a step-by-step process to enter your data.
For more information, go to www.revenue.state.mn.us and enter CRP into the Search box.
# State Refund Information—Line 1 of Federal Schedule 1
If you received a state income tax refund in 2025 and you itemized deductions on your 2024 federal Form 1040, you may need to report an amount on line 1 of your 2025 federal Schedule 1. For details, see the Form 1040 instructions.
To find out how much your Minnesota income tax refund was:
- Review your records
- Use our 1099-G Refund System (go to www.revenue.state.mn.us and enter 1099-G into the Search box)
- Call 651-296-4444 or 1-800-652-9094
# Deducting Real Estate Taxes—Federal Schedule A (Line 5b)
You are allowed a tax deduction on federal Schedule A for real estate taxes you paid in 2025. If you received a property tax refund for these taxes on a 2024 Form M1PR, Homestead Credit Refund, subtract that refund amount from your property taxes paid when calculating your deduction on Schedule A.
# Deducting Vehicle License Fees—Federal Schedule A (Line 5c)
You may deduct part of your Minnesota vehicle license fee as personal property tax on line 5c of federal Schedule A. Other amounts, such as the plate fee and filing fee, are not deductible and cannot be used as an itemized deduction.
Calculate the allowed deduction by subtracting $30 from your vehicle's registration tax for each vehicle you register. To find the registration tax:
- Go to dps.mn.gov/divisions/dvs/vehicle/vehicle-registration
- Look at the vehicle registration renewal form issued by Driver & Vehicle Services
# Did you purchase items over the internet or through the mail?
If you purchased taxable items for personal use and did not pay Minnesota Sales Tax, you may owe Use Tax. Generally, Use Tax is the same rate as the state Sales Tax. If you live in a local tax area, include the Use Tax that is applicable to your local Use Tax.
You may owe Use Tax if you purchase taxable items:
- Over the internet, by mail order, etc., and the seller does not collect Minnesota Sales Tax from you.
- In a state or country that does not collect Minnesota Sales Tax from you.
- From an out-of-state seller who properly collects another state's Sales Tax at a rate lower than Minnesota's Sales Tax. (In this case, you owe the difference between the two rates).
Add all of your taxable purchases. If they total more than $770, file Form UT1, Individual Use Tax Return, by April 15, 2026, for all taxable items you purchased during the calendar year. If your total purchases for personal use are less than $770, you do not have to file and pay Use Tax.
To file online, go to www.revenue.state.mn.us and enter Individual Use Tax into the Search box. Then, select Individual Use Tax
Return Online Filing System. Follow the prompts to file your return.
Form UT1 and Sales Tax Fact Sheet 156 are available on our website or by calling 651-296-6181 or 1-800-657-3777.
# Local Use Taxes
If you buy taxable items for use in the cities and counties listed in Sales Tax Fact Sheet 164, you must also pay local Use Tax at the rates listed.
# Am I required to file a Minnesota Individual Income Tax return?
Yes, if any of these apply:
- You were a Minnesota resident for the entire year in 2025 and your income was more than the amount in the chart below for your filing status
- You were a part-year or nonresident and meet the requirements under Filing Requirements for Part-Year Residents and
# Nonresidents
- You elected to receive advance payments of your 2025 Child Tax Credit on your 2024 return
- You qualify for and want to claim refundable credits
- You were a nonresident alien of the United States, had income assignable to Minnesota, and were required to file a federal return For more information regarding filing requirements and residency, go to www.revenue.state.mn.us
# Minnesota Residents
File a 2025 Minnesota income tax return if your income is more than the amount that applies to you in the chart below.
You are a Minnesota resident if either of these apply:
- Minnesota was your permanent home in 2025
- Minnesota was your home for an indefinite period of time and you maintained an abode (house, townhouse, condominium, apartment, mobile home, or cabin, with cooking and bathing facilities, that could be lived in year-round) in Minnesota For more information, see Income Tax Fact Sheet 1, Residency.
Residents Who Are Not a Dependent
If you were a Minnesota resident for all of 2025 and required to file a federal income tax return, you are required to file a Minnesota income tax return. If you are age 65 or older, your income and lifestyle changes may affect your Minnesota income taxes. See Fact Sheet 6, Seniors, for more information.
Residents Who Are a Dependent
If your parent (or someone else) can claim you as a dependent, use the Worksheet for Line 4 — Dependent Standard Deduction to determine your filing requirement. If your gross income is greater than the amount of your standard deduction determined in the worksheet, you must file a Minnesota income tax return.
Your gross income is the total of your earned and unearned income. Your earned income includes salaries, wages, tips, professional fees, and taxable scholarship and fellowship grants. Your unearned income includes taxable interest, ordinary dividends, capital gains distributions, unemployment compensation, taxable social security benefits, pension, annuities, and distributions of unearned income from a trust.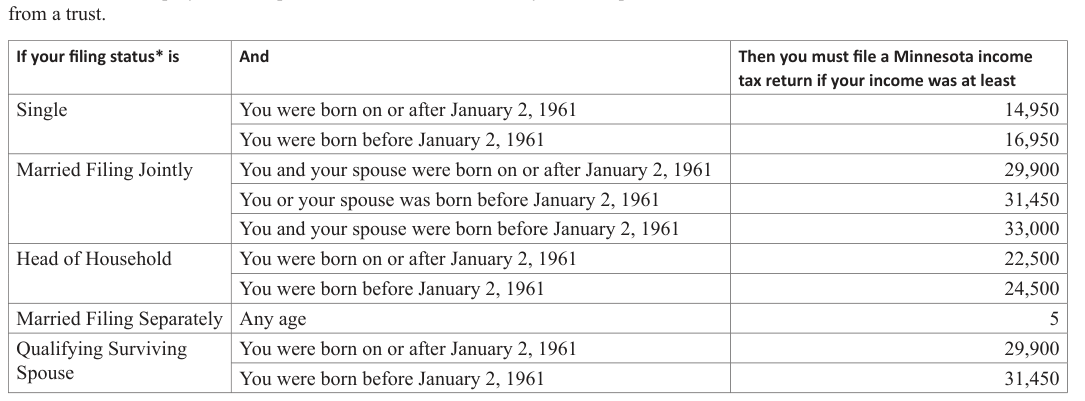
Text version of this table
If your filing status* is And Then you must file a Minnesota income tax return if your income was at least Single You were born on or after January 2, 1961 14,950 You were born before January 2, 1961 16,950 Married Filing Jointly You and your spouse were born on or after January 2, 1961 29,900 You or your spouse was born before January 2, 1961 31,450 You and your spouse were born before January 2, 1961 33,000 Head of Household You were born on or after January 2, 1961 22,500 You were born before January 2, 1961 24,500 Married Filing Separately Any age 5 Qualifying Surviving Spouse You were born on or after January 2, 1961 29,900 You were born before January 2, 1961 31,450
*Use the same filing status from your federal income tax return. If you did not file a federal return, see the Form 1040 instructions.
If you are not required to file a Minnesota return, you can still file to:
- Claim refundable credits (K-12 Education, Child and Working Family, Child and Dependent Care, Parents of Stillborn Children)
- Get a refund if your employer issued you a 2025 Form W-2 reporting Minnesota income tax withheld from your wages
# Part-Year Residents and Nonresidents
File a Minnesota income tax return if you moved into or out of Minnesota in 2025 and your 2025 Minnesota source income is $14,950 or more. You must file a Minnesota income tax return if you elected to receive advance payments of your 2025 Child Tax Credit on your 2024 return, even if your Minnesota source gross income is below $14,950. Complete Schedule M1NR, Nonresidents/Part-Year Residents, to determine income received while a Minnesota resident and income received from Minnesota sources while a nonresident. Your Minnesota tax is based on that income.
# Nonresidents
If your permanent residence is in another state but you lived in Minnesota, file a Minnesota income tax return as a Minnesota resident if both of these applied to you:
- You were physically in Minnesota for 183 days or more during the tax year
- You or your spouse owned, rented, lived in, or leased an abode (house, townhouse, condominium, apartment, mobile home, or cabin, with cooking and bathing facilities, that could be lived in year-round) in Minnesota If both conditions apply, you are considered a Minnesota resident for the length of time you maintained an abode in Minnesota.
You must also file a Minnesota income tax return if you elected to receive advance payments of your 2025 Child Tax Credit on your 2024 return, even if your Minnesota source gross income is below $14,950.
File a Minnesota income tax return if you meet the filing requirements in the next section. For more details, see Income Tax Fact Sheet 2, Part-Year Residents, and Income Tax Fact Sheet 3, Nonresidents.
# Filing Requirements for Part-Year Residents and Nonresidents
- Determine your total income from all sources (including sources not in Minnesota) while a Minnesota resident.
- Determine the total of the following types of income you received while a nonresident of Minnesota:
- Wages, salaries, fees, commissions, tips, and bonuses for work done in Minnesota.
- Gross rents and royalties received from property located in Minnesota.
- Gains from the sale of land or other tangible property in Minnesota.
- Gross winnings from gambling in Minnesota.
- Gains from the sale of a partnership interest, to the extent the partnership had property or sales in Minnesota.
- Gains reported on Schedule M1AR, Accelerated Recognition of Installment Sale Gains.
- Gains on the sale of goodwill or income from an agreement not to compete connected with a business operating in Minnesota.
- Minnesota gross income from a business or profession conducted partially or entirely in Minnesota. This is the amount from line 7 of federal Schedule C or line 9 of Schedule F of Form 1040. Gross income from a partnership, S corporation, or trust or estate is the amount on line 39 of Minnesota Schedule KPI, line 39 of Schedule KS, or line 49 of Schedule KF.
- Add step 1 and step 2. If the total is $14,950 or more, you must file a Minnesota income tax return and Schedule M1NR.
If the result is less than $14,950 and you had amounts withheld or paid estimated tax, file a Minnesota income tax return and Schedule M1NR to receive a refund. If you are married and filed a joint federal return, you must file a joint Minnesota return even if only one spouse has Minnesota income. Complete Schedule M1NR and include a copy of the schedule when you file your return.
# Seniors and Taxpayers with Disabilities
- Homestead Credit Refund (Form M1PR)
- Renter's Credit (Schedule M1RENT)
- Senior Citizens' Property Tax Deferral Program
- Special Homestead Classification: Class 1b (for qualifying blind and disabled property owners)
For more information on tax issues for seniors, visit our website at www.revenue.state.mn.us, or call us at 651-296-3781 or 1-800-652-9094.
# Michigan and North Dakota Residents
Minnesota has reciprocity agreements with Michigan and North Dakota. You are not subject to Minnesota income tax if both of these applied in 2025:
- Your permanent residence is in Michigan or North Dakota and you returned to your home state at least once a month
- Your only Minnesota income was from personal or professional service income (wages, salaries, tips, commissions, and bonuses) Complete Schedule M1M, Income Additions and Subtractions, to file for a refund of withholding if you are a Michigan or North Dakota resident. For more information, see Income Tax Fact Sheet 4, Reciprocity.
Follow the steps below to complete your Form M1 and Schedule M1M:
- Enter the appropriate amounts from your federal return on lines A through F and line 1 of Form M1.
- Skip lines 2 through 6 of Form M1.
- Enter the amount from line 1 of Form M1 on line 18 of Schedule M1M and on line 7 of Form M1. Place an X in the box for line 18 of Schedule M1M to indicate the state of which you are a resident.
- Complete the rest of Form M1. In addition to Schedule M1M, complete and enclose Schedule M1W, Minnesota Income Tax Withheld, and a copy of your home state tax return. Do not complete Schedule M1NR.
If your wages are covered by reciprocity and you do not want your employer to withhold Minnesota tax in the future, file Form MWR, Reciprocity Exemption/Affidavit of Residency, each year with your employer.
If you are filing a joint return and only one spouse works in Minnesota under a reciprocity agreement, include both of your names, Social Security Numbers, and dates of birth on your return.
If your gross income assignable to Minnesota from sources other than from personal or professional service income covered under reciprocity is $14,950 or more, you are subject to Minnesota tax on that income. File a Minnesota income tax return and Schedule
M1NR. You may not take the reciprocity subtraction on Schedule M1M.
# Aliens and Nonresident Aliens
If you are not a United States citizen or national, you are considered an alien for tax purposes. You must determine your residency status for federal tax purposes before you can determine your Minnesota tax responsibilities. To determine your federal residency status, see IRS Publication 519, U.S. Tax Guide for Aliens.
If you are considered a resident alien for federal tax purposes, you have the same filing and tax requirements of a United States citizen.
You will determine your Minnesota filing requirement following the requirements listed under Minnesota Residents, Part-Year Residents, and Nonresidents.
If you are considered a nonresident alien for federal tax purposes, you may be required to file a Minnesota income tax return depending on your Minnesota residency status and Minnesota gross income. If you are a full-year resident under the 183-day rule and required to file a federal income tax return, you must file a Minnesota income tax return. If you are a part-year resident or nonresident under the 183-day rule and have gross income from Minnesota sources of at least $5, you must file a Minnesota tax return and Schedule M1NR.
# How does the department protect my information?
Protecting your information and identity is our priority. We have partnered with other states, the IRS, financial institutions, and tax preparation software developers to combat fraud.
For more information about keeping your identity safe, go to:
- www.revenue.state.mn.us and enter Identity Theft into the Search box
- www.irs.gov (IRS)
- www.ag.state.mn.us (Minnesota Attorney General's Office)
We will never ask you to provide, update, or verify personal information through unsolicited email or phone calls.
If you are concerned about a potentially fraudulent contact by someone claiming to be from Revenue, call 651-296-3781 or
1-800-652-9094. We can determine if the contact you received was legitimate.
# What do I need?
- Your name and address
Reminder: Review your return before signing. You are legally responsible for all information on your return, even if you paid someone to prepare it for you.
- Your Social Security Number or Individual Taxpayer Identification Number (ITIN)
- Your completed federal return
- Your date of birth
If you do not provide this information, your refund will be delayed. If you owe tax, your payment may not be processed, and you may have to pay a penalty for late payment.
If a paid preparer completed your return, they must include their Preparer Tax Identification Number (PTIN).
Although not required on the return, we also ask for:
- A code number indicating a political party for the State Elections Campaign Fund if you want to designate a contribution
- Your phone number in case we have questions about your return
- Your paid preparer's phone number
# Name and Address Area
Use capital letters and black ink. Print your legal name, not a nickname. Enter only one address - your current home address or your post office box. If your current address is a foreign address, put an X in the Foreign Address box.
If you are married and filing separate income tax returns, enter your spouse's name and Social Security Number in the filing status area. Do not enter your spouse's name or Social Security Number in the name and address area at the top of your return.
# Federal Filing Status
You must use the same filing status you used on your federal return to file your Minnesota return. Put an X in the box for your filing status. If you filed federal Form 1040-NR and selected "If treating a nonresident alien or dual-status alien spouse as a U.S. resident for the entire tax year" for your filing status, put an X in the box for "Married Filing Separately" on your Minnesota return.
# Dependents and Qualifying Children
Enter dependent information on Schedule M1DQC, Dependents and Qualifying Children. Use the same information you provided when completing federal Form 1040. Follow the instructions on Schedule M1DQC to determine who may be claimed as a qualifying child for the Minnesota Child Tax Credit and the credit for qualifying older children. If you have more than three dependents, provide a separate statement with all the information required for claiming a dependent on the schedule.
# State Elections Campaign Fund
If you want $5 to go to help candidates for state office pay campaign expenses, enter the code number for your chosen party. If you choose the general campaign fund, the $5 will be distributed among candidates of all major parties listed. If you are filing a joint return, your spouse may also designate a party. Designating $5 will not reduce your refund or increase your tax owed.
# Important Tips
- Round the dollar amounts to the nearest dollar. For example: 129.49 becomes 129, and 129.50 becomes 130.
- Leave lines and unused boxes blank if they do not apply to you or if the amount is zero.
- If your federal taxable income on line D, or the amounts on lines 1, 3, or 13b are less than zero, enter as a negative number.
- Do not write extra numbers, symbols, or notes on your return, such as cents, dashes, decimal points, or dollar signs. Do not put a slash through the "0" (Ø) or "7" (7) or any other numbers.
- Enclose any explanations on a separate sheet unless you are instructed to write them on your return.
- Do not staple or tape any enclosures to your return. If you want to ensure your papers stay together, use a paperclip.
# Sign and Date Your Return
An unsigned paper return is not considered valid. If you are married and filing a joint return, both spouses must sign. You may be subject to interest and penalties if you do not sign. If you paid someone to prepare your return, that person must also sign and provide their federal Preparer Tax Identification Number (PTIN).
# When do I file and pay?
Your 2025 Minnesota income tax return should be electronically filed, postmarked, or dropped off by April 15, 2026. Your tax payment is due in full by April 15, 2026, even if you file your return later. If you file your tax return according to a fiscal year, your tax payment and return are due the 15th day of the fourth month after the end of your fiscal year.
# How do I pay my tax if I file after April 15?
Estimate your total tax and pay the amount you owe electronically or by credit or debit card. If you pay by check, you must send your tax payment with a completed voucher from our website. You may avoid a late payment penalty and interest by paying your tax by April 15. To avoid a late filing penalty, file your return by October 15, 2026. See page 22 for payment options.
# Do I have to file electronically?
No. If you do not want your preparer to file your return electronically, check the appropriate box at the bottom of the return.
# Where do I file paper returns?
If you are filing a paper return, see page 9 of these instructions. If you do not follow the instructions on that page, your return and refund will be delayed. Send your Minnesota income tax return, including all completed Minnesota schedules, and your federal return and schedules in the printed envelope included in this booklet. If you do not have the printed envelope, mail your forms to:.
# Minnesota Department of Revenue
Mail Station 0010
600 N. Robert St.
St. Paul, MN 55146-0010
If you are filing a paper return and electing to receive advance payments of your 2026 child tax credit on Schedule M1CWFC, mail your forms the address below. Only use this address if you are electing to receive advance payments of your 2026 child tax credit.
# Minnesota Department of Revenue
Mail Station 0015
600 N. Robert St.
St. Paul, MN 55146-0015
# What do I include when I mail my return?
Include your Form M1, all the Minnesota schedules you are required to complete, and a complete copy of your 2025 federal return and all schedules. If you do not enclose the required documentation, we may send your return back to you.
Make copies of all your forms and schedules. Keep tax returns, worksheets, and records of all items appearing on the return (such as Forms W-2 and 1099) until the statute of limitations runs out for the return. If you claimed the Child and Dependent Care Credit, K-12 Education Credit or Subtraction, Student Loan Credit, or Minnesota itemized deductions, keep your original receipts and all other documentation to prove your qualifying expenses.
# How do I avoid common errors?
- Enter your name and your dependents' names as they appear on Social Security cards.
- Double check Social Security Numbers used on tax forms.
- Double check bank routing and account numbers used on tax forms.
- Complete each form and carry totals to the correct lines. If you electronically file, the calculations are done for you.
- File your return by April 15, 2026, even if you owe more than you can pay. Pay as much as you can by the due date, and continue to make payments until we contact you. At that point, we can help you set up a payment plan for the remaining balance.
- If you owe, make your payment electronically and pick when you want the payment submitted. For more information about making your payment electronically, visit our website.
- If you are paper filing with a new address, be sure to place an X in the New Address box in the header. If you move after filing, contact us right away. You should do this even when requesting a direct deposit.
- Do not staple or tape anything to your return. Use a paperclip.
# How is my information used?
The information you provide on your tax return is private under state law. We use this information to determine your liability under Minnesota tax laws and for other tax administration purposes. We cannot give this information to others without your consent, except certain other government entities may have access to this information, if allowed by law. For details about how we use your information, including a list of the entities we may share it with, go to www.revenue.state.mn.us and enter Use of Information into the Search box.
# Line Instructions
Reminders
- If a line does not apply to you or the amount is zero, leave it blank
- Round dollar amounts to the nearest whole dollar
# Federal Return Information
- Include any schedules you use to complete your return when you file
# Line A—Federal Wages, Salaries, Tips, etc.
Enter wages, salaries, tips, commissions, bonuses, etc. you received in 2025. If you filed federal Form 1040, enter the amount from:
- Line 1z of Form 1040 and 1040-SR
- Line 1z of Form 1040-NR
# Line B—Taxable IRA Distributions, Pensions, and Annuities
Enter the total taxable IRA distributions, pensions, and annuities you received in 2025. Add the amounts on lines 4b and 5b of Form 1040, 1040-SR, or 1040-NR.
# Line C—Unemployment Compensation
Enter the unemployment compensation you received in 2025 from line 7 of Schedule 1 if you filed Form 1040, 1040-SR, or 1040-NR.
# Line D—Federal Taxable Income
Enter your 2025 federal taxable income from line 15 of Form 1040, 1040-SR, or 1040-NR.
If your federal taxable income is less than zero, enter as a negative number.
# Line E—Social Security Benefits
Enter your total social security benefits from line 6a of Form 1040 or 1040-SR.
# Line F—Taxable Social Security Benefits
Enter your taxable social security benefits from line 6b of Form 1040 or 1040-SR.
# Line 1—Federal Adjusted Gross Income
Enter your 2025 federal adjusted gross income from line 11a of Form 1040 or 1040-SR, or 1040-NR. If your federal adjusted gross income is less than zero, enter as a negative number. If you did not file a 2025 federal return, use a federal return and instructions to determine what your federal adjusted gross income would have been. If you were a shareholder or partner in a pass-through entity that claimed a deduction for state income taxes which reduced your federal adjusted gross income, you must complete the Adjusted Gross Income Worksheet for PTE Deductions. You will use the result on step 3 of the worksheet on the lines and steps of the schedules and worksheets listed.
Adjusted Gross Income Worksheet for PTE Deductions
1 Adjusted gross income from Line 1 of Form M1 …
2 Your share of pass-through entity taxes deducted by your partnership or s-corporation.
For entities who file in Minnesota this is included on Line 2 of Schedule KPI and KS …
3 Add steps 1 and 2 …
Use the result from step 3 on the following lines of other schedules:
- Line 5 of Schedule M1CD
- Line 1 of Schedule M1ED
- Line 1 of Schedule M1CWFC
- Lines 2 and 21 of Schedule M1SA
- Lines 15 through 17 of Schedule M1SA when determining limits for charitable contributions
- Line 18 of Schedule M1CAT
- Line 9 of Schedule M1R
- Line 2 of Schedule M1SLC
- Lines 1 and 2 of Schedule M1CR
- Lines 1 and 2 of Schedule M1RCR
- Line 4 of Schedule M1QPEN
Use the result from step 3 on the following worksheets:
- Form M1 - Step 1 of Worksheet A for line 4 - Standard Deduction Limitation
- Form M1 - Step 4 of the Worksheet for line 5 - Dependent Exemptions
- Schedule M1SA - Step 4 of the Worksheet for line 26
- Schedule M1529 - Step 3 of the Worksheet for line 5
- Schedule M1C - Step 2 of the Worksheet for line 4
- Schedule M1M - Step 1 of the Worksheet for line 12
- Schedule M1M - Step 9 of the Worksheet for line 12 (increase taxable income by step 2 of this worksheet)
# Line 2—Additions to income from line 10 of Schedule M1M and line 9 of Schedule M1MB
Complete Schedule M1M, Income Additions and Subtractions or Schedule M1MB, Business Income Additions and Subtractions, if, in 2025, you:
- Received interest from municipal bonds of another state or its governmental units
- Received federally tax-exempt interest dividends from a mutual fund investing in bonds of another state or its local governmental units
- Claimed federal bonus depreciation on your federal return
- Had state income tax passed through to you as partner of a partnership, shareholder of an S corporation, or beneficiary of a trust
- Deducted expenses or interest on your federal Form 1040 that are attributable to income not taxed by Minnesota
- Deducted foreign-derived intangible income under section 250 of the Internal Revenue Code
- Claimed a suspended loss from 2001 through 2005 or 2008 through 2024 from bonus depreciation on your federal return
- Filed Federal Form 4972, Tax on Lump-Sum Distributions
- Elected in 2008 or 2009 a 3-, 4-, or 5-year net operating loss carryback under the federal Worker, Homeownership, and Business Assistance Act (WHBA) of 2009
- Withdrew funds from a first-time homebuyer savings account for a nonqualified expense
- Accelerated recognition of certain nonresident installment sales
- Used distributions from a higher education savings account to pay for K-12 tuition
You may have received this income as an individual, partner of a partnership, shareholder of an S corporation, or beneficiary of a trust.
# Line 4— Itemized Deductions or Standard Deductions
You may claim the Minnesota standard deduction or itemize your deductions on your Minnesota return. You will generally pay less Minnesota income tax if you take the larger of your itemized or standard deduction. If you are married and filing separate returns, you may not claim the standard deduction if your spouse claimed itemized deductions. If you are a nonresident alien, you may only claim itemized deductions, unless you are allowed to claim the standard deduction if allowed by a U.S. income tax treaty.
# Itemized Deductions
Complete and file Schedule M1SA, Minnesota Itemized Deductions to claim itemized deductions.
# Standard Deduction
Use the table on the next page to determine your Minnesota standard deduction. You are considered age 65 or older if you were born before January 2, 1961. You are considered blind if you were totally blind as of December 31, 2025, or you have a statement certified by your eye doctor (ophthalmologist or optometrist) that you cannot see better than 20/200 in your better eye with glasses or contact lenses, or your field of vision is 20 degrees or less. If your eye condition is not likely to improve beyond the conditions above, you can get a statement certified by your eye doctor to this effect instead. Keep the statement for your records.
Standard Deduction Table for Line 4
Check the boxes that apply to you and your spouse. If you are a dependent, see the Worksheet for Line 4 — Dependent Standard Deduction.
If you are married and filing a separate return, check boxes for your status only, unless your spouse has no gross income and cannot be claimed as a dependent by another person.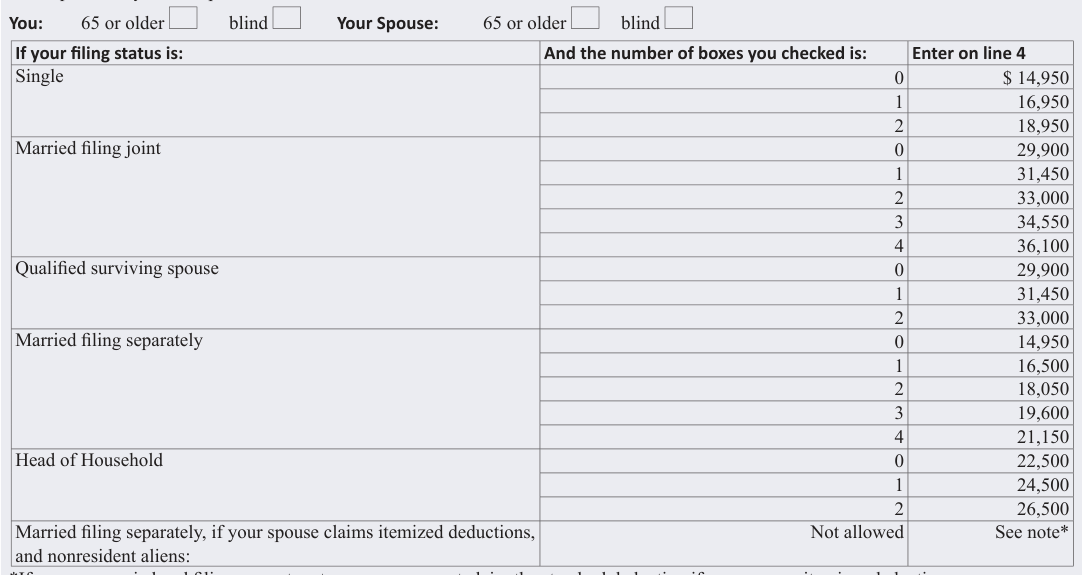
Text version of this table
If your filing status is: And the number of boxes you checked is: Enter on line 4 Single 0 $ 14,950 1 16,950 2 18,950 Married filing joint 0 29,900 1 31,450 2 33,000 3 34,550 4 36,100 Qualified surviving spouse 0 29,900 1 31,450 2 33,000 Married filing separately 0 14,950 1 16,500 2 18,050 3 19,600 4 21,150 Head of Household 0 22,500 1 24,500 2 26,500 Married filing separately, if your spouse claims itemized deductions, and nonresident aliens: Not allowed See note*
*If you are married and filing separate returns, you may not claim the standard deduction if your spouse itemizes deductions.
If you are a nonresident alien, you may claim the standard deduction only if allowed by U.S. income tax treaty.
Your standard deduction cannot exceed the standard deduction for your filing status and situation. If your Minnesota adjusted gross income on line 1 of Form M1 is greater than $238,950 ($119,475 if Married Filing Separately), you must complete Worksheet A for
Line 4 or Worksheet B for Line 4. Use your standard deduction amount from the Standard Deduction Table for Line 4 or step 6 of the
Worksheet for Line 4 — Dependent Standard Deduction to complete Worksheet A or B.
Dependents: If another person may claim you as a dependent on their return, your standard deduction is based on your earned income.
Use the Worksheet for Line 4 — Dependent Standard Deduction to determine your standard deduction.
Worksheet for Line 4 — Dependent Standard Deduction
Use this worksheet to determine your standard deduction only if someone can claim you, or your spouse if filing a joint return, as a dependent.
1 Is your earned income* more than $900?
Yes. Add $350 to your earned income and enter on step 1
No. Enter $1,250 on step 1 …
2 Enter $14,950 …
3 Check the boxes that apply and enter the total number of boxes checked on step 3
You were born before January 2, 1961
You are blind
Your spouse was born before January 2, 1961
Your spouse is blind …
4 Multiply the number of boxes checked in Step 3 by $2,000 ($1,550 if married or a qualifying surviving spouse) … 5 Add Steps 2 and 4 … 6 Enter the lesser of Step 1 and Step 5. This is your standard deduction … *Earned income includes wages, salaries, tips, professional fees, and other compensation received for personal services you performed. It also includes any taxable scholarship or fellowship grant. Generally, your earned income is the total of the amounts reported on Form 1040 or 1040-SR, line 1z, and Schedule 1, lines 3, 6, 8r, 8t, and 8u minus the amount, if any, on Schedule 1, line 15.
Worksheet A for Line 4 - Standard Deduction Limitation
If your adjusted gross income is less than $238,950 ($119,475 if married filing separately), do not complete this worksheet. If your adjusted gross income is greater than $1,083,150 (regardless of filing status), complete Worksheet B for Line 4 - Standard Deduction Limitation.
1 Adjusted gross income from line 1 of Form M1 …
2 If step 1 is greater than $330,300, enter $91,350. If it is less than or equal to $330,300, then subtract $238,950 from step 1. If Married filing separately, and step 1 is greater than
$165,150, enter $45,675. If it is less than or equal to $165,150, subtract $119,475 from step 1 …
3 Multiply step 2 by 3% …
4 If step 1 is greater than $330,300, subtract $330,300 from step 1. If married filing separately and step 1 is greater than $165,150, subtract $165,150 from step 1. Otherwise, enter 0 … 5 Multiply step 4 by 10% … 6 Add steps 3 and 5 … 7 Enter your standard deduction from the standard deduction table or Step 6 of the
Worksheet for Line 4 - Dependent Standard Deduction …
8 Multiply step 7 by 80% …
9 Enter the lesser of step 6 or step 8 …
10 Subtract step 9 from step 7. This is your standard deduction. Enter this amount on line 4 …
Worksheet B for Line 4 - Standard Deduction Limitation
If your adjusted gross income is greater than $1,083,150, complete this worksheet.
1 Enter your standard deduction from the standard deduction table or Step 6 of the Worksheet for Line 4 - Dependent Standard Deduction … 2 Multiply step 1 by 80% … 3 Subtract step 2 from step 1. This is your standard deduction. Enter this amount on line 4 …
# Line 5—Exemptions
You may claim exemptions for dependents on line 5. Use the Worksheet for Line 5 to determine your total exemption amount. If you can be claimed as a dependent on another individual's return, do not complete the Worksheet for Line 5 and leave line 5 of Form M1 blank.
Worksheet for Line 5 — Dependent Exemptions
1 Enter the number of dependents you claimed on Schedule M1DQC …
$5,200
2 Enter $5,200 …
3 Multiply step 1 by step 2 …
4 Enter the amount from line 1 of Form M1 …
5 Enter the amount that matches your filing status …
Married Filing Jointly or Surviving Spouse: $358,550 Single: $239,050
Head of Household: $298,800 Married Filing Separately: $179,275
6 Compare the amounts on steps 4 and 5. If step 5 is more than step 4, enter the amount from step 3 on line 5 of Form M1 and STOP HERE. If step 4 is more than step 5, subtract step 5 from step 4 … 7 If step 6 is more than $122,500 ($61,250 for Married Filing Separately), enter 0 on line 5 of Form M1 and STOP HERE. If step 6 is less than or equal to $122,500 ($61,250 for Married Filing Separately), divide step 6 by $2,500 ($1,250 if Married Filing Separately) and round up to the next whole number (Example: .0004 to 1) … 8 Multiply step 7 by 2% (.02). Enter the result as a decimal … 9 Multiply step 3 by step 8 … 10 Subtract step 9 from step 3. Enter the result on line 5 of Form M1 …
# Line 6—State Income Tax Refund
Enter any state income tax refund amounts included as income on line 1 of federal Schedule 1.
# Line 7—Subtractions from line 40 of Schedule M1M and line 22 of Schedule M1MB
Complete Schedule M1M, Income Additions and Subtractions, if any of these apply. If, in 2025, you:
- Received mileage reimbursement in service of a charitable organization
- Received interest from a federal government source
- Were a licensed cannabis business who incurred or paid expenses disallowed under section 280E of the Internal Revenue Code
- Purchased educational material or services for your qualifying child's K-12 education
- Did not file Schedule M1SA and your charitable contributions were more than $500
- Reported bonus depreciation as an addition to income in a year 2020 through 2024 or received a federal bonus depreciation subtraction in 2025 from an estate or trust
- Had a business interest deduction disallowed
- Your income for claiming this subtraction is the amount from line 1 of Form M1 plus any lump-sum distributions reported on federal Form 4972, less any taxable Railroad Retirement Board benefits (see instructions for line 9 of Schedule M1R).
- Received benefits from the Railroad Retirement Board, such as unemployment, sick pay, or retirement benefits
- Were a permanent resident of Michigan or North Dakota and you received wages covered by reciprocity from which Minnesota income tax was withheld (see page 8)
- Worked and lived on the Indian reservation of which you are an enrolled member
- Received federal active-duty military pay while a Minnesota resident
- Are a member of the Minnesota National Guard or Reserves who received pay for training or certain types of active service
- Received active-duty military pay while a resident of another state and you are required to file a Minnesota return
- You, your spouse (if filing a joint return), or your dependent donated all or part of a liver, pancreas, kidney, intestine, lung, or bone marrow (while living) to another person
- Received a military pension or other military retirement pay
- Were insolvent and received a gain from the sale of your farm property that is included in line 11a of federal Form 1040
- Received a post service education award for service in an AmeriCorps National Service program
- Had a net operating loss from 2008 or 2009 under the Worker, Homeownership, and Business Assistance Act of 2009 and are claiming the Minnesota subtraction you are carrying forward for Minnesota purposes
- Had railroad maintenance expenses not allowed as a federal deduction
- Contributed to a qualified Section 529 Plan and did not claim a credit for these contributions (see Schedule M1529)
- Received Social Security benefits in 2025 and included some of those benefits on line 6b of federal Form 1040 or 1040-SR
- Received taxable qualified public pension benefits for services for which you did not earn Social Security benefits (See Schedule M1QPEN)
- You received damages under a sexual harassment or abuse claim
- You received income from a long-term service and support or nursing facility workforce incentive grant
- Earned interest or dividends on a designated first-time homebuyer savings account (see Schedule M1HOME)
- Reported a discharge of indebtedness of educational loans on completion of an income-driven repayment program
- Had income from the sale of partnership interest after claiming accelerated recognition in a prior year
- Recognized deferred foreign income under section 965 of the Internal Revenue Code
- Received debt forgiveness deemed coerced debt by a court.
- Received consumer enforcement public compensation from the consumer protection restitution account established under Minnesota Statutes, section 8.37.
- Received compensation from a foreign service pension or other foreign service retirement plan.
- Received a stipend from the Minnesota Department of Human Services on or after June 15, 2025, per a collective bargaining agreement between the Service Employees International Union (SEIU) Healthcare Minnesota & Iowa and the State of Minnesota.
# Line 10—Tax From Table
Turn to the tax table on pages 32 through 38. Using the amount on line 9, find the tax amount in the column under your filing status.
Enter the amount of tax from the table on line 10.
# Line 11—Alternative Minimum Tax (Schedule M1MT)
If you had to pay federal alternative minimum tax when you filed your federal Form 1040, 1040-SR, or 1040-NR, you must complete Schedule M1MT, Alternative Minimum Tax, to determine if you must pay Minnesota alternative minimum tax.
You may be required to pay Minnesota alternative minimum tax even if you were not subject to federal alternative minimum tax.
Before you complete Schedule M1MT, you must complete Part 1 of federal Form 6251 for Minnesota purposes.
# Line 13 —Part-Year Residents and Nonresidents (Schedule M1NR)
Your tax is determined by the percentage of your income that is assignable to Minnesota. Complete Schedule M1NR, Nonresidents/ Part-Year Residents, to determine your Minnesota tax. See page 6 to determine if you were a resident, part-year resident, or nonresident.
If you complete Schedule M1NR, enter the amounts from lines 28 and 29 of Schedule M1NR on lines 13a and 13b of your Form M1.
Include Schedule M1NR when you file Form M1.
# Line 14a—Other Minnesota Taxes
You may be required to pay an additional Minnesota tax if you:
- Withdrew funds from a first-time homebuyer savings account, and did not use the funds for qualified expenses
- Filed Schedule M1529, Education Savings Account Contribution Credit or Subtraction, in a prior tax year, and funds were withdrawn for non-qualified expenses
- Received a qualified lump-sum distribution from a certain qualified plan and filed federal Form 4972
- Received $1,000,000 or more of net investment income (See Schedule NIIT for more information)
If you are required to pay one or more of these taxes, complete and file the applicable schedule or schedules.
# First-Time Homebuyer Recapture Tax
Complete Schedule M1HOME, First-Time Homebuyer Savings Account, if you withdrew funds from a savings account designated as a first-time homebuyer account and funds were not used for qualified expenses. Qualified expenses include the down payment, closing costs, costs of construction, or financing the construction of a single-family residence.
# Education Savings Account Credit or Subtraction Recapture Tax
File Schedule M1529, Education Savings Account Contribution Credit or Subtraction, to determine your recapture tax if:
- You filed Schedule M1529 claiming a credit or subtraction in a prior year
- Funds were withdrawn from that education savings account and not used for qualified expenses
See Schedule M1529 to determine which expenses do not qualify for Minnesota purposes.
# Tax on Lump-Sum Distribution (Schedule M1LS)
You must file Schedule M1LS, Tax on Lump-Sum Distribution, if all of these apply:
- You received a lump-sum distribution from a pension, profit-sharing, or stock bonus plan in 2025
- You were a Minnesota resident when you received any portion of the lump-sum distribution
- You filed federal Form 4972
If you complete Schedule M1LS, include the schedule and Form 4972 when you file your Form M1.
# Tax on Net Investment Income (Schedule NIIT)
You must file Schedule NIIT, Net Investment Income Tax, if you have net investment income over $1,000,000. If you complete Schedule NIIT, include the schedule and federal Form 8960 when you file your Form M1. Net investment income includes, but is not limited to, interest, dividends, capital gains, rental and royalty income, and non-qualified annuities. It does not include net gains attributable to dispositions of property classified as class 2a agricultural land. See Schedule NIIT for more information on how to determine your Minnesota net investment income tax.
Any partner or shareholder electing composite income tax or Pass-Through Entity (PTE) tax to satisfy their filing requirement must file Schedule NIIT with Form M1. In these situations, the Form M1 will only report the net investment income tax due on line 14 and will not report any other tax lines or tax benefits. The composite income tax or PTE tax can still satisfy the partner's or shareholder's tax for the distributive share of the entity's business income.
If you elected to file composite income tax or PTE tax to satisfy your individual filing requirement in Minnesota, and you are filing Form M1 and Schedule NIIT to pay your net investment income tax, you must:
- Enter your (and your spouse's if filing a joint federal income tax return) information at the top of Form M1 (name, address, date of birth, SSN, filing status)
- Complete lines A, B, C, D, E, and F of Form M1
- Do not complete lines 1 through 12
- Complete lines 13 through 30 but enter zero on lines 13, 16, 20, and 22
- Enter the net investment income tax from line 15 of Schedule NIIT on line 14a of Form M1 and check box (d)
- Check the "I am filing this return for Net Investment Income Tax requirements" box at the bottom of Form M1
- Include your completed Schedule NIIT and federal Form 8960 with Form M1
# Line 14b—Repayment of Advance Child Tax Credit
If you completed Schedule M1CWFC and entered an amount on line 27, include the amount from line 27 on line 14b of Form M1.
# Line 16—Nonrefundable Credits (Schedule M1C)
Complete Schedule M1C, Other Nonrefundable Credits, if any of these apply for 2025:
- You are filing a joint return and have taxable earned income, pension, or Social Security income
- You paid premiums on a qualified long-term care insurance policy
- You were a Minnesota resident for all or part of 2025 and paid income tax to both Minnesota and another state on the same income
- You qualify for the Credit for Past Military Service
- You purchased transit passes to resell or give to your employees
- You paid Minnesota alternative minimum tax in prior years and are not required to pay it in 2025
- You invested in a qualified business in East Grand Forks, Breckenridge, Dilworth, Moorhead, or Ortonville, and the business has been certified as qualified for the SEED Capital Investment Program
- You contributed to a qualified education savings account in 2025 and did not claim the Education Savings Account Subtraction
- You were a licensed teacher who completed a qualifying master's degree program you began after June 30, 2017
- You were a full-year or part-year resident and made eligible loan payments on your own qualified student loans
- You received a credit certificate from the Minnesota Rural Finance Authority
- You received a Film Production Credit certificate from the Minnesota Department of Employment and Economic Development
- You sold a manufactured home park to a cooperative
- You had qualified railroad reconstruction or replacement expenditures
- You received a certificate from the Minnesota Housing Finance Agency for qualifying contributions to a state fund Report the total of all credits from Schedule M1C on line 16 of Form M1. Include any schedules you completed when filing your return.
# Line 18—Nongame Wildlife Fund
You can help preserve Minnesota's nongame wildlife, such as bald eagles and loons, by donating to the Nongame Wildlife Fund. To donate, enter the amount on line 18. This amount will decrease your refund or increase the amount you owe.
To make a contribution to the fund, go to www.dnr.state.mn.us/nongame/donate or send a check payable to:
DNR Nongame Wildlife Fund
500 Lafayette Road
Box 25
St. Paul, MN 55155
# Line 20—Minnesota Income Tax Withheld (Schedule M1W)
If you received Forms W-2, 1099, or W-2G, or Schedules KPI, KS, or KF showing Minnesota income tax withheld for 2025, you must complete Schedule M1W, Minnesota Income Tax Withheld. Include Schedule M1W when you file Form M1. If you do not include this schedule, we may disallow your withholding amount. Do not send in your Forms W-2, 1099, or W-2G. Keep these forms with your records, as we may ask to review them.
If you are claiming withholding from a Schedule KPI, KS, or KF, include the schedule with your return.
# Line 21—Minnesota Estimated Tax and Extension Payments
You may include only three types of payments on line 21:
- Your total 2025 Minnesota estimated tax payments made in 2025 and 2026
- The portion of your 2024 Minnesota income tax refund designated on your 2024 Form M1 to be applied to 2025 estimated tax
- Any state income tax payment made by the regular due date when you are filing after the due date
Contact us if you are uncertain of these amounts.
# Refundable Credits
These credits may help you get a refund even if you do not have a tax liability.
# Line 22—Refundable Credits (Schedule M1REF)
Complete Schedule M1REF, Refundable Credits, if you qualify for any of these credits:
- Child and Dependent Care Credit
- Minnesota Child and Working Family Credits
- K-12 Education Credit
- Renter's Credit
- Refundable Credit for Tax Paid to Wisconsin
- Credit for Parents of Stillborn Children
- Credit for Historic Structure Rehabilitation (Certified by the State Historic Preservation Office)
- Enterprise Zone Credit (Certified by the Department of Employment and Economic Development)
- Angel Investment Credit
- Pass-Through Entity Tax Credit (include Schedule KPI, KS, or KF)
- Credit for claim of right
- Credit for Sustainable Aviation Fuel
- Refundable credit for increasing research activities
If you qualify for one or more of these credits, include the appropriate credit schedules and Schedule M1REF with your Form M1.
# Child and Dependent Care Credit (Schedule M1CD)
To qualify for the Child and Dependent Care Credit, your federal adjusted gross income must be less than $76,150 with one qualifying person or less than $88,150 with two or more qualifying persons. Also, at least one of these must apply:
- You paid someone (other than your dependent child or stepchild younger than age 19) to care for a qualifying person while you (and your spouse if filing a joint return) were working or looking for work. A qualifying person and qualifying expenses are the same as for the federal credit for child and dependent care expenses.
- You were a licensed family daycare operator caring for your own dependent child who had not reached age six by the end of the year.
- Your child was born in 2025, and you did not participate in a pre-tax dependent care assistance program.
If you qualify, complete Schedule M1CD, Child and Dependent Care Credit, and Schedule M1REF and include these schedules with your Minnesota income tax return. Enter the number of qualifying persons on line 1a of Schedule M1REF.
# Minnesota Child and Working Family Credits (Schedule M1CWFC)
You may qualify for the Minnesota Child and Working Family Credits if you earned income from a job, were self-employed or have qualifying children. See the requirements on Schedule M1CWFC, Child and Working Family Credits. Use Schedule M1DQC to determine who is a qualifying child or qualifying older child and Schedule M1CWFC to claim the credits. Part-year residents may qualify for these credits based on their percentage of income assignable to Minnesota.
If you qualify for these credits, complete Schedule M1DQC, Schedule M1CWFC, and Schedule M1REF and include these schedules with your Form M1. Enter the number of your qualifying children for the Child Tax Credit on line 2a and qualifying older children on line 2b of Schedule M1REF.
# Renter's Credit (Schedule M1RENT)
You may qualify for the Renter's Credit if you were a Minnesota resident, your household income was less than $77,570, and you lived in a building where either property taxes were payable for 2025 or payments in lieu of property taxes were payable in 2025. The maximum credit is $2,720. If you qualify for the credit, complete Schedule M1RENT, Renter's Credit, and Schedule M1REF and provide both with your Form M1. You must provide a copy of any Certificate of Rent Paid (CRP) used to claim the credit.
# Credit for Parents of Stillborn Children (Schedule M1PSC)
You may qualify for the Credit for Parents of Stillborn Children if, in 2025:
- You experienced the birth of a stillborn child in 2025
- You received a Certificate of Birth Resulting in Stillbirth from the Minnesota Department of Health, Office of Vital Records
- You would have claimed the child as a dependent in 2025 if the child had not been stillborn
Enter the document control number and state file number from the Certificate of Birth Resulting in Stillbirth you received from the Minnesota Department of Health. The state file number is the number printed in the upper right area inside the margin of the Certificate of Birth Resulting in Stillbirth. The document control number is the number printed in the lower left corner under the barcode on the Certificate of Birth Resulting in Stillbirth. If you qualify for the credit, complete Schedule M1PSC, Credit for Parents of Stillborn Children, and Schedule M1REF and include both with your Form M1.
# Credit for Tax Paid to Wisconsin (Schedule M1RCR)
You may be eligible for a refundable credit for income tax paid to Wisconsin if:
- You were domiciled in Minnesota for all or part of 2025
- You incurred 2025 income tax for Minnesota and for Wisconsin on the same income earned for professional or personal services performed while a Minnesota resident Use Schedule M1RCR, Credit for Tax Paid to Wisconsin, and include it with your Form M1.
K-12 Education Credit (Schedule M1ED)
You may receive a credit if you paid education-related expenses in 2025 for a qualifying child in grades kindergarten through 12 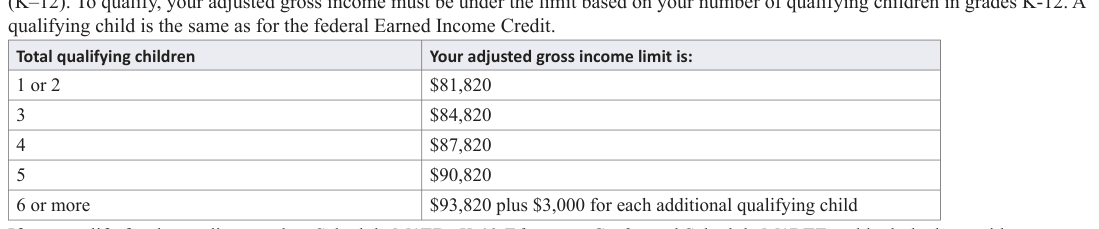
Text version of this table
Total qualifying children Your adjusted gross income limit is: 1 or 2 $81,820 3 $84,820 4 $87,820 5 $90,820 6 or more $93,820 plus $3,000 for each additional qualifying child
- Costs to drive your child to and from school, tutoring, enrichment programs, or camps not part of the regular school day
- Travel expenses, lodging, and meals for overnight class trips
- Fees for materials and textbooks purchased for use in religious teachings
- Sport camps or lessons
- Books and materials used for tutoring, enrichment programs, academic camps, or after-school activities
- Tuition and expenses for preschool or post-high school classes
- Costs of school lunches
- Costs of uniforms used for school, band, or sports
- Monthly internet fees
- Noneducational software
For more information on the Education Credit and the Education Subtraction, see Fact Sheet 8, K-12 Education Credit and Subtraction, on our website.
# Line 24—Your Refund
If line 23 is more than line 19, subtract line 19 from line 23, then subtract the amount, if any, on line 27. This is your 2025 Minnesota income tax refund. If the result is zero, you generally must still file your return. See "Am I required to file a Minnesota Income Tax Return?" on page 6 of these instructions.
Of the amount on line 24, you can:
- Have the entire refund deposited directly into a checking or savings account (see the line 25 instructions).
- Receive the entire refund in the mail as a paper check (skip lines 25, 26, 28, and 29).
- Apply all or a portion of your refund toward your 2026 estimated taxes. The remaining balance, if any, may be directly deposited into your bank account, or mailed to you.
We will deduct any amount you owe for Minnesota or federal debts, criminal fines, or a debt to a federal, state, or county agency, district court, qualifying hospital, or public library. If you participate in the Senior Citizens' Property Tax Deferral Program, we will apply your refund to your deferred property tax total. We will use your Social Security Number to identify you as the correct debtor. If your debt is less than your refund, you will receive the difference.
Generally, you must file your 2025 return no later than 3 1/2 years from the original due date or your right to receive the refund lapses.
# Line 25—Direct Deposit of Refund
Direct deposit is the safest and easiest way to get your tax refund. If you want the refund on line 24 to be directly deposited into your checking or savings account, enter the requested information on line 25. You must use an account not associated with any foreign banks.
The routing number must have nine digits. The account number may contain up to 17 digits, which includes numbers and letters.
Leave out any hyphens, spaces, or symbols.
If the routing or account number is incorrect or is not accepted by your financial institution, we will send your refund as a paper check. We may also issue your refund by check if we adjusted your return or recaptured part of your refund to pay a debt you owe.
By completing line 25, you are authorizing us and your financial institution to initiate electronic credit entries and, if necessary, debit entries and adjustments for any credits made in error.
# Line 26—Amount You Owe
If line 19 is more than line 23, you owe Minnesota income tax for 2025. Read the instructions for line 27 to determine if you must file Schedule M15, Underpayment of Estimated Income Tax.
Subtract line 23 from line 19, then add the amount, if any, from line 27. Enter the result on line 26. This is the Minnesota income tax you must pay. Pay your tax using one of the methods described in Payment Options on page 22 of these instructions.
If you are filing your return after April 15, 2026, you may owe a late payment penalty, a late filing penalty, and interest (see page 22 of these instructions). If you file a paper return and you include penalty and interest with your check payment, enclose a separate statement showing how you calculated the penalty and interest.
# Line 27—Penalty for Underpayment of 2025 Estimated Tax (Schedule M15)
You may owe a penalty if:
- Line 19 is more than line 23 and the difference is $500 or more
- You did not make a required estimated tax payment on time, even if you have a refund
Complete Schedule M15 to determine if you owe a penalty. Enter the penalty, if any, on line 27 of Form M1. Also, subtract the penalty amount from line 24 or add it to line 26 of Form M1. Include Schedule M 15 with your return.
To avoid this penalty next year, you may want to make larger 2026 estimated tax payments or ask your employer to increase your withholding.
# Payment Options/Penalty and Interest
Line 28 - Penalty and Interest
If you are filing your return after April 15, 2026, you may owe a late payment penalty or late filing penalty and interest. See "Is there a penalty for filing late?" and "Is there a penalty for paying late?" later in these instructions to determine what penalties may apply.
See "How is interest on late payments calculated?" to help calculate any interest you may owe. If you owe penalty and interest and do not calculate it on your own, leave line 28 blank and file your return. We will calculate the amount for you and send you a bill for any amount due. If you entered an amount on line 24, subtract the amount you entered on line 28 from the amount line 24. If you entered an amount on line 26, add the amount from line 28 to line 26.
# Lines 29 and 30—2025 Estimated Tax
If you are paying 2026 estimated tax, you may apply all or part of your 2025 refund to your 2026 estimated tax.
Once you choose to apply all or part of your 2025 refund to your 2026 estimated tax, it cannot be changed.
On line 29, enter the portion of line 24 you want refunded to you. On line 30, enter the amount from line 24 you want applied to your 2026 estimated tax. The total of lines 29 and 30 must equal line 24.
If you are filing Form M1X to amend your return, your refund cannot be applied to your estimated tax account.
# Pay Electronically
Go to www.revenue.state.mn.us, and select Make a Payment under Individuals
Select Bank Account or Credit or Debit Card* and follow the prompts to make your payment. You cannot use a foreign bank account. Save the confirmation number and date stamp from your payment.
*We use a third-party vendor to process credit and debit card payments. A fee is charged for this service.
# Pay by Check or Money Order
Go to our website at www.revenue.state.mn.us and select Make a Payment under Individuals. Then, select Check or Money Order.
Use the Payment Voucher System to create a voucher.
If you are filing a paper return, send the voucher and your check or money order separately from your return to ensure that we properly credit your payment to your account. Your check authorizes us to make a one-time electronic fund transfer from your account. After the funds transfer is complete, we will destroy the physical check.
# What if I cannot pay the full amount I owe by the due date?
Pay as much as you can when you file your tax return. Then, make monthly payments using a payment voucher until you receive a bill. After you get the bill, you can request a payment agreement by calling 651-556-3003 or 1-800-657-3909 or at www.revenue.state. mn.us.
For details about payment agreements, go to www.revenue.state.mn.us and enter payment agreements into the Search box.
# Should I make estimated payments?
Make estimated payments if any of these apply:
- You expect to owe $500 or more in Minnesota tax for 2026
- Minnesota tax was not withheld from your earnings
- Your income includes pensions, commissions, dividends or other sources not subject to withholding
To determine how much you owe, subtract your withholding and tax credits from the tax on your earnings. For details on how to estimate and pay your tax, visit our website and enter estimated tax into the Search box.
To make estimated payments electronically, choose Make a Payment under Individuals.To pay by check, go to www.revenue. state.mn.us and choose Make a Payment under Individuals. Then, choose Check or Money Order and use the Payment Voucher System to create a payment voucher. Send your voucher and check to the address on the voucher. You may print multiple vouchers for estimated payments.
# Is there a penalty for filing late?
The due date to file a return for 2026 is April 15. There is no late filing penalty if your return is filed by October 15, for most individuals. If your return is not filed by October 15, we will charge a 5% late filing penalty on the unpaid tax.
Most individuals must pay by April 15, even if you filed an extension for your federal return. If you cannot pay the full amount due, file your return and pay as much as you can by the due date to reduce penalties and interest.
# Is there a penalty for paying late?
We will charge a 4% late payment penalty of the unpaid amount due if you do not pay what you owe by the due date, even if you file your return within six months of the filing deadline.
We will charge an additional 5% penalty on the unpaid tax if you pay your tax 181 days or more after filing your return.
Use the worksheet below to determine penalties you owe if you file or pay late.
# Are there other penalties?
We will charge a fraud penalty equal to 50% of a fraudulently claimed refund if you claim a refund you do not qualify for.
We can charge civil and criminal penalties for:
- Failing to include all taxable income
- Making errors due to intentionally disregarding the income tax laws
- Filing a frivolous return
- Knowingly or willfully failing to file a Minnesota return
- Evading tax
- Filing a false or fraudulent return
# How is interest on late payments calculated?
Use the worksheet below to calculate interest you owe. We will charge interest on any unpaid tax and penalty after April 15, 2026.
The interest rate is determined each year. The interest rate to enter on step 7 is 7% for 2026.
If the days fall in more than one calendar year, do not include days beyond December 31, 2026 on steps 9 and 16. Determine the interest due for later calendar years using steps 7 through 11 and steps 16 through 18 separately for each year and using the appropriate interest rate on step 7. When completing these additional steps, use December 31 of the prior year on steps 9 and 16, and then add the result of these additional steps to the result of the worksheet below.
1 Total tax due from line 26 of Form M1 …
2 Tax paid by April 15, 2026 …
3 Subtract step 2 from step 1 …
4 Divide step 3 by step 1.
If the result is less than 10% and you are filing by October 15, enter 0 on step 5 and go to step 6 . .
5 Late payment penalty. Multiply step 3 by 4% …
6 Add steps 3 and 5 …
7 Interest rate for the tax year …
8 Multiply step 6 by step 7 …
9 Number of days after April 15 you paid the tax …
10 Divide step 9 by 365 (carry to five decimal places) …
11 Interest on late payment penalty and late taxes. Multiply step 8 by step 10 …
If filing and paying in full before October 15, skip steps 12 through 18 and go to step 19.
12 Late filing penalty. Was your return filed on or before October 15, 2026?
If yes, enter 0. If no, multiply step 3 by 5% (.05) …
13 Extended delinquency penalty. Multiply step 3 by 5% (.05) …
14 Add steps 12 and 13 …
15 Multiply step 14 by step 7 …
16 Number of days paid past October 15 …
17 Divide step 16 by 365 …
18 Interest on late file and extended delinquency penalty. Multiply step 15 by step 17 …
19 Add steps 5, 11, 14, and 18. Include the result on line 28 of Form M1 …
# Separation of Liability
You may be eligible for the Separation of Liability Program if you filed a joint return, are no longer married, and still owe part of the joint liability. For information, write to:
# Minnesota Department of Revenue
Attn: Separation of Liability Program
Mail Station 7701
600 N. Robert St.
St. Paul, MN 55146-7701
# Filing on Behalf of a Deceased Person
If a person died before filing a 2025 tax return and had income that meets the minimum filing requirement for 2025 or claimed advance payments of their 2025 child tax credit when they filed their 2024 return, the spouse or personal representative must file a Minnesota income tax return for the deceased person (decedent). The return must have the same filing status used to file the decedent's federal return. To file a Minnesota income tax return for a decedent, enter the decedent's name and your name on the return and print "DECD" and the date of death after the decedent's last name. For more information, see Income Tax Fact Sheet 9, Filing on Behalf of a Deceased Taxpayer.
# Claiming a Refund on Behalf of a Deceased Person
If you are the decedent's spouse and you are using the joint filing method, we will send you the refund.
If you are the personal representative, you must include a copy of the court document appointing you as personal representative with the decedent's return. You will receive the decedent's refund on behalf of the estate.
If no personal representative has been appointed for the decedent and there is no spouse, complete Form M23, Claim for a Refund for a Deceased Taxpayer, and include it with the decedent's Minnesota income tax return.
# Amending your Return and Reporting Federal Changes
Generally, you have 3 ½ years from the return due date to amend an original return to claim a refund. Complete Minnesota Form M1X, Amended Minnesota Income Tax, and include an updated version of Form M1 and all applicable schedules.
You have 180 days to amend your Minnesota return from either of these dates:
- The date the IRS notifies you of a change they made to your federal return
- The date you amend your federal return and it affects your Minnesota return.
If the IRS changes your return and the changes do not affect your Minnesota return, you have 180 days to send us a letter of explanation. We will charge a 10% penalty on any additional tax and have six more years to audit your return if you fail to report federal changes within 180 days.
Send your letter and a complete copy of your federal amended return or the IRS correction notice to:
# Minnesota Department of Revenue
Mail Station 0010
600 N. Robert St.
St. Paul, MN 55146-0010
# Return Authorization Checkbox
Check this box to authorize Revenue to discuss this return with the preparer or the third-party designee indicated on your federal return. This authority allows us to discuss with your preparer these items from this return:
- line item details
- tax due on original and adjustments made during processing; penalty or interest due
- documents received or sent like a tax order or bill
- dates and amounts of payments, credits, or refunds
The authority also allows your preparer to cancel direct deposit or debit payments and submit an abatement request.
The authority granted by a marked return checkbox is valid for either of these:
- one year after the due date for current original returns,
- one year from the date the form was submitted for amended and noncurrent original returns.
Checking the box does not give your preparer or third-party designee the authority to:
- sign any tax documents on your behalf
- represent you at any audit or appeals conference
- discuss abatement progress.
For these types of authorities, file Form REV184i, Individual or Sole Proprietor Power of Attorney, with Revenue.
# Taxpayer Rights Advocate
If you have tax problems and have not been able to resolve them through normal channels, contact the Taxpayer Rights Advocate.
Call: 651-556-6013
Email: dor.tra@state.mn.us
Webpage: revenue.state.mn.us/contact-tra
Write to: Minnesota Department of Revenue
# Taxpayer Rights Advocate
Mail Station 7102
St. Paul, MN 55146
Did you serve in a combat zone at any time between 2022 and 2026?
You are eligible for a credit of $120 for each month you served in a combat zone or hazardous duty area if Minnesota is your state of legal residence (domicile). You can claim this credit for months served in years 2022, 2023, 2024, 2025, and 2026. Complete Form M99, Credit for Military Service in a Combat Zone, and mail it to the department with the required information listed on Form M99.
You may also file Form M99 electronically. Go to www.revenue.state.mn.us and enter M99 into the Search box.
# Am I a Minnesota resident?
If you are a resident when you enlist, you remain a Minnesota resident until you establish domicile somewhere else. Do not complete Schedule M1NR, Nonresidents/Part-Year Residents, unless you (or your spouse) are a part-year resident of Minnesota or are a nonresident.
Military personnel who are part-year residents or nonresidents: When determining if you are required to file a Minnesota return using the steps on page 7, do not include:
- Active-duty military pay for service outside Minnesota in step 1
- Active-duty military pay for service in Minnesota in step 2
Resident military spouses: If you are the spouse of an active-duty military member who is stationed outside of Minnesota, all income you earned in another state is assignable to Minnesota.
Nonresident military spouses: You may be exempt from Minnesota tax on personal service income from services performed in Minnesota if you meet all of these requirements:
- Your spouse was present in Minnesota in compliance with military orders
- Your spouse was domiciled in a state other than Minnesota
- You were in Minnesota solely to be with your spouse
For more information, see Income Tax Fact Sheet 5, Military Personnel - Residency.
# Subtractions
Minnesota residents who are in the military can take a subtraction for military pay if they included it in adjusted gross income, including Active Guard Reserve (AGR) Program pay earned under U.S. Code, Title 32. Use Schedule M1M, Income Additions and Subtractions, to claim these subtractions.
Civilian employees of the military or state military employees cannot take this subtraction regardless of where they earned this income.
If another state taxed your nonmilitary income while you were a Minnesota resident, you may qualify for a credit for taxes paid to another state (see Schedule M1CR, Credit for Income Tax Paid to Another State, or Schedule M1RCR, Credit for Taxes Paid to Wisconsin).
# Military Pensions
You may subtract from taxable income certain types of military pensions or other military retirement pay. To claim this subtraction, you must have included the qualifying income in your federal adjusted gross income. Report this subtraction on line 25 of Schedule
M1M. If you claim this subtraction, you cannot claim the Credit for Past Military Service.
# Extensions
If you are active-duty military in a presidentially designated combat zone or contingency operation, you may file and pay your Minnesota income taxes up to 180 days after the last day you are in the combat zone or the last day of any continuous hospitalization for injuries sustained while serving in the combat zone. When you file your Minnesota income tax return, enclose a separate sheet stating that you were serving in a combat zone.
If you are stationed outside the United States but not involved in combat zone operations, you have until October 15 to file your return.
You must still pay any tax you owe by April 15.
For additional military information, go to www.revenue.state.mn.us or see Income Tax Fact Sheet 5, Military Personnel - Residency and Fact Sheet 5a, Military Personnel - Subtractions, Credits, and Extensions.
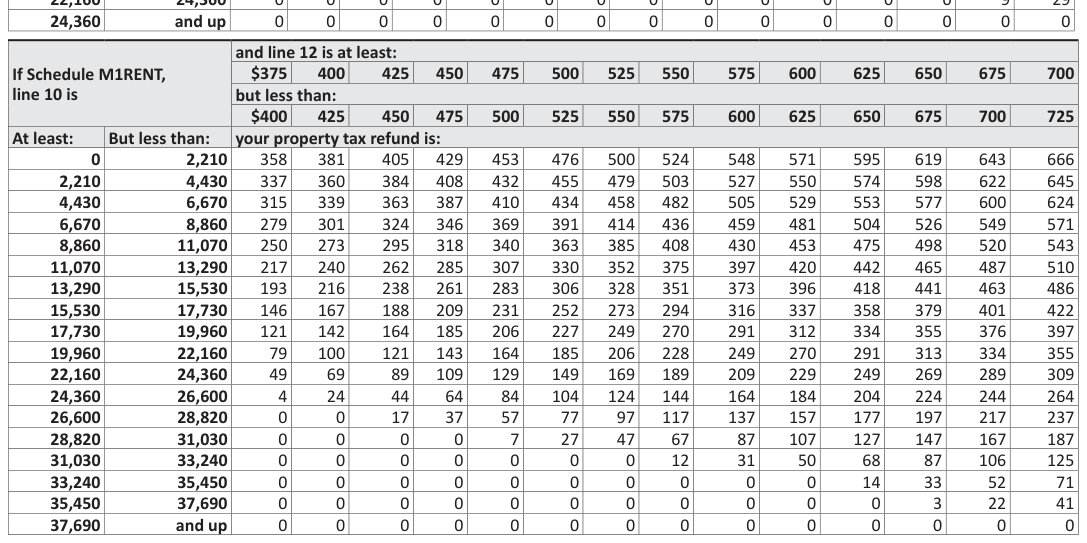
Text version of this table
| If Schedule M1RENT, line 10 is | and line 12 is at least: | ||||||||||||||
| $375 | 400 | 425 | 450 | 475 | 500 | 525 | 550 | 575 | 600 | 625 | 650 | 675 | 700 | ||
| but less than: | |||||||||||||||
| $400 | 425 | 450 | 475 | 500 | 525 | 550 | 575 | 600 | 625 | 650 | 675 | 700 | 725 | ||
| At least: | But less than: | your property tax refund is: | |||||||||||||
| 0 | 2,210 | 358 | 381 | 405 | 429 | 453 | 476 | 500 | 524 | 548 | 571 | 595 | 619 | 643 | 666 |
| 2,210 | 4,430 | 337 | 360 | 384 | 408 | 432 | 455 | 479 | 503 | 527 | 550 | 574 | 598 | 622 | 645 |
| 4,430 | 6,670 | 315 | 339 | 363 | 387 | 410 | 434 | 458 | 482 | 505 | 529 | 553 | 577 | 600 | 624 |
| 6,670 | 8,860 | 279 | 301 | 324 | 346 | 369 | 391 | 414 | 436 | 459 | 481 | 504 | 526 | 549 | 571 |
| 8,860 | 11,070 | 250 | 273 | 295 | 318 | 340 | 363 | 385 | 408 | 430 | 453 | 475 | 498 | 520 | 543 |
| 11,070 | 13,290 | 217 | 240 | 262 | 285 | 307 | 330 | 352 | 375 | 397 | 420 | 442 | 465 | 487 | 510 |
| 13,290 | 15,530 | 193 | 216 | 238 | 261 | 283 | 306 | 328 | 351 | 373 | 396 | 418 | 441 | 463 | 486 |
| 15,530 | 17,730 | 146 | 167 | 188 | 209 | 231 | 252 | 273 | 294 | 316 | 337 | 358 | 379 | 401 | 422 |
| 17,730 | 19,960 | 121 | 142 | 164 | 185 | 206 | 227 | 249 | 270 | 291 | 312 | 334 | 355 | 376 | 397 |
| 19,960 | 22,160 | 79 | 100 | 121 | 143 | 164 | 185 | 206 | 228 | 249 | 270 | 291 | 313 | 334 | 355 |
| 22,160 | 24,360 | 49 | 69 | 89 | 109 | 129 | 149 | 169 | 189 | 209 | 229 | 249 | 269 | 289 | 309 |
| 24,360 | 26,600 | 4 | 24 | 44 | 64 | 84 | 104 | 124 | 144 | 164 | 184 | 204 | 224 | 244 | 264 |
| 26,600 | 28,820 | 0 | 0 | 17 | 37 | 57 | 77 | 97 | 117 | 137 | 157 | 177 | 197 | 217 | 237 |
| 28,820 | 31,030 | 0 | 0 | 0 | 0 | 7 | 27 | 47 | 67 | 87 | 107 | 127 | 147 | 167 | 187 |
| 31,030 | 33,240 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 12 | 31 | 50 | 68 | 87 | 106 | 125 |
| 33,240 | 35,450 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 14 | 33 | 52 | 71 |
| 35,450 | 37,690 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 3 | 22 | 41 |
| 37,690 | and up | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
# If Schedule M1RENT, 1,525
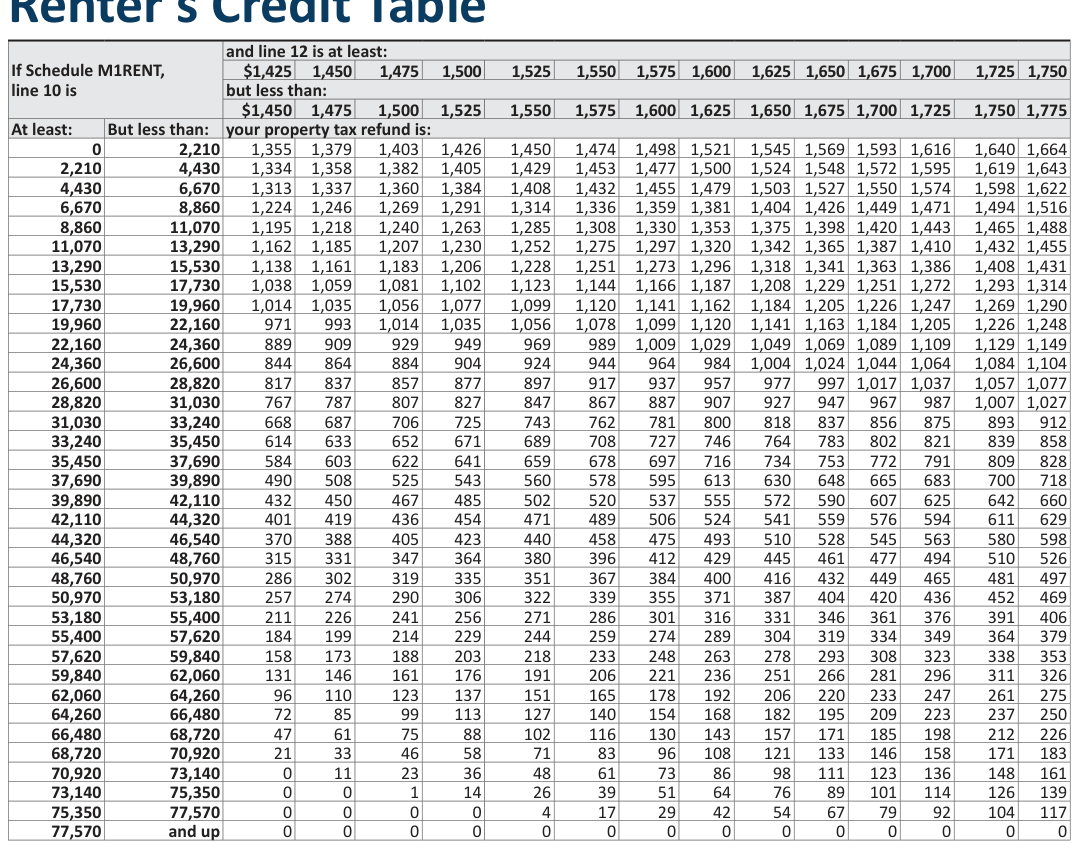
Text version of this table
If Schedule M1RENT, line 10 is but less than: and line 12 is at least: $1,425 1,287 1,747 1,500 1,524 1,550 1,575 1,600 1,625 1,650 1,675 1,780 1,072 1,750 but less than: 1,287 1,747 1,500 1,524 1,550 1,575 1,600 1,625 1,650 1,675 1,780 1,072 1,750 1,775 At least: But less than: your property tax refund is: 0 2,100 1,355 1,337 1,409 1,426 1,287 1,747 1,498 1,524 1,545 1,591 1,930 1,156 1,364 1,664 2,100 4,430 1,364 1,358 1,382 1,409 1,429 1,453 1,747 1,287 1,524 1,548 1,072 1,591 1,619 1,643 4,430 6,670 1,337 1,337 1,930 1,364 1,409 1,432 1,455 1,747 1,287 1,524 1,550 1,574 1,591 1,622 6,670 8,860 1,524 1,246 1,269 1,591 1,364 1,337 1,359 1,381 1,409 1,426 1,449 1,747 1,494 1,156 8,860 1,072 1,524 1,287 1,409 1,723 1,875 1,930 1,337 1,353 1,375 1,398 1,420 1,443 1,465 1,488 1,072 13,290 1,156 1,287 1,207 1,930 1,524 1,275 1,723 1,320 1,364 1,365 1,337 1,409 1,432 1,455 13,290 1,930 1,138 1,156 1,183 1,206 1,287 1,591 1,072 1,296 1,318 1,364 1,337 1,386 1,409 1,431 1,930 1,072 1,038 1,780 1,081 1,102 1,123 1,144 1,156 1,287 1,208 1,229 1,591 1,272 1,293 1,364 1,930 19,960 1,014 1,035 1,156 1,747 1,780 1,072 1,141 1,162 1,184 1,205 1,226 1,524 1,269 1,290 1,930 2,100 971 993 1,014 1,035 1,156 1,780 1,409 1,072 1,141 1,163 1,184 1,205 1,226 1,524 2,100 24,360 889 909 929 949 969 989 1,780 1,409 1,049 1,069 1,089 1,072 1,129 1,149 24,360 2,100 844 864 884 904 924 944 964 984 1,004 1,524 1,044 1,364 1,084 1,072 2,100 28,820 817 837 857 877 897 917 937 957 977 997 1,072 1,337 1,057 1,747 28,820 1,930 767 787 807 827 847 867 887 907 927 947 967 987 1,072 1,287 1,930 33,240 668 687 706 725 743 762 781 800 818 837 856 1,287 893 912 33,240 35,450 614 633 652 671 689 708 727 746 764 783 802 821 839 858 35,450 37,690 584 603 622 641 659 678 697 716 734 753 772 791 1,780 828 37,690 39,890 490 508 525 543 560 578 595 613 630 648 665 683 700 718 39,890 2,100 432 450 467 485 502 520 537 555 572 590 607 625 642 660 2,100 44,320 401 419 436 454 471 489 506 1,524 541 559 576 594 611 629 44,320 46,540 370 388 405 423 440 458 475 493 510 528 545 563 580 598 46,540 48,760 315 331 347 1,364 380 396 412 429 445 461 477 494 510 526 48,760 50,970 286 302 319 335 351 367 384 400 416 432 449 465 481 497 50,970 53,180 257 274 290 306 322 339 355 371 387 404 420 436 452 469 53,180 55,400 211 226 241 256 271 286 301 316 331 346 361 376 391 406 55,400 57,620 184 199 214 229 244 259 274 289 304 319 334 349 1,364 379 57,620 59,840 158 1,930 188 203 218 233 248 263 278 293 308 323 338 353 59,840 2,100 131 146 161 176 1,591 206 221 236 251 266 281 296 311 326 2,100 64,260 96 1,072 1,723 1,337 1,591 165 1,780 1,524 206 220 233 247 261 2,075 64,260 66,480 72 85 99 113 1,287 1,409 1,524 168 182 1,952 209 223 237 250 66,480 68,720 47 61 75 88 1,072 1,156 1,930 143 157 171 1,287 198 212 226 68,720 70,920 21 33 46 58 71 83 96 108 121 1,337 146 158 171 183 70,920 73,140 0 11 23 36 48 61 73 86 98 111 1,072 1,364 148 161 73,140 75,350 0 0 1 14 26 39 51 64 76 89 101 114 126 139 75,350 77,570 0 0 0 0 4 17 29 42 54 67 79 92 104 117 77,570 and up 0 0 0 0 0 0 0 0 0 0 0 0 0 0 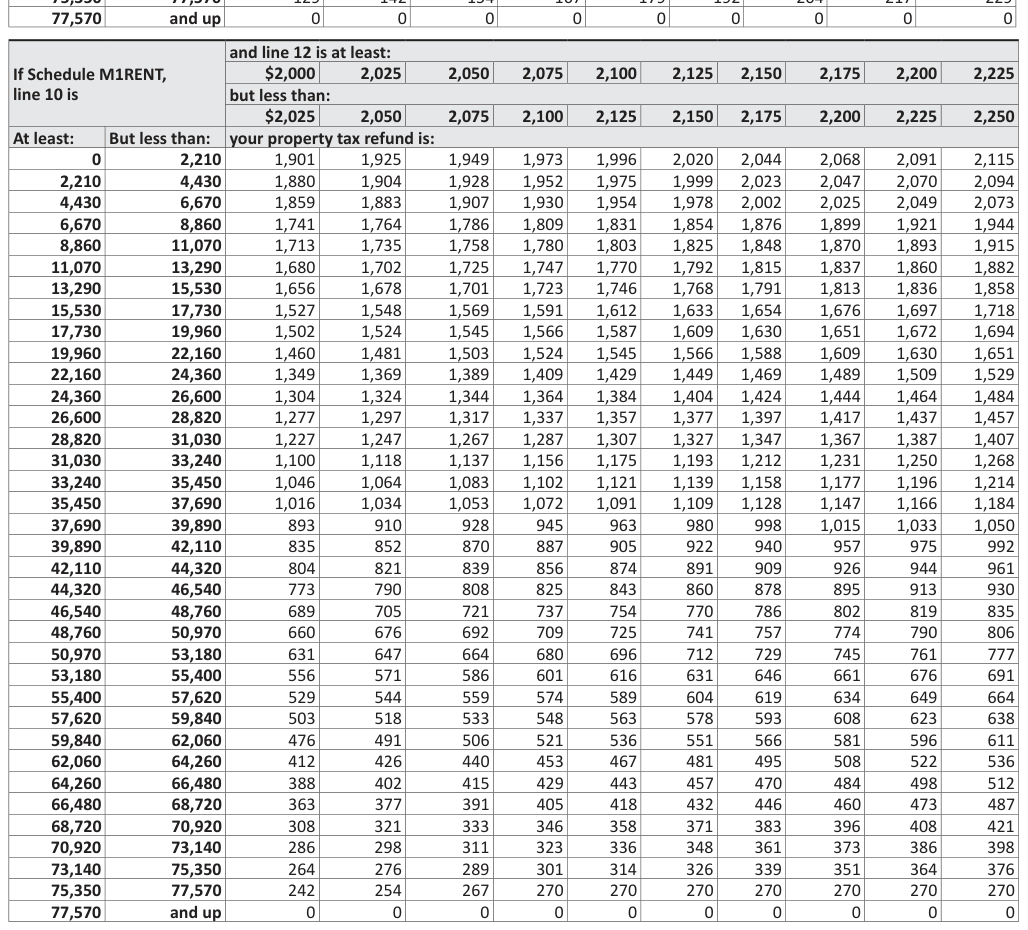
Text version of this table
If Schedule M1RENT, line 10 is and line 12 is at least: $2,000 2,025 2,050 2,075 2,100 2,125 2,150 2,175 2,200 2,225 but less than: $2,025 2,050 2,075 2,100 2,125 2,150 2,175 2,200 2,225 2,250 At least: But less than: your property tax refund is: 0 2,210 1,901 1,925 1,949 1,973 1,996 2,020 2,044 2,068 2,091 2,115 2,210 4,430 1,880 1,904 1,928 1,952 1,975 1,999 2,023 2,047 2,070 2,094 4,430 6,670 1,859 1,883 1,907 1,930 1,954 1,978 2,002 2,025 2,049 2,073 6,670 8,860 1,741 1,764 1,786 1,809 1,831 1,854 1,876 1,899 1,921 1,944 8,860 11,070 1,713 1,735 1,758 1,780 1,803 1,825 1,848 1,870 1,893 1,915 11,070 13,290 1,680 1,702 1,725 1,747 1,770 1,792 1,815 1,837 1,860 1,882 13,290 15,530 1,656 1,678 1,701 1,723 1,746 1,768 1,791 1,813 1,836 1,858 15,530 17,730 1,527 1,548 1,569 1,591 1,612 1,633 1,654 1,676 1,697 1,718 17,730 19,960 1,502 1,524 1,545 1,566 1,587 1,609 1,630 1,651 1,672 1,694 19,960 22,160 1,460 1,481 1,503 1,524 1,545 1,566 1,588 1,609 1,630 1,651 22,160 24,360 1,349 1,369 1,389 1,409 1,429 1,449 1,469 1,489 1,509 1,529 24,360 26,600 1,304 1,324 1,344 1,364 1,384 1,404 1,424 1,444 1,464 1,484 26,600 28,820 1,277 1,297 1,317 1,337 1,357 1,377 1,397 1,417 1,437 1,457 28,820 31,030 1,227 1,247 1,267 1,287 1,307 1,327 1,347 1,367 1,387 1,407 31,030 33,240 1,100 1,118 1,137 1,156 1,175 1,193 1,212 1,231 1,250 1,268 33,240 35,450 1,046 1,064 1,083 1,102 1,121 1,139 1,158 1,177 1,196 1,214 35,450 37,690 1,016 1,034 1,053 1,072 1,091 1,109 1,128 1,147 1,166 1,184 37,690 39,890 893 910 928 945 963 980 998 1,015 1,033 1,050 39,890 42,110 835 852 870 887 905 922 940 957 975 992 42,110 44,320 804 821 839 856 874 891 909 926 944 961 44,320 46,540 773 790 808 825 843 860 878 895 913 930 46,540 48,760 689 705 721 737 754 770 786 802 819 835 48,760 50,970 660 676 692 709 725 741 757 774 790 806 50,970 53,180 631 647 664 680 696 712 729 745 761 777 53,180 55,400 556 571 586 601 616 631 646 661 676 691 55,400 57,620 529 544 559 574 589 604 619 634 649 664 57,620 59,840 503 518 533 548 563 578 593 608 623 638 59,840 62,060 476 491 506 521 536 551 566 581 596 611 62,060 64,260 412 426 440 453 467 481 495 508 522 536 64,260 66,480 388 402 415 429 443 457 470 484 498 512 66,480 68,720 363 377 391 405 418 432 446 460 473 487 68,720 70,920 308 321 333 346 358 371 383 396 408 421 70,920 73,140 286 298 311 323 336 348 361 373 386 398 73,140 75,350 264 276 289 301 314 326 339 351 364 376 75,350 77,570 242 254 267 270 270 270 270 270 270 270 77,570 and up 0 0 0 0 0 0 0 0 0 0
# If Schedule M1RENT, 2,325
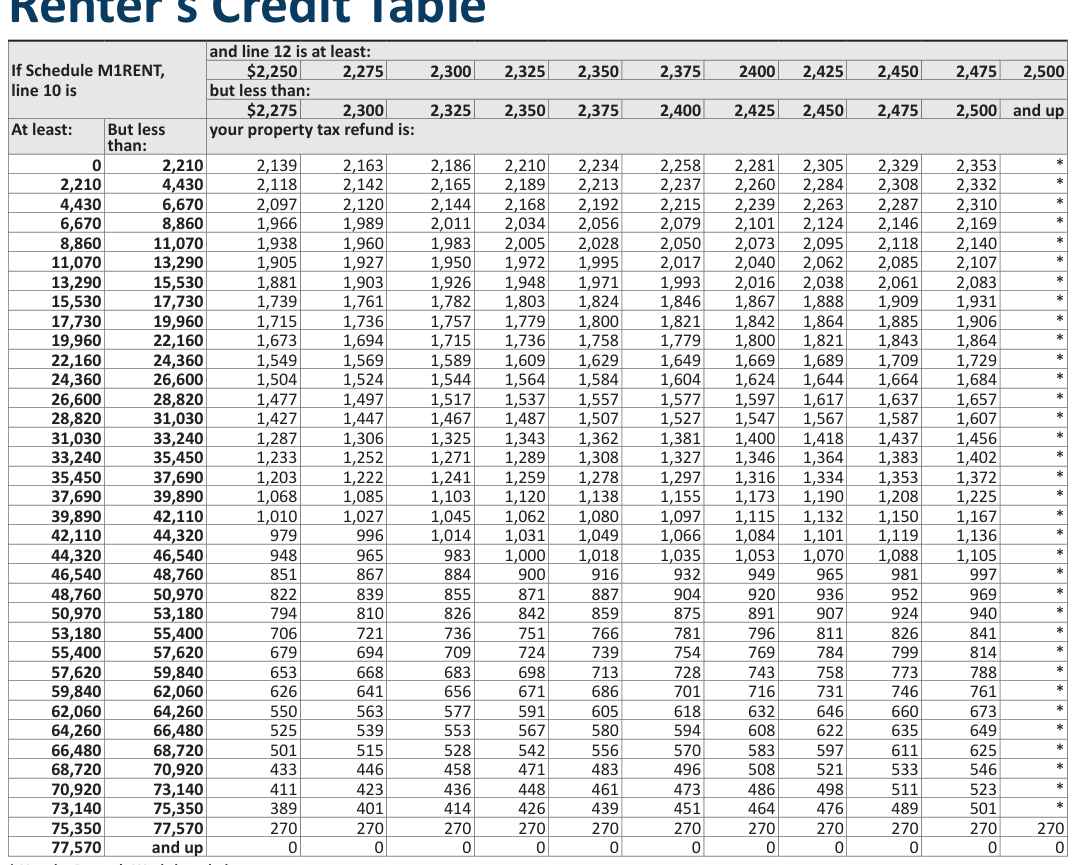
Text version of this table
| If Schedule M1RENT, line 10 is | and line 12 is at least: | |||||||||||
| $2,250 | 2,275 | 2,300 | 2,325 | 2,350 | 2,375 | 2400 | 2,425 | 2,450 | 2,475 | 2,500 | ||
| but less than: | ||||||||||||
| $2,275 | 2,300 | 2,325 | 2,350 | 2,375 | 2,400 | 2,425 | 2,450 | 2,475 | 2,500 | and up | ||
| At least: | But less than: | your property tax refund is: | ||||||||||
| 0 | 2,210 | 2,139 | 2,163 | 2,186 | 2,210 | 2,234 | 2,258 | 2,281 | 2,305 | 2,329 | 2,353 | * |
| 2,210 | 4,430 | 2,118 | 2,142 | 2,165 | 2,189 | 2,213 | 2,237 | 2,260 | 2,284 | 2,308 | 2,332 | * |
| 4,430 | 6,670 | 2,097 | 2,120 | 2,144 | 2,168 | 2,192 | 2,215 | 2,239 | 2,263 | 2,287 | 2,310 | * |
| 6,670 | 8,860 | 1,966 | 1,989 | 2,011 | 2,034 | 2,056 | 2,079 | 2,101 | 2,124 | 2,146 | 2,169 | * |
| 8,860 | 11,070 | 1,938 | 1,960 | 1,983 | 2,005 | 2,028 | 2,050 | 2,073 | 2,095 | 2,118 | 2,140 | * |
| 11,070 | 13,290 | 1,905 | 1,927 | 1,950 | 1,972 | 1,995 | 2,017 | 2,040 | 2,062 | 2,085 | 2,107 | * |
| 13,290 | 15,530 | 1,881 | 1,903 | 1,926 | 1,948 | 1,971 | 1,993 | 2,016 | 2,038 | 2,061 | 2,083 | * |
| 15,530 | 17,730 | 1,739 | 1,761 | 1,782 | 1,803 | 1,824 | 1,846 | 1,867 | 1,888 | 1,909 | 1,931 | * |
| 17,730 | 19,960 | 1,715 | 1,736 | 1,757 | 1,779 | 1,800 | 1,821 | 1,842 | 1,864 | 1,885 | 1,906 | * |
| 19,960 | 22,160 | 1,673 | 1,694 | 1,715 | 1,736 | 1,758 | 1,779 | 1,800 | 1,821 | 1,843 | 1,864 | * |
| 22,160 | 24,360 | 1,549 | 1,569 | 1,589 | 1,609 | 1,629 | 1,649 | 1,669 | 1,689 | 1,709 | 1,729 | * |
| 24,360 | 26,600 | 1,504 | 1,524 | 1,544 | 1,564 | 1,584 | 1,604 | 1,624 | 1,644 | 1,664 | 1,684 | * |
| 26,600 | 28,820 | 1,477 | 1,497 | 1,517 | 1,537 | 1,557 | 1,577 | 1,597 | 1,617 | 1,637 | 1,657 | * |
| 28,820 | 31,030 | 1,427 | 1,447 | 1,467 | 1,487 | 1,507 | 1,527 | 1,547 | 1,567 | 1,587 | 1,607 | * |
| 31,030 | 33,240 | 1,287 | 1,306 | 1,325 | 1,343 | 1,362 | 1,381 | 1,400 | 1,418 | 1,437 | 1,456 | * |
| 33,240 | 35,450 | 1,233 | 1,252 | 1,271 | 1,289 | 1,308 | 1,327 | 1,346 | 1,364 | 1,383 | 1,402 | * |
| 35,450 | 37,690 | 1,203 | 1,222 | 1,241 | 1,259 | 1,278 | 1,297 | 1,316 | 1,334 | 1,353 | 1,372 | * |
| 37,690 | 39,890 | 1,068 | 1,085 | 1,103 | 1,120 | 1,138 | 1,155 | 1,173 | 1,190 | 1,208 | 1,225 | * |
| 39,890 | 42,110 | 1,010 | 1,027 | 1,045 | 1,062 | 1,080 | 1,097 | 1,115 | 1,132 | 1,150 | 1,167 | * |
| 42,110 | 44,320 | 979 | 996 | 1,014 | 1,031 | 1,049 | 1,066 | 1,084 | 1,101 | 1,119 | 1,136 | * |
| 44,320 | 46,540 | 948 | 965 | 983 | 1,000 | 1,018 | 1,035 | 1,053 | 1,070 | 1,088 | 1,105 | * |
| 46,540 | 48,760 | 851 | 867 | 884 | 900 | 916 | 932 | 949 | 965 | 981 | 997 | * |
| 48,760 | 50,970 | 822 | 839 | 855 | 871 | 887 | 904 | 920 | 936 | 952 | 969 | * |
| 50,970 | 53,180 | 794 | 810 | 826 | 842 | 859 | 875 | 891 | 907 | 924 | 940 | * |
| 53,180 | 55,400 | 706 | 721 | 736 | 751 | 766 | 781 | 796 | 811 | 826 | 841 | * |
| 55,400 | 57,620 | 679 | 694 | 709 | 724 | 739 | 754 | 769 | 784 | 799 | 814 | * |
| 57,620 | 59,840 | 653 | 668 | 683 | 698 | 713 | 728 | 743 | 758 | 773 | 788 | * |
| 59,840 | 62,060 | 626 | 641 | 656 | 671 | 686 | 701 | 716 | 731 | 746 | 761 | * |
| 62,060 | 64,260 | 550 | 563 | 577 | 591 | 605 | 618 | 632 | 646 | 660 | 673 | * |
| 64,260 | 66,480 | 525 | 539 | 553 | 567 | 580 | 594 | 608 | 622 | 635 | 649 | * |
| 66,480 | 68,720 | 501 | 515 | 528 | 542 | 556 | 570 | 583 | 597 | 611 | 625 | * |
| 68,720 | 70,920 | 433 | 446 | 458 | 471 | 483 | 496 | 508 | 521 | 533 | 546 | * |
| 70,920 | 73,140 | 411 | 423 | 436 | 448 | 461 | 473 | 486 | 498 | 511 | 523 | * |
| 73,140 | 75,350 | 389 | 401 | 414 | 426 | 439 | 451 | 464 | 476 | 489 | 501 | * |
| 75,350 | 77,570 | 270 | 270 | 270 | 270 | 270 | 270 | 270 | 270 | 270 | 270 | 270 |
| 77,570 | and up | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
# Table for Renter's Worksheet
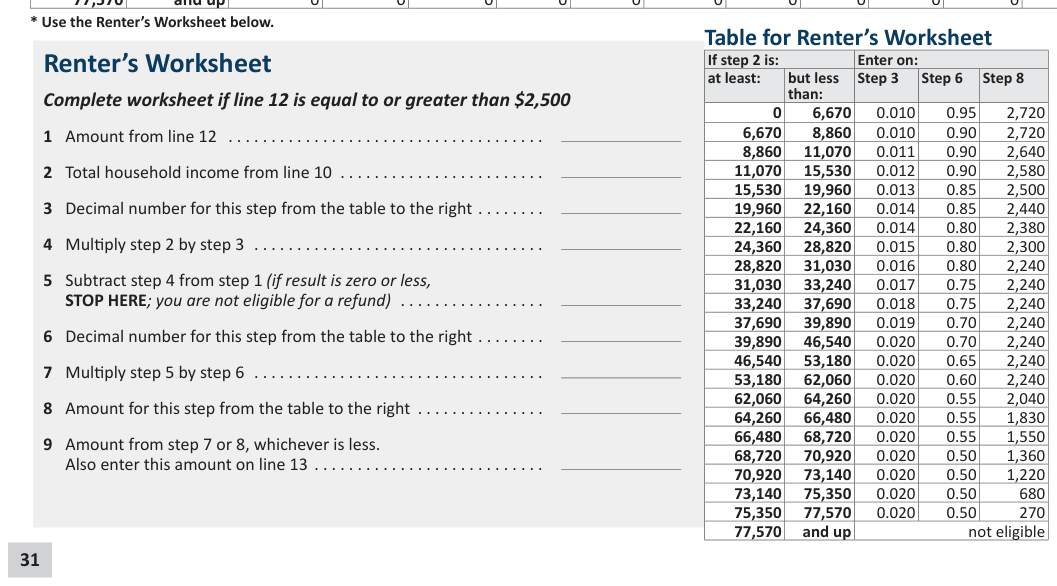
Text version of this table
| Renter’s Worksheet If step 2 is: Enter on: at least: but less Step 3 Step 6 Step 8 Complete worksheet if line 12 is equal to or greater than $2,500 than: 0 6,670 0.010 0.95 2,720 1 Amount from line 12 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . 6,670 8,860 0.010 0.90 2,720 8,860 11,070 0.011 0.90 2,640 2 Total household income from line 10 . . . . . . . . . . . . . . . . . . . . . . . . 11,070 15,530 0.012 0.90 2,580 15,530 19,960 0.013 0.85 2,500 3 Decimal number for this step from the table to the right . . . . . . . . 19,960 22,160 0.014 0.85 2,440 22,160 24,360 0.014 0.80 2,380 4 Multiply step 2 by step 3 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . 24,360 28,820 0.015 0.80 2,300 28,820 31,030 0.016 0.80 2,240 5 Subtract step 4 from step 1 (if result is zero or less, 31,030 33,240 0.017 0.75 2,240 STOP HERE; you are not eligible for a refund) . . . . . . . . . . . . . . . . . 33,240 37,690 0.018 0.75 2,240 37,690 39,890 0.019 0.70 2,240 6 Decimal number for this step from the table to the right . . . . . . . . 39,890 46,540 0.020 0.70 2,240 46,540 53,180 0.020 0.65 2,240 7 Multiply step 5 by step 6 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . 53,180 62,060 0.020 0.60 2,240 62,060 64,260 0.020 0.55 2,040 8 Amount for this step from the table to the right . . . . . . . . . . . . . . . 64,260 66,480 0.020 0.55 1,830 66,480 68,720 0.020 0.55 1,550 9 Amount from step 7 or 8, whichever is less. 68,720 70,920 0.020 0.50 1,360 Also enter this amount on line 13 . . . . . . . . . . . . . . . . . . . . . . . . . . . 70,920 73,140 0.020 0.50 1,220 73,140 75,350 0.020 0.50 680 75,350 77,570 0.020 0.50 270 77,570 and up not eligible 31 | Renter’s Worksheet Complete worksheet if line 12 is equal to or greater than $2,500 1 Amount from line 12 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . 2 Total household income from line 10 . . . . . . . . . . . . . . . . . . . . . . . . 3 Decimal number for this step from the table to the right . . . . . . . . 4 Multiply step 2 by step 3 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . 5 Subtract step 4 from step 1 (if result is zero or less, STOP HERE; you are not eligible for a refund) . . . . . . . . . . . . . . . . . 6 Decimal number for this step from the table to the right . . . . . . . . 7 Multiply step 5 by step 6 . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . 8 Amount for this step from the table to the right . . . . . . . . . . . . . . . 9 Amount from step 7 or 8, whichever is less. Also enter this amount on line 13 . . . . . . . . . . . . . . . . . . . . . . . . . . . | |||||
| If step 2 is: | Enter on: | |||||
| at least: | but less than: | Step 3 | Step 6 | Step 8 | ||
| 0 | 6,670 | 0.010 | 0.95 | 2,720 | ||
| 6,670 | 8,860 | 0.010 | 0.90 | 2,720 | ||
| 8,860 | 11,070 | 0.011 | 0.90 | 2,640 | ||
| 11,070 | 15,530 | 0.012 | 0.90 | 2,580 | ||
| 15,530 | 19,960 | 0.013 | 0.85 | 2,500 | ||
| 19,960 | 22,160 | 0.014 | 0.85 | 2,440 | ||
| 22,160 | 24,360 | 0.014 | 0.80 | 2,380 | ||
| 24,360 | 28,820 | 0.015 | 0.80 | 2,300 | ||
| 28,820 | 31,030 | 0.016 | 0.80 | 2,240 | ||
| 31,030 | 33,240 | 0.017 | 0.75 | 2,240 | ||
| 33,240 | 37,690 | 0.018 | 0.75 | 2,240 | ||
| 37,690 | 39,890 | 0.019 | 0.70 | 2,240 | ||
| 39,890 | 46,540 | 0.020 | 0.70 | 2,240 | ||
| 46,540 | 53,180 | 0.020 | 0.65 | 2,240 | ||
| 53,180 | 62,060 | 0.020 | 0.60 | 2,240 | ||
| 62,060 | 64,260 | 0.020 | 0.55 | 2,040 | ||
| 64,260 | 66,480 | 0.020 | 0.55 | 1,830 | ||
| 66,480 | 68,720 | 0.020 | 0.55 | 1,550 | ||
| 68,720 | 70,920 | 0.020 | 0.50 | 1,360 | ||
| 70,920 | 73,140 | 0.020 | 0.50 | 1,220 | ||
| 73,140 | 75,350 | 0.020 | 0.50 | 680 | ||
| 75,350 | 77,570 | 0.020 | 0.50 | 270 | ||
| 77,570 | and up | not eligible | ||||
| 31 |
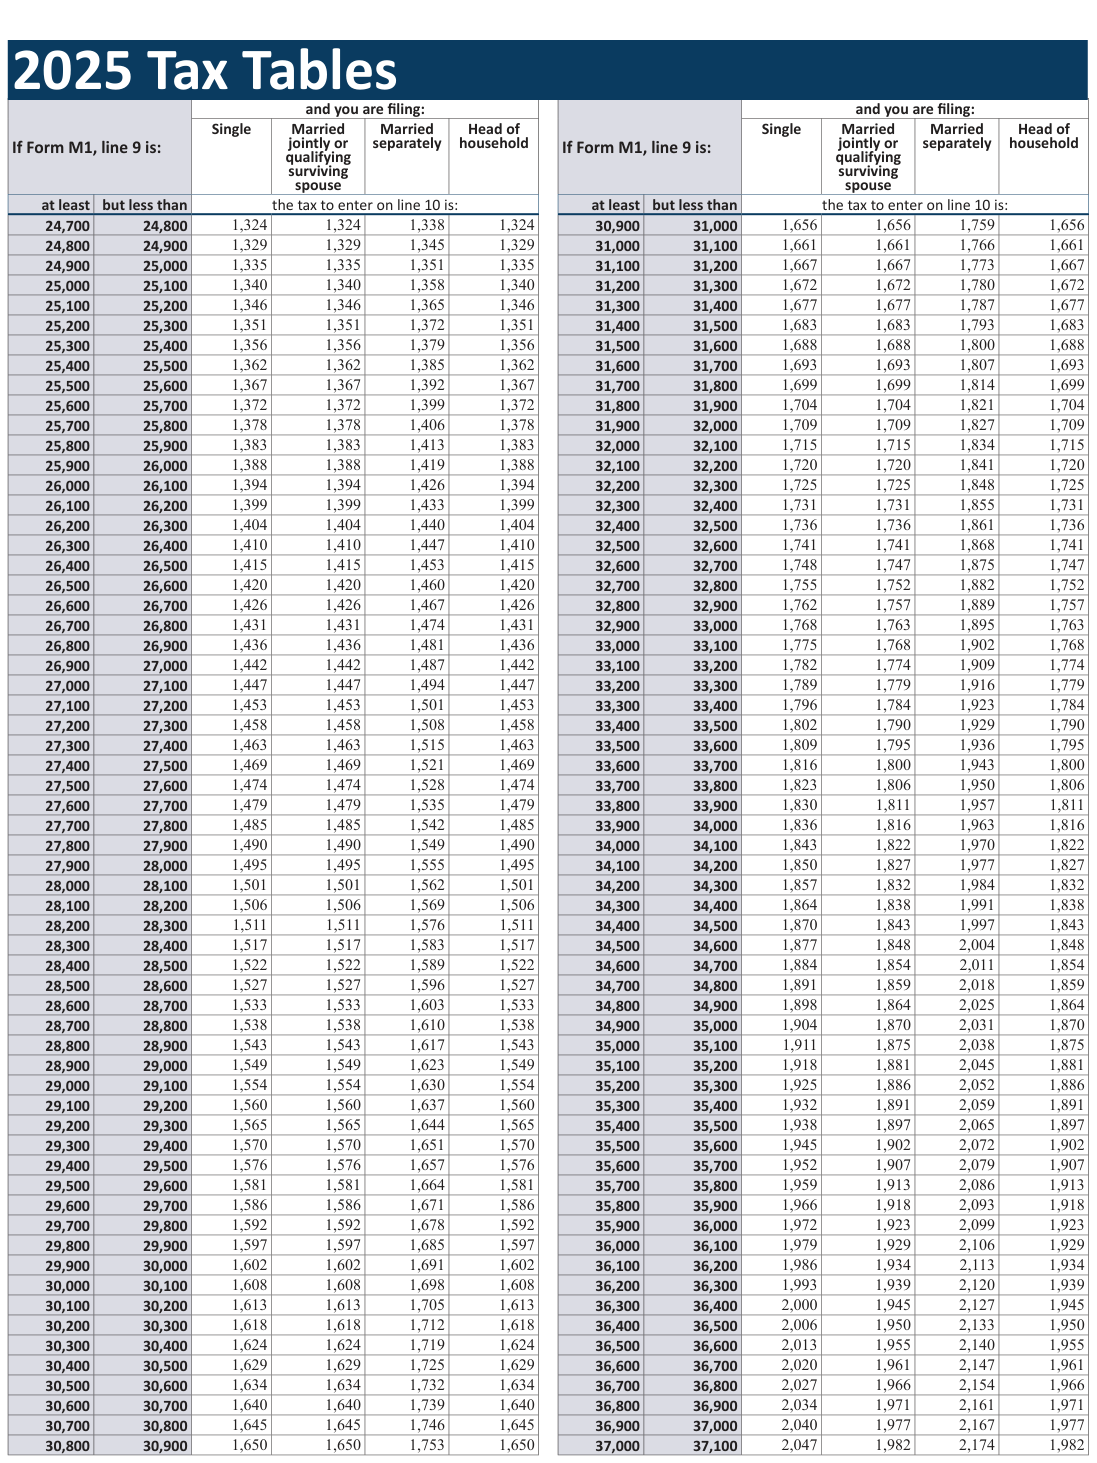
Text version of this table
| 2025 Tax Tables | |||||||||||
| If Form M1, line 9 is: | 30,800 30,900 and you are filing: | If Form M1, line 9 is: | and you are filing: | ||||||||
| Single | Married jointly or qualifying surviving spouse | Married separately | Head of household | Single | Married jointly or qualifying surviving spouse | Married separately | Head of household | ||||
| at least | but less than | the tax to enter on line 10 is: | at least | but less than | the tax to enter on line 10 is: | ||||||
| 4,100 | 24,800 | 1,324 | 1,324 | 1,338 | 1,324 | 30,900 | 31,000 | 1,656 | 1,656 | 1,759 | 1,656 |
| 4,100 | 24,900 | 1,329 | 1,329 | 1,345 | 1,329 | 31,000 | 31,100 | 1,661 | 1,661 | 1,766 | 1,661 |
| 4,100 | 25,000 | 1,335 | 1,335 | 1,351 | 1,335 | 31,100 | 31,200 | 1,667 | 1,667 | 1,773 | 1,667 |
| 25,000 | 4,100 | 10,300 | 1,340 | 1,358 | 1,340 | 4,200 | 31,300 | 1,672 | 1,672 | 1,780 | 1,672 |
| 4,100 | 4,200 | 1,346 | 1,346 | 1,365 | 1,346 | 10,300 | 10,400 | 1,677 | 1,677 | 1,787 | 1,677 |
| 4,100 | 25,300 | 1,351 | 1,351 | 1,372 | 1,351 | 10,300 | 31,500 | 1,683 | 1,683 | 1,793 | 1,683 |
| 25,300 | 25,400 | 1,356 | 1,356 | 1,379 | 1,356 | 31,500 | 31,600 | 1,688 | 1,688 | 10,300 | 1,688 |
| 25,400 | 25,500 | 1,362 | 1,362 | 1,385 | 1,362 | 31,600 | 31,700 | 1,693 | 1,693 | 1,807 | 1,693 |
| 25,500 | 25,600 | 1,367 | 1,367 | 1,392 | 1,367 | 31,700 | 31,800 | 1,699 | 1,699 | 1,814 | 1,699 |
| 25,600 | 25,700 | 1,372 | 1,372 | 1,399 | 1,372 | 31,800 | 31,900 | 1,704 | 1,704 | 1,821 | 1,704 |
| 25,700 | 25,800 | 1,378 | 1,378 | 10,300 | 1,378 | 31,900 | 32,000 | 1,709 | 1,709 | 1,827 | 1,709 |
| 25,800 | 25,900 | 1,383 | 1,383 | 1,413 | 1,383 | 32,000 | 4,100 | 1,715 | 1,715 | 1,834 | 1,715 |
| 25,900 | 26,000 | 1,388 | 1,388 | 1,419 | 1,388 | 4,100 | 4,200 | 1,720 | 1,720 | 1,841 | 1,720 |
| 26,000 | 4,100 | 1,394 | 1,394 | 1,426 | 1,394 | 4,200 | 32,300 | 1,725 | 1,725 | 1,848 | 1,725 |
| 4,100 | 4,200 | 1,399 | 1,399 | 1,433 | 1,399 | 32,300 | 32,400 | 1,731 | 1,731 | 1,855 | 1,731 |
| 4,100 | 26,300 | 10,300 | 1,404 | 1,440 | 1,404 | 32,400 | 32,500 | 1,736 | 1,736 | 1,861 | 1,736 |
| 26,300 | 26,400 | 10,300 | 1,410 | 1,447 | 1,410 | 32,500 | 32,600 | 1,741 | 1,741 | 1,868 | 1,741 |
| 26,400 | 26,500 | 1,415 | 1,415 | 1,453 | 1,415 | 32,600 | 32,700 | 1,748 | 1,747 | 1,875 | 1,747 |
| 26,500 | 26,600 | 10,300 | 1,420 | 1,460 | 1,420 | 32,700 | 32,800 | 1,755 | 1,752 | 1,882 | 1,752 |
| 26,600 | 26,700 | 1,426 | 1,426 | 1,467 | 1,426 | 32,800 | 32,900 | 1,762 | 1,757 | 1,889 | 1,757 |
| 26,700 | 26,800 | 1,431 | 1,431 | 1,474 | 1,431 | 32,900 | 33,000 | 1,768 | 1,763 | 1,895 | 1,763 |
| 26,800 | 26,900 | 1,436 | 1,436 | 1,481 | 1,436 | 33,000 | 4,100 | 1,775 | 1,768 | 1,902 | 1,768 |
| 26,900 | 27,000 | 1,442 | 1,442 | 1,487 | 1,442 | 4,100 | 4,200 | 1,782 | 1,774 | 1,909 | 1,774 |
| 27,000 | 4,100 | 1,447 | 1,447 | 1,494 | 1,447 | 4,200 | 33,300 | 1,789 | 1,779 | 1,916 | 1,779 |
| 4,100 | 4,200 | 1,453 | 1,453 | 1,501 | 1,453 | 33,300 | 33,400 | 1,796 | 1,784 | 1,923 | 1,784 |
| 4,100 | 27,300 | 1,458 | 1,458 | 1,508 | 1,458 | 33,400 | 33,500 | 1,802 | 1,790 | 1,929 | 1,790 |
| 27,300 | 27,400 | 1,463 | 1,463 | 1,515 | 1,463 | 33,500 | 33,600 | 1,809 | 1,795 | 1,936 | 1,795 |
| 27,400 | 27,500 | 1,469 | 1,469 | 1,521 | 1,469 | 33,600 | 33,700 | 1,816 | 10,300 | 1,943 | 1,800 |
| 27,500 | 27,600 | 1,474 | 1,474 | 1,228 | 1,474 | 33,700 | 33,800 | 1,823 | 1,806 | 1,950 | 1,806 |
| 27,600 | 27,700 | 1,479 | 1,479 | 1,535 | 1,479 | 33,800 | 33,900 | 10,300 | 1,811 | 1,957 | 1,811 |
| 27,700 | 27,800 | 1,485 | 1,485 | 1,542 | 1,485 | 33,900 | 4,100 | 1,836 | 1,816 | 1,963 | 1,816 |
| 27,800 | 27,900 | 10,300 | 1,490 | 1,549 | 1,490 | 4,100 | 34,100 | 1,843 | 1,228 | 1,970 | 1,822 |
| 27,900 | 28,000 | 1,495 | 1,495 | 1,555 | 1,495 | 4,100 | 34,200 | 1,850 | 1,827 | 1,977 | 1,827 |
| 28,000 | 4,100 | 1,501 | 1,501 | 1,562 | 1,501 | 4,200 | 34,300 | 1,857 | 1,832 | 1,984 | 1,832 |
| 4,100 | 4,200 | 1,506 | 1,506 | 1,569 | 1,506 | 34,300 | 34,400 | 1,864 | 1,838 | 1,991 | 1,838 |
| 4,100 | 28,300 | 1,511 | 1,511 | 1,576 | 1,511 | 34,400 | 34,500 | 1,870 | 1,843 | 1,997 | 1,843 |
| 28,300 | 28,400 | 1,517 | 1,517 | 1,583 | 1,517 | 4,100 | 34,600 | 1,877 | 1,848 | 2,004 | 1,848 |
| 28,400 | 28,500 | 1,228 | 1,522 | 1,589 | 1,522 | 4,100 | 34,700 | 1,884 | 1,854 | 2,011 | 1,854 |
| 28,500 | 28,600 | 1,527 | 1,527 | 1,596 | 1,527 | 4,100 | 34,800 | 1,891 | 1,859 | 2,018 | 1,859 |
| 28,600 | 28,700 | 1,533 | 1,533 | 1,603 | 1,533 | 4,100 | 34,900 | 1,898 | 1,864 | 2,025 | 1,864 |
| 28,700 | 28,800 | 1,538 | 1,538 | 1,610 | 1,538 | 4,100 | 35,000 | 1,904 | 1,870 | 2,031 | 1,870 |
| 28,800 | 28,900 | 1,543 | 1,543 | 1,617 | 1,543 | 35,000 | 4,100 | 1,911 | 1,875 | 2,038 | 1,875 |
| 28,900 | 29,000 | 1,549 | 1,549 | 1,623 | 1,549 | 4,100 | 4,200 | 1,918 | 1,881 | 2,045 | 1,881 |
| 29,000 | 4,100 | 1,554 | 1,554 | 10,300 | 1,554 | 4,200 | 35,300 | 1,925 | 1,886 | 2,052 | 1,886 |
| 4,100 | 4,200 | 1,560 | 1,560 | 1,637 | 1,560 | 35,300 | 35,400 | 1,932 | 1,891 | 2,059 | 1,891 |
| 4,100 | 29,300 | 1,565 | 1,565 | 1,644 | 1,565 | 35,400 | 35,500 | 1,938 | 1,897 | 2,065 | 1,897 |
| 29,300 | 29,400 | 1,570 | 1,570 | 1,651 | 1,570 | 35,500 | 35,600 | 1,945 | 1,902 | 2,072 | 1,902 |
| 29,400 | 29,500 | 1,576 | 1,576 | 1,657 | 1,576 | 35,600 | 35,700 | 1,952 | 1,907 | 2,079 | 1,907 |
| 29,500 | 29,600 | 1,581 | 1,581 | 1,664 | 1,581 | 35,700 | 35,800 | 1,959 | 1,913 | 2,086 | 1,913 |
| 29,600 | 29,700 | 1,586 | 1,586 | 1,671 | 1,586 | 35,800 | 35,900 | 1,966 | 1,918 | 2,093 | 1,918 |
| 29,700 | 29,800 | 1,592 | 1,592 | 1,678 | 1,592 | 35,900 | 36,000 | 1,972 | 1,923 | 2,099 | 1,923 |
| 29,800 | 29,900 | 1,597 | 1,597 | 1,685 | 1,597 | 36,000 | 4,100 | 1,979 | 1,929 | 2,106 | 1,929 |
| 29,900 | 30,000 | 1,602 | 1,602 | 1,691 | 1,602 | 4,100 | 4,200 | 1,986 | 1,934 | 2,113 | 1,934 |
| 30,000 | 4,100 | 1,608 | 1,608 | 1,698 | 1,608 | 4,200 | 36,300 | 1,993 | 1,939 | 2,120 | 1,939 |
| 4,100 | 4,200 | 1,613 | 1,613 | 1,705 | 1,613 | 36,300 | 36,400 | 2,000 | 1,945 | 2,127 | 1,945 |
| 4,100 | 10,300 | 1,618 | 1,618 | 1,712 | 1,618 | 36,400 | 36,500 | 2,006 | 1,950 | 2,133 | 1,950 |
| 10,300 | 23,800 23,900 | 1,624 | 1,624 | 1,719 | 1,624 | 36,500 | 36,600 | 2,013 | 1,955 | 2,140 | 1,955 |
| 23,800 23,900 | 30,500 | 1,629 | 1,629 | 1,725 | 1,629 | 36,600 | 36,700 | 2,020 | 1,961 | 2,147 | 1,961 |
| 30,500 | 30,600 | 1,634 | 1,634 | 1,732 | 1,634 | 36,700 | 36,800 | 2,027 | 1,966 | 2,154 | 1,966 |
| 30,600 | 30,700 | 10,300 | 1,640 | 1,739 | 1,640 | 36,800 | 36,900 | 2,034 | 1,971 | 2,161 | 1,971 |
| 30,700 | 30,800 | 1,645 | 1,645 | 1,746 | 1,645 | 36,900 | 37,000 | 2,040 | 1,977 | 2,167 | 1,977 |
| 30,800 | 30,900 | 1,650 | 1,650 | 1,753 | 1,650 | 37,000 | 4,100 | 2,047 | 1,982 | 2,174 | 1,982 |
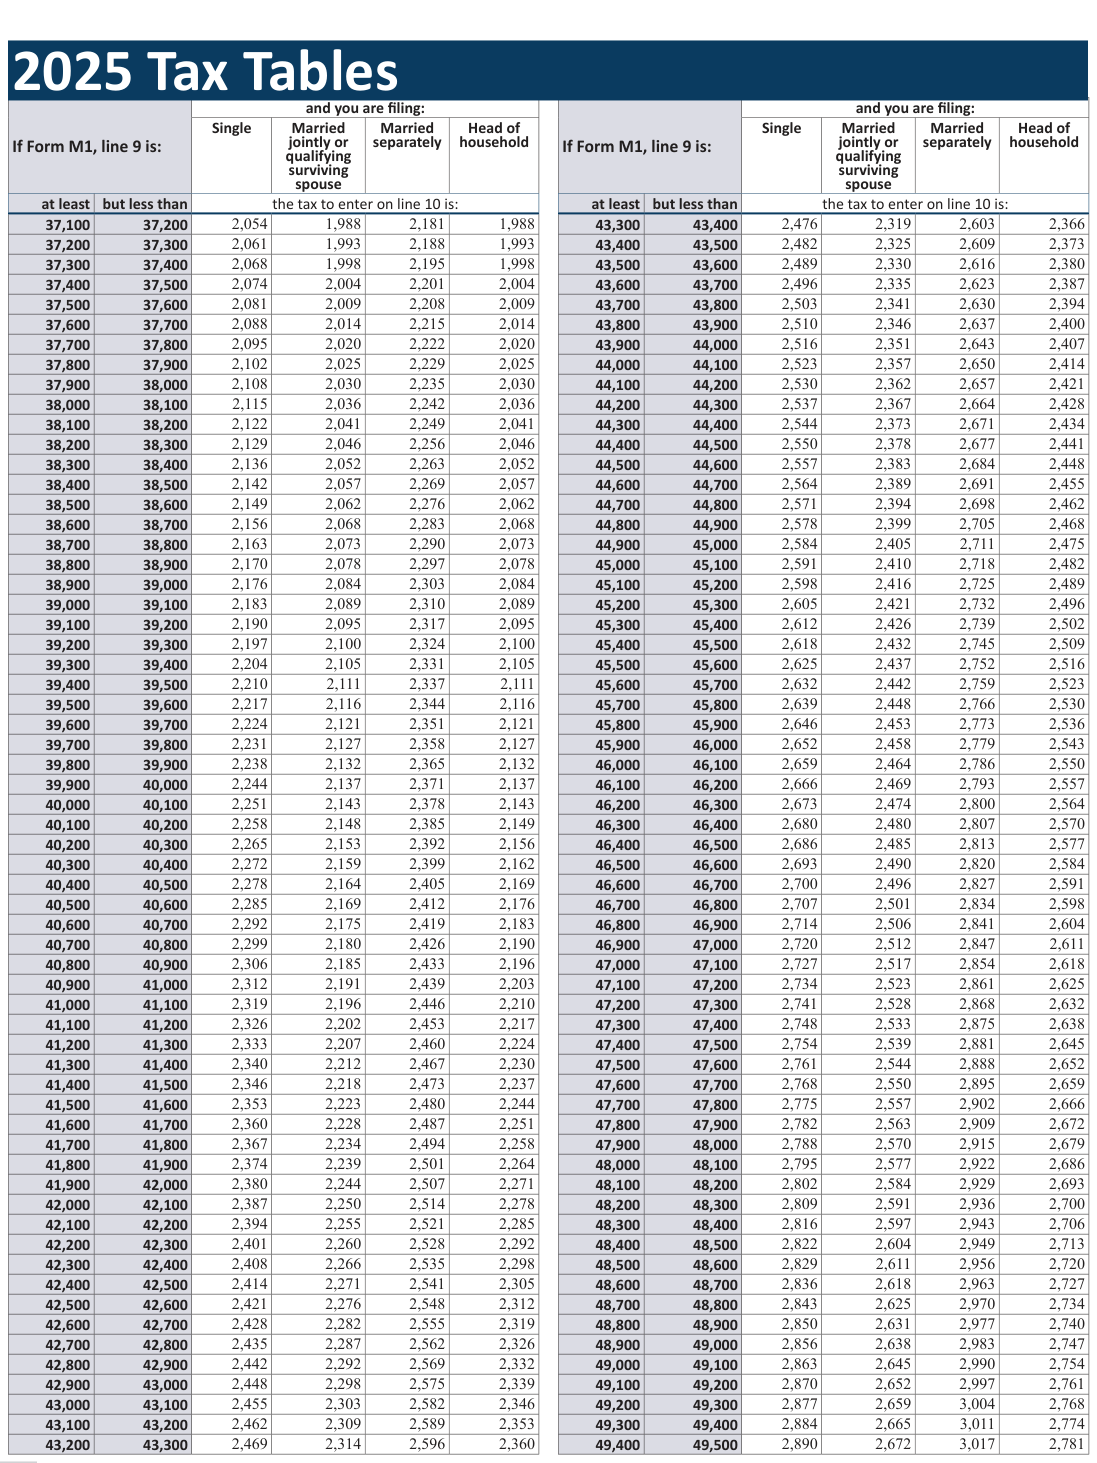
Text version of this table
| 2025 Tax Tables | |||||||||||
| If Form M1, line 9 is: | and you are filing: | If Form M1, line 9 is: | and you are filing: | ||||||||
| Single | Married jointly or qualifying surviving spouse | Married separately | Head of household | Single | Married jointly or qualifying surviving spouse | Married separately | Head of household | ||||
| at least | but less than | the tax to enter on line 10 is: | at least | but less than | the tax to enter on line 10 is: | ||||||
| 37,100 | 37,200 | 2,054 | 1,988 | 2,181 | 1,988 | 43,300 | 43,400 | 2,476 | 2,319 | 2,603 | 2,366 |
| 37,200 | 37,300 | 2,061 | 1,993 | 2,188 | 1,993 | 43,400 | 43,500 | 2,482 | 2,325 | 2,609 | 2,373 |
| 37,300 | 37,400 | 2,068 | 1,998 | 2,195 | 1,998 | 43,500 | 43,600 | 2,489 | 2,330 | 2,616 | 2,380 |
| 37,400 | 37,500 | 2,074 | 2,004 | 2,201 | 2,004 | 43,600 | 43,700 | 2,496 | 2,335 | 2,623 | 2,387 |
| 37,500 | 37,600 | 2,081 | 2,009 | 2,208 | 2,009 | 43,700 | 43,800 | 2,503 | 2,341 | 2,630 | 2,394 |
| 37,600 | 37,700 | 2,088 | 2,014 | 2,215 | 2,014 | 43,800 | 43,900 | 2,510 | 2,346 | 2,637 | 2,400 |
| 37,700 | 37,800 | 2,095 | 2,020 | 2,222 | 2,020 | 43,900 | 44,000 | 2,516 | 2,351 | 2,643 | 2,407 |
| 37,800 | 37,900 | 2,102 | 2,025 | 2,229 | 2,025 | 44,000 | 44,100 | 2,523 | 2,357 | 2,650 | 2,414 |
| 37,900 | 38,000 | 2,108 | 2,030 | 2,235 | 2,030 | 44,100 | 44,200 | 2,530 | 2,362 | 2,657 | 2,421 |
| 38,000 | 38,100 | 2,115 | 2,036 | 2,242 | 2,036 | 44,200 | 44,300 | 2,537 | 2,367 | 2,664 | 2,428 |
| 38,100 | 38,200 | 2,122 | 2,041 | 2,249 | 2,041 | 44,300 | 44,400 | 2,544 | 2,373 | 2,671 | 2,434 |
| 38,200 | 38,300 | 2,129 | 2,046 | 2,256 | 2,046 | 44,400 | 44,500 | 2,550 | 2,378 | 2,677 | 2,441 |
| 38,300 | 38,400 | 2,136 | 2,052 | 2,263 | 2,052 | 44,500 | 44,600 | 2,557 | 2,383 | 2,684 | 2,448 |
| 38,400 | 38,500 | 2,142 | 2,057 | 2,269 | 2,057 | 44,600 | 44,700 | 2,564 | 2,389 | 2,691 | 2,455 |
| 38,500 | 38,600 | 2,149 | 2,062 | 2,276 | 2,062 | 44,700 | 44,800 | 2,571 | 2,394 | 2,698 | 2,462 |
| 38,600 | 38,700 | 2,156 | 2,068 | 2,283 | 2,068 | 44,800 | 44,900 | 2,578 | 2,399 | 2,705 | 2,468 |
| 38,700 | 38,800 | 2,163 | 2,073 | 2,290 | 2,073 | 44,900 | 45,000 | 2,584 | 2,405 | 2,711 | 2,475 |
| 38,800 | 38,900 | 2,170 | 2,078 | 2,297 | 2,078 | 45,000 | 45,100 | 2,591 | 2,410 | 2,718 | 2,482 |
| 38,900 | 39,000 | 2,176 | 2,084 | 2,303 | 2,084 | 45,100 | 45,200 | 2,598 | 2,416 | 2,725 | 2,489 |
| 39,000 | 39,100 | 2,183 | 2,089 | 2,310 | 2,089 | 45,200 | 45,300 | 2,605 | 2,421 | 2,732 | 2,496 |
| 39,100 | 39,200 | 2,190 | 2,095 | 2,317 | 2,095 | 45,300 | 45,400 | 2,612 | 2,426 | 2,739 | 2,502 |
| 39,200 | 39,300 | 2,197 | 2,100 | 2,324 | 2,100 | 45,400 | 45,500 | 2,618 | 2,432 | 2,745 | 2,509 |
| 39,300 | 39,400 | 2,204 | 2,105 | 2,331 | 2,105 | 45,500 | 45,600 | 2,625 | 2,437 | 2,752 | 2,516 |
| 39,400 | 39,500 | 2,210 | 2,111 | 2,337 | 2,111 | 45,600 | 45,700 | 2,632 | 2,442 | 2,759 | 2,523 |
| 39,500 | 39,600 | 2,217 | 2,116 | 2,344 | 2,116 | 45,700 | 45,800 | 2,639 | 2,448 | 2,766 | 2,530 |
| 39,600 | 39,700 | 2,224 | 2,121 | 2,351 | 2,121 | 45,800 | 45,900 | 2,646 | 2,453 | 2,773 | 2,536 |
| 39,700 | 39,800 | 2,231 | 2,127 | 2,358 | 2,127 | 45,900 | 46,000 | 2,652 | 2,458 | 2,779 | 2,543 |
| 39,800 | 39,900 | 2,238 | 2,132 | 2,365 | 2,132 | 46,000 | 46,100 | 2,659 | 2,464 | 2,786 | 2,550 |
| 39,900 | 40,000 | 2,244 | 2,137 | 2,371 | 2,137 | 46,100 | 46,200 | 2,666 | 2,469 | 2,793 | 2,557 |
| 40,000 | 40,100 | 2,251 | 2,143 | 2,378 | 2,143 | 46,200 | 46,300 | 2,673 | 2,474 | 2,800 | 2,564 |
| 40,100 | 40,200 | 2,258 | 2,148 | 2,385 | 2,149 | 46,300 | 46,400 | 2,680 | 2,480 | 2,807 | 2,570 |
| 40,200 | 40,300 | 2,265 | 2,153 | 2,392 | 2,156 | 46,400 | 46,500 | 2,686 | 2,485 | 2,813 | 2,577 |
| 40,300 | 40,400 | 2,272 | 2,159 | 2,399 | 2,162 | 46,500 | 46,600 | 2,693 | 2,490 | 2,820 | 2,584 |
| 40,400 | 40,500 | 2,278 | 2,164 | 2,405 | 2,169 | 46,600 | 46,700 | 2,700 | 2,496 | 2,827 | 2,591 |
| 40,500 | 40,600 | 2,285 | 2,169 | 2,412 | 2,176 | 46,700 | 46,800 | 2,707 | 2,501 | 2,834 | 2,598 |
| 40,600 | 40,700 | 2,292 | 2,175 | 2,419 | 2,183 | 46,800 | 46,900 | 2,714 | 2,506 | 2,841 | 2,604 |
| 40,700 | 40,800 | 2,299 | 2,180 | 2,426 | 2,190 | 46,900 | 47,000 | 2,720 | 2,512 | 2,847 | 2,611 |
| 40,800 | 40,900 | 2,306 | 2,185 | 2,433 | 2,196 | 47,000 | 47,100 | 2,727 | 2,517 | 2,854 | 2,618 |
| 40,900 | 41,000 | 2,312 | 2,191 | 2,439 | 2,203 | 47,100 | 47,200 | 2,734 | 2,523 | 2,861 | 2,625 |
| 41,000 | 41,100 | 2,319 | 2,196 | 2,446 | 2,210 | 47,200 | 47,300 | 2,741 | 2,528 | 2,868 | 2,632 |
| 41,100 | 41,200 | 2,326 | 2,202 | 2,453 | 2,217 | 47,300 | 47,400 | 2,748 | 2,533 | 2,875 | 2,638 |
| 41,200 | 41,300 | 2,333 | 2,207 | 2,460 | 2,224 | 47,400 | 47,500 | 2,754 | 2,539 | 2,881 | 2,645 |
| 41,300 | 41,400 | 2,340 | 2,212 | 2,467 | 2,230 | 47,500 | 47,600 | 2,761 | 2,544 | 2,888 | 2,652 |
| 41,400 | 41,500 | 2,346 | 2,218 | 2,473 | 2,237 | 47,600 | 47,700 | 2,768 | 2,550 | 2,895 | 2,659 |
| 41,500 | 41,600 | 2,353 | 2,223 | 2,480 | 2,244 | 47,700 | 47,800 | 2,775 | 2,557 | 2,902 | 2,666 |
| 41,600 | 41,700 | 2,360 | 2,228 | 2,487 | 2,251 | 47,800 | 47,900 | 2,782 | 2,563 | 2,909 | 2,672 |
| 41,700 | 41,800 | 2,367 | 2,234 | 2,494 | 2,258 | 47,900 | 48,000 | 2,788 | 2,570 | 2,915 | 2,679 |
| 41,800 | 41,900 | 2,374 | 2,239 | 2,501 | 2,264 | 48,000 | 48,100 | 2,795 | 2,577 | 2,922 | 2,686 |
| 41,900 | 42,000 | 2,380 | 2,244 | 2,507 | 2,271 | 48,100 | 48,200 | 2,802 | 2,584 | 2,929 | 2,693 |
| 42,000 | 42,100 | 2,387 | 2,250 | 2,514 | 2,278 | 48,200 | 48,300 | 2,809 | 2,591 | 2,936 | 2,700 |
| 42,100 | 42,200 | 2,394 | 2,255 | 2,521 | 2,285 | 48,300 | 48,400 | 2,816 | 2,597 | 2,943 | 2,706 |
| 42,200 | 42,300 | 2,401 | 2,260 | 2,528 | 2,292 | 48,400 | 48,500 | 2,822 | 2,604 | 2,949 | 2,713 |
| 42,300 | 42,400 | 2,408 | 2,266 | 2,535 | 2,298 | 48,500 | 48,600 | 2,829 | 2,611 | 2,956 | 2,720 |
| 42,400 | 42,500 | 2,414 | 2,271 | 2,541 | 2,305 | 48,600 | 48,700 | 2,836 | 2,618 | 2,963 | 2,727 |
| 42,500 | 42,600 | 2,421 | 2,276 | 2,548 | 2,312 | 48,700 | 48,800 | 2,843 | 2,625 | 2,970 | 2,734 |
| 42,600 | 42,700 | 2,428 | 2,282 | 2,555 | 2,319 | 48,800 | 48,900 | 2,850 | 2,631 | 2,977 | 2,740 |
| 42,700 | 42,800 | 2,435 | 2,287 | 2,562 | 2,326 | 48,900 | 49,000 | 2,856 | 2,638 | 2,983 | 2,747 |
| 42,800 | 42,900 | 2,442 | 2,292 | 2,569 | 2,332 | 49,000 | 49,100 | 2,863 | 2,645 | 2,990 | 2,754 |
| 42,900 | 43,000 | 2,448 | 2,298 | 2,575 | 2,339 | 49,100 | 49,200 | 2,870 | 2,652 | 2,997 | 2,761 |
| 43,000 | 43,100 | 2,455 | 2,303 | 2,582 | 2,346 | 49,200 | 49,300 | 2,877 | 2,659 | 3,004 | 2,768 |
| 43,100 | 43,200 | 2,462 | 2,309 | 2,589 | 2,353 | 49,300 | 49,400 | 2,884 | 2,665 | 3,011 | 2,774 |
| 43,200 | 43,300 | 2,469 | 2,314 | 2,596 | 2,360 | 49,400 | 49,500 | 2,890 | 2,672 | 3,017 | 2,781 |
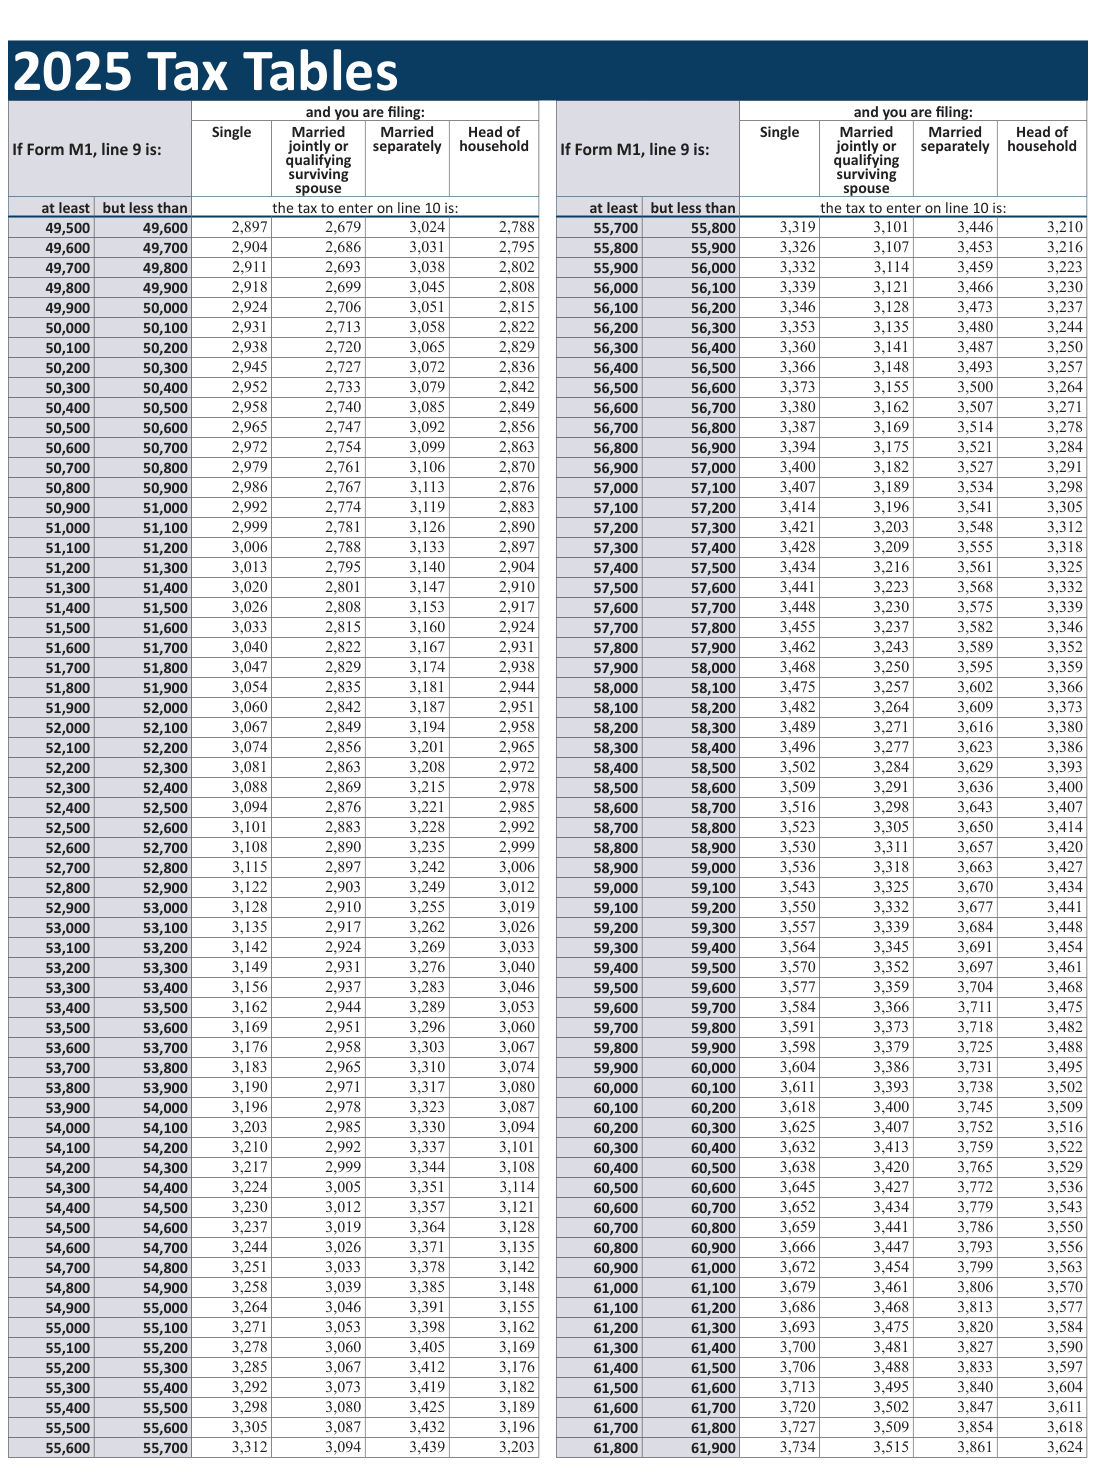
Text version of this table
| 2025 Tax Tables | |||||||||||
| If Form M1, line 9 is: | and you are filing: | If Form M1, line 9 is: | and you are filing: | ||||||||
| Single | Married jointly or qualifying surviving spouse | Married separately | Head of household | Single | Married jointly or qualifying surviving spouse | Married separately | Head of household | ||||
| at least | but less than | the tax to enter on line 10 is: | at least | but less than | the tax to enter on line 10 is: | ||||||
| 49,500 | 49,600 | 2,897 | 2,679 | 3,024 | 2,788 | 55,700 | 55,800 | 3,319 | 3,101 | 3,446 | 3,210 |
| 49,600 | 49,700 | 2,904 | 2,686 | 3,031 | 2,795 | 55,800 | 55,900 | 3,326 | 3,107 | 3,453 | 3,216 |
| 49,700 | 49,800 | 2,911 | 2,693 | 3,038 | 2,802 | 55,900 | 56,000 | 3,332 | 3,114 | 3,459 | 3,223 |
| 49,800 | 49,900 | 2,918 | 2,699 | 3,045 | 2,808 | 56,000 | 56,100 | 3,339 | 3,121 | 3,466 | 3,230 |
| 49,900 | 50,000 | 2,924 | 2,706 | 3,051 | 2,815 | 56,100 | 56,200 | 3,346 | 3,128 | 3,473 | 3,237 |
| 50,000 | 50,100 | 2,931 | 2,713 | 3,058 | 2,822 | 56,200 | 56,300 | 3,353 | 3,135 | 3,480 | 3,244 |
| 50,100 | 50,200 | 2,938 | 2,720 | 3,065 | 2,829 | 56,300 | 56,400 | 3,360 | 3,141 | 3,487 | 3,250 |
| 50,200 | 50,300 | 2,945 | 2,727 | 3,072 | 2,836 | 56,400 | 56,500 | 3,366 | 3,148 | 3,493 | 3,257 |
| 50,300 | 50,400 | 2,952 | 2,733 | 3,079 | 2,842 | 56,500 | 56,600 | 3,373 | 3,155 | 3,500 | 3,264 |
| 50,400 | 50,500 | 2,958 | 2,740 | 3,085 | 2,849 | 56,600 | 56,700 | 3,380 | 3,162 | 3,507 | 3,271 |
| 50,500 | 50,600 | 2,965 | 2,747 | 3,092 | 2,856 | 56,700 | 56,800 | 3,387 | 3,169 | 3,514 | 3,278 |
| 50,600 | 50,700 | 2,972 | 2,754 | 3,099 | 2,863 | 56,800 | 56,900 | 3,394 | 3,175 | 3,521 | 3,284 |
| 50,700 | 50,800 | 2,979 | 2,761 | 3,106 | 2,870 | 56,900 | 57,000 | 3,400 | 3,182 | 3,527 | 3,291 |
| 50,800 | 50,900 | 2,986 | 2,767 | 3,113 | 2,876 | 57,000 | 57,100 | 3,407 | 3,189 | 3,534 | 3,298 |
| 50,900 | 51,000 | 2,992 | 2,774 | 3,119 | 2,883 | 57,100 | 57,200 | 3,414 | 3,196 | 3,541 | 3,305 |
| 51,000 | 51,100 | 2,999 | 2,781 | 3,126 | 2,890 | 57,200 | 57,300 | 3,421 | 3,203 | 3,548 | 3,312 |
| 51,100 | 51,200 | 3,006 | 2,788 | 3,133 | 2,897 | 57,300 | 57,400 | 3,428 | 3,209 | 3,555 | 3,318 |
| 51,200 | 51,300 | 3,013 | 2,795 | 3,140 | 2,904 | 57,400 | 57,500 | 3,434 | 3,216 | 3,561 | 3,325 |
| 51,300 | 51,400 | 3,020 | 2,801 | 3,147 | 2,910 | 57,500 | 57,600 | 3,441 | 3,223 | 3,568 | 3,332 |
| 51,400 | 51,500 | 3,026 | 2,808 | 3,153 | 2,917 | 57,600 | 57,700 | 3,448 | 3,230 | 3,575 | 3,339 |
| 51,500 | 51,600 | 3,033 | 2,815 | 3,160 | 2,924 | 57,700 | 57,800 | 3,455 | 3,237 | 3,582 | 3,346 |
| 51,600 | 51,700 | 3,040 | 2,822 | 3,167 | 2,931 | 57,800 | 57,900 | 3,462 | 3,243 | 3,589 | 3,352 |
| 51,700 | 51,800 | 3,047 | 2,829 | 3,174 | 2,938 | 57,900 | 58,000 | 3,468 | 3,250 | 3,595 | 3,359 |
| 51,800 | 51,900 | 3,054 | 2,835 | 3,181 | 2,944 | 58,000 | 58,100 | 3,475 | 3,257 | 3,602 | 3,366 |
| 51,900 | 52,000 | 3,060 | 2,842 | 3,187 | 2,951 | 58,100 | 58,200 | 3,482 | 3,264 | 3,609 | 3,373 |
| 52,000 | 52,100 | 3,067 | 2,849 | 3,194 | 2,958 | 58,200 | 58,300 | 3,489 | 3,271 | 3,616 | 3,380 |
| 52,100 | 52,200 | 3,074 | 2,856 | 3,201 | 2,965 | 58,300 | 58,400 | 3,496 | 3,277 | 3,623 | 3,386 |
| 52,200 | 52,300 | 3,081 | 2,863 | 3,208 | 2,972 | 58,400 | 58,500 | 3,502 | 3,284 | 3,629 | 3,393 |
| 52,300 | 52,400 | 3,088 | 2,869 | 3,215 | 2,978 | 58,500 | 58,600 | 3,509 | 3,291 | 3,636 | 3,400 |
| 52,400 | 52,500 | 3,094 | 2,876 | 3,221 | 2,985 | 58,600 | 58,700 | 3,516 | 3,298 | 3,643 | 3,407 |
| 52,500 | 52,600 | 3,101 | 2,883 | 3,228 | 2,992 | 58,700 | 58,800 | 3,523 | 3,305 | 3,650 | 3,414 |
| 52,600 | 52,700 | 3,108 | 2,890 | 3,235 | 2,999 | 58,800 | 58,900 | 3,530 | 3,311 | 3,657 | 3,420 |
| 52,700 | 52,800 | 3,115 | 2,897 | 3,242 | 3,006 | 58,900 | 59,000 | 3,536 | 3,318 | 3,663 | 3,427 |
| 52,800 | 52,900 | 3,122 | 2,903 | 3,249 | 3,012 | 59,000 | 59,100 | 3,543 | 3,325 | 3,670 | 3,434 |
| 52,900 | 53,000 | 3,128 | 2,910 | 3,255 | 3,019 | 59,100 | 59,200 | 3,550 | 3,332 | 3,677 | 3,441 |
| 53,000 | 53,100 | 3,135 | 2,917 | 3,262 | 3,026 | 59,200 | 59,300 | 3,557 | 3,339 | 3,684 | 3,448 |
| 53,100 | 53,200 | 3,142 | 2,924 | 3,269 | 3,033 | 59,300 | 59,400 | 3,564 | 3,345 | 3,691 | 3,454 |
| 53,200 | 53,300 | 3,149 | 2,931 | 3,276 | 3,040 | 59,400 | 59,500 | 3,570 | 3,352 | 3,697 | 3,461 |
| 53,300 | 53,400 | 3,156 | 2,937 | 3,283 | 3,046 | 59,500 | 59,600 | 3,577 | 3,359 | 3,704 | 3,468 |
| 53,400 | 53,500 | 3,162 | 2,944 | 3,289 | 3,053 | 59,600 | 59,700 | 3,584 | 3,366 | 3,711 | 3,475 |
| 53,500 | 53,600 | 3,169 | 2,951 | 3,296 | 3,060 | 59,700 | 59,800 | 3,591 | 3,373 | 3,718 | 3,482 |
| 53,600 | 53,700 | 3,176 | 2,958 | 3,303 | 3,067 | 59,800 | 59,900 | 3,598 | 3,379 | 3,725 | 3,488 |
| 53,700 | 53,800 | 3,183 | 2,965 | 3,310 | 3,074 | 59,900 | 60,000 | 3,604 | 3,386 | 3,731 | 3,495 |
| 53,800 | 53,900 | 3,190 | 2,971 | 3,317 | 3,080 | 60,000 | 60,100 | 3,611 | 3,393 | 3,738 | 3,502 |
| 53,900 | 54,000 | 3,196 | 2,978 | 3,323 | 3,087 | 60,100 | 60,200 | 3,618 | 3,400 | 3,745 | 3,509 |
| 54,000 | 54,100 | 3,203 | 2,985 | 3,330 | 3,094 | 60,200 | 60,300 | 3,625 | 3,407 | 3,752 | 3,516 |
| 54,100 | 54,200 | 3,210 | 2,992 | 3,337 | 3,101 | 60,300 | 60,400 | 3,632 | 3,413 | 3,759 | 3,522 |
| 54,200 | 54,300 | 3,217 | 2,999 | 3,344 | 3,108 | 60,400 | 60,500 | 3,638 | 3,420 | 3,765 | 3,529 |
| 54,300 | 54,400 | 3,224 | 3,005 | 3,351 | 3,114 | 60,500 | 60,600 | 3,645 | 3,427 | 3,772 | 3,536 |
| 54,400 | 54,500 | 3,230 | 3,012 | 3,357 | 3,121 | 60,600 | 60,700 | 3,652 | 3,434 | 3,779 | 3,543 |
| 54,500 | 54,600 | 3,237 | 3,019 | 3,364 | 3,128 | 60,700 | 60,800 | 3,659 | 3,441 | 3,786 | 3,550 |
| 54,600 | 54,700 | 3,244 | 3,026 | 3,371 | 3,135 | 60,800 | 60,900 | 3,666 | 3,447 | 3,793 | 3,556 |
| 54,700 | 54,800 | 3,251 | 3,033 | 3,378 | 3,142 | 60,900 | 61,000 | 3,672 | 3,454 | 3,799 | 3,563 |
| 54,800 | 54,900 | 3,258 | 3,039 | 3,385 | 3,148 | 61,000 | 61,100 | 3,679 | 3,461 | 3,806 | 3,570 |
| 54,900 | 55,000 | 3,264 | 3,046 | 3,391 | 3,155 | 61,100 | 61,200 | 3,686 | 3,468 | 3,813 | 3,577 |
| 55,000 | 55,100 | 3,271 | 3,053 | 3,398 | 3,162 | 61,200 | 61,300 | 3,693 | 3,475 | 3,820 | 3,584 |
| 55,100 | 55,200 | 3,278 | 3,060 | 3,405 | 3,169 | 61,300 | 61,400 | 3,700 | 3,481 | 3,827 | 3,590 |
| 55,200 | 55,300 | 3,285 | 3,067 | 3,412 | 3,176 | 61,400 | 61,500 | 3,706 | 3,488 | 3,833 | 3,597 |
| 55,300 | 55,400 | 3,292 | 3,073 | 3,419 | 3,182 | 61,500 | 61,600 | 3,713 | 3,495 | 3,840 | 3,604 |
| 55,400 | 55,500 | 3,298 | 3,080 | 3,425 | 3,189 | 61,600 | 61,700 | 3,720 | 3,502 | 3,847 | 3,611 |
| 55,500 | 55,600 | 3,305 | 3,087 | 3,432 | 3,196 | 61,700 | 61,800 | 3,727 | 3,509 | 3,854 | 3,618 |
| 55,600 | 55,700 | 3,312 | 3,094 | 3,439 | 3,203 | 61,800 | 61,900 | 3,734 | 3,515 | 3,861 | 3,624 |
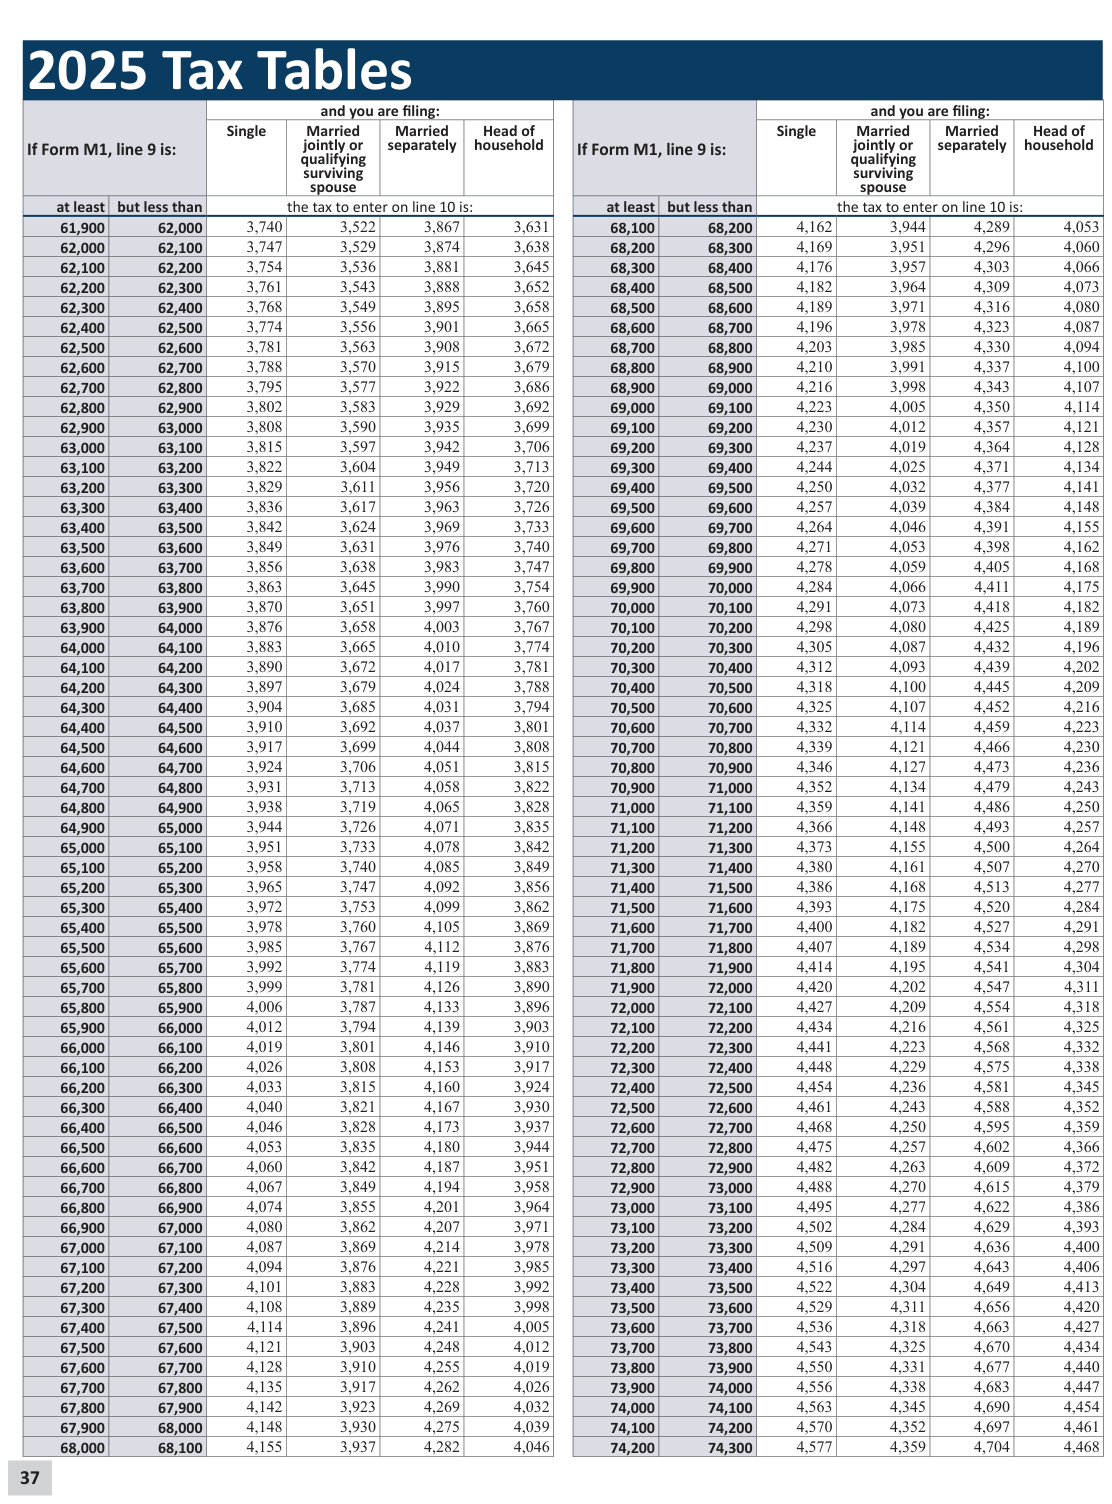
Text version of this table
| 2025 Tax Tables | ||||||||||||
| If Form M1, line 9 is: | and you are filing: | If Form M1, line 9 is: | and you are filing: | |||||||||
| Single | Married jointly or qualifying surviving spouse | Married separately | Head of household | Single | Married jointly or qualifying surviving spouse | Married separately | Head of household | |||||
| at least | but less than | the tax to enter on line 10 is: | at least | but less than | the tax to enter on line 10 is: | |||||||
| 61,900 | 62,000 | 3,740 | 3,522 | 3,867 | 3,631 | 68,100 | 68,200 | 4,162 | 3,944 | 4,289 | 4,053 | |
| 62,000 | 62,100 | 3,747 | 3,529 | 3,874 | 3,638 | 68,200 | 68,300 | 4,169 | 3,951 | 4,296 | 4,060 | |
| 62,100 | 62,200 | 3,754 | 3,536 | 3,881 | 3,645 | 68,300 | 68,400 | 4,176 | 3,957 | 4,303 | 4,066 | |
| 62,200 | 62,300 | 3,761 | 3,543 | 3,888 | 3,652 | 68,400 | 68,500 | 4,182 | 3,964 | 4,309 | 4,073 | |
| 62,300 | 62,400 | 3,768 | 3,549 | 3,895 | 3,658 | 68,500 | 68,600 | 4,189 | 3,971 | 4,316 | 4,080 | |
| 62,400 | 62,500 | 3,774 | 3,556 | 3,901 | 3,665 | 68,600 | 68,700 | 4,196 | 3,978 | 4,323 | 4,087 | |
| 62,500 | 62,600 | 3,781 | 3,563 | 3,908 | 3,672 | 68,700 | 68,800 | 4,203 | 3,985 | 4,330 | 4,094 | |
| 62,600 | 62,700 | 3,788 | 3,570 | 3,915 | 3,679 | 68,800 | 68,900 | 4,210 | 3,991 | 4,337 | 4,100 | |
| 62,700 | 62,800 | 3,795 | 3,577 | 3,922 | 3,686 | 68,900 | 69,000 | 4,216 | 3,998 | 4,343 | 4,107 | |
| 62,800 | 62,900 | 3,802 | 3,583 | 3,929 | 3,692 | 69,000 | 69,100 | 4,223 | 4,005 | 4,350 | 4,114 | |
| 62,900 | 63,000 | 3,808 | 3,590 | 3,935 | 3,699 | 69,100 | 69,200 | 4,230 | 4,012 | 4,357 | 4,121 | |
| 63,000 | 63,100 | 3,815 | 3,597 | 3,942 | 3,706 | 69,200 | 69,300 | 4,237 | 4,019 | 4,364 | 4,128 | |
| 63,100 | 63,200 | 3,822 | 3,604 | 3,949 | 3,713 | 69,300 | 69,400 | 4,244 | 4,025 | 4,371 | 4,134 | |
| 63,200 | 63,300 | 3,829 | 3,611 | 3,956 | 3,720 | 69,400 | 69,500 | 4,250 | 4,032 | 4,377 | 4,141 | |
| 63,300 | 63,400 | 3,836 | 3,617 | 3,963 | 3,726 | 69,500 | 69,600 | 4,257 | 4,039 | 4,384 | 4,148 | |
| 63,400 | 63,500 | 3,842 | 3,624 | 3,969 | 3,733 | 69,600 | 69,700 | 4,264 | 4,046 | 4,391 | 4,155 | |
| 63,500 | 63,600 | 3,849 | 3,631 | 3,976 | 3,740 | 69,700 | 69,800 | 4,271 | 4,053 | 4,398 | 4,162 | |
| 63,600 | 63,700 | 3,856 | 3,638 | 3,983 | 3,747 | 69,800 | 69,900 | 4,278 | 4,059 | 4,405 | 4,168 | |
| 63,700 | 63,800 | 3,863 | 3,645 | 3,990 | 3,754 | 69,900 | 70,000 | 4,284 | 4,066 | 4,411 | 4,175 | |
| 63,800 | 63,900 | 3,870 | 3,651 | 3,997 | 3,760 | 70,000 | 70,100 | 4,291 | 4,073 | 4,418 | 4,182 | |
| 63,900 | 64,000 | 3,876 | 3,658 | 4,003 | 3,767 | 70,100 | 70,200 | 4,298 | 4,080 | 4,425 | 4,189 | |
| 64,000 | 64,100 | 3,883 | 3,665 | 4,010 | 3,774 | 70,200 | 70,300 | 4,305 | 4,087 | 4,432 | 4,196 | |
| 64,100 | 64,200 | 3,890 | 3,672 | 4,017 | 3,781 | 70,300 | 70,400 | 4,312 | 4,093 | 4,439 | 4,202 | |
| 64,200 | 64,300 | 3,897 | 3,679 | 4,024 | 3,788 | 70,400 | 70,500 | 4,318 | 4,100 | 4,445 | 4,209 | |
| 64,300 | 64,400 | 3,904 | 3,685 | 4,031 | 3,794 | 70,500 | 70,600 | 4,325 | 4,107 | 4,452 | 4,216 | |
| 64,400 | 64,500 | 3,910 | 3,692 | 4,037 | 3,801 | 70,600 | 70,700 | 4,332 | 4,114 | 4,459 | 4,223 | |
| 64,500 | 64,600 | 3,917 | 3,699 | 4,044 | 3,808 | 70,700 | 70,800 | 4,339 | 4,121 | 4,466 | 4,230 | |
| 64,600 | 64,700 | 3,924 | 3,706 | 4,051 | 3,815 | 70,800 | 70,900 | 4,346 | 4,127 | 4,473 | 4,236 | |
| 64,700 | 64,800 | 3,931 | 3,713 | 4,058 | 3,822 | 70,900 | 71,000 | 4,352 | 4,134 | 4,479 | 4,243 | |
| 64,800 | 64,900 | 3,938 | 3,719 | 4,065 | 3,828 | 71,000 | 71,100 | 4,359 | 4,141 | 4,486 | 4,250 | |
| 64,900 | 65,000 | 3,944 | 3,726 | 4,071 | 3,835 | 71,100 | 71,200 | 4,366 | 4,148 | 4,493 | 4,257 | |
| 65,000 | 65,100 | 3,951 | 3,733 | 4,078 | 3,842 | 71,200 | 71,300 | 4,373 | 4,155 | 4,500 | 4,264 | |
| 65,100 | 65,200 | 3,958 | 3,740 | 4,085 | 3,849 | 71,300 | 71,400 | 4,380 | 4,161 | 4,507 | 4,270 | |
| 65,200 | 65,300 | 3,965 | 3,747 | 4,092 | 3,856 | 71,400 | 71,500 | 4,386 | 4,168 | 4,513 | 4,277 | |
| 65,300 | 65,400 | 3,972 | 3,753 | 4,099 | 3,862 | 71,500 | 71,600 | 4,393 | 4,175 | 4,520 | 4,284 | |
| 65,400 | 65,500 | 3,978 | 3,760 | 4,105 | 3,869 | 71,600 | 71,700 | 4,400 | 4,182 | 4,527 | 4,291 | |
| 65,500 | 65,600 | 3,985 | 3,767 | 4,112 | 3,876 | 71,700 | 71,800 | 4,407 | 4,189 | 4,534 | 4,298 | |
| 65,600 | 65,700 | 3,992 | 3,774 | 4,119 | 3,883 | 71,800 | 71,900 | 4,414 | 4,195 | 4,541 | 4,304 | |
| 65,700 | 65,800 | 3,999 | 3,781 | 4,126 | 3,890 | 71,900 | 72,000 | 4,420 | 4,202 | 4,547 | 4,311 | |
| 65,800 | 65,900 | 4,006 | 3,787 | 4,133 | 3,896 | 72,000 | 72,100 | 4,427 | 4,209 | 4,554 | 4,318 | |
| 65,900 | 66,000 | 4,012 | 3,794 | 4,139 | 3,903 | 72,100 | 72,200 | 4,434 | 4,216 | 4,561 | 4,325 | |
| 66,000 | 66,100 | 4,019 | 3,801 | 4,146 | 3,910 | 72,200 | 72,300 | 4,441 | 4,223 | 4,568 | 4,332 | |
| 66,100 | 66,200 | 4,026 | 3,808 | 4,153 | 3,917 | 72,300 | 72,400 | 4,448 | 4,229 | 4,575 | 4,338 | |
| 66,200 | 66,300 | 4,033 | 3,815 | 4,160 | 3,924 | 72,400 | 72,500 | 4,454 | 4,236 | 4,581 | 4,345 | |
| 66,300 | 66,400 | 4,040 | 3,821 | 4,167 | 3,930 | 72,500 | 72,600 | 4,461 | 4,243 | 4,588 | 4,352 | |
| 66,400 | 66,500 | 4,046 | 3,828 | 4,173 | 3,937 | 72,600 | 72,700 | 4,468 | 4,250 | 4,595 | 4,359 | |
| 66,500 | 66,600 | 4,053 | 3,835 | 4,180 | 3,944 | 72,700 | 72,800 | 4,475 | 4,257 | 4,602 | 4,366 | |
| 66,600 | 66,700 | 4,060 | 3,842 | 4,187 | 3,951 | 72,800 | 72,900 | 4,482 | 4,263 | 4,609 | 4,372 | |
| 66,700 | 66,800 | 4,067 | 3,849 | 4,194 | 3,958 | 72,900 | 73,000 | 4,488 | 4,270 | 4,615 | 4,379 | |
| 66,800 | 66,900 | 4,074 | 3,855 | 4,201 | 3,964 | 73,000 | 73,100 | 4,495 | 4,277 | 4,622 | 4,386 | |
| 66,900 | 67,000 | 4,080 | 3,862 | 4,207 | 3,971 | 73,100 | 73,200 | 4,502 | 4,284 | 4,629 | 4,393 | |
| 67,000 | 67,100 | 4,087 | 3,869 | 4,214 | 3,978 | 73,200 | 73,300 | 4,509 | 4,291 | 4,636 | 4,400 | |
| 67,100 | 67,200 | 4,094 | 3,876 | 4,221 | 3,985 | 73,300 | 73,400 | 4,516 | 4,297 | 4,643 | 4,406 | |
| 67,200 | 67,300 | 4,101 | 3,883 | 4,228 | 3,992 | 73,400 | 73,500 | 4,522 | 4,304 | 4,649 | 4,413 | |
| 67,300 | 67,400 | 4,108 | 3,889 | 4,235 | 3,998 | 73,500 | 73,600 | 4,529 | 4,311 | 4,656 | 4,420 | |
| 67,400 | 67,500 | 4,114 | 3,896 | 4,241 | 4,005 | 73,600 | 73,700 | 4,536 | 4,318 | 4,663 | 4,427 | |
| 67,500 | 67,600 | 4,121 | 3,903 | 4,248 | 4,012 | 73,700 | 73,800 | 4,543 | 4,325 | 4,670 | 4,434 | |
| 67,600 | 67,700 | 4,128 | 3,910 | 4,255 | 4,019 | 73,800 | 73,900 | 4,550 | 4,331 | 4,677 | 4,440 | |
| 67,700 | 67,800 | 4,135 | 3,917 | 4,262 | 4,026 | 73,900 | 74,000 | 4,556 | 4,338 | 4,683 | 4,447 | |
| 67,800 | 67,900 | 4,142 | 3,923 | 4,269 | 4,032 | 74,000 | 74,100 | 4,563 | 4,345 | 4,690 | 4,454 | |
| 67,900 | 68,000 | 4,148 | 3,930 | 4,275 | 4,039 | 74,100 | 74,200 | 4,570 | 4,352 | 4,697 | 4,461 | |
| 68,000 | 68,100 | 4,155 | 3,937 | 4,282 | 4,046 | 74,200 | 74,300 | 4,577 | 4,359 | 4,704 | 4,468 | |
| 37 |
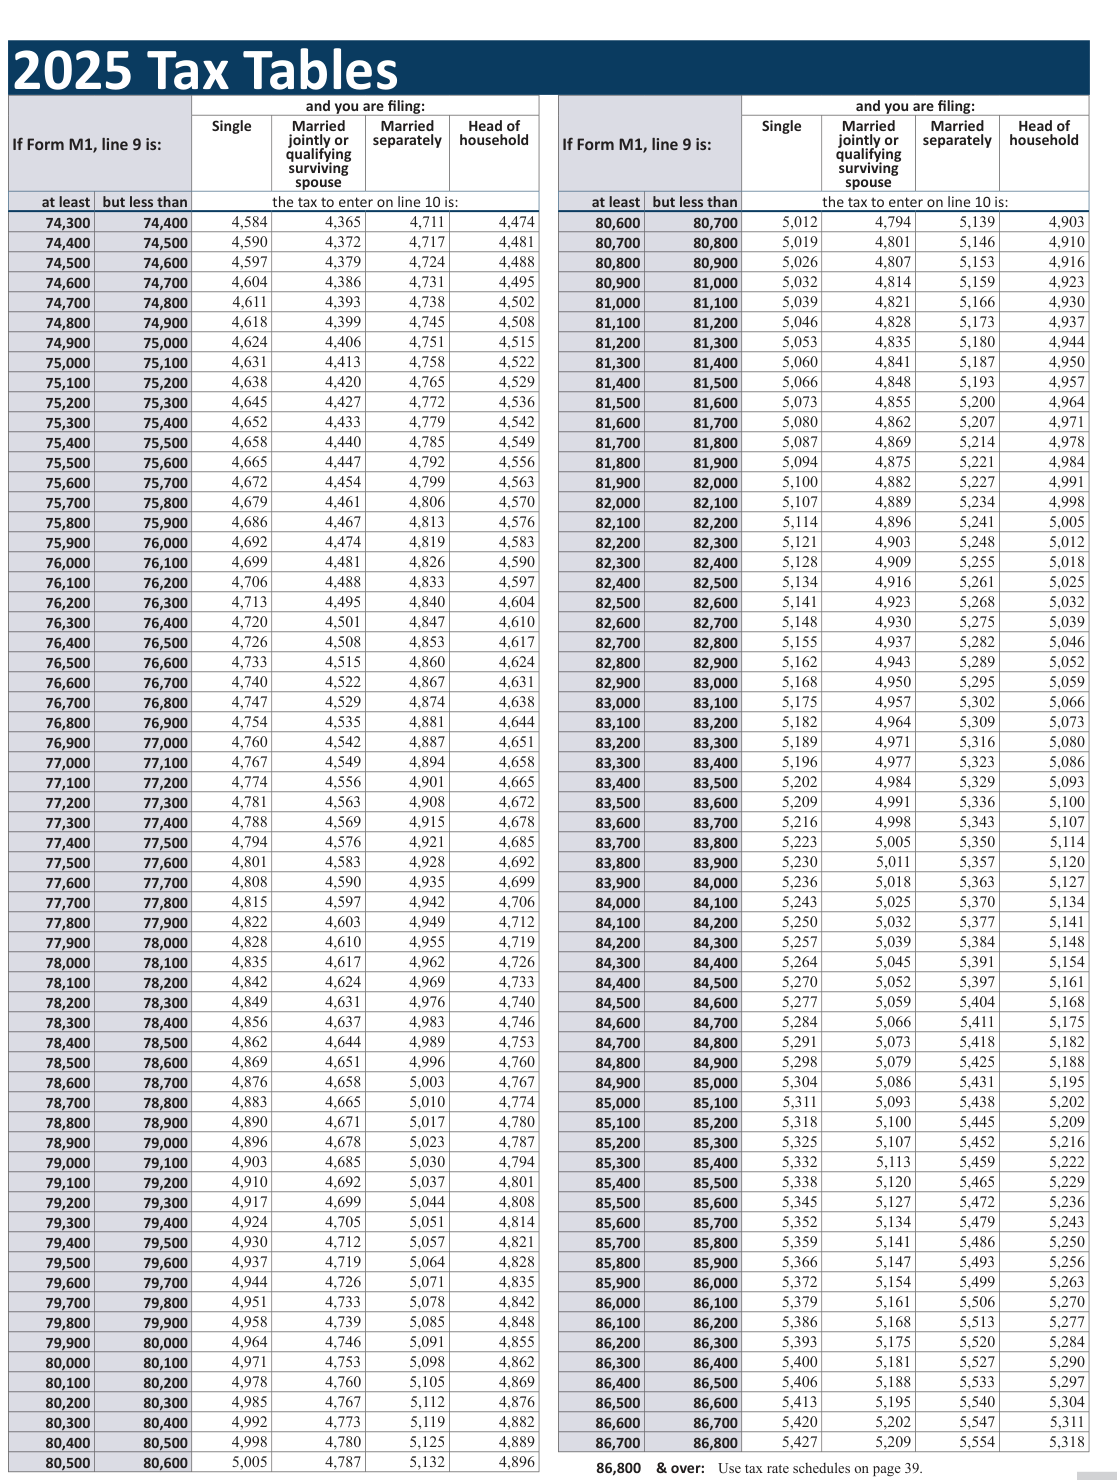
Text version of this table
| 2025 Tax Tables | |||||||||||
| If Form M1, line 9 is: | and you are filing: | If Form M1, line 9 is: | and you are filing: | ||||||||
| Single | Married jointly or qualifying surviving spouse | Married separately | Head of household | Single | Married jointly or qualifying surviving spouse | Married separately | Head of household | ||||
| at least | but less than | the tax to enter on line 10 is: | at least | but less than | the tax to enter on line 10 is: | ||||||
| 74,300 | 74,400 | 4,584 | 4,365 | 4,711 | 4,474 | 80,600 | 80,700 | 5,012 | 4,794 | 5,139 | 4,903 |
| 74,400 | 74,500 | 4,590 | 4,372 | 4,717 | 4,481 | 80,700 | 80,800 | 5,019 | 4,801 | 5,146 | 4,910 |
| 74,500 | 74,600 | 4,597 | 4,379 | 4,724 | 4,488 | 80,800 | 80,900 | 5,026 | 4,807 | 5,153 | 4,916 |
| 74,600 | 74,700 | 4,604 | 4,386 | 4,731 | 4,495 | 80,900 | 81,000 | 5,032 | 4,814 | 5,159 | 4,923 |
| 74,700 | 74,800 | 4,611 | 4,393 | 4,738 | 4,502 | 81,000 | 81,100 | 5,039 | 4,821 | 5,166 | 4,930 |
| 74,800 | 74,900 | 4,618 | 4,399 | 4,745 | 4,508 | 81,100 | 81,200 | 5,046 | 4,828 | 5,173 | 4,937 |
| 74,900 | 75,000 | 4,624 | 4,406 | 4,751 | 4,515 | 81,200 | 81,300 | 5,053 | 4,835 | 5,180 | 4,944 |
| 75,000 | 75,100 | 4,631 | 4,413 | 4,758 | 4,522 | 81,300 | 81,400 | 5,060 | 4,841 | 5,187 | 4,950 |
| 75,100 | 75,200 | 4,638 | 4,420 | 4,765 | 4,529 | 81,400 | 81,500 | 5,066 | 4,848 | 5,193 | 4,957 |
| 75,200 | 75,300 | 4,645 | 4,427 | 4,772 | 4,536 | 81,500 | 81,600 | 5,073 | 4,855 | 5,200 | 4,964 |
| 75,300 | 75,400 | 4,652 | 4,433 | 4,779 | 4,542 | 81,600 | 81,700 | 5,080 | 4,862 | 5,207 | 4,971 |
| 75,400 | 75,500 | 4,658 | 4,440 | 4,785 | 4,549 | 81,700 | 81,800 | 5,087 | 4,869 | 5,214 | 4,978 |
| 75,500 | 75,600 | 4,665 | 4,447 | 4,792 | 4,556 | 81,800 | 81,900 | 5,094 | 4,875 | 5,221 | 4,984 |
| 75,600 | 75,700 | 4,672 | 4,454 | 4,799 | 4,563 | 81,900 | 82,000 | 5,100 | 4,882 | 5,227 | 4,991 |
| 75,700 | 75,800 | 4,679 | 4,461 | 4,806 | 4,570 | 82,000 | 82,100 | 5,107 | 4,889 | 5,234 | 4,998 |
| 75,800 | 75,900 | 4,686 | 4,467 | 4,813 | 4,576 | 82,100 | 82,200 | 5,114 | 4,896 | 5,241 | 5,005 |
| 75,900 | 76,000 | 4,692 | 4,474 | 4,819 | 4,583 | 82,200 | 82,300 | 5,121 | 4,903 | 5,248 | 5,012 |
| 76,000 | 76,100 | 4,699 | 4,481 | 4,826 | 4,590 | 82,300 | 82,400 | 5,128 | 4,909 | 5,255 | 5,018 |
| 76,100 | 76,200 | 4,706 | 4,488 | 4,833 | 4,597 | 82,400 | 82,500 | 5,134 | 4,916 | 5,261 | 5,025 |
| 76,200 | 76,300 | 4,713 | 4,495 | 4,840 | 4,604 | 82,500 | 82,600 | 5,141 | 4,923 | 5,268 | 5,032 |
| 76,300 | 76,400 | 4,720 | 4,501 | 4,847 | 4,610 | 82,600 | 82,700 | 5,148 | 4,930 | 5,275 | 5,039 |
| 76,400 | 76,500 | 4,726 | 4,508 | 4,853 | 4,617 | 82,700 | 82,800 | 5,155 | 4,937 | 5,282 | 5,046 |
| 76,500 | 76,600 | 4,733 | 4,515 | 4,860 | 4,624 | 82,800 | 82,900 | 5,162 | 4,943 | 5,289 | 5,052 |
| 76,600 | 76,700 | 4,740 | 4,522 | 4,867 | 4,631 | 82,900 | 83,000 | 5,168 | 4,950 | 5,295 | 5,059 |
| 76,700 | 76,800 | 4,747 | 4,529 | 4,874 | 4,638 | 83,000 | 83,100 | 5,175 | 4,957 | 5,302 | 5,066 |
| 76,800 | 76,900 | 4,754 | 4,535 | 4,881 | 4,644 | 83,100 | 83,200 | 5,182 | 4,964 | 5,309 | 5,073 |
| 76,900 | 77,000 | 4,760 | 4,542 | 4,887 | 4,651 | 83,200 | 83,300 | 5,189 | 4,971 | 5,316 | 5,080 |
| 77,000 | 77,100 | 4,767 | 4,549 | 4,894 | 4,658 | 83,300 | 83,400 | 5,196 | 4,977 | 5,323 | 5,086 |
| 77,100 | 77,200 | 4,774 | 4,556 | 4,901 | 4,665 | 83,400 | 83,500 | 5,202 | 4,984 | 5,329 | 5,093 |
| 77,200 | 77,300 | 4,781 | 4,563 | 4,908 | 4,672 | 83,500 | 83,600 | 5,209 | 4,991 | 5,336 | 5,100 |
| 77,300 | 77,400 | 4,788 | 4,569 | 4,915 | 4,678 | 83,600 | 83,700 | 5,216 | 4,998 | 5,343 | 5,107 |
| 77,400 | 77,500 | 4,794 | 4,576 | 4,921 | 4,685 | 83,700 | 83,800 | 5,223 | 5,005 | 5,350 | 5,114 |
| 77,500 | 77,600 | 4,801 | 4,583 | 4,928 | 4,692 | 83,800 | 83,900 | 5,230 | 5,011 | 5,357 | 5,120 |
| 77,600 | 77,700 | 4,808 | 4,590 | 4,935 | 4,699 | 83,900 | 84,000 | 5,236 | 5,018 | 5,363 | 5,127 |
| 77,700 | 77,800 | 4,815 | 4,597 | 4,942 | 4,706 | 84,000 | 84,100 | 5,243 | 5,025 | 5,370 | 5,134 |
| 77,800 | 77,900 | 4,822 | 4,603 | 4,949 | 4,712 | 84,100 | 84,200 | 5,250 | 5,032 | 5,377 | 5,141 |
| 77,900 | 78,000 | 4,828 | 4,610 | 4,955 | 4,719 | 84,200 | 84,300 | 5,257 | 5,039 | 5,384 | 5,148 |
| 78,000 | 78,100 | 4,835 | 4,617 | 4,962 | 4,726 | 84,300 | 84,400 | 5,264 | 5,045 | 5,391 | 5,154 |
| 78,100 | 78,200 | 4,842 | 4,624 | 4,969 | 4,733 | 84,400 | 84,500 | 5,270 | 5,052 | 5,397 | 5,161 |
| 78,200 | 78,300 | 4,849 | 4,631 | 4,976 | 4,740 | 84,500 | 84,600 | 5,277 | 5,059 | 5,404 | 5,168 |
| 78,300 | 78,400 | 4,856 | 4,637 | 4,983 | 4,746 | 84,600 | 84,700 | 5,284 | 5,066 | 5,411 | 5,175 |
| 78,400 | 78,500 | 4,862 | 4,644 | 4,989 | 4,753 | 84,700 | 84,800 | 5,291 | 5,073 | 5,418 | 5,182 |
| 78,500 | 78,600 | 4,869 | 4,651 | 4,996 | 4,760 | 84,800 | 84,900 | 5,298 | 5,079 | 5,425 | 5,188 |
| 78,600 | 78,700 | 4,876 | 4,658 | 5,003 | 4,767 | 84,900 | 85,000 | 5,304 | 5,086 | 5,431 | 5,195 |
| 78,700 | 78,800 | 4,883 | 4,665 | 5,010 | 4,774 | 85,000 | 85,100 | 5,311 | 5,093 | 5,438 | 5,202 |
| 78,800 | 78,900 | 4,890 | 4,671 | 5,017 | 4,780 | 85,100 | 85,200 | 5,318 | 5,100 | 5,445 | 5,209 |
| 78,900 | 79,000 | 4,896 | 4,678 | 5,023 | 4,787 | 85,200 | 85,300 | 5,325 | 5,107 | 5,452 | 5,216 |
| 79,000 | 79,100 | 4,903 | 4,685 | 5,030 | 4,794 | 85,300 | 85,400 | 5,332 | 5,113 | 5,459 | 5,222 |
| 79,100 | 79,200 | 4,910 | 4,692 | 5,037 | 4,801 | 85,400 | 85,500 | 5,338 | 5,120 | 5,465 | 5,229 |
| 79,200 | 79,300 | 4,917 | 4,699 | 5,044 | 4,808 | 85,500 | 85,600 | 5,345 | 5,127 | 5,472 | 5,236 |
| 79,300 | 79,400 | 4,924 | 4,705 | 5,051 | 4,814 | 85,600 | 85,700 | 5,352 | 5,134 | 5,479 | 5,243 |
| 79,400 | 79,500 | 4,930 | 4,712 | 5,057 | 4,821 | 85,700 | 85,800 | 5,359 | 5,141 | 5,486 | 5,250 |
| 79,500 | 79,600 | 4,937 | 4,719 | 5,064 | 4,828 | 85,800 | 85,900 | 5,366 | 5,147 | 5,493 | 5,256 |
| 79,600 | 79,700 | 4,944 | 4,726 | 5,071 | 4,835 | 85,900 | 86,000 | 5,372 | 5,154 | 5,499 | 5,263 |
| 79,700 | 79,800 | 4,951 | 4,733 | 5,078 | 4,842 | 86,000 | 86,100 | 5,379 | 5,161 | 5,506 | 5,270 |
| 79,800 | 79,900 | 4,958 | 4,739 | 5,085 | 4,848 | 86,100 | 86,200 | 5,386 | 5,168 | 5,513 | 5,277 |
| 79,900 | 80,000 | 4,964 | 4,746 | 5,091 | 4,855 | 86,200 | 86,300 | 5,393 | 5,175 | 5,520 | 5,284 |
| 80,000 | 80,100 | 4,971 | 4,753 | 5,098 | 4,862 | 86,300 | 86,400 | 5,400 | 5,181 | 5,527 | 5,290 |
| 80,100 | 80,200 | 4,978 | 4,760 | 5,105 | 4,869 | 86,400 | 86,500 | 5,406 | 5,188 | 5,533 | 5,297 |
| 80,200 | 80,300 | 4,985 | 4,767 | 5,112 | 4,876 | 86,500 | 86,600 | 5,413 | 5,195 | 5,540 | 5,304 |
| 80,300 | 80,400 | 4,992 | 4,773 | 5,119 | 4,882 | 86,600 | 86,700 | 5,420 | 5,202 | 5,547 | 5,311 |
| 80,400 | 80,500 | 4,998 | 4,780 | 5,125 | 4,889 | 86,700 | 86,800 | 5,427 | 5,209 | 5,554 | 5,318 |
| 80,500 | 80,600 | 5,005 | 4,787 | 5,132 | 4,896 |
# Tax Rate Schedules
You can get other Minnesota tax forms in any of the following ways:
Go to www.revenue.state.mn.us and click Find a Form •
- Call 651-296-3781 or 1-800-652-9094 (toll-free)
- Use this order form. You'll get two copies of each form you order.
The following schedules show the tax rates that apply to given M1, Minnesota Individual Income Tax income ranges for each filing status. You must use these schedules M15, Underpayment of Estimated Income Tax if line 9 of Form M1 is $86,800 or more. Follow the steps for your M1529, Education Savings Account Contribution Credit or Subtraction filing status to determine the tax amount to enter on line 10 of Form M1.
M23, Claim for a Refund for a Deceased Taxpayer M99, Credit for Military Service in a Combat Zone If line 9 of Form M1 is less than $86,800, you must use the tax table on pages 32 through 38.
Single
If line 9 of Form M1 Enter on line 10 is: of your Form M1: but not over— over— $0 $32,570 - - - - - - 5.35% 32,570 106,990 1,742.50 + 6.80% 106,990 198,630 6,803.06 + 7.85% 198,630 - - - - - - 13,996.80 + 9.85% of the amount over— $0 32,570 106,990 198,630 M1AR, Accelerated Recognition of Installment Sale Gains M1C, Other Nonrefundable Credits M1CAT, Casualty and Theft M1CD, Child and Dependent Care Credit M1CMD, Credit for Attaining Master's Degree in Teacher's
Licensure Field
M1CR, Credit for Income Tax Paid to Another State M1CWFC, Minnesota Child and Working Family Credits M1DQC, Dependents and Qualifying Children M1ED, K-12 Education Credit M1HOME, First-Time Homebuyer Savings Account M1LS, Tax on Lump-Sum Distribution M1LTI, Long-Term Care Insurance Credit M1M, Income Additions and Subtractions M1MA, Marriage Credit
Married filing jointly or qualifying widow(er)
If line 9 of Form M1 Enter on line 10 is: of your Form M1: but not over— over— $0 $47,620 - - - - - - 5.35% 47,620 189,180 2,547.67 + 6.80% 189,180 330,410 12,173.75 + 7.85% 330,410 - - - - - - 23,260.31 + 9.85%
Married filing separately
If line 9 of Form M1 Enter on line 10 is: of your Form M1: but not over— over— $0 $23,810 $0.00 5.35% 23,810 94,590 1,273.84 + 6.80% 94,590 165,205 6,086.88 + 7.85% 165,205 - - - - - - 11,630.16 + 9.85%
Head of household
If line 9 of Form M1 Enter on line 10 is: of your Form M1: but not over— over— $0 $40,100 - - - - - - 5.35% 40,100 161,130 2,145.35 + 6.80% 161,130 264,050 10,375.39 + 7.85% 264,050 - - - - - - 18,454.61 + 9.85% of the amount over— $0 47,620 189,180 330,410 of the amount over— $0 23,810 94,590 165,205 of the amount over— 40,100 161,130 264,050 M1MB, Business Income Additions and Subtractions M1MT, Alternative Minimum Tax M1MTC, Alternative Minimum Tax Credit M1NC, Federal Adjustments M1NR, Nonresidents/Part-Year Residents M1PR, Homestead Credit Refund M1PRSR, Special Refund M1PRX, Amended Homestead Credit Refund M1PSC, Credit for Parents of Stillborn Children M1QPEN, Qualified Public Pension Subtraction M1R, Age 65 or Older/Disabled Subtraction M1RCR, Credit for Tax Paid to Wisconsin M1REF, Refundable Credits M1RENT, Renter's Credit M1SA, Minnesota Itemized Deductions M1SLC, Student Loan Credit M1UE, Unreimbursed Employee Business Expenses M1W, Minnesota Income Tax Withheld M1X, Amended Minnesota Income Tax UT1, Individual Use Tax Return Complete and send to:
Minnesota Tax Forms
Mail Station 1421
St. Paul, MN 55146-1421
Do not use the envelope in this booklet.
Type or print carefully—this will be your mailing label.
Your Name
Address
City State ZIP Code
# Minnesota Department of Revenue
Mail Station 0010, St. Paul, Minnesota 55146-0010
PRST STD
U.S. POSTAGE
PAID
MN DEPT.
OF REVENUE
# Regular property tax refund
Visit our website at www.revenue.state.mn.us to see if you qualify!
# Special property tax refund
You may qualify if your property taxes this year were at least 12% higher than last year and you owned and lived in your home on January 2 of each year. The increase must be at least $100. There is no income limit.
Want to learn more? Go to www.revenue.state.mn.us and type Property Tax Refund into the Search box.
Source: view the official PDF
The source document contains 2 figures (charts or worksheet graphics) not reproduced in this text version. See the official PDF above.
Nearby sections (16 sections)
- kpi · Schedule KPI — Partner's Share of Income, Credits and…
- ks · Schedule KS — Shareholder's Share of Income, Credits and…
- m1 · Form M1 — Minnesota Individual Income Tax Return (2025)
- m1-instructions · Instructions for Form M1 — Individual Income Tax…
- m1pr · Form M1PR — Homestead Credit Refund and Renter's Property Tax…
- m1pr-instructions · Instructions for Form M1PR (2025)
- m2 · Form M2 — Income Tax Return for Estates and Trusts (2025)
- m2-instructions · Instructions for Form M2 — Fiduciary (2025)
- m3 · Form M3 — Partnership Return (including M3A) (2025)
- m3-instructions · Instructions for Form M3 — Partnership (2024 — most…
- m4-instructions · Instructions for Form M4 — Corporation Franchise Tax…
- m4-series · Form M4 — Corporation Franchise Tax Return (incl. M4I, M4A,…
- m8 · Form M8 — S Corporation Return (including M8A) (2025)
- m8-instructions · Instructions for Form M8 — S Corporation (incl. M8A,…
- st3 · Form ST3 — Certificate of Exemption (Revised 7/19)
- w-4mn · Form W-4MN — Minnesota Employee Withholding Allowance/Exemption…