Washington Department of Revenue Forms & Publications
Business Tax Basics — Overview of Washington State Taxes
# Tax reporting responsibilities for Washington business owners
Business
Tax Basics
# Contents
Business tax basics . . . . . . . . . . . . . . . . . 1
Rights and responsibilities . . . . . . . . . . . . . 2
Registering with the Department of Revenue . . . 2 Filing frequency and due dates . . . . . . . . . . . 3
Business and occupation (B&O) tax . . . . . . . . 4
Retailing . . . . . . . . . . . . . . . . . . . . . . . . 4 Wholesaling . . . . . . . . . . . . . . . . . . . . . . 5 Reseller permit . . . . . . . . . . . . . . . . . . . . 5 Manufacturing . . . . . . . . . . . . . . . . . . . . . 6 Service and other activities . . . . . . . . . . . . . 6 B&O tax deductions . . . . . . . . . . . . . . . . . . 6 B&O tax credits . . . . . . . . . . . . . . . . . . . . 7
Retail sales tax . . . . . . . . . . . . . . . . . . . . 8
Definition of retail sales . . . . . . . . . . . . . . . 8 Collecting and reporting sales tax . . . . . . . . . . 8 Sales tax rates . . . . . . . . . . . . . . . . . . . . . 8 Local coding of retail sales . . . . . . . . . . . . . . 9 Rental of tangible goods . . . . . . . . . . . . . . . 9 Single payment . . . . . . . . . . . . . . . . . . . . 9 Periodic payments . . . . . . . . . . . . . . . . . . 9 Tools to determine sales tax rates and codes . . . . 9 Retail sales tax deductions . . . . . . . . . . . . . 10 Use tax . . . . . . . . . . . . . . . . . . . . . . . . 10 Taxable amount and rates . . . . . . . . . . . . . . 12 Property used in a trade or business . . . . . . . . 12 Use tax exemption . . . . . . . . . . . . . . . . . . 12 Use tax credit . . . . . . . . . . . . . . . . . . . . 12 Report and pay use tax . . . . . . . . . . . . . . . 12 Public utility tax . . . . . . . . . . . . . . . . . . . 13
Special taxes and fees . . . . . . . . . . . . . . . 14
Late penalties and delinquency . . . . . . . . . . 16 Audits and appeals . . . . . . . . . . . . . . . . . 17 Personal property tax . . . . . . . . . . . . . . . . 18
Unclaimed property . . . . . . . . . . . . . . . . 19
Filing a return . . . . . . . . . . . . . . . . . . . . 20 Electronic filing (My DOR) . . . . . . . . . . . . . 20 Reporting no business activity . . . . . . . . . . . 20 Correcting a previously filed return . . . . . . . . 20 Services and resources . . . . . . . . . . . . . . . 22 Other agencies to contact . . . . . . . . . . . . . 22 Tax incentives . . . . . . . . . . . . . . . . . . . . 24 Due dates . . . . . . . . . . . . . . . . . . . . . . 25
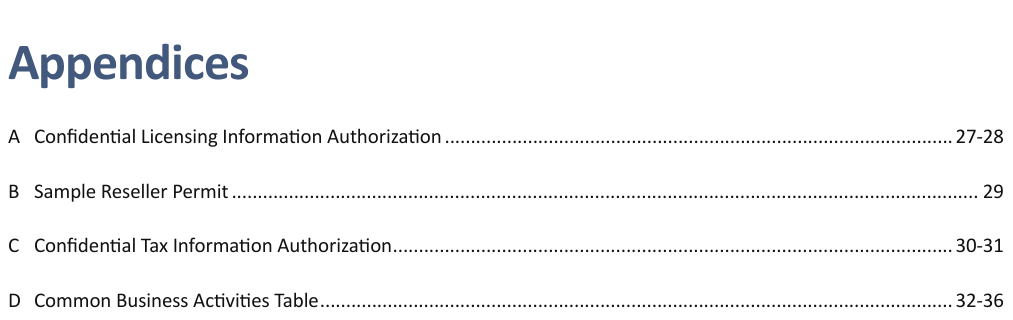
Appendices . . . . . . . . . . . . . . . . . . . . . 26
A | Combined Licensing Information
Authorization . . . . . . . . . . . . . . . . . . 27 B | Sample reseller permit . . . . . . . . . . . . . 29 C | Confidential Tax Information Authorization . . 30 D | Common business activities table . . . . . . . 32
# Business tax basics
This guide is created to help you understand Washington's tax structure. It's intended to provide an overview of the taxes that apply to various business activities in Washington.
Washington does not have a corporate or personal income tax. Most Washington businesses are subject to three major state taxes, all administered or overseen by the Department of Revenue:
- Business and occupation tax (B&O).
- Retail sales tax.
- Use tax.
Other taxes may apply to your business, such as:
- Public utility tax.
- Specialty taxes.
- County and city taxes.
# Reminder
State tax laws change regularly. The information provided is current at the time of the publication.
# Questions
Specialists are available to answer your tax questions Monday through Friday from 8 a.m. to 5 p.m.
(Closed most Wednesdays 8-9 a.m.)
- Phone: 360-705-6705.
- Live Chat: Go to dor.wa.gov/contact, and then click on the Live Chat icon.
Wait times increase around due dates.
# Resources
Go to dor.wa.gov, then click Forms and Publications.
- Industry-specific guides.
- Special notices.
- Tax topic articles.
# More services
Information on other services and publications can be found at the back of this publication or on our website at dor.wa.gov.
# Tax revenue collected and what it provides
$16.2 billion — State retail sales and use tax $7.0 billion — Business and occupation tax $4.7 billion — State share property tax $5.5 billion — Other state taxes and fees $7.3 billion — Local retail sales and use tax $0.9 billion — Other local taxes $41.6 BILLION Natural Education resources Human services Public safety Health care
# Your rights as a taxpayer include:
- Written explanations when tax assessments, interest, and penalties are issued.
- Reliable, written advice and reporting instructions provided by the department specifically to the taxpayer, and to have interest, penalties, and in some instances, tax assessments waived if complying with that information worked against the taxpayer.
- Prompt administrative remedies when tax laws or rules are found to be unconstitutional by the final decision of a court of record.
- Confidentiality of their financial and business information in the department's possession in accordance with the requirements of RCW 82.32.330.
- Clear and current tax instructions, rules, procedures, forms, and other tax information received upon request.
- Prompt and independent administrative review by the department of a decision to revoke a tax registration, and to a written determination that either upholds the revocation or reinstates the registration.
# Your responsibilities as a taxpayer include:
- Register with the Department of Revenue.
- Know your tax reporting obligations, and to ask the department for instructions when you are uncertain.
- Keep accurate and complete business records.
- File returns and pay taxes on time.
- Provide accurate information on tax returns.
- Substantiate claims for refund.
- Pay all taxes on time after closing a business, and request cancellation of the tax account.
- Respond to communications from the department in a timely manner.
# Register if:
- Your business requires city, county, or state endorsements.
- You are doing business using a name other than your full legal name.
- You plan to hire employees within the next 90 days.
- Your business is required to collect retail sales tax.
- Your gross income is $12,000 per year or more.
- Your business is required to pay taxes or fees to the Department of Revenue.
- You are a buyer or processor of specialty wood products.
- Your out-of-state business meets one or more of the following in the current or previous year:
□Has physical presence nexus in Washington.
□Has more than $100,000 in combined gross receipts source or attributed to Washington.
□Is organized or commercially domiciled in Washington.
For any business type other than a sole proprietorship, you must first register with the Secretary of State, and then register with the Department of Revenue.
Also, see our requirements for out-of-state businesses at dor.wa.gov/education/industry-guides/out-statebusinesses.
You can register online at dor.wa.gov/open-business.
# Paying your taxes
Your state business taxes are reported on the excise tax return. Businesses file tax returns either monthly, quarterly, or annually. After registering your business, we will determine your reporting frequency based on your estimated gross income and your type of business.
Businesses are required to file and pay taxes electronically.
If you don't conduct any business or don't owe tax, you are still responsible for timely filing an excise tax return.
# Due dates
If a due date falls on a weekend or legal holiday, the due date is extended to the next business day.
Monthly filers: Monthly tax returns are due the 25th of the month following the reporting period.
Quarterly filers: Quarterly tax returns are due the last day of the month following the reporting period.
Annual filers: Annual tax returns are due April 15th of the year following the reporting period.
# Business records to keep
You should keep the following records for a minimum of five years:
- State excise tax returns and workpapers.
- Federal income tax returns.
- Summary accounting records and source journals such as the check register, general ledger, sales journal, general journal, cash receipts journal, and any other records you use to record income and expenses.
- Sales invoices.
- Purchase invoices.
- Depreciation schedules listing all assets acquired or disposed of, along with invoices for those assets.
- Reseller permits for any wholesale sales.
- Supporting documentation for all deductions and exemptions.
You may keep records in either paper or electronic format. You must provide these records if requested by the Department of Revenue.
# Excise tax
An excise tax is an indirect type of taxation imposed on the manufacture, sale, or use of goods and services.
# Accounting methods
Accrual accounting means that you record and report revenues when sales are made, even if you have not yet received payment.
Cash accounting means that you record and report revenues when you receive payment from your customers.
You must report to the Department of Revenue using the same accounting method that you use to report to the Internal Revenue Service.
# Gross income vs. net income
Generally, businesses must report their gross income on their excise tax returns. Gross income is the total amount charged to customers, without any deductions for labor, materials, taxes, or other costs of doing business. Washington's business taxes are calculated on gross income, rather than net income.
Net income is calculated by deducting certain costs of doing business from gross income. Federal income tax is based on the net income of a business.
# Business and occupation (B&O) tax
The state business and occupation (B&O) tax is a gross receipts tax based on the value of products, gross proceeds of sales, or gross income of your business.
The B&O tax is a cost of doing business and should not be collected from your customers as a separate line item. Almost all businesses located or doing business in Washington are subject to the B&O tax, including corporations, LLCs, partnerships, sole proprietors, and nonprofit corporations.
The B&O tax is due on gross income from business conducted in Washington. No deductions are allowed for labor, materials, taxes, or other costs of doing business. Your business may qualify for certain exemptions, deductions, and credits.
There are more than 50 B&O tax classifications for business activities. The B&O tax rate is based on the type of business activity you engage in. Your business may report income under multiple tax classifications if you engage in more than one type of activity. You are responsible for determining which classification(s) to report your income under. Contact us if you are unsure of which classification(s) apply to your business.
For the complete list of B&O tax classifications, definitions, and tax classifications for common business activities, visit dor.wa.gov and click Taxes & rates.
# Retailing
Businesses that sell goods and certain services to consumers are retailers. Retail sales tax is collected on retail sales unless an exemption applies.
Taxable retail services include:
- Improving real or personal property, such as:
□Custom construction.
□Repairs to real or personal property.
- Certain personal services, such as:
□Tanning.
□Use of athletic and fitness facilities.
□Recreational services.
□Tattooing.
- Specialized activities, such as:
□Lawn mowing, tree and shrub pruning, and trimming.
□Escrow services.
- Renting equipment with operators.
- Extended warranties.
Businesses making retail sales are subject to retailing B&O tax, even when the sales are not subject to retail sales tax. For example, certain food products are exempt from sales tax, but the income from food sales is subject to retailing B&O tax.
# Wholesaling
Wholesalers sell goods and services to businesses Notes Business and occupation (B&O) tax who will resell them to others in the regular course of business. The B&O tax is calculated on the wholesale selling price. Retail sales tax is not collected on wholesale transactions. If you are a wholesaler, you must keep a reseller permit or other approved exemption certificate on file from each buyer to document the transaction as a wholesale sale. Do not send reseller permits to the Department of Revenue.
# Reseller permit
Businesses buying goods or services for resale must use a reseller permit or other approved exemption certificate to make purchases without paying sales tax.
Reseller permits may be used to buy:
- Merchandise and inventory for resale without the buyer using it first.
- Ingredients, components, or chemicals used in processing new products for sale.
- Feed, seed, seedlings, fertilizer, and spray materials if you are a farmer.
- Materials and contract labor for retail/wholesale construction.
- Items for dual purposes.
Reseller permits may not be used to buy:
- Items for personal or household use.
- Items used in a business that are not resold, such as office supplies and equipment.
- Promotional items or gifts.
- Tools, equipment, or equipment rentals.
- Materials and contract labor for public road construction, federal government contracting, or speculative building.
Verify customers' reseller permits We recommend that at least once per year you verify that your customers' reseller permits are valid.
For a single permit, use our Business Lookup at dor. wa.gov/businesslookup and print a copy for your records.
For multiple permits, use our Reseller Permit Verification Service at dor.wa.gov/ResellerPermitVerificationService and keep the confirmation code(s) for your records.
# Manufacturing
Companies that manufacture items in Washington pay Business and occupation (B&O) tax the manufacturing B&O tax. Manufactured products used by the manufacturer are also subject to this tax.
The manufacturing B&O tax is based on the value of the products, usually determined by the selling price. In cases when there is no sale, the value is the selling price of similar products.
The manufacturer must also report under the wholesaling or retailing B&O tax. However, the Multiple Activities Tax Credit eliminates the lesser of the production or selling taxes.
# Service and other activities
The service and other activities B&O tax is due on sales of personal and professional services. Any business activity that is not subject to another B&O tax must report under this "catch all" category.
The types of businesses and services that report under this category include:
- Consulting services.
- Management services.
- Attorneys.
- Beauticians.
- Doctors.
- Tutors.
- Janitors.
This tax classification has three rates:
- For businesses with less than $1 million subject to service and other activities B&O tax in the previous year, the rate is 1.5%.
- For businesses with $1 million or more subject to service and other activities B&O tax in the previous year, the rate is 1.75%.
- For businesses or affiliated groups that has $5,000,000 or more in sales subject to service & other activities income under the higher rate of 2.1%.
For more information about rates, please see our website dor.wa.gov/forms-publications/publicationssubject/special-notices/service-and-other-activitiesrate-changes.
# B&O tax exemptions
There are few exemptions from B&O tax. The most common exemptions are the sale and long-term rental of real estate.
# B&O tax deductions
Common B&O deductions are listed on this page. For a full list of available deductions, please see our website dor.wa.gov/deductions. Deductions must be included in your gross income on the excise tax return and then subtracted as a deduction.
# Notes
Bad debts Please see our website dor.wa.gov/credits for more Deductible when written off in accounting records information.
# Business and occupation (B&O) tax
(e.g. deductible for federal income tax purposes) and reported on a previous tax return. Documentation for this deduction includes the sales invoice, proof that the original sale was reported on the excise tax return, and Notes proof that the debt was written off.
Casual sales
As a registered business, you are required to collect retail sales tax on all retail sales of goods. If you make sales of goods outside the regular course of your business, you may claim a deduction under the retailing B&O tax classification. Documentation includes the sales invoice.
Interstate and foreign sales
Items shipped or delivered to your customer outside Washington. Documentation for this deduction includes the sales invoice and shipping document.
Returns and allowances
For sales reported in full on a previous tax return, but later returned and refunded to the customer.
Documentation includes the original sales invoice, proof that the full sale amount was reported on a previous return, and the credit memo.
# B&O tax credits
Small Business B&O Tax Credit
The most common B&O tax credit is the Small Business B&O Tax Credit. Businesses below a certain B&O tax liability are entitled to a credit. The credit varies depending on the total amount of B&O tax due.
When you file your excise tax return electronically on My DOR, the Small Business B&O Tax Credit is calculated and applied automatically. If you file your excise taxes on a paper return, see our website for details about claiming this credit.
Multiple Activities Tax Credit (MATC)
Another common B&O tax credit available to manufacturers is the MATC. Companies who manufacture and sell goods in Washington are required to report their income under both the manufacturing tax classification and the selling (retailing and/or wholesaling) tax classification. This credit removes the lesser of the two taxes so that the sale of manufactured products in Washington is subject to B&O tax only once.
There are additional B&O tax credits available.
# Retail sales tax
The retail sales tax, often referred to simply as sales tax, is Washington's largest tax source.
All sales tax amounts collected from customers are considered trust funds of the state. The retailer holds these amounts until paid to the Department of Revenue.
Definition of retail sales
Unless specifically exempted by law, every sale of tangible personal property, digital goods, and digital codes is a retail sale. In addition, sales of certain services such as installing, improving, or constructing real or personal property for consumers are also retail sales.
Certain services are specifically defined as retail sales in the law, such as:
- Transient lodging.
- Automobile parking.
- Title insurance.
- Escrow services.
- Extended warranties.
- Use of athletic or fitness facilities.
Collecting and reporting sales tax
Retail sales tax applies to the selling price of taxable transactions and must be separately stated on the bill to the customer. The selling price includes shipping and delivery charges. The advertised price may include the amount of tax, if so indicated in the advertisement.
Tax liability must be reported for all sales made during the reporting period on either the accrual basis or cash basis of accounting. Sellers are liable for submitting the correct amount of sales tax, even if they did not collect the proper amount from the purchaser.
All amounts collected are legally considered trust funds for the state. Any excess sales tax collected from the customer must be paid to the Department of Revenue unless the over-collected amount is refunded to the customer.
Sales tax rates
The sales tax rate you charge to your customer includes both the state portion (6.5%) and the local portion (rate varies by location). Local sales tax is the secondlargest revenue generator for local governments, behind property tax. Retail sales tax is used by the government entity that imposes the tax. The state tax is deposited in the state general fund, while the city and county taxes are distributed to the local governments. The city and county governments use these taxes for general expenditures.
# Local coding of retail sales
You must report your total retail sales by location code Notes Retail sales tax for each place of sale so local sales tax revenues are accurately distributed to cities and counties.
Sales of tangible goods, digital goods, and digital codes are coded to the location where the customer receives the item. Usually, the location of the business is where the customer receives tangible goods. If an item is shipped or delivered, then the sale is coded to the location where it is shipped or delivered to. For sales of digital goods and digital codes the location is usually the address of the buyer.
Labor and services are coded according to where they are primarily performed. If an installation charge is normally added to the cost of an item, the entire charge for that item is coded to the site where it is installed.
Certain sales are coded to the location of the seller regardless of where the customer receives the good, such as vehicles, boats, and floral arrangements.
Rental of tangible goods
The local sales tax rate for the lease or rental of tangible goods depends on the number of lease or rental payments.
Single payment
If a lease or rental of tangible goods is paid with a single payment, then the location of the rental company determines the local sales tax rate.
Periodic payments
If a lease or rental of tangible goods is paid with multiple payments, the first payment is coded to the location of the rental company. All subsequent payments are coded to the location where the rental item is primarily located or stored.
# Tools to determine sales tax rates and codes
We have several tools available to assist you with determining the correct local tax rates:
- Mobile app for iOs and Android devices. It's free to download from the Apple App Store or Google Play.
- Tax rate lookup on our website. It searches according to address, map lookup, or latitude and longitude.
Free mobile app
- Local sales and use tax rates and changes flyer on for iOs and Android our website. This lists local rates alphabetically by devices. city/county.
Visit dor.wa.gov/salesandusetaxtools for more options.
WA Sales Tax
# Retail sales tax deductions
Some deductions are valid for retail sales tax only and Retail sales tax some for B&O tax only, and some are valid for both.
The most common retail sales tax deductions are listed here. Some of the deductions listed here are also included in the B&O tax deductions section. For a full list of available deductions, please see our website dor. wa.gov/deductions.
The following deductions must be included in your gross income on the excise tax return and then subtracted as a deduction:
Bad debts
Deductible when written off in accounting records (e.g. deductible for federal income tax purposes) and reported on a previous tax return. Documentation for this deduction includes the sales invoice, proof that the original sale was reported on the excise tax return, and proof that the debt was written off.
Exempt food sales
Food and food ingredients must meet specific criteria (WAC 458 20 244). Documentation includes the sales invoice.
Gross sales tax collected by facilitator
Marketplace sellers may claim this deduction when a marketplace facilitator collects and pays Washington retail sales tax on their behalf. Documentation includes proof the facilitator is collecting sales tax on behalf of the seller, which is usually included in the contract between the two parties.
Interstate and foreign sales
Shipped or delivered to your customer outside Washington. Documentation for this deduction includes the sales invoice and shipping document.
Returns and allowances
For sales reported in full on a previous tax return, but later returned and refunded to the customer.
Documentation includes the original sales invoice, proof that the full sale amount was reported on a previous return, and the credit memo.
Sales to the U.S. Government
Purchased with U.S. Government funds; does not include sales to federal employees. Documentation for this deduction includes the sales invoice and proof of payment from the U.S. Government.
Taxable amount for tax paid at source
The amount paid for goods that were later resold without intervening use, where retail sales tax was paid at the time of purchase. Documentation includes the purchase invoice and sales invoice.
Trade-in allowance
For exchanges of like-kind goods. Documentation includes the sales invoice showing the item sold and the item taken on trade.
Tribal tax-exempt sales with delivery in Indian country
Sales to enrolled tribal members where the goods are delivered to the tribal member on their reservation or trust land. Documentation includes the sales invoice and completed Tax Exemption for Sales to Tribes form.
Tribal fishing, hunting, and gathering
Retail goods and services directly used in tribal fishing, hunting, and gathering activities are not subject to sales tax. Documentation includes sales invoice and completed Tribal fishing, hunting and gathering form.
# Use tax
Many people don't realize there are Washington tax obligations for goods and certain retail services purchased or acquired when sales tax was not paid. For instance, even though you don't pay sales tax when you shop in Oregon, your purchases are subject to use tax when you bring them into Washington.
Washington citizens also owe use tax in this state when they purchase items in other states that have a sales tax rate lower than Washington's. However, a credit may be available for sales or use tax paid to other states.
There are many instances when Washington's sales tax is not paid on purchases. In most of these situations, use tax is due. Unless specifically exempted, goods used in this state are subject to either sales tax or use tax, but not both. The tax applies regardless of where, or from whom, the property is purchased.
# Notes
Here are examples of situations when use tax is due:
Retail sales tax • Goods purchased from out of state by subscription, through the Internet, or from a mail order catalog company when the company doesn't collect Washington sales or use tax.
- Goods purchased from someone not required to collect sales tax. For example, when you purchase furniture or appliances from an individual through a newspaper classified ad or a garage sale.
- Personal property acquired with the purchase of real property. Machinery and equipment used in a manufacturing process may qualify for the Manufacturer's sales/use tax exemption.
Use tax is not due on purchases of inventory for resale without intervening use.
# Taxable amount and rates
The use tax rates are the same as the sales tax rates. You can find them at dor.wa.gov/SalesTaxRates.
Use tax is due at the rate applicable to the location where you first use the article. The state portion of the tax is 6.5% with local governments imposing their own additional use tax.
Use tax is calculated on the value of the goods when first used in Washington, which is generally the purchase price. Fair market value may be used if the goods are used outside the state for a lengthy period of time before being used in Washington by the same person.
The value of the goods includes shipping, delivery, and installation charges.
# Property used in a trade or business
Use tax is due when goods are purchased for consumption or used by a business and sales tax has not been paid. Some examples of goods that might be purchased without sales tax include:
- Supplies, fixtures, and equipment purchased or leased from an out-of-state vendor.
- Supplies, fixtures, and equipment acquired when an existing business is purchased.
- Promotional items, such as hats, t-shirts, calendars, pens, and other items given to customers or individuals.
- Magazine subscriptions.
- Advertising or promotional materials printed out of state and distributed in Washington.
- Parts installed and labor performed on tangible personal property repaired out of state.
- Materials installed when performing contracts for the federal government or city/county housing authorities, or public road construction.
- Equipment rented by a contractor on which sales tax was not previously paid.
- Articles withdrawn from inventory and used by the business.
- Articles manufactured by the business for its own use.
# Use tax exemption
Residents of another state who move to Washington are exempt from the use tax on their household goods, personal effects, and private motor vehicles, if they acquired the property more than 90 days prior to the move.
For this exemption, boats, motorhomes, trailers, and other recreational vehicles don't qualify as private motor vehicles or personal effects and are subject to use tax. However, a credit is allowed for sales/use tax paid on the article. You must provide proof of sales/use tax previously paid by you to qualify for the credit.
When items are donated to nonprofit charitable organizations, local governments, and the state, the use tax isn't due even if the donor didn't originally pay sales tax or use tax on the item. The donor is also exempt from the use tax as long as they didn't use the item prior to donation.
# Use tax credit
When you bring goods into Washington that you purchased in another state and paid sales tax at the time of purchase, you can deduct the sales or use tax you paid from the amount of use tax due to Washington. You must provide proof of the tax paid to another state prior to use of the goods in Washington.
See WAC 458-20-178 and chapter 82.12 RCW for more information about use tax.
# Report and pay use tax
Registered businesses must report use tax on the excise tax return. Individuals must report use tax to the Department of Revenue on the consumer use tax return.
# Public utility tax
Instead of B&O tax, the public utility tax applies if you engage in any of the following activities in Washington.
# Hauling for hire
Motor transportation: Operating any motor propelled vehicle on public roads to transport property belonging to others or people on a for-hire basis.
Urban transportation: Operating any motor propelled vehicle on public roads to transport property belonging to others or people on a for-hire basis when the origin and destination of the haul are within any of the following:
- The corporate limits of the same city.
- Five miles of the corporate limits of the same city.
- Five miles of the corporate limits of any two cities whose corporate limits are no more than five miles apart.
- Mileage is determined by the straight-line distance, rather than road miles.
Log transportation: The business of transporting logs by truck, except when the transportation either:
- Meets the definition of urban transportation.
- Occurs only on private roads.
□Income from transporting logs on private roads is subject to service and other activities B&O tax.
# Public utility tax
Motor Urban Transportation Lookup Tool: Use this tool to determine which transportation tax applies to a trip based on the starting and ending location.
Visit dor.wa.gov/motorurban.
# Other utilities
Gas distribution: Operating a plant or system for the producing or distributing of natural and/or manufactured gas for hire or sale.
Power: Operating a plant or system for generating, producing, or distributing of electrical energy for hire or sale.
Sewer collection: Collection of sewerage.
Water distribution: Operation of a plant or system for the distribution of water for hire or sale.
# Public utility tax exemption
Public utility businesses earning gross revenues less than these amounts must report, but do not owe the tax:
- Monthly - $2,000.
- Quarterly - $6,000.
- Annually - $24,000.
# Litter tax
Paid by manufacturers, wholesalers, and retailers of products that contribute to the state's litter problem.
The tax is due on the gross amount of sales within this state of items in the following categories:
- Food for human or pet consumption.
- Groceries.
- Cigarette and tobacco products.
- Soft drinks and carbonated waters.
- Beer and other malt beverages.
- Wine.
- Newspapers and magazines.
- Household paper and paper products.
- Glass containers.
- Metal containers.
- Plastic or fiber containers made of synthetic material.
- Cleaning agents and toiletries.
- Non-drug drugstore sundry products.
# Lodging taxes
Convention and trade center tax
Additional tax is charged by hotels/motels located in King County. Convention and trade center tax location codes are found in the Lodging Information Rates and Changes flyer, available at dor.wa.gov.
Special hotel/motel tax
Some areas levy an additional tax for transient rentals (less than 30 consecutive days) of hotel/motels, RV parks, or any other type of lodging. Special hotel/motel location codes are found in the Lodging Information Rates and Changes flyer, available at dor.wa.gov.
Tourism promotion area (TPA) charges
These charges may apply to lodging businesses in participating cities or counties. Different zone rates may apply. For information, please see the Lodging Special Notice for your county, available at dor.wa.gov.
Transient rental income
Businesses providing lodging for less than 30 days must report transient rental income. Lodging businesses include hotels, motels, bed and breakfasts, vacation rentals, trailer camps, RV parks, and tent campgrounds.
Reporting this income allows cities and counties to receive a distribution from the state portion of the retail sales tax. It is not an additional tax.
# Motor vehicle sales/leases tax
An additional 0.5% tax due on sales, leases, and transfers of motor vehicles licensed for on-road use. This tax does not apply to retail car rentals that are subject to the rental car tax.
# Refuse collection tax
Paid by customers and submitted by the refuse collectors on the refuse collection charge only. Landfill charges are also subject to the tax.
# Rental car tax
Paid by the consumer on the rental of a passenger car for a period less than 30 days in addition to sales tax.
# Solid fuel burning device fee
A fee is paid by the consumer on purchases of wood Late penalties and delinquency stoves, coal stoves, fireplaces including masonry and zero clearance fireplace inserts, and other similar devices that burn solid fuel. The fee is collected by the retailer who submits it with their excise tax return.
# Spirits taxes
The Department of Revenue administers two spirits taxes: the liter tax and the sales tax. Liquor and Cannabis Board administers additional spirit tax. Spirits includes any beverage containing alcohol obtained by distillation, including wines with more than 24% alcohol by volume.
If you sell spirits, you must collect the spirits taxes from your customers. You must report and submit these taxes on your excise tax return.
Spirits liter tax
A tax on the sales of spirits in the original container and is based on the volume sold. The tax rate differs for consumers and on-premises retailers.
Spirits sales tax
A tax on the selling price of spirits in their original container. The tax rate for consumers is different from the tax rate for on-premises retailers.
Retail sales tax applies to sales of spirits by the drink or glass but does not apply to sales of spirits unopened in their original containers.
# Syrup tax
This tax is based on the volume used to produce carbonated beverages sold at wholesale and retail in Washington. The business activity of selling such syrups in Washington is also taxed. An exemption is provided for syrup previously subject to this tax in Washington.
# Tire fee
Tire retailers collect this fee on each retail sale of new replacement vehicle tires.
# Tobacco products tax
Tax on distributors who sell tobacco products at wholesale, or retailers who purchase tobacco products directly from out-of-state manufacturers.
# Vapor products tax
Tax on the first business or consumer who possesses vapor products in Washington. This tax does not apply to vapor products containing marijuana.
For more information about these and other special taxes and fees, visit dor.wa.gov/other-taxes.
# Late penalties and delinquency
What happens if I can't file or pay on time?
Call our telephone information center. Filing extensions can be requested and penalties may be waived under limited circumstances.
The penalties on late filings are:
- 9% after the due date until the last day of the month following the due date.
- 19% after the last day of the month following the due date.
- 29% after the last day of the second month following the due date.
# Delinquent tax collection process
What is a delinquent account?
An account becomes delinquent when the due date for a tax return or other established liability has passed and the amount due remains unpaid.
What happens if your account becomes delinquent?
- Penalties and interest begin to accrue on the unpaid tax until the entire balance is paid in full.
- If you don't respond to letters or notices and your account continues to be delinquent, it is assigned to a Revenue Agent for collection.
- The Revenue Agent will attempt to contact you by telephone, letter, or in person to resolve the delinquency.
# Will I be audited?
As a registered business you may be selected for an audit. Audits are routine procedures used to verify that state excise taxes have been reported and paid correctly.
In general, your records will be reviewed to verify proper tax reporting. Where appropriate, you will also receive helpful instructions and information to help you file your excise tax returns in the future. We are committed to working with you in a professional and cooperative manner.
Audit procedures and programs may include:
- Obtaining electronic files of the accounting records for the audit period.
- Random, non-statistical sampling of specific audit areas.
- Computer-assisted audits using a statistical sampling technique. These audits are primarily used for large businesses.
# What to expect during an audit
Audits normally cover the four prior calendar years, plus the current year through the end of the last calendar quarter. All income, deductions, and exemptions reported on your excise tax return may be reviewed.
An audit of your business activities may cover several major areas, including:
- Gross income: Verification of the proper amounts and classifications reported on the return.
- Deductions, credits, and exemptions: Verification of proper amounts, classifications, and documentation.
- Purchases: Verification of retail sales tax or use tax paid on capital assets, consumable supplies, or articles manufactured for your own use.
# Appeals process
You have the right to petition for a review of any action proposed by the Department of Revenue.
If you disagree with an assessment, you may ask for a supervisor's conference before the assessment is issued. For example, when your business records are audited the auditor will meet with you to discuss the results. If you disagree with those results, you can have a conference with the auditor's supervisor.
# Audits and appeals
If the differences can't be resolved at the supervisor level, you can file a petition for review with the Department of Revenue's Administrative Review and Hearings Division.
You must file your petition before the due date or extension date of the assessment or action of the department.
If you do not file your petition before the due date, you must:
- Pay the assessment.
- File a petition for review requesting a refund within four years of the close of the tax year in which taxes were paid.
Example: If you paid tax in June 2022, you have until December 31, 2026, to petition for a refund.
A full discussion of the petition review process is contained in WAC 458-20-100.
For more information, visit dor.wa.gov/appeals.
# Personal property tax
Property tax applies to real property such as land and improvements to land. Property tax also applies to personal property used in conducting business, unless exempted by law.
The chief characteristic that distinguishes personal property from real property is mobility. Personal property includes machinery, equipment, furniture, and supplies. It does not include inventory purchased for sale.
# Administration
County assessors and treasurers administer the property tax in Washington. Assessors value property at 100% of its true and fair value. Treasurers collect the property tax. The Department of Revenue advises assessors and treasurers and oversees the valuation and taxation of property across the state to ensure uniformity.
# Personal property tax listing form
By April 30 of each year, property owners complete and file a Personal Property Listing Form with the county assessor. Forms are available from your county assessor's office. Each Personal Property Listing Form Notes must list all taxable property located in the county that was owned on January 1 of that year. For businesses with multiple locations, property owners must file a separate listing for each location.
# Penalty for failure to file
Property owners who do not file a listing of personal property by April 30 are subject to an estimated tax assessment by the assessor. A penalty of 5% of the tax will be added for each month after the deadline the listing is filed, up to a maximum penalty of 25% of the tax due.
# More information
A personal property tax fact sheet is available at dor. wa.gov. Specific questions about your personal property tax listing should be directed to your county assessor.
Questions about property tax statements should be sent to your county treasurer.
# Unclaimed property
is money or intangible property owed to an individual or business that has not been claimed by the owner. Property is considered unclaimed after it is held for a period of time with no owner contact, and a good faith effort has been made to locate the owner.
# Abandonment periods
An abandonment period is the time between the day the property is due to the owner and the day it becomes reportable as unclaimed property. Abandonment periods vary depending on the type of property.
# Due diligence letters
You are required to attempt to return the unclaimed property to its owner. If the property is valued over $75, you must send a letter to the owner at least 60 days before the deadline to file your unclaimed property report. The letter should be sent to the last known address you have for the property owner.
# Reporting unclaimed property
If the property owner does not respond to your attempts to return the property, then you must report it to the department by October 31, except for insurance companies. Insurance companies must report by April 30.
# Searching for your unclaimed property
You might have property that was reported and is being held by the department. You can search your name or your business name to see if you have property owed to you at ucp.dor.wa.gov.
# Electronic filing (My DOR)
Electronic filing is required for nearly all businesses.
This free service is accessed through our website. Our electronic filing allows you to:
- Customize your tax return, showing only the tax classifications you need.
- Calculate taxes due and flag potential errors, helping you avoid costly mistakes.
- Choose an electronic payment method - Bank account (ACH Debit), Credit/Debit card or ACH credit.
- Save postage and avoid the chance of your return being lost or delayed in the mail.
- File your return early and choose the date you want your payment withdrawn or charged.
For more information visit, dor.wa.gov/MyDORHelp.
# Reporting no business activity
Your business must file a tax return each reporting period even if you did not conduct business or receive income. You must file your return by using one of the following options:
- My DOR: Go to My DOR at dor.wa.gov, file your return and check the box to report No business.
- Express file: Go to dor.wa.gov/expressfilenobiz.
No login required. You will need your 9-digit tax registration number and the filing period.
- Phone: To use our automated system, call 360-705-
# Correcting a previously filed return
If you have reported your taxes incorrectly, you can file an amended return to correct the error. If additional taxes are due, you should submit the additional tax with the amended return. If the original return was filed or paid late, then you should also send payment for additional interest and penalties due.
If you overpaid taxes with the original return, a refund will be issued or a credit will be applied to your account.
The Department of Revenue can honor refunds for taxes paid dating back four calendar years before the year the refund request is made.
Returns filed online can be amended online through My DOR.
# Services and resources
Our website, dor.wa.gov, offers a wide variety of information and resources, including:
Business information update: You can notify us online if your business has moved, closed, or changed activities.
Business lookup: Lookup information on businesses registered in Washington or verify a reseller permit.
Public information includes:
- Business name.
- Open and close dates.
- North American Industry Classification System (NAICS) code and description.
- UBI/Account ID.
- Owner type.
- Reseller permit information includes:
□Permit number.
□Effective date.
□Expiration date.
This information is available for non-commercial purposes only.
Electronic filing (My DOR): File and pay taxes online.
Laws and rules (Taxpedia): Search our online database for Department of Revenue rules and laws. Also research Special Notices, Tax Topic articles, industry guides, advisories, administrative decisions, and court cases through Taxpedia.
Local offices: Find telephone numbers, office hours, and directions to a local office near you.
Motor Urban Transportation Lookup: Find the correct transportation code that applies based on the starting and ending location.
Publications and forms: Find our tax guides, fact sheets, reports, news releases, and forms online.
Reporting fraud: Report Washington state tax and license fraud using our online form. You may also link to other state agencies for information on fraud cases and consumer protection.
Research statistics: Access research publications, data on tax collections, tax-related statistics on business activity by industry and geographical area, and other statistical information about the state's tax structure.
Tax consultation service: Upon request, a representative from the Department of Revenue will meet with you and explain how state taxes apply to your specific business activities.
Tax Rate Lookup Tool: Find the correct code and tax rate for specific locations.
Tax ruling request: Request a binding tax ruling for a specific tax question.
Voluntary Disclosure Program: The Department of Revenue's Voluntary Disclosure Program encourages unregistered businesses to comply with Washington tax laws and to voluntarily register and pay prior tax obligations. If your business has established substantial nexus in Washington, and is required to register and report taxes according to WAC 458-20-101, we can assist you in becoming compliant.
# Department of Licensing
Professional license registration www.dol.wa.gov
# Department of Social and Health Services
Washington State Support Registry www.childsupportonline.wa.gov 800-562-0479 If you have one or more employees, you must report all newly hired or rehired employees with the Washington State Department of Social and Health Services. This information is used to collect child support.
# Employment Security
Unemployment insurance, paid family medical leave Notes Other agencies to contact www.esd.wa.gov If you have employees, you must apply for unemployment insurance coverage with the Washington State Employment Security Department.
# Labor and Industries
Industrial insurance (worker's compensation) 360-902-4817 www.lni.wa.gov If you have one or more employees, you must apply for industrial insurance coverage with the Washington State Department of Labor and Industries. Industrial insurance is not required for business owners, but if you want it you can complete an application for employer coverage.
# Secretary of State
Corporations Division
360-725-0377 www.secstate.wa.gov/corps Contact the Secretary of State's office to file Articles of Incorporation or a Certificate of Limited Partnership if your business has either type of ownership. The Secretary of State also registers trademarks.
Small Business Liaison Team www.business.wa.gov Find information and services from multiple agencies to help you start, register, operate, and grow your business.
# City and county taxing offices
You will need to contact the city or county directly for information.
# Internal Revenue Service
Federal Employer Identification Number (FEIN) Individuals: 800-829-1040 Businesses: 800-829-4933 www.irs.gov If you pay unemployment taxes, such as industrial and employment insurance, you need to have a FEIN. In some special cases, businesses without employees may be required to obtain a FEIN.
# Tax incentives
We offer many tax incentives for businesses. The tax incentives may apply to B&O tax, retail sales tax, leasehold excise tax, or property tax. Here we have listed the general categories of incentives that are available.
The qualifying criteria is specific and can be found on our website at dor.wa.gov.
Please note: If your business claims a tax incentive, you may be required to file an Annual Tax Performance Report by May 31 of each year.
# Notes
- Aerospace
- Biofuel Industry
- Data Centers
- Employer Credits
- Extracting & Timber Manufacturing
- Farming & Agriculture Industries
- Food Manufacturing Industry
- General Manufacturing
- Leasehold Excise Tax (LET) Exemption
- Miscellaneous Incentives
- Renewable Energy/Green Incentives
- Rural County / Community Empowerment Zone
(CEZ) Incentives
- Semiconductor Industry
- Warehouse Incentives
# Due dates
# Appendices
Text version of this table
| Appendices | |
| A Confdi entai l Licensing Inform | atoi n Authorizatoi n...................................................................................................27-28 |
| B Sample Reseller Permit......... | ........................................................................................................................................ 29 |
| C Confdi entai l Tax Informatoi n | Authorizatoi n............................................................................................................30-31 |
| D Common Business Actvi itei s | Table..........................................................................................................................32-36 |
A | Confidential Licensing Information Authorization
# Confidential Licensing Information Authorization
REV 700 002 (8/6/24) Page 1 of 3
# A My information
Owner name:
UBI number: Phone:
# B Which authorization are you providing?
1. Send my confidential licensing information by email or fax.
By checking this box, I authorize the department to send my confidential licensing information using regular email to all email addresses or fax numbers listed on this form.
I am aware of the department's secure message system described on page 3. I know regular email and fax are not as secure, and confidential information may be intercepted by unauthorized persons. I accept these conditions and waive any violation of confidentiality resulting from use of unsecured email or fax (RCW 19.02.115).
Email: Fax number:
2. Share my confidential licensing information with the individuals/company listed below.
If you are authorizing an entire company, add the words "and staff" to the company name you are granting access to. If authorizing specific people, add additional name(s) in the Authorized names section.
Individual or company name:
Mailing address:
City: State: Zip: Phone:
Check the appropriate box below:
Any information for any time period.
Certain information.
List the specific information or time period to be shared:
# Confidential Licensing Information Authorization
Use this form to authorize the Department of Revenue to:
- Send confidential licensing information through unsecure email or fax (to you or an authorized third party) and/or
- Share your confidential licensing information with a third party.
Any information included on this form will not be used to update your account information. Log into your My DOR at dor.wa.gov to make any updates.
# Form 700 002
To request this document in an alternate format, please complete the form dor.wa.gov/AccessibilityRequest or call 360-705-6705. Teletype (TTY) users please dial 711.
# Confidential Licensing Information Authorization
Authorized Names
Only include email address/fax number if you checked the "send my confidential licensing information by A | Confidential Licensing Information Authorization email or fax" below. Attach additional pages if needed.
Authorized name:
Email:
Authorized name:
Email:
# C Signature
Fax number:
Fax number:
I authorize the Department of Revenue to share my confidential licensing information as indicated on page 1 of this form. I declare, under penalty of perjury, that I am authorized to sign this form. I am listed as the real property owner or as the business owner, partner, corporate officer, or LLC member or manager in official records held by Washington State, or I have attached documentation (for example: power of attorney, annual report) that grants me the authority to sign.
Signature:
Print name:
Date:
Title:
This authorization remains in effect until revoked in writing by either party. Keep a copy for your files. To revoke this authorization, write "Revoke" across the front of this form and return it to the department as indicated in the next section.
# What to do next
ATTN (if you are working with a Revenue employee, list name here):
Submit this form by fax, email, or mail:
Fax: 360-705-6699
Email: bls@dor.wa.gov
Mail: Dept. of Revenue
Business Licensing Service
PO Box 47475
Olympia, WA 98504-7475
For licensing questions, please call 360-705-6741.
REV 700 002 (8/6/24)
# B | Sample Reseller Permit
RESELLER PERMIT
Washington State Department of Revenue PO Box 47476 • Olympia, WA 98504-7476 • 360-705-6705 STATE OF WASHINGTON
# SAMPLE
Business Activities:
This permit can be used to purchase:
- Merchandise and inventory for resale without intervening use
- Ingredients, components, or chemicals used in processing new articles of tangible personal property produced for sale
- Feed, seed, seedlings, fertilizer, and spray materials by a farmer
- Materials and contract labor for retail/wholesale construction
- Items for dual purposes (see Purchases for Dual Purposes on back)
This permit cannot be used to purchase:
- Items for personal or household use
- Promotional items or gifts
- Items used in your business that are not resold, such as office supplies, equipment, tools, and equipment rentals
- Materials and contract labor for public road construction or U.S. government contracting (see Definitions on back)
- Materials and contract labor for speculative building
This permit is no longer valid if the business is closed.
The business named on this permit acknowledges:
- It is solely responsible for all purchases made under this permit
- Misuse of the permit:
- Subjects the business to a penalty of 50 percent of the tax due, in addition to the tax, interest, and penalties imposed (RCW 82.32.291)
- May result in this permit being revoked
Notes (optional):
Important: The Department of Revenue may use information from sellers to verify all purchases made with this permit were qualified.
Reseller: Keep this original permit on file. Provide copies to sellers from which you make purchases.
# Confidential Tax Information Authorization
Use this form to authorize the Department of Revenue to:
- Send confidential tax information through unsecure email or fax (to you or an authorized third party) and/or
• Share your confidential tax information with a third party.
# Reset form
My information (This information will not be used to update your business record.*) Taxpayer or business name: Account ID/UBI number:
Mailing address: City: State: Zip:
Phone: Email: Fax:
*To update your business record, go to dor.wa.gov and log in to your My DOR account.
# Which authorization are you providing? (For third party authorizations, complete A and B.)
A. Send my confidential tax information by email or fax.
By checking this box, I authorize the department to send my confidential tax information using regular email or fax to all email addresses or fax numbers listed on this form.
I am aware of the department's secure message system described on page 3. I know regular email and fax are not as secure, and confidential information may be intercepted by unauthorized persons. I accept these conditions and waive any violation of confidentiality resulting from use of unsecured email or fax. (RCW 82.32.330)
B. Share my confidential tax information with the individuals/company listed below.
If you are not authorizing a third party, skip this section and go to the signature page. If you are authorizing an entire company or a Legislator's office, add the words "and staff." If authorizing specific people, add additional name(s) in the Authorized names/email section.
Individual or company name:
Mailing address: City: State: Zip:
Phone: Email: Fax:
Check the appropriate box below:
Any information for any reporting period.
Any information for this reporting period:
Month/quarter/year: to Month/quarter/year:
Only listed information for this reporting period.
Month/quarter/year: to Month/quarter/year:
Information to be shared:
List authorized names. Include email addresses only if you've checked the box in section A.
To request this document in an alternate format, please complete the form dor.wa.gov/AccessibilityRequest or call 360-705-6705. Teletype (TTY) users please dial 711.
REV 42 2446 (10/31/23) Page 1 of 3
# Signature
I authorize the Department of Revenue to share my confidential tax information as indicated on page 1 of this form. I declare, under penalty of perjury, that I am authorized to sign this form. I am listed as the real property owner or as the business owner, partner, corporate officer, or LLC member or manager in official records held by Washington State, or I have attached documentation (for example: power of attorney, annual report, executor) that grants me the authority to sign.
Taxpayer signature: Title: Date:
Print name: City and state where signed:
This authorization remains in effect until revoked in writing by either party. Keep a copy for your files. To revoke this authorization, write "Revoke" across the front of this form and return it to the department as indicated in the next section
# What to do next
ATTN (if you are working with a Revenue employee, write their name here):
Submit this form by fax, email, or mail:
Fax: 360-705-6175
Email: DORTAAFaxIn@dor.wa.gov
Mail: Dept. of Revenue
Taxpayer Account Administration - ICAP PO Box 47476 Olympia, WA 98504-7476
REV 42 2446 (10/31/23) Page 2 of 3
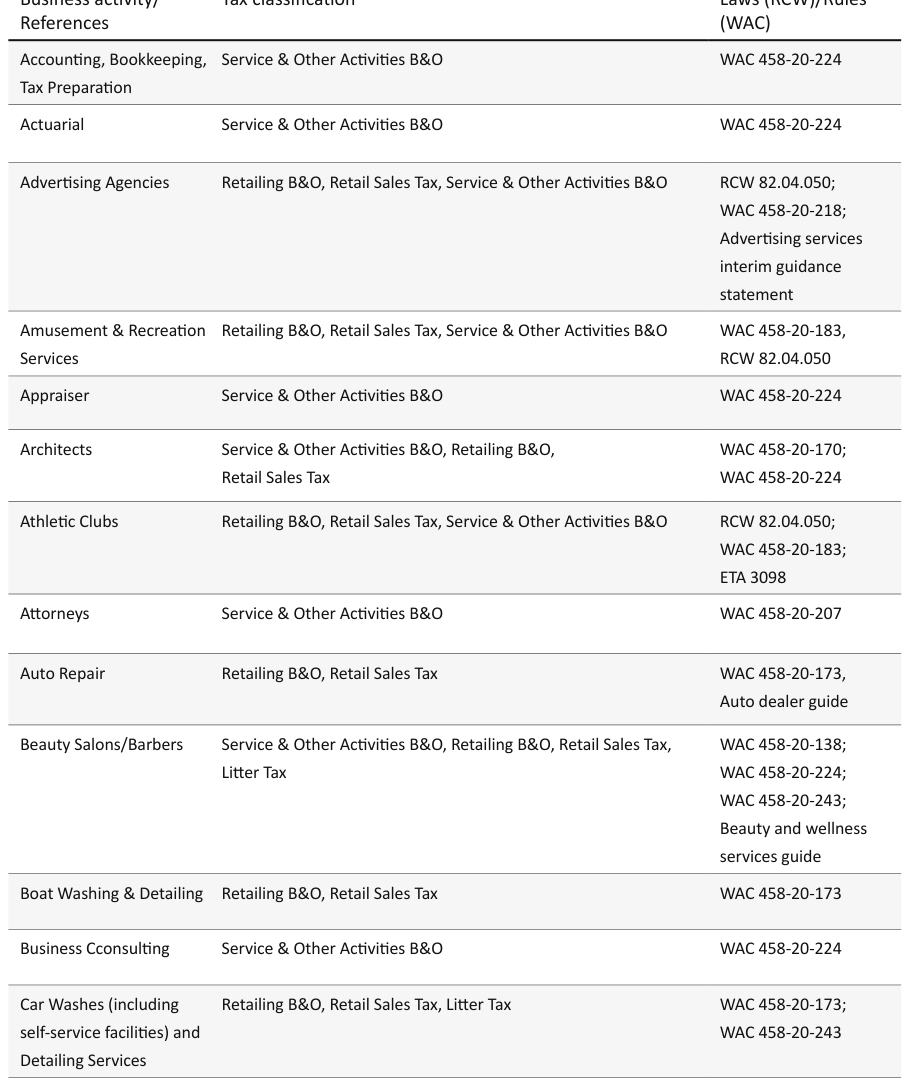
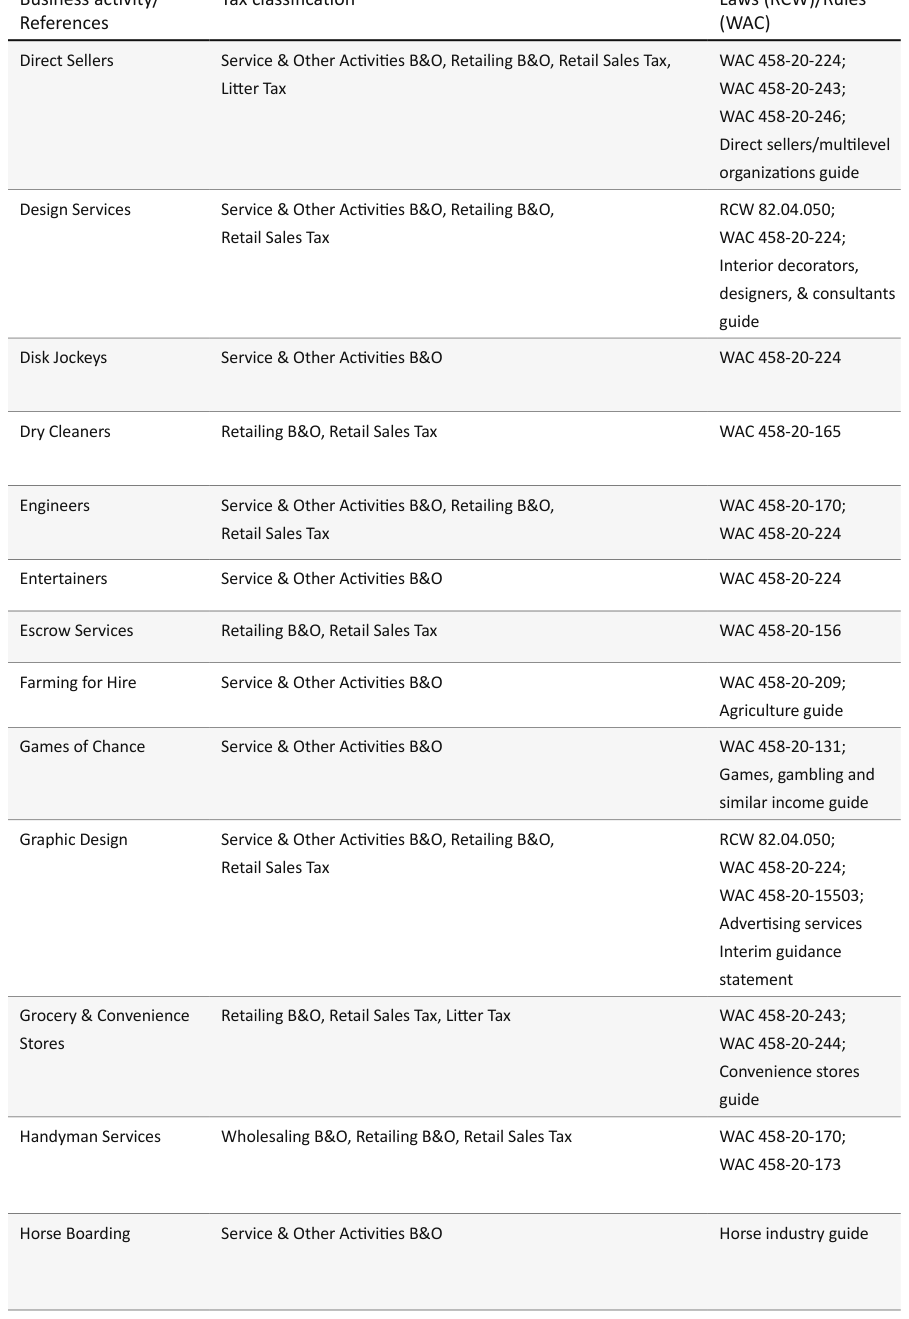
# D | Common Business Activities Table
The following is a list of common business activities and which tax classifications to use on the Excise Tax Return. It provides general guidelines, not specific reporting instructions.
If you conduct multiple business activities, it may be necessary to report under more than one tax classification. Specific activities, such as cigarette sales, may also be subject to other taxes.
If you have questions, contact us or visit your local Revenue office. Business activity/
Text version of this table
Accountni g, Bookkeeping, Tax Preparatoi n Court Reporters Service & Other Activities B&O WAC 458-20-224 Actuarial Service & Other Actvi itei s B&O WAC 458-20-224 Advertsi ing Agencies Retailing B&O, Retail Sales Tax, Service & Other Actvi itei s B&O RCW 82.04.050; WAC 458-20-218; Advertsi ing services interim guidance statement Amusement & Recreatoi n Retailing B&O, Retail Sales Tax, Service & Other Actvi itei s B&O WAC 458-20-183, Services RCW 82.04.050 Appraiser Court Reporters Service & Other Activities B&O WAC 458-20-224 Architects Service & Other Actvi itei s B&O, Retailing B&O, WAC 458-20-170; Retail Sales Tax WAC 458-20-224 Athletci Clubs Retailing B&O, Retail Sales Tax, Service & Other Actvi itei s B&O RCW 82.04.050; WAC 458-20-183; ETA 3098 Atot rneys Service & Other Actvi itei s B&O WAC 458-20-207 Auto Repair Dating, Escort Services Retailing B&O, Retail Sales Tax WAC 458-20-173, Auto dealer guide Beauty Salons/Barbers Service & Other Actvi itei s B&O, Retailing B&O, Retail Sales Tax, WAC 458-20-138; Litet r Tax WAC 458-20-224; WAC 458-20-243; Beauty and wellness services guide Boat Washing & Detailing Dating, Escort Services Retailing B&O, Retail Sales Tax WAC 458-20-224 Business Cconsultni g Service & Other Actvi itei s B&O WAC 458-20-224 Car Washes (including self-service facilitei s) and Detailing Services Retailing B&O, Retail Sales Tax, Wholesaling B&O, Litter Tax WAC 458-20-173; WAC 458-20-243
WAC 458-20-151
Service & Other Activities B&O, Retailing B&O, Retail Sales Tax Dentists/Orthodontists WAC 458-20-151;
Denturists guide
Business activity/
References
Tax classification Laws (RCW)/Rules (WAC) Service & Other Activities B&O, Retailing B&O, Retail Sales Tax,
# D | Common Business Activities Table
Direct Sellers
Design Services
Disk Jockeys
Dry Cleaners
Engineers
Entertainers
Escrow Services
Farming for Hire
Games of Chance
Graphic Design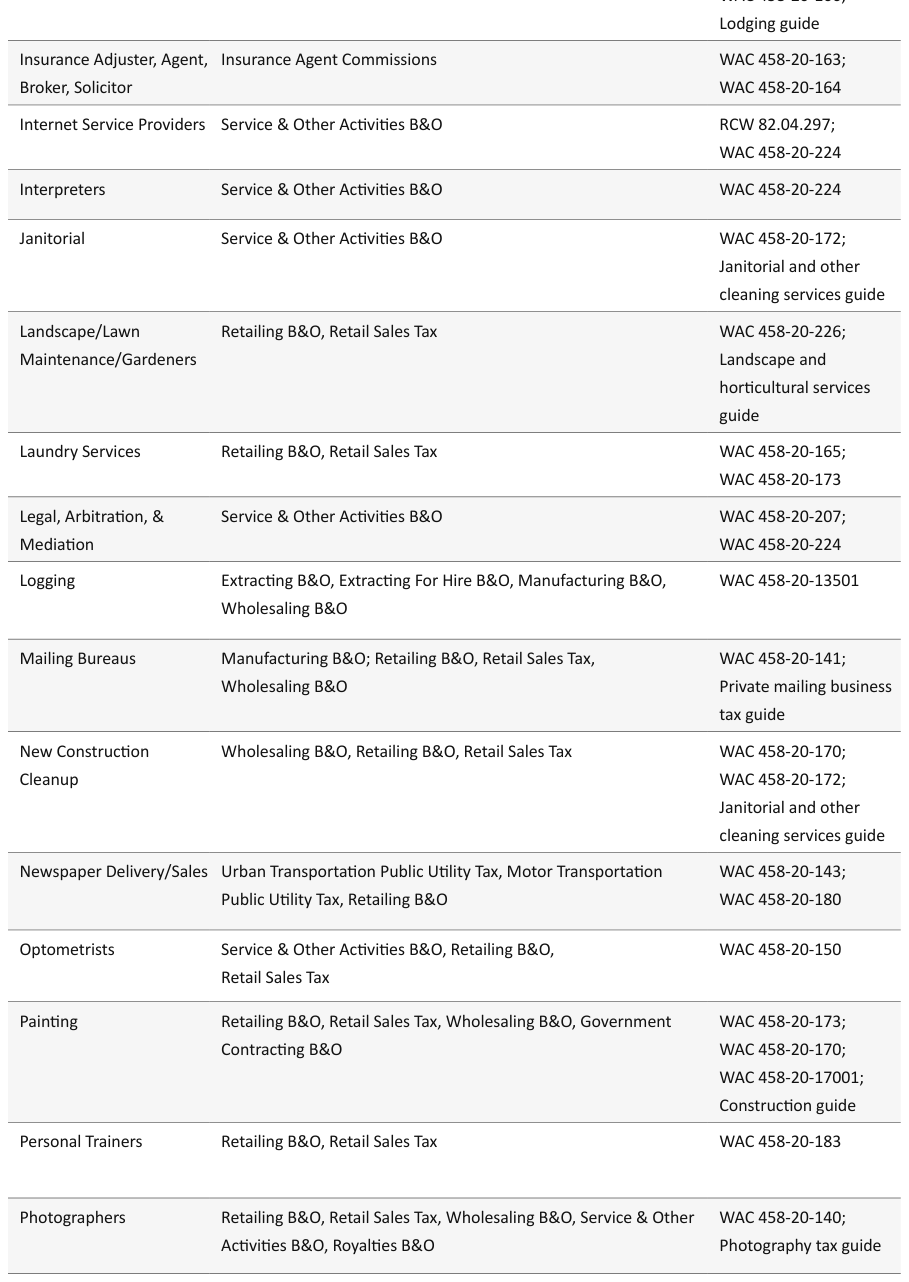
Text version of this table
Insurance Adjuster, Agent, Broker, Solicitor Insurance Agent Commissions WAC 458-20-163; WAC 458-20-164 Internet Service Providers Service & Other Actvi itei s B&O RCW 82.04.297; WAC 458-20-224 Interpreters Motel, Service & Other Activities B&O WAC 458-20-224 Janitorial Service & Other Actvi itei s B&O WAC 458-20-172; Janitorial and other cleaning services guide Landscape/Lawn Maintenance/Gardeners Retailing B&O, Retail Sales Tax WAC 458-20-226; Landscape and hortci ultural services guide Laundry Services Retailing B&O, Retail Sales Tax WAC 458-20-165; WAC 458-20-173 Legal, Arbitratoi n, & Mediatoi n Motel, Service & Other Activities B&O WAC 458-20-207; WAC 458-20-224 Logging Extractni g B&O, Extractni g For Hire B&O, Manufacturing B&O, WAC 458-20-13501 Wholesaling B&O Mailing Bureaus Manufacturing B&O; Retailing B&O, Retail Sales Tax, Wholesaling B&O WAC 458-20-141; Private mailing business tax guide New Constructoi n Wholesaling B&O, Retailing B&O, Retail Sales Tax WAC 458-20-170; Cleanup WAC 458-20-172; Janitorial and other cleaning services guide Newspaper Delivery/Sales Urban Transportatoi n Public Utliity Tax, Motor Transportatoi n Public Utliity Tax, Retailing B&O WAC 458-20-143; WAC 458-20-180 Optometrists Service & Other Actvi itei s B&O, Retailing B&O, WAC 458-20-150 Retail Sales Tax Paintni g Retailing B&O, Retail Sales Tax, Wholesaling B&O, Government Contractni g B&O WAC 458-20-173; WAC 458-20-170; WAC 458-20-17001; Constructoi n guide Personal Trainers Retailing B&O, Retail Sales Tax WAC 458-20-183 Photographers Retailing B&O, Retail Sales Tax, Wholesaling B&O, Service & Other Actvi itei s B&O, Royaltei s B&O WAC 458-20-140; Photography tax guide
# D | Common Business Activities Table
WAC 458-20-118;
WAC 458-20-166;
Lodging guide
WAC 458-20-163;
WAC 458-20-224
Extracting B&O, Extracting For Hire B&O, Manufacturing B&O, Logging Wholesaling B&O WAC 458-20-13501 Manufacturing B&O; Retailing B&O, Retail Sales Tax, Mailing Bureaus Wholesaling B&O New Construction Wholesaling B&O, Retailing B&O, Retail Sales Tax Cleanup WAC 458-20-141;
Private mailing business tax guide WAC 458-20-170;
WAC 458-20-172;
Janitorial and other cleaning services guide Newspaper Delivery/Sales Urban Transportation Public Utility Tax, Motor Transportation Public Utility Tax, Retailing B&O Optometrists Service & Other Activities B&O, Retailing B&O, Retail Sales Tax WAC 458-20-143;
WAC 458-20-180
WAC 458-20-150
Retailing B&O, Retail Sales Tax, Wholesaling B&O, Government Painting Contracting B&O Personal Trainers Retailing B&O, Retail Sales Tax WAC 458-20-173;
WAC 458-20-170;
WAC 458-20-17001;
Construction guide
WAC 458-20-183
Retailing B&O, Retail Sales Tax, Wholesaling B&O, Service & Other Photographers Activities B&O, Royalties B&O WAC 458-20-140;
Photography tax guide
Business activity/
Text version of this table
| Direct Sellers | Service & Other Actvi itei s B&O, Retailing B&O, Retail Sales Tax, Litet r Tax | WAC 458-20-224; WAC 458-20-243; WAC 458-20-246; Direct sellers/multlievel organizatoi ns guide |
| Design Services Service & Other Actvi itei s B&O, Retailing B&O, RCW 82.04.050; Retail Sales Tax WAC 458-20-224; Interior decorators, designers, & consultants guide | ||
| Disk Jockeys | Service & Other Actvi itei s B&O | WAC 458-20-224 |
| Dry Cleaners Retailing B&O, Retail Sales Tax WAC 458-20-165 | ||
| Engineers | Service & Other Actvi itei s B&O, Retailing B&O, Retail Sales Tax | WAC 458-20-170; WAC 458-20-224 |
| Entertainers Service & Other Actvi itei s B&O WAC 458-20-224 | ||
| Escrow Services | Retailing B&O, Retail Sales Tax | WAC 458-20-156 |
| Farming for Hire Service & Other Actvi itei s B&O WAC 458-20-209; Agriculture guide | ||
| Games of Chance | Service & Other Actvi itei s B&O | WAC 458-20-131; Games, gambling and similar income guide |
| Graphic Design Service & Other Actvi itei s B&O, Retailing B&O, RCW 82.04.050; Retail Sales Tax WAC 458-20-224; WAC 458-20-15503; Advertsi ing services Interim guidance statement | ||
| Grocery & Convenience Stores | Retailing B&O, Retail Sales Tax, Litet r Tax | WAC 458-20-243; WAC 458-20-244; Convenience stores guide |
| Handyman Services Wholesaling B&O, Retailing B&O, Retail Sales Tax WAC 458-20-170; WAC 458-20-173 | ||
| Horse Boarding | Service & Other Actvi itei s B&O | Horse industry guide |
# D | Common Business Activities Table
Physicians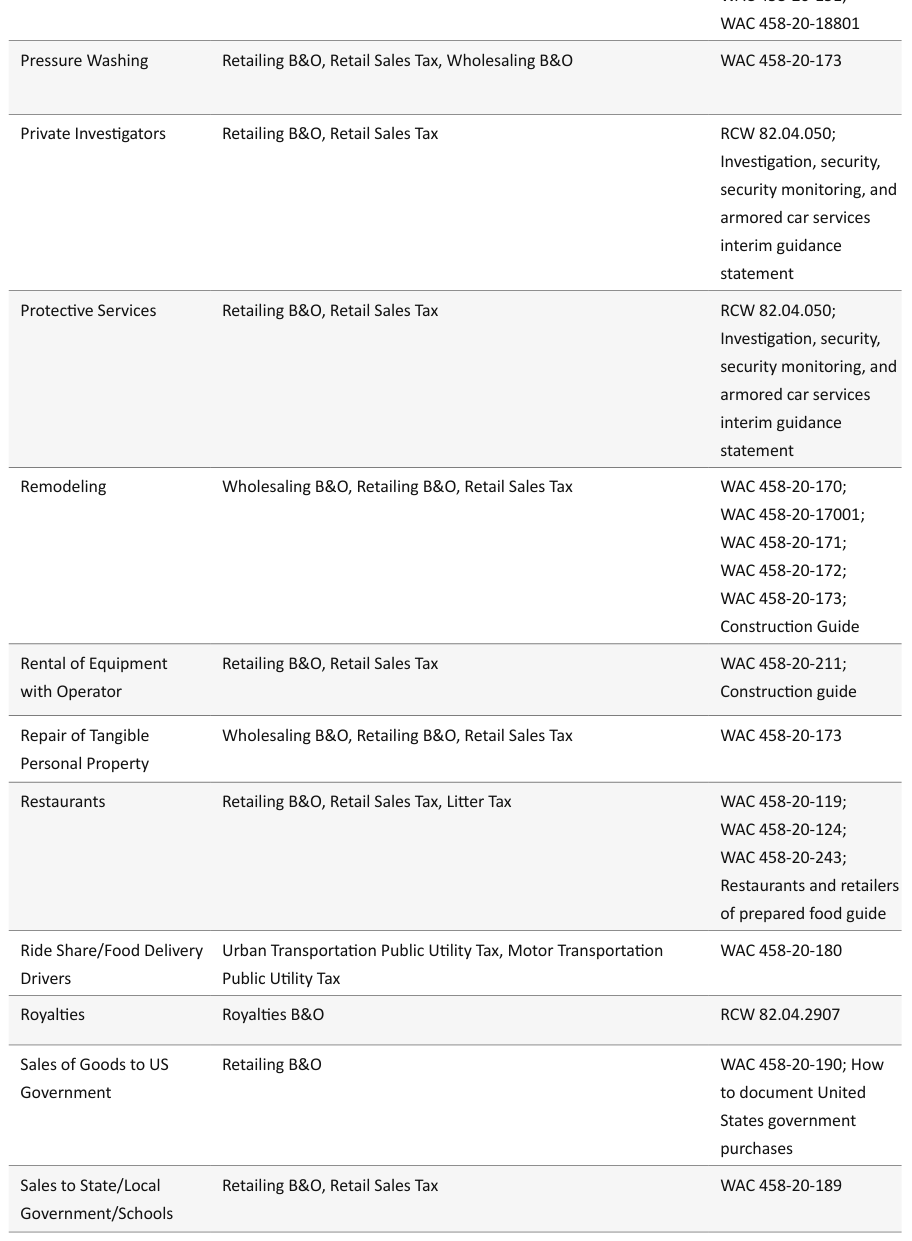
Text version of this table
Pressure Washing Retailing B&O, Retail Sales Tax, Wholesaling B&O WAC 458-20-15502; Private Investgi ators Retailing B&O, Retail Sales Tax RCW 82.04.050; Investgi atoi n, security, security monitoring, and armored car services interim guidance statement Protectvi e Services Tattooing Retailing B&O, Retail Sales Tax RCW 82.04.050; Investgi atoi n, security, security monitoring, and armored car services interim guidance statement Remodeling Wholesaling B&O, Retailing B&O, Retail Sales Tax WAC 458-20-170; WAC 458-20-17001; WAC 458-20-171; WAC 458-20-172; WAC 458-20-173; Constructoi n Guide Rental of Equipment with Operator Tattooing Retailing B&O, Retail Sales Tax WAC 458-20-211; Constructoi n guide Repair of Tangible Wholesaling B&O, Retailing B&O, Retail Sales Tax WAC 458-20-173 Personal Property Restaurants Tattooing Retailing B&O, Retail Sales Tax WAC 458-20-119; WAC 458-20-124; WAC 458-20-243; Restaurants and retailers of prepared food guide Ride Share/Food Delivery Urban Transportatoi n Public Utliity Tax, Motor Transportatoi n WAC 458-20-180 Drivers Public Utliity Tax Royaltei s Royaltei s B&O RCW 82.04.215; Sales of Goods to US Retailing B&O WAC 458-20-190; How Government to document United States government purchases Sales to State/Local Government/Schools Tattooing Retailing B&O, Retail Sales Tax WAC 458-20-15502; 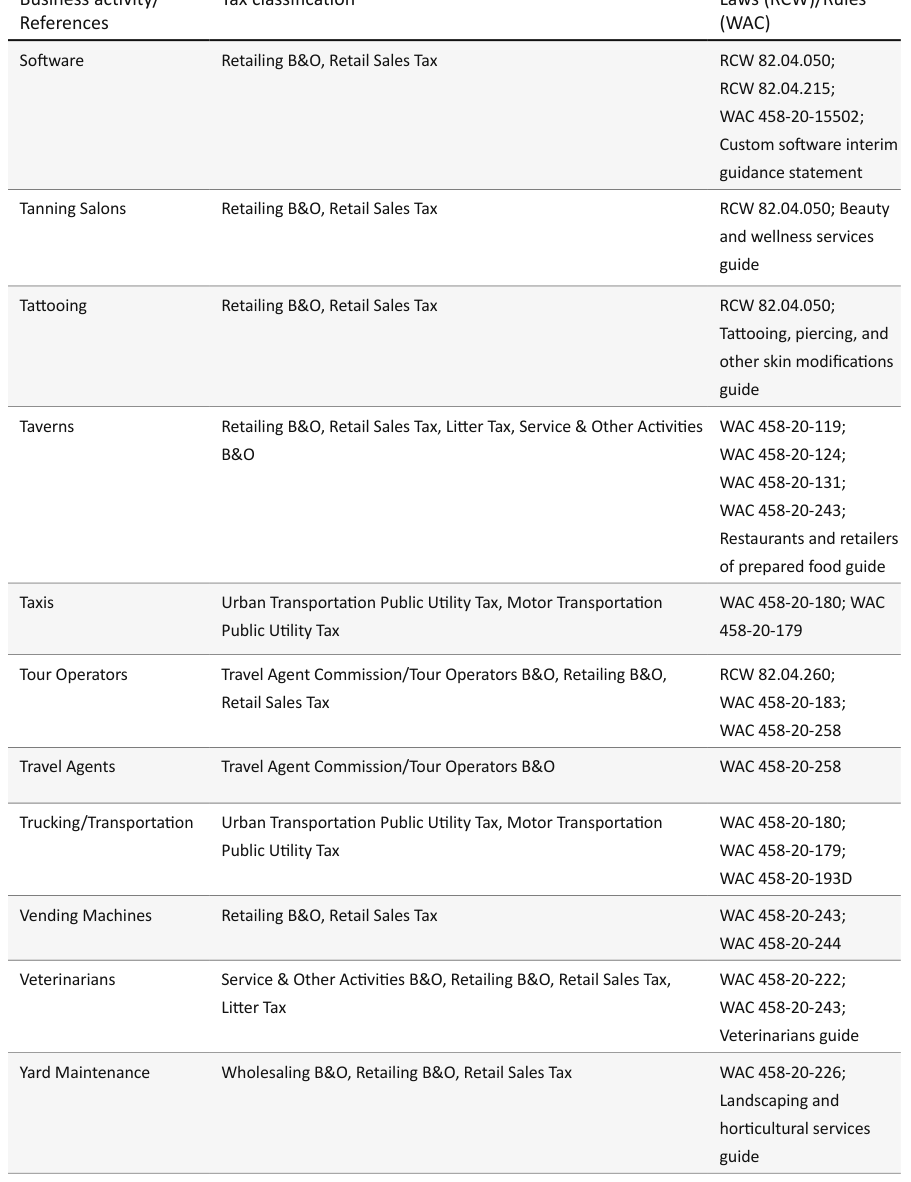
Text version of this table
Sofwt are Retailing B&O, Retail Sales Tax RCW 82.04.050; RCW 82.04.215; WAC 458-20-15502; Custom sofwt are interim guidance statement Tanning Salons Retailing B&O, Retail Sales Tax RCW 82.04.050; Beauty and wellness services guide Tatot oing Retailing B&O, Retail Sales Tax RCW 82.04.050; Tatot oing, piercing, and other skin modifci atoi ns guide Taverns Retailing B&O, Retail Sales Tax, Litet r Tax, Service & Other Actvi itei s WAC 458-20-119; B&O WAC 458-20-124; WAC 458-20-131; WAC 458-20-243; Restaurants and retailers of prepared food guide Taxis Urban Transportatoi n Public Utliity Tax, Motor Transportatoi n Public Utliity Tax WAC 458-20-180; WAC 458-20-179 Tour Operators Travel Agent Commission/Tour Operators B&O, Retailing B&O, RCW 82.04.260; Retail Sales Tax WAC 458-20-183; WAC 458-20-258 Travel Agents Travel Agent Commission/Tour Operators B&O WAC 458-20-258 Trucking/Transportatoi n Urban Transportatoi n Public Utliity Tax, Motor Transportatoi n WAC 458-20-180; Public Utliity Tax WAC 458-20-179; WAC 458-20-193D Vending Machines Retailing B&O, Retail Sales Tax WAC 458-20-243; WAC 458-20-244 Veterinarians Service & Other Actvi itei s B&O, Retailing B&O, Retail Sales Tax, WAC 458-20-222; Litet r Tax WAC 458-20-243; Veterinarians guide Yard Maintenance Wholesaling B&O, Retailing B&O, Retail Sales Tax WAC 458-20-226; Landscaping and hortci ultural services guide
# Local offices
Bellingham
1904 Humboldt St, Suite A
Bellingham, WA 98225
360-594-4840
Bothell
12100 Northeast 195th St.
Suite 100
Bothell, WA 98011
425-984-6400
Kent
20819 72nd Ave South, Suite 680 Kent, WA 98032 425-656-5100 Port Angeles 734 E First St, Suite B Port Angeles, WA 98362 360-417-9900 Richland 1657 Fowler St Richland, WA 99352 509-987-1201 Seattle 2101 4th Ave, Suite 1400 Seattle, WA 98121 206-727-5300 Spokane 1330 N Washington, Suite 5600 Spokane, WA 99201 509-327-0200 Tacoma 3315 South 23rd St, Suite 300 Tacoma, WA 98411 253-382-2000 Tumwater 6500 Linderson Way SW, Suite 102 Tumwater, WA 98501 360-705-6705 Vancouver 8008 NE 4th Plain Blvd, Suite 320 PO Box 1648 Vancouver, WA 98668 360-256-2060 Wenatchee 630 N Chelan Ave, Suite B3 Wenatchee, WA 98807 509-885-9825 Yakima 3703 River Rd, Suite 3 Yakima, WA 98902 509-454-5160 Prepared by the Customer Expierence and For tax assistance or to request this document in an alternate format, visit dor.wa.gov or call Communications Division 360-705-6705. Teletype (TTY) users may use the Washington Relay Service by calling 711.
TPS0017 02/17/2026
Source: view the official PDF
The source document contains 10 figures (charts or worksheet graphics) not reproduced in this text version. See the official PDF above.
Nearby sections (13 sections)
- business-tax-basics · Business Tax Basics — Overview of Washington…
- clean-fuel-vehicle · Clean Alternative Fuel Passenger Vehicle Leases…
- dairy-fruitveg-seafood · Dairy, Fresh Fruit/Vegetable & Seafood…
- energy-eff-comm-credit · Energy Efficient Commercial Equipment Credit…
- estate-tax-add1 · Estate Tax Addendum 1 — Qualified Terminable Interest…
- estate-tax-add2 · Estate Tax Addendum 2 — Property Used for Farming…
- estate-tax-add3 · Estate Tax Addendum 3 — Qualified Family-Owned…
- estate-tax-add4 · Estate Tax Addendum 4 — Apportionment for…
- estate-tax-instructions · Washington Estate Tax — Filing Instructions
- lodging-addendum · Lodging Addendum — Form & Instructions
- matc-schedule-c · Multiple Activities Tax Credit (MATC) Schedule C
- natural-gas-use-tax · Natural Gas Use Tax — Form & Instructions
- sbc-annual · Annual Combined Excise Tax Return — Form & Instructions