Nevada Department of Taxation Forms & Instructions
Nevada Commerce Tax Return — Form EXC-F025 (combo form+instructions)
Commerce Tax Return or NVBID:
Account No.:
Choose:
Business Entity NAICS Code Category:
Business Entity Legal Name:
Business Entity Address:
N V
For the Taxable Year through
*Please note: if Nevada gross revenue of your business exceeds $4,000,000 during the tax year, you are REQUIRED to file this return.
Business Closed Alternative Situsing Method
Amended Return
Gross Revenue from engaging in business in Nevada
1 Sale of inventory
Sitused to Nevada
2 Service performance
3 Rents, royalties and leases
4 Interest income from credit sales and loans
5 Damages received from litigation for loss of business income 6 Insurance proceeds for loss of business income 7 Forgiven debt 8 Other revenue
9 Total Gross Revenue (Line 1 through Line 8)
10 Less $4,000,000 Threshold
11 Adjusted Gross Revenue (Line 9 less Line 10)
# General Business Deductions
12 Returns and refunds to customers
13 Bad debt
To the extent included in revenue
14 Distributions required by fiduciary duty or law 15 Distributions under certain written contracts 16 Reimbursement of certain expenses and advances from clients Taxes collected from 3rd party and remitted to taxing authority 18 Other deductions
Industry Specific Deductions
19 Employee leasing deduction
20 Gaming deduction
21 Health care provider deduction
22 Insurance deduction
23 Liquor tax deduction
24 Mining deduction
25 US Armed Forces housing deduction
26 Total Deductions (Line 12 through Line 25)
Estimates Used
10 (4,000,000.00)
Nevada Taxable Revenue (Line 11 less Line 26, but not less than $0) 28 Tax rate per NAICS code category
# 29 Commerce Tax due
Text version of this table
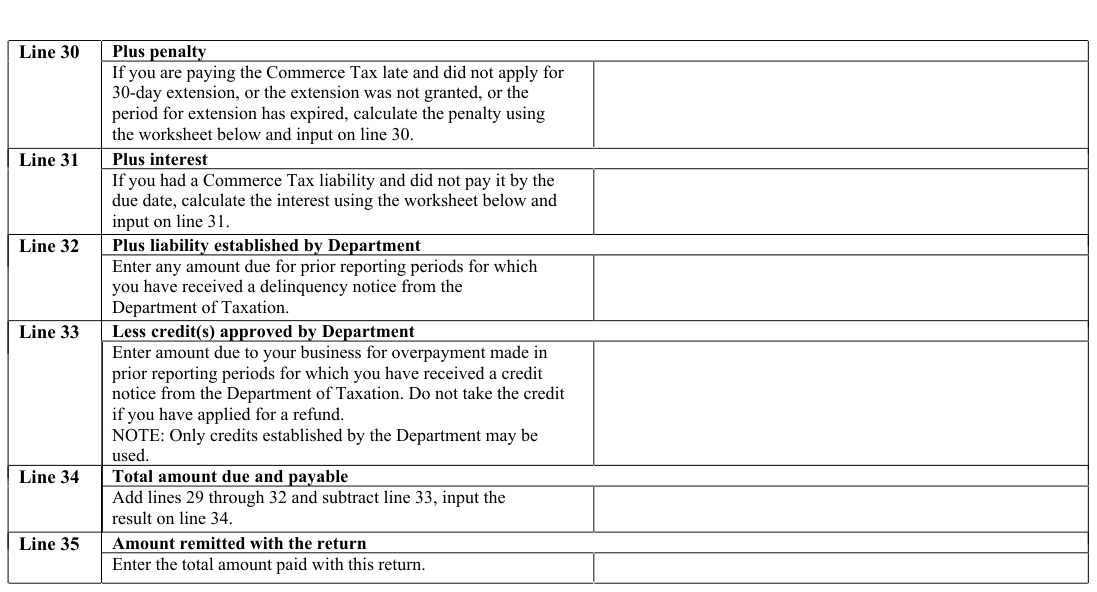
Line 30 Plus penalty If you are paying the Commerce Tax late and did not apply for 30-day extension, or the extension was not granted, or the period for extension has expired, calculate the penalty using the worksheet below and input on line 30. Line 31 Plus interest If you had a Commerce Tax liability and did not pay it by the due date, calculate the interest using the worksheet below and input on line 31. Line 32 Plus liability established by Department Enter any amount due for prior reporting periods for which you have received a delinquency notice from the Department of Taxation. Line 33 Less credit(s) approved by Department Enter amount due to your business for overpayment made in prior reporting periods for which you have received a credit notice from the Department of Taxation. Do not take the credit if you have applied for a refund. NOTE: Only credits established by the Department may be used. Line 34 Total amount due and payable Add lines 29 through 32 and subtract line 33, input the result on line 34. Line 35 Amount remitted with the return Enter the total amount paid with this return.
Under penalty of perjury, I certify that I have examined this return and to the best of my knowledge and belief it is true, correct and complete.
Text version of this table
Business Entity Authorized Representative's Signature: SIGN Phone Number: Name and Title: Date: For Department use only Print
# Instructions for Commerce Tax Return
General instructions
Purpose of the Form:
Use the Commerce Tax Return form to report the gross revenue from engaging in business in Nevada and deductions of a business entity to arrive at the amount of Nevada Commerce Tax for the taxable year July 1 through June 30.
Who Must File:
Each business entity, whose Nevada gross revenue exceeds $4,000,000 during the taxable year, unless specifically exempted by Commerce Tax law (Nevada Revised Statutes (NRS), Chapter 363C), has to file a Commerce Tax return.
If a merger or conversion, as ascribed by NRS 92A, takes place during the taxable year, the surviving/resulting business entity may file a single combined Commerce Tax return.
Taxable Year:
The taxable year is 12-months period beginning on July 1st and ending on June 30th of the following year. If the business entity ceases to exist before the end of the taxable year, input the date the entity ceased to exist in the second box of line "For the taxable year… through". The box "Business Closed" should also be checked.
When to File:
The Commerce Tax return can be filed between the end of the taxable year July 1st and the due date of the Commerce tax return, August 14th. If the due date falls on a weekend, the Commerce Tax is due the next business day.
Where to File:
Returns can be filed electronically or via paper.
- To file electronically, go to: https://mynvtax.nv.gov
- To mail a paper copy, use the address below:
# 3850 ARROWHEAD DRIVE
CARSON CITY, NV 89706
Accounting Method:
The accounting method for the purposes of determining the amount of the Commerce Tax must be the same as the method used for federal income tax purposes.
Recordkeeping:
Each person responsible for maintaining the records of a business entity shall:
Keep such records as may be necessary to determine the amount of the liability of the business entity for Commerce Tax;
Preserve those records for 4 years from the date the Commerce Tax return is filed or Commerce Tax liability is paid or until any litigation or prosecution pursuant to Commerce Tax law is finally determined, whichever is longer; and Make the records available for inspection by the Department upon demand at reasonable times during regular business hours.
# Amended Return
If the original return filed is based on estimates, or if, after filing the return, you discover an error with the reported revenue or deduction(s), you should file an amended return. If you amend the return, check the box "Amended Return".
Enclose supporting documentation, including worksheet(s) and explanations, to the amended return and mail it to:
# 3850 ARROWHEAD DRIVE
CARSON CITY, NV 89706
An amended Commerce Tax Return can also be filed electronically by going to https://mynvtax.nv.gov. Supporting documentation is required to be uploaded to validate the amended amounts. If the amendment results in a credit and a refund is sought, a refund request statement should be included in the supporting documentation.
Extension of Time to File and Pay Commerce Tax:
If you have good cause, you may request a 30-day extension to file and pay Commerce Tax. If the commerce tax is paid during the period of extension, no penalty or late charge will be imposed for failure to pay the Commerce Tax at the time required, but the interest will accrue at the rate of 0.75 percent per month from the date on which the amount of tax would have been due without extension until the date of payment. Use the Application for 30-day Extension to File and Pay Commerce Tax form to request an extension. Submit the Application before the date on which the payment of the Commerce Tax becomes due.
Who Must Sign:
The return must be signed by the business entity's authorized representative under penalty of perjury; the "certification of the return" box shall be checked. Enter the name, title, and the contact phone number of the authorized representative.
NAICS Code Category:
The NAICS code category is selected on the first return the business entity files. Use the keyword search for the 2012 North American Industry Classification System website to determine your NAICS code: https://www.census.gov/naics/. If your business is engaged in multiple business activities, the NAICS code category is based on the category in which the highest percentage of Nevada gross revenue is generated. Use the first two or three digits of your NAICS code to locate your NAICS code category in the NAICS Code Categories/Tax Rates chart on page 7 of the instructions.
Once the NAICS code category is selected on the initial Commerce Tax return, it may be changed only upon obtaining permission from the Department. Use the NAICS Code Category Change form to request the NAICS code category change.
Use of Estimates:
For the calculation of the uncompensated care amounts refer to Commerce Tax Regulations. If you rely on the most recent federal income tax return or the previous year's Commerce Tax return for the calculation of revenue for Commerce Tax, check the box "Estimates used". However, you will have to file an amended return, once the true amounts become available.
Alternative Situsing Method:
If the situsing rules of Commerce Tax law or Commerce Tax Regulations do not fairly represent the extent of the business conducted in Nevada, the business entity may utilize an alternative method of situsing. The alternative method should be reasonable, consistent, uniformly applied and supported by the records. Check the box "Alternative situsing method", if you used an alternative method to situs the revenue.
Revenue:
Include only sitused to Nevada revenue. For situsing guidance, see line-by-line instructions on page 3.
Do not include in the reported gross revenue:
Cash discounts taken by customers
Value of complimentary goods or services provided to customers Value of property or services donated to a nonprofit organization that qualifies as a tax-exempt organization pursuant to
# IRC 501(c)(3)
Amounts indirectly realized from a reduction of an expense or deduction Interest or dividends received, except for the interest on credit sales or from loans to customers (see instructions for line 4) Distributions from corporations, including S-corporations, and distributive or proportionate share of receipts and income from partnerships or LLCs Revenue from hedging transactions as defined by IRC §1221 or FAS No.133, unless the title to real or tangible personal property is transferred in such transactions Revenue received from another member of an affiliated group (50% or more direct or indirect ownership, control or possession of a business entity) Proceeds attributable to the repayment, maturity or redemption of the principal of a loan, bond, mutual fund, certificate of deposit or marketable instrument The principal amount received under a repurchase agreement or on account of any transaction characterized as a loan.
Proceeds from the issuance of the business entity's own stock, options, warrants, puts or calls, from the sale of the treasury stock Contributions to a corporation or a partnership (IRC §118 and §721) Amounts realized in corporate liquidations (IRC §331 and §336) Amounts realized from liquidation of subsidiaries by a corporation (IRC §332 and §337) Amounts realized from certain corporate acquisitions (IRC §338) Amounts realized from transfer of assets to a corporation in exchange for stock (IRC §351) Amounts realized from corporate modifications and reorganizations (IRC §355 and §368) Distributions from a partnership (IRC §731) Amounts realized in like-kind exchanges (IRC §1031) Amounts realized from the sale of an account receivable Amounts realized from the sale, exchange, disposition or other grant of the right to use trademarks, trade names, patents, copyrights and similar intellectual property Receipts from sale, exchange or other disposition of the capital and business assets (IRC§ 1221 and 1231) Amounts realized from involuntary conversions (IRC §1033) Insurance policy proceeds, except for the proceeds received for the loss of business revenue (see instructions for line 6) Damages received as a result of litigation, except for the damages received for loss of business income (see instructions for line 5) Revenue that is not subject to tax pursuant to the Constitution or laws of the United States or the Nevada Constitution Amounts that are not considered revenue under generally accepted accounting principles.
Deductions
Deductions are limited to those specifically stated in Commerce Tax law and allowed to the extent they are included in the gross revenue.
The cost of goods sold or other expenses incurred, that contributes to the production of gross income, are not deductible.
# Line 1 Sale of Inventory
Text version of this table
| LINE # | INSTRUCTIONS | EXAMPLES |
|---|---|---|
| Line 1 | Sale of Inventory | |
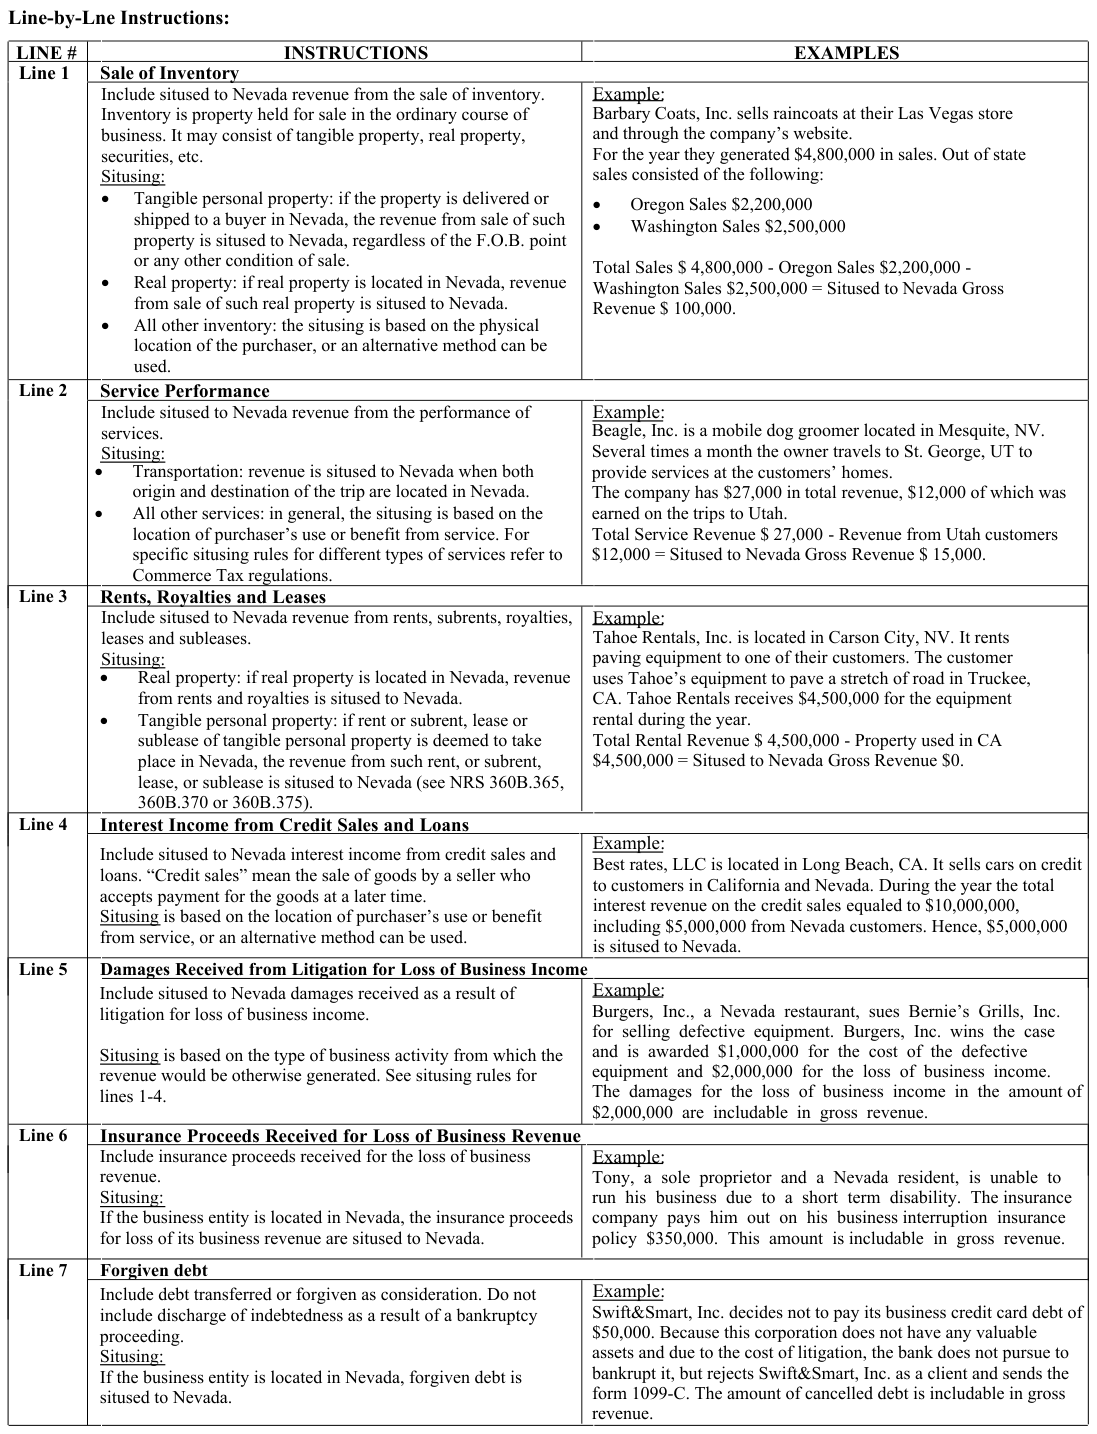
| Include sitused to Nevada revenue from the sale of inventory. Inventory is property held for sale in the ordinary course of business. It may consist of tangible property, real property, securities, etc. Situsing: Tangible personal property: if the property is delivered or shipped to a buyer in Nevada, the revenue from sale of such property is sitused to Nevada, regardless of the F.O.B. point or any other condition of sale. Real property: if real property is located in Nevada, revenue from sale of such real property is sitused to Nevada. All other inventory: the situsing is based on the physical location of the purchaser, or an alternative method can be used. | Example: Barbary Coats, Inc. sells raincoats at their Las Vegas store and through the company’s website. For the year they generated $4,800,000 in sales. Out of state sales consisted of the following: Oregon Sales $2,200,000 Washington Sales $2,500,000 Total Sales $ 4,800,000 - Oregon Sales $2,200,000 - Washington Sales $2,500,000 = Sitused to Nevada Gross Revenue $ 100,000. | |
| Line 2 | Service Performance | |
| Include sitused to Nevada revenue from the performance of services. Situsing: Transportation: revenue is sitused to Nevada when both origin and destination of the trip are located in Nevada. All other services: in general, the situsing is based on the location of purchaser’s use or benefit from service. For specific situsing rules for different types of services refer to Commerce Tax regulations. | Example: Beagle, Inc. is a mobile dog groomer located in Mesquite, NV. Several times a month the owner travels to St. George, UT to provide services at the customers’ homes. The company has $27,000 in total revenue, $12,000 of which was earned on the trips to Utah. Total Service Revenue $ 27,000 - Revenue from Utah customers $12,000 = Sitused to Nevada Gross Revenue $ 15,000. | |
| Line 3 | Rents, Royalties and Leases | |
| Include sitused to Nevada revenue from rents, subrents, royalties, leases and subleases. Situsing: Real property: if real property is located in Nevada, revenue from rents and royalties is sitused to Nevada. Tangible personal property: if rent or subrent, lease or sublease of tangible personal property is deemed to take place in Nevada, the revenue from such rent, or subrent, lease, or sublease is sitused to Nevada (see NRS 360B.365, 360B.370 or 360B.375). | Example: Tahoe Rentals, Inc. is located in Carson City, NV. It rents paving equipment to one of their customers. The customer uses Tahoe’s equipment to pave a stretch of road in Truckee, CA. Tahoe Rentals receives $4,500,000 for the equipment rental during the year. Total Rental Revenue $ 4,500,000 - Property used in CA $4,500,000 = Sitused to Nevada Gross Revenue $0. | |
| Line 4 | Interest Income from Credit Sales and Loans | |
| Include sitused to Nevada interest income from credit sales and loans. “Credit sales” mean the sale of goods by a seller who accepts payment for the goods at a later time. Situsing is based on the location of purchaser’s use or benefit from service, or an alternative method can be used. | Example: Best rates, LLC is located in Long Beach, CA. It sells carson credit to customers in California and Nevada. During the year the total interest revenue on the credit sales equaled to $10,000,000, including $5,000,000 from Nevada customers. Hence, $5,000,000 is sitused to Nevada. | |
| Line 5 | Damages Received from Litigation for Loss of Business Income Include sitused to Nevada damages received as a result of Example: litigation for loss of business income. Burgers, Inc., a Nevada restaurant, sues Bernie’s Grills, Inc. for selling defective equipment. Burgers, Inc. wins the case Situsing is based on the type of business activity from which the and is awarded $1,000,000 for the cost of the defective revenue would be otherwise generated. See situsing rules for equipment and $2,000,000 for the loss of business income. lines 1-4. The damages for the loss of business income in the amount of $2,000,000 are includable in gross revenue. | |
| Example: Burgers, Inc., a Nevada restaurant, sues Bernie’s Grills, Inc. for selling defective equipment. Burgers, Inc. wins the case and is awarded $1,000,000 for the cost of the defective equipment and $2,000,000 for the loss of business income. The damages for the loss of business income in the amount of $2,000,000 are includable in gross revenue. | ||
| Line 6 | Insurance Proceeds Received for Loss of Business Revenue | |
| Include insurance proceeds received for the loss of business revenue. Situsing: If the business entity is located in Nevada, the insurance proceeds for loss of its business revenue are sitused to Nevada. | Example: Tony, a sole proprietor and a Nevada resident, is unable to run his business due to a short term disability. The insurance company pays him out on his business interruption insurance policy $350,000. This amount is includable in gross revenue. | |
| Line 7 | Forgiven debt | |
| Include debt transferred or forgiven as consideration. Do not include discharge of indebtedness as a result of a bankruptcy proceeding. Situsing: If the business entity is located in Nevada, forgiven debt is sitused to Nevada. | Example: Swift&Smart, Inc. decides not to pay its business credit card debt of $50,000. Because this corporation does not have any valuable assets and due to the cost of litigation, the bank does not pursue to bankrupt it, but rejects Swift&Smart, Inc. as a client and sends the form 1099-C. The amount of cancelled debt is includable in gross revenue. |
# Line 2
Include sitused to Nevada revenue from the performance of services.
Situsing:
Transportation: revenue is sitused to Nevada when both origin and destination of the trip are located in Nevada.
All other services: in general, the situsing is based on the location of purchaser's use or benefit from service. For specific situsing rules for different types of services refer to Commerce Tax regulations.
Rents, Royalties and Leases
# EXAMPLES
# Line 4
Include sitused to Nevada interest income from credit sales and loans. "Credit sales" mean the sale of goods by a seller who accepts payment for the goods at a later time.
Situsing is based on the location of purchaser's use or benefit from service, or an alternative method can be used.
Example:
Tahoe Rentals, Inc. is located in Carson City, NV. It rents paving equipment to one of their customers. The customer uses Tahoe's equipment to pave a stretch of road in Truckee,
CA. Tahoe Rentals receives $4,500,000 for the equipment rental during the year.
Total Rental Revenue $ 4,500,000 - Property used in CA $4,500,000 = Sitused to Nevada Gross Revenue $0.
Example:
Best rates, LLC is located in Long Beach, CA. It sells carson credit to customers in California and Nevada. During the year the total interest revenue on the credit sales equaled to $10,000,000, including $5,000,000 from Nevada customers. Hence, $5,000,000 is sitused to Nevada.
Damages Received from Litigation for Loss of Business Income
# Line 5
# Line 6
Example:
Burgers, Inc., a Nevada restaurant, sues Bernie's Grills, Inc. for selling defective equipment. Burgers, Inc. wins the case and is awarded $1,000,000 for the cost of the defective equipment and $2,000,000 for the loss of business income.
The damages for the loss of business income in the amount of $2,000,000 are includable in gross revenue.
Insurance Proceeds Received for Loss of Business Revenue
Include insurance proceeds received for the loss of business revenue.
Situsing:
Example:
Tony, a sole proprietor and a Nevada resident, is unable to run his business due to a short term disability. The insurance company pays him out on his business interruption insurance If the business entity is located in Nevada, the insurance proceeds for loss of its business revenue are sitused to Nevada.
Line 7 Forgiven debt
Include debt transferred or forgiven as consideration. Do not include discharge of indebtedness as a result of a bankruptcy proceeding.
Situsing:
If the business entity is located in Nevada, forgiven debt is sitused to Nevada. policy $350,000. This amount is includable in gross revenue.
Example:
Swift&Smart, Inc. decides not to pay its business credit card debt of $50,000. Because this corporation does not have any valuable assets and due to the cost of litigation, the bank does not pursue to bankrupt it, but rejects Swift&Smart, Inc. as a client and sends the form 1099-C. The amount of cancelled debt is includable in gross revenue.
# Line 17
Text version of this table
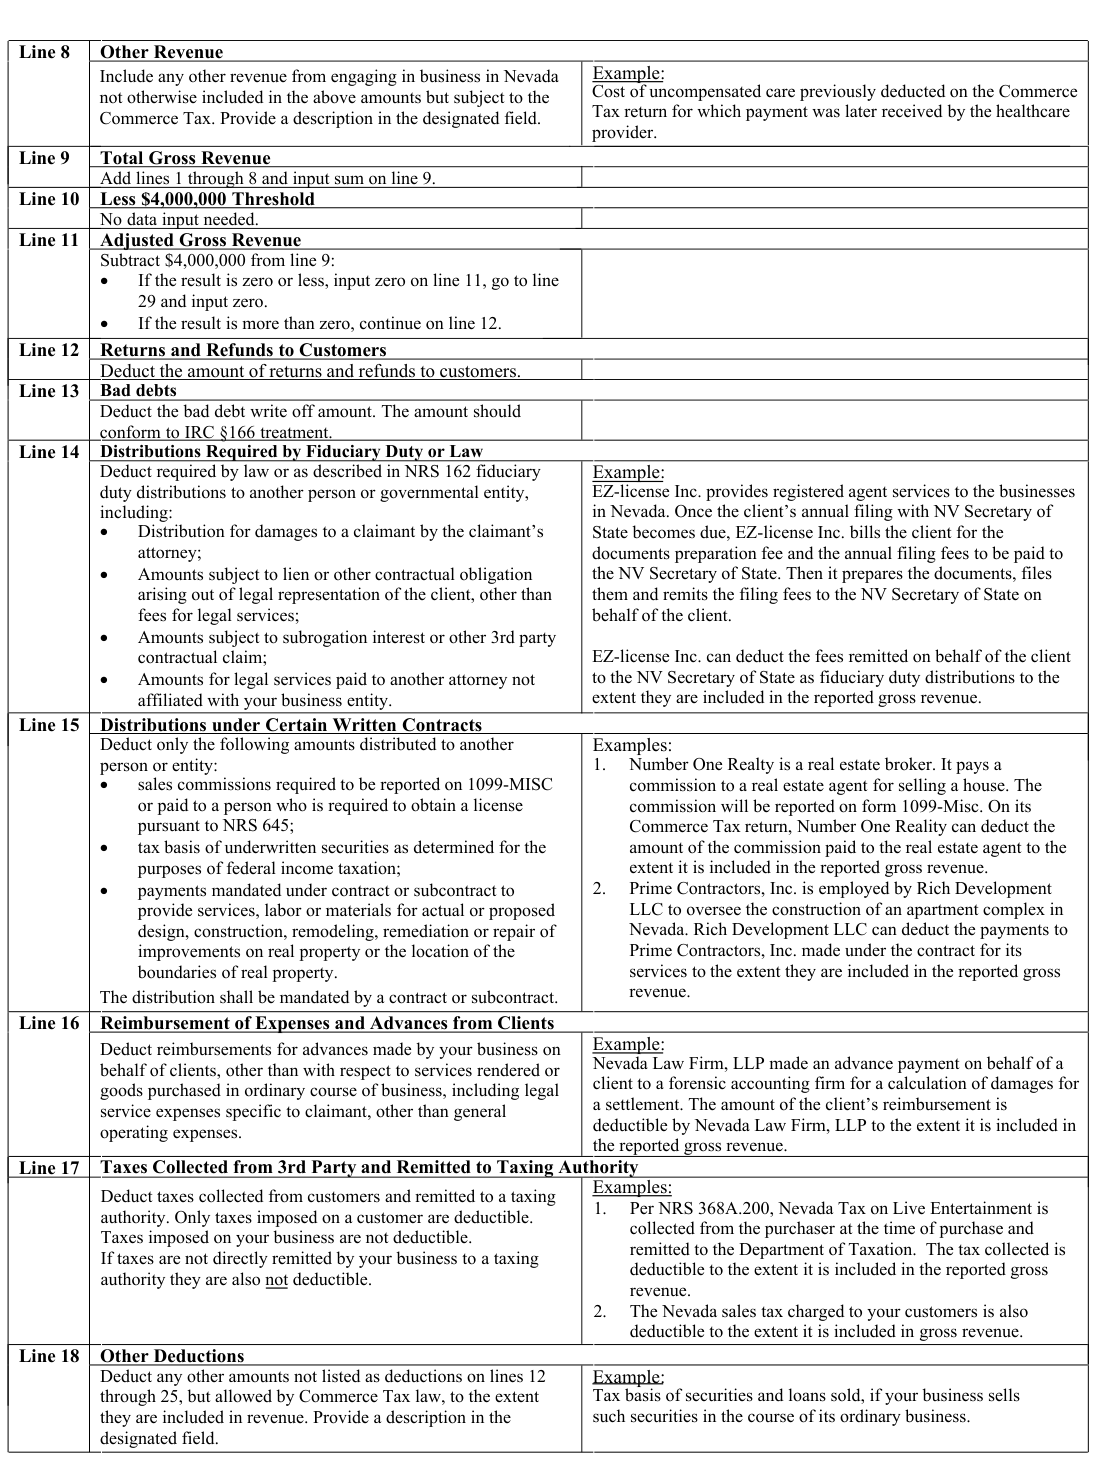
| Line 8 | Other Revenue | |
| Include any other revenue from engaging in business in Nevada not otherwise included in the above amounts but subject to the Commerce Tax. Provide a description in the designated field. | Example: Cost of uncompensated care previously deducted on the Commerce Tax return for which payment was later received by the healthcare provider. | |
| Line 9 | Total Gross Revenue | |
| Add lines 1 through 8 and input sum on line 9. | ||
| Line 10 | Less $4,000,000 Threshold | |
| No data input needed. | ||
| Line 11 | Adjusted Gross Revenue | |
| Subtract $4,000,000 from line 9: If the result is zero or less, input zero on line 11, go to line 29 and input zero. If the result is more than zero, continue on line 12. | ||
| Line 12 | Returns and Refunds to Customers | |
| Deduct the amount of returns and refunds to customers. | ||
| Line 13 | Bad debts | |
| Deduct the bad debt write off amount. The amount should conform to IRC §166 treatment. | ||
| Line 14 | Distributions Required by Fiduciary Duty or Law | |
| Deduct required by law or as described in NRS 162 fiduciary duty distributions to another person or governmental entity, including: Distribution for damages to a claimant by the claimant’s attorney; Amounts subject to lien or other contractual obligation arising out of legal representation of the client, other than fees for legal services; Amounts subject to subrogation interest or other 3rd party contractual claim; Amounts for legal services paid to another attorney not affiliated with your business entity. | Example: EZ-license Inc. provides registered agent services to the businesses in Nevada. Once the client’s annual filing with NV Secretary of State becomes due, EZ-license Inc. bills the client for the documents preparation fee and the annual filing fees to be paid to the NV Secretary of State. Then it prepares the documents, files them and remits the filing fees to the NV Secretary of State on behalf of the client. EZ-license Inc. can deduct the fees remitted on behalf of the client to the NV Secretary of State as fiduciary duty distributions to the extent they are included in the reported gross revenue. | |
| Line 15 | Distributions under Certain Written Contracts | |
| Deduct only the following amounts distributed to another person or entity: sales commissions required to be reported on 1099-MISC or paid to a person who is required to obtain a license pursuant to NRS 645; tax basis of underwritten securities as determined for the purposes of federal income taxation; payments mandated under contract or subcontract to provide services, labor or materials for actual or proposed design, construction, remodeling, remediation or repair of improvements on real property or the location of the boundaries of real property. The distribution shall be mandated by a contract or subcontract. | Examples: 1. Number One Realty is a real estate broker. It pays a commission to a real estate agent for selling a house. The commission will be reported on form 1099-Misc. On its Commerce Tax return, Number One Reality can deduct the amount of the commission paid to the real estate agent to the extent it is included in the reported gross revenue. 2. Prime Contractors, Inc. is employed by Rich Development LLC to oversee the construction of an apartment complex in Nevada. Rich Development LLC can deduct the payments to Prime Contractors, Inc. made under the contract for its services to the extent they are included in the reported gross revenue. | |
| Line 16 | Reimbursement of Expenses and Advances from Clients | |
| Deduct reimbursements for advances made by your business on behalf of clients, other than with respect to services rendered or goods purchased in ordinary course of business, including legal service expenses specific to claimant, other than general operating expenses. | Example: Nevada Law Firm, LLP made an advance payment on behalf of a client to a forensic accounting firm for a calculation of damages for a settlement. The amount of the client’s reimbursement is deductible by Nevada Law Firm, LLP to the extent it is included in the reported gross revenue. | |
| Line 17 | Taxes Collected from 3rd Party and Remitted to Taxing Authority | |
| Deduct taxes collected from customers and remitted to a taxing authority. Only taxes imposed on a customer are deductible. Taxes imposed on your business are not deductible. If taxes are not directly remitted by your business to a taxing authority they are also not deductible. | Examples: 1. Per NRS 368A.200, Nevada Tax on Live Entertainment is collected from the purchaser at the time of purchase and remitted to the Department of Taxation. The tax collected is deductible to the extent it is included in the reported gross revenue. 2. The Nevada sales tax charged to your customers is also deductible to the extent it is included in gross revenue. | |
| Line 18 | Other Deductions | |
| Deduct any other amounts not listed as deductions on lines 12 through 25, but allowed by Commerce Tax law, to the extent they are included in revenue. Provide a description in the designated field. | Example: Tax basis of securities and loans sold, if your business sells such securities in the course of its ordinary business. |
# Line 18 Other Deductions
- The Nevada sales tax charged to your customers is also deductible to the extent it is included in gross revenue.
# Line 19 Employee Leasing Deduction
If your business is an employee leasing company, deduct wages, payroll taxes on those wages, employee and worker's compensation benefits received from your clients for the leased employees.
# Line 20 Gaming Deduction
# Line 21 Health Care Provide Deduction
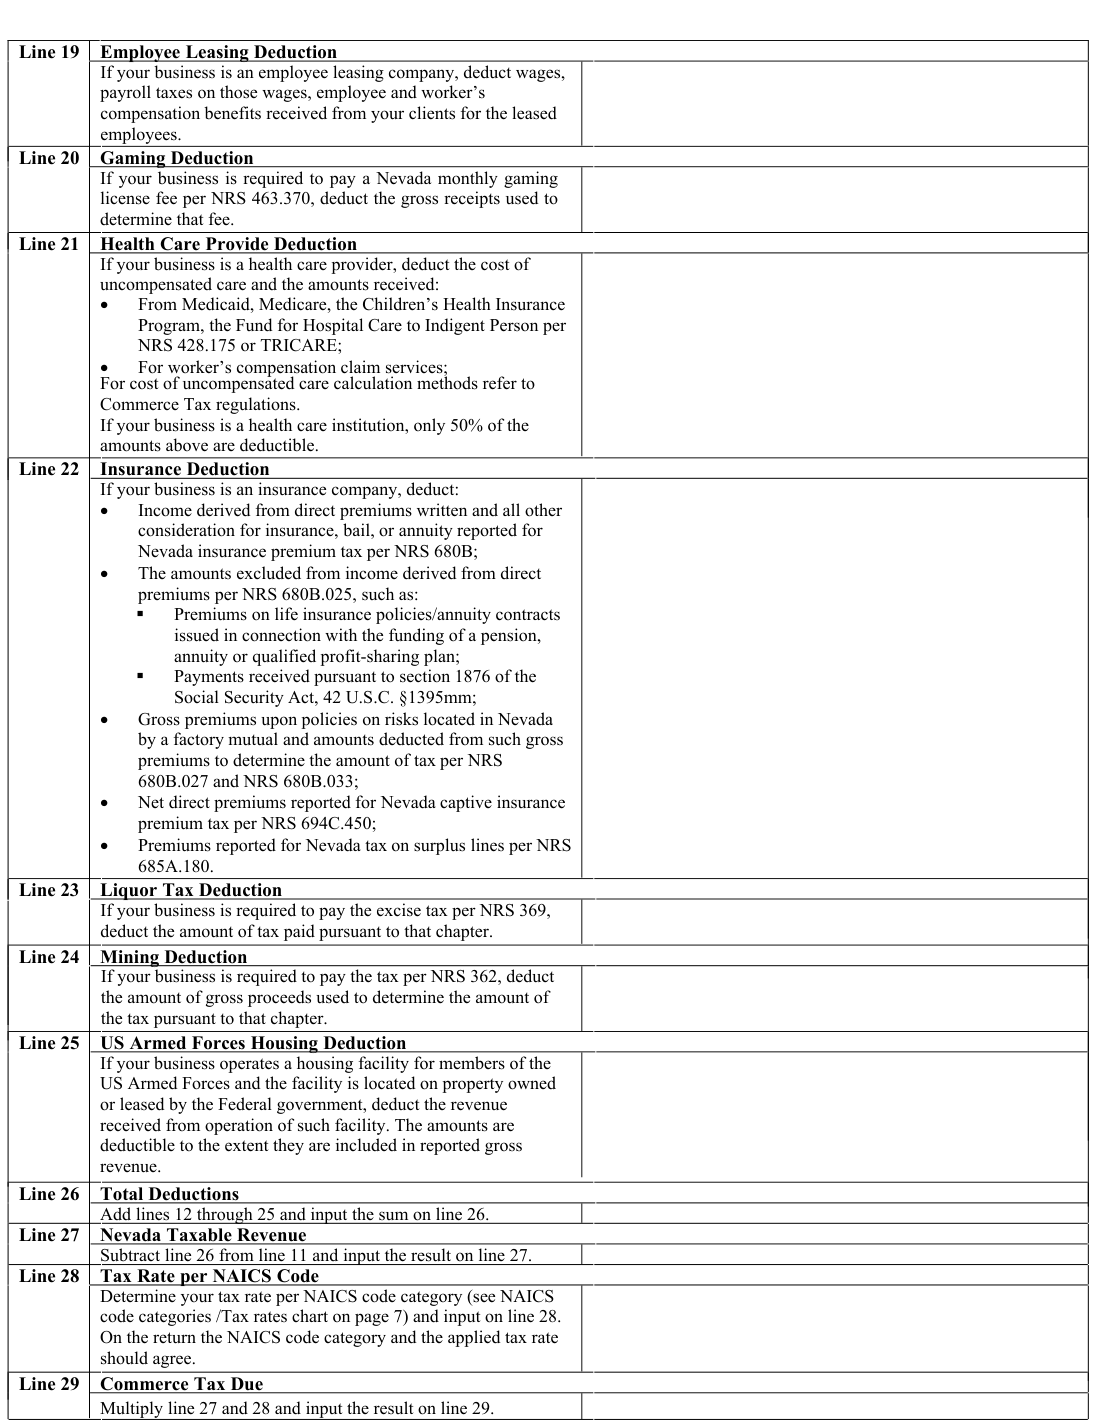
Text version of this table
| Line 19 | Employee Leasing Deduction |
| If your business is an employee leasing company, deduct wages, payroll taxes on those wages, employee and worker’s compensation benefits received from your clients for the leased employees. | |
| Line 20 | Gaming Deduction |
| If your business is required to pay a Nevada monthly gaming license fee per NRS 463.370, deduct the gross receipts used to determine that fee. | |
| Line 21 | Health Care Provide Deduction |
| If your business is a health care provider, deduct the cost of uncompensated care and the amounts received: From Medicaid, Medicare, the Children’s Health Insurance Program, the Fund for Hospital Care to Indigent Person per NRS 428.175 or TRICARE; For worker’s compensation claim services; For cost of uncompensated care calculation methods refer to Commerce Tax regulations. If your business is a health care institution, only 50% of the amounts above are deductible. | |
| Line 22 | Insurance Deduction |
| If your business is an insurance company, deduct: Income derived from direct premiums written and all other consideration for insurance, bail, or annuity reported for Nevada insurance premium tax per NRS 680B; The amounts excluded from income derived from direct premiums per NRS 680B.025, such as: Premiums on life insurance policies/annuity contracts issued in connection with the funding of a pension, annuity or qualified profit-sharing plan; Payments received pursuant to section 1876 of the Social Security Act, 42 U.S.C. §1395mm; Gross premiums upon policies on risks located in Nevada by a factory mutual and amounts deducted from such gross premiums to determine the amount of tax per NRS 680B.027 and NRS 680B.033; Net direct premiums reported for Nevada captive insurance premium tax per NRS 694C.450; Premiums reported for Nevada tax on surplus lines per NRS 685A.180. | |
| Line 23 | Liquor Tax Deduction |
| If your business is required to pay the excise tax per NRS 369, deduct the amount of tax paid pursuant to that chapter. | |
| Line 24 | Mining Deduction |
| If your business is required to pay the tax per NRS 362, deduct the amount of gross proceeds used to determine the amount of the tax pursuant to that chapter. | |
| Line 25 | US Armed Forces Housing Deduction |
| If your business operates a housing facility for members of the US Armed Forces and the facility is located on property owned or leased by the Federal government, deduct the revenue received from operation of such facility. The amounts are deductible to the extent they are included in reported gross revenue. | |
| Line 26 | Total Deductions |
| Add lines 12 through 25 and input the sum on line 26. | |
| Line 27 | Nevada Taxable Revenue |
| Subtract line 26 from line 11 and input the result on line 27. | |
| Line 28 | Tax Rate per NAICS Code |
| Determine your tax rate per NAICS code category (see NAICS code categories /Tax rates chart on page 7) and input on line 28. On the return the NAICS code category and the applied tax rate should agree. | |
| Line 29 | Commerce Tax Due |
| Multiply line 27 and 28 and input the result on line 29. |
# Line 22 Insurance Deduction
# Line 25 US Armed Forces Housing Deduction
# Line 31 Plus interest
# Interest and Penalties Worksheet
Penalty charge: If the Commerce Tax return is not submitted/postmarked and taxes are not paid on or before the due date, the amount of penalty due is based on the number of days the payment is late per NAC 360.395 (see table below). The maximum penalty amount is 10%.
# Number of Days Late Penalty Percentage
1-10 2%
11-15 4%
16-20 6%
21-30 8%
31+ 10%
Multiply by
0.02
0.04
0.06
0.08
0.10
Example: the Commerce Tax was due August 14, 2024, but not paid until August 29, 2024. The number of days late is 15 so the penalty is 4%.
Penalty Calculation:
Using a calendar, determine the number of days the payment is late: Determine the appropriate penalty rate from the table above:
Commerce Tax Due (Line 29): _ multiplied by rate = _. Enter the result on Line 30.
Interest Calculation:
Commerce Tax Due (Line 29): __ multiplied by .075% (.0075) multiplied by the number of months late =
__. Enter the results on Line 31.
# NAICS Code Category
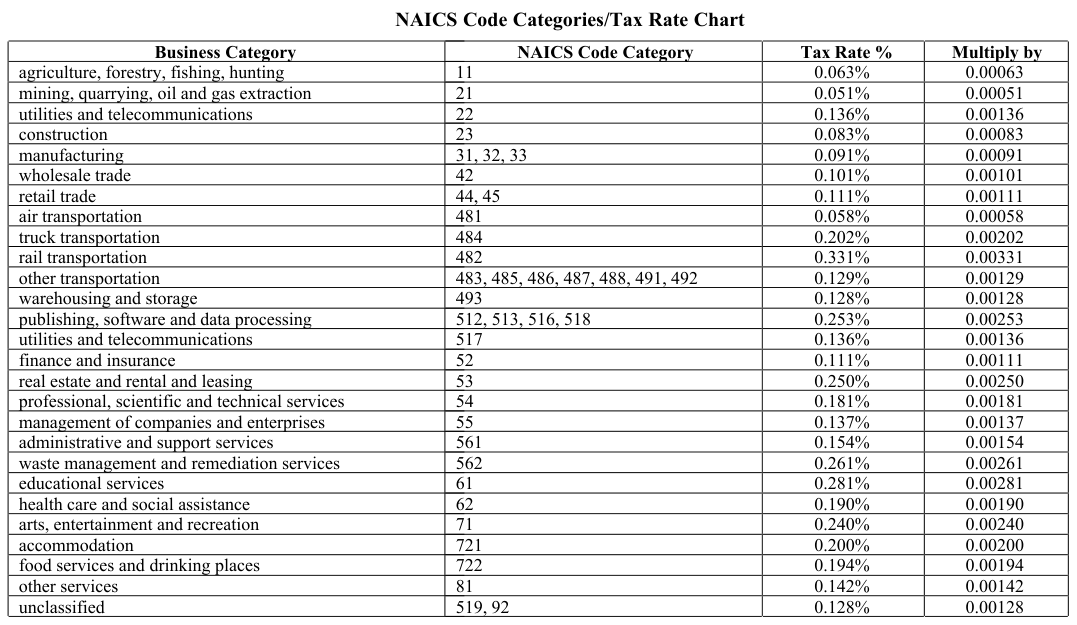
Text version of this table
| Business Category | NAICS Code Category | Tax Rate % | Multiply by |
|---|---|---|---|
| agriculture, forestry, fishing, hunting | 11 | 0.063% | 0.00063 |
| mining, quarrying, oil and gas extraction | 21 | 0.051% | 0.00051 |
| utilities and telecommunications | 22 | 0.136% | 0.00136 |
| construction | 23 | 0.083% | 0.00083 |
| manufacturing | 31, 32, 33 | 0.091% | 0.00091 |
| wholesale trade | 42 | 0.101% | 0.00101 |
| retail trade | 44, 45 | 0.111% | 0.00111 |
| air transportation | 481 | 0.058% | 0.00058 |
| truck transportation | 484 | 0.202% | 0.00202 |
| rail transportation | 482 | 0.331% | 0.00331 |
| other transportation | 483, 485, 486, 487, 488, 491, 492 | 0.129% | 0.00129 |
| warehousing and storage | 493 | 0.128% | 0.00128 |
| publishing, software and data processing | 512, 513, 516, 518 | 0.253% | 0.00253 |
| utilities and telecommunications | 517 | 0.136% | 0.00136 |
| finance and insurance | 52 | 0.111% | 0.00111 |
| real estate and rental and leasing | 53 | 0.250% | 0.00250 |
| professional, scientific and technical services | 54 | 0.181% | 0.00181 |
| management of companies and enterprises | 55 | 0.137% | 0.00137 |
| administrative and support services | 561 | 0.154% | 0.00154 |
| waste management and remediation services | 562 | 0.261% | 0.00261 |
| educational services | 61 | 0.281% | 0.00281 |
| health care and social assistance | 62 | 0.190% | 0.00190 |
| arts, entertainment and recreation | 71 | 0.240% | 0.00240 |
| accommodation | 721 | 0.200% | 0.00200 |
| food services and drinking places | 722 | 0.194% | 0.00194 |
| other services | 81 | 0.142% | 0.00142 |
| unclassified | 519, 92 | 0.128% | 0.00128 |
- the Commerce Tax return.
Enter tax rate in a decimal format ("Multiply by" column in the table above) in the "Tax rate per NAICS Code Category" field on
- the Commerce Tax return.
If the current year NAICS code category is different from the category reported on the prior year's Commerce Tax return, your
- business must obtain permission from the Department. Use the NAICS Code Category Change form to request the category change.
Additional Resources:
The Department's website for the Commerce Tax: https://tax.nv.gov/tax-types/commerce-tax/ Text of Commerce Tax Law (NRS 363C): https://www.leg.state.nv.us/Division/Legal/LawLibrary/NRS/NRS-363C.html Text of Commerce Tax Regulations (NAC 363C): https://www.leg.state.nv.us/Division/Legal/LawLibrary/NAC/NAC-363C.html Commerce Tax video training: https://tax.nv.gov/tax-types/commerce-tax/ Commerce Tax forms and instructions: https://tax.nv.gov/tax-types/commerce-tax/
Contact:
For general questions, such as business registration and filing electronically via Nevada Tax Center, please call the Call Center at
(866) 962-3707.
Hours of operation are Monday through Friday.
Reminder:
If your business pays Commerce Tax, it may be eligible for a Commerce Tax Credit toward Modified Business Tax.
Please refer to https://tax.nv.gov/faqs/commerce-tax-faqs/ for more details.
Source: view the official PDF
Nearby sections (17 sections)
- centrally-assessed-properties-instructions · Nevada Centrally Assessed…
- commerce-tax-return-instructions · Nevada Commerce Tax Return…
- exc-f013-affiliated-group-payroll-provider · Nevada Affiliated Group…
- exc-f021-let-non-gaming · Nevada Live Entertainment Tax (Non-Gaming,…
- exc-f025-commerce-tax-return · Nevada Commerce Tax Return — Form…
- exc-f029-gold-silver-excise · Nevada Gold and Silver Excise Tax Return…
- exc-f040-remote-retail-seller-tax-return · Nevada Remote Retail Seller…
- exc-f067-liquor-excise-tax-return · Nevada Liquor Excise Tax Return —…
- exc-f079-medical-cannabis-tax-return · Nevada Medical Cannabis Tax…
- exemption-certificate-instructions · Nevada Sales/Use Exemption…
- lgs-f018-agricultural-use-assessment · Nevada Agricultural Use…
- lgs-f024-geothermal-operator-instructions · Nevada Geothermal Operator…
- lgs-f025-net-proceeds-operators · Nevada Net Proceeds of Minerals —…
- lgs-f026-net-proceeds-royalty · Nevada Net Proceeds of Minerals —…
- one-time-event-guidelines · Nevada One-Time Event Sales Tax Guidelines
- rev-f009-consumer-use-tax-return · Nevada Consumer Use Tax Return —…
- rev-f013-sales-and-use-tax-return · Nevada Sales and Use Tax Return —…