North Carolina Department of Revenue Form Instructions
NC-30 — Income Tax Withholding Tables & Instructions for Employers
NC - 30
# 2026 Income Tax Withholding
Web
11-25
North Carolina ncdor.gov
Tables and Instructions for Employers
# New for 2026
- As a result of Session Law 2023-134, the individual income tax rate for tax year 2026 will be 3.99%. This change is reflected in the tables and computations included in this publication, and withholding allowance certificate forms published on the Department's website.
# You can file your return and pay your tax online at ncdor.gov/file-pay.
Issued by: North Carolina Department of Revenue, PO Box 25000, Raleigh, NC 27640-0001
Calendar of Employer's Duties
# At The Time a New
Employee is Hired … Obtain a North Carolina Employee's Withholding Allowance Certificate, Form NC-4, Form
NC-4 EZ, or Form NC-4 NRA. On each payment of wages to an employee, withhold North Carolina income tax in accordance with the employee's withholding allowance certificate.
On February 16 … Begin withholding for each employee who previously claimed an exemption from withholding but has not given you a new Form NC-4 EZ, for the current year. In such situations, if the employee does not give you a new, completed Form NC-4 EZ or Form NC-4, withhold North Carolina income tax as if the employee is single with no allowances.
Due Dates for:
Quarterly Filers … See Section 14 for reporting and paying the tax withheld on a quarterly basis.
Monthly Filers … See Section 15 for reporting and paying the tax withheld on a monthly basis.
Semiweekly Filers … See Section 16 for reporting and paying the tax withheld on a semiweekly basis.
NOTE: If any due date falls on a Saturday, Sunday, or legal holiday, use the next business day. Semiweekly filers have at least three business days following the close of the semiweekly period to pay the required North Carolina income tax withheld. If any of the three weekdays after the end of a semiweekly period is a legal holiday, the semiweekly filer will have an additional day for each day that is a legal holiday.
- General Information … 3
- Who Are Employers? … 4
- Withholding Identification Number … 4
- Who Are Employees? … 4
- Treatment of Residents and Nonresidents … 4
- Withholding from Pensions, Annuities, and Deferred Compensation … 5
- Withholding from Nonwage Compensation … 7
- Payee's Taxpayer Identification Number … 9
- Withholding from Wages … 9
- Payments Exempt From Withholding … 9
- Supplemental Wages … 10
- Employee's Withholding Allowance Certificates, Form NC-4, Form NC-4 EZ, or Form NC-4 NRA … 10
# Table of Contents
Section Page Section Page
# You Terminate Your Business,
On or Before the Last Day of the Month Following the End of the Calendar Quarter in
# Which You Closed Your
Business … Electronically file Form NC-3, Annual Withholding Reconciliation, and the State's copies of the forms W-2, W-2G, 1099-MISC, 1099-NEC, 1099-R, NC-1099M, or 1042-S. If you terminate your business, you must file Form NC-3 and all required W-2 and 1099 statements that are available to you by the due date of Form NC-3. You must file the remaining W-2 and 1099 statements when they become available to you, but no later than January 31 of the following year.
On or Before January 31 and At The End of Employment … Give each employee who received wages a Federal Form W-2, Wage and Tax Statement.
Also, give each payee who received nonwage compensation for services performed in North Carolina a Form NC-1099M, Compensation Paid to a Payee. In lieu of Form
NC-1099M, you may give each payee a Federal Form 1099-MISC, Miscellaneous
Information, or Federal Form 1099-NEC, Nonemployee Compensation. Give each recipient of retirement distributions a completed Federal Form 1099-R, Distributions From Pensions, Annuities, Retirement or Profit-Sharing Plans, IRAs, Insurance Contracts, etc. Give each foreign person who receives U.S. source income that is subject to federal income tax withholding a completed Federal Form 1042-S, Foreign Person's U.S. Source Income Subject to Withholding, if the income reported on Form 1042-S is North Carolina source income or if the income was subject to North Carolina income tax withholding.
# Section 1. General Information
North Carolina law requires withholding of income tax from:
# (a) Salaries and Wages
(1) Of all North Carolina residents regardless of where earned, and
(2) Of nonresidents for services performed in North
Carolina.
# (b) Nonwage Compensation
(1) Paid to nonresident contractors for certain personal services performed in North Carolina,
(2) Paid to contractors identified by an Individual
Taxpayer Identification Number (ITIN), including applied for and expired numbers, if the contractor performs services in North Carolina for compensation other than wages,
(3) Paid to individuals or entities who fail to provide a taxpayer identification number (TIN), if the individual performs or the entity provides services in North Carolina, and
(4) Paid to individuals or entities who fail to provide a valid taxpayer identification number (TIN), if the individual performs or the entity provides services in North Carolina and you are notified by the Department that the individual's or entity's TIN is not valid.
# (c) Other Payments
(1) Pension payments paid to North Carolina residents if federal withholding is required on the payments, and
(2) Winnings of $600 or more paid by the North
Carolina State Lottery Commission at the rate of 3.99 percent.
Each employee must complete a North Carolina
# Withholding Allowance Certificate, Form NC-4, Form
NC-4 EZ, or Form NC-4 NRA. To determine the amount of tax to be withheld, select the table in this book which corresponds with the employee's filing status and your payroll period; i.e., weekly, biweekly, etc.; locate the gross wages in the left-hand column and then follow across to the column which corresponds to the number of withholding allowances claimed by the employee. The tax withheld can also be computed by using the Percentage Method or Annualized Wages Method. Important: Always use the single filing status for Nonresident Aliens.
When you determine that you will begin paying wages, nonwage compensation, or pension payments subject to North Carolina income tax withholding, you must file Form NC-BR, Business Registration Application for Income Tax Withholding, Sales and Use Tax, and Other Taxes and Service Charge, with the Department of Revenue to obtain a North Carolina withholding identification number. Form NC-BR can be submitted via the Department's online business registration system, or the completed paper form can be mailed to the N.C. Department of Revenue, Business Registration Unit, PO Box 25000, Raleigh, NC 27640-0100. For additional details, see Section 3 on page 4.
The tax must be withheld from each payment of wages, and the amount is considered to be held in trust until it is paid to the Department. North Carolina does not use a depository system for income tax withheld. A report of the tax withheld must be filed and the tax paid by the required due date. You are required to report and pay the tax withheld on a quarterly, monthly, or semiweekly basis. Your initial filing frequency is determined by your expected average monthly withholding as indicated on Form NC-BR. An employer required to file a certain frequency (quarterly, monthly, or semiweekly) because of it's average monthly withholding, must continue on that basis until the Department of Revenue authorizes a change to a new filing frequency. The employer must continue on the same filing frequency until written authorization to change is received from the Department of Revenue.
At the end of each year, you must prepare W-2 and
1099 statements, furnish copies to the employees and contractors for use in filing their income tax returns and submit the information to the Department of
# Revenue along with Form NC-3, Annual Withholding
Reconciliation.
You can file and pay your withholding tax online. For additional details, see Sections 17 and 18. If you would like to file and pay your withholding tax by mail, you may call the Department and request a coupon booklet with the preaddressed forms which will be mailed to you. If your coupon booklet is misplaced, request a new one from the Department. If a blank form is used, show the name and North Carolina withholding identification number exactly as they appeared on previous reports.
If you go out of business or cease to pay wages permanently, complete Form NC-BN, Out-of-Business
Notification, on the Department's website or include a copy of Form NC-BN with your final report. You can also let us know that you are out of business by calling
1-877-252-3052 (toll-free) and selecting Business
Taxes. Follow the menu instructions under withholding tax to close your withholding account. On or before the last day of the month following the end of the calendar quarter in which you closed your business, electronically file Form NC-3, Annual Withholding Reconciliation, with the State's copies of the W-2 and 1099 statements and provide copies of the W-2 and 1099 statements to all employees and contractors.
The principal duties of employers are outlined in the calendar on page 2, and the requirements concerning withholding, reporting and paying North Carolina income tax are summarized in this booklet. For more information, contact the North Carolina Department of Revenue, Customer Service Division, PO Box
25000, Raleigh, NC 27640-0001 or you may call
1-877-252-3052.
# Section 2. Who are Employers?
An employer is any person or organization for whom an individual performs any service as an employee. The term includes federal, state, and local governmental agencies as well as religious, charitable, educational, and other nonprofit organizations even though they may be exempt for other tax purposes. Note: Compliance with any of the provisions of North Carolina withholding by a nonresident employer will not be deemed to be evidence that the nonresident is doing business in this State.
# Number
Each new employer required to withhold North Carolina income tax must complete and file Form NC-BR with the Department of Revenue. Form NC-BR can be submitted via the Department's online business registration system, or the completed paper form can be mailed to the N.C. Department of Revenue, Business Registration Unit, PO Box 25000, Raleigh, NC 27640-
- Note: This form may also be used to apply for a sales and use tax number.
The Department will assign a withholding identification number which should be recorded in a permanent place and used on all reports and correspondence concerning withholding. Do not use the number of another employer from whom you acquired a business or your federal identification number. You should receive your new State identification number within four weeks of filing Form NC-BR.
Each employer corporation is required to apply for a withholding identification number, and each must maintain separate records. Changing a proprietorship or partnership to a corporation requires a new withholding identification number and reconciliation of the old account. A new identification number generally is not required merely to change a trade name or to show partial changes of ownership in a partnership, such as adding or removing the name of one partner.
Report the details and date of such changes to the
Department of Revenue by letter.
Each employer should have only one withholding identification number. Even though you have several operations, you may file a single report for your total payroll. If, however, you operate distinct businesses and maintain completely separate payrolls, you may register each. If you register each business, you must file separate reports for each business, including separate annual reconciliations at the end of the year.
# Section 4. Who are Employees?
An employee is either a resident individual legally domiciled in this State who performs services within or outside North Carolina for wages, or a nonresident of this State who performs services within the State for wages. For North Carolina withholding purposes, the location of the services performed by the employee is determined by the physical location at which the employee performs the services.
# Nonresidents
(a) Resident employees. An employee who is a resident of this State is subject to North Carolina withholding on all of their wages, whether the employee works within or outside the State; except that, to prevent double withholding and to anticipate any allowable tax credit, North Carolina withholding is not required from wages paid to a resident for services performed in another state if that state requires the employer to withhold. Withholding does not relieve the employee of the obligation to file a North Carolina individual income tax return and pay any balance due after tax credit.
(b) Nonresident employees. A nonresident employee is subject to North Carolina withholding on any part of their wages paid for performing services in this State. Any relief from double withholding must be granted by the employee's state of residence.
See Section 7 for information on withholding from nonresidents who receive nonwage compensation for personal services performed in North Carolina.
# (c) Employers operating in interstate commerce.
The Amtrak Reauthorization and Improvement Act of 1990 provides that no part of the compensation paid to an employee of an interstate railroad subject to the jurisdiction of the Surface Transportation Board (STB) may be subject to income tax, or income tax withholding, in any state except the state of the employee's residence when such employee performs regular assigned duties in more than one state. The Act also precludes the taxation of compensation paid by an interstate motor carrier subject to the jurisdiction of the STB or to an employee of a private motor carrier performing services in two or more states except by the state of the employee's residence. Therefore, the compensation received by such nonresident employees for services performed in this State will not be subject to North Carolina income tax or income tax withholding.
Under the Federal Aviation Act (49 USCS-40116), a nonresident airline employee rendering service on an aircraft would not be liable for North Carolina income tax unless the scheduled flight time in North Carolina is more than 50 percent of the total scheduled flight time during the calendar year. If the employee's flight logs show that more than 50 percent of the scheduled flight time is in North Carolina, the amount of income reportable to this state would be based on the percentage that the North Carolina flight time is to the total flight time for the year.
# Compensation
Definitions. Unless otherwise specified below, the definitions, provisions, and requirements of section 3405 of the Internal Revenue Code with respect to federal withholding on pensions are applicable to State withholding on pensions.
Pension payer - A payor or a plan administrator with respect to a pension payment under section 3405 of the Code.
Pension payment - A periodic payment or a nonperiodic distribution as those terms are defined in section 3405 of the Code.
Withholding Required. A pension payer required to withhold federal tax under section 3405 of the Code on a pension payment to a North Carolina resident must also withhold State income tax from the pension payment. If a payee has provided a North Carolina address to a pension payer, the payee is presumed to be a North Carolina resident and the payer is required to withhold State tax unless the payee elects no withholding. A pension payer that either fails to withhold or to remit tax that is withheld is liable for the tax.
A pension payer must treat a pension payment paid to an individual as if it were an employer's payment of wages to an employee. If the pension payer has more than one arrangement under which distributions may be made to an individual, each arrangement must be treated separately.
Amount to Withhold. In the case of a periodic payment, as defined in Code section 3405(e)(2), the payer must withhold as if the recipient were a single person with no allowances unless the recipient provides an allowance certificate (Form NC-4P) reflecting a different filing status or number of allowances. Form NC-4P, Withholding Allowance Certificate for Pension or Annuity Payments, is used by a recipient of pension payments who is a North Carolina resident to report the correct filing status, number of allowances, and any additional amount the recipient wants withheld from the pension payment. It may also be used to elect not to have State income tax withheld. In lieu of Form NC-4P, payers may use a substitute form if it contains all the provisions included on Form NC-4P.
For a nonperiodic distribution, as defined in Code section 3405(e)(3), other than an eligible rollover distribution, federal law imposes withholding at the rate of 10 percent of the distribution. If the nonperiodic distribution is an eligible rollover distribution, federal law requires 20 percent of the distribution to be withheld.
Federal law imposes a higher rate of withholding on eligible rollover distributions than on other nonperiodic distributions. State law imposes the same rate of withholding on all nonperiodic distributions. For State purposes, a payer must withhold four percent (4%) of any nonperiodic distribution unless one of the two exceptions explained below applies.
Exception 1: If the nonperiodic distribution is not an eligible rollover distribution, the recipient may elect not to have State tax withheld if the recipient is permitted to elect not to have federal income tax withheld from the distribution. The election not to have State tax withheld may be made even if the recipient did not elect to not have federal tax withheld.
Exception 2: If the nonperiodic distribution is an eligible rollover distribution, State tax withheld is not required on a distribution paid in a direct rollover to an eligible retirement plan, including an IRA. Otherwise, the recipient cannot elect not to have State tax withheld from an eligible rollover distribution.
Election Not to Have Income Tax Withheld. If under Code section 3405, a recipient is permitted to elect to not have federal income taxes withheld from a pension payment, the recipient may elect not to have State income tax withheld from the same pension payment.
An election not to have tax withheld from a pension payment remains in effect until revoked by the recipient.
An election not to have tax withheld is void if the recipient does not furnish the recipient's tax identification number to the payer or furnishes an incorrect identification number. In such cases, the payer will withhold on periodic payments as if the recipient is single claiming no allowances and on nonperiodic distributions at the rate of four percent (4%).
A nonresident with a North Carolina address should also use Form NC-4P to elect not to have State income tax withheld. Completing Form NC-4P and electing not to have State income tax withheld does not necessarily mean that the recipient is a resident of North Carolina.
Exceptions to Withholding. State income tax is not required to be withheld from the following pension payments:
(1) A pension payment that is wages.
(2) Any portion of a pension payment that meets both of the following conditions: a. It is not a distribution or payment from an individual retirement plan as defined in section 7701 of the Code. b. The pension payer reasonably believes it is not taxable to the recipient.
(3) A distribution described in section 404(k)(2) of the
Code, relating to dividends on corporate securities.
(4) A pension payment that consists only of securities of the recipient's employer corporation plus cash not in excess of $200 in lieu of securities of the employer corporation.
(5) Distributions of retirement benefits received from North Carolina State and local government retirement systems and federal retirement systems identified as qualifying retirement systems under the terms of the Bailey/Emory/Patton settlement that are paid to retirees who were vested in the retirement systems as of August 12, 1989.
(6) Retirement pay for service in the uniformed services of the United States to a retired member that meets either of the following conditions: a. Served at least 20 years in the uniformed services. b. Medically retired under Title 10 U.S.C. Chapter
- This exclusion does not apply to severance pay received by a person due to separation under 10 U.S.C. Chapter 61.
This exemption includes payments from a Survivor
Benefit Plan to a beneficiary of a retired member eligible to deduct retirement pay pursuant to the above-mentioned requirements. The Survivor Benefit Plan referenced above, is the plan that is established by Subchapter II of Title 10 U.S.C. Chapter 73.
Notification Procedures for Pension Payers. A pension payer is required to provide each recipient with notice of the right not to have State withholding apply and of the right to revoke the election. The notice requirements for North Carolina purposes are the same as the federal notice requirements, which are provided in section 3405(e)(10) of the Code. Section D of Federal Regulation 35.3405-1 contains sample notices that may be modified for State purposes to satisfy the notice and election requirements for periodic payments and nonperiodic distributions.
Instead of notification that tax will be withheld unless the recipient chooses not to have tax withheld, pension payers may notify recipients whose annual payments are less than $12,750 that no State income tax will be withheld unless the recipient chooses to have State withholding apply. Such notice may be provided when making the first payment.
Reporting and Paying the Withheld Tax. A pension payer required to withhold State income tax from a pension payment but not already registered with the Department of Revenue for wage withholding must register by completing Form NC-BR. Form NC-BR can be submitted via the Department's online business registration system, or the completed paper form can be mailed to the N.C. Department of Revenue, Business Registration Unit, PO Box 25000, Raleigh, NC 27640-
- After the payer's application is processed, the payer's North Carolina withholding identification number will be mailed to them. The payer will initially be classified as a quarterly filer. The filing frequency may change after the first year depending on the amount of State income tax withheld.
A payer that withholds tax from pensions and also withholds tax from wages must report the withholding from pensions with the wage withholding unless the payer chooses to report the withholding from pensions separately. For those payers that do not choose to report the two types of withholding separately, the payment of tax withheld from pensions is due at the time the withholding from wages is due and the payer will be subject to penalties and interest on both types of withholding based on that due date. Payers that also withhold from wages but choose to report the withholding from pensions separately must file Form NC-BR to receive a separate North Carolina withholding identification number.
A payer that initially chooses to report withholding from pensions separately may, at any time, begin reporting the two types of withholding together. If combined reporting is preferred, a payer should report the combined withholding under the account number for reporting wages. The payer should complete Form NC-BN, Out-of-Business Notification, for the separate pension withholding account and file it with the Department. The separate withholding account will be closed. A payer that initially reports the two types of withholding at the same time may choose to begin reporting the withholding on pensions separately by notifying the Business Registration Unit. The payer must continue to report the two types of withholding together until the payer receives the separate account identification number from the Department.
In either case, the payer must file separate annual reconciliations beginning with the year in which the choice is changed.
Annual Statements. Payers must report pension income and State income tax withheld on Federal
Form 1099-R, Distributions From Pensions, Annuities,
Retirement or Profit-Sharing Plans, IRAs, Insurance
Contracts, etc. Form 1099-R must be given to the recipient on or before January 31 following the calendar year in which the pension payments were made. The payer must electronically file Form NC-3, Annual Withholding Reconciliation, with the State's copies of Federal Form 1099-R. Form NC-3 reconciles the amounts withheld from each recipient. Payers choosing to report pension withholding with wage withholding must file one annual reconciliation report that includes the two types of withholding. Payers subject to both wage withholding and pension withholding that report the two types of withholding separately must file separate annual reconciliations for each type of withholding. Unless you terminate your business, the annual reconciliation for withholding from pensions is due on or before January 31.
# Compensation
The following definitions are applicable with respect to withholding from nonwage compensation paid to a recipient for services performed in North Carolina:
(a) Compensation. Consideration a payer pays a payee.
# (b) Individual Taxpayer Identification Number
(ITIN). A taxpayer identification number issued by the Internal Revenue Service to an individual who is required to have a U.S. taxpayer identification
(e) Nonresident Contractor. Either of the following:
(1) A nonresident individual who performs in this
State for compensation other than wages any personal services in connection with a performance, an entertainment, an athletic event, a speech, or the creation of a film, radio, or television program.
(2) A nonresident entity that provides for the performance in this State for compensation of any personal services in connection with a performance, an entertainment, an athletic event, a speech, or the creation of a film, radio, or television program.
(f) Nonresident Entity. Any of the following:
(1) A foreign limited liability company, defined using the same definition for the term "foreign
LLC" in G.S. 57D-1-03, that has not obtained a certificate of authority from the Secretary of
State pursuant to Article 7 of Chapter 57D of the General Statutes.
(2) A foreign limited partnership as defined in G.S.
59-102 or a general partnership formed under the laws of any jurisdiction other than this State, unless the partnership maintains a permanent place of business in this State.
(3) A foreign corporation, as defined in G.S. 55-
1-40, that has not obtained a certificate of authority from the Secretary of State pursuant to
Article 15 of Chapter 55 of the General Statutes.
(g) Payee. Any of the following:
(1) A nonresident contractor.
(2) An ITIN contractor.
(3) A person who performs services in this State for compensation that fails to provide the payer a taxpayer identification number.
(4) A person who performs services in this State for compensation that fails to provide the payer a valid taxpayer identification number. The Secretary must notify a payer that a taxpayer identification number is not valid.
(h) Payer. A person who, in the course of a trade or number but who does not have, or is not eligible to obtain, a Social Security number (SSN) from the Social Security Administration. business, pays compensation.
(i) Taxpayer Identification Number (TIN). An
(c) ITIN Contractor. An ITIN holder who performs services in this State for compensation other than wages.
(d) ITIN Holder. A person whose taxpayer identification number is an Individual Taxpayer Identification Number (ITIN), including applied for and expired identification number issued by the Social Security Administration or the Internal Revenue Service, excluding a Taxpayer Identification Number for
# Pending U.S. Adoptions (ATIN) and Preparer
Taxpayer Identification Number (PTIN).
Withholding requirement. If, in the course of your numbers. trade or business, you pay compensation of more than
$1,500 during the calendar year to a payee for services performed in North Carolina, you must deduct and withhold North Carolina income tax at the rate of four percent (4%) from the compensation.
Withholding threshold. Withholding is only required if the payee is paid more than $1,500 during the calendar year.
No tax is required to be withheld if a payment is $1,500 or less and, at the time the payment is made, the payer does not believe that the total compensation to be paid to the payee for services performed in North Carolina during the year will exceed $1,500. If additional compensation paid later in the year causes total compensation for the year to exceed $1,500, the payer is not required to withhold tax from the additional compensation to make up for the compensation from which no tax was withheld. If the payer expects to pay a payee more than $1,500 during the year, the payer should withhold from each payment even if the first payment does not exceed $1,500.
Withholding from nonwage compensation paid to a nonresident contractor. The tax must be withheld from any nonresident individual and from any nonresident entity (C or S corporation, partnership, or limited liability company) receiving personal services income in connection with a performance, an entertainment, an athletic event, a speech, or the creation of a film, radio, or television program. Tax is not required to be withheld from a corporation or limited liability company that has obtained a certificate of authority from the Secretary of State or from a partnership that has a permanent place of business in North Carolina. If a payer does not withhold from payments to an individual because the individual is a resident, the payer must obtain the individual's address and social security number. If a payer does not withhold from payments to a nonresident corporation or a nonresident limited liability company because the entity has obtained a certificate of authority from the Secretary of State, the payer must obtain from the entity its Secretary of State ID Number. If a payer does not withhold from a partnership because the partnership has a permanent place of business in this State, the payer must obtain the partnership's address and taxpayer identification number.
No tax is required to be withheld from an entity that is exempt from North Carolina corporate income tax under G.S. 105-130.11. This includes any organization that is exempt from federal income tax under the Internal Revenue Code. The entity must provide documentation of its tax exemption to the payer, such as a copy of the organization's federal determination letter of tax exemption or a copy of a letter of tax exemption from the Department of Revenue.
Tax is not required to be withheld from personal services income paid to an individual who is an ordained or licensed member of the clergy.
Withholding from nonwage compensation paid to an ITIN contractor. The tax must be withheld from an ITIN contractor whose taxpayer identification number is an ITIN, including applied for and expired numbers.
Therefore, the withholding requirement applies not only to a person whose taxpayer identification number is an ITIN, but also to a person who has applied for an ITIN number and a person whose ITIN number has expired.
However, withholding is not required on compensation paid to an ITIN holder who is temporarily admitted to the United States to perform agricultural labor or services under an H-2A visa and who is not subject to federal income tax withholding under section 1441 of the Code.
Reporting and Paying the Withheld Tax. If you pay compensation to a payee and you do not already have a withholding account identification number, you must complete Form NC-BR.
If you are required to withhold State income tax on wages to employees and nonwage compensation to payees, you may choose to report the withholding from nonwage compensation separately from the withholding from wages. If you choose not to report the two types of withholding separately, the payment of tax withheld from nonwage compensation paid to a payee is due at the same time the withholding from wages is due. You will be subject to penalties and interest on both types of withholding based on the due date of returns and payments for withholding from wages.
If you choose to report the withholding from nonwage compensation paid to payees separately, you must file Form NC-BR to receive a separate North Carolina withholding identification number. Important: You must continue to report the two types of withholding together until you receive a separate North Carolina withholding identification number from the Department. For details on how to complete Form NC-BR, see Withholding Tax Frequently Asked Questions.
If you initially choose to report State income tax withholding from nonwage compensation paid to payees separately, you may, at any time, begin reporting the two types of withholding together. If combined reporting is preferred, you must report the combined withholding under the account number for reporting wages. You must also complete the Form NC-BN, Out-of-Business Notification, for the separate withholding account. The separate withholding account will be closed.
Annual Statements. If you withhold State income tax from a payee, you must give the payee Form
NC-1099M, Compensation Paid to a Payee, showing the amount of compensation paid and the amount of State income tax withheld during the calendar year.
To the extent that a payer is able to file Federal Form
1099-MISC or Federal Form 1099-NEC with the IRS and report the compensation paid to a payee on the federal forms, the payer may file these federal forms with the Department in lieu of Form NC-1099M. Form NC-1099M must be given to the payee by January 31 following the calendar year in which the compensation was paid. If the services are completed before the end of the calendar year, Form NC-1099M must be given to the payee within 30 days after the last payment of compensation to the payee.
You must electronically file Form NC-3, Annual
Withholding Reconciliation, with the State's copies of Form NC-1099M, Federal Form 1099-MISC, or
Federal Form 1099-NEC. Unless you terminate your business, Form NC-3 and the required 1099 statements are due on or before January 31 for the preceding calendar year. Form NC-3 reconciles the amount of State income tax withheld from each payee.
Payers who report withholding for only compensation paid to a payee must file the annual reconciliation report and include all required 1099 statements.
Payers who choose to report State income tax withheld from compensation paid to a payee, along with State income tax withheld from wages paid to an employee, must file one Form NC-3 that includes both types of withholding.
Payers who choose to report State income tax withheld from compensation paid to a payee separately from State income tax withheld from wages paid to an employee, must file a separate Form NC-3 for each type of withholding.
Amounts withheld in error. If you withhold an amount in error and the amount is refunded to the payee before the end of the calendar year and before you give Form NC-1099M, Federal Form 1099-MISC, or Federal Form 1099-NEC to the payee, do not report the refunded amount on the 1099 statements or the annual reconciliation statement. If the amount withheld in error has already been paid to the Department, reduce your next withholding payment accordingly. Amounts are considered withheld in error if they are withheld from a person who is not a payee, if it is withheld from a payment that is not compensation, or if it is in excess of the amount required to be withheld.
Section 8. Payee's Taxpayer
# Identification Number
An individual employee or nonresident contractor is identified by the individual's social security number.
A contractor that is not an individual (corporation, partnership, limited liability company) is identified by its federal employer identification number. Show the payee's social security number, federal employer identification number and the name and address on Forms W-2 and NC-1099M and use it in any correspondence pertaining to a particular employee or contractor. ITIN contractors are identified by their ITINs. An ITIN is issued by the IRS to an individual who is required to have a taxpayer identification number but does not have and is not eligible to obtain a social security number. Show the payee's ITIN number on Form NC-1099M.
If the payee did not provide the payee's federal taxpayer identification number, do not enter anything for the payee's federal taxpayer identification number on Form NC-1099M. If the payee did not provide a valid federal taxpayer identification number, enter the federal taxpayer identification number provided by the payee on Form NC-1099M.
# Section 9. Withholding from Wages
The term wages has the same meaning as in section
3401 of the Internal Revenue Code. North Carolina has no provision requiring backup withholding.
Farm labor. Farmers are required to withhold State income tax from wages paid to agricultural workers if they are required to withhold tax for federal purposes.
For more information on taxable wages, see Publication
15, Circular E, Employer's Tax Guide.
# Withholding
Employers are required to withhold on wages to the same extent required for federal income tax purposes.
A recipient of any payments exempt from withholding is required to pay estimated income tax if the recipient's income meets the minimum gross income filing requirements.
If you and the individual wish to enter into a voluntary agreement to withhold North Carolina income tax, you must report and pay the amount withheld to the Department, and the individual will receive credit on their income tax return provided you follow the rules which apply to withholding. Since the agreement is voluntary, credit cannot be claimed for any amount withheld unless it is properly paid to the Department of Revenue. The individual should complete a withholding allowance certificate, Form NC-4, Form NC-4 EZ, or Form NC-4 NRA, and request that the agreed amount be withheld.
Domestic employees. Employers are not required to withhold State income tax from the wages of domestic employees; however, the employer and employee may enter into a voluntary agreement to withhold from the employee's wages. Employers may wish to contact the Employment Security Commission regarding any employment insurance liability.
Military Spouses. The Servicemembers Civil Relief Act allows the spouse of a servicemember to elect to use the same state of residence as the servicemember for state tax purposes.
The Act prohibits North Carolina from taxing the income earned for services performed in North Carolina by the spouse of a servicemember if (1) the servicemember is present in North Carolina serving in compliance with military orders, (2) the servicemember's spouse is in North Carolina solely to be with the servicemember, and (3) the active duty servicemember maintains legal residence in a state other than North Carolina and the servicemember's spouse elects that same state as their state of legal residence. If all three of the conditions are met, an employer is not required to withhold North Carolina tax from wages paid to such military spouses if the employee has furnished to their employer Form NC-4 EZ with Line 4 checked. To maintain the exemption, the employee must submit a new Form NC-4 EZ each year. The Act does not apply to military spouses who are domiciled in North Carolina. Withholding from wages paid to military spouses domiciled in North Carolina is still required.
Seamen. The Vessel Worker Tax Fairness Act, 46
U.S.C., 11108, prohibits withholding of state income tax from the wages of a seaman on a vessel engaged in foreign, coastwide, inter-coastal, interstate, or noncontiguous trade or an individual employed on a fishing vessel or any fish processing vessel. Vessels engaged in other activity do not come under the restrictions; however, any seaman who is employed in coastwide trade between ports in this State may have tax withheld if the withholding is pursuant to a voluntary agreement between such seaman and his employer.
Indian Reservation Income: Employers are not required to withhold State income tax from wages earned or received by an enrolled member of a federally recognized Indian tribe if such income is derived from activities on a federally recognized Indian reservation while the member resides on the reservation. An employee who meets these criteria should furnish their employer Form NC-4 EZ with Line 5 checked.
To maintain the exemption, the employee must submit a new Form NC-4 EZ each year. Intangible income having a situs on the reservation and retirement income associated with activities on the reservation are considered income derived from activities on the reservation.
# Section 11. Payroll Period
For more information on a payroll period, see
Publication 15, Circular E, Employer's Tax Guide.
# Section 12. Supplemental Wages
If you pay supplemental wages separately (or combine them with regular wages in a single payment and specify the amount of each), the income tax withholding method depends in part on whether you withhold income tax from your employee's regular wages. If you withhold income tax from an employee's regular wages, you can use one of these methods for the supplemental wages:
(a) Withhold a flat 4.09 percent, or
(b) Add the supplemental and regular wages for the most recent payroll period this year. Then figure the income tax as if the total were a single payment. Subtract the tax already withheld from the regular wages. Withhold the remaining tax from the supplemental wages. If you did not withhold income tax from the employee's regular wages, use method (b).
Vacation pay is subject to withholding as if it were a regular wage payment. If vacation pay is paid in addition to the regular wages, treat the vacation pay as supplemental wages. If vacation pay is for a time longer than your usual payroll period, spread it over the pay periods for which you pay it.
For more information on supplemental wages, see
Publication 15, Circular E, Employer's Tax Guide.
Tips treated as supplemental wages. Withhold the income tax on tips from wages or from funds the employee makes available. If an employee receives regular wages and reports tips, figure income tax as if the tips were supplemental wages. If you have not withheld income tax from the regular wages, add the tips to the regular wages and withhold income tax on the total. If you withheld income tax from the regular wages, you can withhold on the tips by method (a) or (b).
Section 13. Employee's Withholding
# Allowance Certificates,
Form NC-4, Form NC-4 EZ, or Form NC-4 NRA
Each new employee must complete and sign a
North Carolina Employee's Withholding Allowance
Certificate, Form NC-4, Form NC-4 EZ, or Form NC-4
NRA. If an employee does not give you a completed
Form NC-4, Form NC-4 EZ, or Form NC-4 NRA, you must withhold tax as if the employee is single with no withholding allowances. A certificate filed by a new employee is effective upon the first payment of wages thereafter and remains in effect until a new one is furnished unless the employee claimed total exemption from withholding during the prior year. Important:
A military spouse who claims exemption from withholding under the Servicemembers Civil
Relief Act must submit a new Form NC-4 EZ each year. The military spouse must attach a copy of their spousal military identification card and a copy of the servicemember's most recent leave and earnings statement. The military spouse must also submit a new NC-4 EZ immediately upon determining that the spouse no longer meets the requirements for the exemption. State and federal definitions of qualifying child, single person, married, head of household and surviving spouse are the same; however, the number of allowances to which an individual is entitled will differ. Federal Withholding Allowance Certificates are not acceptable.
You are not required to determine whether the total amount of allowances claimed is greater than the total amount to which the employee is entitled.
Nonresident Alien Employee's Withholding
Allowance Certificate, Form NC-4 NRA. Because nonresident aliens are generally not allowed an N.C. standard deduction, nonresident alien employees must complete and sign a North Carolina Nonresident Alien Employee's Withholding Allowance Certificate, Form NC-4 NRA. You must withhold tax using the "Single" filing status regardless of the employee's actual marital status.
If an employee does not give you a completed NC-4 NRA, you must withhold as single with no allowances and also withhold the additional tax as directed below.
Form NC-4 NRA requires the nonresident alien employee to enter on Line 2 an additional amount of
State income tax to be withheld for each pay period to account for the inclusion of the N.C. standard deduction in the wage bracket tables, percentage, and annualized methods of computing income tax withheld. The additional tax to withhold per pay period is identified in the following chart and represents the income tax on the N.C. standard deduction for the single filing status ($12,750) divided by the number of payroll periods during the year. For example, an employee paid monthly is required to enter $44 ($12,750 x 4.09% ÷ 12).
Payroll Weekly Biweekly Semimonthly Monthly
Period
Additional $11 $21 $22 $44
# Withholding
The additional withholding results in overwithholding in two instances - (1) employees who earn less than $12,750 per year, and (2) employees who are students or business apprentices and residents of India. To prevent overwithholding in the first instance, an employer should limit the additional withholding to the lesser of the amount reported by the employee on Line 2 or 4.09% of the wages for that period if the amount of wages for that period multiplied by the number of payroll periods during the year is $12,750 or less. The following chart lists the wages per period that qualify for the 4.09% limitation.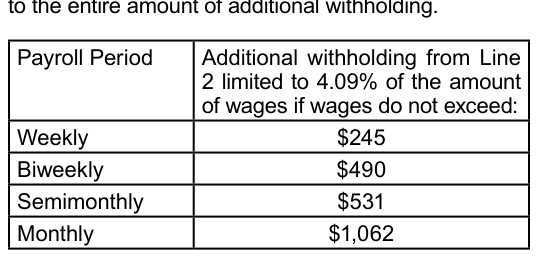
Text version of this table
Payroll Period Additional withholding from Line 2 limited to 4.09% of the amount of wages if wages do not exceed: Weekly $245 Biweekly $490 Semimonthly $531 Monthly $1,062
# Monthly $1,062
Example: Employee is a nonresident alien and is paid on a monthly basis. Employee earns wages of
$500 in February 2026. Employee files a Form NC-4
NRA claiming no allowances on Line 1 and additional withholding of $44 on Line 2. According to the tax tables, no withholding is due. Without the modification, Employer will withhold $44. Using the modification, Employer will withhold $21 ($500 X 4.09%).
To prevent overwithholding in the second instance, an employee who is a student or business apprentice and a resident of India should enter $0 on Line 2 of Form NC-4 NRA.
Wages that are exempt from U. S. income tax under an income tax treaty are generally exempt from withholding.
Residents of Canada and Mexico who enter or leave the United States at frequent intervals are not subject to withholding on their wages if these persons either (1) perform duties in transportation service between the United States and Canada or Mexico, or (2) perform duties connected to the construction, maintenance, or operation of water-way, viaduct, dam, or bridge crossed by, or crossing, the boundary between the United States and Canada or the boundary between the United States and Mexico. Nonresident aliens who are bona fide residents of the U.S. Virgin Islands are not subject to withholding of tax on income earned while temporarily employed in the United States.
Submission of certain withholding allowance certificates. North Carolina requires an employer to submit copies of any certificates (Form NC-4, Form NC-4 EZ, or Form NC-4 NRA) on which the employee claims more than 10 withholding allowances or claims exemption from withholding and the employee's weekly wages would normally exceed an amount equal to the N.C. standard deduction for an individual with a filing status of single divided by 52. For tax year 2026, the weekly wage amount would be $245 (N.C. standard deduction for single individual is $12,750 divided by 52 = $245). Retain the original certificate in your files.
When to submit. An employer filing quarterly withholding reports is required to submit copies of the certificates received during the quarter at the time for filing the quarterly report. An employer filing monthly withholding reports is required to submit copies of the certificates received during the quarter at the time for filing the monthly report for the third month of the calendar quarter. Copies may be submitted earlier and for shorter reporting periods.
Mail the certificate to:
Raleigh, NC 27640-0001
Penalty. If an employee furnishes an Employee's
Withholding Allowance Certificate that contains information that has no reasonable basis and that results in a lesser amount of State income tax being withheld than would have been withheld if the employee furnished reasonable information, the employee is subject to a penalty of fifty percent (50%) of the amount not properly withheld.
If an employee's withholding allowances should decrease, requiring more tax to be withheld, the employee is required to provide an amended certificate within 10 days after the change. If the allowance increases, requiring less tax to be withheld, the employee may provide an amended certificate any time after the change.
Additional withholding allowances may be claimed by employees expecting to have allowable N.C. itemized deductions exceeding the N.C. standard deduction or allowable adjustments to income. One additional allowance may be claimed for each $2,500 that the N.C. itemized deductions are expected to exceed the N.C. standard deduction and for each $2,500 of adjustments reducing income. If an employee will be entitled to a tax credit, he may claim one additional allowance for each $103.
Additional withholding. To increase withholding, an employee may claim fewer allowances or may enter into an agreement with his employer and request that an additional amount be withheld by entering the desired amount on Line 2 of Form NC-4 or Form NC-4 EZ or Line 3 of Form NC-4 NRA.
# Payments
An employer who withholds an average of less than
$250 of North Carolina income tax per month must file a quarterly Withholding Return, Form NC-5, and pay the tax quarterly. The quarterly return and payment are due by the last day of the month following the end of the calendar quarter.
If you temporarily cease to pay wages after you are registered, you should file a return for each quarter even though you have no withholding or wages to report. Do not report more than one calendar quarter on one return.
# Payments
An employer who withholds an average of at least $250 but less than $2,000 of North Carolina income tax per month must file a monthly Withholding Return, Form NC-5, and pay the tax monthly. All monthly returns and payments are due by the 15th day of the month following the month in which the tax was withheld; except the return and payment for the month of December are due by January 31.
# Section 16. Semiweekly Payments
An employer who withholds an average of $2,000 or more of North Carolina income tax per month must pay the tax withheld at the same time it is required to pay the tax withheld on the same wages for federal income tax purposes.
Each time you are required to deposit federal employment taxes (income tax withheld and FICA), you must remit the North Carolina income tax withheld on those same wages. Exception: For federal tax purposes, if an employer withholds $100,000 or more, the federal deposit is required on the next banking day. North Carolina law did not adopt that provision of federal law, and the State income tax withholding is due on or before the normal federal semiweekly due date for those wages. You must submit payment of the North Carolina income tax withheld by the due date.
Payments are submitted with Form NC-5P, Withholding
Payment Voucher.
Form NC-5Q, North Carolina Quarterly Income Tax
Withholding Return, reconciles the tax paid for the quarter with the tax withheld for the quarter. Form NC-5Q must be filed each quarter on or before the last day of the month following the close of the quarter. Due dates for Form NC-5Q are the same as for your federal quarterly return (Federal Form 941). You have 10 additional days to file Form NC-5Q if you made all your required payments during the quarter and no additional tax is due. You can file Form NC-5Q electronically via the Department's eNC5Q Application. For additional details, visit ncdor.gov/enc5q.
# Electronically
You can file your North Carolina withholding return and pay the tax online. The Department of Revenue's E-File system offers the convenience of paying the tax 24 hours a day, 7 days a week. Payments can be made online by bank draft (no convenience fee), or credit or debit card using Mastercard or Visa ($2 convenience fee for every $100 paid). To file your withholding return and pay the tax online, visit ncdor.gov/file-pay.
# (EFT)
If you are interested in submitting ACH credit or ACH debit payments to the Department of Revenue, you should complete the Department's enrollment process.
If you have questions about the ACH credit or ACH debit batch payment methods or need assistance with the enrollment process, you may contact the EFT Helpline at 877-308-9103 (toll-free) for additional information. Local callers may dial 919-814-1501. For more information, you may visit ncdor.gov/file-pay/ electronic-funds-transfer.
# Section 19. Adjustments
You are liable to report and pay the correct amount of tax to the Department even if, through error, you deduct less than the correct amount from a wage payment. If you discover such an error, report and pay the correct amount of tax to the Department and recover the amount due to you from the employee by deducting it from later payments to the employee or adjusting in any other way agreeable to both of you.
If you deduct more than the correct amount of tax from any wage payment, you must report and pay to the Department the actual amount withheld unless you repay the over-deducted amount to the employee or otherwise make applicable administrative adjustments and maintain records to show that you have done so.
If you fail to remit all collected taxes when due, the
Department can propose an assessment ten years after the due date of the return or ten years after the return was filed, whichever is later.
Reporting guidance if you discover an error while preparing your Form NC-3 or after filing your Form NC-3. If you discover an underpayment while preparing your Form NC-3, Annual Withholding Reconciliation, report the underpayment on your Form NC-3 and make the payment of additional tax and interest due.
If you discover an underpayment after filing your Form
NC-3, file Form NC-3X, Amended Annual Withholding
Reconciliation, to report the corrected amount of tax due and make the payment of additional tax, interest, and penalties due. If you have overpaid withholding tax, you may use Form NC-3 or Form NC-3X to claim a refund of the overpayment. Important: No refund is allowed if you withheld the overpaid amount from the wages or compensation of your employees or contractors.
Reporting guidance if you are a monthly or quarterly filer, and you discover an error before preparing your Form NC-3. If you have reported an incorrect amount of tax, and you are a monthly or quarterly filer, you should file Form NC-5X, Amended Withholding Return. If additional tax is due, you must pay the total amount of tax and interest due with your amended return. If you have overpaid withholding tax, you may use Form NC-5X to claim a refund of the overpayment.
Reporting guidance if you are a semiweekly filer, and you discover an error before preparing your
Form NC-3. If you are a semiweekly filer and you discover an underpayment before filing your Form
NC-5Q, Quarterly Income Tax Withholding Return, use Form NC-5PX, Amended Withholding Payment
Voucher, and make the payment for additional tax and interest due. If you discover an underpayment while preparing your Form NC-5Q, report the underpayment on your Form NC-5Q and use Form NC-5PX to make the payment of additional tax and interest due. If you discover an underpayment after filing your Form NC-5Q, file Form NC-5Q to report the corrected amount of tax due, mark the form "Amended", and use Form NC-5PX to make the payment of additional tax and interest due.
If you have overpaid withholding tax, you may use Form
NC-5Q to claim a refund of the overpayment.
# Section 20. Federal Corrections
If a federal determination changes or corrects the amount of tax you are required to withhold and pay to the IRS and the change or correction affects the amount of North Carolina income tax withholding, you must file the applicable North Carolina forms with the Department within six months of being notified about each change or correction.
If you voluntarily file an amended return or corrected statements with the IRS and the adjustments increase the amount of the North Carolina income tax withholding, you must file the applicable North Carolina forms with the Department within six months of filing the amended return or statements with the IRS. If the adjustment results in a decrease in the North Carolina income tax withholding, generally, the claim for refund of overpayment of taxes must be filed with the Department on or before three years after the due date of the return or two years after payment of the tax, whichever is later.
Important: No refund is allowed if you withheld the overpaid amount from the wages or compensation of your employees or contractors.
To report these federal corrections to the Department, you must file the applicable North Carolina Form
NC-5X, Amended Withholding Return, Form NC-5Q,
Quarterly Income Tax Withholding Return, or Form
NC-3X, Amended Annual Withholding Reconciliation.
For additional details about Form NC-5X and Form NC-
5Q, see Section 19. For additional details about Form
NC-3X, see Section 23.
# Section 21. Payment of Tax
North Carolina does not use a depository system for income tax withheld. The amount you withhold is deemed by law to be held in trust by you for the State of North Carolina.
Penalties and Interest. The penalty for failure to timely file a withholding return is 5% of the tax due per month (maximum 25%). A penalty of 5% of the tax due is required for failure to withhold or pay the tax when due.
Additional criminal penalties are provided for willful failure or refusal to withhold, file a return, or pay tax when due. Interest is due from the time the tax was due until paid.
Relief for semiweekly filers. If a payment falls under the shortfall provisions of Federal Regulation 31.6302-1, you are not subject to interest or penalty on the additional tax due.
Personal liability. An employer who fails to withhold or pay the amount required to be withheld is personally and individually liable for such amounts, and the Department is required to assess the tax and penalty against the employer. If an employer has failed to collect or pay over income tax withheld or required to have been withheld, the tax not deducted or paid may be assessed against the responsible corporate officers or other such responsible officer whenever such taxes cannot be immediately collected from the employer. The liability includes the tax not deducted or paid previously assessed against the employer. More than one person may be liable as a person responsible for the payment of withholding taxes; however, the amount of the income tax withheld or required to have been withheld will be collected only once, whether from the employer or one or more responsible officers. The term "responsible officers" includes the president and the treasurer of a corporation, the manager of a limited liability company, and any officer of a corporation or member of a limited liability company who has a duty to deduct, account for, or pay over income tax withheld. It is not necessary that the failure to collect and pay the withholding amounts was willful; it is only necessary that the responsible officer failed to pay the tax withheld or required to have been withheld to the Secretary of Revenue.
Jeopardy reporting and payment. Whenever the Department deems the collection of tax to be in jeopardy, an employer may be required to report and pay the tax withheld at any time after payment of the wages.
# Section 22. Wage and Tax Statements
At the end of each calendar year, prepare a wage and tax statement for each employee. Report the total wages, tips and other compensation you paid to the employee during the calendar year to the same extent reported for federal tax purposes.
Residents and Nonresidents. For residents of
North Carolina, report all wages regardless of where earned and report the North Carolina tax withheld. For nonresidents, report the wages earned in this State and the North Carolina tax withheld. If you show the total wages for the year and the total state tax withheld, provide a breakdown showing the wages paid and tax withheld for each state.
By January 31, give each employee a copy of the wage and tax statement for the preceding calendar year. If an employee ceases employment, provide the completed copy of the wage and tax statement to the employee within 30 days of the final wage payment.
If it is necessary to change a wage and tax statement after it has been given to the employee, issue a corrected statement clearly marked "Corrected by Employer". If a statement is lost, give the employee a substitute marked "Reissued by Employer".
Criminal and civil penalties are provided for willful failure to furnish the required statements or for willfully furnishing a false or fraudulent statement.
# Reconciliation
Unless you terminate your business, Form NC-3,
Annual Withholding Reconciliation, and the State's copy of each Form W-2, Form W-2G, Form NC-1099M,
Federal Form 1099-MISC, Federal Form 1099-NEC,
Federal Form 1099-R, and Federal Form 1042-S must be filed with the Department on or before January 31 for the preceding calendar year. During the calendar year, if you terminate your business, Form NC-3 and the required W-2 and 1099 statements must be filed on or before the last day of the month following the end of the calendar quarter in which you closed your business.
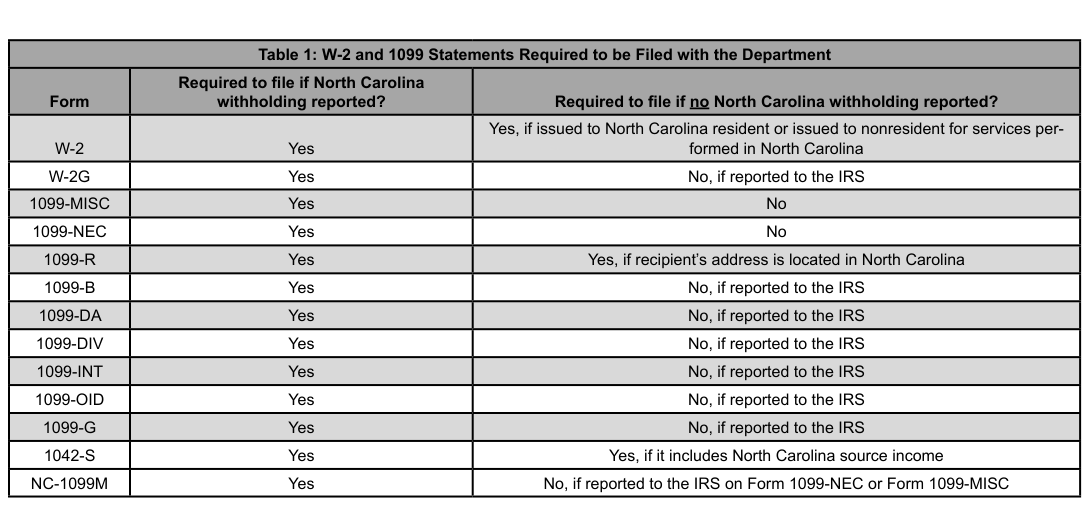
Form NC-3 and the required W-2 and 1099 statements must be filed electronically. See Table 1 on page 15, for a list of W-2 and 1099 statements that are required to be filed with the Department.
Text version of this table
| Table 1: W-2 and 1099 Statements Required to be Filed with the Department | ||
| Form | Required to file if North Carolina withholding reported? | Required to file if no North Carolina withholding reported? |
| W-2 | Yes | Yes, if issued to North Carolina resident or issued to nonresident for services per- formed in North Carolina |
| W-2G | Yes | No, if reported to the IRS |
| 1099-MISC | Yes | No |
| 1099-NEC | Yes | No |
| 1099-R | Yes | Yes, if recipient’s address is located in North Carolina |
| 1099-B | Yes | No, if reported to the IRS |
| 1099-DA | Yes | No, if reported to the IRS |
| 1099-DIV | Yes | No, if reported to the IRS |
| 1099-INT | Yes | No, if reported to the IRS |
| 1099-OID | Yes | No, if reported to the IRS |
| 1099-G | Yes | No, if reported to the IRS |
| 1042-S | Yes | Yes, if it includes North Carolina source income |
| NC-1099M | Yes | No, if reported to the IRS on Form 1099-NEC or Form 1099-MISC |
# 1042-S Yes formed in North Carolina
No, if reported to the IRS
No
No
Yes, if recipient's address is located in North Carolina
No, if reported to the IRS
No, if reported to the IRS
No, if reported to the IRS
No, if reported to the IRS
No, if reported to the IRS
No, if reported to the IRS
Yes, if it includes North Carolina source income
No, if reported to the IRS on Form 1099-NEC or Form 1099-MISC
# NC-1099M Yes
You may amend a previously filed Form NC-3, by filing Form NC-3X, Amended Annual Withholding
Reconciliation. Form NC-3X and corrected W-2 and
1099 statements may be filed electronically. Generally,
Form NC-3X and the corrected statements must be filed with the Department as soon as you discover an error on Form NC-3 or any statement attached to Form NC-3. If your federal employment tax liability was impacted by a federal determination or correction or a voluntarily filed amended federal employment tax return or statement, see Section 20 for your State filing requirements related to your federal corrections.
Important: No refund is allowed if you withheld the overpaid amount from the wages or compensation of your employees or contractors.
For more information on filing Form NC-3, Form NC-3X, and the required W-2 and 1099 statements, visit ncdor. gov/taxes-forms/withholding-tax/enc3.
# Penalties
If you fail to file Form NC-3 by the due date of the return, you will be subject to a failure to timely file an informational return penalty of $50 per day, up to a maximum of $1,000.
If you fail to file Form NC-3 in the format prescribed by the
Secretary, you will be subject to a penalty of $200. The format prescribed by the Secretary requires one Form NC-3, along with the required W-2 and 1099 statements, to be filed in an electronic format using the Department's eNC3 Application. A taxpayer may request a waiver of an informational return penalty by submitting Form NC-5501, available from the Department's website.
For more information on informational return penalties, visit ncdor.gov/taxes-forms/withholding-tax/enc3.
# Section 25. Reporting 1099 Information
A payer must provide a payee a statement showing the total compensation paid and the amount withheld during the calendar year. The payer must give Form NC-1099M, Compensation Paid to a Payee, to the payee on or before January 31 following the calendar year in which the compensation was paid, or if the services are completed before the end of the calendar year, within 30 days after the last payment of compensation to the payee. Federal Form 1099-MISC or Federal Form 1099-NEC can be provided in lieu of Form NC-1099M as long as it shows the North Carolina income tax withheld. Also give each recipient of pension payments a copy of Federal Form 1099-R by January 31.
Form NC-1099NRS, Report of Sale of Real Property by Nonresidents, is required to be filed by any person buying real property located in North Carolina from a nonresident. The form must be filed within 15 days of the closing date of the sale.
Payment Settlement Entities. North Carolina law requires a "payment settlement entity" to submit a duplicate of all information filed with the Internal Revenue Service pursuant to 6050W of the Internal Revenue Code (i.e. the Form 1099-K, "Payment Card and Third Party Network Transactions" information return) with the Department. A payment settlement entity has the same meaning as in section 6050W of the Internal Revenue Code. The statute also requires the entity to submit the 1099-K information return to the Secretary in an electronic format. This information return must be filed with the Department on or before March 31 for the preceding calendar year. Any 1099 information return not timely filed with the Secretary or in the format prescribed by the Secretary is subject to the informational return penalties listed in Section 24.
For more information on filing your 1099-K information return, see ncdor.gov/file-pay/information-reporting.
# Section 26. Records to be Kept
You should retain the names, addresses, and social security numbers or ITIN numbers of employees or payees receiving payments; their withholding allowance certificates; the amounts and dates of wages and other payments and records of the amounts withheld; copies or records of all reports or returns filed; and records of all payments made to the Department. Retain these records for at least ten years after the last filing of all required reports for a calendar year or the last payment of any amount due for the calendar year, whichever is later.
# Withholding
There are three primary methods for computing the amount to withhold from wages. The formula tables for the Percentage Method and the Annualized Wages Method are on pages 17 through 20. The wage bracket tables are on pages 21 through 56. These methods are suitable for computer processing. In addition, an employer may use any other method or formula to determine the amount of tax required to be withheld if the amount determined is substantially the same as that obtained by using the wage bracket tables.
There is a difference in the tax calculated using the percentage method and the tax determined from the withholding tables. The tax tables calculate withholding tax based on an income range. The applicable N.C. standard deduction allowance is factored into the tables.
The percentage method calculates withholding tax based on a specific dollar amount. Taxable income is derived by reducing gross wages by the appropriate deductions. For this reason, tax amounts derived from one method will differ slightly from those derived from the other.
# Percentage Method - Formula Tables for Percentage Method Withholding Computations
(The withholding calculations are based on the individual income tax rate of 3.99% plus 0.1%. This results in a withholding tax rate of 4.09%. Round off the final amount to the nearest whole dollar.)
# Single Person, Married Person, or Surviving Spouse
- Enter weekly wages __
- Weekly portion of N.C. standard deduction __
- Multiply the number of allowances by $48.08 __
- Add Line 2 and Line 3 __
- Net weekly wages. Subtract Line 4 from Line 1 __
- Tax to be withheld. Multiply Line 5 by .0409 (Round to the nearest whole dollar) __
$245.19
# Head of Household
- Enter weekly wages __
- Weekly portion of N.C. standard deduction __
- Multiply the number of allowances by $48.08 __
- Add Line 2 and Line 3 __
- Net weekly wages. Subtract Line 4 from Line 1 __
- Tax to be withheld. Multiply Line 5 by .0409 (Round to the nearest whole dollar) __
$367.79
# Single Person, Married Person, or Surviving Spouse
- Enter biweekly wages __
- Biweekly portion of N.C. standard deduction __
- Multiply the number of allowances by $96.15 __
- Add Line 2 and Line 3 __
- Net biweekly wages. Subtract Line 4 from Line 1 __
- Tax to be withheld. Multiply Line 5 by .0409 (Round to the nearest whole dollar) __
$490.38
# Head of Household
- Enter biweekly wages __
- Biweekly portion of N.C. standard deduction __
- Multiply the number of allowances by $96.15 __
- Add Line 2 and Line 3 __
- Net biweekly wages. Subtract Line 4 from Line 1 __
- Tax to be withheld. Multiply Line 5 by .0409 (Round to the nearest whole dollar) __
$735.58
# Percentage Method - Formula Tables for Percentage Method Withholding Computations
(The withholding calculations are based on the individual income tax rate of 3.99% plus 0.1%. This results in a withholding tax rate of 4.09%. Round off the final amount to the nearest whole dollar.)
# Single Person, Married Person, or Surviving Spouse
- Enter semimonthly wages __
- Semimonthly portion of N.C. standard deduction __
- Multiply the number of allowances by $104.17 __
- Add Lines 2 and 3 __
- Net semimonthly wages. Subtract Line 4 from Line 1 __
- Tax to be withheld. Multiply Line 5 by .0409 (Round to the nearest whole dollar) __
$531.25
# Head of Household
- Enter semimonthly wages __
- Semimonthly portion of N.C. standard deduction __
- Multiply the number of allowances by $104.17 __
- Add Line 2 and Line 3 __
- Net semimonthly wages. Subtract Line 4 from Line 1 __
- Tax to be withheld. Multiply Line 5 by .0409 (Round to the nearest whole dollar) __
$796.88
# Single Person, Married Person, or Surviving Spouse
- Enter monthly wages __
- Monthly portion of N.C. standard deduction __
- Multiply the number of allowances by $208.33 __
- Add Line 2 and Line 3 __
- Net monthly wages. Subtract Line 4 from Line 1 __
- Tax to be withheld. Multiply Line 5 by .0409 (Round to the nearest whole dollar) __
$1,062.50
# Head of Household
- Enter monthly wages __
- Monthly portion of N.C. standard deduction __
- Multiply the number of allowances by $208.33 __
- Add Line 2 and Line 3 __
- Net monthly wages. Subtract Line 4 from Line 1 __
- Tax to be withheld. Multiply Line 5 by .0409 (Round to the nearest whole dollar) __
$1,593.75
Example:
An unmarried employee is paid $450.00 weekly. This employee has in effect a Form NC-4 or Form NC-4 EZ claiming single with two withholding allowances. Using the percentage method, figure the income tax to withhold as follows:
- Enter weekly wages
- Weekly portion of N.C. standard deduction
- Multiply the number of allowances by $48.08
- Add Line 2 and Line 3
- Net weekly wages. Subtract Line 4 from Line 1
$450.00
$245.19
$96.16
$341.35
$108.65
$4.00
Tax to be withheld each payroll period. Multiply Line 5 by .0409 (Round to the nearest whole dollar)__ 6.
# Annualized Method - Formula Tables for Annualized Method Withholding Computations
(The withholding calculations are based on the individual income tax rate of 3.99% plus 0.1%. This results in a withholding tax rate of 4.09%. Round off the final amount to the nearest whole dollar.)
# Single Person, Married Person, or Surviving Spouse
- Enter wages for current payroll period
- Enter number of payroll periods
- Annualized wages. Multiply Line 1 by Line 2
- N.C. standard deduction
- Multiply the number of allowances by $2,500.00
- Add Line 4 and Line 5
- Net annualized wages. Subtract Line 6 from Line 3
- Annualized tax. Multiply Line 7 by .0409
- Enter the number of payroll periods from Line 2
$12,750.00
- Tax to be withheld each payroll period. Divide Line 8 by Line 9 (Round to the nearest whole dollar) __
# Head of Household
- Enter wages for current payroll period
- Enter number of payroll periods
- Annualized wages. Multiply Line 1 by Line 2
- N.C. standard deduction
- Multiply the number of allowances by $2,500.00
- Add Line 4 and Line 5
- Net annualized wages. Subtract Line 6 from Line 3
- Annualized tax. Multiply Line 7 by .0409
- Enter the number of payroll periods from Line 2
$19,125.00
- Tax to be withheld each payroll period. Divide Line 8 by Line 9 (Round to the nearest whole dollar) __
Example:
An unmarried employee is paid $450.00 weekly. This employee has in effect a Form NC-4 or Form NC-4 EZ claiming single with two withholding allowances. Using the annualized wages method, figure the income tax to withhold as follows:
- Enter wages for current payroll period
- Enter number of payroll periods
- Annualized wages. Multiply Line 1 by Line 2
- N.C. standard deduction
- Multiply the number of allowances by $2,500.00
- Add Line 4 and Line 5
- Net annualized wages. Subtract Line 6 from Line 3
- Annualized tax. Multiply Line 7 by .0409
- Enter the number of payroll periods from Line 2 $450.00
$23,400.00
$12,750.00
$5,000.00
$17,750.00
$5,650.00
$231.09
$4.00
- Tax to be withheld each payroll period. Divide Line 8 by Line 9 (Round to the nearest whole dollar) __
# Section 28. Wage Bracket Tables
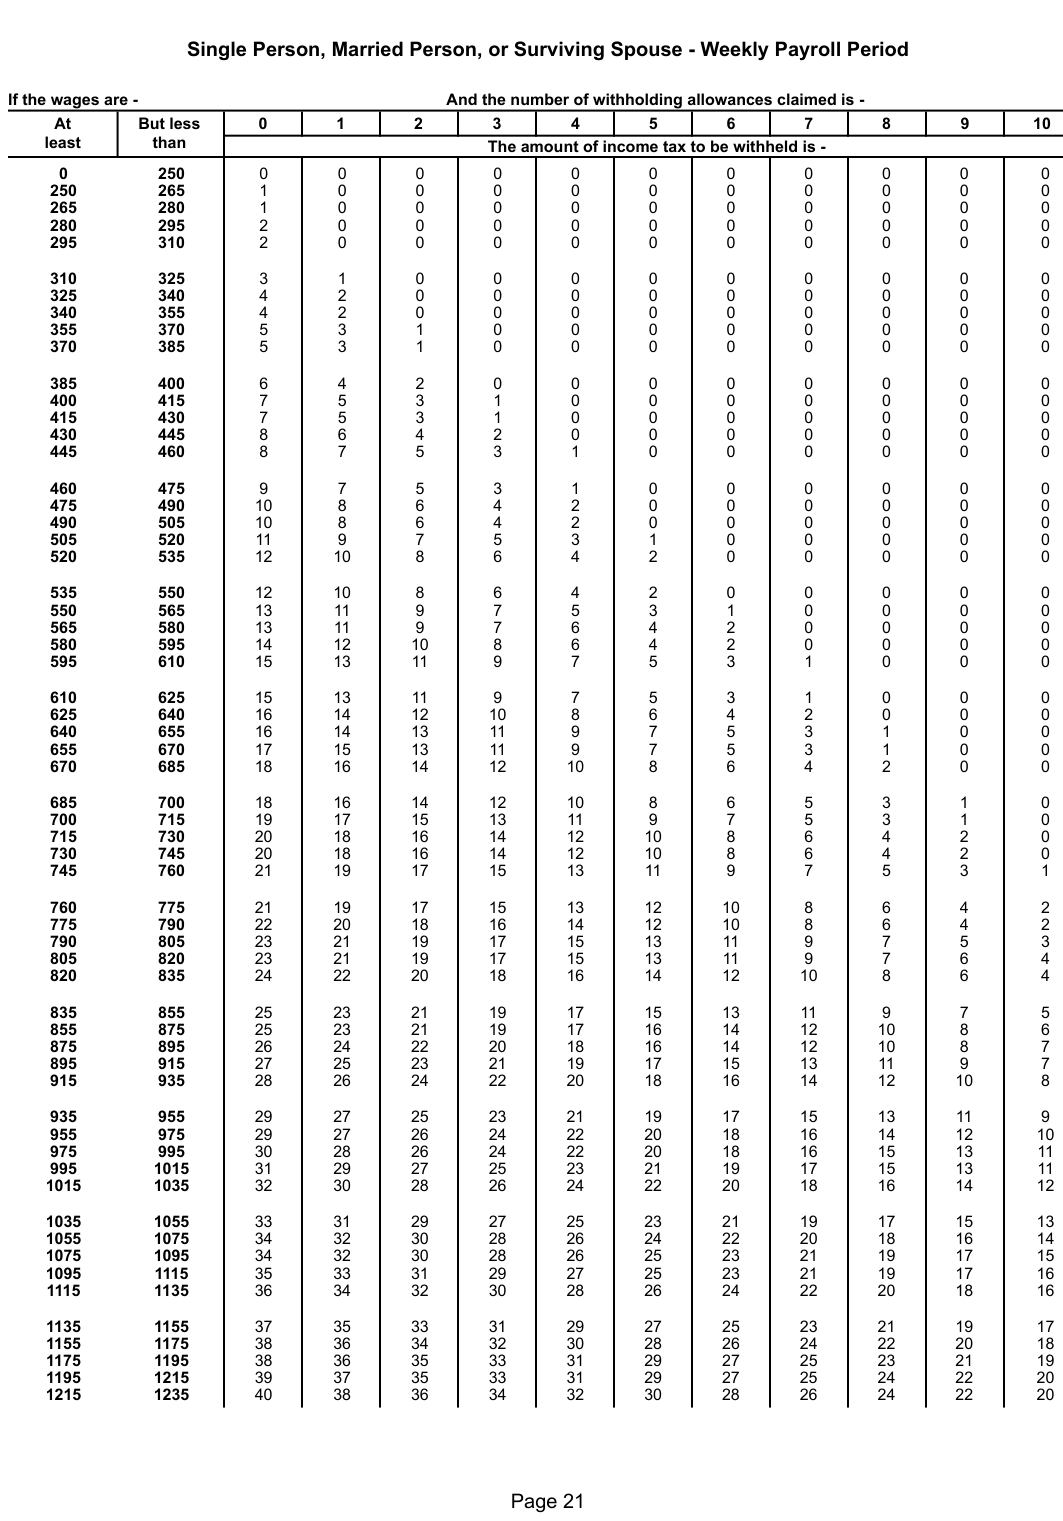
The wage bracket tables begin on the next page. Using this method of withholding, select the table which corresponds with the employee's filing status (Married, Single, Head of Household, Surviving Spouse) as shown on Form NC-4 or Form NC-4 EZ and your payroll period (Weekly, Biweekly, Semimonthly, Monthly). Locate the gross wages in the left-hand column and follow across to the column which corresponds to the number of withholding allowances claimed by the employee.
The wage bracket tables are for up to 10 allowances. If an employee claims more than 10 allowances on Form NC-4 or Form NC-4 EZ:
(a) Multiply the number of withholding allowances over
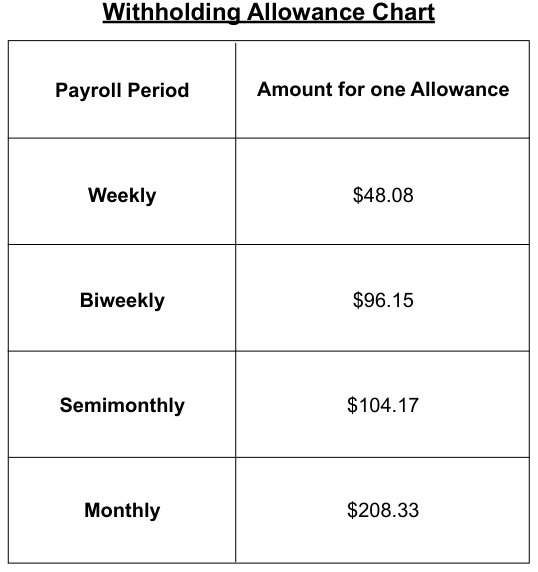
10 by the allowance value for the payroll period. Use the amounts for one allowance in the Withholding Allowance Chart.
(b) Subtract the result from the employee's wages.
(c) On this amount, find and withhold the tax in the column for 10 allowances.
# Payroll Period
Text version of this table
| Payroll Period | Amount for one Allowance |
|---|---|
| Weekly | $48.08 |
| Biweekly | $96.15 |
| Semimonthly | $104.17 |
| Monthly | $208.33 |
# Single Person, Married Person, or Surviving Spouse - Weekly Payroll Period
Text version of this table
| Single | Person, | Married | Person, | or Survi | ving Spo | use | - Weekly | Payroll Per | iod | |||
| wages are - | And t | he numbe | r of withho | lding | allowances | claimed is - | ||||||
| At B | ut less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
| least | than | The amou | nt of incom | e tax | to be withh | eld is - | ||||||
| 0 | 250 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 250 | 265 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 265 | 280 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 280 | 295 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 295 | 310 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 310 | 325 | 3 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 325 | 340 | 4 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 340 | 355 | 4 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 355 | 370 | 5 | 3 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 370 | 385 | 5 | 3 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 385 | 400 | 6 | 4 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 400 | 415 | 7 | 5 | 3 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 415 | 430 | 7 | 5 | 3 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 430 | 445 | 8 | 6 | 4 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 445 | 460 | 8 | 7 | 5 | 3 | 1 | 0 | 0 | 0 | 0 | 0 | 0 |
| 460 | 475 | 9 | 7 | 5 | 3 | 1 | 0 | 0 | 0 | 0 | 0 | 0 |
| 475 | 490 | 10 | 8 | 6 | 4 | 2 | 0 | 0 | 0 | 0 | 0 | 0 |
| 490 | 505 | 10 | 8 | 6 | 4 | 2 | 0 | 0 | 0 | 0 | 0 | 0 |
| 505 | 520 | 11 | 9 | 7 | 5 | 3 | 1 | 0 | 0 | 0 | 0 | 0 |
| 520 | 535 | 12 | 10 | 8 | 6 | 4 | 2 | 0 | 0 | 0 | 0 | 0 |
| 535 | 550 | 12 | 10 | 8 | 6 | 4 | 2 | 0 | 0 | 0 | 0 | 0 |
| 550 | 565 | 13 | 11 | 9 | 7 | 5 | 3 | 1 | 0 | 0 | 0 | 0 |
| 565 | 580 | 13 | 11 | 9 | 7 | 6 | 4 | 2 | 0 | 0 | 0 | 0 |
| 580 | 595 | 14 | 12 | 10 | 8 | 6 | 4 | 2 | 0 | 0 | 0 | 0 |
| 595 | 610 | 15 | 13 | 11 | 9 | 7 | 5 | 3 | 1 | 0 | 0 | 0 |
| 610 | 625 | 15 | 13 | 11 | 9 | 7 | 5 | 3 | 1 | 0 | 0 | 0 |
| 625 | 640 | 16 | 14 | 12 | 10 | 8 | 6 | 4 | 2 | 0 | 0 | 0 |
| 640 | 655 | 16 | 14 | 13 | 11 | 9 | 7 | 5 | 3 | 1 | 0 | 0 |
| 655 | 670 | 17 | 15 | 13 | 11 | 9 | 7 | 5 | 3 | 1 | 0 | 0 |
| 670 | 685 | 18 | 16 | 14 | 12 | 10 | 8 | 6 | 4 | 2 | 0 | 0 |
| 685 | 700 | 18 | 16 | 14 | 12 | 10 | 8 | 6 | 5 | 3 | 1 | 0 |
| 700 | 715 | 19 | 17 | 15 | 13 | 11 | 9 | 7 | 5 | 3 | 1 | 0 |
| 715 | 730 | 20 | 18 | 16 | 14 | 12 | 10 | 8 | 6 | 4 | 2 | 0 |
| 730 | 745 | 20 | 18 | 16 | 14 | 12 | 10 | 8 | 6 | 4 | 2 | 0 |
| 745 | 760 | 21 | 19 | 17 | 15 | 13 | 11 | 9 | 7 | 5 | 3 | 1 |
| 760 | 775 | 21 | 19 | 17 | 15 | 13 | 12 | 10 | 8 | 6 | 4 | 2 |
| 775 | 790 | 22 | 20 | 18 | 16 | 14 | 12 | 10 | 8 | 6 | 4 | 2 |
| 790 | 805 | 23 | 21 | 19 | 17 | 15 | 13 | 11 | 9 | 7 | 5 | 3 |
| 805 | 820 | 23 | 21 | 19 | 17 | 15 | 13 | 11 | 9 | 7 | 6 | 4 |
| 820 | 835 | 24 | 22 | 20 | 18 | 16 | 14 | 12 | 10 | 8 | 6 | 4 |
| 835 | 855 | 25 | 23 | 21 | 19 | 17 | 15 | 13 | 11 | 9 | 7 | 5 |
| 855 | 875 | 25 | 23 | 21 | 19 | 17 | 16 | 14 | 12 | 10 | 8 | 6 |
| 875 | 895 | 26 | 24 | 22 | 20 | 18 | 16 | 14 | 12 | 10 | 8 | 7 |
| 895 | 915 | 27 | 25 | 23 | 21 | 19 | 17 | 15 | 13 | 11 | 9 | 7 |
| 915 | 935 | 28 | 26 | 24 | 22 | 20 | 18 | 16 | 14 | 12 | 10 | 8 |
| 935 | 955 | 29 | 27 | 25 | 23 | 21 | 19 | 17 | 15 | 13 | 11 | 9 |
| 955 | 975 | 29 | 27 | 26 | 24 | 22 | 20 | 18 | 16 | 14 | 12 | 10 |
| 975 | 995 | 30 | 28 | 26 | 24 | 22 | 20 | 18 | 16 | 15 | 13 | 11 |
| 995 | 1015 | 31 | 29 | 27 | 25 | 23 | 21 | 19 | 17 | 15 | 13 | 11 |
| 1015 | 1035 | 32 | 30 | 28 | 26 | 24 | 22 | 20 | 18 | 16 | 14 | 12 |
| 1035 | 1055 | 33 | 31 | 29 | 27 | 25 | 23 | 21 | 19 | 17 | 15 | 13 |
| 1055 | 1075 | 34 | 32 | 30 | 28 | 26 | 24 | 22 | 20 | 18 | 16 | 14 |
| 1075 | 1095 | 34 | 32 | 30 | 28 | 26 | 25 | 23 | 21 | 19 | 17 | 15 |
| 1095 | 1115 | 35 | 33 | 31 | 29 | 27 | 25 | 23 | 21 | 19 | 17 | 16 |
| 1115 | 1135 | 36 | 34 | 32 | 30 | 28 | 26 | 24 | 22 | 20 | 18 | 16 |
| 1135 | 1155 | 37 | 35 | 33 | 31 | 29 | 27 | 25 | 23 | 21 | 19 | 17 |
| 1155 | 1175 | 38 | 36 | 34 | 32 | 30 | 28 | 26 | 24 | 22 | 20 | 18 |
| 1175 | 1195 | 38 | 36 | 35 | 33 | 31 | 29 | 27 | 25 | 23 | 21 | 19 |
| 1195 | 1215 | 39 | 37 | 35 | 33 | 31 | 29 | 27 | 25 | 24 | 22 | 20 |
| 1215 | 1235 | 40 | 38 | 36 | 34 | 32 | 30 | 28 | 26 | 24 | 22 | 20 |
| Page | 21 |
# Single Person, Married Person, or Surviving Spouse - Weekly Payroll Period
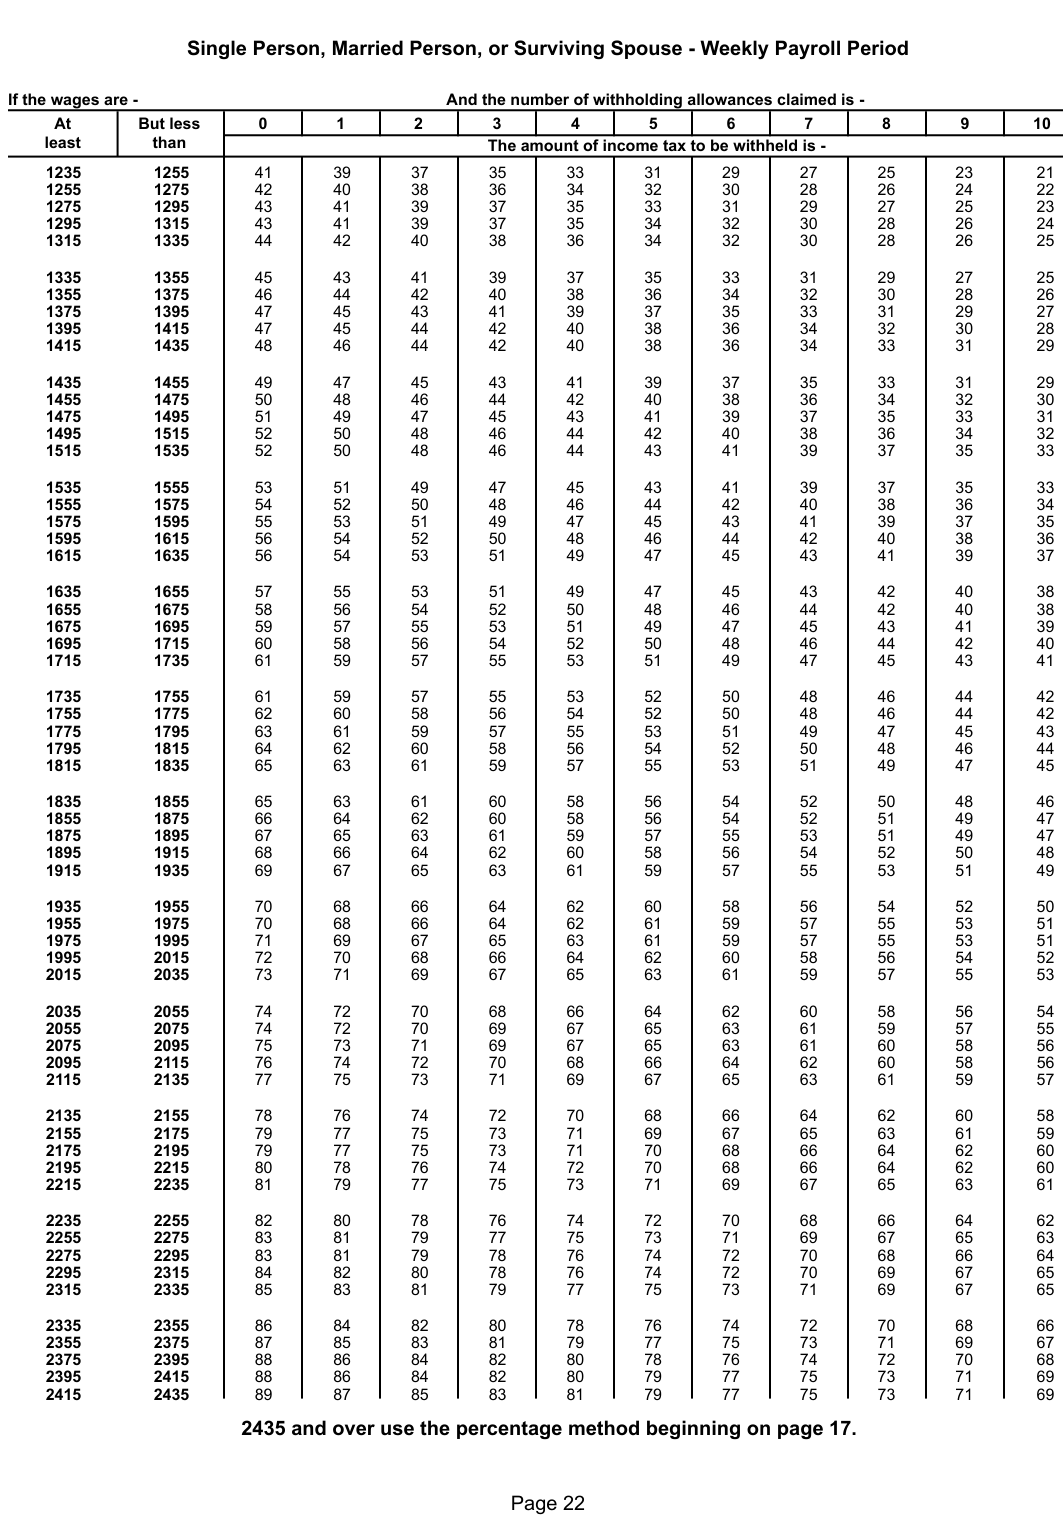
Text version of this table
| Singl | e Person, | Married | Person, | or Survi | ving Spo | use | - Weekly | Payroll Per | iod | |||
| wages are - | And t | he numbe | r of withho | lding | allowances | claimed is - | ||||||
| At B | ut less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
| least | than | The amou | nt of incom | e tax | to be withh | eld is - | ||||||
| 1235 | 1255 | 41 | 39 | 37 | 35 | 33 | 31 | 29 | 27 | 25 | 23 | 21 |
| 1255 | 1275 | 42 | 40 | 38 | 36 | 34 | 32 | 30 | 28 | 26 | 24 | 22 |
| 1275 | 1295 | 43 | 41 | 39 | 37 | 35 | 33 | 31 | 29 | 27 | 25 | 23 |
| 1295 | 1315 | 43 | 41 | 39 | 37 | 35 | 34 | 32 | 30 | 28 | 26 | 24 |
| 1315 | 1335 | 44 | 42 | 40 | 38 | 36 | 34 | 32 | 30 | 28 | 26 | 25 |
| 1335 | 1355 | 45 | 43 | 41 | 39 | 37 | 35 | 33 | 31 | 29 | 27 | 25 |
| 1355 | 1375 | 46 | 44 | 42 | 40 | 38 | 36 | 34 | 32 | 30 | 28 | 26 |
| 1375 | 1395 | 47 | 45 | 43 | 41 | 39 | 37 | 35 | 33 | 31 | 29 | 27 |
| 1395 | 1415 | 47 | 45 | 44 | 42 | 40 | 38 | 36 | 34 | 32 | 30 | 28 |
| 1415 | 1435 | 48 | 46 | 44 | 42 | 40 | 38 | 36 | 34 | 33 | 31 | 29 |
| 1435 | 1455 | 49 | 47 | 45 | 43 | 41 | 39 | 37 | 35 | 33 | 31 | 29 |
| 1455 | 1475 | 50 | 48 | 46 | 44 | 42 | 40 | 38 | 36 | 34 | 32 | 30 |
| 1475 | 1495 | 51 | 49 | 47 | 45 | 43 | 41 | 39 | 37 | 35 | 33 | 31 |
| 1495 | 1515 | 52 | 50 | 48 | 46 | 44 | 42 | 40 | 38 | 36 | 34 | 32 |
| 1515 | 1535 | 52 | 50 | 48 | 46 | 44 | 43 | 41 | 39 | 37 | 35 | 33 |
| 1535 | 1555 | 53 | 51 | 49 | 47 | 45 | 43 | 41 | 39 | 37 | 35 | 33 |
| 1555 | 1575 | 54 | 52 | 50 | 48 | 46 | 44 | 42 | 40 | 38 | 36 | 34 |
| 1575 | 1595 | 55 | 53 | 51 | 49 | 47 | 45 | 43 | 41 | 39 | 37 | 35 |
| 1595 | 1615 | 56 | 54 | 52 | 50 | 48 | 46 | 44 | 42 | 40 | 38 | 36 |
| 1615 | 1635 | 56 | 54 | 53 | 51 | 49 | 47 | 45 | 43 | 41 | 39 | 37 |
| 1635 | 1655 | 57 | 55 | 53 | 51 | 49 | 47 | 45 | 43 | 42 | 40 | 38 |
| 1655 | 1675 | 58 | 56 | 54 | 52 | 50 | 48 | 46 | 44 | 42 | 40 | 38 |
| 1675 | 1695 | 59 | 57 | 55 | 53 | 51 | 49 | 47 | 45 | 43 | 41 | 39 |
| 1695 | 1715 | 60 | 58 | 56 | 54 | 52 | 50 | 48 | 46 | 44 | 42 | 40 |
| 1715 | 1735 | 61 | 59 | 57 | 55 | 53 | 51 | 49 | 47 | 45 | 43 | 41 |
| 1735 | 1755 | 61 | 59 | 57 | 55 | 53 | 52 | 50 | 48 | 46 | 44 | 42 |
| 1755 | 1775 | 62 | 60 | 58 | 56 | 54 | 52 | 50 | 48 | 46 | 44 | 42 |
| 1775 | 1795 | 63 | 61 | 59 | 57 | 55 | 53 | 51 | 49 | 47 | 45 | 43 |
| 1795 | 1815 | 64 | 62 | 60 | 58 | 56 | 54 | 52 | 50 | 48 | 46 | 44 |
| 1815 | 1835 | 65 | 63 | 61 | 59 | 57 | 55 | 53 | 51 | 49 | 47 | 45 |
| 1835 | 1855 | 65 | 63 | 61 | 60 | 58 | 56 | 54 | 52 | 50 | 48 | 46 |
| 1855 | 1875 | 66 | 64 | 62 | 60 | 58 | 56 | 54 | 52 | 51 | 49 | 47 |
| 1875 | 1895 | 67 | 65 | 63 | 61 | 59 | 57 | 55 | 53 | 51 | 49 | 47 |
| 1895 | 1915 | 68 | 66 | 64 | 62 | 60 | 58 | 56 | 54 | 52 | 50 | 48 |
| 1915 | 1935 | 69 | 67 | 65 | 63 | 61 | 59 | 57 | 55 | 53 | 51 | 49 |
| 1935 | 1955 | 70 | 68 | 66 | 64 | 62 | 60 | 58 | 56 | 54 | 52 | 50 |
| 1955 | 1975 | 70 | 68 | 66 | 64 | 62 | 61 | 59 | 57 | 55 | 53 | 51 |
| 1975 | 1995 | 71 | 69 | 67 | 65 | 63 | 61 | 59 | 57 | 55 | 53 | 51 |
| 1995 | 2015 | 72 | 70 | 68 | 66 | 64 | 62 | 60 | 58 | 56 | 54 | 52 |
| 2015 | 2035 | 73 | 71 | 69 | 67 | 65 | 63 | 61 | 59 | 57 | 55 | 53 |
| 2035 | 2055 | 74 | 72 | 70 | 68 | 66 | 64 | 62 | 60 | 58 | 56 | 54 |
| 2055 | 2075 | 74 | 72 | 70 | 69 | 67 | 65 | 63 | 61 | 59 | 57 | 55 |
| 2075 | 2095 | 75 | 73 | 71 | 69 | 67 | 65 | 63 | 61 | 60 | 58 | 56 |
| 2095 | 2115 | 76 | 74 | 72 | 70 | 68 | 66 | 64 | 62 | 60 | 58 | 56 |
| 2115 | 2135 | 77 | 75 | 73 | 71 | 69 | 67 | 65 | 63 | 61 | 59 | 57 |
| 2135 | 2155 | 78 | 76 | 74 | 72 | 70 | 68 | 66 | 64 | 62 | 60 | 58 |
| 2155 | 2175 | 79 | 77 | 75 | 73 | 71 | 69 | 67 | 65 | 63 | 61 | 59 |
| 2175 | 2195 | 79 | 77 | 75 | 73 | 71 | 70 | 68 | 66 | 64 | 62 | 60 |
| 2195 | 2215 | 80 | 78 | 76 | 74 | 72 | 70 | 68 | 66 | 64 | 62 | 60 |
| 2215 | 2235 | 81 | 79 | 77 | 75 | 73 | 71 | 69 | 67 | 65 | 63 | 61 |
| 2235 | 2255 | 82 | 80 | 78 | 76 | 74 | 72 | 70 | 68 | 66 | 64 | 62 |
| 2255 | 2275 | 83 | 81 | 79 | 77 | 75 | 73 | 71 | 69 | 67 | 65 | 63 |
| 2275 | 2295 | 83 | 81 | 79 | 78 | 76 | 74 | 72 | 70 | 68 | 66 | 64 |
| 2295 | 2315 | 84 | 82 | 80 | 78 | 76 | 74 | 72 | 70 | 69 | 67 | 65 |
| 2315 | 2335 | 85 | 83 | 81 | 79 | 77 | 75 | 73 | 71 | 69 | 67 | 65 |
| 2335 | 2355 | 86 | 84 | 82 | 80 | 78 | 76 | 74 | 72 | 70 | 68 | 66 |
| 2355 | 2375 | 87 | 85 | 83 | 81 | 79 | 77 | 75 | 73 | 71 | 69 | 67 |
| 2375 | 2395 | 88 | 86 | 84 | 82 | 80 | 78 | 76 | 74 | 72 | 70 | 68 |
| 2395 | 2415 | 88 | 86 | 84 | 82 | 80 | 79 | 77 | 75 | 73 | 71 | 69 |
| 2415 | 2435 | 89 | 87 | 85 | 83 | 81 | 79 | 77 | 75 | 73 | 71 | 69 |
| 2435 and | over use | the per | centage | method | begi | nning on | page 17. | |||||
| Page | 22 |
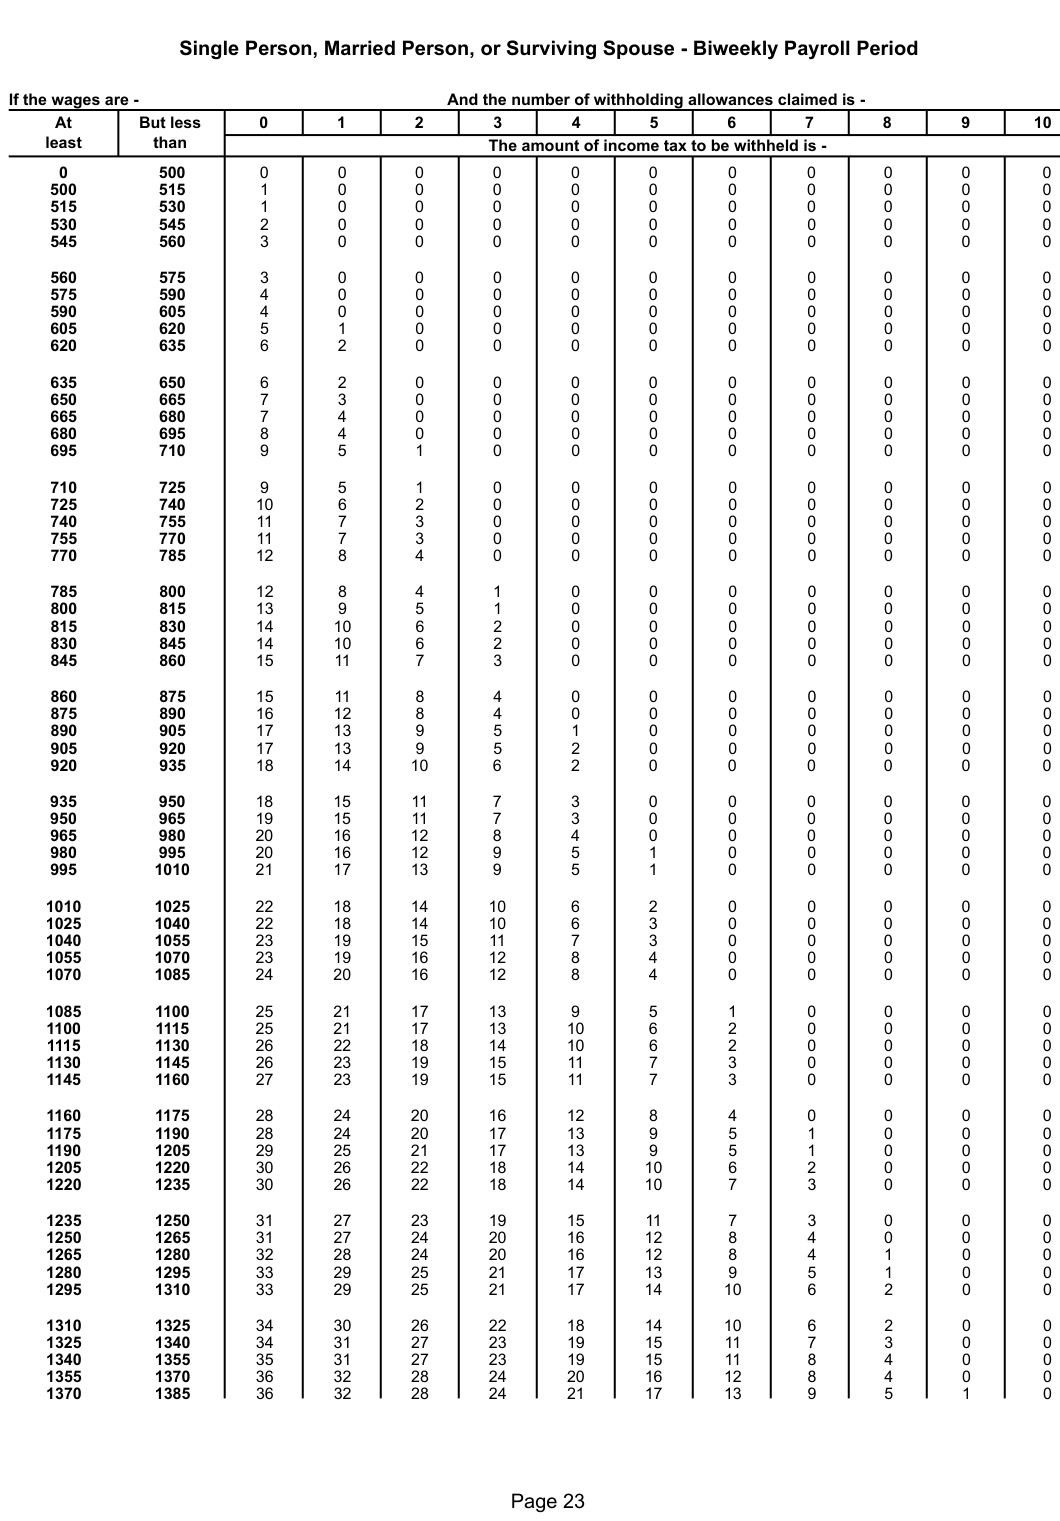
Text version of this table
| Single P | erson, M | arried P | erson, o | r Surviv | ing Spo | use - | Biweekly | Payroll | Period | |||
| wages are - | And t | he numbe | r of withho | lding | allowances | claimed is | - | |||||
| At B | ut less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
| least | than | The amou | nt of incom | e tax | to be withh | eld is - | ||||||
| 0 | 500 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 500 | 515 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 515 | 530 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 530 | 545 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 545 | 560 | 3 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 560 | 575 | 3 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 575 | 590 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 590 | 605 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 605 | 620 | 5 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 620 | 635 | 6 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 635 | 650 | 6 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 650 | 665 | 7 | 3 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 665 | 680 | 7 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 680 | 695 | 8 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 695 | 710 | 9 | 5 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 710 | 725 | 9 | 5 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 725 | 740 | 10 | 6 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 740 | 755 | 11 | 7 | 3 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 755 | 770 | 11 | 7 | 3 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 770 | 785 | 12 | 8 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 785 | 800 | 12 | 8 | 4 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 800 | 815 | 13 | 9 | 5 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 815 | 830 | 14 | 10 | 6 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 830 | 845 | 14 | 10 | 6 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 845 | 860 | 15 | 11 | 7 | 3 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 860 | 875 | 15 | 11 | 8 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 875 | 890 | 16 | 12 | 8 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 890 | 905 | 17 | 13 | 9 | 5 | 1 | 0 | 0 | 0 | 0 | 0 | 0 |
| 905 | 920 | 17 | 13 | 9 | 5 | 2 | 0 | 0 | 0 | 0 | 0 | 0 |
| 920 | 935 | 18 | 14 | 10 | 6 | 2 | 0 | 0 | 0 | 0 | 0 | 0 |
| 935 | 950 | 18 | 15 | 11 | 7 | 3 | 0 | 0 | 0 | 0 | 0 | 0 |
| 950 | 965 | 19 | 15 | 11 | 7 | 3 | 0 | 0 | 0 | 0 | 0 | 0 |
| 965 | 980 | 20 | 16 | 12 | 8 | 4 | 0 | 0 | 0 | 0 | 0 | 0 |
| 980 | 995 | 20 | 16 | 12 | 9 | 5 | 1 | 0 | 0 | 0 | 0 | 0 |
| 995 | 1010 | 21 | 17 | 13 | 9 | 5 | 1 | 0 | 0 | 0 | 0 | 0 |
| 1010 | 1025 | 22 | 18 | 14 | 10 | 6 | 2 | 0 | 0 | 0 | 0 | 0 |
| 1025 | 1040 | 22 | 18 | 14 | 10 | 6 | 3 | 0 | 0 | 0 | 0 | 0 |
| 1040 | 1055 | 23 | 19 | 15 | 11 | 7 | 3 | 0 | 0 | 0 | 0 | 0 |
| 1055 | 1070 | 23 | 19 | 16 | 12 | 8 | 4 | 0 | 0 | 0 | 0 | 0 |
| 1070 | 1085 | 24 | 20 | 16 | 12 | 8 | 4 | 0 | 0 | 0 | 0 | 0 |
| 1085 | 1100 | 25 | 21 | 17 | 13 | 9 | 5 | 1 | 0 | 0 | 0 | 0 |
| 1100 | 1115 | 25 | 21 | 17 | 13 | 10 | 6 | 2 | 0 | 0 | 0 | 0 |
| 1115 | 1130 | 26 | 22 | 18 | 14 | 10 | 6 | 2 | 0 | 0 | 0 | 0 |
| 1130 | 1145 | 26 | 23 | 19 | 15 | 11 | 7 | 3 | 0 | 0 | 0 | 0 |
| 1145 | 1160 | 27 | 23 | 19 | 15 | 11 | 7 | 3 | 0 | 0 | 0 | 0 |
| 1160 | 1175 | 28 | 24 | 20 | 16 | 12 | 8 | 4 | 0 | 0 | 0 | 0 |
| 1175 | 1190 | 28 | 24 | 20 | 17 | 13 | 9 | 5 | 1 | 0 | 0 | 0 |
| 1190 | 1205 | 29 | 25 | 21 | 17 | 13 | 9 | 5 | 1 | 0 | 0 | 0 |
| 1205 | 1220 | 30 | 26 | 22 | 18 | 14 | 10 | 6 | 2 | 0 | 0 | 0 |
| 1220 | 1235 | 30 | 26 | 22 | 18 | 14 | 10 | 7 | 3 | 0 | 0 | 0 |
| 1235 | 1250 | 31 | 27 | 23 | 19 | 15 | 11 | 7 | 3 | 0 | 0 | 0 |
| 1250 | 1265 | 31 | 27 | 24 | 20 | 16 | 12 | 8 | 4 | 0 | 0 | 0 |
| 1265 | 1280 | 32 | 28 | 24 | 20 | 16 | 12 | 8 | 4 | 1 | 0 | 0 |
| 1280 | 1295 | 33 | 29 | 25 | 21 | 17 | 13 | 9 | 5 | 1 | 0 | 0 |
| 1295 | 1310 | 33 | 29 | 25 | 21 | 17 | 14 | 10 | 6 | 2 | 0 | 0 |
| 1310 | 1325 | 34 | 30 | 26 | 22 | 18 | 14 | 10 | 6 | 2 | 0 | 0 |
| 1325 | 1340 | 34 | 31 | 27 | 23 | 19 | 15 | 11 | 7 | 3 | 0 | 0 |
| 1340 | 1355 | 35 | 31 | 27 | 23 | 19 | 15 | 11 | 8 | 4 | 0 | 0 |
| 1355 | 1370 | 36 | 32 | 28 | 24 | 20 | 16 | 12 | 8 | 4 | 0 | 0 |
| 1370 | 1385 | 36 | 32 | 28 | 24 | 21 | 17 | 13 | 9 | 5 | 1 | 0 |
| Page | 23 |
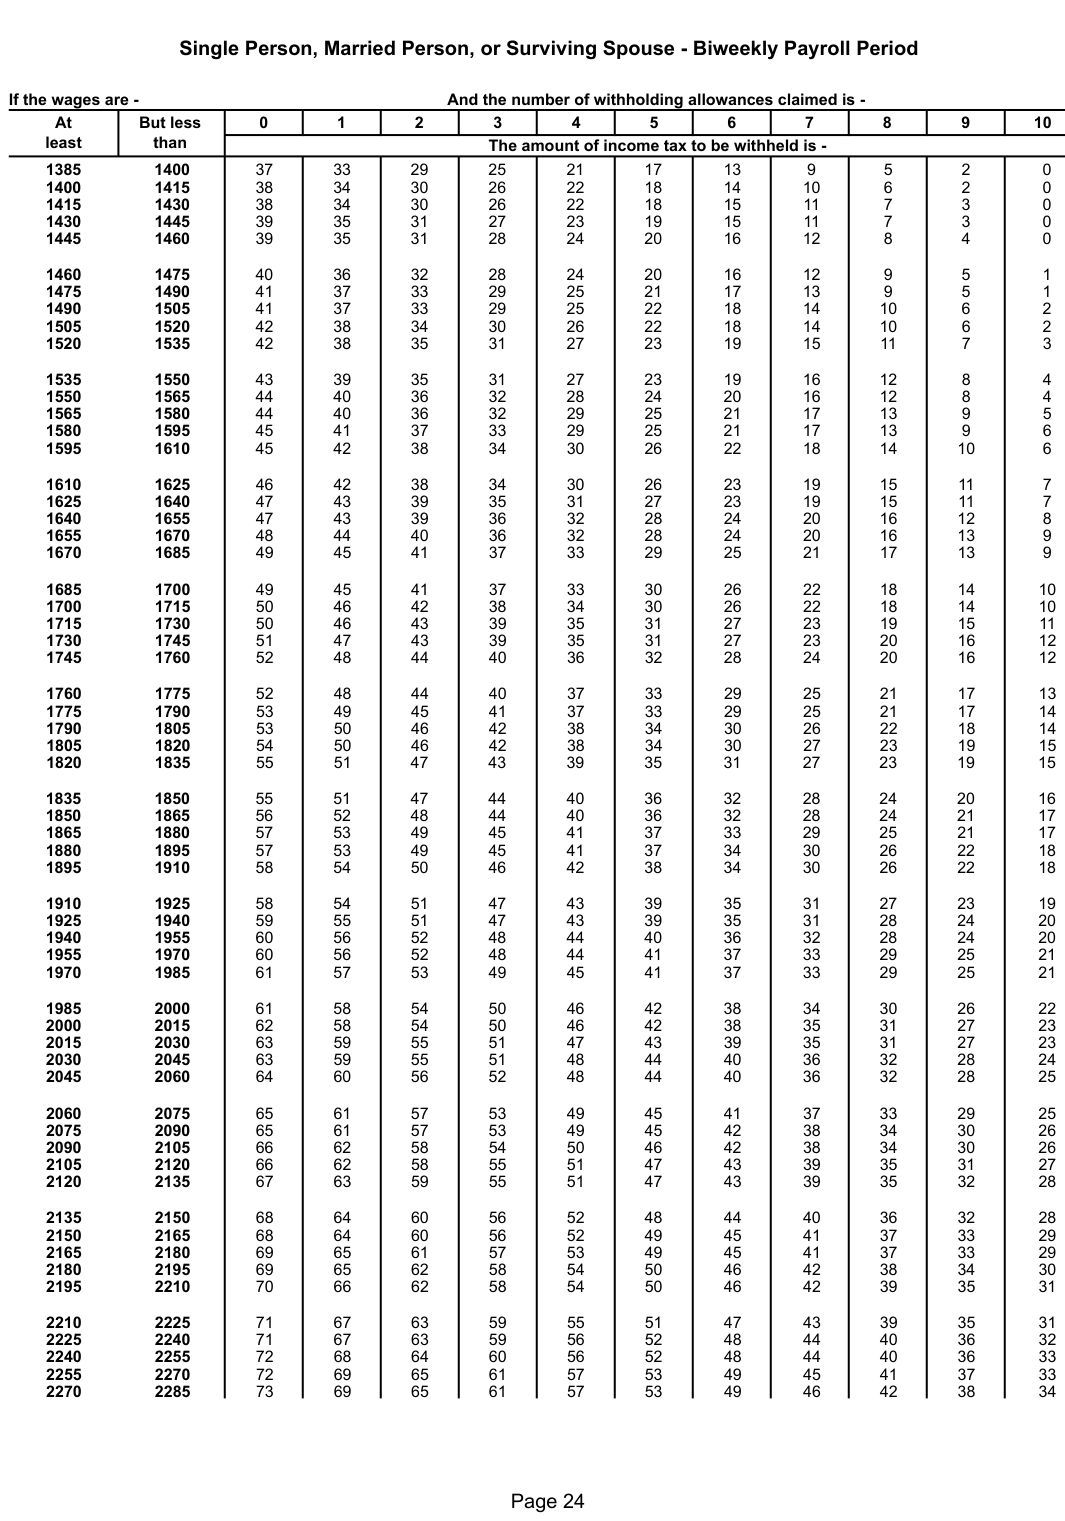
Text version of this table
| Single P | erson, M | arried P | erson, o | r Surviv | ing Spo | use - | Biweekly | Payroll | Period | |||
| wages are - | And t | he numbe | r of withho | lding | allowances | claimed is | - | |||||
| At B | ut less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
| least | than | The amou | nt of incom | e tax | to be withh | eld is - | ||||||
| 1385 | 1400 | 37 | 33 | 29 | 25 | 21 | 17 | 13 | 9 | 5 | 2 | 0 |
| 1400 | 1415 | 38 | 34 | 30 | 26 | 22 | 18 | 14 | 10 | 6 | 2 | 0 |
| 1415 | 1430 | 38 | 34 | 30 | 26 | 22 | 18 | 15 | 11 | 7 | 3 | 0 |
| 1430 | 1445 | 39 | 35 | 31 | 27 | 23 | 19 | 15 | 11 | 7 | 3 | 0 |
| 1445 | 1460 | 39 | 35 | 31 | 28 | 24 | 20 | 16 | 12 | 8 | 4 | 0 |
| 1460 | 1475 | 40 | 36 | 32 | 28 | 24 | 20 | 16 | 12 | 9 | 5 | 1 |
| 1475 | 1490 | 41 | 37 | 33 | 29 | 25 | 21 | 17 | 13 | 9 | 5 | 1 |
| 1490 | 1505 | 41 | 37 | 33 | 29 | 25 | 22 | 18 | 14 | 10 | 6 | 2 |
| 1505 | 1520 | 42 | 38 | 34 | 30 | 26 | 22 | 18 | 14 | 10 | 6 | 2 |
| 1520 | 1535 | 42 | 38 | 35 | 31 | 27 | 23 | 19 | 15 | 11 | 7 | 3 |
| 1535 | 1550 | 43 | 39 | 35 | 31 | 27 | 23 | 19 | 16 | 12 | 8 | 4 |
| 1550 | 1565 | 44 | 40 | 36 | 32 | 28 | 24 | 20 | 16 | 12 | 8 | 4 |
| 1565 | 1580 | 44 | 40 | 36 | 32 | 29 | 25 | 21 | 17 | 13 | 9 | 5 |
| 1580 | 1595 | 45 | 41 | 37 | 33 | 29 | 25 | 21 | 17 | 13 | 9 | 6 |
| 1595 | 1610 | 45 | 42 | 38 | 34 | 30 | 26 | 22 | 18 | 14 | 10 | 6 |
| 1610 | 1625 | 46 | 42 | 38 | 34 | 30 | 26 | 23 | 19 | 15 | 11 | 7 |
| 1625 | 1640 | 47 | 43 | 39 | 35 | 31 | 27 | 23 | 19 | 15 | 11 | 7 |
| 1640 | 1655 | 47 | 43 | 39 | 36 | 32 | 28 | 24 | 20 | 16 | 12 | 8 |
| 1655 | 1670 | 48 | 44 | 40 | 36 | 32 | 28 | 24 | 20 | 16 | 13 | 9 |
| 1670 | 1685 | 49 | 45 | 41 | 37 | 33 | 29 | 25 | 21 | 17 | 13 | 9 |
| 1685 | 1700 | 49 | 45 | 41 | 37 | 33 | 30 | 26 | 22 | 18 | 14 | 10 |
| 1700 | 1715 | 50 | 46 | 42 | 38 | 34 | 30 | 26 | 22 | 18 | 14 | 10 |
| 1715 | 1730 | 50 | 46 | 43 | 39 | 35 | 31 | 27 | 23 | 19 | 15 | 11 |
| 1730 | 1745 | 51 | 47 | 43 | 39 | 35 | 31 | 27 | 23 | 20 | 16 | 12 |
| 1745 | 1760 | 52 | 48 | 44 | 40 | 36 | 32 | 28 | 24 | 20 | 16 | 12 |
| 1760 | 1775 | 52 | 48 | 44 | 40 | 37 | 33 | 29 | 25 | 21 | 17 | 13 |
| 1775 | 1790 | 53 | 49 | 45 | 41 | 37 | 33 | 29 | 25 | 21 | 17 | 14 |
| 1790 | 1805 | 53 | 50 | 46 | 42 | 38 | 34 | 30 | 26 | 22 | 18 | 14 |
| 1805 | 1820 | 54 | 50 | 46 | 42 | 38 | 34 | 30 | 27 | 23 | 19 | 15 |
| 1820 | 1835 | 55 | 51 | 47 | 43 | 39 | 35 | 31 | 27 | 23 | 19 | 15 |
| 1835 | 1850 | 55 | 51 | 47 | 44 | 40 | 36 | 32 | 28 | 24 | 20 | 16 |
| 1850 | 1865 | 56 | 52 | 48 | 44 | 40 | 36 | 32 | 28 | 24 | 21 | 17 |
| 1865 | 1880 | 57 | 53 | 49 | 45 | 41 | 37 | 33 | 29 | 25 | 21 | 17 |
| 1880 | 1895 | 57 | 53 | 49 | 45 | 41 | 37 | 34 | 30 | 26 | 22 | 18 |
| 1895 | 1910 | 58 | 54 | 50 | 46 | 42 | 38 | 34 | 30 | 26 | 22 | 18 |
| 1910 | 1925 | 58 | 54 | 51 | 47 | 43 | 39 | 35 | 31 | 27 | 23 | 19 |
| 1925 | 1940 | 59 | 55 | 51 | 47 | 43 | 39 | 35 | 31 | 28 | 24 | 20 |
| 1940 | 1955 | 60 | 56 | 52 | 48 | 44 | 40 | 36 | 32 | 28 | 24 | 20 |
| 1955 | 1970 | 60 | 56 | 52 | 48 | 44 | 41 | 37 | 33 | 29 | 25 | 21 |
| 1970 | 1985 | 61 | 57 | 53 | 49 | 45 | 41 | 37 | 33 | 29 | 25 | 21 |
| 1985 | 2000 | 61 | 58 | 54 | 50 | 46 | 42 | 38 | 34 | 30 | 26 | 22 |
| 2000 | 2015 | 62 | 58 | 54 | 50 | 46 | 42 | 38 | 35 | 31 | 27 | 23 |
| 2015 | 2030 | 63 | 59 | 55 | 51 | 47 | 43 | 39 | 35 | 31 | 27 | 23 |
| 2030 | 2045 | 63 | 59 | 55 | 51 | 48 | 44 | 40 | 36 | 32 | 28 | 24 |
| 2045 | 2060 | 64 | 60 | 56 | 52 | 48 | 44 | 40 | 36 | 32 | 28 | 25 |
| 2060 | 2075 | 65 | 61 | 57 | 53 | 49 | 45 | 41 | 37 | 33 | 29 | 25 |
| 2075 | 2090 | 65 | 61 | 57 | 53 | 49 | 45 | 42 | 38 | 34 | 30 | 26 |
| 2090 | 2105 | 66 | 62 | 58 | 54 | 50 | 46 | 42 | 38 | 34 | 30 | 26 |
| 2105 | 2120 | 66 | 62 | 58 | 55 | 51 | 47 | 43 | 39 | 35 | 31 | 27 |
| 2120 | 2135 | 67 | 63 | 59 | 55 | 51 | 47 | 43 | 39 | 35 | 32 | 28 |
| 2135 | 2150 | 68 | 64 | 60 | 56 | 52 | 48 | 44 | 40 | 36 | 32 | 28 |
| 2150 | 2165 | 68 | 64 | 60 | 56 | 52 | 49 | 45 | 41 | 37 | 33 | 29 |
| 2165 | 2180 | 69 | 65 | 61 | 57 | 53 | 49 | 45 | 41 | 37 | 33 | 29 |
| 2180 | 2195 | 69 | 65 | 62 | 58 | 54 | 50 | 46 | 42 | 38 | 34 | 30 |
| 2195 | 2210 | 70 | 66 | 62 | 58 | 54 | 50 | 46 | 42 | 39 | 35 | 31 |
| 2210 | 2225 | 71 | 67 | 63 | 59 | 55 | 51 | 47 | 43 | 39 | 35 | 31 |
| 2225 | 2240 | 71 | 67 | 63 | 59 | 56 | 52 | 48 | 44 | 40 | 36 | 32 |
| 2240 | 2255 | 72 | 68 | 64 | 60 | 56 | 52 | 48 | 44 | 40 | 36 | 33 |
| 2255 | 2270 | 72 | 69 | 65 | 61 | 57 | 53 | 49 | 45 | 41 | 37 | 33 |
| 2270 | 2285 | 73 | 69 | 65 | 61 | 57 | 53 | 49 | 46 | 42 | 38 | 34 |
| Page | 24 |
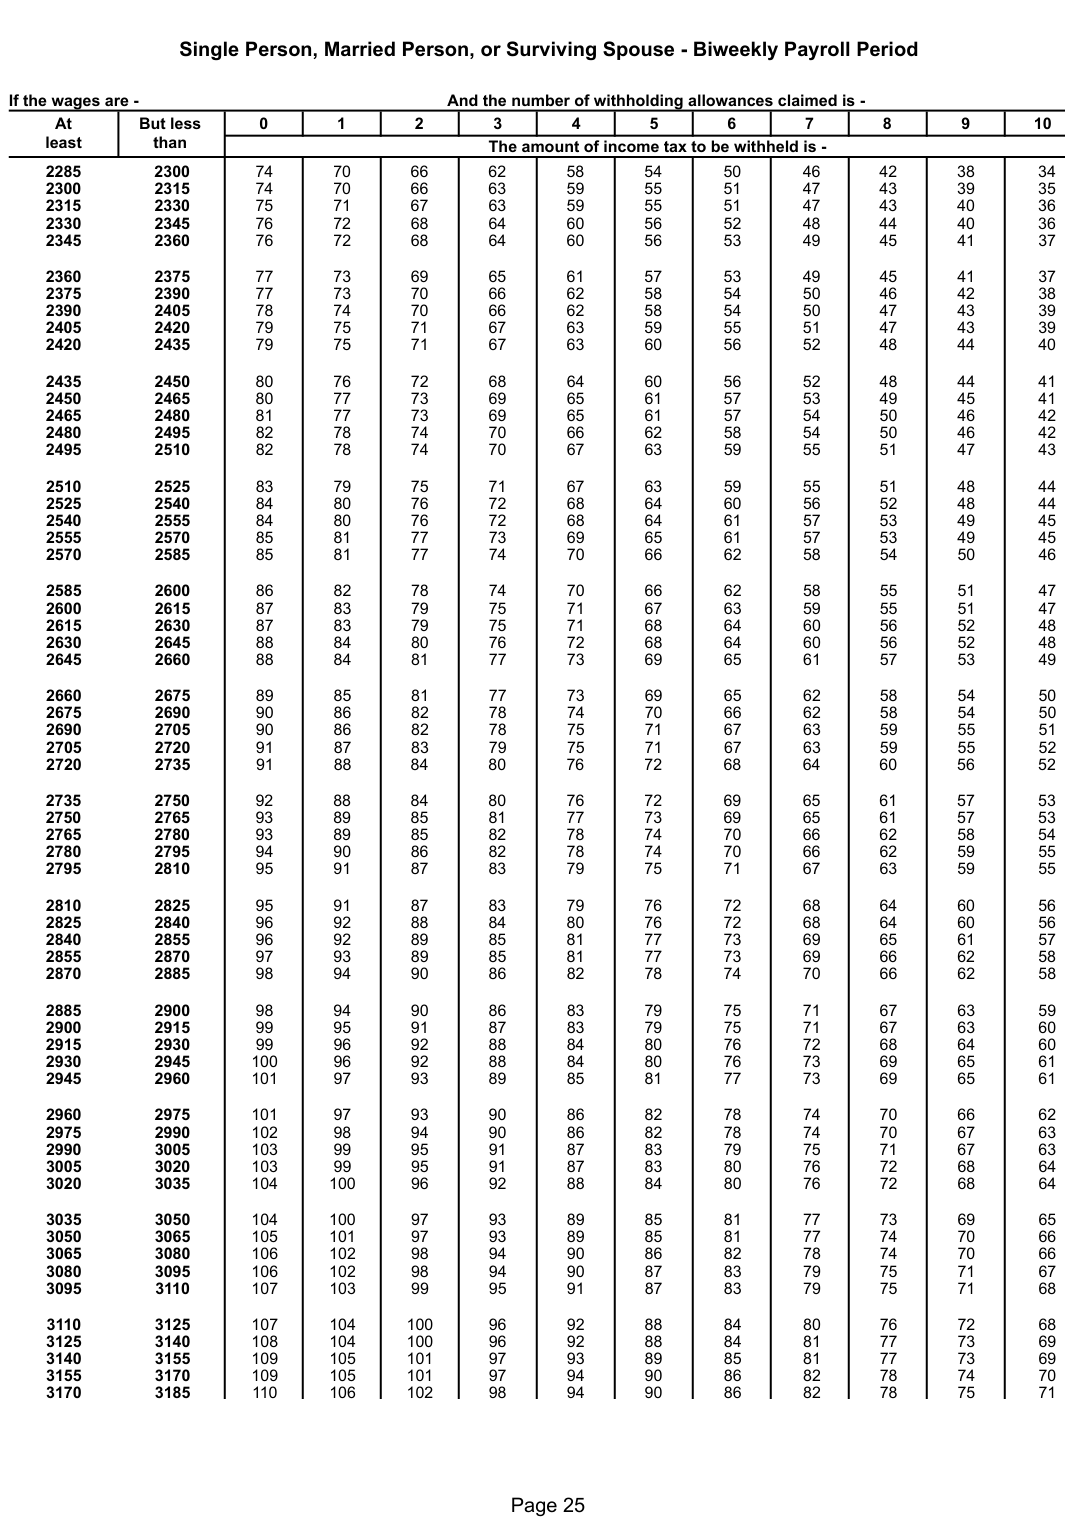
Text version of this table
| Single | Person, | Married | Person, o | r Surviv | ing Spo | use - | Biweekly | Payroll | Period | |||
| wages are - | And t | he numbe | r of withho | lding | allowances | claimed is | - | |||||
| At B | ut less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
| least | than | The amou | nt of incom | e tax | to be withh | eld is - | ||||||
| 2285 | 2300 | 74 | 70 | 66 | 62 | 58 | 54 | 50 | 46 | 42 | 38 | 34 |
| 2300 | 2315 | 74 | 70 | 66 | 63 | 59 | 55 | 51 | 47 | 43 | 39 | 35 |
| 2315 | 2330 | 75 | 71 | 67 | 63 | 59 | 55 | 51 | 47 | 43 | 40 | 36 |
| 2330 | 2345 | 76 | 72 | 68 | 64 | 60 | 56 | 52 | 48 | 44 | 40 | 36 |
| 2345 | 2360 | 76 | 72 | 68 | 64 | 60 | 56 | 53 | 49 | 45 | 41 | 37 |
| 2360 | 2375 | 77 | 73 | 69 | 65 | 61 | 57 | 53 | 49 | 45 | 41 | 37 |
| 2375 | 2390 | 77 | 73 | 70 | 66 | 62 | 58 | 54 | 50 | 46 | 42 | 38 |
| 2390 | 2405 | 78 | 74 | 70 | 66 | 62 | 58 | 54 | 50 | 47 | 43 | 39 |
| 2405 | 2420 | 79 | 75 | 71 | 67 | 63 | 59 | 55 | 51 | 47 | 43 | 39 |
| 2420 | 2435 | 79 | 75 | 71 | 67 | 63 | 60 | 56 | 52 | 48 | 44 | 40 |
| 2435 | 2450 | 80 | 76 | 72 | 68 | 64 | 60 | 56 | 52 | 48 | 44 | 41 |
| 2450 | 2465 | 80 | 77 | 73 | 69 | 65 | 61 | 57 | 53 | 49 | 45 | 41 |
| 2465 | 2480 | 81 | 77 | 73 | 69 | 65 | 61 | 57 | 54 | 50 | 46 | 42 |
| 2480 | 2495 | 82 | 78 | 74 | 70 | 66 | 62 | 58 | 54 | 50 | 46 | 42 |
| 2495 | 2510 | 82 | 78 | 74 | 70 | 67 | 63 | 59 | 55 | 51 | 47 | 43 |
| 2510 | 2525 | 83 | 79 | 75 | 71 | 67 | 63 | 59 | 55 | 51 | 48 | 44 |
| 2525 | 2540 | 84 | 80 | 76 | 72 | 68 | 64 | 60 | 56 | 52 | 48 | 44 |
| 2540 | 2555 | 84 | 80 | 76 | 72 | 68 | 64 | 61 | 57 | 53 | 49 | 45 |
| 2555 | 2570 | 85 | 81 | 77 | 73 | 69 | 65 | 61 | 57 | 53 | 49 | 45 |
| 2570 | 2585 | 85 | 81 | 77 | 74 | 70 | 66 | 62 | 58 | 54 | 50 | 46 |
| 2585 | 2600 | 86 | 82 | 78 | 74 | 70 | 66 | 62 | 58 | 55 | 51 | 47 |
| 2600 | 2615 | 87 | 83 | 79 | 75 | 71 | 67 | 63 | 59 | 55 | 51 | 47 |
| 2615 | 2630 | 87 | 83 | 79 | 75 | 71 | 68 | 64 | 60 | 56 | 52 | 48 |
| 2630 | 2645 | 88 | 84 | 80 | 76 | 72 | 68 | 64 | 60 | 56 | 52 | 48 |
| 2645 | 2660 | 88 | 84 | 81 | 77 | 73 | 69 | 65 | 61 | 57 | 53 | 49 |
| 2660 | 2675 | 89 | 85 | 81 | 77 | 73 | 69 | 65 | 62 | 58 | 54 | 50 |
| 2675 | 2690 | 90 | 86 | 82 | 78 | 74 | 70 | 66 | 62 | 58 | 54 | 50 |
| 2690 | 2705 | 90 | 86 | 82 | 78 | 75 | 71 | 67 | 63 | 59 | 55 | 51 |
| 2705 | 2720 | 91 | 87 | 83 | 79 | 75 | 71 | 67 | 63 | 59 | 55 | 52 |
| 2720 | 2735 | 91 | 88 | 84 | 80 | 76 | 72 | 68 | 64 | 60 | 56 | 52 |
| 2735 | 2750 | 92 | 88 | 84 | 80 | 76 | 72 | 69 | 65 | 61 | 57 | 53 |
| 2750 | 2765 | 93 | 89 | 85 | 81 | 77 | 73 | 69 | 65 | 61 | 57 | 53 |
| 2765 | 2780 | 93 | 89 | 85 | 82 | 78 | 74 | 70 | 66 | 62 | 58 | 54 |
| 2780 | 2795 | 94 | 90 | 86 | 82 | 78 | 74 | 70 | 66 | 62 | 59 | 55 |
| 2795 | 2810 | 95 | 91 | 87 | 83 | 79 | 75 | 71 | 67 | 63 | 59 | 55 |
| 2810 | 2825 | 95 | 91 | 87 | 83 | 79 | 76 | 72 | 68 | 64 | 60 | 56 |
| 2825 | 2840 | 96 | 92 | 88 | 84 | 80 | 76 | 72 | 68 | 64 | 60 | 56 |
| 2840 | 2855 | 96 | 92 | 89 | 85 | 81 | 77 | 73 | 69 | 65 | 61 | 57 |
| 2855 | 2870 | 97 | 93 | 89 | 85 | 81 | 77 | 73 | 69 | 66 | 62 | 58 |
| 2870 | 2885 | 98 | 94 | 90 | 86 | 82 | 78 | 74 | 70 | 66 | 62 | 58 |
| 2885 | 2900 | 98 | 94 | 90 | 86 | 83 | 79 | 75 | 71 | 67 | 63 | 59 |
| 2900 | 2915 | 99 | 95 | 91 | 87 | 83 | 79 | 75 | 71 | 67 | 63 | 60 |
| 2915 | 2930 | 99 | 96 | 92 | 88 | 84 | 80 | 76 | 72 | 68 | 64 | 60 |
| 2930 | 2945 | 100 | 96 | 92 | 88 | 84 | 80 | 76 | 73 | 69 | 65 | 61 |
| 2945 | 2960 | 101 | 97 | 93 | 89 | 85 | 81 | 77 | 73 | 69 | 65 | 61 |
| 2960 | 2975 | 101 | 97 | 93 | 90 | 86 | 82 | 78 | 74 | 70 | 66 | 62 |
| 2975 | 2990 | 102 | 98 | 94 | 90 | 86 | 82 | 78 | 74 | 70 | 67 | 63 |
| 2990 | 3005 | 103 | 99 | 95 | 91 | 87 | 83 | 79 | 75 | 71 | 67 | 63 |
| 3005 | 3020 | 103 | 99 | 95 | 91 | 87 | 83 | 80 | 76 | 72 | 68 | 64 |
| 3020 | 3035 | 104 | 100 | 96 | 92 | 88 | 84 | 80 | 76 | 72 | 68 | 64 |
| 3035 | 3050 | 104 | 100 | 97 | 93 | 89 | 85 | 81 | 77 | 73 | 69 | 65 |
| 3050 | 3065 | 105 | 101 | 97 | 93 | 89 | 85 | 81 | 77 | 74 | 70 | 66 |
| 3065 | 3080 | 106 | 102 | 98 | 94 | 90 | 86 | 82 | 78 | 74 | 70 | 66 |
| 3080 | 3095 | 106 | 102 | 98 | 94 | 90 | 87 | 83 | 79 | 75 | 71 | 67 |
| 3095 | 3110 | 107 | 103 | 99 | 95 | 91 | 87 | 83 | 79 | 75 | 71 | 68 |
| 3110 | 3125 | 107 | 104 | 100 | 96 | 92 | 88 | 84 | 80 | 76 | 72 | 68 |
| 3125 | 3140 | 108 | 104 | 100 | 96 | 92 | 88 | 84 | 81 | 77 | 73 | 69 |
| 3140 | 3155 | 109 | 105 | 101 | 97 | 93 | 89 | 85 | 81 | 77 | 73 | 69 |
| 3155 | 3170 | 109 | 105 | 101 | 97 | 94 | 90 | 86 | 82 | 78 | 74 | 70 |
| 3170 | 3185 | 110 | 106 | 102 | 98 | 94 | 90 | 86 | 82 | 78 | 75 | 71 |
| Page | 25 |
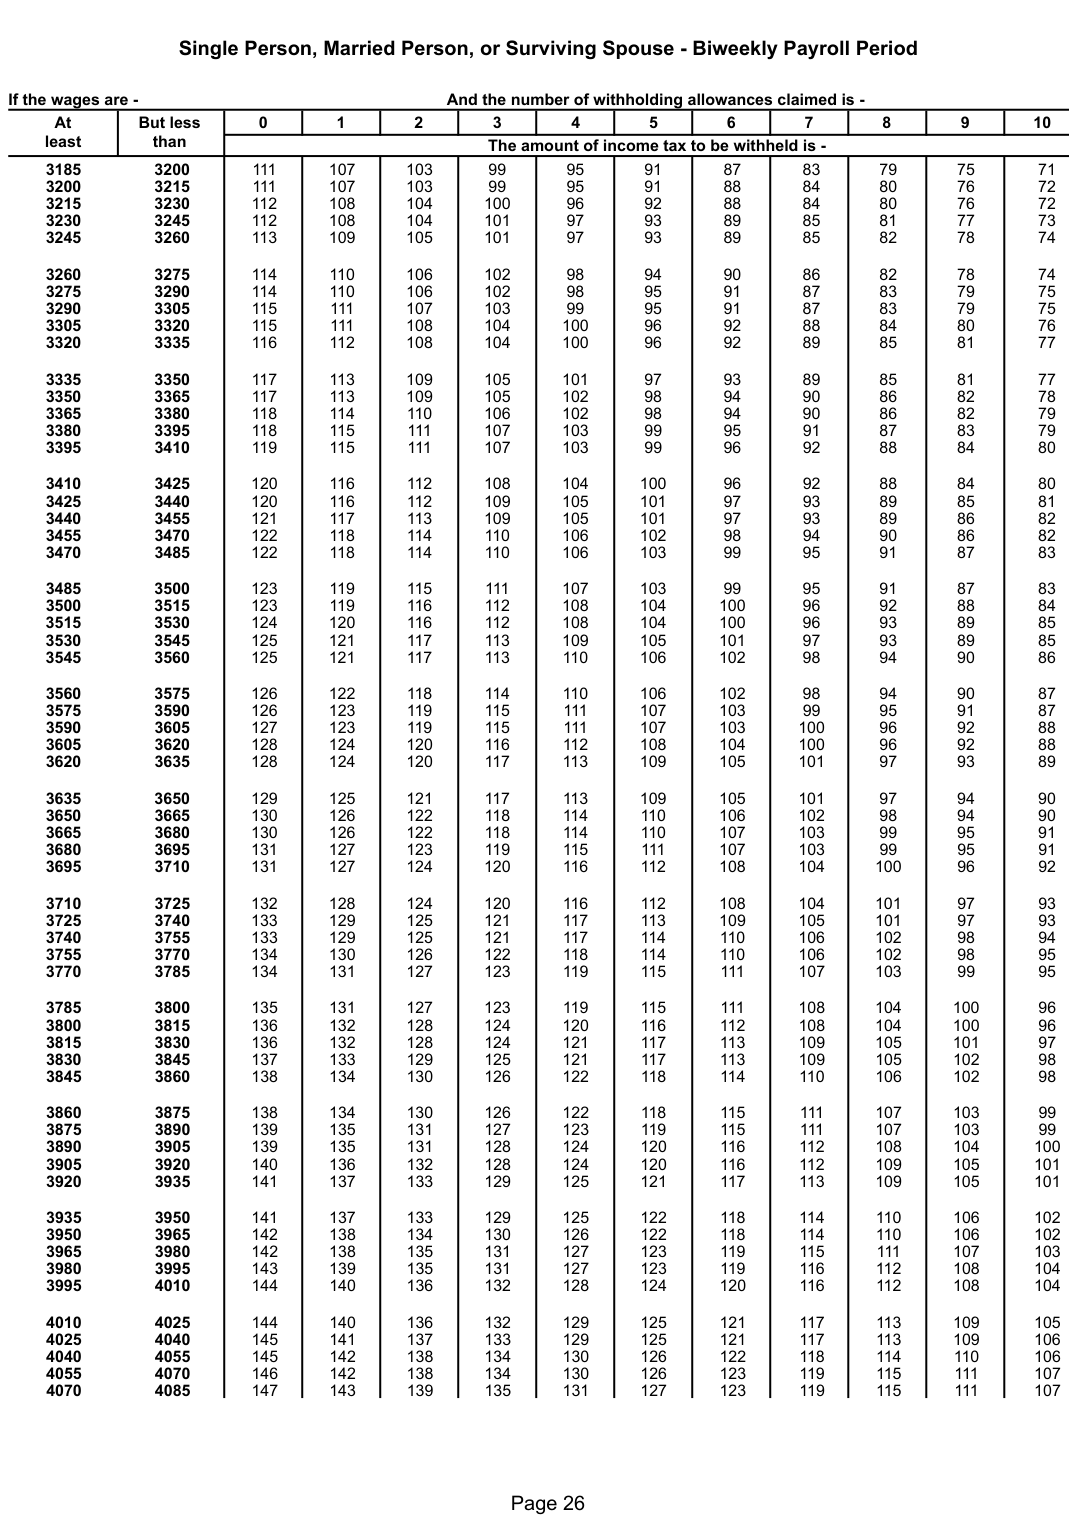
Text version of this table
| Single | Person, | Married | Person, | or Surviv | ing Spo | use - | Biweekly | P | ayroll | Period | |||
| wages are - | And | the numbe | r of withh | olding | allowances | cla | imed is | - | |||||
| At B | ut less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 | |
| least | than | The amou | nt of inco | me tax | to be withh | eld | is - | ||||||
| 3185 | 3200 | 111 | 107 | 103 | 99 | 95 | 91 | 87 | 83 | 79 | 75 | 71 | |
| 3200 | 3215 | 111 | 107 | 103 | 99 | 95 | 91 | 88 | 84 | 80 | 76 | 72 | |
| 3215 | 3230 | 112 | 108 | 104 | 100 | 96 | 92 | 88 | 84 | 80 | 76 | 72 | |
| 3230 | 3245 | 112 | 108 | 104 | 101 | 97 | 93 | 89 | 85 | 81 | 77 | 73 | |
| 3245 | 3260 | 113 | 109 | 105 | 101 | 97 | 93 | 89 | 85 | 82 | 78 | 74 | |
| 3260 | 3275 | 114 | 110 | 106 | 102 | 98 | 94 | 90 | 86 | 82 | 78 | 74 | |
| 3275 | 3290 | 114 | 110 | 106 | 102 | 98 | 95 | 91 | 87 | 83 | 79 | 75 | |
| 3290 | 3305 | 115 | 111 | 107 | 103 | 99 | 95 | 91 | 87 | 83 | 79 | 75 | |
| 3305 | 3320 | 115 | 111 | 108 | 104 | 100 | 96 | 92 | 88 | 84 | 80 | 76 | |
| 3320 | 3335 | 116 | 112 | 108 | 104 | 100 | 96 | 92 | 89 | 85 | 81 | 77 | |
| 3335 | 3350 | 117 | 113 | 109 | 105 | 101 | 97 | 93 | 89 | 85 | 81 | 77 | |
| 3350 | 3365 | 117 | 113 | 109 | 105 | 102 | 98 | 94 | 90 | 86 | 82 | 78 | |
| 3365 | 3380 | 118 | 114 | 110 | 106 | 102 | 98 | 94 | 90 | 86 | 82 | 79 | |
| 3380 | 3395 | 118 | 115 | 111 | 107 | 103 | 99 | 95 | 91 | 87 | 83 | 79 | |
| 3395 | 3410 | 119 | 115 | 111 | 107 | 103 | 99 | 96 | 92 | 88 | 84 | 80 | |
| 3410 | 3425 | 120 | 116 | 112 | 108 | 104 | 100 | 96 | 92 | 88 | 84 | 80 | |
| 3425 | 3440 | 120 | 116 | 112 | 109 | 105 | 101 | 97 | 93 | 89 | 85 | 81 | |
| 3440 | 3455 | 121 | 117 | 113 | 109 | 105 | 101 | 97 | 93 | 89 | 86 | 82 | |
| 3455 | 3470 | 122 | 118 | 114 | 110 | 106 | 102 | 98 | 94 | 90 | 86 | 82 | |
| 3470 | 3485 | 122 | 118 | 114 | 110 | 106 | 103 | 99 | 95 | 91 | 87 | 83 | |
| 3485 | 3500 | 123 | 119 | 115 | 111 | 107 | 103 | 99 | 95 | 91 | 87 | 83 | |
| 3500 | 3515 | 123 | 119 | 116 | 112 | 108 | 104 | 100 | 96 | 92 | 88 | 84 | |
| 3515 | 3530 | 124 | 120 | 116 | 112 | 108 | 104 | 100 | 96 | 93 | 89 | 85 | |
| 3530 | 3545 | 125 | 121 | 117 | 113 | 109 | 105 | 101 | 97 | 93 | 89 | 85 | |
| 3545 | 3560 | 125 | 121 | 117 | 113 | 110 | 106 | 102 | 98 | 94 | 90 | 86 | |
| 3560 | 3575 | 126 | 122 | 118 | 114 | 110 | 106 | 102 | 98 | 94 | 90 | 87 | |
| 3575 | 3590 | 126 | 123 | 119 | 115 | 111 | 107 | 103 | 99 | 95 | 91 | 87 | |
| 3590 | 3605 | 127 | 123 | 119 | 115 | 111 | 107 | 103 | 100 | 96 | 92 | 88 | |
| 3605 | 3620 | 128 | 124 | 120 | 116 | 112 | 108 | 104 | 100 | 96 | 92 | 88 | |
| 3620 | 3635 | 128 | 124 | 120 | 117 | 113 | 109 | 105 | 101 | 97 | 93 | 89 | |
| 3635 | 3650 | 129 | 125 | 121 | 117 | 113 | 109 | 105 | 101 | 97 | 94 | 90 | |
| 3650 | 3665 | 130 | 126 | 122 | 118 | 114 | 110 | 106 | 102 | 98 | 94 | 90 | |
| 3665 | 3680 | 130 | 126 | 122 | 118 | 114 | 110 | 107 | 103 | 99 | 95 | 91 | |
| 3680 | 3695 | 131 | 127 | 123 | 119 | 115 | 111 | 107 | 103 | 99 | 95 | 91 | |
| 3695 | 3710 | 131 | 127 | 124 | 120 | 116 | 112 | 108 | 104 | 100 | 96 | 92 | |
| 3710 | 3725 | 132 | 128 | 124 | 120 | 116 | 112 | 108 | 104 | 101 | 97 | 93 | |
| 3725 | 3740 | 133 | 129 | 125 | 121 | 117 | 113 | 109 | 105 | 101 | 97 | 93 | |
| 3740 | 3755 | 133 | 129 | 125 | 121 | 117 | 114 | 110 | 106 | 102 | 98 | 94 | |
| 3755 | 3770 | 134 | 130 | 126 | 122 | 118 | 114 | 110 | 106 | 102 | 98 | 95 | |
| 3770 | 3785 | 134 | 131 | 127 | 123 | 119 | 115 | 111 | 107 | 103 | 99 | 95 | |
| 3785 | 3800 | 135 | 131 | 127 | 123 | 119 | 115 | 111 | 108 | 104 | 100 | 96 | |
| 3800 | 3815 | 136 | 132 | 128 | 124 | 120 | 116 | 112 | 108 | 104 | 100 | 96 | |
| 3815 | 3830 | 136 | 132 | 128 | 124 | 121 | 117 | 113 | 109 | 105 | 101 | 97 | |
| 3830 | 3845 | 137 | 133 | 129 | 125 | 121 | 117 | 113 | 109 | 105 | 102 | 98 | |
| 3845 | 3860 | 138 | 134 | 130 | 126 | 122 | 118 | 114 | 110 | 106 | 102 | 98 | |
| 3860 | 3875 | 138 | 134 | 130 | 126 | 122 | 118 | 115 | 111 | 107 | 103 | 99 | |
| 3875 | 3890 | 139 | 135 | 131 | 127 | 123 | 119 | 115 | 111 | 107 | 103 | 99 | |
| 3890 | 3905 | 139 | 135 | 131 | 128 | 124 | 120 | 116 | 112 | 108 | 104 | 100 | |
| 3905 | 3920 | 140 | 136 | 132 | 128 | 124 | 120 | 116 | 112 | 109 | 105 | 101 | |
| 3920 | 3935 | 141 | 137 | 133 | 129 | 125 | 121 | 117 | 113 | 109 | 105 | 101 | |
| 3935 | 3950 | 141 | 137 | 133 | 129 | 125 | 122 | 118 | 114 | 110 | 106 | 102 | |
| 3950 | 3965 | 142 | 138 | 134 | 130 | 126 | 122 | 118 | 114 | 110 | 106 | 102 | |
| 3965 | 3980 | 142 | 138 | 135 | 131 | 127 | 123 | 119 | 115 | 111 | 107 | 103 | |
| 3980 | 3995 | 143 | 139 | 135 | 131 | 127 | 123 | 119 | 116 | 112 | 108 | 104 | |
| 3995 | 4010 | 144 | 140 | 136 | 132 | 128 | 124 | 120 | 116 | 112 | 108 | 104 | |
| 4010 | 4025 | 144 | 140 | 136 | 132 | 129 | 125 | 121 | 117 | 113 | 109 | 105 | |
| 4025 | 4040 | 145 | 141 | 137 | 133 | 129 | 125 | 121 | 117 | 113 | 109 | 106 | |
| 4040 | 4055 | 145 | 142 | 138 | 134 | 130 | 126 | 122 | 118 | 114 | 110 | 106 | |
| 4055 | 4070 | 146 | 142 | 138 | 134 | 130 | 126 | 123 | 119 | 115 | 111 | 107 | |
| 4070 | 4085 | 147 | 143 | 139 | 135 | 131 | 127 | 123 | 119 | 115 | 111 | 107 | |
| Page | 26 |
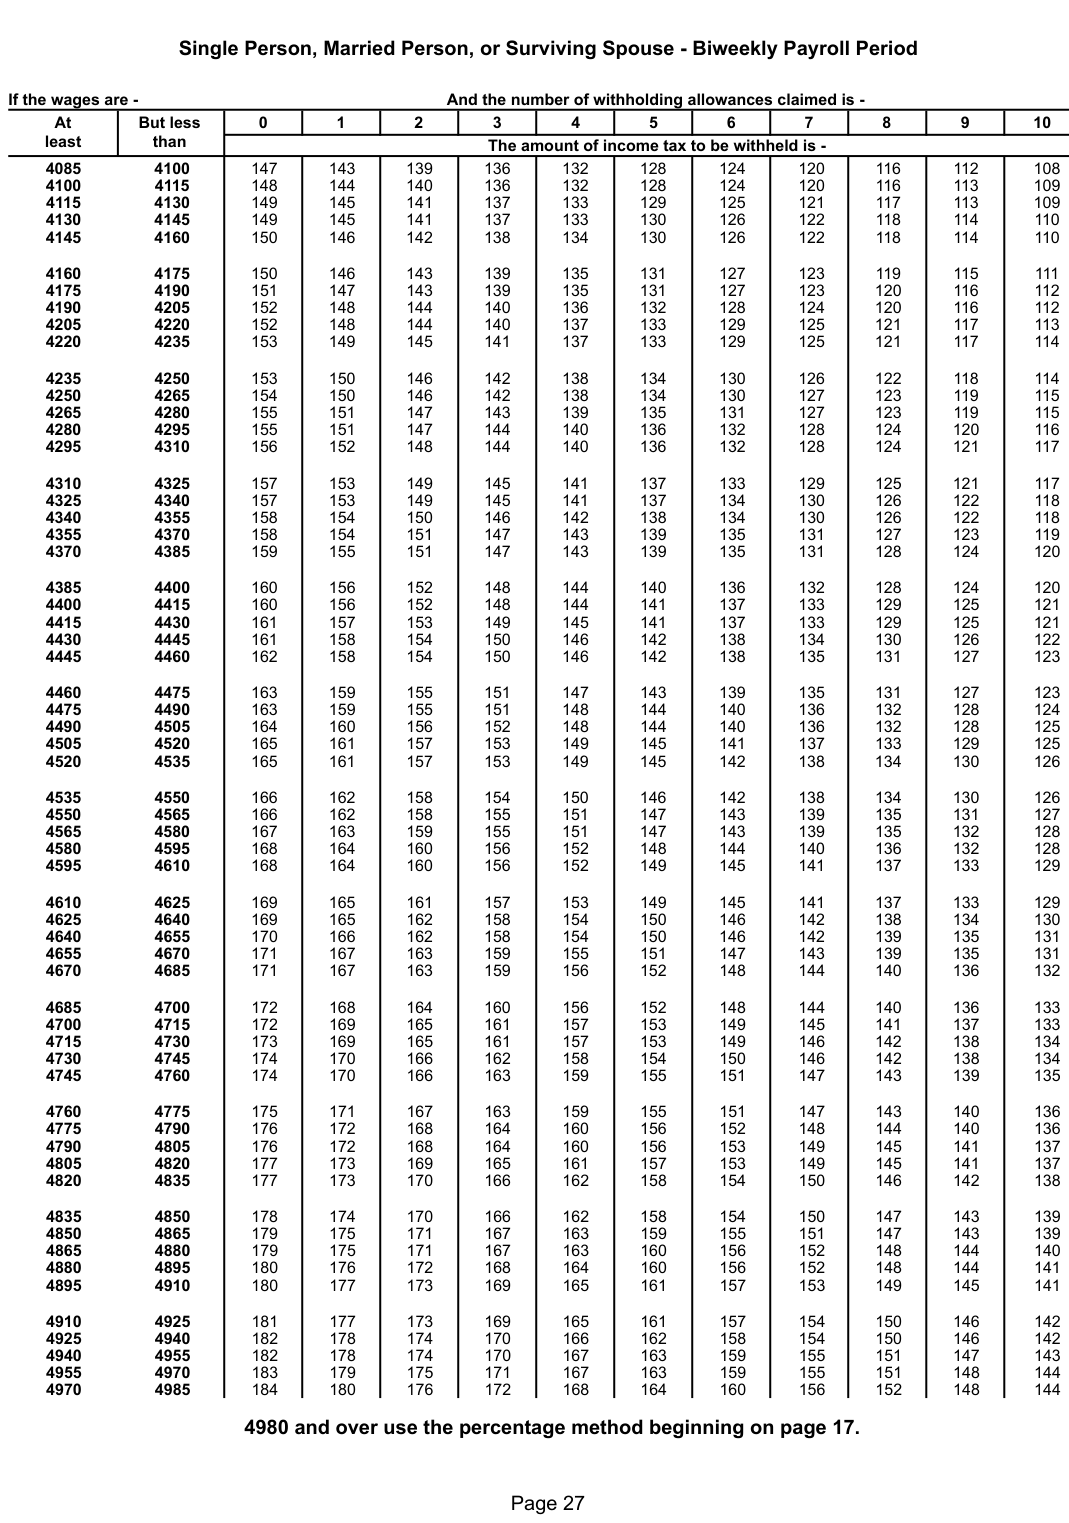
Text version of this table
| Single | Person, | Married | Person, | or Surviv | ing Spo | use - | Biweekly | Payroll | Period | |||
| wages are - | And | the numbe | r of withh | olding | allowances | claimed is | - | |||||
| At B | ut less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
| least | than | The amou | nt of inco | me tax | to be withhe | ld is - | ||||||
| 4085 | 4100 | 147 | 143 | 139 | 136 | 132 | 128 | 124 | 120 | 116 | 112 | 108 |
| 4100 | 4115 | 148 | 144 | 140 | 136 | 132 | 128 | 124 | 120 | 116 | 113 | 109 |
| 4115 | 4130 | 149 | 145 | 141 | 137 | 133 | 129 | 125 | 121 | 117 | 113 | 109 |
| 4130 | 4145 | 149 | 145 | 141 | 137 | 133 | 130 | 126 | 122 | 118 | 114 | 110 |
| 4145 | 4160 | 150 | 146 | 142 | 138 | 134 | 130 | 126 | 122 | 118 | 114 | 110 |
| 4160 | 4175 | 150 | 146 | 143 | 139 | 135 | 131 | 127 | 123 | 119 | 115 | 111 |
| 4175 | 4190 | 151 | 147 | 143 | 139 | 135 | 131 | 127 | 123 | 120 | 116 | 112 |
| 4190 | 4205 | 152 | 148 | 144 | 140 | 136 | 132 | 128 | 124 | 120 | 116 | 112 |
| 4205 | 4220 | 152 | 148 | 144 | 140 | 137 | 133 | 129 | 125 | 121 | 117 | 113 |
| 4220 | 4235 | 153 | 149 | 145 | 141 | 137 | 133 | 129 | 125 | 121 | 117 | 114 |
| 4235 | 4250 | 153 | 150 | 146 | 142 | 138 | 134 | 130 | 126 | 122 | 118 | 114 |
| 4250 | 4265 | 154 | 150 | 146 | 142 | 138 | 134 | 130 | 127 | 123 | 119 | 115 |
| 4265 | 4280 | 155 | 151 | 147 | 143 | 139 | 135 | 131 | 127 | 123 | 119 | 115 |
| 4280 | 4295 | 155 | 151 | 147 | 144 | 140 | 136 | 132 | 128 | 124 | 120 | 116 |
| 4295 | 4310 | 156 | 152 | 148 | 144 | 140 | 136 | 132 | 128 | 124 | 121 | 117 |
| 4310 | 4325 | 157 | 153 | 149 | 145 | 141 | 137 | 133 | 129 | 125 | 121 | 117 |
| 4325 | 4340 | 157 | 153 | 149 | 145 | 141 | 137 | 134 | 130 | 126 | 122 | 118 |
| 4340 | 4355 | 158 | 154 | 150 | 146 | 142 | 138 | 134 | 130 | 126 | 122 | 118 |
| 4355 | 4370 | 158 | 154 | 151 | 147 | 143 | 139 | 135 | 131 | 127 | 123 | 119 |
| 4370 | 4385 | 159 | 155 | 151 | 147 | 143 | 139 | 135 | 131 | 128 | 124 | 120 |
| 4385 | 4400 | 160 | 156 | 152 | 148 | 144 | 140 | 136 | 132 | 128 | 124 | 120 |
| 4400 | 4415 | 160 | 156 | 152 | 148 | 144 | 141 | 137 | 133 | 129 | 125 | 121 |
| 4415 | 4430 | 161 | 157 | 153 | 149 | 145 | 141 | 137 | 133 | 129 | 125 | 121 |
| 4430 | 4445 | 161 | 158 | 154 | 150 | 146 | 142 | 138 | 134 | 130 | 126 | 122 |
| 4445 | 4460 | 162 | 158 | 154 | 150 | 146 | 142 | 138 | 135 | 131 | 127 | 123 |
| 4460 | 4475 | 163 | 159 | 155 | 151 | 147 | 143 | 139 | 135 | 131 | 127 | 123 |
| 4475 | 4490 | 163 | 159 | 155 | 151 | 148 | 144 | 140 | 136 | 132 | 128 | 124 |
| 4490 | 4505 | 164 | 160 | 156 | 152 | 148 | 144 | 140 | 136 | 132 | 128 | 125 |
| 4505 | 4520 | 165 | 161 | 157 | 153 | 149 | 145 | 141 | 137 | 133 | 129 | 125 |
| 4520 | 4535 | 165 | 161 | 157 | 153 | 149 | 145 | 142 | 138 | 134 | 130 | 126 |
| 4535 | 4550 | 166 | 162 | 158 | 154 | 150 | 146 | 142 | 138 | 134 | 130 | 126 |
| 4550 | 4565 | 166 | 162 | 158 | 155 | 151 | 147 | 143 | 139 | 135 | 131 | 127 |
| 4565 | 4580 | 167 | 163 | 159 | 155 | 151 | 147 | 143 | 139 | 135 | 132 | 128 |
| 4580 | 4595 | 168 | 164 | 160 | 156 | 152 | 148 | 144 | 140 | 136 | 132 | 128 |
| 4595 | 4610 | 168 | 164 | 160 | 156 | 152 | 149 | 145 | 141 | 137 | 133 | 129 |
| 4610 | 4625 | 169 | 165 | 161 | 157 | 153 | 149 | 145 | 141 | 137 | 133 | 129 |
| 4625 | 4640 | 169 | 165 | 162 | 158 | 154 | 150 | 146 | 142 | 138 | 134 | 130 |
| 4640 | 4655 | 170 | 166 | 162 | 158 | 154 | 150 | 146 | 142 | 139 | 135 | 131 |
| 4655 | 4670 | 171 | 167 | 163 | 159 | 155 | 151 | 147 | 143 | 139 | 135 | 131 |
| 4670 | 4685 | 171 | 167 | 163 | 159 | 156 | 152 | 148 | 144 | 140 | 136 | 132 |
| 4685 | 4700 | 172 | 168 | 164 | 160 | 156 | 152 | 148 | 144 | 140 | 136 | 133 |
| 4700 | 4715 | 172 | 169 | 165 | 161 | 157 | 153 | 149 | 145 | 141 | 137 | 133 |
| 4715 | 4730 | 173 | 169 | 165 | 161 | 157 | 153 | 149 | 146 | 142 | 138 | 134 |
| 4730 | 4745 | 174 | 170 | 166 | 162 | 158 | 154 | 150 | 146 | 142 | 138 | 134 |
| 4745 | 4760 | 174 | 170 | 166 | 163 | 159 | 155 | 151 | 147 | 143 | 139 | 135 |
| 4760 | 4775 | 175 | 171 | 167 | 163 | 159 | 155 | 151 | 147 | 143 | 140 | 136 |
| 4775 | 4790 | 176 | 172 | 168 | 164 | 160 | 156 | 152 | 148 | 144 | 140 | 136 |
| 4790 | 4805 | 176 | 172 | 168 | 164 | 160 | 156 | 153 | 149 | 145 | 141 | 137 |
| 4805 | 4820 | 177 | 173 | 169 | 165 | 161 | 157 | 153 | 149 | 145 | 141 | 137 |
| 4820 | 4835 | 177 | 173 | 170 | 166 | 162 | 158 | 154 | 150 | 146 | 142 | 138 |
| 4835 | 4850 | 178 | 174 | 170 | 166 | 162 | 158 | 154 | 150 | 147 | 143 | 139 |
| 4850 | 4865 | 179 | 175 | 171 | 167 | 163 | 159 | 155 | 151 | 147 | 143 | 139 |
| 4865 | 4880 | 179 | 175 | 171 | 167 | 163 | 160 | 156 | 152 | 148 | 144 | 140 |
| 4880 | 4895 | 180 | 176 | 172 | 168 | 164 | 160 | 156 | 152 | 148 | 144 | 141 |
| 4895 | 4910 | 180 | 177 | 173 | 169 | 165 | 161 | 157 | 153 | 149 | 145 | 141 |
| 4910 | 4925 | 181 | 177 | 173 | 169 | 165 | 161 | 157 | 154 | 150 | 146 | 142 |
| 4925 | 4940 | 182 | 178 | 174 | 170 | 166 | 162 | 158 | 154 | 150 | 146 | 142 |
| 4940 | 4955 | 182 | 178 | 174 | 170 | 167 | 163 | 159 | 155 | 151 | 147 | 143 |
| 4955 | 4970 | 183 | 179 | 175 | 171 | 167 | 163 | 159 | 155 | 151 | 148 | 144 |
| 4970 | 4985 | 184 | 180 | 176 | 172 | 168 | 164 | 160 | 156 | 152 | 148 | 144 |
| 4980 and | over us | e the pe | rcentage | method | begi | nning on | page 17 | . | ||||
| Page | 27 |
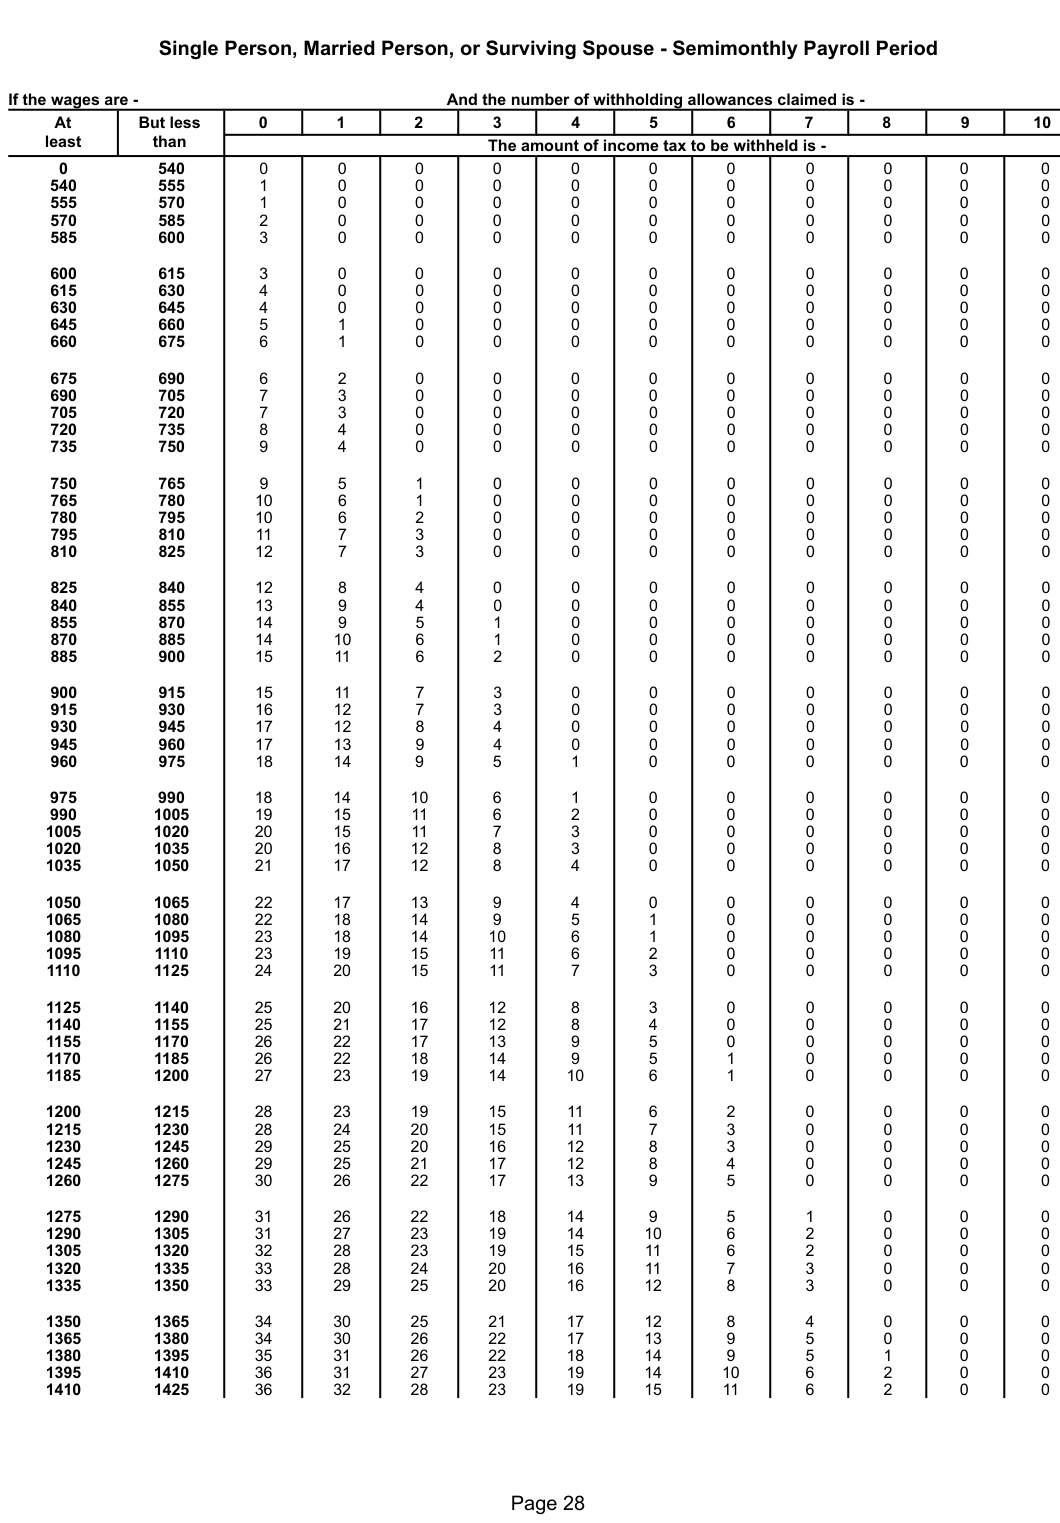
Text version of this table
| Single Per | son, | Married | Person, or | Survivin | g Spous | e - S | emimonthly | Payroll | Period | |||
| wages are - | And t | he numbe | r of withho | lding | allowances clai | med is - | ||||||
| At B | ut less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
| least | than | The amou | nt of incom | e tax | to be withheld | is - | ||||||
| 0 | 540 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 540 | 555 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 555 | 570 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 570 | 585 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 585 | 600 | 3 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 600 | 615 | 3 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 615 | 630 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 630 | 645 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 645 | 660 | 5 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 660 | 675 | 6 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 675 | 690 | 6 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 690 | 705 | 7 | 3 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 705 | 720 | 7 | 3 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 720 | 735 | 8 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 735 | 750 | 9 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 750 | 765 | 9 | 5 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 765 | 780 | 10 | 6 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 780 | 795 | 10 | 6 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 795 | 810 | 11 | 7 | 3 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 810 | 825 | 12 | 7 | 3 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 825 | 840 | 12 | 8 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 840 | 855 | 13 | 9 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 855 | 870 | 14 | 9 | 5 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 870 | 885 | 14 | 10 | 6 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 885 | 900 | 15 | 11 | 6 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 900 | 915 | 15 | 11 | 7 | 3 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 915 | 930 | 16 | 12 | 7 | 3 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 930 | 945 | 17 | 12 | 8 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 945 | 960 | 17 | 13 | 9 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 960 | 975 | 18 | 14 | 9 | 5 | 1 | 0 | 0 | 0 | 0 | 0 | 0 |
| 975 | 990 | 18 | 14 | 10 | 6 | 1 | 0 | 0 | 0 | 0 | 0 | 0 |
| 990 | 1005 | 19 | 15 | 11 | 6 | 2 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1005 | 1020 | 20 | 15 | 11 | 7 | 3 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1020 | 1035 | 20 | 16 | 12 | 8 | 3 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1035 | 1050 | 21 | 17 | 12 | 8 | 4 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1050 | 1065 | 22 | 17 | 13 | 9 | 4 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1065 | 1080 | 22 | 18 | 14 | 9 | 5 | 1 | 0 | 0 | 0 | 0 | 0 |
| 1080 | 1095 | 23 | 18 | 14 | 10 | 6 | 1 | 0 | 0 | 0 | 0 | 0 |
| 1095 | 1110 | 23 | 19 | 15 | 11 | 6 | 2 | 0 | 0 | 0 | 0 | 0 |
| 1110 | 1125 | 24 | 20 | 15 | 11 | 7 | 3 | 0 | 0 | 0 | 0 | 0 |
| 1125 | 1140 | 25 | 20 | 16 | 12 | 8 | 3 | 0 | 0 | 0 | 0 | 0 |
| 1140 | 1155 | 25 | 21 | 17 | 12 | 8 | 4 | 0 | 0 | 0 | 0 | 0 |
| 1155 | 1170 | 26 | 22 | 17 | 13 | 9 | 5 | 0 | 0 | 0 | 0 | 0 |
| 1170 | 1185 | 26 | 22 | 18 | 14 | 9 | 5 | 1 | 0 | 0 | 0 | 0 |
| 1185 | 1200 | 27 | 23 | 19 | 14 | 10 | 6 | 1 | 0 | 0 | 0 | 0 |
| 1200 | 1215 | 28 | 23 | 19 | 15 | 11 | 6 | 2 | 0 | 0 | 0 | 0 |
| 1215 | 1230 | 28 | 24 | 20 | 15 | 11 | 7 | 3 | 0 | 0 | 0 | 0 |
| 1230 | 1245 | 29 | 25 | 20 | 16 | 12 | 8 | 3 | 0 | 0 | 0 | 0 |
| 1245 | 1260 | 29 | 25 | 21 | 17 | 12 | 8 | 4 | 0 | 0 | 0 | 0 |
| 1260 | 1275 | 30 | 26 | 22 | 17 | 13 | 9 | 5 | 0 | 0 | 0 | 0 |
| 1275 | 1290 | 31 | 26 | 22 | 18 | 14 | 9 | 5 | 1 | 0 | 0 | 0 |
| 1290 | 1305 | 31 | 27 | 23 | 19 | 14 | 10 | 6 | 2 | 0 | 0 | 0 |
| 1305 | 1320 | 32 | 28 | 23 | 19 | 15 | 11 | 6 | 2 | 0 | 0 | 0 |
| 1320 | 1335 | 33 | 28 | 24 | 20 | 16 | 11 | 7 | 3 | 0 | 0 | 0 |
| 1335 | 1350 | 33 | 29 | 25 | 20 | 16 | 12 | 8 | 3 | 0 | 0 | 0 |
| 1350 | 1365 | 34 | 30 | 25 | 21 | 17 | 12 | 8 | 4 | 0 | 0 | 0 |
| 1365 | 1380 | 34 | 30 | 26 | 22 | 17 | 13 | 9 | 5 | 0 | 0 | 0 |
| 1380 | 1395 | 35 | 31 | 26 | 22 | 18 | 14 | 9 | 5 | 1 | 0 | 0 |
| 1395 | 1410 | 36 | 31 | 27 | 23 | 19 | 14 | 10 | 6 | 2 | 0 | 0 |
| 1410 | 1425 | 36 | 32 | 28 | 23 | 19 | 15 | 11 | 6 | 2 | 0 | 0 |
| Page | 28 |
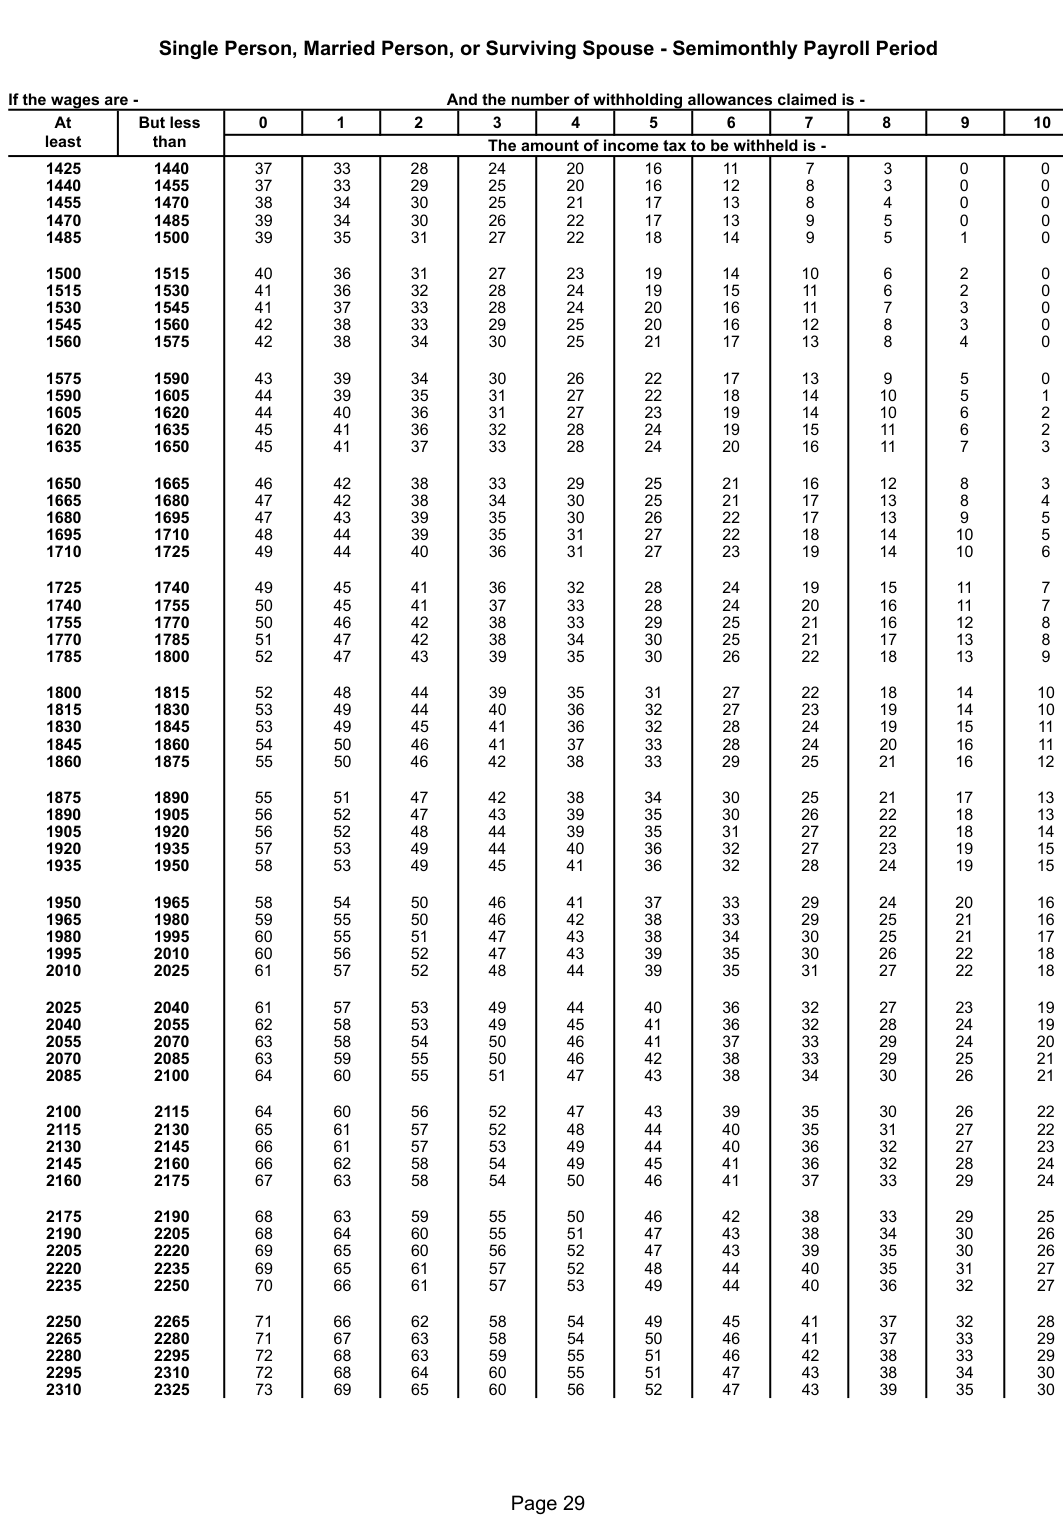
Text version of this table
| Single Per | son, | Married | Person, or | Survivin | g Spous | e - S | emimonthly | Payroll | Period | |||
| wages are - | And t | he numbe | r of withho | lding | allowances cla | imed is - | ||||||
| At B | ut less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
| least | than | The amou | nt of incom | e tax | to be withheld | is - | ||||||
| 1425 | 1440 | 37 | 33 | 28 | 24 | 20 | 16 | 11 | 7 | 3 | 0 | 0 |
| 1440 | 1455 | 37 | 33 | 29 | 25 | 20 | 16 | 12 | 8 | 3 | 0 | 0 |
| 1455 | 1470 | 38 | 34 | 30 | 25 | 21 | 17 | 13 | 8 | 4 | 0 | 0 |
| 1470 | 1485 | 39 | 34 | 30 | 26 | 22 | 17 | 13 | 9 | 5 | 0 | 0 |
| 1485 | 1500 | 39 | 35 | 31 | 27 | 22 | 18 | 14 | 9 | 5 | 1 | 0 |
| 1500 | 1515 | 40 | 36 | 31 | 27 | 23 | 19 | 14 | 10 | 6 | 2 | 0 |
| 1515 | 1530 | 41 | 36 | 32 | 28 | 24 | 19 | 15 | 11 | 6 | 2 | 0 |
| 1530 | 1545 | 41 | 37 | 33 | 28 | 24 | 20 | 16 | 11 | 7 | 3 | 0 |
| 1545 | 1560 | 42 | 38 | 33 | 29 | 25 | 20 | 16 | 12 | 8 | 3 | 0 |
| 1560 | 1575 | 42 | 38 | 34 | 30 | 25 | 21 | 17 | 13 | 8 | 4 | 0 |
| 1575 | 1590 | 43 | 39 | 34 | 30 | 26 | 22 | 17 | 13 | 9 | 5 | 0 |
| 1590 | 1605 | 44 | 39 | 35 | 31 | 27 | 22 | 18 | 14 | 10 | 5 | 1 |
| 1605 | 1620 | 44 | 40 | 36 | 31 | 27 | 23 | 19 | 14 | 10 | 6 | 2 |
| 1620 | 1635 | 45 | 41 | 36 | 32 | 28 | 24 | 19 | 15 | 11 | 6 | 2 |
| 1635 | 1650 | 45 | 41 | 37 | 33 | 28 | 24 | 20 | 16 | 11 | 7 | 3 |
| 1650 | 1665 | 46 | 42 | 38 | 33 | 29 | 25 | 21 | 16 | 12 | 8 | 3 |
| 1665 | 1680 | 47 | 42 | 38 | 34 | 30 | 25 | 21 | 17 | 13 | 8 | 4 |
| 1680 | 1695 | 47 | 43 | 39 | 35 | 30 | 26 | 22 | 17 | 13 | 9 | 5 |
| 1695 | 1710 | 48 | 44 | 39 | 35 | 31 | 27 | 22 | 18 | 14 | 10 | 5 |
| 1710 | 1725 | 49 | 44 | 40 | 36 | 31 | 27 | 23 | 19 | 14 | 10 | 6 |
| 1725 | 1740 | 49 | 45 | 41 | 36 | 32 | 28 | 24 | 19 | 15 | 11 | 7 |
| 1740 | 1755 | 50 | 45 | 41 | 37 | 33 | 28 | 24 | 20 | 16 | 11 | 7 |
| 1755 | 1770 | 50 | 46 | 42 | 38 | 33 | 29 | 25 | 21 | 16 | 12 | 8 |
| 1770 | 1785 | 51 | 47 | 42 | 38 | 34 | 30 | 25 | 21 | 17 | 13 | 8 |
| 1785 | 1800 | 52 | 47 | 43 | 39 | 35 | 30 | 26 | 22 | 18 | 13 | 9 |
| 1800 | 1815 | 52 | 48 | 44 | 39 | 35 | 31 | 27 | 22 | 18 | 14 | 10 |
| 1815 | 1830 | 53 | 49 | 44 | 40 | 36 | 32 | 27 | 23 | 19 | 14 | 10 |
| 1830 | 1845 | 53 | 49 | 45 | 41 | 36 | 32 | 28 | 24 | 19 | 15 | 11 |
| 1845 | 1860 | 54 | 50 | 46 | 41 | 37 | 33 | 28 | 24 | 20 | 16 | 11 |
| 1860 | 1875 | 55 | 50 | 46 | 42 | 38 | 33 | 29 | 25 | 21 | 16 | 12 |
| 1875 | 1890 | 55 | 51 | 47 | 42 | 38 | 34 | 30 | 25 | 21 | 17 | 13 |
| 1890 | 1905 | 56 | 52 | 47 | 43 | 39 | 35 | 30 | 26 | 22 | 18 | 13 |
| 1905 | 1920 | 56 | 52 | 48 | 44 | 39 | 35 | 31 | 27 | 22 | 18 | 14 |
| 1920 | 1935 | 57 | 53 | 49 | 44 | 40 | 36 | 32 | 27 | 23 | 19 | 15 |
| 1935 | 1950 | 58 | 53 | 49 | 45 | 41 | 36 | 32 | 28 | 24 | 19 | 15 |
| 1950 | 1965 | 58 | 54 | 50 | 46 | 41 | 37 | 33 | 29 | 24 | 20 | 16 |
| 1965 | 1980 | 59 | 55 | 50 | 46 | 42 | 38 | 33 | 29 | 25 | 21 | 16 |
| 1980 | 1995 | 60 | 55 | 51 | 47 | 43 | 38 | 34 | 30 | 25 | 21 | 17 |
| 1995 | 2010 | 60 | 56 | 52 | 47 | 43 | 39 | 35 | 30 | 26 | 22 | 18 |
| 2010 | 2025 | 61 | 57 | 52 | 48 | 44 | 39 | 35 | 31 | 27 | 22 | 18 |
| 2025 | 2040 | 61 | 57 | 53 | 49 | 44 | 40 | 36 | 32 | 27 | 23 | 19 |
| 2040 | 2055 | 62 | 58 | 53 | 49 | 45 | 41 | 36 | 32 | 28 | 24 | 19 |
| 2055 | 2070 | 63 | 58 | 54 | 50 | 46 | 41 | 37 | 33 | 29 | 24 | 20 |
| 2070 | 2085 | 63 | 59 | 55 | 50 | 46 | 42 | 38 | 33 | 29 | 25 | 21 |
| 2085 | 2100 | 64 | 60 | 55 | 51 | 47 | 43 | 38 | 34 | 30 | 26 | 21 |
| 2100 | 2115 | 64 | 60 | 56 | 52 | 47 | 43 | 39 | 35 | 30 | 26 | 22 |
| 2115 | 2130 | 65 | 61 | 57 | 52 | 48 | 44 | 40 | 35 | 31 | 27 | 22 |
| 2130 | 2145 | 66 | 61 | 57 | 53 | 49 | 44 | 40 | 36 | 32 | 27 | 23 |
| 2145 | 2160 | 66 | 62 | 58 | 54 | 49 | 45 | 41 | 36 | 32 | 28 | 24 |
| 2160 | 2175 | 67 | 63 | 58 | 54 | 50 | 46 | 41 | 37 | 33 | 29 | 24 |
| 2175 | 2190 | 68 | 63 | 59 | 55 | 50 | 46 | 42 | 38 | 33 | 29 | 25 |
| 2190 | 2205 | 68 | 64 | 60 | 55 | 51 | 47 | 43 | 38 | 34 | 30 | 26 |
| 2205 | 2220 | 69 | 65 | 60 | 56 | 52 | 47 | 43 | 39 | 35 | 30 | 26 |
| 2220 | 2235 | 69 | 65 | 61 | 57 | 52 | 48 | 44 | 40 | 35 | 31 | 27 |
| 2235 | 2250 | 70 | 66 | 61 | 57 | 53 | 49 | 44 | 40 | 36 | 32 | 27 |
| 2250 | 2265 | 71 | 66 | 62 | 58 | 54 | 49 | 45 | 41 | 37 | 32 | 28 |
| 2265 | 2280 | 71 | 67 | 63 | 58 | 54 | 50 | 46 | 41 | 37 | 33 | 29 |
| 2280 | 2295 | 72 | 68 | 63 | 59 | 55 | 51 | 46 | 42 | 38 | 33 | 29 |
| 2295 | 2310 | 72 | 68 | 64 | 60 | 55 | 51 | 47 | 43 | 38 | 34 | 30 |
| 2310 | 2325 | 73 | 69 | 65 | 60 | 56 | 52 | 47 | 43 | 39 | 35 | 30 |
| Page | 29 |
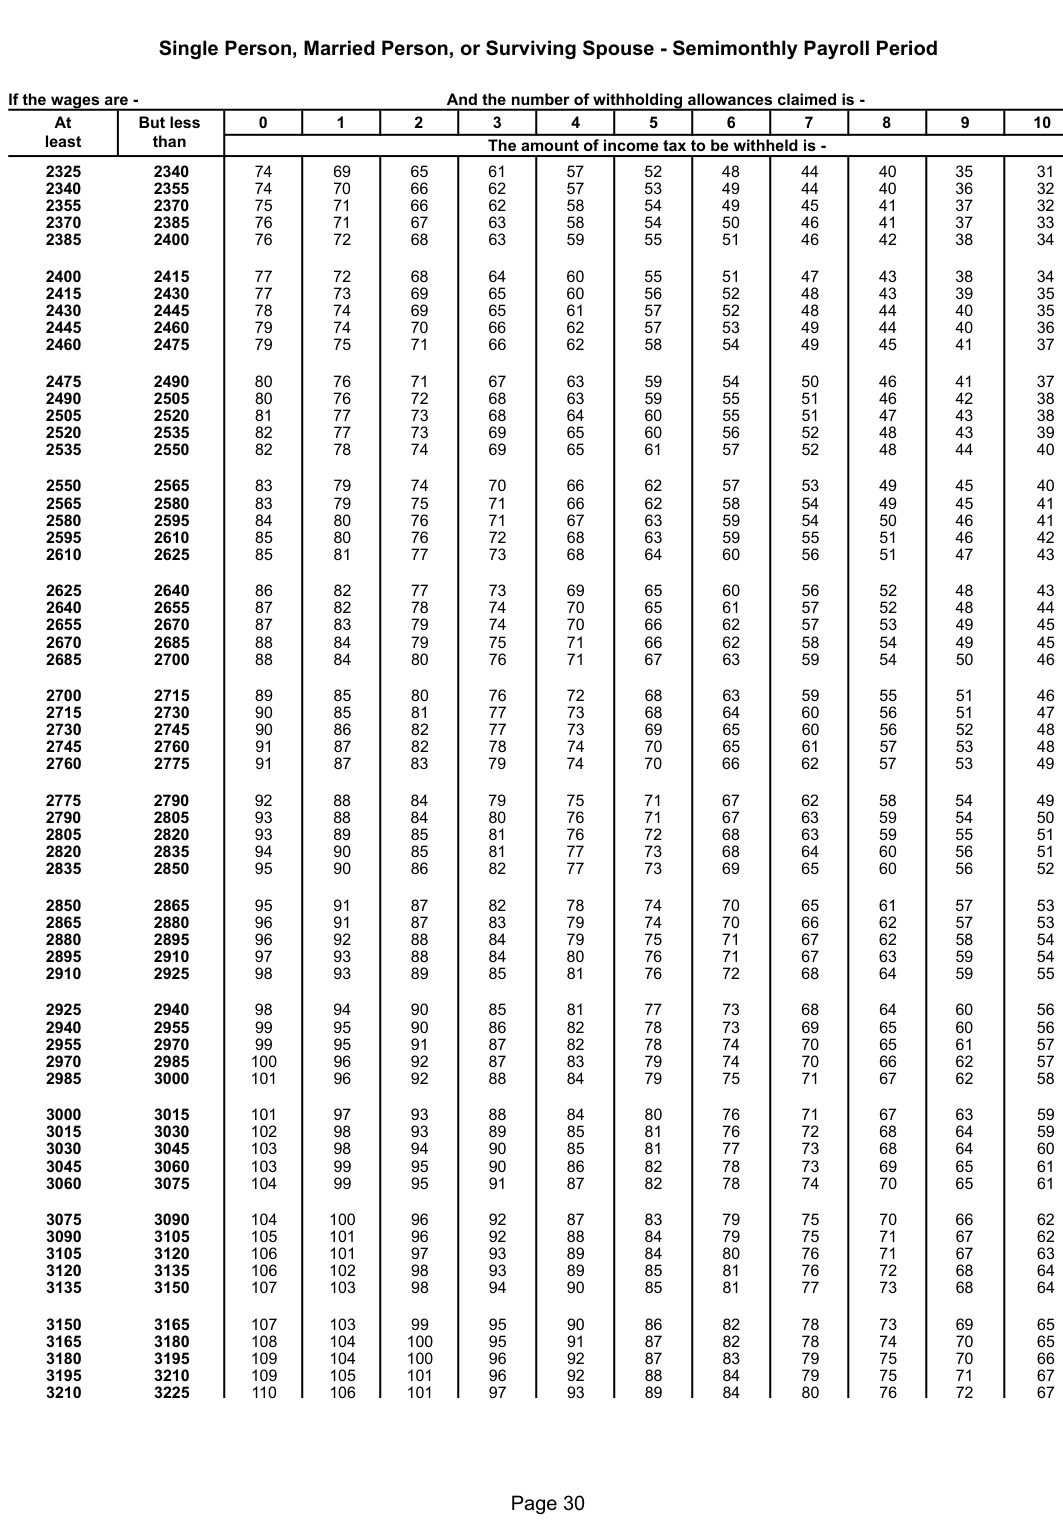
Text version of this table
| Single Pe | rson, | Married | Person, or | Survivin | g Spous | e - S | emimonthly | Payroll | Period | |||
| wages are - | And t | he numbe | r of withho | lding | allowances cla | imed is - | ||||||
| At B | ut less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
| least | than | The amou | nt of incom | e tax | to be withheld | is - | ||||||
| 2325 | 2340 | 74 | 69 | 65 | 61 | 57 | 52 | 48 | 44 | 40 | 35 | 31 |
| 2340 | 2355 | 74 | 70 | 66 | 62 | 57 | 53 | 49 | 44 | 40 | 36 | 32 |
| 2355 | 2370 | 75 | 71 | 66 | 62 | 58 | 54 | 49 | 45 | 41 | 37 | 32 |
| 2370 | 2385 | 76 | 71 | 67 | 63 | 58 | 54 | 50 | 46 | 41 | 37 | 33 |
| 2385 | 2400 | 76 | 72 | 68 | 63 | 59 | 55 | 51 | 46 | 42 | 38 | 34 |
| 2400 | 2415 | 77 | 72 | 68 | 64 | 60 | 55 | 51 | 47 | 43 | 38 | 34 |
| 2415 | 2430 | 77 | 73 | 69 | 65 | 60 | 56 | 52 | 48 | 43 | 39 | 35 |
| 2430 | 2445 | 78 | 74 | 69 | 65 | 61 | 57 | 52 | 48 | 44 | 40 | 35 |
| 2445 | 2460 | 79 | 74 | 70 | 66 | 62 | 57 | 53 | 49 | 44 | 40 | 36 |
| 2460 | 2475 | 79 | 75 | 71 | 66 | 62 | 58 | 54 | 49 | 45 | 41 | 37 |
| 2475 | 2490 | 80 | 76 | 71 | 67 | 63 | 59 | 54 | 50 | 46 | 41 | 37 |
| 2490 | 2505 | 80 | 76 | 72 | 68 | 63 | 59 | 55 | 51 | 46 | 42 | 38 |
| 2505 | 2520 | 81 | 77 | 73 | 68 | 64 | 60 | 55 | 51 | 47 | 43 | 38 |
| 2520 | 2535 | 82 | 77 | 73 | 69 | 65 | 60 | 56 | 52 | 48 | 43 | 39 |
| 2535 | 2550 | 82 | 78 | 74 | 69 | 65 | 61 | 57 | 52 | 48 | 44 | 40 |
| 2550 | 2565 | 83 | 79 | 74 | 70 | 66 | 62 | 57 | 53 | 49 | 45 | 40 |
| 2565 | 2580 | 83 | 79 | 75 | 71 | 66 | 62 | 58 | 54 | 49 | 45 | 41 |
| 2580 | 2595 | 84 | 80 | 76 | 71 | 67 | 63 | 59 | 54 | 50 | 46 | 41 |
| 2595 | 2610 | 85 | 80 | 76 | 72 | 68 | 63 | 59 | 55 | 51 | 46 | 42 |
| 2610 | 2625 | 85 | 81 | 77 | 73 | 68 | 64 | 60 | 56 | 51 | 47 | 43 |
| 2625 | 2640 | 86 | 82 | 77 | 73 | 69 | 65 | 60 | 56 | 52 | 48 | 43 |
| 2640 | 2655 | 87 | 82 | 78 | 74 | 70 | 65 | 61 | 57 | 52 | 48 | 44 |
| 2655 | 2670 | 87 | 83 | 79 | 74 | 70 | 66 | 62 | 57 | 53 | 49 | 45 |
| 2670 | 2685 | 88 | 84 | 79 | 75 | 71 | 66 | 62 | 58 | 54 | 49 | 45 |
| 2685 | 2700 | 88 | 84 | 80 | 76 | 71 | 67 | 63 | 59 | 54 | 50 | 46 |
| 2700 | 2715 | 89 | 85 | 80 | 76 | 72 | 68 | 63 | 59 | 55 | 51 | 46 |
| 2715 | 2730 | 90 | 85 | 81 | 77 | 73 | 68 | 64 | 60 | 56 | 51 | 47 |
| 2730 | 2745 | 90 | 86 | 82 | 77 | 73 | 69 | 65 | 60 | 56 | 52 | 48 |
| 2745 | 2760 | 91 | 87 | 82 | 78 | 74 | 70 | 65 | 61 | 57 | 53 | 48 |
| 2760 | 2775 | 91 | 87 | 83 | 79 | 74 | 70 | 66 | 62 | 57 | 53 | 49 |
| 2775 | 2790 | 92 | 88 | 84 | 79 | 75 | 71 | 67 | 62 | 58 | 54 | 49 |
| 2790 | 2805 | 93 | 88 | 84 | 80 | 76 | 71 | 67 | 63 | 59 | 54 | 50 |
| 2805 | 2820 | 93 | 89 | 85 | 81 | 76 | 72 | 68 | 63 | 59 | 55 | 51 |
| 2820 | 2835 | 94 | 90 | 85 | 81 | 77 | 73 | 68 | 64 | 60 | 56 | 51 |
| 2835 | 2850 | 95 | 90 | 86 | 82 | 77 | 73 | 69 | 65 | 60 | 56 | 52 |
| 2850 | 2865 | 95 | 91 | 87 | 82 | 78 | 74 | 70 | 65 | 61 | 57 | 53 |
| 2865 | 2880 | 96 | 91 | 87 | 83 | 79 | 74 | 70 | 66 | 62 | 57 | 53 |
| 2880 | 2895 | 96 | 92 | 88 | 84 | 79 | 75 | 71 | 67 | 62 | 58 | 54 |
| 2895 | 2910 | 97 | 93 | 88 | 84 | 80 | 76 | 71 | 67 | 63 | 59 | 54 |
| 2910 | 2925 | 98 | 93 | 89 | 85 | 81 | 76 | 72 | 68 | 64 | 59 | 55 |
| 2925 | 2940 | 98 | 94 | 90 | 85 | 81 | 77 | 73 | 68 | 64 | 60 | 56 |
| 2940 | 2955 | 99 | 95 | 90 | 86 | 82 | 78 | 73 | 69 | 65 | 60 | 56 |
| 2955 | 2970 | 99 | 95 | 91 | 87 | 82 | 78 | 74 | 70 | 65 | 61 | 57 |
| 2970 | 2985 | 100 | 96 | 92 | 87 | 83 | 79 | 74 | 70 | 66 | 62 | 57 |
| 2985 | 3000 | 101 | 96 | 92 | 88 | 84 | 79 | 75 | 71 | 67 | 62 | 58 |
| 3000 | 3015 | 101 | 97 | 93 | 88 | 84 | 80 | 76 | 71 | 67 | 63 | 59 |
| 3015 | 3030 | 102 | 98 | 93 | 89 | 85 | 81 | 76 | 72 | 68 | 64 | 59 |
| 3030 | 3045 | 103 | 98 | 94 | 90 | 85 | 81 | 77 | 73 | 68 | 64 | 60 |
| 3045 | 3060 | 103 | 99 | 95 | 90 | 86 | 82 | 78 | 73 | 69 | 65 | 61 |
| 3060 | 3075 | 104 | 99 | 95 | 91 | 87 | 82 | 78 | 74 | 70 | 65 | 61 |
| 3075 | 3090 | 104 | 100 | 96 | 92 | 87 | 83 | 79 | 75 | 70 | 66 | 62 |
| 3090 | 3105 | 105 | 101 | 96 | 92 | 88 | 84 | 79 | 75 | 71 | 67 | 62 |
| 3105 | 3120 | 106 | 101 | 97 | 93 | 89 | 84 | 80 | 76 | 71 | 67 | 63 |
| 3120 | 3135 | 106 | 102 | 98 | 93 | 89 | 85 | 81 | 76 | 72 | 68 | 64 |
| 3135 | 3150 | 107 | 103 | 98 | 94 | 90 | 85 | 81 | 77 | 73 | 68 | 64 |
| 3150 | 3165 | 107 | 103 | 99 | 95 | 90 | 86 | 82 | 78 | 73 | 69 | 65 |
| 3165 | 3180 | 108 | 104 | 100 | 95 | 91 | 87 | 82 | 78 | 74 | 70 | 65 |
| 3180 | 3195 | 109 | 104 | 100 | 96 | 92 | 87 | 83 | 79 | 75 | 70 | 66 |
| 3195 | 3210 | 109 | 105 | 101 | 96 | 92 | 88 | 84 | 79 | 75 | 71 | 67 |
| 3210 | 3225 | 110 | 106 | 101 | 97 | 93 | 89 | 84 | 80 | 76 | 72 | 67 |
| Page | 30 |
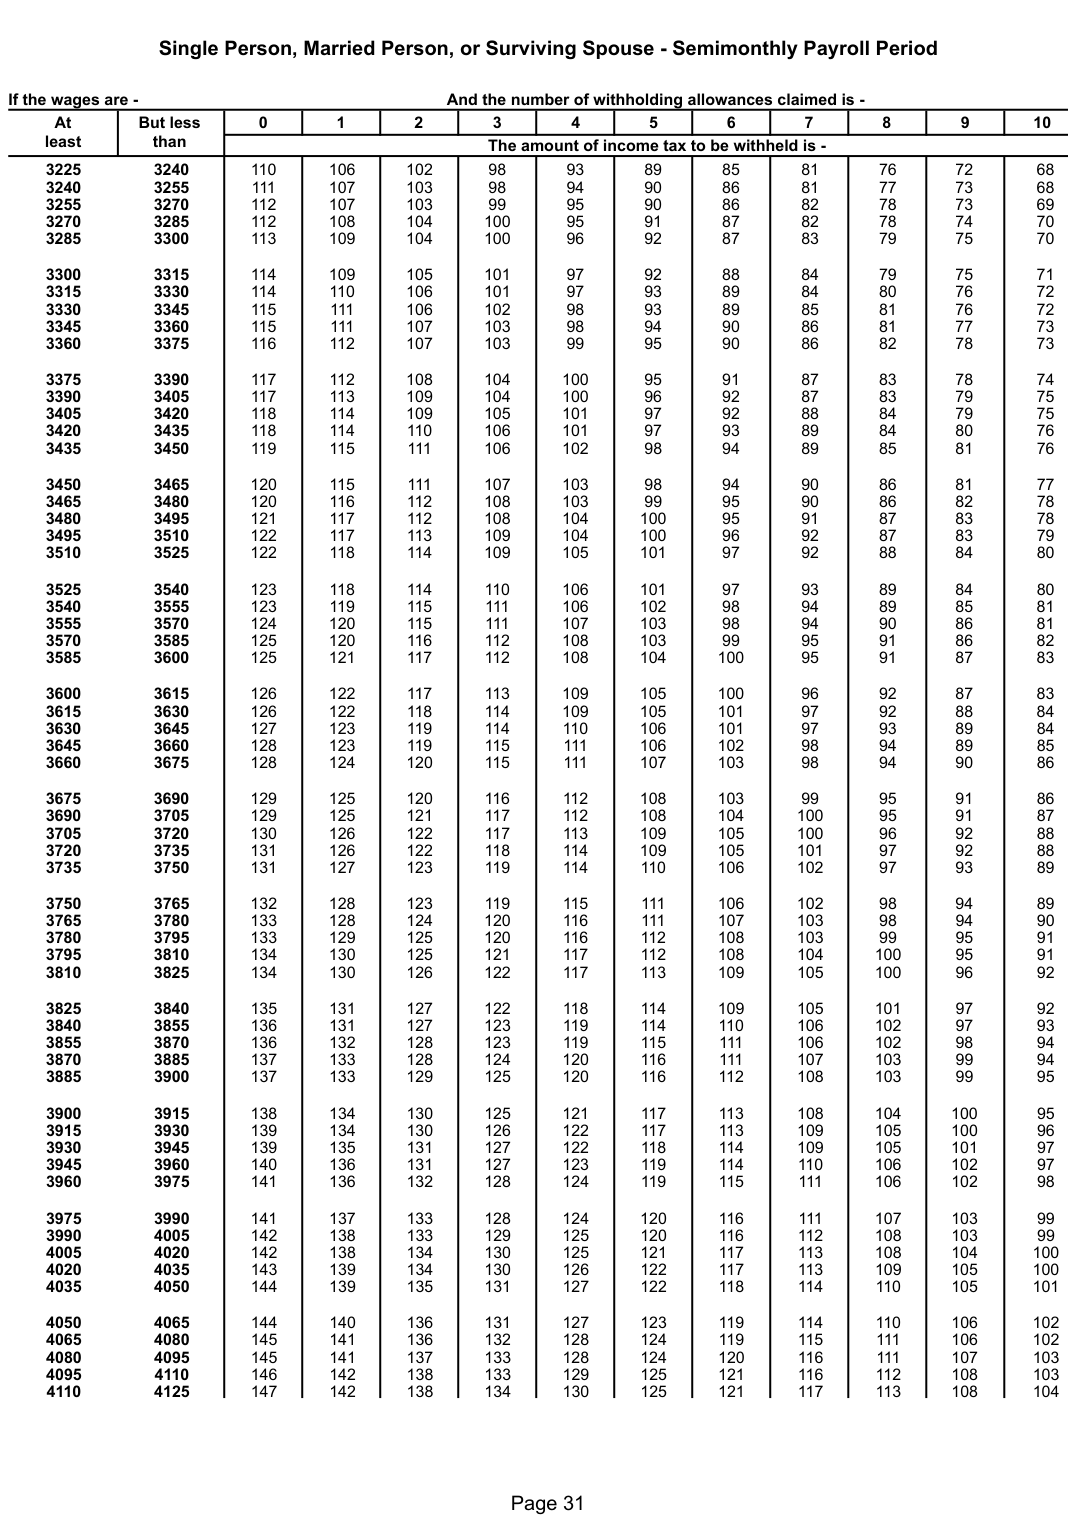
Text version of this table
| Single Pe | rson, | Married | Person, or | Survivin | g Spous | e - S | emimonth | ly Payroll | Period | |||
| wages are - | And | the numbe | r of withh | olding | allowances | claimed is - | ||||||
| At B | ut less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
| least | than | The amou | nt of inco | me tax | to be withh | eld is - | ||||||
| 3225 | 3240 | 110 | 106 | 102 | 98 | 93 | 89 | 85 | 81 | 76 | 72 | 68 |
| 3240 | 3255 | 111 | 107 | 103 | 98 | 94 | 90 | 86 | 81 | 77 | 73 | 68 |
| 3255 | 3270 | 112 | 107 | 103 | 99 | 95 | 90 | 86 | 82 | 78 | 73 | 69 |
| 3270 | 3285 | 112 | 108 | 104 | 100 | 95 | 91 | 87 | 82 | 78 | 74 | 70 |
| 3285 | 3300 | 113 | 109 | 104 | 100 | 96 | 92 | 87 | 83 | 79 | 75 | 70 |
| 3300 | 3315 | 114 | 109 | 105 | 101 | 97 | 92 | 88 | 84 | 79 | 75 | 71 |
| 3315 | 3330 | 114 | 110 | 106 | 101 | 97 | 93 | 89 | 84 | 80 | 76 | 72 |
| 3330 | 3345 | 115 | 111 | 106 | 102 | 98 | 93 | 89 | 85 | 81 | 76 | 72 |
| 3345 | 3360 | 115 | 111 | 107 | 103 | 98 | 94 | 90 | 86 | 81 | 77 | 73 |
| 3360 | 3375 | 116 | 112 | 107 | 103 | 99 | 95 | 90 | 86 | 82 | 78 | 73 |
| 3375 | 3390 | 117 | 112 | 108 | 104 | 100 | 95 | 91 | 87 | 83 | 78 | 74 |
| 3390 | 3405 | 117 | 113 | 109 | 104 | 100 | 96 | 92 | 87 | 83 | 79 | 75 |
| 3405 | 3420 | 118 | 114 | 109 | 105 | 101 | 97 | 92 | 88 | 84 | 79 | 75 |
| 3420 | 3435 | 118 | 114 | 110 | 106 | 101 | 97 | 93 | 89 | 84 | 80 | 76 |
| 3435 | 3450 | 119 | 115 | 111 | 106 | 102 | 98 | 94 | 89 | 85 | 81 | 76 |
| 3450 | 3465 | 120 | 115 | 111 | 107 | 103 | 98 | 94 | 90 | 86 | 81 | 77 |
| 3465 | 3480 | 120 | 116 | 112 | 108 | 103 | 99 | 95 | 90 | 86 | 82 | 78 |
| 3480 | 3495 | 121 | 117 | 112 | 108 | 104 | 100 | 95 | 91 | 87 | 83 | 78 |
| 3495 | 3510 | 122 | 117 | 113 | 109 | 104 | 100 | 96 | 92 | 87 | 83 | 79 |
| 3510 | 3525 | 122 | 118 | 114 | 109 | 105 | 101 | 97 | 92 | 88 | 84 | 80 |
| 3525 | 3540 | 123 | 118 | 114 | 110 | 106 | 101 | 97 | 93 | 89 | 84 | 80 |
| 3540 | 3555 | 123 | 119 | 115 | 111 | 106 | 102 | 98 | 94 | 89 | 85 | 81 |
| 3555 | 3570 | 124 | 120 | 115 | 111 | 107 | 103 | 98 | 94 | 90 | 86 | 81 |
| 3570 | 3585 | 125 | 120 | 116 | 112 | 108 | 103 | 99 | 95 | 91 | 86 | 82 |
| 3585 | 3600 | 125 | 121 | 117 | 112 | 108 | 104 | 100 | 95 | 91 | 87 | 83 |
| 3600 | 3615 | 126 | 122 | 117 | 113 | 109 | 105 | 100 | 96 | 92 | 87 | 83 |
| 3615 | 3630 | 126 | 122 | 118 | 114 | 109 | 105 | 101 | 97 | 92 | 88 | 84 |
| 3630 | 3645 | 127 | 123 | 119 | 114 | 110 | 106 | 101 | 97 | 93 | 89 | 84 |
| 3645 | 3660 | 128 | 123 | 119 | 115 | 111 | 106 | 102 | 98 | 94 | 89 | 85 |
| 3660 | 3675 | 128 | 124 | 120 | 115 | 111 | 107 | 103 | 98 | 94 | 90 | 86 |
| 3675 | 3690 | 129 | 125 | 120 | 116 | 112 | 108 | 103 | 99 | 95 | 91 | 86 |
| 3690 | 3705 | 129 | 125 | 121 | 117 | 112 | 108 | 104 | 100 | 95 | 91 | 87 |
| 3705 | 3720 | 130 | 126 | 122 | 117 | 113 | 109 | 105 | 100 | 96 | 92 | 88 |
| 3720 | 3735 | 131 | 126 | 122 | 118 | 114 | 109 | 105 | 101 | 97 | 92 | 88 |
| 3735 | 3750 | 131 | 127 | 123 | 119 | 114 | 110 | 106 | 102 | 97 | 93 | 89 |
| 3750 | 3765 | 132 | 128 | 123 | 119 | 115 | 111 | 106 | 102 | 98 | 94 | 89 |
| 3765 | 3780 | 133 | 128 | 124 | 120 | 116 | 111 | 107 | 103 | 98 | 94 | 90 |
| 3780 | 3795 | 133 | 129 | 125 | 120 | 116 | 112 | 108 | 103 | 99 | 95 | 91 |
| 3795 | 3810 | 134 | 130 | 125 | 121 | 117 | 112 | 108 | 104 | 100 | 95 | 91 |
| 3810 | 3825 | 134 | 130 | 126 | 122 | 117 | 113 | 109 | 105 | 100 | 96 | 92 |
| 3825 | 3840 | 135 | 131 | 127 | 122 | 118 | 114 | 109 | 105 | 101 | 97 | 92 |
| 3840 | 3855 | 136 | 131 | 127 | 123 | 119 | 114 | 110 | 106 | 102 | 97 | 93 |
| 3855 | 3870 | 136 | 132 | 128 | 123 | 119 | 115 | 111 | 106 | 102 | 98 | 94 |
| 3870 | 3885 | 137 | 133 | 128 | 124 | 120 | 116 | 111 | 107 | 103 | 99 | 94 |
| 3885 | 3900 | 137 | 133 | 129 | 125 | 120 | 116 | 112 | 108 | 103 | 99 | 95 |
| 3900 | 3915 | 138 | 134 | 130 | 125 | 121 | 117 | 113 | 108 | 104 | 100 | 95 |
| 3915 | 3930 | 139 | 134 | 130 | 126 | 122 | 117 | 113 | 109 | 105 | 100 | 96 |
| 3930 | 3945 | 139 | 135 | 131 | 127 | 122 | 118 | 114 | 109 | 105 | 101 | 97 |
| 3945 | 3960 | 140 | 136 | 131 | 127 | 123 | 119 | 114 | 110 | 106 | 102 | 97 |
| 3960 | 3975 | 141 | 136 | 132 | 128 | 124 | 119 | 115 | 111 | 106 | 102 | 98 |
| 3975 | 3990 | 141 | 137 | 133 | 128 | 124 | 120 | 116 | 111 | 107 | 103 | 99 |
| 3990 | 4005 | 142 | 138 | 133 | 129 | 125 | 120 | 116 | 112 | 108 | 103 | 99 |
| 4005 | 4020 | 142 | 138 | 134 | 130 | 125 | 121 | 117 | 113 | 108 | 104 | 100 |
| 4020 | 4035 | 143 | 139 | 134 | 130 | 126 | 122 | 117 | 113 | 109 | 105 | 100 |
| 4035 | 4050 | 144 | 139 | 135 | 131 | 127 | 122 | 118 | 114 | 110 | 105 | 101 |
| 4050 | 4065 | 144 | 140 | 136 | 131 | 127 | 123 | 119 | 114 | 110 | 106 | 102 |
| 4065 | 4080 | 145 | 141 | 136 | 132 | 128 | 124 | 119 | 115 | 111 | 106 | 102 |
| 4080 | 4095 | 145 | 141 | 137 | 133 | 128 | 124 | 120 | 116 | 111 | 107 | 103 |
| 4095 | 4110 | 146 | 142 | 138 | 133 | 129 | 125 | 121 | 116 | 112 | 108 | 103 |
| 4110 | 4125 | 147 | 142 | 138 | 134 | 130 | 125 | 121 | 117 | 113 | 108 | 104 |
| Page | 31 |
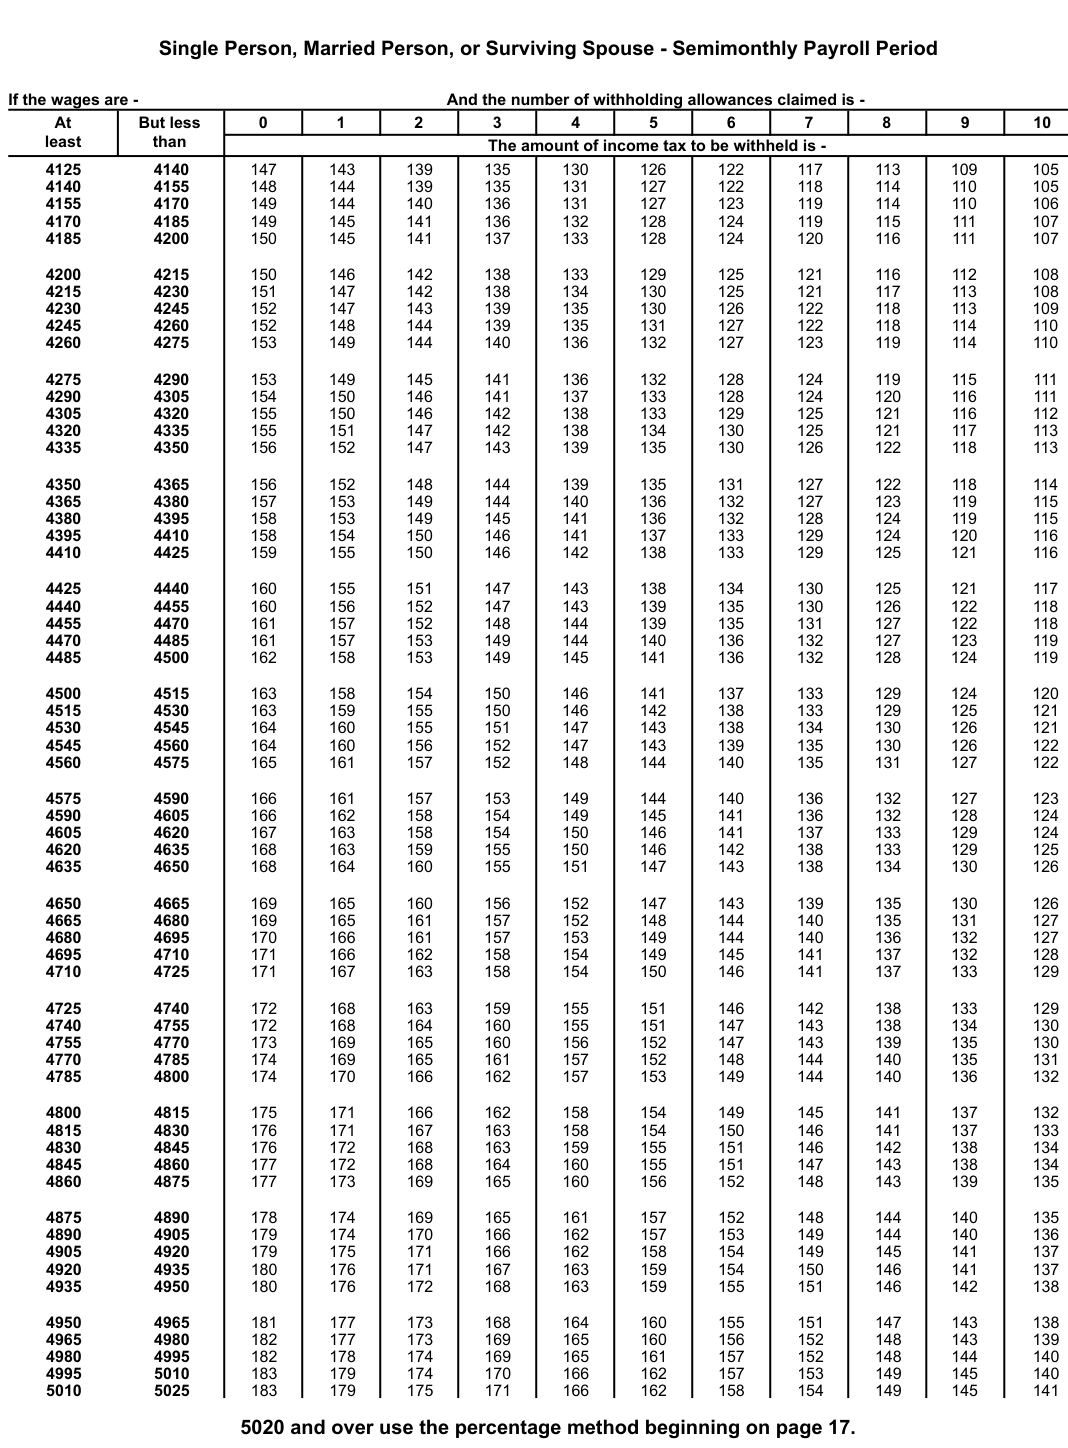
Text version of this table
| Single | Person, | Married | Person, or | Surviving Spous | e - S | emimonth | ly Payroll | Period | |||
| wages are - | And | the number of withh | olding | allowances | claimed is - | ||||||
| At B | ut less | 0 | 1 | 2 | 3 4 | 5 | 6 | 7 | 8 | 9 | 10 |
| least | than | The amount of inco | me tax | to be withh | eld is - | ||||||
| 4125 | 4140 | 147 | 143 | 139 | 135 130 | 126 | 122 | 117 | 113 | 109 | 105 |
| 4140 | 4155 | 148 | 144 | 139 | 135 131 | 127 | 122 | 118 | 114 | 110 | 105 |
| 4155 | 4170 | 149 | 144 | 140 | 136 131 | 127 | 123 | 119 | 114 | 110 | 106 |
| 4170 | 4185 | 149 | 145 | 141 | 136 132 | 128 | 124 | 119 | 115 | 111 | 107 |
| 4185 | 4200 | 150 | 145 | 141 | 137 133 | 128 | 124 | 120 | 116 | 111 | 107 |
| 4200 | 4215 | 150 | 146 | 142 | 138 133 | 129 | 125 | 121 | 116 | 112 | 108 |
| 4215 | 4230 | 151 | 147 | 142 | 138 134 | 130 | 125 | 121 | 117 | 113 | 108 |
| 4230 | 4245 | 152 | 147 | 143 | 139 135 | 130 | 126 | 122 | 118 | 113 | 109 |
| 4245 | 4260 | 152 | 148 | 144 | 139 135 | 131 | 127 | 122 | 118 | 114 | 110 |
| 4260 | 4275 | 153 | 149 | 144 | 140 136 | 132 | 127 | 123 | 119 | 114 | 110 |
| 4275 | 4290 | 153 | 149 | 145 | 141 136 | 132 | 128 | 124 | 119 | 115 | 111 |
| 4290 | 4305 | 154 | 150 | 146 | 141 137 | 133 | 128 | 124 | 120 | 116 | 111 |
| 4305 | 4320 | 155 | 150 | 146 | 142 138 | 133 | 129 | 125 | 121 | 116 | 112 |
| 4320 | 4335 | 155 | 151 | 147 | 142 138 | 134 | 130 | 125 | 121 | 117 | 113 |
| 4335 | 4350 | 156 | 152 | 147 | 143 139 | 135 | 130 | 126 | 122 | 118 | 113 |
| 4350 | 4365 | 156 | 152 | 148 | 144 139 | 135 | 131 | 127 | 122 | 118 | 114 |
| 4365 | 4380 | 157 | 153 | 149 | 144 140 | 136 | 132 | 127 | 123 | 119 | 115 |
| 4380 | 4395 | 158 | 153 | 149 | 145 141 | 136 | 132 | 128 | 124 | 119 | 115 |
| 4395 | 4410 | 158 | 154 | 150 | 146 141 | 137 | 133 | 129 | 124 | 120 | 116 |
| 4410 | 4425 | 159 | 155 | 150 | 146 142 | 138 | 133 | 129 | 125 | 121 | 116 |
| 4425 | 4440 | 160 | 155 | 151 | 147 143 | 138 | 134 | 130 | 125 | 121 | 117 |
| 4440 | 4455 | 160 | 156 | 152 | 147 143 | 139 | 135 | 130 | 126 | 122 | 118 |
| 4455 | 4470 | 161 | 157 | 152 | 148 144 | 139 | 135 | 131 | 127 | 122 | 118 |
| 4470 | 4485 | 161 | 157 | 153 | 149 144 | 140 | 136 | 132 | 127 | 123 | 119 |
| 4485 | 4500 | 162 | 158 | 153 | 149 145 | 141 | 136 | 132 | 128 | 124 | 119 |
| 4500 | 4515 | 163 | 158 | 154 | 150 146 | 141 | 137 | 133 | 129 | 124 | 120 |
| 4515 | 4530 | 163 | 159 | 155 | 150 146 | 142 | 138 | 133 | 129 | 125 | 121 |
| 4530 | 4545 | 164 | 160 | 155 | 151 147 | 143 | 138 | 134 | 130 | 126 | 121 |
| 4545 | 4560 | 164 | 160 | 156 | 152 147 | 143 | 139 | 135 | 130 | 126 | 122 |
| 4560 | 4575 | 165 | 161 | 157 | 152 148 | 144 | 140 | 135 | 131 | 127 | 122 |
| 4575 | 4590 | 166 | 161 | 157 | 153 149 | 144 | 140 | 136 | 132 | 127 | 123 |
| 4590 | 4605 | 166 | 162 | 158 | 154 149 | 145 | 141 | 136 | 132 | 128 | 124 |
| 4605 | 4620 | 167 | 163 | 158 | 154 150 | 146 | 141 | 137 | 133 | 129 | 124 |
| 4620 | 4635 | 168 | 163 | 159 | 155 150 | 146 | 142 | 138 | 133 | 129 | 125 |
| 4635 | 4650 | 168 | 164 | 160 | 155 151 | 147 | 143 | 138 | 134 | 130 | 126 |
| 4650 | 4665 | 169 | 165 | 160 | 156 152 | 147 | 143 | 139 | 135 | 130 | 126 |
| 4665 | 4680 | 169 | 165 | 161 | 157 152 | 148 | 144 | 140 | 135 | 131 | 127 |
| 4680 | 4695 | 170 | 166 | 161 | 157 153 | 149 | 144 | 140 | 136 | 132 | 127 |
| 4695 | 4710 | 171 | 166 | 162 | 158 154 | 149 | 145 | 141 | 137 | 132 | 128 |
| 4710 | 4725 | 171 | 167 | 163 | 158 154 | 150 | 146 | 141 | 137 | 133 | 129 |
| 4725 | 4740 | 172 | 168 | 163 | 159 155 | 151 | 146 | 142 | 138 | 133 | 129 |
| 4740 | 4755 | 172 | 168 | 164 | 160 155 | 151 | 147 | 143 | 138 | 134 | 130 |
| 4755 | 4770 | 173 | 169 | 165 | 160 156 | 152 | 147 | 143 | 139 | 135 | 130 |
| 4770 | 4785 | 174 | 169 | 165 | 161 157 | 152 | 148 | 144 | 140 | 135 | 131 |
| 4785 | 4800 | 174 | 170 | 166 | 162 157 | 153 | 149 | 144 | 140 | 136 | 132 |
| 4800 | 4815 | 175 | 171 | 166 | 162 158 | 154 | 149 | 145 | 141 | 137 | 132 |
| 4815 | 4830 | 176 | 171 | 167 | 163 158 | 154 | 150 | 146 | 141 | 137 | 133 |
| 4830 | 4845 | 176 | 172 | 168 | 163 159 | 155 | 151 | 146 | 142 | 138 | 134 |
| 4845 | 4860 | 177 | 172 | 168 | 164 160 | 155 | 151 | 147 | 143 | 138 | 134 |
| 4860 | 4875 | 177 | 173 | 169 | 165 160 | 156 | 152 | 148 | 143 | 139 | 135 |
| 4875 | 4890 | 178 | 174 | 169 | 165 161 | 157 | 152 | 148 | 144 | 140 | 135 |
| 4890 | 4905 | 179 | 174 | 170 | 166 162 | 157 | 153 | 149 | 144 | 140 | 136 |
| 4905 | 4920 | 179 | 175 | 171 | 166 162 | 158 | 154 | 149 | 145 | 141 | 137 |
| 4920 | 4935 | 180 | 176 | 171 | 167 163 | 159 | 154 | 150 | 146 | 141 | 137 |
| 4935 | 4950 | 180 | 176 | 172 | 168 163 | 159 | 155 | 151 | 146 | 142 | 138 |
| 4950 | 4965 | 181 | 177 | 173 | 168 164 | 160 | 155 | 151 | 147 | 143 | 138 |
| 4965 | 4980 | 182 | 177 | 173 | 169 165 | 160 | 156 | 152 | 148 | 143 | 139 |
| 4980 | 4995 | 182 | 178 | 174 | 169 165 | 161 | 157 | 152 | 148 | 144 | 140 |
| 4995 | 5010 | 183 | 179 | 174 | 170 166 | 162 | 157 | 153 | 149 | 145 | 140 |
| 5010 | 5025 | 183 | 179 | 175 | 171 166 | 162 | 158 | 154 | 149 | 145 | 141 |
| 5020 a | nd over | use the per | centage method | begi | nning on | page 17. |
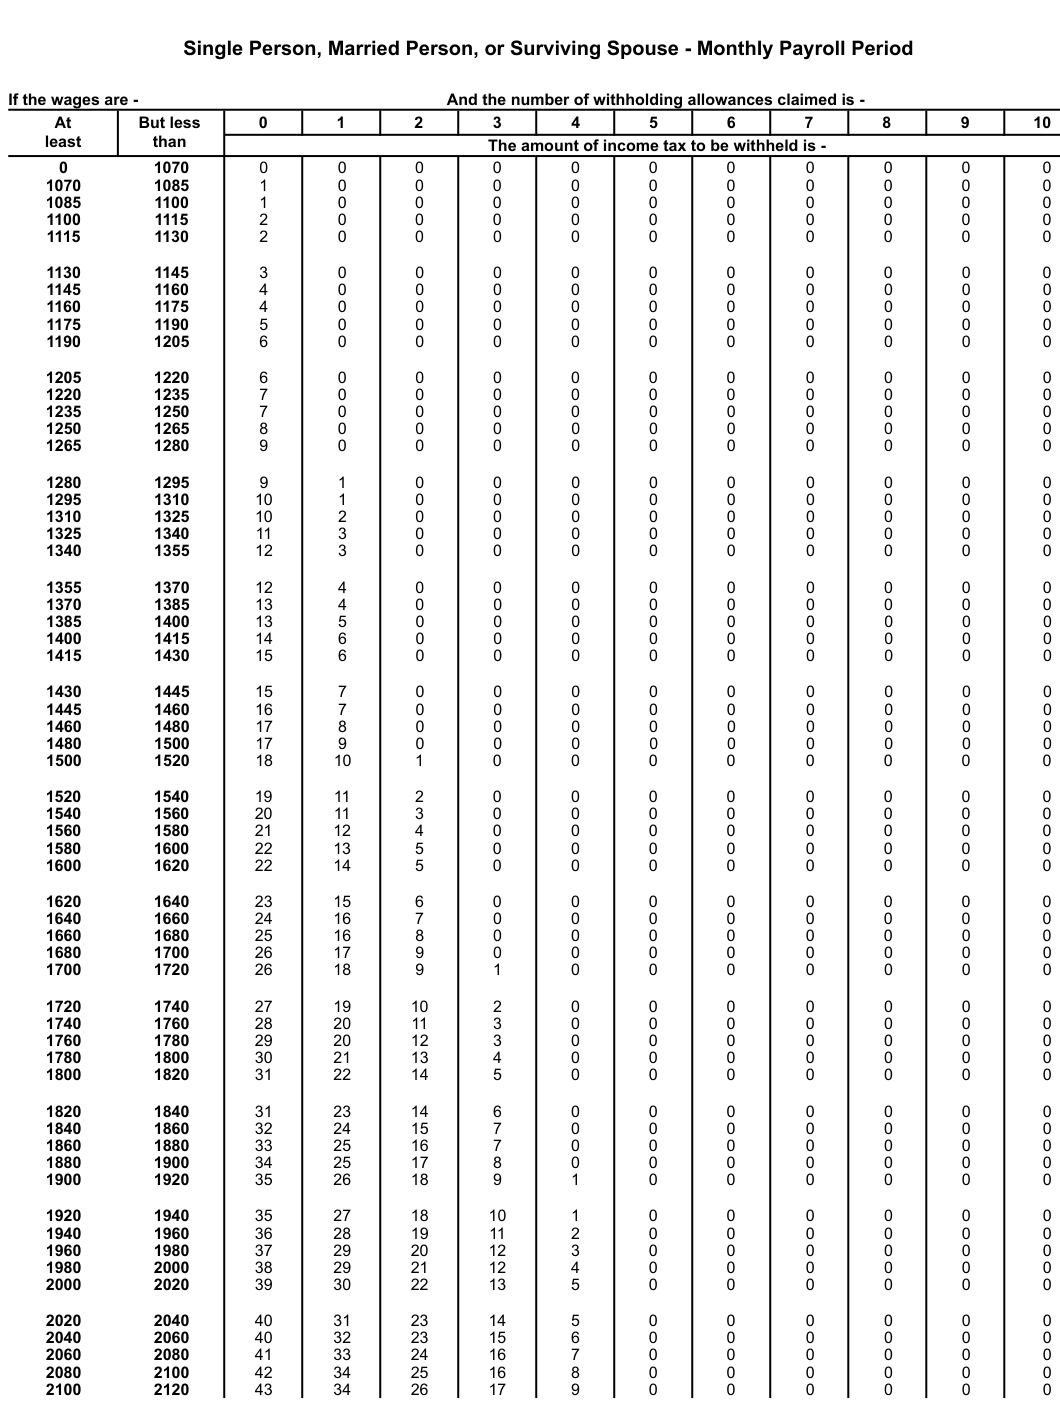
Text version of this table
| Single | Person, | Married | Person, | or S | urviving | Spouse | - Monthly | Payroll Per | iod | |||
| wages are - | And t | he n | umber of w | ithholding | allowances | claimed is - | ||||||
| At B | ut less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
| least | than | The | amount of | income tax | to be withh | eld is - | ||||||
| 0 | 1070 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1070 | 1085 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1085 | 1100 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1100 | 1115 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1115 | 1130 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1130 | 1145 | 3 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1145 | 1160 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1160 | 1175 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1175 | 1190 | 5 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1190 | 1205 | 6 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1205 | 1220 | 6 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1220 | 1235 | 7 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1235 | 1250 | 7 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1250 | 1265 | 8 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1265 | 1280 | 9 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1280 | 1295 | 9 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1295 | 1310 | 10 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1310 | 1325 | 10 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1325 | 1340 | 11 | 3 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1340 | 1355 | 12 | 3 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1355 | 1370 | 12 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1370 | 1385 | 13 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1385 | 1400 | 13 | 5 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1400 | 1415 | 14 | 6 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1415 | 1430 | 15 | 6 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1430 | 1445 | 15 | 7 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1445 | 1460 | 16 | 7 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1460 | 1480 | 17 | 8 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1480 | 1500 | 17 | 9 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1500 | 1520 | 18 | 10 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1520 | 1540 | 19 | 11 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1540 | 1560 | 20 | 11 | 3 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1560 | 1580 | 21 | 12 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1580 | 1600 | 22 | 13 | 5 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1600 | 1620 | 22 | 14 | 5 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1620 | 1640 | 23 | 15 | 6 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1640 | 1660 | 24 | 16 | 7 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1660 | 1680 | 25 | 16 | 8 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1680 | 1700 | 26 | 17 | 9 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1700 | 1720 | 26 | 18 | 9 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1720 | 1740 | 27 | 19 | 10 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1740 | 1760 | 28 | 20 | 11 | 3 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1760 | 1780 | 29 | 20 | 12 | 3 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1780 | 1800 | 30 | 21 | 13 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1800 | 1820 | 31 | 22 | 14 | 5 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1820 | 1840 | 31 | 23 | 14 | 6 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1840 | 1860 | 32 | 24 | 15 | 7 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1860 | 1880 | 33 | 25 | 16 | 7 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1880 | 1900 | 34 | 25 | 17 | 8 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1900 | 1920 | 35 | 26 | 18 | 9 | 1 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1920 | 1940 | 35 | 27 | 18 | 10 | 1 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1940 | 1960 | 36 | 28 | 19 | 11 | 2 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1960 | 1980 | 37 | 29 | 20 | 12 | 3 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1980 | 2000 | 38 | 29 | 21 | 12 | 4 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2000 | 2020 | 39 | 30 | 22 | 13 | 5 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2020 | 2040 | 40 | 31 | 23 | 14 | 5 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2040 | 2060 | 40 | 32 | 23 | 15 | 6 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2060 | 2080 | 41 | 33 | 24 | 16 | 7 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2080 | 2100 | 42 | 34 | 25 | 16 | 8 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2100 | 2120 | 43 | 34 | 26 | 17 | 9 | 0 | 0 | 0 | 0 | 0 | 0 |
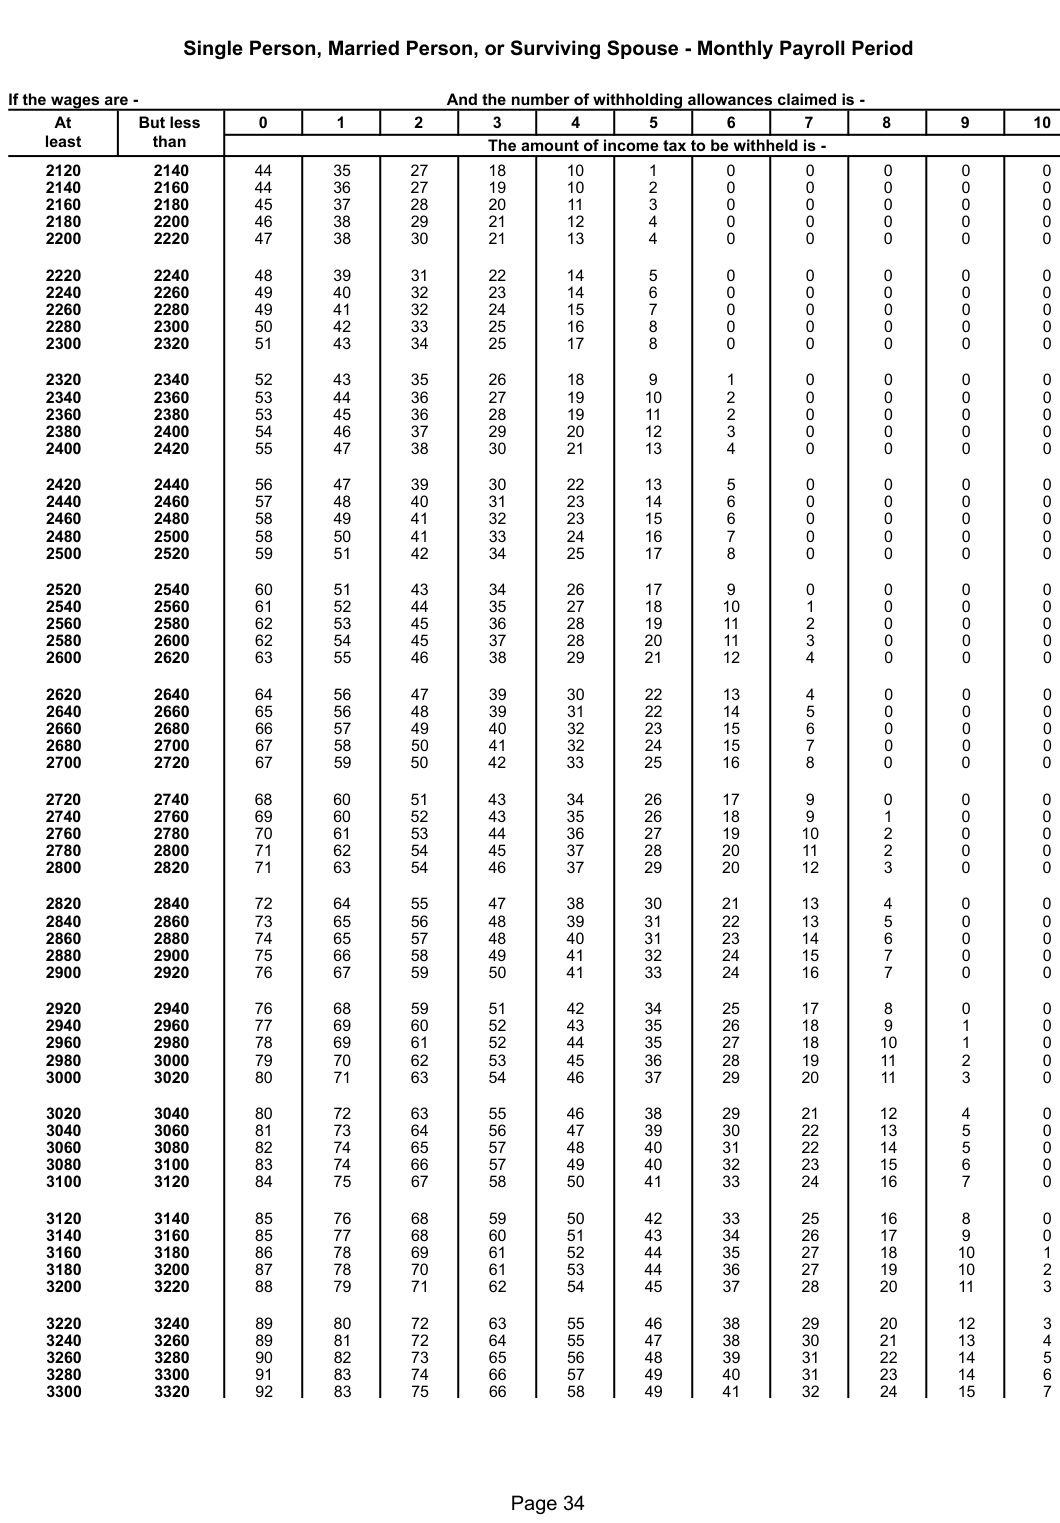
Text version of this table
| Single | Person, | Married | Person, | or Survi | ving Spo | use | - Monthly | Payroll Per | iod | |||
| wages are - | And | the numbe | r of withho | lding | allowances | claimed is - | ||||||
| At B | ut less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
| least | than | The amou | nt of incom | e tax | to be withh | eld is - | ||||||
| 2120 | 2140 | 44 | 35 | 27 | 18 | 10 | 1 | 0 | 0 | 0 | 0 | 0 |
| 2140 | 2160 | 44 | 36 | 27 | 19 | 10 | 2 | 0 | 0 | 0 | 0 | 0 |
| 2160 | 2180 | 45 | 37 | 28 | 20 | 11 | 3 | 0 | 0 | 0 | 0 | 0 |
| 2180 | 2200 | 46 | 38 | 29 | 21 | 12 | 4 | 0 | 0 | 0 | 0 | 0 |
| 2200 | 2220 | 47 | 38 | 30 | 21 | 13 | 4 | 0 | 0 | 0 | 0 | 0 |
| 2220 | 2240 | 48 | 39 | 31 | 22 | 14 | 5 | 0 | 0 | 0 | 0 | 0 |
| 2240 | 2260 | 49 | 40 | 32 | 23 | 14 | 6 | 0 | 0 | 0 | 0 | 0 |
| 2260 | 2280 | 49 | 41 | 32 | 24 | 15 | 7 | 0 | 0 | 0 | 0 | 0 |
| 2280 | 2300 | 50 | 42 | 33 | 25 | 16 | 8 | 0 | 0 | 0 | 0 | 0 |
| 2300 | 2320 | 51 | 43 | 34 | 25 | 17 | 8 | 0 | 0 | 0 | 0 | 0 |
| 2320 | 2340 | 52 | 43 | 35 | 26 | 18 | 9 | 1 | 0 | 0 | 0 | 0 |
| 2340 | 2360 | 53 | 44 | 36 | 27 | 19 | 10 | 2 | 0 | 0 | 0 | 0 |
| 2360 | 2380 | 53 | 45 | 36 | 28 | 19 | 11 | 2 | 0 | 0 | 0 | 0 |
| 2380 | 2400 | 54 | 46 | 37 | 29 | 20 | 12 | 3 | 0 | 0 | 0 | 0 |
| 2400 | 2420 | 55 | 47 | 38 | 30 | 21 | 13 | 4 | 0 | 0 | 0 | 0 |
| 2420 | 2440 | 56 | 47 | 39 | 30 | 22 | 13 | 5 | 0 | 0 | 0 | 0 |
| 2440 | 2460 | 57 | 48 | 40 | 31 | 23 | 14 | 6 | 0 | 0 | 0 | 0 |
| 2460 | 2480 | 58 | 49 | 41 | 32 | 23 | 15 | 6 | 0 | 0 | 0 | 0 |
| 2480 | 2500 | 58 | 50 | 41 | 33 | 24 | 16 | 7 | 0 | 0 | 0 | 0 |
| 2500 | 2520 | 59 | 51 | 42 | 34 | 25 | 17 | 8 | 0 | 0 | 0 | 0 |
| 2520 | 2540 | 60 | 51 | 43 | 34 | 26 | 17 | 9 | 0 | 0 | 0 | 0 |
| 2540 | 2560 | 61 | 52 | 44 | 35 | 27 | 18 | 10 | 1 | 0 | 0 | 0 |
| 2560 | 2580 | 62 | 53 | 45 | 36 | 28 | 19 | 11 | 2 | 0 | 0 | 0 |
| 2580 | 2600 | 62 | 54 | 45 | 37 | 28 | 20 | 11 | 3 | 0 | 0 | 0 |
| 2600 | 2620 | 63 | 55 | 46 | 38 | 29 | 21 | 12 | 4 | 0 | 0 | 0 |
| 2620 | 2640 | 64 | 56 | 47 | 39 | 30 | 22 | 13 | 4 | 0 | 0 | 0 |
| 2640 | 2660 | 65 | 56 | 48 | 39 | 31 | 22 | 14 | 5 | 0 | 0 | 0 |
| 2660 | 2680 | 66 | 57 | 49 | 40 | 32 | 23 | 15 | 6 | 0 | 0 | 0 |
| 2680 | 2700 | 67 | 58 | 50 | 41 | 32 | 24 | 15 | 7 | 0 | 0 | 0 |
| 2700 | 2720 | 67 | 59 | 50 | 42 | 33 | 25 | 16 | 8 | 0 | 0 | 0 |
| 2720 | 2740 | 68 | 60 | 51 | 43 | 34 | 26 | 17 | 9 | 0 | 0 | 0 |
| 2740 | 2760 | 69 | 60 | 52 | 43 | 35 | 26 | 18 | 9 | 1 | 0 | 0 |
| 2760 | 2780 | 70 | 61 | 53 | 44 | 36 | 27 | 19 | 10 | 2 | 0 | 0 |
| 2780 | 2800 | 71 | 62 | 54 | 45 | 37 | 28 | 20 | 11 | 2 | 0 | 0 |
| 2800 | 2820 | 71 | 63 | 54 | 46 | 37 | 29 | 20 | 12 | 3 | 0 | 0 |
| 2820 | 2840 | 72 | 64 | 55 | 47 | 38 | 30 | 21 | 13 | 4 | 0 | 0 |
| 2840 | 2860 | 73 | 65 | 56 | 48 | 39 | 31 | 22 | 13 | 5 | 0 | 0 |
| 2860 | 2880 | 74 | 65 | 57 | 48 | 40 | 31 | 23 | 14 | 6 | 0 | 0 |
| 2880 | 2900 | 75 | 66 | 58 | 49 | 41 | 32 | 24 | 15 | 7 | 0 | 0 |
| 2900 | 2920 | 76 | 67 | 59 | 50 | 41 | 33 | 24 | 16 | 7 | 0 | 0 |
| 2920 | 2940 | 76 | 68 | 59 | 51 | 42 | 34 | 25 | 17 | 8 | 0 | 0 |
| 2940 | 2960 | 77 | 69 | 60 | 52 | 43 | 35 | 26 | 18 | 9 | 1 | 0 |
| 2960 | 2980 | 78 | 69 | 61 | 52 | 44 | 35 | 27 | 18 | 10 | 1 | 0 |
| 2980 | 3000 | 79 | 70 | 62 | 53 | 45 | 36 | 28 | 19 | 11 | 2 | 0 |
| 3000 | 3020 | 80 | 71 | 63 | 54 | 46 | 37 | 29 | 20 | 11 | 3 | 0 |
| 3020 | 3040 | 80 | 72 | 63 | 55 | 46 | 38 | 29 | 21 | 12 | 4 | 0 |
| 3040 | 3060 | 81 | 73 | 64 | 56 | 47 | 39 | 30 | 22 | 13 | 5 | 0 |
| 3060 | 3080 | 82 | 74 | 65 | 57 | 48 | 40 | 31 | 22 | 14 | 5 | 0 |
| 3080 | 3100 | 83 | 74 | 66 | 57 | 49 | 40 | 32 | 23 | 15 | 6 | 0 |
| 3100 | 3120 | 84 | 75 | 67 | 58 | 50 | 41 | 33 | 24 | 16 | 7 | 0 |
| 3120 | 3140 | 85 | 76 | 68 | 59 | 50 | 42 | 33 | 25 | 16 | 8 | 0 |
| 3140 | 3160 | 85 | 77 | 68 | 60 | 51 | 43 | 34 | 26 | 17 | 9 | 0 |
| 3160 | 3180 | 86 | 78 | 69 | 61 | 52 | 44 | 35 | 27 | 18 | 10 | 1 |
| 3180 | 3200 | 87 | 78 | 70 | 61 | 53 | 44 | 36 | 27 | 19 | 10 | 2 |
| 3200 | 3220 | 88 | 79 | 71 | 62 | 54 | 45 | 37 | 28 | 20 | 11 | 3 |
| 3220 | 3240 | 89 | 80 | 72 | 63 | 55 | 46 | 38 | 29 | 20 | 12 | 3 |
| 3240 | 3260 | 89 | 81 | 72 | 64 | 55 | 47 | 38 | 30 | 21 | 13 | 4 |
| 3260 | 3280 | 90 | 82 | 73 | 65 | 56 | 48 | 39 | 31 | 22 | 14 | 5 |
| 3280 | 3300 | 91 | 83 | 74 | 66 | 57 | 49 | 40 | 31 | 23 | 14 | 6 |
| 3300 | 3320 | 92 | 83 | 75 | 66 | 58 | 49 | 41 | 32 | 24 | 15 | 7 |
| Page | 34 |
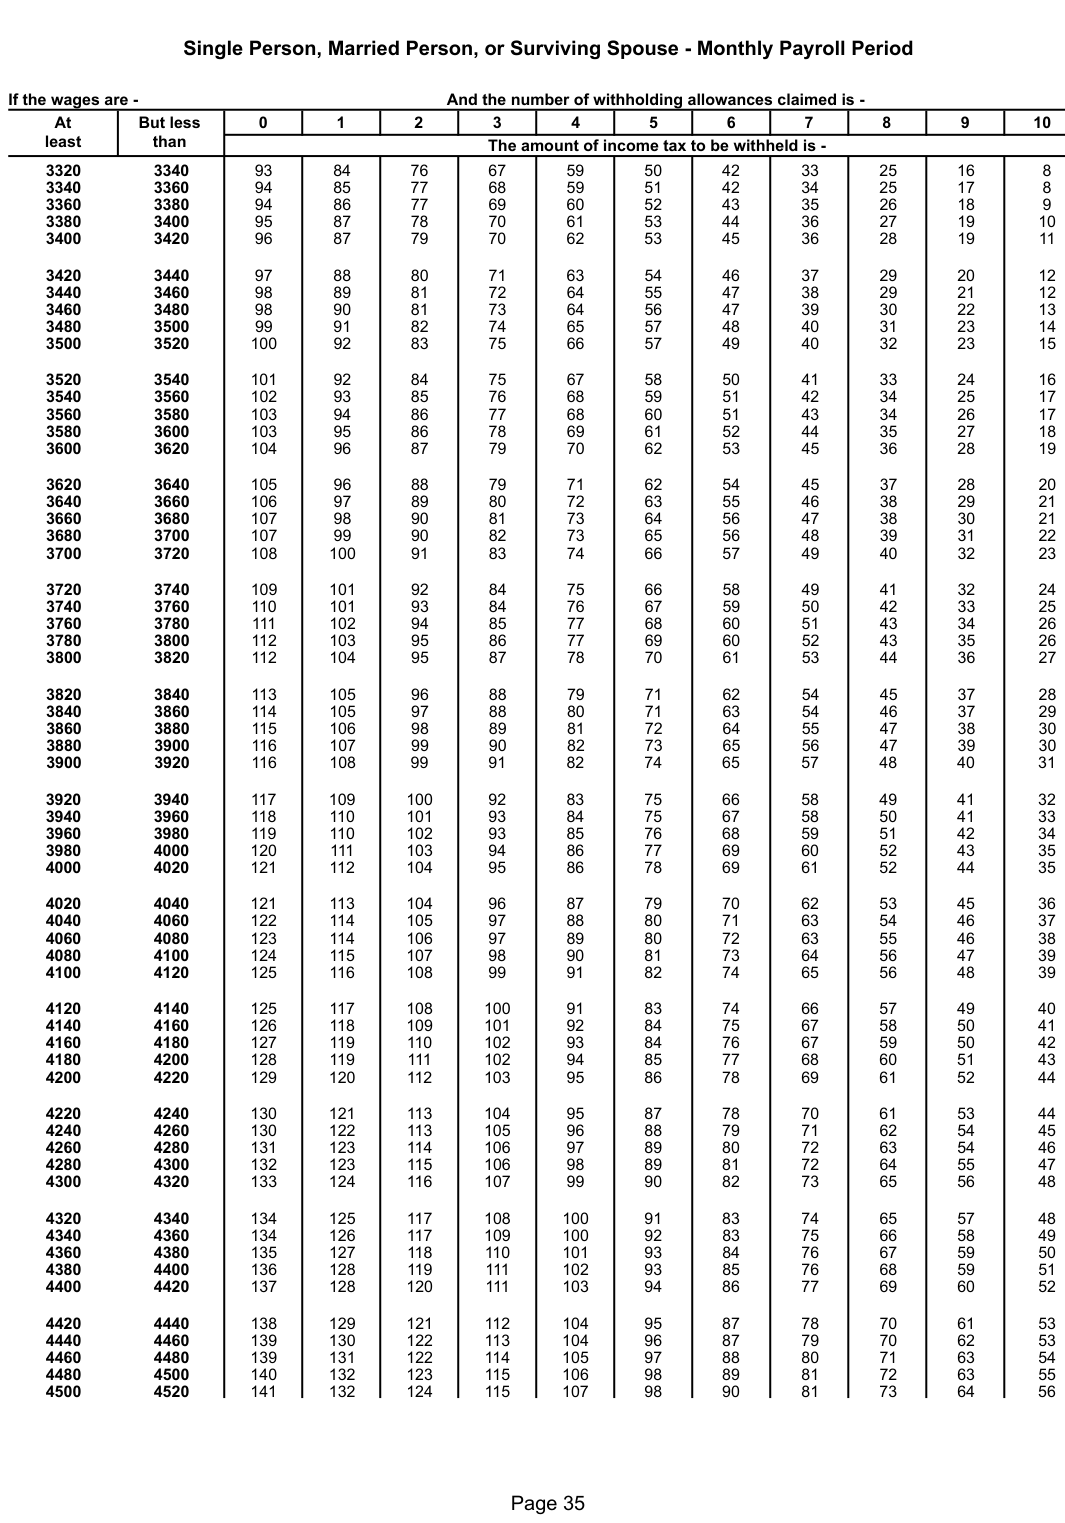
Text version of this table
| Single | Person, | Married | Person, | or Survi | ving Spo | use | - Monthly | Payroll Pe | riod | |||
| wages are - | And | the numbe | r of withho | lding | allowances | claimed is - | ||||||
| At B | ut less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 1 | 0 |
| least | than | The amou | nt of incom | e tax | to be withh | eld is - | ||||||
| 3320 | 3340 | 93 | 84 | 76 | 67 | 59 | 50 | 42 | 33 | 25 | 16 | 8 |
| 3340 | 3360 | 94 | 85 | 77 | 68 | 59 | 51 | 42 | 34 | 25 | 17 | 8 |
| 3360 | 3380 | 94 | 86 | 77 | 69 | 60 | 52 | 43 | 35 | 26 | 18 | 9 |
| 3380 | 3400 | 95 | 87 | 78 | 70 | 61 | 53 | 44 | 36 | 27 | 19 | 10 |
| 3400 | 3420 | 96 | 87 | 79 | 70 | 62 | 53 | 45 | 36 | 28 | 19 | 11 |
| 3420 | 3440 | 97 | 88 | 80 | 71 | 63 | 54 | 46 | 37 | 29 | 20 | 12 |
| 3440 | 3460 | 98 | 89 | 81 | 72 | 64 | 55 | 47 | 38 | 29 | 21 | 12 |
| 3460 | 3480 | 98 | 90 | 81 | 73 | 64 | 56 | 47 | 39 | 30 | 22 | 13 |
| 3480 | 3500 | 99 | 91 | 82 | 74 | 65 | 57 | 48 | 40 | 31 | 23 | 14 |
| 3500 | 3520 | 100 | 92 | 83 | 75 | 66 | 57 | 49 | 40 | 32 | 23 | 15 |
| 3520 | 3540 | 101 | 92 | 84 | 75 | 67 | 58 | 50 | 41 | 33 | 24 | 16 |
| 3540 | 3560 | 102 | 93 | 85 | 76 | 68 | 59 | 51 | 42 | 34 | 25 | 17 |
| 3560 | 3580 | 103 | 94 | 86 | 77 | 68 | 60 | 51 | 43 | 34 | 26 | 17 |
| 3580 | 3600 | 103 | 95 | 86 | 78 | 69 | 61 | 52 | 44 | 35 | 27 | 18 |
| 3600 | 3620 | 104 | 96 | 87 | 79 | 70 | 62 | 53 | 45 | 36 | 28 | 19 |
| 3620 | 3640 | 105 | 96 | 88 | 79 | 71 | 62 | 54 | 45 | 37 | 28 | 20 |
| 3640 | 3660 | 106 | 97 | 89 | 80 | 72 | 63 | 55 | 46 | 38 | 29 | 21 |
| 3660 | 3680 | 107 | 98 | 90 | 81 | 73 | 64 | 56 | 47 | 38 | 30 | 21 |
| 3680 | 3700 | 107 | 99 | 90 | 82 | 73 | 65 | 56 | 48 | 39 | 31 | 22 |
| 3700 | 3720 | 108 | 100 | 91 | 83 | 74 | 66 | 57 | 49 | 40 | 32 | 23 |
| 3720 | 3740 | 109 | 101 | 92 | 84 | 75 | 66 | 58 | 49 | 41 | 32 | 24 |
| 3740 | 3760 | 110 | 101 | 93 | 84 | 76 | 67 | 59 | 50 | 42 | 33 | 25 |
| 3760 | 3780 | 111 | 102 | 94 | 85 | 77 | 68 | 60 | 51 | 43 | 34 | 26 |
| 3780 | 3800 | 112 | 103 | 95 | 86 | 77 | 69 | 60 | 52 | 43 | 35 | 26 |
| 3800 | 3820 | 112 | 104 | 95 | 87 | 78 | 70 | 61 | 53 | 44 | 36 | 27 |
| 3820 | 3840 | 113 | 105 | 96 | 88 | 79 | 71 | 62 | 54 | 45 | 37 | 28 |
| 3840 | 3860 | 114 | 105 | 97 | 88 | 80 | 71 | 63 | 54 | 46 | 37 | 29 |
| 3860 | 3880 | 115 | 106 | 98 | 89 | 81 | 72 | 64 | 55 | 47 | 38 | 30 |
| 3880 | 3900 | 116 | 107 | 99 | 90 | 82 | 73 | 65 | 56 | 47 | 39 | 30 |
| 3900 | 3920 | 116 | 108 | 99 | 91 | 82 | 74 | 65 | 57 | 48 | 40 | 31 |
| 3920 | 3940 | 117 | 109 | 100 | 92 | 83 | 75 | 66 | 58 | 49 | 41 | 32 |
| 3940 | 3960 | 118 | 110 | 101 | 93 | 84 | 75 | 67 | 58 | 50 | 41 | 33 |
| 3960 | 3980 | 119 | 110 | 102 | 93 | 85 | 76 | 68 | 59 | 51 | 42 | 34 |
| 3980 | 4000 | 120 | 111 | 103 | 94 | 86 | 77 | 69 | 60 | 52 | 43 | 35 |
| 4000 | 4020 | 121 | 112 | 104 | 95 | 86 | 78 | 69 | 61 | 52 | 44 | 35 |
| 4020 | 4040 | 121 | 113 | 104 | 96 | 87 | 79 | 70 | 62 | 53 | 45 | 36 |
| 4040 | 4060 | 122 | 114 | 105 | 97 | 88 | 80 | 71 | 63 | 54 | 46 | 37 |
| 4060 | 4080 | 123 | 114 | 106 | 97 | 89 | 80 | 72 | 63 | 55 | 46 | 38 |
| 4080 | 4100 | 124 | 115 | 107 | 98 | 90 | 81 | 73 | 64 | 56 | 47 | 39 |
| 4100 | 4120 | 125 | 116 | 108 | 99 | 91 | 82 | 74 | 65 | 56 | 48 | 39 |
| 4120 | 4140 | 125 | 117 | 108 | 100 | 91 | 83 | 74 | 66 | 57 | 49 | 40 |
| 4140 | 4160 | 126 | 118 | 109 | 101 | 92 | 84 | 75 | 67 | 58 | 50 | 41 |
| 4160 | 4180 | 127 | 119 | 110 | 102 | 93 | 84 | 76 | 67 | 59 | 50 | 42 |
| 4180 | 4200 | 128 | 119 | 111 | 102 | 94 | 85 | 77 | 68 | 60 | 51 | 43 |
| 4200 | 4220 | 129 | 120 | 112 | 103 | 95 | 86 | 78 | 69 | 61 | 52 | 44 |
| 4220 | 4240 | 130 | 121 | 113 | 104 | 95 | 87 | 78 | 70 | 61 | 53 | 44 |
| 4240 | 4260 | 130 | 122 | 113 | 105 | 96 | 88 | 79 | 71 | 62 | 54 | 45 |
| 4260 | 4280 | 131 | 123 | 114 | 106 | 97 | 89 | 80 | 72 | 63 | 54 | 46 |
| 4280 | 4300 | 132 | 123 | 115 | 106 | 98 | 89 | 81 | 72 | 64 | 55 | 47 |
| 4300 | 4320 | 133 | 124 | 116 | 107 | 99 | 90 | 82 | 73 | 65 | 56 | 48 |
| 4320 | 4340 | 134 | 125 | 117 | 108 | 100 | 91 | 83 | 74 | 65 | 57 | 48 |
| 4340 | 4360 | 134 | 126 | 117 | 109 | 100 | 92 | 83 | 75 | 66 | 58 | 49 |
| 4360 | 4380 | 135 | 127 | 118 | 110 | 101 | 93 | 84 | 76 | 67 | 59 | 50 |
| 4380 | 4400 | 136 | 128 | 119 | 111 | 102 | 93 | 85 | 76 | 68 | 59 | 51 |
| 4400 | 4420 | 137 | 128 | 120 | 111 | 103 | 94 | 86 | 77 | 69 | 60 | 52 |
| 4420 | 4440 | 138 | 129 | 121 | 112 | 104 | 95 | 87 | 78 | 70 | 61 | 53 |
| 4440 | 4460 | 139 | 130 | 122 | 113 | 104 | 96 | 87 | 79 | 70 | 62 | 53 |
| 4460 | 4480 | 139 | 131 | 122 | 114 | 105 | 97 | 88 | 80 | 71 | 63 | 54 |
| 4480 | 4500 | 140 | 132 | 123 | 115 | 106 | 98 | 89 | 81 | 72 | 63 | 55 |
| 4500 | 4520 | 141 | 132 | 124 | 115 | 107 | 98 | 90 | 81 | 73 | 64 | 56 |
| Page | 35 |
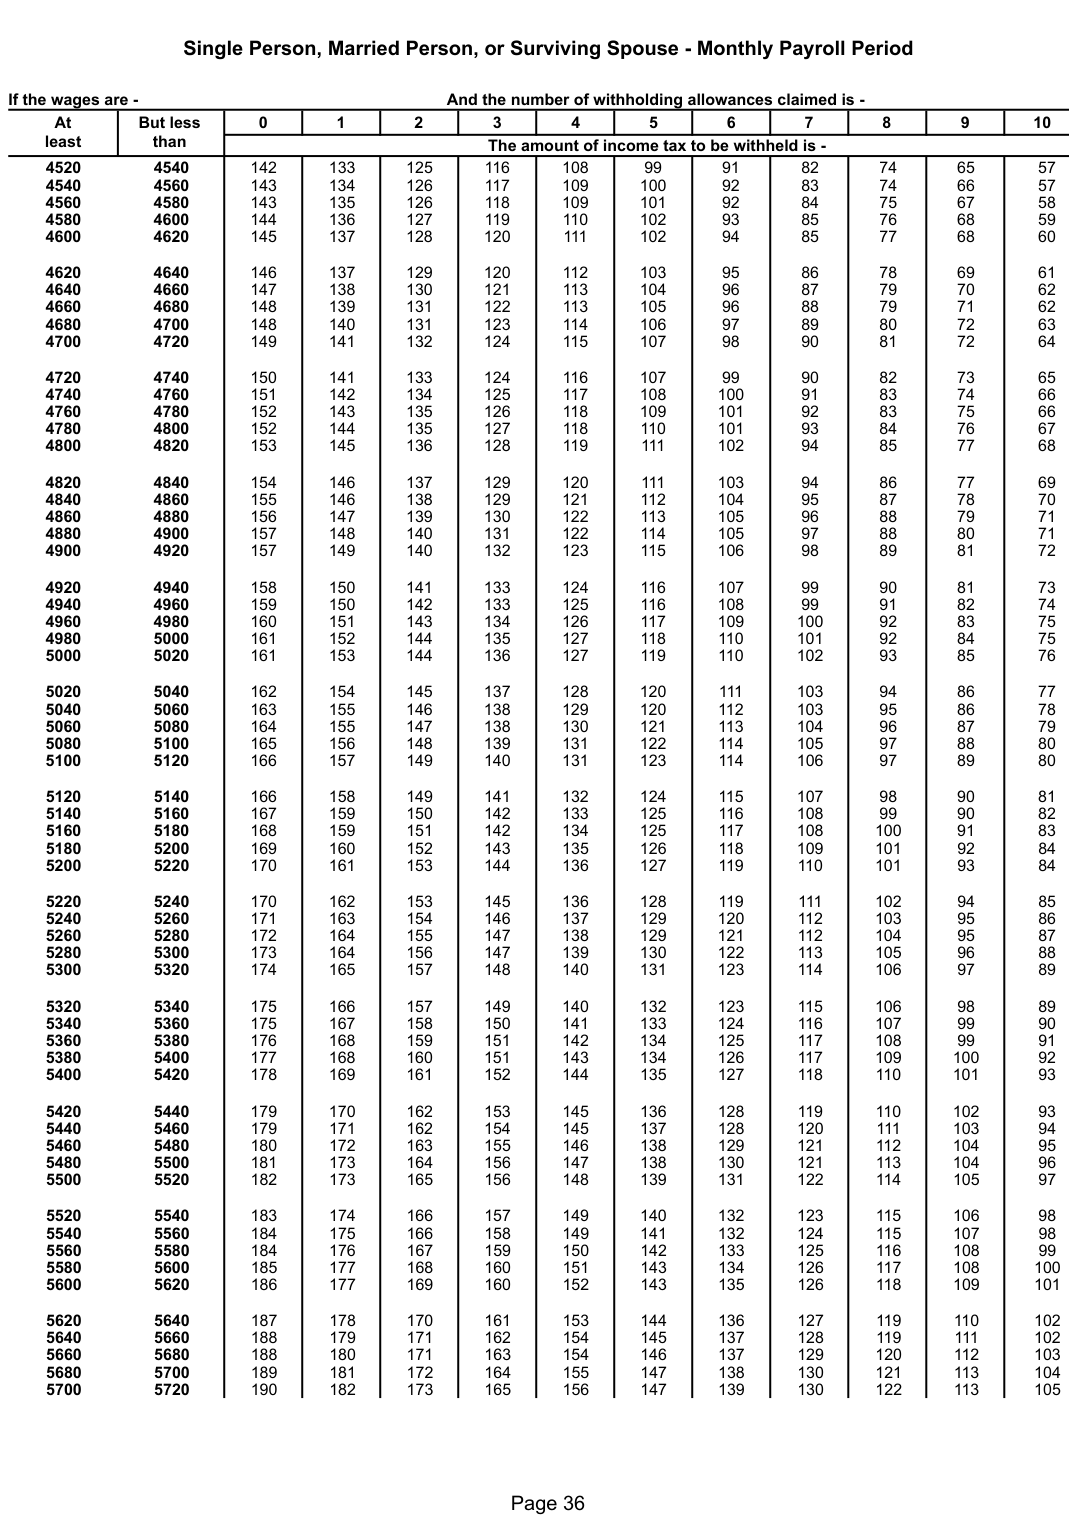
Text version of this table
| Single | Person, | Married | Person, | or Survi | ving Spo | use | - Monthly | Payroll Pe | riod | |||
| wages are - | And | the numbe | r of withh | olding | allowances | claimed is - | ||||||
| At B | ut less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
| least | than | The amou | nt of inco | me tax | to be withh | eld is - | ||||||
| 4520 | 4540 | 142 | 133 | 125 | 116 | 108 | 99 | 91 | 82 | 74 | 65 | 57 |
| 4540 | 4560 | 143 | 134 | 126 | 117 | 109 | 100 | 92 | 83 | 74 | 66 | 57 |
| 4560 | 4580 | 143 | 135 | 126 | 118 | 109 | 101 | 92 | 84 | 75 | 67 | 58 |
| 4580 | 4600 | 144 | 136 | 127 | 119 | 110 | 102 | 93 | 85 | 76 | 68 | 59 |
| 4600 | 4620 | 145 | 137 | 128 | 120 | 111 | 102 | 94 | 85 | 77 | 68 | 60 |
| 4620 | 4640 | 146 | 137 | 129 | 120 | 112 | 103 | 95 | 86 | 78 | 69 | 61 |
| 4640 | 4660 | 147 | 138 | 130 | 121 | 113 | 104 | 96 | 87 | 79 | 70 | 62 |
| 4660 | 4680 | 148 | 139 | 131 | 122 | 113 | 105 | 96 | 88 | 79 | 71 | 62 |
| 4680 | 4700 | 148 | 140 | 131 | 123 | 114 | 106 | 97 | 89 | 80 | 72 | 63 |
| 4700 | 4720 | 149 | 141 | 132 | 124 | 115 | 107 | 98 | 90 | 81 | 72 | 64 |
| 4720 | 4740 | 150 | 141 | 133 | 124 | 116 | 107 | 99 | 90 | 82 | 73 | 65 |
| 4740 | 4760 | 151 | 142 | 134 | 125 | 117 | 108 | 100 | 91 | 83 | 74 | 66 |
| 4760 | 4780 | 152 | 143 | 135 | 126 | 118 | 109 | 101 | 92 | 83 | 75 | 66 |
| 4780 | 4800 | 152 | 144 | 135 | 127 | 118 | 110 | 101 | 93 | 84 | 76 | 67 |
| 4800 | 4820 | 153 | 145 | 136 | 128 | 119 | 111 | 102 | 94 | 85 | 77 | 68 |
| 4820 | 4840 | 154 | 146 | 137 | 129 | 120 | 111 | 103 | 94 | 86 | 77 | 69 |
| 4840 | 4860 | 155 | 146 | 138 | 129 | 121 | 112 | 104 | 95 | 87 | 78 | 70 |
| 4860 | 4880 | 156 | 147 | 139 | 130 | 122 | 113 | 105 | 96 | 88 | 79 | 71 |
| 4880 | 4900 | 157 | 148 | 140 | 131 | 122 | 114 | 105 | 97 | 88 | 80 | 71 |
| 4900 | 4920 | 157 | 149 | 140 | 132 | 123 | 115 | 106 | 98 | 89 | 81 | 72 |
| 4920 | 4940 | 158 | 150 | 141 | 133 | 124 | 116 | 107 | 99 | 90 | 81 | 73 |
| 4940 | 4960 | 159 | 150 | 142 | 133 | 125 | 116 | 108 | 99 | 91 | 82 | 74 |
| 4960 | 4980 | 160 | 151 | 143 | 134 | 126 | 117 | 109 | 100 | 92 | 83 | 75 |
| 4980 | 5000 | 161 | 152 | 144 | 135 | 127 | 118 | 110 | 101 | 92 | 84 | 75 |
| 5000 | 5020 | 161 | 153 | 144 | 136 | 127 | 119 | 110 | 102 | 93 | 85 | 76 |
| 5020 | 5040 | 162 | 154 | 145 | 137 | 128 | 120 | 111 | 103 | 94 | 86 | 77 |
| 5040 | 5060 | 163 | 155 | 146 | 138 | 129 | 120 | 112 | 103 | 95 | 86 | 78 |
| 5060 | 5080 | 164 | 155 | 147 | 138 | 130 | 121 | 113 | 104 | 96 | 87 | 79 |
| 5080 | 5100 | 165 | 156 | 148 | 139 | 131 | 122 | 114 | 105 | 97 | 88 | 80 |
| 5100 | 5120 | 166 | 157 | 149 | 140 | 131 | 123 | 114 | 106 | 97 | 89 | 80 |
| 5120 | 5140 | 166 | 158 | 149 | 141 | 132 | 124 | 115 | 107 | 98 | 90 | 81 |
| 5140 | 5160 | 167 | 159 | 150 | 142 | 133 | 125 | 116 | 108 | 99 | 90 | 82 |
| 5160 | 5180 | 168 | 159 | 151 | 142 | 134 | 125 | 117 | 108 | 100 | 91 | 83 |
| 5180 | 5200 | 169 | 160 | 152 | 143 | 135 | 126 | 118 | 109 | 101 | 92 | 84 |
| 5200 | 5220 | 170 | 161 | 153 | 144 | 136 | 127 | 119 | 110 | 101 | 93 | 84 |
| 5220 | 5240 | 170 | 162 | 153 | 145 | 136 | 128 | 119 | 111 | 102 | 94 | 85 |
| 5240 | 5260 | 171 | 163 | 154 | 146 | 137 | 129 | 120 | 112 | 103 | 95 | 86 |
| 5260 | 5280 | 172 | 164 | 155 | 147 | 138 | 129 | 121 | 112 | 104 | 95 | 87 |
| 5280 | 5300 | 173 | 164 | 156 | 147 | 139 | 130 | 122 | 113 | 105 | 96 | 88 |
| 5300 | 5320 | 174 | 165 | 157 | 148 | 140 | 131 | 123 | 114 | 106 | 97 | 89 |
| 5320 | 5340 | 175 | 166 | 157 | 149 | 140 | 132 | 123 | 115 | 106 | 98 | 89 |
| 5340 | 5360 | 175 | 167 | 158 | 150 | 141 | 133 | 124 | 116 | 107 | 99 | 90 |
| 5360 | 5380 | 176 | 168 | 159 | 151 | 142 | 134 | 125 | 117 | 108 | 99 | 91 |
| 5380 | 5400 | 177 | 168 | 160 | 151 | 143 | 134 | 126 | 117 | 109 | 100 | 92 |
| 5400 | 5420 | 178 | 169 | 161 | 152 | 144 | 135 | 127 | 118 | 110 | 101 | 93 |
| 5420 | 5440 | 179 | 170 | 162 | 153 | 145 | 136 | 128 | 119 | 110 | 102 | 93 |
| 5440 | 5460 | 179 | 171 | 162 | 154 | 145 | 137 | 128 | 120 | 111 | 103 | 94 |
| 5460 | 5480 | 180 | 172 | 163 | 155 | 146 | 138 | 129 | 121 | 112 | 104 | 95 |
| 5480 | 5500 | 181 | 173 | 164 | 156 | 147 | 138 | 130 | 121 | 113 | 104 | 96 |
| 5500 | 5520 | 182 | 173 | 165 | 156 | 148 | 139 | 131 | 122 | 114 | 105 | 97 |
| 5520 | 5540 | 183 | 174 | 166 | 157 | 149 | 140 | 132 | 123 | 115 | 106 | 98 |
| 5540 | 5560 | 184 | 175 | 166 | 158 | 149 | 141 | 132 | 124 | 115 | 107 | 98 |
| 5560 | 5580 | 184 | 176 | 167 | 159 | 150 | 142 | 133 | 125 | 116 | 108 | 99 |
| 5580 | 5600 | 185 | 177 | 168 | 160 | 151 | 143 | 134 | 126 | 117 | 108 | 100 |
| 5600 | 5620 | 186 | 177 | 169 | 160 | 152 | 143 | 135 | 126 | 118 | 109 | 101 |
| 5620 | 5640 | 187 | 178 | 170 | 161 | 153 | 144 | 136 | 127 | 119 | 110 | 102 |
| 5640 | 5660 | 188 | 179 | 171 | 162 | 154 | 145 | 137 | 128 | 119 | 111 | 102 |
| 5660 | 5680 | 188 | 180 | 171 | 163 | 154 | 146 | 137 | 129 | 120 | 112 | 103 |
| 5680 | 5700 | 189 | 181 | 172 | 164 | 155 | 147 | 138 | 130 | 121 | 113 | 104 |
| 5700 | 5720 | 190 | 182 | 173 | 165 | 156 | 147 | 139 | 130 | 122 | 113 | 105 |
| Page | 36 |
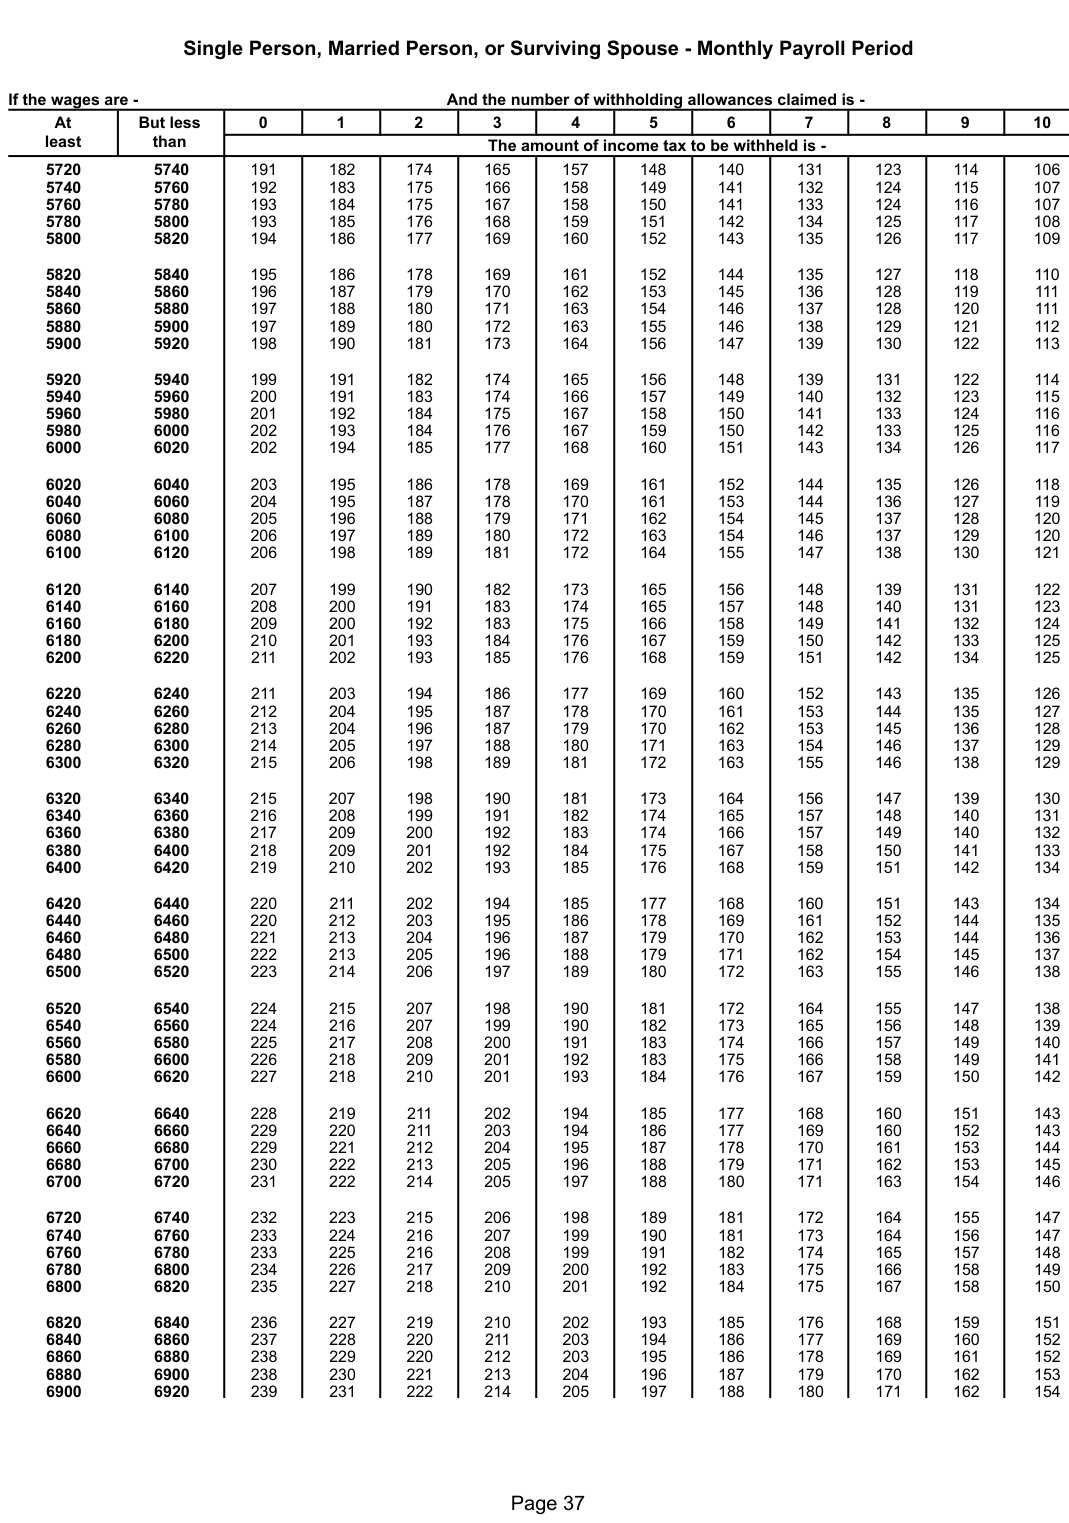
Text version of this table
| Single | Person, | Married | Person, | or Survi | ving Spo | use | - Monthly | Payroll Pe | riod | |||
| wages are - | And | the numbe | r of withh | olding | allowances | claimed is - | ||||||
| At B | ut less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
| least | than | The amou | nt of inco | me tax | to be withh | eld is - | ||||||
| 5720 | 5740 | 191 | 182 | 174 | 165 | 157 | 148 | 140 | 131 | 123 | 114 | 106 |
| 5740 | 5760 | 192 | 183 | 175 | 166 | 158 | 149 | 141 | 132 | 124 | 115 | 107 |
| 5760 | 5780 | 193 | 184 | 175 | 167 | 158 | 150 | 141 | 133 | 124 | 116 | 107 |
| 5780 | 5800 | 193 | 185 | 176 | 168 | 159 | 151 | 142 | 134 | 125 | 117 | 108 |
| 5800 | 5820 | 194 | 186 | 177 | 169 | 160 | 152 | 143 | 135 | 126 | 117 | 109 |
| 5820 | 5840 | 195 | 186 | 178 | 169 | 161 | 152 | 144 | 135 | 127 | 118 | 110 |
| 5840 | 5860 | 196 | 187 | 179 | 170 | 162 | 153 | 145 | 136 | 128 | 119 | 111 |
| 5860 | 5880 | 197 | 188 | 180 | 171 | 163 | 154 | 146 | 137 | 128 | 120 | 111 |
| 5880 | 5900 | 197 | 189 | 180 | 172 | 163 | 155 | 146 | 138 | 129 | 121 | 112 |
| 5900 | 5920 | 198 | 190 | 181 | 173 | 164 | 156 | 147 | 139 | 130 | 122 | 113 |
| 5920 | 5940 | 199 | 191 | 182 | 174 | 165 | 156 | 148 | 139 | 131 | 122 | 114 |
| 5940 | 5960 | 200 | 191 | 183 | 174 | 166 | 157 | 149 | 140 | 132 | 123 | 115 |
| 5960 | 5980 | 201 | 192 | 184 | 175 | 167 | 158 | 150 | 141 | 133 | 124 | 116 |
| 5980 | 6000 | 202 | 193 | 184 | 176 | 167 | 159 | 150 | 142 | 133 | 125 | 116 |
| 6000 | 6020 | 202 | 194 | 185 | 177 | 168 | 160 | 151 | 143 | 134 | 126 | 117 |
| 6020 | 6040 | 203 | 195 | 186 | 178 | 169 | 161 | 152 | 144 | 135 | 126 | 118 |
| 6040 | 6060 | 204 | 195 | 187 | 178 | 170 | 161 | 153 | 144 | 136 | 127 | 119 |
| 6060 | 6080 | 205 | 196 | 188 | 179 | 171 | 162 | 154 | 145 | 137 | 128 | 120 |
| 6080 | 6100 | 206 | 197 | 189 | 180 | 172 | 163 | 154 | 146 | 137 | 129 | 120 |
| 6100 | 6120 | 206 | 198 | 189 | 181 | 172 | 164 | 155 | 147 | 138 | 130 | 121 |
| 6120 | 6140 | 207 | 199 | 190 | 182 | 173 | 165 | 156 | 148 | 139 | 131 | 122 |
| 6140 | 6160 | 208 | 200 | 191 | 183 | 174 | 165 | 157 | 148 | 140 | 131 | 123 |
| 6160 | 6180 | 209 | 200 | 192 | 183 | 175 | 166 | 158 | 149 | 141 | 132 | 124 |
| 6180 | 6200 | 210 | 201 | 193 | 184 | 176 | 167 | 159 | 150 | 142 | 133 | 125 |
| 6200 | 6220 | 211 | 202 | 193 | 185 | 176 | 168 | 159 | 151 | 142 | 134 | 125 |
| 6220 | 6240 | 211 | 203 | 194 | 186 | 177 | 169 | 160 | 152 | 143 | 135 | 126 |
| 6240 | 6260 | 212 | 204 | 195 | 187 | 178 | 170 | 161 | 153 | 144 | 135 | 127 |
| 6260 | 6280 | 213 | 204 | 196 | 187 | 179 | 170 | 162 | 153 | 145 | 136 | 128 |
| 6280 | 6300 | 214 | 205 | 197 | 188 | 180 | 171 | 163 | 154 | 146 | 137 | 129 |
| 6300 | 6320 | 215 | 206 | 198 | 189 | 181 | 172 | 163 | 155 | 146 | 138 | 129 |
| 6320 | 6340 | 215 | 207 | 198 | 190 | 181 | 173 | 164 | 156 | 147 | 139 | 130 |
| 6340 | 6360 | 216 | 208 | 199 | 191 | 182 | 174 | 165 | 157 | 148 | 140 | 131 |
| 6360 | 6380 | 217 | 209 | 200 | 192 | 183 | 174 | 166 | 157 | 149 | 140 | 132 |
| 6380 | 6400 | 218 | 209 | 201 | 192 | 184 | 175 | 167 | 158 | 150 | 141 | 133 |
| 6400 | 6420 | 219 | 210 | 202 | 193 | 185 | 176 | 168 | 159 | 151 | 142 | 134 |
| 6420 | 6440 | 220 | 211 | 202 | 194 | 185 | 177 | 168 | 160 | 151 | 143 | 134 |
| 6440 | 6460 | 220 | 212 | 203 | 195 | 186 | 178 | 169 | 161 | 152 | 144 | 135 |
| 6460 | 6480 | 221 | 213 | 204 | 196 | 187 | 179 | 170 | 162 | 153 | 144 | 136 |
| 6480 | 6500 | 222 | 213 | 205 | 196 | 188 | 179 | 171 | 162 | 154 | 145 | 137 |
| 6500 | 6520 | 223 | 214 | 206 | 197 | 189 | 180 | 172 | 163 | 155 | 146 | 138 |
| 6520 | 6540 | 224 | 215 | 207 | 198 | 190 | 181 | 172 | 164 | 155 | 147 | 138 |
| 6540 | 6560 | 224 | 216 | 207 | 199 | 190 | 182 | 173 | 165 | 156 | 148 | 139 |
| 6560 | 6580 | 225 | 217 | 208 | 200 | 191 | 183 | 174 | 166 | 157 | 149 | 140 |
| 6580 | 6600 | 226 | 218 | 209 | 201 | 192 | 183 | 175 | 166 | 158 | 149 | 141 |
| 6600 | 6620 | 227 | 218 | 210 | 201 | 193 | 184 | 176 | 167 | 159 | 150 | 142 |
| 6620 | 6640 | 228 | 219 | 211 | 202 | 194 | 185 | 177 | 168 | 160 | 151 | 143 |
| 6640 | 6660 | 229 | 220 | 211 | 203 | 194 | 186 | 177 | 169 | 160 | 152 | 143 |
| 6660 | 6680 | 229 | 221 | 212 | 204 | 195 | 187 | 178 | 170 | 161 | 153 | 144 |
| 6680 | 6700 | 230 | 222 | 213 | 205 | 196 | 188 | 179 | 171 | 162 | 153 | 145 |
| 6700 | 6720 | 231 | 222 | 214 | 205 | 197 | 188 | 180 | 171 | 163 | 154 | 146 |
| 6720 | 6740 | 232 | 223 | 215 | 206 | 198 | 189 | 181 | 172 | 164 | 155 | 147 |
| 6740 | 6760 | 233 | 224 | 216 | 207 | 199 | 190 | 181 | 173 | 164 | 156 | 147 |
| 6760 | 6780 | 233 | 225 | 216 | 208 | 199 | 191 | 182 | 174 | 165 | 157 | 148 |
| 6780 | 6800 | 234 | 226 | 217 | 209 | 200 | 192 | 183 | 175 | 166 | 158 | 149 |
| 6800 | 6820 | 235 | 227 | 218 | 210 | 201 | 192 | 184 | 175 | 167 | 158 | 150 |
| 6820 | 6840 | 236 | 227 | 219 | 210 | 202 | 193 | 185 | 176 | 168 | 159 | 151 |
| 6840 | 6860 | 237 | 228 | 220 | 211 | 203 | 194 | 186 | 177 | 169 | 160 | 152 |
| 6860 | 6880 | 238 | 229 | 220 | 212 | 203 | 195 | 186 | 178 | 169 | 161 | 152 |
| 6880 | 6900 | 238 | 230 | 221 | 213 | 204 | 196 | 187 | 179 | 170 | 162 | 153 |
| 6900 | 6920 | 239 | 231 | 222 | 214 | 205 | 197 | 188 | 180 | 171 | 162 | 154 |
| Page | 37 |
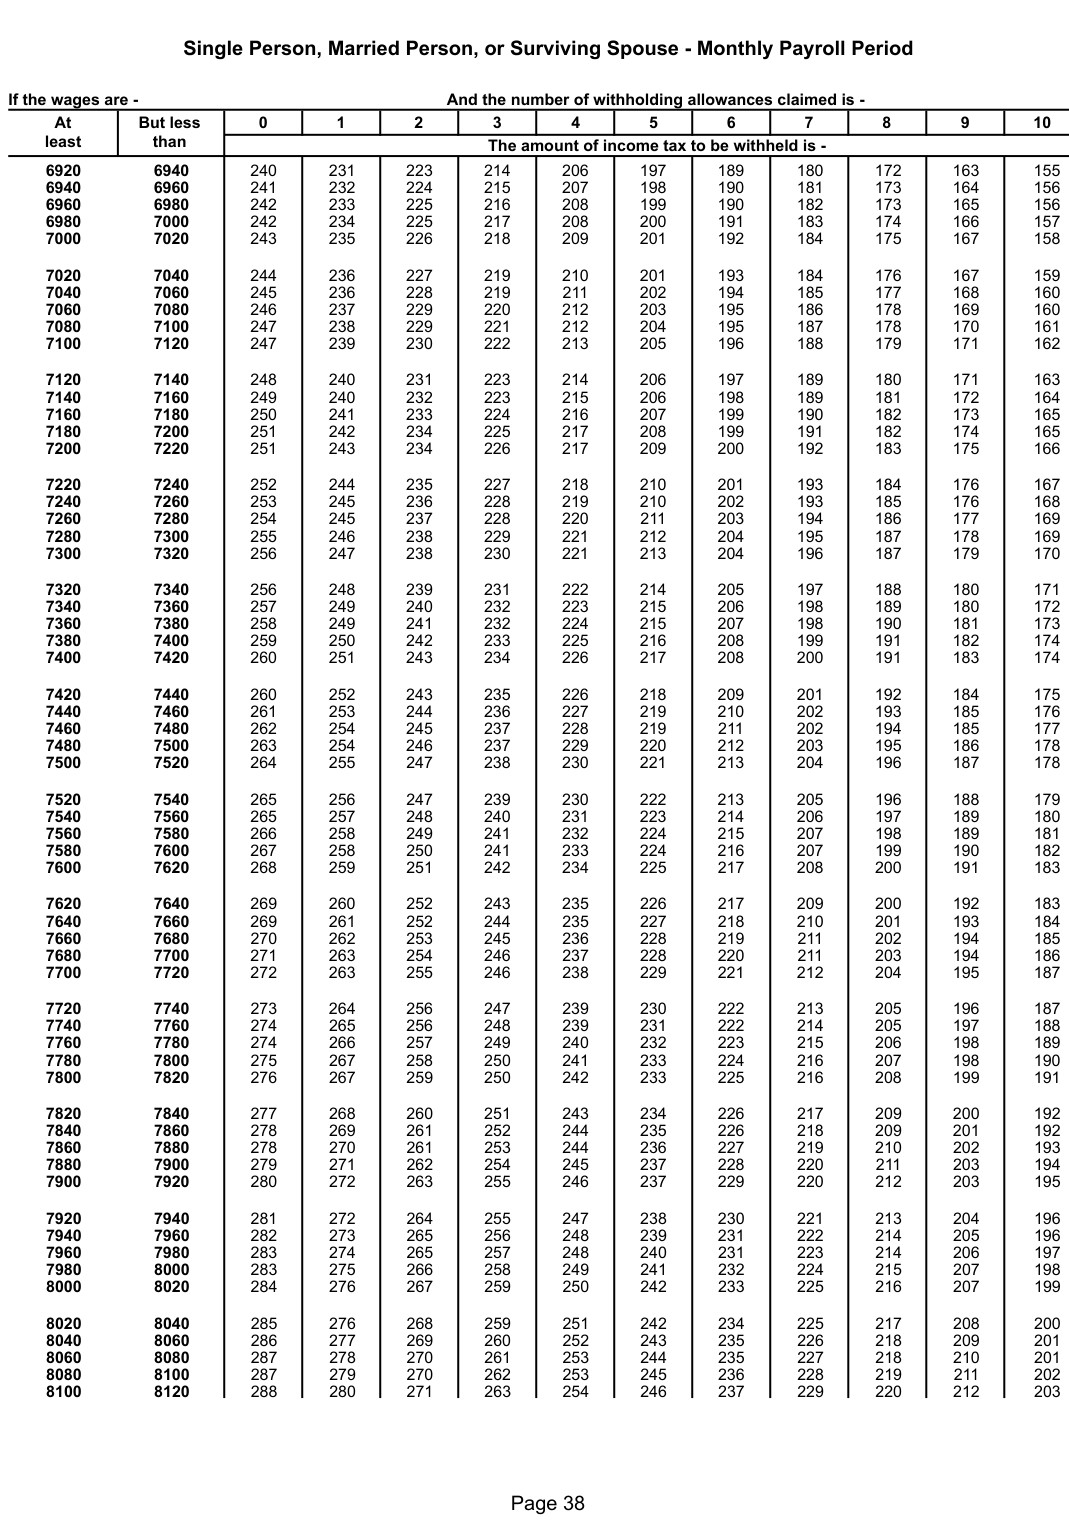
Text version of this table
| Single | Person, | Married | Person, | or Survi | ving Spo | use | - Monthly | Payroll Pe | riod | |||
| wages are - | And | the numbe | r of withh | olding | allowances | claimed is - | ||||||
| At B | ut less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
| least | than | The amou | nt of inco | me tax | to be withh | eld is - | ||||||
| 6920 | 6940 | 240 | 231 | 223 | 214 | 206 | 197 | 189 | 180 | 172 | 163 | 155 |
| 6940 | 6960 | 241 | 232 | 224 | 215 | 207 | 198 | 190 | 181 | 173 | 164 | 156 |
| 6960 | 6980 | 242 | 233 | 225 | 216 | 208 | 199 | 190 | 182 | 173 | 165 | 156 |
| 6980 | 7000 | 242 | 234 | 225 | 217 | 208 | 200 | 191 | 183 | 174 | 166 | 157 |
| 7000 | 7020 | 243 | 235 | 226 | 218 | 209 | 201 | 192 | 184 | 175 | 167 | 158 |
| 7020 | 7040 | 244 | 236 | 227 | 219 | 210 | 201 | 193 | 184 | 176 | 167 | 159 |
| 7040 | 7060 | 245 | 236 | 228 | 219 | 211 | 202 | 194 | 185 | 177 | 168 | 160 |
| 7060 | 7080 | 246 | 237 | 229 | 220 | 212 | 203 | 195 | 186 | 178 | 169 | 160 |
| 7080 | 7100 | 247 | 238 | 229 | 221 | 212 | 204 | 195 | 187 | 178 | 170 | 161 |
| 7100 | 7120 | 247 | 239 | 230 | 222 | 213 | 205 | 196 | 188 | 179 | 171 | 162 |
| 7120 | 7140 | 248 | 240 | 231 | 223 | 214 | 206 | 197 | 189 | 180 | 171 | 163 |
| 7140 | 7160 | 249 | 240 | 232 | 223 | 215 | 206 | 198 | 189 | 181 | 172 | 164 |
| 7160 | 7180 | 250 | 241 | 233 | 224 | 216 | 207 | 199 | 190 | 182 | 173 | 165 |
| 7180 | 7200 | 251 | 242 | 234 | 225 | 217 | 208 | 199 | 191 | 182 | 174 | 165 |
| 7200 | 7220 | 251 | 243 | 234 | 226 | 217 | 209 | 200 | 192 | 183 | 175 | 166 |
| 7220 | 7240 | 252 | 244 | 235 | 227 | 218 | 210 | 201 | 193 | 184 | 176 | 167 |
| 7240 | 7260 | 253 | 245 | 236 | 228 | 219 | 210 | 202 | 193 | 185 | 176 | 168 |
| 7260 | 7280 | 254 | 245 | 237 | 228 | 220 | 211 | 203 | 194 | 186 | 177 | 169 |
| 7280 | 7300 | 255 | 246 | 238 | 229 | 221 | 212 | 204 | 195 | 187 | 178 | 169 |
| 7300 | 7320 | 256 | 247 | 238 | 230 | 221 | 213 | 204 | 196 | 187 | 179 | 170 |
| 7320 | 7340 | 256 | 248 | 239 | 231 | 222 | 214 | 205 | 197 | 188 | 180 | 171 |
| 7340 | 7360 | 257 | 249 | 240 | 232 | 223 | 215 | 206 | 198 | 189 | 180 | 172 |
| 7360 | 7380 | 258 | 249 | 241 | 232 | 224 | 215 | 207 | 198 | 190 | 181 | 173 |
| 7380 | 7400 | 259 | 250 | 242 | 233 | 225 | 216 | 208 | 199 | 191 | 182 | 174 |
| 7400 | 7420 | 260 | 251 | 243 | 234 | 226 | 217 | 208 | 200 | 191 | 183 | 174 |
| 7420 | 7440 | 260 | 252 | 243 | 235 | 226 | 218 | 209 | 201 | 192 | 184 | 175 |
| 7440 | 7460 | 261 | 253 | 244 | 236 | 227 | 219 | 210 | 202 | 193 | 185 | 176 |
| 7460 | 7480 | 262 | 254 | 245 | 237 | 228 | 219 | 211 | 202 | 194 | 185 | 177 |
| 7480 | 7500 | 263 | 254 | 246 | 237 | 229 | 220 | 212 | 203 | 195 | 186 | 178 |
| 7500 | 7520 | 264 | 255 | 247 | 238 | 230 | 221 | 213 | 204 | 196 | 187 | 178 |
| 7520 | 7540 | 265 | 256 | 247 | 239 | 230 | 222 | 213 | 205 | 196 | 188 | 179 |
| 7540 | 7560 | 265 | 257 | 248 | 240 | 231 | 223 | 214 | 206 | 197 | 189 | 180 |
| 7560 | 7580 | 266 | 258 | 249 | 241 | 232 | 224 | 215 | 207 | 198 | 189 | 181 |
| 7580 | 7600 | 267 | 258 | 250 | 241 | 233 | 224 | 216 | 207 | 199 | 190 | 182 |
| 7600 | 7620 | 268 | 259 | 251 | 242 | 234 | 225 | 217 | 208 | 200 | 191 | 183 |
| 7620 | 7640 | 269 | 260 | 252 | 243 | 235 | 226 | 217 | 209 | 200 | 192 | 183 |
| 7640 | 7660 | 269 | 261 | 252 | 244 | 235 | 227 | 218 | 210 | 201 | 193 | 184 |
| 7660 | 7680 | 270 | 262 | 253 | 245 | 236 | 228 | 219 | 211 | 202 | 194 | 185 |
| 7680 | 7700 | 271 | 263 | 254 | 246 | 237 | 228 | 220 | 211 | 203 | 194 | 186 |
| 7700 | 7720 | 272 | 263 | 255 | 246 | 238 | 229 | 221 | 212 | 204 | 195 | 187 |
| 7720 | 7740 | 273 | 264 | 256 | 247 | 239 | 230 | 222 | 213 | 205 | 196 | 187 |
| 7740 | 7760 | 274 | 265 | 256 | 248 | 239 | 231 | 222 | 214 | 205 | 197 | 188 |
| 7760 | 7780 | 274 | 266 | 257 | 249 | 240 | 232 | 223 | 215 | 206 | 198 | 189 |
| 7780 | 7800 | 275 | 267 | 258 | 250 | 241 | 233 | 224 | 216 | 207 | 198 | 190 |
| 7800 | 7820 | 276 | 267 | 259 | 250 | 242 | 233 | 225 | 216 | 208 | 199 | 191 |
| 7820 | 7840 | 277 | 268 | 260 | 251 | 243 | 234 | 226 | 217 | 209 | 200 | 192 |
| 7840 | 7860 | 278 | 269 | 261 | 252 | 244 | 235 | 226 | 218 | 209 | 201 | 192 |
| 7860 | 7880 | 278 | 270 | 261 | 253 | 244 | 236 | 227 | 219 | 210 | 202 | 193 |
| 7880 | 7900 | 279 | 271 | 262 | 254 | 245 | 237 | 228 | 220 | 211 | 203 | 194 |
| 7900 | 7920 | 280 | 272 | 263 | 255 | 246 | 237 | 229 | 220 | 212 | 203 | 195 |
| 7920 | 7940 | 281 | 272 | 264 | 255 | 247 | 238 | 230 | 221 | 213 | 204 | 196 |
| 7940 | 7960 | 282 | 273 | 265 | 256 | 248 | 239 | 231 | 222 | 214 | 205 | 196 |
| 7960 | 7980 | 283 | 274 | 265 | 257 | 248 | 240 | 231 | 223 | 214 | 206 | 197 |
| 7980 | 8000 | 283 | 275 | 266 | 258 | 249 | 241 | 232 | 224 | 215 | 207 | 198 |
| 8000 | 8020 | 284 | 276 | 267 | 259 | 250 | 242 | 233 | 225 | 216 | 207 | 199 |
| 8020 | 8040 | 285 | 276 | 268 | 259 | 251 | 242 | 234 | 225 | 217 | 208 | 200 |
| 8040 | 8060 | 286 | 277 | 269 | 260 | 252 | 243 | 235 | 226 | 218 | 209 | 201 |
| 8060 | 8080 | 287 | 278 | 270 | 261 | 253 | 244 | 235 | 227 | 218 | 210 | 201 |
| 8080 | 8100 | 287 | 279 | 270 | 262 | 253 | 245 | 236 | 228 | 219 | 211 | 202 |
| 8100 | 8120 | 288 | 280 | 271 | 263 | 254 | 246 | 237 | 229 | 220 | 212 | 203 |
| Page | 38 |
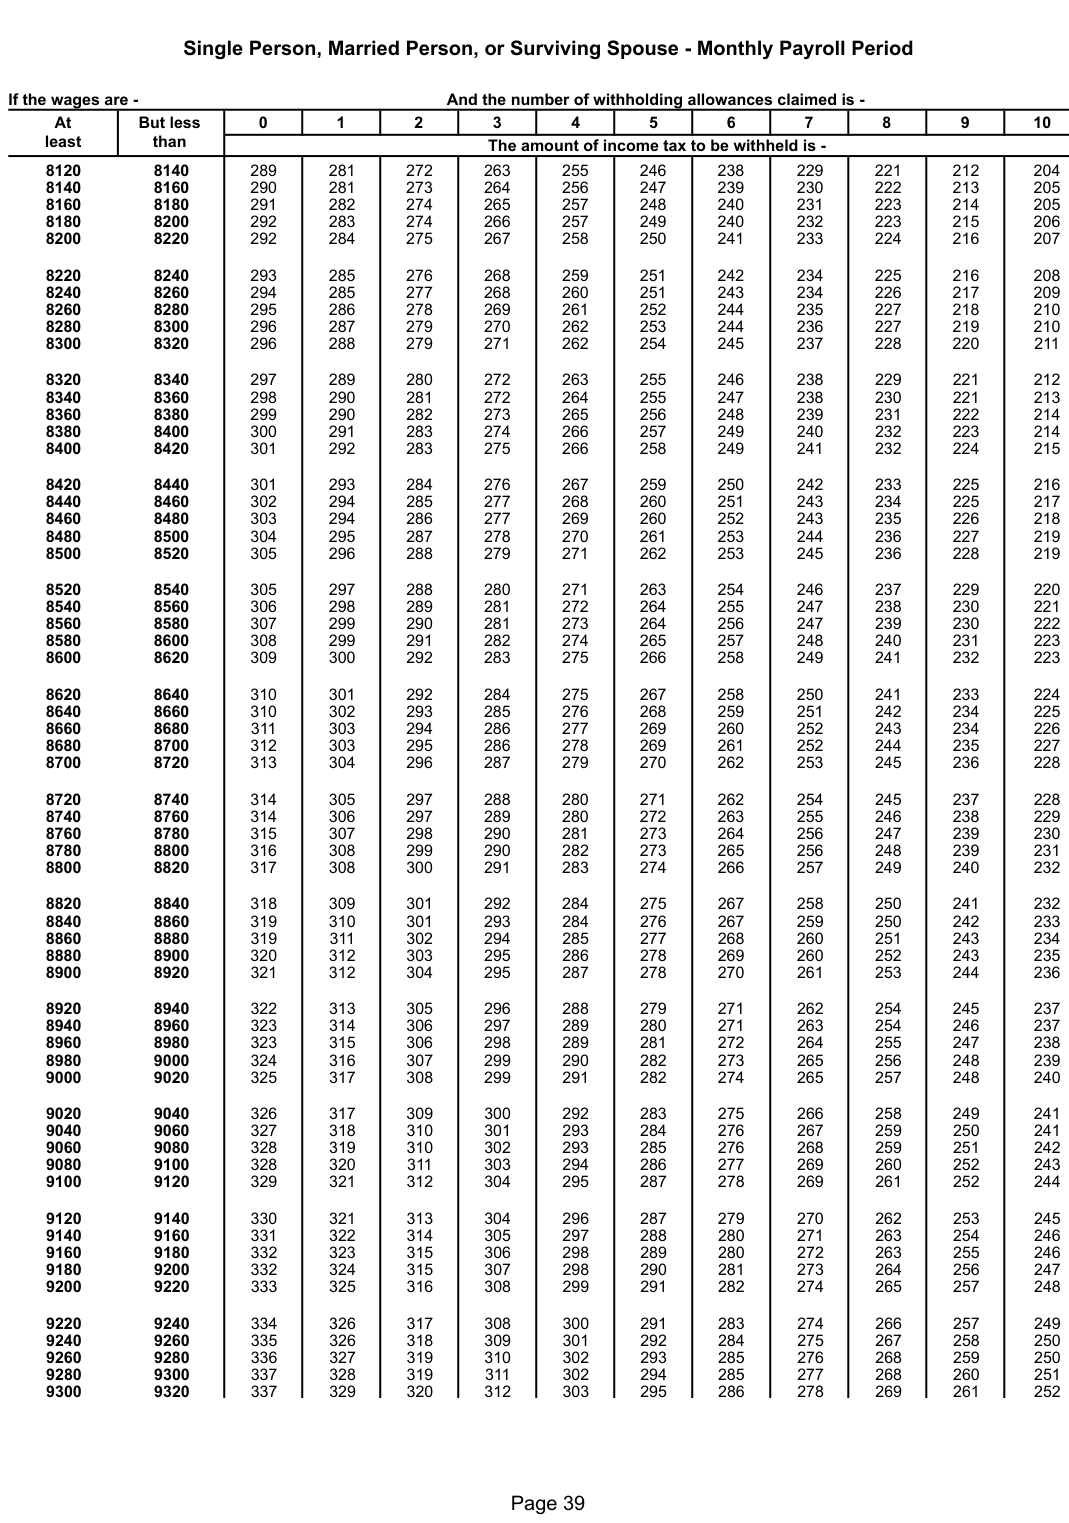
Text version of this table
| Single | Person, | Married | Person, | or Survi | ving Spo | use | - Monthly | Payroll Pe | riod | |||
| wages are - | And | the numbe | r of withh | olding | allowances | claimed is - | ||||||
| At B | ut less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
| least | than | The amou | nt of inco | me tax | to be withh | eld is - | ||||||
| 8120 | 8140 | 289 | 281 | 272 | 263 | 255 | 246 | 238 | 229 | 221 | 212 | 204 |
| 8140 | 8160 | 290 | 281 | 273 | 264 | 256 | 247 | 239 | 230 | 222 | 213 | 205 |
| 8160 | 8180 | 291 | 282 | 274 | 265 | 257 | 248 | 240 | 231 | 223 | 214 | 205 |
| 8180 | 8200 | 292 | 283 | 274 | 266 | 257 | 249 | 240 | 232 | 223 | 215 | 206 |
| 8200 | 8220 | 292 | 284 | 275 | 267 | 258 | 250 | 241 | 233 | 224 | 216 | 207 |
| 8220 | 8240 | 293 | 285 | 276 | 268 | 259 | 251 | 242 | 234 | 225 | 216 | 208 |
| 8240 | 8260 | 294 | 285 | 277 | 268 | 260 | 251 | 243 | 234 | 226 | 217 | 209 |
| 8260 | 8280 | 295 | 286 | 278 | 269 | 261 | 252 | 244 | 235 | 227 | 218 | 210 |
| 8280 | 8300 | 296 | 287 | 279 | 270 | 262 | 253 | 244 | 236 | 227 | 219 | 210 |
| 8300 | 8320 | 296 | 288 | 279 | 271 | 262 | 254 | 245 | 237 | 228 | 220 | 211 |
| 8320 | 8340 | 297 | 289 | 280 | 272 | 263 | 255 | 246 | 238 | 229 | 221 | 212 |
| 8340 | 8360 | 298 | 290 | 281 | 272 | 264 | 255 | 247 | 238 | 230 | 221 | 213 |
| 8360 | 8380 | 299 | 290 | 282 | 273 | 265 | 256 | 248 | 239 | 231 | 222 | 214 |
| 8380 | 8400 | 300 | 291 | 283 | 274 | 266 | 257 | 249 | 240 | 232 | 223 | 214 |
| 8400 | 8420 | 301 | 292 | 283 | 275 | 266 | 258 | 249 | 241 | 232 | 224 | 215 |
| 8420 | 8440 | 301 | 293 | 284 | 276 | 267 | 259 | 250 | 242 | 233 | 225 | 216 |
| 8440 | 8460 | 302 | 294 | 285 | 277 | 268 | 260 | 251 | 243 | 234 | 225 | 217 |
| 8460 | 8480 | 303 | 294 | 286 | 277 | 269 | 260 | 252 | 243 | 235 | 226 | 218 |
| 8480 | 8500 | 304 | 295 | 287 | 278 | 270 | 261 | 253 | 244 | 236 | 227 | 219 |
| 8500 | 8520 | 305 | 296 | 288 | 279 | 271 | 262 | 253 | 245 | 236 | 228 | 219 |
| 8520 | 8540 | 305 | 297 | 288 | 280 | 271 | 263 | 254 | 246 | 237 | 229 | 220 |
| 8540 | 8560 | 306 | 298 | 289 | 281 | 272 | 264 | 255 | 247 | 238 | 230 | 221 |
| 8560 | 8580 | 307 | 299 | 290 | 281 | 273 | 264 | 256 | 247 | 239 | 230 | 222 |
| 8580 | 8600 | 308 | 299 | 291 | 282 | 274 | 265 | 257 | 248 | 240 | 231 | 223 |
| 8600 | 8620 | 309 | 300 | 292 | 283 | 275 | 266 | 258 | 249 | 241 | 232 | 223 |
| 8620 | 8640 | 310 | 301 | 292 | 284 | 275 | 267 | 258 | 250 | 241 | 233 | 224 |
| 8640 | 8660 | 310 | 302 | 293 | 285 | 276 | 268 | 259 | 251 | 242 | 234 | 225 |
| 8660 | 8680 | 311 | 303 | 294 | 286 | 277 | 269 | 260 | 252 | 243 | 234 | 226 |
| 8680 | 8700 | 312 | 303 | 295 | 286 | 278 | 269 | 261 | 252 | 244 | 235 | 227 |
| 8700 | 8720 | 313 | 304 | 296 | 287 | 279 | 270 | 262 | 253 | 245 | 236 | 228 |
| 8720 | 8740 | 314 | 305 | 297 | 288 | 280 | 271 | 262 | 254 | 245 | 237 | 228 |
| 8740 | 8760 | 314 | 306 | 297 | 289 | 280 | 272 | 263 | 255 | 246 | 238 | 229 |
| 8760 | 8780 | 315 | 307 | 298 | 290 | 281 | 273 | 264 | 256 | 247 | 239 | 230 |
| 8780 | 8800 | 316 | 308 | 299 | 290 | 282 | 273 | 265 | 256 | 248 | 239 | 231 |
| 8800 | 8820 | 317 | 308 | 300 | 291 | 283 | 274 | 266 | 257 | 249 | 240 | 232 |
| 8820 | 8840 | 318 | 309 | 301 | 292 | 284 | 275 | 267 | 258 | 250 | 241 | 232 |
| 8840 | 8860 | 319 | 310 | 301 | 293 | 284 | 276 | 267 | 259 | 250 | 242 | 233 |
| 8860 | 8880 | 319 | 311 | 302 | 294 | 285 | 277 | 268 | 260 | 251 | 243 | 234 |
| 8880 | 8900 | 320 | 312 | 303 | 295 | 286 | 278 | 269 | 260 | 252 | 243 | 235 |
| 8900 | 8920 | 321 | 312 | 304 | 295 | 287 | 278 | 270 | 261 | 253 | 244 | 236 |
| 8920 | 8940 | 322 | 313 | 305 | 296 | 288 | 279 | 271 | 262 | 254 | 245 | 237 |
| 8940 | 8960 | 323 | 314 | 306 | 297 | 289 | 280 | 271 | 263 | 254 | 246 | 237 |
| 8960 | 8980 | 323 | 315 | 306 | 298 | 289 | 281 | 272 | 264 | 255 | 247 | 238 |
| 8980 | 9000 | 324 | 316 | 307 | 299 | 290 | 282 | 273 | 265 | 256 | 248 | 239 |
| 9000 | 9020 | 325 | 317 | 308 | 299 | 291 | 282 | 274 | 265 | 257 | 248 | 240 |
| 9020 | 9040 | 326 | 317 | 309 | 300 | 292 | 283 | 275 | 266 | 258 | 249 | 241 |
| 9040 | 9060 | 327 | 318 | 310 | 301 | 293 | 284 | 276 | 267 | 259 | 250 | 241 |
| 9060 | 9080 | 328 | 319 | 310 | 302 | 293 | 285 | 276 | 268 | 259 | 251 | 242 |
| 9080 | 9100 | 328 | 320 | 311 | 303 | 294 | 286 | 277 | 269 | 260 | 252 | 243 |
| 9100 | 9120 | 329 | 321 | 312 | 304 | 295 | 287 | 278 | 269 | 261 | 252 | 244 |
| 9120 | 9140 | 330 | 321 | 313 | 304 | 296 | 287 | 279 | 270 | 262 | 253 | 245 |
| 9140 | 9160 | 331 | 322 | 314 | 305 | 297 | 288 | 280 | 271 | 263 | 254 | 246 |
| 9160 | 9180 | 332 | 323 | 315 | 306 | 298 | 289 | 280 | 272 | 263 | 255 | 246 |
| 9180 | 9200 | 332 | 324 | 315 | 307 | 298 | 290 | 281 | 273 | 264 | 256 | 247 |
| 9200 | 9220 | 333 | 325 | 316 | 308 | 299 | 291 | 282 | 274 | 265 | 257 | 248 |
| 9220 | 9240 | 334 | 326 | 317 | 308 | 300 | 291 | 283 | 274 | 266 | 257 | 249 |
| 9240 | 9260 | 335 | 326 | 318 | 309 | 301 | 292 | 284 | 275 | 267 | 258 | 250 |
| 9260 | 9280 | 336 | 327 | 319 | 310 | 302 | 293 | 285 | 276 | 268 | 259 | 250 |
| 9280 | 9300 | 337 | 328 | 319 | 311 | 302 | 294 | 285 | 277 | 268 | 260 | 251 |
| 9300 | 9320 | 337 | 329 | 320 | 312 | 303 | 295 | 286 | 278 | 269 | 261 | 252 |
| Page | 39 |
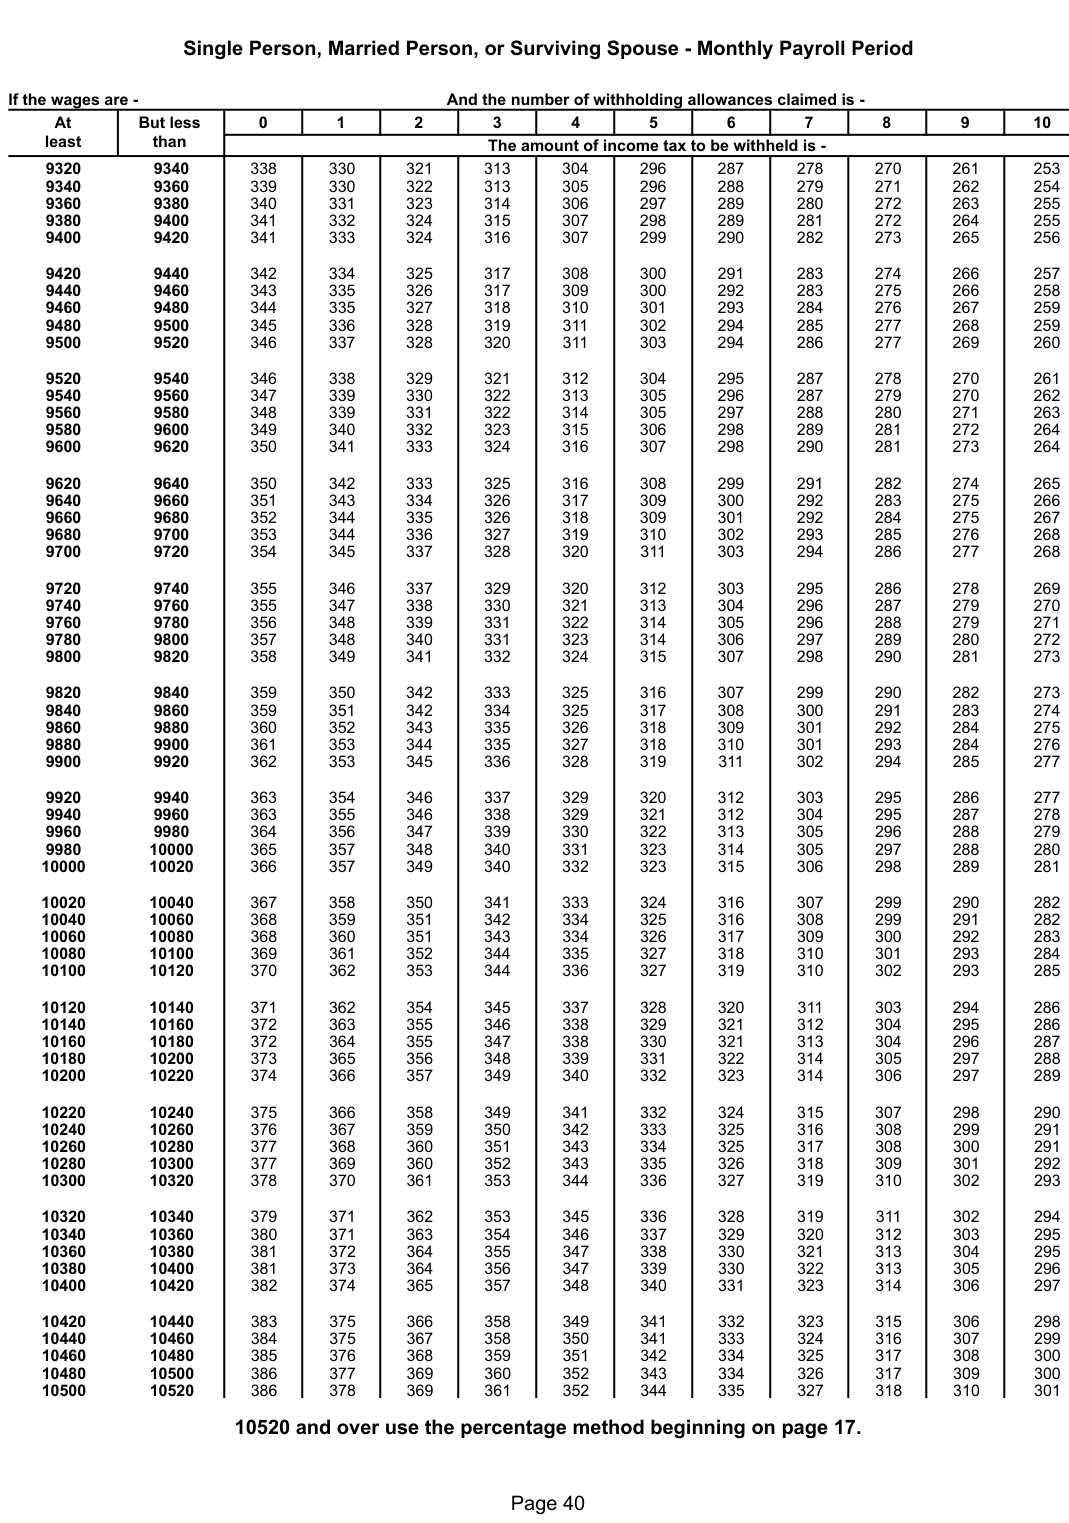
Text version of this table
| Singl | e Person, | Married | Person, | or Survi | ving Spo | use | - Monthly | Payroll Pe | riod | |||
| e wages are - | And | the numbe | r of withh | olding | allowances | claimed is - | ||||||
| At B | ut less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
| least | than | The amou | nt of inco | me tax | to be withh | eld is - | ||||||
| 9320 | 9340 | 338 | 330 | 321 | 313 | 304 | 296 | 287 | 278 | 270 | 261 | 253 |
| 9340 | 9360 | 339 | 330 | 322 | 313 | 305 | 296 | 288 | 279 | 271 | 262 | 254 |
| 9360 | 9380 | 340 | 331 | 323 | 314 | 306 | 297 | 289 | 280 | 272 | 263 | 255 |
| 9380 | 9400 | 341 | 332 | 324 | 315 | 307 | 298 | 289 | 281 | 272 | 264 | 255 |
| 9400 | 9420 | 341 | 333 | 324 | 316 | 307 | 299 | 290 | 282 | 273 | 265 | 256 |
| 9420 | 9440 | 342 | 334 | 325 | 317 | 308 | 300 | 291 | 283 | 274 | 266 | 257 |
| 9440 | 9460 | 343 | 335 | 326 | 317 | 309 | 300 | 292 | 283 | 275 | 266 | 258 |
| 9460 | 9480 | 344 | 335 | 327 | 318 | 310 | 301 | 293 | 284 | 276 | 267 | 259 |
| 9480 | 9500 | 345 | 336 | 328 | 319 | 311 | 302 | 294 | 285 | 277 | 268 | 259 |
| 9500 | 9520 | 346 | 337 | 328 | 320 | 311 | 303 | 294 | 286 | 277 | 269 | 260 |
| 9520 | 9540 | 346 | 338 | 329 | 321 | 312 | 304 | 295 | 287 | 278 | 270 | 261 |
| 9540 | 9560 | 347 | 339 | 330 | 322 | 313 | 305 | 296 | 287 | 279 | 270 | 262 |
| 9560 | 9580 | 348 | 339 | 331 | 322 | 314 | 305 | 297 | 288 | 280 | 271 | 263 |
| 9580 | 9600 | 349 | 340 | 332 | 323 | 315 | 306 | 298 | 289 | 281 | 272 | 264 |
| 9600 | 9620 | 350 | 341 | 333 | 324 | 316 | 307 | 298 | 290 | 281 | 273 | 264 |
| 9620 | 9640 | 350 | 342 | 333 | 325 | 316 | 308 | 299 | 291 | 282 | 274 | 265 |
| 9640 | 9660 | 351 | 343 | 334 | 326 | 317 | 309 | 300 | 292 | 283 | 275 | 266 |
| 9660 | 9680 | 352 | 344 | 335 | 326 | 318 | 309 | 301 | 292 | 284 | 275 | 267 |
| 9680 | 9700 | 353 | 344 | 336 | 327 | 319 | 310 | 302 | 293 | 285 | 276 | 268 |
| 9700 | 9720 | 354 | 345 | 337 | 328 | 320 | 311 | 303 | 294 | 286 | 277 | 268 |
| 9720 | 9740 | 355 | 346 | 337 | 329 | 320 | 312 | 303 | 295 | 286 | 278 | 269 |
| 9740 | 9760 | 355 | 347 | 338 | 330 | 321 | 313 | 304 | 296 | 287 | 279 | 270 |
| 9760 | 9780 | 356 | 348 | 339 | 331 | 322 | 314 | 305 | 296 | 288 | 279 | 271 |
| 9780 | 9800 | 357 | 348 | 340 | 331 | 323 | 314 | 306 | 297 | 289 | 280 | 272 |
| 9800 | 9820 | 358 | 349 | 341 | 332 | 324 | 315 | 307 | 298 | 290 | 281 | 273 |
| 9820 | 9840 | 359 | 350 | 342 | 333 | 325 | 316 | 307 | 299 | 290 | 282 | 273 |
| 9840 | 9860 | 359 | 351 | 342 | 334 | 325 | 317 | 308 | 300 | 291 | 283 | 274 |
| 9860 | 9880 | 360 | 352 | 343 | 335 | 326 | 318 | 309 | 301 | 292 | 284 | 275 |
| 9880 | 9900 | 361 | 353 | 344 | 335 | 327 | 318 | 310 | 301 | 293 | 284 | 276 |
| 9900 | 9920 | 362 | 353 | 345 | 336 | 328 | 319 | 311 | 302 | 294 | 285 | 277 |
| 9920 | 9940 | 363 | 354 | 346 | 337 | 329 | 320 | 312 | 303 | 295 | 286 | 277 |
| 9940 | 9960 | 363 | 355 | 346 | 338 | 329 | 321 | 312 | 304 | 295 | 287 | 278 |
| 9960 | 9980 | 364 | 356 | 347 | 339 | 330 | 322 | 313 | 305 | 296 | 288 | 279 |
| 9980 | 10000 | 365 | 357 | 348 | 340 | 331 | 323 | 314 | 305 | 297 | 288 | 280 |
| 10000 | 10020 | 366 | 357 | 349 | 340 | 332 | 323 | 315 | 306 | 298 | 289 | 281 |
| 10020 | 10040 | 367 | 358 | 350 | 341 | 333 | 324 | 316 | 307 | 299 | 290 | 282 |
| 10040 | 10060 | 368 | 359 | 351 | 342 | 334 | 325 | 316 | 308 | 299 | 291 | 282 |
| 10060 | 10080 | 368 | 360 | 351 | 343 | 334 | 326 | 317 | 309 | 300 | 292 | 283 |
| 10080 | 10100 | 369 | 361 | 352 | 344 | 335 | 327 | 318 | 310 | 301 | 293 | 284 |
| 10100 | 10120 | 370 | 362 | 353 | 344 | 336 | 327 | 319 | 310 | 302 | 293 | 285 |
| 10120 | 10140 | 371 | 362 | 354 | 345 | 337 | 328 | 320 | 311 | 303 | 294 | 286 |
| 10140 | 10160 | 372 | 363 | 355 | 346 | 338 | 329 | 321 | 312 | 304 | 295 | 286 |
| 10160 | 10180 | 372 | 364 | 355 | 347 | 338 | 330 | 321 | 313 | 304 | 296 | 287 |
| 10180 | 10200 | 373 | 365 | 356 | 348 | 339 | 331 | 322 | 314 | 305 | 297 | 288 |
| 10200 | 10220 | 374 | 366 | 357 | 349 | 340 | 332 | 323 | 314 | 306 | 297 | 289 |
| 10220 | 10240 | 375 | 366 | 358 | 349 | 341 | 332 | 324 | 315 | 307 | 298 | 290 |
| 10240 | 10260 | 376 | 367 | 359 | 350 | 342 | 333 | 325 | 316 | 308 | 299 | 291 |
| 10260 | 10280 | 377 | 368 | 360 | 351 | 343 | 334 | 325 | 317 | 308 | 300 | 291 |
| 10280 | 10300 | 377 | 369 | 360 | 352 | 343 | 335 | 326 | 318 | 309 | 301 | 292 |
| 10300 | 10320 | 378 | 370 | 361 | 353 | 344 | 336 | 327 | 319 | 310 | 302 | 293 |
| 10320 | 10340 | 379 | 371 | 362 | 353 | 345 | 336 | 328 | 319 | 311 | 302 | 294 |
| 10340 | 10360 | 380 | 371 | 363 | 354 | 346 | 337 | 329 | 320 | 312 | 303 | 295 |
| 10360 | 10380 | 381 | 372 | 364 | 355 | 347 | 338 | 330 | 321 | 313 | 304 | 295 |
| 10380 | 10400 | 381 | 373 | 364 | 356 | 347 | 339 | 330 | 322 | 313 | 305 | 296 |
| 10400 | 10420 | 382 | 374 | 365 | 357 | 348 | 340 | 331 | 323 | 314 | 306 | 297 |
| 10420 | 10440 | 383 | 375 | 366 | 358 | 349 | 341 | 332 | 323 | 315 | 306 | 298 |
| 10440 | 10460 | 384 | 375 | 367 | 358 | 350 | 341 | 333 | 324 | 316 | 307 | 299 |
| 10460 | 10480 | 385 | 376 | 368 | 359 | 351 | 342 | 334 | 325 | 317 | 308 | 300 |
| 10480 | 10500 | 386 | 377 | 369 | 360 | 352 | 343 | 334 | 326 | 317 | 309 | 300 |
| 10500 | 10520 | 386 | 378 | 369 | 361 | 352 | 344 | 335 | 327 | 318 | 310 | 301 |
| 10520 and | over us | e the pe | rcentage | method | beg | inning on | page 17. | |||||
| Page | 40 |
# Head of Household - Weekly Payroll Period
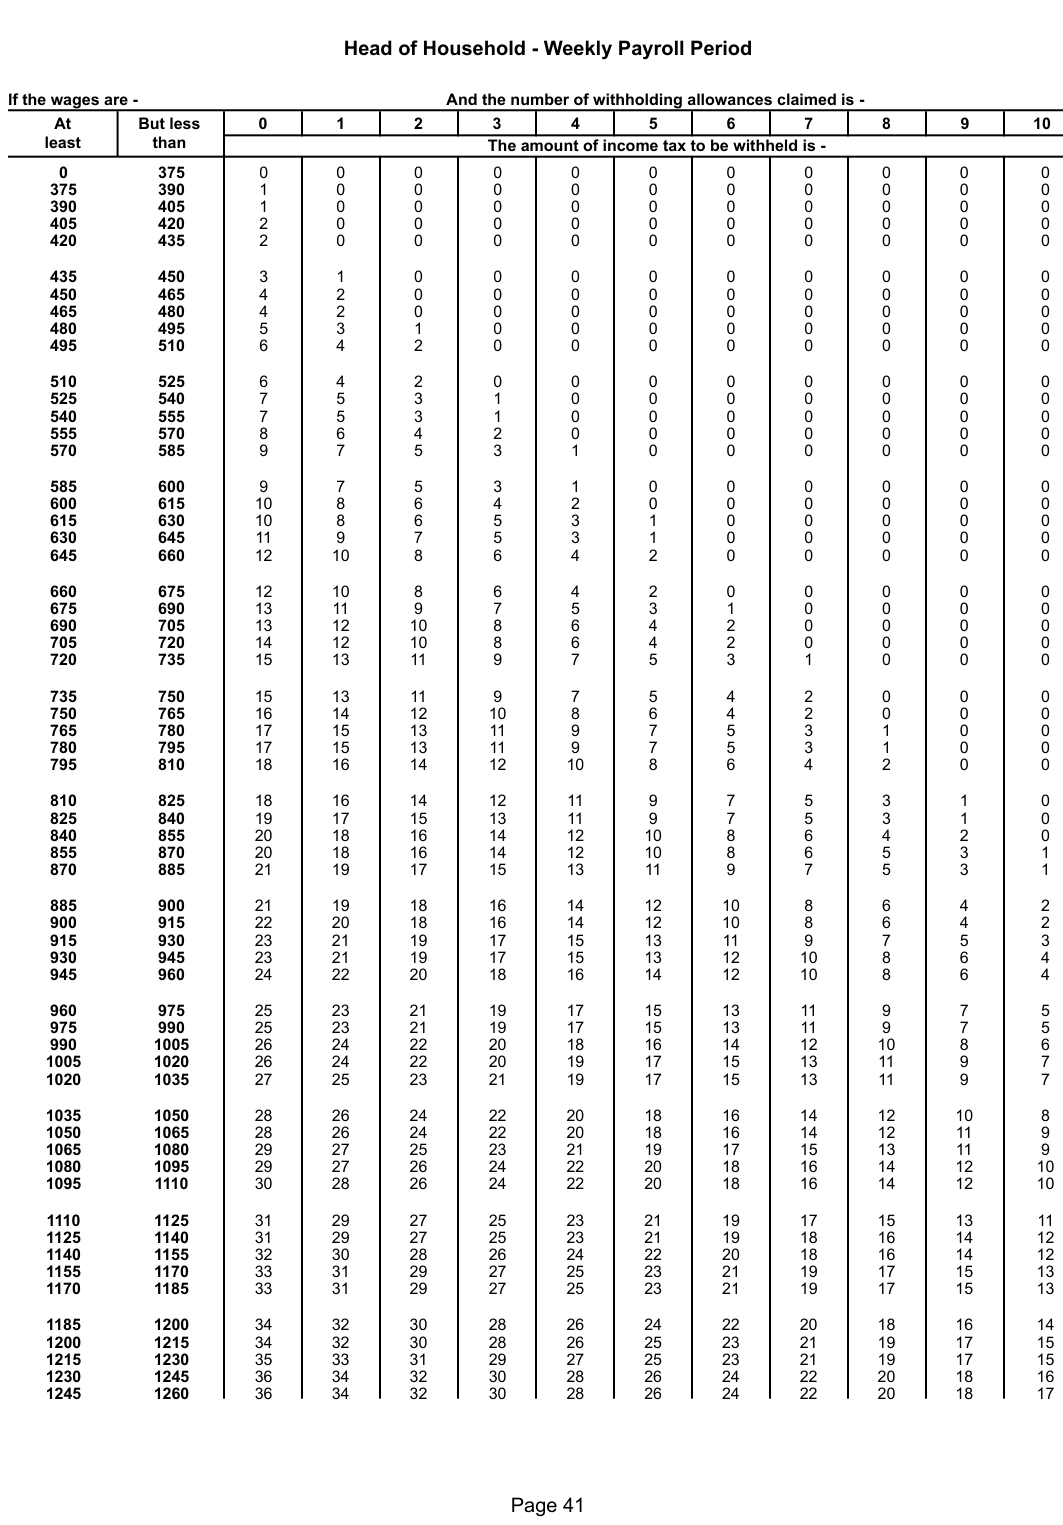
Text version of this table
| Head o | f House | hold - W | eekly | Payroll | Period | |||||||
| wages are - | And t | he numbe | r of wit | hholding | allowances | claimed is - | ||||||
| At B | ut less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
| least | than | The amou | nt of in | come tax | to be withh | eld is - | ||||||
| 0 | 375 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 375 | 390 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 390 | 405 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 405 | 420 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 420 | 435 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 435 | 450 | 3 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 450 | 465 | 4 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 465 | 480 | 4 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 480 | 495 | 5 | 3 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 495 | 510 | 6 | 4 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 510 | 525 | 6 | 4 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 525 | 540 | 7 | 5 | 3 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 540 | 555 | 7 | 5 | 3 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 555 | 570 | 8 | 6 | 4 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 570 | 585 | 9 | 7 | 5 | 3 | 1 | 0 | 0 | 0 | 0 | 0 | 0 |
| 585 | 600 | 9 | 7 | 5 | 3 | 1 | 0 | 0 | 0 | 0 | 0 | 0 |
| 600 | 615 | 10 | 8 | 6 | 4 | 2 | 0 | 0 | 0 | 0 | 0 | 0 |
| 615 | 630 | 10 | 8 | 6 | 5 | 3 | 1 | 0 | 0 | 0 | 0 | 0 |
| 630 | 645 | 11 | 9 | 7 | 5 | 3 | 1 | 0 | 0 | 0 | 0 | 0 |
| 645 | 660 | 12 | 10 | 8 | 6 | 4 | 2 | 0 | 0 | 0 | 0 | 0 |
| 660 | 675 | 12 | 10 | 8 | 6 | 4 | 2 | 0 | 0 | 0 | 0 | 0 |
| 675 | 690 | 13 | 11 | 9 | 7 | 5 | 3 | 1 | 0 | 0 | 0 | 0 |
| 690 | 705 | 13 | 12 | 10 | 8 | 6 | 4 | 2 | 0 | 0 | 0 | 0 |
| 705 | 720 | 14 | 12 | 10 | 8 | 6 | 4 | 2 | 0 | 0 | 0 | 0 |
| 720 | 735 | 15 | 13 | 11 | 9 | 7 | 5 | 3 | 1 | 0 | 0 | 0 |
| 735 | 750 | 15 | 13 | 11 | 9 | 7 | 5 | 4 | 2 | 0 | 0 | 0 |
| 750 | 765 | 16 | 14 | 12 | 10 | 8 | 6 | 4 | 2 | 0 | 0 | 0 |
| 765 | 780 | 17 | 15 | 13 | 11 | 9 | 7 | 5 | 3 | 1 | 0 | 0 |
| 780 | 795 | 17 | 15 | 13 | 11 | 9 | 7 | 5 | 3 | 1 | 0 | 0 |
| 795 | 810 | 18 | 16 | 14 | 12 | 10 | 8 | 6 | 4 | 2 | 0 | 0 |
| 810 | 825 | 18 | 16 | 14 | 12 | 11 | 9 | 7 | 5 | 3 | 1 | 0 |
| 825 | 840 | 19 | 17 | 15 | 13 | 11 | 9 | 7 | 5 | 3 | 1 | 0 |
| 840 | 855 | 20 | 18 | 16 | 14 | 12 | 10 | 8 | 6 | 4 | 2 | 0 |
| 855 | 870 | 20 | 18 | 16 | 14 | 12 | 10 | 8 | 6 | 5 | 3 | 1 |
| 870 | 885 | 21 | 19 | 17 | 15 | 13 | 11 | 9 | 7 | 5 | 3 | 1 |
| 885 | 900 | 21 | 19 | 18 | 16 | 14 | 12 | 10 | 8 | 6 | 4 | 2 |
| 900 | 915 | 22 | 20 | 18 | 16 | 14 | 12 | 10 | 8 | 6 | 4 | 2 |
| 915 | 930 | 23 | 21 | 19 | 17 | 15 | 13 | 11 | 9 | 7 | 5 | 3 |
| 930 | 945 | 23 | 21 | 19 | 17 | 15 | 13 | 12 | 10 | 8 | 6 | 4 |
| 945 | 960 | 24 | 22 | 20 | 18 | 16 | 14 | 12 | 10 | 8 | 6 | 4 |
| 960 | 975 | 25 | 23 | 21 | 19 | 17 | 15 | 13 | 11 | 9 | 7 | 5 |
| 975 | 990 | 25 | 23 | 21 | 19 | 17 | 15 | 13 | 11 | 9 | 7 | 5 |
| 990 | 1005 | 26 | 24 | 22 | 20 | 18 | 16 | 14 | 12 | 10 | 8 | 6 |
| 1005 | 1020 | 26 | 24 | 22 | 20 | 19 | 17 | 15 | 13 | 11 | 9 | 7 |
| 1020 | 1035 | 27 | 25 | 23 | 21 | 19 | 17 | 15 | 13 | 11 | 9 | 7 |
| 1035 | 1050 | 28 | 26 | 24 | 22 | 20 | 18 | 16 | 14 | 12 | 10 | 8 |
| 1050 | 1065 | 28 | 26 | 24 | 22 | 20 | 18 | 16 | 14 | 12 | 11 | 9 |
| 1065 | 1080 | 29 | 27 | 25 | 23 | 21 | 19 | 17 | 15 | 13 | 11 | 9 |
| 1080 | 1095 | 29 | 27 | 26 | 24 | 22 | 20 | 18 | 16 | 14 | 12 | 10 |
| 1095 | 1110 | 30 | 28 | 26 | 24 | 22 | 20 | 18 | 16 | 14 | 12 | 10 |
| 1110 | 1125 | 31 | 29 | 27 | 25 | 23 | 21 | 19 | 17 | 15 | 13 | 11 |
| 1125 | 1140 | 31 | 29 | 27 | 25 | 23 | 21 | 19 | 18 | 16 | 14 | 12 |
| 1140 | 1155 | 32 | 30 | 28 | 26 | 24 | 22 | 20 | 18 | 16 | 14 | 12 |
| 1155 | 1170 | 33 | 31 | 29 | 27 | 25 | 23 | 21 | 19 | 17 | 15 | 13 |
| 1170 | 1185 | 33 | 31 | 29 | 27 | 25 | 23 | 21 | 19 | 17 | 15 | 13 |
| 1185 | 1200 | 34 | 32 | 30 | 28 | 26 | 24 | 22 | 20 | 18 | 16 | 14 |
| 1200 | 1215 | 34 | 32 | 30 | 28 | 26 | 25 | 23 | 21 | 19 | 17 | 15 |
| 1215 | 1230 | 35 | 33 | 31 | 29 | 27 | 25 | 23 | 21 | 19 | 17 | 15 |
| 1230 | 1245 | 36 | 34 | 32 | 30 | 28 | 26 | 24 | 22 | 20 | 18 | 16 |
| 1245 | 1260 | 36 | 34 | 32 | 30 | 28 | 26 | 24 | 22 | 20 | 18 | 17 |
| Page | 41 |
# Head of Household - Weekly Payroll Period
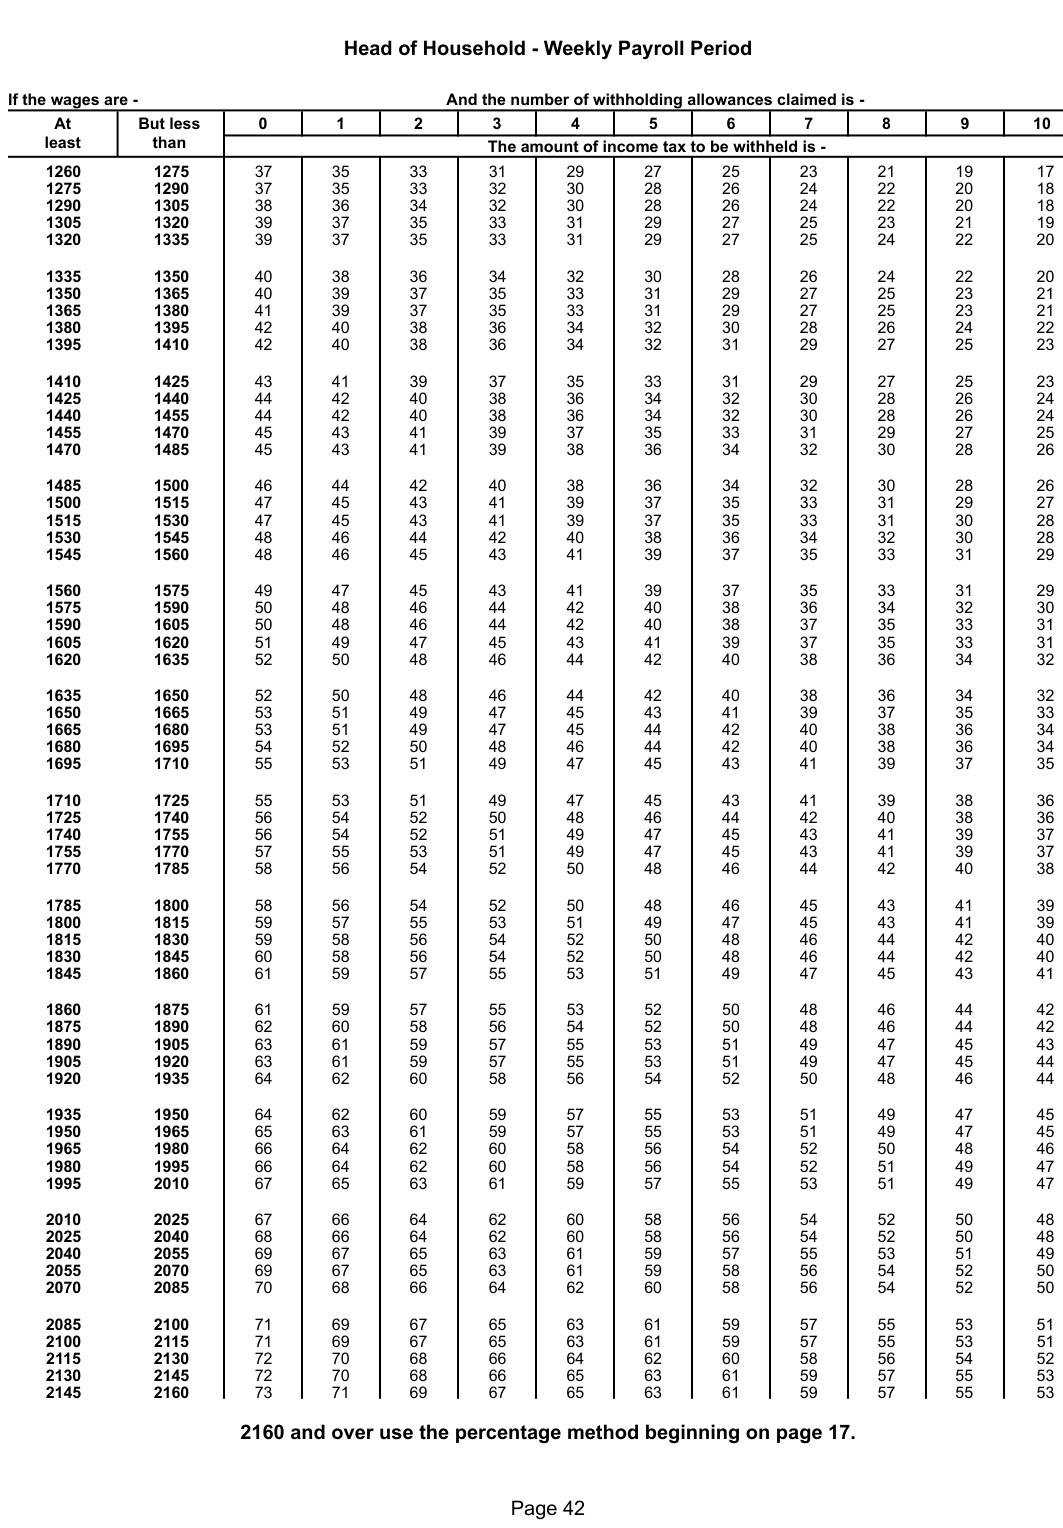
Text version of this table
| Head o | f House | hold - W | eekly | Payroll | Period | |||||||
| wages are - | And t | he numbe | r of wit | hholding | allowances | claimed is - | ||||||
| At B | ut less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
| least | than | The amou | nt of in | come tax | to be withh | eld is - | ||||||
| 1260 | 1275 | 37 | 35 | 33 | 31 | 29 | 27 | 25 | 23 | 21 | 19 | 17 |
| 1275 | 1290 | 37 | 35 | 33 | 32 | 30 | 28 | 26 | 24 | 22 | 20 | 18 |
| 1290 | 1305 | 38 | 36 | 34 | 32 | 30 | 28 | 26 | 24 | 22 | 20 | 18 |
| 1305 | 1320 | 39 | 37 | 35 | 33 | 31 | 29 | 27 | 25 | 23 | 21 | 19 |
| 1320 | 1335 | 39 | 37 | 35 | 33 | 31 | 29 | 27 | 25 | 24 | 22 | 20 |
| 1335 | 1350 | 40 | 38 | 36 | 34 | 32 | 30 | 28 | 26 | 24 | 22 | 20 |
| 1350 | 1365 | 40 | 39 | 37 | 35 | 33 | 31 | 29 | 27 | 25 | 23 | 21 |
| 1365 | 1380 | 41 | 39 | 37 | 35 | 33 | 31 | 29 | 27 | 25 | 23 | 21 |
| 1380 | 1395 | 42 | 40 | 38 | 36 | 34 | 32 | 30 | 28 | 26 | 24 | 22 |
| 1395 | 1410 | 42 | 40 | 38 | 36 | 34 | 32 | 31 | 29 | 27 | 25 | 23 |
| 1410 | 1425 | 43 | 41 | 39 | 37 | 35 | 33 | 31 | 29 | 27 | 25 | 23 |
| 1425 | 1440 | 44 | 42 | 40 | 38 | 36 | 34 | 32 | 30 | 28 | 26 | 24 |
| 1440 | 1455 | 44 | 42 | 40 | 38 | 36 | 34 | 32 | 30 | 28 | 26 | 24 |
| 1455 | 1470 | 45 | 43 | 41 | 39 | 37 | 35 | 33 | 31 | 29 | 27 | 25 |
| 1470 | 1485 | 45 | 43 | 41 | 39 | 38 | 36 | 34 | 32 | 30 | 28 | 26 |
| 1485 | 1500 | 46 | 44 | 42 | 40 | 38 | 36 | 34 | 32 | 30 | 28 | 26 |
| 1500 | 1515 | 47 | 45 | 43 | 41 | 39 | 37 | 35 | 33 | 31 | 29 | 27 |
| 1515 | 1530 | 47 | 45 | 43 | 41 | 39 | 37 | 35 | 33 | 31 | 30 | 28 |
| 1530 | 1545 | 48 | 46 | 44 | 42 | 40 | 38 | 36 | 34 | 32 | 30 | 28 |
| 1545 | 1560 | 48 | 46 | 45 | 43 | 41 | 39 | 37 | 35 | 33 | 31 | 29 |
| 1560 | 1575 | 49 | 47 | 45 | 43 | 41 | 39 | 37 | 35 | 33 | 31 | 29 |
| 1575 | 1590 | 50 | 48 | 46 | 44 | 42 | 40 | 38 | 36 | 34 | 32 | 30 |
| 1590 | 1605 | 50 | 48 | 46 | 44 | 42 | 40 | 38 | 37 | 35 | 33 | 31 |
| 1605 | 1620 | 51 | 49 | 47 | 45 | 43 | 41 | 39 | 37 | 35 | 33 | 31 |
| 1620 | 1635 | 52 | 50 | 48 | 46 | 44 | 42 | 40 | 38 | 36 | 34 | 32 |
| 1635 | 1650 | 52 | 50 | 48 | 46 | 44 | 42 | 40 | 38 | 36 | 34 | 32 |
| 1650 | 1665 | 53 | 51 | 49 | 47 | 45 | 43 | 41 | 39 | 37 | 35 | 33 |
| 1665 | 1680 | 53 | 51 | 49 | 47 | 45 | 44 | 42 | 40 | 38 | 36 | 34 |
| 1680 | 1695 | 54 | 52 | 50 | 48 | 46 | 44 | 42 | 40 | 38 | 36 | 34 |
| 1695 | 1710 | 55 | 53 | 51 | 49 | 47 | 45 | 43 | 41 | 39 | 37 | 35 |
| 1710 | 1725 | 55 | 53 | 51 | 49 | 47 | 45 | 43 | 41 | 39 | 38 | 36 |
| 1725 | 1740 | 56 | 54 | 52 | 50 | 48 | 46 | 44 | 42 | 40 | 38 | 36 |
| 1740 | 1755 | 56 | 54 | 52 | 51 | 49 | 47 | 45 | 43 | 41 | 39 | 37 |
| 1755 | 1770 | 57 | 55 | 53 | 51 | 49 | 47 | 45 | 43 | 41 | 39 | 37 |
| 1770 | 1785 | 58 | 56 | 54 | 52 | 50 | 48 | 46 | 44 | 42 | 40 | 38 |
| 1785 | 1800 | 58 | 56 | 54 | 52 | 50 | 48 | 46 | 45 | 43 | 41 | 39 |
| 1800 | 1815 | 59 | 57 | 55 | 53 | 51 | 49 | 47 | 45 | 43 | 41 | 39 |
| 1815 | 1830 | 59 | 58 | 56 | 54 | 52 | 50 | 48 | 46 | 44 | 42 | 40 |
| 1830 | 1845 | 60 | 58 | 56 | 54 | 52 | 50 | 48 | 46 | 44 | 42 | 40 |
| 1845 | 1860 | 61 | 59 | 57 | 55 | 53 | 51 | 49 | 47 | 45 | 43 | 41 |
| 1860 | 1875 | 61 | 59 | 57 | 55 | 53 | 52 | 50 | 48 | 46 | 44 | 42 |
| 1875 | 1890 | 62 | 60 | 58 | 56 | 54 | 52 | 50 | 48 | 46 | 44 | 42 |
| 1890 | 1905 | 63 | 61 | 59 | 57 | 55 | 53 | 51 | 49 | 47 | 45 | 43 |
| 1905 | 1920 | 63 | 61 | 59 | 57 | 55 | 53 | 51 | 49 | 47 | 45 | 44 |
| 1920 | 1935 | 64 | 62 | 60 | 58 | 56 | 54 | 52 | 50 | 48 | 46 | 44 |
| 1935 | 1950 | 64 | 62 | 60 | 59 | 57 | 55 | 53 | 51 | 49 | 47 | 45 |
| 1950 | 1965 | 65 | 63 | 61 | 59 | 57 | 55 | 53 | 51 | 49 | 47 | 45 |
| 1965 | 1980 | 66 | 64 | 62 | 60 | 58 | 56 | 54 | 52 | 50 | 48 | 46 |
| 1980 | 1995 | 66 | 64 | 62 | 60 | 58 | 56 | 54 | 52 | 51 | 49 | 47 |
| 1995 | 2010 | 67 | 65 | 63 | 61 | 59 | 57 | 55 | 53 | 51 | 49 | 47 |
| 2010 | 2025 | 67 | 66 | 64 | 62 | 60 | 58 | 56 | 54 | 52 | 50 | 48 |
| 2025 | 2040 | 68 | 66 | 64 | 62 | 60 | 58 | 56 | 54 | 52 | 50 | 48 |
| 2040 | 2055 | 69 | 67 | 65 | 63 | 61 | 59 | 57 | 55 | 53 | 51 | 49 |
| 2055 | 2070 | 69 | 67 | 65 | 63 | 61 | 59 | 58 | 56 | 54 | 52 | 50 |
| 2070 | 2085 | 70 | 68 | 66 | 64 | 62 | 60 | 58 | 56 | 54 | 52 | 50 |
| 2085 | 2100 | 71 | 69 | 67 | 65 | 63 | 61 | 59 | 57 | 55 | 53 | 51 |
| 2100 | 2115 | 71 | 69 | 67 | 65 | 63 | 61 | 59 | 57 | 55 | 53 | 51 |
| 2115 | 2130 | 72 | 70 | 68 | 66 | 64 | 62 | 60 | 58 | 56 | 54 | 52 |
| 2130 | 2145 | 72 | 70 | 68 | 66 | 65 | 63 | 61 | 59 | 57 | 55 | 53 |
| 2145 | 2160 | 73 | 71 | 69 | 67 | 65 | 63 | 61 | 59 | 57 | 55 | 53 |
| 2160 and | over use | the per | centage | meth | od begi | nning on | page 17. | |||||
| Page | 42 |
# Head of Household - Biweekly Payroll Period
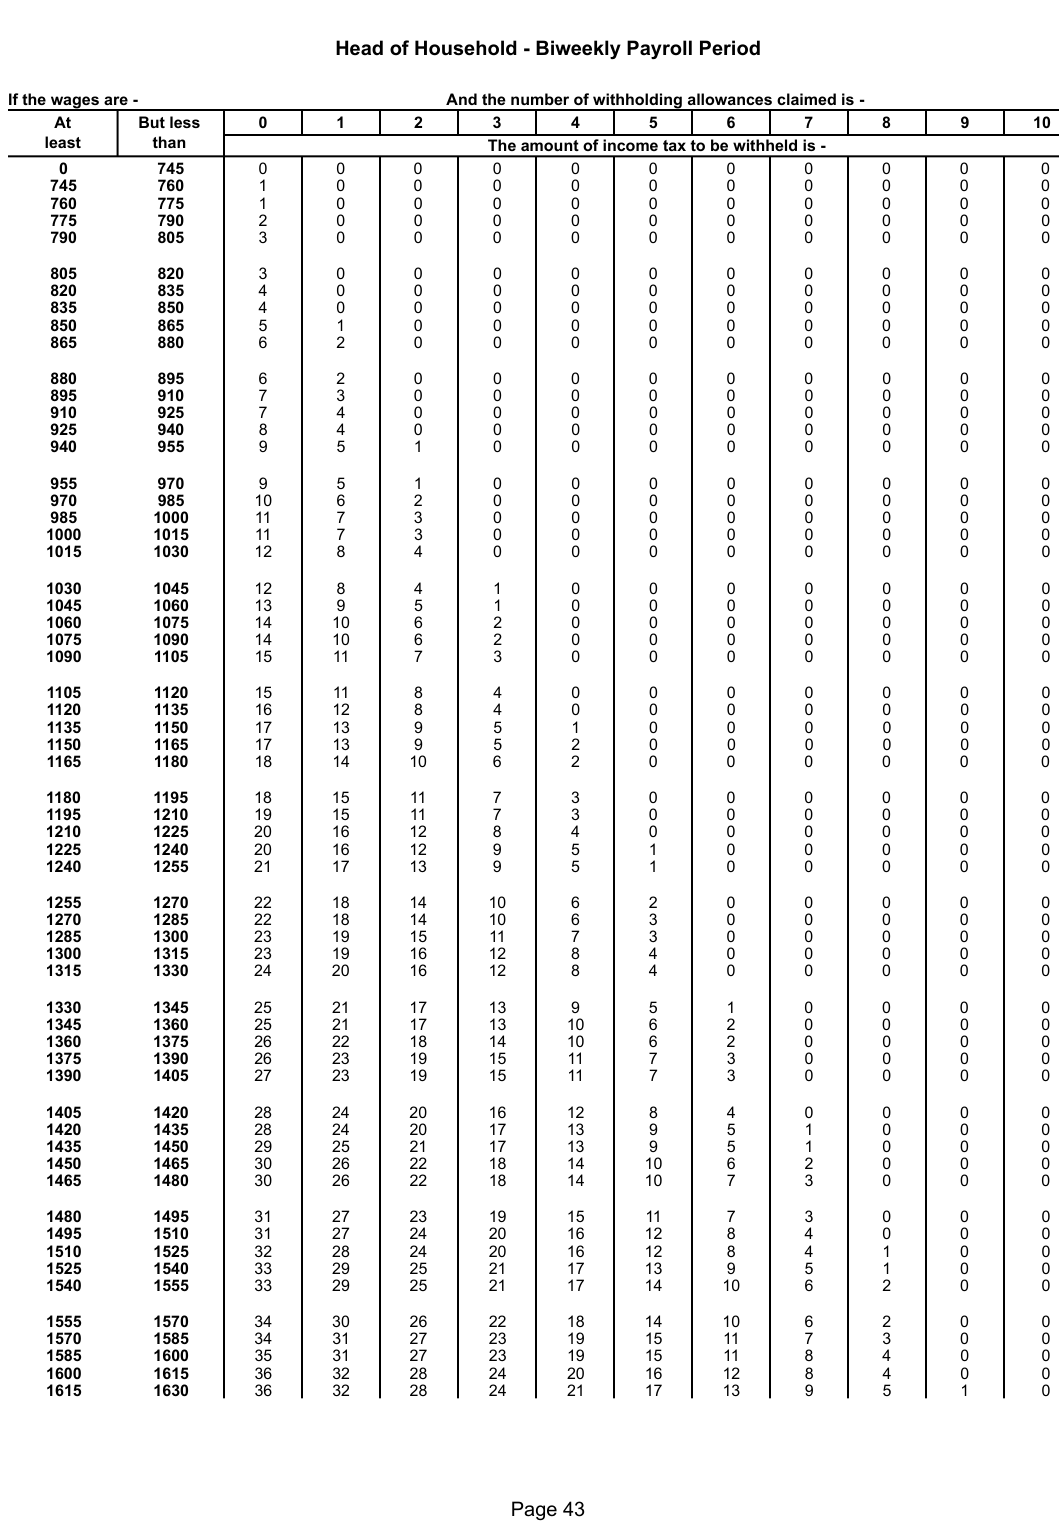
Text version of this table
| Head of | Househ | old - Biw | eekly P | ayrol | l Period | |||||||
| wages are - | And t | he numbe | r of withho | lding | allowances | claimed is - | ||||||
| At B | ut less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
| least | than | The amou | nt of incom | e tax | to be withh | eld is - | ||||||
| 0 | 745 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 745 | 760 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 760 | 775 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 775 | 790 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 790 | 805 | 3 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 805 | 820 | 3 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 820 | 835 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 835 | 850 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 850 | 865 | 5 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 865 | 880 | 6 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 880 | 895 | 6 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 895 | 910 | 7 | 3 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 910 | 925 | 7 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 925 | 940 | 8 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 940 | 955 | 9 | 5 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 955 | 970 | 9 | 5 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 970 | 985 | 10 | 6 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 985 | 1000 | 11 | 7 | 3 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1000 | 1015 | 11 | 7 | 3 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1015 | 1030 | 12 | 8 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1030 | 1045 | 12 | 8 | 4 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1045 | 1060 | 13 | 9 | 5 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1060 | 1075 | 14 | 10 | 6 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1075 | 1090 | 14 | 10 | 6 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1090 | 1105 | 15 | 11 | 7 | 3 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1105 | 1120 | 15 | 11 | 8 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1120 | 1135 | 16 | 12 | 8 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1135 | 1150 | 17 | 13 | 9 | 5 | 1 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1150 | 1165 | 17 | 13 | 9 | 5 | 2 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1165 | 1180 | 18 | 14 | 10 | 6 | 2 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1180 | 1195 | 18 | 15 | 11 | 7 | 3 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1195 | 1210 | 19 | 15 | 11 | 7 | 3 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1210 | 1225 | 20 | 16 | 12 | 8 | 4 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1225 | 1240 | 20 | 16 | 12 | 9 | 5 | 1 | 0 | 0 | 0 | 0 | 0 |
| 1240 | 1255 | 21 | 17 | 13 | 9 | 5 | 1 | 0 | 0 | 0 | 0 | 0 |
| 1255 | 1270 | 22 | 18 | 14 | 10 | 6 | 2 | 0 | 0 | 0 | 0 | 0 |
| 1270 | 1285 | 22 | 18 | 14 | 10 | 6 | 3 | 0 | 0 | 0 | 0 | 0 |
| 1285 | 1300 | 23 | 19 | 15 | 11 | 7 | 3 | 0 | 0 | 0 | 0 | 0 |
| 1300 | 1315 | 23 | 19 | 16 | 12 | 8 | 4 | 0 | 0 | 0 | 0 | 0 |
| 1315 | 1330 | 24 | 20 | 16 | 12 | 8 | 4 | 0 | 0 | 0 | 0 | 0 |
| 1330 | 1345 | 25 | 21 | 17 | 13 | 9 | 5 | 1 | 0 | 0 | 0 | 0 |
| 1345 | 1360 | 25 | 21 | 17 | 13 | 10 | 6 | 2 | 0 | 0 | 0 | 0 |
| 1360 | 1375 | 26 | 22 | 18 | 14 | 10 | 6 | 2 | 0 | 0 | 0 | 0 |
| 1375 | 1390 | 26 | 23 | 19 | 15 | 11 | 7 | 3 | 0 | 0 | 0 | 0 |
| 1390 | 1405 | 27 | 23 | 19 | 15 | 11 | 7 | 3 | 0 | 0 | 0 | 0 |
| 1405 | 1420 | 28 | 24 | 20 | 16 | 12 | 8 | 4 | 0 | 0 | 0 | 0 |
| 1420 | 1435 | 28 | 24 | 20 | 17 | 13 | 9 | 5 | 1 | 0 | 0 | 0 |
| 1435 | 1450 | 29 | 25 | 21 | 17 | 13 | 9 | 5 | 1 | 0 | 0 | 0 |
| 1450 | 1465 | 30 | 26 | 22 | 18 | 14 | 10 | 6 | 2 | 0 | 0 | 0 |
| 1465 | 1480 | 30 | 26 | 22 | 18 | 14 | 10 | 7 | 3 | 0 | 0 | 0 |
| 1480 | 1495 | 31 | 27 | 23 | 19 | 15 | 11 | 7 | 3 | 0 | 0 | 0 |
| 1495 | 1510 | 31 | 27 | 24 | 20 | 16 | 12 | 8 | 4 | 0 | 0 | 0 |
| 1510 | 1525 | 32 | 28 | 24 | 20 | 16 | 12 | 8 | 4 | 1 | 0 | 0 |
| 1525 | 1540 | 33 | 29 | 25 | 21 | 17 | 13 | 9 | 5 | 1 | 0 | 0 |
| 1540 | 1555 | 33 | 29 | 25 | 21 | 17 | 14 | 10 | 6 | 2 | 0 | 0 |
| 1555 | 1570 | 34 | 30 | 26 | 22 | 18 | 14 | 10 | 6 | 2 | 0 | 0 |
| 1570 | 1585 | 34 | 31 | 27 | 23 | 19 | 15 | 11 | 7 | 3 | 0 | 0 |
| 1585 | 1600 | 35 | 31 | 27 | 23 | 19 | 15 | 11 | 8 | 4 | 0 | 0 |
| 1600 | 1615 | 36 | 32 | 28 | 24 | 20 | 16 | 12 | 8 | 4 | 0 | 0 |
| 1615 | 1630 | 36 | 32 | 28 | 24 | 21 | 17 | 13 | 9 | 5 | 1 | 0 |
| Page | 43 |
# Head of Household - Biweekly Payroll Period
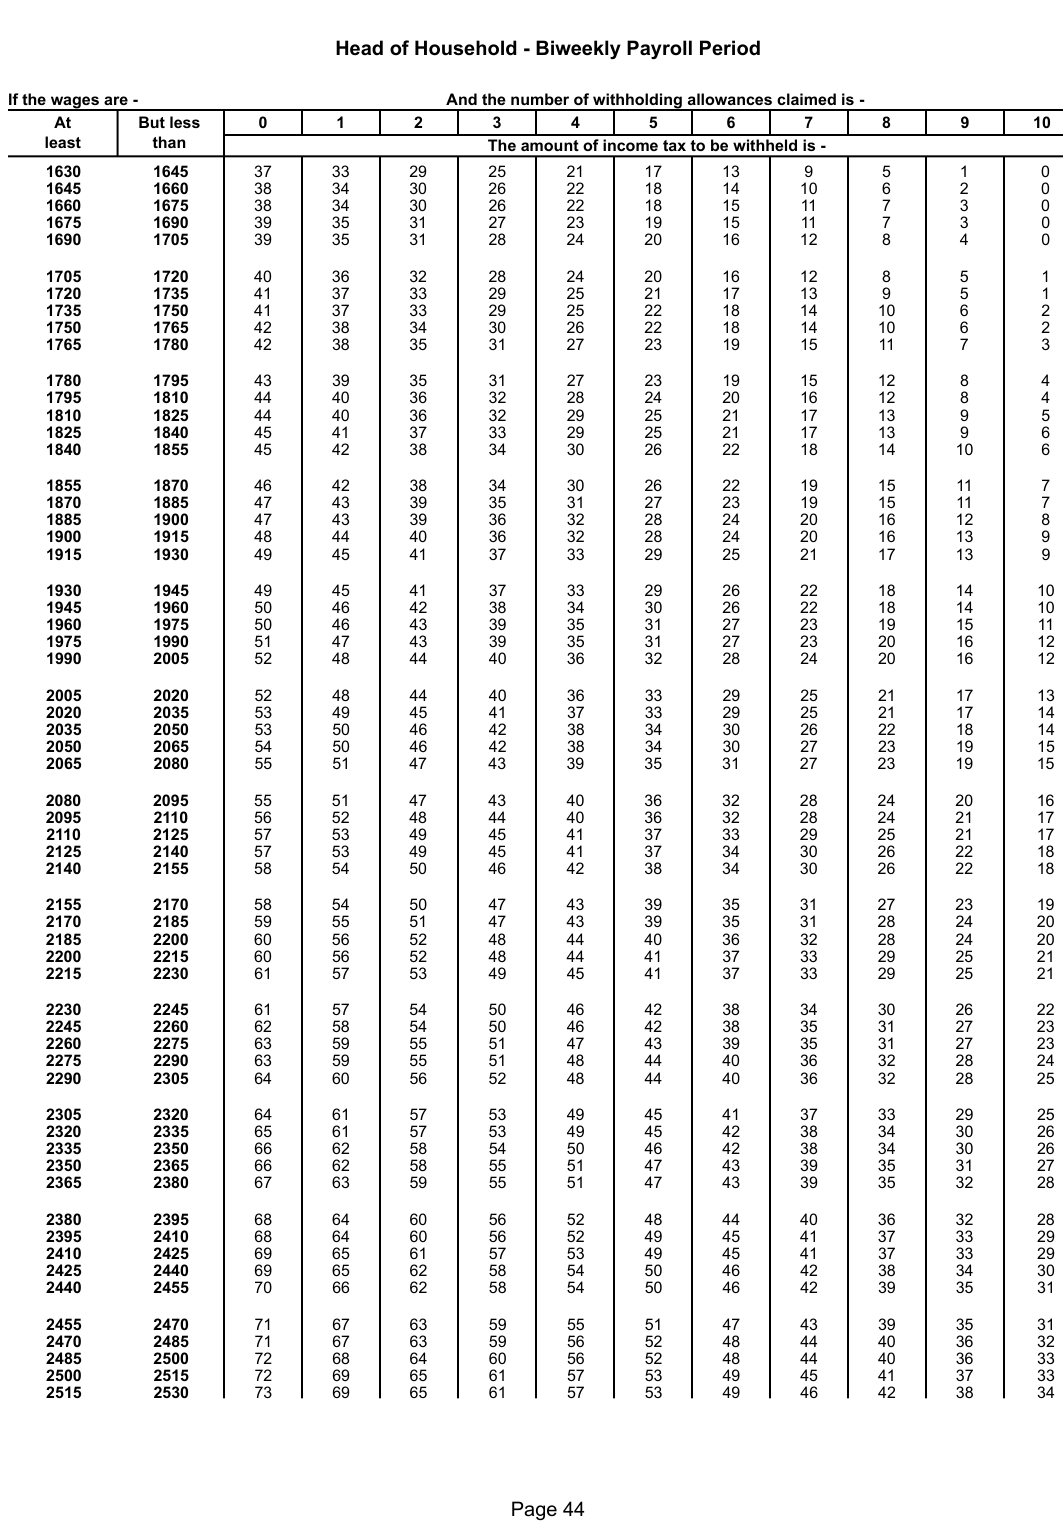
Text version of this table
| Head of | Househ | old - Biw | eekly P | ayrol | l Period | |||||||
| wages are - | And t | he numbe | r of withho | lding | allowances | claimed is - | ||||||
| At B | ut less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
| least | than | The amou | nt of incom | e tax | to be withh | eld is - | ||||||
| 1630 | 1645 | 37 | 33 | 29 | 25 | 21 | 17 | 13 | 9 | 5 | 1 | 0 |
| 1645 | 1660 | 38 | 34 | 30 | 26 | 22 | 18 | 14 | 10 | 6 | 2 | 0 |
| 1660 | 1675 | 38 | 34 | 30 | 26 | 22 | 18 | 15 | 11 | 7 | 3 | 0 |
| 1675 | 1690 | 39 | 35 | 31 | 27 | 23 | 19 | 15 | 11 | 7 | 3 | 0 |
| 1690 | 1705 | 39 | 35 | 31 | 28 | 24 | 20 | 16 | 12 | 8 | 4 | 0 |
| 1705 | 1720 | 40 | 36 | 32 | 28 | 24 | 20 | 16 | 12 | 8 | 5 | 1 |
| 1720 | 1735 | 41 | 37 | 33 | 29 | 25 | 21 | 17 | 13 | 9 | 5 | 1 |
| 1735 | 1750 | 41 | 37 | 33 | 29 | 25 | 22 | 18 | 14 | 10 | 6 | 2 |
| 1750 | 1765 | 42 | 38 | 34 | 30 | 26 | 22 | 18 | 14 | 10 | 6 | 2 |
| 1765 | 1780 | 42 | 38 | 35 | 31 | 27 | 23 | 19 | 15 | 11 | 7 | 3 |
| 1780 | 1795 | 43 | 39 | 35 | 31 | 27 | 23 | 19 | 15 | 12 | 8 | 4 |
| 1795 | 1810 | 44 | 40 | 36 | 32 | 28 | 24 | 20 | 16 | 12 | 8 | 4 |
| 1810 | 1825 | 44 | 40 | 36 | 32 | 29 | 25 | 21 | 17 | 13 | 9 | 5 |
| 1825 | 1840 | 45 | 41 | 37 | 33 | 29 | 25 | 21 | 17 | 13 | 9 | 6 |
| 1840 | 1855 | 45 | 42 | 38 | 34 | 30 | 26 | 22 | 18 | 14 | 10 | 6 |
| 1855 | 1870 | 46 | 42 | 38 | 34 | 30 | 26 | 22 | 19 | 15 | 11 | 7 |
| 1870 | 1885 | 47 | 43 | 39 | 35 | 31 | 27 | 23 | 19 | 15 | 11 | 7 |
| 1885 | 1900 | 47 | 43 | 39 | 36 | 32 | 28 | 24 | 20 | 16 | 12 | 8 |
| 1900 | 1915 | 48 | 44 | 40 | 36 | 32 | 28 | 24 | 20 | 16 | 13 | 9 |
| 1915 | 1930 | 49 | 45 | 41 | 37 | 33 | 29 | 25 | 21 | 17 | 13 | 9 |
| 1930 | 1945 | 49 | 45 | 41 | 37 | 33 | 29 | 26 | 22 | 18 | 14 | 10 |
| 1945 | 1960 | 50 | 46 | 42 | 38 | 34 | 30 | 26 | 22 | 18 | 14 | 10 |
| 1960 | 1975 | 50 | 46 | 43 | 39 | 35 | 31 | 27 | 23 | 19 | 15 | 11 |
| 1975 | 1990 | 51 | 47 | 43 | 39 | 35 | 31 | 27 | 23 | 20 | 16 | 12 |
| 1990 | 2005 | 52 | 48 | 44 | 40 | 36 | 32 | 28 | 24 | 20 | 16 | 12 |
| 2005 | 2020 | 52 | 48 | 44 | 40 | 36 | 33 | 29 | 25 | 21 | 17 | 13 |
| 2020 | 2035 | 53 | 49 | 45 | 41 | 37 | 33 | 29 | 25 | 21 | 17 | 14 |
| 2035 | 2050 | 53 | 50 | 46 | 42 | 38 | 34 | 30 | 26 | 22 | 18 | 14 |
| 2050 | 2065 | 54 | 50 | 46 | 42 | 38 | 34 | 30 | 27 | 23 | 19 | 15 |
| 2065 | 2080 | 55 | 51 | 47 | 43 | 39 | 35 | 31 | 27 | 23 | 19 | 15 |
| 2080 | 2095 | 55 | 51 | 47 | 43 | 40 | 36 | 32 | 28 | 24 | 20 | 16 |
| 2095 | 2110 | 56 | 52 | 48 | 44 | 40 | 36 | 32 | 28 | 24 | 21 | 17 |
| 2110 | 2125 | 57 | 53 | 49 | 45 | 41 | 37 | 33 | 29 | 25 | 21 | 17 |
| 2125 | 2140 | 57 | 53 | 49 | 45 | 41 | 37 | 34 | 30 | 26 | 22 | 18 |
| 2140 | 2155 | 58 | 54 | 50 | 46 | 42 | 38 | 34 | 30 | 26 | 22 | 18 |
| 2155 | 2170 | 58 | 54 | 50 | 47 | 43 | 39 | 35 | 31 | 27 | 23 | 19 |
| 2170 | 2185 | 59 | 55 | 51 | 47 | 43 | 39 | 35 | 31 | 28 | 24 | 20 |
| 2185 | 2200 | 60 | 56 | 52 | 48 | 44 | 40 | 36 | 32 | 28 | 24 | 20 |
| 2200 | 2215 | 60 | 56 | 52 | 48 | 44 | 41 | 37 | 33 | 29 | 25 | 21 |
| 2215 | 2230 | 61 | 57 | 53 | 49 | 45 | 41 | 37 | 33 | 29 | 25 | 21 |
| 2230 | 2245 | 61 | 57 | 54 | 50 | 46 | 42 | 38 | 34 | 30 | 26 | 22 |
| 2245 | 2260 | 62 | 58 | 54 | 50 | 46 | 42 | 38 | 35 | 31 | 27 | 23 |
| 2260 | 2275 | 63 | 59 | 55 | 51 | 47 | 43 | 39 | 35 | 31 | 27 | 23 |
| 2275 | 2290 | 63 | 59 | 55 | 51 | 48 | 44 | 40 | 36 | 32 | 28 | 24 |
| 2290 | 2305 | 64 | 60 | 56 | 52 | 48 | 44 | 40 | 36 | 32 | 28 | 25 |
| 2305 | 2320 | 64 | 61 | 57 | 53 | 49 | 45 | 41 | 37 | 33 | 29 | 25 |
| 2320 | 2335 | 65 | 61 | 57 | 53 | 49 | 45 | 42 | 38 | 34 | 30 | 26 |
| 2335 | 2350 | 66 | 62 | 58 | 54 | 50 | 46 | 42 | 38 | 34 | 30 | 26 |
| 2350 | 2365 | 66 | 62 | 58 | 55 | 51 | 47 | 43 | 39 | 35 | 31 | 27 |
| 2365 | 2380 | 67 | 63 | 59 | 55 | 51 | 47 | 43 | 39 | 35 | 32 | 28 |
| 2380 | 2395 | 68 | 64 | 60 | 56 | 52 | 48 | 44 | 40 | 36 | 32 | 28 |
| 2395 | 2410 | 68 | 64 | 60 | 56 | 52 | 49 | 45 | 41 | 37 | 33 | 29 |
| 2410 | 2425 | 69 | 65 | 61 | 57 | 53 | 49 | 45 | 41 | 37 | 33 | 29 |
| 2425 | 2440 | 69 | 65 | 62 | 58 | 54 | 50 | 46 | 42 | 38 | 34 | 30 |
| 2440 | 2455 | 70 | 66 | 62 | 58 | 54 | 50 | 46 | 42 | 39 | 35 | 31 |
| 2455 | 2470 | 71 | 67 | 63 | 59 | 55 | 51 | 47 | 43 | 39 | 35 | 31 |
| 2470 | 2485 | 71 | 67 | 63 | 59 | 56 | 52 | 48 | 44 | 40 | 36 | 32 |
| 2485 | 2500 | 72 | 68 | 64 | 60 | 56 | 52 | 48 | 44 | 40 | 36 | 33 |
| 2500 | 2515 | 72 | 69 | 65 | 61 | 57 | 53 | 49 | 45 | 41 | 37 | 33 |
| 2515 | 2530 | 73 | 69 | 65 | 61 | 57 | 53 | 49 | 46 | 42 | 38 | 34 |
| Page | 44 |
# Head of Household - Biweekly Payroll Period
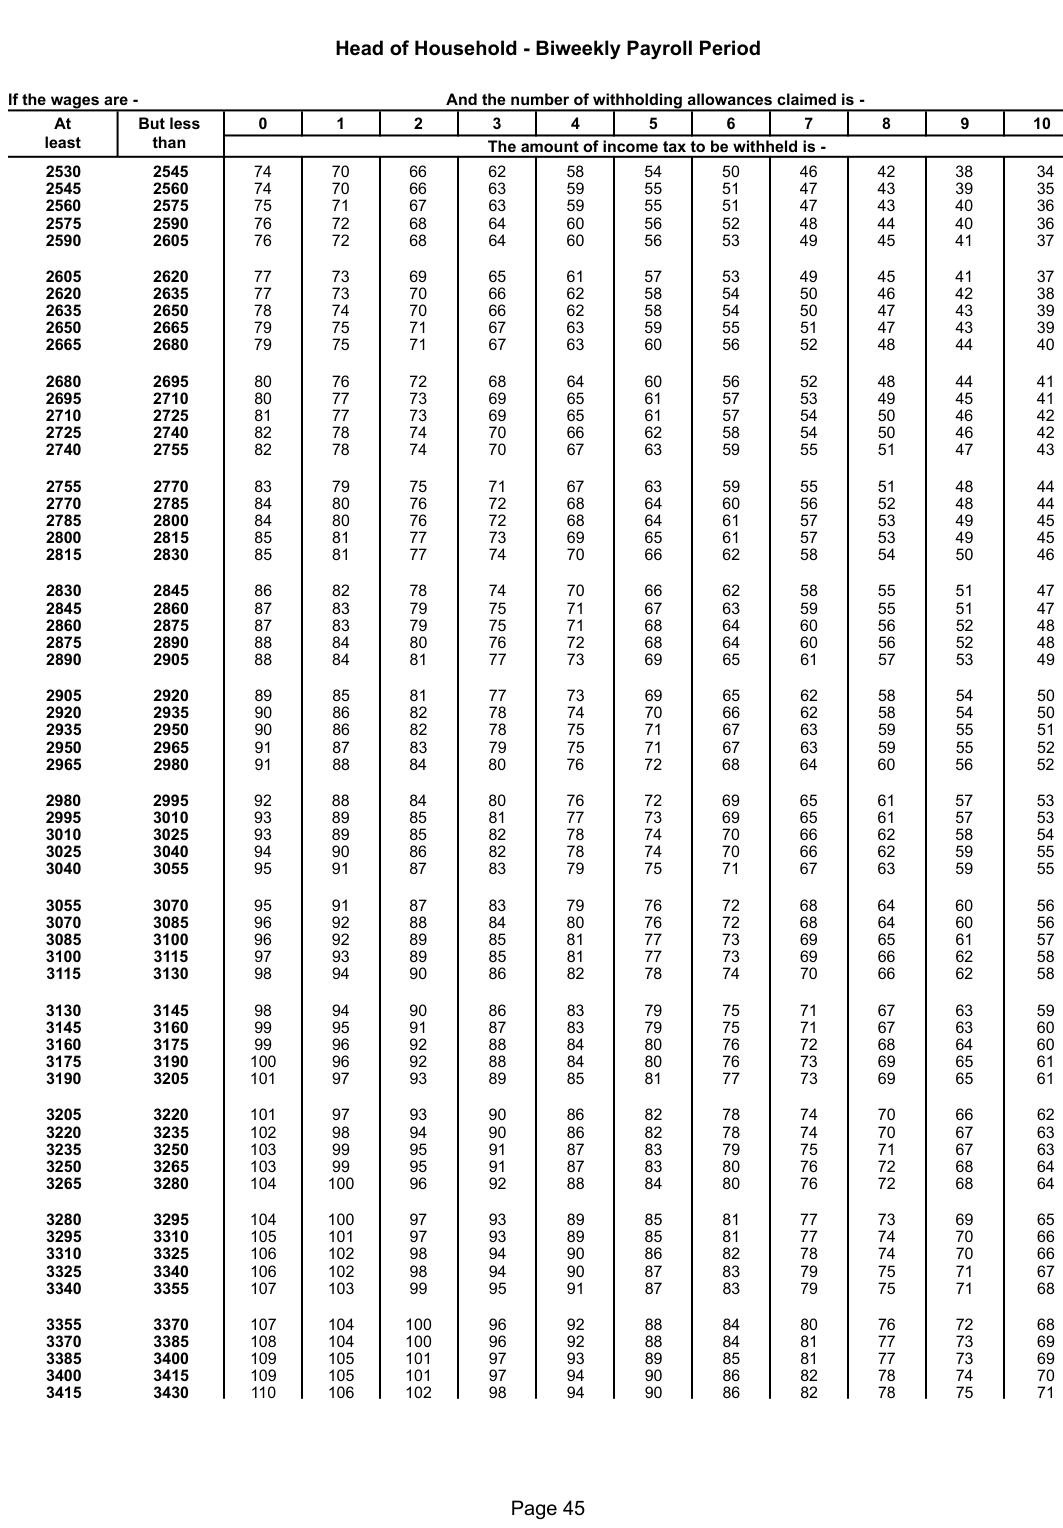
Text version of this table
| Head o | f Househ | old - Biw | eekly P | ayrol | l Period | |||||||
| wages are - | And t | he numbe | r of withho | lding | allowances | claimed is - | ||||||
| At B | ut less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
| least | than | The amou | nt of incom | e tax | to be withh | eld is - | ||||||
| 2530 | 2545 | 74 | 70 | 66 | 62 | 58 | 54 | 50 | 46 | 42 | 38 | 34 |
| 2545 | 2560 | 74 | 70 | 66 | 63 | 59 | 55 | 51 | 47 | 43 | 39 | 35 |
| 2560 | 2575 | 75 | 71 | 67 | 63 | 59 | 55 | 51 | 47 | 43 | 40 | 36 |
| 2575 | 2590 | 76 | 72 | 68 | 64 | 60 | 56 | 52 | 48 | 44 | 40 | 36 |
| 2590 | 2605 | 76 | 72 | 68 | 64 | 60 | 56 | 53 | 49 | 45 | 41 | 37 |
| 2605 | 2620 | 77 | 73 | 69 | 65 | 61 | 57 | 53 | 49 | 45 | 41 | 37 |
| 2620 | 2635 | 77 | 73 | 70 | 66 | 62 | 58 | 54 | 50 | 46 | 42 | 38 |
| 2635 | 2650 | 78 | 74 | 70 | 66 | 62 | 58 | 54 | 50 | 47 | 43 | 39 |
| 2650 | 2665 | 79 | 75 | 71 | 67 | 63 | 59 | 55 | 51 | 47 | 43 | 39 |
| 2665 | 2680 | 79 | 75 | 71 | 67 | 63 | 60 | 56 | 52 | 48 | 44 | 40 |
| 2680 | 2695 | 80 | 76 | 72 | 68 | 64 | 60 | 56 | 52 | 48 | 44 | 41 |
| 2695 | 2710 | 80 | 77 | 73 | 69 | 65 | 61 | 57 | 53 | 49 | 45 | 41 |
| 2710 | 2725 | 81 | 77 | 73 | 69 | 65 | 61 | 57 | 54 | 50 | 46 | 42 |
| 2725 | 2740 | 82 | 78 | 74 | 70 | 66 | 62 | 58 | 54 | 50 | 46 | 42 |
| 2740 | 2755 | 82 | 78 | 74 | 70 | 67 | 63 | 59 | 55 | 51 | 47 | 43 |
| 2755 | 2770 | 83 | 79 | 75 | 71 | 67 | 63 | 59 | 55 | 51 | 48 | 44 |
| 2770 | 2785 | 84 | 80 | 76 | 72 | 68 | 64 | 60 | 56 | 52 | 48 | 44 |
| 2785 | 2800 | 84 | 80 | 76 | 72 | 68 | 64 | 61 | 57 | 53 | 49 | 45 |
| 2800 | 2815 | 85 | 81 | 77 | 73 | 69 | 65 | 61 | 57 | 53 | 49 | 45 |
| 2815 | 2830 | 85 | 81 | 77 | 74 | 70 | 66 | 62 | 58 | 54 | 50 | 46 |
| 2830 | 2845 | 86 | 82 | 78 | 74 | 70 | 66 | 62 | 58 | 55 | 51 | 47 |
| 2845 | 2860 | 87 | 83 | 79 | 75 | 71 | 67 | 63 | 59 | 55 | 51 | 47 |
| 2860 | 2875 | 87 | 83 | 79 | 75 | 71 | 68 | 64 | 60 | 56 | 52 | 48 |
| 2875 | 2890 | 88 | 84 | 80 | 76 | 72 | 68 | 64 | 60 | 56 | 52 | 48 |
| 2890 | 2905 | 88 | 84 | 81 | 77 | 73 | 69 | 65 | 61 | 57 | 53 | 49 |
| 2905 | 2920 | 89 | 85 | 81 | 77 | 73 | 69 | 65 | 62 | 58 | 54 | 50 |
| 2920 | 2935 | 90 | 86 | 82 | 78 | 74 | 70 | 66 | 62 | 58 | 54 | 50 |
| 2935 | 2950 | 90 | 86 | 82 | 78 | 75 | 71 | 67 | 63 | 59 | 55 | 51 |
| 2950 | 2965 | 91 | 87 | 83 | 79 | 75 | 71 | 67 | 63 | 59 | 55 | 52 |
| 2965 | 2980 | 91 | 88 | 84 | 80 | 76 | 72 | 68 | 64 | 60 | 56 | 52 |
| 2980 | 2995 | 92 | 88 | 84 | 80 | 76 | 72 | 69 | 65 | 61 | 57 | 53 |
| 2995 | 3010 | 93 | 89 | 85 | 81 | 77 | 73 | 69 | 65 | 61 | 57 | 53 |
| 3010 | 3025 | 93 | 89 | 85 | 82 | 78 | 74 | 70 | 66 | 62 | 58 | 54 |
| 3025 | 3040 | 94 | 90 | 86 | 82 | 78 | 74 | 70 | 66 | 62 | 59 | 55 |
| 3040 | 3055 | 95 | 91 | 87 | 83 | 79 | 75 | 71 | 67 | 63 | 59 | 55 |
| 3055 | 3070 | 95 | 91 | 87 | 83 | 79 | 76 | 72 | 68 | 64 | 60 | 56 |
| 3070 | 3085 | 96 | 92 | 88 | 84 | 80 | 76 | 72 | 68 | 64 | 60 | 56 |
| 3085 | 3100 | 96 | 92 | 89 | 85 | 81 | 77 | 73 | 69 | 65 | 61 | 57 |
| 3100 | 3115 | 97 | 93 | 89 | 85 | 81 | 77 | 73 | 69 | 66 | 62 | 58 |
| 3115 | 3130 | 98 | 94 | 90 | 86 | 82 | 78 | 74 | 70 | 66 | 62 | 58 |
| 3130 | 3145 | 98 | 94 | 90 | 86 | 83 | 79 | 75 | 71 | 67 | 63 | 59 |
| 3145 | 3160 | 99 | 95 | 91 | 87 | 83 | 79 | 75 | 71 | 67 | 63 | 60 |
| 3160 | 3175 | 99 | 96 | 92 | 88 | 84 | 80 | 76 | 72 | 68 | 64 | 60 |
| 3175 | 3190 | 100 | 96 | 92 | 88 | 84 | 80 | 76 | 73 | 69 | 65 | 61 |
| 3190 | 3205 | 101 | 97 | 93 | 89 | 85 | 81 | 77 | 73 | 69 | 65 | 61 |
| 3205 | 3220 | 101 | 97 | 93 | 90 | 86 | 82 | 78 | 74 | 70 | 66 | 62 |
| 3220 | 3235 | 102 | 98 | 94 | 90 | 86 | 82 | 78 | 74 | 70 | 67 | 63 |
| 3235 | 3250 | 103 | 99 | 95 | 91 | 87 | 83 | 79 | 75 | 71 | 67 | 63 |
| 3250 | 3265 | 103 | 99 | 95 | 91 | 87 | 83 | 80 | 76 | 72 | 68 | 64 |
| 3265 | 3280 | 104 | 100 | 96 | 92 | 88 | 84 | 80 | 76 | 72 | 68 | 64 |
| 3280 | 3295 | 104 | 100 | 97 | 93 | 89 | 85 | 81 | 77 | 73 | 69 | 65 |
| 3295 | 3310 | 105 | 101 | 97 | 93 | 89 | 85 | 81 | 77 | 74 | 70 | 66 |
| 3310 | 3325 | 106 | 102 | 98 | 94 | 90 | 86 | 82 | 78 | 74 | 70 | 66 |
| 3325 | 3340 | 106 | 102 | 98 | 94 | 90 | 87 | 83 | 79 | 75 | 71 | 67 |
| 3340 | 3355 | 107 | 103 | 99 | 95 | 91 | 87 | 83 | 79 | 75 | 71 | 68 |
| 3355 | 3370 | 107 | 104 | 100 | 96 | 92 | 88 | 84 | 80 | 76 | 72 | 68 |
| 3370 | 3385 | 108 | 104 | 100 | 96 | 92 | 88 | 84 | 81 | 77 | 73 | 69 |
| 3385 | 3400 | 109 | 105 | 101 | 97 | 93 | 89 | 85 | 81 | 77 | 73 | 69 |
| 3400 | 3415 | 109 | 105 | 101 | 97 | 94 | 90 | 86 | 82 | 78 | 74 | 70 |
| 3415 | 3430 | 110 | 106 | 102 | 98 | 94 | 90 | 86 | 82 | 78 | 75 | 71 |
| Page | 45 |
# Head of Household - Biweekly Payroll Period
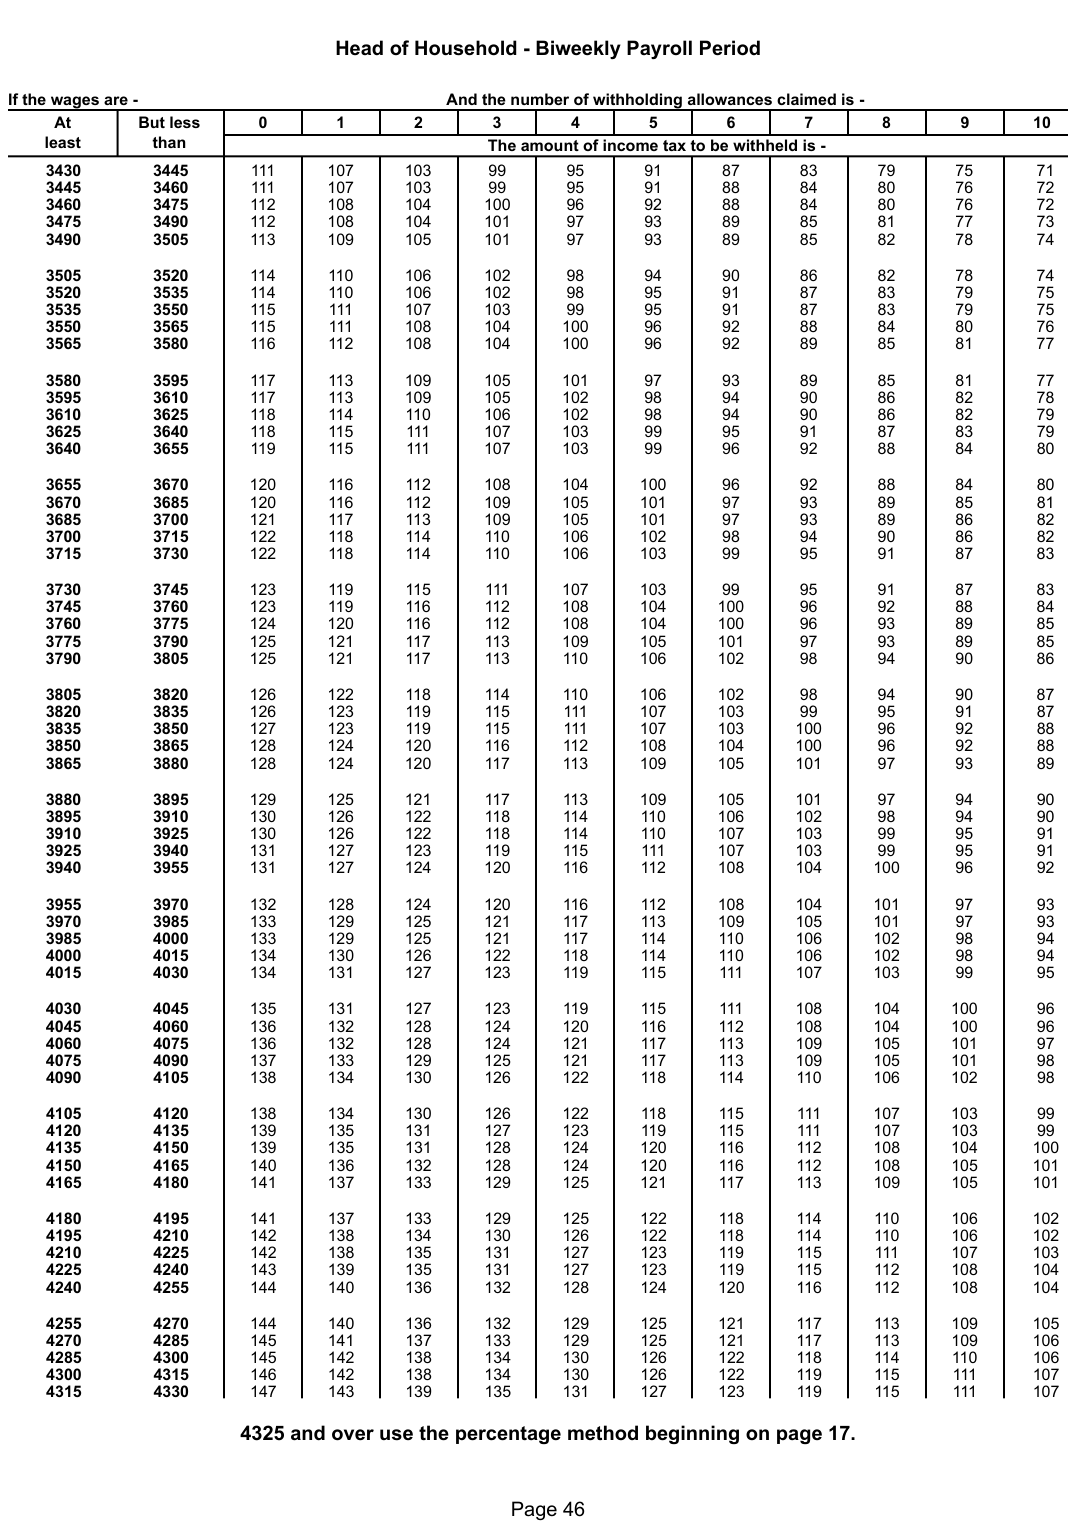
Text version of this table
| Head o | f Househ | old - Bi | weekly P | ayrol | l Period | |||||||
| wages are - | And | the numbe | r of withho | lding | allowances | claimed is - | ||||||
| At B | ut less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
| least | than | The amou | nt of inco | me tax | to be withh | eld is - | ||||||
| 3430 | 3445 | 111 | 107 | 103 | 99 | 95 | 91 | 87 | 83 | 79 | 75 | 71 |
| 3445 | 3460 | 111 | 107 | 103 | 99 | 95 | 91 | 88 | 84 | 80 | 76 | 72 |
| 3460 | 3475 | 112 | 108 | 104 | 100 | 96 | 92 | 88 | 84 | 80 | 76 | 72 |
| 3475 | 3490 | 112 | 108 | 104 | 101 | 97 | 93 | 89 | 85 | 81 | 77 | 73 |
| 3490 | 3505 | 113 | 109 | 105 | 101 | 97 | 93 | 89 | 85 | 82 | 78 | 74 |
| 3505 | 3520 | 114 | 110 | 106 | 102 | 98 | 94 | 90 | 86 | 82 | 78 | 74 |
| 3520 | 3535 | 114 | 110 | 106 | 102 | 98 | 95 | 91 | 87 | 83 | 79 | 75 |
| 3535 | 3550 | 115 | 111 | 107 | 103 | 99 | 95 | 91 | 87 | 83 | 79 | 75 |
| 3550 | 3565 | 115 | 111 | 108 | 104 | 100 | 96 | 92 | 88 | 84 | 80 | 76 |
| 3565 | 3580 | 116 | 112 | 108 | 104 | 100 | 96 | 92 | 89 | 85 | 81 | 77 |
| 3580 | 3595 | 117 | 113 | 109 | 105 | 101 | 97 | 93 | 89 | 85 | 81 | 77 |
| 3595 | 3610 | 117 | 113 | 109 | 105 | 102 | 98 | 94 | 90 | 86 | 82 | 78 |
| 3610 | 3625 | 118 | 114 | 110 | 106 | 102 | 98 | 94 | 90 | 86 | 82 | 79 |
| 3625 | 3640 | 118 | 115 | 111 | 107 | 103 | 99 | 95 | 91 | 87 | 83 | 79 |
| 3640 | 3655 | 119 | 115 | 111 | 107 | 103 | 99 | 96 | 92 | 88 | 84 | 80 |
| 3655 | 3670 | 120 | 116 | 112 | 108 | 104 | 100 | 96 | 92 | 88 | 84 | 80 |
| 3670 | 3685 | 120 | 116 | 112 | 109 | 105 | 101 | 97 | 93 | 89 | 85 | 81 |
| 3685 | 3700 | 121 | 117 | 113 | 109 | 105 | 101 | 97 | 93 | 89 | 86 | 82 |
| 3700 | 3715 | 122 | 118 | 114 | 110 | 106 | 102 | 98 | 94 | 90 | 86 | 82 |
| 3715 | 3730 | 122 | 118 | 114 | 110 | 106 | 103 | 99 | 95 | 91 | 87 | 83 |
| 3730 | 3745 | 123 | 119 | 115 | 111 | 107 | 103 | 99 | 95 | 91 | 87 | 83 |
| 3745 | 3760 | 123 | 119 | 116 | 112 | 108 | 104 | 100 | 96 | 92 | 88 | 84 |
| 3760 | 3775 | 124 | 120 | 116 | 112 | 108 | 104 | 100 | 96 | 93 | 89 | 85 |
| 3775 | 3790 | 125 | 121 | 117 | 113 | 109 | 105 | 101 | 97 | 93 | 89 | 85 |
| 3790 | 3805 | 125 | 121 | 117 | 113 | 110 | 106 | 102 | 98 | 94 | 90 | 86 |
| 3805 | 3820 | 126 | 122 | 118 | 114 | 110 | 106 | 102 | 98 | 94 | 90 | 87 |
| 3820 | 3835 | 126 | 123 | 119 | 115 | 111 | 107 | 103 | 99 | 95 | 91 | 87 |
| 3835 | 3850 | 127 | 123 | 119 | 115 | 111 | 107 | 103 | 100 | 96 | 92 | 88 |
| 3850 | 3865 | 128 | 124 | 120 | 116 | 112 | 108 | 104 | 100 | 96 | 92 | 88 |
| 3865 | 3880 | 128 | 124 | 120 | 117 | 113 | 109 | 105 | 101 | 97 | 93 | 89 |
| 3880 | 3895 | 129 | 125 | 121 | 117 | 113 | 109 | 105 | 101 | 97 | 94 | 90 |
| 3895 | 3910 | 130 | 126 | 122 | 118 | 114 | 110 | 106 | 102 | 98 | 94 | 90 |
| 3910 | 3925 | 130 | 126 | 122 | 118 | 114 | 110 | 107 | 103 | 99 | 95 | 91 |
| 3925 | 3940 | 131 | 127 | 123 | 119 | 115 | 111 | 107 | 103 | 99 | 95 | 91 |
| 3940 | 3955 | 131 | 127 | 124 | 120 | 116 | 112 | 108 | 104 | 100 | 96 | 92 |
| 3955 | 3970 | 132 | 128 | 124 | 120 | 116 | 112 | 108 | 104 | 101 | 97 | 93 |
| 3970 | 3985 | 133 | 129 | 125 | 121 | 117 | 113 | 109 | 105 | 101 | 97 | 93 |
| 3985 | 4000 | 133 | 129 | 125 | 121 | 117 | 114 | 110 | 106 | 102 | 98 | 94 |
| 4000 | 4015 | 134 | 130 | 126 | 122 | 118 | 114 | 110 | 106 | 102 | 98 | 94 |
| 4015 | 4030 | 134 | 131 | 127 | 123 | 119 | 115 | 111 | 107 | 103 | 99 | 95 |
| 4030 | 4045 | 135 | 131 | 127 | 123 | 119 | 115 | 111 | 108 | 104 | 100 | 96 |
| 4045 | 4060 | 136 | 132 | 128 | 124 | 120 | 116 | 112 | 108 | 104 | 100 | 96 |
| 4060 | 4075 | 136 | 132 | 128 | 124 | 121 | 117 | 113 | 109 | 105 | 101 | 97 |
| 4075 | 4090 | 137 | 133 | 129 | 125 | 121 | 117 | 113 | 109 | 105 | 101 | 98 |
| 4090 | 4105 | 138 | 134 | 130 | 126 | 122 | 118 | 114 | 110 | 106 | 102 | 98 |
| 4105 | 4120 | 138 | 134 | 130 | 126 | 122 | 118 | 115 | 111 | 107 | 103 | 99 |
| 4120 | 4135 | 139 | 135 | 131 | 127 | 123 | 119 | 115 | 111 | 107 | 103 | 99 |
| 4135 | 4150 | 139 | 135 | 131 | 128 | 124 | 120 | 116 | 112 | 108 | 104 | 100 |
| 4150 | 4165 | 140 | 136 | 132 | 128 | 124 | 120 | 116 | 112 | 108 | 105 | 101 |
| 4165 | 4180 | 141 | 137 | 133 | 129 | 125 | 121 | 117 | 113 | 109 | 105 | 101 |
| 4180 | 4195 | 141 | 137 | 133 | 129 | 125 | 122 | 118 | 114 | 110 | 106 | 102 |
| 4195 | 4210 | 142 | 138 | 134 | 130 | 126 | 122 | 118 | 114 | 110 | 106 | 102 |
| 4210 | 4225 | 142 | 138 | 135 | 131 | 127 | 123 | 119 | 115 | 111 | 107 | 103 |
| 4225 | 4240 | 143 | 139 | 135 | 131 | 127 | 123 | 119 | 115 | 112 | 108 | 104 |
| 4240 | 4255 | 144 | 140 | 136 | 132 | 128 | 124 | 120 | 116 | 112 | 108 | 104 |
| 4255 | 4270 | 144 | 140 | 136 | 132 | 129 | 125 | 121 | 117 | 113 | 109 | 105 |
| 4270 | 4285 | 145 | 141 | 137 | 133 | 129 | 125 | 121 | 117 | 113 | 109 | 106 |
| 4285 | 4300 | 145 | 142 | 138 | 134 | 130 | 126 | 122 | 118 | 114 | 110 | 106 |
| 4300 | 4315 | 146 | 142 | 138 | 134 | 130 | 126 | 122 | 119 | 115 | 111 | 107 |
| 4315 | 4330 | 147 | 143 | 139 | 135 | 131 | 127 | 123 | 119 | 115 | 111 | 107 |
| 4325 and | over us | e the per | centage | method | begi | nning on | page 17. | |||||
| Page | 46 |
# Head of Household - Semimonthly Payroll Period
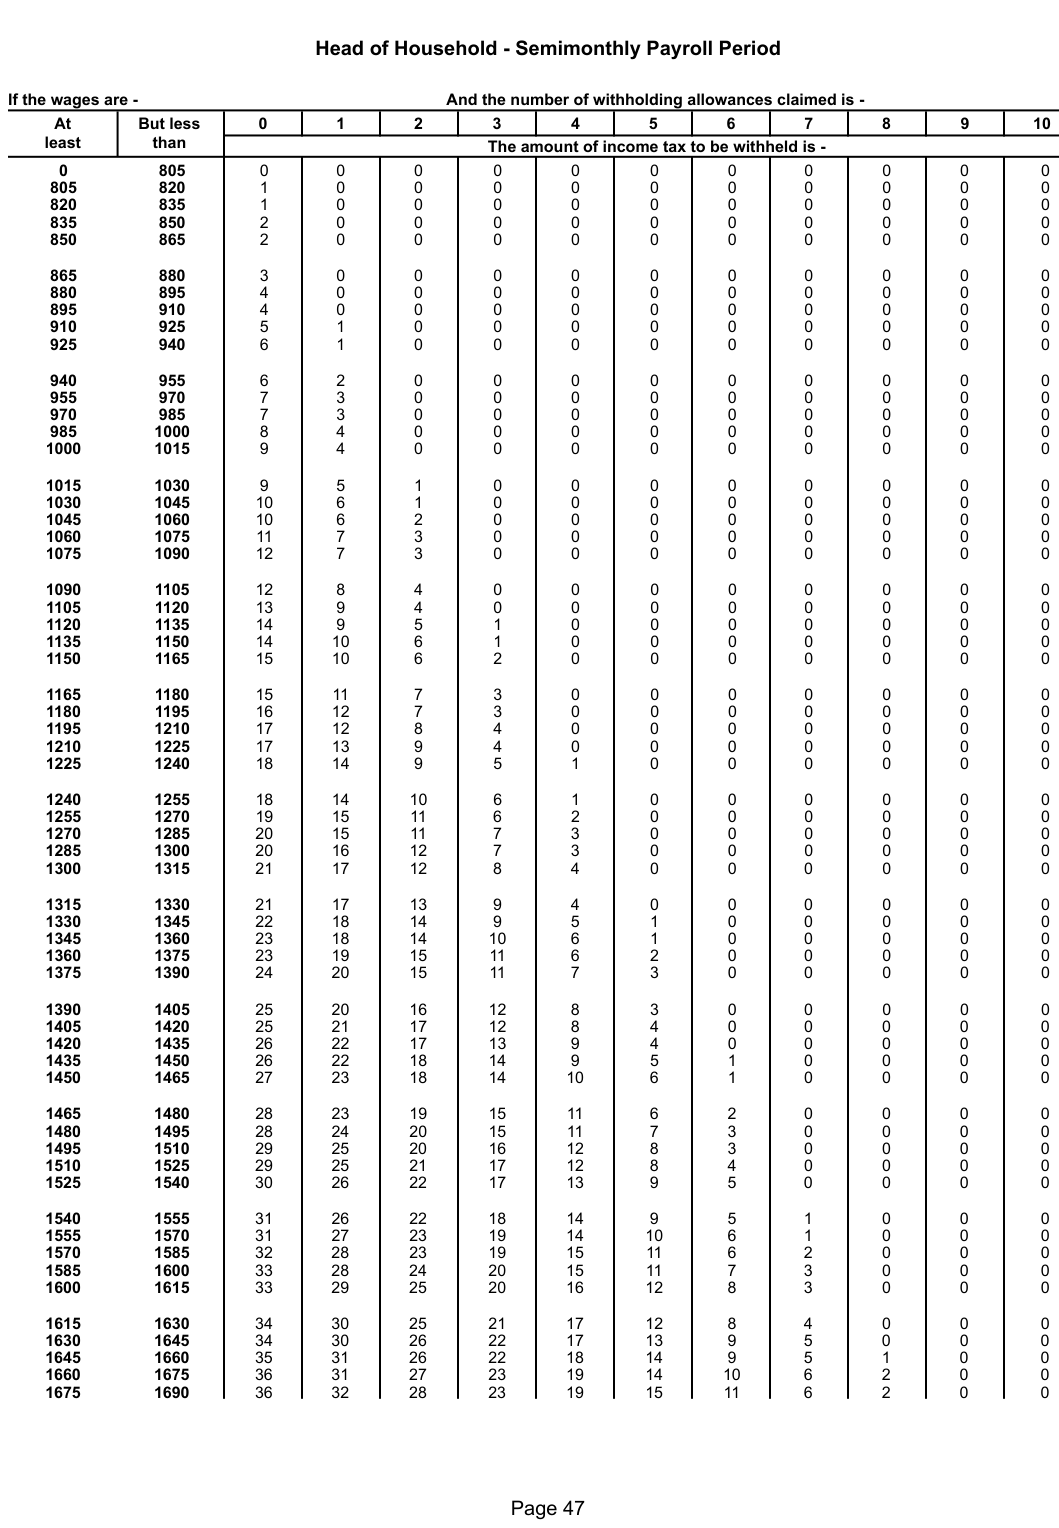
Text version of this table
| Head of H | ousehol | d - Semi | monthly | Payr | oll Period | |||||||
| wages are - | And t | he numbe | r of withho | lding | allowances | claimed is - | ||||||
| At B | ut less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
| least | than | The amou | nt of incom | e tax | to be withh | eld is - | ||||||
| 0 | 805 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 805 | 820 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 820 | 835 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 835 | 850 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 850 | 865 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 865 | 880 | 3 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 880 | 895 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 895 | 910 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 910 | 925 | 5 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 925 | 940 | 6 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 940 | 955 | 6 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 955 | 970 | 7 | 3 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 970 | 985 | 7 | 3 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 985 | 1000 | 8 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1000 | 1015 | 9 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1015 | 1030 | 9 | 5 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1030 | 1045 | 10 | 6 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1045 | 1060 | 10 | 6 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1060 | 1075 | 11 | 7 | 3 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1075 | 1090 | 12 | 7 | 3 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1090 | 1105 | 12 | 8 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1105 | 1120 | 13 | 9 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1120 | 1135 | 14 | 9 | 5 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1135 | 1150 | 14 | 10 | 6 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1150 | 1165 | 15 | 10 | 6 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1165 | 1180 | 15 | 11 | 7 | 3 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1180 | 1195 | 16 | 12 | 7 | 3 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1195 | 1210 | 17 | 12 | 8 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1210 | 1225 | 17 | 13 | 9 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1225 | 1240 | 18 | 14 | 9 | 5 | 1 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1240 | 1255 | 18 | 14 | 10 | 6 | 1 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1255 | 1270 | 19 | 15 | 11 | 6 | 2 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1270 | 1285 | 20 | 15 | 11 | 7 | 3 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1285 | 1300 | 20 | 16 | 12 | 7 | 3 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1300 | 1315 | 21 | 17 | 12 | 8 | 4 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1315 | 1330 | 21 | 17 | 13 | 9 | 4 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1330 | 1345 | 22 | 18 | 14 | 9 | 5 | 1 | 0 | 0 | 0 | 0 | 0 |
| 1345 | 1360 | 23 | 18 | 14 | 10 | 6 | 1 | 0 | 0 | 0 | 0 | 0 |
| 1360 | 1375 | 23 | 19 | 15 | 11 | 6 | 2 | 0 | 0 | 0 | 0 | 0 |
| 1375 | 1390 | 24 | 20 | 15 | 11 | 7 | 3 | 0 | 0 | 0 | 0 | 0 |
| 1390 | 1405 | 25 | 20 | 16 | 12 | 8 | 3 | 0 | 0 | 0 | 0 | 0 |
| 1405 | 1420 | 25 | 21 | 17 | 12 | 8 | 4 | 0 | 0 | 0 | 0 | 0 |
| 1420 | 1435 | 26 | 22 | 17 | 13 | 9 | 4 | 0 | 0 | 0 | 0 | 0 |
| 1435 | 1450 | 26 | 22 | 18 | 14 | 9 | 5 | 1 | 0 | 0 | 0 | 0 |
| 1450 | 1465 | 27 | 23 | 18 | 14 | 10 | 6 | 1 | 0 | 0 | 0 | 0 |
| 1465 | 1480 | 28 | 23 | 19 | 15 | 11 | 6 | 2 | 0 | 0 | 0 | 0 |
| 1480 | 1495 | 28 | 24 | 20 | 15 | 11 | 7 | 3 | 0 | 0 | 0 | 0 |
| 1495 | 1510 | 29 | 25 | 20 | 16 | 12 | 8 | 3 | 0 | 0 | 0 | 0 |
| 1510 | 1525 | 29 | 25 | 21 | 17 | 12 | 8 | 4 | 0 | 0 | 0 | 0 |
| 1525 | 1540 | 30 | 26 | 22 | 17 | 13 | 9 | 5 | 0 | 0 | 0 | 0 |
| 1540 | 1555 | 31 | 26 | 22 | 18 | 14 | 9 | 5 | 1 | 0 | 0 | 0 |
| 1555 | 1570 | 31 | 27 | 23 | 19 | 14 | 10 | 6 | 1 | 0 | 0 | 0 |
| 1570 | 1585 | 32 | 28 | 23 | 19 | 15 | 11 | 6 | 2 | 0 | 0 | 0 |
| 1585 | 1600 | 33 | 28 | 24 | 20 | 15 | 11 | 7 | 3 | 0 | 0 | 0 |
| 1600 | 1615 | 33 | 29 | 25 | 20 | 16 | 12 | 8 | 3 | 0 | 0 | 0 |
| 1615 | 1630 | 34 | 30 | 25 | 21 | 17 | 12 | 8 | 4 | 0 | 0 | 0 |
| 1630 | 1645 | 34 | 30 | 26 | 22 | 17 | 13 | 9 | 5 | 0 | 0 | 0 |
| 1645 | 1660 | 35 | 31 | 26 | 22 | 18 | 14 | 9 | 5 | 1 | 0 | 0 |
| 1660 | 1675 | 36 | 31 | 27 | 23 | 19 | 14 | 10 | 6 | 2 | 0 | 0 |
| 1675 | 1690 | 36 | 32 | 28 | 23 | 19 | 15 | 11 | 6 | 2 | 0 | 0 |
| Page | 47 |
# Head of Household - Semimonthly Payroll Period
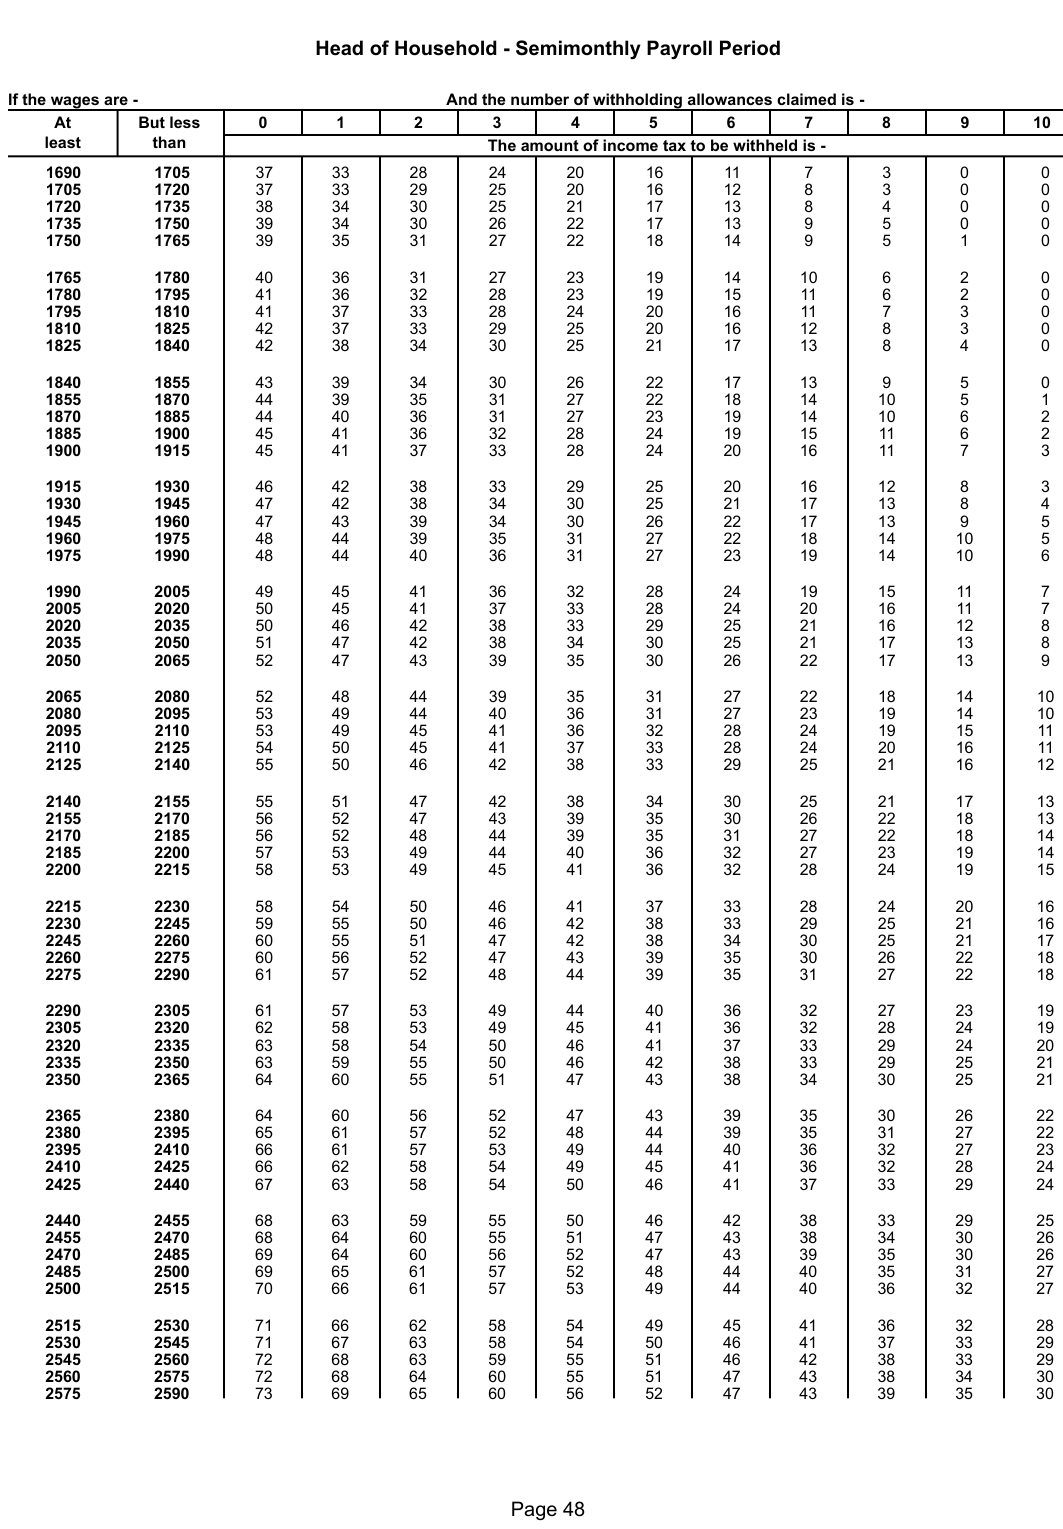
Text version of this table
| Head of H | ousehol | d - Semi | monthly | Payr | oll Period | |||||||
| wages are - | And t | he numbe | r of withho | lding | allowances | claimed is - | ||||||
| At B | ut less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
| least | than | The amou | nt of incom | e tax | to be withh | eld is - | ||||||
| 1690 | 1705 | 37 | 33 | 28 | 24 | 20 | 16 | 11 | 7 | 3 | 0 | 0 |
| 1705 | 1720 | 37 | 33 | 29 | 25 | 20 | 16 | 12 | 8 | 3 | 0 | 0 |
| 1720 | 1735 | 38 | 34 | 30 | 25 | 21 | 17 | 13 | 8 | 4 | 0 | 0 |
| 1735 | 1750 | 39 | 34 | 30 | 26 | 22 | 17 | 13 | 9 | 5 | 0 | 0 |
| 1750 | 1765 | 39 | 35 | 31 | 27 | 22 | 18 | 14 | 9 | 5 | 1 | 0 |
| 1765 | 1780 | 40 | 36 | 31 | 27 | 23 | 19 | 14 | 10 | 6 | 2 | 0 |
| 1780 | 1795 | 41 | 36 | 32 | 28 | 23 | 19 | 15 | 11 | 6 | 2 | 0 |
| 1795 | 1810 | 41 | 37 | 33 | 28 | 24 | 20 | 16 | 11 | 7 | 3 | 0 |
| 1810 | 1825 | 42 | 37 | 33 | 29 | 25 | 20 | 16 | 12 | 8 | 3 | 0 |
| 1825 | 1840 | 42 | 38 | 34 | 30 | 25 | 21 | 17 | 13 | 8 | 4 | 0 |
| 1840 | 1855 | 43 | 39 | 34 | 30 | 26 | 22 | 17 | 13 | 9 | 5 | 0 |
| 1855 | 1870 | 44 | 39 | 35 | 31 | 27 | 22 | 18 | 14 | 10 | 5 | 1 |
| 1870 | 1885 | 44 | 40 | 36 | 31 | 27 | 23 | 19 | 14 | 10 | 6 | 2 |
| 1885 | 1900 | 45 | 41 | 36 | 32 | 28 | 24 | 19 | 15 | 11 | 6 | 2 |
| 1900 | 1915 | 45 | 41 | 37 | 33 | 28 | 24 | 20 | 16 | 11 | 7 | 3 |
| 1915 | 1930 | 46 | 42 | 38 | 33 | 29 | 25 | 20 | 16 | 12 | 8 | 3 |
| 1930 | 1945 | 47 | 42 | 38 | 34 | 30 | 25 | 21 | 17 | 13 | 8 | 4 |
| 1945 | 1960 | 47 | 43 | 39 | 34 | 30 | 26 | 22 | 17 | 13 | 9 | 5 |
| 1960 | 1975 | 48 | 44 | 39 | 35 | 31 | 27 | 22 | 18 | 14 | 10 | 5 |
| 1975 | 1990 | 48 | 44 | 40 | 36 | 31 | 27 | 23 | 19 | 14 | 10 | 6 |
| 1990 | 2005 | 49 | 45 | 41 | 36 | 32 | 28 | 24 | 19 | 15 | 11 | 7 |
| 2005 | 2020 | 50 | 45 | 41 | 37 | 33 | 28 | 24 | 20 | 16 | 11 | 7 |
| 2020 | 2035 | 50 | 46 | 42 | 38 | 33 | 29 | 25 | 21 | 16 | 12 | 8 |
| 2035 | 2050 | 51 | 47 | 42 | 38 | 34 | 30 | 25 | 21 | 17 | 13 | 8 |
| 2050 | 2065 | 52 | 47 | 43 | 39 | 35 | 30 | 26 | 22 | 17 | 13 | 9 |
| 2065 | 2080 | 52 | 48 | 44 | 39 | 35 | 31 | 27 | 22 | 18 | 14 | 10 |
| 2080 | 2095 | 53 | 49 | 44 | 40 | 36 | 31 | 27 | 23 | 19 | 14 | 10 |
| 2095 | 2110 | 53 | 49 | 45 | 41 | 36 | 32 | 28 | 24 | 19 | 15 | 11 |
| 2110 | 2125 | 54 | 50 | 45 | 41 | 37 | 33 | 28 | 24 | 20 | 16 | 11 |
| 2125 | 2140 | 55 | 50 | 46 | 42 | 38 | 33 | 29 | 25 | 21 | 16 | 12 |
| 2140 | 2155 | 55 | 51 | 47 | 42 | 38 | 34 | 30 | 25 | 21 | 17 | 13 |
| 2155 | 2170 | 56 | 52 | 47 | 43 | 39 | 35 | 30 | 26 | 22 | 18 | 13 |
| 2170 | 2185 | 56 | 52 | 48 | 44 | 39 | 35 | 31 | 27 | 22 | 18 | 14 |
| 2185 | 2200 | 57 | 53 | 49 | 44 | 40 | 36 | 32 | 27 | 23 | 19 | 14 |
| 2200 | 2215 | 58 | 53 | 49 | 45 | 41 | 36 | 32 | 28 | 24 | 19 | 15 |
| 2215 | 2230 | 58 | 54 | 50 | 46 | 41 | 37 | 33 | 28 | 24 | 20 | 16 |
| 2230 | 2245 | 59 | 55 | 50 | 46 | 42 | 38 | 33 | 29 | 25 | 21 | 16 |
| 2245 | 2260 | 60 | 55 | 51 | 47 | 42 | 38 | 34 | 30 | 25 | 21 | 17 |
| 2260 | 2275 | 60 | 56 | 52 | 47 | 43 | 39 | 35 | 30 | 26 | 22 | 18 |
| 2275 | 2290 | 61 | 57 | 52 | 48 | 44 | 39 | 35 | 31 | 27 | 22 | 18 |
| 2290 | 2305 | 61 | 57 | 53 | 49 | 44 | 40 | 36 | 32 | 27 | 23 | 19 |
| 2305 | 2320 | 62 | 58 | 53 | 49 | 45 | 41 | 36 | 32 | 28 | 24 | 19 |
| 2320 | 2335 | 63 | 58 | 54 | 50 | 46 | 41 | 37 | 33 | 29 | 24 | 20 |
| 2335 | 2350 | 63 | 59 | 55 | 50 | 46 | 42 | 38 | 33 | 29 | 25 | 21 |
| 2350 | 2365 | 64 | 60 | 55 | 51 | 47 | 43 | 38 | 34 | 30 | 25 | 21 |
| 2365 | 2380 | 64 | 60 | 56 | 52 | 47 | 43 | 39 | 35 | 30 | 26 | 22 |
| 2380 | 2395 | 65 | 61 | 57 | 52 | 48 | 44 | 39 | 35 | 31 | 27 | 22 |
| 2395 | 2410 | 66 | 61 | 57 | 53 | 49 | 44 | 40 | 36 | 32 | 27 | 23 |
| 2410 | 2425 | 66 | 62 | 58 | 54 | 49 | 45 | 41 | 36 | 32 | 28 | 24 |
| 2425 | 2440 | 67 | 63 | 58 | 54 | 50 | 46 | 41 | 37 | 33 | 29 | 24 |
| 2440 | 2455 | 68 | 63 | 59 | 55 | 50 | 46 | 42 | 38 | 33 | 29 | 25 |
| 2455 | 2470 | 68 | 64 | 60 | 55 | 51 | 47 | 43 | 38 | 34 | 30 | 26 |
| 2470 | 2485 | 69 | 64 | 60 | 56 | 52 | 47 | 43 | 39 | 35 | 30 | 26 |
| 2485 | 2500 | 69 | 65 | 61 | 57 | 52 | 48 | 44 | 40 | 35 | 31 | 27 |
| 2500 | 2515 | 70 | 66 | 61 | 57 | 53 | 49 | 44 | 40 | 36 | 32 | 27 |
| 2515 | 2530 | 71 | 66 | 62 | 58 | 54 | 49 | 45 | 41 | 36 | 32 | 28 |
| 2530 | 2545 | 71 | 67 | 63 | 58 | 54 | 50 | 46 | 41 | 37 | 33 | 29 |
| 2545 | 2560 | 72 | 68 | 63 | 59 | 55 | 51 | 46 | 42 | 38 | 33 | 29 |
| 2560 | 2575 | 72 | 68 | 64 | 60 | 55 | 51 | 47 | 43 | 38 | 34 | 30 |
| 2575 | 2590 | 73 | 69 | 65 | 60 | 56 | 52 | 47 | 43 | 39 | 35 | 30 |
| Page | 48 |
# Head of Household - Semimonthly Payroll Period
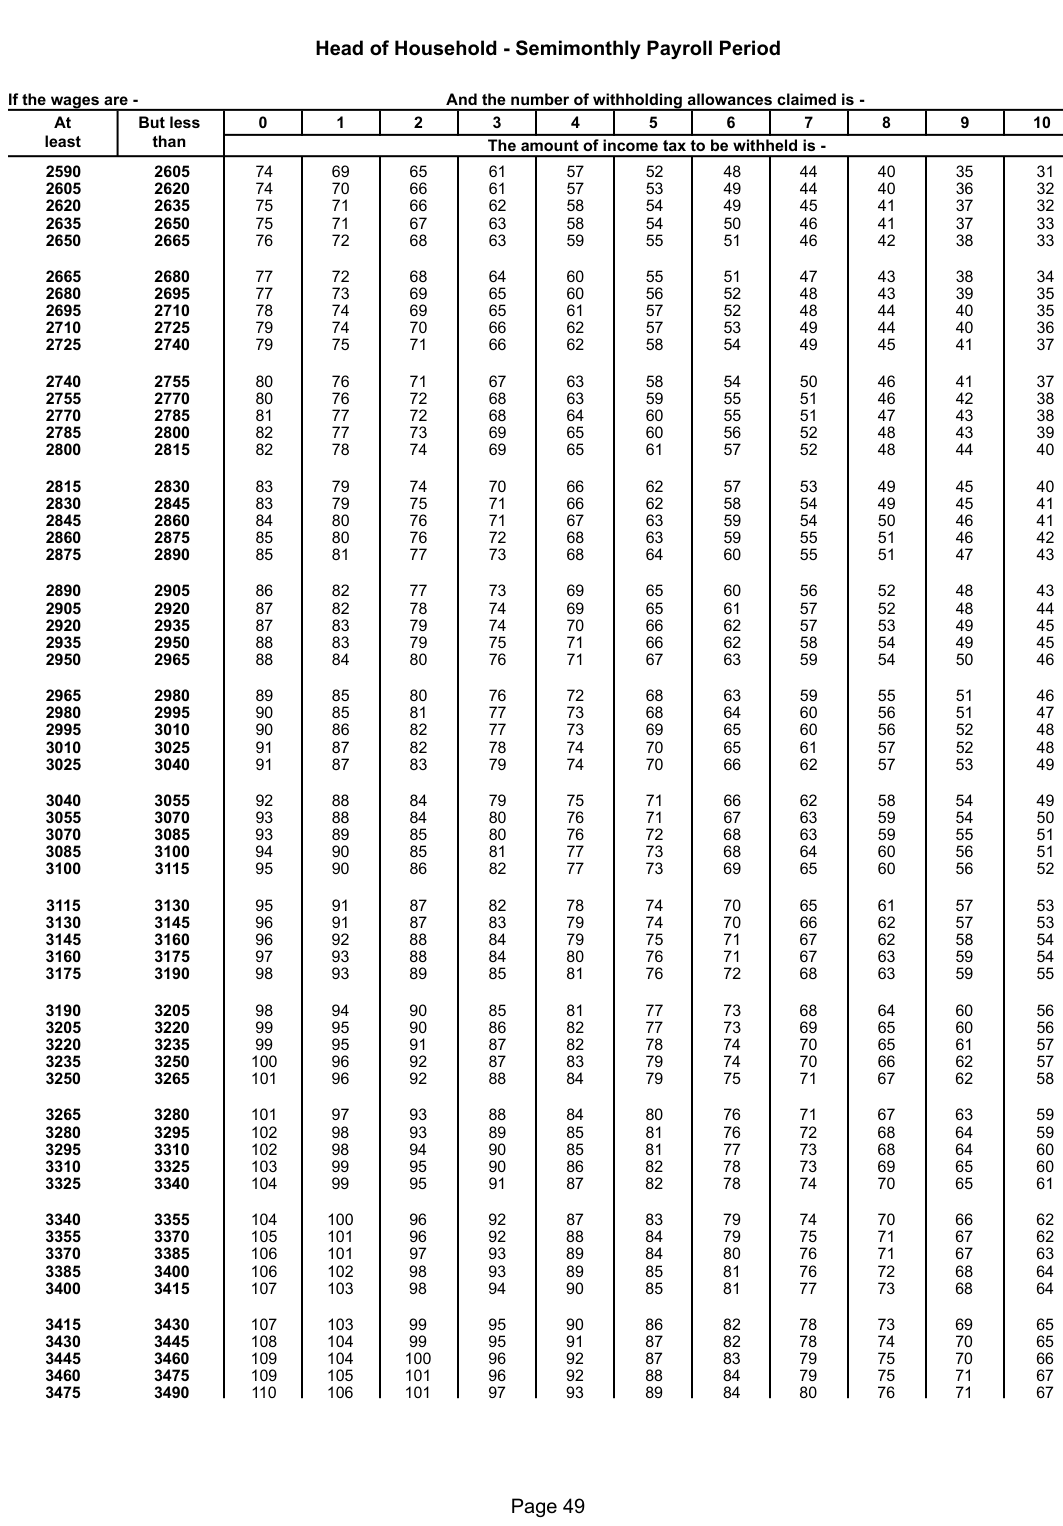
Text version of this table
| Head of H | ousehol | d - Semi | monthly | Payr | oll Period | |||||||
| wages are - | And t | he numbe | r of withho | lding | allowances | claimed is - | ||||||
| At B | ut less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
| least | than | The amou | nt of incom | e tax | to be withh | eld is - | ||||||
| 2590 | 2605 | 74 | 69 | 65 | 61 | 57 | 52 | 48 | 44 | 40 | 35 | 31 |
| 2605 | 2620 | 74 | 70 | 66 | 61 | 57 | 53 | 49 | 44 | 40 | 36 | 32 |
| 2620 | 2635 | 75 | 71 | 66 | 62 | 58 | 54 | 49 | 45 | 41 | 37 | 32 |
| 2635 | 2650 | 75 | 71 | 67 | 63 | 58 | 54 | 50 | 46 | 41 | 37 | 33 |
| 2650 | 2665 | 76 | 72 | 68 | 63 | 59 | 55 | 51 | 46 | 42 | 38 | 33 |
| 2665 | 2680 | 77 | 72 | 68 | 64 | 60 | 55 | 51 | 47 | 43 | 38 | 34 |
| 2680 | 2695 | 77 | 73 | 69 | 65 | 60 | 56 | 52 | 48 | 43 | 39 | 35 |
| 2695 | 2710 | 78 | 74 | 69 | 65 | 61 | 57 | 52 | 48 | 44 | 40 | 35 |
| 2710 | 2725 | 79 | 74 | 70 | 66 | 62 | 57 | 53 | 49 | 44 | 40 | 36 |
| 2725 | 2740 | 79 | 75 | 71 | 66 | 62 | 58 | 54 | 49 | 45 | 41 | 37 |
| 2740 | 2755 | 80 | 76 | 71 | 67 | 63 | 58 | 54 | 50 | 46 | 41 | 37 |
| 2755 | 2770 | 80 | 76 | 72 | 68 | 63 | 59 | 55 | 51 | 46 | 42 | 38 |
| 2770 | 2785 | 81 | 77 | 72 | 68 | 64 | 60 | 55 | 51 | 47 | 43 | 38 |
| 2785 | 2800 | 82 | 77 | 73 | 69 | 65 | 60 | 56 | 52 | 48 | 43 | 39 |
| 2800 | 2815 | 82 | 78 | 74 | 69 | 65 | 61 | 57 | 52 | 48 | 44 | 40 |
| 2815 | 2830 | 83 | 79 | 74 | 70 | 66 | 62 | 57 | 53 | 49 | 45 | 40 |
| 2830 | 2845 | 83 | 79 | 75 | 71 | 66 | 62 | 58 | 54 | 49 | 45 | 41 |
| 2845 | 2860 | 84 | 80 | 76 | 71 | 67 | 63 | 59 | 54 | 50 | 46 | 41 |
| 2860 | 2875 | 85 | 80 | 76 | 72 | 68 | 63 | 59 | 55 | 51 | 46 | 42 |
| 2875 | 2890 | 85 | 81 | 77 | 73 | 68 | 64 | 60 | 55 | 51 | 47 | 43 |
| 2890 | 2905 | 86 | 82 | 77 | 73 | 69 | 65 | 60 | 56 | 52 | 48 | 43 |
| 2905 | 2920 | 87 | 82 | 78 | 74 | 69 | 65 | 61 | 57 | 52 | 48 | 44 |
| 2920 | 2935 | 87 | 83 | 79 | 74 | 70 | 66 | 62 | 57 | 53 | 49 | 45 |
| 2935 | 2950 | 88 | 83 | 79 | 75 | 71 | 66 | 62 | 58 | 54 | 49 | 45 |
| 2950 | 2965 | 88 | 84 | 80 | 76 | 71 | 67 | 63 | 59 | 54 | 50 | 46 |
| 2965 | 2980 | 89 | 85 | 80 | 76 | 72 | 68 | 63 | 59 | 55 | 51 | 46 |
| 2980 | 2995 | 90 | 85 | 81 | 77 | 73 | 68 | 64 | 60 | 56 | 51 | 47 |
| 2995 | 3010 | 90 | 86 | 82 | 77 | 73 | 69 | 65 | 60 | 56 | 52 | 48 |
| 3010 | 3025 | 91 | 87 | 82 | 78 | 74 | 70 | 65 | 61 | 57 | 52 | 48 |
| 3025 | 3040 | 91 | 87 | 83 | 79 | 74 | 70 | 66 | 62 | 57 | 53 | 49 |
| 3040 | 3055 | 92 | 88 | 84 | 79 | 75 | 71 | 66 | 62 | 58 | 54 | 49 |
| 3055 | 3070 | 93 | 88 | 84 | 80 | 76 | 71 | 67 | 63 | 59 | 54 | 50 |
| 3070 | 3085 | 93 | 89 | 85 | 80 | 76 | 72 | 68 | 63 | 59 | 55 | 51 |
| 3085 | 3100 | 94 | 90 | 85 | 81 | 77 | 73 | 68 | 64 | 60 | 56 | 51 |
| 3100 | 3115 | 95 | 90 | 86 | 82 | 77 | 73 | 69 | 65 | 60 | 56 | 52 |
| 3115 | 3130 | 95 | 91 | 87 | 82 | 78 | 74 | 70 | 65 | 61 | 57 | 53 |
| 3130 | 3145 | 96 | 91 | 87 | 83 | 79 | 74 | 70 | 66 | 62 | 57 | 53 |
| 3145 | 3160 | 96 | 92 | 88 | 84 | 79 | 75 | 71 | 67 | 62 | 58 | 54 |
| 3160 | 3175 | 97 | 93 | 88 | 84 | 80 | 76 | 71 | 67 | 63 | 59 | 54 |
| 3175 | 3190 | 98 | 93 | 89 | 85 | 81 | 76 | 72 | 68 | 63 | 59 | 55 |
| 3190 | 3205 | 98 | 94 | 90 | 85 | 81 | 77 | 73 | 68 | 64 | 60 | 56 |
| 3205 | 3220 | 99 | 95 | 90 | 86 | 82 | 77 | 73 | 69 | 65 | 60 | 56 |
| 3220 | 3235 | 99 | 95 | 91 | 87 | 82 | 78 | 74 | 70 | 65 | 61 | 57 |
| 3235 | 3250 | 100 | 96 | 92 | 87 | 83 | 79 | 74 | 70 | 66 | 62 | 57 |
| 3250 | 3265 | 101 | 96 | 92 | 88 | 84 | 79 | 75 | 71 | 67 | 62 | 58 |
| 3265 | 3280 | 101 | 97 | 93 | 88 | 84 | 80 | 76 | 71 | 67 | 63 | 59 |
| 3280 | 3295 | 102 | 98 | 93 | 89 | 85 | 81 | 76 | 72 | 68 | 64 | 59 |
| 3295 | 3310 | 102 | 98 | 94 | 90 | 85 | 81 | 77 | 73 | 68 | 64 | 60 |
| 3310 | 3325 | 103 | 99 | 95 | 90 | 86 | 82 | 78 | 73 | 69 | 65 | 60 |
| 3325 | 3340 | 104 | 99 | 95 | 91 | 87 | 82 | 78 | 74 | 70 | 65 | 61 |
| 3340 | 3355 | 104 | 100 | 96 | 92 | 87 | 83 | 79 | 74 | 70 | 66 | 62 |
| 3355 | 3370 | 105 | 101 | 96 | 92 | 88 | 84 | 79 | 75 | 71 | 67 | 62 |
| 3370 | 3385 | 106 | 101 | 97 | 93 | 89 | 84 | 80 | 76 | 71 | 67 | 63 |
| 3385 | 3400 | 106 | 102 | 98 | 93 | 89 | 85 | 81 | 76 | 72 | 68 | 64 |
| 3400 | 3415 | 107 | 103 | 98 | 94 | 90 | 85 | 81 | 77 | 73 | 68 | 64 |
| 3415 | 3430 | 107 | 103 | 99 | 95 | 90 | 86 | 82 | 78 | 73 | 69 | 65 |
| 3430 | 3445 | 108 | 104 | 99 | 95 | 91 | 87 | 82 | 78 | 74 | 70 | 65 |
| 3445 | 3460 | 109 | 104 | 100 | 96 | 92 | 87 | 83 | 79 | 75 | 70 | 66 |
| 3460 | 3475 | 109 | 105 | 101 | 96 | 92 | 88 | 84 | 79 | 75 | 71 | 67 |
| 3475 | 3490 | 110 | 106 | 101 | 97 | 93 | 89 | 84 | 80 | 76 | 71 | 67 |
| Page | 49 |
# Head of Household - Semimonthly Payroll Period
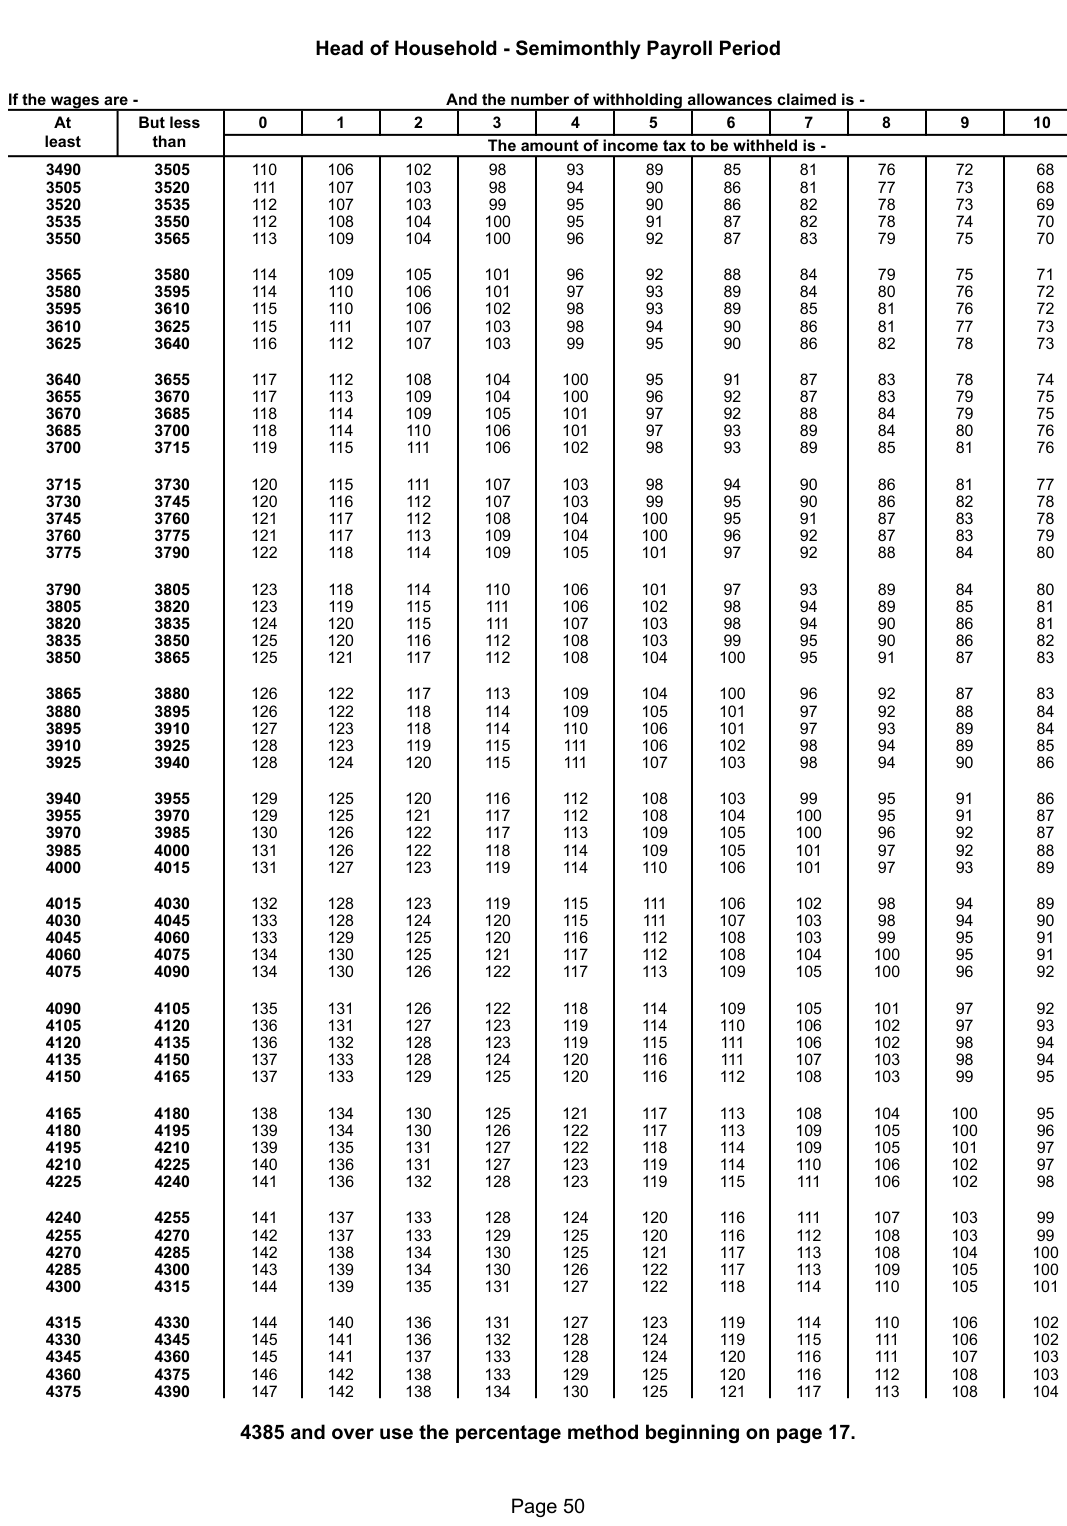
Text version of this table
| Head of H | ousehol | d - Semi | monthly | Payr | oll Period | |||||||
| wages are - | And | the numbe | r of withho | lding | allowances | claimed is - | ||||||
| At B | ut less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
| least | than | The amou | nt of inco | me tax | to be withh | eld is - | ||||||
| 3490 | 3505 | 110 | 106 | 102 | 98 | 93 | 89 | 85 | 81 | 76 | 72 | 68 |
| 3505 | 3520 | 111 | 107 | 103 | 98 | 94 | 90 | 86 | 81 | 77 | 73 | 68 |
| 3520 | 3535 | 112 | 107 | 103 | 99 | 95 | 90 | 86 | 82 | 78 | 73 | 69 |
| 3535 | 3550 | 112 | 108 | 104 | 100 | 95 | 91 | 87 | 82 | 78 | 74 | 70 |
| 3550 | 3565 | 113 | 109 | 104 | 100 | 96 | 92 | 87 | 83 | 79 | 75 | 70 |
| 3565 | 3580 | 114 | 109 | 105 | 101 | 96 | 92 | 88 | 84 | 79 | 75 | 71 |
| 3580 | 3595 | 114 | 110 | 106 | 101 | 97 | 93 | 89 | 84 | 80 | 76 | 72 |
| 3595 | 3610 | 115 | 110 | 106 | 102 | 98 | 93 | 89 | 85 | 81 | 76 | 72 |
| 3610 | 3625 | 115 | 111 | 107 | 103 | 98 | 94 | 90 | 86 | 81 | 77 | 73 |
| 3625 | 3640 | 116 | 112 | 107 | 103 | 99 | 95 | 90 | 86 | 82 | 78 | 73 |
| 3640 | 3655 | 117 | 112 | 108 | 104 | 100 | 95 | 91 | 87 | 83 | 78 | 74 |
| 3655 | 3670 | 117 | 113 | 109 | 104 | 100 | 96 | 92 | 87 | 83 | 79 | 75 |
| 3670 | 3685 | 118 | 114 | 109 | 105 | 101 | 97 | 92 | 88 | 84 | 79 | 75 |
| 3685 | 3700 | 118 | 114 | 110 | 106 | 101 | 97 | 93 | 89 | 84 | 80 | 76 |
| 3700 | 3715 | 119 | 115 | 111 | 106 | 102 | 98 | 93 | 89 | 85 | 81 | 76 |
| 3715 | 3730 | 120 | 115 | 111 | 107 | 103 | 98 | 94 | 90 | 86 | 81 | 77 |
| 3730 | 3745 | 120 | 116 | 112 | 107 | 103 | 99 | 95 | 90 | 86 | 82 | 78 |
| 3745 | 3760 | 121 | 117 | 112 | 108 | 104 | 100 | 95 | 91 | 87 | 83 | 78 |
| 3760 | 3775 | 121 | 117 | 113 | 109 | 104 | 100 | 96 | 92 | 87 | 83 | 79 |
| 3775 | 3790 | 122 | 118 | 114 | 109 | 105 | 101 | 97 | 92 | 88 | 84 | 80 |
| 3790 | 3805 | 123 | 118 | 114 | 110 | 106 | 101 | 97 | 93 | 89 | 84 | 80 |
| 3805 | 3820 | 123 | 119 | 115 | 111 | 106 | 102 | 98 | 94 | 89 | 85 | 81 |
| 3820 | 3835 | 124 | 120 | 115 | 111 | 107 | 103 | 98 | 94 | 90 | 86 | 81 |
| 3835 | 3850 | 125 | 120 | 116 | 112 | 108 | 103 | 99 | 95 | 90 | 86 | 82 |
| 3850 | 3865 | 125 | 121 | 117 | 112 | 108 | 104 | 100 | 95 | 91 | 87 | 83 |
| 3865 | 3880 | 126 | 122 | 117 | 113 | 109 | 104 | 100 | 96 | 92 | 87 | 83 |
| 3880 | 3895 | 126 | 122 | 118 | 114 | 109 | 105 | 101 | 97 | 92 | 88 | 84 |
| 3895 | 3910 | 127 | 123 | 118 | 114 | 110 | 106 | 101 | 97 | 93 | 89 | 84 |
| 3910 | 3925 | 128 | 123 | 119 | 115 | 111 | 106 | 102 | 98 | 94 | 89 | 85 |
| 3925 | 3940 | 128 | 124 | 120 | 115 | 111 | 107 | 103 | 98 | 94 | 90 | 86 |
| 3940 | 3955 | 129 | 125 | 120 | 116 | 112 | 108 | 103 | 99 | 95 | 91 | 86 |
| 3955 | 3970 | 129 | 125 | 121 | 117 | 112 | 108 | 104 | 100 | 95 | 91 | 87 |
| 3970 | 3985 | 130 | 126 | 122 | 117 | 113 | 109 | 105 | 100 | 96 | 92 | 87 |
| 3985 | 4000 | 131 | 126 | 122 | 118 | 114 | 109 | 105 | 101 | 97 | 92 | 88 |
| 4000 | 4015 | 131 | 127 | 123 | 119 | 114 | 110 | 106 | 101 | 97 | 93 | 89 |
| 4015 | 4030 | 132 | 128 | 123 | 119 | 115 | 111 | 106 | 102 | 98 | 94 | 89 |
| 4030 | 4045 | 133 | 128 | 124 | 120 | 115 | 111 | 107 | 103 | 98 | 94 | 90 |
| 4045 | 4060 | 133 | 129 | 125 | 120 | 116 | 112 | 108 | 103 | 99 | 95 | 91 |
| 4060 | 4075 | 134 | 130 | 125 | 121 | 117 | 112 | 108 | 104 | 100 | 95 | 91 |
| 4075 | 4090 | 134 | 130 | 126 | 122 | 117 | 113 | 109 | 105 | 100 | 96 | 92 |
| 4090 | 4105 | 135 | 131 | 126 | 122 | 118 | 114 | 109 | 105 | 101 | 97 | 92 |
| 4105 | 4120 | 136 | 131 | 127 | 123 | 119 | 114 | 110 | 106 | 102 | 97 | 93 |
| 4120 | 4135 | 136 | 132 | 128 | 123 | 119 | 115 | 111 | 106 | 102 | 98 | 94 |
| 4135 | 4150 | 137 | 133 | 128 | 124 | 120 | 116 | 111 | 107 | 103 | 98 | 94 |
| 4150 | 4165 | 137 | 133 | 129 | 125 | 120 | 116 | 112 | 108 | 103 | 99 | 95 |
| 4165 | 4180 | 138 | 134 | 130 | 125 | 121 | 117 | 113 | 108 | 104 | 100 | 95 |
| 4180 | 4195 | 139 | 134 | 130 | 126 | 122 | 117 | 113 | 109 | 105 | 100 | 96 |
| 4195 | 4210 | 139 | 135 | 131 | 127 | 122 | 118 | 114 | 109 | 105 | 101 | 97 |
| 4210 | 4225 | 140 | 136 | 131 | 127 | 123 | 119 | 114 | 110 | 106 | 102 | 97 |
| 4225 | 4240 | 141 | 136 | 132 | 128 | 123 | 119 | 115 | 111 | 106 | 102 | 98 |
| 4240 | 4255 | 141 | 137 | 133 | 128 | 124 | 120 | 116 | 111 | 107 | 103 | 99 |
| 4255 | 4270 | 142 | 137 | 133 | 129 | 125 | 120 | 116 | 112 | 108 | 103 | 99 |
| 4270 | 4285 | 142 | 138 | 134 | 130 | 125 | 121 | 117 | 113 | 108 | 104 | 100 |
| 4285 | 4300 | 143 | 139 | 134 | 130 | 126 | 122 | 117 | 113 | 109 | 105 | 100 |
| 4300 | 4315 | 144 | 139 | 135 | 131 | 127 | 122 | 118 | 114 | 110 | 105 | 101 |
| 4315 | 4330 | 144 | 140 | 136 | 131 | 127 | 123 | 119 | 114 | 110 | 106 | 102 |
| 4330 | 4345 | 145 | 141 | 136 | 132 | 128 | 124 | 119 | 115 | 111 | 106 | 102 |
| 4345 | 4360 | 145 | 141 | 137 | 133 | 128 | 124 | 120 | 116 | 111 | 107 | 103 |
| 4360 | 4375 | 146 | 142 | 138 | 133 | 129 | 125 | 120 | 116 | 112 | 108 | 103 |
| 4375 | 4390 | 147 | 142 | 138 | 134 | 130 | 125 | 121 | 117 | 113 | 108 | 104 |
| 4385 an | d over us | e the per | centage | method | begi | nning on | page 17. | |||||
| Page | 50 |
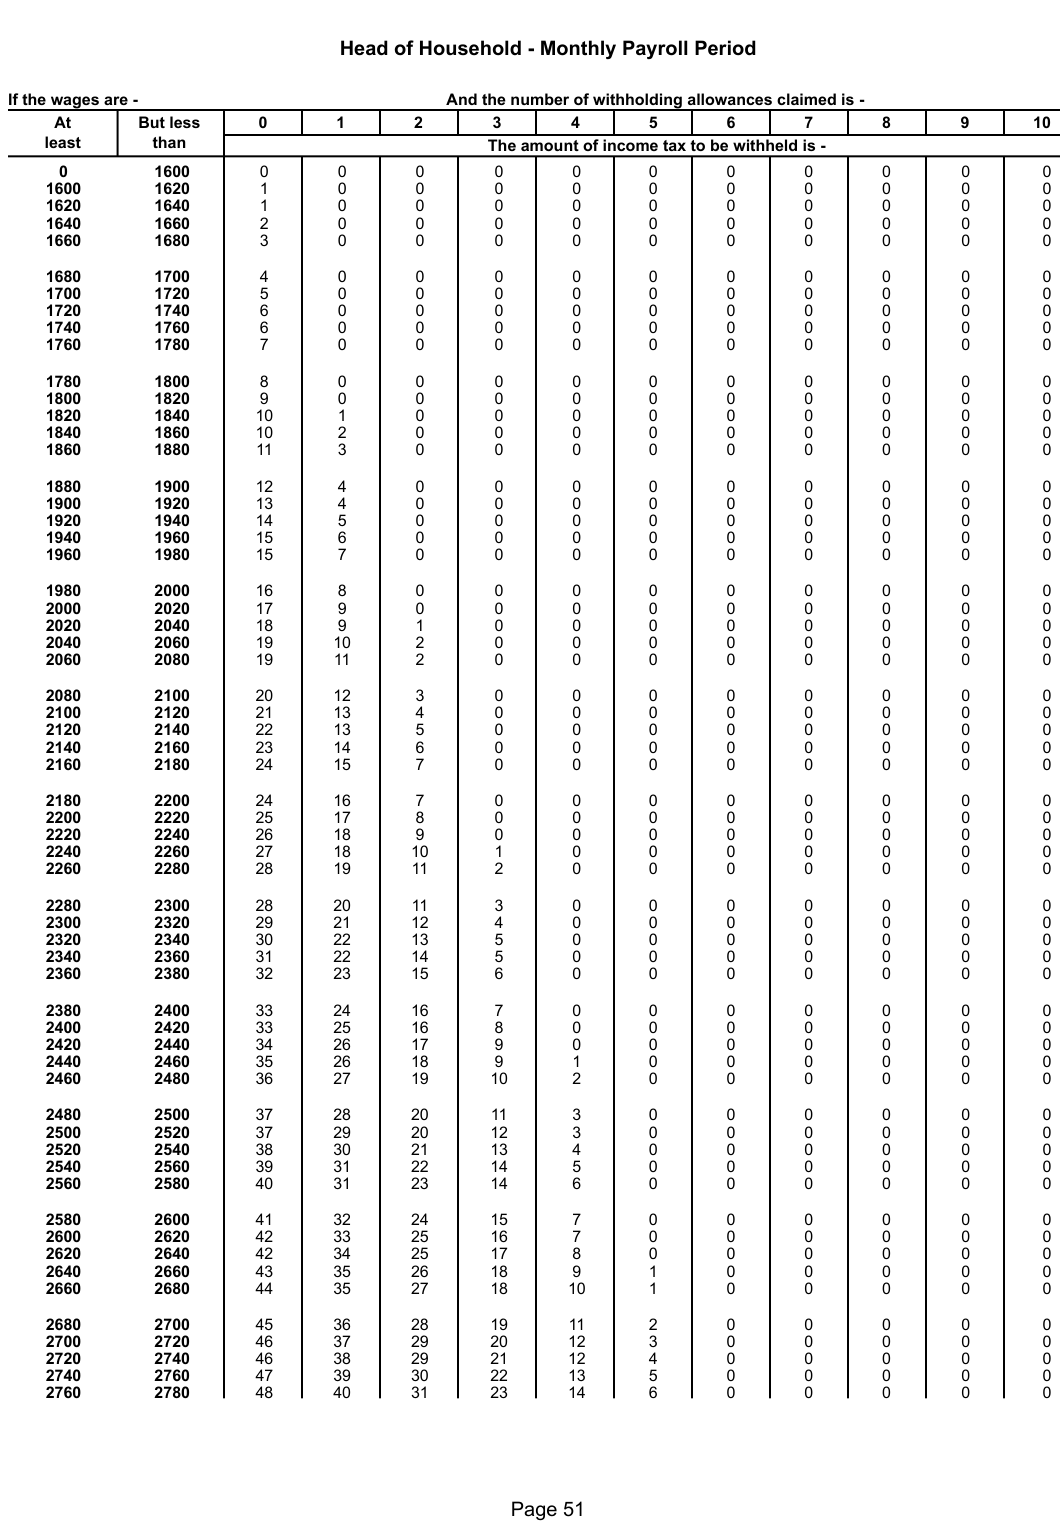
Text version of this table
| Head of | Househ | old - | Monthly Pa | yroll | Period | |||||||
| wages are - | And t | he num | ber of withhol | ding | allowances | claimed is - | ||||||
| At B | ut less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
| least | than | The am | ount of incom | e tax | to be withh | eld is - | ||||||
| 0 | 1600 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1600 | 1620 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1620 | 1640 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1640 | 1660 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1660 | 1680 | 3 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1680 | 1700 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1700 | 1720 | 5 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1720 | 1740 | 6 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1740 | 1760 | 6 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1760 | 1780 | 7 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1780 | 1800 | 8 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1800 | 1820 | 9 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1820 | 1840 | 10 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1840 | 1860 | 10 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1860 | 1880 | 11 | 3 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1880 | 1900 | 12 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1900 | 1920 | 13 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1920 | 1940 | 14 | 5 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1940 | 1960 | 15 | 6 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1960 | 1980 | 15 | 7 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 1980 | 2000 | 16 | 8 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2000 | 2020 | 17 | 9 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2020 | 2040 | 18 | 9 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2040 | 2060 | 19 | 10 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2060 | 2080 | 19 | 11 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2080 | 2100 | 20 | 12 | 3 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2100 | 2120 | 21 | 13 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2120 | 2140 | 22 | 13 | 5 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2140 | 2160 | 23 | 14 | 6 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2160 | 2180 | 24 | 15 | 7 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2180 | 2200 | 24 | 16 | 7 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2200 | 2220 | 25 | 17 | 8 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2220 | 2240 | 26 | 18 | 9 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2240 | 2260 | 27 | 18 | 10 | 1 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2260 | 2280 | 28 | 19 | 11 | 2 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2280 | 2300 | 28 | 20 | 11 | 3 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2300 | 2320 | 29 | 21 | 12 | 4 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2320 | 2340 | 30 | 22 | 13 | 5 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2340 | 2360 | 31 | 22 | 14 | 5 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2360 | 2380 | 32 | 23 | 15 | 6 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2380 | 2400 | 33 | 24 | 16 | 7 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2400 | 2420 | 33 | 25 | 16 | 8 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2420 | 2440 | 34 | 26 | 17 | 9 | 0 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2440 | 2460 | 35 | 26 | 18 | 9 | 1 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2460 | 2480 | 36 | 27 | 19 | 10 | 2 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2480 | 2500 | 37 | 28 | 20 | 11 | 3 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2500 | 2520 | 37 | 29 | 20 | 12 | 3 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2520 | 2540 | 38 | 30 | 21 | 13 | 4 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2540 | 2560 | 39 | 31 | 22 | 14 | 5 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2560 | 2580 | 40 | 31 | 23 | 14 | 6 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2580 | 2600 | 41 | 32 | 24 | 15 | 7 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2600 | 2620 | 42 | 33 | 25 | 16 | 7 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2620 | 2640 | 42 | 34 | 25 | 17 | 8 | 0 | 0 | 0 | 0 | 0 | 0 |
| 2640 | 2660 | 43 | 35 | 26 | 18 | 9 | 1 | 0 | 0 | 0 | 0 | 0 |
| 2660 | 2680 | 44 | 35 | 27 | 18 | 10 | 1 | 0 | 0 | 0 | 0 | 0 |
| 2680 | 2700 | 45 | 36 | 28 | 19 | 11 | 2 | 0 | 0 | 0 | 0 | 0 |
| 2700 | 2720 | 46 | 37 | 29 | 20 | 12 | 3 | 0 | 0 | 0 | 0 | 0 |
| 2720 | 2740 | 46 | 38 | 29 | 21 | 12 | 4 | 0 | 0 | 0 | 0 | 0 |
| 2740 | 2760 | 47 | 39 | 30 | 22 | 13 | 5 | 0 | 0 | 0 | 0 | 0 |
| 2760 | 2780 | 48 | 40 | 31 | 23 | 14 | 6 | 0 | 0 | 0 | 0 | 0 |
| Pa | ge 51 |
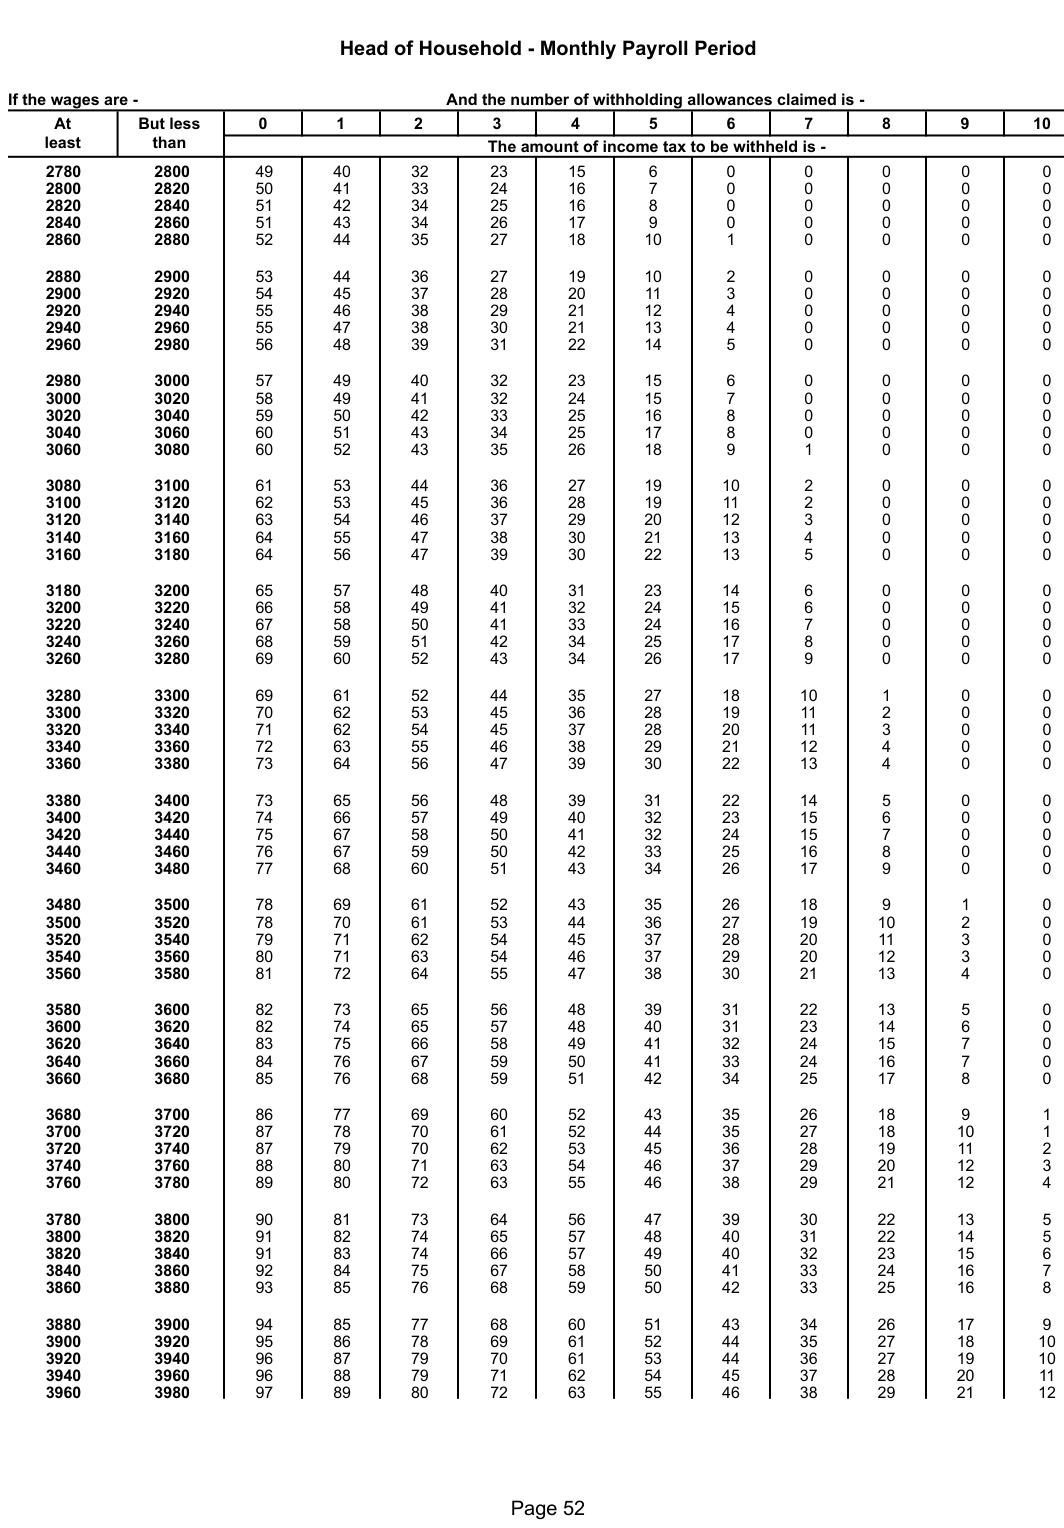
Text version of this table
| Head of | Househ | old - | Monthly Pa | yroll | Period | |||||||
| wages are - | And t | he num | ber of withho | lding | allowances | claimed is - | ||||||
| At B | ut less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 1 | 0 |
| least | than | The am | ount of incom | e tax | to be withh | eld is - | ||||||
| 2780 | 2800 | 49 | 40 | 32 | 23 | 15 | 6 | 0 | 0 | 0 | 0 | 0 |
| 2800 | 2820 | 50 | 41 | 33 | 24 | 16 | 7 | 0 | 0 | 0 | 0 | 0 |
| 2820 | 2840 | 51 | 42 | 34 | 25 | 16 | 8 | 0 | 0 | 0 | 0 | 0 |
| 2840 | 2860 | 51 | 43 | 34 | 26 | 17 | 9 | 0 | 0 | 0 | 0 | 0 |
| 2860 | 2880 | 52 | 44 | 35 | 27 | 18 | 10 | 1 | 0 | 0 | 0 | 0 |
| 2880 | 2900 | 53 | 44 | 36 | 27 | 19 | 10 | 2 | 0 | 0 | 0 | 0 |
| 2900 | 2920 | 54 | 45 | 37 | 28 | 20 | 11 | 3 | 0 | 0 | 0 | 0 |
| 2920 | 2940 | 55 | 46 | 38 | 29 | 21 | 12 | 4 | 0 | 0 | 0 | 0 |
| 2940 | 2960 | 55 | 47 | 38 | 30 | 21 | 13 | 4 | 0 | 0 | 0 | 0 |
| 2960 | 2980 | 56 | 48 | 39 | 31 | 22 | 14 | 5 | 0 | 0 | 0 | 0 |
| 2980 | 3000 | 57 | 49 | 40 | 32 | 23 | 15 | 6 | 0 | 0 | 0 | 0 |
| 3000 | 3020 | 58 | 49 | 41 | 32 | 24 | 15 | 7 | 0 | 0 | 0 | 0 |
| 3020 | 3040 | 59 | 50 | 42 | 33 | 25 | 16 | 8 | 0 | 0 | 0 | 0 |
| 3040 | 3060 | 60 | 51 | 43 | 34 | 25 | 17 | 8 | 0 | 0 | 0 | 0 |
| 3060 | 3080 | 60 | 52 | 43 | 35 | 26 | 18 | 9 | 1 | 0 | 0 | 0 |
| 3080 | 3100 | 61 | 53 | 44 | 36 | 27 | 19 | 10 | 2 | 0 | 0 | 0 |
| 3100 | 3120 | 62 | 53 | 45 | 36 | 28 | 19 | 11 | 2 | 0 | 0 | 0 |
| 3120 | 3140 | 63 | 54 | 46 | 37 | 29 | 20 | 12 | 3 | 0 | 0 | 0 |
| 3140 | 3160 | 64 | 55 | 47 | 38 | 30 | 21 | 13 | 4 | 0 | 0 | 0 |
| 3160 | 3180 | 64 | 56 | 47 | 39 | 30 | 22 | 13 | 5 | 0 | 0 | 0 |
| 3180 | 3200 | 65 | 57 | 48 | 40 | 31 | 23 | 14 | 6 | 0 | 0 | 0 |
| 3200 | 3220 | 66 | 58 | 49 | 41 | 32 | 24 | 15 | 6 | 0 | 0 | 0 |
| 3220 | 3240 | 67 | 58 | 50 | 41 | 33 | 24 | 16 | 7 | 0 | 0 | 0 |
| 3240 | 3260 | 68 | 59 | 51 | 42 | 34 | 25 | 17 | 8 | 0 | 0 | 0 |
| 3260 | 3280 | 69 | 60 | 52 | 43 | 34 | 26 | 17 | 9 | 0 | 0 | 0 |
| 3280 | 3300 | 69 | 61 | 52 | 44 | 35 | 27 | 18 | 10 | 1 | 0 | 0 |
| 3300 | 3320 | 70 | 62 | 53 | 45 | 36 | 28 | 19 | 11 | 2 | 0 | 0 |
| 3320 | 3340 | 71 | 62 | 54 | 45 | 37 | 28 | 20 | 11 | 3 | 0 | 0 |
| 3340 | 3360 | 72 | 63 | 55 | 46 | 38 | 29 | 21 | 12 | 4 | 0 | 0 |
| 3360 | 3380 | 73 | 64 | 56 | 47 | 39 | 30 | 22 | 13 | 4 | 0 | 0 |
| 3380 | 3400 | 73 | 65 | 56 | 48 | 39 | 31 | 22 | 14 | 5 | 0 | 0 |
| 3400 | 3420 | 74 | 66 | 57 | 49 | 40 | 32 | 23 | 15 | 6 | 0 | 0 |
| 3420 | 3440 | 75 | 67 | 58 | 50 | 41 | 32 | 24 | 15 | 7 | 0 | 0 |
| 3440 | 3460 | 76 | 67 | 59 | 50 | 42 | 33 | 25 | 16 | 8 | 0 | 0 |
| 3460 | 3480 | 77 | 68 | 60 | 51 | 43 | 34 | 26 | 17 | 9 | 0 | 0 |
| 3480 | 3500 | 78 | 69 | 61 | 52 | 43 | 35 | 26 | 18 | 9 | 1 | 0 |
| 3500 | 3520 | 78 | 70 | 61 | 53 | 44 | 36 | 27 | 19 | 10 | 2 | 0 |
| 3520 | 3540 | 79 | 71 | 62 | 54 | 45 | 37 | 28 | 20 | 11 | 3 | 0 |
| 3540 | 3560 | 80 | 71 | 63 | 54 | 46 | 37 | 29 | 20 | 12 | 3 | 0 |
| 3560 | 3580 | 81 | 72 | 64 | 55 | 47 | 38 | 30 | 21 | 13 | 4 | 0 |
| 3580 | 3600 | 82 | 73 | 65 | 56 | 48 | 39 | 31 | 22 | 13 | 5 | 0 |
| 3600 | 3620 | 82 | 74 | 65 | 57 | 48 | 40 | 31 | 23 | 14 | 6 | 0 |
| 3620 | 3640 | 83 | 75 | 66 | 58 | 49 | 41 | 32 | 24 | 15 | 7 | 0 |
| 3640 | 3660 | 84 | 76 | 67 | 59 | 50 | 41 | 33 | 24 | 16 | 7 | 0 |
| 3660 | 3680 | 85 | 76 | 68 | 59 | 51 | 42 | 34 | 25 | 17 | 8 | 0 |
| 3680 | 3700 | 86 | 77 | 69 | 60 | 52 | 43 | 35 | 26 | 18 | 9 | 1 |
| 3700 | 3720 | 87 | 78 | 70 | 61 | 52 | 44 | 35 | 27 | 18 | 10 | 1 |
| 3720 | 3740 | 87 | 79 | 70 | 62 | 53 | 45 | 36 | 28 | 19 | 11 | 2 |
| 3740 | 3760 | 88 | 80 | 71 | 63 | 54 | 46 | 37 | 29 | 20 | 12 | 3 |
| 3760 | 3780 | 89 | 80 | 72 | 63 | 55 | 46 | 38 | 29 | 21 | 12 | 4 |
| 3780 | 3800 | 90 | 81 | 73 | 64 | 56 | 47 | 39 | 30 | 22 | 13 | 5 |
| 3800 | 3820 | 91 | 82 | 74 | 65 | 57 | 48 | 40 | 31 | 22 | 14 | 5 |
| 3820 | 3840 | 91 | 83 | 74 | 66 | 57 | 49 | 40 | 32 | 23 | 15 | 6 |
| 3840 | 3860 | 92 | 84 | 75 | 67 | 58 | 50 | 41 | 33 | 24 | 16 | 7 |
| 3860 | 3880 | 93 | 85 | 76 | 68 | 59 | 50 | 42 | 33 | 25 | 16 | 8 |
| 3880 | 3900 | 94 | 85 | 77 | 68 | 60 | 51 | 43 | 34 | 26 | 17 | 9 |
| 3900 | 3920 | 95 | 86 | 78 | 69 | 61 | 52 | 44 | 35 | 27 | 18 | 10 |
| 3920 | 3940 | 96 | 87 | 79 | 70 | 61 | 53 | 44 | 36 | 27 | 19 | 10 |
| 3940 | 3960 | 96 | 88 | 79 | 71 | 62 | 54 | 45 | 37 | 28 | 20 | 11 |
| 3960 | 3980 | 97 | 89 | 80 | 72 | 63 | 55 | 46 | 38 | 29 | 21 | 12 |
| Pa | ge 52 |
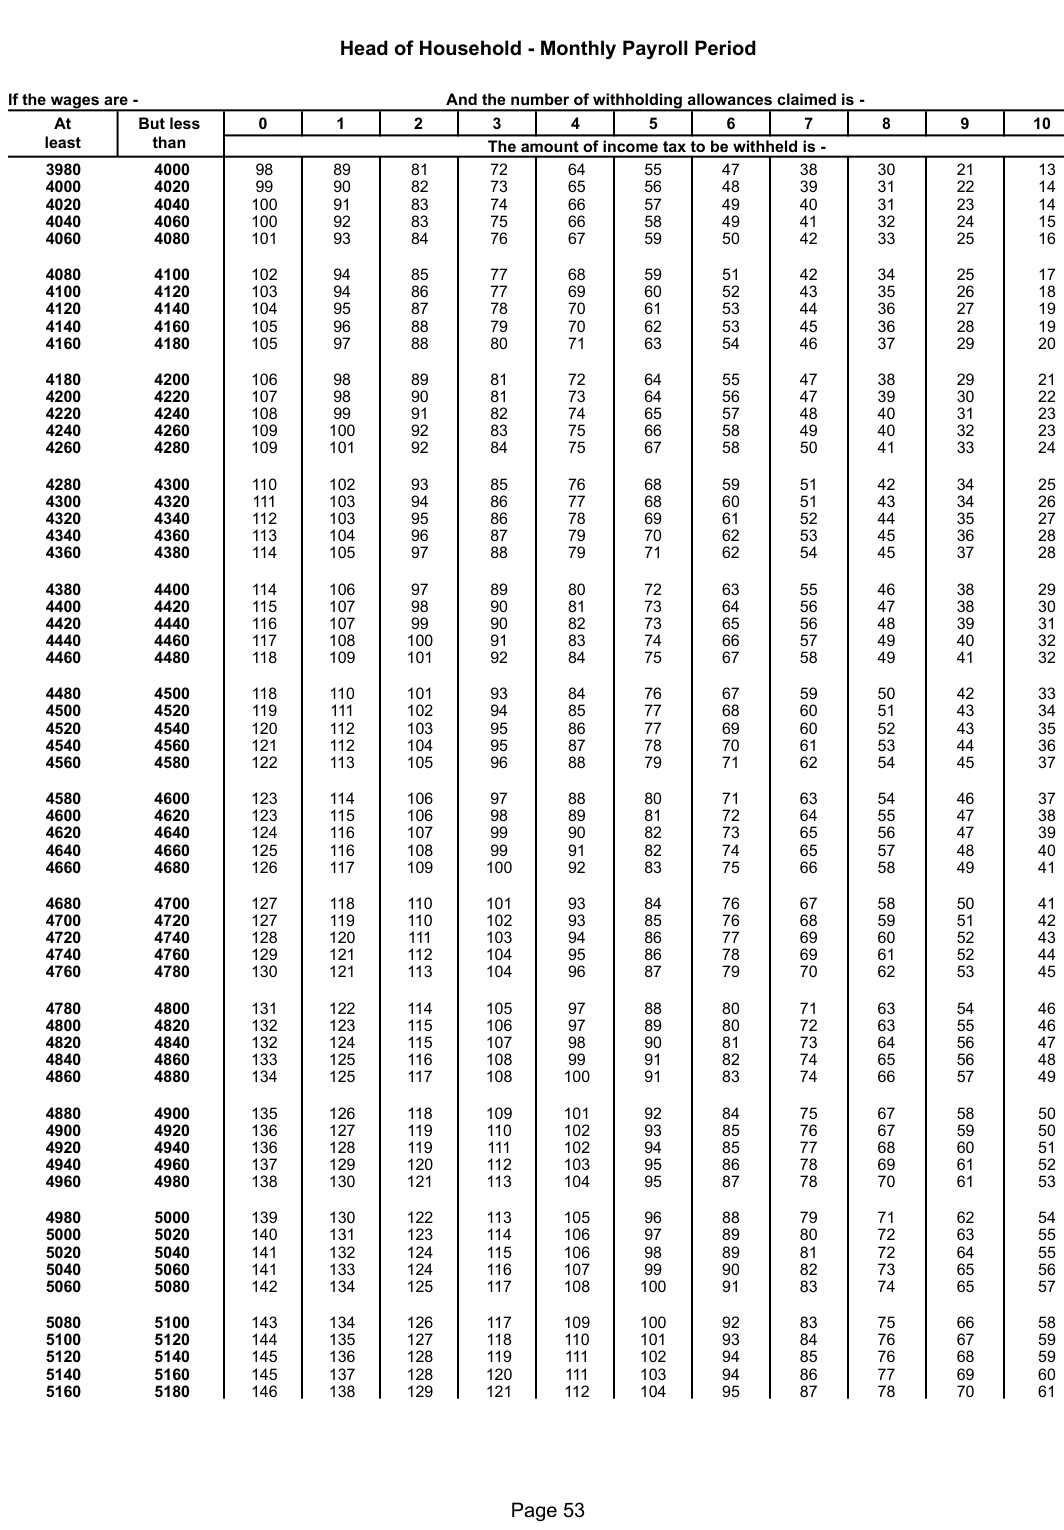
Text version of this table
| Head o | f House | hold - | Monthly P | ayroll | Period | |||||||
| wages are - | And t | he num | ber of withho | lding | allowances | claimed is - | ||||||
| At B | ut less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 1 | 0 |
| least | than | The am | ount of inco | me tax | to be withh | eld is - | ||||||
| 3980 | 4000 | 98 | 89 | 81 | 72 | 64 | 55 | 47 | 38 | 30 | 21 | 13 |
| 4000 | 4020 | 99 | 90 | 82 | 73 | 65 | 56 | 48 | 39 | 31 | 22 | 14 |
| 4020 | 4040 | 100 | 91 | 83 | 74 | 66 | 57 | 49 | 40 | 31 | 23 | 14 |
| 4040 | 4060 | 100 | 92 | 83 | 75 | 66 | 58 | 49 | 41 | 32 | 24 | 15 |
| 4060 | 4080 | 101 | 93 | 84 | 76 | 67 | 59 | 50 | 42 | 33 | 25 | 16 |
| 4080 | 4100 | 102 | 94 | 85 | 77 | 68 | 59 | 51 | 42 | 34 | 25 | 17 |
| 4100 | 4120 | 103 | 94 | 86 | 77 | 69 | 60 | 52 | 43 | 35 | 26 | 18 |
| 4120 | 4140 | 104 | 95 | 87 | 78 | 70 | 61 | 53 | 44 | 36 | 27 | 19 |
| 4140 | 4160 | 105 | 96 | 88 | 79 | 70 | 62 | 53 | 45 | 36 | 28 | 19 |
| 4160 | 4180 | 105 | 97 | 88 | 80 | 71 | 63 | 54 | 46 | 37 | 29 | 20 |
| 4180 | 4200 | 106 | 98 | 89 | 81 | 72 | 64 | 55 | 47 | 38 | 29 | 21 |
| 4200 | 4220 | 107 | 98 | 90 | 81 | 73 | 64 | 56 | 47 | 39 | 30 | 22 |
| 4220 | 4240 | 108 | 99 | 91 | 82 | 74 | 65 | 57 | 48 | 40 | 31 | 23 |
| 4240 | 4260 | 109 | 100 | 92 | 83 | 75 | 66 | 58 | 49 | 40 | 32 | 23 |
| 4260 | 4280 | 109 | 101 | 92 | 84 | 75 | 67 | 58 | 50 | 41 | 33 | 24 |
| 4280 | 4300 | 110 | 102 | 93 | 85 | 76 | 68 | 59 | 51 | 42 | 34 | 25 |
| 4300 | 4320 | 111 | 103 | 94 | 86 | 77 | 68 | 60 | 51 | 43 | 34 | 26 |
| 4320 | 4340 | 112 | 103 | 95 | 86 | 78 | 69 | 61 | 52 | 44 | 35 | 27 |
| 4340 | 4360 | 113 | 104 | 96 | 87 | 79 | 70 | 62 | 53 | 45 | 36 | 28 |
| 4360 | 4380 | 114 | 105 | 97 | 88 | 79 | 71 | 62 | 54 | 45 | 37 | 28 |
| 4380 | 4400 | 114 | 106 | 97 | 89 | 80 | 72 | 63 | 55 | 46 | 38 | 29 |
| 4400 | 4420 | 115 | 107 | 98 | 90 | 81 | 73 | 64 | 56 | 47 | 38 | 30 |
| 4420 | 4440 | 116 | 107 | 99 | 90 | 82 | 73 | 65 | 56 | 48 | 39 | 31 |
| 4440 | 4460 | 117 | 108 | 100 | 91 | 83 | 74 | 66 | 57 | 49 | 40 | 32 |
| 4460 | 4480 | 118 | 109 | 101 | 92 | 84 | 75 | 67 | 58 | 49 | 41 | 32 |
| 4480 | 4500 | 118 | 110 | 101 | 93 | 84 | 76 | 67 | 59 | 50 | 42 | 33 |
| 4500 | 4520 | 119 | 111 | 102 | 94 | 85 | 77 | 68 | 60 | 51 | 43 | 34 |
| 4520 | 4540 | 120 | 112 | 103 | 95 | 86 | 77 | 69 | 60 | 52 | 43 | 35 |
| 4540 | 4560 | 121 | 112 | 104 | 95 | 87 | 78 | 70 | 61 | 53 | 44 | 36 |
| 4560 | 4580 | 122 | 113 | 105 | 96 | 88 | 79 | 71 | 62 | 54 | 45 | 37 |
| 4580 | 4600 | 123 | 114 | 106 | 97 | 88 | 80 | 71 | 63 | 54 | 46 | 37 |
| 4600 | 4620 | 123 | 115 | 106 | 98 | 89 | 81 | 72 | 64 | 55 | 47 | 38 |
| 4620 | 4640 | 124 | 116 | 107 | 99 | 90 | 82 | 73 | 65 | 56 | 47 | 39 |
| 4640 | 4660 | 125 | 116 | 108 | 99 | 91 | 82 | 74 | 65 | 57 | 48 | 40 |
| 4660 | 4680 | 126 | 117 | 109 | 100 | 92 | 83 | 75 | 66 | 58 | 49 | 41 |
| 4680 | 4700 | 127 | 118 | 110 | 101 | 93 | 84 | 76 | 67 | 58 | 50 | 41 |
| 4700 | 4720 | 127 | 119 | 110 | 102 | 93 | 85 | 76 | 68 | 59 | 51 | 42 |
| 4720 | 4740 | 128 | 120 | 111 | 103 | 94 | 86 | 77 | 69 | 60 | 52 | 43 |
| 4740 | 4760 | 129 | 121 | 112 | 104 | 95 | 86 | 78 | 69 | 61 | 52 | 44 |
| 4760 | 4780 | 130 | 121 | 113 | 104 | 96 | 87 | 79 | 70 | 62 | 53 | 45 |
| 4780 | 4800 | 131 | 122 | 114 | 105 | 97 | 88 | 80 | 71 | 63 | 54 | 46 |
| 4800 | 4820 | 132 | 123 | 115 | 106 | 97 | 89 | 80 | 72 | 63 | 55 | 46 |
| 4820 | 4840 | 132 | 124 | 115 | 107 | 98 | 90 | 81 | 73 | 64 | 56 | 47 |
| 4840 | 4860 | 133 | 125 | 116 | 108 | 99 | 91 | 82 | 74 | 65 | 56 | 48 |
| 4860 | 4880 | 134 | 125 | 117 | 108 | 100 | 91 | 83 | 74 | 66 | 57 | 49 |
| 4880 | 4900 | 135 | 126 | 118 | 109 | 101 | 92 | 84 | 75 | 67 | 58 | 50 |
| 4900 | 4920 | 136 | 127 | 119 | 110 | 102 | 93 | 85 | 76 | 67 | 59 | 50 |
| 4920 | 4940 | 136 | 128 | 119 | 111 | 102 | 94 | 85 | 77 | 68 | 60 | 51 |
| 4940 | 4960 | 137 | 129 | 120 | 112 | 103 | 95 | 86 | 78 | 69 | 61 | 52 |
| 4960 | 4980 | 138 | 130 | 121 | 113 | 104 | 95 | 87 | 78 | 70 | 61 | 53 |
| 4980 | 5000 | 139 | 130 | 122 | 113 | 105 | 96 | 88 | 79 | 71 | 62 | 54 |
| 5000 | 5020 | 140 | 131 | 123 | 114 | 106 | 97 | 89 | 80 | 72 | 63 | 55 |
| 5020 | 5040 | 141 | 132 | 124 | 115 | 106 | 98 | 89 | 81 | 72 | 64 | 55 |
| 5040 | 5060 | 141 | 133 | 124 | 116 | 107 | 99 | 90 | 82 | 73 | 65 | 56 |
| 5060 | 5080 | 142 | 134 | 125 | 117 | 108 | 100 | 91 | 83 | 74 | 65 | 57 |
| 5080 | 5100 | 143 | 134 | 126 | 117 | 109 | 100 | 92 | 83 | 75 | 66 | 58 |
| 5100 | 5120 | 144 | 135 | 127 | 118 | 110 | 101 | 93 | 84 | 76 | 67 | 59 |
| 5120 | 5140 | 145 | 136 | 128 | 119 | 111 | 102 | 94 | 85 | 76 | 68 | 59 |
| 5140 | 5160 | 145 | 137 | 128 | 120 | 111 | 103 | 94 | 86 | 77 | 69 | 60 |
| 5160 | 5180 | 146 | 138 | 129 | 121 | 112 | 104 | 95 | 87 | 78 | 70 | 61 |
| Pa | ge 53 |
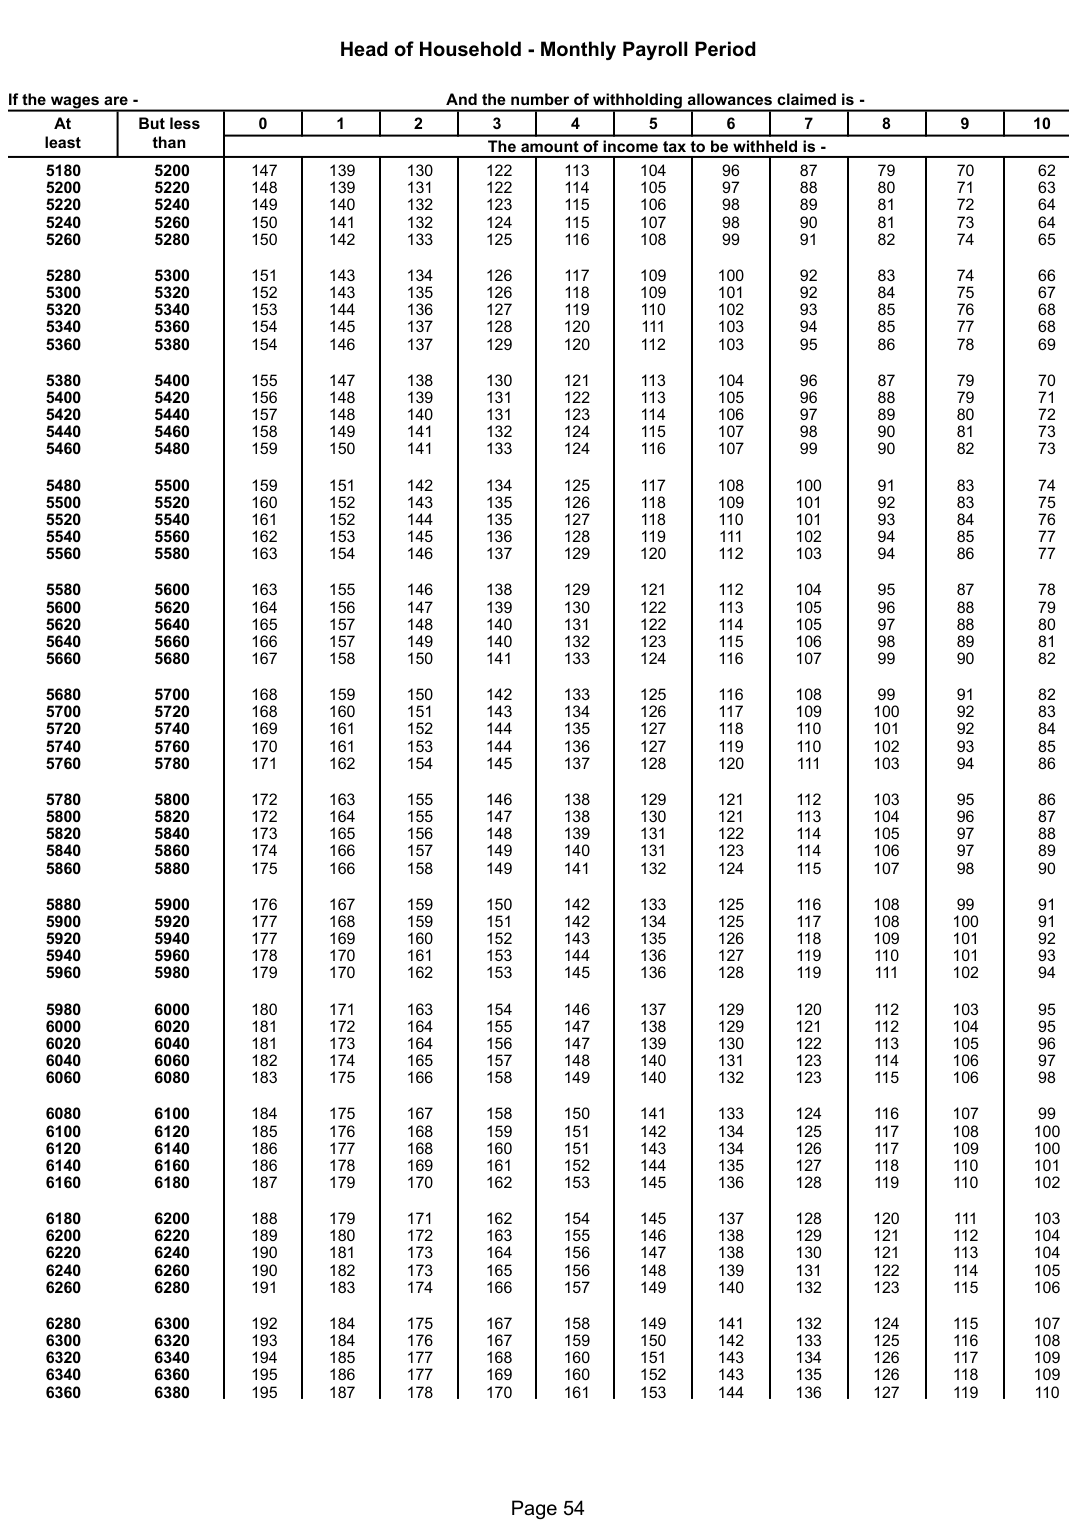
Text version of this table
| Head o | f House | hold - | Monthly P | ayroll | Period | |||||||
| wages are - | And t | he num | ber of withho | lding | allowances | claimed is - | ||||||
| At B | ut less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
| least | than | The am | ount of inco | me tax | to be withh | eld is - | ||||||
| 5180 | 5200 | 147 | 139 | 130 | 122 | 113 | 104 | 96 | 87 | 79 | 70 | 62 |
| 5200 | 5220 | 148 | 139 | 131 | 122 | 114 | 105 | 97 | 88 | 80 | 71 | 63 |
| 5220 | 5240 | 149 | 140 | 132 | 123 | 115 | 106 | 98 | 89 | 81 | 72 | 64 |
| 5240 | 5260 | 150 | 141 | 132 | 124 | 115 | 107 | 98 | 90 | 81 | 73 | 64 |
| 5260 | 5280 | 150 | 142 | 133 | 125 | 116 | 108 | 99 | 91 | 82 | 74 | 65 |
| 5280 | 5300 | 151 | 143 | 134 | 126 | 117 | 109 | 100 | 92 | 83 | 74 | 66 |
| 5300 | 5320 | 152 | 143 | 135 | 126 | 118 | 109 | 101 | 92 | 84 | 75 | 67 |
| 5320 | 5340 | 153 | 144 | 136 | 127 | 119 | 110 | 102 | 93 | 85 | 76 | 68 |
| 5340 | 5360 | 154 | 145 | 137 | 128 | 120 | 111 | 103 | 94 | 85 | 77 | 68 |
| 5360 | 5380 | 154 | 146 | 137 | 129 | 120 | 112 | 103 | 95 | 86 | 78 | 69 |
| 5380 | 5400 | 155 | 147 | 138 | 130 | 121 | 113 | 104 | 96 | 87 | 79 | 70 |
| 5400 | 5420 | 156 | 148 | 139 | 131 | 122 | 113 | 105 | 96 | 88 | 79 | 71 |
| 5420 | 5440 | 157 | 148 | 140 | 131 | 123 | 114 | 106 | 97 | 89 | 80 | 72 |
| 5440 | 5460 | 158 | 149 | 141 | 132 | 124 | 115 | 107 | 98 | 90 | 81 | 73 |
| 5460 | 5480 | 159 | 150 | 141 | 133 | 124 | 116 | 107 | 99 | 90 | 82 | 73 |
| 5480 | 5500 | 159 | 151 | 142 | 134 | 125 | 117 | 108 | 100 | 91 | 83 | 74 |
| 5500 | 5520 | 160 | 152 | 143 | 135 | 126 | 118 | 109 | 101 | 92 | 83 | 75 |
| 5520 | 5540 | 161 | 152 | 144 | 135 | 127 | 118 | 110 | 101 | 93 | 84 | 76 |
| 5540 | 5560 | 162 | 153 | 145 | 136 | 128 | 119 | 111 | 102 | 94 | 85 | 77 |
| 5560 | 5580 | 163 | 154 | 146 | 137 | 129 | 120 | 112 | 103 | 94 | 86 | 77 |
| 5580 | 5600 | 163 | 155 | 146 | 138 | 129 | 121 | 112 | 104 | 95 | 87 | 78 |
| 5600 | 5620 | 164 | 156 | 147 | 139 | 130 | 122 | 113 | 105 | 96 | 88 | 79 |
| 5620 | 5640 | 165 | 157 | 148 | 140 | 131 | 122 | 114 | 105 | 97 | 88 | 80 |
| 5640 | 5660 | 166 | 157 | 149 | 140 | 132 | 123 | 115 | 106 | 98 | 89 | 81 |
| 5660 | 5680 | 167 | 158 | 150 | 141 | 133 | 124 | 116 | 107 | 99 | 90 | 82 |
| 5680 | 5700 | 168 | 159 | 150 | 142 | 133 | 125 | 116 | 108 | 99 | 91 | 82 |
| 5700 | 5720 | 168 | 160 | 151 | 143 | 134 | 126 | 117 | 109 | 100 | 92 | 83 |
| 5720 | 5740 | 169 | 161 | 152 | 144 | 135 | 127 | 118 | 110 | 101 | 92 | 84 |
| 5740 | 5760 | 170 | 161 | 153 | 144 | 136 | 127 | 119 | 110 | 102 | 93 | 85 |
| 5760 | 5780 | 171 | 162 | 154 | 145 | 137 | 128 | 120 | 111 | 103 | 94 | 86 |
| 5780 | 5800 | 172 | 163 | 155 | 146 | 138 | 129 | 121 | 112 | 103 | 95 | 86 |
| 5800 | 5820 | 172 | 164 | 155 | 147 | 138 | 130 | 121 | 113 | 104 | 96 | 87 |
| 5820 | 5840 | 173 | 165 | 156 | 148 | 139 | 131 | 122 | 114 | 105 | 97 | 88 |
| 5840 | 5860 | 174 | 166 | 157 | 149 | 140 | 131 | 123 | 114 | 106 | 97 | 89 |
| 5860 | 5880 | 175 | 166 | 158 | 149 | 141 | 132 | 124 | 115 | 107 | 98 | 90 |
| 5880 | 5900 | 176 | 167 | 159 | 150 | 142 | 133 | 125 | 116 | 108 | 99 | 91 |
| 5900 | 5920 | 177 | 168 | 159 | 151 | 142 | 134 | 125 | 117 | 108 | 100 | 91 |
| 5920 | 5940 | 177 | 169 | 160 | 152 | 143 | 135 | 126 | 118 | 109 | 101 | 92 |
| 5940 | 5960 | 178 | 170 | 161 | 153 | 144 | 136 | 127 | 119 | 110 | 101 | 93 |
| 5960 | 5980 | 179 | 170 | 162 | 153 | 145 | 136 | 128 | 119 | 111 | 102 | 94 |
| 5980 | 6000 | 180 | 171 | 163 | 154 | 146 | 137 | 129 | 120 | 112 | 103 | 95 |
| 6000 | 6020 | 181 | 172 | 164 | 155 | 147 | 138 | 129 | 121 | 112 | 104 | 95 |
| 6020 | 6040 | 181 | 173 | 164 | 156 | 147 | 139 | 130 | 122 | 113 | 105 | 96 |
| 6040 | 6060 | 182 | 174 | 165 | 157 | 148 | 140 | 131 | 123 | 114 | 106 | 97 |
| 6060 | 6080 | 183 | 175 | 166 | 158 | 149 | 140 | 132 | 123 | 115 | 106 | 98 |
| 6080 | 6100 | 184 | 175 | 167 | 158 | 150 | 141 | 133 | 124 | 116 | 107 | 99 |
| 6100 | 6120 | 185 | 176 | 168 | 159 | 151 | 142 | 134 | 125 | 117 | 108 | 100 |
| 6120 | 6140 | 186 | 177 | 168 | 160 | 151 | 143 | 134 | 126 | 117 | 109 | 100 |
| 6140 | 6160 | 186 | 178 | 169 | 161 | 152 | 144 | 135 | 127 | 118 | 110 | 101 |
| 6160 | 6180 | 187 | 179 | 170 | 162 | 153 | 145 | 136 | 128 | 119 | 110 | 102 |
| 6180 | 6200 | 188 | 179 | 171 | 162 | 154 | 145 | 137 | 128 | 120 | 111 | 103 |
| 6200 | 6220 | 189 | 180 | 172 | 163 | 155 | 146 | 138 | 129 | 121 | 112 | 104 |
| 6220 | 6240 | 190 | 181 | 173 | 164 | 156 | 147 | 138 | 130 | 121 | 113 | 104 |
| 6240 | 6260 | 190 | 182 | 173 | 165 | 156 | 148 | 139 | 131 | 122 | 114 | 105 |
| 6260 | 6280 | 191 | 183 | 174 | 166 | 157 | 149 | 140 | 132 | 123 | 115 | 106 |
| 6280 | 6300 | 192 | 184 | 175 | 167 | 158 | 149 | 141 | 132 | 124 | 115 | 107 |
| 6300 | 6320 | 193 | 184 | 176 | 167 | 159 | 150 | 142 | 133 | 125 | 116 | 108 |
| 6320 | 6340 | 194 | 185 | 177 | 168 | 160 | 151 | 143 | 134 | 126 | 117 | 109 |
| 6340 | 6360 | 195 | 186 | 177 | 169 | 160 | 152 | 143 | 135 | 126 | 118 | 109 |
| 6360 | 6380 | 195 | 187 | 178 | 170 | 161 | 153 | 144 | 136 | 127 | 119 | 110 |
| Pa | ge 54 |
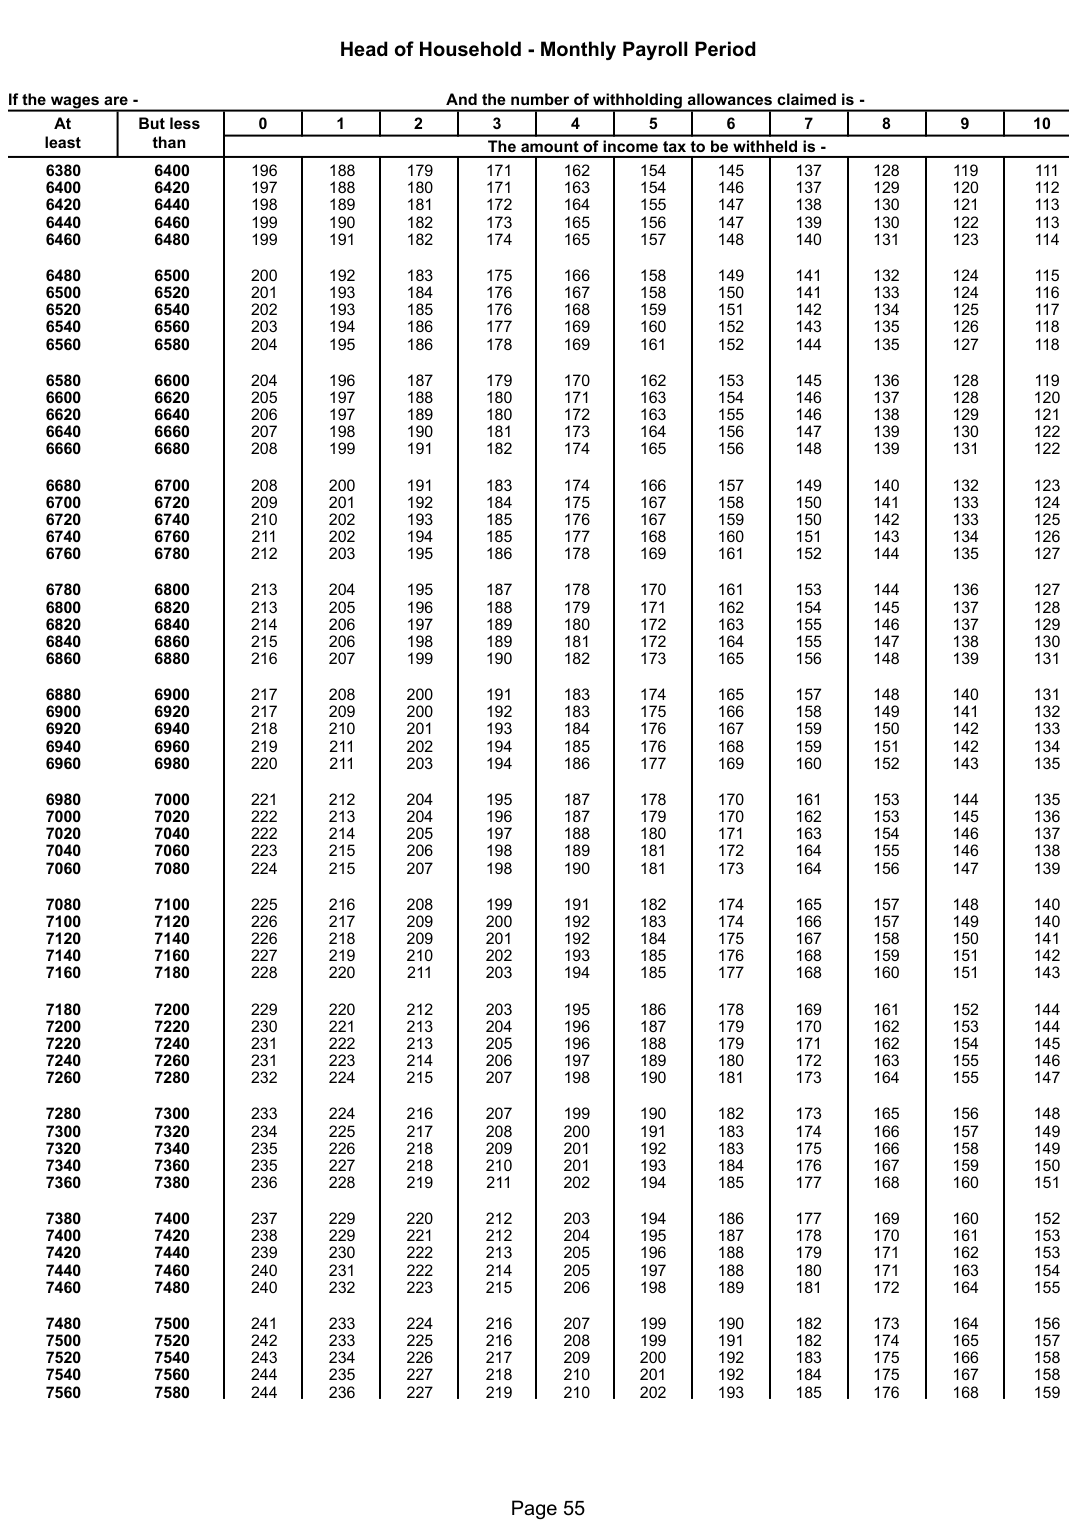
Text version of this table
| Head o | f House | hold - | Monthly P | ayroll | Period | |||||||
| wages are - | And t | he num | ber of withho | lding | allowances | claimed is - | ||||||
| At B | ut less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
| least | than | The am | ount of inco | me tax | to be withh | eld is - | ||||||
| 6380 | 6400 | 196 | 188 | 179 | 171 | 162 | 154 | 145 | 137 | 128 | 119 | 111 |
| 6400 | 6420 | 197 | 188 | 180 | 171 | 163 | 154 | 146 | 137 | 129 | 120 | 112 |
| 6420 | 6440 | 198 | 189 | 181 | 172 | 164 | 155 | 147 | 138 | 130 | 121 | 113 |
| 6440 | 6460 | 199 | 190 | 182 | 173 | 165 | 156 | 147 | 139 | 130 | 122 | 113 |
| 6460 | 6480 | 199 | 191 | 182 | 174 | 165 | 157 | 148 | 140 | 131 | 123 | 114 |
| 6480 | 6500 | 200 | 192 | 183 | 175 | 166 | 158 | 149 | 141 | 132 | 124 | 115 |
| 6500 | 6520 | 201 | 193 | 184 | 176 | 167 | 158 | 150 | 141 | 133 | 124 | 116 |
| 6520 | 6540 | 202 | 193 | 185 | 176 | 168 | 159 | 151 | 142 | 134 | 125 | 117 |
| 6540 | 6560 | 203 | 194 | 186 | 177 | 169 | 160 | 152 | 143 | 135 | 126 | 118 |
| 6560 | 6580 | 204 | 195 | 186 | 178 | 169 | 161 | 152 | 144 | 135 | 127 | 118 |
| 6580 | 6600 | 204 | 196 | 187 | 179 | 170 | 162 | 153 | 145 | 136 | 128 | 119 |
| 6600 | 6620 | 205 | 197 | 188 | 180 | 171 | 163 | 154 | 146 | 137 | 128 | 120 |
| 6620 | 6640 | 206 | 197 | 189 | 180 | 172 | 163 | 155 | 146 | 138 | 129 | 121 |
| 6640 | 6660 | 207 | 198 | 190 | 181 | 173 | 164 | 156 | 147 | 139 | 130 | 122 |
| 6660 | 6680 | 208 | 199 | 191 | 182 | 174 | 165 | 156 | 148 | 139 | 131 | 122 |
| 6680 | 6700 | 208 | 200 | 191 | 183 | 174 | 166 | 157 | 149 | 140 | 132 | 123 |
| 6700 | 6720 | 209 | 201 | 192 | 184 | 175 | 167 | 158 | 150 | 141 | 133 | 124 |
| 6720 | 6740 | 210 | 202 | 193 | 185 | 176 | 167 | 159 | 150 | 142 | 133 | 125 |
| 6740 | 6760 | 211 | 202 | 194 | 185 | 177 | 168 | 160 | 151 | 143 | 134 | 126 |
| 6760 | 6780 | 212 | 203 | 195 | 186 | 178 | 169 | 161 | 152 | 144 | 135 | 127 |
| 6780 | 6800 | 213 | 204 | 195 | 187 | 178 | 170 | 161 | 153 | 144 | 136 | 127 |
| 6800 | 6820 | 213 | 205 | 196 | 188 | 179 | 171 | 162 | 154 | 145 | 137 | 128 |
| 6820 | 6840 | 214 | 206 | 197 | 189 | 180 | 172 | 163 | 155 | 146 | 137 | 129 |
| 6840 | 6860 | 215 | 206 | 198 | 189 | 181 | 172 | 164 | 155 | 147 | 138 | 130 |
| 6860 | 6880 | 216 | 207 | 199 | 190 | 182 | 173 | 165 | 156 | 148 | 139 | 131 |
| 6880 | 6900 | 217 | 208 | 200 | 191 | 183 | 174 | 165 | 157 | 148 | 140 | 131 |
| 6900 | 6920 | 217 | 209 | 200 | 192 | 183 | 175 | 166 | 158 | 149 | 141 | 132 |
| 6920 | 6940 | 218 | 210 | 201 | 193 | 184 | 176 | 167 | 159 | 150 | 142 | 133 |
| 6940 | 6960 | 219 | 211 | 202 | 194 | 185 | 176 | 168 | 159 | 151 | 142 | 134 |
| 6960 | 6980 | 220 | 211 | 203 | 194 | 186 | 177 | 169 | 160 | 152 | 143 | 135 |
| 6980 | 7000 | 221 | 212 | 204 | 195 | 187 | 178 | 170 | 161 | 153 | 144 | 135 |
| 7000 | 7020 | 222 | 213 | 204 | 196 | 187 | 179 | 170 | 162 | 153 | 145 | 136 |
| 7020 | 7040 | 222 | 214 | 205 | 197 | 188 | 180 | 171 | 163 | 154 | 146 | 137 |
| 7040 | 7060 | 223 | 215 | 206 | 198 | 189 | 181 | 172 | 164 | 155 | 146 | 138 |
| 7060 | 7080 | 224 | 215 | 207 | 198 | 190 | 181 | 173 | 164 | 156 | 147 | 139 |
| 7080 | 7100 | 225 | 216 | 208 | 199 | 191 | 182 | 174 | 165 | 157 | 148 | 140 |
| 7100 | 7120 | 226 | 217 | 209 | 200 | 192 | 183 | 174 | 166 | 157 | 149 | 140 |
| 7120 | 7140 | 226 | 218 | 209 | 201 | 192 | 184 | 175 | 167 | 158 | 150 | 141 |
| 7140 | 7160 | 227 | 219 | 210 | 202 | 193 | 185 | 176 | 168 | 159 | 151 | 142 |
| 7160 | 7180 | 228 | 220 | 211 | 203 | 194 | 185 | 177 | 168 | 160 | 151 | 143 |
| 7180 | 7200 | 229 | 220 | 212 | 203 | 195 | 186 | 178 | 169 | 161 | 152 | 144 |
| 7200 | 7220 | 230 | 221 | 213 | 204 | 196 | 187 | 179 | 170 | 162 | 153 | 144 |
| 7220 | 7240 | 231 | 222 | 213 | 205 | 196 | 188 | 179 | 171 | 162 | 154 | 145 |
| 7240 | 7260 | 231 | 223 | 214 | 206 | 197 | 189 | 180 | 172 | 163 | 155 | 146 |
| 7260 | 7280 | 232 | 224 | 215 | 207 | 198 | 190 | 181 | 173 | 164 | 155 | 147 |
| 7280 | 7300 | 233 | 224 | 216 | 207 | 199 | 190 | 182 | 173 | 165 | 156 | 148 |
| 7300 | 7320 | 234 | 225 | 217 | 208 | 200 | 191 | 183 | 174 | 166 | 157 | 149 |
| 7320 | 7340 | 235 | 226 | 218 | 209 | 201 | 192 | 183 | 175 | 166 | 158 | 149 |
| 7340 | 7360 | 235 | 227 | 218 | 210 | 201 | 193 | 184 | 176 | 167 | 159 | 150 |
| 7360 | 7380 | 236 | 228 | 219 | 211 | 202 | 194 | 185 | 177 | 168 | 160 | 151 |
| 7380 | 7400 | 237 | 229 | 220 | 212 | 203 | 194 | 186 | 177 | 169 | 160 | 152 |
| 7400 | 7420 | 238 | 229 | 221 | 212 | 204 | 195 | 187 | 178 | 170 | 161 | 153 |
| 7420 | 7440 | 239 | 230 | 222 | 213 | 205 | 196 | 188 | 179 | 171 | 162 | 153 |
| 7440 | 7460 | 240 | 231 | 222 | 214 | 205 | 197 | 188 | 180 | 171 | 163 | 154 |
| 7460 | 7480 | 240 | 232 | 223 | 215 | 206 | 198 | 189 | 181 | 172 | 164 | 155 |
| 7480 | 7500 | 241 | 233 | 224 | 216 | 207 | 199 | 190 | 182 | 173 | 164 | 156 |
| 7500 | 7520 | 242 | 233 | 225 | 216 | 208 | 199 | 191 | 182 | 174 | 165 | 157 |
| 7520 | 7540 | 243 | 234 | 226 | 217 | 209 | 200 | 192 | 183 | 175 | 166 | 158 |
| 7540 | 7560 | 244 | 235 | 227 | 218 | 210 | 201 | 192 | 184 | 175 | 167 | 158 |
| 7560 | 7580 | 244 | 236 | 227 | 219 | 210 | 202 | 193 | 185 | 176 | 168 | 159 |
| Pa | ge 55 |
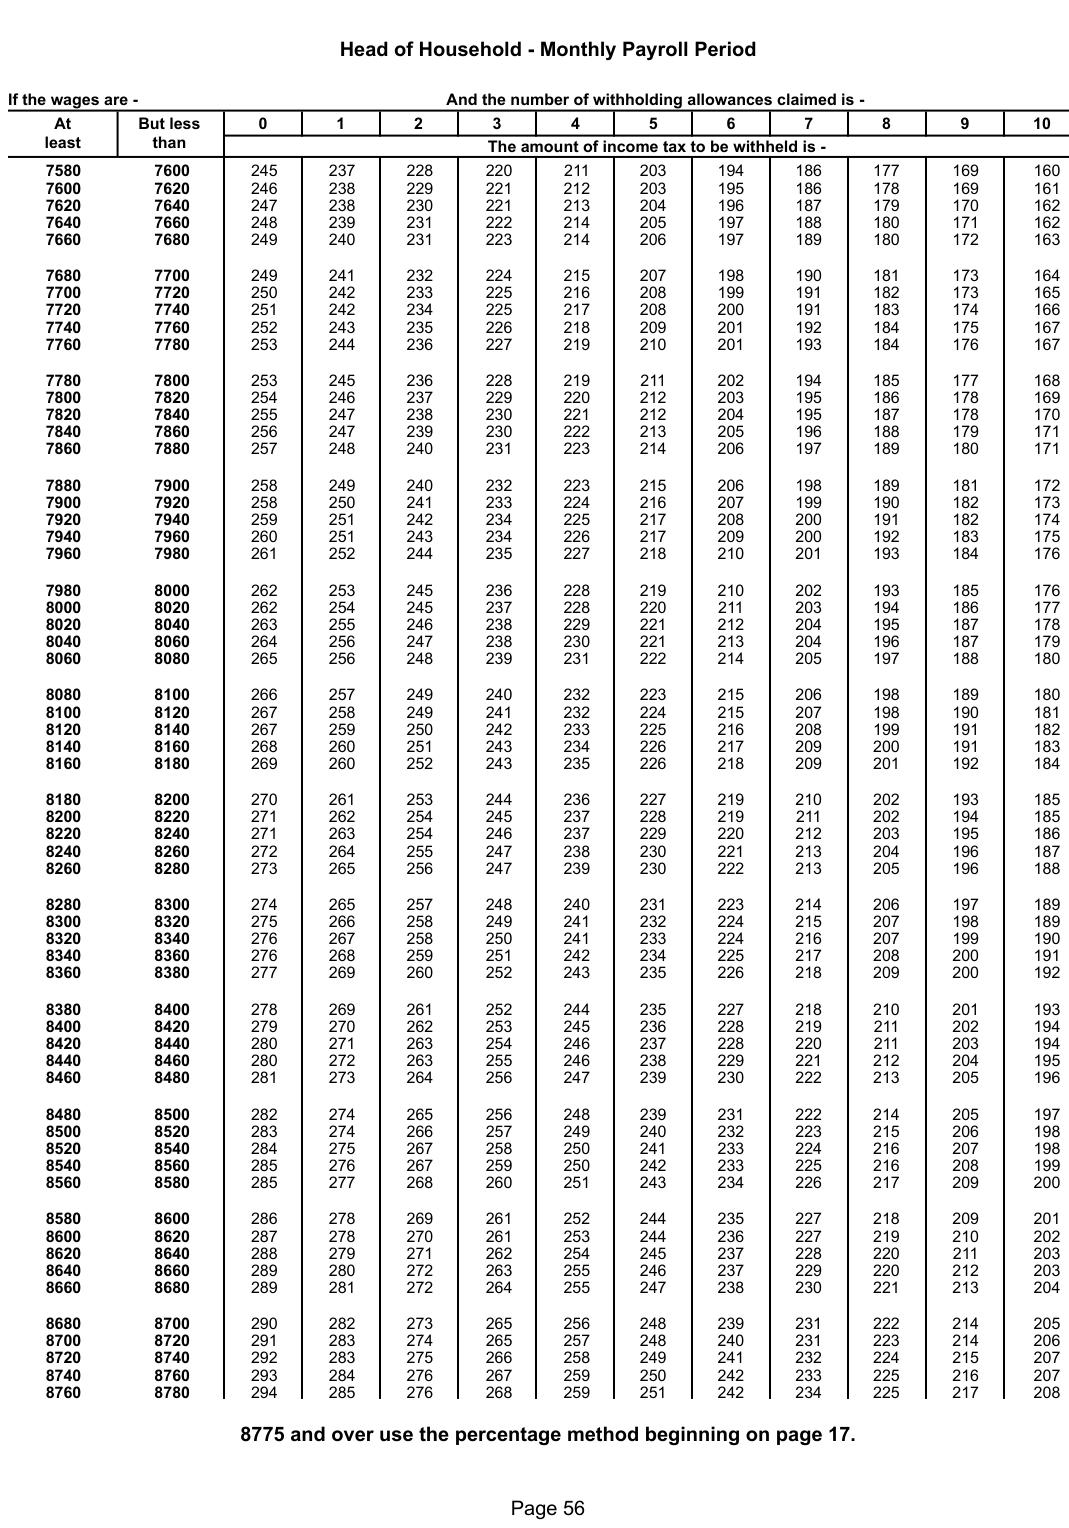
Text version of this table
| Head o | f House | hold - | Monthly P | ayroll | Period | |||||||
| wages are - | And t | he num | ber of withho | lding | allowances | claimed is - | ||||||
| At B | ut less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
| least | than | The am | ount of inco | me tax | to be withh | eld is - | ||||||
| 7580 | 7600 | 245 | 237 | 228 | 220 | 211 | 203 | 194 | 186 | 177 | 169 | 160 |
| 7600 | 7620 | 246 | 238 | 229 | 221 | 212 | 203 | 195 | 186 | 178 | 169 | 161 |
| 7620 | 7640 | 247 | 238 | 230 | 221 | 213 | 204 | 196 | 187 | 179 | 170 | 162 |
| 7640 | 7660 | 248 | 239 | 231 | 222 | 214 | 205 | 197 | 188 | 180 | 171 | 162 |
| 7660 | 7680 | 249 | 240 | 231 | 223 | 214 | 206 | 197 | 189 | 180 | 172 | 163 |
| 7680 | 7700 | 249 | 241 | 232 | 224 | 215 | 207 | 198 | 190 | 181 | 173 | 164 |
| 7700 | 7720 | 250 | 242 | 233 | 225 | 216 | 208 | 199 | 191 | 182 | 173 | 165 |
| 7720 | 7740 | 251 | 242 | 234 | 225 | 217 | 208 | 200 | 191 | 183 | 174 | 166 |
| 7740 | 7760 | 252 | 243 | 235 | 226 | 218 | 209 | 201 | 192 | 184 | 175 | 167 |
| 7760 | 7780 | 253 | 244 | 236 | 227 | 219 | 210 | 201 | 193 | 184 | 176 | 167 |
| 7780 | 7800 | 253 | 245 | 236 | 228 | 219 | 211 | 202 | 194 | 185 | 177 | 168 |
| 7800 | 7820 | 254 | 246 | 237 | 229 | 220 | 212 | 203 | 195 | 186 | 178 | 169 |
| 7820 | 7840 | 255 | 247 | 238 | 230 | 221 | 212 | 204 | 195 | 187 | 178 | 170 |
| 7840 | 7860 | 256 | 247 | 239 | 230 | 222 | 213 | 205 | 196 | 188 | 179 | 171 |
| 7860 | 7880 | 257 | 248 | 240 | 231 | 223 | 214 | 206 | 197 | 189 | 180 | 171 |
| 7880 | 7900 | 258 | 249 | 240 | 232 | 223 | 215 | 206 | 198 | 189 | 181 | 172 |
| 7900 | 7920 | 258 | 250 | 241 | 233 | 224 | 216 | 207 | 199 | 190 | 182 | 173 |
| 7920 | 7940 | 259 | 251 | 242 | 234 | 225 | 217 | 208 | 200 | 191 | 182 | 174 |
| 7940 | 7960 | 260 | 251 | 243 | 234 | 226 | 217 | 209 | 200 | 192 | 183 | 175 |
| 7960 | 7980 | 261 | 252 | 244 | 235 | 227 | 218 | 210 | 201 | 193 | 184 | 176 |
| 7980 | 8000 | 262 | 253 | 245 | 236 | 228 | 219 | 210 | 202 | 193 | 185 | 176 |
| 8000 | 8020 | 262 | 254 | 245 | 237 | 228 | 220 | 211 | 203 | 194 | 186 | 177 |
| 8020 | 8040 | 263 | 255 | 246 | 238 | 229 | 221 | 212 | 204 | 195 | 187 | 178 |
| 8040 | 8060 | 264 | 256 | 247 | 238 | 230 | 221 | 213 | 204 | 196 | 187 | 179 |
| 8060 | 8080 | 265 | 256 | 248 | 239 | 231 | 222 | 214 | 205 | 197 | 188 | 180 |
| 8080 | 8100 | 266 | 257 | 249 | 240 | 232 | 223 | 215 | 206 | 198 | 189 | 180 |
| 8100 | 8120 | 267 | 258 | 249 | 241 | 232 | 224 | 215 | 207 | 198 | 190 | 181 |
| 8120 | 8140 | 267 | 259 | 250 | 242 | 233 | 225 | 216 | 208 | 199 | 191 | 182 |
| 8140 | 8160 | 268 | 260 | 251 | 243 | 234 | 226 | 217 | 209 | 200 | 191 | 183 |
| 8160 | 8180 | 269 | 260 | 252 | 243 | 235 | 226 | 218 | 209 | 201 | 192 | 184 |
| 8180 | 8200 | 270 | 261 | 253 | 244 | 236 | 227 | 219 | 210 | 202 | 193 | 185 |
| 8200 | 8220 | 271 | 262 | 254 | 245 | 237 | 228 | 219 | 211 | 202 | 194 | 185 |
| 8220 | 8240 | 271 | 263 | 254 | 246 | 237 | 229 | 220 | 212 | 203 | 195 | 186 |
| 8240 | 8260 | 272 | 264 | 255 | 247 | 238 | 230 | 221 | 213 | 204 | 196 | 187 |
| 8260 | 8280 | 273 | 265 | 256 | 247 | 239 | 230 | 222 | 213 | 205 | 196 | 188 |
| 8280 | 8300 | 274 | 265 | 257 | 248 | 240 | 231 | 223 | 214 | 206 | 197 | 189 |
| 8300 | 8320 | 275 | 266 | 258 | 249 | 241 | 232 | 224 | 215 | 207 | 198 | 189 |
| 8320 | 8340 | 276 | 267 | 258 | 250 | 241 | 233 | 224 | 216 | 207 | 199 | 190 |
| 8340 | 8360 | 276 | 268 | 259 | 251 | 242 | 234 | 225 | 217 | 208 | 200 | 191 |
| 8360 | 8380 | 277 | 269 | 260 | 252 | 243 | 235 | 226 | 218 | 209 | 200 | 192 |
| 8380 | 8400 | 278 | 269 | 261 | 252 | 244 | 235 | 227 | 218 | 210 | 201 | 193 |
| 8400 | 8420 | 279 | 270 | 262 | 253 | 245 | 236 | 228 | 219 | 211 | 202 | 194 |
| 8420 | 8440 | 280 | 271 | 263 | 254 | 246 | 237 | 228 | 220 | 211 | 203 | 194 |
| 8440 | 8460 | 280 | 272 | 263 | 255 | 246 | 238 | 229 | 221 | 212 | 204 | 195 |
| 8460 | 8480 | 281 | 273 | 264 | 256 | 247 | 239 | 230 | 222 | 213 | 205 | 196 |
| 8480 | 8500 | 282 | 274 | 265 | 256 | 248 | 239 | 231 | 222 | 214 | 205 | 197 |
| 8500 | 8520 | 283 | 274 | 266 | 257 | 249 | 240 | 232 | 223 | 215 | 206 | 198 |
| 8520 | 8540 | 284 | 275 | 267 | 258 | 250 | 241 | 233 | 224 | 216 | 207 | 198 |
| 8540 | 8560 | 285 | 276 | 267 | 259 | 250 | 242 | 233 | 225 | 216 | 208 | 199 |
| 8560 | 8580 | 285 | 277 | 268 | 260 | 251 | 243 | 234 | 226 | 217 | 209 | 200 |
| 8580 | 8600 | 286 | 278 | 269 | 261 | 252 | 244 | 235 | 227 | 218 | 209 | 201 |
| 8600 | 8620 | 287 | 278 | 270 | 261 | 253 | 244 | 236 | 227 | 219 | 210 | 202 |
| 8620 | 8640 | 288 | 279 | 271 | 262 | 254 | 245 | 237 | 228 | 220 | 211 | 203 |
| 8640 | 8660 | 289 | 280 | 272 | 263 | 255 | 246 | 237 | 229 | 220 | 212 | 203 |
| 8660 | 8680 | 289 | 281 | 272 | 264 | 255 | 247 | 238 | 230 | 221 | 213 | 204 |
| 8680 | 8700 | 290 | 282 | 273 | 265 | 256 | 248 | 239 | 231 | 222 | 214 | 205 |
| 8700 | 8720 | 291 | 283 | 274 | 265 | 257 | 248 | 240 | 231 | 223 | 214 | 206 |
| 8720 | 8740 | 292 | 283 | 275 | 266 | 258 | 249 | 241 | 232 | 224 | 215 | 207 |
| 8740 | 8760 | 293 | 284 | 276 | 267 | 259 | 250 | 242 | 233 | 225 | 216 | 207 |
| 8760 | 8780 | 294 | 285 | 276 | 268 | 259 | 251 | 242 | 234 | 225 | 217 | 208 |
| 8775 and | over us | e the per | centa | ge method | begi | nning on | page 17. | |||||
| Pa | ge 56 |
# 1-877-252-3052 (Toll-free)
For more information about withholding tax and to obtain withholding forms, visit ncdor. gov/taxes-forms/withholding-tax. You may also call the Department at 1-877-252-3052 (toll-free).
Taxpayers may receive other important notices about law changes and related tax matters by subscribing to the Department's Tax Updates Email List, which can be located by choosing the "Sign up for E-Alerts" option on the Department's Contact Us page.
# You can file your return and pay your tax online at ncdor.gov/file-pay.
Access the Department's website, ncdor.gov, 24 hours a day, 7 days a week to:
Download withholding forms, instructions, and other publications
Find answers to frequently asked withholding tax questions
Find the latest information regarding the Department of Revenue
Sign up to receive information about State law changes and other related tax matters by e-mail
Source: view the official PDF
The source document contains 1 figure (charts or worksheet graphics) not reproduced in this text version. See the official PDF above.
Nearby sections (13 sections)
- cd-401s · CD-401S — S Corporation Tax Return Instructions
- cd-405 · CD-405 — C Corporation Tax Return Instructions
- cd-405-cw · CD-405 CW — Combined Corporate Income Tax Worksheet…
- d-401 · D-401 — Individual Income Tax Instructions
- d-403a · D-403A — Partnership Tax Return Instructions
- d-407a · D-407A — Estates and Trusts Income Tax Return Instructions
- e-500 · E-500 — Sales and Use Tax Return Instructions
- e-585 · E-585 — Nonprofit / Governmental Entity Claim for Refund of…
- e-595e · E-595E — Streamlined Sales Tax Exemption Certificate
- gen-58 · GEN-58 — NC Power of Attorney Instructions (GEN-58 / GEN-58R)
- nc-30 · NC-30 — Income Tax Withholding Tables & Instructions for…
- nc-478 · NC-478 — Summary of Tax Credits Limited to 50% of Tax…
- nc-nol · NC-NOL — Instructions for Form NC-NOL (Net Operating Loss)