Louisiana Department of Revenue Form Instructions
R-1029 Instructions - Louisiana Sales Tax Return
- Who Should File: All persons and dealers who are subject to the tax levied under Chapter 2 of Subtitle II of Title 47 of the Louisiana Revised Statutes of 1950, as amended, are required to file a tax return monthly or quarterly. Returns are due on or before the 20th day of each month for the preceding calendar month or quarter.
If the due date falls on a weekend or holiday, the return is due the next business day and becomes delinquent the next day thereafter.
# 2. U.S. NAICS Code: Louisiana Department of Revenue
(LDR) is assigning business codes to sales tax accounts based upon the North American Industry Classification System (NAICS). If your Louisiana Revenue tax account currently does not have a NAICS code assigned to it, please include this information on your sales tax return. NAICS codes may be found on your federal corporate income tax return or on your Louisiana Workforce Commission account. NAICS codes may also be found on the U.S.
Census Bureau's webpage at www.census.gov.
# Sales Tax Return - General Instructions
- FEIN Numbers: LDR is now requiring a federal employer identification number for all sales tax accounts.
Please enter this information at the bottom of the return.
- Amended/Final Return: If this is an amended return, place an "X" in the box labeled "Amended Return" at the bottom of the return. If this is a final return, place an "X" in the box labeled "Final Return" at the bottom of the return and enter the date the business was sold or closed in the space provided.
- Dollar Amounts: All amounts on the return should be rounded to the nearest dollar and handprinted in the appropriate boxes.
- Paid Preparer: If your return was prepared by a paid preparer, that person must also sign in the appropriate space, complete the information in the "Paid Preparer Use Only" box, and enter his or her identification number in the space provided under the box. If the paid preparer has a PTIN, the PTIN must be provided; otherwise, the FEIN or LDR account number must be provided. If the paid preparer represents a firm, the firm's FEIN must be entered in the "Paid Preparer Use Only" box. The failure of a paid preparer to sign or provide an identification number will result in the assessment of the unidentified preparer penalty on the preparer. The penalty is $50 for each occurrence of failing to sign or failing to provide an identification number.
- Before Mailing: Care should be exercised to ensure that (a) the correct period is entered or shown in the appropriate area near the upper left-hand corner of the return; (b) the handprinted numerals in the boxes are clear and legible; (c) the return is signed and dated by the appropriate company official; (d) a payment for the exact amount of tax, penalty, and interest accompanies the return and that this payment amount is properly entered on Line 14 of the form; (e) if payment is made electronically, mark the box on Line 14; and (f) the return and payment are placed in the provided preaddressed envelope, stamped, and mailed.
Sales Tax Return - Specific Instructions for Filing Periods January 2025
# Electronic Filing Requirements for Certain Dealers
Aviation Fuel - For tax periods beginning on or after
May 1, 2024, aviation fuel dealers are required to file
Form R-1029, Louisiana Sales Tax Return, electronically.
The state sales tax return for aviation fuel dealers filing electronically will include Form R-1029AF, Schedule AF Aviation Fuel - Sales and Use Tax, requiring the separate reporting of sales and purchases of aviation fuel.
Hotel/Motel Room and Other Accommodations to
Transient Guests - Dealers who collect sales tax on hotel/ motel room rentals are also required to complete a special electronic registration and file their sales tax returns electronically using a different tax return that allows for separate sales tax reporting.
Motor Vehicle Lease and Rentals - Dealers who collect sales tax on motor vehicle leases and rentals are required to complete a special electronic registration and file Form
R-1029E, Louisiana Sales Tax Return, electronically.
# Telecommunication, Cable Television, and Satellite
Service - For tax periods beginning on or after January 1, 2025, dealers providing telecommunications services, cable television services, direct-to-home satellite services, video programming services, and satellite digital audio radio services as described in La. R.S. 47:301.1(F)(2) and La. R.S. 47:301.3(10)(a)(iii) (collectively referred to herein as "dealers") are required to file Form R-1029E,
Louisiana Sales Tax Return, electronically.
For additional information on electronic filing requirements, please visit https://revenue.louisiana.gov/tax-policy. To register and file your sales tax return electronically using the Louisiana Taxpayer Access Point (LaTAP), visit our website at https://revenue.louisiana.gov/.
Line 1 - "Gross sales" is the total sales price for each individual item or article of tangible personal property with no reduction for any purpose. All taxable and exempt sales must be entered on this line, including sales made through a marketplace.
Line 2 - A use tax is due on the purchaser's acquisition price of the tangible personal property used, consumed, distributed, stored for use or consumption in Louisiana.
The total cost or value of the property on which the tax has not been paid to vendors must be entered on this line.
Line 3(a) - Enter the gross receipts billed for the lease or rental of tangible personal property.
Line 3(b) - Beginning January 1, 2025, enter the gross receipts from taxable services defined in La. R.S.
47:301(14) and provided for in La. R.S. 47:301.3. The following services subject to state sales tax should be reported on this line: admissions to places of amusement, athletic, entertainment, and recreational events and dues, fees, or other consideration for the privilege of accessing clubs or amusement, entertainment, athletic, or recreational facilities; storage or parking privileges; printing and related services; laundry, cleaning, pressing, and dyeing services of textiles (includes storage space for clothing, furs, and rugs); furnishing of cold storage space; repairs to tangible personal property; providing of prewritten computer software access services; and providing of information services. Do not enter taxable telecommunication, cable, and satellite services on this line. Dealers selling telecommunication, cable, and satellite services must file Form R-1029E, Louisiana Sales Tax Return, electronically. Sales of prepaid phone cards must be reported on Line 1. Additional information regarding the taxation of these transactions can be found at https://revenue.louisiana.gov/.
Line 3(c) - Beginning January 1, 2025, enter the gross receipts from taxable digital products as defined in
La. R.S. 47:301(31). Digital products are products that are transferred electronically and include digital audiovisual works; digital audio works; digital books; digital codes; digital applications and games; and digital periodicals and discussion forums.
Additional information regarding the taxation of these transactions can be found at https://revenue.louisiana.gov/.
Line 3 - Add Lines 3(a), 3(b), and 3(c).
Line 4 - Add Lines 1, 2, and 3.
Line 5 - (From Line 32-Schedule A) No deduction can be claimed unless the transaction has been included on either Line 1, 2, or 3.
Line 6 - Subtract Line 5 from Line 4.
Line 7- Tax due (Multiply amount on Line 6 by 5%.) Line 8 - In cases where the total amount of Louisiana sales or use taxes collected by use of tax-bracket tables exceeds the amount shown on Line 7, any excess must be remitted to LDR. Do not include local sales tax on this line.
Line 9 - Add Lines 7 and 8.
Line 10 - To compute vendor's compensation, multiply the amount shown on Line 9 by 0.84%.
La. R.S. 47:306(A)(3)(a) allows dealers to deduct and retain 1.05% of the total amount of sales and use tax due for the purpose of compensating the dealer for accurate and timely reporting. La. R.S. 47:306(A)(3)
(a) imposes two restrictions on the State of Louisiana's vendor's compensation. Under one restriction, the sales tax imposed pursuant to La. R.S. 47:321.1 is not eligible for vendor's compensation. The 0.84% rate is the mathematical equivalent of 4 cents out of 5 cents (4/5) of the 1.05% vendor's compensation. The second restriction limits the State of Louisiana's vendor's compensation to $750 per Louisiana dealer per calendar month beginning January 1, 2025. This compensation is allowed only if the return is timely filed and paid. See Revenue Information Bulletin No. 25-006.
Vendor's compensation as provided by La. R.S.
47:306(A)(3)(a) is allowed only when the dealer remits all sales tax as shown due on the return. Partial vendor's compensation for a partial payment of sales tax due is not allowed.
Line 11 - Subtract Line 10 from Line 9.
Line 11(a) - Taxpayers may donate to The Louisiana Military Family Assistance Fund by entering the amount of the donation on Lines 33(a) and 33(b) and entering the total of those donations on Lines 33 and 11(a). Donations can be made by 1) contributing all or any portion of the vendor's compensation listed on Line 10 or 2) paying an amount in addition to the net tax due on Line 11 of this return. The amount entered on Line 11(a) must equal Line 33.
Line 12 - A return becomes delinquent on the day after the due date as discussed in the General Instructions above. If the return is filed late, a delinquent penalty of 5 percent is assessed for each 30 days, or fraction thereof, of delinquency, not to exceed 25 percent of the net tax due on Line 11, and must be entered on Line 12.
NOTE - In addition to the delinquent penalties reported above, a taxpayer may also incur a negligence penalty under La. R.S. 47:1604.1 if circumstances indicate willful negligence or intentional disregard of rules and regulations.
Also, an examination fee may be imposed in the event the
Department is required to issue a billing notice necessitated by the filing or lack of filing of this return.
Line 13 - Refer to the Interest Rate Schedule (R-1111) for daily interest rates that apply. Form R-1111 is available on the Department's website at https://revenue.louisiana.gov/.
Line 14 - Add Lines 11, 11(a), 12, and 13. Make payment to the Louisiana Department of Revenue. You can file and pay your Louisiana Sales Tax at https:// latap.revenue.louisiana.gov/. You can also pay by credit card over the internet or by phone. Visit https://revenue. louisiana.gov/file-pay-online/ or call (833) 458-6521.
NOTE - Do not claim credit on Line 14 for any previous overpayment. A refund will be issued.
# Schedule A Instructions for Lines 15 through 33
Enter the sales amounts for this reporting period in the boxes provided in the total sales column. Multiply these sales amounts by the percent factor appearing in the middle column and enter the result in the Sales Deduction boxes appearing in the right-hand column.
The sales amount must also be included on Line 1, 2, or 3 for allowable deductions claimed on Schedule A.
# Line 15 - Beginning January 1, 2025, report the first
$150,000 of the sales price of farm equipment as provided for in Act 11 of the 2024 Third Extraordinary Session of the Louisiana Legislature. Farm equipment includes rubber tired farm tractors, cane harvesters, cane loaders, cotton pickers, combines, haybaylers, attachments, sprayers, clippers, cultivators, discs, plows, spreaders, irrigation wells, drives, motors, and polyroll tubing. You must qualify as a commercial farmer under La. R.S. 47:301(28)(a), and you must have the approved Form R-1091, Commercial Farmer Certification. Forms R-1091, Commercial Farmer Certification and R-1060, Farm Equipment, must be supplied to the vendor. Farmers must apply for Form R-1091 by completing Form R-1085, Application for Certification as a Commercial Farmer.
# Line 16 - Beginning January 1, 2025, report the sales of materials and services involved in lump sum, unit price, fixed fee, or guaranteed maximum price construction contracts entered into prior to and within
90 days of the fifty-five hundredths of one percent (.55%) additional state sales tax levied under La. R.S.
47.321.1. Form R-1074, Contracts Prior To and Within 90 Days of Tax Levy, must be supplied to the vendor.
Contractors must apply for an exemption certificate by completing Form R-1075, Application to Utilize Revised
Statute 47:305.11 for Contracts Prior To and Within 90
Days of Tax Levy.
Line 17 - Beginning January 1, 2025, sales of insulin without a prescription are subject to 2% state sales tax.
An exemption certificate is not required to claim this exemption. (Prescription drugs are exempt per Article VII, Section 2.2 of the Louisiana Constitution. Report sales of insulin with a prescription on Line 23.) Line 18 - Sales of electricity and natural gas or energy for nonresidential use are subject to 2% state sales tax beginning 7/1/2018.
Line 19 - Steam and bulk or utility water used for other than residential use are subject to 2% state sales tax beginning 7/1/2018.
Line 20 - Sales of boiler fuel when used for nonresidential (business) purposes are subject to 2% state sales tax beginning 7/1/2018. This includes coal, lignite, nuclear fuel, and natural gas used to generate electricity.
Line 21 - Enter sales of agricultural fencing materials to commercial farmers as provided in La. R.S.
47:305.3(B)(3)(b). You must qualify as a commercial farmer under La. R.S. 47:301(28)(a), and you must have the approved Form R-1091, Commercial Farmer Certification. Form R-1091 and R-1007, Farm-Related Products, must be supplied to the vendor. Farmers must apply for Form R-1091 by completing Form R-1085, Application for Certification as a Commercial Farmer.
Line 22 - Enter sales to agencies, branches, or instrumentalities of the U.S. government, State of Louisiana, or any political subdivision of Louisiana. U.S. governmental agencies located in Louisiana must supply documentation of its exempt status to the vendor.
In order for transactions with the State of Louisiana and its political subdivision to be exempted, Form R-1056, Certificate of Sales/Use Tax Exemption/Exclusion of Purchases by a Political Subdivision of the State of Louisiana, or Form R-1356L, Sales Tax Exemption for Purchases by the Federal Government, must be supplied to the vendor.
Line 23 - Enter sales of prescription drugs. All drugs must be prescribed by a physician and used exclusively for the treatment of diseases.
Line 24 - Enter sales of food items for further preparation and consumption in the home. Qualifying items include, but are not limited to, meats, pastries, cookies, candy, flour, spices, coffee, rice, and pasta. Gift packages of food items that include non-food items of tangible personal property are not eligible for the deduction. These items include re-usable baskets and similar containers, serving trays, cups, and souvenirs.
# Line 25 - Enter sales of electricity, natural gas, bulk water, butane, propane, and other residential heating
Instructions for Schedule A-1 fuels to residential customers. Do not include sales to business, commercial, or governmental customers. See Revenue Information Bulletins 02-020A and 04-015 for additional information.
Line 26 - Enter sales of tangible personal property delivered or shipped to customers outside the territorial boundaries of Louisiana by common carrier or seller owned or leased vehicles.
# Line 27 - The gross sales of tangible personal property for resale are exempt from the payment of sales tax provided the purchaser furnishes a valid Form R-1064,
Louisiana Resale Certificate, indicating that the purchaser is entitled to purchase tax-free for resale purposes.
Vendors may verify Louisiana resale certificates on the LDR website at https://revenue.louisiana.gov/businesses/ general-resources/resale-certificate/.
Line 28 - Enter the sale, importation, lease, or rental of manufacturing machinery and equipment by a qualifying manufacturer, as defined by La. R.S.
47:305.5(A) and (B). The first $150,000 of qualifying farm equipment and other farm implements should be reported on Line 15.
Line 29 - Enter sales of tangible personal property sold to lease/rental dealers for lease or rental in arm's length transactions. Lease/rental dealers must claim an exemption using Form R-1344, Purchases of Tangible Personal Property for Rent or Lease, Other than Motor Vehicles Sales Tax Exemption Certificate, and must be registered to collect and remit sales taxes on all rental receipts. Sales to dealers who furnish an operator with the leased/rented property are not eligible for this exemption.
Line 30 - Enter sales of gasoline, diesel, and motor fuels that road use (motor fuel) tax has been paid. Sales of these items for resale must be reported on Line 27.
Line 31 - Enter the amount from Schedule A-1, Line 21.
Line 32 - Add Lines 15 through 31 (Sales Deduction Column). Enter the sum here and on Line 5. No item can be included as a deduction unless the item has been included on Line 1, 2, or 3.
Line 33(a) - Enter the amount of vendor's compensation that is to be donated to The Louisiana Military Family Assistance Fund. Line 33(a) cannot exceed Line 10.
Line 33(b) - Enter any additional payment that is to be donated to The Louisiana Military Family Assistance Fund.
Line 33 Total - The total of Lines 33(a) and 33(b) must be entered on Line 11(a) on the front of the return.
NOTE: Sales codes are the same for the exemption in prior periods, BUT the rate may have changed.
- Enter your LDR Account number.
- Enter the sales, purchases for use, leases, rentals, or sales of services description, identifying code, and the total dollar amount of transactions for the period in the appropriate spaces.
Schedule Number State Sales Tax Rate
# Schedule A-1 Schedule Name
Transactions subject to 0% tax 0%
- Use one line for each different code or type of transaction for the reporting period.
- In order to be exempted, the transaction must be included on Line 1, 2, or 3 of the Louisiana General Sales Tax return.
- Enter the total of the schedule on the TOTAL line of the schedule and on line on Schedule A (Line 31) of the Louisiana General Sales Tax Return.
Visit our website at https://revenue. Louisiana Department of Revenue louisiana.gov/ for tax, registration, P.O. Box 3138 and filing information. For additional Baton Rouge, LA 70821-3138 assistance, call, visit or write: (855) 307-3893 You can also pay your Louisiana Sales Tax by credit card over the internet or by phone. Visit https://revenue.louisiana.gov/file-pay-online/ or call (833) 458-6521.
File online at
https://revenue.louisiana.gov/file-pay-online/.
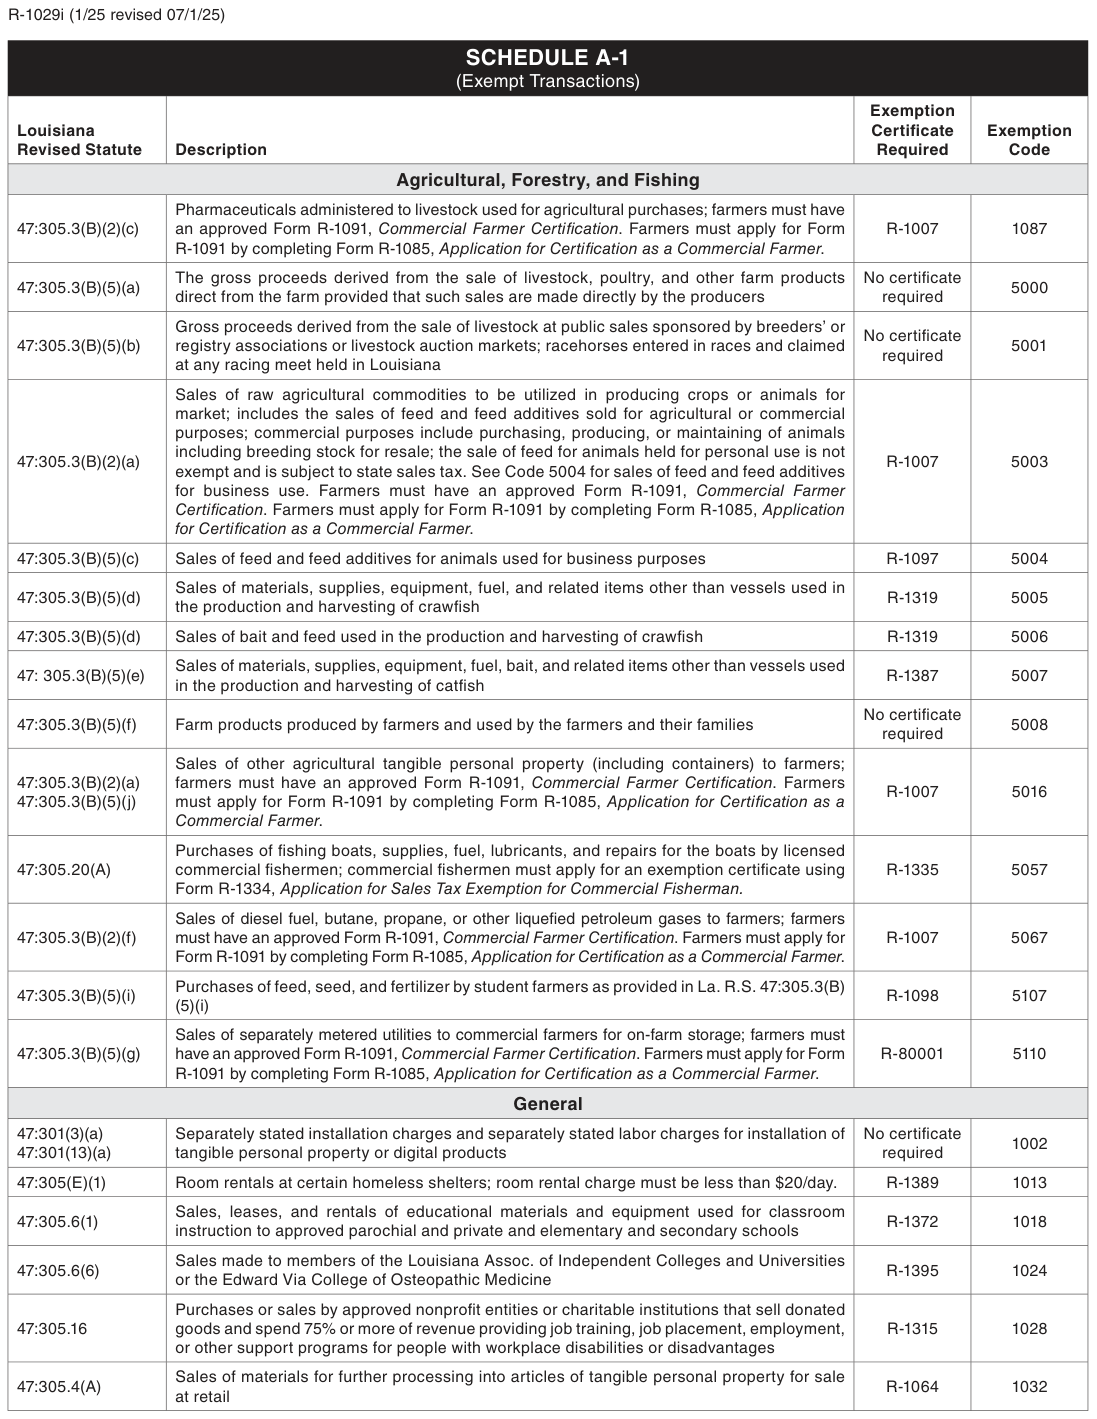
Text version of this table
| SCHEDULE A-1 (Exempt Transactions) | |||
| Louisiana Revised Statute | Description | Exemption Certificate Required | Exemption Code |
| Agricultural, Forestry, and Fishing | |||
| 47:305.3(B)(2)(c) | Pharmaceuticals administered to livestock used for agricultural purchases; farmers must have an approved Form R-1091, Commercial Farmer Certification. Farmers must apply for Form R-1091 by completing Form R-1085, Application for Certification as a Commercial Farmer. | R-1007 | 1087 |
| 47:305.3(B)(5)(a) | The gross proceeds derived from the sale of livestock, poultry, and other farm products direct from the farm provided that such sales are made directly by the producers | No certificate required | 5000 |
| 47:305.3(B)(5)(b) | Gross proceeds derived from the sale of livestock at public sales sponsored by breeders’ or registry associations or livestock auction markets; racehorses entered in races and claimed at any racing meet held in Louisiana | No certificate required | 5001 |
| 47:305.3(B)(2)(a) | Sales of raw agricultural commodities to be utilized in producing crops or animals for market; includes the sales of feed and feed additives sold for agricultural or commercial purposes; commercial purposes include purchasing, producing, or maintaining of animals including breeding stock for resale; the sale of feed for animals held for personal use is not exempt and is subject to state sales tax. See Code 5004 for sales of feed and feed additives for business use. Farmers must have an approved Form R-1091, Commercial Farmer Certification. Farmers must apply for Form R-1091 by completing Form R-1085, Application for Certification as a Commercial Farmer. | R-1007 | 5003 |
| 47:305.3(B)(5)(c) | Sales of feed and feed additives for animals used for business purposes | R-1097 | 5004 |
| 47:305.3(B)(5)(d) | Sales of materials, supplies, equipment, fuel, and related items other than vessels used in the production and harvesting of crawfish | R-1319 | 5005 |
| 47:305.3(B)(5)(d) | Sales of bait and feed used in the production and harvesting of crawfish | R-1319 | 5006 |
| 47: 305.3(B)(5)(e) | Sales of materials, supplies, equipment, fuel, bait, and related items other than vessels used in the production and harvesting of catfish | R-1387 | 5007 |
| 47:305.3(B)(5)(f) | Farm products produced by farmers and used by the farmers and their families | No certificate required | 5008 |
| 47:305.3(B)(2)(a) 47:305.3(B)(5)(j) | Sales of other agricultural tangible personal property (including containers) to farmers; farmers must have an approved Form R-1091, Commercial Farmer Certification. Farmers must apply for Form R-1091 by completing Form R-1085, Application for Certification as a Commercial Farmer. | R-1007 | 5016 |
| 47:305.20(A) | Purchases of fishing boats, supplies, fuel, lubricants, and repairs for the boats by licensed commercial fishermen; commercial fishermen must apply for an exemption certificate using Form R-1334, Application for Sales Tax Exemption for Commercial Fisherman. | R-1335 | 5057 |
| 47:305.3(B)(2)(f) | Sales of diesel fuel, butane, propane, or other liquefied petroleum gases to farmers; farmers must have an approved Form R-1091, Commercial Farmer Certification. Farmers must apply for Form R-1091 by completing Form R-1085, Application for Certification as a Commercial Farmer. | R-1007 | 5067 |
| 47:305.3(B)(5)(i) | Purchases of feed, seed, and fertilizer by student farmers as provided in La. R.S. 47:305.3(B) (5)(i) | R-1098 | 5107 |
| 47:305.3(B)(5)(g) | Sales of separately metered utilities to commercial farmers for on-farm storage; farmers must have an approved Form R-1091, Commercial Farmer Certification. Farmers must apply for Form R-1091 by completing Form R-1085, Application for Certification as a Commercial Farmer. | R-80001 | 5110 |
| General | |||
| 47:301(3)(a) 47:301(13)(a) | Separately stated installation charges and separately stated labor charges for installation of tangible personal property or digital products | No certificate required | 1002 |
| 47:305(E)(1) | Room rentals at certain homeless shelters; room rental charge must be less than $20/day. | R-1389 | 1013 |
| 47:305.6(1) | Sales, leases, and rentals of educational materials and equipment used for classroom instruction to approved parochial and private and elementary and secondary schools | R-1372 | 1018 |
| 47:305.6(6) | Sales made to members of the Louisiana Assoc. of Independent Colleges and Universities or the Edward Via College of Osteopathic Medicine | R-1395 | 1024 |
| 47:305.16 | Purchases or sales by approved nonprofit entities or charitable institutions that sell donated goods and spend 75% or more of revenue providing job training, job placement, employment, or other support programs for people with workplace disabilities or disadvantages | R-1315 | 1028 |
| 47:305.4(A) | Sales of materials for further processing into articles of tangible personal property for sale at retail | R-1064 | 1032 |
# Agricultural, Forestry, and Fishing
# R-1007 1087
# R-1007 5003
# R-1319 5005
# R-1387 5007
# R-1335 5057
# R-1098 5107
# R-1395 1024
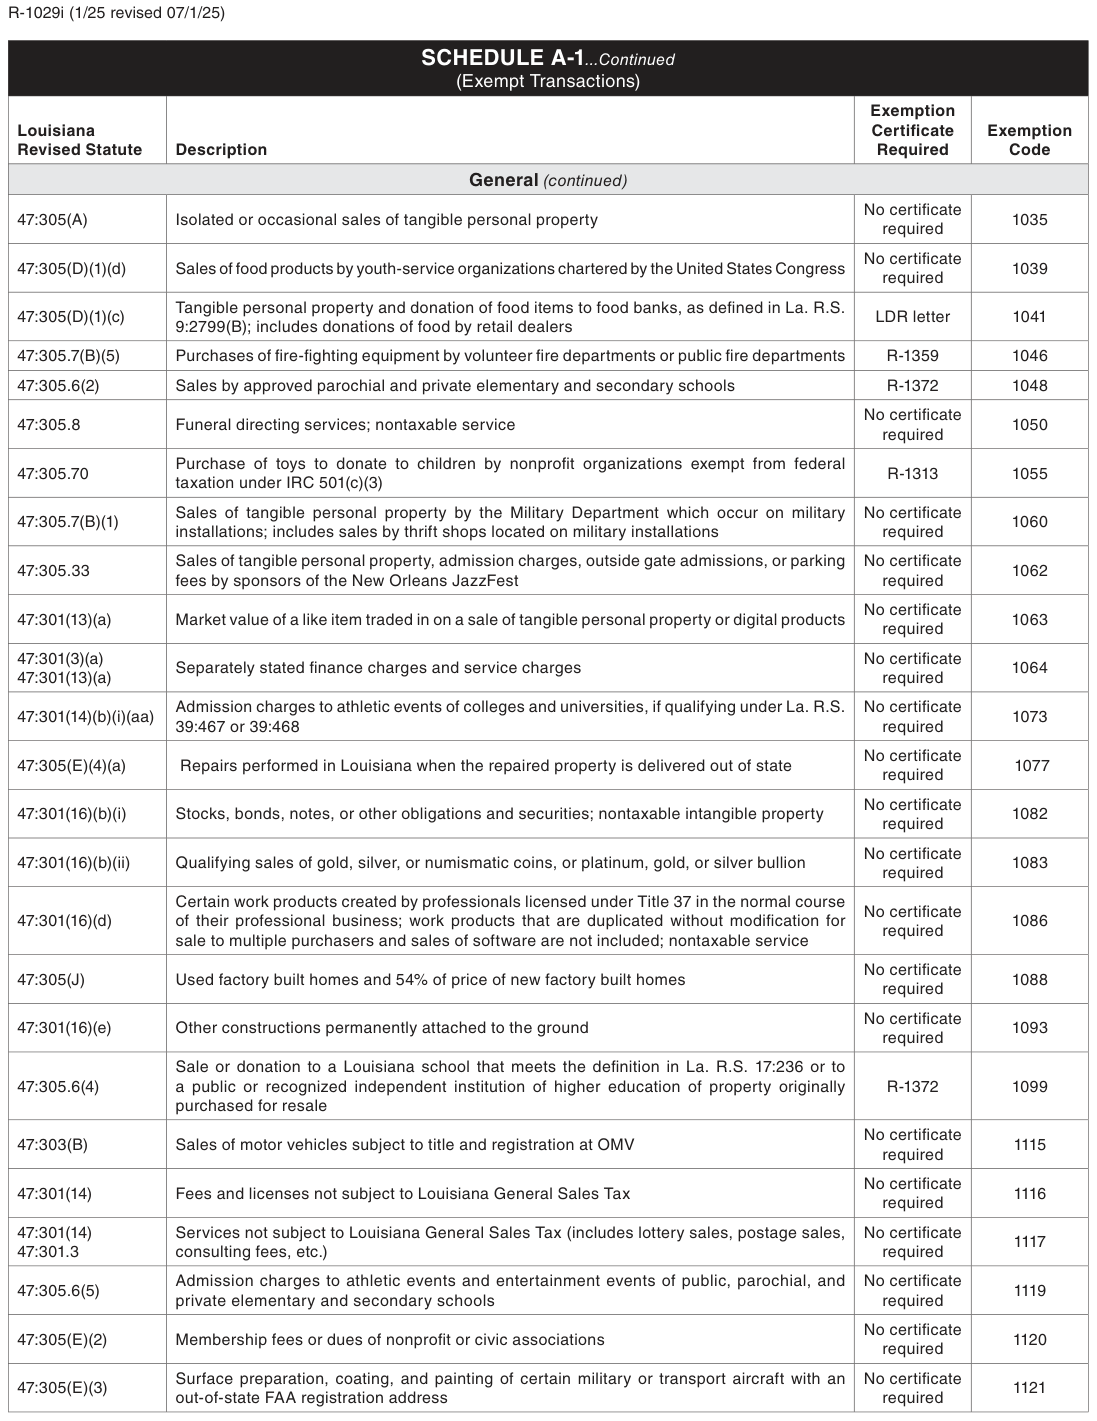
Text version of this table
| SCHEDULE A-1...Continued (Exempt Transactions) | |||
| Louisiana Revised Statute | Description | Exemption Certificate Required | Exemption Code |
| General (continued) | |||
| 47:305(A) | Isolated or occasional sales of tangible personal property | No certificate required | 1035 |
| 47:305(D)(1)(d) | Sales of food products by youth-service organizations chartered by the United States Congress | No certificate required | 1039 |
| 47:305(D)(1)(c) | Tangible personal property and donation of food items to food banks, as defined in La. R.S. 9:2799(B); includes donations of food by retail dealers | LDR letter | 1041 |
| 47:305.7(B)(5) | Purchases of fire-fighting equipment by volunteer fire departments or public fire departments | R-1359 | 1046 |
| 47:305.6(2) | Sales by approved parochial and private elementary and secondary schools | R-1372 | 1048 |
| 47:305.8 | Funeral directing services; nontaxable service | No certificate required | 1050 |
| 47:305.70 | Purchase of toys to donate to children by nonprofit organizations exempt from federal taxation under IRC 501(c)(3) | R-1313 | 1055 |
| 47:305.7(B)(1) | Sales of tangible personal property by the Military Department which occur on military installations; includes sales by thrift shops located on military installations | No certificate required | 1060 |
| 47:305.33 | Sales of tangible personal property, admission charges, outside gate admissions, or parking fees by sponsors of the New Orleans JazzFest | No certificate required | 1062 |
| 47:301(13)(a) | Market value of a like item traded in on a sale of tangible personal property or digital products | No certificate required | 1063 |
| 47:301(3)(a) 47:301(13)(a) | Separately stated finance charges and service charges | No certificate required | 1064 |
| 47:301(14)(b)(i)(aa) | Admission charges to athletic events of colleges and universities, if qualifying under La. R.S. 39:467 or 39:468 | No certificate required | 1073 |
| 47:305(E)(4)(a) | Repairs performed in Louisiana when the repaired property is delivered out of state | No certificate required | 1077 |
| 47:301(16)(b)(i) | Stocks, bonds, notes, or other obligations and securities; nontaxable intangible property | No certificate required | 1082 |
| 47:301(16)(b)(ii) | Qualifying sales of gold, silver, or numismatic coins, or platinum, gold, or silver bullion | No certificate required | 1083 |
| 47:301(16)(d) | Certain work products created by professionals licensed under Title 37 in the normal course of their professional business; work products that are duplicated without modification for sale to multiple purchasers and sales of software are not included; nontaxable service | No certificate required | 1086 |
| 47:305(J) | Used factory built homes and 54% of price of new factory built homes | No certificate required | 1088 |
| 47:301(16)(e) | Other constructions permanently attached to the ground | No certificate required | 1093 |
| 47:305.6(4) | Sale or donation to a Louisiana school that meets the definition in La. R.S. 17:236 or to a public or recognized independent institution of higher education of property originally purchased for resale | R-1372 | 1099 |
| 47:303(B) | Sales of motor vehicles subject to title and registration at OMV | No certificate required | 1115 |
| 47:301(14) | Fees and licenses not subject to Louisiana General Sales Tax | No certificate required | 1116 |
| 47:301(14) 47:301.3 | Services not subject to Louisiana General Sales Tax (includes lottery sales, postage sales, consulting fees, etc.) | No certificate required | 1117 |
| 47:305.6(5) | Admission charges to athletic events and entertainment events of public, parochial, and private elementary and secondary schools | No certificate required | 1119 |
| 47:305(E)(2) | Membership fees or dues of nonprofit or civic associations | No certificate required | 1120 |
| 47:305(E)(3) | Surface preparation, coating, and painting of certain military or transport aircraft with an out-of-state FAA registration address | No certificate required | 1121 |
# Required Code
# R-1313 1055
# R-1372 1099
# Required Code
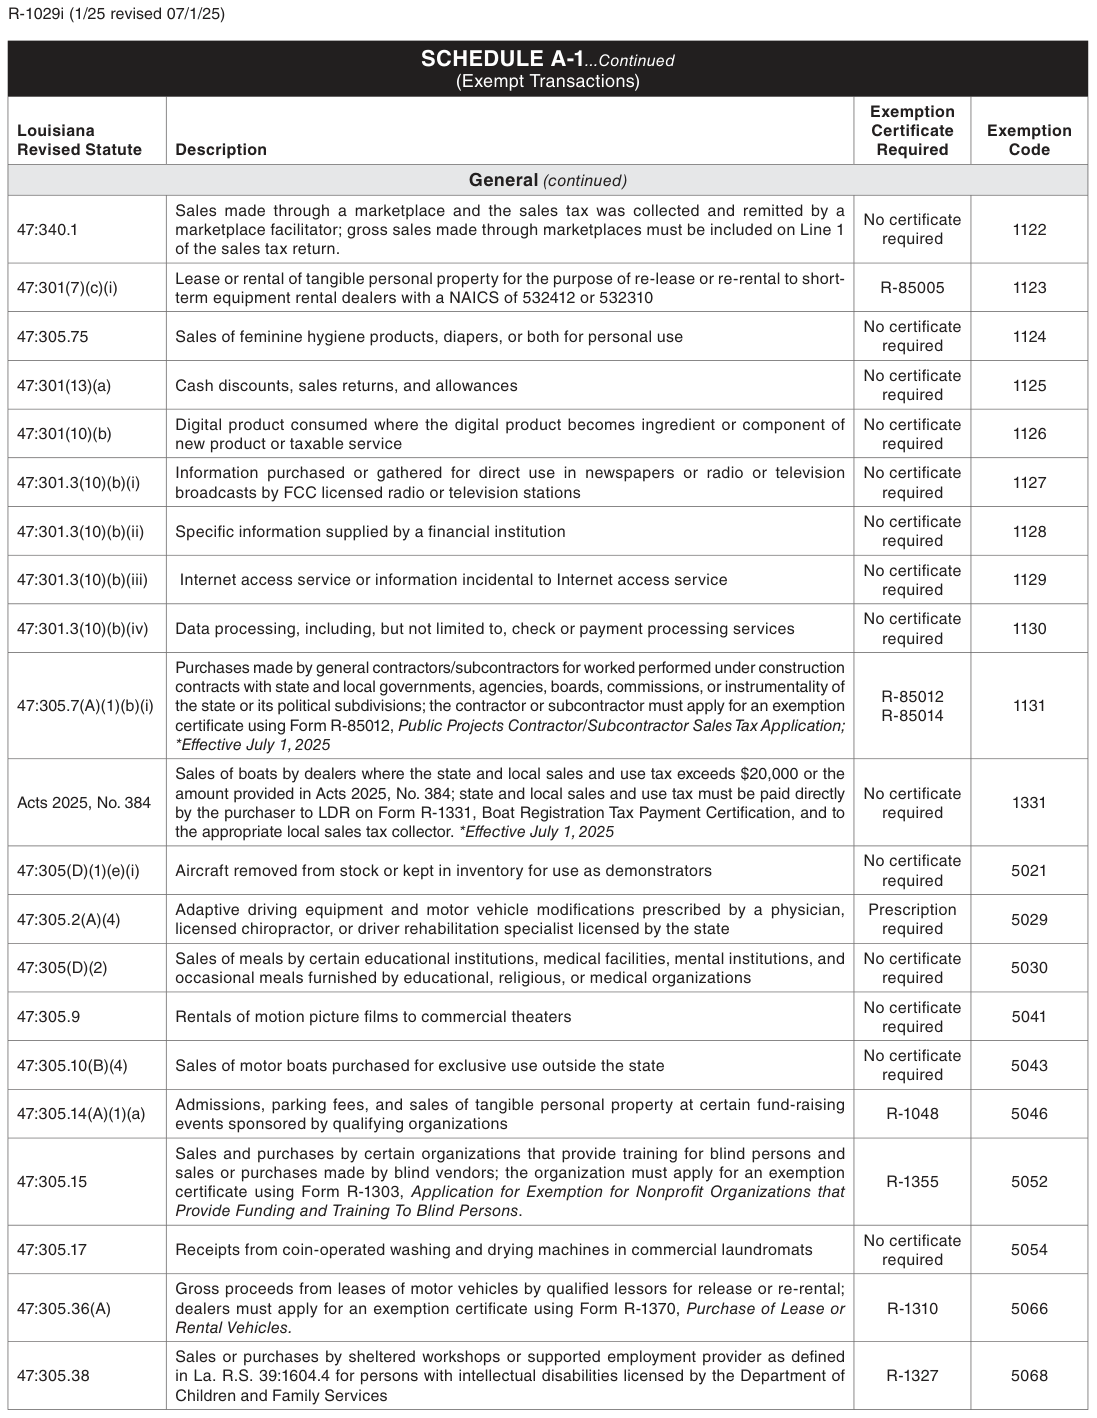
Text version of this table
| SCHEDULE A-1...Continued (Exempt Transactions) | |||
| Louisiana Revised Statute | Description | Exemption Certificate Required | Exemption Code |
| General (continued) | |||
| 47:340.1 | Sales made through a marketplace and the sales tax was collected and remitted by a marketplace facilitator; gross sales made through marketplaces must be included on Line 1 of the sales tax return. | No certificate required | 1122 |
| 47:301(7)(c)(i) | Lease or rental of tangible personal property for the purpose of re-lease or re-rental to short- term equipment rental dealers with a NAICS of 532412 or 532310 | R-85005 | 1123 |
| 47:305.75 | Sales of feminine hygiene products, diapers, or both for personal use | No certificate required | 1124 |
| 47:301(13)(a) | Cash discounts, sales returns, and allowances | No certificate required | 1125 |
| 47:301(10)(b) | Digital product consumed where the digital product becomes ingredient or component of new product or taxable service | No certificate required | 1126 |
| 47:301.3(10)(b)(i) | Information purchased or gathered for direct use in newspapers or radio or television broadcasts by FCC licensed radio or television stations | No certificate required | 1127 |
| 47:301.3(10)(b)(ii) | Specific information supplied by a financial institution | No certificate required | 1128 |
| 47:301.3(10)(b)(iii) | Internet access service or information incidental to Internet access service | No certificate required | 1129 |
| 47:301.3(10)(b)(iv) | Data processing, including, but not limited to, check or payment processing services | No certificate required | 1130 |
| 47:305.7(A)(1)(b)(i) | Purchases made by general contractors/subcontractors for worked performed under construction contracts with state and local governments, agencies, boards, commissions, or instrumentality of the state or its political subdivisions; the contractor or subcontractor must apply for an exemption certificate using Form R-85012, Public Projects Contractor/Subcontractor Sales Tax Application; *Effective July 1, 2025 | R-85012 R-85014 | 1131 |
| Acts 2025, No. 384 | Sales of boats by dealers where the state and local sales and use tax exceeds $20,000 or the amount provided in Acts 2025, No. 384; state and local sales and use tax must be paid directly by the purchaser to LDR on Form R-1331, Boat Registration Tax Payment Certification, and to the appropriate local sales tax collector. *Effective July 1, 2025 | No certificate required | 1331 |
| 47:305(D)(1)(e)(i) | Aircraft removed from stock or kept in inventory for use as demonstrators | No certificate required | 5021 |
| 47:305.2(A)(4) | Adaptive driving equipment and motor vehicle modifications prescribed by a physician, licensed chiropractor, or driver rehabilitation specialist licensed by the state | Prescription required | 5029 |
| 47:305(D)(2) | Sales of meals by certain educational institutions, medical facilities, mental institutions, and occasional meals furnished by educational, religious, or medical organizations | No certificate required | 5030 |
| 47:305.9 | Rentals of motion picture films to commercial theaters | No certificate required | 5041 |
| 47:305.10(B)(4) | Sales of motor boats purchased for exclusive use outside the state | No certificate required | 5043 |
| 47:305.14(A)(1)(a) | Admissions, parking fees, and sales of tangible personal property at certain fund-raising events sponsored by qualifying organizations | R-1048 | 5046 |
| 47:305.15 | Sales and purchases by certain organizations that provide training for blind persons and sales or purchases made by blind vendors; the organization must apply for an exemption certificate using Form R-1303, Application for Exemption for Nonprofit Organizations that Provide Funding and Training To Blind Persons. | R-1355 | 5052 |
| 47:305.17 | Receipts from coin-operated washing and drying machines in commercial laundromats | No certificate required | 5054 |
| 47:305.36(A) | Gross proceeds from leases of motor vehicles by qualified lessors for release or re-rental; dealers must apply for an exemption certificate using Form R-1370, Purchase of Lease or Rental Vehicles. | R-1310 | 5066 |
| 47:305.38 | Sales or purchases by sheltered workshops or supported employment provider as defined in La. R.S. 39:1604.4 for persons with intellectual disabilities licensed by the Department of Children and Family Services | R-1327 | 5068 |
# R-1048 5046
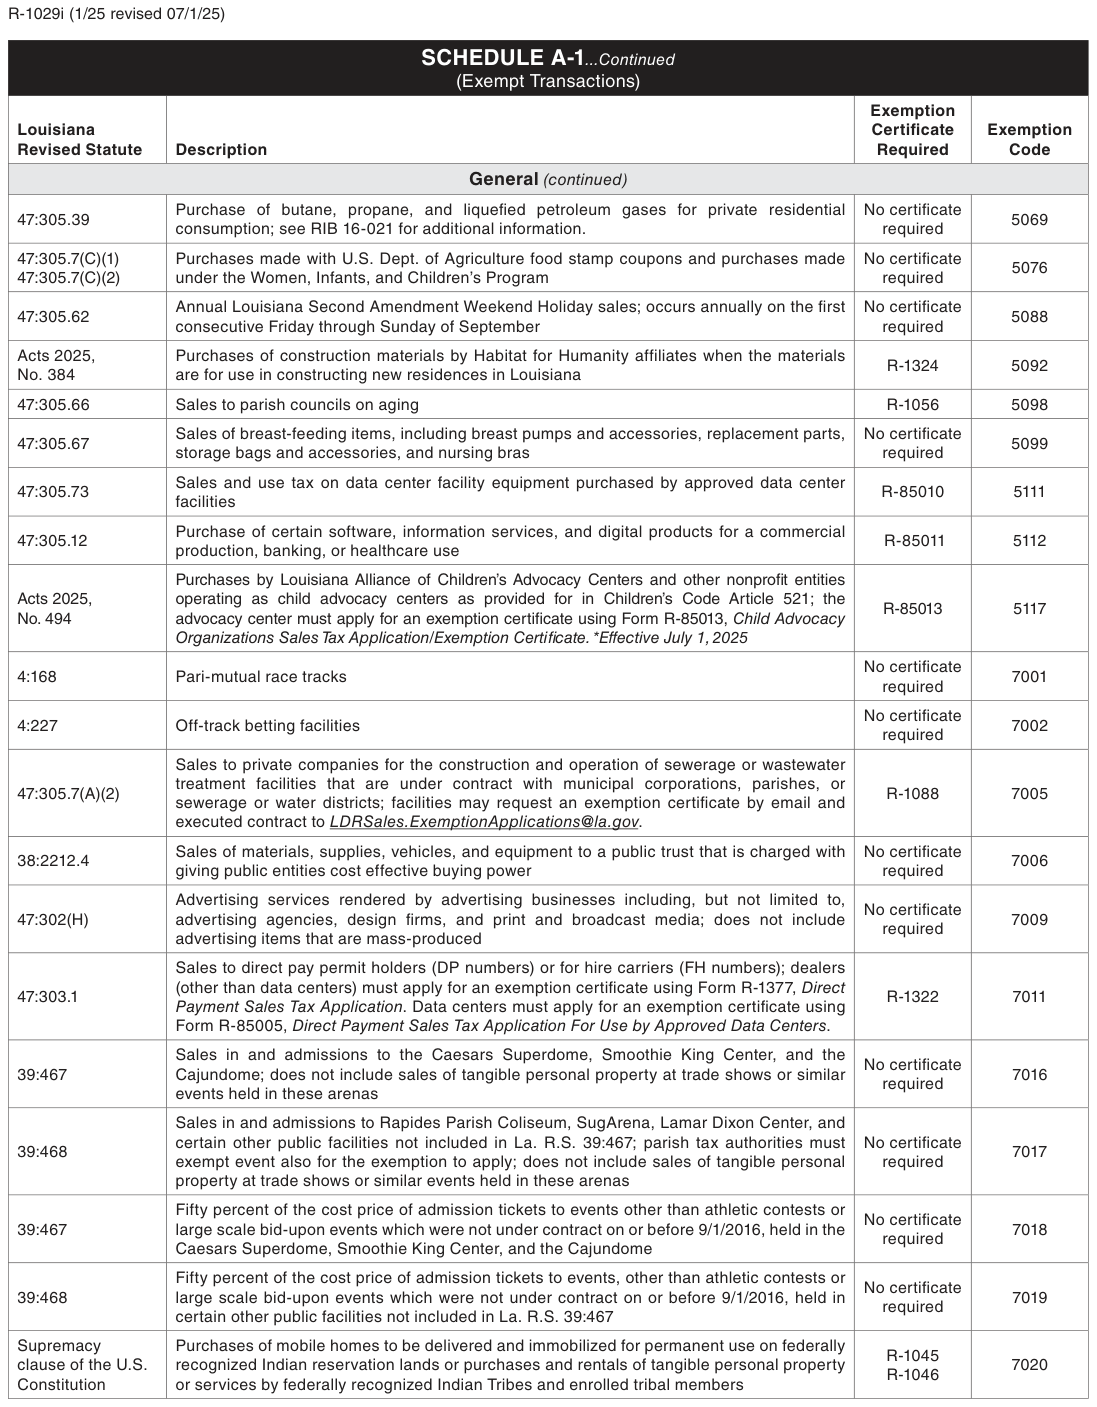
Text version of this table
| SCHEDULE A-1...Continued (Exempt Transactions) | |||
| Louisiana Revised Statute | Description | Exemption Certificate Required | Exemption Code |
| General (continued) | |||
| 47:305.39 | Purchase of butane, propane, and liquefied petroleum gases for private residential consumption; see RIB 16-021 for additional information. | No certificate required | 5069 |
| 47:305.7(C)(1) 47:305.7(C)(2) | Purchases made with U.S. Dept. of Agriculture food stamp coupons and purchases made under the Women, Infants, and Children’s Program | No certificate required | 5076 |
| 47:305.62 | Annual Louisiana Second Amendment Weekend Holiday sales; occurs annually on the first consecutive Friday through Sunday of September | No certificate required | 5088 |
| Acts 2025, No. 384 | Purchases of construction materials by Habitat for Humanity affiliates when the materials are for use in constructing new residences in Louisiana | R-1324 | 5092 |
| 47:305.66 | Sales to parish councils on aging | R-1056 | 5098 |
| 47:305.67 | Sales of breast-feeding items, including breast pumps and accessories, replacement parts, storage bags and accessories, and nursing bras | No certificate required | 5099 |
| 47:305.73 | Sales and use tax on data center facility equipment purchased by approved data center facilities | R-85010 | 5111 |
| 47:305.12 | Purchase of certain software, information services, and digital products for a commercial production, banking, or healthcare use | R-85011 | 5112 |
| Acts 2025, No. 494 | Purchases by Louisiana Alliance of Children’s Advocacy Centers and other nonprofti entities operating as child advocacy centers as provided for in Children’s Code Article 521; the advocacy center must apply for an exemption certificate using Form R-85013, Child Advocacy Organizations Sales Tax Application/Exemption Certificate. *Effective July 1, 2025 | R-85013 | 5117 |
| 4:168 | Pari-mutual race tracks | No certificate required | 7001 |
| 4:227 | Off-track betting facilities | No certificate required | 7002 |
| 47:305.7(A)(2) | Sales to private companies for the construction and operation of sewerage or wastewater treatment facilities that are under contract with municipal corporations, parishes, or sewerage or water districts; facilities may request an exemption certificate by email and executed contract to LDRSales.ExemptionApplications@la.gov. | R-1088 | 7005 |
| 38:2212.4 | Sales of materials, supplies, vehicles, and equipment to a public trust that is charged with giving public entities cost effective buying power | No certificate required | 7006 |
| 47:302(H) | Advertising services rendered by advertising businesses including, but not limited to, advertising agencies, design firms, and print and broadcast media; does not include advertising items that are mass-produced | No certificate required | 7009 |
| 47:303.1 | Sales to direct pay permit holders (DP numbers) or for hire carriers (FH numbers); dealers (other than data centers) must apply for an exemption certificate using Form R-1377, Direct Payment Sales Tax Application. Data centers must apply for an exemption certificate using Form R-85005, Direct Payment Sales Tax Application For Use by Approved Data Centers. | R-1322 | 7011 |
| 39:467 | Sales in and admissions to the Caesars Superdome, Smoothie King Center, and the Cajundome; does not include sales of tangible personal property at trade shows or similar events held in these arenas | No certificate required | 7016 |
| 39:468 | Sales in and admissions to Rapides Parish Coliseum, SugArena, Lamar Dixon Center, and certain other public facilities not included in La. R.S. 39:467; parish tax authorities must exempt event also for the exemption to apply; does not include sales of tangible personal property at trade shows or similar events held in these arenas | No certificate required | 7017 |
| 39:467 | Fifty percent of the cost price of admission tickets to events other than athletic contests or large scale bid-upon events which were not under contract on or before 9/1/2016, held in the Caesars Superdome, Smoothie King Center, and the Cajundome | No certificate required | 7018 |
| 39:468 | Fifty percent of the cost price of admission tickets to events, other than athletic contests or large scale bid-upon events which were not under contract on or before 9/1/2016, held in certain other public facilities not included in La. R.S. 39:467 | No certificate required | 7019 |
| Supremacy clause of the U.S. Constitution | Purchases of mobile homes to be delivered and immobilized for permanent use on federally recognized Indian reservation lands or purchases and rentals of tangible personal property or services by federally recognized Indian Tribes and enrolled tribal members | R-1045 R-1046 | 7020 |
# 47:305.7(C)(1)
# R-1056 5098
Sales of breast-feeding items, including breast pumps and accessories, replacement parts, 47:305.67 storage bags and accessories, and nursing bras Sales and use tax on data center facility equipment purchased by approved data center 47:305.73 facilities R-85010 5111 Purchase of certain software, information services, and digital products for a commercial 47:305.12 production, banking, or healthcare use R-85011 5112 Purchases by Louisiana Alliance of Children's Advocacy Centers and other nonprofit entities operating as child advocacy centers as provided for in Children's Code Article 521; the Acts 2025, R-85013 5117 advocacy center must apply for an exemption certificate using Form R-85013, Child Advocacy
No. 494
Organizations Sales Tax Application/Exemption Certificate. *Effective July 1, 2025
4:168 Pari-mutual race tracks
4:227 Off-track betting facilities
Sales to private companies for the construction and operation of sewerage or wastewater treatment facilities that are under contract with municipal corporations, parishes, or 47:305.7(A)(2) R-1088 7005 sewerage or water districts; facilities may request an exemption certificate by email and executed contract to LDRSales. ExemptionApplications@la.gov.
Sales of materials, supplies, vehicles, and equipment to a public trust that is charged with 38:2212.4 giving public entities cost effective buying power Advertising services rendered by advertising businesses including, but not limited to, advertising agencies, design firms, and print and broadcast media; does not include 47:302(H) advertising items that are mass-produced Sales to direct pay permit holders (DP numbers) or for hire carriers (FH numbers); dealers (other than data centers) must apply for an exemption certificate using Form R-1377, Direct
# 47:303.1 R-1322 7011
# Caesars Superdome, Smoothie King Center, and the Cajundome
# 47:305.5(C)
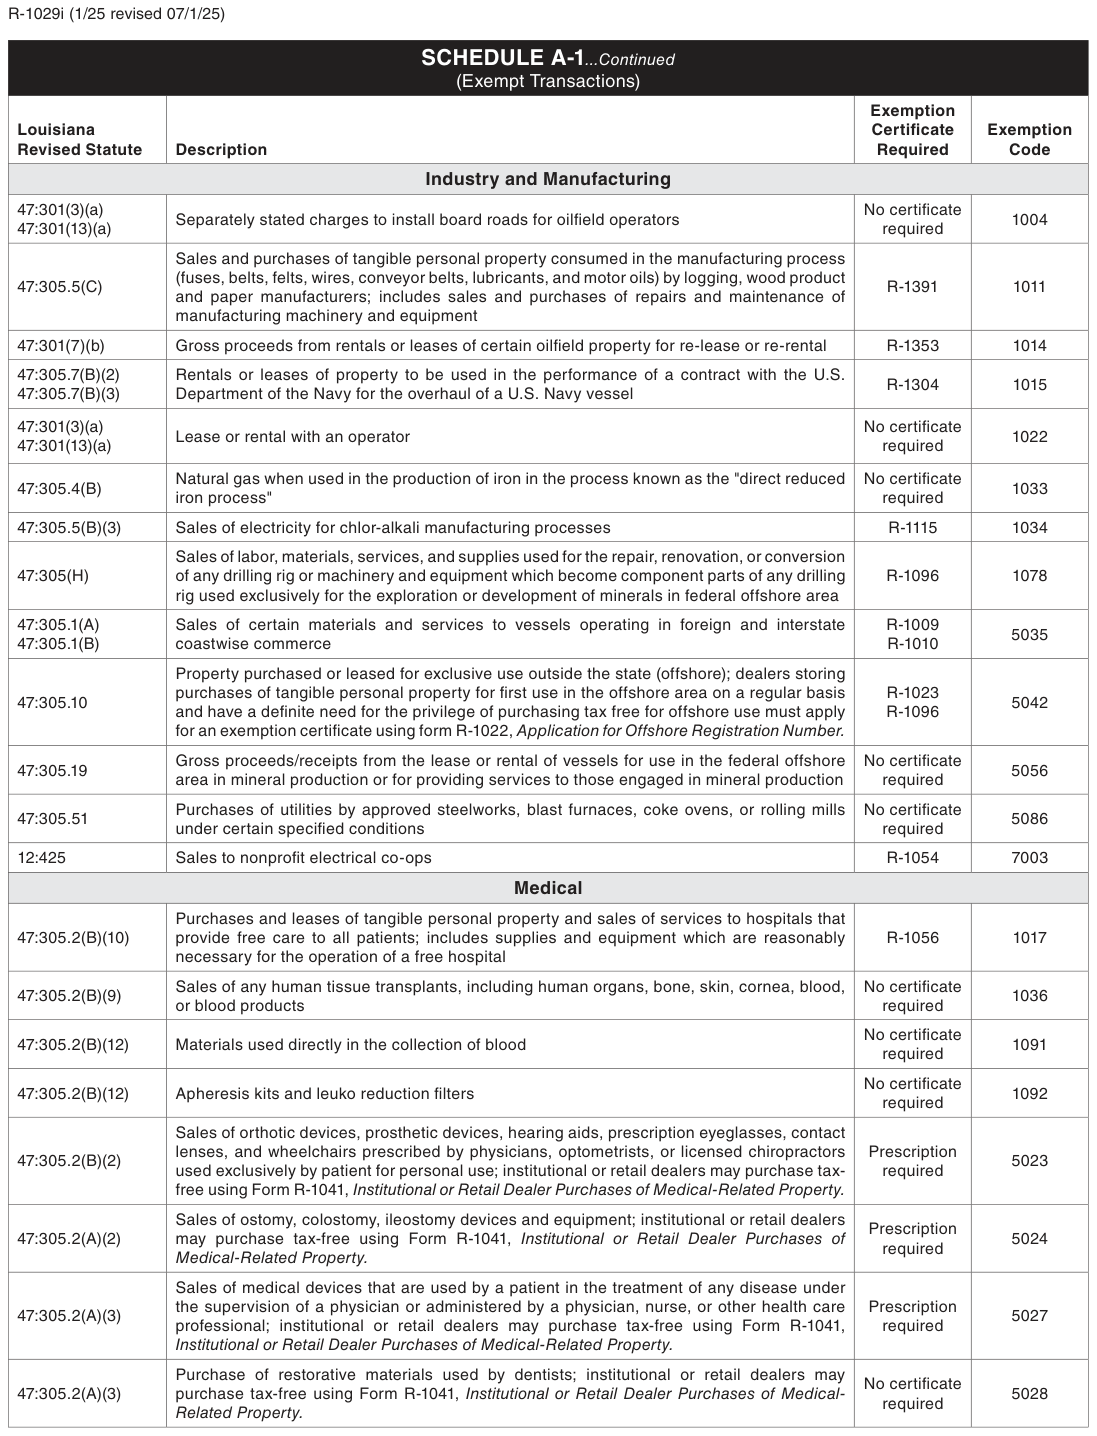
Text version of this table
| SCHEDULE A-1...Continued (Exempt Transactions) | |||
| Louisiana Revised Statute | Description | Exemption Certificate Required | Exemption Code |
| Industry and Manufacturing | |||
| 47:301(3)(a) 47:301(13)(a) | Separately stated charges to install board roads for oilfield operators | No certificate required | 1004 |
| 47:305.5(C) | Sales and purchases of tangible personal property consumed in the manufacturing process (fuses, belts, felts, wires, conveyor belts, lubricants, and motor oils) by logging, wood product and paper manufacturers; includes sales and purchases of repairs and maintenance of manufacturing machinery and equipment | R-1391 | 1011 |
| 47:301(7)(b) | Gross proceeds from rentals or leases of certain oilfield property for re-lease or re-rental | R-1353 | 1014 |
| 47:305.7(B)(2) 47:305.7(B)(3) | Rentals or leases of property to be used in the performance of a contract with the U.S. Department of the Navy for the overhaul of a U.S. Navy vessel | R-1304 | 1015 |
| 47:301(3)(a) 47:301(13)(a) | Lease or rental with an operator | No certificate required | 1022 |
| 47:305.4(B) | Natural gas when used in the production of iron in the process known as the "direct reduced iron process" | No certificate required | 1033 |
| 47:305.5(B)(3) | Sales of electricity for chlor-alkali manufacturing processes | R-1115 | 1034 |
| 47:305(H) | Sales of labor, materials, services, and supplies used for the repair, renovation, or conversion of any drilling rig or machinery and equipment which become component parts of any drilling rig used exclusively for the exploration or development of minerals in federal offshore area | R-1096 | 1078 |
| 47:305.1(A) 47:305.1(B) | Sales of certain materials and services to vessels operating in foreign and interstate coastwise commerce | R-1009 R-1010 | 5035 |
| 47:305.10 | Property purchased or leased for exclusive use outside the state (offshore); dealers storing purchases of tangible personal property for first use in the offshore area on a regular basis and have a definite need for the privilege of purchasing tax free for offshore use must apply for an exemption certificate using form R-1022, Application for Offshore Registration Number. | R-1023 R-1096 | 5042 |
| 47:305.19 | Gross proceeds/receipts from the lease or rental of vessels for use in the federal offshore area in mineral production or for providing services to those engaged in mineral production | No certificate required | 5056 |
| 47:305.51 | Purchases of utilities by approved steelworks, blast furnaces, coke ovens, or rolling mills under certain specified conditions | No certificate required | 5086 |
| 12:425 | Sales to nonprofit electrical co-ops | R-1054 | 7003 |
| Medical | |||
| 47:305.2(B)(10) | Purchases and leases of tangible personal property and sales of services to hospitals that provide free care to all patients; includes supplies and equipment which are reasonably necessary for the operation of a free hospital | R-1056 | 1017 |
| 47:305.2(B)(9) | Sales of any human tissue transplants, including human organs, bone, skin, cornea, blood, or blood products | No certificate required | 1036 |
| 47:305.2(B)(12) | Materials used directly in the collection of blood | No certificate required | 1091 |
| 47:305.2(B)(12) | Apheresis kits and leuko reduction filters | No certificate required | 1092 |
| 47:305.2(B)(2) | Sales of orthotic devices, prosthetic devices, hearing aids, prescription eyeglasses, contact lenses, and wheelchairs prescribed by physicians, optometrists, or licensed chiropractors used exclusively by patient for personal use; institutional or retail dealers may purchase tax- free using Form R-1041, Institutional or Retail Dealer Purchases of Medical-Related Property. | Prescription required | 5023 |
| 47:305.2(A)(2) | Sales of ostomy, colostomy, ileostomy devices and equipment; institutional or retail dealers may purchase tax-free using Form R-1041, Institutional or Retail Dealer Purchases of Medical-Related Property. | Prescription required | 5024 |
| 47:305.2(A)(3) | Sales of medical devices that are used by a patient in the treatment of any disease under the supervision of a physician or administered by a physician, nurse, or other health care professional; institutional or retail dealers may purchase tax-free using Form R-1041, Institutional or Retail Dealer Purchases of Medical-Related Property. | Prescription required | 5027 |
| 47:305.2(A)(3) | Purchase of restorative materials used by dentists; institutional or retail dealers may purchase tax-free using Form R-1041, Institutional or Retail Dealer Purchases of Medical- Related Property. | No certificate required | 5028 |
# 47:305(H)
# 47:305.1(B)
# 47:305.2(B)(2)
Sales of orthotic devices, prosthetic devices, hearing aids, prescription eyeglasses, contact lenses, and wheelchairs prescribed by physicians, optometrists, or licensed chiropractors used exclusively by patient for personal use; institutional or retail dealers may purchase taxfree using Form R-1041, Institutional or Retail Dealer Purchases of Medical-Related Property.
Prescription
# 47:305.2(B)(6)
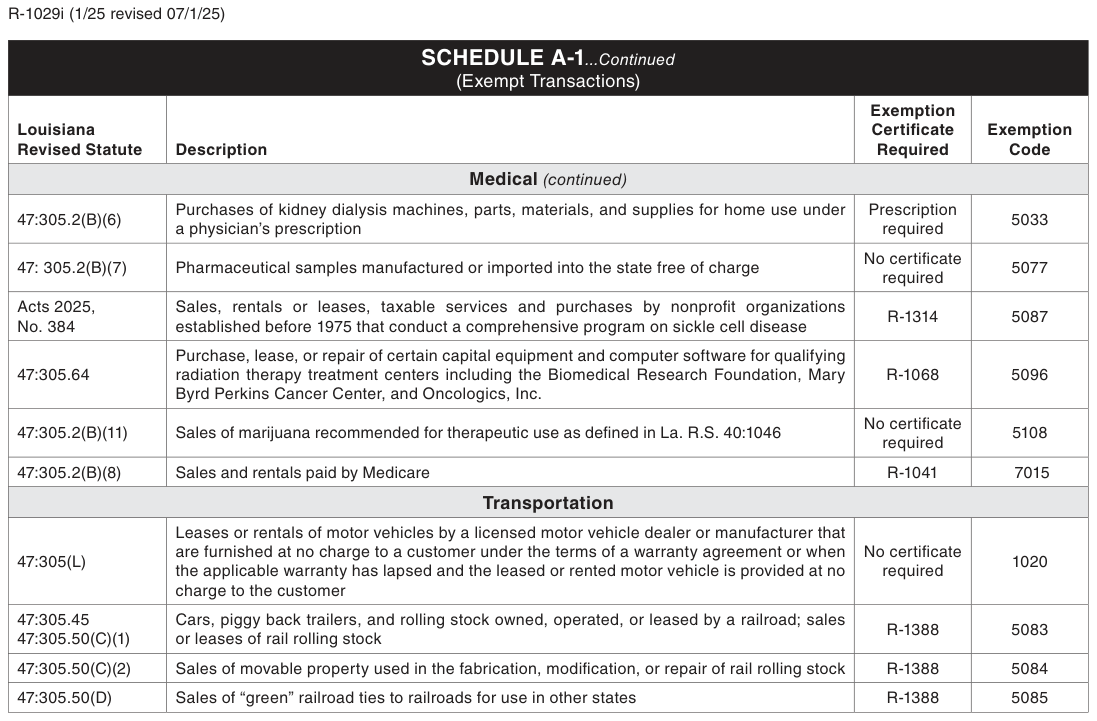
Text version of this table
| SCHEDULE A-1...Continued (Exempt Transactions) | |||
| Louisiana Revised Statute | Description | Exemption Certificate Required | Exemption Code |
| Medical (continued) | |||
| 47:305.2(B)(6) | Purchases of kidney dialysis machines, parts, materials, and supplies for home use under a physician’s prescription | Prescription required | 5033 |
| 47: 305.2(B)(7) | Pharmaceutical samples manufactured or imported into the state free of charge | No certificate required | 5077 |
| Acts 2025, No. 384 | Sales, rentals or leases, taxable services and purchases by nonprofit organizations established before 1975 that conduct a comprehensive program on sickle cell disease | R-1314 | 5087 |
| 47:305.64 | Purchase, lease, or repair of certain capital equipment and computer software for qualifying radiation therapy treatment centers including the Biomedical Research Foundation, Mary Byrd Perkins Cancer Center, and Oncologics, Inc. | R-1068 | 5096 |
| 47:305.2(B)(11) | Sales of marijuana recommended for therapeutic use as defined in La. R.S. 40:1046 | No certificate required | 5108 |
| 47:305.2(B)(8) | Sales and rentals paid by Medicare | R-1041 | 7015 |
| Transportation | |||
| 47:305(L) | Leases or rentals of motor vehicles by a licensed motor vehicle dealer or manufacturer that are furnished at no charge to a customer under the terms of a warranty agreement or when the applicable warranty has lapsed and the leased or rented motor vehicle is provided at no charge to the customer | No certificate required | 1020 |
| 47:305.45 47:305.50(C)(1) | Cars, piggy back trailers, and rolling stock owned, operated, or leased by a railroad; sales or leases of rail rolling stock | R-1388 | 5083 |
| 47:305.50(C)(2) | Sales of movable property used in the fabrication, modification, or repair of rail rolling stock | R-1388 | 5084 |
| 47:305.50(D) | Sales of “green” railroad ties to railroads for use in other states | R-1388 | 5085 |
# 47:305(L)
R-1388 5083
47:305.50(C)(2) Sales of movable property used in the fabrication, modification, or repair of rail rolling stock R-1388 5084 47:305.50(D) Sales of "green" railroad ties to railroads for use in other states R-1388 5085
Source: view the official PDF
Nearby sections (9 sections)
- cift-620 · CIFT-620 Instructions - Corporation Income & Franchise Tax
- cift-620es · CIFT-620ES Instructions - Corporation Estimated Tax
- cit-620es · CIT-620ES Instructions - Corporation Estimated Tax (2026…
- it-540 · IT-540 Instructions - Louisiana Resident Income Tax…
- it-540b · IT-540B Instructions - Louisiana Nonresident & Part-Year…
- it-540es · IT-540ES Instructions - Estimated Tax for Individuals
- it-541 · IT-541 Instructions - Louisiana Fiduciary Income Tax
- it-565 · IT-565 Instructions - Partnership Return of Income (incl.…
- r-1029 · R-1029 Instructions - Louisiana Sales Tax Return