Kentucky Department of Revenue Form Instructions
Form 740-ES Instructions - Individual Estimated Tax
42A740-S4 (9-25)
# INSTRUCTIONS FOR FILING ESTIMATED TAX VOUCHERS DEPARTMENT OF REVENUE
WHAT'S NEW FOR 2026-The standard deduction will increase to $3,360.00 for 2026. Individuals, estates, or trusts who electronically file their return will now have the option to have their estimated tax payment(s) debited from their bank account.
WHO MUST MAKE PAYMENTS-Individuals, estates, or trusts who can reasonably expect to have income of more than $5,000 from which no Kentucky income tax will be withheld may be required to make estimated tax payments as required by KRS 141.305. Payments may be made through withholding, a credit forward from the previous year's income tax return or estimated tax payments. The worksheet on the reverse should be used to determine the amount which should be paid through estimated tax payments. If the amount of estimated tax for the year is $500 or less, no payment is required.
General Rule
In most cases, you must pay estimated tax for 2026 if both of the following apply.
1 You expect to owe at least $500 in tax for 2026, after subtracting your withholding and refundable credits.
2 You expect your withholding and refundable credits to be less than the smaller of:
(a) 90% of the tax to be shown on your 2026 tax return; or
(b) 100% of the tax shown on your 2025 tax return. Your 2025 tax return must cover all 12 months.
Note: These percentages may be different if you are a farmer, fisherman, or higher income taxpayer. See Special Rules.
EXCEPTION-You don't have to pay estimated tax payments for 2026 if you had no Kentucky tax liability for the full 12-month 2025 tax year. You had no liability for 2025 if your total tax was zero or you didn't have to file a Kentucky tax return.
# SPECIAL RULES
There are special rules for farmers, fisherman, and certain higher income taxpayers.
FARMERS AND FISHERMAN-If at least two-thirds of your gross income for 2025 or 2026 is from farming, substitute 66 2/ % for 90% in (2a) under General Rule.
HIGHER INCOME TAXPAYERS-If your Kentucky adjusted gross income for 2025 was more than $150,000 ($75,000 if your filing status for 2026 is married filing separately), substitute 110% for 100% in
(2b) under General Rule. This rule does not apply to farmers.
FAMILY SIZE TAX CREDIT-The Family Size Tax Credit is based on modified gross income (MGI) and the size of the family. If your total MGI is $42,760 or less you may qualify for Kentucky Family Size Tax Credit.
Note: This credit is not applicable to fiduciary returns.
"Modified gross income" used to calculate the Family Size Tax Credit means the greater of:
Federal adjusted gross income adjusted to include interest income derived from municipal bonds (non-Kentucky) and lump-sum pension distributions not included in federal adjusted gross income; or Kentucky adjusted gross income adjusted to include lump-sum pension distributions not included in federal adjusted gross income.
PASS-THROUGH ENTITIES AND INDIVIDUAL OWNERS OF
DISREGARDED SINGLE MEMBER LLCs-All pass-through entities and individual owners of disregarded single member LLCs that file on Schedules C, E or F for federal income tax purposes are treated the same for Kentucky income tax purposes as they are treated for federal income tax purposes except for the differences between Kentucky law and federal law. Individuals with income from pass-through entities or disregarded single member LLCs that file Schedule C, E or F for federal income tax purposes may be required to make individual estimated tax payments.
WHEN TO PAY-Taxpayers may pay the full amount of estimated tax in one payment on the earliest applicable due date, or they may pay in installments. Installments for calendar year 2026 are due April 15, June 15, September 15, 2026, and January 15, 2027.
Any credit from a 2025 income tax return should be applied to the amount owed before any payments are made. Installment payments should not be made until the amount of the credit has been used.
A voucher should be filed only when a payment is required.
FARMERS AND FISHERMAN-If at least two-thirds of your gross income for 2025 or 2026 is from farming or fishing, you can do one of the following:
- Pay all of your estimated tax by January 15, 2027.
- File your 2026 Form 740 or Form 740-NP by March 1, 2027, and pay the total tax due. In this case, 2026 estimated tax payments aren't required to avoid a penalty.
PENALTY FOR UNTIMELY ESTIMATED PAYMENT-Failure to pay estimated tax installments on or before the due date will result in assessment of penalty on the late payment. This penalty will be calculated using the rate provided by KRS 131.183.
HOW TO USE ESTIMATED TAX VOUCHERS-Enter your name, address and Social Security number(s)/FEIN in the spaces provided.
In the payment block, enter the amount of payment. Do not enter amounts paid through a credit from a previous year.
HOW TO PAY-You may pay your estimated tax installments using the following options:
- Pay by check using Form 740-ES. Make check payable to
# Kentucky State Treasurer, and write your Social Security
Number on the face of the check. If you chose to pay your first installment with Form 740, please prepare a separate check for the amount shown on the Form 740-ES voucher and include the voucher marked "Installment 1".
- Form 8879-K, you may authorize the Kentucky Department of Revenue to debit all four of your installments on the dates due.
This option must be initiated at the time of the filing and is only available for electronic filers.
- Pay by ACH debit, you may access the Department of Revenue's secure website revenue.ky.gov.
ANNUALIZED INCOME INSTALLMENTS-If you receive your income unevenly throughout the year (for example, because you operate your business on a seasonal basis or you have a large capital gain late in the year), you may be able to lower or eliminate the amount of your required estimated tax payment for one or more periods by using the annualized income installments method. See chapter 2 of federal publication 505 for details.
# Period When
Estimate Required Number of or Change Occurs Due Date Equal Installments January 1-April 1 April 15, 2026 4 April 2-June 1 June 15, 2026 3 June 2-September 1 September 15, 2026 2 September 2-December 31* January 15, 2027 1 *If the change occurs after September 1, 2026, the voucher is not required if the 2026 Kentucky income tax return is filed and the tax shown to be due is paid on or before February 1, 2027.
Failure to make required estimated installments by the specified dates may result in penalty due.
FISCAL YEAR FILERS-If you pay tax for a fiscal year instead of a calendar year, your due date is the 15th day of the fourth, sixth and ninth months of your fiscal year and the 15th day of the first month of the following fiscal year.
# Estimated Tax Worksheet (2026)
1 Enter your total estimated wages subject to withholding … 1 2 Enter your total estimated taxable income from sources with no withholding … 2 3 Add lines 1 and 2 … 3 4 Enter estimated adjustments to income … 4 5 Subtract line 4 from line 3. This is your ESTIMATED ADJUSTED GROSS INCOME … 5 6 Enter estimated allowable itemized deductions or the standard deduction of $3,360.00 (Enter zero for estates or trusts) … 6 7 Subtract line 6 from line 5. Enter the difference here. This is your ESTIMATED NET INCOME … 7 8 Compute tax on estimated net income from line 7. Multiply line 7 by 3.5% and ENTER TAX HERE … 8 9 Enter your tax credits ($40 if you are 65 or over or blind; $20 if you are in the Kentucky National Guard) … 9 10 Enter Family Size Tax Credit using percentage from worksheet below (Enter zero for estates or trusts) … 10 11 Enter Kentucky income tax to be withheld in 2026. Add lines 9 through 11 and enter total at right … 11 12 Subtract the total on line 11 from line 8. This is your Estimated Kentucky Income Tax for 2026. Enter here. If this amount is $500 or less, estimated tax payment is not required … 12 13(a) Multiply line 12 by 90% (66 2/ % for farmers and fishermen, see instructions) … 13a
(b) Enter amount of tax liability from 2025 return (see 2(b) of General Rule) (Multiply by 110% for high income taxpayers, see instructions) … 13b
(c) Required annual payment. Enter the smaller of line 13(a) or 13(b) … 13c 14 Divide line 13(c) by 4. This is amount of each installment. Enter here and in Column B, lines 1 through 4 of Record of Estimated Tax Payments Schedule … 14
Family Size Tax Credit (FSTC) is based on modified gross income (MGI) and the size of the family. Refer to page 1 for the definition of MGI. The 2025 table is provided for your convenience.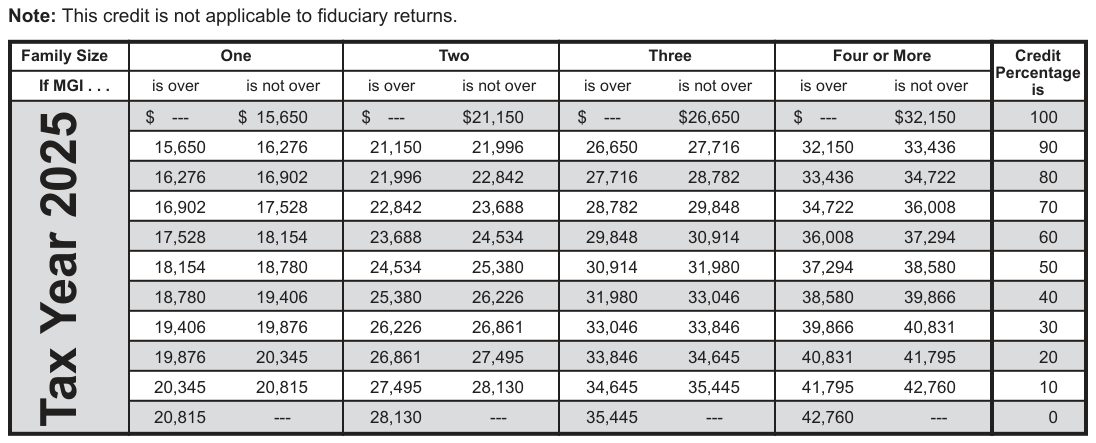
Text version of this table
Family Size One Two Three Four or More Credit Percentage is If MGI . . . is over is not over is over is not over is over is not over is over is not over Tax Year 2025 $ --- $ 15,650 $ --- $21,150 $ --- $26,650 $ --- $32,150 100 15,650 16,276 21,150 21,996 26,650 27,716 32,150 33,436 90 16,276 16,902 21,996 22,842 27,716 28,782 33,436 34,722 80 16,902 17,528 22,842 23,688 28,782 29,848 34,722 36,008 70 17,528 18,154 23,688 24,534 29,848 30,914 36,008 37,294 60 18,154 18,780 24,534 25,380 30,914 31,980 37,294 38,580 50 18,780 19,406 25,380 26,226 31,980 33,046 38,580 39,866 40 19,406 19,876 26,226 26,861 33,046 33,846 39,866 40,831 30 19,876 20,345 26,861 27,495 33,846 34,645 40,831 41,795 20 20,345 20,815 27,495 28,130 34,645 35,445 41,795 42,760 10 20,815 --- 28,130 --- 35,445 --- 42,760 --- 0
# Two Three Four or More Credit
# Tax Year 2025
# AMENDED COMPUTATION SCHEDULE
Use if your estimated tax substantially changes after you make your first payment.
1 Enter amended estimated tax …
2 Less:
(a) Amount of 2025 overpayment credited to 2026 estimated tax …
(b) Payments made on 2026 estimated tax to date …
(c) Total of Lines 2(a) and 2(b) …
3 Unpaid balance (line 1 less line 2(c)) …
4 Amount to be paid (line 3 divided by number of remaining installments less any unused 2025 overpayment credit). Enter here and in block on voucher …
# RECORD OF ESTIMATED TAX PAYMENTS SCHEDULE
Col. A Col. B Col. C Col. D
2025 overpayment
Amount to be
Voucher Amount credit applied to paid with voucher.
Number Date from line 14 installment.
Enter here and on above. Subtract C
Vouchers 1-4.* from B.
Total
*If zero or less, do not file a voucher. If amount credited exceeds amount of installment enter excess in Column C of the next line.
Source: view the official PDF
Nearby sections (10 sections)
- 41apte · Form PTE Instructions - Kentucky Pass-Through Entity (incl.…
- 51a205 · Form 51A205 - Kentucky Sales and Use Tax Return (with…
- 720u · Form 720/720U Instructions - Corporation Income Tax & LLET…
- 740 · Form 740 - Kentucky Individual Income Tax Return packet…
- 740-es · Form 740-ES Instructions - Individual Estimated Tax
- 740-np · Form 740-NP - Kentucky Nonresident/Part-Year Resident Income…
- 740-ptet · Form 740-PTET — Kentucky Pass-Through Entity Tax Instructions
- 740np-wh · Form 740NP-WH — Kentucky Nonresident Income Tax Withholding…
- 740np-wh-es-inst · Form 740NP-WH-ES — Estimated Payment Voucher…
- 741 · Form 741 Instructions - Kentucky Fiduciary Income Tax