Iowa Department of Revenue Forms & Instructions
IA 2220 Underpayment of Estimated Tax by Corporations (with instructions)
2025 IA 2220 Underpayment of Estimated Tax
# Corporations, S Corporations, Financial Institutions, and Partnerships
Name: __
Federal Employer Identification Number (FEIN): _ Tax Period: _ This form must be included with your return, even if no underpayment penalty is due.
# Computation of Underpayment
Note: If you meet any of the exceptions that avoid the underpayment penalty for all quarters (see instructions), skip lines 1 through 8, and go directly to line 9.
- 2025 tax from IA 1120, line 14; IA 1120F, line 11; IA 1120S, lines 35 and 38; or IA 1065, line 29 … 1. __
- Credits from IA 1120, line 15; IA 1120F, lines 12 and 14; IA 1120S, lines 36, 39, and 43; or IA 1065, lines 30 and 34 … 2. __
- Balance. Subtract line 2 from line 1 … 3. __
# 1st Quarter 2nd Quarter 3rd Quarter 4th Quarter
Text version of this table
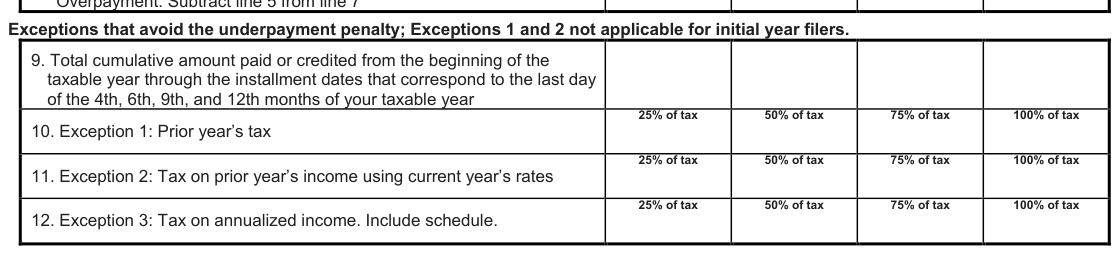
| 9. Total cumulative amount paid or credited from the beginning of the taxable year through the installment dates that correspond to the last day of the 4th, 6th, 9th, and 12th months of your taxable year | ||||
| 10. Exception 1: Prior year's tax | 25% of tax | 50% of tax | 75% of tax | 100% of tax |
| 11. Exception 2: Tax on prior year's income using current year's rates | 25% of tax | 50% of tax | 75% of tax | 100% of tax |
| 12. Exception 3: Tax on annualized income. Include schedule. | 25% of tax | 50% of tax | 75% of tax | 100% of tax |
# Computation of Underpayment Penalty
- Enter same installment dates used in line 4
- Amount of underpayment from line 8
- Date of payment. See Instructions.
- (a) Number of days from due date of installment to date of payment or 12/31/2025, whichever is earlier
- (b) Number of days inclusively from 01/01/2026, or due date of installment, whichever is later, to the date of payment or the last day of the 4th month after the close of the tax year, whichever is earlier
- (a) 10% per year on the amount shown on line 14 for the number of days shown on line 16(a). See Instructions.
- (b) 10% per year on the amount shown on line 14 for the number of days shown on line 16(b). See Instructions.
- Total of lines 17(a) and 17(b).
- Penalty: Add the four columns of line 18 and enter here. Also, show the amount on IA 1120, line 20, IA 1120F, line 19, IA 1120S, line 49, or IA 1065, line 40.
# Purpose of Form
Corporations, financial institutions, S Corporations that owe built-in gains/passive investment tax or make a Pass-Through Entity Tax (PTET) election, and partnerships that make a PTET election, use the IA 2220 to determine if they paid the correct amount of estimated tax by the proper due date. If the minimum amount was not paid timely, an underpayment penalty is imposed for the period of the underpayment. This form helps determine whether or not a taxpayer is subject to such a penalty.
# Estimated Tax
Every taxpayer with more than $1,000 in tax due after credits is required to pay estimated tax.
Exceptions that Avoid the Underpayment Penalty
No penalty will be charged for any underpayment on line 8 if:
- All of the payments were made on or before the due date of the installment; and
- The total payments made by that installment date equal or exceed the amount which would have been due if the estimated tax were calculated using any of the exceptions listed below.
A different exception may be applied to each underpayment. If there has been an underpayment of the amount of the estimated tax, and the taxpayer believes that one or more of the exceptions to the penalty precludes the assertion of the underpayment penalty, the taxpayer should complete lines 9 through 12 showing the applicability of any exception upon which the taxpayer relies. If no exception applies, complete lines 13 through 19 to determine the amount of the penalty on the underpayment from line 8.
Line 6a. Amount Paid or Credited for Each Period Include on this line estimated tax payments made on or before the due date for each applicable quarter. Do not include any tax credits, including Composite Tax Credits or PTET Credits you received from a pass-through entity, as these credits are already included on Line 2.
Line 10: Exception 1 - Prior year's tax This exception allows taxpayers to substitute for the current year's estimate the amount of the tax shown on the return for the preceding taxable year. This exception may be utilized only if the preceding taxable year was a taxable year of 12 months and a return showing a tax liability (including a "zero" liability) was filed for that year.
Taxpayers filing an initial year Iowa return may not use Exception 1.
Note: This exception does not apply to partnerships that did not make a PTET election in the previous tax year or to S corporations that did not make a PTET election or owe built-in gains/passive investment income tax in the previous tax year.
2025 IA 2220 Instructions
Line 11: Exception 2 - Tax on prior year's income using current year's rates This exception allows taxpayers to use a tax computed by using the current year's rates but otherwise on the basis of the facts and law applicable to the prior year.
Taxpayers filing an initial year Iowa return may not use Exception 2.
# Line 12: Exception 3 - Tax on annualized income
This section applies if the taxpayer made an estimated tax payment of at least 100% of the amount it would owe if its estimated tax were a tax computed on annualized taxable income for the months preceding an installment date.
A taxpayer may thus annualize its income:
- For the first 3 months if the installment was required to be paid in the 4th month;
- For the first 3 months or the first 5 months if the installment was required to be paid in the 6th month;
- For the first 6 months or the first 8 months if the installment was required to be paid in the 9th month; and
- For the first 9 months or for the first 11 months if the installment was required to be paid in the 12th month.
To annualize, multiply taxable income for the period by 12 and divide the resulting amount by the number of months in the period (3, 5, 6, 8, 9, or 11, as the case may be). Enclose income statements for appropriate months in the tax period.
Overpayment
A payment of estimated tax on any installment date is considered a payment of any previous underpayment only to the extent the payment exceeds the amount of the installment as computed on line 5.
# Line 15: Date of payment
Once a payment is made to cover an exception to the penalty, the underpayment is no longer outstanding, so the penalty computation stops at the date that payment is made.
To Compute Penalty Use the following formula:
Daily % Number of x Underpayment
Penalty = rate x days
(line 14)
(line 17) (line 16)
The daily percentage rate is:
10% per annum = .027397%% per day (01/01/25-12/31/25) 10% per annum = 0.027397% per day (01/01/26-12/31/26)
Include this form with your Iowa return, IA 1120, IA
1120S, IA 1120F, or IA 1065.
Questions: Call 515-281-3114 or 800-367-3388 Additional information can be found on the Department website (revenue.iowa.gov).
Email: idr@iowa.gov
Source: view the official PDF
Nearby sections (23 sections)
- ia-1041-inst · IA 1041 Iowa Fiduciary Return Instructions
- ia-1065-estimated-inst · IA 1065 Estimated Tax for Partnerships…
- ia-1065-inst · IA 1065 Instructions — Iowa Partnership Return of Income
- ia-1120-inst · IA 1120 Iowa Corporation Income Tax Instructions
- ia-1120f-inst · IA 1120F Iowa Franchise Tax Instructions (Financial…
- ia-1120s-estimated-inst · IA 1120S Estimated Tax for S Corporations…
- ia-1120s-inst · IA 1120S Instructions — Iowa Income Tax Return of S…
- ia-126-nonresident-credit · IA 126 — Iowa Nonresident and Part-year…
- ia-130-out-of-state-credit · IA 130 — Iowa Out-of-State Tax Credit…
- ia-148-inst · IA 148 Iowa Tax Credits Schedule Instructions
- ia-2210-ai · IA 2210 AI — Iowa Annualized Income Installment Method…
- ia-2210-individuals · IA 2210 — Iowa Underpayment of Estimated Tax by…
- ia-2220-inst · IA 2220 Underpayment of Estimated Tax by Corporations…
- ia-2440-disability-exclusion · IA 2440 — Iowa Disability Income…
- ia-32-028-sales-use-return · Iowa Sales and Use Tax Return (with…
- ia-4136-fuel-tax-credit · IA 4136 — Iowa Fuel Tax Credit (with…
- ia-54-036-special-assessment-ptc · Iowa Special Assessment Property Tax…
- ia-cigarette-tobacco-uniformity-guide · Iowa Cigarette and Tobacco Tax…
- ia-nonresident-composite-agreement · IA Nonresident Member Composite…
- ia-pte-c-inst · IA PTE-C Instructions — Iowa Composite Return (PTET…
- ia-sf-2472-homestead-exemption · Application of Homestead Tax Exemption…
- ia-w-4 · IA W-4 — Employee Withholding Allowance Certificate (with…
- ia-w-4p · IA W-4P — Withholding Certificate for Pension or Annuity…