Georgia Department of Revenue Form Instructions
GA DOR employers-tax-guide
Georgia Employer's Tax Guide
EMPLOYER'S
# REVISED:
INTRODUCTION … 3
BUSINESS ELECTRONIC FILING … 3 TELEPHONE ASSISTANCE … 3 WITHHOLDING DUE DATES … 5 WITHHOLDING REQUIREMENTS SUMMARY … ...6 FILING STATUS … 7 BASIC DEFINITIONS … 9 PAYMENT and FILING REQUIREMENTS … 10 ELECTRONIC FILING and PAYMENT … 10 OTHER EMPLOYER RESPONSIBILITIES and REQUIREMENTS … 16 EMPLOYEE RESPONSIBILITIES … 14 INCOME STATEMENT REPORTING REQUIREMENTS … … 17 FILM CREDIT WITHHOLDING … 20 OTHER FILING and REPORTING REQUIREMENTS … .. 21 PENALTY and INTEREST … 25 FILING TIPS … 27 TAX TABLE … 28 PERCENTAGE METHOD for EMPLOYEE WITHHOLDING … 48 TABLE E … 48 TABLE F … 49 FORMS … . 50 DEPARTMENT OF REVENUE RESOURCES … 51
# TABLE OF CONTENTS
J
J
-------------------------------------------------------------------· ------------------------------------------------------------------- /} J -------------------------------------------------------------------· -------------------------------------------------------------------,> ----------------------------------------------· ---------------------------------------------
# INTRODUCTION
This publication contains information regarding withholding tax filing requirements based on Georgia income t a x la ws si gned in to effect on Ma y 11 , 20 26. It includes applicable withholding ta x tables, basic definitions, answers to frequently asked questions, and references to applicable sections of Title 48 of the Off ic i a l C o d e o f Georgia Annotated ( O.C.G.A. ), which govern withholding tax requirements. Additional information concerni ng withholding tax is available at Georgia Department of Revenue webpage for additional information concerning withholding tax.https://dor.georgia.gov/withholding
# BUSINESS ELECTRONIC FILING
The
Georgia Tax Center (GTC) allows business customers to file returns and pay taxes electronically. Employers can file withholding tax returns and make payments using this system. See Georgia Tax Center webpage for more information on electronic filing of business taxes for more information. https:// gtc.dor.ga.gov It is mandatory fo r business c u s tomers who are cur rently required to submit tax payments via electronic funds transfer to fil e their returns electronic a lly through GTC . Business customers who a re required to submit tax payments via e le ctro nic funds transfer must f i l e refund claims e l e c troni c ally through G T C. Failure to electronically fi l e the refund claim shall result in the deemed failure to file the refund claim for all purposes, including applying any statute, which limits the time when a refund claim may be filed. Taxpayers may electronically refile a rejected claim at any time within the statute of limitations. It is mandatory for withholding returns that include any series 100 tax credits to be electronically filed. Customers may voluntarily use GTC if they know their tax-specific identification number(s), zip code of the location address, most recent payment and email address. Visit our website at Georgia Department of Revenue Website for instructions and registration information. dor.georgia.govI t is mandatory fo r business customers who are currently required to submit tax payments via electronic funds transfer to file their returns electronically through GTC. Business customers who are required to submit tax payments via electronic funds transfer must file refund claims electronically through GTC. Failure to electronically file the refund claim shall result in the deemed failure to file the refund claim for all purposes, including applying any statute, which limits the time when a refund claim may be filed. Taxpayers may electronically refile a rejected claim at any time within the statute of limitations. It is mandatory for withholding returns that include any series 100 tax credits to be electronically filed. Customers may voluntarily use GTC if they know their tax-specific identification number(s), zip code of the location address, most recent payment and email address. Visit our website at Georgia Department of Revenue Website for instructions and registration information.
# TELEPHONE ASSISTANCE
For telephone assistance with GTC, for all tax types, contact our Customer Contact Center at 1-877-423-6711.
# Georgia Tax Changes Effective January 1, 2026:
The following changes are effective upon signature of HB 463, but retroactive to taxable years beginning on or after January 1, 2026:
- The income tax rate has been reduced from a flat rate of 5.19% to a flat rate of 4.99%. Note: Employers must continue to withhold at the rate of 5.19% before the effective date of the change and can begin withholding at the new rate of 4.99%, starting May 11, 2026.
- Georgia standard
- The dependent deduction was raised from $4,000 to $5,000.
With the signing of HB 1199, Georgia conformed to the Internal Revenue Code, as amended, provided for in federal law enacted on or before January 1, 2026; however, Georgia did not adopt all federal provisions. Some notable federal provisions Georgia chose to decouple from includes:
# Federal Tax Changes Effective January 1, 2026:
- The Federal increase in the SALT deduction cap. Georgia will continue to follow the $10,000 limit.
- The Federal exemptions on tips and overtime wages; however, HB 463 - The Georgia Economic Growth and Tax Relief Act of 2026, Georgia adopted more limited exceptions for
Qualified Overtime Compensation and Cash Tips.
# Georgia Qualified Overtime Compensation and Cash Tips Reporting
House Bill 463 creates Georgia income tax treatment for certain qualified overtime compensation and qualified cash tips. For tax year 2026, employers and payers must continue to follow existing Georgia withholding, deposit, and Form G-7 filing requirements unless the Department issues separate withholding calculation guidance. Qualified overtime compensation and qualified cash tips for tax year 2026 must be reported annually with the year-end 2026 income statements. Beginning in 2027, Form G-7 will be updated to collect this information.
For taxable years beginning on or after January 1, 2026, and ending on December 31, 2028, employers must report qualified overtime compensation and qualified cash tips annually to the Department on the Income Statements, (W2s and 1099s) with Form G-1003.
Employers must include the employee or payee level detail on the related income statements submitted with Form G-1003. For W-2 reporting, report cash tips, qualified overtime compensation, and TTOC information using the applicable federal W-2 fields and codes. Follow the IRS instructions when completing the W2 using the correct box 12 codes. For Form 1099-NEC, report cash tips in box 1b, the TTOC in box 1c, and overtime compensation in box 1d. For Form 1099-MISC, report cash tips in box 13a, the TTOC in box 13b, and overtime compensation in box 14.
Do not report these annual qualified overtime compensation and cash tips totals on Form G-7 for tax year 2026. Form G-7 remains the same for Georgia income tax withheld, adjustments to withholding, tax due, tax paid, and payments remitted. If qualified overtime compensation or cash tips are corrected after Form G-1003 is filed, submit corrected income statements and an amended Form G-1003. If the correction changes Georgia withholding previously reported for a period, file the appropriate amended Form G-7.
See the Income Statement Reporting Requirements section for additional details on reporting.
For more details on Georgia's conformity to federal tax laws, please see https://dor.georgia.gov/taxes/tax-rules-and-policies/income-tax-federal-tax-changes.
J
------------------------------------------------------------------------------,
# WITHHOLDING DUE DATES
------------------------------------------------------------------·-----------·
# 2026 Withholding Tax Due Dates for Monthly Filers
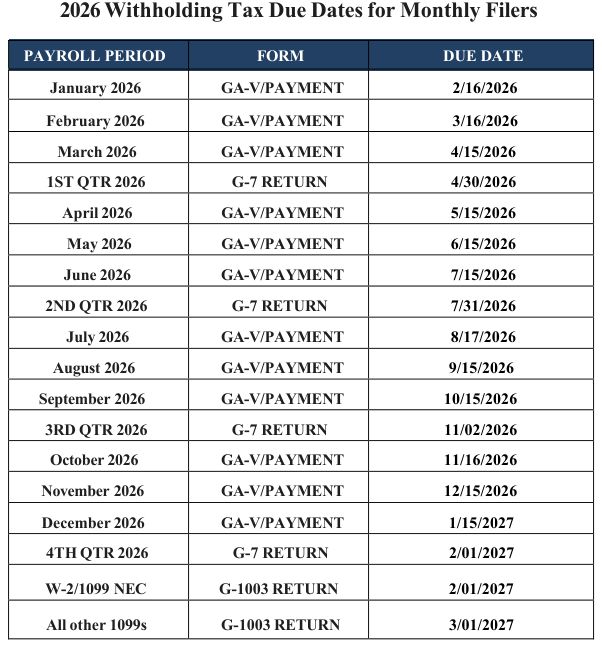
Text version of this table
| PAYROLL PERIOD | FORM | DUE DATE |
|---|---|---|
| January 2026 | GA-V/PAYMENT | 2/16/2026 |
| February 2026 | GA-V/PAYMENT | 3/16/2026 |
| March 2026 | GA-V/PAYMENT | 4/15/2026 |
| 1ST QTR 2026 | G-7 RETURN | 4/30/2026 |
| April 2026 | GA-V/PAYMENT | 5/15/2026 |
| May 2026 | GA-V/PAYMENT | 6/15/2026 |
| June 2026 | GA-V/PAYMENT | 7/15/2026 |
| 2ND QTR 2026 | G-7 RETURN | 7/31/2026 |
| July 2026 | GA-V/PAYMENT | 8/17/2026 |
| August 2026 | GA-V/PAYMENT | 9/15/2026 |
| September 2026 | GA-V/PAYMENT | 10/15/2026 |
| 3RD QTR 2026 | G-7 RETURN | 11/02/2026 |
| October 2026 | GA-V/PAYMENT | 11/16/2026 |
| November 2026 | GA-V/PAYMENT | 12/15/2026 |
| December 2026 | GA-V/PAYMENT | 1/15/2027 |
| 4TH QTR 2026 | G-7 RETURN | 2/01/2027 |
| W-2/1099 NEC | G-1003 RETURN | 2/01/2027 |
| All other 1099s | G-1003 RETURN | 3/01/2027 |
# FORM
# 2026 Withholding Tax Due Dates for Quarterly & Annual Filers
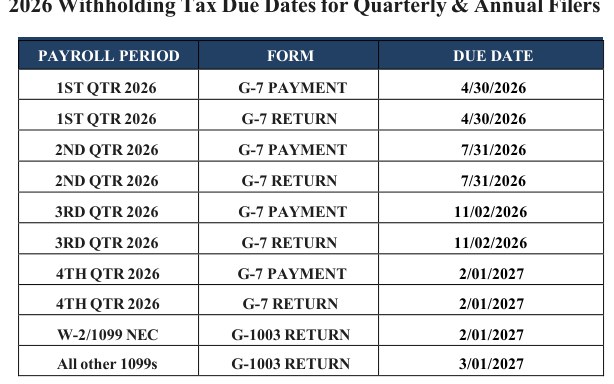
Text version of this table
| PAYROLL PERIOD | FORM | DUE DATE |
|---|---|---|
| 1ST QTR 2026 | G-7 PAYMENT | 4/30/2026 |
| 1ST QTR 2026 | G-7 RETURN | 4/30/2026 |
| 2ND QTR 2026 | G-7 PAYMENT | 7/31/2026 |
| 2ND QTR 2026 | G-7 RETURN | 7/31/2026 |
| 3RD QTR 2026 | G-7 PAYMENT | 11/02/2026 |
| 3RD QTR 2026 | G-7 RETURN | 11/02/2026 |
| 4TH QTR 2026 | G-7 PAYMENT | 2/01/2027 |
| 4TH QTR 2026 | G-7 RETURN | 2/01/2027 |
| W-2/1099 NEC | G-1003 RETURN | 2/01/2027 |
| All other 1099s | G-1003 RETURN | 3/01/2027 |
# FORM
IMPORTANT NOTICE FOR ALL FILERS-EXCEPTION TO ALL DUE DATES:
If $100,000 or more is required to be withheld for a payday, the payment must be submitted electronically by the next banking day.
NOTE: Form GA-V is not required if no tax was withheld or if payment was made electronically. If a due date falls on a Federal Reserve bank holiday, Georgia State Holiday, Saturday or Sunday, the due date is extended to the next banking day.
1099s are only required to be submitted if there is Georgia Withholding. Please note, Form 1099-K must be submitted even if there is no Georgia state income tax withheld.
# Center (GTC) located at https://gtc.dor.ga.gov. These payments
ACH Debits are submitted via the Georgia Tax must be completed on or before the due date. i s the type of EFT specifically requested and granted under certain circumstances. These payments must be received by the due date via EFT. Employers must register for ACH credit by filing Form Georgia Department of Revenue webpage for Form EFT-002.
# EFT- 002.
Visit our website at Georgia Department of Revenue Website or email Georgia Department of Revenue electronic funds transfer email for more information. dor.georgia.govVisit our website at Georgia Department of Revenue Website or email Georgia Department of Revenue electronic funds transfer email for more information. DOR.electronicfundstransfer@dor.ga.gov
# Fedwire Payments are not accepted.
------------------------------------------------------------------------------------------------------------\ J
# WITHHOLDING REQUIREMENTS SUMMARY
----------------------------------------------------------------------------------------- __ , 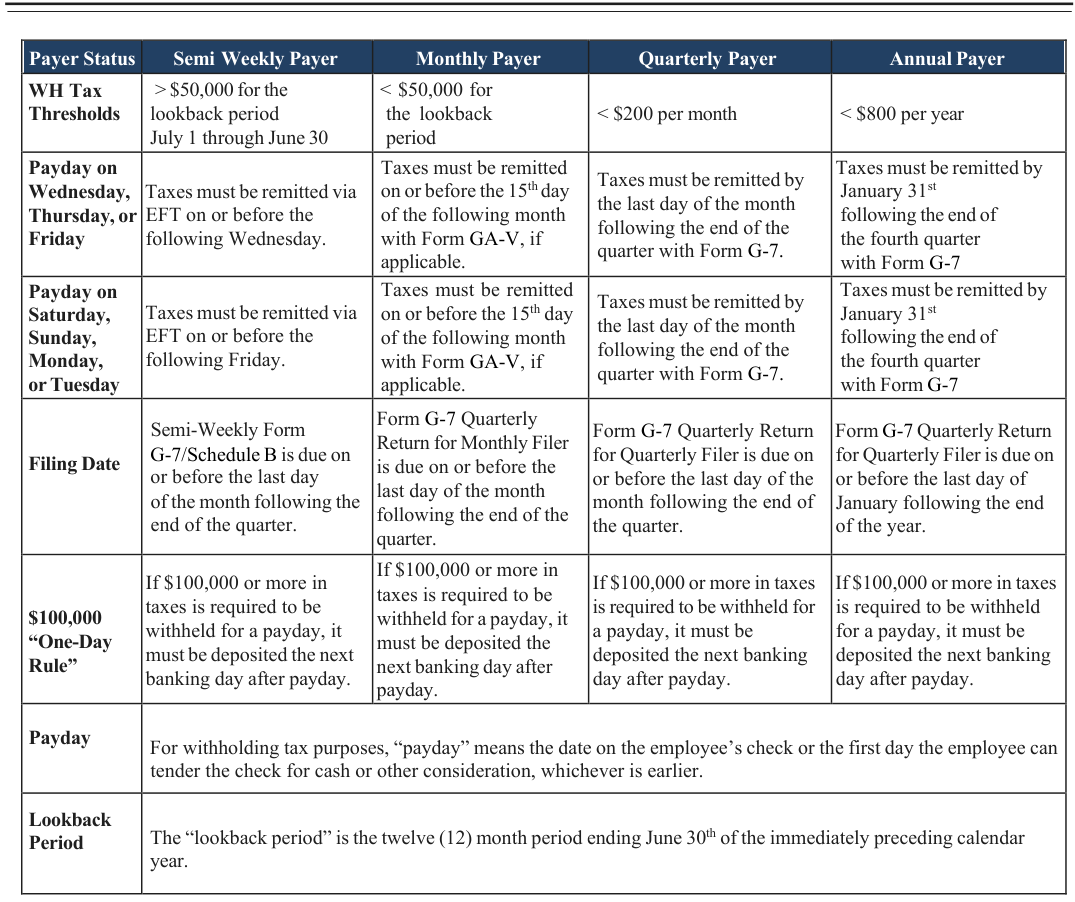
Text version of this table
Payer Status Semi-Wekly Par Monthly Payer Quarterly Payer Annual Payer WH Tax Thresholds > $50,000 for the lookback period July 1 through June 30 < $50,000 for the lookback period < $200 per month < $800 per year Payday on Wednesday, Thursday, or Friday Taxes must be remitted via EFT on or before the following Wednesday. Taxes must be remitted on or before the 15th day of the following month with Form GA-V, if applicable. Taxes must be remitted by the last day of the month following the end of the quarter with Form G-7. Taxes must be remitted by January 31st following the end of the fourth quarter with Form G-7 Payday on Saturday, Sunday, Monday, or Tuesday Taxes must be remitted via EFT on or before the following Friday. Taxes must be remitted on or before the 15th day of the following month with Form GA-V, if applicable. Taxes must be remitted by the last day of the month following the end of the quarter with Form G-7. Taxes must be remitted by January 31st following the end of the fourth quarter with Form G-7 Filing Date Semi-Weekly Form G-7/Schedule B is due on or before the last day of the month following the end of the quarter. Form G-7 Quarterly Return for Monthly Filer is due on or before the last day of the month following the end of the quarter. Form G-7 Quarterly Return for Quarterly Filer is due on or before the last day of the month following the end of the quarter. Form G-7 Quarterly Return for Quarterly Filer is due on or before the last day of January following the end of the year. $100,000 “One-Day Rule” If $100,000 or more in taxes is required to be withheld for a payday, it must be deposited the next banking day after payday. If $100,000 or more in taxes is required to be withheld for a payday, it must be deposited the next banking day after payday. If $100,000 or more in taxes is required to be withheld for a payday, it must be deposited the next banking day after payday. If $100,000 or more in taxes is required to be withheld for a payday, it must be deposited the next banking day after payday. Payday For withholding tax purposes, “payday” means the date on the employee’s check or the first day the employee can tender the check for cash or other consideration, whichever is earlier. Lookback Period The “lookback period” is the twelve (12) month period ending June 30th of the immediately preceding calendar year.
# Thresholds
# Saturday,
# Monthly Payer
# Quarterly Payer
# Annual Payer
< $800 per year
Taxes must be remitted by
January 31st following the end of the fourth quarter with Form G-7 Taxes must be remitted by January 31st following the end of the fourth quarter with Form G-7 Form G-7 Quarterly Return for Quarterly Filer is due on or before the last day of January following the end of t he year.
If $100,000 or more in taxes is required to be withheld for a payday, it must be deposited the next banking day after payday.
For withholding tax purposes, "payday" means the date on the employee's check or the first day the employee can tender the check for cash or other consideration, whichever is earlier.
# Lookback
The "lookback period" is the twelve (12) month period ending June 30th of the immediately preceding calendar Period year.
J
----------------------------------------------·
# All Filers:
If the total tax withheld, or required to be withheld, on Form G-7 exceeds $500.00, the amount must be remitted via electronic funds transfer (EFT) on any payment and return thereafter. Employers who are required to pay the tax withheld or required to be withheld via EFT must file all applicable withholding tax returns electronically. It is also mandatory for business customers who are required to submit tax payments via EFT to file refund claims electronically through GTC. Failure to electronically file the refund claim shall result in it being deemed not filed for all purposes, including the application of any statute of limitations, which limits the time when a refund claim may be filed. Taxpayers may electronically refile a rejected claim at any time within the statute of limitations. Employers must electronically file withholding returns that include any series 100 tax credits. Employers can also voluntarily file electronically, regardless of the payment amount. Form GA-V is not required if tax will be paid electronically or by EFT.
See https://dor.georgia.gov/withholding for more information.
"One-Day Rule" - Employers who are required to withhold more than $100,000 in taxes for a payday must remit those taxes via EFT by the next banking day. The Georgia rule differs from Federal requirements in that the due date for withholding tax deposits greater than $100,000 is the banking day after the payday and not the next banking day after it has been accumulated. This rule is applicable to all employers required to withhold tax and takes priority over all other remittance requirements. Please note that the filing frequency does not automatically change.
Annual Filers. Each employer whose tax withheld or tax required to be withheld is $800.00 or less per year can remit payment with Form G-7 Quarterly Return on or before January 31 of the following year, unless required to remit such payment electronically. Employers must submit a request via GTC to file annually prior to the first quarter due date. Additional information regarding annual filing is in the "Employer Responsibilities and Filing Requirements" section of this guide.
Quarterly Filers. Each employer whose tax withheld or required to be withheld is $200.00 per month or less, but more than $800.00 per year, is required to file and remit payment with Form G-7 Quarterly Return (For Quarterly Payer) on or before the last day of the month following the end of the quarter, unless required to remit such payment electronically. Form G-7 is required even if there was no tax withheld for the quarter.
Monthly Filers. Each employer whose tax withheld or required to be withheld exceeds $200.00 per month is required to remit payment with Form GA-V Payment Voucher on or before the fifteenth day of the following month, unless required to remit such payment electronically. The employer is required to file Form G-7 Quarterly Return (For Monthly Payer) on or before the last day of the month following the end of the quarter, listing all payments made during the quarter. Form GA-V is not required if no tax was withheld for the quarter or if payment was made via EFT. However, Form G-7 must still be filed on or before the statutory due date mentioned previously.
Semi-weekly Filers. The semi-weekly remittance schedule is fashioned after federal employment tax laws as set forth in the Internal Revenue Code. The due date and method of payment depends on the employer's cl assification for Georgia witholding tax purposes. Employer s who withheld more than $50,000 in the aggregate during the "lookback period" are classified as semi-weekly payers and must remit withholding taxes via EFT. For withholding tax purposes, the "lookback period" is defined as the 12-month period that ended the previous June 30th. The payment schedule for semi-weekly payers is as follows:
# FILING STATUS
Wednesday Payer -
Friday Payer - aggregate during the "lookback period" are classified as semi-weekly payers and must remit withholding taxes via EFT. For withholding tax purposes, the "lookback period" is defined as the 12-month period that ended the previous June 30th. The payment schedule for semi-w eekly payers is as follows:
For paydays occurring on Wednesday, Thursday, or Friday, the taxes required to be withheld must be remitted via EFT by the following Wednesday.
For paydays occurring on Saturday, Sunday, Monday, or Tuesday, the taxes required to be withheld must be remitted via EFT by the following Friday.
Because semi-weekly payers are required to remit tax withheld or required to be withheld via EFT, Form GA-V is not required. However, each employer must report tax withheld and paid for the quarter on Form G-7/Schedule B, which is due on or before the last day of the month following the end of the quarter.
For additional withholding tax information or assistance, contact the Taxpayer Services Division at 1-877-423-6711. For a new ACH authorization request, send the completed EFT-002 Georgia ACH Credit Taxpayer Registration Authorization Form to dor.electronicfundstransfer@dor.ga.gov.
J
------------------------------------------------------------------------------------------------------------~ ------------------------------------------------------------------------------. -----------------. ----------_
# Who is required to withhold Georgia Income?
Employers are required to withhold Georgia income tax from the taxable wages of residents for services performed inside or outside of Georgia and from the taxable wages of taxable nonresidents for services performed in Georgia.
Withholding is not required for residents if the services are performed outside Georgia and the other state requires withholding.
# What is withholding?
Payroll Withholding refers to the portion of wages deducted by employers to pay individual income tax on behalf of their employees. Employers are required to withhold Georgia income tax from the wages of residents for services performed inside or outside of Georgia and from nonresidents for services performed in Georgia.
# Who is an employer?
An employer is any entity for which a person performs services as an employee.
An employer may be an individual, corporation, limited liability company, partnership, estate, trust, association, or joint venture. Religious, educational, charitable, government, and social organizations a lso qualify as employers.
# Who is an employee?
An employee is a person who performs services for an entity under the direction and control of that entity. The relationship of employee/employer exists when the person for whom services are performed controls wages and terms of employment.
# Who is a resident?
A resident is an individual who, on income tax day , is legally a Georgia resident; lives in Georgia on a regular or permanent basis and not as a temporary visitor; or has lived in Georgia for 183 days or more, including part-days, during the 365-day period ending on income tax day.
Income tax day is December 31.
# Who is a taxable nonresident?
A taxable nonresident is any individual who is not a legal resident of Georgia and who regularly engages in activity for financial gain in Georgia during the taxable year. This includes individuals who work in Georgia and who can attribute more than 5% of their wages to Georgia or more than $5,000 of their wages to Georgia. It also includes individuals who receive certain deferred compensation (see O.C.G.A. § 48-7-1(11) for more information).
# What are taxable wages?
Taxable wages include all compensation to an employee for services performed. Payments include salaries, tips, commissions, bonuses, fees, or any other item of value paid to an individual for services performed as an employee.
# What is taxable income?
Taxable income is the income remaining after credit has been given for appropriate allowances and deductions.
J
------------------------------------------------------------------------------~ \\ ------------------------------------------------------------------------------'
# What is a periodic payment?
A periodic payment is a designated distribution from a pension, annuity, or similar f und, that is one of a series of distributions made over th e life expectancy of the participant or for a specified period o f t en years or more.
How is the lookback period determined if the employer used available job tax credits to reduce their withholding taxes during that period?
The liability that was due prior to the application of any job tax credit is included in the aggregate lookback period calculation. For example, an employer with available job tax credits incurred a total withholding tax liability of $100,000 during the lookback period. However, the employer applied $75,000 in job tax credits that resulted in a total withholding tax payment to the Department of Revenue of only $25,000. The employer's total withholding tax liability, used to determine their payer status, is still $100,000.
What is a "lookback period"?
For withholding purposes, a lookback period is defined as the 12-month period that ended the previous June 30th.
# What is a payday?
For withholding tax purposes, a payday is the date on an employee's check or the first day an employee can tender the check for payment or other consideration, whichever comes first.
What is a "one-day rule"?
The "o ne-day rul e" requ ires employers who w i thho l d more than $10 0,000 for the payday to remit tax b y the next banking day. This rule applies to all employers required to withhold tax and takes p riority over all other remittance requirements.
# How is the withholding threshold determined for employers who were not in business during the entire lookback period?
In most cases the filing status will not be changed if an employer did not file a return for any portion of the 12-month lookback period. You should verify the filing status by logging into your account at the Georgia Tax Center (GTC). Filing statuses are determined by the Department.
# If I pay electronically using GTC, when is my payment due?
Electronic payments must be initiated on or before the due date to be considered timely for ACH Debit. For ACH Credit, payments must be submitted by the due date.
# If the due date for making a payment falls on a weekend or holiday, when is the payment due?
The due date is on or before the following business day.
# can i make a payment on a return before i file it?
Yes, you can make a payment for a return before it is filed. can i make multiple payments on one return?
Yes. if i file multiple returns, can i make a single payment?
No.
# How far into the future can I set up a payment?
Estimated payments can be scheduled up to one (1) year in advance. The length of time varies for other payments but is generally up to 30 days from the date you are making the payment.
# Can I cancel an electronic payment?
Payments can be canceled if they are in a pending status. If the payment has been processed, then a refund must be requested.
# Is there a charge to pay on-line?
GTC is free to use if you pay by e-Check or ACH debit. However, if you pay by credit card or PayPal or Venmo, you will have to pay a 2.31% with a $1.00 minimum convenience fee that is charged by the processor.
# If I overpaid my withholding taxes, will I be sent a refund automatically?
No. You must request a refund on GTC if mandated. If not mandated, you still have the option to submit the request through GTC or complete Form IT-550, Claim for Refund, and mail it along with all supporting documentation (copy of amended returns, W-2Cs, corrected 1099s, etc.) to: Georgia Department of Revenue, Withholding Unit, PO Box 105665, Atlanta, GA 30348-5665. All claims are subject to verification.
# How is withholding tax paid?
Tax withheld by employers is paid electronically or mailed with the appropriate form or payment voucher to the address on the form (if the payment is not required to be remitted electronically). If you do not have a form, the GA-V is located on our website at https://dor.georgia.gov/ga-v-withholding-monthly-payment-voucher. Write your withholding number on your check and all correspondence. Tax withheld prior to receipt of a withholding account number is due in accordance with established filing requirements.
# How should semi-weekly employers who pay employees on different days pay and report withholding tax?
Employers must determine a due date for each payroll system. All wages paid during the calendar quarter must be reported on the same Form G-7/Schedule B listing the tax withheld for each pay date of the quarter. For example, if an employer has employees who are paid on a weekly basis and employees who are paid semi-monthly, the employer has a separate remittance liability for each group of employees. However, only one Form G-7/Schedule B is required.
J
------------------------------------------------------------------------------,
# What is the penalty for failing to file a withholding return electronically?
O.C.G.A. § 48-2-44.1 imposes a penalty on a taxpayer who fails to electronically file any withholding tax return that is required to be filed electronically.
- The taxpayer will be considered to have not filed the required return, which is similar to the Internal Revenue Code electronic filing provisions. However, any such taxpayer whose electronic filing was first transmitted on or before the due date of the return, including any extensions, and was rejected, shall be allowed to perfect the electronic filing under rules consistent with those applied by the Internal Revenue Service for rejections of returns which are required to be electronically transmitted or filed.
- The penalty is the greater of $25 for each such return, or 5% of the tax due on each such r e t u r n ( b e f o r e any payments or credits are applied).
- The penalty will not be imposed if the failure to file was due to reasonable cause and not due to gross or willful neglect or disregard for the law.
# Can I file withholding tax returns online for free?
Yes. All available returns can be filed free of charge using GTC.
# Can I cancel a return after it has been filed?
You can cancel a return if it is pending status. After it has been received and processed, you m u s t f i l e a n a m ended return to make corrections.
# What forms can be filed using GTC?
You may file the following withholding tax forms using GTC:
•
Original G-7 forms (For Monthly, Quarterly and Semi-weekly Payers) • Amended G-7 forms (For Monthly, Quarterly and Semi-weekly Payers) • Original G-1003 Income Statement Transmittal • Amended G-1003 Income Statement Transmittal NOTE: If you pay by check or money order, the GA-V Payment Voucher can be completed and printed for mailing to the Department. You do not need to complete this voucher if you pay electronically.
Please see instructional videos at: https://dor.georgia.gov/withholding-videos
# Can I amend a return using GTC?
Yes. To amend, click the appropriate box or button on the screen. Select the tax period and enter the correct amounts. O.C.G.A. § 48-7-104 allows an employer to adjust a prior period on a subsequent return for the same calendar year.
J
J
------------------------------------------------------------------------------~
__ ,>
------------------------------------------------------------------------------· ------------------------------------------------------------------■-----------'
# When filing an amended G-1003 return, what documentation is needed?
All applicable W-2Cs must accompany an amended G-1003. If the refund claim is not required to be submitted electronically and if the amended return results in an overpayment, a copy of the amended Form G-7 for the period in question and applicable W-2Cs (if the year has ended) must be attached to Form IT-550 and mailed to: Attn: Withholding Tax Unit, Georgia Department of Revenue, P.O. Box 105665, Atlanta, GA 30348.
All amended returns are subject to verification. For mandated electronic filers, refund requests must be made on GTC after the amended return is processed and a credit shows on the account.
# Is a return required if no tax is withheld for a given period?
Yes. If a withholding account number is active, Form G-7 must be filed to indicate zero tax withheld. Returns filed after the due date are subject to a late filing penalty. Form GA-V is not required if no tax was withheld during a particular month. O.C.G.A. § 48-7-103
# How are corrections and amendments made to Withholding returns?
Corrections and amendments can be made by submitting a copy of the original return marked "Amended" with an explanation of the indicated changes or on GTC if the returns are required to be submitted electronically. If a copy of the return is unavailable, changes can be reported by letter or as an adjustment on the "Adjustment to Tax" line of Form G-7.
Amendments will not be allowed if a reason for the change is not provided. O.C.G.A. § 48-7-104
# How does an employer claim a refund of tax withheld?
Employers should submit through GTC if mandated. If not mandated, employers have the option to submit through GTC or complete Form IT-550 to claim a refund of withholding tax by mail. An amended return should be filed on GTC or mailed to the address on the form. Mail the form with copies of the amended return and applicable W-2Cs (if the taxable year has ended) to Withholding Tax Unit, Georgia Department of Revenue, P.O. Box 105665, Atlanta, GA 30348.
# How do employers calculate the amount of tax to withhold?
The amount of tax to withhold is based on wages, number of allowances, and additional withholding amounts as indicated on Form G-4 Employee's Withholding Allowance Certificate or Form G-4P Withholding Certificate for Pension and Annuity Payments.
Employers can use the Withholding Tax tables found on pages 28-47 in this document or the percentage method to determine the amount of tax to withhold. O.C.G.A. § 48-7-101
J
------------------------------------------------------------------------------, ······----------------------------------············-----·············-······· '
# What is the difference between the tax tables and the percentage method?
The tax tables calculate withholding tax based on an income range. Applicable standard deductions and allowances are factored into the tables. The percentage method calculates withholding tax based on a specific dollar amount. Taxable income is derived by reducing gross wages by the appropriate deductions. As a result, tax amounts derived from one method will differ slightly from those derived f rom the other.
# What is the withholding rate on bonuses and other compensation? O.C.G.A. § 48-7-101(f)(5)
For tax year 2026, bonuses and other compensation are subject to Georgia withholding at the applicable income tax rate in effect at the time the compensation is paid. Employers must continue to withhold at the rate of 5.19% before the effective date of the rate change and may begin withholding at the new rate of 4.99% starting May 11, 2026.
# How is withholding calculated if an employee fails to submit a Form G-4?
Employers can use the federal election to determine state income tax withholding if sufficient information is available to do so. Otherwise, employers should withhold as if the employee is single with zero allowances. O.C.G.A. § 48-7-102
# How do employers register for withholding?
Employers can register for a withholding number by going to GTC at https://gtc.dor.ga.gov.
# Do I need a new withholding number to use GTC?
No. If you already have a Georgia withholding number, you should continue using it. If you do not have a number, you can register for one on GTC by visiting https://gtc.dor.ga.gov.
# Do I need to register to use GTC?
Yes. If you have already filed a return with a withholding number, you c an request a web logon.
You must know your account type, tax-specific identification number(s), zip code of the location address, and most recent return payment to access the system. Visit our website at https://dor.georgia.gov/help-georgia-tax-center for more information.
# What happens after the registration application is processed?
Employers will receive notification of their assigned withholding number and filing frequency via GTC within 15 minutes.
No. Employers must register first. Then they must file and pay with a valid withholding number.
# How do employers register for EFT?
Please visit our website at https://dor.georgia.gov/eft-002-georgia-ach-credit-taxpayerregistration-authorization-form.
# Can I file without a withholding number?
J
J
------------------------------------------------------------------------------, ······---············---------------········-------------········-·----·······' ------------------------------------------------------------------------------~
__ ,>
# NONRESIDENTS
-
# Should employers withhold Georgia income tax from wages earned by a nonresident?
Yes. Employers must withhold state income tax from wages earned in Georgia by nonresident employees working in this state if more than 5% of their total earned income is attributable to Georgia, or if more than $5,000 of their wages are attributable to Georgia.
O.C.G.A. § 48-7-100(10) (K); O.C.G.A. § 48-7-1
# Should employers withhold tax from wages earned by Georgia residents working in another state?
Georgia residents are subject to the withholding tax laws of the state in which they work. If that state does not require withholding, tax should be withheld and paid to Georgia.
O.C.G.A. § 48-7-100(10) (H)
# What if an employee fails to file a Form G-4?
Employers can use information contained on Form W-4 if it is sufficient to allow for the calculation of state income tax withholding. If sufficient information is not available, employers should calculate withholding as if the employee is single with zero allowances. O.C.G.A. § 48-7-102
# Should an employer honor a G-4 claiming exempt from withholding or more than 14 allowances?
Yes. Employers will honor the properly completed form as submitted unless notified by the Georgia Department of Revenue. Forms claiming more than 14 allowances or exempt from withholding must be mailed to the Georgia Department of Revenue, Taxpayer Services Division, P.O. Box 105685, Atlanta, GA 30348-5685. The Department will no longer issue written correspondence for any Form G-4 submissions received unless the certificate should not be honored.
As an employer, please maintain a copy of Form G-4 for your records. Such forms remain in effect until changed or until February 15 of the following year. Employers who know that a G-4 is erroneous should not honor the form and should withhold as if the employee is single claiming zero allowances until a corrected form has been received.
# What information must employees provide to their employers?
Employees are required
O.C.G.A. § 48-7-102(c)
------------------------------------------------------------------------------------------------------------. :
-. ---. ---. -... -·· ----. --------. ---------.. -------------. ----. -. ----------.. -... -. -----------.. ------. -------,/
# How can employees obtain a copy of Form G-4?
Employees can obtain Form G-4 from their employers or from our website a t https://dor.georgia.gov/form-g-4-employee-withholding
# Should employees file Form G-4 and Form W-4?
Yes. Employees should file each form for state and federal withholding.
O.C.G.A. § 48-7-102(c)
# Can employees change their Form G-4?
Yes. Employees can update their Form G-4 as often as they wish. A new Form G-4 becomes effective with the first payroll period after the fo rm is received by the employer and remains in effect until another form is submitted. O.C.G.A. § 48-7-102(c)(3)
# Is there a limit to the number of allowances an employee can claim on Form G-4?
No. Forms claiming more than 14 allowances or exempt from withholding must be mailed to the
# Georgia Department of Revenue, Taxpayer Services Division, P.
O . Box 105685, Atlanta, GA 3 348-5685 for a p proval. The Department will no longer issue written correspondence for any For m G-4 submissions received unless the certificate should not be honored. As an employer, please maintain a copy of Form G-4 for your records. Employers will honor the properly complete d form as submitted unless notified by the Department. Employers who know that a G-4 is erroneous should not honor the form and should withhold as if the employee is single claiming zero allowances until a corrected form has been received. Lexis Nexis webpage for Georgia Tax Codes.
O.C.G.A. § 48-7-102; O.C.G.A. § 48-7-102.1; R eg 560-7-4-.03
# Can employees request an additional amount of tax withheld?
Yes. Employees can indicate their desire to have a specific tax amount withheld by completing the area marked "Additional Withholding" on Form G-4.
O.C.G.A. § 48-7-101(f) (3)
# Can an employee or recipient of pension or annuity payments elect not to have tax withheld?
Yes, in some circumstances. Employees can indicate their preference not to have tax withheld on Form G-4 if the stated requirements are met. Recipients of pension or annuity payments can make their election on Form G-4P. O.C.G.A. § 48-7-101(g); O.C.G.A. § 48-7-101(h)
# How should employers submit requests to file annually?
Employer requests to update their filing frequency must be made on the Georgia Tax Center.
Requests also can be mailed to the Taxpayer Services Division, P. O. Box 105499, Atlanta, GA 30359. A copy of the payroll records should be included as proof that the requirement for annual filing has been met. To qualify as an "Annual payer", an employer must have withheld or was required to withhold $800.00 or less in the aggregate for the lookback period.
J
# How long must employers retain payroll records?
Employers must retain payroll records for at least four (4) years after tax is due or paid, whichever is later. O.C.G.A. § 48-7-111
# How do employers report changes in their business?
Employers can report changes in their business through their GTC account or by submitting a letter to the Taxpayer Services Division, P.O. Box 105685, Atlanta, GA 30348-5685.
# Are employers required to submit copies of income statements to the Georgia Department of Revenue?
Yes. Employers are required to submit copies of W-2, 1099, and other income statements with Form G-1003 reflecting payments that are subject to Georgia income tax withholding. A substitute form is acceptable provided state wage and tax information is included. Statements should be mailed to Georgia Department of Revenue, Processing Center, P.O. Box 105685, Atlanta, GA 30348-5685 or submitted through GTC if required to do so. Lexis Nexis webpage for Georgia Tax Codes.
O.C.G.A. § 48-7-106
# Does Georgia participate in the Combined Federal/State Filing Program?
Yes. However, only non-wage statements reporting payments that did not have Georgia income tax withheld can be filed under this program. All statements containing Georgia income tax withholding must be reported directly to the Department of Revenue.
# Who is required to file electronically?
If you are mandated to file and pay electronically, you must file the G-1003 and related income statements electronically.
Employers who are federally required to file income statements electronically must file them electronically for Georgia purposes. Additionally, Please see instructional videos below: https://dor.georgia.gov/file-g-1003-using-gtc-online-entry-video https://dor.georgia.gov/how-create-g-1003-csv-file-video
# What is the due date for submitting income statements to the Department of Revenue?
All W-2s and 1099 NECs (1099's where Georgia tax was withheld) are due by January 31 for the preceding year. All other income statements are due by February 28 for the preceding calendar year. If that date is a weekend or holiday, statements are due on the next business day. If a business closes or ceases to have employees during the taxable year, income statements are due with the final return within 30 days after that date. Lexis Nexis webpage for Georgia Tax Codes.
O.C.G.A. § 48-7-106(a)
# What is the due date for providing income statements to employees?
Income statements showing wages paid and tax withheld must be provided to employees no later than January 31 for the preceding year. O.C.G.A. § 48-7-105
# How can employers and payers obtain blank copies of income statements?
Employers and payers can request blank copies of income statements by telephoning the IRS at 1-800-829-3676 or visiting the IRS website at www.irs.gov. Income statements published by Georgia DOR can be obtained on our website at dor.georgia.gov.
# When are income statements due if a business closes before December 31?
Income statements are due within 30 days after payment of final wages if a business closes during the taxable year. Employers may submit a written extension request if additional time is needed.
O.C.G.A. § 48-7-106
# What are the requirements for reporting corrected income statements?
Corrected statements should be filed in accordance with the criteria for original reports. A transmittal form should be included indicating that the report contains corrected information.
What income statements are not required to be sent to the Georgia Department of Revenue by the employer or issuer?
Form 1099s that do not indicate Georgia state income tax withheld or W-2s whose employer does not have a withholding number and is not required to withhold state income tax from their employees, are not required to be submitted to the Georgia Department of Revenue by the employer or issuer.
Please note, Form 1099-K must be submitted even if there is no Georgia state income tax withheld. See Regulation 560-3-2-.26 for more information about Form 1099-K.
# How long are employers required to retain income statements?
Employers must retain income statements, or be able to recreate the data, for at least four years after the due date of the report or the date the report was filed, whichever is later.
O.C.G.A. § 48-7-111
How is withholding reported on individuals who have not provided a valid taxpayer identification number?
Withholding is required at the rate of 6 percent of the amount of compensation paid for labor services (which means the physical performance of services in this state) to an individual when the compensation is reported on Form 1099 NEC and when the individual has: a. Failed to provide a taxpayer identification number. b. Failed to provide a correct taxpayer identification number which is determined in the same manner as provided for in Section 3406 of the Internal Revenue Code and regulations thereunder; or c. Provided an Internal Revenue Service issued taxpayer identification number issued for nonresident aliens. O.C.G.A. § 48-7-101
# How should employers and payers report qualified overtime compensation and qualified cash tips?
For 2026, Overtime and Tips will be reported on the W2 and other income statements with the G-1003. Follow the IRS instructions to complete box 12, using the appropriate codes.
The annual G-1003 totals should reconcile to the employee or payee level income statements submitted to the Department. Amounts must be reported using the applicable federal income statement fields, including W-2 fields and codes for employees, Form 1099-NEC boxes 1b, 1c, and 1d, and Form 1099-MISC boxes 13a, 13b, and 14 where applicable.
If an employer or payer discovers an error after filing, corrected income statements must be filed with an amended Form G-1003. If the correction affects Georgia tax withheld for a prior period, the employer or payer must also file the applicable amended Form G-7.
When reporting this information, DO NOT account for the $1,750 amount for either Overtime Compensation or Cash Tips. The employee should make this adjustment on their Georgia Individual Income Tax return.
Any withholding agent who fails to comply with the withholding requirements of this subsection shall be liable for the taxes required to have been withheld unless such withholding agent is exempt from federal withholding with respect to such individual pursuant to a properly filed Internal Revenue Service Form 8233 and has provided a copy of such form to the Georgia Department of Revenue at the following address:
# FILM CREDIT WITHHOLDING
What is the film withholding registration requirements for a film production company, production company or qualified interactive entertainment production company?
A film production company, production company or qualified interactive entertainment production company that makes payments to a loan out company must electronically register at https://gtc.dor.ga.gov to obtain a withholding film account. Additional filing and reporting requirements are explained at https://dor.georgia.gov/withholding-instructions.
How often must a film production company, production company or qualified interactive entertainment production company file a film withholding return?
A return must be electronically filed for each calendar quarter.
# How are withholding payments remitted to the Georgia Department of Revenue?
Payments must be electronically remitted using ACH Debit or ACH Credit as outlined in
Regulation 560-3-2-.26.
# What is the due date for filing and remitting the film withholding?
The due date for such filing and remittance shall be the last day of the month following the calendar quarter in which the withholding payments w ere required to be made.
# Are there any forms to provide to the loan-out company reflecting payments made?
The production company or qualified interactive entertainment production company must J ----- annually -------------------------------------------------------------------------, complete Form G2-FP and provide it to the loan out company by January 31st of the year following the calendar year in which the withholding payments were made. The G2-FP ·······························---············--------------------············' is not submitted to the Commissioner. The Commissioner receives this information when the production company files its quarterly return. The G2-FP can be found here: https://dor.georgia.gov/g2-fp
# I am a loan out company. What are my registration requirements?
The loan-out company must register for a payroll withholding account electronically at https://gtc.dor.ga.gov. Additional filing and reporting requirements are explained at https://dor.georgia.gov/withholding-instructions.
# What are my payroll filing requirements?
The loan-out company must electronically file Form G-1003 on or before February 28th of the following calendar year.
# As a loan out company, are there any other payroll forms that we are required to submit?
Yes, as part of the annual Form G-1003 electronic submission, you should also attach all Forms G2-FL for the reporting calendar year. The G2-FL transfers the G2-FP loan out withholding to the employees of the production company. The G2-FP amounts cannot be claimed on the loan out company's income tax return. Please see the following for more information: https://dor.georgia.gov/how-claim-wit hholding -reported -g2-fp-and-g2-fl
- Please note * You must send a copy of the Form G2-FL to each employee. The employee must attach Form G2-FL to their individual tax return.
Where can more information about the Form G2-FP and Form G2-FL processes be found? https://dor.georgia.gov/how-claim-withholding-reported-g2-fp-and-g2-fl
# What are jeopardy returns?
Jeopardy returns are those returns believed to be in danger of not being submitted. The Commissioner of Revenue may require an employer to file such returns and remit the required tax at any time. O.C.G.A. § 48-7-103(c)
# Is withholding required on lottery winnings?
Yes. Winnings of more than $5,000 paid by the Georgia Lottery Commission are subject to withholding at the rate of 4.99% of the total amount won.
O.C.G.A. § 48-7-101(f) (7)
2007 HB 515 Section 4 (b) states:
"The right of a person to a prize payable by the corporation in installment payments may be voluntarily assigned as a whole or in part if the assignment is made to a person designated in accordance with an order of the superior court in the county where the corporation is located. In the case of a voluntary assignment for consideration made under a J ------------------------------------------------------------------------------------------------------------· judicial order, the assignee shall withhold from the purchase price to be paid to the assignor federal and state income taxes in a manner and amount consistent with the ------------------------------------------------------------------------------------------------------------/ procedures of the corporation and pay such withheld taxes to the proper taxing authority in a timely manner and maintain and file all required records, forms, and reports."
Please follow the process below:
- Withholding will be 4.99% of the purchase price.
- The amount is due within 10 days of the purchase date.
- Form G2-LP should be included with your payment.
# Are periodic pension and annuity payments subject to withholding?
Yes. Periodic payments are subject to withholding and must be remitted to the Department of Revenue in the same manner as employee withholding, unless the recipient elects not to have tax withheld. Recipients should indicate their withholding preferences by submitting Form G-4P to the payer. O.C.G.A. § 48-7-101(h); Reg 560-7-4-.32
# Are non-periodic pension and annuity payments subject to withholding?
Upon the election by a payee of any non-periodic payment or distribution from a pension, annuity or similar fund, the payor shall withhold from such payment the amount specified by the payee, but in no event shall the amount withheld be less than the amount which would be required to be withheld if such payment w ere a payment of wages by an employer to an employee for the appropriate payroll period. O.C.G.A. § 48-7-101 What are the withholding requirements for nonresident distributions for partnerships, limited liability companies, and Subchapter S corporations?
Nonresident Distributions - Withholding at a rate of 4% is required for nonresident members of partnerships, limited liability companies, and Su bchapter S corporations. Registration for a withholding number is required. This is a different number from the number used to report tax withheld from wages. Form G2-A must be provided to the recipients no later than the date the entity's income tax return is filed or the due date of the entity's income tax return excluding extensions. Payments must be submitted electronically (if mandated) or mailed with the appropriate Form G7 on or before the due date for filing the entity's income tax return excluding extensions. O.C.G.A. § 48-7-129
# What are the withholding requirements for nonresident real property sales or transfers?
Sale or Transfer of Real Property - Withholding at a rate of 3% is required on the sale or transfer of real property and associated tangible personal property in Georgia by nonresidents. Payment must be accompanied by Form G2-RP and appropriate documentation related to the sale. O.C.G.A. § 48- 7-128 Can nonresident withholding be transferred to partners, members, or shareholders of a flow through entity and how should it be documented?
Yes. Nonresident withholding may be passed through each tier of a flow-through entity. To claim the withholding credit, the entity must attach the applicable Form G2-RP or Form G2-A provided by the entity that withheld the tax and complete the allocation schedule on page 2 of that form.
The allocation schedule must identify each partner, member, or shareholder receiving a portion of the withholding credit and show the amount allocated to each recipient based on the applicable profit/loss percentage. Failure to attach the required form and complete the page 2 allocation schedule will result in disallowance of the withholding credit.
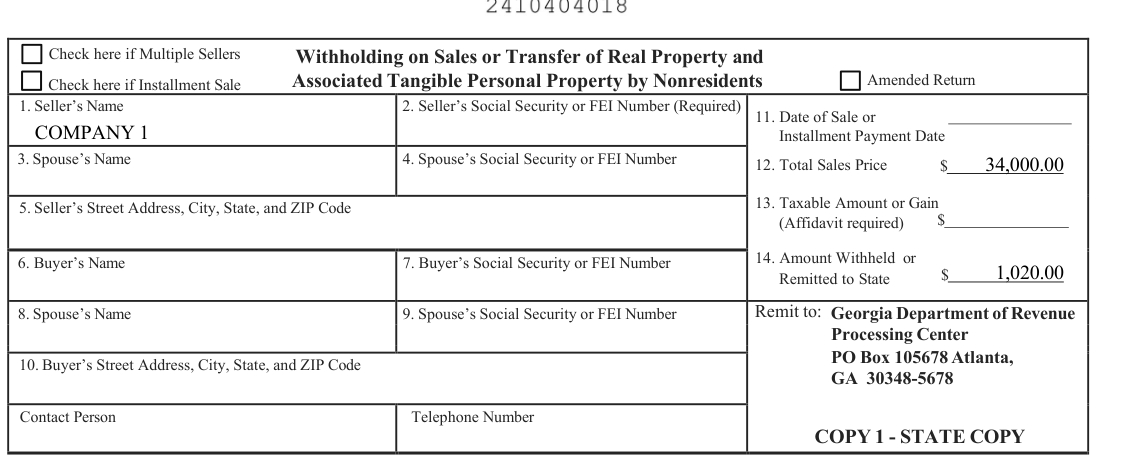
If withholding credit is being claimed on a return, documentation showing withholding must be submitted with the return (Individual Income GA 500, Composite IT-CR, Corporate GA 600 and S-Corporation GA 600S, Partnership GA 700, and Fiduciary GA 501). Failure to include this documentation will result in disallowance of withholding credit and delay or denial of the refund if requested. The following example illustrates this:
# Form G2-RP (Rev. 06/01/23)
■
Text version of this table
I I Check here if Multiple Sellers Withholding on Sales or TransferI oIfI RIe al I PrI o pIelrlt yI al nl d Check here if Installment Sale Associat1ed1 1T1an1g1ib1l1e 1P1er1s1on1a1l1 Property by Nonresidents Amended Return 1. Seller’s Name COMPANY 1 2. Seller’s Soc2ia4l S1ec0ur4ity0 o4r F0E1I N8u mber (Required) 11. Date of Sale or Installment Payment Date 12. Total Sales Price $ 34,000.00 □ 13. Taxable Amount or Gain (Affidavit required) $ 14. Amount Withheld or Remitted to State $ 1,020.00 3□. Sp ouse’s Name □ 4. Spouse’s Social Security or FEI Number 5. Seller’s Street Address, City, State, and ZIP Code 6. Buyer’s Name 7. Buyer’s Social Security or FEI Number 8. Spouse’s Name 9. Spouse’s Social Security or FEI Number Remit to: Georgia Department of Revenue Processing Center PO Box 105678 Atlanta, GA 30348-5678 COPY 1 - STATE COPY 10. Buyer’s Street Address, City, State, and ZIP Code Contact Person Telephone Number
# Associated Tangible Personal Property by Nonresidents
- Seller's Social Security or FEI Number (Required)
- Seller's Name
- Spouse's Name 4. Spouse's Social Security or FEI Number □
- Seller's Street Address, City, State, and ZIP Code
- Buyer's Name 7. Buyer's Social Security or FEI Number
- Spouse's Name 9. Spouse's Social Security or FEI Number
- Buyer's Street Address, City, State, and ZIP Code Contact Person Telephone Number
- Date of Sale or
- Total Sales Price $
□
- Taxable Amount or Gain
- Amount Withheld or
COPY 1 - STATE COPY
As reflected on the above G2-RP, Company 1 had $1020.00 withheld.
Company 1 passed withholding of $1020.00 to Company 2.
Company 2 passed withholding of $1020.00 to its members/partners based on their profit/loss percentage as follows:
# Partner Identifying Information
# Number
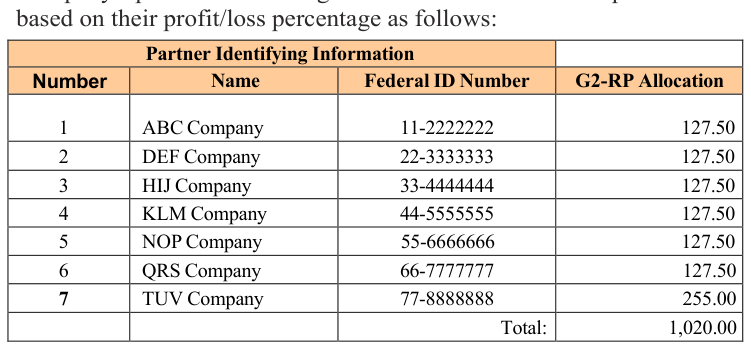
Text version of this table
| Partner Identifying Information | |||
| Number | Name | Federal ID Number | G2-RP Allocation |
| 1 | ABC Company | 11-2222222 | 127.50 |
| 2 | DEF Company | 22-3333333 | 127.50 |
| 3 | HIJ Company | 33-4444444 | 127.50 |
| 4 | KLM Company | 44-5555555 | 127.50 |
| 5 | NOP Company | 55-6666666 | 127.50 |
| 6 | QRS Company | 66-7777777 | 127.50 |
| 7 | TUV Company | 77-8888888 | 255.00 |
| Total: | 1,020.00 |
# G2-RP Allocation
# Partner Identifying Information
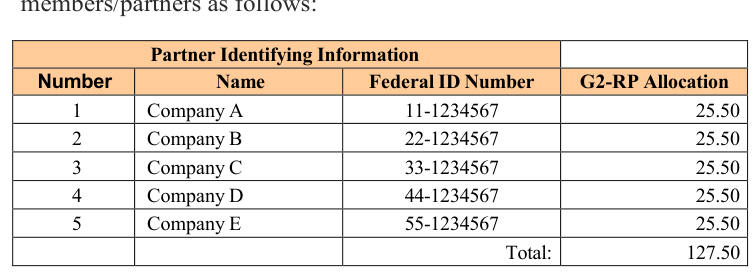
Text version of this table
| Partner Identifying Information | |||
| Number | Name | Federal ID Number | G2-RP Allocation |
| 1 | Company A | 11-1234567 | 25.50 |
| 2 | Company B | 22-1234567 | 25.50 |
| 3 | Company C | 33-1234567 | 25.50 |
| 4 | Company D | 44-1234567 | 25.50 |
| 5 | Company E | 55-1234567 | 25.50 |
| Total: | 127.50 |
# Partner Identifying Information
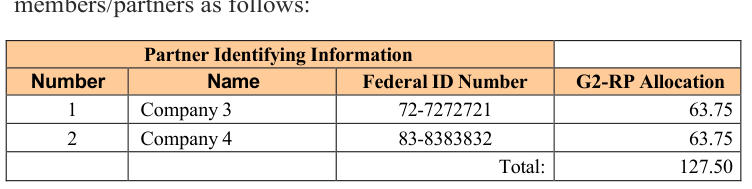
Text version of this table
| Partner Identifying Information | |||
| Number | Name | Federal ID Number | G2-RP Allocation |
| 1 | Company 3 | 72-7272721 | 63.75 |
| 2 | Company 4 | 83-8383832 | 63.75 |
| Total: | 127.50 |
# Partner Identifying Information
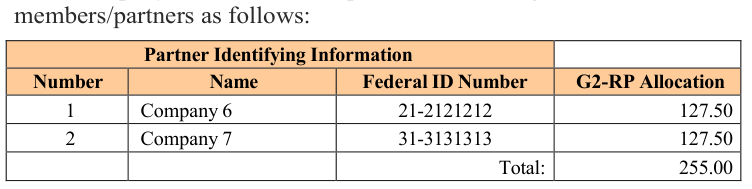
Text version of this table
Partner Identifying Information Number Name Federal ID Number G2-RP Allocation 1 Company 6 21-2121212 127.50 2 Company 7 31-3131313 127.50 Total: 255.00
QRS Company EIN 66-7777777 passed withholding of $127.50 to its members/partners as follows:
TUV Company EIN 77-8888888 passed withholding of $255.00 to its members/partners as follows:
# Is withholding required on wages paid to domestic workers?
No. Withholding is not required on wages paid to housekeepers, nannies, farm laborers, or ministers, provided that the recipient of the service is the employer. However, employers can elect to withhold f rom such wages. O.C.G.A. § 48-7-100(10)
# Are there special requirements for withholding on severance pay?
Withholding should be treated the same as employee withholding if the person is a Georgia resident when the payment is made. If the person is not a Georgia resident when the payment is made, Georgia income tax withholding does not apply.
O.C.G.A. § 48-7-101(f)(5)
# Are contributions to qualified 401(k), profit sharing, or deferred compensation plans taxable?
No. Georgia follows the federal guidelines governing such plans. Contributions must be deducted from gross wages prior to the calculation of taxable income.
O.C.G.A. § 48-7-27
J
------------------------------------------------------------------------------· ----------------------------------------·········---·······-------·-······----·
# What is required if a business ceases to have employees or changes its structure?
When a business c e a ses to h ave employees or und e rgoes a s t r ucture change th a t require s a new Georgia withholding payroll number, the employer must file a final Form G-7 and pay any tax withheld wit h i n 30 days of the date the change occurs. Copies of applicable income statements should be file d w i t h t h e final return. If th e structure change result s in a new FEIN/E IN or other wi se r equires a ne w withholding payroll number, the employer should close the prior withholding account and r e g ister the business under the new structure before co ntin uing withholding acti vity. Lexis Nexis webpage for Georgia Tax Codes. Rules and Regulations of the State of Georgia webpage for Chapter 560-7.O.C.G.A. § 48-7-106; Reg 560-7-8-.33 The IRS has provided guidance for employment taxes with respect to a single member LLC that is disregarded as an entity that is separate from its owner. Does Georgia follow these provisions?
Yes. Accordingly, beginning with wages paid in 2009, such single member LLC must pay its own employment taxes and file its own tax reports for Federal and Georgia purposes.
# Are penalty and interest assessed for late payment of tax withheld or late filing?
A penalty of $25.00 plus 5% of the tax due on the return is imposed for late payment and 5% of the tax due (before applying any payments or credits) for late filing. Penalties accrue monthly, or a fraction thereof, not to exceed $25.00 plus 25% of the tax due before applying any payments or credits. For monthly interest periods beginning before July 1, 2016, interest accrues at the rate of 1% per month, or fraction thereof, until payment is received. For monthly interest periods beginning on or after July 1, 2016, the yearly interest rate will change to the Federal Reserve prime rate plus 3% and updated each January. This is in addition to any other applicable penalties.
O.C.G.A. § 48-7-126(c); O.C.G.A. § 48-2-40
# Are penalty and interest assessed for underpayment of tax withheld?
A penalty of 5% and interest is assessed on payments not adjusted in accordance with Code Section 48-7-104. Penalty should not exceed $25.00 plus 25% of the tax due; interest accrues until the tax is paid in full. O.C.G.A. § 48-7-126
# What is the penalty if a taxpayer who is mandated to pay electronically fails to do so?
A penalty of 10% will be applied to the amount of tax due for any timely payment that is not remitted via EFT. This penalty is in addition to other applicable penalties and interest prescribed under
# O.C.G.A. §§ 48-2-32 and 48-7-126.
What penalties are assessed against payors if they fail to provide W-2s or 1099s to payees by the required time?
(1) Ten dollars per statement filed up to 30 calendar days after the date such statement is due, provided that the total amount imposed on a person pursuant to this paragraph shall not exceed $50,000;
(2) Twenty dollars per statement filed at least 31 calendar days, but not more than 210 calendar days after the date such statement is due, provided that the total amount imposed on a person pursuant to this paragraph shall not exceed $100,000; or (3) Fifty dollars per statement filed 211 calendar days or more after such statement is due, provided that the total amount imposed on a person pursuant to this paragraph shall not exceed $200,000.
What penalties are assessed against payors if they fail to file W-2s or 1099s with the Department by the required time?
(1) Ten dollars per statement filed up to 30 calendar days after the date such statement is due, provided that the total amount imposed on a person pursuant to this paragraph shall not exceed $50,000;
(2) Twenty dollars per statement filed at least 31 calendar days, but not more than 210 calendar days after the date such statement is due, provided that the total amount imposed on a person pursuant to this paragraph shall not exceed $100,000; or
(3) Fifty dollars per statement filed 211 calendar days or more after such statement is due, provided that the total amount imposed on a person pursuant to this paragraph shall not exceed $200,000.
# What other penalties are assessed against employers?
Failure to remit electronic payment when required - 10% of tax due Failure to report nonresident distributions - 25% of tax due plus interest Failure to withhold tax - $10.00 per quarter for each employee Fraudulent withholding receipt
- $50.00 for each fraudulent receipt Willful failure to comply with code sections governing withholding tax filing and payment is a misdemeanor.
O.C.G.A. § 48-7-126; O.C.G.A. § 48-7-127; O.C.G.A. § 48-2-32; O.C.G.A. § 48-7-129
# How are employers notified of penalty and interest assessments?
Employers who file late returns or remit late payments are provided assessment notices by first class mail to their last known address as shown on Department records. The notice will become final if a written appeal is not filed within 45 days of the date of the notice. O.C.G.A. § 48-2-45
# Can employers protest penalty and interest assessments?
Yes. Employers should submit through GTC or the Protest of Proposed Assessment or Refund Denial (Form TSD-1). Collection attempts will be suspended until the protest has been resolved. O.C.G.A. § 48-2-46
# Can employers request a waiver of the assessed penalty?
Yes. Employers can request a penalty waiver through GTC or by submitting a written explanation of the reason for late payment, which must include a specific waiver request statement.
O.C.G.A. § 48-2-43
# Can employers request a waiver of assessed interest?
Interest can only be waived if it is determined that the delay in payment was caused by the action or inaction of the Department. O.C.G.A. § 48-2-41
J
----------------------------------\
(1) Effective May 1, 2006, employers who are required to pay withholding tax by electronic funds transfer must also file returns electronically. Employers may also voluntarily file electronically.
(2) I do not have my withholding account number. Should I mail in my payment to the Georgia
# Department of Revenue?
No, you must first register for a withholding account electronically at https://gtc.dor.ga.gov.
You will receive your withholding number within 15 minutes.
Once you have obtained your withholding account number you may file and/or remit your payment electronically.
(3) I am a third-party payroll provider and our client has not provided us with a withholding account number. May we mail the payment in?
No. Either the client or a va Important: If a third-party payroll provider has more than 250 employers, they MUST pay the taxes by ELECTRONIC FUNDS TRANSFER as provided by Lexis Nexis webpage for Georgia Tax Codes.
O.C.G.A. § 48-2-32.
(4) File Form G-7 timely even if there is no tax withheld. Late returns are subject to a penalty. It is not necessary to file Form GA-V if no tax is withheld.
(5) Before mailing a reporting form, verify the withholding number, tax period, tax due, and tax paid.
(6) You must notify the Department to deactivate your withholding account number or report changes to your business. Changes may be made through your GTC account. You may also submit the information via e-mail to withholding.issues@dor.ga.gov.
(7) You must apply for a new withholding account number if you purchase an ongoing business or change the structure of your business. Contact the Department at 1-877-423-6711 before you begin making payments using a withholding number that was previously deactivated.
(8) Continue to file returns while your withholding number is active. You may deactivate your number once you cease to meet withholding requirements.
# FILING TIPS
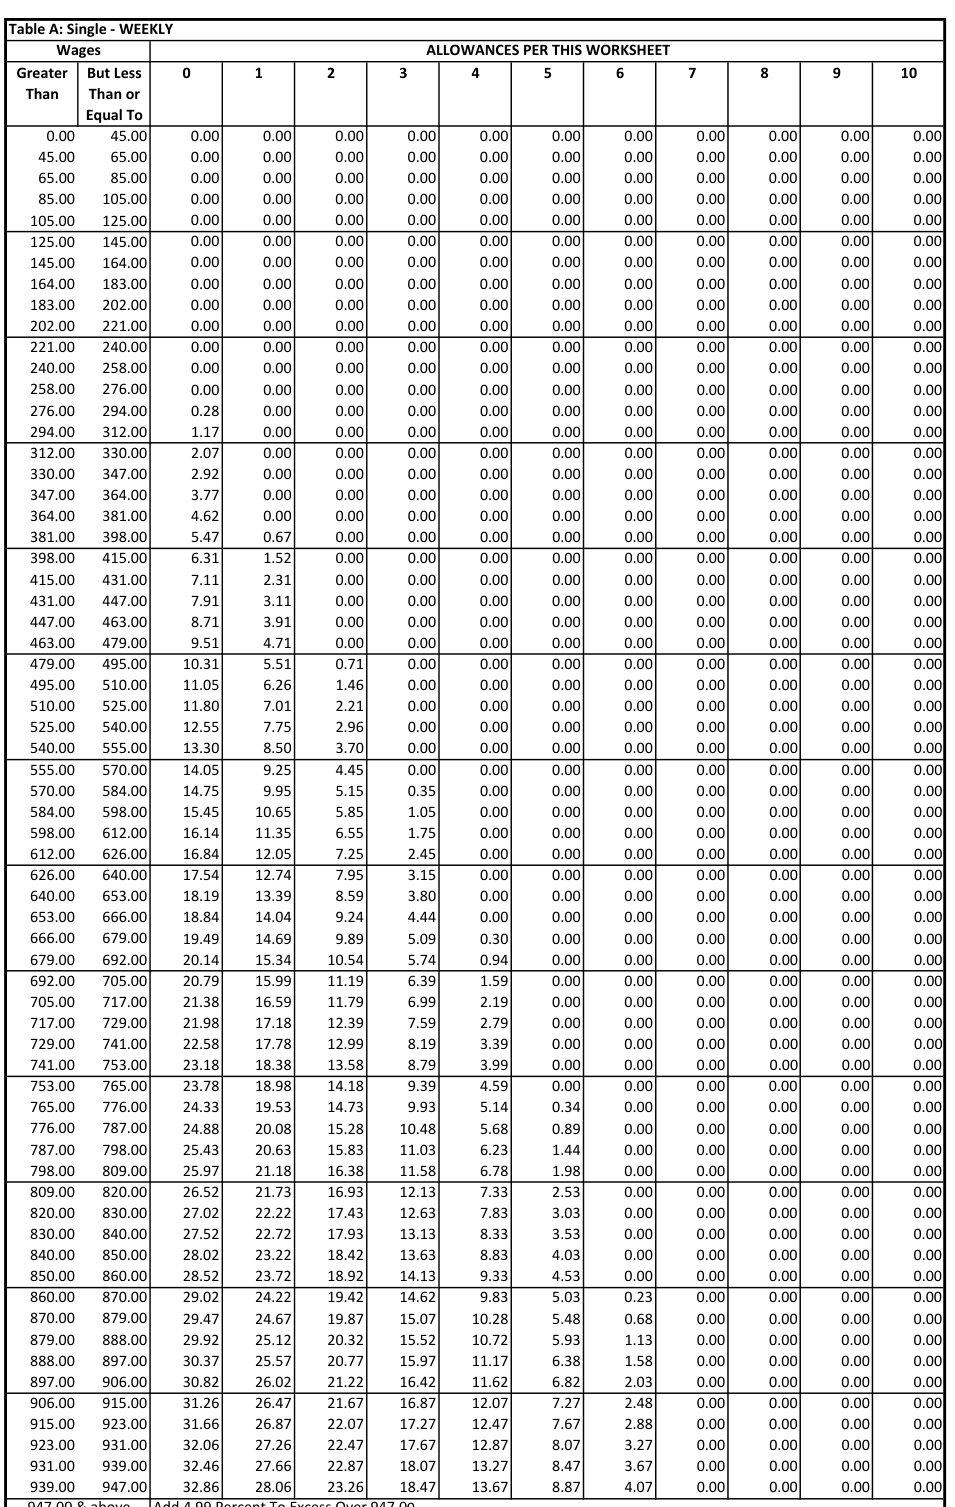
Text version of this table
| Wages | ALLOW | ANCES PER | THIS WOR | KSHEET | |||||||||
| eater Bu | t | Less | 0 | 1 | 2 | 3 | 4 5 | 6 | 7 | 8 | 9 | 1 0 | |
| han Th | a | n or | |||||||||||
| Eq | u | al To | |||||||||||
| 0.00 | 45.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 45.00 | 65.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 65.00 | 85.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 85.00 | 1 | 05.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 105.00 | 1 | 25.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 125.00 | 1 | 45.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 145.00 | 1 | 64.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 164.00 | 1 | 83.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 183.00 | 2 | 02.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 202.00 | 2 | 21.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 221.00 | 2 | 40.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 240.00 | 2 | 58.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 258.00 | 2 | 76.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 276.00 | 2 | 94.00 | 0.28 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 294.00 | 3 | 12.00 | 1.17 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 312.00 | 3 | 30.00 | 2.07 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 330.00 | 3 | 47.00 | 2.92 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 347.00 | 3 | 64.00 | 3.77 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 364.00 | 3 | 81.00 | 4.62 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 381.00 | 3 | 98.00 | 5.47 | 0.67 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 398.00 | 4 | 15.00 | 6.31 | 1.52 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 415.00 | 4 | 31.00 | 7.11 | 2.31 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 431.00 | 4 | 47.00 | 7.91 | 3.11 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 447.00 | 4 | 63.00 | 8.71 | 3.91 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 463.00 | 4 | 79.00 | 9.51 | 4.71 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 479.00 | 4 | 95.00 | 10.31 | 5.51 | 0.71 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 495.00 | 5 | 10.00 | 11.05 | 6.26 | 1.46 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 510.00 | 5 | 25.00 | 11.80 | 7.01 | 2.21 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 525.00 | 5 | 40.00 | 12.55 | 7.75 | 2.96 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 540.00 | 5 | 55.00 | 13.30 | 8.50 | 3.70 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 555.00 | 5 | 70.00 | 14.05 | 9.25 | 4.45 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 570.00 | 5 | 84.00 | 14.75 | 9.95 | 5.15 | 0.35 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 584.00 | 5 | 98.00 | 15.45 | 10.65 | 5.85 | 1.05 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 598.00 | 6 | 12.00 | 16.14 | 11.35 | 6.55 | 1.75 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 612.00 | 6 | 26.00 | 16.84 | 12.05 | 7.25 | 2.45 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 626.00 | 6 | 40.00 | 17.54 | 12.74 | 7.95 | 3.15 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 640.00 | 6 | 53.00 | 18.19 | 13.39 | 8.59 | 3.80 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 653.00 | 6 | 66.00 | 18.84 | 14.04 | 9.24 | 4.44 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 666.00 | 6 | 79.00 | 19.49 | 14.69 | 9.89 | 5.09 | 0.30 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 679.00 | 6 | 92.00 | 20.14 | 15.34 | 10.54 | 5.74 | 0.94 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 692.00 | 7 | 05.00 | 20.79 | 15.99 | 11.19 | 6.39 | 1.59 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 705.00 | 7 | 17.00 | 21.38 | 16.59 | 11.79 | 6.99 | 2.19 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 717.00 | 7 | 29.00 | 21.98 | 17.18 | 12.39 | 7.59 | 2.79 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 729.00 | 7 | 41.00 | 22.58 | 17.78 | 12.99 | 8.19 | 3.39 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 741.00 | 7 | 53.00 | 23.18 | 18.38 | 13.58 | 8.79 | 3.99 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 753.00 | 7 | 65.00 | 23.78 | 18.98 | 14.18 | 9.39 | 4.59 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 765.00 | 7 | 76.00 | 24.33 | 19.53 | 14.73 | 9.93 | 5.14 | 0.34 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 776.00 | 7 | 87.00 | 24.88 | 20.08 | 15.28 | 10.48 | 5.68 | 0.89 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 787.00 | 7 | 98.00 | 25.43 | 20.63 | 15.83 | 11.03 | 6.23 | 1.44 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 798.00 | 8 | 09.00 | 25.97 | 21.18 | 16.38 | 11.58 | 6.78 | 1.98 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 809.00 | 8 | 20.00 | 26.52 | 21.73 | 16.93 | 12.13 | 7.33 | 2.53 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 820.00 | 8 | 30.00 | 27.02 | 22.22 | 17.43 | 12.63 | 7.83 | 3.03 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 830.00 | 8 | 40.00 | 27.52 | 22.72 | 17.93 | 13.13 | 8.33 | 3.53 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 840.00 | 8 | 50.00 | 28.02 | 23.22 | 18.42 | 13.63 | 8.83 | 4.03 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 850.00 | 8 | 60.00 | 28.52 | 23.72 | 18.92 | 14.13 | 9.33 | 4.53 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 860.00 | 8 | 70.00 | 29.02 | 24.22 | 19.42 | 14.62 | 9.83 | 5.03 | 0.23 | 0.00 | 0.00 | 0.00 | 0.00 |
| 870.00 | 8 | 79.00 | 29.47 | 24.67 | 19.87 | 15.07 | 10.28 | 5.48 | 0.68 | 0.00 | 0.00 | 0.00 | 0.00 |
| 879.00 | 8 | 88.00 | 29.92 | 25.12 | 20.32 | 15.52 | 10.72 | 5.93 | 1.13 | 0.00 | 0.00 | 0.00 | 0.00 |
| 888.00 | 8 | 97.00 | 30.37 | 25.57 | 20.77 | 15.97 | 11.17 | 6.38 | 1.58 | 0.00 | 0.00 | 0.00 | 0.00 |
| 897.00 | 9 | 06.00 | 30.82 | 26.02 | 21.22 | 16.42 | 11.62 | 6.82 | 2.03 | 0.00 | 0.00 | 0.00 | 0.00 |
| 906.00 | 9 | 15.00 | 31.26 | 26.47 | 21.67 | 16.87 | 12.07 | 7.27 | 2.48 | 0.00 | 0.00 | 0.00 | 0.00 |
| 915.00 | 9 | 23.00 | 31.66 | 26.87 | 22.07 | 17.27 | 12.47 | 7.67 | 2.88 | 0.00 | 0.00 | 0.00 | 0.00 |
| 923.00 | 9 | 31.00 | 32.06 | 27.26 | 22.47 | 17.67 | 12.87 | 8.07 | 3.27 | 0.00 | 0.00 | 0.00 | 0.00 |
| 931.00 | 9 | 39.00 | 32.46 | 27.66 | 22.87 | 18.07 | 13.27 | 8.47 | 3.67 | 0.00 | 0.00 | 0.00 | 0.00 |
| 939.00 | 9 | 47.00 | 32.86 | 28.06 | 23.26 | 18.47 | 13.67 | 8.87 | 4.07 | 0.00 | 0.00 | 0.00 | 0.00 |
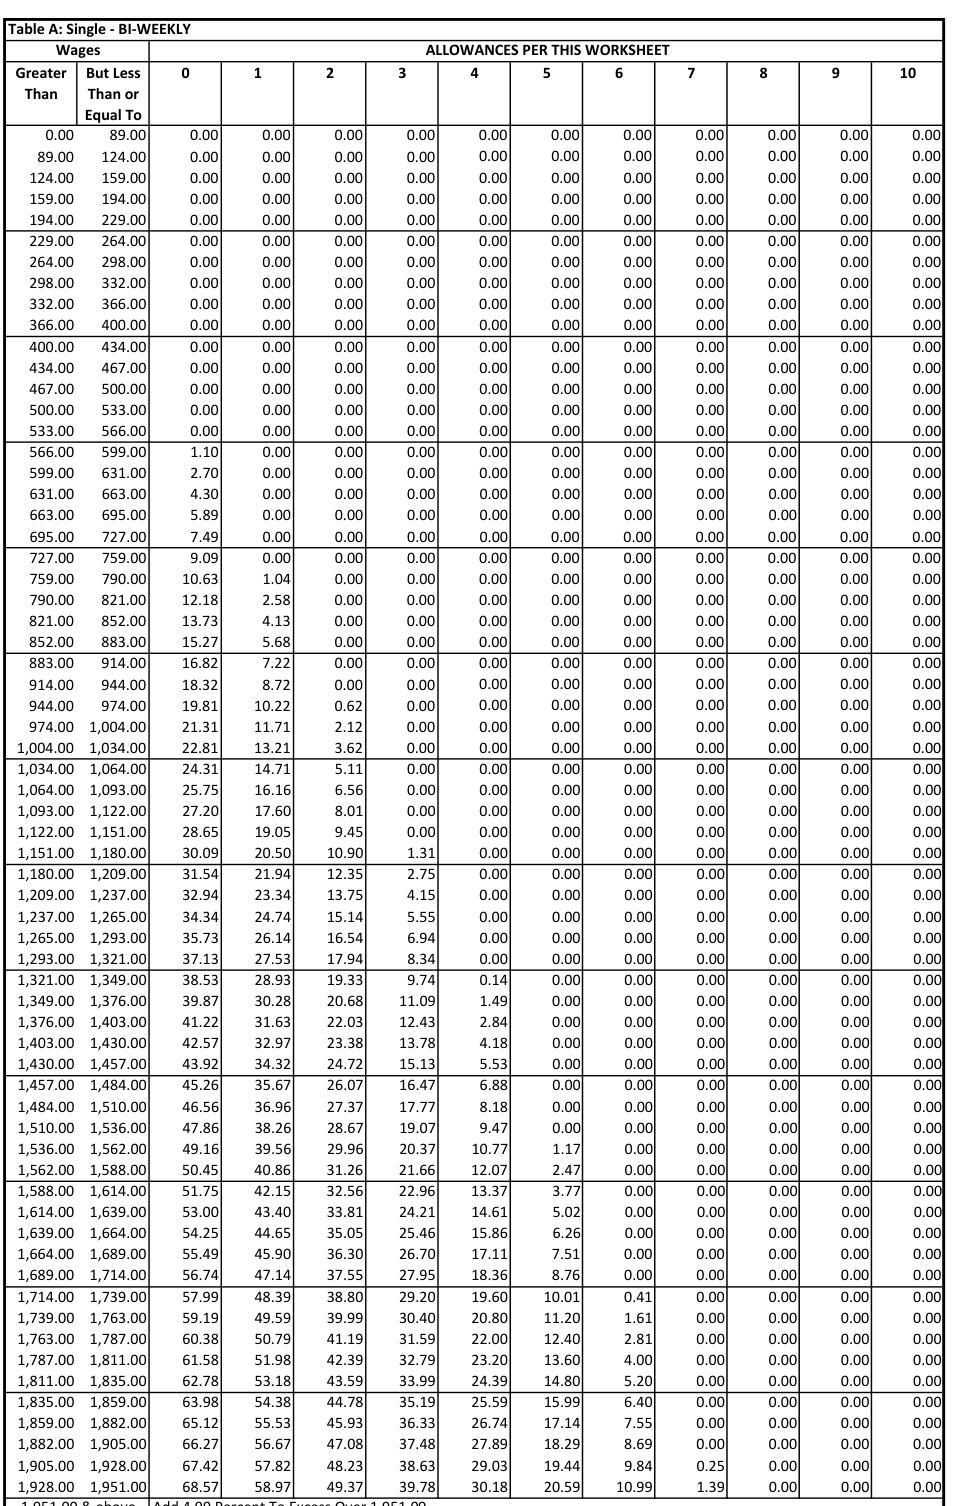
Text version of this table
| Wag | es | ALLOW | ANCES PER | THIS WOR | KSHEET | ||||||||
| Greater | But | Less | 0 | 1 | 2 | 3 | 4 | 5 | 6 7 | 8 | 9 | 1 0 | |
| Than | Tha | n or | |||||||||||
| E | qu | al To | |||||||||||
| 0.00 | 89.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 89.00 | 1 | 24.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 124.00 | 1 | 59.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 159.00 | 1 | 94.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 194.00 | 2 | 29.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 229.00 | 2 | 64.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 264.00 | 2 | 98.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 298.00 | 3 | 32.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 332.00 | 3 | 66.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 366.00 | 4 | 00.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 400.00 | 4 | 34.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 434.00 | 4 | 67.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 467.00 | 5 | 00.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 500.00 | 5 | 33.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 533.00 | 5 | 66.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 566.00 | 5 | 99.00 | 1.10 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 599.00 | 6 | 31.00 | 2.70 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 631.00 | 6 | 63.00 | 4.30 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 663.00 | 6 | 95.00 | 5.89 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 695.00 | 7 | 27.00 | 7.49 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 727.00 | 7 | 59.00 | 9.09 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 759.00 | 7 | 90.00 | 10.63 | 1.04 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 790.00 | 8 | 21.00 | 12.18 | 2.58 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 821.00 | 8 | 52.00 | 13.73 | 4.13 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 852.00 | 8 | 83.00 | 15.27 | 5.68 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 883.00 | 9 | 14.00 | 16.82 | 7.22 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 914.00 | 9 | 44.00 | 18.32 | 8.72 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 944.00 | 9 | 74.00 | 19.81 | 10.22 | 0.62 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 974.00 | 1,0 | 04.00 | 21.31 | 11.71 | 2.12 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,004.00 | 1,0 | 34.00 | 22.81 | 13.21 | 3.62 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,034.00 | 1,0 | 64.00 | 24.31 | 14.71 | 5.11 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,064.00 | 1,0 | 93.00 | 25.75 | 16.16 | 6.56 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,093.00 | 1,1 | 22.00 | 27.20 | 17.60 | 8.01 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,122.00 | 1,1 | 51.00 | 28.65 | 19.05 | 9.45 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,151.00 | 1,1 | 80.00 | 30.09 | 20.50 | 10.90 | 1.31 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,180.00 | 1,2 | 09.00 | 31.54 | 21.94 | 12.35 | 2.75 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,209.00 | 1,2 | 37.00 | 32.94 | 23.34 | 13.75 | 4.15 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,237.00 | 1,2 | 65.00 | 34.34 | 24.74 | 15.14 | 5.55 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,265.00 | 1,2 | 93.00 | 35.73 | 26.14 | 16.54 | 6.94 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,293.00 | 1,3 | 21.00 | 37.13 | 27.53 | 17.94 | 8.34 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,321.00 | 1,3 | 49.00 | 38.53 | 28.93 | 19.33 | 9.74 | 0.14 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,349.00 | 1,3 | 76.00 | 39.87 | 30.28 | 20.68 | 11.09 | 1.49 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,376.00 | 1,4 | 03.00 | 41.22 | 31.63 | 22.03 | 12.43 | 2.84 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,403.00 | 1,4 | 30.00 | 42.57 | 32.97 | 23.38 | 13.78 | 4.18 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,430.00 | 1,4 | 57.00 | 43.92 | 34.32 | 24.72 | 15.13 | 5.53 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,457.00 | 1,4 | 84.00 | 45.26 | 35.67 | 26.07 | 16.47 | 6.88 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,484.00 | 1,5 | 10.00 | 46.56 | 36.96 | 27.37 | 17.77 | 8.18 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,510.00 | 1,5 | 36.00 | 47.86 | 38.26 | 28.67 | 19.07 | 9.47 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,536.00 | 1,5 | 62.00 | 49.16 | 39.56 | 29.96 | 20.37 | 10.77 | 1.17 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,562.00 | 1,5 | 88.00 | 50.45 | 40.86 | 31.26 | 21.66 | 12.07 | 2.47 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,588.00 | 1,6 | 14.00 | 51.75 | 42.15 | 32.56 | 22.96 | 13.37 | 3.77 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,614.00 | 1,6 | 39.00 | 53.00 | 43.40 | 33.81 | 24.21 | 14.61 | 5.02 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,639.00 | 1,6 | 64.00 | 54.25 | 44.65 | 35.05 | 25.46 | 15.86 | 6.26 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,664.00 | 1,6 | 89.00 | 55.49 | 45.90 | 36.30 | 26.70 | 17.11 | 7.51 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,689.00 | 1,7 | 14.00 | 56.74 | 47.14 | 37.55 | 27.95 | 18.36 | 8.76 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,714.00 | 1,7 | 39.00 | 57.99 | 48.39 | 38.80 | 29.20 | 19.60 | 10.01 | 0.41 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,739.00 | 1,7 | 63.00 | 59.19 | 49.59 | 39.99 | 30.40 | 20.80 | 11.20 | 1.61 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,763.00 | 1,7 | 87.00 | 60.38 | 50.79 | 41.19 | 31.59 | 22.00 | 12.40 | 2.81 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,787.00 | 1,8 | 11.00 | 61.58 | 51.98 | 42.39 | 32.79 | 23.20 | 13.60 | 4.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,811.00 | 1,8 | 35.00 | 62.78 | 53.18 | 43.59 | 33.99 | 24.39 | 14.80 | 5.20 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,835.00 | 1,8 | 59.00 | 63.98 | 54.38 | 44.78 | 35.19 | 25.59 | 15.99 | 6.40 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,859.00 | 1,8 | 82.00 | 65.12 | 55.53 | 45.93 | 36.33 | 26.74 | 17.14 | 7.55 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,882.00 | 1,9 | 05.00 | 66.27 | 56.67 | 47.08 | 37.48 | 27.89 | 18.29 | 8.69 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,905.00 | 1,9 | 28.00 | 67.42 | 57.82 | 48.23 | 38.63 | 29.03 | 19.44 | 9.84 | 0.25 | 0.00 | 0.00 | 0.00 |
| 1,928.00 | 1,9 | 51.00 | 68.57 | 58.97 | 49.37 | 39.78 | 30.18 | 20.59 | 10.99 | 1.39 | 0.00 | 0.00 | 0.00 |
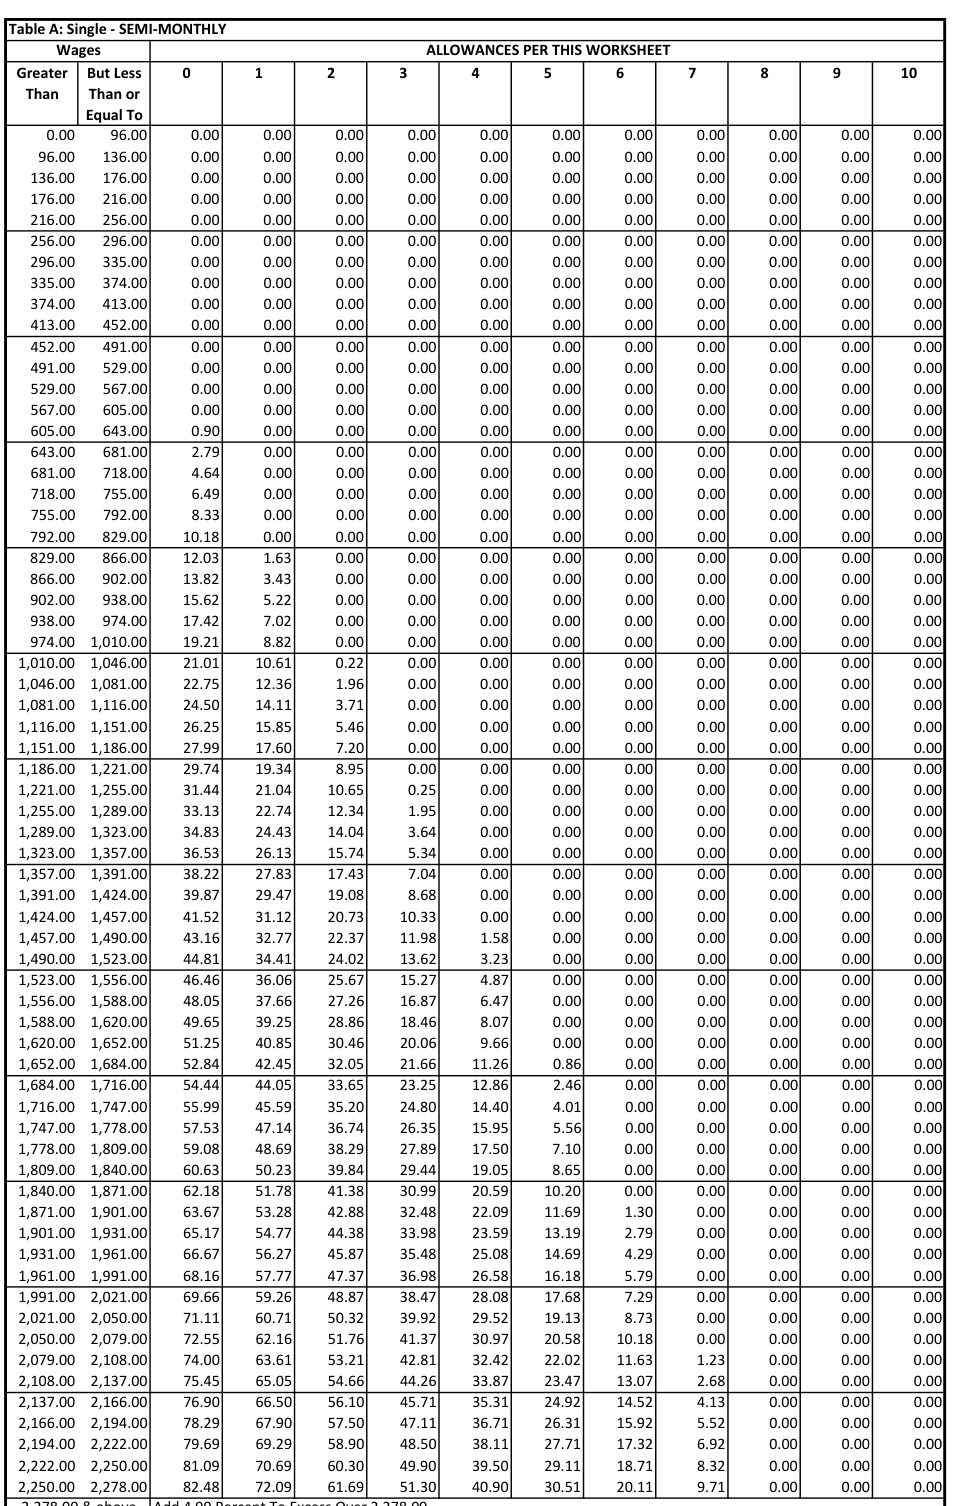
Text version of this table
| Wag | es | ALLOW | ANCES PER | THIS WOR | KSHEET | ||||||||
| Greater | But | Less | 0 | 1 | 2 | 3 | 4 | 5 | 6 7 | 8 | 9 | 1 0 | |
| Than | Tha | n or | |||||||||||
| E | qu | al To | |||||||||||
| 0.00 | 96.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 96.00 | 1 | 36.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 136.00 | 1 | 76.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 176.00 | 2 | 16.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 216.00 | 2 | 56.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 256.00 | 2 | 96.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 296.00 | 3 | 35.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 335.00 | 3 | 74.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 374.00 | 4 | 13.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 413.00 | 4 | 52.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 452.00 | 4 | 91.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 491.00 | 5 | 29.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 529.00 | 5 | 67.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 567.00 | 6 | 05.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 605.00 | 6 | 43.00 | 0.90 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 643.00 | 6 | 81.00 | 2.79 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 681.00 | 7 | 18.00 | 4.64 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 718.00 | 7 | 55.00 | 6.49 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 755.00 | 7 | 92.00 | 8.33 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 792.00 | 8 | 29.00 | 10.18 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 829.00 | 8 | 66.00 | 12.03 | 1.63 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 866.00 | 9 | 02.00 | 13.82 | 3.43 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 902.00 | 9 | 38.00 | 15.62 | 5.22 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 938.00 | 9 | 74.00 | 17.42 | 7.02 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 974.00 | 1,0 | 10.00 | 19.21 | 8.82 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,010.00 | 1,0 | 46.00 | 21.01 | 10.61 | 0.22 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,046.00 | 1,0 | 81.00 | 22.75 | 12.36 | 1.96 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,081.00 | 1,1 | 16.00 | 24.50 | 14.11 | 3.71 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,116.00 | 1,1 | 51.00 | 26.25 | 15.85 | 5.46 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,151.00 | 1,1 | 86.00 | 27.99 | 17.60 | 7.20 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,186.00 | 1,2 | 21.00 | 29.74 | 19.34 | 8.95 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,221.00 | 1,2 | 55.00 | 31.44 | 21.04 | 10.65 | 0.25 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,255.00 | 1,2 | 89.00 | 33.13 | 22.74 | 12.34 | 1.95 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,289.00 | 1,3 | 23.00 | 34.83 | 24.43 | 14.04 | 3.64 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,323.00 | 1,3 | 57.00 | 36.53 | 26.13 | 15.74 | 5.34 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,357.00 | 1,3 | 91.00 | 38.22 | 27.83 | 17.43 | 7.04 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,391.00 | 1,4 | 24.00 | 39.87 | 29.47 | 19.08 | 8.68 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,424.00 | 1,4 | 57.00 | 41.52 | 31.12 | 20.73 | 10.33 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,457.00 | 1,4 | 90.00 | 43.16 | 32.77 | 22.37 | 11.98 | 1.58 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,490.00 | 1,5 | 23.00 | 44.81 | 34.41 | 24.02 | 13.62 | 3.23 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,523.00 | 1,5 | 56.00 | 46.46 | 36.06 | 25.67 | 15.27 | 4.87 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,556.00 | 1,5 | 88.00 | 48.05 | 37.66 | 27.26 | 16.87 | 6.47 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,588.00 | 1,6 | 20.00 | 49.65 | 39.25 | 28.86 | 18.46 | 8.07 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,620.00 | 1,6 | 52.00 | 51.25 | 40.85 | 30.46 | 20.06 | 9.66 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,652.00 | 1,6 | 84.00 | 52.84 | 42.45 | 32.05 | 21.66 | 11.26 | 0.86 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,684.00 | 1,7 | 16.00 | 54.44 | 44.05 | 33.65 | 23.25 | 12.86 | 2.46 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,716.00 | 1,7 | 47.00 | 55.99 | 45.59 | 35.20 | 24.80 | 14.40 | 4.01 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,747.00 | 1,7 | 78.00 | 57.53 | 47.14 | 36.74 | 26.35 | 15.95 | 5.56 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,778.00 | 1,8 | 09.00 | 59.08 | 48.69 | 38.29 | 27.89 | 17.50 | 7.10 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,809.00 | 1,8 | 40.00 | 60.63 | 50.23 | 39.84 | 29.44 | 19.05 | 8.65 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,840.00 | 1,8 | 71.00 | 62.18 | 51.78 | 41.38 | 30.99 | 20.59 | 10.20 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,871.00 | 1,9 | 01.00 | 63.67 | 53.28 | 42.88 | 32.48 | 22.09 | 11.69 | 1.30 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,901.00 | 1,9 | 31.00 | 65.17 | 54.77 | 44.38 | 33.98 | 23.59 | 13.19 | 2.79 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,931.00 | 1,9 | 61.00 | 66.67 | 56.27 | 45.87 | 35.48 | 25.08 | 14.69 | 4.29 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,961.00 | 1,9 | 91.00 | 68.16 | 57.77 | 47.37 | 36.98 | 26.58 | 16.18 | 5.79 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,991.00 | 2,0 | 21.00 | 69.66 | 59.26 | 48.87 | 38.47 | 28.08 | 17.68 | 7.29 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,021.00 | 2,0 | 50.00 | 71.11 | 60.71 | 50.32 | 39.92 | 29.52 | 19.13 | 8.73 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,050.00 | 2,0 | 79.00 | 72.55 | 62.16 | 51.76 | 41.37 | 30.97 | 20.58 | 10.18 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,079.00 | 2,1 | 08.00 | 74.00 | 63.61 | 53.21 | 42.81 | 32.42 | 22.02 | 11.63 | 1.23 | 0.00 | 0.00 | 0.00 |
| 2,108.00 | 2,1 | 37.00 | 75.45 | 65.05 | 54.66 | 44.26 | 33.87 | 23.47 | 13.07 | 2.68 | 0.00 | 0.00 | 0.00 |
| 2,137.00 | 2,1 | 66.00 | 76.90 | 66.50 | 56.10 | 45.71 | 35.31 | 24.92 | 14.52 | 4.13 | 0.00 | 0.00 | 0.00 |
| 2,166.00 | 2,1 | 94.00 | 78.29 | 67.90 | 57.50 | 47.11 | 36.71 | 26.31 | 15.92 | 5.52 | 0.00 | 0.00 | 0.00 |
| 2,194.00 | 2,2 | 22.00 | 79.69 | 69.29 | 58.90 | 48.50 | 38.11 | 27.71 | 17.32 | 6.92 | 0.00 | 0.00 | 0.00 |
| 2,222.00 | 2,2 | 50.00 | 81.09 | 70.69 | 60.30 | 49.90 | 39.50 | 29.11 | 18.71 | 8.32 | 0.00 | 0.00 | 0.00 |
| 2,250.00 | 2,2 | 78.00 | 82.48 | 72.09 | 61.69 | 51.30 | 40.90 | 30.51 | 20.11 | 9.71 | 0.00 | 0.00 | 0.00 |
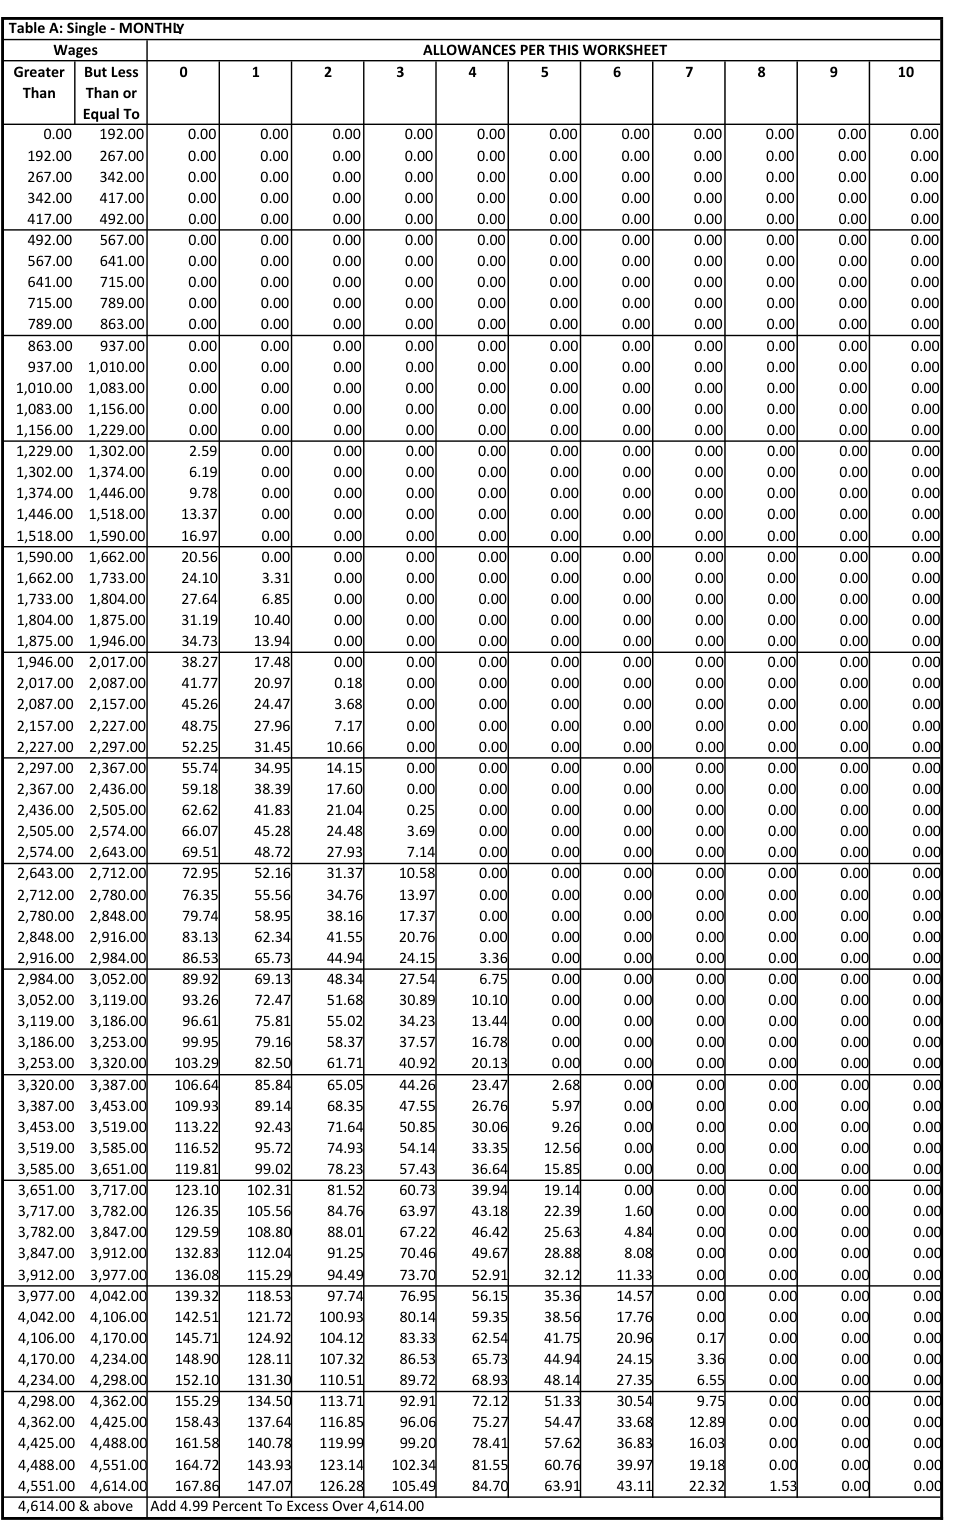
Text version of this table
| Wage | s | ALLOW | ANCES PER | THIS WOR | KSHEET | ||||||||
| Greater | But | Less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 8 | 9 | 1 0 | |
| Than | Tha | n or | |||||||||||
| E | qu | al To | |||||||||||
| 0.00 | 1 | 92.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 192.00 | 2 | 67.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 267.00 | 3 | 42.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 342.00 | 4 | 17.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 417.00 | 4 | 92.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 492.00 | 5 | 67.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 567.00 | 6 | 41.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 641.00 | 7 | 15.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 715.00 | 7 | 89.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 789.00 | 8 | 63.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 863.00 | 9 | 37.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 937.00 | 1,0 | 10.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,010.00 | 1,0 | 83.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,083.00 | 1,1 | 56.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,156.00 | 1,2 | 29.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,229.00 | 1,3 | 02.00 | 2.59 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,302.00 | 1,3 | 74.00 | 6.19 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,374.00 | 1,4 | 46.00 | 9.78 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,446.00 | 1,5 | 18.00 | 13.37 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,518.00 | 1,5 | 90.00 | 16.97 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,590.00 | 1,6 | 62.00 | 20.56 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,662.00 | 1,7 | 33.00 | 24.10 | 3.31 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,733.00 | 1,8 | 04.00 | 27.64 | 6.85 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,804.00 | 1,8 | 75.00 | 31.19 | 10.40 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,875.00 | 1,9 | 46.00 | 34.73 | 13.94 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,946.00 | 2,0 | 17.00 | 38.27 | 17.48 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,017.00 | 2,0 | 87.00 | 41.77 | 20.97 | 0.18 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,087.00 | 2,1 | 57.00 | 45.26 | 24.47 | 3.68 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,157.00 | 2,2 | 27.00 | 48.75 | 27.96 | 7.17 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,227.00 | 2,2 | 97.00 | 52.25 | 31.45 | 10.66 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,297.00 | 2,3 | 67.00 | 55.74 | 34.95 | 14.15 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,367.00 | 2,4 | 36.00 | 59.18 | 38.39 | 17.60 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,436.00 | 2,5 | 05.00 | 62.62 | 41.83 | 21.04 | 0.25 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,505.00 | 2,5 | 74.00 | 66.07 | 45.28 | 24.48 | 3.69 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,574.00 | 2,6 | 43.00 | 69.51 | 48.72 | 27.93 | 7.14 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,643.00 | 2,7 | 12.00 | 72.95 | 52.16 | 31.37 | 10.58 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,712.00 | 2,7 | 80.00 | 76.35 | 55.56 | 34.76 | 13.97 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,780.00 | 2,8 | 48.00 | 79.74 | 58.95 | 38.16 | 17.37 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,848.00 | 2,9 | 16.00 | 83.13 | 62.34 | 41.55 | 20.76 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,916.00 | 2,9 | 84.00 | 86.53 | 65.73 | 44.94 | 24.15 | 3.36 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,984.00 | 3,0 | 52.00 | 89.92 | 69.13 | 48.34 | 27.54 | 6.75 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,052.00 | 3,1 | 19.00 | 93.26 | 72.47 | 51.68 | 30.89 | 10.10 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,119.00 | 3,1 | 86.00 | 96.61 | 75.81 | 55.02 | 34.23 | 13.44 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,186.00 | 3,2 | 53.00 | 99.95 | 79.16 | 58.37 | 37.57 | 16.78 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,253.00 | 3,3 | 20.00 | 103.29 | 82.50 | 61.71 | 40.92 | 20.13 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,320.00 | 3,3 | 87.00 | 106.64 | 85.84 | 65.05 | 44.26 | 23.47 | 2.68 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,387.00 | 3,4 | 53.00 | 109.93 | 89.14 | 68.35 | 47.55 | 26.76 | 5.97 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,453.00 | 3,5 | 19.00 | 113.22 | 92.43 | 71.64 | 50.85 | 30.06 | 9.26 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,519.00 | 3,5 | 85.00 | 116.52 | 95.72 | 74.93 | 54.14 | 33.35 | 12.56 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,585.00 | 3,6 | 51.00 | 119.81 | 99.02 | 78.23 | 57.43 | 36.64 | 15.85 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,651.00 | 3,7 | 17.00 | 123.10 | 102.31 | 81.52 | 60.73 | 39.94 | 19.14 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,717.00 | 3,7 | 82.00 | 126.35 | 105.56 | 84.76 | 63.97 | 43.18 | 22.39 | 1.60 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,782.00 | 3,8 | 47.00 | 129.59 | 108.80 | 88.01 | 67.22 | 46.42 | 25.63 | 4.84 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,847.00 | 3,9 | 12.00 | 132.83 | 112.04 | 91.25 | 70.46 | 49.67 | 28.88 | 8.08 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,912.00 | 3,9 | 77.00 | 136.08 | 115.29 | 94.49 | 73.70 | 52.91 | 32.12 | 11.33 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,977.00 | 4,0 | 42.00 | 139.32 | 118.53 | 97.74 | 76.95 | 56.15 | 35.36 | 14.57 | 0.00 | 0.00 | 0.00 | 0.00 |
| 4,042.00 | 4,1 | 06.00 | 142.51 | 121.72 | 100.93 | 80.14 | 59.35 | 38.56 | 17.76 | 0.00 | 0.00 | 0.00 | 0.00 |
| 4,106.00 | 4,1 | 70.00 | 145.71 | 124.92 | 104.12 | 83.33 | 62.54 | 41.75 | 20.96 | 0.17 | 0.00 | 0.00 | 0.00 |
| 4,170.00 | 4,2 | 34.00 | 148.90 | 128.11 | 107.32 | 86.53 | 65.73 | 44.94 | 24.15 | 3.36 | 0.00 | 0.00 | 0.00 |
| 4,234.00 | 4,2 | 98.00 | 152.10 | 131.30 | 110.51 | 89.72 | 68.93 | 48.14 | 27.35 | 6.55 | 0.00 | 0.00 | 0.00 |
| 4,298.00 | 4,3 | 62.00 | 155.29 | 134.50 | 113.71 | 92.91 | 72.12 | 51.33 | 30.54 | 9.75 | 0.00 | 0.00 | 0.00 |
| 4,362.00 | 4,4 | 25.00 | 158.43 | 137.64 | 116.85 | 96.06 | 75.27 | 54.47 | 33.68 | 12.89 | 0.00 | 0.00 | 0.00 |
| 4,425.00 | 4,4 | 88.00 | 161.58 | 140.78 | 119.99 | 99.20 | 78.41 | 57.62 | 36.83 | 16.03 | 0.00 | 0.00 | 0.00 |
| 4,488.00 | 4,5 | 51.00 | 164.72 | 143.93 | 123.14 | 102.34 | 81.55 | 60.76 | 39.97 | 19.18 | 0.00 | 0.00 | 0.00 |
| 4,551.00 | 4,6 | 14.00 | 167.86 | 147.07 | 126.28 | 105.49 | 84.70 | 63.91 | 43.11 | 22.32 | 1.53 | 0.00 | 0.00 |
| 4,614.00 & | ab | ove Add | 4.99 Perce | nt To Exces | s Over 4,6 | 14.00 |
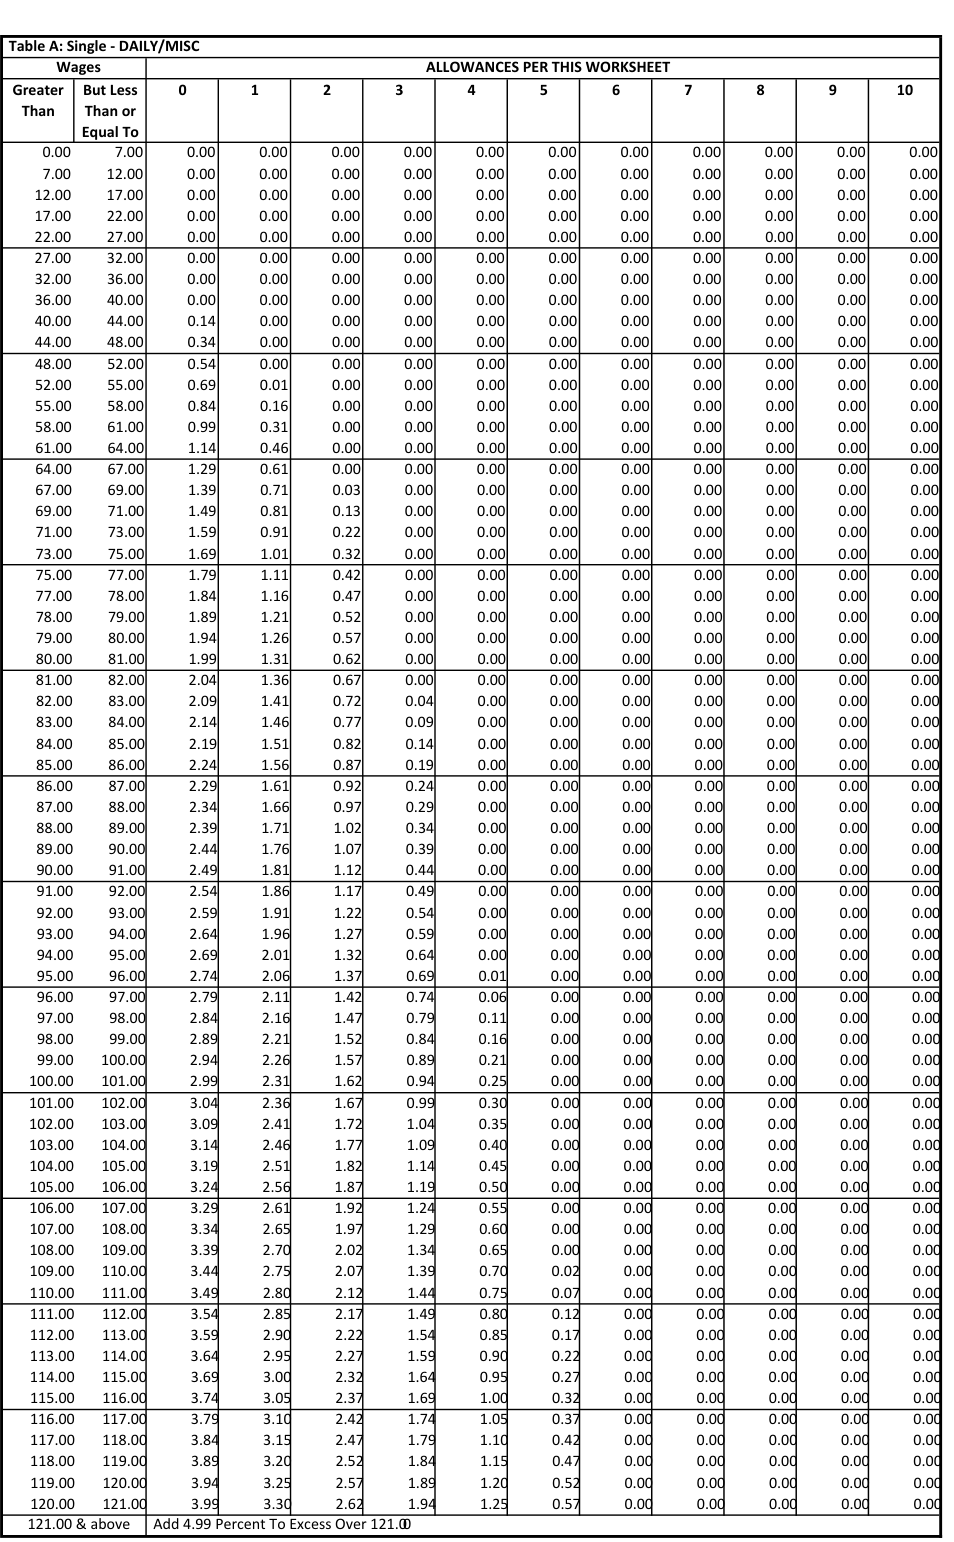
Text version of this table
| ble A: Singl | e - DAILY/MI | SC | ||||||||||
| Wages | ALLOW | ANCES PER | THIS WOR | KSHEET | ||||||||
| eater Bu | t Less 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 1 0 | |
| han Th | an or | |||||||||||
| Eq | ual To | |||||||||||
| 0.00 | 7.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 7.00 | 12.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 12.00 | 17.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 17.00 | 22.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 22.00 | 27.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 27.00 | 32.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 32.00 | 36.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 36.00 | 40.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 40.00 | 44.00 | 0.14 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 44.00 | 48.00 | 0.34 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 48.00 | 52.00 | 0.54 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 52.00 | 55.00 | 0.69 | 0.01 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 55.00 | 58.00 | 0.84 | 0.16 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 58.00 | 61.00 | 0.99 | 0.31 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 61.00 | 64.00 | 1.14 | 0.46 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 64.00 | 67.00 | 1.29 | 0.61 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 67.00 | 69.00 | 1.39 | 0.71 | 0.03 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 69.00 | 71.00 | 1.49 | 0.81 | 0.13 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 71.00 | 73.00 | 1.59 | 0.91 | 0.22 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 73.00 | 75.00 | 1.69 | 1.01 | 0.32 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 75.00 | 77.00 | 1.79 | 1.11 | 0.42 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 77.00 | 78.00 | 1.84 | 1.16 | 0.47 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 78.00 | 79.00 | 1.89 | 1.21 | 0.52 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 79.00 | 80.00 | 1.94 | 1.26 | 0.57 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 80.00 | 81.00 | 1.99 | 1.31 | 0.62 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 81.00 | 82.00 | 2.04 | 1.36 | 0.67 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 82.00 | 83.00 | 2.09 | 1.41 | 0.72 | 0.04 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 83.00 | 84.00 | 2.14 | 1.46 | 0.77 | 0.09 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 84.00 | 85.00 | 2.19 | 1.51 | 0.82 | 0.14 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 85.00 | 86.00 | 2.24 | 1.56 | 0.87 | 0.19 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 86.00 | 87.00 | 2.29 | 1.61 | 0.92 | 0.24 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 87.00 | 88.00 | 2.34 | 1.66 | 0.97 | 0.29 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 88.00 | 89.00 | 2.39 | 1.71 | 1.02 | 0.34 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 89.00 | 90.00 | 2.44 | 1.76 | 1.07 | 0.39 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 90.00 | 91.00 | 2.49 | 1.81 | 1.12 | 0.44 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 91.00 | 92.00 | 2.54 | 1.86 | 1.17 | 0.49 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 92.00 | 93.00 | 2.59 | 1.91 | 1.22 | 0.54 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 93.00 | 94.00 | 2.64 | 1.96 | 1.27 | 0.59 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 94.00 | 95.00 | 2.69 | 2.01 | 1.32 | 0.64 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 95.00 | 96.00 | 2.74 | 2.06 | 1.37 | 0.69 | 0.01 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 96.00 | 97.00 | 2.79 | 2.11 | 1.42 | 0.74 | 0.06 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 97.00 | 98.00 | 2.84 | 2.16 | 1.47 | 0.79 | 0.11 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 98.00 | 99.00 | 2.89 | 2.21 | 1.52 | 0.84 | 0.16 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 99.00 | 100.00 | 2.94 | 2.26 | 1.57 | 0.89 | 0.21 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 100.00 | 101.00 | 2.99 | 2.31 | 1.62 | 0.94 | 0.25 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 101.00 | 102.00 | 3.04 | 2.36 | 1.67 | 0.99 | 0.30 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 102.00 | 103.00 | 3.09 | 2.41 | 1.72 | 1.04 | 0.35 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 103.00 | 104.00 | 3.14 | 2.46 | 1.77 | 1.09 | 0.40 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 104.00 | 105.00 | 3.19 | 2.51 | 1.82 | 1.14 | 0.45 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 105.00 | 106.00 | 3.24 | 2.56 | 1.87 | 1.19 | 0.50 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 106.00 | 107.00 | 3.29 | 2.61 | 1.92 | 1.24 | 0.55 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 107.00 | 108.00 | 3.34 | 2.65 | 1.97 | 1.29 | 0.60 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 108.00 | 109.00 | 3.39 | 2.70 | 2.02 | 1.34 | 0.65 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 109.00 | 110.00 | 3.44 | 2.75 | 2.07 | 1.39 | 0.70 | 0.02 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 110.00 | 111.00 | 3.49 | 2.80 | 2.12 | 1.44 | 0.75 | 0.07 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 111.00 | 112.00 | 3.54 | 2.85 | 2.17 | 1.49 | 0.80 | 0.12 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 112.00 | 113.00 | 3.59 | 2.90 | 2.22 | 1.54 | 0.85 | 0.17 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 113.00 | 114.00 | 3.64 | 2.95 | 2.27 | 1.59 | 0.90 | 0.22 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 114.00 | 115.00 | 3.69 | 3.00 | 2.32 | 1.64 | 0.95 | 0.27 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 115.00 | 116.00 | 3.74 | 3.05 | 2.37 | 1.69 | 1.00 | 0.32 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 116.00 | 117.00 | 3.79 | 3.10 | 2.42 | 1.74 | 1.05 | 0.37 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 117.00 | 118.00 | 3.84 | 3.15 | 2.47 | 1.79 | 1.10 | 0.42 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 118.00 | 119.00 | 3.89 | 3.20 | 2.52 | 1.84 | 1.15 | 0.47 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 119.00 | 120.00 | 3.94 | 3.25 | 2.57 | 1.89 | 1.20 | 0.52 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 120.00 | 121.00 | 3.99 | 3.30 | 2.62 | 1.94 | 1.25 | 0.57 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 121.00 & a | bove Add | 4.99 Percen | t To Excess | Over 121.0 | 0 |
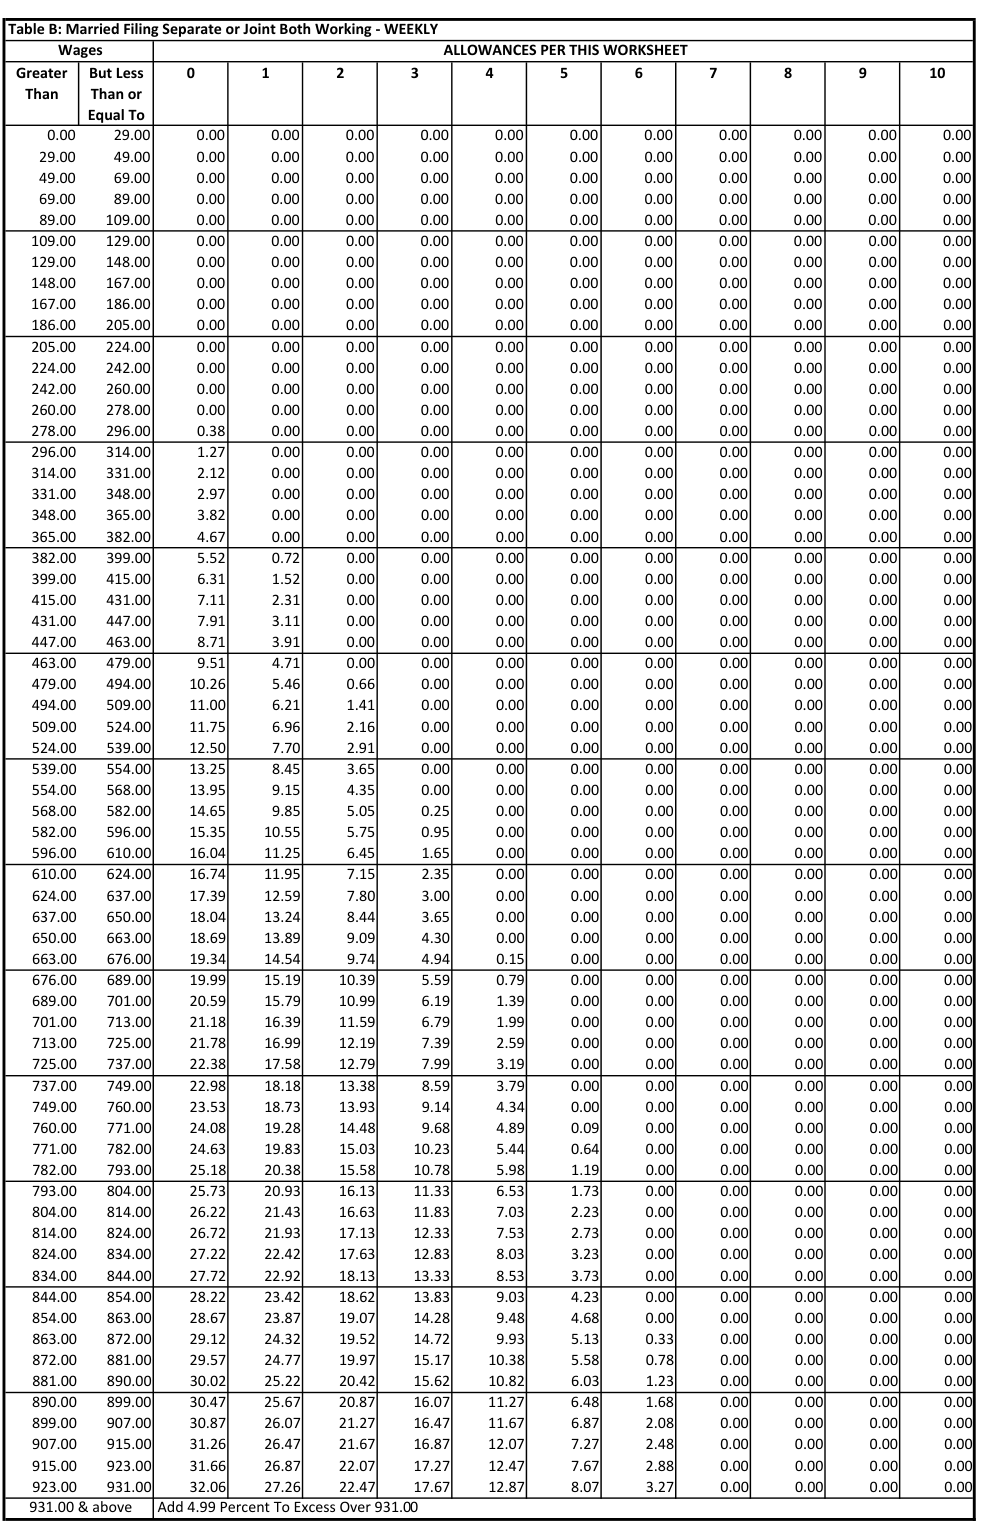
Text version of this table
| Wages | ALLOW | ANCES PER | THIS WORK | SHEET | |||||||||
| eater Bu | t | Less | 0 | 1 | 2 | 3 | 4 5 | 6 | 7 | 8 | 9 | 1 0 | |
| Than Th | a | n or | |||||||||||
| Eq | u | al To | |||||||||||
| 0.00 | 29.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 29.00 | 49.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 49.00 | 69.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 69.00 | 89.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 89.00 | 1 | 09.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 109.00 | 1 | 29.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 129.00 | 1 | 48.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 148.00 | 1 | 67.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 167.00 | 1 | 86.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 186.00 | 2 | 05.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 205.00 | 2 | 24.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 224.00 | 2 | 42.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 242.00 | 2 | 60.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 260.00 | 2 | 78.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 278.00 | 2 | 96.00 | 0.38 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 296.00 | 3 | 14.00 | 1.27 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 314.00 | 3 | 31.00 | 2.12 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 331.00 | 3 | 48.00 | 2.97 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 348.00 | 3 | 65.00 | 3.82 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 365.00 | 3 | 82.00 | 4.67 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 382.00 | 3 | 99.00 | 5.52 | 0.72 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 399.00 | 4 | 15.00 | 6.31 | 1.52 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 415.00 | 4 | 31.00 | 7.11 | 2.31 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 431.00 | 4 | 47.00 | 7.91 | 3.11 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 447.00 | 4 | 63.00 | 8.71 | 3.91 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 463.00 | 4 | 79.00 | 9.51 | 4.71 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 479.00 | 4 | 94.00 | 10.26 | 5.46 | 0.66 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 494.00 | 5 | 09.00 | 11.00 | 6.21 | 1.41 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 509.00 | 5 | 24.00 | 11.75 | 6.96 | 2.16 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 524.00 | 5 | 39.00 | 12.50 | 7.70 | 2.91 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 539.00 | 5 | 54.00 | 13.25 | 8.45 | 3.65 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 554.00 | 5 | 68.00 | 13.95 | 9.15 | 4.35 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 568.00 | 5 | 82.00 | 14.65 | 9.85 | 5.05 | 0.25 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 582.00 | 5 | 96.00 | 15.35 | 10.55 | 5.75 | 0.95 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 596.00 | 6 | 10.00 | 16.04 | 11.25 | 6.45 | 1.65 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 610.00 | 6 | 24.00 | 16.74 | 11.95 | 7.15 | 2.35 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 624.00 | 6 | 37.00 | 17.39 | 12.59 | 7.80 | 3.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 637.00 | 6 | 50.00 | 18.04 | 13.24 | 8.44 | 3.65 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 650.00 | 6 | 63.00 | 18.69 | 13.89 | 9.09 | 4.30 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 663.00 | 6 | 76.00 | 19.34 | 14.54 | 9.74 | 4.94 | 0.15 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 676.00 | 6 | 89.00 | 19.99 | 15.19 | 10.39 | 5.59 | 0.79 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 689.00 | 7 | 01.00 | 20.59 | 15.79 | 10.99 | 6.19 | 1.39 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 701.00 | 7 | 13.00 | 21.18 | 16.39 | 11.59 | 6.79 | 1.99 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 713.00 | 7 | 25.00 | 21.78 | 16.99 | 12.19 | 7.39 | 2.59 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 725.00 | 7 | 37.00 | 22.38 | 17.58 | 12.79 | 7.99 | 3.19 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 737.00 | 7 | 49.00 | 22.98 | 18.18 | 13.38 | 8.59 | 3.79 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 749.00 | 7 | 60.00 | 23.53 | 18.73 | 13.93 | 9.14 | 4.34 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 760.00 | 7 | 71.00 | 24.08 | 19.28 | 14.48 | 9.68 | 4.89 | 0.09 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 771.00 | 7 | 82.00 | 24.63 | 19.83 | 15.03 | 10.23 | 5.44 | 0.64 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 782.00 | 7 | 93.00 | 25.18 | 20.38 | 15.58 | 10.78 | 5.98 | 1.19 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 793.00 | 8 | 04.00 | 25.73 | 20.93 | 16.13 | 11.33 | 6.53 | 1.73 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 804.00 | 8 | 14.00 | 26.22 | 21.43 | 16.63 | 11.83 | 7.03 | 2.23 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 814.00 | 8 | 24.00 | 26.72 | 21.93 | 17.13 | 12.33 | 7.53 | 2.73 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 824.00 | 8 | 34.00 | 27.22 | 22.42 | 17.63 | 12.83 | 8.03 | 3.23 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 834.00 | 8 | 44.00 | 27.72 | 22.92 | 18.13 | 13.33 | 8.53 | 3.73 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 844.00 | 8 | 54.00 | 28.22 | 23.42 | 18.62 | 13.83 | 9.03 | 4.23 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 854.00 | 8 | 63.00 | 28.67 | 23.87 | 19.07 | 14.28 | 9.48 | 4.68 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 863.00 | 8 | 72.00 | 29.12 | 24.32 | 19.52 | 14.72 | 9.93 | 5.13 | 0.33 | 0.00 | 0.00 | 0.00 | 0.00 |
| 872.00 | 8 | 81.00 | 29.57 | 24.77 | 19.97 | 15.17 | 10.38 | 5.58 | 0.78 | 0.00 | 0.00 | 0.00 | 0.00 |
| 881.00 | 8 | 90.00 | 30.02 | 25.22 | 20.42 | 15.62 | 10.82 | 6.03 | 1.23 | 0.00 | 0.00 | 0.00 | 0.00 |
| 890.00 | 8 | 99.00 | 30.47 | 25.67 | 20.87 | 16.07 | 11.27 | 6.48 | 1.68 | 0.00 | 0.00 | 0.00 | 0.00 |
| 899.00 | 9 | 07.00 | 30.87 | 26.07 | 21.27 | 16.47 | 11.67 | 6.87 | 2.08 | 0.00 | 0.00 | 0.00 | 0.00 |
| 907.00 | 9 | 15.00 | 31.26 | 26.47 | 21.67 | 16.87 | 12.07 | 7.27 | 2.48 | 0.00 | 0.00 | 0.00 | 0.00 |
| 915.00 | 9 | 23.00 | 31.66 | 26.87 | 22.07 | 17.27 | 12.47 | 7.67 | 2.88 | 0.00 | 0.00 | 0.00 | 0.00 |
| 923.00 | 9 | 31.00 | 32.06 | 27.26 | 22.47 | 17.67 | 12.87 | 8.07 | 3.27 | 0.00 | 0.00 | 0.00 | 0.00 |
| 931.00 & ab | o | ve Add | 4.99 Percen | t To Excess | Over 931.0 | 0 |
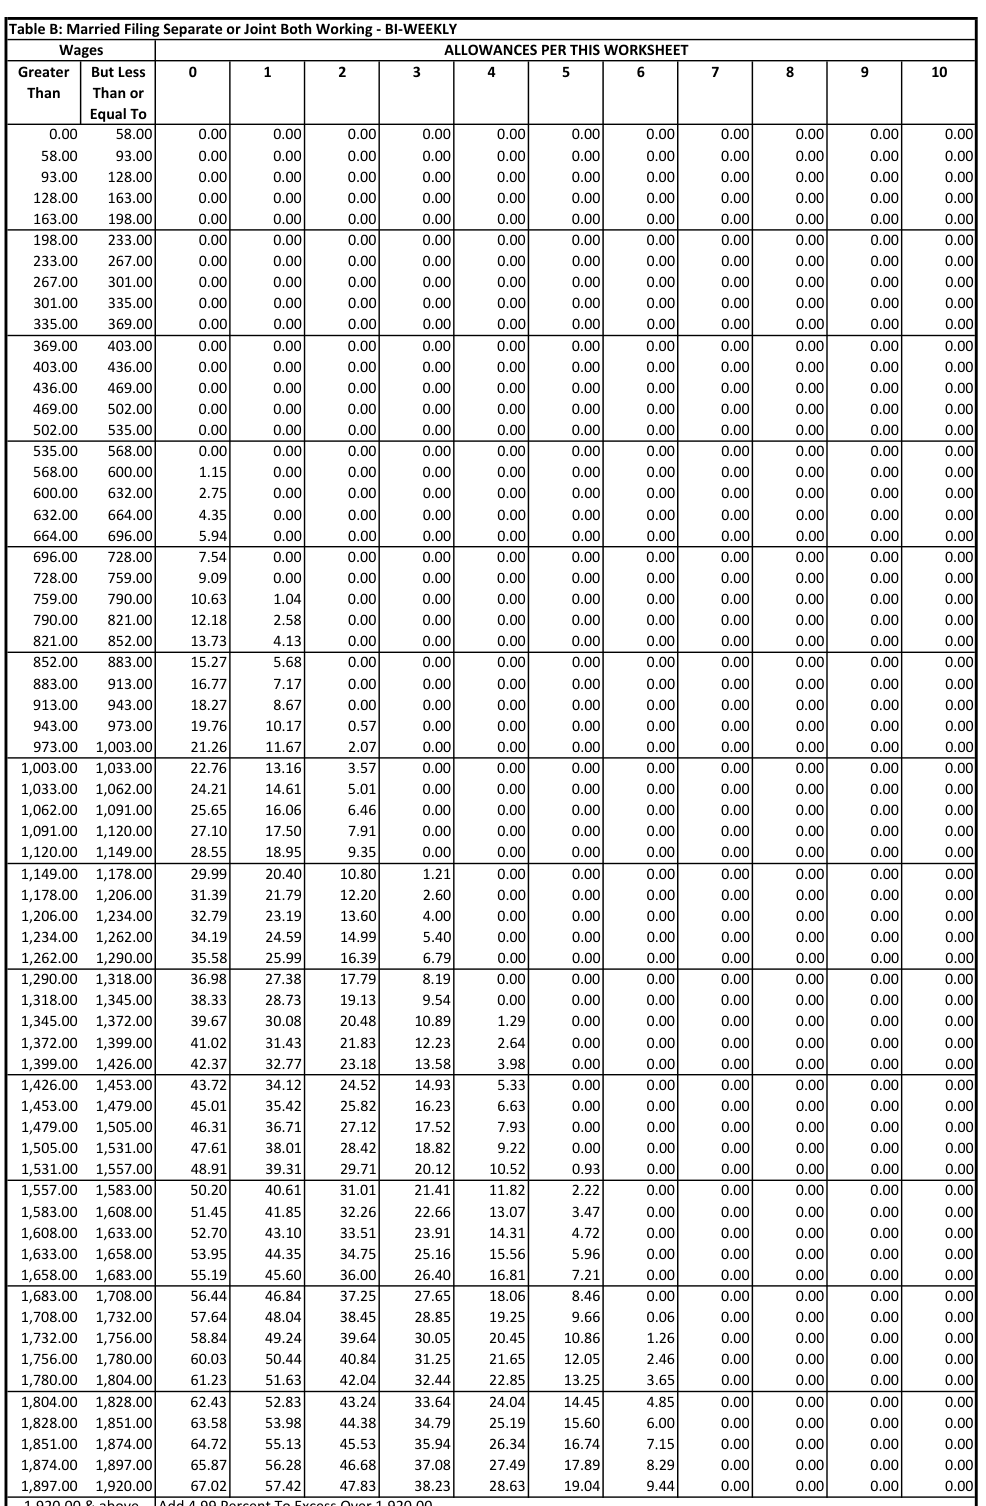
Text version of this table
| Wag | es | ALLOW | ANCES PER | THIS WORK | SHEET | |||||||
| Greater | But Less | 0 | 1 | 2 | 3 | 4 | 5 6 | 7 | 8 | 9 | 1 0 | |
| Than | Than or | |||||||||||
| Equal To | ||||||||||||
| 0.00 | 58.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 58.00 | 93.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 93.00 | 128.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 128.00 | 163.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 163.00 | 198.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 198.00 | 233.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 233.00 | 267.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 267.00 | 301.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 301.00 | 335.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 335.00 | 369.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 369.00 | 403.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 403.00 | 436.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 436.00 | 469.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 469.00 | 502.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 502.00 | 535.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 535.00 | 568.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 568.00 | 600.00 | 1.15 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 600.00 | 632.00 | 2.75 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 632.00 | 664.00 | 4.35 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 664.00 | 696.00 | 5.94 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 696.00 | 728.00 | 7.54 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 728.00 | 759.00 | 9.09 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 759.00 | 790.00 | 10.63 | 1.04 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 790.00 | 821.00 | 12.18 | 2.58 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 821.00 | 852.00 | 13.73 | 4.13 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 852.00 | 883.00 | 15.27 | 5.68 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 883.00 | 913.00 | 16.77 | 7.17 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 913.00 | 943.00 | 18.27 | 8.67 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 943.00 | 973.00 | 19.76 | 10.17 | 0.57 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 973.00 | 1,003.00 | 21.26 | 11.67 | 2.07 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,003.00 | 1,033.00 | 22.76 | 13.16 | 3.57 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,033.00 | 1,062.00 | 24.21 | 14.61 | 5.01 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,062.00 | 1,091.00 | 25.65 | 16.06 | 6.46 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,091.00 | 1,120.00 | 27.10 | 17.50 | 7.91 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,120.00 | 1,149.00 | 28.55 | 18.95 | 9.35 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,149.00 | 1,178.00 | 29.99 | 20.40 | 10.80 | 1.21 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,178.00 | 1,206.00 | 31.39 | 21.79 | 12.20 | 2.60 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,206.00 | 1,234.00 | 32.79 | 23.19 | 13.60 | 4.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,234.00 | 1,262.00 | 34.19 | 24.59 | 14.99 | 5.40 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,262.00 | 1,290.00 | 35.58 | 25.99 | 16.39 | 6.79 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,290.00 | 1,318.00 | 36.98 | 27.38 | 17.79 | 8.19 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,318.00 | 1,345.00 | 38.33 | 28.73 | 19.13 | 9.54 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,345.00 | 1,372.00 | 39.67 | 30.08 | 20.48 | 10.89 | 1.29 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,372.00 | 1,399.00 | 41.02 | 31.43 | 21.83 | 12.23 | 2.64 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,399.00 | 1,426.00 | 42.37 | 32.77 | 23.18 | 13.58 | 3.98 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,426.00 | 1,453.00 | 43.72 | 34.12 | 24.52 | 14.93 | 5.33 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,453.00 | 1,479.00 | 45.01 | 35.42 | 25.82 | 16.23 | 6.63 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,479.00 | 1,505.00 | 46.31 | 36.71 | 27.12 | 17.52 | 7.93 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,505.00 | 1,531.00 | 47.61 | 38.01 | 28.42 | 18.82 | 9.22 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,531.00 | 1,557.00 | 48.91 | 39.31 | 29.71 | 20.12 | 10.52 | 0.93 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,557.00 | 1,583.00 | 50.20 | 40.61 | 31.01 | 21.41 | 11.82 | 2.22 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,583.00 | 1,608.00 | 51.45 | 41.85 | 32.26 | 22.66 | 13.07 | 3.47 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,608.00 | 1,633.00 | 52.70 | 43.10 | 33.51 | 23.91 | 14.31 | 4.72 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,633.00 | 1,658.00 | 53.95 | 44.35 | 34.75 | 25.16 | 15.56 | 5.96 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,658.00 | 1,683.00 | 55.19 | 45.60 | 36.00 | 26.40 | 16.81 | 7.21 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,683.00 | 1,708.00 | 56.44 | 46.84 | 37.25 | 27.65 | 18.06 | 8.46 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,708.00 | 1,732.00 | 57.64 | 48.04 | 38.45 | 28.85 | 19.25 | 9.66 | 0.06 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,732.00 | 1,756.00 | 58.84 | 49.24 | 39.64 | 30.05 | 20.45 | 10.86 | 1.26 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,756.00 | 1,780.00 | 60.03 | 50.44 | 40.84 | 31.25 | 21.65 | 12.05 | 2.46 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,780.00 | 1,804.00 | 61.23 | 51.63 | 42.04 | 32.44 | 22.85 | 13.25 | 3.65 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,804.00 | 1,828.00 | 62.43 | 52.83 | 43.24 | 33.64 | 24.04 | 14.45 | 4.85 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,828.00 | 1,851.00 | 63.58 | 53.98 | 44.38 | 34.79 | 25.19 | 15.60 | 6.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,851.00 | 1,874.00 | 64.72 | 55.13 | 45.53 | 35.94 | 26.34 | 16.74 | 7.15 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,874.00 | 1,897.00 | 65.87 | 56.28 | 46.68 | 37.08 | 27.49 | 17.89 | 8.29 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,897.00 | 1,920.00 | 67.02 | 57.42 | 47.83 | 38.23 | 28.63 | 19.04 | 9.44 | 0.00 | 0.00 | 0.00 | 0.00 |
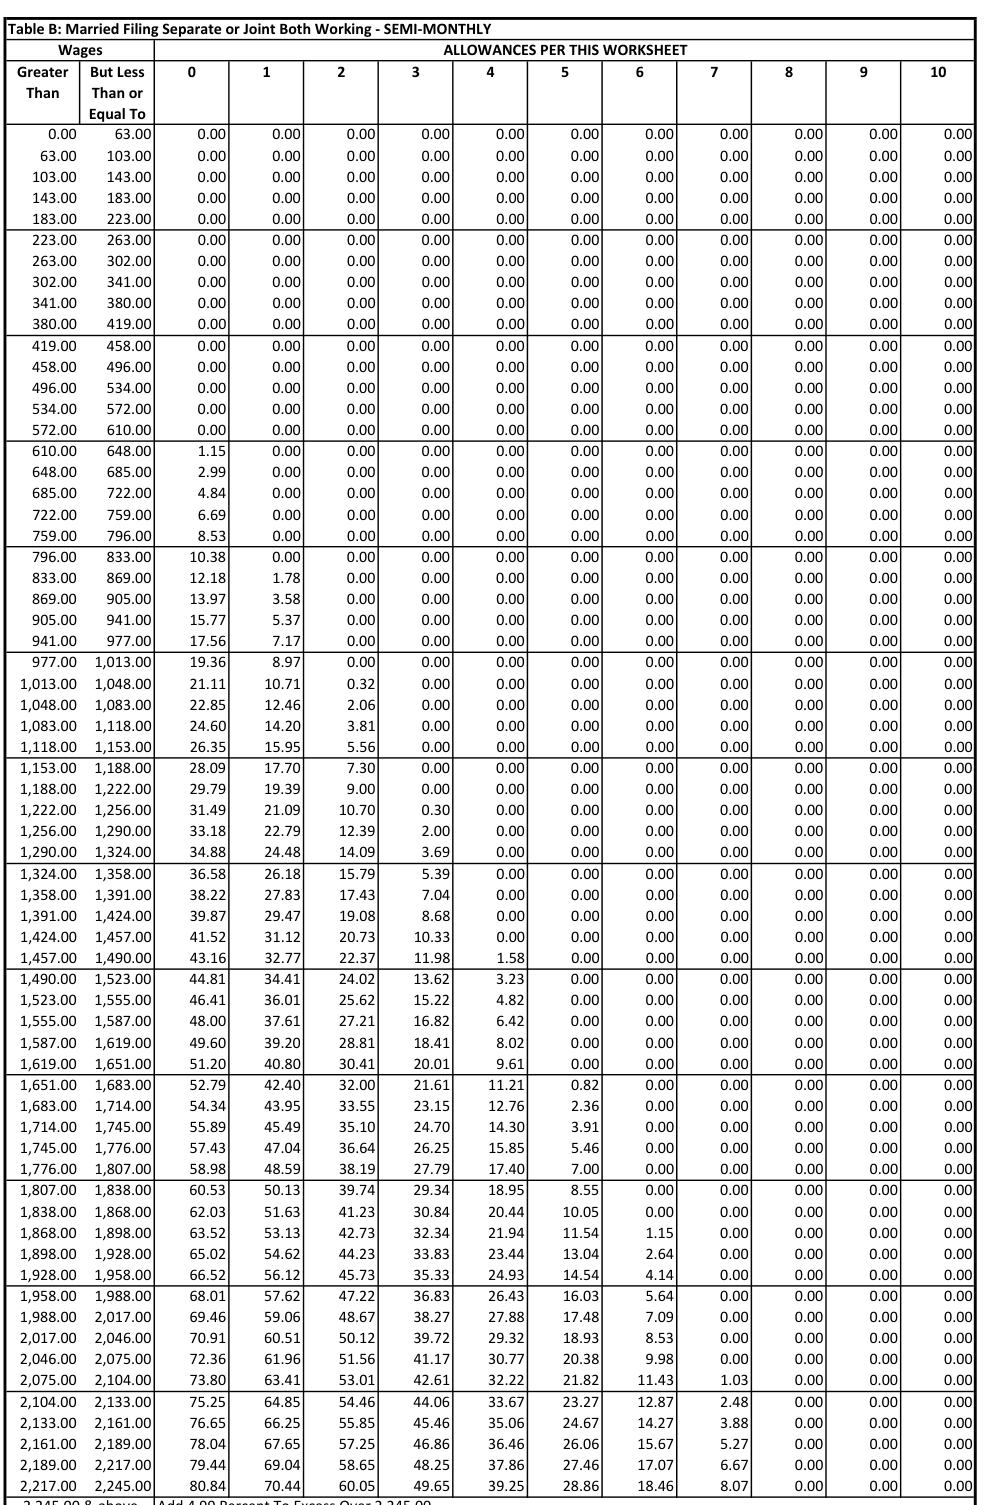
Text version of this table
| Wag | es | ALLOW | ANCES PER | THIS WOR | KSHEET | |||||||
| Greater | But Less | 0 | 1 | 2 | 3 | 4 | 5 | 6 7 | 8 | 9 | 1 0 | |
| Than | Than or | |||||||||||
| Equal To | ||||||||||||
| 0.00 | 63.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 63.00 | 103.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 103.00 | 143.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 143.00 | 183.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 183.00 | 223.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 223.00 | 263.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 263.00 | 302.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 302.00 | 341.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 341.00 | 380.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 380.00 | 419.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 419.00 | 458.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 458.00 | 496.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 496.00 | 534.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 534.00 | 572.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 572.00 | 610.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 610.00 | 648.00 | 1.15 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 648.00 | 685.00 | 2.99 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 685.00 | 722.00 | 4.84 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 722.00 | 759.00 | 6.69 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 759.00 | 796.00 | 8.53 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 796.00 | 833.00 | 10.38 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 833.00 | 869.00 | 12.18 | 1.78 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 869.00 | 905.00 | 13.97 | 3.58 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 905.00 | 941.00 | 15.77 | 5.37 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 941.00 | 977.00 | 17.56 | 7.17 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 977.00 | 1,013.00 | 19.36 | 8.97 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,013.00 | 1,048.00 | 21.11 | 10.71 | 0.32 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,048.00 | 1,083.00 | 22.85 | 12.46 | 2.06 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,083.00 | 1,118.00 | 24.60 | 14.20 | 3.81 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,118.00 | 1,153.00 | 26.35 | 15.95 | 5.56 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,153.00 | 1,188.00 | 28.09 | 17.70 | 7.30 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,188.00 | 1,222.00 | 29.79 | 19.39 | 9.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,222.00 | 1,256.00 | 31.49 | 21.09 | 10.70 | 0.30 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,256.00 | 1,290.00 | 33.18 | 22.79 | 12.39 | 2.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,290.00 | 1,324.00 | 34.88 | 24.48 | 14.09 | 3.69 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,324.00 | 1,358.00 | 36.58 | 26.18 | 15.79 | 5.39 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,358.00 | 1,391.00 | 38.22 | 27.83 | 17.43 | 7.04 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,391.00 | 1,424.00 | 39.87 | 29.47 | 19.08 | 8.68 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,424.00 | 1,457.00 | 41.52 | 31.12 | 20.73 | 10.33 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,457.00 | 1,490.00 | 43.16 | 32.77 | 22.37 | 11.98 | 1.58 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,490.00 | 1,523.00 | 44.81 | 34.41 | 24.02 | 13.62 | 3.23 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,523.00 | 1,555.00 | 46.41 | 36.01 | 25.62 | 15.22 | 4.82 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,555.00 | 1,587.00 | 48.00 | 37.61 | 27.21 | 16.82 | 6.42 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,587.00 | 1,619.00 | 49.60 | 39.20 | 28.81 | 18.41 | 8.02 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,619.00 | 1,651.00 | 51.20 | 40.80 | 30.41 | 20.01 | 9.61 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,651.00 | 1,683.00 | 52.79 | 42.40 | 32.00 | 21.61 | 11.21 | 0.82 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,683.00 | 1,714.00 | 54.34 | 43.95 | 33.55 | 23.15 | 12.76 | 2.36 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,714.00 | 1,745.00 | 55.89 | 45.49 | 35.10 | 24.70 | 14.30 | 3.91 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,745.00 | 1,776.00 | 57.43 | 47.04 | 36.64 | 26.25 | 15.85 | 5.46 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,776.00 | 1,807.00 | 58.98 | 48.59 | 38.19 | 27.79 | 17.40 | 7.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,807.00 | 1,838.00 | 60.53 | 50.13 | 39.74 | 29.34 | 18.95 | 8.55 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,838.00 | 1,868.00 | 62.03 | 51.63 | 41.23 | 30.84 | 20.44 | 10.05 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,868.00 | 1,898.00 | 63.52 | 53.13 | 42.73 | 32.34 | 21.94 | 11.54 | 1.15 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,898.00 | 1,928.00 | 65.02 | 54.62 | 44.23 | 33.83 | 23.44 | 13.04 | 2.64 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,928.00 | 1,958.00 | 66.52 | 56.12 | 45.73 | 35.33 | 24.93 | 14.54 | 4.14 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,958.00 | 1,988.00 | 68.01 | 57.62 | 47.22 | 36.83 | 26.43 | 16.03 | 5.64 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,988.00 | 2,017.00 | 69.46 | 59.06 | 48.67 | 38.27 | 27.88 | 17.48 | 7.09 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,017.00 | 2,046.00 | 70.91 | 60.51 | 50.12 | 39.72 | 29.32 | 18.93 | 8.53 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,046.00 | 2,075.00 | 72.36 | 61.96 | 51.56 | 41.17 | 30.77 | 20.38 | 9.98 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,075.00 | 2,104.00 | 73.80 | 63.41 | 53.01 | 42.61 | 32.22 | 21.82 | 11.43 | 1.03 | 0.00 | 0.00 | 0.00 |
| 2,104.00 | 2,133.00 | 75.25 | 64.85 | 54.46 | 44.06 | 33.67 | 23.27 | 12.87 | 2.48 | 0.00 | 0.00 | 0.00 |
| 2,133.00 | 2,161.00 | 76.65 | 66.25 | 55.85 | 45.46 | 35.06 | 24.67 | 14.27 | 3.88 | 0.00 | 0.00 | 0.00 |
| 2,161.00 | 2,189.00 | 78.04 | 67.65 | 57.25 | 46.86 | 36.46 | 26.06 | 15.67 | 5.27 | 0.00 | 0.00 | 0.00 |
| 2,189.00 | 2,217.00 | 79.44 | 69.04 | 58.65 | 48.25 | 37.86 | 27.46 | 17.07 | 6.67 | 0.00 | 0.00 | 0.00 |
| 2,217.00 | 2,245.00 | 80.84 | 70.44 | 60.05 | 49.65 | 39.25 | 28.86 | 18.46 | 8.07 | 0.00 | 0.00 | 0.00 |
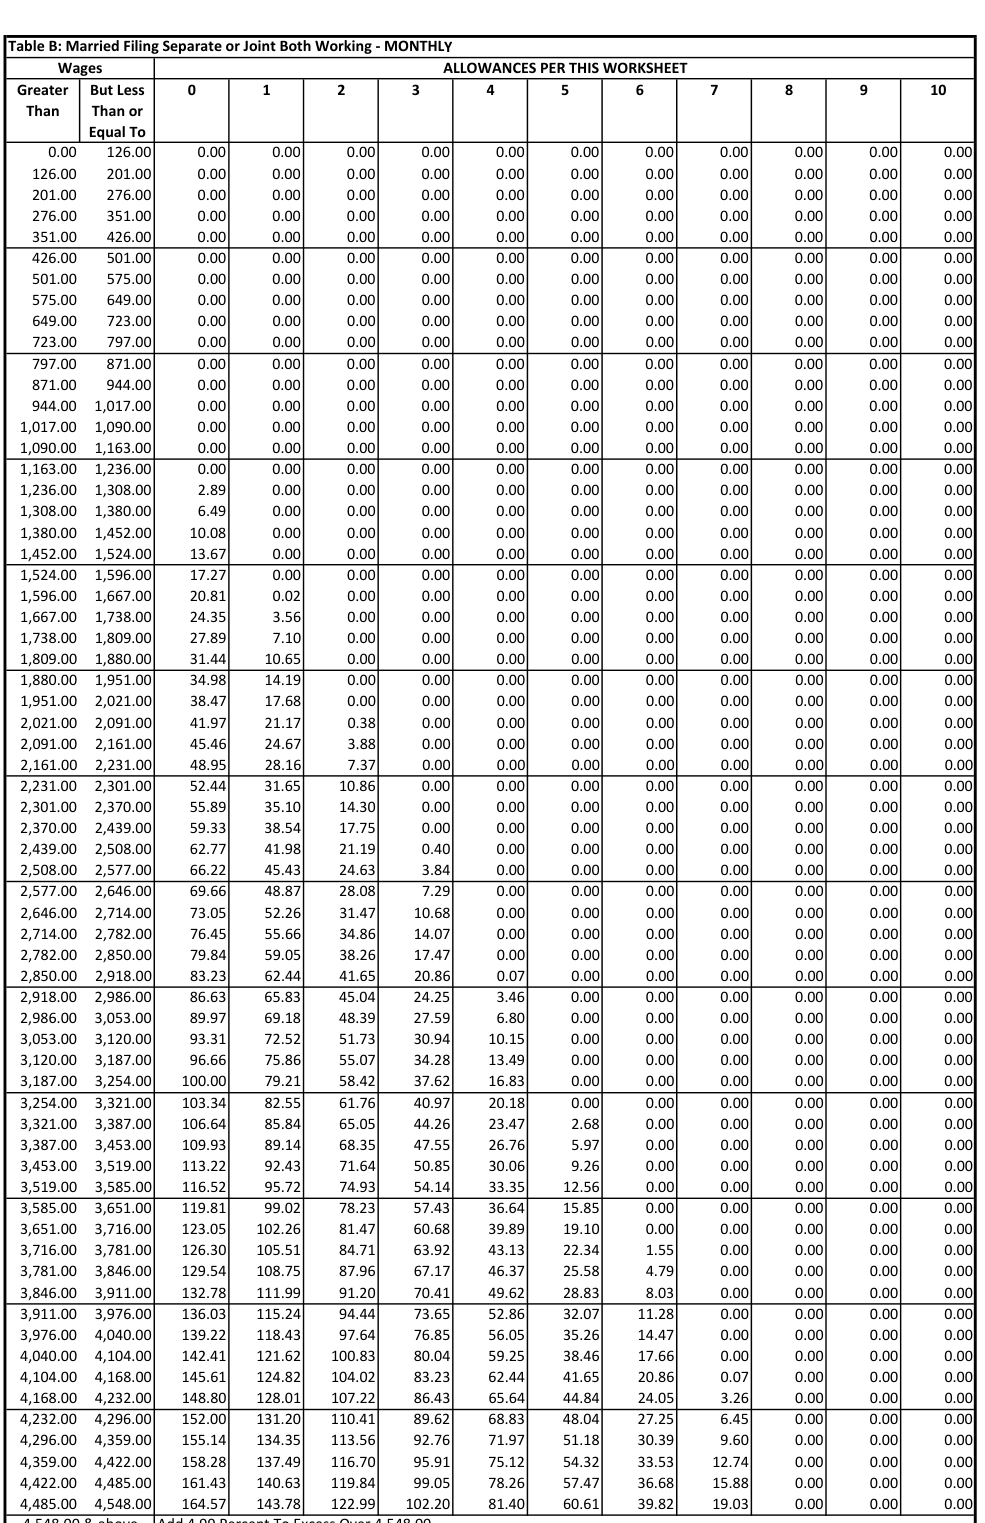
Text version of this table
| able B: Mar | ried Filing Se | parate or Jo | int Both W | orking - | MONTHLY | |||||||
| Wag | es | ALLOW | ANCES PER | THIS WOR | KSHEET | |||||||
| Greater | But Less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 8 | 9 | 1 0 | |
| Than | Than or | |||||||||||
| Equal To | ||||||||||||
| 0.00 | 126.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 126.00 | 201.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 201.00 | 276.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 276.00 | 351.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 351.00 | 426.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 426.00 | 501.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 501.00 | 575.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 575.00 | 649.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 649.00 | 723.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 723.00 | 797.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 797.00 | 871.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 871.00 | 944.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 944.00 | 1,017.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,017.00 | 1,090.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,090.00 | 1,163.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,163.00 | 1,236.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,236.00 | 1,308.00 | 2.89 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,308.00 | 1,380.00 | 6.49 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,380.00 | 1,452.00 | 10.08 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,452.00 | 1,524.00 | 13.67 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,524.00 | 1,596.00 | 17.27 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,596.00 | 1,667.00 | 20.81 | 0.02 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,667.00 | 1,738.00 | 24.35 | 3.56 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,738.00 | 1,809.00 | 27.89 | 7.10 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,809.00 | 1,880.00 | 31.44 | 10.65 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,880.00 | 1,951.00 | 34.98 | 14.19 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,951.00 | 2,021.00 | 38.47 | 17.68 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,021.00 | 2,091.00 | 41.97 | 21.17 | 0.38 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,091.00 | 2,161.00 | 45.46 | 24.67 | 3.88 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,161.00 | 2,231.00 | 48.95 | 28.16 | 7.37 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,231.00 | 2,301.00 | 52.44 | 31.65 | 10.86 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,301.00 | 2,370.00 | 55.89 | 35.10 | 14.30 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,370.00 | 2,439.00 | 59.33 | 38.54 | 17.75 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,439.00 | 2,508.00 | 62.77 | 41.98 | 21.19 | 0.40 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,508.00 | 2,577.00 | 66.22 | 45.43 | 24.63 | 3.84 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,577.00 | 2,646.00 | 69.66 | 48.87 | 28.08 | 7.29 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,646.00 | 2,714.00 | 73.05 | 52.26 | 31.47 | 10.68 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,714.00 | 2,782.00 | 76.45 | 55.66 | 34.86 | 14.07 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,782.00 | 2,850.00 | 79.84 | 59.05 | 38.26 | 17.47 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,850.00 | 2,918.00 | 83.23 | 62.44 | 41.65 | 20.86 | 0.07 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,918.00 | 2,986.00 | 86.63 | 65.83 | 45.04 | 24.25 | 3.46 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,986.00 | 3,053.00 | 89.97 | 69.18 | 48.39 | 27.59 | 6.80 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,053.00 | 3,120.00 | 93.31 | 72.52 | 51.73 | 30.94 | 10.15 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,120.00 | 3,187.00 | 96.66 | 75.86 | 55.07 | 34.28 | 13.49 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,187.00 | 3,254.00 | 100.00 | 79.21 | 58.42 | 37.62 | 16.83 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,254.00 | 3,321.00 | 103.34 | 82.55 | 61.76 | 40.97 | 20.18 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,321.00 | 3,387.00 | 106.64 | 85.84 | 65.05 | 44.26 | 23.47 | 2.68 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,387.00 | 3,453.00 | 109.93 | 89.14 | 68.35 | 47.55 | 26.76 | 5.97 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,453.00 | 3,519.00 | 113.22 | 92.43 | 71.64 | 50.85 | 30.06 | 9.26 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,519.00 | 3,585.00 | 116.52 | 95.72 | 74.93 | 54.14 | 33.35 | 12.56 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,585.00 | 3,651.00 | 119.81 | 99.02 | 78.23 | 57.43 | 36.64 | 15.85 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,651.00 | 3,716.00 | 123.05 | 102.26 | 81.47 | 60.68 | 39.89 | 19.10 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,716.00 | 3,781.00 | 126.30 | 105.51 | 84.71 | 63.92 | 43.13 | 22.34 | 1.55 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,781.00 | 3,846.00 | 129.54 | 108.75 | 87.96 | 67.17 | 46.37 | 25.58 | 4.79 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,846.00 | 3,911.00 | 132.78 | 111.99 | 91.20 | 70.41 | 49.62 | 28.83 | 8.03 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,911.00 | 3,976.00 | 136.03 | 115.24 | 94.44 | 73.65 | 52.86 | 32.07 | 11.28 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,976.00 | 4,040.00 | 139.22 | 118.43 | 97.64 | 76.85 | 56.05 | 35.26 | 14.47 | 0.00 | 0.00 | 0.00 | 0.00 |
| 4,040.00 | 4,104.00 | 142.41 | 121.62 | 100.83 | 80.04 | 59.25 | 38.46 | 17.66 | 0.00 | 0.00 | 0.00 | 0.00 |
| 4,104.00 | 4,168.00 | 145.61 | 124.82 | 104.02 | 83.23 | 62.44 | 41.65 | 20.86 | 0.07 | 0.00 | 0.00 | 0.00 |
| 4,168.00 | 4,232.00 | 148.80 | 128.01 | 107.22 | 86.43 | 65.64 | 44.84 | 24.05 | 3.26 | 0.00 | 0.00 | 0.00 |
| 4,232.00 | 4,296.00 | 152.00 | 131.20 | 110.41 | 89.62 | 68.83 | 48.04 | 27.25 | 6.45 | 0.00 | 0.00 | 0.00 |
| 4,296.00 | 4,359.00 | 155.14 | 134.35 | 113.56 | 92.76 | 71.97 | 51.18 | 30.39 | 9.60 | 0.00 | 0.00 | 0.00 |
| 4,359.00 | 4,422.00 | 158.28 | 137.49 | 116.70 | 95.91 | 75.12 | 54.32 | 33.53 | 12.74 | 0.00 | 0.00 | 0.00 |
| 4,422.00 | 4,485.00 | 161.43 | 140.63 | 119.84 | 99.05 | 78.26 | 57.47 | 36.68 | 15.88 | 0.00 | 0.00 | 0.00 |
| 4,485.00 | 4,548.00 | 164.57 | 143.78 | 122.99 | 102.20 | 81.40 | 60.61 | 39.82 | 19.03 | 0.00 | 0.00 | 0.00 |
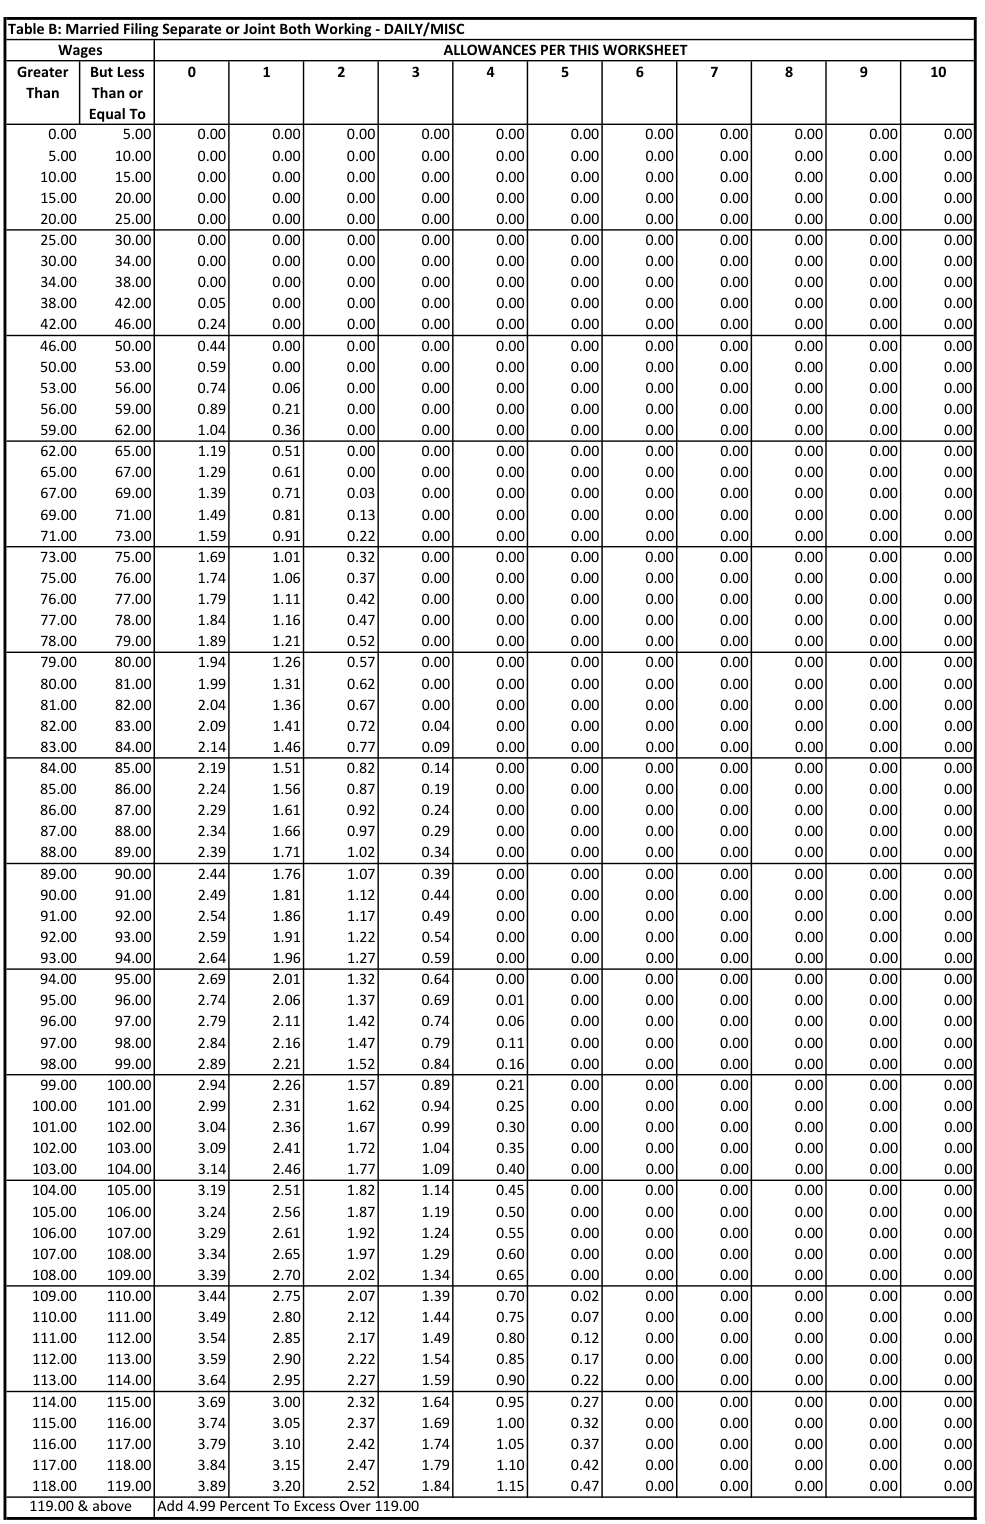
Text version of this table
| Wages | ALLOW | ANCES PER | THIS WORK | SHEET | |||||||||
| eater Bu | t | Less 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 1 0 | |
| han Th | a | n or | |||||||||||
| Eq | u | al To | |||||||||||
| 0.00 | 5.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 5.00 | 10.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 10.00 | 15.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 15.00 | 20.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 20.00 | 25.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 25.00 | 30.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 30.00 | 34.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 34.00 | 38.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 38.00 | 42.00 | 0.05 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 42.00 | 46.00 | 0.24 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 46.00 | 50.00 | 0.44 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 50.00 | 53.00 | 0.59 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 53.00 | 56.00 | 0.74 | 0.06 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 56.00 | 59.00 | 0.89 | 0.21 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 59.00 | 62.00 | 1.04 | 0.36 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 62.00 | 65.00 | 1.19 | 0.51 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 65.00 | 67.00 | 1.29 | 0.61 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 67.00 | 69.00 | 1.39 | 0.71 | 0.03 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 69.00 | 71.00 | 1.49 | 0.81 | 0.13 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 71.00 | 73.00 | 1.59 | 0.91 | 0.22 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 73.00 | 75.00 | 1.69 | 1.01 | 0.32 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 75.00 | 76.00 | 1.74 | 1.06 | 0.37 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 76.00 | 77.00 | 1.79 | 1.11 | 0.42 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 77.00 | 78.00 | 1.84 | 1.16 | 0.47 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 78.00 | 79.00 | 1.89 | 1.21 | 0.52 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 79.00 | 80.00 | 1.94 | 1.26 | 0.57 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 80.00 | 81.00 | 1.99 | 1.31 | 0.62 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 81.00 | 82.00 | 2.04 | 1.36 | 0.67 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 82.00 | 83.00 | 2.09 | 1.41 | 0.72 | 0.04 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 83.00 | 84.00 | 2.14 | 1.46 | 0.77 | 0.09 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 84.00 | 85.00 | 2.19 | 1.51 | 0.82 | 0.14 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 85.00 | 86.00 | 2.24 | 1.56 | 0.87 | 0.19 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 86.00 | 87.00 | 2.29 | 1.61 | 0.92 | 0.24 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 87.00 | 88.00 | 2.34 | 1.66 | 0.97 | 0.29 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 88.00 | 89.00 | 2.39 | 1.71 | 1.02 | 0.34 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 89.00 | 90.00 | 2.44 | 1.76 | 1.07 | 0.39 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 90.00 | 91.00 | 2.49 | 1.81 | 1.12 | 0.44 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 91.00 | 92.00 | 2.54 | 1.86 | 1.17 | 0.49 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 92.00 | 93.00 | 2.59 | 1.91 | 1.22 | 0.54 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 93.00 | 94.00 | 2.64 | 1.96 | 1.27 | 0.59 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 94.00 | 95.00 | 2.69 | 2.01 | 1.32 | 0.64 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 95.00 | 96.00 | 2.74 | 2.06 | 1.37 | 0.69 | 0.01 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 96.00 | 97.00 | 2.79 | 2.11 | 1.42 | 0.74 | 0.06 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 97.00 | 98.00 | 2.84 | 2.16 | 1.47 | 0.79 | 0.11 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 98.00 | 99.00 | 2.89 | 2.21 | 1.52 | 0.84 | 0.16 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 99.00 | 1 | 00.00 | 2.94 | 2.26 | 1.57 | 0.89 | 0.21 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 100.00 | 1 | 01.00 | 2.99 | 2.31 | 1.62 | 0.94 | 0.25 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 101.00 | 1 | 02.00 | 3.04 | 2.36 | 1.67 | 0.99 | 0.30 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 102.00 | 1 | 03.00 | 3.09 | 2.41 | 1.72 | 1.04 | 0.35 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 103.00 | 1 | 04.00 | 3.14 | 2.46 | 1.77 | 1.09 | 0.40 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 104.00 | 1 | 05.00 | 3.19 | 2.51 | 1.82 | 1.14 | 0.45 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 105.00 | 1 | 06.00 | 3.24 | 2.56 | 1.87 | 1.19 | 0.50 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 106.00 | 1 | 07.00 | 3.29 | 2.61 | 1.92 | 1.24 | 0.55 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 107.00 | 1 | 08.00 | 3.34 | 2.65 | 1.97 | 1.29 | 0.60 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 108.00 | 1 | 09.00 | 3.39 | 2.70 | 2.02 | 1.34 | 0.65 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 109.00 | 1 | 10.00 | 3.44 | 2.75 | 2.07 | 1.39 | 0.70 | 0.02 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 110.00 | 1 | 11.00 | 3.49 | 2.80 | 2.12 | 1.44 | 0.75 | 0.07 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 111.00 | 1 | 12.00 | 3.54 | 2.85 | 2.17 | 1.49 | 0.80 | 0.12 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 112.00 | 1 | 13.00 | 3.59 | 2.90 | 2.22 | 1.54 | 0.85 | 0.17 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 113.00 | 1 | 14.00 | 3.64 | 2.95 | 2.27 | 1.59 | 0.90 | 0.22 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 114.00 | 1 | 15.00 | 3.69 | 3.00 | 2.32 | 1.64 | 0.95 | 0.27 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 115.00 | 1 | 16.00 | 3.74 | 3.05 | 2.37 | 1.69 | 1.00 | 0.32 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 116.00 | 1 | 17.00 | 3.79 | 3.10 | 2.42 | 1.74 | 1.05 | 0.37 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 117.00 | 1 | 18.00 | 3.84 | 3.15 | 2.47 | 1.79 | 1.10 | 0.42 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 118.00 | 1 | 19.00 | 3.89 | 3.20 | 2.52 | 1.84 | 1.15 | 0.47 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 119.00 & ab | o | ve Add 4. | 99 Percent | To Excess O | ver 119.00 |
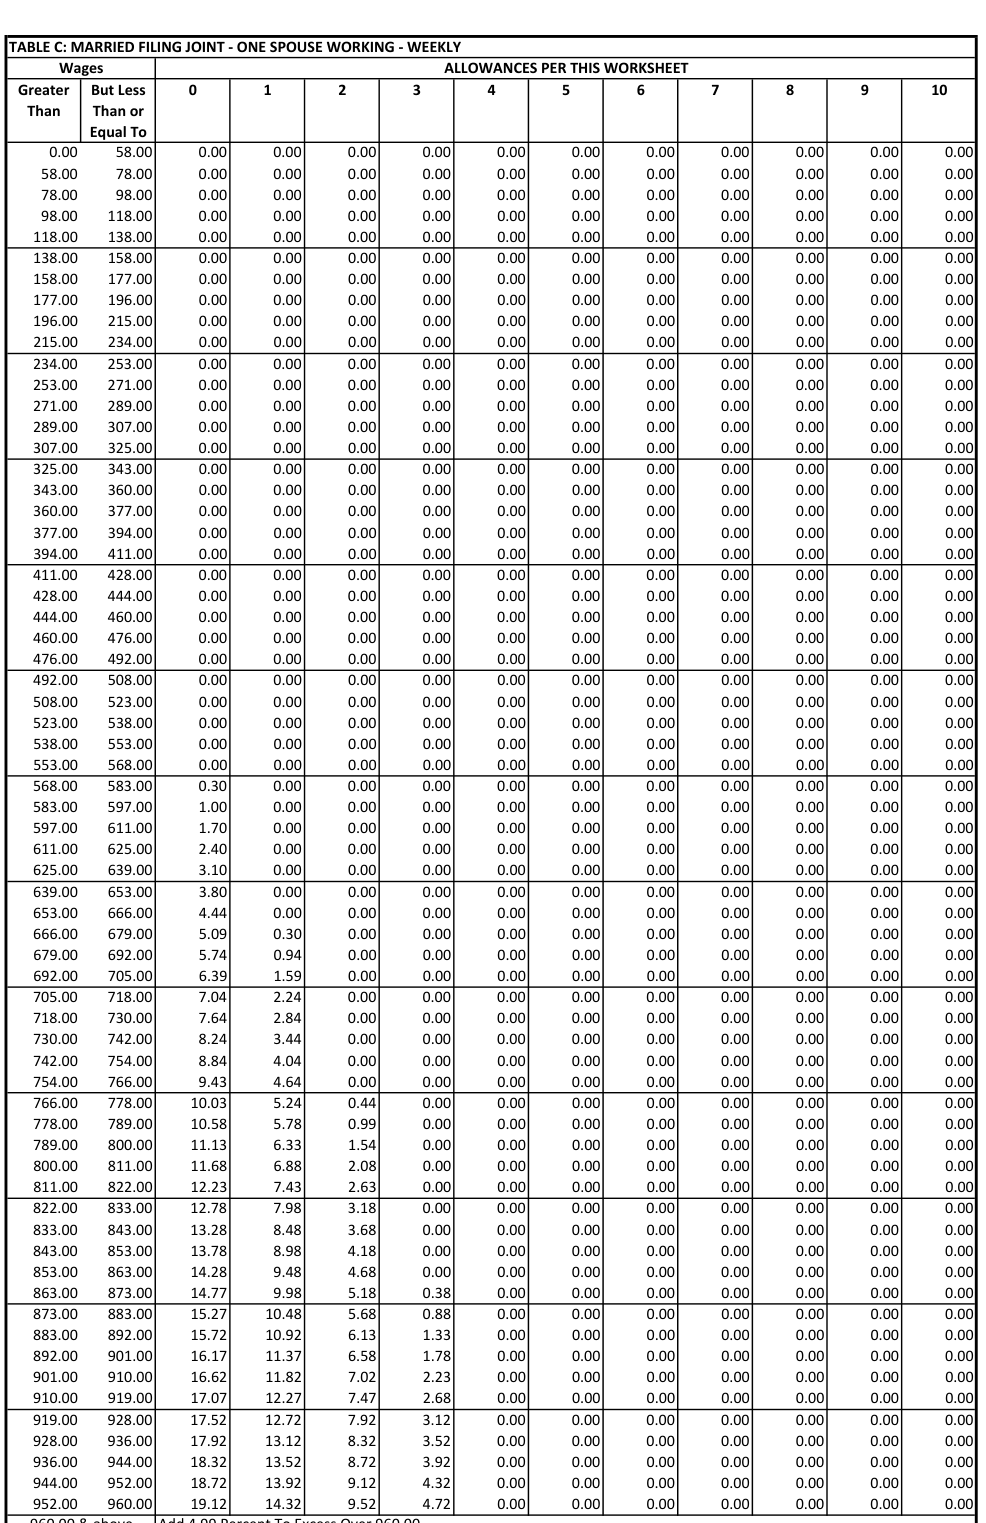
Text version of this table
| LE C: MAR | RI | ED FILING J | OINT - ONE | SPOUSE | WORKING - W | EEKLY | |||||||
| Wages | ALLOW | ANCES PER | THIS WORK | SHEET | |||||||||
| eater Bu | t | Less | 0 | 1 | 2 3 | 4 | 5 | 6 | 7 | 8 | 9 | 1 0 | |
| han Th | a | n or | |||||||||||
| Eq | u | al To | |||||||||||
| 0.00 | 58.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 58.00 | 78.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 78.00 | 98.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 98.00 | 1 | 18.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 118.00 | 1 | 38.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 138.00 | 1 | 58.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 158.00 | 1 | 77.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 177.00 | 1 | 96.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 196.00 | 2 | 15.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 215.00 | 2 | 34.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 234.00 | 2 | 53.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 253.00 | 2 | 71.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 271.00 | 2 | 89.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 289.00 | 3 | 07.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 307.00 | 3 | 25.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 325.00 | 3 | 43.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 343.00 | 3 | 60.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 360.00 | 3 | 77.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 377.00 | 3 | 94.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 394.00 | 4 | 11.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 411.00 | 4 | 28.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 428.00 | 4 | 44.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 444.00 | 4 | 60.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 460.00 | 4 | 76.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 476.00 | 4 | 92.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 492.00 | 5 | 08.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 508.00 | 5 | 23.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 523.00 | 5 | 38.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 538.00 | 5 | 53.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 553.00 | 5 | 68.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 568.00 | 5 | 83.00 | 0.30 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 583.00 | 5 | 97.00 | 1.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 597.00 | 6 | 11.00 | 1.70 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 611.00 | 6 | 25.00 | 2.40 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 625.00 | 6 | 39.00 | 3.10 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 639.00 | 6 | 53.00 | 3.80 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 653.00 | 6 | 66.00 | 4.44 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 666.00 | 6 | 79.00 | 5.09 | 0.30 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 679.00 | 6 | 92.00 | 5.74 | 0.94 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 692.00 | 7 | 05.00 | 6.39 | 1.59 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 705.00 | 7 | 18.00 | 7.04 | 2.24 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 718.00 | 7 | 30.00 | 7.64 | 2.84 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 730.00 | 7 | 42.00 | 8.24 | 3.44 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 742.00 | 7 | 54.00 | 8.84 | 4.04 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 754.00 | 7 | 66.00 | 9.43 | 4.64 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 766.00 | 7 | 78.00 | 10.03 | 5.24 | 0.44 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 778.00 | 7 | 89.00 | 10.58 | 5.78 | 0.99 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 789.00 | 8 | 00.00 | 11.13 | 6.33 | 1.54 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 800.00 | 8 | 11.00 | 11.68 | 6.88 | 2.08 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 811.00 | 8 | 22.00 | 12.23 | 7.43 | 2.63 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 822.00 | 8 | 33.00 | 12.78 | 7.98 | 3.18 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 833.00 | 8 | 43.00 | 13.28 | 8.48 | 3.68 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 843.00 | 8 | 53.00 | 13.78 | 8.98 | 4.18 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 853.00 | 8 | 63.00 | 14.28 | 9.48 | 4.68 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 863.00 | 8 | 73.00 | 14.77 | 9.98 | 5.18 | 0.38 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 873.00 | 8 | 83.00 | 15.27 | 10.48 | 5.68 | 0.88 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 883.00 | 8 | 92.00 | 15.72 | 10.92 | 6.13 | 1.33 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 892.00 | 9 | 01.00 | 16.17 | 11.37 | 6.58 | 1.78 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 901.00 | 9 | 10.00 | 16.62 | 11.82 | 7.02 | 2.23 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 910.00 | 9 | 19.00 | 17.07 | 12.27 | 7.47 | 2.68 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 919.00 | 9 | 28.00 | 17.52 | 12.72 | 7.92 | 3.12 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 928.00 | 9 | 36.00 | 17.92 | 13.12 | 8.32 | 3.52 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 936.00 | 9 | 44.00 | 18.32 | 13.52 | 8.72 | 3.92 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 944.00 | 9 | 52.00 | 18.72 | 13.92 | 9.12 | 4.32 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 952.00 | 9 | 60.00 | 19.12 | 14.32 | 9.52 | 4.72 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
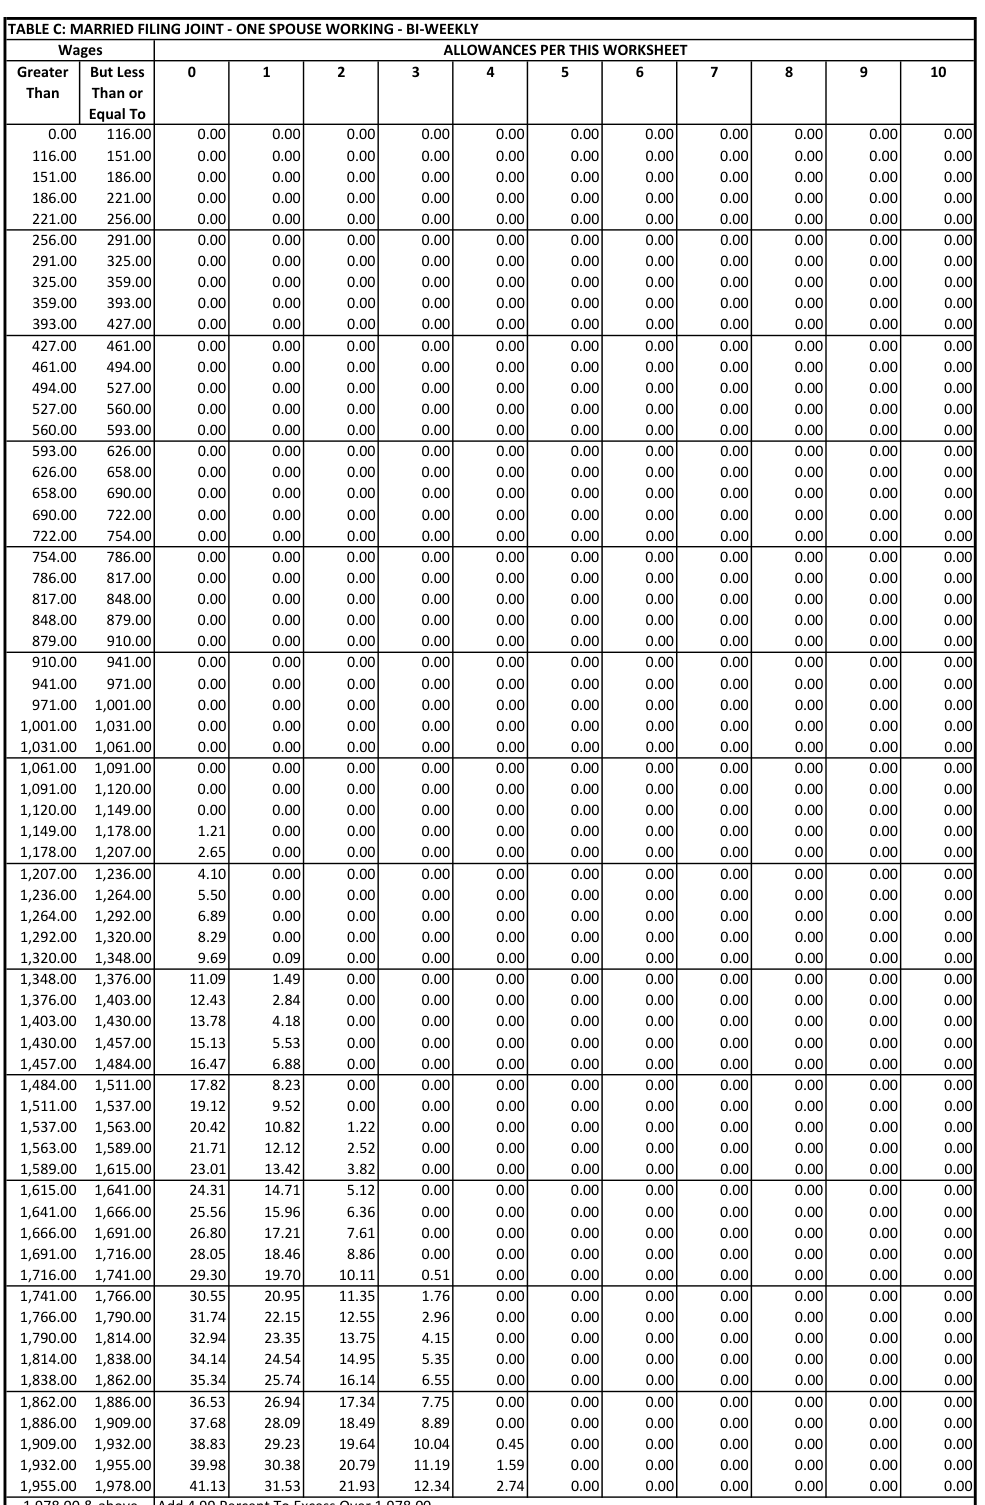
Text version of this table
| Wag | es | ALLOW | ANCES PER | THIS WORK | SHEET | |||||||
| Greater | But Less | 0 | 1 | 2 | 3 4 | 5 | 6 | 7 | 8 | 9 | 1 0 | |
| Than | Than or | |||||||||||
| Equal To | ||||||||||||
| 0.00 | 116.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 116.00 | 151.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 151.00 | 186.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 186.00 | 221.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 221.00 | 256.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 256.00 | 291.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 291.00 | 325.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 325.00 | 359.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 359.00 | 393.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 393.00 | 427.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 427.00 | 461.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 461.00 | 494.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 494.00 | 527.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 527.00 | 560.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 560.00 | 593.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 593.00 | 626.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 626.00 | 658.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 658.00 | 690.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 690.00 | 722.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 722.00 | 754.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 754.00 | 786.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 786.00 | 817.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 817.00 | 848.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 848.00 | 879.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 879.00 | 910.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 910.00 | 941.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 941.00 | 971.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 971.00 | 1,001.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,001.00 | 1,031.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,031.00 | 1,061.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,061.00 | 1,091.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,091.00 | 1,120.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,120.00 | 1,149.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,149.00 | 1,178.00 | 1.21 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,178.00 | 1,207.00 | 2.65 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,207.00 | 1,236.00 | 4.10 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,236.00 | 1,264.00 | 5.50 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,264.00 | 1,292.00 | 6.89 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,292.00 | 1,320.00 | 8.29 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,320.00 | 1,348.00 | 9.69 | 0.09 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,348.00 | 1,376.00 | 11.09 | 1.49 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,376.00 | 1,403.00 | 12.43 | 2.84 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,403.00 | 1,430.00 | 13.78 | 4.18 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,430.00 | 1,457.00 | 15.13 | 5.53 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,457.00 | 1,484.00 | 16.47 | 6.88 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,484.00 | 1,511.00 | 17.82 | 8.23 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,511.00 | 1,537.00 | 19.12 | 9.52 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,537.00 | 1,563.00 | 20.42 | 10.82 | 1.22 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,563.00 | 1,589.00 | 21.71 | 12.12 | 2.52 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,589.00 | 1,615.00 | 23.01 | 13.42 | 3.82 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,615.00 | 1,641.00 | 24.31 | 14.71 | 5.12 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,641.00 | 1,666.00 | 25.56 | 15.96 | 6.36 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,666.00 | 1,691.00 | 26.80 | 17.21 | 7.61 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,691.00 | 1,716.00 | 28.05 | 18.46 | 8.86 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,716.00 | 1,741.00 | 29.30 | 19.70 | 10.11 | 0.51 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,741.00 | 1,766.00 | 30.55 | 20.95 | 11.35 | 1.76 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,766.00 | 1,790.00 | 31.74 | 22.15 | 12.55 | 2.96 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,790.00 | 1,814.00 | 32.94 | 23.35 | 13.75 | 4.15 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,814.00 | 1,838.00 | 34.14 | 24.54 | 14.95 | 5.35 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,838.00 | 1,862.00 | 35.34 | 25.74 | 16.14 | 6.55 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,862.00 | 1,886.00 | 36.53 | 26.94 | 17.34 | 7.75 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,886.00 | 1,909.00 | 37.68 | 28.09 | 18.49 | 8.89 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,909.00 | 1,932.00 | 38.83 | 29.23 | 19.64 | 10.04 | 0.45 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,932.00 | 1,955.00 | 39.98 | 30.38 | 20.79 | 11.19 | 1.59 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,955.00 | 1,978.00 | 41.13 | 31.53 | 21.93 | 12.34 | 2.74 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
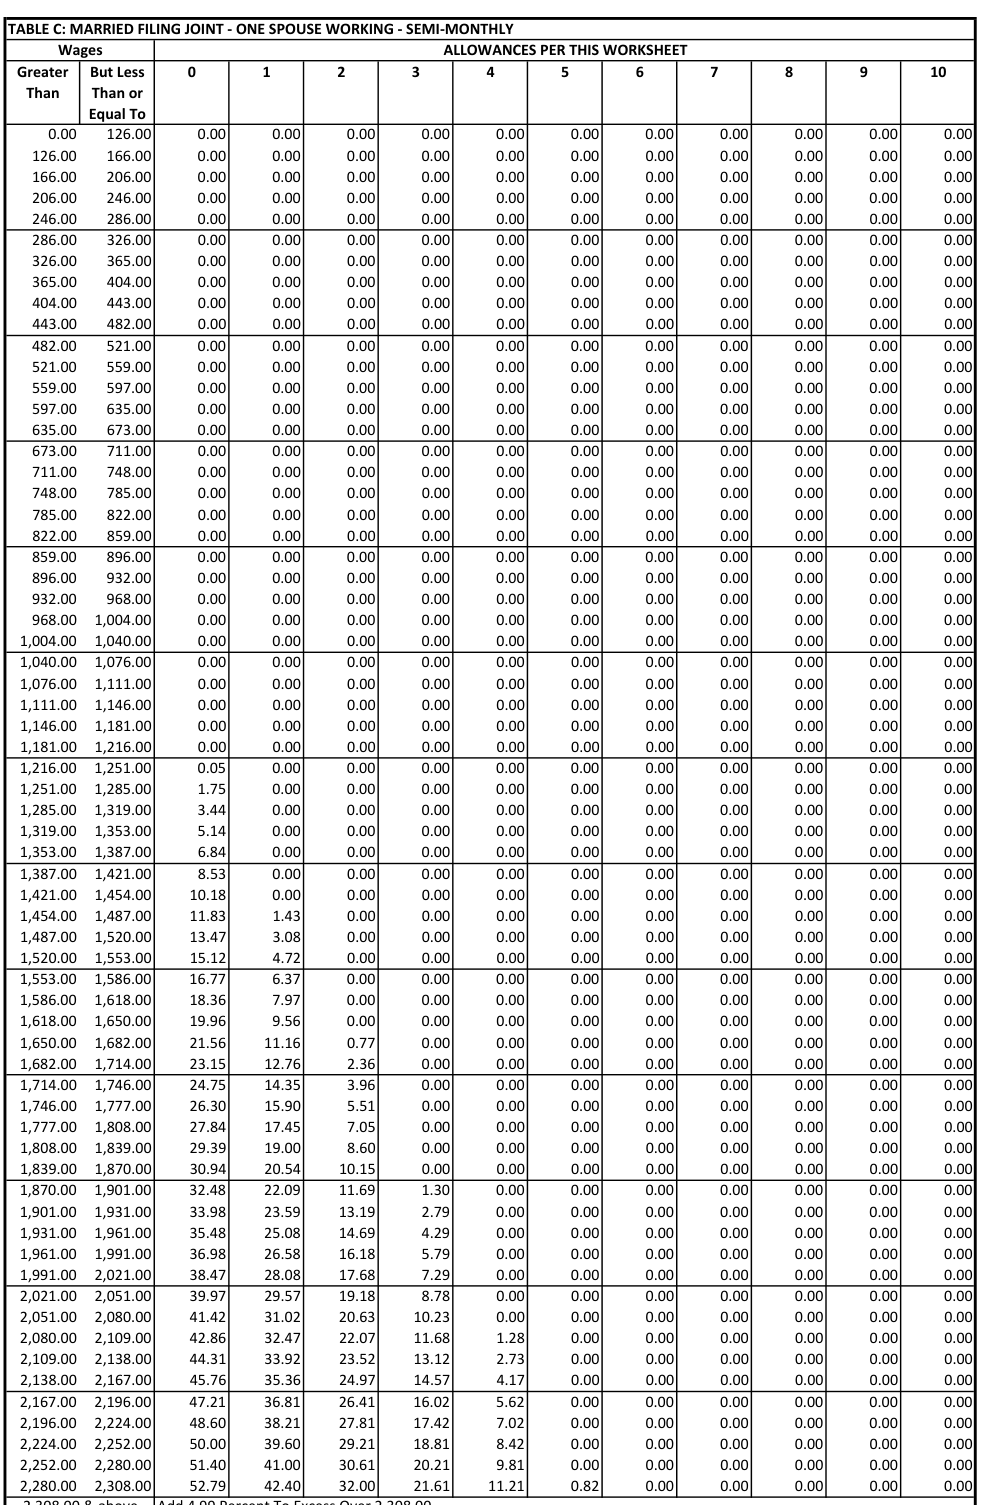
Text version of this table
| Wag | es | ALLOW | ANCES PER | THIS WORK | SHEET | |||||||
| Greater | But Less | 0 | 1 | 2 | 3 | 4 5 | 6 | 7 | 8 | 9 | 1 0 | |
| Than | Than or | |||||||||||
| Equal To | ||||||||||||
| 0.00 | 126.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 126.00 | 166.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 166.00 | 206.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 206.00 | 246.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 246.00 | 286.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 286.00 | 326.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 326.00 | 365.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 365.00 | 404.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 404.00 | 443.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 443.00 | 482.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 482.00 | 521.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 521.00 | 559.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 559.00 | 597.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 597.00 | 635.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 635.00 | 673.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 673.00 | 711.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 711.00 | 748.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 748.00 | 785.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 785.00 | 822.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 822.00 | 859.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 859.00 | 896.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 896.00 | 932.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 932.00 | 968.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 968.00 | 1,004.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,004.00 | 1,040.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,040.00 | 1,076.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,076.00 | 1,111.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,111.00 | 1,146.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,146.00 | 1,181.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,181.00 | 1,216.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,216.00 | 1,251.00 | 0.05 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,251.00 | 1,285.00 | 1.75 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,285.00 | 1,319.00 | 3.44 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,319.00 | 1,353.00 | 5.14 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,353.00 | 1,387.00 | 6.84 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,387.00 | 1,421.00 | 8.53 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,421.00 | 1,454.00 | 10.18 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,454.00 | 1,487.00 | 11.83 | 1.43 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,487.00 | 1,520.00 | 13.47 | 3.08 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,520.00 | 1,553.00 | 15.12 | 4.72 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,553.00 | 1,586.00 | 16.77 | 6.37 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,586.00 | 1,618.00 | 18.36 | 7.97 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,618.00 | 1,650.00 | 19.96 | 9.56 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,650.00 | 1,682.00 | 21.56 | 11.16 | 0.77 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,682.00 | 1,714.00 | 23.15 | 12.76 | 2.36 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,714.00 | 1,746.00 | 24.75 | 14.35 | 3.96 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,746.00 | 1,777.00 | 26.30 | 15.90 | 5.51 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,777.00 | 1,808.00 | 27.84 | 17.45 | 7.05 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,808.00 | 1,839.00 | 29.39 | 19.00 | 8.60 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,839.00 | 1,870.00 | 30.94 | 20.54 | 10.15 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,870.00 | 1,901.00 | 32.48 | 22.09 | 11.69 | 1.30 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,901.00 | 1,931.00 | 33.98 | 23.59 | 13.19 | 2.79 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,931.00 | 1,961.00 | 35.48 | 25.08 | 14.69 | 4.29 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,961.00 | 1,991.00 | 36.98 | 26.58 | 16.18 | 5.79 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,991.00 | 2,021.00 | 38.47 | 28.08 | 17.68 | 7.29 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,021.00 | 2,051.00 | 39.97 | 29.57 | 19.18 | 8.78 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,051.00 | 2,080.00 | 41.42 | 31.02 | 20.63 | 10.23 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,080.00 | 2,109.00 | 42.86 | 32.47 | 22.07 | 11.68 | 1.28 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,109.00 | 2,138.00 | 44.31 | 33.92 | 23.52 | 13.12 | 2.73 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,138.00 | 2,167.00 | 45.76 | 35.36 | 24.97 | 14.57 | 4.17 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,167.00 | 2,196.00 | 47.21 | 36.81 | 26.41 | 16.02 | 5.62 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,196.00 | 2,224.00 | 48.60 | 38.21 | 27.81 | 17.42 | 7.02 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,224.00 | 2,252.00 | 50.00 | 39.60 | 29.21 | 18.81 | 8.42 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,252.00 | 2,280.00 | 51.40 | 41.00 | 30.61 | 20.21 | 9.81 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,280.00 | 2,308.00 | 52.79 | 42.40 | 32.00 | 21.61 | 11.21 | 0.82 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
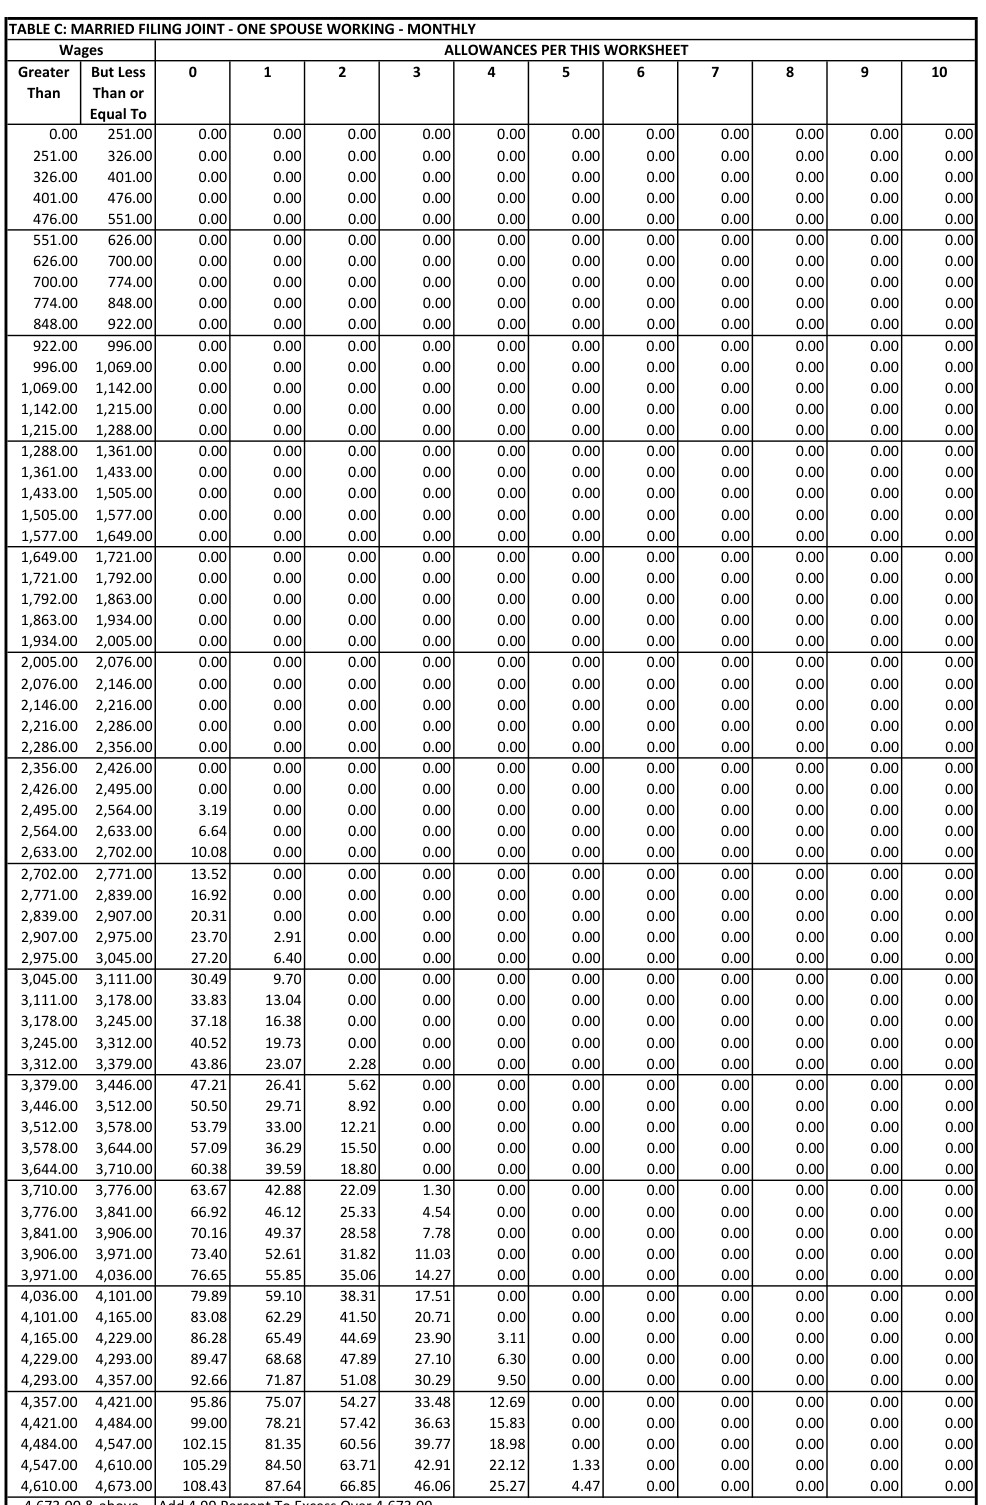
Text version of this table
| Wag | es | ALLOW | ANCES PER | THIS WORK | SHEET | |||||||
| Greater | But Less | 0 | 1 | 2 | 3 | 4 5 | 6 | 7 | 8 | 9 | 1 0 | |
| Than | Than or | |||||||||||
| Equal To | ||||||||||||
| 0.00 | 251.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 251.00 | 326.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 326.00 | 401.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 401.00 | 476.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 476.00 | 551.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 551.00 | 626.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 626.00 | 700.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 700.00 | 774.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 774.00 | 848.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 848.00 | 922.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 922.00 | 996.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 996.00 | 1,069.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,069.00 | 1,142.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,142.00 | 1,215.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,215.00 | 1,288.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,288.00 | 1,361.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,361.00 | 1,433.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,433.00 | 1,505.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,505.00 | 1,577.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,577.00 | 1,649.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,649.00 | 1,721.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,721.00 | 1,792.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,792.00 | 1,863.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,863.00 | 1,934.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,934.00 | 2,005.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,005.00 | 2,076.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,076.00 | 2,146.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,146.00 | 2,216.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,216.00 | 2,286.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,286.00 | 2,356.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,356.00 | 2,426.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,426.00 | 2,495.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,495.00 | 2,564.00 | 3.19 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,564.00 | 2,633.00 | 6.64 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,633.00 | 2,702.00 | 10.08 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,702.00 | 2,771.00 | 13.52 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,771.00 | 2,839.00 | 16.92 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,839.00 | 2,907.00 | 20.31 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,907.00 | 2,975.00 | 23.70 | 2.91 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,975.00 | 3,045.00 | 27.20 | 6.40 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,045.00 | 3,111.00 | 30.49 | 9.70 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,111.00 | 3,178.00 | 33.83 | 13.04 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,178.00 | 3,245.00 | 37.18 | 16.38 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,245.00 | 3,312.00 | 40.52 | 19.73 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,312.00 | 3,379.00 | 43.86 | 23.07 | 2.28 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,379.00 | 3,446.00 | 47.21 | 26.41 | 5.62 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,446.00 | 3,512.00 | 50.50 | 29.71 | 8.92 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,512.00 | 3,578.00 | 53.79 | 33.00 | 12.21 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,578.00 | 3,644.00 | 57.09 | 36.29 | 15.50 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,644.00 | 3,710.00 | 60.38 | 39.59 | 18.80 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,710.00 | 3,776.00 | 63.67 | 42.88 | 22.09 | 1.30 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,776.00 | 3,841.00 | 66.92 | 46.12 | 25.33 | 4.54 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,841.00 | 3,906.00 | 70.16 | 49.37 | 28.58 | 7.78 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,906.00 | 3,971.00 | 73.40 | 52.61 | 31.82 | 11.03 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,971.00 | 4,036.00 | 76.65 | 55.85 | 35.06 | 14.27 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 4,036.00 | 4,101.00 | 79.89 | 59.10 | 38.31 | 17.51 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 4,101.00 | 4,165.00 | 83.08 | 62.29 | 41.50 | 20.71 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 4,165.00 | 4,229.00 | 86.28 | 65.49 | 44.69 | 23.90 | 3.11 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 4,229.00 | 4,293.00 | 89.47 | 68.68 | 47.89 | 27.10 | 6.30 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 4,293.00 | 4,357.00 | 92.66 | 71.87 | 51.08 | 30.29 | 9.50 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 4,357.00 | 4,421.00 | 95.86 | 75.07 | 54.27 | 33.48 | 12.69 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 4,421.00 | 4,484.00 | 99.00 | 78.21 | 57.42 | 36.63 | 15.83 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 4,484.00 | 4,547.00 | 102.15 | 81.35 | 60.56 | 39.77 | 18.98 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 4,547.00 | 4,610.00 | 105.29 | 84.50 | 63.71 | 42.91 | 22.12 | 1.33 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 4,610.00 | 4,673.00 | 108.43 | 87.64 | 66.85 | 46.06 | 25.27 | 4.47 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
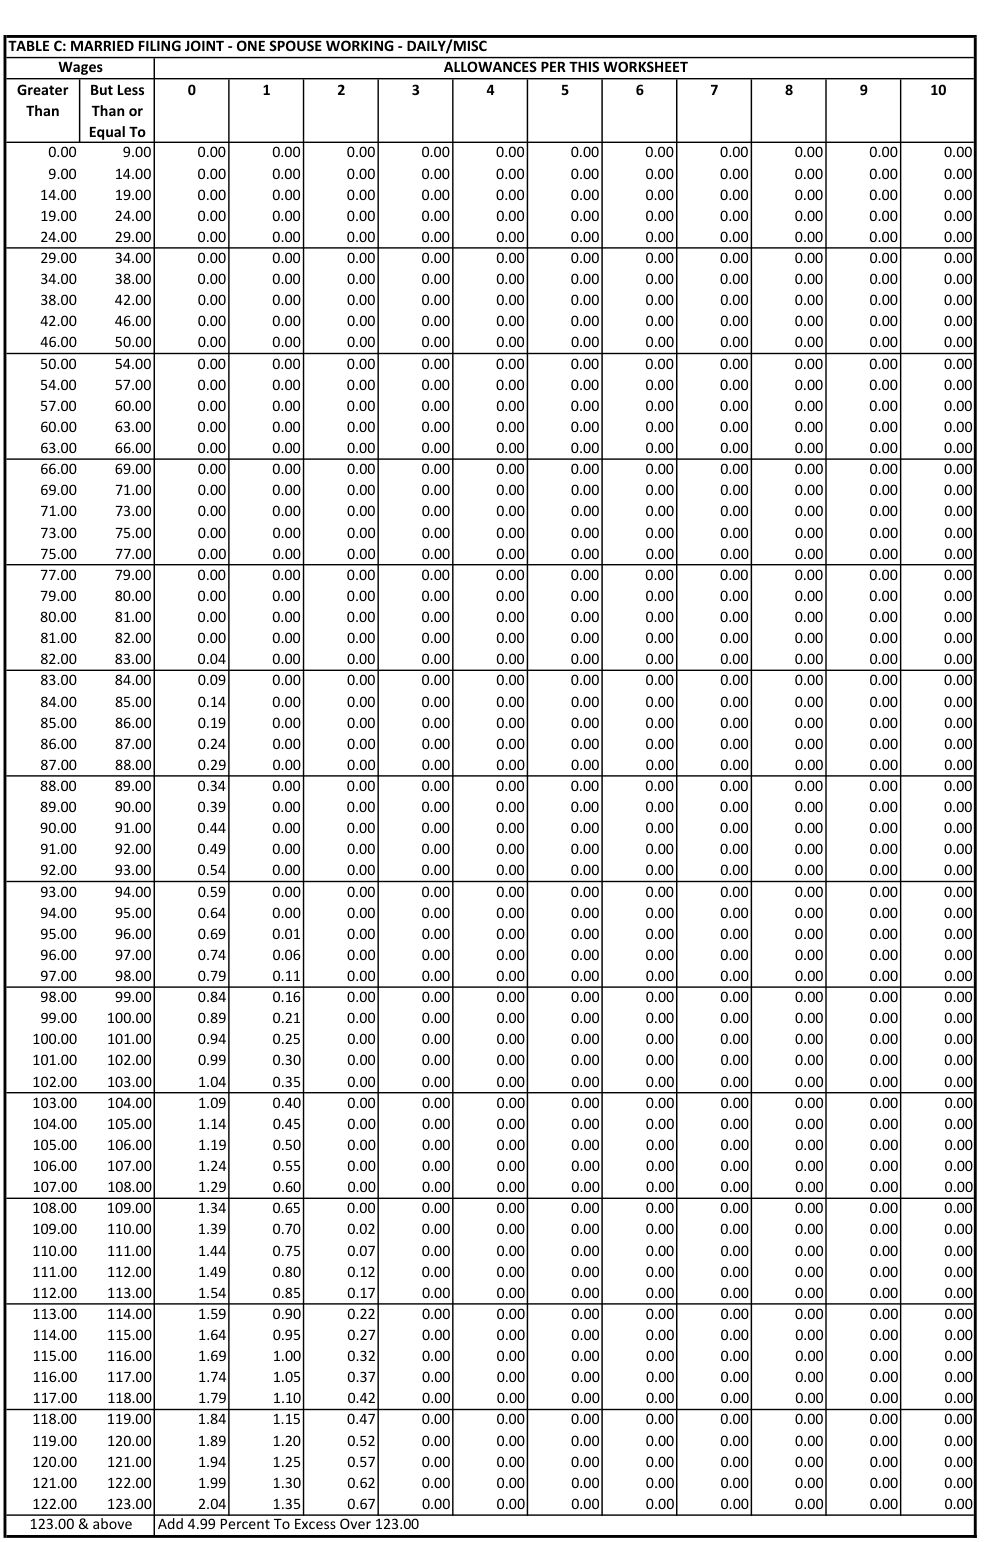
Text version of this table
| LE C: MAR | RI | ED FILING | JOINT - ONE | SPOUSE | WORKING - D | AILY/MISC | |||||||
| Wages | ALLOW | ANCES PER | THIS WORK | SHEET | |||||||||
| eater Bu | t | Less | 0 1 | 2 3 | 4 | 5 | 6 | 7 | 8 | 9 | 1 0 | ||
| han Th | a | n or | |||||||||||
| Eq | u | al To | |||||||||||
| 0.00 | 9.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 9.00 | 14.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 14.00 | 19.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 19.00 | 24.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 24.00 | 29.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 29.00 | 34.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 34.00 | 38.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 38.00 | 42.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 42.00 | 46.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 46.00 | 50.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 50.00 | 54.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 54.00 | 57.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 57.00 | 60.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 60.00 | 63.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 63.00 | 66.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 66.00 | 69.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 69.00 | 71.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 71.00 | 73.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 73.00 | 75.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 75.00 | 77.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 77.00 | 79.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 79.00 | 80.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 80.00 | 81.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 81.00 | 82.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 82.00 | 83.00 | 0.04 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 83.00 | 84.00 | 0.09 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 84.00 | 85.00 | 0.14 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 85.00 | 86.00 | 0.19 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 86.00 | 87.00 | 0.24 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 87.00 | 88.00 | 0.29 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 88.00 | 89.00 | 0.34 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 89.00 | 90.00 | 0.39 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 90.00 | 91.00 | 0.44 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 91.00 | 92.00 | 0.49 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 92.00 | 93.00 | 0.54 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 93.00 | 94.00 | 0.59 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 94.00 | 95.00 | 0.64 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 95.00 | 96.00 | 0.69 | 0.01 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 96.00 | 97.00 | 0.74 | 0.06 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 97.00 | 98.00 | 0.79 | 0.11 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 98.00 | 99.00 | 0.84 | 0.16 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 99.00 | 1 | 00.00 | 0.89 | 0.21 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 100.00 | 1 | 01.00 | 0.94 | 0.25 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 101.00 | 1 | 02.00 | 0.99 | 0.30 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 102.00 | 1 | 03.00 | 1.04 | 0.35 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 103.00 | 1 | 04.00 | 1.09 | 0.40 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 104.00 | 1 | 05.00 | 1.14 | 0.45 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 105.00 | 1 | 06.00 | 1.19 | 0.50 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 106.00 | 1 | 07.00 | 1.24 | 0.55 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 107.00 | 1 | 08.00 | 1.29 | 0.60 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 108.00 | 1 | 09.00 | 1.34 | 0.65 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 109.00 | 1 | 10.00 | 1.39 | 0.70 | 0.02 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 110.00 | 1 | 11.00 | 1.44 | 0.75 | 0.07 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 111.00 | 1 | 12.00 | 1.49 | 0.80 | 0.12 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 112.00 | 1 | 13.00 | 1.54 | 0.85 | 0.17 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 113.00 | 1 | 14.00 | 1.59 | 0.90 | 0.22 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 114.00 | 1 | 15.00 | 1.64 | 0.95 | 0.27 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 115.00 | 1 | 16.00 | 1.69 | 1.00 | 0.32 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 116.00 | 1 | 17.00 | 1.74 | 1.05 | 0.37 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 117.00 | 1 | 18.00 | 1.79 | 1.10 | 0.42 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 118.00 | 1 | 19.00 | 1.84 | 1.15 | 0.47 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 119.00 | 1 | 20.00 | 1.89 | 1.20 | 0.52 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 120.00 | 1 | 21.00 | 1.94 | 1.25 | 0.57 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 121.00 | 1 | 22.00 | 1.99 | 1.30 | 0.62 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 122.00 | 1 | 23.00 | 2.04 | 1.35 | 0.67 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 123.00 & ab | o | ve Add | 4.99 Percent | To Exce | ss Over 123.00 |
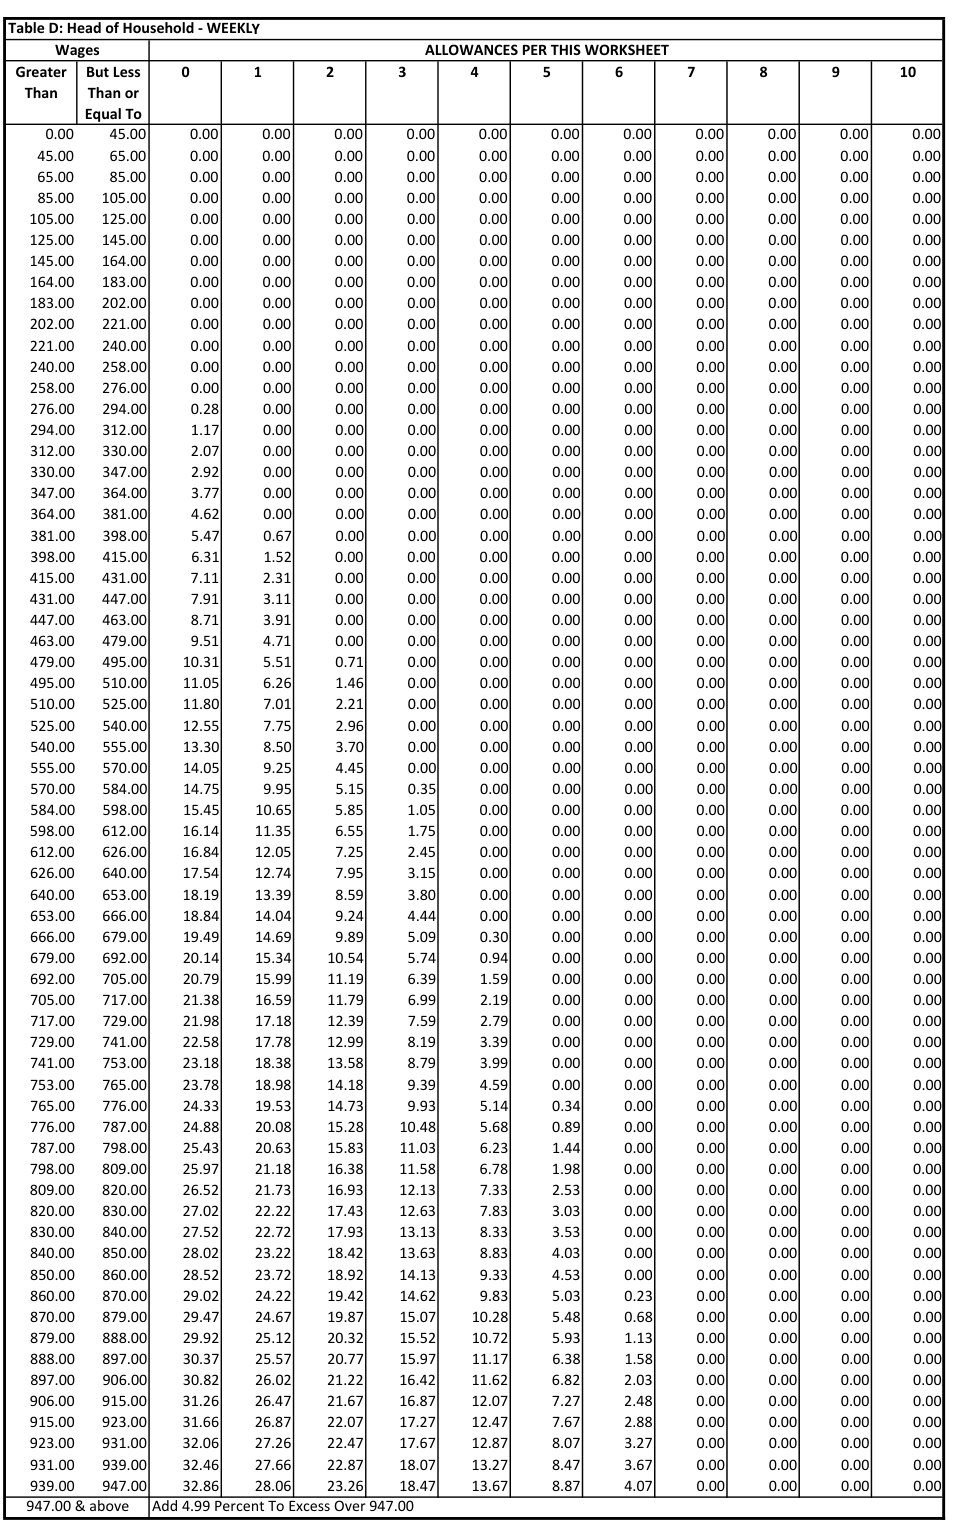
Text version of this table
| Wages | ALLOW | ANCES PER | THIS WORK | SHEET | ||||||||
| eater Bu | t Less | 0 | 1 | 2 | 3 | 4 5 | 6 | 7 | 8 | 9 | 1 0 | |
| han Th | an or | |||||||||||
| Eq | ual To | |||||||||||
| 0.00 | 45.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 45.00 | 65.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 65.00 | 85.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 85.00 | 105.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 105.00 | 125.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 125.00 | 145.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 145.00 | 164.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 164.00 | 183.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 183.00 | 202.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 202.00 | 221.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 221.00 | 240.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 240.00 | 258.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 258.00 | 276.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 276.00 | 294.00 | 0.28 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 294.00 | 312.00 | 1.17 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 312.00 | 330.00 | 2.07 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 330.00 | 347.00 | 2.92 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 347.00 | 364.00 | 3.77 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 364.00 | 381.00 | 4.62 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 381.00 | 398.00 | 5.47 | 0.67 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 398.00 | 415.00 | 6.31 | 1.52 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 415.00 | 431.00 | 7.11 | 2.31 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 431.00 | 447.00 | 7.91 | 3.11 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 447.00 | 463.00 | 8.71 | 3.91 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 463.00 | 479.00 | 9.51 | 4.71 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 479.00 | 495.00 | 10.31 | 5.51 | 0.71 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 495.00 | 510.00 | 11.05 | 6.26 | 1.46 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 510.00 | 525.00 | 11.80 | 7.01 | 2.21 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 525.00 | 540.00 | 12.55 | 7.75 | 2.96 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 540.00 | 555.00 | 13.30 | 8.50 | 3.70 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 555.00 | 570.00 | 14.05 | 9.25 | 4.45 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 570.00 | 584.00 | 14.75 | 9.95 | 5.15 | 0.35 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 584.00 | 598.00 | 15.45 | 10.65 | 5.85 | 1.05 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 598.00 | 612.00 | 16.14 | 11.35 | 6.55 | 1.75 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 612.00 | 626.00 | 16.84 | 12.05 | 7.25 | 2.45 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 626.00 | 640.00 | 17.54 | 12.74 | 7.95 | 3.15 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 640.00 | 653.00 | 18.19 | 13.39 | 8.59 | 3.80 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 653.00 | 666.00 | 18.84 | 14.04 | 9.24 | 4.44 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 666.00 | 679.00 | 19.49 | 14.69 | 9.89 | 5.09 | 0.30 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 679.00 | 692.00 | 20.14 | 15.34 | 10.54 | 5.74 | 0.94 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 692.00 | 705.00 | 20.79 | 15.99 | 11.19 | 6.39 | 1.59 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 705.00 | 717.00 | 21.38 | 16.59 | 11.79 | 6.99 | 2.19 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 717.00 | 729.00 | 21.98 | 17.18 | 12.39 | 7.59 | 2.79 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 729.00 | 741.00 | 22.58 | 17.78 | 12.99 | 8.19 | 3.39 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 741.00 | 753.00 | 23.18 | 18.38 | 13.58 | 8.79 | 3.99 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 753.00 | 765.00 | 23.78 | 18.98 | 14.18 | 9.39 | 4.59 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 765.00 | 776.00 | 24.33 | 19.53 | 14.73 | 9.93 | 5.14 | 0.34 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 776.00 | 787.00 | 24.88 | 20.08 | 15.28 | 10.48 | 5.68 | 0.89 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 787.00 | 798.00 | 25.43 | 20.63 | 15.83 | 11.03 | 6.23 | 1.44 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 798.00 | 809.00 | 25.97 | 21.18 | 16.38 | 11.58 | 6.78 | 1.98 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 809.00 | 820.00 | 26.52 | 21.73 | 16.93 | 12.13 | 7.33 | 2.53 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 820.00 | 830.00 | 27.02 | 22.22 | 17.43 | 12.63 | 7.83 | 3.03 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 830.00 | 840.00 | 27.52 | 22.72 | 17.93 | 13.13 | 8.33 | 3.53 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 840.00 | 850.00 | 28.02 | 23.22 | 18.42 | 13.63 | 8.83 | 4.03 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 850.00 | 860.00 | 28.52 | 23.72 | 18.92 | 14.13 | 9.33 | 4.53 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 860.00 | 870.00 | 29.02 | 24.22 | 19.42 | 14.62 | 9.83 | 5.03 | 0.23 | 0.00 | 0.00 | 0.00 | 0.00 |
| 870.00 | 879.00 | 29.47 | 24.67 | 19.87 | 15.07 | 10.28 | 5.48 | 0.68 | 0.00 | 0.00 | 0.00 | 0.00 |
| 879.00 | 888.00 | 29.92 | 25.12 | 20.32 | 15.52 | 10.72 | 5.93 | 1.13 | 0.00 | 0.00 | 0.00 | 0.00 |
| 888.00 | 897.00 | 30.37 | 25.57 | 20.77 | 15.97 | 11.17 | 6.38 | 1.58 | 0.00 | 0.00 | 0.00 | 0.00 |
| 897.00 | 906.00 | 30.82 | 26.02 | 21.22 | 16.42 | 11.62 | 6.82 | 2.03 | 0.00 | 0.00 | 0.00 | 0.00 |
| 906.00 | 915.00 | 31.26 | 26.47 | 21.67 | 16.87 | 12.07 | 7.27 | 2.48 | 0.00 | 0.00 | 0.00 | 0.00 |
| 915.00 | 923.00 | 31.66 | 26.87 | 22.07 | 17.27 | 12.47 | 7.67 | 2.88 | 0.00 | 0.00 | 0.00 | 0.00 |
| 923.00 | 931.00 | 32.06 | 27.26 | 22.47 | 17.67 | 12.87 | 8.07 | 3.27 | 0.00 | 0.00 | 0.00 | 0.00 |
| 931.00 | 939.00 | 32.46 | 27.66 | 22.87 | 18.07 | 13.27 | 8.47 | 3.67 | 0.00 | 0.00 | 0.00 | 0.00 |
| 939.00 | 947.00 | 32.86 | 28.06 | 23.26 | 18.47 | 13.67 | 8.87 | 4.07 | 0.00 | 0.00 | 0.00 | 0.00 |
| 947.00 & ab | ove Add | 4.99 Perce | nt To Exces | s Over 947. | 00 |
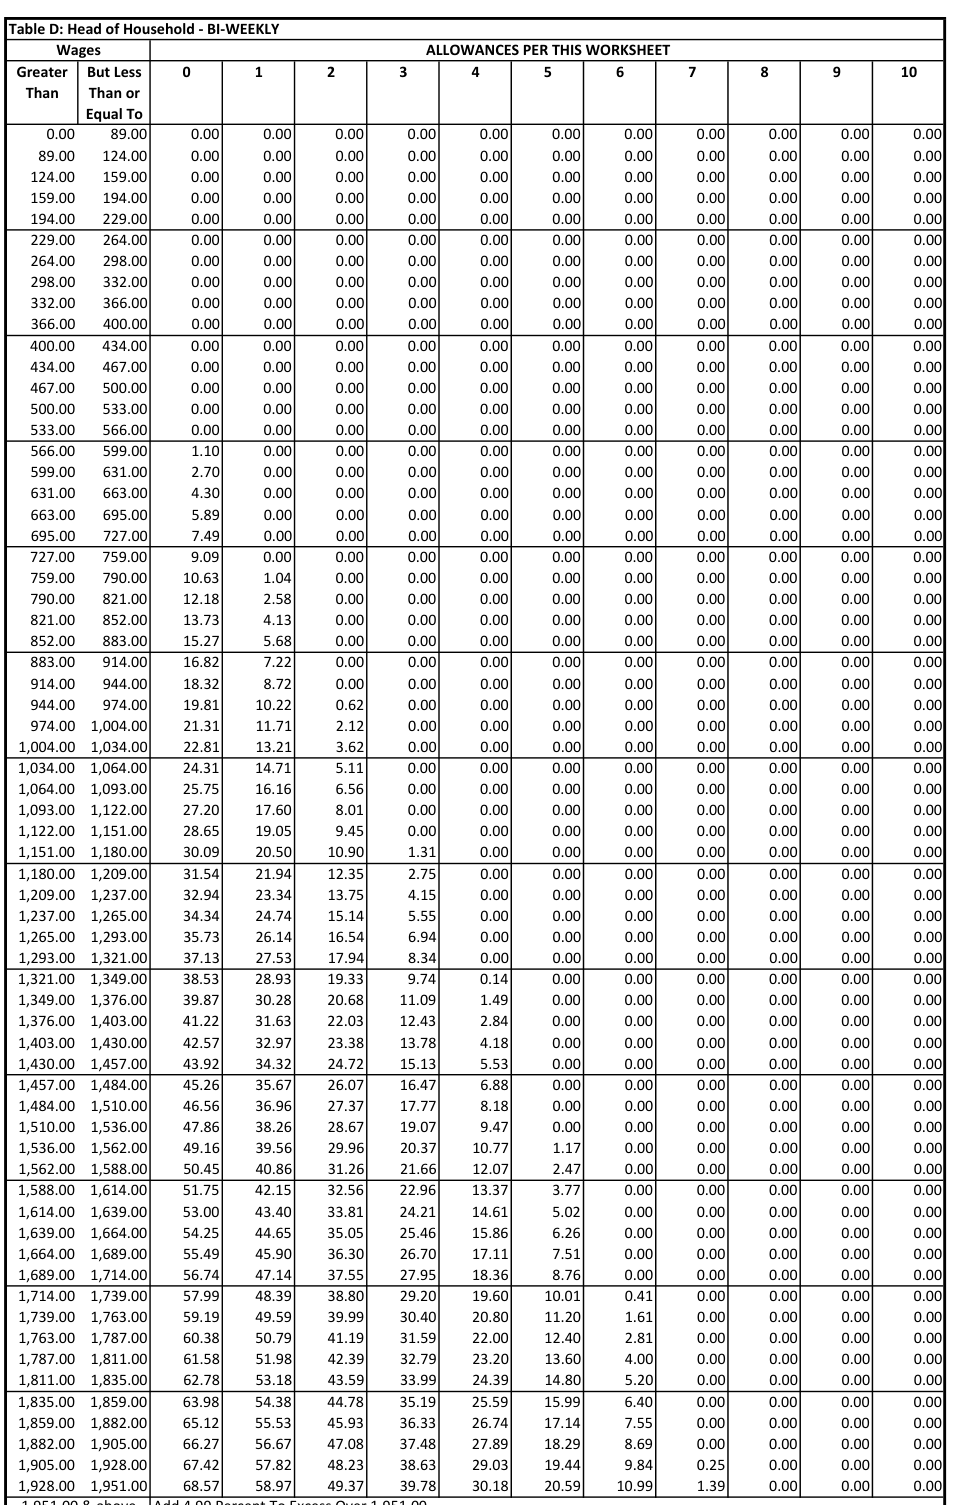
Text version of this table
| Wag | es | ALLOW | ANCES PER | THIS WOR | KSHEET | ||||||||
| Greater | But | Less | 0 | 1 | 2 | 3 | 4 | 5 | 6 7 | 8 | 9 | 1 0 | |
| Than | Tha | n or | |||||||||||
| E | qu | al To | |||||||||||
| 0.00 | 89.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 89.00 | 1 | 24.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 124.00 | 1 | 59.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 159.00 | 1 | 94.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 194.00 | 2 | 29.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 229.00 | 2 | 64.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 264.00 | 2 | 98.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 298.00 | 3 | 32.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 332.00 | 3 | 66.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 366.00 | 4 | 00.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 400.00 | 4 | 34.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 434.00 | 4 | 67.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 467.00 | 5 | 00.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 500.00 | 5 | 33.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 533.00 | 5 | 66.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 566.00 | 5 | 99.00 | 1.10 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 599.00 | 6 | 31.00 | 2.70 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 631.00 | 6 | 63.00 | 4.30 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 663.00 | 6 | 95.00 | 5.89 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 695.00 | 7 | 27.00 | 7.49 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 727.00 | 7 | 59.00 | 9.09 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 759.00 | 7 | 90.00 | 10.63 | 1.04 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 790.00 | 8 | 21.00 | 12.18 | 2.58 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 821.00 | 8 | 52.00 | 13.73 | 4.13 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 852.00 | 8 | 83.00 | 15.27 | 5.68 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 883.00 | 9 | 14.00 | 16.82 | 7.22 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 914.00 | 9 | 44.00 | 18.32 | 8.72 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 944.00 | 9 | 74.00 | 19.81 | 10.22 | 0.62 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 974.00 | 1,0 | 04.00 | 21.31 | 11.71 | 2.12 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,004.00 | 1,0 | 34.00 | 22.81 | 13.21 | 3.62 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,034.00 | 1,0 | 64.00 | 24.31 | 14.71 | 5.11 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,064.00 | 1,0 | 93.00 | 25.75 | 16.16 | 6.56 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,093.00 | 1,1 | 22.00 | 27.20 | 17.60 | 8.01 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,122.00 | 1,1 | 51.00 | 28.65 | 19.05 | 9.45 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,151.00 | 1,1 | 80.00 | 30.09 | 20.50 | 10.90 | 1.31 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,180.00 | 1,2 | 09.00 | 31.54 | 21.94 | 12.35 | 2.75 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,209.00 | 1,2 | 37.00 | 32.94 | 23.34 | 13.75 | 4.15 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,237.00 | 1,2 | 65.00 | 34.34 | 24.74 | 15.14 | 5.55 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,265.00 | 1,2 | 93.00 | 35.73 | 26.14 | 16.54 | 6.94 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,293.00 | 1,3 | 21.00 | 37.13 | 27.53 | 17.94 | 8.34 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,321.00 | 1,3 | 49.00 | 38.53 | 28.93 | 19.33 | 9.74 | 0.14 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,349.00 | 1,3 | 76.00 | 39.87 | 30.28 | 20.68 | 11.09 | 1.49 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,376.00 | 1,4 | 03.00 | 41.22 | 31.63 | 22.03 | 12.43 | 2.84 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,403.00 | 1,4 | 30.00 | 42.57 | 32.97 | 23.38 | 13.78 | 4.18 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,430.00 | 1,4 | 57.00 | 43.92 | 34.32 | 24.72 | 15.13 | 5.53 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,457.00 | 1,4 | 84.00 | 45.26 | 35.67 | 26.07 | 16.47 | 6.88 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,484.00 | 1,5 | 10.00 | 46.56 | 36.96 | 27.37 | 17.77 | 8.18 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,510.00 | 1,5 | 36.00 | 47.86 | 38.26 | 28.67 | 19.07 | 9.47 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,536.00 | 1,5 | 62.00 | 49.16 | 39.56 | 29.96 | 20.37 | 10.77 | 1.17 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,562.00 | 1,5 | 88.00 | 50.45 | 40.86 | 31.26 | 21.66 | 12.07 | 2.47 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,588.00 | 1,6 | 14.00 | 51.75 | 42.15 | 32.56 | 22.96 | 13.37 | 3.77 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,614.00 | 1,6 | 39.00 | 53.00 | 43.40 | 33.81 | 24.21 | 14.61 | 5.02 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,639.00 | 1,6 | 64.00 | 54.25 | 44.65 | 35.05 | 25.46 | 15.86 | 6.26 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,664.00 | 1,6 | 89.00 | 55.49 | 45.90 | 36.30 | 26.70 | 17.11 | 7.51 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,689.00 | 1,7 | 14.00 | 56.74 | 47.14 | 37.55 | 27.95 | 18.36 | 8.76 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,714.00 | 1,7 | 39.00 | 57.99 | 48.39 | 38.80 | 29.20 | 19.60 | 10.01 | 0.41 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,739.00 | 1,7 | 63.00 | 59.19 | 49.59 | 39.99 | 30.40 | 20.80 | 11.20 | 1.61 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,763.00 | 1,7 | 87.00 | 60.38 | 50.79 | 41.19 | 31.59 | 22.00 | 12.40 | 2.81 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,787.00 | 1,8 | 11.00 | 61.58 | 51.98 | 42.39 | 32.79 | 23.20 | 13.60 | 4.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,811.00 | 1,8 | 35.00 | 62.78 | 53.18 | 43.59 | 33.99 | 24.39 | 14.80 | 5.20 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,835.00 | 1,8 | 59.00 | 63.98 | 54.38 | 44.78 | 35.19 | 25.59 | 15.99 | 6.40 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,859.00 | 1,8 | 82.00 | 65.12 | 55.53 | 45.93 | 36.33 | 26.74 | 17.14 | 7.55 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,882.00 | 1,9 | 05.00 | 66.27 | 56.67 | 47.08 | 37.48 | 27.89 | 18.29 | 8.69 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,905.00 | 1,9 | 28.00 | 67.42 | 57.82 | 48.23 | 38.63 | 29.03 | 19.44 | 9.84 | 0.25 | 0.00 | 0.00 | 0.00 |
| 1,928.00 | 1,9 | 51.00 | 68.57 | 58.97 | 49.37 | 39.78 | 30.18 | 20.59 | 10.99 | 1.39 | 0.00 | 0.00 | 0.00 |
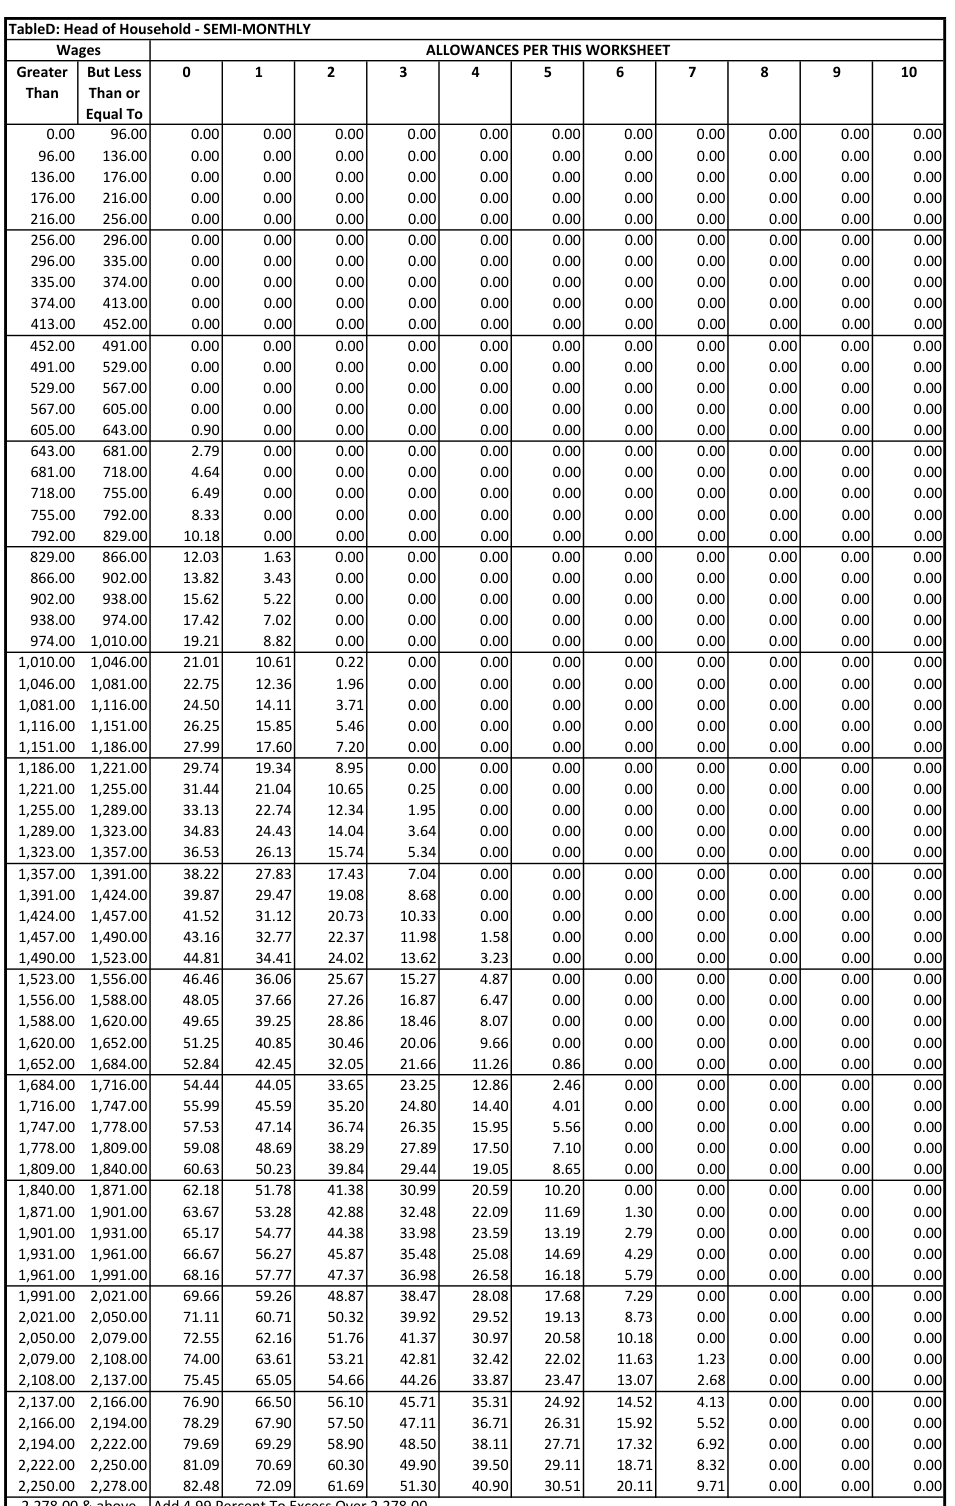
Text version of this table
| Wag | es | ALLOW | ANCES PER | THIS WOR | KSHEET | ||||||||
| Greater | But | Less | 0 | 1 | 2 | 3 | 4 | 5 | 6 7 | 8 | 9 | 1 0 | |
| Than | Tha | n or | |||||||||||
| E | qu | al To | |||||||||||
| 0.00 | 96.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 96.00 | 1 | 36.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 136.00 | 1 | 76.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 176.00 | 2 | 16.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 216.00 | 2 | 56.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 256.00 | 2 | 96.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 296.00 | 3 | 35.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 335.00 | 3 | 74.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 374.00 | 4 | 13.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 413.00 | 4 | 52.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 452.00 | 4 | 91.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 491.00 | 5 | 29.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 529.00 | 5 | 67.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 567.00 | 6 | 05.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 605.00 | 6 | 43.00 | 0.90 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 643.00 | 6 | 81.00 | 2.79 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 681.00 | 7 | 18.00 | 4.64 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 718.00 | 7 | 55.00 | 6.49 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 755.00 | 7 | 92.00 | 8.33 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 792.00 | 8 | 29.00 | 10.18 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 829.00 | 8 | 66.00 | 12.03 | 1.63 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 866.00 | 9 | 02.00 | 13.82 | 3.43 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 902.00 | 9 | 38.00 | 15.62 | 5.22 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 938.00 | 9 | 74.00 | 17.42 | 7.02 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 974.00 | 1,0 | 10.00 | 19.21 | 8.82 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,010.00 | 1,0 | 46.00 | 21.01 | 10.61 | 0.22 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,046.00 | 1,0 | 81.00 | 22.75 | 12.36 | 1.96 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,081.00 | 1,1 | 16.00 | 24.50 | 14.11 | 3.71 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,116.00 | 1,1 | 51.00 | 26.25 | 15.85 | 5.46 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,151.00 | 1,1 | 86.00 | 27.99 | 17.60 | 7.20 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,186.00 | 1,2 | 21.00 | 29.74 | 19.34 | 8.95 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,221.00 | 1,2 | 55.00 | 31.44 | 21.04 | 10.65 | 0.25 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,255.00 | 1,2 | 89.00 | 33.13 | 22.74 | 12.34 | 1.95 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,289.00 | 1,3 | 23.00 | 34.83 | 24.43 | 14.04 | 3.64 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,323.00 | 1,3 | 57.00 | 36.53 | 26.13 | 15.74 | 5.34 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,357.00 | 1,3 | 91.00 | 38.22 | 27.83 | 17.43 | 7.04 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,391.00 | 1,4 | 24.00 | 39.87 | 29.47 | 19.08 | 8.68 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,424.00 | 1,4 | 57.00 | 41.52 | 31.12 | 20.73 | 10.33 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,457.00 | 1,4 | 90.00 | 43.16 | 32.77 | 22.37 | 11.98 | 1.58 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,490.00 | 1,5 | 23.00 | 44.81 | 34.41 | 24.02 | 13.62 | 3.23 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,523.00 | 1,5 | 56.00 | 46.46 | 36.06 | 25.67 | 15.27 | 4.87 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,556.00 | 1,5 | 88.00 | 48.05 | 37.66 | 27.26 | 16.87 | 6.47 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,588.00 | 1,6 | 20.00 | 49.65 | 39.25 | 28.86 | 18.46 | 8.07 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,620.00 | 1,6 | 52.00 | 51.25 | 40.85 | 30.46 | 20.06 | 9.66 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,652.00 | 1,6 | 84.00 | 52.84 | 42.45 | 32.05 | 21.66 | 11.26 | 0.86 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,684.00 | 1,7 | 16.00 | 54.44 | 44.05 | 33.65 | 23.25 | 12.86 | 2.46 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,716.00 | 1,7 | 47.00 | 55.99 | 45.59 | 35.20 | 24.80 | 14.40 | 4.01 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,747.00 | 1,7 | 78.00 | 57.53 | 47.14 | 36.74 | 26.35 | 15.95 | 5.56 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,778.00 | 1,8 | 09.00 | 59.08 | 48.69 | 38.29 | 27.89 | 17.50 | 7.10 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,809.00 | 1,8 | 40.00 | 60.63 | 50.23 | 39.84 | 29.44 | 19.05 | 8.65 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,840.00 | 1,8 | 71.00 | 62.18 | 51.78 | 41.38 | 30.99 | 20.59 | 10.20 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,871.00 | 1,9 | 01.00 | 63.67 | 53.28 | 42.88 | 32.48 | 22.09 | 11.69 | 1.30 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,901.00 | 1,9 | 31.00 | 65.17 | 54.77 | 44.38 | 33.98 | 23.59 | 13.19 | 2.79 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,931.00 | 1,9 | 61.00 | 66.67 | 56.27 | 45.87 | 35.48 | 25.08 | 14.69 | 4.29 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,961.00 | 1,9 | 91.00 | 68.16 | 57.77 | 47.37 | 36.98 | 26.58 | 16.18 | 5.79 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,991.00 | 2,0 | 21.00 | 69.66 | 59.26 | 48.87 | 38.47 | 28.08 | 17.68 | 7.29 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,021.00 | 2,0 | 50.00 | 71.11 | 60.71 | 50.32 | 39.92 | 29.52 | 19.13 | 8.73 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,050.00 | 2,0 | 79.00 | 72.55 | 62.16 | 51.76 | 41.37 | 30.97 | 20.58 | 10.18 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,079.00 | 2,1 | 08.00 | 74.00 | 63.61 | 53.21 | 42.81 | 32.42 | 22.02 | 11.63 | 1.23 | 0.00 | 0.00 | 0.00 |
| 2,108.00 | 2,1 | 37.00 | 75.45 | 65.05 | 54.66 | 44.26 | 33.87 | 23.47 | 13.07 | 2.68 | 0.00 | 0.00 | 0.00 |
| 2,137.00 | 2,1 | 66.00 | 76.90 | 66.50 | 56.10 | 45.71 | 35.31 | 24.92 | 14.52 | 4.13 | 0.00 | 0.00 | 0.00 |
| 2,166.00 | 2,1 | 94.00 | 78.29 | 67.90 | 57.50 | 47.11 | 36.71 | 26.31 | 15.92 | 5.52 | 0.00 | 0.00 | 0.00 |
| 2,194.00 | 2,2 | 22.00 | 79.69 | 69.29 | 58.90 | 48.50 | 38.11 | 27.71 | 17.32 | 6.92 | 0.00 | 0.00 | 0.00 |
| 2,222.00 | 2,2 | 50.00 | 81.09 | 70.69 | 60.30 | 49.90 | 39.50 | 29.11 | 18.71 | 8.32 | 0.00 | 0.00 | 0.00 |
| 2,250.00 | 2,2 | 78.00 | 82.48 | 72.09 | 61.69 | 51.30 | 40.90 | 30.51 | 20.11 | 9.71 | 0.00 | 0.00 | 0.00 |
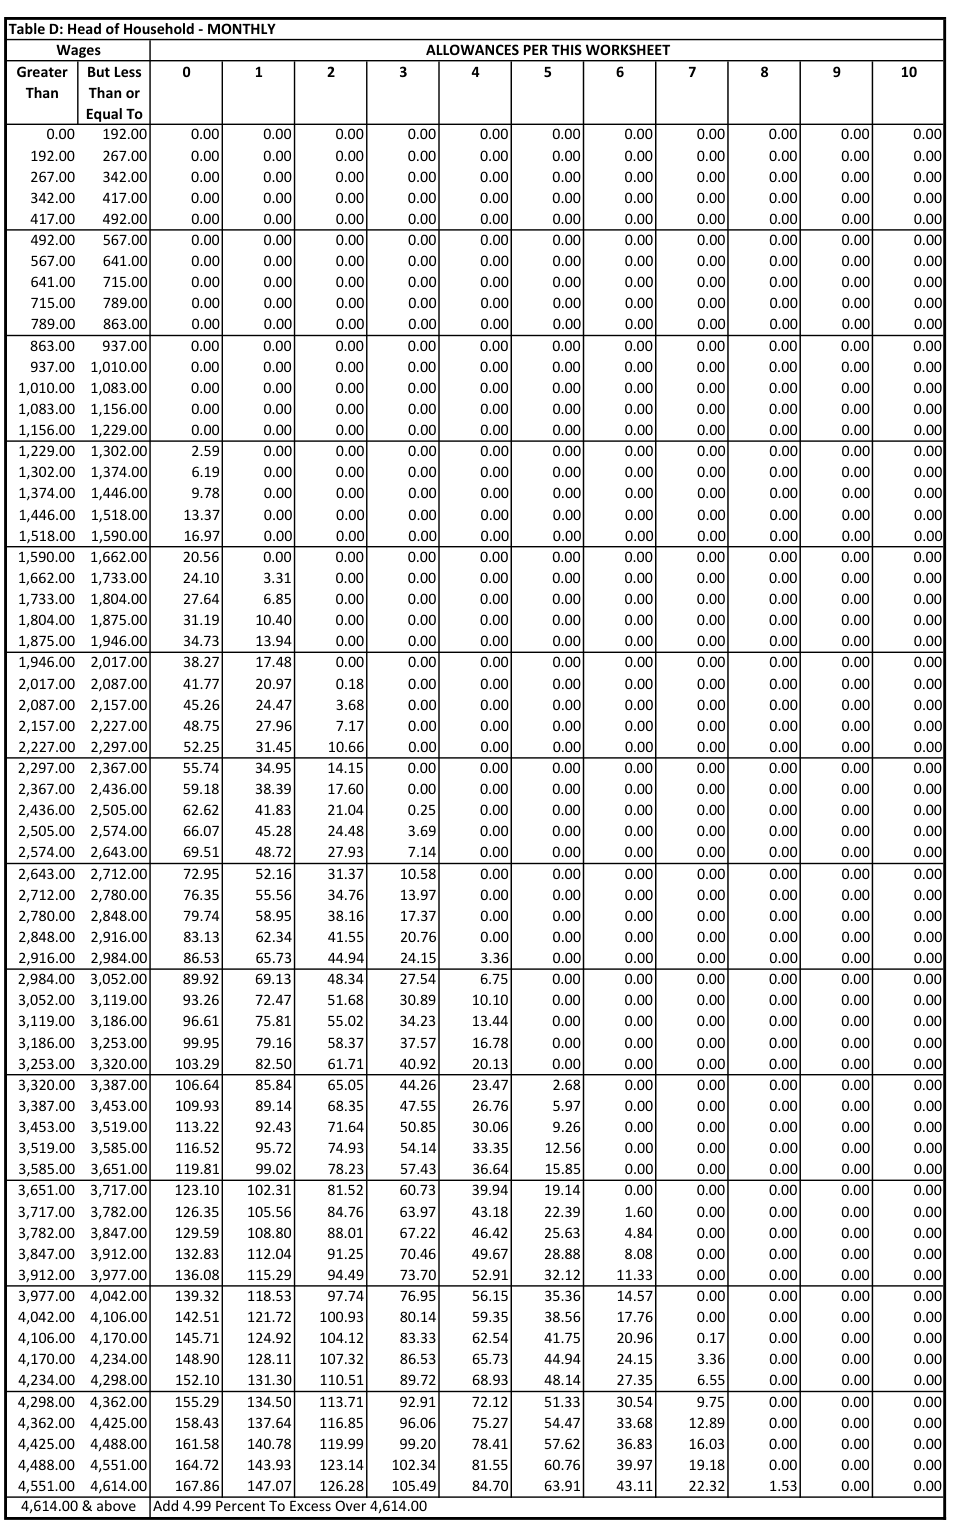
Text version of this table
| Wag | es | ALLOW | ANCES PER | THIS WOR | KSHEET | ||||||||
| Greater | But | Less | 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 8 | 9 | 1 0 | |
| Than | Tha | n or | |||||||||||
| E | qu | al To | |||||||||||
| 0.00 | 1 | 92.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 192.00 | 2 | 67.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 267.00 | 3 | 42.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 342.00 | 4 | 17.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 417.00 | 4 | 92.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 492.00 | 5 | 67.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 567.00 | 6 | 41.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 641.00 | 7 | 15.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 715.00 | 7 | 89.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 789.00 | 8 | 63.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 863.00 | 9 | 37.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 937.00 | 1,0 | 10.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,010.00 | 1,0 | 83.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,083.00 | 1,1 | 56.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,156.00 | 1,2 | 29.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,229.00 | 1,3 | 02.00 | 2.59 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,302.00 | 1,3 | 74.00 | 6.19 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,374.00 | 1,4 | 46.00 | 9.78 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,446.00 | 1,5 | 18.00 | 13.37 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,518.00 | 1,5 | 90.00 | 16.97 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,590.00 | 1,6 | 62.00 | 20.56 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,662.00 | 1,7 | 33.00 | 24.10 | 3.31 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,733.00 | 1,8 | 04.00 | 27.64 | 6.85 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,804.00 | 1,8 | 75.00 | 31.19 | 10.40 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,875.00 | 1,9 | 46.00 | 34.73 | 13.94 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 1,946.00 | 2,0 | 17.00 | 38.27 | 17.48 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,017.00 | 2,0 | 87.00 | 41.77 | 20.97 | 0.18 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,087.00 | 2,1 | 57.00 | 45.26 | 24.47 | 3.68 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,157.00 | 2,2 | 27.00 | 48.75 | 27.96 | 7.17 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,227.00 | 2,2 | 97.00 | 52.25 | 31.45 | 10.66 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,297.00 | 2,3 | 67.00 | 55.74 | 34.95 | 14.15 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,367.00 | 2,4 | 36.00 | 59.18 | 38.39 | 17.60 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,436.00 | 2,5 | 05.00 | 62.62 | 41.83 | 21.04 | 0.25 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,505.00 | 2,5 | 74.00 | 66.07 | 45.28 | 24.48 | 3.69 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,574.00 | 2,6 | 43.00 | 69.51 | 48.72 | 27.93 | 7.14 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,643.00 | 2,7 | 12.00 | 72.95 | 52.16 | 31.37 | 10.58 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,712.00 | 2,7 | 80.00 | 76.35 | 55.56 | 34.76 | 13.97 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,780.00 | 2,8 | 48.00 | 79.74 | 58.95 | 38.16 | 17.37 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,848.00 | 2,9 | 16.00 | 83.13 | 62.34 | 41.55 | 20.76 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,916.00 | 2,9 | 84.00 | 86.53 | 65.73 | 44.94 | 24.15 | 3.36 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 2,984.00 | 3,0 | 52.00 | 89.92 | 69.13 | 48.34 | 27.54 | 6.75 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,052.00 | 3,1 | 19.00 | 93.26 | 72.47 | 51.68 | 30.89 | 10.10 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,119.00 | 3,1 | 86.00 | 96.61 | 75.81 | 55.02 | 34.23 | 13.44 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,186.00 | 3,2 | 53.00 | 99.95 | 79.16 | 58.37 | 37.57 | 16.78 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,253.00 | 3,3 | 20.00 | 103.29 | 82.50 | 61.71 | 40.92 | 20.13 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,320.00 | 3,3 | 87.00 | 106.64 | 85.84 | 65.05 | 44.26 | 23.47 | 2.68 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,387.00 | 3,4 | 53.00 | 109.93 | 89.14 | 68.35 | 47.55 | 26.76 | 5.97 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,453.00 | 3,5 | 19.00 | 113.22 | 92.43 | 71.64 | 50.85 | 30.06 | 9.26 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,519.00 | 3,5 | 85.00 | 116.52 | 95.72 | 74.93 | 54.14 | 33.35 | 12.56 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,585.00 | 3,6 | 51.00 | 119.81 | 99.02 | 78.23 | 57.43 | 36.64 | 15.85 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,651.00 | 3,7 | 17.00 | 123.10 | 102.31 | 81.52 | 60.73 | 39.94 | 19.14 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,717.00 | 3,7 | 82.00 | 126.35 | 105.56 | 84.76 | 63.97 | 43.18 | 22.39 | 1.60 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,782.00 | 3,8 | 47.00 | 129.59 | 108.80 | 88.01 | 67.22 | 46.42 | 25.63 | 4.84 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,847.00 | 3,9 | 12.00 | 132.83 | 112.04 | 91.25 | 70.46 | 49.67 | 28.88 | 8.08 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,912.00 | 3,9 | 77.00 | 136.08 | 115.29 | 94.49 | 73.70 | 52.91 | 32.12 | 11.33 | 0.00 | 0.00 | 0.00 | 0.00 |
| 3,977.00 | 4,0 | 42.00 | 139.32 | 118.53 | 97.74 | 76.95 | 56.15 | 35.36 | 14.57 | 0.00 | 0.00 | 0.00 | 0.00 |
| 4,042.00 | 4,1 | 06.00 | 142.51 | 121.72 | 100.93 | 80.14 | 59.35 | 38.56 | 17.76 | 0.00 | 0.00 | 0.00 | 0.00 |
| 4,106.00 | 4,1 | 70.00 | 145.71 | 124.92 | 104.12 | 83.33 | 62.54 | 41.75 | 20.96 | 0.17 | 0.00 | 0.00 | 0.00 |
| 4,170.00 | 4,2 | 34.00 | 148.90 | 128.11 | 107.32 | 86.53 | 65.73 | 44.94 | 24.15 | 3.36 | 0.00 | 0.00 | 0.00 |
| 4,234.00 | 4,2 | 98.00 | 152.10 | 131.30 | 110.51 | 89.72 | 68.93 | 48.14 | 27.35 | 6.55 | 0.00 | 0.00 | 0.00 |
| 4,298.00 | 4,3 | 62.00 | 155.29 | 134.50 | 113.71 | 92.91 | 72.12 | 51.33 | 30.54 | 9.75 | 0.00 | 0.00 | 0.00 |
| 4,362.00 | 4,4 | 25.00 | 158.43 | 137.64 | 116.85 | 96.06 | 75.27 | 54.47 | 33.68 | 12.89 | 0.00 | 0.00 | 0.00 |
| 4,425.00 | 4,4 | 88.00 | 161.58 | 140.78 | 119.99 | 99.20 | 78.41 | 57.62 | 36.83 | 16.03 | 0.00 | 0.00 | 0.00 |
| 4,488.00 | 4,5 | 51.00 | 164.72 | 143.93 | 123.14 | 102.34 | 81.55 | 60.76 | 39.97 | 19.18 | 0.00 | 0.00 | 0.00 |
| 4,551.00 | 4,6 | 14.00 | 167.86 | 147.07 | 126.28 | 105.49 | 84.70 | 63.91 | 43.11 | 22.32 | 1.53 | 0.00 | 0.00 |
| 4,614.00 & | ab | ove Ad | d 4.99 Perc | ent To Exce | ss Over 4,6 | 14.00 |
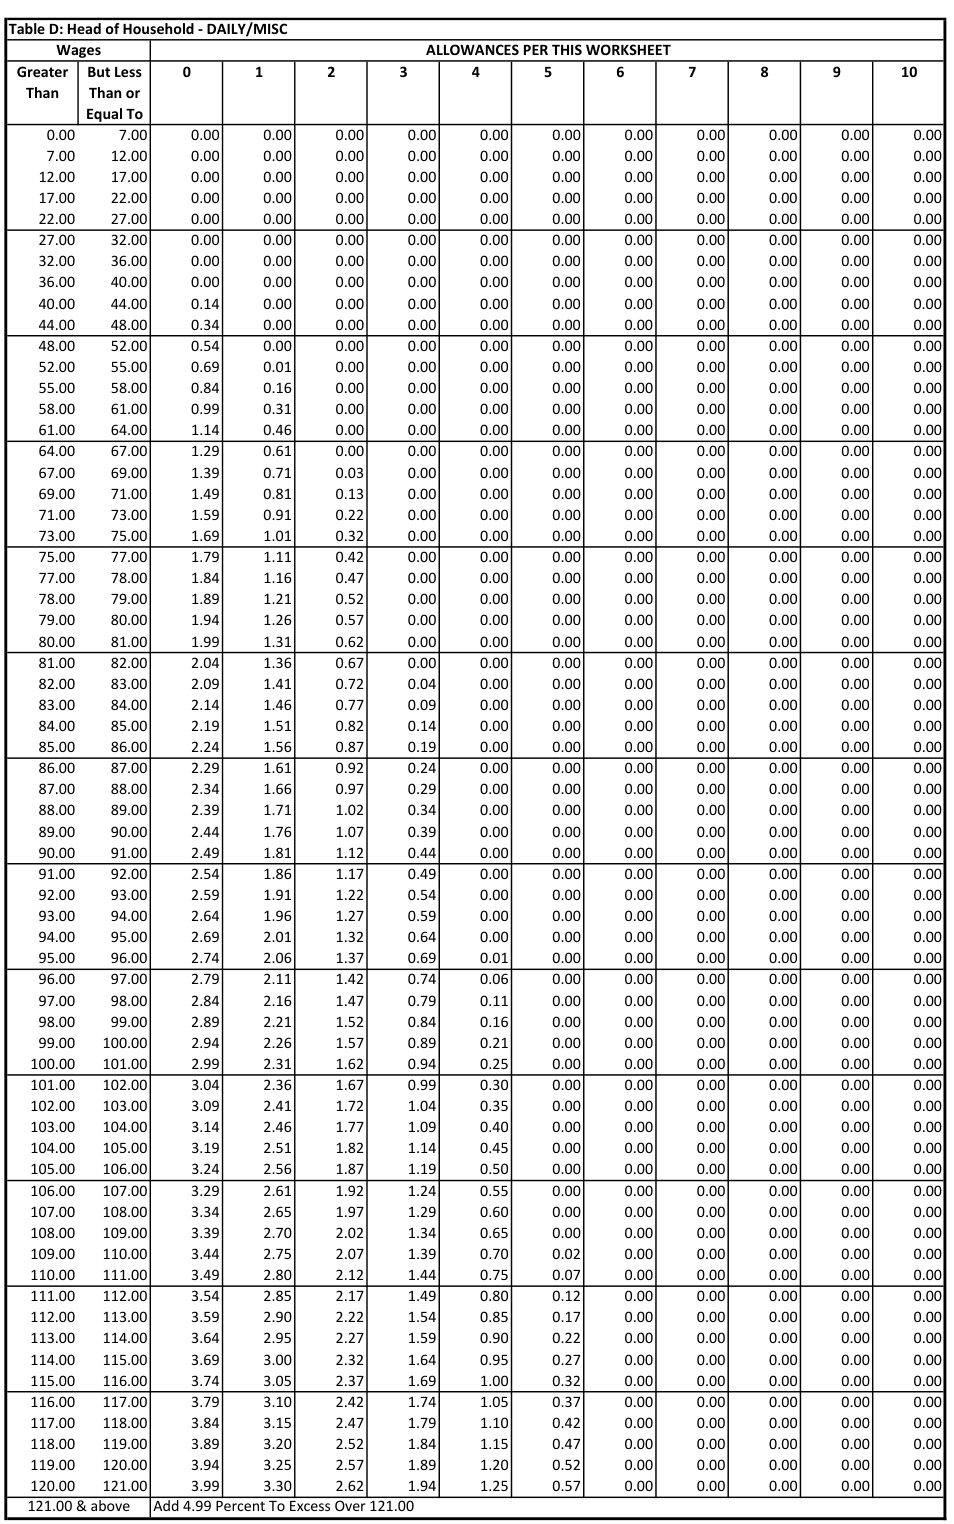
Text version of this table
| Wages | ALLOWA | NCES PER | THIS WOR | KSHEET | |||||||||
| eater Bu | t | Less 0 | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 1 0 | |
| han Th | a | n or | |||||||||||
| Eq | u | al To | |||||||||||
| 0.00 | 7.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 7.00 | 12.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 12.00 | 17.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 17.00 | 22.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 22.00 | 27.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 27.00 | 32.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 32.00 | 36.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 36.00 | 40.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 40.00 | 44.00 | 0.14 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 44.00 | 48.00 | 0.34 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 48.00 | 52.00 | 0.54 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 52.00 | 55.00 | 0.69 | 0.01 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 55.00 | 58.00 | 0.84 | 0.16 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 58.00 | 61.00 | 0.99 | 0.31 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 61.00 | 64.00 | 1.14 | 0.46 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 64.00 | 67.00 | 1.29 | 0.61 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 67.00 | 69.00 | 1.39 | 0.71 | 0.03 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 69.00 | 71.00 | 1.49 | 0.81 | 0.13 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 71.00 | 73.00 | 1.59 | 0.91 | 0.22 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 73.00 | 75.00 | 1.69 | 1.01 | 0.32 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 75.00 | 77.00 | 1.79 | 1.11 | 0.42 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 77.00 | 78.00 | 1.84 | 1.16 | 0.47 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 78.00 | 79.00 | 1.89 | 1.21 | 0.52 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 79.00 | 80.00 | 1.94 | 1.26 | 0.57 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 80.00 | 81.00 | 1.99 | 1.31 | 0.62 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 81.00 | 82.00 | 2.04 | 1.36 | 0.67 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 82.00 | 83.00 | 2.09 | 1.41 | 0.72 | 0.04 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 83.00 | 84.00 | 2.14 | 1.46 | 0.77 | 0.09 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 84.00 | 85.00 | 2.19 | 1.51 | 0.82 | 0.14 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 85.00 | 86.00 | 2.24 | 1.56 | 0.87 | 0.19 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 86.00 | 87.00 | 2.29 | 1.61 | 0.92 | 0.24 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 87.00 | 88.00 | 2.34 | 1.66 | 0.97 | 0.29 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 88.00 | 89.00 | 2.39 | 1.71 | 1.02 | 0.34 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 89.00 | 90.00 | 2.44 | 1.76 | 1.07 | 0.39 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 90.00 | 91.00 | 2.49 | 1.81 | 1.12 | 0.44 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 91.00 | 92.00 | 2.54 | 1.86 | 1.17 | 0.49 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 92.00 | 93.00 | 2.59 | 1.91 | 1.22 | 0.54 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 93.00 | 94.00 | 2.64 | 1.96 | 1.27 | 0.59 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 94.00 | 95.00 | 2.69 | 2.01 | 1.32 | 0.64 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 95.00 | 96.00 | 2.74 | 2.06 | 1.37 | 0.69 | 0.01 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 96.00 | 97.00 | 2.79 | 2.11 | 1.42 | 0.74 | 0.06 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 97.00 | 98.00 | 2.84 | 2.16 | 1.47 | 0.79 | 0.11 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 98.00 | 99.00 | 2.89 | 2.21 | 1.52 | 0.84 | 0.16 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | |
| 99.00 | 1 | 00.00 | 2.94 | 2.26 | 1.57 | 0.89 | 0.21 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 100.00 | 1 | 01.00 | 2.99 | 2.31 | 1.62 | 0.94 | 0.25 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 101.00 | 1 | 02.00 | 3.04 | 2.36 | 1.67 | 0.99 | 0.30 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 102.00 | 1 | 03.00 | 3.09 | 2.41 | 1.72 | 1.04 | 0.35 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 103.00 | 1 | 04.00 | 3.14 | 2.46 | 1.77 | 1.09 | 0.40 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 104.00 | 1 | 05.00 | 3.19 | 2.51 | 1.82 | 1.14 | 0.45 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 105.00 | 1 | 06.00 | 3.24 | 2.56 | 1.87 | 1.19 | 0.50 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 106.00 | 1 | 07.00 | 3.29 | 2.61 | 1.92 | 1.24 | 0.55 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 107.00 | 1 | 08.00 | 3.34 | 2.65 | 1.97 | 1.29 | 0.60 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 108.00 | 1 | 09.00 | 3.39 | 2.70 | 2.02 | 1.34 | 0.65 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 109.00 | 1 | 10.00 | 3.44 | 2.75 | 2.07 | 1.39 | 0.70 | 0.02 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 110.00 | 1 | 11.00 | 3.49 | 2.80 | 2.12 | 1.44 | 0.75 | 0.07 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 111.00 | 1 | 12.00 | 3.54 | 2.85 | 2.17 | 1.49 | 0.80 | 0.12 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 112.00 | 1 | 13.00 | 3.59 | 2.90 | 2.22 | 1.54 | 0.85 | 0.17 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 113.00 | 1 | 14.00 | 3.64 | 2.95 | 2.27 | 1.59 | 0.90 | 0.22 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 114.00 | 1 | 15.00 | 3.69 | 3.00 | 2.32 | 1.64 | 0.95 | 0.27 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 115.00 | 1 | 16.00 | 3.74 | 3.05 | 2.37 | 1.69 | 1.00 | 0.32 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 116.00 | 1 | 17.00 | 3.79 | 3.10 | 2.42 | 1.74 | 1.05 | 0.37 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 117.00 | 1 | 18.00 | 3.84 | 3.15 | 2.47 | 1.79 | 1.10 | 0.42 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 118.00 | 1 | 19.00 | 3.89 | 3.20 | 2.52 | 1.84 | 1.15 | 0.47 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 119.00 | 1 | 20.00 | 3.94 | 3.25 | 2.57 | 1.89 | 1.20 | 0.52 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 120.00 | 1 | 21.00 | 3.99 | 3.30 | 2.62 | 1.94 | 1.25 | 0.57 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| 121.00 & ab | o | ve Add 4 | .99 Percent | To Excess | Over 121.0 | 0 |
J
-------------------------------------------------------------------------------------------------- ----------' .. -.. ----.. --- … - … - … -- … - … - … "' .. - … -.. -... --- … ---- … -.. -- … ,
# PERCENTAGE METHOD FOR EMPLOYEE WITHHOLDING
Use these instructions to calculate employee withholding using the percentage method.
(1) Subtract from the taxable wages the applicable standard deduction as indicated in column (1) - (3) of Table E.
(2) If employees claim dependents, subtract from the amount arrived at in (1) the appropriate dependent amount as set out in column (4) of Table E.
(3) Multiply the amount arrived in (2) by 4.99%
(4) If zero exemption is claimed, subtract the standard deduction only.
# TABLE E
EXAMPLE #1
# STANDARD DEDUCTION
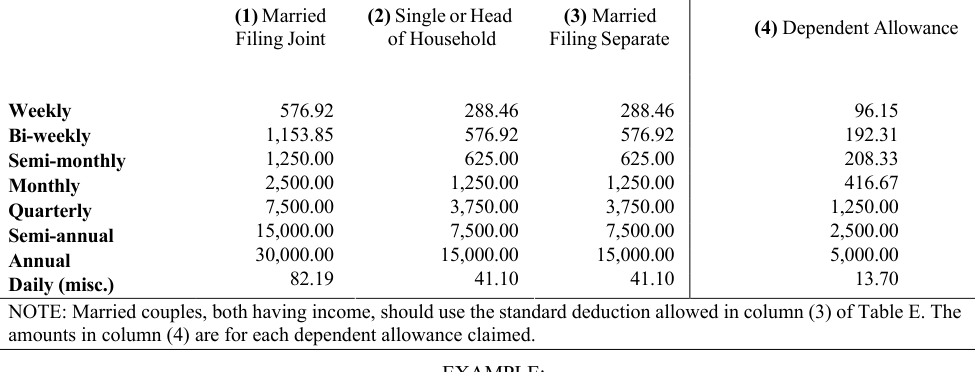
# DEPENDENT ALLOWANCE
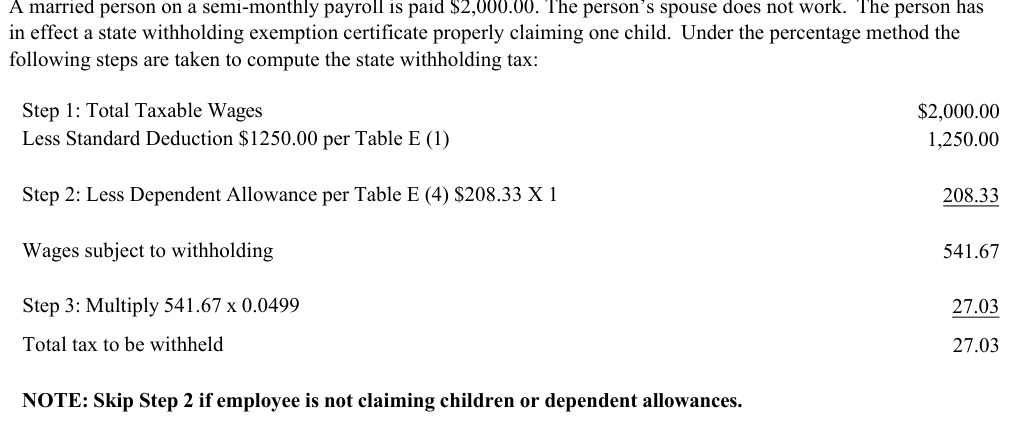
# NOTE: Skip Step 2 if employee is not claiming children or dependent allowances.
------------------------------------------------------------------------------------------------------------'
# PERCENTAGE METHOD FOR EMPLOYEE WITHHOLDING
J
# PERCENTAGE METHOD FOR EMPLOYEE WITHHOLDING
-----------------------------------------------------------------------------------------------------------Use these instructions to calculate employee withholding using the percentage method.
(1) Subtract from the taxable wages the applicable standard deduction as indicated in column (1) - (3) of Table F.
(2) If employees claim dependents, subtract from the amount arrived at in (1) the appropriate dependent amount as set out in column (4) of Table F.
(3) Multiply the amount arrived in (2) by 4.99%
(4) If zero exemption is claimed, subtract the standard deduction only.
# TABLE F
EXAMPLE #2
# STANDARD DEDUCTION
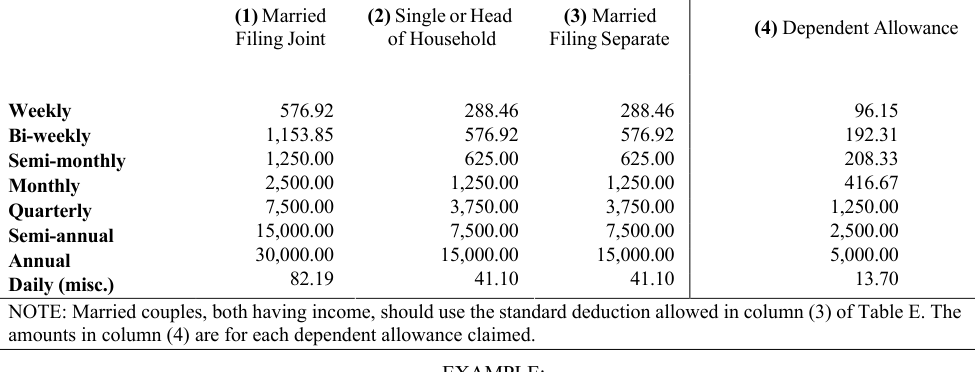
# Bi-weekly
# Semi-monthly
# Monthly
# Quarterly
# Semi-annual
# Annual
82.19
# DEPENDENT ALLOWANCE
(2) Single or Head (3) Married
(4) Dependent Allowance of Household Filing Separate 96.15 288.46 288.46 192.31 576.92 576.92 208.33 625.00 625.00 416.67 1,250.00 1,250.00 1,250.00 3,750.00 3,750.00 2,500.00 7,500.00 7,500.00 5,000.00 15,000.00 15,000.00 13.70 41.10 41.10 NOTE: Married couples, both having income, should use the standard deduction allowed in column (3) of Table F. The amounts in column (4) are for each dependent allowance claimed.
EXAMPLE: is paid $ 935.00. The person has in effect a state A single person filing Head of Household on a bi-weekly payroll withholding exemption certificate properly claiming two children. The person would have $0 withheld from their biweekly paycheck. Under the percentage method the following steps are taken to compute the state withholding tax:
Step 1: Total Taxable Wages
Less Standard Deduction $576.92 per Table F (1) $935.00 $576.92 $384.62 Step 2: Less Dependent Allowance per Table F (4) $192.31 X 2 Wages subject to withholding Step 3: Multiply 0.00 x 0.0499 Total tax to be withheld
# NOTE: Skip Step 2 if employee is not claiming children or dependent allowances.
$0.00
$0.00
$0.00 l
0 0 H • 0 •--• H
H• " • •- • ,.H "" "" ,., •- ••- - , _ ,._ S G-7 Schedule B Quarterly Return for Semi-weekly Payers
G-7 Quarterly Return for Monthly Payers G-7 Quarterly Return for Quarterly Payers G-7 NRW Nonresident Withholding Return G2-FP Production Companies Withholding Georgia Income Tax G2-FL Claim withholding reported on the G2-FP and G2-FL GA-V Withholding Payment Voucher
G-1003 Income Statement Transmittal G-4 Employee's Withholding Allowance Certificate G-4P Withholding Certificate for Pension or Annuity Payments G2-RP Withholding on Sale of Real Property
G2-A Withholding on Distributions to Nonresident Members/Shareholders IT-550 Claim for Refund of Georgia Income Tax Erroneously or Illegally Collected G2-LP Withholding on Sales or Assignment of Lottery Payments
Request a Tax Clearance Certificate
# FORM
------------------------------------------------------------------------------------------,
DEPARTMENT OF REVENUE RESOURCES
J
PARTMENT OF REVENUE RESOURCES
DE
For additional information regarding Georgia withholding tax reporting and payment requirements, you may contact the Taxpayer Services Division at 1-877-423-6711. You may also contact one of the Regional Offices listed below.
# Albany Regional Office:
Text version of this table
| Albany Regional Office: 735 N Westover Blvd Suite A Albany, GA 31707 United States Phone: (229) 430-4241 | Cartersville Regional Office: 314 East Main Street Suite 150 Cartersville, GA 30120 United States Phone: (770) 387-4060 | Macon Regional Office: 6055 Lakeside Commons Dr. Suite 220 Macon, GA 31210 United States Phone: (478) 471-3550 |
| Athens Regional Office: 1047 Summit Grove Dr. Building 100, Suite 101 Watkinsville, GA 30677 United States Phone: (706) 389-6977 | Columbus Regional Office: 7300 Blackmon Road, Ste 100B Columbus, GA 31909 United States Phone: (706) 649-7451 | Savannah Regional Office: 1000 Towne Center Blvd., Building 900, Suite A Pooler, GA 31322 United States Phone: (912) 748-5199 |
| Atlanta Regional Office: 2595 Century Pkwy. NE Suite 301 Atlanta, GA 30345 United States Phone: (404) 417-6605 | Douglas Regional Office: 1214 N Peterson Ave., Suite I Douglas, GA 31533 United States Phone: (912) 389-4094 | South Metro Regional Office: 4125 Welcome All Road, Suite 914 Atlanta, GA 30349 United States Phone: (404) 724-7200 |
| Augusta Regional Office: 610 Ronald Reagan Drive, Building G-1 Evans, GA 30809 United States Phone: (706) 650-6300 | Gainesville Regional Office: 528 Broad St SE Gainesville, GA 30501-3728 United States Phone: (770) 718-3700 |
# Athens Regional Office:
# Atlanta Regional Office:
# Augusta Regional Office:
# Cartersville Regional Office:
# Columbus Regional Office:
# Douglas Regional Office:
# Gainesville Regional Office:
# Macon Regional Office:
# Savannah Regional Office:
# South Metro Regional Office:
Source: view the official PDF
The source document contains 2 figures (charts or worksheet graphics) not reproduced in this text version. See the official PDF above.
Nearby sections (13 sections)
- 500-es · Form 500-ES — Individual & Fiduciary Estimated Tax Payment…
- 602-es · Form 602-ES — Corporate and Partnership Estimated Tax
- cr-es · Form CR-ES — Composite Return Estimated Tax / Payment Voucher
- employers-tax-guide · Georgia Employer's Tax Guide
- g-7m · Form G-7M — Withholding Quarterly Return (Monthly Payer)
- ga-8453 · Form GA-8453 — Individual Income Tax Declaration for E-filing
- it-501 · IT-501/501X — Fiduciary Income Tax Instruction Booklet
- it-511 · IT-511 — Individual Income Tax Instruction Booklet
- it-560c · Form IT-560C — Corporate Extension / Payment Voucher
- it-611 · IT-611 — Corporation Income Tax Instruction Booklet
- it-611s · IT-611S — S Corporation Income Tax Instruction Booklet
- it-711 · IT-711 — Partnership Income Tax Instruction Booklet
- st-3 · Form ST-3 — Sales and Use Tax Returns (effective Oct 2022)