Florida Department of Revenue Form Instructions
Form DR-15TDT — Local Option Transient Rental Tax Rates
R. 03/25
Local Option Transient Rental Tax Rates
(Tourist Development Tax Rates)
Individual Florida counties and certain cities may impose a local option tax on the rental or lease of living, sleeping, or housekeeping accommodations for a term of six months or less. These taxes, often called local option transient rental taxes, include the tourist development tax, convention development tax, tourist impact tax, and municipal resort tax. The local tax imposed is in addition to the 6% state sales tax and any applicable discretionary sales surtax.
For the counties shaded in gray in the chart below, the local option transient rental taxes are reported and remitted to the Florida Department of Revenue (DOR). For all other counties, the local option transient rental taxes are reported and remitted directly to the county; however, sales tax and discretionary sales surtax on transient rentals are always reported and remitted to the Department.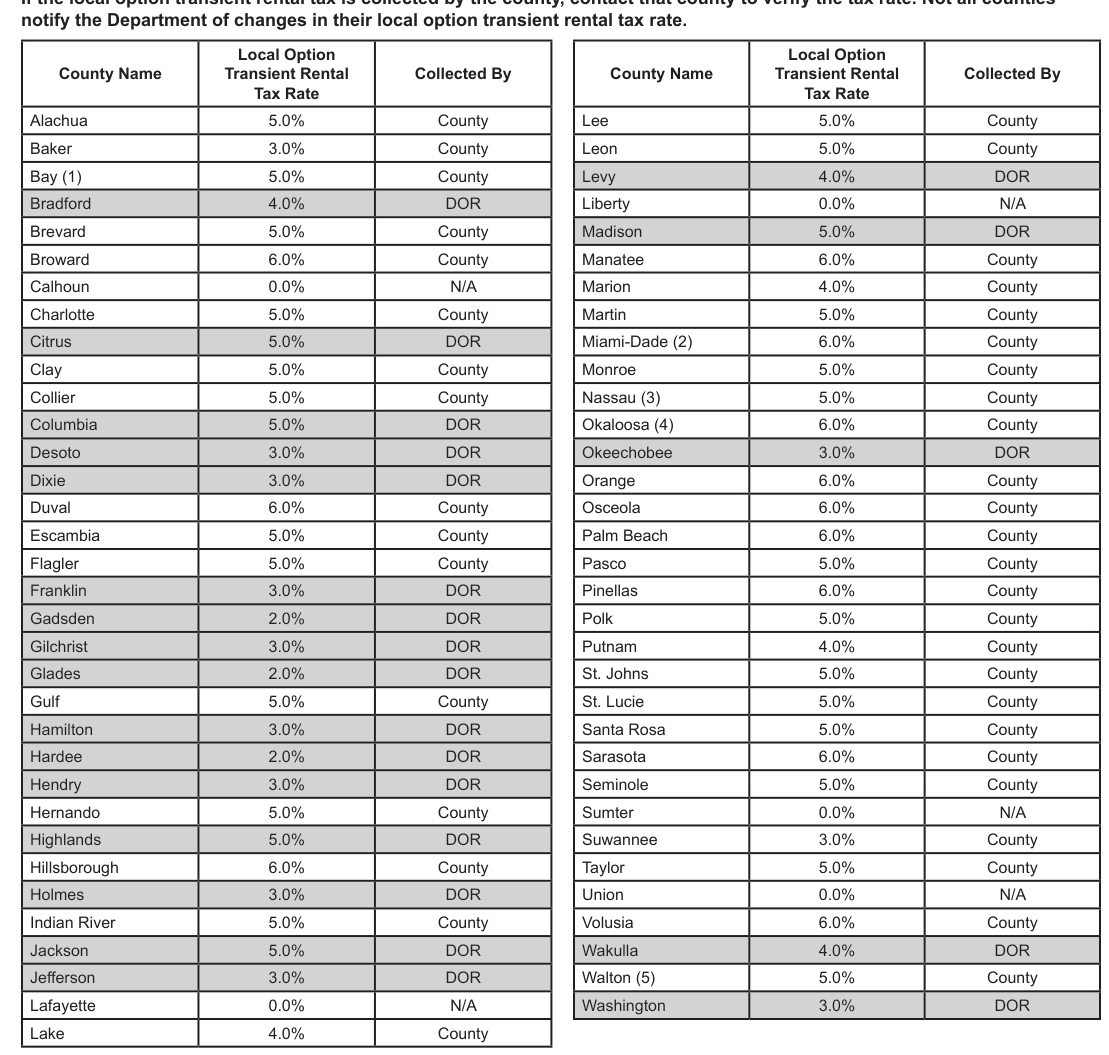
Text version of this table
County Name Local Option Transient Rental Tax Rate Collected By County Name Local Option Transient Rental Tax Rate Collected By Alachua 5.0% County Lee 5.0% County Baker 3.0% County Leon 5.0% County Levy 4.0% DOR Liberty 0.0% N/A Madison 5.0% DOR Manatee 6.0% County Marion 4.0% County Martin 5.0% County Miami-Dade (2) 6.0% County Monroe 5.0% County Nassau (3) 5.0% County Okaloosa (4) 6.0% County Okeechobee 3.0% DOR Orange 6.0% County Osceola 6.0% County Palm Beach 6.0% County Pasco 5.0% County Pinellas 6.0% County Polk 5.0% County Putnam 4.0% County St. Johns 5.0% County St. Lucie 5.0% County Santa Rosa 5.0% County Sarasota 6.0% County Seminole 5.0% County Sumter 0.0% N/A Suwannee 3.0% County Taylor 5.0% County Union 0.0% N/A Volusia 6.0% County Wakulla 4.0% DOR Walton (5) 5.0% County Washington 3.0% DOR Leon 5.0% County Bay (1) 5.0% County Levy 4.0% DOR Bradford 4.0% DOR Liberty 0.0% N/A Brevard 5.0% County Madison 5.0% DOR Broward 6.0% County Manatee 6.0% County Calhoun 0.0% N/A Marion 4.0% County Martin 5.0% County Charlotte 5.0% County Citrus 5.0% DOR Miami-Dade (2) 6.0% County Clay 5.0% County Monroe 5.0% County Collier 5.0% County Nassau (3) 5.0% County Columbia 5.0% DOR Okaloosa (4) 6.0% County Desoto 3.0% DOR Okeechobee 3.0% DOR Dixie 3.0% DOR Orange 6.0% County Duval 6.0% County Osceola 6.0% County Escambia 5.0% County Palm Beach 6.0% County Flagler 5.0% County Pasco 5.0% County Franklin 3.0% DOR Pinellas 6.0% County Gadsden 2.0% DOR Polk 5.0% County Gilchrist 3.0% DOR Putnam 4.0% County Glades 2.0% DOR St. Johns 5.0% County Gulf 5.0% County St. Lucie 5.0% County Hamilton 3.0% DOR Santa Rosa 5.0% County Hardee 2.0% DOR Sarasota 6.0% County Hendry 3.0% DOR Seminole 5.0% County Hernando 5.0% County Sumter 0.0% N/A Highlands 5.0% DOR Suwannee 3.0% County Hillsborough 6.0% County Taylor 5.0% County Holmes 3.0% DOR Union 0.0% N/A Indian River 5.0% County Volusia 6.0% County Wakulla 4.0% DOR Jackson 5.0% DOR Jefferson 3.0% DOR Walton (5) 5.0% County Lafayette 0.0% N/A Washington 3.0% DOR Lake 4.0% County
DOR
(1) Bay: Applies only to ZIP codes 32401, 32404, 32405, 32407, 32408, 32410, and Bay County portion of 32413.
(2) Miami-Dade: 4% for Surfside and Bal Harbour, 7% for Miami Beach, and 6% for the rest of the county.
(3) Nassau: Applies only to Amelia Island (ZIP code 32034).
(4) Okaloosa: 6% for the Okaloosa County Tourist Development Tax District and 6% for the Expansion District.
(5) Walton: 5% for ZIP codes 32459, 32550, 32454, 32461, and Walton County portion of 32413; and 2% for the rest of the county.
For local option transient rental tax collected by the Florida Department of Revenue:
- The transient rental tax is filed and paid along with the 6% state sales tax and any discretionary sales surtax, using the Sales and Use Tax Return (Form DR-15).
- For questions, call Taxpayer Services at 850-488-6800, Monday through Friday, excluding holidays.
For local option transient rental taxes collected by the county:
- The transient rental tax is reported and paid directly to the county; however, the 6% state sales tax and any discretionary sales surtax is reported and paid to the Florida Department of Revenue using Line D. (Transient Rentals) on the Sales and Use Tax Return (Form DR-15).
- For questions, contact the county imposing the local option tax.
For more information regarding the taxability of transient rentals, review Rule 12A-1.061, Florida Administrative Code, available online at flrules.org.
R. 03/25
Source: view the official PDF
Nearby sections (12 sections)
- dr-1 · Form DR-1 — Florida Business Tax Application
- dr-15 · Form DR-15 — Florida Sales and Use Tax Return
- dr-15n · Form DR-15N — Instructions for Form DR-15 (Sales and Use Tax)
- dr-15tdt · Form DR-15TDT — Local Option Transient Rental Tax Rates
- dr-309632 · Form DR-309632 — Wholesaler/Importer Fuel Tax Return
- f-1065 · Form F-1065 — Florida Partnership Information Return
- f-1120 · Form F-1120 — Florida Corporate Income/Franchise Tax Return
- f-1120es · Form F-1120ES — Declaration/Installment of Florida Estimated…
- f-1120n · Form F-1120N — Instructions for Form F-1120 (Corporate Income…
- f-2220 · Form F-2220 — Underpayment of Estimated Tax on Florida…
- f-7004 · Form F-7004 — Florida Tentative Income/Franchise Tax Return…
- dr-15ezn · Form DR-15EZN — Instructions for DR-15EZ Sales and Use Tax…