Form CT-1040X — Amended Connecticut Income Tax Return for Individuals
Department of Revenue Services
State of Connecticut
1040X 1225W 01 9999
# Tax Return for Individuals
File and pay Form CT‑1040X electronically using myconneCT at portal.ct.gov/DRS-myconneCT.
2 0 2 5
For January 1 ‑ December 31, 2025, or other tax year beginning Your first name Middle initial If joint return, spouse's first name Middle initial Mailing address (number and street) and ending M M - D D - Y Y Y Y M M - D D - Y Y Y Y Last name Deceased Your Social Security Number (SSN) Last name Deceased Spouse's SSN Mailing address 2 (apartment number, PO Box) State City, town, or post office City or town of residence if different from above
Filing Status
# Single
On original return:
On this return:
ZIP code Country code
ZIP code Spouse's name (if Married filing separately) Head of Married Qualifying Married Filing Household Filing Jointly Surviving Spouse Separately Check the box below if you are amending your return as a result of federal or state audit changes to your income tax return or as a result of a timely-filed amended federal or state return. Enter the date of the federal or other state's final determination below. See Instructions Page 1.
Final Determination Date: Federal or state changes M M - D D - Y Y Y Y You must attach a copy of the IRS audit or other state's results, federal Form 1040X, Form 1045, the other state's amended return, supporting documentation, and proof of the final determination.
Form CT-1040 CRC, Claim of Right Credit Check the appropriate box to identify if you are attaching a completed:
Form CT-19IT, Title 19 Status Release Form CT-8379, Nonobligated Spouse Claim Federal Form 1310, Statement of Person Claiming Refund Due a Deceased Taxpayer Declaration: I declare under penalty of law that I have examined this return and all accompanying schedules and statements, including reporting and payment of any use tax due, and, to the best of my knowledge and belief, it is true, complete, and correct. I understand the penalty for willfully delivering a false return or document to the Department of Revenue Services (DRS) is a fine of not more than $5,000, or imprisonment for not more than five years, or both. The declaration of a paid preparer other than the taxpayer is based on all information of which the preparer has any knowledge.
Your signature
Sign Here
Spouse's signature (if joint return) Keep a copy of this return Type or print paid preparer's name for your records.
Paid preparer's signature
Paid preparer's PTIN
Firm's name, address, and ZIP code Date (MM-DD-YYYY) Home/cell telephone number Date (MM-DD-YYYY) Daytime telephone number Your email address Date (MM-DD-YYYY) Telephone number Firm's Federal Employer Identification Number (FEIN) Check if self- employed Make your check payable to Commissioner of Revenue Services. To ensure proper Mail to: Department of Revenue Services posting of your payment, write your Social Security Number(s) (SSN) (optional) PO Box 2935 and "2025 Form CT‑1040X" on your check. DRS may submit your check to your bank electronically.
Hartford CT 06104-2935
1040X 1225W 02 9999
A. Original amount or as C. Correct amount
Income
B. Net change increase previously adjusted
- Federal adjusted gross income from federal Form 1040, Line 11a, or federal
Form 1040‑SR, Line 11a … 1.
- Additions, if any: See instructions … 2.
- Add Line 1 and Line 2 … 3.
- Subtractions, if any: See instructions … 4.
- Connecticut adjusted gross income:
Subtract Line 4 from Line 3 … 5.
Residents go to Line 10;
Nonresidents and part-year residents go to Line 6.
Nonresidents and Part-Year Residents Only
- Enter your income from Connecticut sources from Schedule CT‑SI. If less than or equal to zero, enter "0." … 6.
- Enter the greater of Line 5 or Line 6. If zero, go to Line 10 and enter "0." … 7.
- Income tax from Tax Calculation Schedule:
See instructions … 8.
- Divide Line 6 by Line 5. If Line 6 is equal to
. or greater than Line 5, enter 1.0000 … 9.
Tax
- Income tax: See instructions … 10.
- Credit for income taxes paid to qualifying jurisdictions: See instructions. Residents and part-year residents only … 11.
- Subtract Line 11 from Line 10 … 12.
- Connecticut alternative minimum tax from
Form CT‑6251 … 13.
- Add Line 12 and Line 13 … 14.
- Credit for property tax paid on your primary residence or motor vehicle, or both: Residents only, see instructions … 15.
- Subtract Line 15 from Line 14. If less than or equal to zero, enter "0." … 16.
- Total allowable credits from
Schedule CT‑IT Credit, Part 1, Line 10 … 17.
- Connecticut income tax: Subtract Line 17 from Line 16 … 18.
- Individual use tax: See instructions … 19.
- Total tax: Add Line 18 and Line 19 … 20. or (decrease) .
.00 .00 .00 .00 .00 .00 .00 .00 .00 .00 .00 .00 .00 .00 .00 .00 .00 .00 .00
Continue on Page 3. Taxpayers must sign declaration on Page 1.
1040X 1225W 03 9999
B. Net change increase
A. Original amount or as previously adjusted or (decrease)
20a. Enter amounts from Line 20 … 20a.
Payments and refundable credits
- Connecticut tax withheld: Enter amount from Line 70 … 21.
- All 2025 estimated Connecticut income tax payments (including any overpayments applied from a prior year) and extension payments … 22. 22a. Connecticut earned income tax credit:
From Schedule CT‑EITC, Line 16. Schedule must be attached. Residents only … 22a.
22b. Claim of right credit:
From Form CT‑1040 CRC, Line 6. Form must be attached … 22b.
22c. Pass‑Through Entity Tax Credit: From
Schedule CT‑PE, Line 1. Schedule must be attached … 22c.
22d. Historic Home Rehabilitation Credit … 22d.
- Amounts paid with original return, plus additional tax paid after it was filed:
Do not include penalty and interest … 23.
- Total payments and refundable credits:
C. Correct amount .00 .00
.00 .00
.00
.00
.00 .00
Add Lines 21, 22, 22a, 22b, 22c, 22d and 23 … 24. .00
- Overpayment, if any, as shown on original return or as previously adjusted … 25. .00
- Subtract Line 25 from Line 24 … 26.
Refund .00 .00
- If Line 26 is greater than Line 20a, Column C, enter the amount overpaid … 27.
Amount You Owe
- If Line 20a, Column C, is greater than Line 26 enter the amount of tax due … 28. .00
- Interest: Multiply Line 28 by number of months or fraction of a month, then by 1% (.01) … 29. .00
- Amount you owe with this return: Add Line 28 and Line 29 … Amount you owe 30. .00
Reason(s) for amending return: Enter the line number for each item you are changing and give the reason for each change in the space below.
Attach supporting forms and schedules for items changed. Write your name and SSN(s) on all attachments.
# Subtractions From Federal Adjusted Gross Income
- Interest on U.S. government obligations … 39. .00
- Exempt dividends from certain qualifying mutual funds derived from U.S. government obligations … 40. .00
- Social Security benefit adjustment from Social Security Benefit Adjustment Worksheet … 41. .00
- Refunds of state and local income taxes … 42. .00
- Tier 1 and Tier 2 railroad retirement benefits and supplemental annuities … 43. .00
- Military retirement pay … 44. .00
- 50% of income received from the Connecticut Teachers' Retirement System … 45. .00
- Beneficiary's share of Connecticut fiduciary adjustment: Enter only if less than zero … 46. .00
- Gain on sale of Connecticut state and local government bonds … 47. .00
- Connecticut Higher Education Trust (CHET) contributions made in 2025 or an excess carried forward from. 48. .00 a prior year. See instructions …
48a. 25% of Section 168(k) federal bonus depreciation deduction added back in preceding four years … 48a. .00
48b. Pension or annuity income. See instructions … 48b. .00
48c. Ordinary and necessary business expenses for taxpayers licensed under Chapter 420f or 420h that are not claimed for federal income tax purposes … 48c. .00
48d. Achieving Better Life Experience (ABLE) … 48d. .00
- Other - specify: Do not include out-of-state income. 49. .00
- Total subtractions: Add Lines 39 through 49. Enter here and on Page 2, Line 4, Column C … 50. .00 1040X 1225W 04 9999
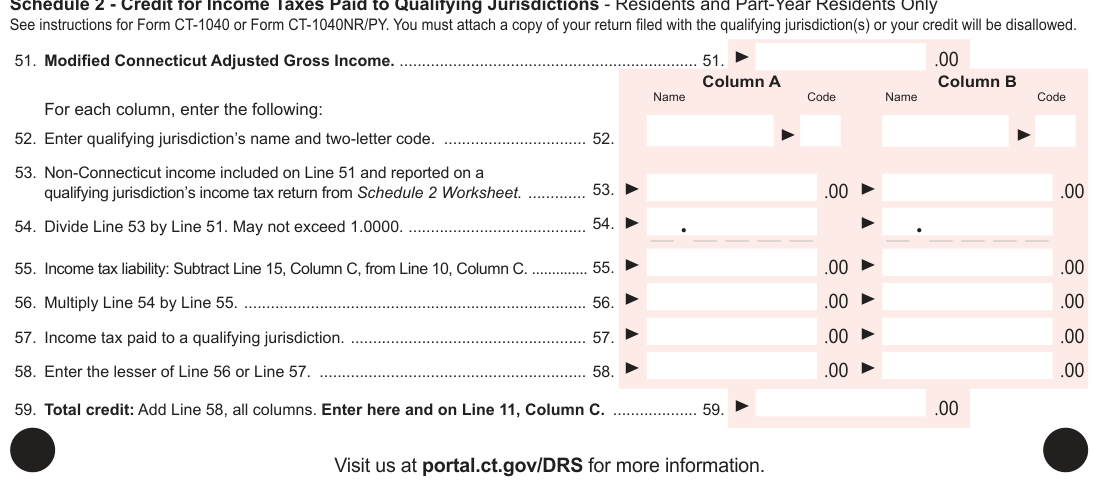
Text version of this table
.................. 51. .00 Col Name . umn A Colu Code Name .00 . .00 .00 .00 .00 mn B Code .00 .00 .00 .00 .00 .................. 59. .00 more information. .00
# Additions to Federal Adjusted Gross Income
- Interest on state and local government obligations other than Connecticut … 31. .00
- Mutual fund exempt‑interest dividends from non‑Connecticut state or municipal government obligations other than Connecticut … 32. .00
- Taxable amount of lump-sum distributions from qualified plans not included in federal adjusted gross income … 33. .00
- Beneficiary's share of Connecticut fiduciary adjustment: Enter only if greater than zero … 34. .00
- Loss on sale of Connecticut state and local government bonds … 35. .00
- Section 168(k) federal bonus depreciation deduction allowed for property placed in service during this year … 36. .00 36a. 80% of Section 179 federal deduction. See instructions … 36a. .00
- Other ‑ specify. .37. .00
- Total additions: Add Lines 31 through 37. Enter here and on Page 2, Line 2, Column C … 38. .00 Schedule 1 - Modifications to Federal Adjusted Gross Income - Enter all amounts as positive numbers.
1040X 1225W 05 9999
Schedule 3 - Property Tax Credit - (Connecticut full-year residents only.) See instructions.
Qualifying Property Description of Property
Name of Date(s) Paid Amount Paid If primary residence, enter street address. If Connecticut Tax (MM-DD-YYYY) motor vehicle, enter year, make, and model.
Town or District
# 60. Primary Residence
- Auto 1
- Auto 2 - Married filing jointly or qualifying surviving spouse only.
- Total property tax paid: Add Lines 60, 61, and 62.
- Maximum property tax credit allowed.
- Enter the lesser of Line 63 or Line 64. .00
- .00
- .00
- .00
- .00
- .00
65.
- Enter the decimal amount for your filing status and Connecticut AGI from the 2025 Property Tax Credit Table.
If zero, enter the amount from Line 65 on Line 68.
- Multiply Line 65 by Line 66. .
67.
- Subtract Line 67 from Line 65. Enter here and on Line 15, Column C. Attach Schedule 3 to your return or your credit will be disallowed. .00
Schedule 4 - Individual Use Tax - Do you owe use tax? Complete the Connecticut Individual Use Tax Worksheet in the Connecticut Resident Tax Information Return Instructions to calculate your use tax liability. .00
69a. Total use tax due at 1%: From Connecticut Individual Use Tax Worksheet, Section A, Column 7 69a. .00
69b. Total use tax due at 6.35%: From Connecticut Individual Use Tax Worksheet, Section B, Column 7 69b. .00
69c. Total use tax due at 7.75%: From Connecticut Individual Use Tax Worksheet, Section C, Column 7 69c. .00
69d. Total use tax due at 2.99%: From Connecticut Individual Use Tax Worksheet, Section D, Column 7 69d.
- Individual use tax: Add Lines 69a through 69d. If no use tax is due, enter "0."
Enter here and on Line 19, Column C. .00 69.
Withholding Schedule: Only enter information from your Forms W‑2, 1099, and Schedules CT K‑1 if Connecticut income tax was withheld.
Column A: Employer Federal ID Number Column C: CT Income Tax Withheld Schedule
Column B: CT Wages, Tips, etc.
Do not include dashes.
70a.
70b.
70c.
70d.
70e.
CT K-1 Check box at left if from Schedule CT K‑1. .00 .00 .00 .00 .00 .00 .00 .00 .00 .00
70f. Enter additional Connecticut withholding from Supplemental Schedule CT‑1040WH, Line 3. .00
- Total Connecticut income tax withheld: Enter here and on Line 21, Column C. .00
Department of Revenue Services
# State of Connecticut
Purpose: Use this form to amend a previously-filed 2025 Connecticut income tax return for individuals. This form may not be used to amend any other year's return. Do not use this form to amend Form CT‑1041 or Form CT‑1065/CT-1120SI.
Please note that each form is year specific. To prevent any delay in processing your return, the correct year's form must be submitted to DRS. Do not use staples.
Visit the Department of Revenue Services website at portal.ct.gov/DRS-myconneCT to file Form CT-1040X electronically using myconneCT.
If Form CT‑1040X is filed to request an overpayment of Connecticut income tax refunded or credited, it must be filed before the Connecticut statute of limitations expires. Generally, the Connecticut statute of for refunding or crediting any Connecticut income tax overpayment expires three years after the due date of the return, but if a timely request for an extension of time to file a return was filed, the statute of limitations expires three years after the extended due date of the return or three years after the date of filing the return, whichever is earlier. If you were required to file an amended return, but failed to do so, a penalty may be imposed. Interest will also be assessed on any additional Connecticut income tax not paid on or before the due date.
If you are filing Form CT‑1040X due to federal or another state's changes or corrections to your federal or other state's income tax return, you must check the box labeled Federal or state changes and enter the date of the final determination on Form CT‑1040X, Page 1.
# You must file Form CT-1040X in the following circumstances:
- To have an overpayment refunded instead of applied to next year's estimated tax or to change your contributions to designated charities. The elections that you made on your original return cannot be changed by filing Form CT‑1040X.
- To amend your Connecticut income tax return for an earlier year to claim a credit for income tax paid on income included in your Connecticut adjusted gross income for that year and repaid in a later taxable year. File Form CT‑1040 CRC, Claim of Right Credit, with your Connecticut income tax return for the later taxable year.
Financial Disability: If you are financially disabled, as defined in IRC § 6511(h)(2), the time for having an overpayment of Connecticut income tax refunded or credited to you is extended for as long as you are financially disabled. You are considered financially disabled if you are unable to manage your own affairs by reason of a medically determinable physical or mental impairment that has lasted or can be expected to last for a continuous period of not less than 12 months.
You are not considered financially disabled during any period that your spouse or any other person is authorized to act on your behalf in financial matters. See Policy Statement 2001(14), Claims for Refund Made by Financially Disabled Individuals.
# Completing Form CT‑1040X
Line numbers on Form CT‑1040X may be different from the line numbers on your original return.
Step 1: Check the box labeled Federal or state changes on Form CT‑1040X, Page 1 if you are amending your return as a result of the following:
- An IRS or federal court change or correction made to your federal return;
- If tax officials or courts of a qualifying jurisdiction made a change or correction to an income tax return filed with that jurisdiction and for which you claimed a credit in your Connecticut return for taxes paid to that jurisdiction; or
- A timely-filed amended federal or other state's income tax return.
Enter the final determination date as listed on the document received from the IRS or by the other jurisdiction.
Step 2: Refer to your original return and identify all the changes that need to be made.
Step 3: Find the corresponding line items on Form CT‑1040X.
Step 4: Complete Schedules 1, 2, 3, and 4. Enter the corrected amounts for each line. If you are not making corrections, enter the amounts reported on your original return.
Step 5: Use Column A to enter the amounts shown on your original or previously-adjusted return.
Step 6: Use Column B to enter the net increase or decrease for each line you are changing.
Step 7: Explain each change in the space provided on Form CT‑1040X, Page 3.
Step 8: Use Column C to report the corrected amounts for each line.
If there is no change, enter the amount from Column A in Column C.
# Form CT‑1040X Instructions
Filing Status
Generally, your filing status must match your federal income tax filing status for the year. However, when one spouse is a Connecticut resident or a nonresident and the other spouse is a part‑year resident, each spouse who is required to file a Connecticut income tax return must file as married filing separately. When one spouse is a Connecticut resident and the other is a nonresident, each spouse who is required to file a Connecticut income tax return must file as married filing separately, unless they file jointly for federal income tax purposes and they elect to be treated as if both were Connecticut residents for the entire taxable year. See Special Rules for Married Individuals at portal.ct.gov/DRS/Individuals/Individual-Income-Tax.
Line 2 and Line 4: Enter the amount from Schedule 1, Line 38, on Line 2, Column C, and the amount from Schedule 1, Line 50, on Line 4, Column C.
Lines 6 through 9: Nonresidents and Part‑Year Residents
Only: Refer to your previously-filed Form CT‑1040NR/PY when completing this section. Attach a copy of your corrected Schedule CT‑SI, Nonresident or Part‑Year Resident Schedule of Income from Connecticut Sources. Part‑Year Residents: Also attach a copy of your corrected Schedule CT‑1040AW, Part‑Year Resident
Income Allocation.
Line 8: Calculate the tax on the amount you entered on Line 7, Column C, using the 2025 Tax Calculation Schedule on Instructions Page 3.
Enter the result on Line 8, Column C.
Line 10: Residents: Calculate the tax on the amount you entered on Line 5, Column C, using the 2025 Tax Calculation Schedule on Instructions Page 3. Enter the result in Column C.
Nonresidents and Part-Year Residents: Multiply Line 9, Column C, by Line 8, Column C. Enter the result in Column C.
Line 11: Residents and Part-Year Residents: Enter the amount from Schedule 2, Line 59, in Column C. See the return instructions to Form CT‑1040 or Form CT‑1040NR/PY at portal.ct.gov/DRS/
Individuals/Individual-Income-Tax.
Line 13: If changes are being made to your Connecticut Alternative Minimum Tax, you must complete a corrected Form CT‑6251, Connecticut Alternative Minimum Tax Return - Individuals. Write the word "Amended" across the top and attach it to Form CT‑1040X.
Line 15: Residents: Enter the amount from Schedule 3, Line 68, in Column C. You must attach Schedule 3 to your return or your credit will be disallowed.
Nonresidents and Part-Year Residents: Enter "0" in Column C.
Line 17: If changes are being made to your allowable credits, you must complete a corrected Schedule CT‑IT Credit, Income Tax Credit Summary. Write the word "Amended" across the top and attach it to Form CT‑1040X. You must also attach a corrected Form CT‑8801, Credit for Prior Year Connecticut Minimum Tax for Individuals, Trusts, and Estates if the prior year alternative minimum tax credit is being changed. If you are filing a corrected Form CT‑8801, write the word "Amended" across the top and attach it to Form CT‑1040X.
Line 19: Enter the amount from Schedule 4, Line 69, in Column C.
Line 21: If changes are being made to your Connecticut income tax withholding, complete the Withholding Schedule on Form CT‑1040X, Page 5, and enter the total from Line 70 in Column C.
You must complete all columns or your withholding will be disallowed. Do not send Forms W‑2 or 1099, or Schedules CT K‑1. If you have more than five federal Forms W‑2 or 1099, or Schedules CT K‑1, you must complete Supplemental Schedule CT‑1040WH and attach it to the back of your amended Connecticut income tax return. Enter the total from Supplemental Schedule CT‑1040WH, Line 3, on Line 70f, Column C.
Line 22a: Connecticut Earned Income Tax Credit: Complete Schedule CT‑EITC, Connecticut Earned Income Tax Credit, to calculate your earned income tax credit. Enter the amount from Schedule CT‑EITC, Line 16. You must attach a copy of your schedule or the credit will be disallowed.
Only full‑year residents can claim the Connecticut earned income tax credit (CT EITC). Part-year residents and nonresidents do not qualify for the credit.
Line 22b: Claim of Right Credit: Complete Form CT‑1040 CRC, Claim of Right Credit, to calculate the amount of your Connecticut Claim of Right Credit if you have a claim of right credit for federal tax purposes.
Enter the amount from Form CT‑1040 CRC, Line 6. You must check off the box for filing Form CT‑1040 CRC on CT‑1040X (Page 1) and attach a copy of Form CT‑1040 CRC to the back of Form CT‑1040X.
Line 22c: Pass‑Through Entity Tax Credit: Complete Schedule CT‑PE, Pass‑Through Entity Tax Credit for Individuals, to calculate the amount of your Connecticut Pass‑Through Entity Tax Credit if you have a Schedule
CT K‑1, Member's Share of Certain Connecticut Items, or Schedule CT‑1041 K‑1, Beneficiary's Share of Certain Connecticut Items. Enter the amount from Schedule CT‑PE, Line 1. You must attach a copy of Schedule CT‑PE to the back of Form CT‑1040X.
Line 22d: Historic Home Rehabilitation Credit: Subtract the amount received from your Historic Home Rehabilitation tax credit voucher and attach a copy of the voucher you receive from the Department of Economic and Community Development with your Connecticut income tax return.
Interest
Interest at 1% per month or fraction of a month will continue to accrue from the original due date until the tax is paid in full. A month is measured from the sixteenth day of the first month to the fifteenth day of the next month. Any fraction of a month is considered a whole month.
# Schedules 1 Through 4
If you are making corrections to any of these schedules (Modifications to Federal Adjusted Gross Income, Credit for Income Taxes Paid to Qualifying Jurisdictions, Property Tax Credit, and Individual Use Tax), refer to the Form CT‑1040 or Form CT‑1040NR/PY return instructions at portal.ct.gov/DRS/Individuals/Individual-Income-Tax.
Enter the corrected amounts for each line. If you are not making corrections, enter the amounts reported on your original return. Enter all amounts as positive numbers.
# 2025 Tax Calculation Schedule
Tax Calculation Schedule on the myconneCT homepage, select View Tax Calculators, then select Income Tax Calculator.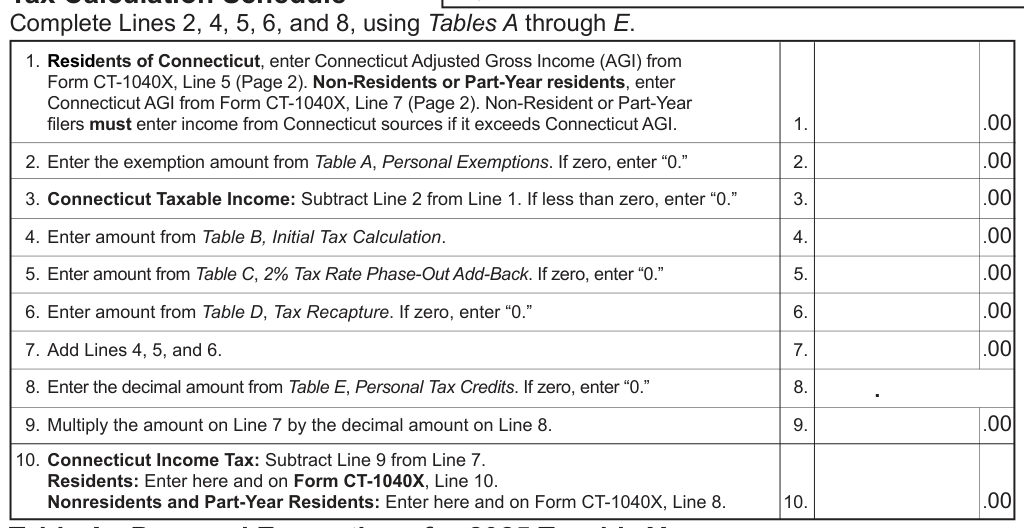
Text version of this table
1. Residents of Connecticut, enter Connecticut Adjusted Gross Income (AGI) from Form CT‑1040X, Line 5 (Page 2). Non‑Residents or Part‑Year residents, enter Connecticut AGI from Form CT‑1040X, Line 7 (Page 2). Non‑Resident or Part‑Year fliers must enter income from Connecticut sources if it exceeds Connecticut AGI. 1. .00 2. Enter the exemption amount from Table A, Personal Exemptions. If zero, enter “0.” 2. .00 3. Connecticut Taxable Income: Subtract Line 2 from Line 1. If less than zero, enter “0.” 3. .00 4. Enter amount from Table B, Initial Tax Calculation. 4. .00 6. Enter amount from Table D, Tax Recapture. If zero, enter "0." 5. .00 6. Enter amount from Table D, Tax Recapture. If zero, enter "0." 6. .00 7. Add Lines 4, 5, and 6. 7. .00 6. Enter amount from Table D, Tax Recapture. If zero, enter "0." 8. . 9. Multiply the amount on Line 7 by the decimal amount on Line 8. 9. .00 10. Connecticut Income Tax: Subtract Line 9 from Line 7. Residents: Enter here and on Form CT‑1040X, Line 10. Nonresidents and Part‑Year Residents: Enter here and on Form CT‑1040X, Line 8. 10. .00
# Table A - Personal Exemptions for 2025 Taxable Year
Enter the exemption amount on the Tax Calculation Schedule, Line 2 and continue to Line 3.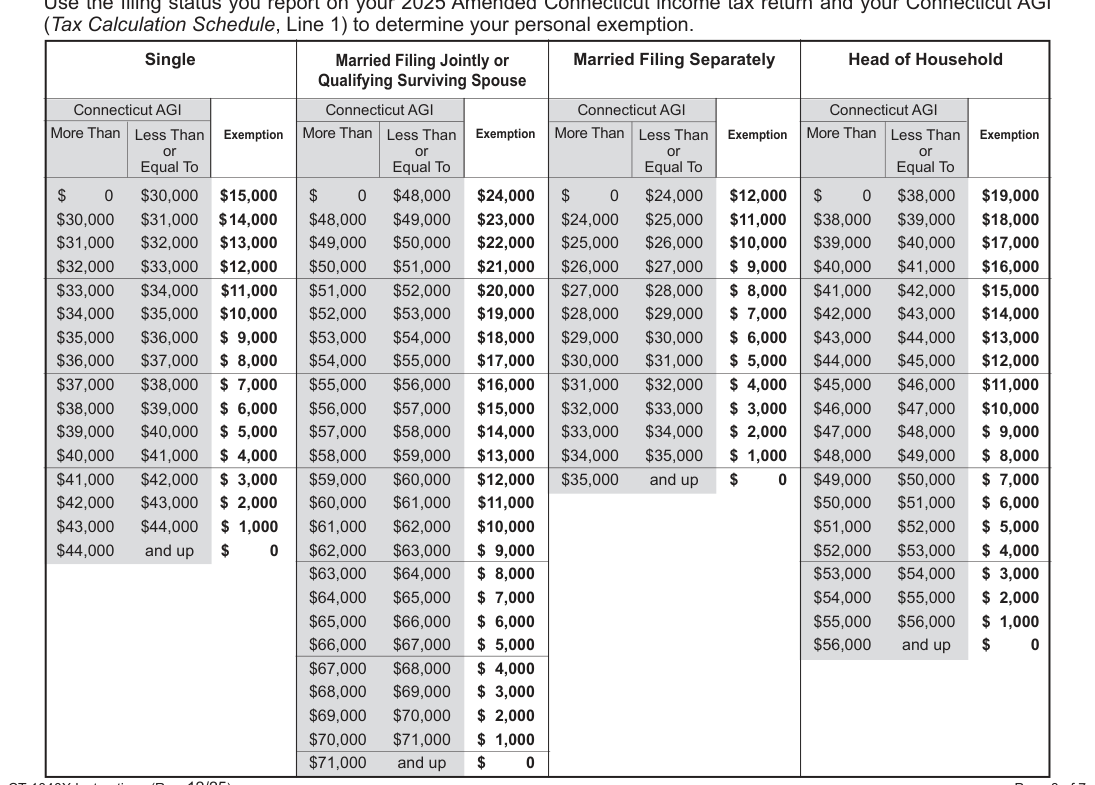
Text version of this table
Single Married Filing Jointly or Qualifying Surviving Spouse Married Filing Separately Head of Household Connecticut AGI Exemption Connecticut AGI Exemption Connecticut AGI Exemption Connecticut AGI Exemption More Than Less Than or Equal To More Than Less Than or Equal To More Than Less Than or Equal To More Than Less Than or Equal To $ 0 $30,000 $30,000 $31,000 $31,000 $32,000 $32,000 $33,000 $15,000 $14,000 $13,000 $12,000 $ 0 $48,000 $48,000 $49,000 $49,000 $50,000 $50,000 $51,000 $24,000 $23,000 $22,000 $21,000 $ 0 $24,000 $24,000 $25,000 $25,000 $26,000 $26,000 $27,000 $12,000 $11,000 $10,000 $ 9,000 $ 0 $38,000 $38,000 $39,000 $39,000 $40,000 $40,000 $41,000 $19,000 $18,000 $17,000 $16,000 $33,000 $34,000 $34,000 $35,000 $35,000 $36,000 $36,000 $37,000 $11,000 $10,000 $ 9,000 $ 8,000 $51,000 $52,000 $52,000 $53,000 $53,000 $54,000 $54,000 $55,000 $20,000 $19,000 $18,000 $17,000 $27,000 $28,000 $28,000 $29,000 $29,000 $30,000 $30,000 $31,000 $ 8,000 $ 7,000 $ 6,000 $ 5,000 $41,000 $42,000 $42,000 $43,000 $43,000 $44,000 $44,000 $45,000 $15,000 $14,000 $13,000 $12,000 $37,000 $38,000 $38,000 $39,000 $39,000 $40,000 $40,000 $41,000 $ 7,000 $ 6,000 $ 5,000 $ 4,000 $55,000 $56,000 $56,000 $57,000 $57,000 $58,000 $58,000 $59,000 $16,000 $15,000 $14,000 $13,000 $31,000 $32,000 $32,000 $33,000 $33,000 $34,000 $34,000 $35,000 $ 4,000 $ 3,000 $ 2,000 $ 1,000 $45,000 $46,000 $46,000 $47,000 $47,000 $48,000 $48,000 $49,000 $11,000 $10,000 $ 9,000 $ 8,000 $41,000 $42,000 $42,000 $43,000 $43,000 $44,000 $44,000 and up $59,000 $60,000 $60,000 $61,000 $61,000 $62,000 $62,000 $63,000 $12,000 $11,000 $10,000 $ 9,000 $35,000 and up $49,000 $50,000 $50,000 $51,000 $51,000 $52,000 $52,000 $53,000 $ 7,000 $ 6,000 $ 5,000 $ 4,000 $63,000 $64,000 $64,000 $65,000 $65,000 $66,000 $66,000 $67,000 $ 8,000 $ 7,000 $ 6,000 $ 5,000 $53,000 $54,000 $54,000 $55,000 $55,000 $56,000 $56,000 and up $67,000 $68,000 $68,000 $69,000 $69,000 $70,000 $70,000 $71,000 $ 4,000 $ 3,000 $ 2,000 $ 1,000 $71,000 and up $ 0
# Qualifying Surviving Spouse
# for 2025 Taxable Year
Enter the initial tax calculation amount on the
Tax Calculation Schedule, Line 4 and continue to Line 5.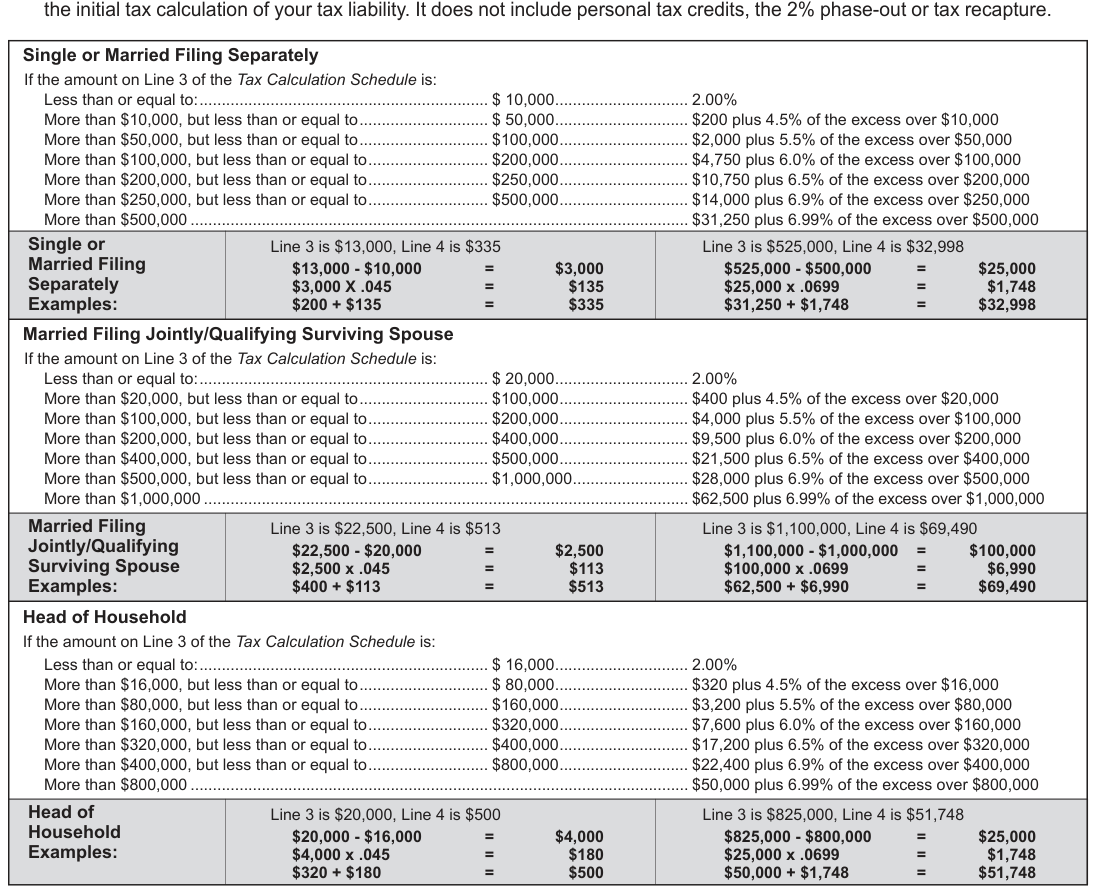
Text version of this table
Single or Married Filing Separately If the amount on Line 3 of the Tax Calculation Schedule is: Less than or equal to:................................................................. $ 10,000.............................. 2.00% More than $10,000, but less than or equal to............................. $ 50,000.............................. $200 plus 4.5% of the excess over $10,000 More than $50,000, but less than or equal to............................. $100,000............................. $2,000 plus 5.5% of the excess over $50,000 More than $100,000, but less than or equal to........................... $200,000............................. $4,750 plus 6.0% of the excess over $100,000 More than $200,000, but less than or equal to........................... $250,000............................. $10,750 plus 6.5% of the excess over $200,000 More than $250,000, but less than or equal to........................... $500,000............................. $14,000 plus 6.9% of the excess over $250,000 More than $500,000................................................................................................................. $31,250 plus 6.99% of the excess over $500,000 Single or Married Filing Separately Examples: Line 3 is $13,000, Line 4 is $335 $13,000 - $10,000 = $3,000 $3,000 X .045 = $135 $200 + $135 = $335 Line 3 is $525,000, Line 4 is $32,998 $525,000 - $500,000 = $25,000 $25,000 x .0699 = $1,748 $31,250 + $1,748 = $32,998 Married Filing Jointly/Qualifying Surviving Spouse If the amount on Line 3 of the Tax Calculation Schedule is: Less than or equal to:................................................................. $ 20,000.............................. 2.00% More than $20,000, but less than or equal to............................. $100,000............................. $400 plus 4.5% of the excess over $20,000 More than $100,000, but less than or equal to........................... $200,000............................. $4,000 plus 5.5% of the excess over $100,000 More than $200,000, but less than or equal to........................... $400,000............................. $9,500 plus 6.0% of the excess over $200,000 More than $400,000, but less than or equal to........................... $500,000............................. $21,500 plus 6.5% of the excess over $400,000 More than $500,000, but less than or equal to........................... $1,000,000.......................... $28,000 plus 6.9% of the excess over $500,000 More than $1,000,000.............................................................................................................. $62,500 plus 6.99% of the excess over $1,000,000 Married Filing Jointly/Qualifying Surviving Spouse Examples: Line 3 is $22,500, Line 4 is $513 $22,500 - $20,000 = $2,500 $2,500 x .045 = $113 $400 + $113 = $513 Line 3 is $1,100,000, Line 4 is $69,490 $1,100,000 - $1,000,000 = $100,000 $100,000 x .0699 = $6,990 $62,500 + $6,990 = $69,490 Head of Household If the amount on Line 3 of the Tax Calculation Schedule is: Less than or equal to:................................................................. $ 16,000.............................. 2.00% More than $16,000, but less than or equal to............................. $ 80,000.............................. $320 plus 4.5% of the excess over $16,000 More than $80,000, but less than or equal to............................. $160,000............................. $3,200 plus 5.5% of the excess over $80,000 More than $160,000, but less than or equal to........................... $320,000............................. $7,600 plus 6.0% of the excess over $160,000 More than $320,000, but less than or equal to........................... $400,000............................. $17,200 plus 6.5% of the excess over $320,000 More than $400,000, but less than or equal to........................... $800,000............................. $22,400 plus 6.9% of the excess over $400,000 More than $800,000................................................................................................................. $50,000 plus 6.99% of the excess over $800,000 Head of Household Examples: Line 3 is $20,000, Line 4 is $500 $20,000 - $16,000 = $4,000 $4,000 x .045 = $180 $320 + $180 = $500 Line 3 is $825,000, Line 4 is $51,748 $825,000 - $800,000 = $25,000 $25,000 x .0699 = $1,748 $50,000 + $1,748 = $51,748
# Head of Household
# Table C - 2% Tax Rate Phase-Out Add-Back
# Qualifying Surviving Spouse
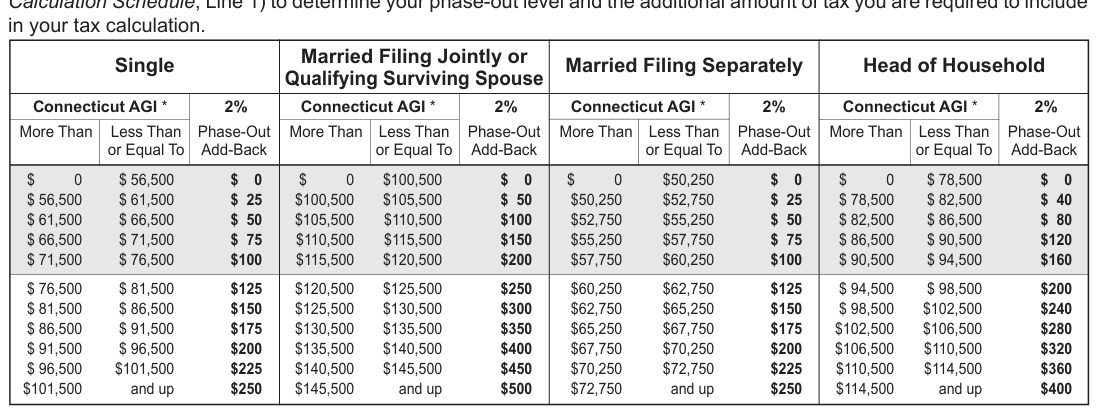
Text version of this table
| Single | Married Filing Jointly or Qualifying Surviving Spouse | Married Filing Separately | Head of Household | ||||||||
| Connecticut AGI * | 2% Phase-Out Add-Back | Connecticut AGI * | 2% Phase-Out Add-Back | Connecticut AGI * | 2% Phase-Out Add-Back | Connecticut AGI * | 2% Phase-Out Add-Back | ||||
| More Than | Less Than or Equal To | More Than | Less Than or Equal To | More Than | Less Than or Equal To | More Than | Less Than or Equal To | ||||
| $ 0 $ 56,500 $ 0 $ 56,500 $ 61,500 $ 25 $ 61,500 $ 66,500 $ 50 $ 66,500 $ 71,500 $ 75 $ 71,500 $ 76,500 $100 | $ 0 $100,500 $ 0 $100,500 $105,500 $ 50 $105,500 $110,500 $100 $110,500 $115,500 $150 $115,500 $120,500 $200 | $ 0 $50,250 $ 0 $50,250 $52,750 $ 25 $52,750 $55,250 $ 50 $55,250 $57,750 $ 75 $57,750 $60,250 $100 | $ 0 $ 78,500 $ 0 $ 78,500 $ 82,500 $ 40 $ 82,500 $ 86,500 $ 80 $ 86,500 $ 90,500 $120 $ 90,500 $ 94,500 $160 | ||||||||
| $ 76,500 $ 81,500 $125 $ 81,500 $ 86,500 $150 $ 86,500 $ 91,500 $175 $ 91,500 $ 96,500 $200 $ 96,500 $101,500 $225 $101,500 and up $250 | $120,500 $125,500 $250 $125,500 $130,500 $300 $130,500 $135,500 $350 $135,500 $140,500 $400 $140,500 $145,500 $450 $145,500 and up $500 | $60,250 $62,750 $125 $62,750 $65,250 $150 $65,250 $67,750 $175 $67,750 $70,250 $200 $70,250 $72,750 $225 $72,750 and up $250 | $ 94,500 $ 98,500 $200 $ 98,500 $102,500 $240 $102,500 $106,500 $280 $106,500 $110,500 $320 $110,500 $114,500 $360 $114,500 and up $400 |
# Table D - Tax Recapture
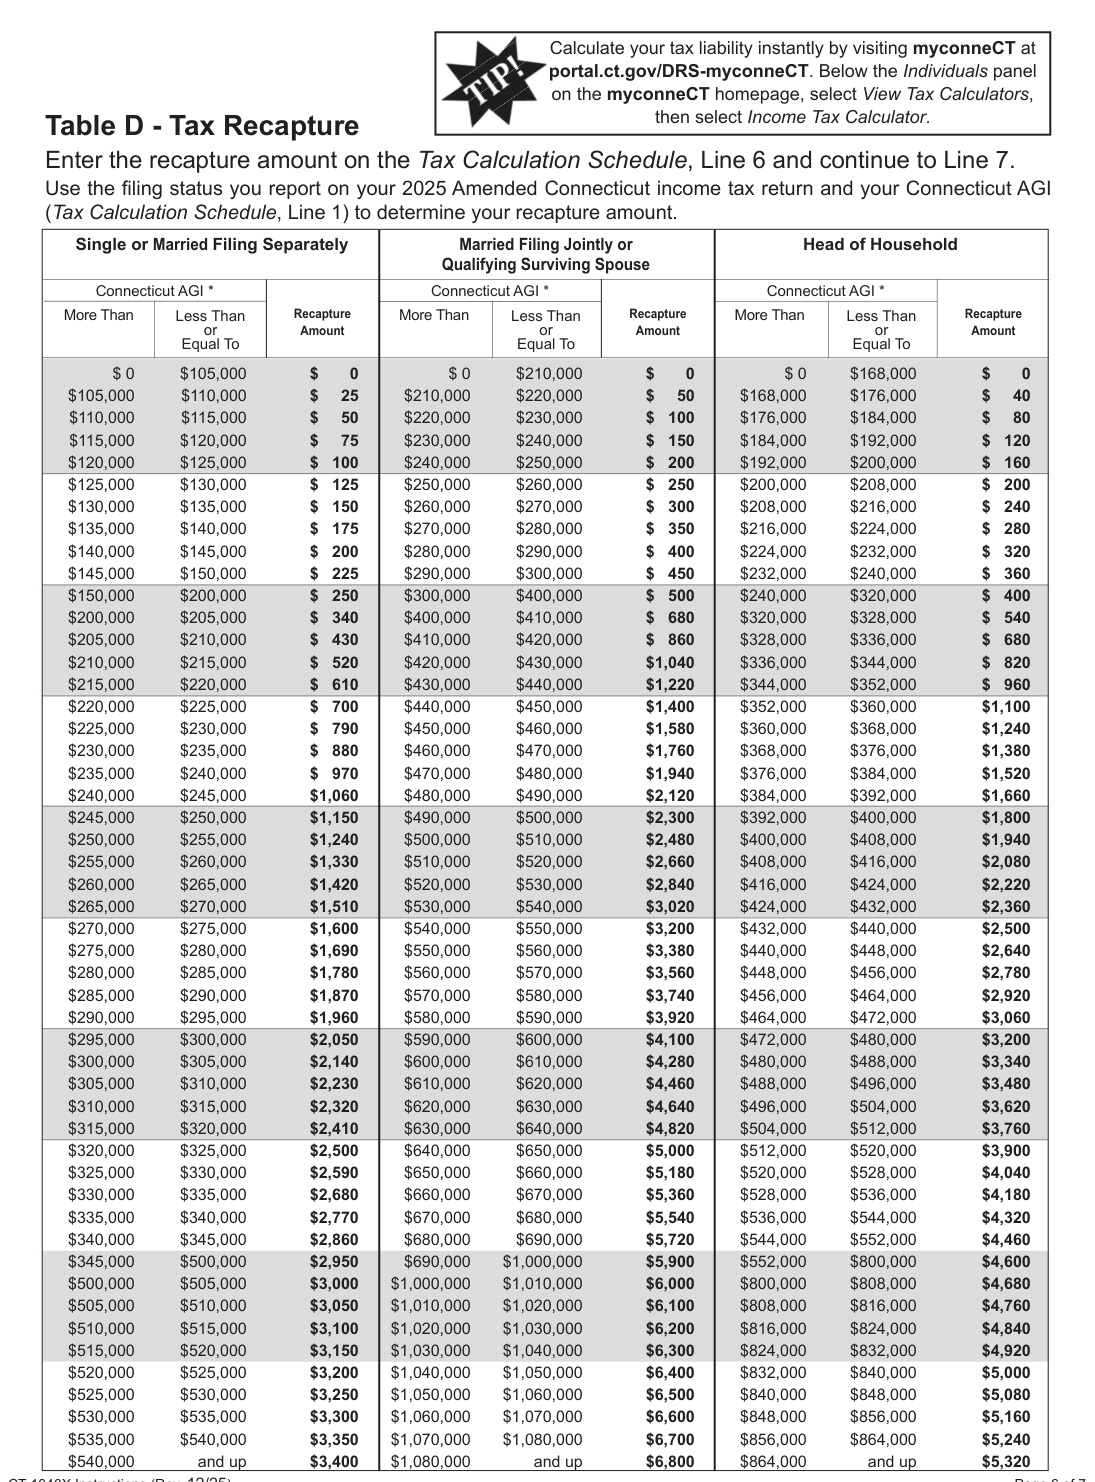
Text version of this table
| Calc | ulate your tax lia | bility instantly by | visiting my | conn | eCT at | |||||
| port | al.ct.gov/DRS-m | yconneCT. Belo | w the Indiv | idual | s panel | |||||
| on th | e myconneCT | homepage, selec | t View Tax | Calcu | lators, | |||||
| then se | lect Income Tax | Calculator. | ||||||||
| Ta | ble D - T | ax Re | cap | ture | ||||||
| En | ter the rec | Recapture | amo | unt on the Tax | Calculation | Schedule, L | ine 6 and co | ntinue to | Lin | e 7. |
| Us | e the filing s | tatus you | repo | rt on your 2025 A | mended Conn | ecticut incom | e tax return and | your Con | nect | icut A |
| (Ta | x Calculatio | n Schedu | le, Lin | e 1) to determine | Recapture | e amount. | ||||
| Single or Mar | ried Filing | Separ | ately | Married Filing Joi | ntly or | Head | of Househo | ld | ||
| Qu | alifying Surviving | Spouse | ||||||||
| Connecticut AGI * | AGI * | Con | necticut AGI * | Connecticut | AGI * | |||||
| More Than L | ess Than | Re | capture More Tha | n Less Than | Recapture | More Than | Less Than | Re | capture | |
| or | A | mount | or | Amount | or | A | mount | |||
| Equal To | Equal To | Equal To | ||||||||
| $ 0 | $105,000 | $ 0 $ | 0 $210,000 | $ 0 | $ 0 | $168,000 | $ 0 | |||
| $105,000 | $110,000 | $ 25 $210,00 | 0 $220,000 | $ 50 | $168,000 | $176,000 | $ 40 | |||
| $110,000 | $115,000 | $ 50 $220,00 | 0 $230,000 | $ 100 | $176,000 | $184,000 | $ 80 | |||
| $115,000 | $120,000 | $ 75 $230,00 | 0 $240,000 | $ 150 | $184,000 | $192,000 | $ 120 | |||
| $120,000 | $125,000 | $ 100 $240,00 | 0 $250,000 | $ 200 | $192,000 | $200,000 | $ 160 | |||
| $125,000 | $130,000 | $ 125 $250,00 | 0 $260,000 | $ 250 | $200,000 | $208,000 | $ 200 | |||
| $130,000 | $135,000 | $ 150 $260,00 | 0 $270,000 | $ 300 | $208,000 | $216,000 | $ 240 | |||
| $135,000 | $140,000 | $ 175 $270,00 | 0 $280,000 | $ 350 | $216,000 | $224,000 | $ 280 | |||
| $140,000 | $145,000 | $ 200 $280,00 | 0 $290,000 | $ 400 | $224,000 | $232,000 | $ 320 | |||
| $145,000 | $150,000 | $ 225 $290,00 | 0 $300,000 | $ 450 | $232,000 | $240,000 | $ 360 | |||
| $150,000 | $200,000 | $ 250 $300,00 | 0 $400,000 | $ 500 | $240,000 | $320,000 | $ 400 | |||
| $200,000 | $205,000 | $ 340 $400,00 | 0 $410,000 | $ 680 | $320,000 | $328,000 | $ 540 | |||
| $205,000 | $210,000 | $ 430 $410,00 | 0 $420,000 | $ 860 | $328,000 | $336,000 | $ 680 | |||
| $210,000 | $215,000 | $ 520 $420,00 | 0 $430,000 | $1,040 | $336,000 | $344,000 | $ 820 | |||
| $215,000 | $220,000 | $ 610 $430,00 | 0 $440,000 | $1,220 | $344,000 | $352,000 | $ 960 | |||
| $220,000 | $225,000 | $ 700 $440,00 | 0 $450,000 | $1,400 | $352,000 | $360,000 | $1,100 | |||
| $225,000 | $230,000 | $ 790 $450,00 | 0 $460,000 | $1,580 | $360,000 | $368,000 | $1,240 | |||
| $230,000 | $235,000 | $ 880 $460,00 | 0 $470,000 | $1,760 | $368,000 | $376,000 | $1,380 | |||
| $235,000 | $240,000 | $ 970 $470,00 | 0 $480,000 | $1,940 | $376,000 | $384,000 | $1,520 | |||
| $240,000 | $245,000 | $1,060 $480,00 | 0 $490,000 | $2,120 | $384,000 | $392,000 | $1,660 | |||
| $245,000 | $250,000 | $1,150 $490,00 | 0 $500,000 | $2,300 | $392,000 | $400,000 | $1,800 | |||
| $250,000 | $255,000 | $1,240 $500,00 | 0 $510,000 | $2,480 | $400,000 | $408,000 | $1,940 | |||
| $255,000 | $260,000 | $1,330 $510,00 | 0 $520,000 | $2,660 | $408,000 | $416,000 | $2,080 | |||
| $260,000 | $265,000 | $1,420 $520,00 | 0 $530,000 | $2,840 | $416,000 | $424,000 | $2,220 | |||
| $265,000 | $270,000 | $1,510 $530,00 | 0 $540,000 | $3,020 | $424,000 | $432,000 | $2,360 | |||
| $270,000 | $275,000 | $1,600 $540,00 | 0 $550,000 | $3,200 | $432,000 | $440,000 | $2,500 | |||
| $275,000 | $280,000 | $1,690 $550,00 | 0 $560,000 | $3,380 | $440,000 | $448,000 | $2,640 | |||
| $280,000 | $285,000 | $1,780 $560,00 | 0 $570,000 | $3,560 | $448,000 | $456,000 | $2,780 | |||
| $285,000 | $290,000 | $1,870 $570,00 | 0 $580,000 | $3,740 | $456,000 | $464,000 | $2,920 | |||
| $290,000 | $295,000 | $1,960 $580,00 | 0 $590,000 | $3,920 | $464,000 | $472,000 | $3,060 | |||
| $295,000 | $300,000 | $2,050 $590,00 | 0 $600,000 | $4,100 | $472,000 | $480,000 | $3,200 | |||
| $300,000 | $305,000 | $2,140 $600,00 | 0 $610,000 | $4,280 | $480,000 | $488,000 | $3,340 | |||
| $305,000 | $310,000 | $2,230 $610,00 | 0 $620,000 | $4,460 | $488,000 | $496,000 | $3,480 | |||
| $310,000 | $315,000 | $2,320 $620,00 | 0 $630,000 | $4,640 | $496,000 | $504,000 | $3,620 | |||
| $315,000 | $320,000 | $2,410 $630,00 | 0 $640,000 | $4,820 | $504,000 | $512,000 | $3,760 | |||
| $320,000 | $325,000 | $2,500 $640,00 | 0 $650,000 | $5,000 | $512,000 | $520,000 | $3,900 | |||
| $325,000 | $330,000 | $2,590 $650,00 | 0 $660,000 | $5,180 | $520,000 | $528,000 | $4,040 | |||
| $330,000 | $335,000 | $2,680 $660,00 | 0 $670,000 | $5,360 | $528,000 | $536,000 | $4,180 | |||
| $335,000 | $340,000 | $2,770 $670,00 | 0 $680,000 | $5,540 | $536,000 | $544,000 | $4,320 | |||
| $340,000 | $345,000 | $2,860 $680,00 | 0 $690,000 | $5,720 | $544,000 | $552,000 | $4,460 | |||
| $345,000 | $500,000 | $2,950 $690,00 | 0 $1,000,000 | $5,900 | $552,000 | $800,000 | $4,600 | |||
| $500,000 | $505,000 | $3,000 $1,000,00 | 0 $1,010,000 | $6,000 | $800,000 | $808,000 | $4,680 | |||
| $505,000 | $510,000 | $3,050 $1,010,00 | 0 $1,020,000 | $6,100 | $808,000 | $816,000 | $4,760 | |||
| $510,000 | $515,000 | $3,100 $1,020,00 | 0 $1,030,000 | $6,200 | $816,000 | $824,000 | $4,840 | |||
| $515,000 | $520,000 | $3,150 $1,030,00 | 0 $1,040,000 | $6,300 | $824,000 | $832,000 | $4,920 | |||
| $520,000 | $525,000 | $3,200 $1,040,00 | 0 $1,050,000 | $6,400 | $832,000 | $840,000 | $5,000 | |||
| $525,000 | $530,000 | $3,250 $1,050,00 | 0 $1,060,000 | $6,500 | $840,000 | $848,000 | $5,080 | |||
| $530,000 | $535,000 | $3,300 $1,060,00 | 0 $1,070,000 | $6,600 | $848,000 | $856,000 | $5,160 | |||
| $535,000 | $540,000 | $3,350 $1,070,00 | 0 $1,080,000 | $6,700 | $856,000 | $864,000 | $5,240 | |||
| $540,000 | and up | $3,400 $1,080,00 | 0 and up | $6,800 | $864,000 | and up | $5,320 |
# Qualifying Surviving Spouse
# Head of Household
Table E - Personal Tax Credits for
2025 Taxable Year on the myconneCT homepage, select View Tax Calculators, then select Income Tax Calculator.
Enter the decimal amount on the Tax Calculation Schedule, Line 8 and continue to Line 9.
Use the filing status you report on your 2025 Amended Connecticut income tax return and your Connecticut AGI (Tax Calculation Schedule, Line 1) to determine your personal credit decimal amount.
# Qualifying Surviving Spouse
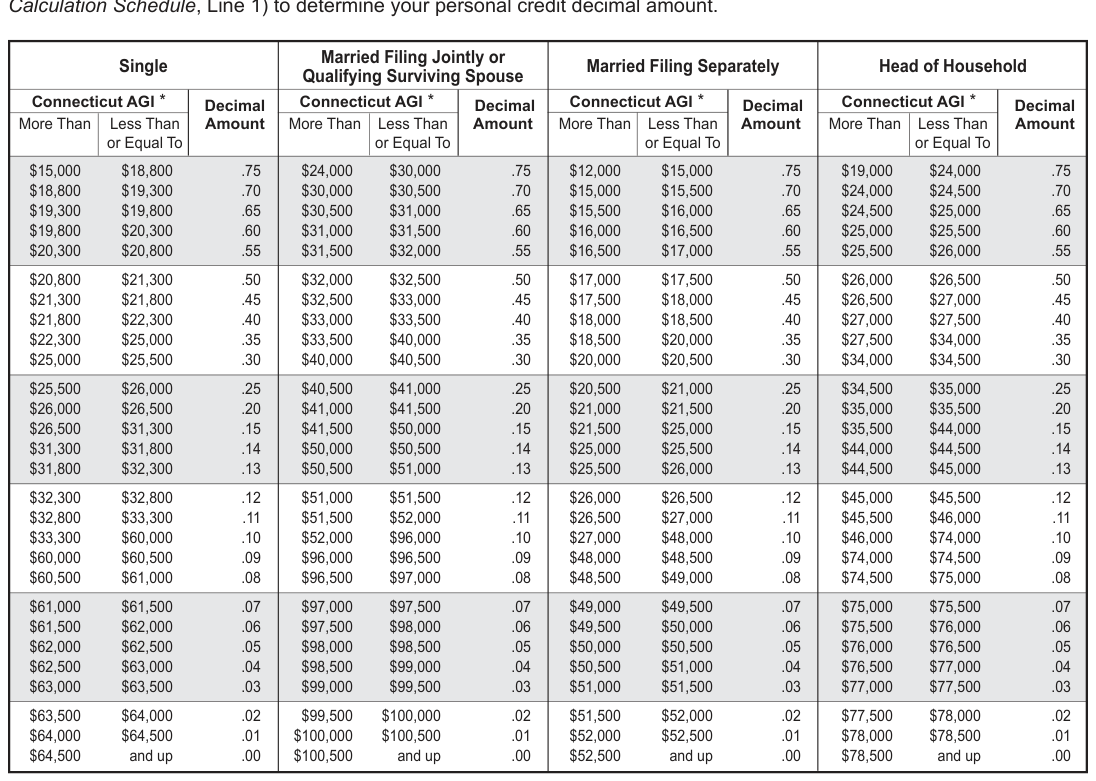
Text version of this table
Single Married Filing Jointly or Qualifying Surviving Spouse Married Filing Separately Head of Household Connecticut AGI * Decimal Amount Connecticut AGI * Decimal Amount Connecticut AGI * Decimal Amount Connecticut AGI * Decimal Amount More Than Less Than or Equal To More Than Less Than or Equal To More Than Less Than or Equal To More Than Less Than or Equal To $15,000 $18,800 .75 $18,800 $19,300 .70 $19,300 $19,800 .65 $19,800 $20,300 .60 $20,300 $20,800 .55 $24,000 $30,000 .75 $30,000 $30,500 .70 $30,500 $31,000 .65 $31,000 $31,500 .60 $31,500 $32,000 .55 $12,000 $15,000 .75 $15,000 $15,500 .70 $15,500 $16,000 .65 $16,000 $16,500 .60 $16,500 $17,000 .55 $19,000 $24,000 .75 $24,000 $24,500 .70 $24,500 $25,000 .65 $25,000 $25,500 .60 $25,500 $26,000 .55 $20,800 $21,300 .50 $21,300 $21,800 .45 $21,800 $22,300 .40 $22,300 $25,000 .35 $25,000 $25,500 .30 $32,000 $32,500 .50 $32,500 $33,000 .45 $33,000 $33,500 .40 $33,500 $40,000 .35 $40,000 $40,500 .30 $17,000 $17,500 .50 $17,500 $18,000 .45 $18,000 $18,500 .40 $18,500 $20,000 .35 $20,000 $20,500 .30 $26,000 $26,500 .50 $26,500 $27,000 .45 $27,000 $27,500 .40 $27,500 $34,000 .35 $34,000 $34,500 .30 $25,500 $26,000 .25 $26,000 $26,500 .20 $26,500 $31,300 .15 $31,300 $31,800 .14 $31,800 $32,300 .13 $40,500 $41,000 .25 $41,000 $41,500 .20 $41,500 $50,000 .15 $50,000 $50,500 .14 $50,500 $51,000 .13 $20,500 $21,000 .25 $21,000 $21,500 .20 $21,500 $25,000 .15 $25,000 $25,500 .14 $25,500 $26,000 .13 $34,500 $35,000 .25 $35,000 $35,500 .20 $35,500 $44,000 .15 $44,000 $44,500 .14 $44,500 $45,000 .13 $32,300 $32,800 .12 $32,800 $33,300 .11 $33,300 $60,000 .10 $60,000 $60,500 .09 $60,500 $61,000 .08 $51,000 $51,500 .12 $51,500 $52,000 .11 $52,000 $96,000 .10 $96,000 $96,500 .09 $96,500 $97,000 .08 $26,000 $26,500 .12 $26,500 $27,000 .11 $27,000 $48,000 .10 $48,000 $48,500 .09 $48,500 $49,000 .08 $45,000 $45,500 .12 $45,500 $46,000 .11 $46,000 $74,000 .10 $74,000 $74,500 .09 $74,500 $75,000 .08 $61,000 $61,500 .07 $61,500 $62,000 .06 $62,000 $62,500 .05 $62,500 $63,000 .04 $63,000 $63,500 .03 $97,000 $97,500 .07 $97,500 $98,000 .06 $98,000 $98,500 .05 $98,500 $99,000 .04 $99,000 $99,500 .03 $49,000 $49,500 .07 $49,500 $50,000 .06 $50,000 $50,500 .05 $50,500 $51,000 .04 $51,000 $51,500 .03 $75,000 $75,500 .07 $75,500 $76,000 .06 $76,000 $76,500 .05 $76,500 $77,000 .04 $77,000 $77,500 .03 $63,500 $64,000 .02 $64,000 $64,500 .01 $64,500 and up .00 $99,500 $100,000 .02 $100,000 $100,500 .01 $100,500 and up .00 $51,500 $52,000 .02 $52,000 $52,500 .01 $52,500 and up .00 $77,500 $78,000 .02 $78,000 $78,500 .01 $78,500 and up .00
* Form CT-1040NR/PY filers must use income from Connecticut sources if it exceeds Connecticut adjusted gross income.
Source: view the official PDF
Nearby sections (17 sections)
- ct-1040 · Instructions for Form CT-1040 — Connecticut Resident Income…
- ct-1040-ext · Form CT-1040 EXT — Application for Extension of Time to…
- ct-1040-nrpy · Instructions for Form CT-1040NR/PY — Nonresident &…
- ct-1040es · Form CT-1040ES — Estimated Connecticut Income Tax Payment…
- ct-1040x · Form CT-1040X — Amended Connecticut Income Tax Return for…
- ct-1041 · Instructions for Form CT-1041 — Connecticut Income Tax Return…
- ct-1041-ext · Form CT-1041 EXT — Application for Extension of Time to…
- ct-1041es · Form CT-1041ES — Estimated Connecticut Income Tax Payment…
- ct-1065-ct-1120si · Instructions for Form CT-1065/CT-1120SI —…
- ct-1065-ct-1120si-ext · Form CT-1065/CT-1120SI EXT — Application for…
- ct-1120 · Instructions for Form CT-1120 — Corporation Business Tax…
- ct-1120-att · Form CT-1120 ATT — Corporation Business Tax Attachment…
- ct-1120-ext · Form CT-1120 EXT — Application for Extension of Time to…
- ct-1120a · Form CT-1120A — Apportionment Computation
- ct-1120cu · Instructions for Form CT-1120CU — Combined Unitary…
- ct-1120es · Form CT-1120ES — Estimated Corporation Business Tax Payment…
- ct-1120i · Form CT-1120I — Computation of Interest Due on Underpayment