Alabama Department of Revenue Forms & Instructions
Form 40NR — Nonresident Individual Income Tax Return Instructions (TY2025)
# Form
40NR
# Booklet
Nonresidents Only Forms and Instructions myalabamataxes.alabama.gov Index G A Gains … 12 and 20 General Information … 14 Address Change … 14 Gifts to Charity … 17 and 18
Addresses of Taxpayer Service
H
Centers … 3
# Alimony or Separate Maintenance
Head of Family … 6
Amount paid … 13
Amount received … 11 I
Amended Return … 14
Income (Examples) -
Amount You Owe … 10
You Must Report … 7
Annuities … 11 and 12
You Do Not Report … 7 and 8
Armed Forces, Members of … 4
Income Tax Withheld (Alabama) … 8
B
Credit Card … 10
ACH Debit (E-Check) … 10
Penalty -
Criminal Liability … 14
Late Filing … 14
Late Payment of Tax … 14
Other Penalties … 14
Pensions … 11 and 12
Personal Exemption … 6
Preparer, Tax Return … 11
Q
Income Tax Deduction (Federal) … 9, 13, 14 and 27 Interest Income … 11 and 19 Business income or (Loss) Interest - Late Payment of Tax … 14 (Federal Schedule C) … 12
Interest - Penalty on Early
Business Use of Home … 19
Withdrawal of Savings … 13
C Individual Retirement Arrangement (IRA) … 13 Itemized Deductions … 8 and 15-19 Casualty and Theft Losses … 18 K
Corresponding With Alabama
Department of Revenue … 14
Keogh Plan - Deduction For … 13
D
L
Death of Taxpayer … 14 and 15
Losses … 12 and 20
Dependents … 9
Dividend Income … 11 and 19 M
Domicile … 4
Married Persons - Filing Joint or
E
Separate Return … 6
Medical and Dental Expenses … 16
E-Check … 10
Military Personnel -
Educational Expenses … 19
Residents of Alabama … 4
Employee Business Expenses … 19
Nonresidents of Alabama … 4
Estates and Trusts … 12 and 20
Moving Expenses … 13
Estimated Tax … 10 and 15
Miscellaneous Itemized Deductions … 18 Extension of Time to file … 15 Mutual Funds … 19 F N Farm Income or (Loss) … 12 Name and Address … 6 Federal Tax Deduction … 9, 13, 14 and 27 Nonresidents of Alabama -Figuring Your Income Tax … 9, 10 and 21-26 Which Form To File … 5 Filing Requirements -Who Must File … 4 When To File … 5 Where To File … 11 O Which Form To File … 5 Other Income … 8 and 12 Who Must File … 4 Filing Status -P Which Box To Check … 6 Forms, How To Get … 29 Partnerships … 12 and 20 Payments -Check/Money Order … 10 Qualified Long-Term Care … 18 R Records - How Long To Keep … 14 Refund, When Should I Receive? … 15 Rents and Royalties … 12 and 20 Requesting a Copy of Your Tax Return … 14 Rounding Off To Whole Dollars … 8 S S Corporations … 12 and 20 Salaries … 8 Schedules A, B, D, E, no Sch. CR on 40NR … 15-19
# Self-employed Health
Insurance Premiums … 13
Setoff Debt Collection … 15
Sign Your Return … 11
Single Person … 6
Social Security Number … 6
Standard Deduction … 8 and 9
Steps For Preparing Your Return … 5
Students and Dependents … 5
Substitute Forms … 14
T
Tax Assistance for Taxpayers … 3
Tax Tables … 21-26
W
What's New … 2
Where to file Form 40NR … 11
Childcare Facility Tax Credit - Act 2024-303 prodeployed to locations outside the United States or acti-What's New For 2025 vides a tax incentive for Alabama childcare providers vated to support certain emergencies. See "Examples of who own and operate a qualified childcare facility. The in-Income You Do Not Report " on page 7 for more infor-Identity Quiz - If you happen to receive a notice to mation. complete an ID Confirmation Quiz, it is not because you centive is based on the facility's quality rating and average monthly number of eligible children. See Schedule Sound Money Tax Neutrality Act - Act 2024-0447 are suspected of ID theft. The purpose of the quiz is to OC instructions for more information. amends Section 40-18-14 to exclude net capital gains protect your identity as the filer and prevent loss of tax-Employer Tax Credit - Act 2024-303 provides a tax derived from the exchange of precious metal bullion from payer dollars to thieves. incentive to Alabama employers who are not childcare state income taxes. See "Examples of Income You Do
# Vehicle Loan Interest - Section 40-18-15 provides
Not Report " on page 7 for more information. a deduction for vehicle loan interest paid on new qualified providers who support their employees' childcare needs by offering financial assistance for the provision of child-Alabama Workforce Housing Tax Credit - Act vehicles in 2025 through 2028 meeting certain requirecare. See Schedule OC instructions for more information.
2024-302 provides an annual credit of up to $2M per projments. See page 17 for more information on this inter-Employer Provider Credit - Act 2024-303 provides ect for up to 10 years for a qualified workforce housing est deduction. a tax incentive to Alabama childcare providers who incur project. The Alabama Housing Finance Authority (AHFA) Military Income Exemption - Act 2024-0170 eligible expenses for the operation, maintenance, and/or is the administering agency for determining the qualifying amends Section 40-18-3 to expand the current state inupdates of a qualified childcare facility. See Schedule projects. See Schedule OC instructions for more inforcome tax exemption on military pay for certain compenmation. sation of National Guard and Reserve members who are OC instructions for more information.
★
Huntsville
★
Shoals
★
Gadsden
Jefferson/
Tuscaloosa
★
Shelby
★
Auburn/Opelika
★
Montgomery
★
Dothan
Mobile
★
★
# Physical Addresses of Taxpayer Service Centers
Alabama income tax assistance may be obtained by calling or visiting any of the Alabama Department of Revenue Taxpayer Service Centers listed below. Additional forms and instructions may also be obtained from these centers.
Auburn/Opelika Taxpayer Service Center Huntsville Taxpayer Service Center 1800 Samford Trace Court, Suite 100 4920 Corporate Drive, Suite H Auburn, AL 36830 Huntsville, AL 35805 Phone - (334) 887-9549 Phone - (256) 837-2319 Dothan Taxpayer Service Center Jefferson/Shelby Taxpayer Service Center
121 Adris Place 250 Riverchase Parkway East, 4th Floor Dothan, AL 36303 Hoover, AL 35244 Phone - (334) 793-5803 Phone - (205) 733-2740
Gadsden Taxpayer Service Center Mobile Taxpayer Service Center 701 Forrest Avenue 851 E. I-65 Service Road South, Bel Air Tower, Suite 100 Gadsden, AL 35901 Mobile, AL 36606 Phone - (256) 547-0554 Phone - (251) 344-4737
Montgomery Taxpayer Service Center
2545 Taylor Road
Montgomery, AL 36117
Phone - (334) 242-2677
Shoals Taxpayer Service Center
201 South Court Street, Suite 200
Florence, AL 35630
Phone - (256) 383-4631
Tuscaloosa Taxpayer Service Center
1434 22nd Avenue
Tuscaloosa, AL 35401
Phone - (205) 759-2571
Refund Status
To check the status of your current year refund, go to our website at www.revenue.alabama.gov, then click on "Where's My Refund," or call our 24-hour toll-free Refund Hotline at 1-855-894-7391.
# How To Use This Instruction Booklet
The instructions for Form 40NR are divided into five main sections.
SECTION 1 contains information on who must file, how to choose the correct form, and when to file a return.
SECTION 2 contains useful steps to help you prepare your return.
SECTION 3 contains specific instructions for most of the lines on your return.
SECTION 4 contains general information about such items as amending your tax return, how long to keep records, and when you should receive your refund.
SECTION 5 contains instructions for completing most of the schedules that may be attached to Form 40NR.
If you follow the steps in Section 2 and the specific instructions in Section 3, you should be able to fill in your return quickly and accurately.
Domicile. Individuals who are domiciled in (or SECTION residents of) Alabama are subject to tax on their en-1 Information tire income whether earned within or without Alabama. This is true regardless of their physical Filing presence within Alabama at any time during the taxable year. Domicile is where one lives, has a permanent home, and has the intention of returning when absent. Domicile may be by birth, choice, or operation of law. Each person has one and only one First, be certain you need to file a tax return. Your domicile which, once established, continues until a marital status, filing status, and gross income deternew one is established coupled with the abandonmine whether you have to file a tax return. Gross inment of the old. Burden of proof regarding change of come usually means money, goods, and property domicile is on the taxpayer even though he/she you received on which you must pay tax. It does not owns no property, earns no income, and has no include nontaxable benefits. See page 7 of the inplace of abode in Alabama. structions to find out which types of income you should include.
If an Alabama resident accepts employment in a foreign country for a definite or indefinite period of Other Filing Requirements time with the intent of returning to the United States, Refunds. Even if your gross income was less the individual remains an Alabama resident and all than the amounts shown, you must file a return to income, wherever earned, is subject to Alabama inget a refund if Alabama income tax was withheld come tax. This is true even if the taxpayer leaves no from any amounts paid to you. property in Alabama.
You Must File A Return If…
You were a: and your marital status at the end of 2025 was: and your filing status is:
# Single
(including divorced and legally separated) Full Year Head of family Resident Married and living with your spouse at the end Married, joint return of 2025 (or on the date your spouse died) Married, separate return
# Single
(including divorced and legally separated) Part Year Head of family Resident Married and living with your spouse at the end Married, joint return of 2025 (or on the date your spouse died) Married, separate return Single (including divorced and legally separated) Single or head of family Nonresident Married and living with your spouse at the end Married, joint return of 2025 (or on the date your spouse died) Married, separate return If a citizen of a foreign country comes to Alabama to work (no matter how long he stays), buys a home, secures an Alabama driver's license, does not intend to apply for U.S. Citizenship, and intends to ultimately return to the country of origin, the individual will be considered to have established domicile in Alabama. In other words, a foreign citizen domiciled in Alabama is liable for Alabama income tax on income earned from all sources.
Military Personnel (Residents). Military personnel whose legal residence is Alabama are subject to Alabama income tax on all income regardless of the source or where earned unless specifically exempt by Alabama law.
Military personnel (Army, Navy, Marine, Air Force, Merchant Marine, and Coast Guard) who were residents of Alabama upon entering military service remain residents of Alabama for income tax purposes regardless of the period of absence or actual place of residence until proof of change in home of record has been made. The burden of proof is on the taxpayer though he owns no property, earns no income, or has no place of abode in Alabama. Under the provisions of the Soldiers' and Sailors' Civil Relief Act, military personnel are not deemed to have lost their permanent residence in any state solely because they are absent in compliance with military orders. In addition, persons are not deemed to have acquired permanent residence in another state when they are required to be absent from their home state by virtue of military orders. If the husband and wife are both in military service, each could be a resident of a different state under the Soldiers' and Sailors' Civil Relief Act. A spouse not in military service has the same domicile as his/her spouse unless proven otherwise.
Military Personnel (Nonresidents). Non resi- dent military personnel merely having a duty station within Alabama (whose legal residence is not Ala- bama) are not required to file an Alabama income tax return unless they have earned income from Alabama sources other than military pay. If they have earned income in Alabama other than military pay, they are required to file Alabama Form 40NR. A married nonresident with income earned in Alabama may file either a separate return claiming himself or and your gross income was at least:
$ 4,500
$ 8,200
$11,500
$ 5,750
$ 4,500 (while an Alabama resident)
$ 8,200 (while an Alabama resident)
$11,500 (while an Alabama resident)
$ 5,750 (while an Alabama resident)
Over the allowable prorated exemption.
herself only, or a joint return claiming the total allowable personal exemption. The "Military Spouses Residency Relief Act" (Public Law 111-97) states that the income for services performed by the spouse of a service member shall not be deemed to be income for services performed or from sources within a tax jurisdiction of the United States if the spouse is not a resident of the jurisdiction in which the income is earned because the spouse is in the jurisdiction solely to be with the service member serving in compliance with military orders.
Dependent's and Student's Income. Dependents who are residents of Alabama must file a return if they meet the requirements under You Must File A Return IF… on page 4. A student's income is fully taxable to the same extent as other individuals who are required to file a return. If a return is required, the dependent or student can claim a personal exemption of $1,500 and his or her parents may claim a dependent exemption if they provided more than 50% of the total support. See Dependent Exemption on page 9.
When To File
You should file as soon as you can after January 1, 2026, but no later than the due date of the federal return. If you file late, you may have to pay penalties and interest. (See Penalties and Interest on page 14.) If you know you cannot file your return by the due date, you do not need to file for an extension.
You will automatically be granted an extension until October 15, 2026. If you anticipate that you will owe additional tax on your return, you should submit your payment with a payment voucher (Form 40V) with the box "Automatic Extension Payment" checked by the due date of the federal return.
Except in cases where taxpayers are abroad, no extension will be granted for more than 6 months.
An extension means only that you will not be assessed a penalty for filing your return after the due date. Interest on the additional tax due from the due date of the return and any penalties will be assessed if applicable to your return.
Original returns must be filed within two years of the date the taxes are paid to be eligible for a refund. Criminal liability could result from a continued failure to file returns. (Refer to "Criminal Liability" on Page 14.) Which Form To File
# ALL The Following Conditions:
You were a resident of Alabama for the entire year, You do not itemize deductions, You do not claim any adjustments to income such as an IRA deduction, alimony paid, federal income tax paid for a prior year, etc., You do not have income from sources other than salaries and wages, except for interest and dividend income, which cannot exceed $1,500, You are not claiming income or a loss from Schedules C, D, E, or F, and You are not claiming credit for taxes paid to another state.
# You MUST Use Form 40 If:
You were a full or part-year resident of Alabama and do not meet ALL of the requirements to file Form 40A, and You are itemizing deductions.
# You MUST Use Form 40NR If:
You are not a resident of Alabama and you received taxable income from Alabama sources or for performing services within Alabama and your gross income from Alabama sources exceeds the allowable prorated personal exemption, or filing Married Filing Joint under the "Military Spouses Residency Relief Act." Non residents must prorate the personal exemption. If your Alabama gross income exceeds the prorated amount, a return must be filed.
# Form 40NR If:
You had sufficient income to require the filing of a part-year return and also had income from Alabama sources while a non-resident during the same tax year. In this case, both the total personal exemption and the dependent exemption must be claimed in the part-year resident return. No exemption can be claimed on the nonresident return. The part year resident return should include only income and deductions incurred during the period of residency. The nonresident return should include only income and deductions incurred during the period of non-residency.
# SECTION
2 Your Return
# Steps for Preparing
By following these five useful steps, and reading the specific instructions that follow, you should be able to prepare your return quickly and accurately.
Step 1
# Collect all your necessary records.
Income Records. These include any Forms W-2, W-2G, and 1099 that you have. If you do not receive a Form W-2 by February 1, OR if the one you receive is incorrect, please contact your employer as soon as possible. Only your employer can give you a Form W-2, and only he or she can correct it.
If you have someone prepare your return for you, make sure that person has all your income and expense records so he or she can fill in your return correctly. Remember, even if your return is prepared incorrectly by someone else, you are still responsible.
Itemized Deductions. If you itemize deductions (Forms 40 or 40NR), some of the records you need are:
Medical and dental payment records.
Real estate and personal property tax receipts.
Interest payment records for a home mortgage.
Step 2
Obtain any forms or schedules you may need.
The fastest way to obtain forms is to download them from our website www.revenue. alabama.gov. Also see page 29 for more information.
Step 3
Check your return to make sure it is correct.
See Common Mistakes on page 11.
Step 4
# Sign and date your return.
Form 40, 40A, or 40NR is not considered a return unless you sign it. Please sign in black ink only. Your spouse must also sign if it is a joint return.
Original signatures are required or the return will not be accepted.
Step 5
Attach all necessary forms and schedules.
Attach the state copies of all Forms W-2, W-2G, 1099's and completed copy of your federal form to the front of your return. Attach schedules and forms in sequential order starting with Form 40NR.
If you need more space on forms or schedules, attach separate sheets and use the same format as the printed forms, but show your totals on the printed forms. Please use sheets that are the same size as the forms and schedules. Be sure to put your name and social security number on these separate sheets, and attach them at the end of the return.
Before mailing your return, check to make sure you have retained an exact copy for your records. If you owe tax, be sure to include payment and Form 40V with your return. Please see page 10 for additional payment options.
# SECTION
3 Instructions
# Specific
Name and Address
Please type or print your name, address, and social security number in the appropriate blocks.
If you live in an apartment, please include your apartment number in the address. If the post office delivers mail to your P.O. Box number rather than to your street address, write the P.O. Box number instead of your street address.
Social Security Number
Each year thousands of taxpayers file returns using an incorrect social security number. Usually this number belongs to another taxpayer. It is very important that you file your return using the correct social security number. Failure to use your correct social security number(s) in the space(s) provided WILL DELAY the processing of your refund. Listed below are a few of the common reasons that a social security number is reported incorrectly: failure to place number on return, memorized wrong number, copied number wrong, gave an incorrect number to the tax preparer, gave your employer an incorrect number.
IMPORTANT: Check your W-2 forms. Your em ploy - er may be reporting an incorrect number for you.
If you are married and filing a joint return, write both social security numbers in the blocks provided.
If you are married and filing separate Alabama returns, write your spouse's social security number on line 3.
If your spouse is a nonresident alien, has no income, does not have a social security number, and you file a separate return, check the "NRA" box and leave the block for your spouse's social security number blank. If you and your spouse file a joint return, your spouse must have a social security number.
If you or your spouse do not have a social security number, please get Form SS-5 from a Social Security Administration (SSA) office. File it with your local SSA office early enough to get your number before April 15.
IMPORTANT: Notify the Social Security Ad min is tra- tion (SSA) immediately in the event you have changed your name because of marriage, divorce, etc., so the name on your tax return is the same as the name the SSA has on record. This helps prevent delays in processing your return.
Filing Status and Personal
Exemption Lines 1 through 4
You should check only the box that describes your filing status. The personal exemption will be determined by your filing status on the last day of the tax year.
# Single
Consider yourself single if on December 31, you were unmarried or separated from your spouse either by divorce or separate maintenance decree.
If you check box 1, multiply $1,500 by the percentage on line 10, and enter the result on line 15.
# Married
Joint or Separate Returns?
Joint Returns. Most married couples pay less tax if they file a joint return. You must report all income, exemptions, deductions, and credits for you and your spouse. Both of you must sign the return even if only one of you had income. Common law marriages entered into before January 1, 2017, are recognized by the State of Alabama for income tax purposes.
You and your spouse can file a joint return if you were living together on December 31, 2025, even if you did not live together for the entire year. Both of you are responsible for any tax due on a joint return, so if one of you does not pay the other may have to.
Note: If you file a joint return, you may not, after the due date of the return, choose to file separate returns for that year.
If your spouse died in 2025, you can file a joint return for 2025. You can also file a joint return if your spouse died in 2026 before filing a 2025 return. For details on how to file a joint return, see Death of
Taxpayer on page 14 and 15.
If you check box 2, multiply $3,000 by the percentage on line 10, and enter the result on line 15.
Separate Returns. You can file separate returns if both you and your spouse had income, or if only one of you had income.
If you file a separate return, report only your own income, exemptions, deductions, and credits. You are responsible only for the tax due on your return.
Note: Alabama is not a community property state.
If you file a separate return, write your spouse's social security number in the space on line 3.
If your spouse does not file, attach a statement explaining why your spouse is not required to file.
If you check box 3, multiply $1,500 by the percentage on line 10, and enter the result on line 15.
# Head of Family
An individual shall be considered Head of Family if, and only if, such individual is not married at the close of their tax year, is not a surviving spouse and their qualifying dependent is not a foster child.
You may check the box on line 4 ONLY IF on December 31, 2025, you were unmarried or legally separated and meet either test 1 or test 2 below:
Test 1. You paid more than half the cost of keeping up a home for the entire year provided that the home was the main home for your parent whom you can claim as a dependent. Your parent did not have to live with you in your home.
OR
Test 2. You paid more than half the cost of keeping up a home in which you lived and in which one of the following also lived for more than 6 months of the year (temporary absences, such as for vacation or school, are counted as time lived in the home): a. Your unmarried child, grandchild, greatgrandchild, etc., adopted child, or stepchild. This child does not have to be your dependent. b. Your married child, grandchild, great-grandchild, etc., adopted child, or stepchild. This child must be your dependent. However if your child's other parent claims him or her as a dependent under the federal rules for Children of Divorced or Separated Parents, this child does not have to be your dependent. c. Any relative whom you can claim as a dependent. (See definition of a dependent on page 9.) If the person for whom you kept up a home was born or died during the year, you may still file as Head of Family if the home was that person's main home for the part of the year he or she was alive.
If you check box 4, multiply $3,000 by the percentage on line 10, and enter the result on line 15.
Special Rules
A nonresident taxpayer who receives income from Alabama sources or for performing services within Alabama and who also had income while a resident of Alabama during the same tax year must file both the Alabama Nonresident Form 40NR and the Alabama part-year Form 40. If you are required to file both returns, the total personal exemption and the dependent exemption must be claimed on the part-year return (Form 40). No personal exemption or dependent exemption can then be claimed on the nonresident return (Form 40NR).
Income
A nonresident of Alabama is subject to tax on all income received within or for services performed in Alabama and amounts received from the sale of property located in Alabama unless specifically exempt. The term "income" includes, but is not limited to; salaries, wages, commissions, income from business or professions, alimony, rents, royalties, inter- est, dividends, and profits from sales of real estate, stocks, or bonds. Military pay is not taxable for nonresidents of Alabama.
# You MUST Report
The following kinds of income should be reported on Forms 40, 40A, or 40NR and related forms and schedules. You may need some of the forms and schedules listed below:
Wages including salaries, fringe benefits, bonuses, commissions, fees, and tips.
Dividends (Schedule B).
Interest (Schedule B) on: bank deposits, bonds, notes, Federal Income Tax Refunds, mortgages on which you receive payments, accounts with saving and loan associations, mutual savings banks, credit unions, etc.
Original Issue Discount (Schedule B).
Distributions from an Individual Retirement Arrangement (IRA) including SEPs (Simplified Employee Pension) and DECs, if you excluded these amounts in a prior year (Schedule RS).
Bartering income (fair market value of goods or services you received in return for your services).
Business expense reimbursements you received that are more than you spent for the expenses.
Amounts received in place of wages from accident and health plans (including sick pay and disability pensions) if your employer paid for the policy.
Alimony or separate maintenance received from and deductible by your spouse or former spouse.
Life insurance proceeds from a policy you cashed in if the proceeds are more than the premium you paid.
Profits from businesses and professions (Federal Schedule C or C-EZ).
Your share of profits from partnerships and S Corporations (Schedule E).
Profits from farming (Federal Schedule F).
Lump-sum distributions.
Gains from the sale or exchange (including barter) of real estate, securities, coins, gold, silver, gems, or other property (Schedule D).
Gains from the sale of your personal residence as reported on your Federal return (Schedule D).
Rents and Royalties (Schedule E).
Your share of estate or trust income (Schedule E).
Prizes and awards (contests, lotteries, and gambling winnings) (W-2G).
Income from sources outside the United States.
Director's fees.
Fees received as an executor or administrator of an estate.
Embezzled or other illegal income.
Refunds of Federal Income tax if previously deducted in a prior year and resulted in a tax benefit.
Payments received as a member of a military service generally are taxable except for combat pay and certain allowances.
Jury duty pay.
Nonqualified Withdrawal from Alabama College Counts 529 Fund.
# You DO NOT Report
Do not include these amounts when deciding if you must file a return.
United States Retirement System benefits.
State of Alabama Teachers' Retirement System benefits.
State of Alabama Employees' Retirement System benefits.
State of Alabama Judicial Retirement System benefits.
Military retirement pay.
Tennessee Valley Authority Pension System benefits.
United States Government Retirement Fund benefits.
Payments from a Defined Benefit Retirement Plan in accordance with IRC 414(j). Contact your retirement plan administrator to determine if your plan qualifies.
Federal Railroad Retirement benefits.
Federal Social Security benefits.
State income tax refunds.
Unemployment compensation.
Welfare benefits.
Disability retirement payments (and other benefits) paid by the Veteran's Administration.
Workman's compensation benefits, insurance damages, etc., for injury or sickness.
Death benefits received by a designated beneficiary of a peace officer or fireman killed in the line of duty.
Child support.
Gifts, money, or other property you inherit or that was willed to you.
Dividends on veteran's life insurance.
Life insurance proceeds received because of a person's death.
Interest on obligations of the State of Alabama or any county, city, or municipality of Alabama.
Interest on obligations of the United States or any of its possessions.
Amounts you received from insurance because you lost the use of your home due to fire or other casualty to the extent the amounts were more than the cost of your normal expenses while living in your home. (You must report as income reimbursements for normal living expenses.) Military allowances paid to active duty military, National Guard, and active reserves for quarters, subsistence, uniforms, and travel.
Subsistence allowance received by law enforcement and corrections officers of the State of Alabama.
All retirement compensation received by an eligible fire fighter or a designated beneficiary from any Alabama firefighting agency.
All retirement compensation received by an eligible peace officer or a designated beneficiary from any Alabama police retirement system.
Income earned while serving as a foreign missionary after first serving 24 months as a missionary in a foreign country.
Compensation received from the United States for active service as a member of the Armed Forces, including members of the National Guard and Reserve, in a combat zone designated by the President of the United States, deployed to locations outside the United States or activated by the Governor of Alabama or the Presi dent of the United States to support state or federal re sponse to emergencies within or outside of the United States.
An amount up to $50,000 for Tax Years 2020 and forward received as severance, unemployment compensation or termination pay, or as income from a supplemental income plan, or both, by an employee who, as a result of administrative downsizing, is terminated, laid-off, fired, or displaced from his or her employment, shall be exempt from state income tax. If the exempt severance pay is included in your state wages, contact your employer for a corrected W-2.
Beginning January 1, 1998, all benefits received from Alabama Prepaid Affordable College Tuition Contracts (PACT).
Qualified withdrawals from an Alabama 529 savings plan.
Beginning January 1, 2016, all income, interest, dividends, gains or benefits of any kind received from an ABLE (Achieving Better Life Experience) savings account.
Effective with tax year 2020, insurance benefits received by a certified firefighter as a result of a cancer diagnosis to any extent the amounts are included in the federal adjusted gross income of the taxpayer and are not exempt under any other law.
For more information please see Act 2019-361.
Beginning January 1, 2025, any net capital gain on the exchange of precious metal bullion. Precious metal bullion means coins, bars or rounds containing primarily refined gold, silver, platinum, or palladium that is marked and valued primarily by its weight, purity, and content.
# Rounding Off To Whole Dollars
Round off cents to the nearest whole dollar on your return and schedules. You can drop amounts under 50 cents. Increase amounts from 50 to 99 cents to the next dollar. For example: $1.39 becomes $1.00, and $2.69 becomes $3.00.
Negative numbers - Please enter all negative numbers with negative signs (-). Do not use parenthesis ( ).
Line 5
# Wages, Salaries, Tips, Etc.
Alabama tax withheld information must be reported on Schedule W-2. (See Schedule W-2 instructions for more information.) The amount withheld is shown on the state copy of your Form W-2. This copy should be marked "To Be Filed With Your Alabama Income Tax Return."
Note: Do not change or alter the amount of tax withheld or wages reported on your Form W-2. If any amount is incorrect or illegible, you should contact your employer and request a corrected statement.
Do not include these taxes as Alabama income tax:
Federal income tax,
FICA tax (Social Security and Medicare), Local, city, or occupational tax, or Taxes paid to another state.
In Column A - Alabama tax withheld, enter the total amount from Schedule W-2, Line 18, Column G.
Income From ALL Sources. Report income from all sources on Schedule W-2, Column H.
See Schedule W-2 instructions for more information. Show the total amount of wages, salaries, fees, commissions, tips, bonuses, and other amounts you were paid before taxes, insurance, etc. were taken out.
This includes the income earned in Alabama as well as the income earned outside of Alabama. Even though the income earned outside of Alabama is not taxable to Alabama, it must be included in order to determine the ratio of Alabama income to total income from all sources. This determines the personal exemption, dependent exemption, and itemized deductions or standard deduction you may claim in arriving at the income on which you figure the amount of tax you owe Alabama.
In Column B - "All Sources" enter the total income from Schedule W-2, Line 18, Column H.
Alabama Income. Report all W-2 information on Schedule W-2. See Schedule W-2 instructions for more information. On column C - "Alabama Income", enter the amount from Schedule W-2, Line 18, Column I. The amount shown in the box headed "State Wages" on your Form W-2 should be included on Schedule W-2. Report all wages, salaries, fees, commissions, tips, bonuses, and other amounts of income that were earned in Alabama even if you do not have a Form W-2. (These amounts should also have been included in Column B.) Note: State of Alabama employees will find that the amount taxable for state purposes is, in most cases, more than the amount taxable for federal purposes.
This is due to the fact that amounts deducted from their wages as "Contributions to the Alabama State Retirement System" qualify for deferral on the federal return, but do not qualify for deferral on the Alabama return.
Statutory Employees. If you were a statutory employee, the Statutory employee box of your W-2 form should be checked. Statutory employees include full time life insurance salespeople, certain agent or commission drivers and traveling salespeople, and certain homeworkers.
Please see the Schedule W-2 instructions for information on how to report your "Statutory Employee" wages.
Line 6
# Other Income
All taxable income you received that is not reported on line 5 should be entered on line 6. This includes interest income, dividends, rents, royalties, gains from sale of property, etc.
See Examples of Income You DO NOT Report and Examples of Income You MUST Report on page 7 of these instructions for further details on income which should be included on this line.
If you have income from other sources, you must complete page 2, Part I and attach the appropriate schedule(s).
Line 8
# Adjustments to Income
If you made payments to an Individual Retire- ment Arrangement (IRA), Keogh Retirement Plan, Simplified Employee Pension (SEP), paid self-employment health insurance premiums, incurred penalties for the early withdrawal of funds, or incurred deductible moving expenses, then these items should be shown as an adjustment to income.
For more information on the above deductions see the instructions on page 13 for page 2, Part II .
The adjustments to income from Part II, line 8 should be entered on page 1, line 8.
Line 10
# Total Income
You must divide the amount on line 9, Column C, by the amount on line 9, Column B, to determine the ratio of Alabama Adjusted total income to the Adjusted total income from all sources. If the amount in Column C is larger than the amount in Column B, you should enter 100% on line 10. If the amount in Column C is a loss (less than 0) enter 0% on line 10.
Line 11
# Other Adjustments
If you paid alimony, adoption expenses and/or qualifying health insurance for a small employer employee, you should show these amounts as other adjustments to income. The amount that needs to be entered on line 11, will come from the total other adjustments on page 2, part 3, line 4 and line 6 of your return. See instructions for page 2, part 3, on page 13 of this booklet for more instructions.
Line 12
# Adjusted Gross Income
If the amount on Column C, line 12 is less than zero you may have a net operating loss that you can carry to another tax year. If you carry the loss back to earlier years, you should check the amended return box on your Form 40NR and attach Form NOL-85 and/or Form NOL-85A.
Line 13
# Itemized or Standard Deduction
You have the option to either itemize your deductions or you may claim the optional standard deduction. You should compute your deduction both ways to determine the option that gives you the larger deduction. If you elect to claim the standard deduction on your return and it later becomes necessary to change to itemized deductions, you may do so by filing an amended return.
If married and filing separate returns, both spouses must claim the same deduction unless the spouses have lived apart for the entire year, in which case each spouse may claim either deduction. However, neither spouse may claim a deduction for expenses paid by the other. See the instructions for Schedule A for items that may be claimed as an itemized deduction.
Itemized Deductions. If you elect to itemize your deductions, you should check box a on line 13 and complete and attach Schedule A. The amount shown on line 30 of Schedule A should be entered on line 13.
Standard Deduction. If you elect to claim the Standard Deduction, you should check box b on line 13, and use the chart on the next page to determine the Standard Deduction allowable on your return. A dependent or student may take the standard deduction even if claimed as a dependent by someone else. The Standard Deduction must be prorated by the percentage on page 1, line 10.
Line 14
# Federal Income Tax Deduction
A nonresident of Alabama may deduct from Alabama adjusted gross income a portion of the Federal income tax due on the 2025 Federal income tax return. In order to determine the amount deductible, you must complete page 2, Part IV of Form
40NR. The instructions for completing Part IV are on page 13 of this booklet.
Line 15
# Personal Exemption
Enter the personal exemption amount from line 1, 2, 3, or 4 multiplied by the percentage on line 10.
A dependent or student may take the personal exemption even if claimed as a dependent by someone else.
Line 16
# Dependent Exemption
A dependent as defined under Alabama law is an individual other than the taxpayer and his or her spouse who received over 50% of his or her support from the taxpayer during the tax year and is also related to the taxpayer in one of the following relationships:
Son Stepfather
Daughter Mother-in-law
Stepson Father-in-law In figuring total support, you must include money the dependent used for his or her own support even Stepdaughter Brother-in-law if this money was not taxable (for example: gifts, sav-Legally adopted child Sister-in-law ings, welfare benefits). If your child was a student, do Parent Son-in-law not include amounts he or she received as scholar-Grandparent Daughter-in-law ships.
Grandchild If related by blood:
Brother Uncle
Support includes items such as food, a place to Sister Aunt live, clothes, medical and dental care, recreation, Stepbrother Nephew and education. In figuring support use the actual cost Stepsister Niece of these items. However, the cost of a place to live is figured at its fair rental value.
Stepmother
In figuring support, do not include items such as Note: You cannot claim a foster child, friend, cousin, income taxes, social security taxes, premiums for yourself, or your spouse as a dependent under Alalife insurance, or funeral expenses. bama law.
If you qualify to claim your child and/or other in-Birth or Death of Dependent. You can take an dividuals as your dependent, you must complete on exemption for a dependent who was born or who page 2, Part V. The total credit entered on page 2, died during 2025 if he or she met the qualifications Part V, line 4 should be entered on page 1, line 16. for a dependent while alive.
Support. You must have provided over 50% of Amount on Dependent the dependent's support in 2025. If you file a joint
Col. B, Line 12, Page 1 Exemption return, the support can be from you or your spouse.
You cannot claim credit on an Alabama return for a 0 - 50,000 1,000 dependent if you provided less than 50% of the sup-50,001 - 100,000 500 port under Alabama law as you can under federal Over 100,000 300 law in certain conditions.
Line 19
If you are married and filing a separate return, you must consider only the amounts you separately Figuring Your Tax furnished out of your income in determining whether You must figure your tax from the Tax Tables on or not you provided over 50% of the dependent's pages 21-26 unless you are claiming a carryover or support. Do not include any amounts your spouse carryback net operating loss from another year. furnished for the support of the dependent.
Standard Deduction
# Married Filing Separate
Married Filing Joint Head of Family Single
Adjusted Gross
Adjusted Gross Standard Standard Adjusted Gross Standard Adjusted Gross Standard
Income (Col. B, Line 12) Deduction
Income (Col. B, Line 12) Deduction Income (Col. B, Line 12) Deduction Income (Col. B, Line 12) Deduction $ 0 - $12,999 $ 0 - $25,999 $8,500 $4,250 $ 0 - $25,999 $5,200 $ 0 - $25,999 $3,000 $13,000 - $13,249 $26,000 - $26,499 $8,325 $4,162 $26,000 - $26,499 $5,065 $26,000 - $26,499 $2,975 $13,250 - $13,499 $25,500 - $26,999 $8,150 $4,074 $26,500 - $26,999 $4,930 $26,500 - $26,999 $2,950 $13,500 - $13,749 $27,000 - $27,499 $7,975 $3,986 $27,000 - $27,499 $4,795 $27,000 - $27,499 $2,925 $13,750 - $13,999 $27,500 - $27,999 $7,800 $3,898 $27,500 - $27,999 $4,660 $27,500 - $27,999 $2,900 $14,000 - $14,249 $28,000 - $28,499 $7,625 $3,810 $28,000 - $28,499 $4,525 $28,000 - $28,499 $2,875 $14,250 - $14,499 $28,500 - $28,999 $7,450 $3,722 $28,500 - $28,999 $4,390 $28,500 - $28,999 $2,850 $14,500 - $14,749 $29,000 - $29,499 $7,275 $3,634 $29,000 - $29,499 $4,255 $29,000 - $29,499 $2,825 $14,750 - $14,999 $29,500 - $29,999 $7,100 $3,546 $29,500 - $29,999 $4,120 $29,500 - $29,999 $2,800 $15,000 - $15,249 $30,000 - $30,499 $6,925 $3,458 $30,000 - $30,499 $3,985 $30,000 - $30,499 $2,775 $15,250 - $15,499 $30,500 - $30,999 $6,750 $3,370 $30,500 - $30,999 $3,850 $30,500 - $30,999 $2,750 $15,500 - $15,749 $31,000 - $31,499 $6,575 $3,282 $31,000 - $31,499 $3,715 $31,000 - $31,499 $2,725 $15,750 - $15,999 $31,500 - $31,999 $6,400 $3,194 $31,500 - $31,999 $3,580 $31,500 - $31,999 $2,700 $16,000 - $16,249 $32,000 - $32,499 $6,225 $3,106 $32,000 - $32,499 $3,445 $32,000 - $32,499 $2,675 $16,250 - $16,499 $32,500 - $32,999 $6,050 $3,018 $32,500 - $32,999 $3,310 $32,500 - $32,999 $2,650 $16,500 - $16,749 $33,000 - $33,499 $5,875 $2,930 $33,000 - $33,499 $3,175 $33,000 - $33,499 $2,625 $16,750 - $16,999 $33,500 - $33,999 $5,700 $2,842 $33,500 - $33,999 $3,040 $33,500 - $33,999 $2,600 $17,000 - $17,249 $34,000 - $34,499 $5,525 $2,754 $34,000 - $34,499 $2,905 $34,000 - $34,499 $2,575 $17,250 - $17,499 $34,500 - $34,999 $5,350 $2,666 $34,500 - $34,999 $2,770 $34,500 - $34,999 $2,550 $17,500 - $17,749 $35,000 - $35,499 $5,175 $2,578 $35,000 - $35,499 $2,635 $35,000 - $35,499 $2,525 $17,750 and above $35,500 and above $5,000 $2,500 $35,500 and above $2,500 $35,500 and above $2,500
Indicate the method you are using by checking the appropriate box. If you are claiming a net operating loss from another year, you must complete and attach Form NOL-85A.
Line 20
# Net Tax Due Alabama
If you are using tax credits to reduce your tax liability, Schedule OC must be completed in order to compute your net tax due. You must check the box to indicate you are using Schedule OC to compute your net tax due. If you do not have any tax credits, enter the amount from line 19.
# Credits - Schedule OC
Schedule OC must be completed for a credit claim and Individual taxpayers must register to set up an Credit, Innovate Alabama Tax Credit, Volunteer First Responder Mileage Income Tax Credit, Preceptor Tax Incentive Credit, Alabama Workforce Housing Tax Credit, Employer Tax Credit, Childcare Facility Tax Credit, Employer Provider Credit, and Income Tax Capital Credit. For more information on credits see Schedule OC.
Line 22
# Automatic Extension Payments
Enter on this line any payments you made on your estimated Alabama income tax (Form 40ES) for 2025 or automatic extension (Form 40V). Include any overpayments from your 2024 return that you applied to your 2025 estimated tax. (Do not include the balance you paid with your 2024 return in 2025 or any Line 24
# Previous Payments
This line is for amended returns only. Enter the amount of your previous payment made with your original return and/or billing notices and amended return(s).
Line 25
# Refundable Credit
This line is only for the refundable portion of Alabama Accountability Act, Adoption Credit, Historic Tax Rehabilitation Act of 2017 Credit, Childcare Facility Tax Credit or Employer Provider Credit. Enter the amount from Schedule OC, Section F, line F6.
Line 27 account in My Alabama Taxes (MAT) at www.myalabamataxes.alabama.gov for approval before claiming certain credits on their tax return.
Once logged into MAT, a taxpayer will need to locate the "Individual Income Tax" account type, then select "Submit a Credit Claim" from the "Tax Incentives" section on the right margin of the page and follow a short series of steps to reserve their credit.
For individuals who do not have a MAT account or are unable to set up a MAT account, go to the MAT homepage, select "Submit an Individual Credit Claim" from the "Individuals" section on the main page and follow a short series of steps to reserve your credit. If the credit claimed on an individual income tax return is from a Schedule K-1 issued by a pass through entity, the credit claim will be submitted by the entity and no action is required by the individual. Supporting documentation for certain credits is required to be uploaded in MAT. Taxpayers needing assistance with reserving a tax credit may call (334) 353-9770 or (334) 353-0602.
While all tax credits are reported on Schedule OC, some require a separate schedule to be completed before entering the results on Schedule OC and some require a MAT account to reserve their credit approval before submission on Schedule OC.
Please visit the Department's website for more information on the Schedule OC and Schedule OC instructions for each of the following tax credits:
Alabama Enterprise Zone Credit, Basic Skills Education Credit, Rural Physician Credit, Coal Credit, Full Employment Act of 2011 Credit, Veterans Employment Act - Employers Credit, Veterans Employment Act- Business Start Up Expense Credit, Qualified Irrigation System/Reservoir System tax Credit, Alabama Accountability Tax Credit- School Transfer Credit, Alabama Accountability Act Credit -Scholarship Granting Organization (SGO) credit, Alabama Adoption Credit, 2013 Alabama Historic Rehabilitation Tax Credit, Career Technical Dual Enrollment Credit, Investment Credit - Alabama Jobs Act, Alabama Renewal Act - Port Credit, Alabama Renewal Act - Growing Alabama Credit, 2017 Alabama Historic Tax Rehabilitation Credit, Railroad Modernization Act of 2019 Credit, Storm Shelter Credit, Volunteer Emergency Responders Tax overpayment from 2024 that was refunded to you.) If you and your spouse paid joint estimated tax but are now filing separate Alabama income tax returns, either of you may claim all of the amount paid, OR you can each claim a part of it. Please be sure to show both social security numbers on the separate returns. If you and your spouse paid separate estimated tax but are now filing a joint income tax return, add the amounts you each paid. These instructions also apply if your spouse died during the year.
Caution: It is very important that the social security numbers be the same on your current return, last year's return, and all of your estimate vouchers. The department will be unable to allow you proper credit for your payments unless the numbers are the same.
If the department is unable to verify the amount claimed, you may be requested to submit copies of all your canceled checks substantiating the amount claimed. This will cause considerable delay in processing your return.
Name Change. If you changed your name because of marriage, divorce, etc., and you made estimated tax payments using your former name, attach a statement to Form 40NR explaining all the payments you and your spouse made in 2025 and the name(s) and social security number(s) under which you made the payments.
Line 23
# PTE Credit
If you are reporting income from a partnership or S corporation which filed Alabama Form PTE-C, any payment made on your behalf should be entered on Schedule CP. For tax years beginning on or after January 1, 2021, Act 2021-423 allows the owner, member, partner, or shareholder of an electing passthrough entity reporting income to be allowed a refundable credit in an amount equal to its pro rata or distributive share of the Alabama income tax paid by the electing pass-through entity with respect to the corresponding tax year. This amount needs to be reported on Schedule CP. The amount from Schedule CP, Section B, line 1 should be entered on line 23.
# Previous Refund
This line is for amended returns only. Enter the amount of your previous refund from your original return and amended return(s).
Line 29
# Amount You Owe
(If line 20 is larger than line 28)
Subtract line 28 from line 20 and add line 30, and enter the amount on line 29 - this is the amount you owe the State of Alabama.
Pay the full amount by check or money order payable to the "Alabama Department of Revenue."
On your payment write your social security number, your daytime telephone number, and "2025 Form 40NR," and remit your payment with Form 40V.
Electronic Payment Option
You may pay your taxes online using your bank account (e-check), or a debit/credit card through MyAlaba maTaxes.gov.
If you have a My Alabama Tax (MAT) account, log on to your account and click on the "Make a Payment" link. If you do not have a MAT account, go to www. myalabamataxes.alabama.gov. Click on the "Make a Payment" link and complete the requested information.
Paying by e-check is free. There is a convenience fee for debit/credit card payments. Do not use Form 40V when paying by ACH Debit or credit card.
If you are paying with funds on a foreign bank you must include an additional $25 exchange fee.
If payment for the full amount of tax due is not paid by the due date of the return, you will be charged interest and will be subject to penalties.
(See Penalties and Interest on page 14 of these instructions.) More importantly, if you submit your return without payment, a final assessment may be entered by the Department. A final assessment which is not appealed is as conclusive as a judgment of a circuit court. The Department may then proceed with collection by issuance of legal processes including recording of tax liens, garnishment of wages or bank accounts, levy, or a writ of seizure directed to the county sheriff as provided by Sections 40-1-2, 40-2-11(16), and 40-29-23, Code of Alabama 1975.
Line 30
# Estimated Tax Penalty
If the amount you owe (line 29) exceeds $500.00, you may be subject to an estimate, or underestimation penalty. Page 14 of this booklet provides additional information on these penalties, or you can complete Form 2210AL. See page 29, "How To Obtain Forms."
Line 31
# Overpayment
(If line 28 is larger than line 20)
Subtract line 20 from line 28, and enter the amount on line 31 - this is the amount you overpaid.
Line 32
# Applied to 2026 Estimated Tax
You may elect to credit all or part of the overpayment shown on line 31 to your 2026 estimated
Tax. Once an election is made to apply this overpayment to your 2026 estimated tax, it cannot later be refunded to you or applied to pay additional tax for 2025.
Line 33
# Refunded to You
If line 31 is greater than zero, subtract lines 30 and 32 from the amount on line 31. If your return is complete and contains no errors, you should receive your refund within 8 to 12 weeks after you mail it.
See When Should I Receive My Refund? on page 15 of this booklet for further information about your refund.
Sign Your Return
Form 40NR is not considered a return unless you sign it. Please sign in black ink only. Your spouse must also sign if it is a joint return. If you are filing a joint return with your deceased spouse, see
Death of Taxpayer on page 14 and 15.
Did You Have Someone Else Prepare Your
Return? If you fill in your own return, the Paid Preparer's Use Only area should remain blank. Someone who prepares your return but does not charge you should not sign.
Generally, anyone who is paid to prepare your tax return must sign your return and fill in the other blanks in the Paid Preparer's Use Only area of the return.
If you have questions about whether a preparer is required to sign a return, please contact an Alabama Taxpayer Service Center.
The preparer required to sign your return MUST:
Sign, by hand, in the space provided for the preparer's signature. (Signature stamps or labels are not acceptable.) Give you a copy of your return for your records in addition to the copy to be filed with the Alabama Department of Revenue.
BEFORE signing and mailing your return, you should review it to make sure the preparer has entered the correct name(s), address, and social security number(s) in the spaces provided and reported all of your income. REMEMBER, you are responsible for the information on your return even if you pay someone else to prepare it.
Please enter your daytime phone number. This will enable us to contact you and help speed your refund if there are any problems with processing your return.
Common Mistakes
Which Delay Refunds
Errors delay your refund. This checklist should help you file your form correctly:
- Is your address correct?
- If you took the standard deduction, did you use the chart on page 9?
- Did you include your W-2 forms and any other forms? Did you assemble all forms and schedules in the proper order? (See Step 5 on page 5.)
- Is your math correct? (Note: Check your math carefully when figuring your refund or amount you owe.)
- Did you find the correct tax in the Tax Table for your filing status and taxable income?
- Did you write your social security number, daytime phone number, and "2025 Form 40NR" on your check or money order?
- Did you sign and date your tax form?
If you want the Department to contact your tax preparer, please give permission to do so by checking the box above the signature line.
Where To File
If you are receiving a refund (Form 40NR, line 33), mail your return to:
P.O. Box 154
Montgomery, AL 36135-0001
If you are making a payment (Form 40NR, line 29), mail your return, Form 40V and payment to:
P.O. Box 2401
Montgomery, AL 36140-0001
If you are not receiving a refund or making a payment, mail your return to:
P.O. Box 327469
Montgomery, AL 36132-7469
Page 2, Part I
# Other Income
All taxable income other than salaries, wages, commissions, etc. that is not reported on page 1, line 5 should be reported in page 2, Part I.
The total other income from all sources should be reported in Column B under the heading "All Sources." The income reported in Column B should be the same as would be reported by a resident of Alabama.
Example: You may be required to report interest income from obligations of the U.S. Government on your federal return, but since this income is not taxable to Alabama it should not be included in Column B.
All income you listed in Column B earned in the State of Alabama should also be listed in Column C under the heading "Alabama Sources." Use only the lines and schedules applicable to your types of income.
# Interest and Dividend Income
Any interest or dividend income received in 2025 with Alabama legal jurisdiction should be reported in Column C. All other interest or dividend items that would normally be taxable to an Alabama resident should be reported in Column B.
Note: Interest or Dividend items received from pass through entities such as Partnerships or S-Corporations should not be reported as separate line items on Schedule B, but should be included in total on the Alabama Schedule E.
If you received dividends and interest income of more than $1,500 in 2025, you must complete and attach Schedule B. Enter the taxable amount shown in Schedule B on Part I, line 1.
Line 2
# Alimony Received
Alimony and separate maintenance payments received by a nonresident of Alabama in 2025 are not taxable for Alabama purposes. However, any amounts you received in 2025 must be included in the total adjusted gross income from all sources to the same extent that it is includable on your 2025 Federal return. The amount received should be listed in Column B only. Do not include amounts you received which are child support.
Line 3
# Pensions and Annuities
Pension and annuity payments received by a nonresident are not subject to Alabama tax. However, pension and annuity payments you received in 2025 that would be taxable to a resident of Ala- bama must be included in the total adjusted gross income from all sources in order to compute the ratio of Alabama adjusted gross income to total adjusted gross income from all sources:
Payments you received from any of the following are not taxable and should not be included in the income reported on line 3:
State of Alabama Teachers' Retirement.
State of Alabama Employees' Retirement.
State of Alabama Judicial Retirement.
United States Civil Service Retirement.
Retirement systems created by the Federal Social Security Acts.
Railroad retirement benefits received under the Federal Railroad Retirement Acts of 1935 and 1937.
Military Retirement Pay.
TVA Pension System Benefits.
U.S. Foreign Service Retirement and Disability Fund Annuities.
U.S. Government Retirement Fund Benefits.
Any Defined Benefit Retirement Plan in accordance with IRC 414(j). Contact your retirement plan administrator to determine if your plan qualifies.
Complete Schedule RS to report all pensions and/or annuities you received in 2025 that would be taxable to a resident of Alabama. The amount to be reported would be the same as reported on your Federal return except for income from those sources previously listed as exempt.
Line 4
# Business Income or (Loss)
If you conducted a business or practiced a profession during the taxable year, you must complete and attach a copy of Federal Schedule C or C-EZ to your Alabama return.
Generally, you may deduct the ordinary and necessary expenses of doing business - the cost of merchandise, salaries, interest, taxes, rent, repairs, and incidental supplies.
In the case of capital investments and improvements in depreciable property such as buildings, machines, and similar items having a useful life of more than one year, Alabama law provides for a "reasonable allowance" for depreciation over the useful life of the property.
If some of your expenses are part business and part personal, you can deduct ONLY the business portion.
Adjustments to Federal Schedules C and F. Alabama law differs from federal law in the treatment of some of the expenses shown on Federal Schedules C, and F, and certain items may need adjusting for Alabama purposes. The expenses which may need adjusting are:
Percentage Depletion Gas and Oil. In the case of oil and gas wells, the allowance for depletion shall be 12 percent of the gross income from the property during the taxable year, excluding from such gross income an amount equal to any rents or royalties paid or incurred by the taxpayer in respect to the property. Such amounts shall not exceed 50 percent of the net income of the taxpayer, computed without allowance for depletion, from the property, except that in no case shall the depletion allowance be less than the amount allowable under federal income tax law.
Cost Depletion Natural Resources Other than Gas and Oil. Alabama law has no provision for percentage depletion of natural resources other than gas and oil, as currently allowed under federal law. For Alabama purposes, the depletion allowance shall be computed using the cost depletion method.
Depreciation. Alabama law allows IRC Section 179 Expense for all taxable years beginning after December 31, 1989. Adjustments may be necessary if assets were acquired and placed in service prior to tax years beginning January 1, 1990.
Targeted "Jobs Credit." You may have been allowed to take a portion of your payroll expense as a "Targeted Jobs Credit" on your federal return. This is an allowable expense for Alabama income tax purposes.
Passive Activity Losses. Alabama law has no provision, similar to current federal law, which limits the deduction of passive trade or business activity losses.
If you have adjustments involving any of the previously described expenses, attach an explanation and show the adjustment as "Other Expenses" on Federal Schedule C or F.
The net profit or (loss) from business, as shown on Federal Schedule C-EZ or C after above ad just- ments (if applicable), should be entered on Part I, line 4. The net profit or (loss) from all operations within and without Alabama, as shown on Federal Schedule C, after above adjustments (if applicable), should be entered on Part I, line 4, Column B. The net profit or (loss) from operations in Alabama should be entered in Column C.
Line 5
# Real Estate, Stocks, Bonds, Etc.
If you sold real estate, stocks, bonds, or other assets in 2025 the net gain or (loss) should be entered in column B. The net gain or (loss) from the sale of property located in Alabama should also be entered in Column C.
If you sold your personal residence, any gain realized is taxable to the same extent as reported on your federal return.
Please see the instructions for Schedule D for further information.
Line 6
# Estates, Trusts, S Corporations
You must complete and attach Schedule E if you received income in 2025 from any of these sources. The instructions for completing Schedule E are on page 20 of this booklet.
Line 7
# Farm Income or (Loss)
If you operated a farm during the year, you must attach Federal Schedule F to your return.
Alabama law differs from Federal law in the treatment of some of the expenses shown on Federal Schedule F. These differences are discussed in the instructions for line 4, Part I. If any of these adjustments apply to your return, you should show the additional amounts as "Other Expenses" on Federal Schedule F.
The net profit or (loss) from farm operations, within and without Alabama, should be entered on line 7, Column B. The net profit or (loss) from farm operations in Alabama should also be entered in Column C.
Line 8
# Other Income
Enter on line 8 any other income you cannot find a place for on your return or on another schedule.
State the nature and source in the space provided, or attach a separate explanation.
The total other income from all sources should be entered in Column B, and only the other income earned in Alabama should be entered in Column C.
Foreign Income Exclusion. If you are entitled to a foreign income exclusion, please attach a copy of your Federal Form 2555 to your return and report the amount of your exclusion as a credit with a negative sign (Example: -30,000) on line 8 Other Income on page 2 of your return. All foreign income must be reported on your return, in order to receive any foreign income exclusion.
Nonqualified Distribution from Alabama 529
Savings Plan. If you receive a distribution from your Alabama 529 Savings plan and do not use the distribution to pay qualified expenses, the amount not used for qualifying expenses is taxable. Enter the amount of the nonqualified distribution plus 10% of the distribution and description on line 8, Columns B and C, Other Income.
# Nonqualified Withdrawal from ABLE Savings
Account. If you make a nonqualified withdrawal as defined by Internal Revenue Code (26 U.S.C 529A), the amount of the nonqualified withdrawal, plus 10 percent of the amount withdrawn, shall be taxable as income in the year of the nonqualified withdrawal.
Report this amount on line 8, Columns B and C, Other Income.
Note: Net operating losses are not allowed as a deduction on line 8 (Other Income). Net operating losses can only be claimed on Form NOL-85A.
Page 2, Part II
# SEP Deduction
Contributions to Individual Retirement Ar range- ments, Keogh retirement plans, and SEP deduction are deductible as an adjustment to income from "All Sources" in Column B. The amount deductible in Column C is limited to the contributions made from income attributable to Alabama sources. The amount deductible in Columns B and C is subject to the same limitations as on your federal return. However, when figuring the limitation on the amount deductible you must use the adjusted gross income shown on line 12, Columns B and C of your Alabama Return.
Line 2
# Savings
The Form 1099-INT given to you by your bank or savings and loan association will show the amount of any penalty you were charged for withdrawing funds from your time savings deposit before its maturity. Enter this amount on line 2, Column B only.
(Be sure to include the interest income on Part I, line 1, column B.) Note: Penalties on early withdrawal from retirement plans are not deductible.
Line 3
# Moving Expenses
Certain active duty Armed Forces Members may deduct certain moving expenses as an adjustment to gross income to the same extent and subject to the same limitations as currently allowed under federal rules with the following exception:
The new job location must be within the State of Alabama.
If you meet the requirements, complete and attach Federal Form 3903 to figure the amount of moving expenses. Enter the total and the new job location as indicated on line 3.
Line 4
# Deduction
Premiums paid for self-employed health insurance are deductible as an adjustment to income from "All sources" in Column B to the same extent as determined in accordance with the Internal Revenue Code Section 162.
The amount deductible in Column C is limited to premiums paid based on the percentage of Alabama self-employment income to total self-employment income.
Line 6
# Alimony
Enter the total amount of alimony paid as shown on your federal return.
You can deduct payments of alimony or separate maintenance made under a court decree to the same extent allowed for federal income tax purposes. Do not deduct lump-sum cash or property settlements, voluntary payments not made under a court order or a written separation agreement or amounts specified as child support.
Line 2
# Adoption Expenses
Enter the total amount of adoption expenses you paid or incurred.
The reasonable medical and legal expenses paid or incurred by a nonresident taxpayer in connection with the adoption of a minor may be deducted. The term "medical expenses" include any medical and hospital expenses of the adoptee and the adoptee's biological mother which are incident to the adoptee's birth, and subsequent medical care and which, in the case of the adoptee, are paid or incurred before the petition is granted. Adoption agency fees are not deductible. The expenses allowed in your 2025 return are limited to those expenses paid or incurred on or after January 1, 2025, even though adoption proceedings may have begun before this date.
Page 2, Part IV
# Federal Income Tax Deduction
The federal income tax allowed as a deduction to a nonresident of Alabama is the amount calculated using the federal income tax deduction worksheet on page 27. The balance is then prorated by the percentage of income earned in Alabama to the total income from all sources. Self-Employment, Social Security, and Medicare taxes can only be claimed if you itemize deductions on Schedule A.
If you filed a joint federal return and have elected to file a separate Alabama Return, you must complete all lines in Part IV to determine your allowable deduction. If you are single or married and filing a joint Alabama Return with your spouse, you should skip lines 1 through 3.
If you are a nonresident alien with income earned in Alabama, the deduction for Federal Income Tax should be computed by applying the ratio of Alabama source income to total income received from sources within the United States. In other words, in the case of a nonresident alien, total income from all sources does not include foreign source income that is not required to be reported for Federal Income Tax purposes.
Alabama income is determined for nonresident aliens in the same manner as for other nonresidents.
# Line 1
Enter your joint federal adjusted gross income.
Line 2
Enter your federal adjusted gross income.
Line 3
Divide line 2 by line 1.
Line 4
Enter federal income tax liability from line 6 of Federal Income Tax Deduction Worksheet on page 27.
Line 5
Enter percentage from line 3 if you completed lines 1 through 3. Multiply line 4 by the percentage on line 3.
PLEASE NOTE: The Federal line references were correct at the time these forms and instructions were printed. However, there may have been changes to Federal forms after our print deadline and the line numbers referenced for our forms may have changed. If you have questions as to the correct line number on the Federal return, please feel free to call one of our taxpayer service centers listed on page 3.
Line 6
Enter percentage from page 1, line 10.
Line 7
If you completed lines 1-3 above, multiply line 5 by the percentage on line 6. Otherwise, multiply line 4 by the percentage on line 6.
Page 2, Part V
# Dependents
Before completing this section, see page 9 of these instructions for the definition of a dependent. Schedule DS must be finished first and attached to your return to take the deduction for dependents. Please follow the line-by-line instructions on Form 40NR to complete this section.
Page 2, Part VI
# General Information
ALL TAXPAYERS MUST
COMPLETE THIS SECTION
Please follow the line-by-line instructions on Form 40NR to complete this section.
# SECTION
4 Information
# General
This section contains general information about items such as amending your tax return, how long to keep records, filing a return for a deceased person, and when you should receive your refund.
Substitute Tax Forms
You may not use your own version of a tax form unless it meets the requirements of the Alabama Department of Revenue. All privately designed and printed substitute tax forms must be approved by the Alabama Department of Revenue.
# Penalties and Interest
Interest. Interest is charged on taxes not paid by their due date even if an extension of time is granted.
If your return is not filed by the due date and you owe additional tax, you should add interest from the due date of the federal return to date of payment.
Submit payment of the tax and interest with your return. Alabama law provides that the same rate of interest shall be collected as currently prescribed by the Internal Revenue Service. Any of the Alabama Taxpayer Service Centers listed in this booklet will provide you the current rate of interest in effect at the time your return is filed.
Failure To Timely File Return. Alabama law provides a penalty of 10% of the tax due or $50, whichever is greater, if the return is filed late. The penalty does not apply to a tax return filed indicating no tax due or a refund.
Failure To Timely Pay Tax. The penalty for not paying the tax when due is 1% of the unpaid amount for each month or fraction of a month that the tax remains unpaid. The maximum penalty is 25%.
Underpayment Penalty. If the amount you owe for 2025 is $500.00 or more you may owe the penalty for 2025 if the total of your withholding and timely estimated tax payments did not equal at least the smaller of:
- 90% of your 2025 tax (66-2/3% for farmers), OR
- 100% of your 2024 tax. (Your 2024 tax return must cover a 12-month period.) Use Form 2210AL to calculate the penalty.
Note: If you include interest, a failure to timely file, or a failure to timely pay penalty with your payment, identify and enter these amounts in the bottom margin of Form 40NR, page 1. Refer to form 2210AL for instructions on how to calculate the underpayment penalty.
Other Penalties. There are also penalties for underpayment due to negligence, underpayment due to fraud, and filing a frivolous return.
Any person failing to file a return as required by Alabama law or rendering a false or fraudulent return will be assessed. The assessment will be based on the best information obtainable by the department with respect to the income of the taxpayer. In the case of a willfully false or fraudulent return having been rendered, the department shall add a penalty of not more than 50% of such tax. This penalty is in addition to any interest due as described above.
Criminal Liability. Section 40-29-112, Code of Alabama 1975, as amended, provides for a more severe penalty for not filing tax returns. Any person required to file a return under this title who willfully fails to make such return shall be guilty of a misdemeanor and, upon conviction thereof, shall be fined not more than $25,000 or imprisoned not more than one year, or both. Section 40-29-110 provides that any person who willfully attempts to evade any tax imposed by this title or the payment thereof shall be guilty of a felony and, upon conviction thereof, shall be fined not more than $100,000 or imprisoned for not more than five years, or both. These penalties are in addition to any other penalties provided for by Alabama law.
Address Change
If you move after filing your return you should notify the Department of Revenue by sending a Change of Address Form available on the Department's website under the Forms link to:
Income Tax Administration Division
P.O. Box 327410
Montgomery, AL 36132-7410.
Corresponding With
Alabama Department of Revenue
Be sure to include your social security number and phone number in any correspondence with the Alabama Department of Revenue.
How Long Should
# Records Be Kept?
Keep records of income, deductions, and credits shown on your return, as well as any worksheets used to figure them, until the statute of limitations runs out for that return. Usually this is three years from the date the return was filed. If income that should have been reported was not reported and the income omitted is in excess of 25% of the stated income, the period of limitation does not expire until six (6) years after the due date of the return or six (6) years after the date the return was filed, whichever is later. There is no period of limitation when a return is false or fraudulent, or when no return is filed.
Also, keep copies of your filed tax returns as part of your records. You should keep some records longer than the period of limitation. For example, keep property records (including those on your own home) as long as they are needed to figure the basis of the original or replacement property. Copies of your tax returns will help in preparing future returns, and they are necessary if you file an amended return. Copies of your returns and your other records may be helpful to your survivor, or the executor or administrator of your estate.
Requesting a Copy of Your Tax Return
If you need a copy of your tax return or tax account information use Form 4506-A, Request for Copy of Tax Form or Income Tax Account Information. The charge for a copy of a return is $5. There is no charge for tax account information.
# Amended Return
If you have already filed a return and become aware of any changes to income, deductions or credits, you should file an amended tax return. You should file a completed Alabama Individual Income Tax Return with the "Amended" box checked. A detailed explanation page of all the changes made should be attached to the tax return.
Note: If your State return is changed for any reason, it may affect your federal income tax liability. This includes changes made as a result of an examination of your return by the Alabama De part ment of Revenue. Contact the Internal Revenue Service for more information.
# Death of Taxpayer
If a taxpayer died before filing a return, the taxpayer's spouse or personal representative must file a return for the person who died if they were required to file a return. A personal representative can be an executor, administrator, or anyone who is in charge of the taxpayer's property.
The person who files the return should check the box indicating which taxpayer is deceased and provide the date of death in the space provided. A copy of the death certificate must also be attached to the return.
If the taxpayer did not have to file a return but had tax withheld, a return must be filed to receive a refund.
If your spouse died within the tax year, you can file a joint return even if you did not remarry. You can also file a joint return if your spouse died before filing the return. A joint return should show both your and your spouse's income during the tax year. Also, write "Filing as surviving spouse" in the area where you sign the return. If someone else is the personal representative, he or she must also sign.
If you are claiming a refund as a surviving spouse filing a joint return with the deceased and you follow the above instructions, no other form is needed unless you receive a joint refund check and the refund check should be reissued in your name only. In such case, you will need to file Form 1310A.
Form 1310A is used when you are a surviving spouse requesting reissuance of the refund check in your name only, a court-appointed or certified personal representative and did not file paperwork with decedent's original return, or any other person claiming the refund for the decedent or on behalf of the decedent's estate.
# Payment of Estimated Tax
Every individual who reasonably expects to owe at least $500 in 2026 is required to file and pay estimated tax.
Note: If the TOTAL ESTIMATED TAX for 2026 is less than five hundred dollars ($500), an estimate is not required to be paid.
The procedures for filing and paying estimated tax and the due dates are similar to Federal Income Tax Law. Do not include payment of your estimated tax with the payment for tax due on your individual return because the quarterly voucher and remittance MUST be mailed separately. Additional instructions for filing your estimate are on the back of Form 40ES.
No refund will be made for any estimated taxes paid except when such amount is taken as a credit on an income tax return filed at the end of the taxable year by the payor or his authorized representative, or on an amended income tax return if the full amount paid is not claimed on the original income tax return.
# Automatic Extension
If you know you cannot file your return by the due date, you do not need to file for an extension. You will automatically be granted an extension until October 15, 2026. If you anticipate that you will owe additional tax on your return, you should submit your payment with a payment voucher (Form 40V) by the due date of the federal return.
Except in cases where taxpayers are abroad, no extension will be granted for more than 6 months.
An extension means only that you will not be assessed a penalty for filing your return after the due date. Interest on the additional tax due from the due date of the return and any penalties will be assessed if applicable to your return.
# Setoff Debt Collection
If you owe money or have a delinquent account under any of the following public assistance programs, your refund may be applied to offset that debt:
Any and all of the public assistance programs administered by the Alabama Department of Human Resources including the Child Support Act of 1979, Chapter 10 of Title 38.
Any and all of the assistance programs administered by the Alabama Medicaid Agency.
Overpayment of unemployment compensation.
Any and all unpaid debt submitted by local governmental entities.
Any and all court fees/fines owed to the Administrative Office of Courts.
If the Alabama Department of Human Re- sources, the Alabama Department of Labor, the Administrative Office of Courts, or the Alabama Medicaid Agency notifies the Alabama Department of Revenue that you have a delinquent account in excess of $25, part or all of your refund may be applied to offset that debt. If you are married and filing a joint return, the joint refund may be applied to offset any of these debts.
IMPORTANT: If you have been assessed taxes from a prior year, your current year refund will be applied to that debt even if the liability resulted from a jointly filed return.
Federal Refund
Offset Program
Your 2025 federal or state refund will be taken to satisfy any outstanding liabilities owed to the State of Alabama or to the Internal Revenue Service.
When Should I
# Receive My Refund?
If you are due a refund, it will be mailed to you at the earliest possible date. Normally, it takes up to 90 days to process your return and get your refund to you. The earlier you file your return the sooner you will receive your refund.
If you do not receive your refund within 90 days of the due date or within 90 days after you file your return, whichever is later, the state will pay you interest and include it with your refund.
It may take longer than 90 days to process your refund if it is incomplete or incorrect. Your refund may be delayed for the following reasons:
Your name and/or address is incorrect.
Your social security number is incorrect or not shown in the space provided.
You failed to attach all of your withholding statements (W-2 Forms).
You failed to attach one or more of the supporting schedules.
You made an error in figuring your return.
You mailed your return to the wrong address.
You filed more than one return.
You submitted a copy instead of the original return.
You have not paid all taxes due for a prior year.
The Department needs additional information to explain the income or deductions reported on your return.
The Alabama Department of Human Re sources has notified the Alabama Department of Revenue that your account is delinquent on a debt repayment, or any public assistance program (including the Child Support Act of 1979, Chapter 10, Title 38). Note: See Setoff Debt Collection on this page for further information.
Your return was not properly signed.
If you are due a refund and discover, after mailing your return, that you failed to attach your withholding statement(s) or supporting sched ule(s) to your return, do not mail this information until the Department requests it. If you mail it before the Department notifies you, your refund may be further delayed.
The Department requests that you wait 90 days before inquiring about your refund. If you do not receive it within 90 days, go to www.revenue. alabama.gov, click on "Where's My Refund," or complete Form IT:489. This form may be obtained from the Department's website under the Forms link or from any of our Alabama Taxpayer Service Centers listed on page 3 of this booklet. If you find it necessary to call about your refund, you should have a copy of your return in front of you.
# SECTION
5 Schedules for
Instructions For
Schedule A
# Itemized Deductions
Changes You Should Note
The itemized deductions you may claim on your Alabama return are similar to the deductions allowed for federal purposes; however, certain items may be treated differently. Please see the instructions which follow for an explanation of these differences.
Purpose of Schedule
Some taxpayers should itemize their deductions because they will save money. See Itemized or
Standard Deduction on page 8.
If you itemize, you can deduct part of your medical and dental expenses, certain taxes, contributions, and certain miscellaneous deductions. A nonresident of Alabama must prorate these deductions by the ratio of Alabama adjusted gross income to total adjusted gross income from all sources. Unreimbursed business expenses may be deducted if the business expenses were incurred while earning Alabama income.
Married, Filing Separate Returns. If married and filing separate returns, both spouses must claim the same deduction unless the spouses have lived apart for the entire year, in which case each spouse may claim either deduction. However, neither spouse may claim a deduction for expenses paid by the other.
Part-Year Residents and Part-Year Non resi- dents. If you were a resident of Alabama for a part of 2025 and you are required to file Form 40, you may claim only the itemized deductions you actually paid while a resident of Alabama.
If you had income from Alabama sources during the period you were not a resident of Alabama you should also file Form 40NR. You should claim on your nonresident return only the itemized deductions actually paid during the period you were a nonresident.
Lines 1 through 4
# Medical and Dental Expenses
Before you can figure your total medical and dental expenses, you must complete your Form 40NR, page 1, lines 1-12.
Medical and dental expenses are allowed as itemized deductions to the same extent as allowed for federal purposes with the following exception:
You may deduct only that part of your medical and dental expenses that is more than 4% of the amount on Form 40NR, line 12, Column B.
Do not include in medical and dental expenses insurance premiums paid by an employer-sponsored health insurance plan (cafeteria plan). You can deduct self-employment health insurance premiums to the same extent as federal purposes.
# Line 1
Enter the total of your medical and dental expenses after reducing these expenses by any payments received from insurance or other sources.
Include amounts you paid for doctors, dentists, nurses, hospitals, prescription medicines and drugs, or insulin. Also, include the total amount you paid for insurance premiums for medical and dental care, amounts paid for transportation and lodging, and other expenses such as hearing aids, dentures, eyeglasses, and contact lenses.
If your insurance company paid your doctor or dentist directly for part of your medical expenses, and you paid only the amount that remained, include in your medical expenses ONLY the amount you paid.
If you received a reimbursement in 2025 of prior year medical or dental expenses, do not reduce your 2025 expenses by this amount. You must include the reimbursement in income on Form 40NR, page 2, Part I, line 8 if you deducted the medical expense in the earlier year and the deduction reduced your tax. Federal Pub. 502 tells you how to figure the amount to include in income.
When figuring the deduction, you may include medical and dental bills you paid for:
Yourself.
Your spouse.
All dependents claimed on your return.
Your child whom you do not claim as a dependent because of the federal rules explained for
Children of Divorced or Separated Parents.
Examples of Medical and Dental Payments You CAN Deduct To the extent you were not reimbursed, you can deduct what you paid for:
Medicare Part B insurance.
Prescription medicines and drugs, or insulin.
Premiums paid to private insurers for additional Medicare coverage.
Medical doctors, dentists, eye doctors, chiropractors, osteopaths, podiatrists, psychiatrists, psychologists, physical therapists, acupuncturists, and psychoanalysts (medical care only).
Medical examinations, X-ray and laboratory services, insulin treatment, and whirlpool baths the doctor ordered.
If you pay someone to do both nursing and housework, you can deduct only the cost of the nursing help.
Hospital care (including meals and lodging), clinic costs, and lab fees.
Medical treatment at a center for drug addicts or alcoholics.
Cost of a weight-loss program for the purpose of treating diagnosed obesity or another recognized disease. Cost must be out-of-pocket and uncompensated.
Medical aids such as hearing aid batteries, braces, crutches, wheelchairs, guide dogs, and the cost of maintaining them.
Lodging expenses (but not meals) paid while away from home to receive medical care in a hospital or a medical care facility that is related to a hospital. Do not include more than $50 a night for each eligible person.
Ambulance service and other travel costs to get medical care. If you used your own car, you can claim what you spent for gas and oil to go to and from the place you received medical care, or you can claim the federal mileage rate. Add parking and tolls to the amount you claim under either method.
# Payments You CANNOT Deduct
Premiums paid by an employer-sponsored health insurance plan (cafeteria plan).
The basic cost of Medicare Insurance (Medi care A). Note: If you were 65 or older but not entitled to social security benefits, you may deduct premiums you voluntarily paid for Medicare A coverage.
Life insurance or income protection policies.
The 1.45% Medicare (hospital insurance benefits) tax withheld from your pay as part of the Social Security tax, or the Medicare tax paid as part of social security self-employment tax.
Nursing care for a healthy baby.
Illegal operations or drugs.
Nonprescription medicines or drugs.
Travel your doctor told you to take for rest or change.
Funeral, burial, or cremation costs.
Federal Pub. 502 has a discussion of expenses that may and may not be deducted. It also explains when you may deduct capital expenditures and special care for handicapped persons.
Lines 5 through 9
# Income Tax) You CAN Deduct
If deductions are itemized, you CAN DEDUCT the following taxes:
Real estate taxes, Personal property taxes and Generation-Skipping transfer taxes are allowable as itemized deductions to the same extent as currently allowed for federal purposes under 26 U.S.C. 164.
However, when determining any limitations, you must use Alabama (not Federal) adjusted gross income.
Real estate taxes (line 5). Include taxes you paid on property you own in any state that was not used for business. If you pay real estate taxes as part of your mortgage payments do not take a deduction for that amount. Deduct the taxes in the year the mortgage company actually paid them to the taxing authority.
FICA tax (Social Security and Medicare) (line 6). You can deduct the FICA tax (Social Security and Medicare) withheld on your income by your employer. If you worked for more than one employer resulting in more than the maximum FICA tax being withheld, the excess amount claimed as Federal Income Tax Withheld on your federal return cannot be claimed as an itemized deduction on your Alabama return.
Federal Self-Employment Taxes (line 6). You can deduct the Federal Self-Employment Tax you paid during the year 2025 for the tax year 2024 and/or prior years.
Railroad Retirement Tax (line 7). You can deduct the railroad retirement tax you paid in
- Only your contribution to tier one railroad retirement is deductible as an itemized deduction. Other taxes (line 8). In addition to the above taxes, you can also deduct:
(a) City, County, and Occupational Tax, as shown on your W-2.
(b) State Unemployment Insurance Tax (S.U.I.).
Employees were not required to pay S.U.I.
Tax in 2025 since the full amount was paid by their employer. However, if S.U.I. Tax was paid to a state other than Alabama, it may be deducted.
(c) Federal gift taxes. Federal gift taxes are deductible only if you are the person making the gift and you paid the tax. (The person receiving the gift cannot claim this deduction even though he paid the tax.)
(d) Personal property taxes. This tax must be based on the value alone. For example, if part of the fee you paid for the registration of your car was based on the car's value and part was based on its weight, you can deduct only the part based on value.
(e) Generation-Skipping Transfer (GST) taxes.
Generation-Skipping transfer taxes imposed on income distributions by 26 U.S.C. 2601 are deductible if you paid or accrued the taxes within the taxable year.
Taxes You CANNOT Deduct include but are not limited to State income taxes. If you owe taxes to the State of Alabama, you may be entitled to a credit against the taxes you owe to the state of which you are a legal resident. See instructions for that state.
State and local sales taxes.
Income tax you paid to a foreign country.
Taxes you paid for another person.
License fees (marriage, driver's, dog, hunting, pistol, etc.).
Civil Service Retirement contributions (State or Federal).
Federal excise tax on personal property, transportation, telephone, and gasoline.
Customs duties.
Gasoline tax.
State utility taxes.
Tax on liquor, beer, wine, cigarettes, and tobacco.
Car inspection fees.
Taxes you paid for your business or profession.
(Use Schedule C, E, or F to deduct these business expenses.) Assessments for sidewalks or other im prove- ments to your property.
Lines 10a through 14
# Interest You Paid
The interest you paid that can be claimed as an itemized deduction is limited in most cases to the same amount as currently allowable for federal purposes.
You should show on Schedule A interest you paid on nonbusiness items only. Whether your interest expense is treated as investment interest, personal interest, or business interest depends on how and when you used the loan proceeds.
Note: Personal interest is no longer deductible.
Complete and attach Alabama Form 4952A if you are claiming investment interest as an itemized deduction.
If you qualify for the mortgage interest credit on your federal return, the total interest you paid (before the credit) is deductible for Alabama purposes.
Vehicle Loan Interest. Effective for 2025 through 2028, individuals may deduct interest paid on a loan used to purchase a qualified vehicle, provided the vehicle is purchased for personal use and meets other eligibility criteria. (Lease payments do not qualify.) The tax deduction phases out for single taxpayers with modified adjusted gross income that exceeds $100,000 (or $200,000 for married taxpayers filing jointly). Final assembly of the automobile must have been completed in the United States. The interest must be paid on a loan that originated after December 31, 2024, was used to purchase a vehicle originally used by the taxpayer and secured by alien on the vehicle. Enter the date new vehicle was purchased, the vehicle VIN and amount of vehicle loan interest on lines 11a and/or 11b on Schedule
A. If you have more than 2 qualified vehicles, please create a separate spreadsheet with the same fields as lines 11a and 11b and enter "Statement attached" in the vehicle VIN field on 11a. Please make sure your spreadsheet is the same size as the Schedule
A. To determine the Qualified vehicle loan interest on line 11c, please complete the Qualified Vehicle Loan Interest Worksheet on page 27 and enter the amount from line 8 of the worksheet.
For further information describing the interest you may deduct, refer to federal instructions and publications.
Lines 15 through 18
# Gifts to Charity
Contributions are allowable as itemized deductions to the same extent as currently allowed for federal purposes. However, when determining any limitations, you must use adjusted gross income from Column B, line 12.
You can deduct what you gave to organizations that are religious, charitable, educational, scientific, or literary in purpose. You can also deduct what you gave to organizations that work to prevent cruelty to children or animals.
Note: See Federal Pub. 526 for more information
Examples of these organizations are
Churches, temples, synagogues, Salvation Army, Red Cross, CARE, Goodwill Industries, United Way, Boy Scouts, Girl Scouts, Boys and Girls Clubs of America, etc.
Fraternal orders if the gifts will be used for the purposes listed above.
Veteran's and certain cultural groups.
Nonprofit schools, hospitals, and organizations with the purpose of finding a cure for or helping people who have arthritis, asthma, birth defects, cancer, cerebral palsy, cystic fibrosis, diabetes, heart disease, hemophilia, mental illness or retardation, multiple sclerosis, muscular dystrophy, tuberculosis, etc.
Federal, state, and local governments if the gifts are solely for public purposes.
If you contributed to a charitable organization and also received a benefit from it, you can deduct only the amount that is more than the benefit you received. If you do not know whether you can deduct what you gave to an organization, check with that organization or with the IRS.
# Contributions You MAY Deduct
Contributions may be in cash (keep canceled checks, receipts, or other reliable written records showing the name of the organization and the date and amount given,) property, or out-of-pocket expenses you paid to do volunteer work for the kinds of organizations described above. If you drove to and from the volunteer work, you may take 14 cents a mile or the actual cost of gas and oil. Add parking and tolls to the amount you claim under either method. (But don't deduct any amounts that were repaid to you.)
# Contributions
Travel expenses (including meals and lodging) while away from home unless there was no significant element of personal pleasure, recreation, or vacation in the travel.
Political contributions.
Dues, fees, or bills paid to country clubs, lodges, fraternal orders, or similar groups.
Value of any benefit, such as food, entertainment, or merchandise that you received in connection with a contribution to a charitable or gan i zation.
Example. You paid $100 to a charitable organization to attend a fundraising dinner. To figure the amount of your deductible charitable contribution, subtract the value of the dinner from the total amount you paid. If the value of the dinner was $40, your deductible contribution is $60.
Cost of raffle, bingo, or lottery tickets.
Cost of tuition.
Value of your time or services.
Value of blood given to a blood bank.
The transfer of a future interest in tangible personal property (generally, until the entire interest has been transferred.) Gifts to: a. Individuals. b. Foreign organizations. c. Groups that are run for personal profit. d. Groups with the purpose of lobbying for changes in the laws. e. Civic leagues, social and sports clubs, labor unions, and chambers of commerce.
Record Keeping. If you gave property, you should keep a receipt or written statement from the organization you gave the property to, or a reliable written record that shows the organization's name and address, the date and location of the gift, and a description of the property. You should also keep reliable written records for each gift of property that include the following information: a. How you figured the property's value at the time it was given. (If the value was determined by an appraisal, you should also keep a signed copy of the appraisal.) b. The cost or other basis of the property if you must reduce it by any ordinary income or capital gain that would have resulted if the property had been sold at its fair market value. c. How you figured your deduction if you chose to reduce your deduction for gifts of capital gain property. d. Any conditions attached to the gift.
Note: If your total deduction for gifts of property is over $500, or if you gave less than your entire interest in the property, or you made a "qualified conservation contribution" under Federal Section 170(h), your records should contain additional information.
See Federal Pub. 526 for details.
Line 15
Enter the total contributions you made in cash or by check (including out-of-pocket expenses).
Line 16
Enter the contributions of property. If you gave used items such as clothing or furniture, deduct their fair market value at the time you gave them. Fair market value is what a willing buyer would pay a willing seller when neither has to buy or sell and both are aware of the conditions of the sale. If the amount of your deduction is more than $500, you must complete and attach Federal Form 8283, Noncash Charitable Contributions. If your total deduction is over $5,000, you may also need appraisals of the values of the donated property. For this purpose, the "amount of your deduction" means your deduction BEFORE applying any income limitations that could result in a carryover of contributions. See Federal
Form 8283 and its instructions for details.
Line 17
Enter any carryover of contributions that you were unable to deduct in an earlier year because it exceeded your adjusted gross income limit.
Line 19
# Qualified Long-term Care Coverage
Premiums paid pursuant to a qualifying insurance contract for qualified long term care coverage paid by the taxpayer may be deducted on line 19.
Qualified long-term care services include care for necessary diagnostic, preventive, therapeutic, and rehabilitative services and maintenance or personal care services which are required by a chronically ill individual in a qualified facility or services which are provided pursuant to a place of care prescribed by a licensed health care practitioner.
Line 20
# Limit
Most miscellaneous deductions cannot be deducted in full, but must be reduced by 2% of the Alabama adjusted gross income. The deductions which may be claimed on line 20 that are NOT subject to the 2% limit are as follows:
Gambling losses to the extent of gambling winnings. Report gambling winnings on Form 40NR, page 2, Part I, line 8.
Unrecovered investment in a pension.
Impairment-related work expenses of a disabled person.
List the type and amount of each expense. Enter one total in the amount space for line 20.
Line 21
# Proration of Above Amounts
The amounts shown in lines 1 through 20 should be the amounts for the entire period that the return covers. In most cases, these amounts will be the same as shown on your Federal return. Follow the instructions on lines 21 through 23 to determine the portion of these expenses that apply to your Alabama income.
Lines 24a, b, and c
# Casualty and Theft Losses
A casualty or theft loss is determined in the same manner as determined on your federal return with the following exceptions:
A nonresident of Alabama may deduct only those losses where the property was located in Alabama at the time of loss.
The loss may be claimed only in the year during which the loss occurred or the theft was discovered.
The loss on personal property must be reduced by 10% of the Alabama adjusted gross income as shown on Form 40NR, page 1, line 12, column C.
Use lines 24a, b, and c to report casualty or theft losses of Alabama property that is not a trade or business, income-producing, or rent or royalty property. Complete and attach Federal Form 4684 to figure your loss. Enter on line 24a of Alabama Schedule A the amount of loss as shown on Section A line 15 or line 16 of Form 4684.
# Losses You MAY Deduct
You may be able to deduct all or part of each loss caused by theft, vandalism, fire, storm, and car, boat, and other accidents or similar causes. You may also be able to deduct money you had in a financial institution but lost because of the insolvency or bankruptcy of the institution.
You may deduct nonbusiness casualty or theft losses only to the extent that: a. the amount of EACH separate casualty or theft loss is more than $100, and b. the total amount of ALL Alabama losses during the year is more than 10% of your adjusted gross income on Form 40NR, page 1, line 12, column C.
Special rules apply if you had both gains and losses from nonbusiness casualties or thefts. Get
Federal Form 4684 for details.
# Losses You MAY NOT Deduct
Money or property misplaced or lost.
Breakage of china, glassware, furniture, and similar items under normal conditions.
Progressive damage to property (buildings, clothes, trees, etc.) caused by termites, moths, other insects, or disease.
Use Schedule A line 26 to deduct the costs of proving that you had a property loss. (Examples of these costs are appraisal fees and photographs used to establish the amount of your loss.)
For more details, refer to federal instructions and publications.
Lines 25 through 29
# Expenses Subject to the 2% Limit
Most miscellaneous deductions cannot be deducted in full. You must subtract 2% of your Alabama adjusted gross income from the total. You figure the 2% limit on line 28.
A nonresident of Alabama should show on lines 25 through 29 only those expenses incurred in earning Alabama income.
Generally, the 2% limit applies to job expenses you paid for which you were not reimbursed (line 25). The limit also applies to certain expenses you paid to produce or collect taxable income (line 26).
See the instructions for lines 25 and 26 for examples of expenses to deduct on these lines.
The 2% limit does not apply to certain other miscellaneous expenses that you may deduct. See the instructions for line 20 for examples of these expenses.
Line 25
Use this line to report Alabama job expenses you paid for which you were not reimbursed. In some cases, you must first fill out Federal Form 2106, Employee Business Expenses. Fill out Form 2106 if:
- You claim any travel, transportation, or meal expenses for your job; OR
- Your employer paid you for any of your job expenses reportable on line 25.
If 1 or 2 above applies, enter the net deductible amount from Federal Form 2106 on line 25 of Schedule A.
Caution: Federal Form 2106 must be adjusted to include only job expenses related to your Alabama source income.
If you do not have to fill out Form 2106, just list the type and amount of your expenses on the space provided on line 25. If you need more space, attach a statement showing the type and amount of the expense. Enter one total in the amount space on line 25.
Examples of expenses to include on line 25 are:
Travel, transportation, or meal expense. (Note: If you have any of these expenses, you must use
Federal Form 2106 for all your job expenses.)
Union dues.
Safety equipment, small tools, and supplies you used in your job.
Uniforms your employer said you must have and which you may not usually wear away from work.
Protective clothing required in your work such as hard hats, safety shoes, and glasses.
Physical examinations your employer said you must have.
Dues to professional organizations and chambers of commerce.
Subscriptions to professional journals.
Fees to employment agencies and job search expenses in your present occupation.
Education expenses you paid that were required by your employer, or by law or regulations, to keep your salary or job. In general, you may include the cost of keeping or improving skills you must have in your job. For more details, see Federal Pub. 508, Educational Expenses. Some educational expenses are not deductible. See
Expenses You MAY NOT Deduct.
Business use of part of your home, but ONLY if you use that part exclusively and on a regular basis in your work and for the convenience of your employer. For details, including limits that apply, see Federal Pub. 587, Business Use of Your Home.
Line 26
Use this line for amounts you paid for the production or collection of taxable income; for the management, conservation, or maintenance of property held for the production of taxable income; or in connection with the determination, collection, or refund of any tax. List the type and amount of each expense in the space provided on line 26. If you need more space, attach a statement showing the type and amount of each expense. Enter one total in the amount space for line 26. Examples of these expenses are:
Tax return preparation fee.
Safe deposit box rental.
Certain legal and accounting fees.
Clerical help and office rent.
Custodial (e.g., trust account) fees.
Your share of the investment expenses of a regulated investment company.
Certain losses on nonfederally insured deposits in an insolvent or bankrupt financial institution.
For more information (including limits on the amount you can deduct).
# Expenses You MAY NOT Deduct
Some expenses are not deductible at all. Examples are:
Political contributions.
Personal legal expenses.
Lost or misplaced cash or property (but see Casualty and Theft Losses.) Expenses for meals during regular or extra work hours.
The cost of entertaining friends.
Expenses of going to or from work.
Education that you need to meet minimum requirements for your job or that will qualify you for a new occupation.
Expenses of: a. Travel as a form of education. b. Attending a seminar, convention, or similar meeting unless it is related to your employment.
Fines and penalties.
Note: Excess deductions from decedent's estate and irrevocable trust cannot be claimed. See Code of Alabama 40-18-25(4)
Instructions For
Schedule B
# Interest and Dividend Income
Purpose of Schedule
Use Schedule B if you are filing Form 40NR and had more than $1,500 in interest and dividend income in 2025.
Mutual Fund. If you received a 1099-DIV, or 1099-INT, or Substitute Statement from a mutual fund or brokerage firm, you must include the total interest or dividends shown on that form on Schedule B, line 1.
Nonresidents are required to report interest or dividend income with an Alabama business legal jurisdiction in Schedule B, Column C (Regulation 810-3-14-.05). All other personal interest or dividend income received in 2025 that would be taxable to a resident of Alabama should be included in the total adjusted gross income from all sources.
# Line 1
Report on line 1 the total interest and dividends you received in 2025. This does not include interest reported on your Schedule K-1.
Lines 2 and 3
A resident of Alabama is not taxed on interest received from the following sources:
- Obligations of the United States or any of its possessions.
- Obligations of the State of Alabama.
- Obligations of county, municipality or other subdivision of Alabama.
If you received income from any of these sources, list the source and amount(s) on lines 2a through 2d. Add the amounts on these lines and enter the total on line 3.
Instructions For
Schedule D
# Real Estate, Stocks, Bonds, Etc.
Purpose of Schedule
Use Schedule D (Form 40NR) to report the sale or exchange of real estate, stocks, bonds, and other assets.
Mutual Fund. If you received a mutual fund or brokerage statement reporting capital or ordinary gains, you must include these amounts on Schedule D, on line 1.
The gain or profit from any sale, exchange, or other disposition by a nonresident of real or tangible property located in Alabama is taxable even though it is not connected with a business carried on in this state.
The gain or (loss) realized from the disposition of property located outside of Alabama is not taxable to a nonresident, but the gain or (loss) must be included in the total adjusted gross income from all sources in order to compute the ratio of Alabama adjusted gross income to total adjusted gross income from all sources.
The gain or profit of a nonresident from the sale, exchange, or other disposition of intangible personal property including stocks, bonds, and other securities, is ordinarily not taxable and should not be included in gross income except to the extent that such intangible personal property has acquired a business legal jurisdiction in Alabama. Likewise, losses sustained from the sale, ex change, or other disposition of such property are not deductible except to the extent that they are losses incurred in a business carried on within Alabama by the nonresident taxpayer.
Gain from Sale of Personal Residence. If you sold your personal residence, any gain realized is taxable to the same extent as reported on your federal return. If the personal residence was not located in Alabama, the gain should be reported in Column B only. If the personal residence was located in Alabama, the gain should be reported in Columns B and
C. A loss sustained on the sale of a personal residence is NOT deductible.
If a taxpayer elects to determine gain under 26 USC 1033 (relating to involuntary conversions), the amount of gain recognized for Alabama purposes shall be determined in accordance with the same federal statute.
# Line 1
Enter on line 1, the total gain or (loss) from the sale of all assets not subject to Alabama tax.
Line 2
The gain from the sale of all Alabama assets should be reported in detail in Columns a through f.
If more space is needed, use separate sheets with identical Column headings.
Instructions For
Schedule E
# Supplemental Income
Part I Lines 1 through 5
# Rents and Royalties
If you received rent from property owned or controlled by you, or royalties from copyrights, mineral leases and similar rights, report the total amount received on Schedule E lines 1 through 5. If property other than cash was received as rent, its fair market value should be reported.
A reasonable allowance for the exhaustion, wear and tear, and obsolescence of property used in a trade or business, or of property held by the taxpayer for the production of income, shall be allowable as a depreciation deduction. The allowance does not apply to inventories or stock-in-trade nor to land apart from the improvements or physical development added to it. Federal 179 Depreciation Expense allowed by 26 U.S.C §179 is allowable depreciation for Alabama purposes.
The total net gain from all rents and royalties from sources outside Alabama should be shown on line 1. Income from rents and royalties from property located in Alabama should be detailed in Columns 2a through 2e. If more space is needed, use separate sheets with identical column headings.
The net gain or (loss) from all items listed in lines 1 through 4 should be entered on line 5.
Part II Lines 6 and 7
# S Corporations
Use lines 6 and 7 to report income you received from partnerships, estates, trusts, and S corporations. Alabama taxes income from these sources only to the extent the income was earned in Alabama.
List the income you received from these sources on lines 6a through 6c. Show the name, address, and FEIN of each partnership, estate, trust, etc. Report the total income received from these sources in Column B and only the income earned from Alabama sources in Column C.
Partnerships. If you are a partner of a partnership doing business in Alabama, you should receive an Alabama Schedule K-1 Form 65 from the partnership. Report your share of the income (whether you received it or not) or net loss (not to exceed your basis) of the partnership in Part II. A nonresident must pay tax on his share of Alabama income from the partnership.
Beginning with the 2001 tax year, Alabama law required composite filing for all partnerships with nonresident members. In addition to reporting your share of the partnership's profit or loss on Alabama Schedule E, any composite payments made on your behalf should be shown on Schedule CP. Schedule CP, Section B, line 1 will be entered on Form 40NR, page 1, line 23.
Estates and Trusts. Nonresidents are taxed on income from estates and trusts only to the extent that the income was earned in Alabama. The administrator, executor, or trustee should advise you of the amount to report.
S Corporations. An "Alabama S Corporation" means any domestic corporation or foreign corporation qualified to do business or doing business in Alabama which has in effect an election to be an S corporation under 26 U.S.C. Section 1362.
If you are a shareholder of an Alabama S corporation, you should receive an Alabama Schedule K-1 (Form 20S) from the S corporation. Report your share of the income (whether you received it or not) or net loss (not to exceed your basis) of the corporation in Part II. A nonresident must pay tax on his share of an Alabama S corporation's income.
If you claim credit for taxes paid by an S cor po- ra tion on your behalf, enter this amount on Schedule
CP. Schedule CP, Section B, line 1 will be entered on Form 40NR, page 1, line 23.
The net gain or (loss) from all items listed in lines 6a through 6c should be entered on line 7. Also include these amounts in summary on line 8 of Part
III. See Schedule K-1 65 and Schedule K-1 20S instructions for more information.
Note: A loss from an irrevocable trust cannot be claimed on Schedule E part II. See administrative rule 810-3-25-.05(8)(b)
# Tax Table
(Form 40NR)
At But Single Married least less ✱ filing EXAMPLE: than Married jointly filing
Mr. and Mrs. Brown are filing a joint return and sepachecked box 2 on their return. Their taxable income Based on Taxable Income rately on line 18 of Form 40NR is $23,360. First, they find This tax table is based on the taxable income ✱ Head of the $23,300 - $23,400 income line. Next, they find shown on line 18 of Form 40NR and the filing family the column for married filing jointly and read down status you checked on lines 1, 2, 3, or 4 of your the column. The amount shown where the income return.
Your tax isline and the filing status column meet is $1,088. This $23,000 is the amount they must write on line 19 of Form 40NR.
If If taxable And you are - taxable And you are - income is - income is -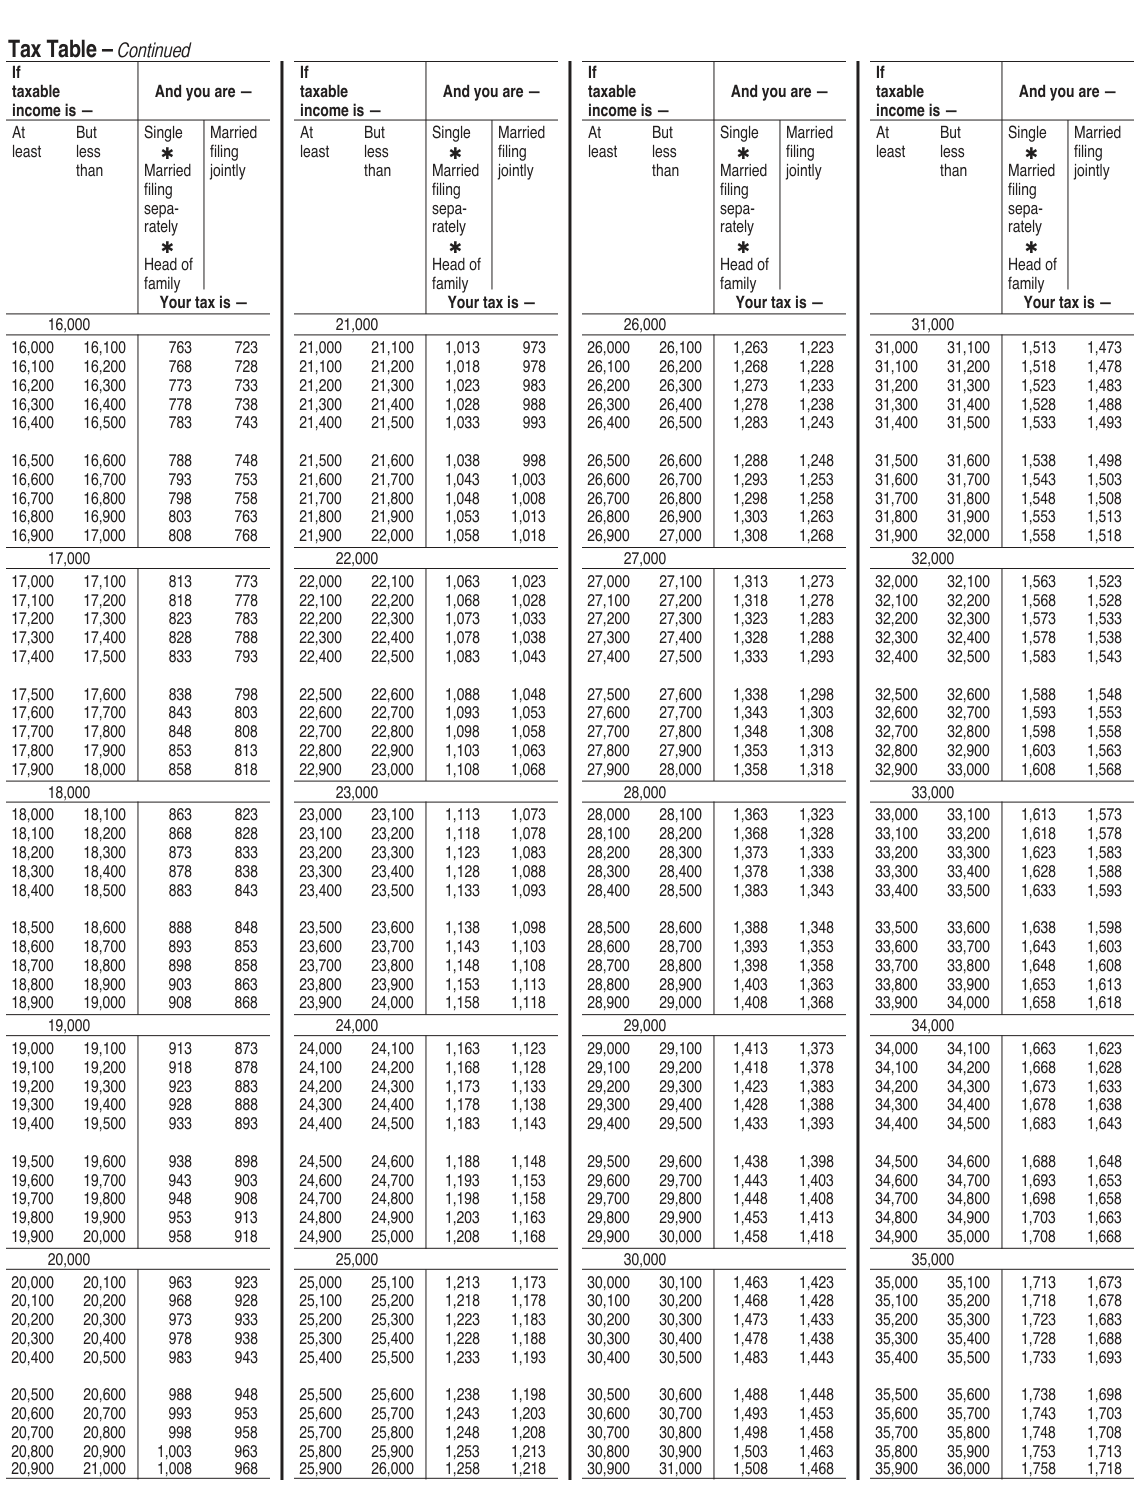
Text version of this table
Tax Tab le – Continued If If If If taxable And you are — taxable And you are — taxable And you are — taxable And you are — income is — income is — income is — income is — At But Single Mar ried At B ut Single Married At B ut Single Married At B ut Single Married least less ✱ filin g least le ss ✱ filing least le ss ✱ filing least le ss ✱ filing than Married joint ly t han Married jointly t han Married jointly t han Married jointly filing filing filing filing sepa- sepa- sepa- sepa- rately rately rately rately ✱ ✱ ✱ ✱ Head of Head of Head of Head of family family family family Your ta x is — Your ta x is — Your ta x is — Your ta x is — 16,0 00 21,0 0 0 26,0 0 0 31,0 0 0 16,000 16,10 0 763 723 21,000 21,100 1,013 973 26,000 26,100 1,263 1,223 31,000 31,100 1,513 1,473 16,100 16,20 0 768 728 21,100 21,200 1,018 978 26,100 26,200 1,268 1,228 31,100 31,200 1,518 1,478 16,200 16,30 0 773 733 21,200 21,300 1,023 983 26,200 26,300 1,273 1,233 31,200 31,300 1,523 1,483 16,300 16,40 0 778 738 21,300 21,400 1,028 988 26,300 26,400 1,278 1,238 31,300 31,400 1,528 1,488 16,400 16,50 0 783 743 21,400 21,500 1,033 993 26,400 26,500 1,283 1,243 31,400 31,500 1,533 1,493 16,500 16,60 0 788 748 21,500 21,600 1,038 998 26,500 26,600 1,288 1,248 31,500 31,600 1,538 1,498 16,600 16,70 0 793 753 21,600 21,700 1,043 1,003 26,600 26,700 1,293 1,253 31,600 31,700 1,543 1,503 16,700 16,80 0 798 758 21,700 21,800 1,048 1,008 26,700 26,800 1,298 1,258 31,700 31,800 1,548 1,508 16,800 16,90 0 803 763 21,800 21,900 1,053 1,013 26,800 26,900 1,303 1,263 31,800 31,900 1,553 1,513 16,900 17,00 0 808 768 21,900 22,000 1,058 1,018 26,900 27,000 1,308 1,268 31,900 32,000 1,558 1,518 17,0 00 22,0 0 0 27,0 0 0 32,0 0 0 17,000 17,10 0 813 773 22,000 22,100 1,063 1,023 27,000 27,100 1,313 1,273 32,000 32,100 1,563 1,523 17,100 17,20 0 818 778 22,100 22,200 1,068 1,028 27,100 27,200 1,318 1,278 32,100 32,200 1,568 1,528 17,200 17,30 0 823 783 22,200 22,300 1,073 1,033 27,200 27,300 1,323 1,283 32,200 32,300 1,573 1,533 17,300 17,40 0 828 788 22,300 22,400 1,078 1,038 27,300 27,400 1,328 1,288 32,300 32,400 1,578 1,538 17,400 17,50 0 833 793 22,400 22,500 1,083 1,043 27,400 27,500 1,333 1,293 32,400 32,500 1,583 1,543 17,500 17,60 0 838 798 22,500 22,600 1,088 1,048 27,500 27,600 1,338 1,298 32,500 32,600 1,588 1,548 17,600 17,70 0 843 803 22,600 22,700 1,093 1,053 27,600 27,700 1,343 1,303 32,600 32,700 1,593 1,553 17,700 17,80 0 848 808 22,700 22,800 1,098 1,058 27,700 27,800 1,348 1,308 32,700 32,800 1,598 1,558 17,800 17,90 0 853 813 22,800 22,900 1,103 1,063 27,800 27,900 1,353 1,313 32,800 32,900 1,603 1,563 17,900 18,00 0 858 818 22,900 23,000 1,108 1,068 27,900 28,000 1,358 1,318 32,900 33,000 1,608 1,568 18,0 00 23,0 0 0 28,0 0 0 33,0 0 0 18,000 18,10 0 863 823 23,000 23,100 1,113 1,073 28,000 28,100 1,363 1,323 33,000 33,100 1,613 1,573 18,100 18,20 0 868 828 23,100 23,200 1,118 1,078 28,100 28,200 1,368 1,328 33,100 33,200 1,618 1,578 18,200 18,30 0 873 833 23,200 23,300 1,123 1,083 28,200 28,300 1,373 1,333 33,200 33,300 1,623 1,583 18,300 18,40 0 878 838 23,300 23,400 1,128 1,088 28,300 28,400 1,378 1,338 33,300 33,400 1,628 1,588 18,400 18,50 0 883 843 23,400 23,500 1,133 1,093 28,400 28,500 1,383 1,343 33,400 33,500 1,633 1,593 18,500 18,60 0 888 848 23,500 23,600 1,138 1,098 28,500 28,600 1,388 1,348 33,500 33,600 1,638 1,598 18,600 18,70 0 893 853 23,600 23,700 1,143 1,103 28,600 28,700 1,393 1,353 33,600 33,700 1,643 1,603 18,700 18,80 0 898 858 23,700 23,800 1,148 1,108 28,700 28,800 1,398 1,358 33,700 33,800 1,648 1,608 18,800 18,90 0 903 863 23,800 23,900 1,153 1,113 28,800 28,900 1,403 1,363 33,800 33,900 1,653 1,613 18,900 19,00 0 908 868 23,900 24,000 1,158 1,118 28,900 29,000 1,408 1,368 33,900 34,000 1,658 1,618 19,0 00 24,0 0 0 29,0 0 0 34,0 0 0 19,000 19,10 0 913 873 24,000 24,100 1,163 1,123 29,000 29,100 1,413 1,373 34,000 34,100 1,663 1,623 19,100 19,20 0 918 878 24,100 24,200 1,168 1,128 29,100 29,200 1,418 1,378 34,100 34,200 1,668 1,628 19,200 19,30 0 923 883 24,200 24,300 1,173 1,133 29,200 29,300 1,423 1,383 34,200 34,300 1,673 1,633 19,300 19,40 0 928 888 24,300 24,400 1,178 1,138 29,300 29,400 1,428 1,388 34,300 34,400 1,678 1,638 19,400 19,50 0 933 893 24,400 24,500 1,183 1,143 29,400 29,500 1,433 1,393 34,400 34,500 1,683 1,643 19,500 19,60 0 938 898 24,500 24,600 1,188 1,148 29,500 29,600 1,438 1,398 34,500 34,600 1,688 1,648 19,600 19,70 0 943 903 24,600 24,700 1,193 1,153 29,600 29,700 1,443 1,403 34,600 34,700 1,693 1,653 19,700 19,80 0 948 908 24,700 24,800 1,198 1,158 29,700 29,800 1,448 1,408 34,700 34,800 1,698 1,658 19,800 19,90 0 953 913 24,800 24,900 1,203 1,163 29,800 29,900 1,453 1,413 34,800 34,900 1,703 1,663 19,900 20,00 0 958 918 24,900 25,000 1,208 1,168 29,900 30,000 1,458 1,418 34,900 35,000 1,708 1,668 20,0 00 25,0 0 0 30,0 0 0 35,0 0 0 20,000 20,10 0 963 923 25,000 25,100 1,213 1,173 30,000 30,100 1,463 1,423 35,000 35,100 1,713 1,673 20,100 20,20 0 968 928 25,100 25,200 1,218 1,178 30,100 30,200 1,468 1,428 35,100 35,200 1,718 1,678 20,200 20,30 0 973 933 25,200 25,300 1,223 1,183 30,200 30,300 1,473 1,433 35,200 35,300 1,723 1,683 20,300 20,40 0 978 938 25,300 25,400 1,228 1,188 30,300 30,400 1,478 1,438 35,300 35,400 1,728 1,688 20,400 20,50 0 983 943 25,400 25,500 1,233 1,193 30,400 30,500 1,483 1,443 35,400 35,500 1,733 1,693 20,500 20,60 0 988 948 25,500 25,600 1,238 1,198 30,500 30,600 1,488 1,448 35,500 35,600 1,738 1,698 20,600 20,70 0 993 953 25,600 25,700 1,243 1,203 30,600 30,700 1,493 1,453 35,600 35,700 1,743 1,703 20,700 20,80 0 998 958 25,700 25,800 1,248 1,208 30,700 30,800 1,498 1,458 35,700 35,800 1,748 1,708 20,800 20,90 0 1,003 963 25,800 25,900 1,253 1,213 30,800 30,900 1,503 1,463 35,800 35,900 1,753 1,713 20,900 21,00 0 1,008 968 25,900 26,000 1,258 1,218 30,900 31,000 1,508 1,468 35,900 36,000 1,758 1,718
# Under $1,000 4,000
0 50 0 0
50 100 1 1 4,000 4,100 163 142
100 200 3 3 4,100 4,200 168 146
200 300 5 5 4,200 4,300 173 150
300 400 7 7 4,300 4,400 178 154
400 500 9 9 4,400 4,500 183 158
500 600 12 11 4,500 4,600 188 162
600 700 16 13 4,600 4,700 193 166
700 800 20 15 4,700 4,800 198 170
800 900 24 17 4,800 4,900 203 174
900 1,000 28 19 4,900 5,000 208 178
1,000 5,000
1,000 1,100 32 22 5,000 5,100 213 182
1,100 1,200 36 26 5,100 5,200 218 186
1,200 1,300 40 30 5,200 5,300 223 190
1,300 1,400 44 34 5,300 5,400 228 194
1,400 1,500 48 38 5,400 5,500 233 198
1,500 1,600 52 42 5,500 5,600 238 202
1,600 1,700 56 46 5,600 5,700 243 206
1,700 1,800 60 50 5,700 5,800 248 210
1,800 1,900 64 54 5,800 5,900 253 214
1,900 2,000 68 58 5,900 6,000 258 218
2,000 6,000
2,000 2,100 72 62 6,000 6,100 263 223
2,100 2,200 76 66 6,100 6,200 268 228
2,200 2,300 80 70 6,200 6,300 273 233
2,300 2,400 84 74 6,300 6,400 278 238
2,400 2,500 88 78 6,400 6,500 283 243
2,500 2,600 92 82 6,500 6,600 288 248
2,600 2,700 96 86 6,600 6,700 293 253
2,700 2,800 100 90 6,700 6,800 298 258 2,800 2,900 104 94 6,800 6,900 303 263 2,900 3,000 108 98 6,900 7,000 308 268 3,000 7,000 3,000 3,100 113 102 7,000 7,100 313 273 3,100 3,200 118 106 7,100 7,200 318 278 3,200 3,300 123 110 7,200 7,300 323 283 3,300 3,400 128 114 7,300 7,400 328 288 3,400 3,500 133 118 7,400 7,500 333 293 3,500 3,600 138 122 7,500 7,600 338 298 3,600 3,700 143 126 7,600 7,700 343 303 3,700 3,800 148 130 7,700 7,800 348 308 3,800 3,900 153 134 7,800 7,900 353 313 3,900 4,000 158 138 7,900 8,000 358 318
If If taxable And you are - taxable And you are - income is - income is -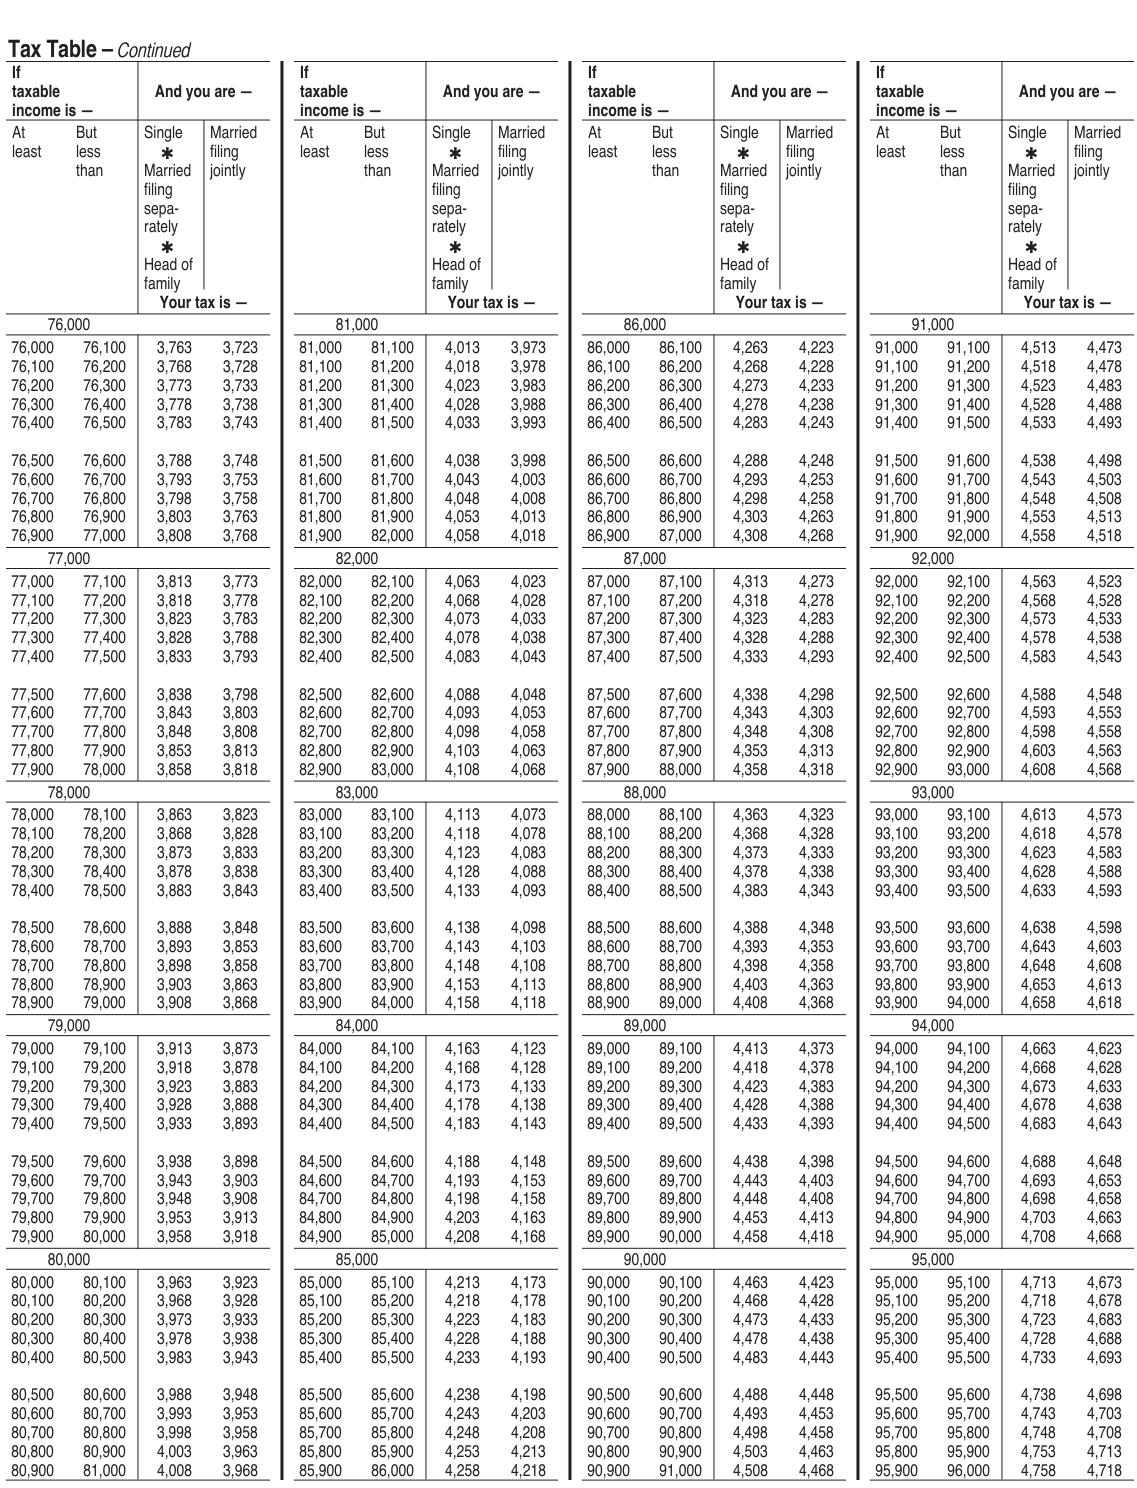
Text version of this table
Tax Tab le – Continued If If If If taxable And you are — taxable And you are — taxable And you are — taxable And you are — income is — income is — income is — income is — At But Single Married At B ut Single Married At B ut Single Married At B ut Single Married least less ✱ filing least le ss ✱ filing least le ss ✱ filing least le ss ✱ filing than Married jointly t han Married jointly t han Married jointly t han Married jointly filing filing filing filing sepa- sepa- sepa- sepa- rately rately rately rately ✱ ✱ ✱ ✱ Head of Head of Head of Head of family family family family Your ta x is — Your ta x is — Your ta x is — Your ta x is — 76,0 00 81,0 0 0 86,0 0 0 91,0 0 0 76,000 76,10 0 3,763 3,723 81,000 81,100 4,013 3,973 86,000 86,100 4,263 4,223 91,000 91,100 4,513 4,473 76,100 76,20 0 3,768 3,728 81,100 81,200 4,018 3,978 86,100 86,200 4,268 4,228 91,100 91,200 4,518 4,478 76,200 76,30 0 3,773 3,733 81,200 81,300 4,023 3,983 86,200 86,300 4,273 4,233 91,200 91,300 4,523 4,483 76,300 76,40 0 3,778 3,738 81,300 81,400 4,028 3,988 86,300 86,400 4,278 4,238 91,300 91,400 4,528 4,488 76,400 76,50 0 3,783 3,743 81,400 81,500 4,033 3,993 86,400 86,500 4,283 4,243 91,400 91,500 4,533 4,493 76,500 76,60 0 3,788 3,748 81,500 81,600 4,038 3,998 86,500 86,600 4,288 4,248 91,500 91,600 4,538 4,498 76,600 76,70 0 3,793 3,753 81,600 81,700 4,043 4,003 86,600 86,700 4,293 4,253 91,600 91,700 4,543 4,503 76,700 76,80 0 3,798 3,758 81,700 81,800 4,048 4,008 86,700 86,800 4,298 4,258 91,700 91,800 4,548 4,508 76,800 76,90 0 3,803 3,763 81,800 81,900 4,053 4,013 86,800 86,900 4,303 4,263 91,800 91,900 4,553 4,513 76,900 77,00 0 3,808 3,768 81,900 82,000 4,058 4,018 86,900 87,000 4,308 4,268 91,900 92,000 4,558 4,518 77,0 00 82,0 0 0 87,0 0 0 92,0 0 0 77,000 77,10 0 3,813 3,773 82,000 82,100 4,063 4,023 87,000 87,100 4,313 4,273 92,000 92,100 4,563 4,523 77,100 77,20 0 3,818 3,778 82,100 82,200 4,068 4,028 87,100 87,200 4,318 4,278 92,100 92,200 4,568 4,528 77,200 77,30 0 3,823 3,783 82,200 82,300 4,073 4,033 87,200 87,300 4,323 4,283 92,200 92,300 4,573 4,533 77,300 77,40 0 3,828 3,788 82,300 82,400 4,078 4,038 87,300 87,400 4,328 4,288 92,300 92,400 4,578 4,538 77,400 77,50 0 3,833 3,793 82,400 82,500 4,083 4,043 87,400 87,500 4,333 4,293 92,400 92,500 4,583 4,543 77,500 77,60 0 3,838 3,798 82,500 82,600 4,088 4,048 87,500 87,600 4,338 4,298 92,500 92,600 4,588 4,548 77,600 77,70 0 3,843 3,803 82,600 82,700 4,093 4,053 87,600 87,700 4,343 4,303 92,600 92,700 4,593 4,553 77,700 77,80 0 3,848 3,808 82,700 82,800 4,098 4,058 87,700 87,800 4,348 4,308 92,700 92,800 4,598 4,558 77,800 77,90 0 3,853 3,813 82,800 82,900 4,103 4,063 87,800 87,900 4,353 4,313 92,800 92,900 4,603 4,563 77,900 78,00 0 3,858 3,818 82,900 83,000 4,108 4,068 87,900 88,000 4,358 4,318 92,900 93,000 4,608 4,568 78,0 00 83,0 0 0 88,0 0 0 93,0 0 0 78,000 78,10 0 3,863 3,823 83,000 83,100 4,113 4,073 88,000 88,100 4,363 4,323 93,000 93,100 4,613 4,573 78,100 78,20 0 3,868 3,828 83,100 83,200 4,118 4,078 88,100 88,200 4,368 4,328 93,100 93,200 4,618 4,578 78,200 78,30 0 3,873 3,833 83,200 83,300 4,123 4,083 88,200 88,300 4,373 4,333 93,200 93,300 4,623 4,583 78,300 78,40 0 3,878 3,838 83,300 83,400 4,128 4,088 88,300 88,400 4,378 4,338 93,300 93,400 4,628 4,588 78,400 78,50 0 3,883 3,843 83,400 83,500 4,133 4,093 88,400 88,500 4,383 4,343 93,400 93,500 4,633 4,593 78,500 78,60 0 3,888 3,848 83,500 83,600 4,138 4,098 88,500 88,600 4,388 4,348 93,500 93,600 4,638 4,598 78,600 78,70 0 3,893 3,853 83,600 83,700 4,143 4,103 88,600 88,700 4,393 4,353 93,600 93,700 4,643 4,603 78,700 78,80 0 3,898 3,858 83,700 83,800 4,148 4,108 88,700 88,800 4,398 4,358 93,700 93,800 4,648 4,608 78,800 78,90 0 3,903 3,863 83,800 83,900 4,153 4,113 88,800 88,900 4,403 4,363 93,800 93,900 4,653 4,613 78,900 79,00 0 3,908 3,868 83,900 84,000 4,158 4,118 88,900 89,000 4,408 4,368 93,900 94,000 4,658 4,618 79,0 00 84,0 0 0 89,0 0 0 94,0 0 0 79,000 79,10 0 3,913 3,873 84,000 84,100 4,163 4,123 89,000 89,100 4,413 4,373 94,000 94,100 4,663 4,623 79,100 79,20 0 3,918 3,878 84,100 84,200 4,168 4,128 89,100 89,200 4,418 4,378 94,100 94,200 4,668 4,628 79,200 79,30 0 3,923 3,883 84,200 84,300 4,173 4,133 89,200 89,300 4,423 4,383 94,200 94,300 4,673 4,633 79,300 79,40 0 3,928 3,888 84,300 84,400 4,178 4,138 89,300 89,400 4,428 4,388 94,300 94,400 4,678 4,638 79,400 79,50 0 3,933 3,893 84,400 84,500 4,183 4,143 89,400 89,500 4,433 4,393 94,400 94,500 4,683 4,643 79,500 79,60 0 3,938 3,898 84,500 84,600 4,188 4,148 89,500 89,600 4,438 4,398 94,500 94,600 4,688 4,648 79,600 79,70 0 3,943 3,903 84,600 84,700 4,193 4,153 89,600 89,700 4,443 4,403 94,600 94,700 4,693 4,653 79,700 79,80 0 3,948 3,908 84,700 84,800 4,198 4,158 89,700 89,800 4,448 4,408 94,700 94,800 4,698 4,658 79,800 79,90 0 3,953 3,913 84,800 84,900 4,203 4,163 89,800 89,900 4,453 4,413 94,800 94,900 4,703 4,663 79,900 80,00 0 3,958 3,918 84,900 85,000 4,208 4,168 89,900 90,000 4,458 4,418 94,900 95,000 4,708 4,668 80,0 00 85,0 0 0 90,0 0 0 95,0 0 0 80,000 80,10 0 3,963 3,923 85,000 85,100 4,213 4,173 90,000 90,100 4,463 4,423 95,000 95,100 4,713 4,673 80,100 80,20 0 3,968 3,928 85,100 85,200 4,218 4,178 90,100 90,200 4,468 4,428 95,100 95,200 4,718 4,678 80,200 80,30 0 3,973 3,933 85,200 85,300 4,223 4,183 90,200 90,300 4,473 4,433 95,200 95,300 4,723 4,683 80,300 80,40 0 3,978 3,938 85,300 85,400 4,228 4,188 90,300 90,400 4,478 4,438 95,300 95,400 4,728 4,688 80,400 80,50 0 3,983 3,943 85,400 85,500 4,233 4,193 90,400 90,500 4,483 4,443 95,400 95,500 4,733 4,693 80,500 80,60 0 3,988 3,948 85,500 85,600 4,238 4,198 90,500 90,600 4,488 4,448 95,500 95,600 4,738 4,698 80,600 80,70 0 3,993 3,953 85,600 85,700 4,243 4,203 90,600 90,700 4,493 4,453 95,600 95,700 4,743 4,703 80,700 80,80 0 3,998 3,958 85,700 85,800 4,248 4,208 90,700 90,800 4,498 4,458 95,700 95,800 4,748 4,708 80,800 80,90 0 4,003 3,963 85,800 85,900 4,253 4,213 90,800 90,900 4,503 4,463 95,800 95,900 4,753 4,713 80,900 81,00 0 4,008 3,968 85,900 86,000 4,258 4,218 90,900 91,000 4,508 4,468 95,900 96,000 4,758 4,718
If If If taxable And you are - taxable And you are - taxable If And you are - taxable And you are - income is - income is - income is - income is -But At But Single Married At But Single Married At Single Married At But Single Married less least less filing least less filing least ✱ ✱ filing least less filing ✱ ✱ than than Married jointly than Married jointly filing filing sepa- separately rately ✱ ✱ Head of Head of family family Your tax is - Your tax is -Married jointly than Married jointly filing filing sepa- separately rately ✱ ✱ Head of Head of family family Your tax is - Your tax is -98,000 96,000 97,000 96,000 96,100 4,763 4,723 97,000 97,100 4,813 4,773 98,000 96,100 96,200 4,768 4,728 97,100 97,200 4,818 4,778 98,100 96,200 96,300 4,773 4,733 97,200 97,300 4,823 4,783 98,200 96,300 96,400 4,778 4,738 97,300 97,400 4,828 4,788 98,300 96,400 96,500 4,783 4,743 97,400 97,500 4,833 4,793 98,400 96,500 96,600 4,788 4,748 97,500 97,600 4,838 4,798 98,500 96,600 96,700 4,793 4,753 97,600 97,700 4,843 4,803 98,600 96,700 96,800 4,798 4,758 97,700 97,800 4,848 4,808 98,700 96,800 96,900 4,803 4,763 97,800 97,900 4,853 4,813 98,800 96,900 97,000 4,808 4,768 97,900 98,000 4,858 4,818 98,900
# Over $100,000.00
If taxable income is over $100,000, use the following worksheet to figure your tax.
- Single
- Married filing separately
1 Enter taxable income . .
2 Less … -100,000.00
3 Subtract line 2 from line 1 …
4 Multiply line 3 by .05 . . x .05
5 Enter result here …
6 Plus … + 4,958.00
7 Add lines 5 and 6.
▼
Your tax is …
- Married filing jointly
1 Enter taxable income . .
2 Less … -100,000.00
3 Subtract line 2 from line 1 …
4 Multiply line 3 by .05 . . x .05
5 Enter result here …
6 Plus … + 4,918.00
7 Add lines 5 and 6.
▼
Your tax is …
99,000
98,100 4,863 4,823 99,000 99,100 4,913 4,873 98,200 4,868 4,828 99,100 99,200 4,918 4,878 98,300 4,873 4,833 99,200 99,300 4,923 4,883 98,400 4,878 4,838 99,300 99,400 4,928 4,888 98,500 4,883 4,843 99,400 99,500 4,933 4,893 98,600 4,888 4,848 99,500 99,600 4,938 4,898 98,700 4,893 4,853 99,600 99,700 4,943 4,903 98,800 4,898 4,858 99,700 99,800 4,948 4,908 98,900 4,903 4,863 99,800 99,900 4,953 4,913 99,000 4,908 4,868 99,900 100,000 4,958 4,918
# Federal Income Tax Deduction Worksheet
Enter the tax as shown on line 22 on 2025 Form 1040/Form 1040-SR/Form 1040NR … 1 00 Net Investment Income Tax. Enter amount from line 17, 2025 Form 8960 … 2 00 Federal Tax. Add Lines 1 and 2 … 4a Earned Income Credit (EIC). Enter the amount from line 27a of 2025 Form 1040/Form 1040-SR. 4a 4b Additional Child Tax Credit. Enter the amount from Line 28 of 2025 Form 1040/Form 1040-SR/1040-NR … 4b 4c American Opportunity Credit. Enter the amount from line 29 of 2025 Form 1040/Form 1040-SR. 4c 4d Refundable Adoption Credit. Enter the amount from line 30 of 2025 Form 1040/Form 1040-SR/1040-NR … 4d 4e Credits from Forms 2439. Enter the amount from Schedule 3, Part II, line 13a of 2025 Form 1040/Form 1040-SR/Form1040NR … 4e Add lines 4a, b, c, d and e … 5 00 Subtract line 5 from line 3. If amount is negative enter zero also enter on line 12 of Form 40, line 9 of Form 40A or page 2, Part IV, line 4 of Form 40NR … 00
# Qualified Vehicle Loan Interest Worksheet
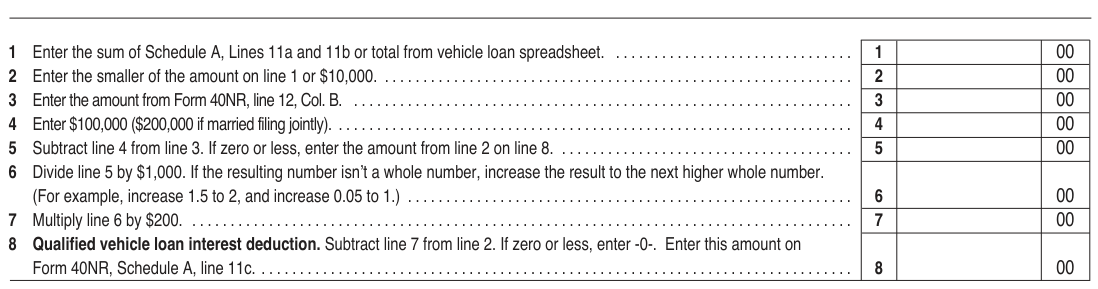
Text version of this table
| 1 Enter the sum of Schedule A, Lines 11a and 11b or total from vehicle loan spreadsheet. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . 2 Enter the smaller of the amount on line 1 or $10,000. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . 3 Enter the amount from Form 40NR, line 12, Col. B. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . 4 Enter $100,000 ($200,000 if married filing jointly). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . 5 Subtract line 4 from line 3. If zero or less, enter the amount from line 2 on line 8. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . 6 Divide line 5 by $1,000. If the resulting number isn’t a whole number, increase the result to the next higher whole number. (For example, increase 1.5 to 2, and increase 0.05 to 1.) . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . 7 Multiply line 6 by $200. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . 8 Qualified vehicle loan interest deduction. Subtract line 7 from line 2. If zero or less, enter -0-. Enter this amount on Form 40NR, Schedule A, line 11c. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . | 1 | 00 |
| 2 | 00 | |
| 3 | 00 | |
| 4 | 00 | |
| 5 | 00 | |
| 6 | 00 | |
| 7 | 00 | |
| 8 | 00 |
# My Alabama Taxes (MAT)
You can file your Alabama Resident and Non-Resident returns online through My Alabama Taxes (MAT) at no charge.
The Alabama Department of Revenue offers several methods for filing your Individual Income Tax Return.
Federal/State Electronic Filing Program
Your professional tax practitioner can file both your Federal and State returns by using the E-File Program or can print a 2-D Barcode for you.
Free Filing of
Federal/State Return
Free electronic filing of your Alabama and Federal Income Tax Returns are provided for low income wage earners, senior citizens, students, and active duty military personnel. For more information on the qualifications, visit our website at https://www.revenue.alabama.gov/individualcorporate/individual-income-tax/individual-income-tax-electronic-fili ng-options/
Federal/State On-Line Filing Program
You can file your own Federal and State return on-line by purchasing the program from a local retailer or going to https://www.revenue.alabama.gov/individual-corporate/ approved-software-vendors/ to see a listing of Approved On-Line Service Providers. If you do not want to file electronically, these programs will print out a 2-D Barcode.
This option is available to all taxpayers filing an Alabama Individual Income tax return. Please visit https://revenue.alabama.gov/services/my-alabama-taxes-sign-up/ to sign up and get started filling out your return.
2-D Barcode Filing Program
All the programs above should produce a 2-D Barcode for you. Also, you can print a 2-D Barcode by using our fillable Form 40 or Form 40NR which you can obtain at https://revenue.alabama.gov/forms. After you fill out the form and print it, a 2-D Barcode will be produced on the top of the form. You can still mail your return, but use of the 2-D Barcode will ensure faster processing.
OTHER FILING OPTIONS:
VITA/AARP/IMPACT ALABAMA
Free tax help and electronic filing of your Federal and State returns for low to moderate income taxpayers, people age 60 and older and military families is provided by the VITA, AARP, or IMPACT ALABAMA volunteers. For more information, visit our website at https://www.revenue.alabama.gov/individual-corporate/.
# How To Obtain Forms
To obtain instructions, schedules and forms visit our Website at: www.revenue.alabama.gov. Additional booklets, forms, and schedules are listed below. Certain booklets may be obtained by visiting the Alabama Taxpayer Service Center nearest you.
BOOKLETS
Form 40 Booklet. This booklet contains the following forms and schedules with instructions: Form 40, Schedules A, B, DC, CR, D, E, W-2, DS, HOF, ATP, RS, and Form 40V.
Form 40NR Booklet. This booklet contains the following forms and schedules with instructions: Form 40NR, Schedules A, B, D, E, W-2, DS, HOF, RS, and Form 40V.
FORMS
Form 40 Individual Income Tax Return for full year residents of Alabama and also part-year residents of Alabama.
Form 40A Individual Income Tax Return (Short Form) for full year residents of Alabama.
Form 40NR Nonresident Individual Income Tax Return for nonresidents of Alabama.
Form 40ES to make estimated tax payments.
SCHEDULES
Schedule A, B, & DC - for itemized deductions, interest and dividend income, and donation check-offs.
Schedule CR - for computation of credit for taxes paid to other states.
Schedule D&E - for reporting income from the sale or exchange of capital assets, and for reporting income from rents, royalties, partnerships, estates, and trusts.
Schedule AAC - for computation of Alabama adoption tax credit.
Schedule AATC - for computation of the credit for transferring a student from a failing public school to a non-failing public school or non-public school.
Schedule DS - form must be completed to receive proper credit for dependents claimed on Form 40 and 40NR.
Schedule HOF - form must be completed to receive proper credit for head of family claimed on Form 40 and 40NR Schedule OC - for computation of individual tax credits.
Schedule W-2 - form must be completed to receive proper credit for Alabama income tax withheld on Forms 40A, 40, and 40NR.
Schedule CP - form must be completed to receive proper credit for Alabama composite payments withheld and Electing PTE Credits Schedule KRCC-I - for reporting the recipient's share of Capital Credit for Individual Taxpayers.
Schedule ATP - for computation of Additional Taxes & Penalties.
Schedule HBC - form must be completed to receive proper credit for First Time Second Chance Home Buyer Deduction.
Schedule RS - form must be completed to report report fully or partially taxable pensions, annuities, ira distributions and retirement distribution(s) exempt from Alabama Income.
NOTE:
Alabama does not provide the following forms and schedules and requests that the appropriate federal schedule be used making the modifications as required by Alabama law.
Schedule C for reporting income from a personally owned business.
Schedule F for reporting income from farming.
Form 2106 for claiming employee business expenses.
Form 3903 for claiming moving expenses.
Form 4684 for reporting casualty and theft losses.
Form 4797 for reporting sale of business property.
Form 6252 for reporting installment sale income.
Form 8283 for reporting noncash contributions.
Tables and rate charts from the source document
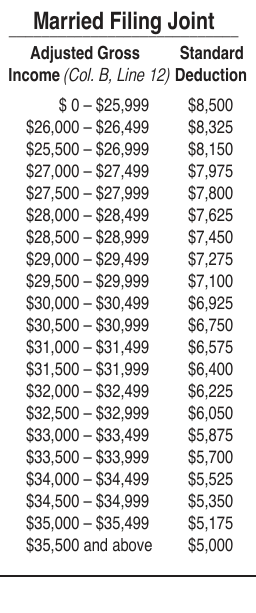
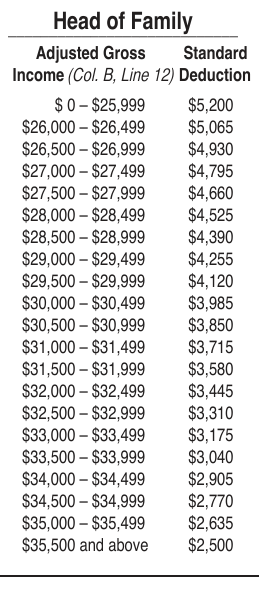
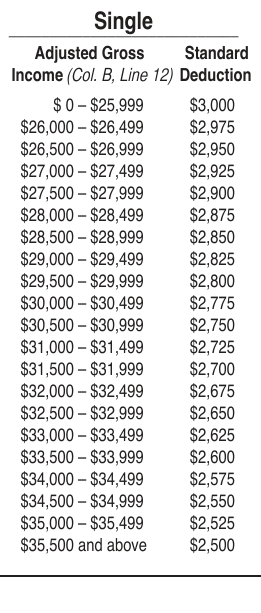
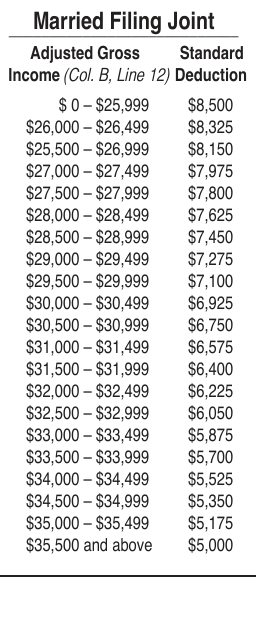
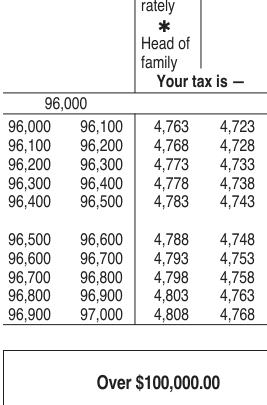
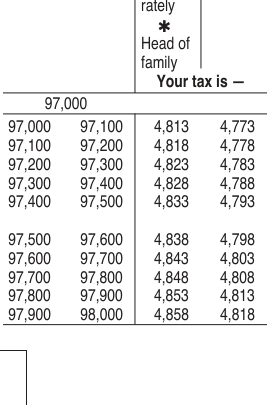
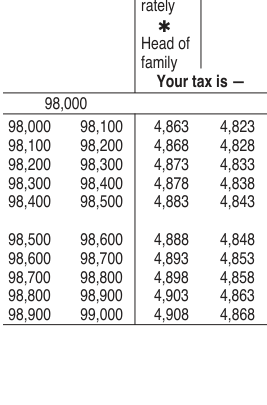
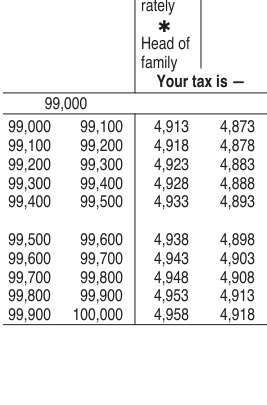
Source: view the official PDF
The source document contains 3 figures (charts or worksheet graphics) not reproduced in this text version. See the official PDF above.
Nearby sections (21 sections)
- Add-Back_Form_with_Instructions · Add-Back Form with Instructions
- BPT_Quick_Reference · Business Privilege Tax — CPT/PPT Quick Reference…
- Composite_Payments_20C_PTEC_EPT_41 · Composite Payments for Forms 20C,…
- Form_20C_Instructions · Form 20C — Corporation Income Tax Return…
- Form_20S_Instructions · Form 20S — S Corporation Information/Tax Return…
- Form_2210AL_Individual_Underpayment · Form 2210AL — Underpayment of…
- Form_2220AL_Corporate_Underpayment · Form 2220AL — Estimated Tax…
- Form_40ES_Individual_Estimated · Form 40ES — Individual Estimated Tax…
- Form_40NR_Instructions · Form 40NR — Nonresident Individual Income Tax…
- Form_40_Instructions · Form 40 — Resident Individual Income Tax Return…
- Form_41_Instructions · Form 41 — Fiduciary Income Tax Return…
- Form_41_NOL_Carryback · Form 41 NOL — Fiduciary NOL…
- Form_65_Instructions · Form 65 — Partnership/LLC Return of Income…
- Form_A-4_Employee_Withholding_Cert · Form A-4 — Employee Withholding…
- Form_BPT-IN_Initial_Instructions · Form BPT-IN — Initial Business…
- Form_CPT_BPT_Instructions · Form CPT — Business Privilege Tax…
- Form_EPT_Credit_Schedule · Form EPT — Electing PTE Credit Schedule
- Form_EPT_Payment_Return · Form EPT — Electing Pass-Through Entity…
- Form_ET-1_Financial_Institution_Excise · Form ET-1 — Financial…
- Form_MPT_Medical_Cannabis_Privilege_Tax · Form MPT — Medical Cannabis…
- Form_PPT_BPT_Instructions · Form PPT — Business Privilege Tax…