N-342 Instructions — Renewable Energy Technologies Income Tax Credit
INSTRUCTIONS
# Clear Form
STATE OF HAWAII-DEPARTMENT OF TAXATION
FORM N-342 INSTRUCTIONS FOR FORM N-342
# RENEWABLE ENERGY TECHNOLOGIES INCOME TAX CREDIT
(FOR SYSTEMS INSTALLED AND PLACED IN SERVICE ON OR AFTER JULY 1, 2009)
(NOTE: References to "married" and "spouse" are also references to "in a civil union"
and "civil union partner," respectively.)
# COMPOSITE FILING OF FORM N-342
Any individual or corporate taxpayer who is eligible to claim the renewable energy technologies income tax credit (RETITC) for 10 or more systems or distributive shares of systems installed and placed in service in a single tax year may file a composite Form N-342. A composite Form N-342, which is designated with the word "COMPOSITE" printed in capital letters at the top of the form, is used to report the total amounts from Form N-342C, Composite Schedule for Form N-342. For more information and instructions on filing a composite Form N-342, see Department of Taxation Announcement No. 2012-01 and the Instructions for Form N-342C. Note:
Failing to properly file and/or comply with the terms and conditions for composite filing (e.g., filing a composite Form N-342 to claim the renewable energy technologies income tax credit for less than 10 systems installed and placed in service in a single tax year) may result in the disallowance of all or part of the credits and the revocation of the election to composite file.
# PURPOSE OF FORM
Use Form N-342 to figure and claim the RETITC under section 235-12.5, Hawaii Revised Statutes (HRS). Use one Form N-342 for each system. If you have carryover credit(s), see the "Carryover Credit" section below.
# WHO MAY CLAIM THIS CREDIT
If you are the economic owner of an eligible renewable energy technology system that was installed and placed in service in Hawaii during the taxable year, you may claim this credit if:
(1) You are an individual or corporate taxpayer subject to Hawaii income tax under chapter 235, HRS; or
(2) You are a taxpayer subject to Hawaii franchise tax under chapter 241, HRS.
MULTIPLE OWNERS OF A SYSTEM
Multiple owners of a single system are entitled to a single tax credit.
Each owner may claim a portion of the credit based on how much it paid towards the cost of the system subject to the tax credit cap. For example, three individuals install and place in service a solar water heater on a single-family residential property in Hawaii. They split the costs evenly. The credit is the lesser of 35% of the actual cost or $2,250. Each individual may claim one-third of the credit. To claim the credit, each owner must complete Form N-342 and report its share of the total costs.
# FLOW-THROUGH ENTITIES
If you are a partnership, S corporation, estate, trust, or condominium apartment association who is the economic owner of an eligible renewable energy technology system that was installed and placed in service in Hawaii during the taxable year, figure the amount of the credit at the entity level on Form N-342 and attach it to your return. Use a separate Form N-342 for each eligible renewable energy technology system. Prepare a separate Form N-342A, Information Statement Concerning the Renewable Energy Technologies Income Tax Credit for Systems Placed in Service on or After July 1, 2009, to report the distributive share of the credit for each partner, shareholder, member, or beneficiary for each eligible system. If you are a partnership or S corporation, attach Form N-342A to each partner's or shareholder's Schedule K-1. Attach a copy of Form N-342A given to each partner, shareholder, member, or beneficiary to your return.
# WHEN THE CREDIT MAY NOT BE CLAIMED
This credit may not be claimed it any of the following apply:
(1) You are using the entire cost of the system to claim another credit.
(2) You are the lessee in a Power Purchase Agreement (PPA).
(3) Your solar water heater system was required to be installed on new single-family residential property under section 196-6.5, HRS.
(4) Your wind-powered energy system is a substitute for a required solar water heater system under section 196-6.5, HRS.
(5) Your solar energy system is five megawatts in total output capacity or larger and requires a power purchase agreement approved by the public utilities commission.
Note: If you install a solar energy system, such as a photovoltaic (PV) system as a substitute for a required solar water heater system under section 196-6.5, HRS, then you must reduce your credit by the lesser of 35% of the actual system cost or $2,250.
# CREDIT REQUIREMENTS
To claim this credit, you must complete and attach to your Hawaii income tax return or Hawaii franchise tax return:
(1) Form N-342
(2) Schedule CR (For tax returns for which Schedule CR is required)
(3) Form N-342A (Required only if you are claiming a distributive share of a credit from a partnership, S corporation, estate, trust, or condominium apartment association)
(4) Schedule K-1 (Required only if you are claiming a distributive share of a credit from a partnership, S corporation, estate, or trust)
# CARRYOVER CREDIT
If you have a carryover credit from last year for a system installed and placed in service before July 1, 2009, use Form N-323 and its instructions instead of this form. If you have a carryover credit(s) from last year for a system(s) installed and placed in service after July 1, 2009, complete one Form N-342 for your carryover credit(s). If you are also claiming a credit(s) for a system(s) installed and placed in service in the taxable year, complete a separate Form N-342 for each system.
# DEADLINE FOR CLAIMING THE CREDIT
The deadline to claim the credit, including any amended claims, is 12 months after the close of your taxable year. You cannot claim or amend the credit after the deadline.
# HOW TO TREAT THE TAX CREDIT
Only taxpayers with excess tax credit may choose on how to treat their excess RETITC. Excess tax credit means tax credit exceeds tax liability owed.
Nonrefundable: If the tax credit exceeds your income tax liability, the excess of the credit over liability may be used as a carryover credit against your income tax liability in subsequent years until exhausted.
Refundable: For solar energy systems, you may elect to reduce the eligible credit amount by 30% and if this reduced amount exceeds the amount of income tax payment due, the excess of the credit amount over payments due will be refunded. This is an irrevocable election. A separate election may be made for each separate system that generates a credit.
Refundable: For any renewable energy technology system, an
Instructions for Form N-342 (REV. 2025)
CALCULATION - ALLOCATION OF TOTAL COST FOR individual taxpayer may elect to have any excess of the credit over OTHER SOLAR ENERGY SYSTEMS payments due refunded if:
Listed below is the calculation to determine the total output capacity
(1) All of your (and your spouse's) income is retirement income such as and the allocation of the total cost per system where more than one system pension distributions, social security, or distributions from a public is installed and placed in service on a single property in the taxable year. retirement system that is exempt from Hawaii income tax; or
(2) Your Hawaii adjusted gross income (AGI) is $20,000 or less (or 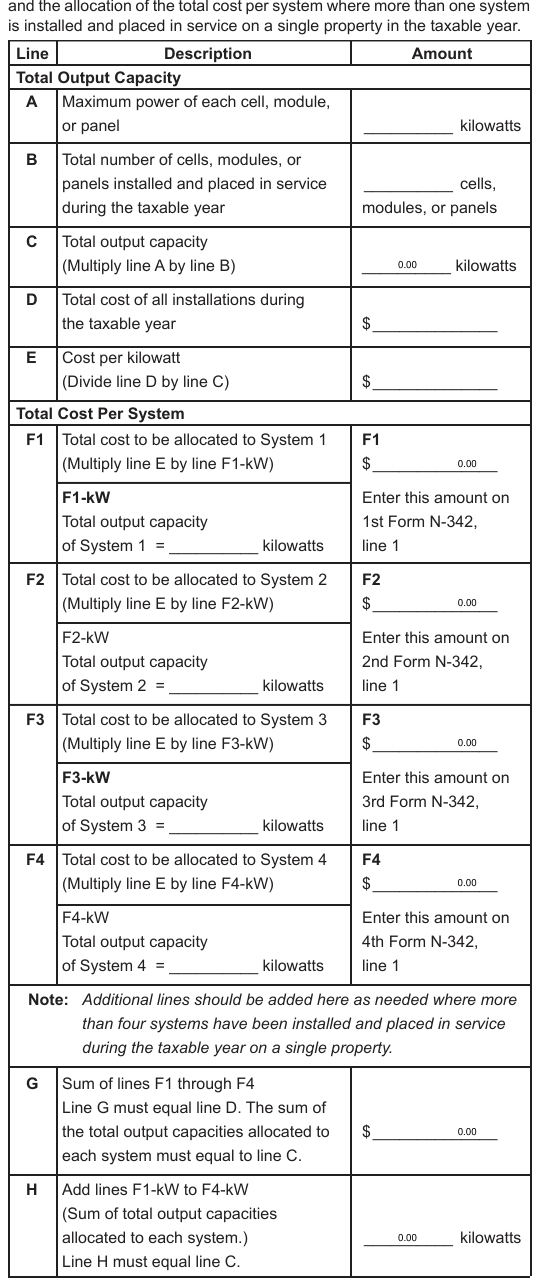
Text version of this table
Line Description Amount TOTAL OUTPUT CAPACITY A Maximum power of each cell, module, or panel _ kilowatts __________ B Total number of cells, modules, or panels installed and placed in service during the taxable year _ cells, __________ modules, or panels C Total output capacity (Multiply line A by line B) 0.00 kilowatts __________ D Total cost of all installations during the taxable year _ $_ ______________ E Cost per kilowatt (Divide line D by line C) _ $_ ______________ Total Cost Per System F1 Total cost to be allocated to System 1 (Multiply line E by line F1-kW) _ F1 _ $_ __________0_.0_0__ Enter this amount on 1st Form N-342, line 1 F1-kW Total output capacity of System 1 = kilowatts __________ F2 Total cost to be allocated to System 2 (Multiply line E by line F2-kW) _ F2 _ $_ 0.00 ______________ Enter this amount on 2nd Form N-342, line 1 F2-kW Total output capacity of System 2 = kilowatts __________ F3 Total cost to be allocated to System 3 (Multiply line E by line F3-kW) _ F3 _ $_ 0.00 ______________ Enter this amount on 3rd Form N-342, line 1 F3-kW Total output capacity of System 3 = kilowatts __________ F4 Total cost to be allocated to System 4 (Multiply line E by line F4-kW) _ F4 _ $_ 0.00 ______________ Enter this amount on 4th Form N-342, line 1 F4-kW Total output capacity of System 4 = kilowatts __________ Note: Additional lines should be added here as needed where more than four systems have been installed and placed in service during the taxable year on a single property. G Sum of lines F1 through F4 Line G must equal line D. The sum of the total output capacities allocated to each system must equal to line C. _ $_ 0.00 ______________ H Add lines F1-kW to F4-kW (Sum of total output capacities allocated to each system.) Line H must equal line C. _ 0.00 kilowatts __________
Instructions for Form N-342 (REV. 2025)
# TAX CREDIT RATES
The tax credit may be claimed for the following renewable energy technology systems installed and placed in service in Hawaii on or after July 1, 2009 Type of Renewable Tax Credit Energy Technology System Rate
Solar energy systems - Primary purpose is to use energy from
- the sun to heat water for household use a. Single-family residential The lesser of 35% of the actual property. cost of the system or $2,250. b. Multi-family residential Per building unit: property. The lesser of 35% of each unit's actual cost of the system or $350. c. Commercial property. The lesser of 35% of the actual cost of the system or $250,000.
Solar energy systems - All other solar energy systems a. Single-family residential The lesser of 35% of the actual property. cost of the system or $5,000. b. Multi-family residential Per building unit: property. The lesser of 35% of each unit's actual cost of the system or $350. c. Commercial property. The lesser of 35% of the actual cost of the system or $500,000.
Wind-powered energy systems
- a. Single-family residential The lesser of 20% of the actual property. cost of the system or $1,500. b. Multi-family residential Per building unit: property. The lesser of 20% of each unit's actual cost of the system or $200. c. Commercial property. The lesser of 20% of the actual cost of the system or $500,000.
# DEFINITIONS
FOR PURPOSES OF THE TAX CREDIT
"Actual cost" means costs related to the renewable energy technology systems provided by section 235-12.5(a), HRS, including accessories and installation, but not including the cost of consumer incentive premiums unrelated to the operation of the system or offered with the sale of the system and costs for which another credit is claimed under Chapter 235, HRS.
"Household use" means any use to which heated water is commonly put in a residential setting, including commercial application of those uses.
"Renewable energy technology system" means a new system that captures and converts a renewable source of energy, such as solar or wind energy into:
(1) A usable source of thermal or mechanical energy;
(2) Electricity; or
(3) Fuel.
"Solar or wind energy system" means any identifiable facility, equipment, apparatus, or the like that converts solar or wind energy to useful thermal or electrical energy for heating, cooling, or reducing the use of other types of energy that are dependent upon fossil fuel for their generation.
"Installed and placed in service" means that the system is ready and available for its specific use. With respect to systems installed for residential property, all requirements will be completed and a system will be deemed to be installed and placed in service when: (1) The actual cost has been incurred; (2) all installation, including all related electrical work, has been completed; and (3) any required requests for inspection of the installation has been received by the appropriate government agency. However, if the residential installation fails to pass all the required inspections the credit is properly claimed in the taxable year in which the system passes such inspection.
# SPECIFIC INSTRUCTIONS
Note: If you are claiming a carryover credit(s), skip lines 1 through 47 and begin on line 48.
Note: Form N-20 and Form N-35 filers complete only lines 1 through 41
(Do Not complete lines 42 through 55).
For eligible systems installed and placed in service in the taxable year, be sure to enter in the appropriate space (1) the physical property address where the system was installed and placed in service (enter "CARRYOVER" if claiming carryover credit(s)), (2) the date the system was installed and placed in service (leave blank if claiming carryover credit(s)), and (3) the Total Output Capacity if the credit being claimed is for an "other solar energy system" (leave blank if claiming carryover credit(s)).
See the General Instructions for more information on "Total Output Capacity."
Lines 1 through 41 - Fill in the lines as they apply to your claim.
Lines 1 or 27 -- Enter the qualifying cost of the eligible renewable energy technology system installed and placed in service in Hawaii. Do not claim more than your share of the costs if there are multiple owners of the eligible renewable energy technology system.
Lines 2 or 28 -- Enter the dollar amount of any consumer incentive premiums unrelated to the operation of the system or offered with the sale of the system (such as "free solar powered products," "free gifts," offers to pay electricity bills, or rebates), costs for which another credit is claimed, and any utility rebate received for the qualifying renewable energy technology system.
The dollar amount of any consumer incentive premiums, costs for which another credit is claimed, and any utility rebate received are to be deducted from the cost of the qualifying system before determining the credit.
Lines 8, 20, and 33 -- The per unit cost of a solar or wind-powered energy system installed and placed in service in Hawaii in a multi-family residential property may be determined as follows:
Total square feet of your unit
Total square feet of all units x The actual cost in the multi-family of the system residential property If the above per unit cost calculation does not fairly represent the owners' contribution to the cost of the system, provide an alternative calculation.
Refundable Tax Credit -
Only taxpayers with excess tax credit may choose on how to treat their excess RETITC. Excess tax credit means tax credit exceeds tax liability owed.
If you are claiming the credit as refundable, choose the appropriate irrevocable election on line 42 or line 46. Complete either lines 42 through 45 or lines 46 through 47.
Lines 42 through 45 - For solar energy systems, you may elect to reduce the eligible credit amount by 30% and if this reduced amount exceeds the amount of income tax payment due, the excess of the credit amount over payments due will be refunded. This is an irrevocable election. A separate election may be made for each separate system that generates a credit.
Lines 46 through 47 - For any renewable energy technology system, an individual taxpayer may elect to have any excess of the credit over payments due refunded if:
(1) All of your (and your spouse's) income is retirement income such as pension distributions, social security, or distributions from a public retirement system that is exempt from Hawaii income tax; or
Page 4 Instructions for Form N-342 (REV. 2025)
CREDIT WORKSHEET
Tax Credit Amount a. Income Taxes Paid to Another
State or Foreign Country … b. Enterprise Zone Tax Credit … c. Carryover of the Energy
Conservation Tax Credit … d. Credit for Employment of
Vocational Rehabilitation
Referrals … e. Credit for School Repair and
Maintenance … f. Carryover of the Renewable
Energy Technologies Income
Tax Credit (For Systems
Installed and Placed in Service
Before July 1, 2009) … g. Nonrefundable Renewable
# Energy Technologies Income
Tax Credit (Form N-342) … h. Add lines a through g. Enter the amount here and on line 52 …
(2) Your Hawaii adjusted gross income (AGI) is $20,000 or less (or $40,000 or less if filing a tax return as married filing jointly).
A husband and wife who do not file a joint tax return shall only be entitled to make this election to the extent that they would have been entitled to make the election had they filed a joint tax return. This is an irrevocable election.
A separate election may be made for each separate system that generates a credit.
Nonrefundable Tax Credit -
Only taxpayers with excess tax credit may choose on how to treat their excess RETITC. Excess tax credit means tax credit exceeds tax liability owed.
Lines 48 through 55 - If you are claiming the credit as nonrefundable, complete lines 48 through 55 as they apply to your claim.
Line 48 - If you have unused renewable energy technologies income tax credit(s) (for one or more systems installed and placed in service on or after July 1, 2009) to carryover from the prior year, enter the total carryover amount on this line. Also include this amount on Schedule CR, line 28 in
Column (a).
If you have carryover credit(s) and are also claiming a credit for an eligible system installed and placed in service in the taxable year, complete one Form N-342 for the carryover credit(s) and then a separate Form N-342 for each eligible system installed and placed in service for that taxable year.
Line 49 - Total New Credit Claimed - Enter the amount from line 14, 26, 39, 40, or 41. Also include this amount on Schedule CR, line 28 in Column (b).
Line 51 - Adjusted Tax Liability - Enter your adjusted tax liability.
- Form N-11 filers, enter the amount from Form N-11, line 34.
- Form N-15 filers, enter the amount from Form N-15, line 51.
- Form N-30 filers, enter the amount from Form N-30, line 13.
- Form N-40 filers, enter the amount from Form N-40, Schedule G, line 3.
- Form N-70NP filers, enter the amount from Form N-70NP, line 19.
Line 52 - The law requires that ALL other credits offset a taxpayer's tax liability BEFORE allowing a renewable energy technologies income tax credit. Complete the Credit Worksheet in these instructions and enter the result on line 52. If you are claiming the nonrefundable renewable energy technologies income tax credit for multiple systems, enter on line h of the worksheet the amount of tax credit that is being claimed on line 54 of other Form(s) N-342 that you have already completed for the taxable year.
Line 54 - Total Credit Applied - Compare the amounts on lines 50 and
- Enter the smaller of line 50 or 53 here and in Column (c) on Schedule CR, line 28. This is your maximum credit applied for the taxable year.
Line 55 - Unused Credit to Carryover - This represents your carryover of renewable energy technologies income tax credit which exceeds your net income tax liability and may be used as a credit against your net income tax liability in subsequent years until exhausted. If this amount is more than zero, also enter this on Schedule CR, line 28 in Column (d).
Source: view the official PDF
Nearby sections (20 sections)
- hw-4-inst · HW-4 Instructions — Hawaii Employee Withholding Allowance…
- m-6-inst · M-6 Instructions — Hawaii Estate and Generation-Skipping…
- n-103-inst · N-103 Instructions — Sale of Your Home
- n-11-inst · N-11 — Hawaii Resident Individual Income Tax Return…
- n-139-inst · N-139 Instructions — Moving Expenses
- n-15-inst · N-15 — Hawaii Nonresident and Part-Year Resident Individual…
- n-152-inst · N-152 Instructions — Tax on Lump-Sum Distributions
- n-20-inst · N-20 Instructions — Hawaii Partnership Return (composite…
- n-210-inst · N-210 — Underpayment of Estimated Tax by Individuals,…
- n-30-inst · N-30 Instructions — Hawaii Corporation Income Tax Return
- n-312-inst · N-312 Instructions — Capital Goods Excise Tax Credit
- n-340-inst · N-340 Instructions — Motion Picture, Digital Media, and…
- n-342-inst · N-342 Instructions — Renewable Energy Technologies Income…
- n-35-inst · N-35 Instructions — Hawaii S Corporation Income Tax Return
- n-356-inst · N-356 Instructions — Hawaii Earned Income Tax Credit
- n-362-inst · N-362 Instructions — Hawaii Pass-Through Entity Tax (PTET)…
- n-40-inst · N-40 Instructions — Hawaii Fiduciary Income Tax Return
- n-848-inst · N-848 Instructions — Power of Attorney
- ta-1-inst · TA-1 Instructions — Hawaii Transient Accommodations Tax…
- ta-2-inst · TA-2 Instructions — Hawaii Transient Accommodations Tax…